

Blogs
Carbide Spray Coating Equipment Market: Why a 6.24% CAGR to $823M Means Real Competition Shifts
By PW Consulting, 2026-09-18
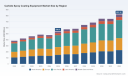
Global Carbide Spray Coating Equipment Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Snapshot and Core Challenges
The worldwide market for carbide spray coating equipment has demonstrated robust expansion over the past half-decade, transitioning from a fragmented industrial niche to a strategically critical enabler of asset durability and performance across heavy industry. Valued at approximately $385.4 million in 2020, the sector has grown to an estimated $538.5 million in 2025, reflecting a compound annual growth rate of roughly 6.24 percent through the forecast horizon to 2032. This trajectory is not merely a function of baseline industrial activity; it signals a structural shift in how manufacturers approach surface engineering, corrosion mitigation, and wear resistance in high-stress environments. The revenue base is projected to cross the $800 million threshold by the early 2030s, driven by sustained capital expenditure in asset-intensive sectors and the gradual replacement of legacy coating methods with high-velocity thermal spray technologies.
Despite the positive headline trajectory, the industry operates at a critical inflection point shaped by three interconnected challenges. First, the supply chain for tungsten and chromium carbide feedstocks has become increasingly volatile. Raw material constraints, particularly those originating from concentrated production hubs in East Asia, have triggered significant price escalations and forced equipment manufacturers and end-users to recalibrate cost models. The resulting margin pressure is reshaping procurement strategies and accelerating demand for alternative feedstock formulations and closed-loop material recovery systems.
Second, the skilled labor bottleneck is intensifying. Thermal spray operations require operators who can precisely manage powder feed rates, gas dynamics, standoff distances, and thermal profiles. Wage inflation in key manufacturing corridors has outpaced broader industrial averages, while apprenticeship pipelines remain underdeveloped. This talent gap is pushing equipment suppliers to embed greater automation, closed-loop control, and operator-assist features directly into their platforms, effectively shifting the value proposition from hardware hardware alone to integrated performance ecosystems.
Gas Dynamic Cold Spray Equipment Market
Third, regulatory and standardization frameworks are tightening the definition of acceptable coating performance. Updated durability testing protocols and revised quality benchmarks for thermally sprayed carbide layers on metallic substrates are forcing manufacturers to validate process consistency with greater rigor. Compliance is no longer a passive checkbox; it is becoming a competitive differentiator that separates suppliers capable of delivering repeatable, auditable coating outcomes from those relying on artisanal or highly variable application methods.
Key Growth Drivers and Structural Shifts
Technology Innovation and Deposition Efficiency
The most consequential driver of market evolution is the steady convergence of deposition technology, automation, and process analytics. High-velocity fuel and plasma-based systems have matured significantly, enabling denser carbide layer formation with improved adhesion and reduced porosity. Recent upgrades in high-pressure injection nozzles, optimized combustion chamber geometries, and closed-loop particle velocity monitoring have narrowed the historical gap between laboratory-grade coating quality and production-floor repeatability. Equipment manufacturers are increasingly packaging these advancements into modular architectures that allow end-users to switch between feedstock types, adjust spray parameters on the fly, and integrate robotic handling for complex geometries. The strategic implication is clear: coating equipment is no longer evaluated solely on throughput or footprint, but on the consistency and traceability of the coating outcome itself.
Policy, Regulation, and Standardization Pressure
Regulatory and standards activity is reshaping demand patterns in subtle but durable ways. Updated international specifications for thermal sprayed carbide coatings have elevated the baseline for durability verification, particularly in applications where failure carries high operational or safety costs. These developments are filtering down into procurement requirements across aerospace-adjacent suppliers, power generation operators, and heavy equipment manufacturers. At the same time, export control dynamics have introduced a new layer of complexity for cross-border equipment flows. Certain high-velocity spray platforms are now subject to tighter licensing scrutiny in dual-use contexts, which is encouraging regional equipment sourcing, localized service networks, and increased investment in domestic application engineering capabilities. Rather than stifling growth, these measures are incentivizing supply chain regionalization and deeper technical partnerships between equipment vendors and end-users.
Demand-Side Behavior and Asset-Longevity Economics
End-user behavior is increasingly governed by total-cost-of-ownership logic rather than upfront equipment price. In sectors where downtime is expensive and component replacement cycles are long, carbide coatings are being deployed earlier in the asset lifecycle as a proactive durability strategy rather than a reactive repair measure. Turbine components, valve trims, drill components, and high-wear industrial surfaces are seeing expanded adoption as operators seek to extend service intervals and reduce metallurgical wear under aggressive chemical or mechanical conditions. Aerospace-adjacent demand has been particularly influential, with engine efficiency mandates and higher operating temperatures pushing OEMs and MRO providers toward more advanced surface treatments that can tolerate thermal stress without compromising structural integrity. This demand-side shift is accelerating the migration from conventional spray methods toward systems that deliver higher deposition efficiency and more predictable metallurgical outcomes.
Supply Chain and Cost Structure Realignment
Cost structures across the equipment and coating value chain are undergoing a quiet but meaningful realignment. Feedstock price volatility has made material yield and overspray recovery economically significant, prompting manufacturers to invest in recovery systems, optimized powder morphology, and process control that reduces waste. Simultaneously, the rising cost of skilled labor is accelerating the business case for automated application cells, programmable manipulators, and integrated inspection workflows. Companies that can offer equipment together with feedstock management, parameter recipe libraries, and application support are capturing more of the economic value than those competing strictly on unit price. The result is a gradual shift from transactional equipment sales toward performance-based engagement models, where outcomes such as coating uniformity, reload frequency, and maintenance intervals become part of the commercial conversation.
Competitive Landscape and Leading Strategies
The competitive arena for carbide spray coating equipment is characterized by a moderate degree of concentration, with a handful of established players holding meaningful share while a broader tier of regional specialists and application-focused integrators competes on responsiveness, niche expertise, and total deployed cost. The market remains dynamic enough that leadership is determined less by scale alone and more by the ability to combine deposition technology, feedstock compatibility, and service depth into a coherent customer value proposition.
Global specialists with strong aerospace and energy pedigrees have built their positioning around high-pressure deposition platforms, process control, and integration into demanding manufacturing environments. Their advantage lies in documented performance in high-stakes applications, mature engineering support networks, and the ability to align equipment specifications with stringent durability expectations. These firms have increasingly emphasized system-level upgrades, demonstrating refined high-pressure platforms and automated application capabilities at industry forums, signaling a shift toward repeatable industrial throughput rather than bespoke, labor-intensive application.
Parallel to the global specialists, a group of technology-focused manufacturers has carved out strong positions by optimizing specific spray architectures for carbide deposition efficiency and industrial robustness. Their strategic emphasis tends to center on nozzle design, combustion stability, and hardware configurations that improve material utilization while maintaining the thermal profiles required for tungsten and chromium carbide adhesion. Product enhancements released over the past couple of years have focused on improving deposition consistency and expanding the practical operating envelope for industrial carbide coatings, appealing to buyers who prioritize throughput reliability and reduced process variability.
A third competitive vector is emerging around turnkey integration and automation. Equipment providers that bundle spray booths, robotic manipulators, powder handling, and environmental controls are targeting sectors where labor availability, floor space, and process repeatability constrain adoption. By demonstrating automated application cells in live industrial settings, these companies are making a compelling case that coating equipment can be deployed as a predictable production resource rather than a specialized craft operation. This is particularly relevant for automotive, steel, and paper industry applications where throughput consistency and operator safety carry significant economic weight.
The market is evolving along two simultaneous paths: consolidation among players seeking broader geographic reach and deeper aftermarket revenue, and fragmentation among specialists pursuing narrow application advantages or regional service intensity. New entrants are unlikely to succeed by replicating established spray hardware alone; they are more likely to gain traction by addressing underserved feedstock-formulations, integrating advanced process monitoring, or offering equipment-as-a-service models that lower the barrier to upgrading legacy lines. Competitive advantage is increasingly tied to lifecycle support, training ecosystems, and the ability to help customers navigate feedstock volatility and compliance requirements without sacrificing coating quality.
Future Outlook: Three Trends Shaping 2026–2032
The next three to five years will likely be defined by the maturation of automation, the hardening of compliance expectations, and the increasing economic importance of material efficiency. First, automated and semi-automated carbide spray cells will move from selective adoption to mainstream consideration in mid-volume industrial environments. As robotic handling, parameter presets, and inline verification become more accessible, the operational case for automation will strengthen even in settings that previously relied on experienced operators. This trend will favor equipment suppliers that can deliver repeatable outcomes with reduced dependency on specialized labor, and it will create aftermarket demand for software updates, recipe management, and service contracts.
Second, standards and export-control dynamics will continue to reshape procurement geography and partner selection. Buyers in regulated industries will place greater weight on documented process validation, traceable parameter records, and supplier capability to support regional compliance requirements. This environment rewards vendors with strong application engineering depth and penalizes those selling hardware without a clear support pathway. For end-users, it means sourcing decisions will increasingly factor in long-term assurance rather than initial price advantage.
PVD Coating Equipment Market
Third, feedstock economics will push the market toward higher material utilization and more disciplined process control. As carbide powder costs remain sensitive to supply constraints and geopolitical factors, companies that can demonstrate lower overspray, better recovery, and tighter control over deposition parameters will capture margin advantages. This creates opportunities for equipment configurations that integrate powder management, closed-loop feedback, and operator guidance tools, as well as for service providers that help plants optimize existing lines rather than replace them outright.
The principal uncertainties lie in the pace of feedstock price normalization, the trajectory of export and dual-use restrictions, and the speed at which labor shortages are mitigated through training or automation. Any significant relaxation in material availability could temporarily ease cost pressure, while tighter controls or sustained wage inflation could accelerate automation adoption faster than some suppliers are prepared to support. Forward-looking strategies should therefore stress flexibility, regional service readiness, and the ability to adapt equipment configurations to evolving feedstock and compliance conditions.
Strategic Recommendations for Decision-Makers
For equipment manufacturers and system integrators, the priority is to shift competitive positioning from hardware specification alone toward demonstrated coating consistency, automation readiness, and lifecycle support. Investing in closed-loop process control, recipe-based application workflows, and regional service coverage will strengthen resilience against labor constraints and feedstock volatility. Partnerships with feedstock suppliers and application engineering teams can also create differentiated offerings that help customers manage cost and compliance without sacrificing performance.
For investors and corporate strategy teams, the most attractive opportunities are likely to emerge in automation-adjacent upgrades, material efficiency solutions, and service-based revenue models rather than in undifferentiated hardware expansion. Monitoring the pace of regional equipment sourcing, the formation of integrated vendor-customer application programs, and the commercial impact of evolving standards will provide early signals of where value is shifting. Caution is warranted around exposure to markets that depend heavily on unrestricted cross-border equipment flows for high-performance platforms, given the regulatory uncertainty.
For procurement and operations leaders in end-user industries, the focus should be on evaluating total deployed cost and outcome reliability rather than sticker price. Requesting documented process validation, training pathways, and spare-parts and service commitments can reduce the risk of variability in coating performance. Aligning equipment selection with anticipated feedstock availability, internal labor capacity, and compliance documentation requirements will help secure longer-term operational stability.
PW Consulting
Detailed segmentation data, regional revenue splits, technology adoption curves, and company-level benchmarking are available in the full market research report, where the underlying figures and scenario analysis can be matched to specific procurement, investment, or product Roadmap decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Carbide Spray Coating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Sewer Repair Services Market: Why Trenchless Tech Reshapes Growth
By PW Consulting, 2026-09-18
全球污水修复服务市场:战略趋势与商业机会洞察
市场现状与核心挑战
全球污水修复服务市场已步入成熟但充满活力的发展阶段。2020年至2025年期间,市场规模从514亿美元增长至684亿美元,体现了基础设施老化与环境合规压力共同驱动的稳健扩张。展望2026年至2032年,市场预计将继续保持中高速增长,年复合增长率约为6.22%,到2032年市场规模有望突破1040亿美元。这一增长轨迹不仅反映了传统修复需求的持续释放,更暗示了技术迭代与政策推动下的市场结构性升级。
Underwater Vessel Repair Services Market
然而,行业增长并非没有阻力。首先,基础设施的地理分布不均与维护优先级的差异,导致服务需求在不同区域呈现显著的波动特征。部分发达地区的管网已进入大规模更新窗口,而新兴市场则面临资金与技术双重约束,这种结构性失衡给服务提供商的资源调配带来了挑战。其次,劳动力成本的上升正在重塑市场的盈利结构。随着现场施工依赖程度较高,人工费用占比增加,企业不得不在效率提升与成本控制之间寻找新的平衡点。最后,监管框架的收紧迫使服务方超越单纯的故障修复,转向系统性的防洪与溢流管理,这对技术能力与项目管理水平提出了更高要求。
从竞争格局来看,市场尚未形成高度集中态势,前五大企业的市场份额合计不足四分之一。这种相对分散的格局为具备差异化技术或区域优势的参与者提供了空间,同时也意味着行业正在经历从小型作业向规模化、服务化解决方案的过渡。企业若想在这一阶段建立稳固地位,不仅需要应对当下的技术与成本压力,更要预判未来三到五年内政策导向与客户偏好的演变方向。
关键驱动因素分析
技术创新正在重新定义污水修复的服务边界。环境管理中的原位修复技术持续演进,使得传统开挖方案在 많은应用场景中不再是唯一选择。新型管道衬里系统与点修复技术的成熟,显著降低了施工对周围环境的干扰,同时缩短了作业周期。这些技术进步不仅提升了单个项目的交付效率,也推动服务提供商向更复杂的复合性问题提供集成解决方案。行业近期的产品迭代与技术 acquisitions 都指向同一个方向:通过增强材料耐久性与施工灵活性,来应对老化管网中多样化的缺陷形态。
PW Consulting
政策与监管环境构成了另一个强有力的驱动力。各国政府针对污水系统溢流控制与处理标准的要求正在收紧,促使市政当局将更多资源投入到预防性修复中。美国相关环境机构推行的溢流管理计划要求数千个许可系统制定明确的减排路径,而欧洲针对城镇污水处理的指令也设定了分阶段达标的时间表。这些法规框架实质上为修复服务创造了长期需求锚点,使得项目规划从临时应急转向可预见的资产管理节奏。与此同时,基础设施投资计划的落地为大中型修复工程提供了必要的资金支持,进一步加速了需求释放的节奏。
需求侧的变化同样值得关注。市政部门作为服务的主要终端,正越来越倾向于长期运维合作模式,而非一次性的维修采购。这种趋势反映在合同结构与服务范围的扩展上,客户希望通过整合 inspection、清洁与修复环节来降低全生命周期成本。住宅与商业领域虽然在整体规模上相对较小,但对快速响应与最小化业务中断的要求推动了轻量化修复方案的普及。供应链与成本结构的变化也在这一过程中发挥作用,材料供应的波动与现场人力成本的上升促使企业重新评估技术路线,以降低对高强度人工的依赖。
竞争格局与领先策略
当前的市场参与者呈现出多元化的战略定位。一些企业专注于特定技术路线的研发与应用,通过提供高性能衬里系统与定制化修复设备,深耕于特定类型的管网缺陷修复。另一些参与者则依托全球运营网络,将污水修复纳入更广泛的城市基础设施服务体系中,利用规模化运营与长期合同积累来增强客户黏性。这两类路径虽然侧重点不同,但都体现了对技术可靠性与服务可扩展性的共同追求。
领先者的差异化优势往往体现在技术响应速度与项目执行能力的结合上。例如,部分企业通过收购扩展了其技术组合与市场覆盖能力,使得原本局限于特定区域或特定工艺的服务能够向更大范围的综合修复方案延伸。还有企业通过产品升级强化了材料在恶劣工况下的适用性,从而打开了工业用水系统等更高要求的应用场景。合同制的长期合作模式也成为一些大型服务提供商的重要策略,他们通过在重大城市项目中的持续投入,建立起基于绩效与可靠性的品牌信任。
市场格局的演变趋势显示出整合与专业化并存的特征。资本活动与技术并购正在推动部分企业扩大其服务范围,以应对客户对一站式解决方案的需求增长。同时,细分领域的创新公司继续在特定技术点上取得突破,为更复杂的修复需求提供了新的工具。对于新进入者而言,单纯依靠价格竞争已难以维持优势,技术适配能力、区域网络布局以及对监管变化的快速响应,正在成为决定竞争成败的关键变量。
未来趋势预测
未来三到五年内,污水修复服务市场将进一步向高效化与集成化方向演进。技术层面的一个关键趋势是修复手段与数字化管理工具的结合加深。通过更精准的缺陷检测与状态评估,服务提供方能够更合理地匹配修复技术与材料,减少不必要的资源消耗。这一趋势将推动行业从经验驱动向数据驱动的决策模式过渡,企业若能在这一环节建立起技术优势,将在项目定级与方案设计中占据更有利的位置。
另一个值得关注的趋势是监管导向与资金流向的持续强化。随着更多国家将污水系统的溢流控制与升级纳入基础设施优先事项,市场需求将在中短期内保持稳定增长。对于服务提供商而言,这意味着长期合同与系统性维护项目的比重将进一步提高,依赖零星修单的商业模式面临一定的边缘化风险。同时,资金集中于大型市政项目也可能导致中小型企业在项目获取上需要更多依赖区域合作网络或细分技术优势。
商业机会的分布将更加依赖于技术适配与服务深度。能够在复杂管网条件下提供可靠修复的企业,以及能够将修复服务与运维管理相结合的参与者,将更易获得市政客户的青睐。然而,市场增长也伴随着不确定性,包括建设成本波动、劳动力供给约束以及区域政策节奏的差异,都可能影响项目的实施节奏与利润空间。企业需要在扩大服务覆盖的同时,保留对成本结构与技术路线的灵活调整能力。
Sewer Cameras Market
决策者行动建议
对于技术制造商与服务提供商而言,应将重点放在能够应对复杂管网缺陷的产品与工艺升级上。强化材料耐久性、施工适应性与快速部署能力,有助于在竞争加剧的环境中抢占更多样化的项目机会。同时,建立与 detection 与评估环节的协同能力,可以提升方案设计的精准度,从而增强客户对整体服务价值的认可。
对于投资者,市场的增长潜力与整合机会并存,但选择标的时需关注企业的技术壁垒与区域执行能力。那些能够将特定技术优势转化为可复制的服务模式,并在监管与资金流向明确的区域建立稳固业务的企业,往往具备更好的成长可持续性。
对于市政采购方与商业用户,制定长期的管网资产管理计划将比单纯的应急修复更具成本效益。通过结合预防性维护与适当的修复技术选择,可以在降低服务中断风险的同时,优化全生命周期的支出结构。及时获取细分市场的技术趋势与区域需求演变信息,有助于在规划与采购决策中把握更合适的时机与方案。
For detailed analysis of this topic, please visit the official page: Worldwide Sewer Repair Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fully Automatic Roll Feeding Paper Bag Making Machine Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-18
Fully Automatic Roll Feeding Paper Bag Making Machine Market
Overview
The Fully Automatic Roll Feeding Paper Bag Making Machine Market encompasses advanced machinery designed for efficient production of paper bags through automated processes. These machines are integral to modern packaging industries, enabling high-speed, precise manufacturing of various paper bag styles with minimal manual intervention. Their core functionalities include roll feeding, cutting, folding, and sealing, supporting industries that demand eco-friendly and customizable packaging solutions. By automating these processes, the market plays a vital role in enhancing productivity and reducing operational costs.
The market for fully automatic roll feeding paper bag making machines is a critical component within the packaging machinery sector. Its importance lies in facilitating sustainable packaging practices and meeting increasing consumer demand for eco-conscious products. The Fully Automatic Roll Feeding Paper Bag Making Machine Market is positioned to support technological innovation and industrial growth, making it a strategic asset for large-scale manufacturers and small enterprises alike.
Market Size and Growth
The current market value for the Fully Automatic Roll Feeding Paper Bag Making Machine Market is estimated to be around USD 1.2 billion. Over the next decade, it is projected to reach approximately USD 2.8 billion, reflecting a compound annual growth rate (CAGR) of about 8%. Growth drivers include rising environmental awareness, increasing adoption of paper-based packaging, and technological advancements in automation. Additionally, expanding e-commerce and retail sectors are fueling demand for efficient, large-volume production equipment.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2212
Key Drivers
- Growing demand for eco-friendly packaging solutions
- Rising automation in manufacturing processes
- Expansion of e-commerce and retail sectors
- Increasing regulatory focus on sustainable packaging
- Technological innovations enhancing efficiency and versatility
Restraints
- High initial investment costs for advanced machinery
- Technical complexity requiring skilled operators
- Stringent regulatory standards impacting design and materials
- Maintenance and operational costs impacting ROI
- Technical limitations in handling diverse paper types
Segmentation
• By Type: Flat Bag, Satchel Bag, T-shirt Bag, Others
• By Deployment: Fully Automatic, Semi-Automatic
• By Enterprise Size: Small, Medium, Large
• By End User: Packaging Companies, Retailers, E-commerce, Food & Beverage
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market benefits from advanced manufacturing infrastructure and rising eco-consciousness, promoting adoption of automated paper bag machinery. Europe exhibits steady growth driven by strict environmental regulations and a focus on sustainable packaging. Asia-Pacific is the largest and fastest-growing region, with expanding manufacturing hubs, increasing industrialization, and a shift towards eco-friendly packaging solutions. Latin America shows moderate growth, mainly driven by retail expansion, while the Middle East & Africa are gradually adopting automation for packaging needs amidst infrastructural development.
Opportunities
- Expansion in emerging markets with increasing industrialization
- Integration of IoT and smart automation technologies
- Development of lightweight, multi-functional machinery
- Adoption of biodegradable and recycled paper materials
- Growing demand in food packaging and e-commerce sectors
Key Companies
Bobst Group, Fosber Group, Jiangsu Boxin Machinery Co., Ltd., Jinan Yiheng Machinery Co., Ltd., Tishma Technologies, Heben Packaging Machinery, Yongli Machinery, Baosuo Machinery, Zhejiang Yuhuan Machinery, Shenzhen Yuhong Machinery Co., Ltd., Zhejiang Rifa Machinery Co., Ltd.
Conclusion
The overall outlook for the Fully Automatic Roll Feeding Paper Bag Making Machine Market remains positive, supported by increasing demand for sustainable packaging and automation. Long-term growth potential is significant as industries continue to prioritize efficiency and eco-friendly solutions. The market’s strategic importance lies in its capacity to drive industrial innovation and meet evolving regulatory and consumer expectations, making it a critical segment within the packaging machinery landscape.
Related Reports
Real Leather Embossing Machine Market , Size Share and Analysis | Report 2033
Fuel Greenhouse Heater Market , Size Share and Analysis | Report 2033
Adjustable Height Portable Stages Market , Size Share and Analysis | Report 2033
Plastic Bottle Recycling Machines Market , Size Share and Analysis | Report 2033
Brazing Torch Market , Size Share and Analysis | Report 2033
Belt Bucket Elevator Market , Size Share and Analysis | Report 2033
Small Portable Stage Market , Size Share and Analysis | Report 2033
Painting And Spraying Collaborative Robots Market , Size Share and Analysis | Report 2033
Coil Wound Heat Exchangers Market , Size Share and Analysis | Report 2033
Sulphur Granulation System Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Microbolometer IR Detector Market: Why 8.5% CAGR and Asia Pacific's Rise Redefine Growth
By PW Consulting, 2026-09-18
Unlocking Strategic Value in the Global Microbolometer Infrared Detector Market
Market Overview and Core Challenges
The worldwide market for microbolometer infrared detectors has entered a phase of robust expansion, driven by the growing integration of thermal imaging capabilities across diverse industrial and consumer sectors. Valued at approximately 815.2 million USD in the base year of 2025, the market has demonstrated consistent growth from its 2020 baseline of 542.15 million USD. Projections indicate a steady compound annual growth rate of 8.51 percent through the forecast period extending to 2032, signaling a market trajectory that favors sustained investment and technological maturation. This growth is not merely linear but reflects a deepening adoption curve where thermal sensing is transitioning from specialized defense and industrial applications toward broader commercial and consumer integrations.
Despite the positive revenue momentum, the industry faces significant structural headwinds that require strategic navigation. One primary challenge involves the regulatory environment surrounding technology transfer and export controls. Restrictions on high-performance detector modules, particularly those exceeding specific resolution or sensitivity thresholds, create complexity for global supply chains and limit market access for certain regions. Companies must balance compliance with the need to serve international customers, often requiring sophisticated legal and operational frameworks to manage technology flow without stifling growth.
PW Consulting
Supply chain vulnerability represents another critical pivot point. The production of Vanadium Oxide thin films, a dominant material type in detector manufacturing, relies on refining capacity that is geographically concentrated. This concentration introduces risk regarding raw material availability and pricing stability, potentially impacting production schedules and cost structures for downstream manufacturers. Diversification of material sourcing or investment in alternative material technologies becomes a strategic imperative to mitigate these exposure risks.
Furthermore, the market exhibits a moderate level of concentration, with a significant portion of revenue controlled by a limited number of key players. This landscape suggests that while entry barriers exist due to technology expertise and certification requirements, there is room for disruption through cost innovation or niche specialization. New entrants focusing on specific application verticals or cost-reduced architectures may find opportunities to capture share from established incumbents, particularly in price-sensitive segments where performance requirements are evolving rapidly.
Key Drivers of Market Growth
Technological innovation remains the most potent catalyst for market expansion within the microbolometer sector. Advances in pixel pitch reduction and noise-equivalent temperature difference (NETD) improvements are enabling detectors to become smaller, lighter, and more sensitive. For instance, recent developments have showcased modules with 12µm pixel pitches, allowing for higher resolution imaging in compact form factors suitable for next-generation security cameras and handheld devices. Simultaneously, improvements in thermal sensitivity, such as achieving NETD values below 40mK, enhance the reliability of detection in challenging environmental conditions. These technical breakthroughs expand the viable use cases, making thermal imaging viable for applications where size, weight, and power (SWaP) constraints were previously prohibitive.
Worldwide Infrared Focal Plane Detector Market
Policy and regulatory frameworks are also shaping demand dynamics, albeit in a dualistic manner. While export controls impose restrictions on high-end components, government initiatives aimed at bolstering domestic manufacturing and supply chain resilience are stimulating local production capabilities. Investments in semiconductor fabrication infrastructure, supported by legislative acts in major economies, encourage the development of domestic sensor production. This shift aims to reduce reliance on imported components for critical security and defense systems, driving demand for locally sourced microbolometer arrays and fostering a competitive environment among regional manufacturers seeking to qualify for government contracts.
On the demand side, there is a marked shift in consumer and enterprise behavior toward integrated sensing solutions. In the security and surveillance sector, the integration of thermal sensors into standard video surveillance systems is becoming more common to enhance threat detection capabilities regardless of lighting conditions. Similarly, the automotive industry is increasingly exploring thermal imaging as a complement to existing autonomous driving sensors. The ability of infrared detectors to identify pedestrians, animals, and obstacles in low-visibility scenarios offers a unique value proposition that addresses safety gaps in current Advanced Driver Assistance Systems (ADAS). This functional differentiation drives OEMs to evaluate thermal modules as a necessary addition to vehicle sensor suites.
Cost structure changes are further accelerating adoption. As manufacturing scales up, particularly in Asian production hubs, the average price of standard resolution detector cores has seen downward pressure. Reductions in unit costs make thermal technology accessible to a broader range of applications, including consumer electronics and cost-sensitive industrial monitoring. This democratization of technology allows smaller enterprises and new market segments to incorporate thermal sensing into their products, expanding the total addressable market beyond traditional high-budget sectors. However, manufacturers must balance cost reduction with performance consistency to maintain trust in critical applications where detection reliability is paramount.
Competitive Landscape and Leading Strategies
The competitive environment for microbolometer infrared detectors is characterized by a mix of established defense contractors, specialized sensor manufacturers, and integrators leveraging in-house capabilities. Companies such as Teledyne FLIR and Raytheon Technologies hold significant positions due to their deep expertise in uncooled infrared technology and strong relationships with government and industrial clients. Teledyne FLIR, for example, has focused on expanding its portfolio of small thermal cores for IoT and commercial sensing, exemplified by recent releases of modules with enhanced radiometry features. This strategy targets the growing need for distributed sensing in smart infrastructure and remote monitoring applications.
Defense-oriented firms like Lockheed Martin and BAE Systems continue to prioritize high-performance focal plane arrays for aerospace and night vision systems. Their strategic advantage lies in the ability to meet rigorous military specifications and integrate detectors into complex platforms. These players often benefit from long-term procurement contracts and the ability to customize solutions for specific mission requirements. Conversely, companies like ULIS (Lynred) have carved out a strong niche in high-volume production of Vanadium Oxide and amorphous silicon arrays, serving OEM customers who require cost-effective thermal cores for integration into their own product lines. Recent launches of detectors with improved sensitivity for low-SWaP applications highlight their focus on enabling compact commercial solutions.
In the commercial and security segment, players such as Guide Sensmart and Hikvision are driving adoption through aggressive product integration and cost competitiveness. Guide Sensmart has demonstrated next-generation pixel architectures at major industry exhibitions, signaling a focus on miniaturization for security cameras. Hikvision integrates proprietary sensors into thermal security and fire detection products, leveraging its massive distribution network to deploy thermal solutions in civilian safety applications. This approach contrasts with the component-focused strategy of pure-play detector manufacturers, as these integrators control both the sensor and the end-user system, allowing for optimized performance tuning and faster time-to-market.
The market landscape is evolving through both consolidation and fragmentation. On one hand, larger entities may seek to acquire specialized technology firms to broaden their IP portfolios or gain access to specific material technologies. On the other hand, the influx of new entrants offering differentiated features, such as ultra-low pixel pitches or specialized packaging, creates a fragmented environment in niche segments. Distributors like Boston Electronics play a crucial role in this ecosystem by providing access to a variety of global manufacturers, enabling research institutions and industrial users to source detectors without committing to large-scale production contracts. Excelitas Technologies further supports this by providing modular solutions for medical and industrial OEM integration, emphasizing flexibility and customization. The interplay between these strategies suggests a market where partnerships and supply chain agility will be as critical as raw technological performance in determining market share.
Future Trends and Commercial Opportunities
Looking ahead, the convergence of thermal imaging with artificial intelligence and edge computing emerges as a defining trend for the next three to five years. Detectors will increasingly be paired with onboard processing capabilities to analyze thermal signatures in real-time, reducing the need for constant data transmission to central servers. This shift enables smarter security systems that can distinguish between false alarms and genuine threats autonomously, as well as industrial inspection tools that can detect anomalies immediately. The commercial opportunity lies in developing software-enabled hardware solutions that offer value-added services, moving beyond selling raw sensor components to providing integrated detection platforms.
Another significant trend is the expansion of thermal sensing into consumer health and wellness applications. As the technology becomes more affordable and compact, opportunities arise for non-contact temperature screening and remote health monitoring devices. The pandemic accelerated interest in such tools, and sustained demand for home health monitoring could drive a new wave of consumer electronics incorporating microbolometer arrays. Manufacturers who can optimize sensors for low-power consumption and ease of integration into wearable or handheld consumer devices may capture emerging revenue streams. However, this expansion requires navigating varying regulatory standards for medical devices across different regions, which could slow adoption in certain markets.
Despite the positive outlook, uncertainty remains regarding material supply chains and geopolitical trade dynamics. The reliance on specific raw materials like vanadium, with refining capacity concentrated in limited regions, poses a risk of supply disruption or cost volatility. Additionally, ongoing export controls and trade restrictions could fragment the global market, forcing companies to maintain separate product lines or manufacturing sites to comply with regional regulations. Firms that proactively diversify their material sourcing or invest in alternative detector materials will be better positioned to manage these risks. Similarly, companies with a flexible manufacturing footprint that can adapt to shifting trade policies will likely maintain a competitive edge over those heavily reliant on single-region production for global distribution.
Strategic Recommendations for Decision Makers
For manufacturers operating in this space, prioritizing supply chain resilience is essential. Diversifying raw material sources or investing in recycling and recovery processes for critical elements can mitigate the risk of geopolitical or logistical disruptions. Additionally, focusing on value-added features, such as integrated processing or modular designs, can help differentiate products in a market where commoditization pressures are increasing. Collaborating with system integrators to co-develop solutions tailored to specific verticals may also unlock higher margins compared to selling standalone components.
Infrared Detector Market
Investors should look closely at companies demonstrating capabilities in scaling production while maintaining performance standards. The downward trend in component pricing suggests that volume growth will be a key driver of revenue, favoring players with efficient manufacturing processes and strong demand partnerships. Monitoring developments in material science, particularly alternatives to Vanadium Oxide, could also reveal long-term investment opportunities in firms that secure intellectual property around next-generation detector technologies. Assessing a company's compliance infrastructure regarding export controls is equally important, as regulatory missteps could severely impact international revenue streams.
Procurement teams and system integrators must balance cost considerations with performance requirements carefully. As detector prices decline, there is temptation to opt for lower-cost options, but ensuring reliability in critical applications remains paramount. Evaluating suppliers based on their ability to provide consistent quality, technical support, and supply continuity should outweigh short-term price advantages. Engaging with multiple suppliers to ensure redundancy and comparing total cost of ownership, including integration complexity and lifecycle support, will lead to more robust sourcing strategies. Access to detailed segmentation data and customized market intelligence can further refine these decisions, allowing stakeholders to align procurement strategies with specific project timelines and performance goals.
For detailed analysis of this topic, please visit the official page: Worldwide Microbolometer Infrared Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market: Strategic Trends and Commercial Opportunities
Market Landscape and Critical Challenges
The global market for vanadium pentoxide (V2O5) serving electrolyte applications in vanadium redox flow batteries (VRFBs) has transitioned from a niche materials segment to a structurally significant pillar of grid-scale energy storage. Valuation data from 2020 through 2025 shows a compounding growth trajectory that moved from approximately $345 million in 2020 to roughly $893 million in 2025. The forward path extends through 2032, with market size projected to reach nearly $3.5 billion by the end of the forecast period. This expansion reflects a compound annual growth rate of 21.45%, positioning the sector among the faster-scaling chemical supply chains tied to clean energy infrastructure.
Such velocity is not merely a function of incremental demand; it signals a structural realignment in how long-duration storage is sourced, financed, and deployed. Yet the same forces that accelerate revenue creation also introduce friction. The market currently navigates three interconnected challenges that will define competitive outcomes over the next several years.
First, purity standardization remains fragmented across procurement channels. While certain grades of vanadium pentoxide meet commercial specifications for electrolyte synthesis, the absence of universally harmonized quality benchmarks creates variability in downstream performance, testing costs, and supplier qualification cycles. Buyers often face trade-offs between cost efficiency and electrochemical consistency, particularly when integrating electrolyte into larger battery systems that require multi-year operational guarantees.
Second, pricing volatility in the upstream feedstock cycle interferes with capacity planning and margin stability. Input costs for vanadium pentoxide are influenced by ore processing economics, by-product recovery from steel and refinery streams, and shifting trade dynamics. When feedstock prices compress, producers may delay capital deployment or scale utilization unevenly. Conversely, when pricing rebounds, customers weigh inventory strategies against long-term offtake commitments, squeezing the predictability that large storage developers require for project financing.
Third, the relationship between raw material supply and specialized electrolyte manufacturing is tightening, but not uniformly. Capacity expansions in electrolyte synthesis are outpacing in some regions while lagging in others, depending on permitting timelines, access to high-purity intermediates, and available offtake structures. This unevenness can create bottlenecks for project developers who must synchronize battery equipment delivery, electrolyte supply, and commissioning schedules.
Key Drivers of Market Momentum
The decisive forces shaping this market operate across technology, policy, demand behavior, and supply chain architecture. Their convergence explains why the segment is expanding at a pace that traditional chemical markets rarely achieve.
Technical Pathways in Purity, Electrolyte Architecture, and Recycling
The industry is moving beyond treating vanadium pentoxide as a commodity input and toward engineering it as a performance-critical component of the electrolyte system. High-purity grades are gaining preference in applications where cycle life, ion stability, and contamination control directly influence total cost of ownership. At the same time, technological efforts are broadening the range of acceptable feedstocks by improving purification processes. This matters because it creates a route to lower-cost inputs without sacrificing electrolyte quality, providing flexibility in a market where upstream availability can vary by region and trade condition.
A parallel trend is the growing emphasis on electrolyte recycling and closed-loop stewardship. As deployed VRFB systems age, reclaiming vanadium from used electrolytes offers a supplementary supply channel and supports long-term sustainability narratives. The commercial relevance lies in reducing dependency on virgin material cycles and improving project economics for operators who plan for multi-decade asset life.
Policy, Incentives, and Standards Development
Electrolyte demand is heavily conditioned by how storage is treated within energy policy and procurement frameworks. In multiple jurisdictions, long-duration storage is increasingly viewed as a complement to intermittent renewable generation, prompting incentive structures, capacity mechanisms, and procurement rules that favor technologies capable of extended discharge and repeated cycling. Vanadium-based storage fits that profile, and policy architecture that rewards duration, reliability, and domestic manufacturing can disproportionately benefit electrolyte supply chains.
At the same time, standards activity is intensifying. Ongoing work under international standardization bodies to align quality control requirements for VRFB electrolyte is significant because consistent specifications lower transaction risk, simplify supplier qualification, and enable larger-scale procurement. Where standards remain uneven, project developers may encounter additional testing, acceptance criteria, and documentation burdens that slow deployment. Harmonization would not only reduce friction; it would also raise the addressable market for suppliers capable of demonstrating repeatable purity and process control.
Demand-Side Shift Toward Utility-Scale and Long-Duration Storage
The demand narrative has shifted from experimental pilots to bankable utility programs and commercial-industrial deployments. Large storage projects are driven by grid stability requirements, renewable integration targets, and the economic need to shift or firm generation over longer durations. These applications create a procurement profile that values predictable performance and long service life more than short-term price minimization. That inclination favors electrolyte suppliers that can provide traceability, consistent specifications, and contractual structures aligned with project finance timelines.
Commercial and industrial storage adds another layer of demand diversity. Facilities seeking resilience, tariff optimization, and sustainability goals are evaluating storage options that can operate with minimal degradation over many cycles. This expands the addressable base beyond purely utility-driven procurement and encourages a broader ecosystem of equipment integrators, developers, and end users to engage with vanadium electrolyte supply.
Supply Chain Reconfiguration and Cost Dynamics
Supply chain strategy is becoming as important as raw material pricing. The upstream picture is shaped by primary mining outputs, by-product recovery from oil refining residues and spent catalysts, and titanomagnetite processing routes. When utilization rates are depressed, pricing may soften, but such periods can also set the stage for later tightening as demand absorption increases. Producers and electrolyte manufacturers are responding by aligning capacity investments with secured offtake, regionalizing supply where policy incentives support domestic production, and building processing flexibility that can accommodate feedstock variability.
Cost structures are also influenced by tariff and trade conditions. Import duties and temporary tariff adjustments can alter sourcing decisions, especially for specialized high-purity material. In markets where trade policy changes quickly, buyers and suppliers must consider not only baseline pricing but also the durability of sourcing arrangements under shifting customs frameworks. This adds a strategic layer to procurement: cost optimization must be weighed against supply continuity and regulatory predictability.
Competition Dynamics and Leading Strategies
The competitive field combines established vanadium producers, dedicated electrolyte manufacturers, and vertically integrated players that operate across the value chain. Differentiation increasingly depends on purity control, processing flexibility, regional supply strategy, and the ability to offer commercial models that align with customer risk preferences.
U.S. Vanadium LLC has positioned itself around high-purity vanadium pentoxide and ultra-high-purity electrolyte production, with capacity scale that supports large-volume electrolyte output. Its recent expansion into high-purity flake production highlights a strategy of broadening specialty vanadium chemical offerings while reinforcing the base needed for battery-grade materials. Support from defense-related logistics funding suggests an additional avenue of institutional alignment that can strengthen manufacturing resilience and supply assurance.
PW Consulting
Storion Energy operates with a distinct lens on domestic electrolyte production and feedstock adaptability. By converting mined and recycled vanadium oxides into high-quality electrolyte and partnering with Largo for supply, it illustrates how purification technology can unlock lower-purity feedstocks without compromising output quality. This approach is commercially relevant because it creates optionality in a supply-constrained environment and can improve margin resilience when primary material economics fluctuate.
Largo Inc. represents the upstream-to-downstream integration model. Through primary vanadium production and its joint venture activities in electrolyte supply, it connects mine output with downstream electrolyte delivery and leasing-oriented commercial structures. The relevance of this model lies in the way it links raw material availability with customer-facing supply arrangements, which can reduce uncertainty for buyers who want more structured access to electrolyte over time.
In China, multiple producers are expanding capacity and linking high-purity V2O5 output with electrolyte operations. LB Group’s commissioning of a large-scale electrolyte facility integrated with high-purity vanadium pentoxide output reflects the continuing scale-up of regional supply aligned with energy storage demand. Other Chinese manufacturers focused on high-purity vanadium pentoxide are strengthening the breadth of available supply for electrolyte applications, reinforcing the region’s role as a significant production center.
European and other international participants are building targeted electrolyte capacity and pursuing integrated or specialized production routes. Companies with operations aimed at European energy storage demand, as well as developers advancing vanadium resource and processing strategies, are contributing to regional diversification. This matters because geographic diversification can reduce concentration risk and offer customers more options for local supply, testing, and logistics.
Vanadium Redox Battery (VRB) Market
Several strategic patterns are becoming visible. One is the move toward vertical coordination, where producers seek to secure or control access to high-purity intermediates and electrolyte conversion capacity. Another is product differentiation through purity grades and processing sophistication rather than price alone, especially as utility-scale buyers place greater weight on reliability and documentation. A third is commercial model innovation, including leasing and structured supply arrangements that can make electrolyte access more predictable for storage developers.
The market is also likely to see a blend of consolidation and fragmentation. Larger integrated players may pursue partnerships, offtake alignment, or selective acquisitions to strengthen supply continuity. Simultaneously, smaller or specialized producers can compete by serving niche purity requirements, regional demand pockets, or flexible feedstock strategies. New entrants will need to demonstrate more than capacity; they will need to prove quality consistency, qualification speed, and commercial terms that fit long-duration storage project economics.
Outlook for the Next Three to Five Years
Three trends are likely to shape the market trajectory through the end of the decade. The first is a continued shift in buyer preference toward high-purity, specification-controlled electrolyte supply. As more large storage projects move from planning to commissioning, qualification cycles will increasingly reward suppliers that can demonstrate process stability, traceability, and repeatable purity levels. This should reinforce the premium associated with grades that can meet stringent application requirements and broaden the opportunity for producers that invest in quality assurance as a competitive asset.
The second trend is capacity expansion becoming more targeted and regionally differentiated. Rather than uniform global scale-up, capacity growth will likely concentrate where demand visibility, policy support, and feedstock access converge. That concentration can create pockets of strong supply availability alongside areas where buyers face longer lead times or higher logistics complexity. For companies planning participation, the strategic task is to match supply expansion with credible offtake or contractual structures that reduce exposure to demand timing risk.
The third trend is price and supply cycle recalibration. After periods of depressed utilization and softer pricing, market conditions are projected to tighten as electrolyte demand accelerates and supply remains constrained in certain channels. If this unfolds, producers with secured intermediate supply, flexible processing, and strong customer relationships will be better positioned to capture value. Buyers, meanwhile, may need to balance spot purchasing with longer-term arrangements to protect project schedules and cost predictability.
Opportunities will be strongest for participants who can connect material quality with commercial reliability. That includes electrolyte manufacturers able to integrate multiple feedstock routes, producers with clear paths to high-purity output, and suppliers offering structured supply or leasing models that reduce upfront uncertainty for storage developers. The main uncertainty lies in the pace and uniformity of standards adoption, the durability of trade and tariff conditions, and the timing of demand absorption relative to new capacity coming online. A market can expand rapidly and still experience local imbalances if procurement, permitting, and production do not stay synchronized.
Strategic Implications for Decision-Makers
For manufacturers and producers, the priority is to convert capacity expansion into competitive advantage through purity control, feedstock flexibility, and qualification readiness. Expanding volume alone is unlikely to secure durable positioning if customers cannot easily validate quality or rely on supply consistency. Investments in process robustness, documentation, and downstream compatibility testing can shorten deployment timelines and improve long-term contract attractiveness.
For investors, the most relevant question is whether a company’s strategy is aligned with the demands of long-duration storage procurement. That means evaluating not only production scale but also offtake visibility, integration depth, regional exposure, and the ability to navigate trade or feedstock volatility. Business models that tie electrolyte supply to structured commercial terms may offer more predictable revenue characteristics than volume-only plays in a market still defining its demand rhythm.
For procurement and project developers, the practical focus should be on minimizing qualification uncertainty while protecting supply continuity. Diversifying supplier options, setting clear purity and testing expectations early, and considering longer-duration supply arrangements can reduce the risk of delays or cost surprises during project execution. In a market where demand is scaling quickly, early alignment with credible suppliers can matter as much as price negotiation.
Detailed segmentation data, company-level assessments, purity-grade dynamics, regional supply patterns, and commercial-model comparisons can help decision-makers narrow options and prioritize engagement. Access to granular research supports faster qualification decisions, sharper supply strategy design, and more informed capital allocation in a market where timing and specification alignment increasingly determine outcomes. Readers seeking a fuller breakdown of sub-segments, competitive positioning, and forward scenarios can explore the complete PW Consulting report for deeper data and tailored guidance.
Ion Exchange Membrane of All-Vanadium Redox Flow Battery Market
For detailed analysis of this topic, please visit the official page: Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global TIG Welding Machines Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-18
The global TIG welding machines market is projected to grow steadily from 2020 to 2035. In 2025, the market is estimated at USD 3,240 Million, rising consistently at a CAGR of 6.8%. By 2030, revenue is expected to reach USD 4,510 Million, while the market will touch USD 6,350 Million by 2035. The surge is attributed to technological advances, expanding end-use sectors, and increasing adoption of high-precision welding solutions around the world. Significant contributions from APAC and North America fuel incremental gains, supported by strong investments in manufacturing and infrastructure.
Read More - https://bussinessinsights.com/research-report/global-tig-welding-machines
The automotive sector commands the largest application share of TIG welding machines in 2025, utilizing precision welding for both ICE and electric vehicle components. Aerospace is the second largest, propelled by the need for defect-free, high-strength welds. Construction and shipbuilding sectors are witnessing increased adoption for structural and fabrication projects, while manufacturing and maintenance & repair gradually grow as automation trends intensify. The continuous innovation in TIG welders with smart features is enabling deeper market penetration across diverse industrial applications.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tig-welding-machines
Frequently Asked Questions
Who are the key players in Global TIG Welding Machines industry?
The top 5 players in the Global TIG Welding Machines industry are Lincoln Electric, ESAB, Miller Electric, Panasonic Welding Systems, and Fronius International. These companies are recognized for their innovation, extensive product offerings, global distribution networks, and commitment to improved welding technology for industrial and commercial applications.
What is the Global TIG Welding Machines growth?
The Global TIG Welding Machines market has shown solid growth, driven by increasing demand in automotive and infrastructure. For example, in 2023, ESAB reported significant revenue increase attributed to expansion in emerging markets and growing adoption of automated TIG welding solutions.
Which segment accounted for the largest Global TIG Welding Machines share?
The automotive and transportation segment accounted for the largest share of the Global TIG Welding Machines market, owing to the need for precision welding in automobile manufacturing and repair. The growing focus on lightweight vehicle parts and electric vehicles further fuels market demand in this segment.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Mountain Protection Net Market: Why 6.4% CAGR Through 2032 Signals Strategic Shifts in Global Safety Infrastructure
By PW Consulting, 2026-09-18
Navigating the Worldwide Mountain Protection Net Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The worldwide mountain protection net market has established itself as a critical infrastructure component, reflecting the growing intersection of safety, engineering, and environmental resilience. From 2020 to 2025, the market expanded from 480.15 million USD to 652.48 million USD, demonstrating sustained growth even amid broader economic uncertainties. This trajectory underscores a fundamental shift: mountain protection systems are no longer peripheral safety add-ons but integral elements of infrastructure planning across transportation, mining, and energy sectors. The forward-looking period from 2026 to 2032 projects continued expansion, with revenues anticipated to reach 1008.64 million USD by 2032. This corresponds to a compound annual growth rate of 6.42 percent, signaling steady, compounding demand rather than speculative growth.
Several structural forces define this market. Demand is distributed across transportation infrastructure, mining operations, hydropower and utilities, and residential and urban development, each with distinct risk profiles and procurement cycles. Regionally, activity spans Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, reflecting both developed-market infrastructure maintenance and emerging-market construction surges. The active protection net segment commands the larger share of revenue, while passive systems maintain significant relevance for long-term slope stabilization and lower-energy hazard zones. Market concentration remains moderate, with the top three companies accounting for 38.45 percent of revenue and the top five reaching 52.12 percent, indicating room for both established leaders and specialized challengers.
Camouflage Netting Market
Despite this growth trajectory, the industry faces three defining challenges. First, raw material volatility has introduced significant cost uncertainty. High-tensile steel wire, the core component of mountain protection nets, represents 60 to 70 percent of final product costs. During recent supply chain disruptions, steel wire prices experienced increases of 25 to 30 percent, compressing margins and forcing manufacturers and buyers to reconsider pricing models, inventory strategies, and contract structures. Second, the regulatory and certification environment continues to tighten. European guidelines such as ETAG 027, now transitioning to EAD 340059-00-0106, require rigorous full-scale testing protocols, including MEL and SEL impact tests on deformable barriers. Compliance is not optional; it is a market access requirement, and the cost of testing, certification, and documentation creates barriers for smaller players while reinforcing the position of firms with dedicated testing infrastructure. Third, the market is experiencing a geographic and application-level divergence. Infrastructure development in mountainous regions is accelerating, but so are requirements for highways, railways, and mining safety. This divergence means that standardized, off-the-shelf solutions are increasingly insufficient; buyers expect systems calibrated to site-specific geology, energy thresholds, and failure modes.
Key Drivers Shaping Market Dynamics
The market's direction is being shaped by four interconnected drivers: technological evolution, regulatory momentum, demand-side transformation, and supply chain restructuring. Each driver carries distinct implications for manufacturers, investors, and procurement teams.
Technological innovation remains the most visible catalyst. The frontier has moved beyond basic rockfall netting toward engineered, dynamically tested systems capable of absorbing extreme impact energies. Recent testing milestones illustrate this shift. In June 2025, a rockfall barrier achieved a world record by absorbing more than 12,500 kJ from a 25-ton block impacting at 115 km/h, validating the potential of flexible steel systems to handle high-energy events previously addressed only by rigid structures. Equally significant is the push toward multi-impact validation. By October 2025, multiple-impact testing on flexible rockfall protection barriers advanced, including simultaneous impacts on the ROCCO system. This matters because real-world hazard scenarios rarely involve single, isolated events; repeated impacts, progressive deformation, and cumulative fatigue increasingly define the performance expectations of engineers and insurers. In February 2026, a Ringnet-type rockfall protection barrier successfully stopped a boulder on the Basque coast, protecting traffic and demonstrating how laboratory-validated systems translate into operational resilience in live environments. These developments are not isolated technical achievements; they are reshaping procurement criteria. Buyers now ask for documented energy absorption capacity, multi-impact behavior, and field-proven reliability, which elevates the importance of testing infrastructure and certification portfolios.
Regulatory and standardization trends reinforce the technology trajectory. The continued application of ETAG 027, transitioning to EAD 340059-00-0106, anchors the European market in full-scale testing and certification expectations. The guideline requires deformable barriers to undergo MEL and SEL impact tests, creating a common benchmark for performance comparison. This standardization has two effects. First, it reduces ambiguity for cross-border procurement, enabling specifiers to compare systems against shared criteria rather than proprietary claims. Second, it raises the compliance burden, favoring companies that can invest in 1:1 scale testing facilities and maintain ongoing certification documentation. Manufacturers routinely conduct testing at sites such as the Styrian Erzberg in Austria to validate systems against rockfall energies at and beyond 12,500 kJ. This is not merely a technical exercise; it is a strategic asset that supports sales cycles, insurance negotiations, and public-sector tenders where demonstrated compliance is a prerequisite.
Demand-side behavior is evolving as infrastructure expansion intersects with risk awareness. Increasing development in mountainous regions, combined with stricter safety regulations for highways, railways, and mining, is driving demand for certified high-tensile steel mountain protection nets. This is visible in the breadth of applications: transportation corridors require systems that can protect traffic and maintain operational continuity; mining operations need mitigation for slope instability and debris movement; hydropower and utilities seek protection for assets that are both expensive and difficult to replace; and residential and urban development in hazard-prone zones increasingly demands visible, certified mitigation measures. Importantly, demand is not purely regulatory. Insurers, operators, and public agencies are increasingly treating protection systems as risk-management investments with measurable ROI in avoided downtime, reduced liability, and extended asset life. This reframing shifts the conversation from cost minimization to performance assurance, which benefits suppliers that can articulate reliability, testing evidence, and lifecycle value.
Supply chain and cost structure changes add another layer of strategic complexity. High-tensile steel wire price volatility, with increases of 25 to 30 percent during recent disruptions, has forced a re-examination of procurement timing, inventory buffers, and supplier diversification. Because steel wire constitutes 60 to 70 percent of final product costs, even modest price swings can materially affect project economics. In response, some manufacturers are adjusting contract terms, exploring forward sourcing, and emphasizing design efficiencies that reduce material intensity without compromising performance. For buyers, this environment rewards early engagement, transparent cost breakdowns, and partnerships with suppliers that can demonstrate supply continuity and stable quality. The supply chain dynamic also favors manufacturers with integrated capabilities, from wire processing to mesh fabrication to system installation support, because integration can reduce exposure to intermediate market fluctuations and improve overall lead-time predictability.
Competitive Landscape and Leading Strategies
The competitive field combines long-established European specialists with growing manufacturing capacity in Asia, creating a landscape defined by performance credibility, geographic reach, and cost positioning. The market's moderate concentration, with the top three players at 38.45 percent and the top five at 52.12 percent, suggests that leadership is earned through differentiated capabilities rather than pure scale.
PW Consulting
Several companies illustrate distinct strategic positions. Geobrugg AG, based in Romanshorn, Switzerland, has built a reputation around high-tensile steel wire mesh systems and rockfall protection nets and barriers for slope stabilization and mountain hazard mitigation. Its recent activity signals a deliberate strategy centered on testing leadership, field validation, and knowledge dissemination. The company's world record absorption of over 12,500 kJ from a 25-ton block at 115 km/h, combined with multiple-impact testing on the ROCCO system, positions it around performance documentation. Field deployment on the Basque coast and participation in GEO-Summit 2025 under the theme "From Risk to Resilience" reinforce a narrative of engineering credibility and operational resilience. The Technical Conference 2025 in Guatemala, drawing 63 engineers from multiple Latin American countries, also reflects a push into regional knowledge building and relationship development, particularly relevant where infrastructure growth and hazard exposure are both rising.
Maccaferri S.p.A., headquartered in Bologna, Italy, offers a broader system portfolio that spans rockfall protection nets, dynamic barriers, drapery systems, and Mac.RO™ solutions for active and passive mountain protection. Its strategic emphasis appears to be comprehensive application coverage and integrated slope management, appealing to specifiers who want a single supplier capable of addressing multiple hazard types and deployment configurations. Trumer Schutzbauten GmbH, based in Oberndorf, Austria, manufactures flexible rockfall protection nets, Omega-Net systems, high-tensile slope meshes, and barriers certified to ETAG 027/EAD standards. Its positioning rests on certification alignment and flexible system options, which matters in European and export markets where compliance documentation is a gating factor. Tensar International, with global operations from Atlanta, Georgia, USA, provides geosynthetic rockfall netting and slope protection systems integrated with stabilization solutions, emphasizing the combination of netting and broader slope engineering for highway and mountain applications.
On the supply and cost side, manufacturers from China are expanding their role. Hebei Xinjuyuan Protective Net Engineering Co., Ltd. and Wanzhi Steel, both based in Hebei, China, produce rockfall netting, high-tensile steel meshes, slope protection nets, galvanized and stainless steel options, and wire rope nets, with monthly output supporting global exports. Hesly Group / HeslyFence similarly produces high-tensile steel wire mesh and rockfall protection nets for slope and mountain applications. These players contribute scale, cost flexibility, and export capacity, which can be attractive for large-volume projects and price-sensitive markets. At the same time, their competitive challenge lies in matching the testing documentation, certification alignment, and field-validation narratives that increasingly guide specification in regulated markets. Other notable participants, including RUD Ketten Rieger & Dietz GmbH u. Co. KG in Germany, Pfeifer Isofer AG in Switzerland, Maeda Kosen Co., Ltd. in Japan, and Geoquest, part of the Reinforced Earth Group with a global footprint from France, add further specialization. RUD focuses on components and systems for heavy-duty mountain applications; Pfeifer Isofer supplies rockfall protection netting and related steel wire systems; Maeda Kosen manufactures high-tensile rockfall protection nets and geosynthetic solutions for natural hazard mitigation; and Geoquest engineers rockfall protection nets, drapery systems, and combined soil nailing solutions for mountain slope stabilization. This breadth indicates a market where differentiation can come from components, integrated systems, geosynthetic combinations, or regional service networks.
The competitive evolution points toward both consolidation and segmentation. Consolidation is plausible among players seeking to combine testing infrastructure, geographic sales coverage, and installation capability into more complete value propositions. Segmentation is equally likely, as different applications and regions prioritize different attributes: some buyers emphasize certified energy absorption and multi-impact performance; others prioritize cost, lead time, or local support. New entrants are most likely to succeed by targeting a specific niche—such as a particular energy class, a regional compliance framework, or an integrated geosynthetic-plus-netting solution—rather than competing broadly on price alone. For decision-makers, the practical implication is that supplier selection should align with project risk profile, certification requirements, and total lifecycle cost rather than headline unit price.
Future Trends and Strategic Implications
Looking ahead three to five years, three trends appear especially consequential. The first is the normalization of extreme-energy, multi-impact validation as a procurement baseline. The June 2025 record absorption of over 12,500 kJ and the October 2025 multiple-impact testing milestone are early indicators of a broader shift. As more systems are tested and documented against these more demanding scenarios, specification language will increasingly reference energy classes, deformation behavior, and cumulative impact performance. Commercial opportunity lies with suppliers that can provide transparent, comparable evidence across these dimensions, and with buyers who use such evidence to right-size solutions rather than over-specify or under-protect.
The second trend is geographic demand migration combined with regional compliance differentiation. Infrastructure development in mountainous regions is expanding, and stricter safety regulations for highways, railways, and mining are amplifying demand for certified high-tensile steel mountain protection nets. Yet compliance expectations differ by market. European projects will continue to be shaped by EAD-aligned testing and certification; other regions may adopt their own acceptance criteria or rely on international benchmarks. The practical outcome is a market where global manufacturers must manage a portfolio of region-specific documentation, testing arrangements, and support capabilities, while buyers benefit from clearer comparative frameworks when they exist.
The third trend is cost and supply chain recalibration. With high-tensile steel wire representing 60 to 70 percent of final product costs and having experienced price increases of 25 to 30 percent during recent disruptions, both suppliers and buyers will increasingly value predictability. This may drive more forward sourcing, longer-term agreements, design optimization to reduce material intensity, and greater interest in suppliers with integrated manufacturing and inventory management. A related risk is that sustained input-cost pressure could push some smaller or less-integrated players out of certain segments, subtly reshaping competition over time.
Worldwide Rockfall Barrier Market
These trends carry risk as well. If steel price volatility persists, project economics and margin structures will remain unstable. If testing and certification requirements continue to expand, time-to-market and compliance costs may rise, potentially slowing entry for newer players. And if demand growth is uneven across regions and applications, companies with broad but shallow portfolios may struggle compared with those that can concentrate on high-growth, high-certification segments. The opportunity for resilient strategies lies in treating performance evidence, compliance readiness, and supply continuity as core commercial assets rather than operational details.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to convert testing and certification capability into a distinct market position. Documented energy absorption, multi-impact results, and field deployments should be organized into clear, comparable narratives that help specifiers evaluate options quickly. Where cost pressure is high, design efficiency and integrated manufacturing can protect margins without sacrificing performance. For investors, the market's 6.42 percent CAGR through 2032 suggests durable growth, but value creation will likely concentrate among companies with credible performance documentation, regional compliance readiness, and the ability to manage steel-cost volatility. Due diligence should therefore weigh testing infrastructure, certification status, and supply chain resilience alongside revenue trends. For procurement teams and project owners, the most effective approach is to define acceptance criteria early, request comparable evidence across energy classes and impact scenarios, and evaluate total lifecycle value rather than initial price alone. Early engagement with suppliers that can demonstrate both compliance and supply continuity can reduce project risk in a market where raw material volatility and certification requirements are both persistent factors.
Detailed segmentation data, company-level comparisons, and customized scenario analysis can sharpen these decisions further. For those evaluating market entry, capacity expansion, or major procurement programs, the full research report provides deeper breakdowns and tailored guidance to support more precise planning.
For detailed analysis of this topic, please visit the official page: Worldwide Mountain Protection Net Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global tire mold market revenue shows steady growth from USD 1,050 Million in 2020 to USD 1,350 Million in 2025, and is estimated to reach USD 2,180 Million by 2035. The increase is underpinned by accelerating automobile production and upgrades in mold technology. Asia Pacific leads revenue generation, thanks to expanding OEM manufacturing bases.
Read More - https://bussinessinsights.com/research-report/global-tire-mold
Passenger vehicles are the primary application segment, accounting for 48% of the tire mold market in 2025, owing to their dominant share in global vehicle production. Commercial vehicles account for 28%, driven by rising transport and logistics needs, while two-wheelers, OTR, and other specialized vehicles make up 24%. The focus remains on passenger and commercial segments as urbanization and e-commerce fuel vehicle demand globally.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tire-mold
Frequently Asked Questions
Who are the key players in Global Tire Mold industry?
The top five players in the Global Tire Mold industry are Himile Mechanical Science and Technology, Saehwa IMC, Greatoo Intelligent, Herbert Maschinenbau, and MK Technology. These leaders are known for their technological innovation, strong production capacities, and extensive international reach, supplying molds to major tire manufacturers across the globe.
What is the Global Tire Mold growth?
The Global Tire Mold market has seen robust growth, driven by rising vehicle production and technological advancement. For example, Himile Mechanical Science and Technology reported significant revenue increases in 2023 due to expanding orders and broadening international partnerships, demonstrating ongoing demand for advanced tire mold solutions.
Which segment accounted for the largest Global Tire Mold share?
The largest share of the Global Tire Mold market is held by the Passenger Car Tire Mold segment. The steady growth in passenger vehicle production, especially in emerging economies, has sustained high demand for these molds. Applications for passenger cars continue to outpace those for trucks, buses, and specialty vehicles.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global tile cutter market is set for notable revenue growth, with total market value expected to rise from $1,250 Million in 2020 to $2,900 Million by 2035. This steady increase is fueled by rising investments in smart construction tools, technological advances, and proliferation of DIY activities worldwide. Notably, the surge in urban redevelopment and infrastructure projects in Asia-Pacific and North America continues to elevate market opportunities, with compounded annual growth rate (CAGR) estimated at 6.4% across the forecast period. Increased penetration of online sales further accelerates market expansion.
Read More - https://bussinessinsights.com/research-report/global-tile-cutter
The residential segment dominates tile cutter applications in 2025, with a share of 40%, reflecting increased home improvement and renovation activity globally. Commercial applications represent 27%, as the construction of offices, hotels, and retail spaces continues apace. Industrial usage is at 13%, driven by factory and warehouse expansions. Infrastructure and renovation collectively hold 13%, with the remainder allocated to miscellaneous uses. The data underscores the predominance of home construction and upgrades as key demand drivers but suggests considerable growth potential in commercial and infrastructure segments amid urbanization and economic expansion.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-tile-cutter
Frequently Asked Questions
Who are the key players in Global Tile Cutter industry?
The top 5 players in the Global Tile Cutter industry are RUBI Tools, Sigma Tool Company, Brevetti Montolit, QEP Co., Inc., and Kaufmann. These companies lead through innovation, broad product portfolios, and global presence, catering to both professional construction markets and DIY consumers with reliable, high-quality tile cutting solutions.
What is the Global Tile Cutter growth?
The Global Tile Cutter market has experienced steady growth, driven by rising construction activity and home renovation trends. For example, RUBI Tools reported a significant sales increase in 2023 due to demand from European and North American housing sectors, reflecting a compound annual growth rate (CAGR) of around 5% in recent years.
Which segment accounted for the largest Global Tile Cutter share?
Manual tile cutters accounted for the largest market share, dominating both residential and commercial applications. Their advantages, including affordability, ease of use, and low maintenance, make them a preferred choice for tile installation. Professionals and DIY users most often select manual cutters for ceramic and porcelain tiles.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com