

Blogs
Power Trading Software Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-10-06
Power Trading Software Market
Overview
The Power Trading Software Market encompasses digital platforms designed to facilitate the buying, selling, and management of electricity and energy commodities. These solutions are essential for energy producers, utilities, and traders to optimize market operations, manage risk, and ensure regulatory compliance. Core functionalities include real-time market data analysis, price forecasting, portfolio management, and automated trading capabilities, supporting the dynamic needs of modern energy industries.
The power trading software market plays a vital role in enabling efficient energy market transactions and supporting the integration of renewable sources. As energy markets become increasingly complex, the market for Power Trading Software Market is crucial for enhancing transparency, reducing operational costs, and improving decision-making accuracy across the energy sector.
Market Size and Growth
The current value of the Power Trading Software Market is estimated at approximately USD 2.5 billion. Over the next decade, it is projected to reach around USD 7.8 billion, with a compound annual growth rate (CAGR) of roughly 11%. Growth is driven by the rising demand for digital transformation in energy trading, increased renewable energy integration, and the need for sophisticated risk management tools.
Factors such as regulatory reforms, market liberalization, and technological advancements in AI and analytics continue to propel market expansion. The increasing complexity of energy markets and the shift toward decentralized energy resources further underscore the importance of advanced trading software solutions.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1738
Key Drivers
• Growing renewable energy integration
• Increasing market deregulation and liberalization
• Rising demand for real-time data analytics
• Adoption of AI and machine learning in trading
• Digital transformation initiatives in energy companies
Restraints
• High implementation and maintenance costs
• Technical complexity and integration challenges
• Regulatory uncertainties across regions
• Data security and privacy concerns
• Limited skilled workforce for advanced software deployment
Segmentation
• By Type: Trading platforms, Risk management tools, Portfolio management systems
• By Deployment: Cloud-based, On-premises
• By Enterprise Size: Large enterprises, SMEs
• By End User: Utilities, Independent power producers, Trading firms, Market operators
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market is driven by liberalized energy markets and technological innovation, with high adoption rates among utilities and trading firms. Europe’s demand is fueled by stringent regulations and a shift toward renewable energy sources, fostering increased use of advanced trading software. The Asia-Pacific region exhibits rapid growth due to expanding energy consumption and market liberalization, particularly in China and India.
Latin America’s market is gradually emerging, with investments in digital infrastructure and renewable integration. The Middle East & Africa present opportunities driven by regional energy diversification efforts, though adoption remains relatively slow due to regulatory and infrastructural challenges.
Opportunities
• Expansion into emerging markets in Asia and Africa
• Integration of blockchain for secure transactions
• Use of AI for predictive analytics and automation
• Adoption of IoT for real-time data collection
• Development of hybrid cloud solutions for scalability
Key Companies
ABB, Schneider Electric, GE Digital, Siemens, Openlink, EKA Software Solutions, Wipro, Osisoft, ICE Data Services, SAP, IBM, Oracle
Conclusion
The Power Trading Software Market demonstrates strong long-term growth potential driven by technological advancements and evolving energy market dynamics. As industries move toward more sustainable and decentralized energy systems, the strategic importance of efficient trading platforms will only increase. Overall, the market offers significant opportunities for innovation and expansion, making it a critical component of future energy trading ecosystems.
Related Reports
Electromagnetic Compatibility Testing Service Market , Size Share and Analysis | Report 2033
Electrified Propulsion Testing Market , Size Share and Analysis | Report 2033
Natural Weathering Testing Service Market , Size Share and Analysis | Report 2033
Laboratory Weathering Testing Service Market , Size Share and Analysis | Report 2033
Strain Gage Service Market , Size Share and Analysis | Report 2033
Automotive Electrical Testing Service Market , Size Share and Analysis | Report 2033
Van Hire Franchise Market , Size Share and Analysis | Report 2033
Airbag Service Franchise Market , Size Share and Analysis | Report 2033
Airbag Validation Service Market , Size Share and Analysis | Report 2033
Automotive Non Destructive Testing Service Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
How Audits and Inspections Work Together to Improve HSE Performance
Workplace safety is no longer limited to satisfying compliance requirements or being ready for an inspection. Organisations increasingly need a transparent view of how risks are identified, addressed, and controlled, showing not only the final outcome but also the process that produced it. When an incident or non conformity occurs, businesses should be able to demonstrate how it was discovered, who owned the response, what corrective action followed, and what will be done to prevent the same issue from returning. At the same time, organisations are looking for patterns that reveal whether risk is genuinely falling. Bringing inspections, audits, and corrective actions together through a unified HSE platform makes this level of control easier to manage and more useful in daily operations.
Inspections and audits contribute to the same safety system, yet they serve different purposes. An inspection concentrates on what is happening in the workplace at a particular moment. It can expose immediate hazards, highlight employee behaviours, and confirm whether work is being performed as intended. An audit looks across the wider management approach, examining systems, procedures, and controls to see whether risks are being handled reliably over time. Put simply, an inspection captures the current situation, while an audit tests the strength and consistency of the system behind it. Connecting these activities creates a continuous improvement cycle: inspection results can reveal areas for deeper audit review, while audit findings can influence future inspection priorities and focus attention on greater risk.
Audits deliver stronger value when they reflect actual workplace risk instead of relying on generic checklists or recycled templates. The audit method should fit the organisation’s operating conditions, regulatory responsibilities, and particular challenges. Several audit categories can support this approach. Compliance audits assess whether legal and environmental obligations are being met, covering matters such as permits, emissions, waste disposal, and discharge requirements. Management system audits review leadership involvement, policies, employee capability, and operational controls. Program audits target higher risk work, such as contractor management, confined spaces, lockout/tagout, and hot work. Environmental audits examine areas including hazardous material storage, spill prevention, waste handling, and protection of air and water resources. This risk based approach turns audits from routine paperwork into useful tools for strengthening safety performance.
The value of an audit also rests on the quality of its findings and the way those findings are reported. Observations need clear supporting evidence and should be linked directly to the requirement that was not met, whether it originates in legislation, internal procedures, or operational standards. Accurate records strengthen both the credibility and consistency of the audit process. When a deficiency is identified, the report should explain what is wrong, clarify the associated risk, and name the department or individual responsible for responding. Effective reporting converts observations into specific actions, rather than leaving teams with vague recommendations that may be forgotten.
A dependable audit program can be organised into seven stages. First, define the scope, objectives, operational areas, participating teams, and priority risk categories. Next, prepare by reviewing relevant records such as SOPs, maintenance histories, training documents, permits, and previous incident reports, while making sure affected stakeholders know the audit schedule. The next stage combines site inspections, operational observations, and discussions with employees, supervisors, contractors, and HSE representatives to see how procedures work in practice. Findings are then assessed according to risk, considering the possible severity of consequences and the likelihood of occurrence. A detailed report follows, recording strengths, weaknesses, accountability, and realistic completion timelines. Issues are then converted into measurable corrective and preventive actions that can be incorporated into routine operations. The final stage is verification, confirming that actions were completed correctly, root causes were addressed, and recurring trends or unresolved high risk concerns remain under review.
Audits matter, but completing them alone does not prove that workplace safety has improved. Organisations also need to determine whether the audit process is producing meaningful results. A completed checklist or recorded inspection offers limited insight when risks are still present. More useful measures include the time taken to close critical findings, the number of overdue actions, recurring problems, and the length of time corrective actions remain open across teams or facilities. These lagging measures should be reviewed alongside leading indicators, including training completion, participation in risk assessments, and other preventive activities. Considering both provides a more complete view of whether risk is actually decreasing instead of simply generating additional records.
A strong audit framework should address operational and safety controls together. Important areas include leadership accountability, risk and change management, competency based training, permit to work processes, lockout/tagout controls, investigation quality, CAPA performance, emergency preparedness, chemical safety, PPE compliance, machinery safeguards, contractor oversight, environmental monitoring, workplace organisation, and document control. Bringing these elements into one framework creates a clearer, more structured, and defensible approach to workplace safety and operational performance.
Digital HSE platforms increasingly help organisations manage this connected model by placing multiple safety activities within one system. They improve coordination by tracking findings consistently, escalating overdue actions, and supporting ongoing compliance with permit and lockout/tagout requirements. They can also initiate maintenance workflows for critical equipment, support procedure updates when operating conditions change, and assign training when competency gaps are identified. Most importantly, digital HSE solutions can retain secure, tamper resistant records that support regulatory and certification requirements. This links identified weaknesses with completed actions and longer term improvements across everyday safety operations. This gives teams a clearer chain from discovery through resolution, verification, and sustained control. Instead of merely recording that an issue was corrected, organisations can maintain evidence showing that the corrective action was completed, verified, and sustained over time.
Book a free demo @
https://toolkitx.com/blogsdetails.aspx?title=EHS-audit-(2025-guide):-definition,-checklist,-process,-and-ISO/OSHA-mapping
From HSE Records to Action: Building a Stronger Safety Strategy
Sustained improvement in Health, Safety, and Environmental performance rarely comes from isolated projects or short lived awareness drives. Real progress takes shape through the choices made every day across sites, teams, departments, and work groups. When supervisors and frontline personnel act on dependable information instead of assumptions, procedures become more consistent, coordination becomes stronger, and routine work begins aligning more closely with organizational objectives. Inspections, incident reports, training records, and near miss submissions can serve a purpose far greater than administration. They help support compliance, reduce operational exposure, and strengthen safer ways of working.
An effective data oriented HSE strategy is not defined by the volume of information collected. Its real value comes from choosing useful information and applying it with purpose. When relevant data becomes part of a continuous improvement process, organizations can set priorities more accurately, assess hazards with greater confidence, and determine whether corrective actions are generating measurable results. The greatest value comes from identifying meaningful indicators and organizing them so performance can be compared across sites, departments, and reporting periods.
An HSE system can only be as dependable as the information behind it. Outdated, incomplete, or inconsistent records can weaken confidence in the overall process. Timely and reliable reporting, however, can reveal recurring issues, operational gaps, and early warning signs that may otherwise go unnoticed. These insights give organizations an opportunity to intervene before concerns escalate into significant incidents. Information collection should therefore serve more than record keeping. Its purpose is to turn information into actions that support decisions, measure progress, and improve performance.
Using data to guide HSE management also reshapes the way risk is controlled. Instead of waiting for an event before taking action, teams can recognize developing patterns and introduce preventive measures earlier. When leaders, workers, and contractors work from the same indicators, communication becomes clearer and accountability is easier to establish. Shared information also promotes consistent execution standards across the organization.
Good documentation is equally important for compliance. Accurate and well organized records can simplify audits, reduce administrative work, and provide stronger evidence during regulatory reviews. Efficiency may also improve as approvals move faster, disruptions decrease, and issues are addressed sooner, reducing delays and downtime. Confidence in the system can increase when employees see that workplace concerns are addressed in a consistent, fair, and transparent manner.
Choosing the right performance indicators is central to making a data driven strategy effective. Leading indicators help teams recognize potential risks before incidents occur, while near miss reports can expose weaknesses while there is still time to act. Behavioral observations can indicate whether safe working practices are becoming routine. Training records matter more when they demonstrate understanding and application rather than attendance alone. Permit to work activity and inspection results can also highlight bottlenecks, inefficient practices, and the effectiveness of existing control measures.
Lagging indicators provide a different but necessary view by showing what has already happened and how performance has changed over time. Injury records can reveal recurring trends across extended periods, while environmental exceedances may indicate persistent compliance concerns. Equipment breakdowns and overdue maintenance can expose broader operational weaknesses requiring further investigation. Financial effects, including claims, operational losses, and interruptions to productivity, can also demonstrate how HSE shortcomings may affect wider business performance.
Creating a data driven HSE framework starts with clear direction. Organizations can select a manageable set of priorities, such as reducing near miss occurrences or improving permit processing efficiency, and define measurable indicators to monitor progress. Consistent data capture methods are essential, while validation checks help keep records accurate, reliable, and suitable for comparison over time.
Another step is improving visibility by bringing information together. Integrating records from inspections, incidents, permits, assets, and training can reveal connections that are difficult to recognize when information remains isolated within separate departments. Dashboards should emphasize the insights most relevant to each role so teams can respond with greater speed and confidence. Information alone does not produce improvement. Insights must lead to action through clear ownership, defined deadlines, and measurable objectives. As results become easier to track, the approach can expand into additional functions.
However, long term success should never depend entirely on software or analytical reports. Strong governance and an open workplace culture are just as important. Organizations need clear ownership over who records information, who verifies its quality, and when reviews take place. Reporting processes should be straightforward and encourage honest participation, so employees feel comfortable sharing accurate information without unnecessary barriers.
Most importantly, employees need to see that reporting has a real purpose. When workers observe their concerns, observations, and submissions leading to visible improvements, participation becomes more meaningful. Over time, this makes continuous improvement part of normal operations.
Ultimately, reliable information enables organizations to move beyond reactive compliance. By focusing on meaningful insights, recognizing risks earlier, and encouraging positive workplace behaviors, HSE management can move beyond reacting after incidents and create direction for teams responsible for maintaining HSE performance over time.
Book a free demo here @ https://toolkitx.com/blogsdetails.aspx?title=Data-driven-decision-making-in-EHS:-what-to-track,-and-where-to-start
Cold Work Safety: How Permits Keep Routine Activities Under Control
Workplace incidents are not limited to hazardous facilities, complicated machinery, or large scale shutdowns. They can also happen during routine work that seems completely ordinary. Removing a cover, opening a connection, checking a valve, or making a small adjustment may feel harmless. But when a hazard is missed, a familiar task can change very quickly into an unsafe situation, even in otherwise familiar surroundings.
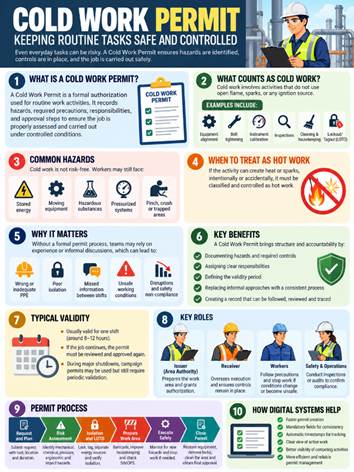
This is why a Cold Work Permit is an important part of workplace safety. Within a Permit to Work (PTW) system, it creates a defined method for planning routine activities by documenting hazards, precautions, responsibilities, and authorization requirements. Its purpose is simple: assess the work properly, confirm that safeguards are available, and ensure the task is carried out in controlled conditions.
Cold work refers to activities that do not use an open flame, generate sparks, or involve another ignition source. Unlike hot work, these jobs generally do not require a dedicated fire watch or broad fire prevention arrangements. Still, the word “cold” does not mean harmless. Workers may encounter stored energy, operating machinery, hazardous materials, pressure, or locations where someone could be caught, pinched, or crushed.
Common examples can include equipment alignment, bolt tightening, instrument calibration, inspections, cleaning, Lockout/Tagout (LOTO) work, and normal housekeeping. If an activity is capable of producing heat or sparks, intentionally or unexpectedly, it should be treated and controlled as hot work instead.
The importance of a Cold Work Permit becomes more obvious when an organization does not have a structured permit process. Without one, teams may depend on personal experience, assumptions, or quick conversations rather than a complete review of the risks. This can lead to unsuitable PPE, weak isolation, or important information being missed between crews or shifts. These gaps may create unsafe conditions, interrupt operations, and make it harder to meet workplace safety requirements.
A strong Cold Work Permit process adds consistency, ownership, and control to routine tasks. It documents the hazards associated with the job, the controls needed to manage them, the person accountable for each action, and the period for which the authorization applies. Instead of relying on informal methods, teams gain a repeatable process that can be followed, checked, reviewed, and traced, helping prevent critical precautions from being forgotten.
At many workplaces, a cold work permit covers one shift, commonly around eight to twelve hours. If the task continues beyond that timeframe, the permit generally has to be reviewed and authorized again. Renewal may require another site check, confirmation that safeguards remain effective, and a discussion of current conditions with the people doing the work. During major maintenance shutdowns, campaign permits may be used, but they still require periodic validation so the work remains controlled.
Clear responsibilities also support effective permit management. The Issuer, also referred to as the Area Authority, prepares the work area and provides authorization. The Receiver oversees the job and verifies that required controls stay in place while work continues. Workers are expected to follow the approved precautions and stop the job immediately if conditions change, become unsafe, or no longer match the expected situation. Safety and operations teams may also inspect or audit the work to verify compliance with permit conditions.
The process usually starts with a formal request describing the task, work location, and expected duration. This is followed by a risk assessment that considers possible mechanical, chemical, pressure, ergonomic, and impact hazards. Required isolation and LOTO measures are then carried out, including locking, tagging, separating energy sources, and confirming that the isolation works as intended.
Next, the work area is made ready. Barricades may be installed, housekeeping problems corrected, and lighting improved where necessary. Simultaneous operations (SIMOPS) nearby are assessed to prevent one task from interfering with or creating danger for another. Workers receive the necessary PPE, and tools and equipment are checked to ensure they are suitable and in good condition. Before work begins, the Issuer and Receiver verify that controls are established and that everyone understands the approved conditions.
While the job is underway, conditions should continue to be watched for new or changing hazards. If an unexpected risk appears, work should stop until the situation is assessed and suitable controls are put back in place. Once the task is finished, systems and equipment are restored to the required state, locks are removed in the correct order, and the area is cleaned and inspected. The permit can then be given final approval and formally closed.
Although there may be no rules devoted only to cold work permits, a structured permit system can support broader workplace safety responsibilities. It can help address machine guarding, LOTO, hazard communication, PPE, and process safety practices. It also leaves a documented record showing that relevant hazards were reviewed and appropriate controls were established before the work started.
A practical Cold Work Permit should record key information, including the task, location, equipment, scope, and permit validity. It should also cover isolation points, verification activities, barricading requirements, guarding arrangements, housekeeping conditions, SIMOPS, and any necessary gas testing. Approval details, restoration activities, and lock removal procedures should be recorded clearly too.
Electronic Permit to Work (e PTW) systems can further simplify this process. Digital tools can make permit preparation faster, use mandatory fields to improve consistency, and automatically record timestamps for tracking and audits. Centralized dashboards provide a clearer view of ongoing work, helping teams identify overlapping activities before they become operational conflicts. The result is a more organized, dependable, and efficient way to manage permits while improving the overall control of workplace safety, while keeping administration organized and accountable.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=Cold-work-permit-(2025-guide)%3A-definition%2C-OSHA%2FHSE-mapping-and-checklist
Asia-Pacific Nuclear Waste Infrastructure Market Growth & Strategy 2026–2032
By chobepooja4, 2026-10-06
The global Radioactive Waste and Nuclear Waste Management Market is undergoing a structural paradigm shift, driven by the dual catalysts of commercial Small Modular Reactor (SMR) deployments and global grid decarbonization targets. According to an exhaustive industry study by Stellar Market Research , the market was valued at USD 6.1 Billion in 2025 and is projected to expand at a steady 6.9% CAGR , reaching USD 9.73 Billion by 2032 . As sovereign nations accelerate reactor life extensions and expand nuclear capacity to backstop volatile renewable grids, establishing end-to-end containment, specialized transportation, and permanent deep geological disposal infrastructure has transformed from a regulatory obligation into a high-yield strategic investment imperative.
The global energy transition is forcing a fundamental re-evaluation of backend nuclear fuel cycles. While historical waste management strategies relied heavily on wet storage facilities and interim surface casks, the rapid commercialization of SMRs, advanced microreactors, and high-assay low-enriched uranium (HALEU) fuels is creating multi-billion-dollar opportunities in closed-loop fuel cycles. Concurrently, a severe structural shift in healthcare—where the World Health Organization projects over 35 million new cancer cases annually by 2050—has caused radiopharmaceutical waste volumes from medical isotopes to surge by 77%, forcing municipal and industrial handling facilities to modernize their low-level waste (LLW) and intermediate-level waste (ILW) supply chains.
Key Findings from the Report
-
Market Valuation & Growth trajectory: The global nuclear waste management market will scale from USD 6.1 Billion in 2025 to USD 9.73 Billion by 2032 (6.9% CAGR), with the U.S. market alone expanding from USD 5.61 Billion to USD 8.95 Billion at a 7.2% CAGR.
-
Nuclear Power Plants Command Volume Lead: Power generation facilities remain the largest source segment, representing over 58% of overall management volume as utilities secure extended 60-to-80-year operating licenses for legacy reactor fleets.
-
Deep Geological Disposal Gains Regulatory Velocity: Deep Geological Disposal (DGD) represents the fastest-growing disposal segment, buoyed by multi-billion-dollar national repository initiatives in Scandinavia, Western Europe, and North America.
-
Recycling & Reprocessing Accelerates: Waste treatment via chemical reprocessing and pyroprocessing is growing faster than standard storage, driven by fuel-security mandates aimed at recovering reusable uranium and plutonium isotopes.
-
Medical & Healthcare Surge: Non-power radioactive waste from medical isotope diagnostics and radiation therapies is projected to grow at an unprecedented 8.1% CAGR.
-
Institutional Capital Inflow: Private equity and infrastructure funds increased capital deployment into specialized waste transport logistics and robotic vitrification technology by 24% year-over-year.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/radioactive-waste-and-nuclear-waste-management-market/2927
Market Drivers and Restraints
Market Drivers
-
Global Nuclear Capacity Expansion & SMR Integration: Over 60 commercial reactors under construction globally, combined with fast-tracked SMR builds, are creating structural demand for modular, scalable spent-fuel storage casks and transport containers.
-
Surge in Radiopharmaceutical Applications: Expanding oncology treatment infrastructure globally is significantly increasing daily low- and intermediate-level radioactive waste yields across hospital and research networks.
-
Mandated Decarbonization Policies: Federal net-zero commitments are compelling governments to co-fund permanent geological repositories to clear legacy waste burdens and ensure public support for new nuclear builds.
Market Restraints
-
Extreme Capital Intensity and Prolonged Licensing Timelines: Developing deep geological repositories requires multi-decade permitting cycles and upfront capital outlays exceeding USD 4–6 Billion per site.
-
Public Opposition and Political Friction (NIMBYism): Local community resistance regarding waste transport corridors and permanent disposal siting continues to stall long-term infrastructure projects worldwide.
Technology, Regulation, and Sustainability Trends
Modern nuclear waste management is undergoing a digital and operational transformation:
-
Robotics & AI Handling: Hazardous sorting and encapsulation facilities are replacing manual handling with autonomous tele-operated robotics, AI-driven spectrographic waste characterization, and digital twin monitoring for long-term cask integrity.
-
Closed Fuel Cycles & Vitrification: Advanced plasma vitrification and ceramic immobilization methods are minimizing waste volumes while locking high-level radioisotopes into stable glass matrices engineered for 10,000+ year durability.
-
Regulatory Modernization: Global regulatory bodies—including the U.S. NRC and IAEA—are updating compliance frameworks to accommodate unique SMR spent-fuel profiles and decentralized waste streams.
Regional Insights
-
North America (Market Leader): Dominates global market share, led by the United States. Growth is anchored by the U.S. Department of Energy’s environmental management allocations, nuclear fleet life extensions, and private-sector investments in consolidated interim storage facilities (CISFs).
-
Asia-Pacific (Fastest-Growing Region): Expected to register the highest regional CAGR through 2032. Aggressive nuclear power construction in China, India’s three-stage nuclear program, and South Korea’s export-driven reactor construction are driving massive regional demand for waste treatment plants and deep disposal facilities.
-
Europe: Maintains stringent circular economy standards, with Finland, Sweden, and France leading globally in operational deep geological repository engineering and large-scale commercial fuel reprocessing.
Recent Industry Developments
-
Orano (2025): Secured a €250M contract expansion to supply advanced transport packages and vitrification technologies for European light water reactor decommissioning projects.
-
Holtec International (2025): Expanded production capacity at its Advanced Manufacturing Complex to deliver HI-STORE Consolidated Interim Storage Casks designed for high-density spent fuel management.
-
Westinghouse Electric Company (2025): Launched its next-generation waste immobilization system utilizing inorganic polymers, reducing high-level liquid waste volumes by up to 35%.
-
Anadear/Posiva (2025): Achieved final regulatory commissioning milestones for the Onkalo Deep Geological Repository in Finland, establishing the world's first operational permanent high-level waste facility.
-
EnergySolutions (2025): Completed the acquisition of specialized nuclear logistics providers to streamline cross-state transport and near-surface processing of low-level radioactive waste in North America.
Competitive Landscape
The global radioactive waste and nuclear waste management industry is moderately consolidated, featuring specialized technology leaders and state-backed environmental engineering conglomerates. Key market participants include Orano SA, Westinghouse Electric Company LLC, Holtec International, EnergySolutions, Veolia Environmental Services, BWX Technologies Inc., Bechtel Corporation, Jacobs Engineering Group, Framatome, and Ansaldo Nucleare . These leaders are aggressively prioritizing strategic partnerships, modular container product expansions, specialized robotic integrations, and long-term government service contracts to lock in recurring revenues across the 60+ year lifecycle of nuclear assets.
Analyst Commentary
"We are witnessing an unprecedented shift in how governments and energy majors approach nuclear waste," stated a Senior Research Analyst at Stellar Market Research . "Waste management is no longer viewed as a terminal cost center at the end of a plant’s lifespan. Instead, it has become a central strategic pillar for the broader nuclear renaissance. The commercial viability of Small Modular Reactors, combined with the explosive growth of nuclear medicine, hinges entirely on scalable, technology-driven waste logistics and permanent disposal infrastructure. The companies mastering closed-loop recycling and automated containment are setting the benchmark for the next half-century of clean energy."
Future Outlook
Through 2032, the market will experience accelerated alignment between reactor design and waste cycle planning. As regulatory approvals for deep geological sites expand in Europe and North America, commercial operators will transition from temporary wet-storage pools to dry-cask storage and automated recycling facilities. The convergence of AI-driven radiation monitoring, standardized SMR waste packages, and government-backed clean energy funding guarantees sustained growth and robust capital deployment across the global nuclear waste management value chain.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/radioactive-waste-and-nuclear-waste-management-market/2927
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656
One Button, Endless Obsession: Getting the Most Out of Your First Geometry Jump
By EleanoPearce, 2026-10-06
There's a particular kind of game that looks almost insultingly simple at first glance — a small square, a floor, a few spikes — and then quietly eats three hours of your evening. That's the strange magic of the geometry jump genre, and nobody has perfected it quite like Geometry Dash . If you've ever watched someone else play and thought "that looks easy, why is he yelling at his monitor," this article is for you. Let's talk about what these games actually are, how to survive your first attempts, and how to keep enjoying them once the difficulty starts biting back.
What You're Actually Doing
At its core, a geometry jump game is a rhythm game wearing a platformer's clothes. You control a small geometric shape that moves forward automatically — you never slow down and you never turn around. Your only job is to jump at the right moment. Hit a spike, clip a wall, or mistime a landing, and you're sent back to the start of the level.
That single-button design is deceptive. Because you can't control speed or direction, everything comes down to timing . Every jump has an ideal frame, and levels are built so that obstacles line up with the beat of the background music. Players who listen carefully often do better than players who stare intently at the character. The music isn't decoration; it's a map. Once you start feeling the rhythm instead of just reacting to what you see, the whole game clicks into place.
Geometry Dash popularized this formula and added layers on top of it. As a level progresses, your little cube transforms — into a ship that you fly by holding and releasing, a ball that flips gravity with each tap, a UFO that hovers, and more. Each transformation changes what the same single button does, which keeps levels fresh and forces you to re-learn your instincts section by section. That constant shifting between "jump" and "fly" and "flip" is what makes the game feel less like a test of reflexes and more like a conversation with the level designer.
Finding Your Way In
The best starting point is the game's built-in levels, which are arranged in increasing difficulty. Resist the urge to skip ahead to the hardest stages — the early levels aren't filler, they're teaching you the vocabulary. By the time you reach something genuinely brutal, you'll have absorbed dozens of small patterns without noticing it.
Once you're comfortable, the real ecosystem opens up: custom levels made by other players, ranked by difficulty from Easy to Insane Demon. This is where the community lives. Finding a creator whose style suits you — chaotic, precise, rhythm-heavy, or visually wild — is half the fun. Many people never finish the toughest levels at all, and that's completely fine. The point is the pursuit.
Use Practice Mode relentlessly. Almost every geometry jump game includes it, and it lets you place checkpoints so you can drill a single nasty section over and over instead of replaying the entire level. There's no shame in it. Even top players use practice runs to memorize patterns before attempting a full run.
Watch patterns, not just obstacles. Spikes and blocks tend to repeat in recognizable clusters. After a few attempts, you'll start recognizing "oh, this is the triple-jump-then-fall part" instead of seeing a wall of random shapes. Pattern recognition is where raw reaction time turns into actual skill.
Stay calm, and take breaks. Frustration ruins precision. If you've died to the same jump fifteen times, you're no longer learning — you're tensing up. Step away, come back, and the section will often feel absurdly easy.
Play with the sound on. Muting the game to listen to your own music is tempting, but you're throwing away your best tool. The official tracks are designed to guide your timing.
Set small goals. "Beat this level" is a monumental task. "Get past the ship section this session" is achievable, and those small wins are what keep the game fun rather than maddening.
The Real Reason People Keep Playing
Somewhere along the way, geometry jump games stop being about the obstacles and start being about you . That jump you couldn't land a hundred times? When you finally clear it, the feeling isn't relief — it's a genuine rush, because you earned every frame of it. The game doesn't hand out victories; it makes you build the skill to take them.
It also connects you to other people. Watching a streamer grind an impossible level, swapping level codes with friends, or cheering on a stranger in a forum thread — the shared frustration creates a surprisingly warm community. Nobody is showing off; everyone remembers being terrible at this.
So if you're curious, don't overthink it. Open the game, press space, and die a few times. Then die a few more. That's not failure — that's the entire experience. The geometry jump genre isn't testing whether you have fast fingers. It's testing whether you'll come back for one more attempt. And once you realize you always will, you're already hooked — in the best possible way.
Space And Satellite Insurance Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-10-06
Space And Satellite Insurance Market
Overview
The space and satellite insurance market encompasses specialized coverage designed to protect assets, operations, and investments related to space missions and satellite deployments. Its purpose is to mitigate financial risks associated with satellite launches, in-orbit operations, and ground-based infrastructure, ensuring stability for satellite operators, governments, and commercial entities. This insurance supports the development and deployment of space technologies by providing financial security against launch failures, damages, or operational disruptions.
The space and satellite insurance market plays a crucial role in enabling the growth of modern industries such as telecommunications, navigation, and Earth observation. It offers core functionalities like risk assessment, claims management, and policy customization, supporting the evolving needs of space-based enterprises. As the industry expands, the importance of comprehensive coverage becomes increasingly significant for safeguarding technological advancements and investments.
Market Size and Growth
The market value for the space and satellite insurance market is estimated at around USD 3.2 billion in the current year. Over the next decade, it is projected to reach approximately USD 8.7 billion, reflecting a compound annual growth rate (CAGR) of about 11%. The expanding satellite constellations, increased launch activities, and rising demand for space-based services are primary growth drivers fueling this upward trajectory.
Key drivers include the surge in commercial satellite launches, technological advancements reducing insurance costs, and growing governmental and private sector investments in space infrastructure. The rise of mega-constellations and increased space traffic further underscore the market’s expanding scope and significance.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1864
Restraints
• High insurance premiums due to launch and operational risks
• Technical complexities in risk assessment and underwriting
• Stringent regulatory requirements affecting policy issuance
• Operational challenges from space debris and satellite congestion
• Limited historical data impacting accurate risk modeling
Segmentation
• By Type: Launch insurance, in-orbit insurance, ground risk insurance
• By Deployment: Commercial, government, military
• By Enterprise Size: Small, medium, large enterprises
• By End User: Satellite operators, launch service providers, governmental agencies
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America dominates the space and satellite insurance market owing to its substantial satellite launch activity and technological innovation. The region’s mature space industry and presence of key insurers drive high adoption rates.
Europe exhibits steady growth, driven by governmental programs and private space companies expanding their satellite fleets. Regulatory support and collaborative initiatives promote market development across the continent.
In Asia-Pacific, rising investments in space infrastructure and increasing launch capabilities contribute to rapid market expansion. Countries like India and China are becoming prominent players in satellite deployment and insurance coverage.
Latin America’s market remains emerging, with growth driven by regional space agencies and increasing private sector interest in satellite-based applications.
Middle East & Africa are witnessing growing demand from governmental space programs and regional satellite operators, with a focus on strategic and security-related applications.
Opportunities
• Expansion of satellite constellations for global connectivity
• Adoption of innovative insurance models, such as parametric coverage
• Integration of AI and data analytics for risk assessment
• Growth in emerging markets and developing economies
• Development of insurance solutions for space tourism and lunar missions
Key Companies
AIG
AXA XL
Allianz Global Corporate & Specialty
Marsh & McLennan
Swiss Re
Hannover Re
Lloyd’s of London
Chubb
Berkshire Hathaway
Aon
Sompo Holdings
Everest Re
Conclusion
The overall outlook for the space and satellite insurance market remains optimistic, driven by technological advancements and increasing satellite deployment. With long-term growth potential fueled by expanding space activities and emerging markets, the market holds strategic importance for supporting the sustainable development of space-based industries. As the industry evolves, the space and satellite insurance market will continue to play a vital role in safeguarding investments and fostering innovation.
Related Reports
Digital Mine Market , Size Share and Analysis | Report 2033
Personal Tax Advisors Market , Size Share and Analysis | Report 2033
Tax Consulting Market , Size Share and Analysis | Report 2033
Human Machine Collaboration Market , Size Share and Analysis | Report 2033
Dna Fragment Synthesis Market , Size Share and Analysis | Report 2033
Digital Lending Software Market , Size Share and Analysis | Report 2033
Electronic Design Automation For Semiconductor Chips Market , Size Share and Analysis | Report 2033
Information Consulting Services Market , Size Share and Analysis | Report 2033
Indoor Location Tracking And Positioning Market , Size Share and Analysis | Report 2033
Lithium Iron Phosphate Battery Recycling Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Smart Toilet Complete Solution Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-10-06
Overview
The Smart Toilet Complete Solution Market encompasses advanced toilet systems integrated with digital and automation features to enhance hygiene, comfort, and user experience. These solutions typically include functions such as bidet washing, heated seats, automatic lids, and water-saving mechanisms, making them vital components of modern smart bathrooms. Their purpose is to support industries aiming for high standards of sanitation, user convenience, and energy efficiency, especially in commercial and high-end residential settings.
The market for smart toilet complete solutions is driven by increasing demand for hygienic and contactless sanitation options. As the Smart Toilet Complete Solution Market continues to evolve, these systems support emerging technologies such as IoT connectivity, AI-based user customization, and remote control functionalities. Their integration into smart building infrastructures underscores their strategic importance for future-proofing sanitation and hygiene solutions.
Market Size and Growth
The current year’s market value for the Smart Toilet Complete Solution Market is estimated at approximately USD 4 billion. Over the next decade, this market is projected to reach around USD 12 billion, reflecting a compound annual growth rate (CAGR) of about 12%. Growth drivers include rising urbanization, increasing disposable incomes, and heightened awareness of hygiene standards globally.
Advancements in smart home technology and the expanding adoption of IoT-enabled appliances further fuel market growth. Additionally, regulatory pushes for water efficiency and sanitation improvements in developing regions are significant contributors to the upward trajectory of this market.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1766
Key Drivers
- Rising consumer demand for hygienic bathroom solutions
- Technological integration with IoT and AI
- Urbanization and smart city initiatives
- Increasing disposable income and premiumization
- Growing awareness of health and sanitation
Restraints
- High initial installation costs
- Technical complexity and maintenance challenges
- Regulatory hurdles in certain regions
- Limited consumer awareness in emerging markets
- Compatibility issues with existing bathroom infrastructure
Segmentation
• By Type: Standard, Premium, Luxury
• By Deployment: Residential, Commercial, Hospitality
• By Enterprise Size: Small, Medium, Large
• By End User: Individual Consumers, Hotels, Hospitals, Public Facilities
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong demand driven by premium residential and commercial infrastructure upgrades. Europe’s focus on sustainability and hygiene standards accelerates adoption, especially in urban centers. Asia-Pacific remains the fastest-growing region, propelled by rapid urbanization, technological adoption, and rising disposable incomes. Latin America shows emerging opportunities, particularly in upscale residential projects. Middle East & Africa are witnessing initial adoption, with growth tied to infrastructure development and luxury hospitality sectors.
Opportunities
- Expansion into emerging markets with rising urban populations
- Development of contactless and AI-enabled toilet systems
- Integration with smart home ecosystems and building automation
- Focus on water conservation and energy efficiency innovations
- Adoption in hospitality and healthcare industries for enhanced hygiene
Key Companies
Toto Ltd., Kohler Co., Duravit AG, Lixil Group Corporation, Villeroy & Boch AG, Geberit AG, American Standard Brands, Brondell Inc., Xiaomi Corporation, Panasonic Corporation, Coway Co., Ltd., Kohler Mira Ltd.
Conclusion
The overall outlook for the Smart Toilet Complete Solution Market remains robust, with long-term growth driven by technological innovation and increasing consumer preferences for hygiene and comfort. As smart bathroom solutions become integral to modern infrastructure, the market’s strategic importance continues to rise. The market is poised for sustained expansion, making it a critical area for enterprise investment and technological advancement in the coming years.
Related Reports
Contract Brewing Market , Size Share and Analysis | Report 2033
Brewing Consulting Services Market , Size Share and Analysis | Report 2033
Construction Drying Services Market , Size Share and Analysis | Report 2033
Mine Dewatering Solutions Market , Size Share and Analysis | Report 2033
Charitable Giving Market , Size Share and Analysis | Report 2033
Stock Trading Training Market , Size Share and Analysis | Report 2033
Fiber Deployment Solutions Market , Size Share and Analysis | Report 2033
Online Ad Management Software Market , Size Share and Analysis | Report 2033
Marine Digital Platform Market , Size Share and Analysis | Report 2033
Pharmaceutical Products Testing Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Ship Performance Monitoring Software Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-10-06
Ship Performance Monitoring Software Market
Overview
The Ship Performance Monitoring Software Market encompasses digital solutions designed to track, analyze, and optimize the operational efficiency of maritime vessels. These platforms collect real-time data on engine performance, fuel consumption, emissions, and maintenance needs, enabling ship operators to improve safety, reduce costs, and comply with environmental regulations. As maritime logistics and shipping industries become increasingly digitalized, the demand for advanced performance monitoring tools continues to grow, supporting smarter fleet management and sustainable operations.
The Ship Performance Monitoring Software Market plays a crucial role in modern maritime industries by providing actionable insights that enhance vessel efficiency and operational longevity. These systems are integral to fleet optimization, predictive maintenance, and regulatory compliance efforts. The importance of such software is underscored by the need for precise, data-driven decision-making in a competitive, environmentally conscious sector. This market is driven by the rising adoption of digital solutions and the necessity for real-time performance analytics.
Market Size and Growth
The current market value for the Ship Performance Monitoring Software Market is estimated at approximately USD 1.2 billion in 2023. It is projected to reach around USD 3.5 billion by 2030, reflecting a compound annual growth rate (CAGR) of approximately 14%. Growth is fueled by increasing regulatory pressures, technological advancements, and a shift towards digital fleet management. The maritime sector’s focus on reducing operational costs and environmental impact further accelerates market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1859
Key Drivers
• Rising demand for fuel efficiency and emissions reduction
• Growing adoption of IoT and sensor technologies onboard vessels
• Regulatory mandates for environmental compliance
• Increasing focus on predictive maintenance
• Digital transformation initiatives in shipping companies
Restraints
• High initial investment costs for software deployment
• Technical integration challenges with existing systems
• Limited digital infrastructure in some maritime regions
• Regulatory uncertainties across different jurisdictions
• Data security and privacy concerns
Segmentation
• By Type: Performance analytics, Fuel management, Emissions monitoring, Maintenance tracking
• By Deployment: Cloud-based, On-premises
• By Enterprise Size: Small, Medium, Large fleets
• By End User: Shipping lines, Offshore operators, Fleet managers, Regulatory bodies
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market is driven by technological innovation and stringent environmental regulations, leading to high adoption rates among shipping companies. Europe’s maritime sector emphasizes compliance with EU directives, fostering demand for advanced monitoring solutions. Asia-Pacific exhibits rapid growth due to expanding shipping fleets and infrastructural investments, particularly in China and Singapore. Latin America’s adoption remains moderate, primarily influenced by regional shipping activity and regulatory frameworks. The Middle East & Africa are emerging markets, with growth fueled by infrastructural development and regional trade expansion.
Opportunities
• Increasing adoption of AI and machine learning in performance analytics
• Expansion into emerging maritime markets in Africa and Southeast Asia
• Development of integrated, multi-modal fleet management platforms
• Adoption of green technologies and alternative fuels
• Customization for niche sectors like offshore energy and cruise shipping
Key Companies
ABB Marine & Ports, Wärtsilä, Rolls-Royce Marine, Navis, Marine Technologies, DNV GL, BASS, Kongsberg, Wärtsilä, Honeywell, MarineTraffic, Wärtsilä
Conclusion
The overall outlook for the Ship Performance Monitoring Software Market remains robust, with long-term growth driven by technological innovation and regulatory pressures. As maritime industries continue to prioritize efficiency, sustainability, and safety, the strategic importance of advanced performance monitoring solutions will only increase. The market offers substantial opportunities for industry players to capitalize on emerging trends and expanding regional demand, cementing its role in the future of sustainable maritime operations.
Related Reports
Wedding Planning Software Market , Size Share and Analysis | Report 2033
Bridal Shop Management Software Market , Size Share and Analysis | Report 2033
Tanning Salon Software Market , Size Share and Analysis | Report 2033
Spa And Salon Management Software Market , Size Share and Analysis | Report 2033
Maritime Crew Management Software Market , Size Share and Analysis | Report 2033
Boat Maintenance Software Market , Size Share and Analysis | Report 2033
Ocean Freight Software Market , Size Share and Analysis | Report 2033
Data Exchange Software Market , Size Share and Analysis | Report 2033
Tsunami Detection System Market , Size Share and Analysis | Report 2033
Toy Safety Testing Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Semiconductor Contamination Control Solutions Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-10-06
Overview
The Semiconductor Contamination Control Solutions Market encompasses advanced systems and protocols designed to minimize particulate, chemical, and biological contaminants during the manufacturing of semiconductor devices. These solutions are vital for maintaining ultra-clean environments, essential for producing high-performance, reliable chips. They support critical industry processes such as wafer cleaning, environmental monitoring, and cleanroom management, ensuring product integrity and operational efficiency.
The market for contamination control solutions is integral to modern semiconductor manufacturing, where even microscopic impurities can cause significant yield loss. The Semiconductor Contamination Control Solutions Market enables fabs to adhere to stringent cleanliness standards, reducing defect rates and improving overall device performance. As industry demands for smaller, more powerful chips grow, the importance of contamination control becomes increasingly paramount.
Market Size and Growth
The current market value is estimated at approximately USD 4.8 billion. It is projected to reach around USD 9.2 billion by the early 2030s, reflecting a compound annual growth rate (CAGR) of about 7%. Key growth drivers include rising demand for advanced semiconductor devices, increased adoption of cleanroom technologies, and stringent regulatory standards for manufacturing environments. The proliferation of IoT, AI, and 5G infrastructure further fuels market expansion.
The ongoing technological evolution and miniaturization in semiconductor devices necessitate more sophisticated contamination control solutions. As manufacturers seek higher yields and lower defect rates, investments in contamination mitigation are expected to rise, supporting long-term growth. The market’s expansion aligns with the broader digital transformation and the increasing complexity of semiconductor fabrication.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1835
Key Drivers
- Rising complexity of semiconductor devices
- Increasing adoption of cleanroom environments
- Growing demand for high-purity manufacturing processes
- Stringent industry and regulatory standards
- Expansion of IoT, AI, and 5G technologies
Restraints
- High operational costs of contamination control systems
- Technical challenges in maintaining ultra-clean environments
- Regulatory compliance complexities
- Limited awareness in emerging markets
- Rapid technological obsolescence
Segmentation
• By Type
- Particulate Control
- Chemical Contamination Control
- Biological Contamination Control
• By Deployment
- In-House Systems
- Outsourced Solutions
• By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
• By End User
- Foundries
- Integrated Device Manufacturers (IDMs)
- Contract Manufacturers
• By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Insights
North America leads the contamination control solutions market due to early adoption of advanced manufacturing standards and high R&D investments. The region’s focus on innovation in semiconductor fabrication drives steady demand for contamination mitigation technologies.
Europe’s market growth is supported by stringent regulatory frameworks and a strong presence of semiconductor manufacturing hubs. Adoption rates are increasing, especially in countries emphasizing sustainable and high-quality production processes.
Asia-Pacific is the fastest-growing region, fueled by expanding semiconductor manufacturing capacities in China, South Korea, and Taiwan. The region’s low-cost manufacturing environment and government incentives promote widespread adoption of contamination control solutions.
Latin America exhibits moderate growth, primarily driven by emerging semiconductor fabs and international investments. Adoption levels are gradually increasing as local industries modernize.
Middle East & Africa are in early stages of adoption, with growth potential tied to regional infrastructure development and strategic investments in high-tech manufacturing.
Opportunities
- Expansion in emerging markets
- Adoption of AI-driven contamination monitoring
- Integration with Industry 4.0 initiatives
- Development of sustainable, eco-friendly solutions
- Growth in advanced packaging and 3D integration
- Increasing demand for miniaturized, high-performance chips
Key Companies
Entegris, Pall Corporation, Veolia, Merck KGaA, Ecolab, BASF, 3M, Sartorius, Kuraray, Tokyo Electron, Applied Materials, Lam Research
Conclusion
The Semiconductor Contamination Control Solutions Market exhibits robust long-term growth prospects driven by technological advancements and increasing industry standards. As demand for smaller, faster, and more reliable semiconductor devices rises, the strategic importance of contamination control solutions becomes even more critical. Overall, the market is poised for sustained expansion, offering significant opportunities for innovation and industry adoption.
Related Reports
Mobile Terminal Payment Processing Software Market , Size Share and Analysis | Report 2033
Pc Terminal Payment Processing Software Market , Size Share and Analysis | Report 2033
Elderly Culture And Entertainment Market , Size Share and Analysis | Report 2033
Pension Finance Market , Size Share and Analysis | Report 2033
Power Battery Recycling Market , Size Share and Analysis | Report 2033
Full Dress Renta Market , Size Share and Analysis | Report 2033
Fashion Design Service Market , Size Share and Analysis | Report 2033
Jewelry Design Service Market , Size Share and Analysis | Report 2033
Leather Repair Service Market , Size Share and Analysis | Report 2033
Photograph Restoration Service Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher