

Blogs
Global Automatic Lubrication System Market Share to Surge to US$ 1,340.63 Million by 2034 | CAGR of 3.66%
By Sam Karan, 2026-10-21
Automatic Lubrication System protects industrial machinery against friction, excessive heat, and premature mechanical wear. Continuous application of fresh lubricant creates a dynamic barrier that repels dust, dirt, and moisture ingress. By sealing out contaminants, it prevents severe abrasive wear inside critical bearings and pins. This protective barrier maintains tight mechanical tolerances and prevents costly unexpected equipment failure.
The global Automatic Lubrication System Market is poised for steady, long-term expansion as industrial facilities, heavy manufacturing plants, and mining operators increasingly automate maintenance workflows to extend equipment lifespan and mitigate operational downtime. According to the latest comprehensive industry analysis, the global automatic lubrication system market size is projected to reach US$ 1,340.63 million by 2034 , expanding from US$ 970.34 million in 2025 . The market is anticipated to register a CAGR of 3.66% during the forecast period from 2026 to 2034.
Market Drivers and Growth Catalyst
Automatic lubrication systems (ALS) also known as centralized lubrication systems dispense controlled amounts of lubricant to multiple critical machine components while machinery is in operation. This process eliminates manual maintenance hazards, prevents premature component failure, and ensures optimal thermal regulation in heavy-duty machinery.
Key factors accelerating market adoption include:
-
Rise of Smart Manufacturing & Industry 4.0 Integration: Modern industrial facilities are integrating real-time sensors and Industrial Internet of Things (IIoT) capabilities into lubrication networks. Connected lubrication units feed operational metrics directly into predictive maintenance platforms, allowing operators to detect pressure drops and lubricant depletion proactively.
-
Operational Efficiency and Cost Mitigation: Unscheduled equipment breakdowns result in significant financial losses across heavy industries. Automatic systems deliver continuous, precise friction management, drastically reducing lubricant waste, energy consumption, and labor expenditures associated with manual greasing.
-
Heightened Focus on Worker Safety: In sectors such as mining, construction, and steel processing, lubricating hard-to-reach components poses significant occupational risks. Automated systems deliver lubricants directly to remote grease points without requiring technicians to enter hazardous machinery zones.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPMC00002537
Key Industry Players
The competitive landscape of the automatic lubrication system market features prominent global manufacturers and specialists driving innovation in pump technologies, distribution meters, and eco-friendly metering solutions. Key players operating in the global market include:
-
Cenlub Systems
-
Klüber Lubrication
-
Bijur Delimon
-
Alemite
-
ATS-Electro Lube
-
BEKAWORLD
-
SKF
-
Andantex
-
Graco
-
Groeneveld Lubrication Solutions
These industry leaders are actively focusing on strategic acquisitions, modular product designs, and sustainable minimal quantity lubrication (MQL) tech to expand their footprint across emerging industrial hubs.
Market Segmentation Highlights
By Type
- Oil lubrication system
- Grease lubrication system
By Application
- Manufacturing
- Cement
- Transportation
- Construction
- Agriculture
- Power
Future Outlook
The strategic horizon for the automatic lubrication system market points toward heightened digitalization, environmental sustainability, and custom modular architectures. Over the next decade, manufacturers will increasingly adopt eco-friendly, biodegradable lubricants alongside precision-metered dosage hardware to comply with strict international environmental standards and corporate sustainability goals.
Furthermore, the integration of edge computing and wireless monitoring modules into centralized pumps will transform lubrication from a routine maintenance task into an intelligent, data-driven utility. Emerging economies across Asia-Pacific and Latin America driven by expanding industrial infrastructure and mining investments are projected to create substantial market opportunities for leading equipment vendors throughout the 2026–2034 forecast period.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person : Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
Global UUV and USV Market Forecast 2034: Industry Developments and Competitive Landscape
By pratikblogsdata, 2026-10-21
International collaboration and research initiatives are supporting the development of advanced unmanned marine technologies. Partnerships among defense agencies, universities, research institutions, and private manufacturers are accelerating innovation in autonomous navigation, underwater sensing, and mission coordination.
Market Overview
The global unmanned underwater vehicle (UUV) and unmanned surface vehicle (USV) market is experiencing significant growth due to increasing demand for autonomous marine technologies, maritime security, ocean exploration, and underwater infrastructure monitoring. These vehicles operate with minimal or no direct human intervention, enabling organizations to perform complex marine operations efficiently, safely, and cost-effectively.
The global unmanned underwater vehicle (UUV) and unmanned surface vehicle (USV) market size is projected to reach US$ 15.45 billion by 2034 from US$ 4.65 billion in 2025 . The market is anticipated to register a CAGR of 22.55% during the forecast period 2026–2034 . This growth is supported by technological advancements in artificial intelligence (AI), robotics, navigation systems, sonar technology, and remote sensing capabilities.
Get a PDF Sample: https://www.theinsightpartners.com/sample/TIPTE100000692
UUVs are primarily designed for underwater missions, including seabed mapping, environmental monitoring, and submarine infrastructure inspection. In comparison, USVs operate on the water's surface and are increasingly used for maritime surveillance, hydrographic surveys, oceanographic research, and defense applications.
Key Market Growth Drivers
One of the major factors driving the UUV and USV market is the growing focus on maritime defense and national security. Governments and defense organizations are investing in autonomous marine vehicles for surveillance, mine detection, reconnaissance, and coastal protection. These systems can operate in challenging environments while reducing risks to human personnel.
The expansion of offshore energy projects is another important growth driver. Offshore oil and gas operators and renewable energy companies use unmanned vehicles to inspect underwater pipelines, wind turbine foundations, subsea cables, and other marine infrastructure. These technologies help reduce inspection costs and improve operational efficiency.
Additionally, increasing demand for oceanographic research and environmental monitoring is creating new opportunities. Research institutions use autonomous vehicles to collect information about marine ecosystems, water quality, ocean currents, and seabed conditions. Improvements in battery performance, communication technologies, and autonomous navigation are further enhancing the capabilities of these vehicles.
Unmanned Underwater Vehicle and Surface Vehicle Market Segmentation
The market is segmented by driving mechanisms, payload, and applications.
By Driving Mechanisms
-
Solar
-
Electric
-
Diesel
By Payload
-
Camera
-
Sensors
-
Sonar
-
Navigation Systems
By Applications
-
Commercial
-
Defense
-
Scientific Research
Electric-powered vehicles are gaining attention because of their suitability for quiet operations and reduced direct emissions. Solar-powered systems can support extended missions in appropriate operating conditions, while diesel-powered platforms can serve applications requiring different endurance and power capabilities.
In the payload segment, sonar systems, cameras, sensors, and navigation systems play essential roles in data collection, obstacle detection, mapping, and autonomous operation. Among applications, defense remains an important area of investment, while commercial operations and scientific research offer additional growth opportunities.
Key Players in the UUV and USV Market
Major companies operating in the global unmanned underwater vehicle and unmanned surface vehicle market include:
-
Kongsberg Gruppen
-
Teledyne Technologies
-
Lockheed Martin
-
ASV Global
-
Atlas Elektronik
-
ECA Group
-
Rafael Advanced Defense Systems
-
General Dynamics
-
Boeing
-
Clearpath Robotics
These companies focus on developing advanced autonomous marine platforms, improving sensor integration, expanding product capabilities, and strengthening their presence across commercial, defense, and scientific applications. Product innovation and strategic collaborations are expected to remain important competitive strategies.
Future Outlook
The future of the unmanned underwater vehicle and unmanned surface vehicle market looks promising as demand for autonomous marine operations continues to increase. The market's projected growth to US$ 15.45 billion by 2034 reflects expanding opportunities across defense, offshore energy, maritime logistics, environmental monitoring, and ocean research.
Advancements in AI-powered navigation, machine learning, energy-efficient propulsion, underwater communication, and real-time data processing are expected to improve vehicle autonomy and mission performance. Increasing investment in maritime security and offshore renewable energy infrastructure may further accelerate adoption.
However, challenges such as high initial development costs, limited underwater communication, battery constraints, regulatory requirements, and cybersecurity risks could affect market expansion. Companies that address these challenges through innovation, reliability, and cost-effective solutions are likely to strengthen their competitive positions.
Overall, the UUV and USV market is expected to witness substantial growth during 2026–2034, driven by technological innovation and increasing demand for safer, more efficient, and autonomous marine operations.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
Transplant Box Market to Reach US$ 390.96 Million by 2034 from US$ 185.24 Million in 2025
By Divya Sawant, 2026-10-21
The Transplant Box Market is expanding as healthcare providers increasingly prioritize organ preservation, safe transportation, and improved transplant outcomes. Transplant boxes are specialized containers designed to protect donor organs during transportation from the donor site to the recipient hospital.
Transplant Box Market Overview
The Transplant Box Market size is expected to reach US$ 390.96 Million by 2034 from US$ 185.24 Million in 2025. The market is estimated to record a CAGR of 8.65% from 2026 to 2034. These solutions help maintain appropriate preservation conditions and minimize damage during transit. Growing demand for organ transplantation, improvements in organ preservation technologies, and increasing emphasis on transplant logistics are supporting market development.
Download Sample Report: https://www.theinsightpartners.com/sample/TIPRE00019738
Transplant Box Market Growth Drivers
The increasing demand for organ transplantation is a major factor driving the Transplant Box Market. The need for kidney, liver, heart, lung, and other organ transplants has encouraged healthcare systems to strengthen organ procurement, preservation, and transportation processes. Reliable transplant boxes are essential for protecting organs during transit and helping transplant teams manage the time-sensitive requirements associated with transplantation procedures.
Technological advancements in organ preservation are also supporting market growth. Traditional cold-storage transport systems remain widely used, while newer solutions incorporate improved insulation, temperature monitoring, and tracking technologies. These features help healthcare professionals monitor transportation conditions and support the maintenance of suitable preservation environments. Growing collaboration among hospitals, organ procurement organizations, and medical logistics providers is further contributing to market development.
Transplant Box Market Trends and Growth Analysis
One of the key trends shaping the Transplant Box Market is the increasing integration of temperature monitoring and digital tracking technologies. Advanced transplant containers may incorporate sensors and monitoring systems that provide information about storage conditions during transportation. These capabilities can help transplant teams identify potential temperature deviations and improve visibility across the organ transportation process.
Another important trend is the growing interest in advanced organ preservation solutions. Alongside conventional static cold storage, machine perfusion technologies are increasingly being used for selected organs and clinical applications. These systems circulate preservation fluids through organs under controlled conditions and may support organ assessment and preservation. The development of specialized transport containers compatible with evolving preservation approaches is creating opportunities for manufacturers.
Key Factors Driving Market Expansion
The expansion of organ donation programs and transplant infrastructure is supporting demand for transplant boxes. Hospitals and transplant centers require dependable transportation equipment to coordinate organ recovery and delivery across different locations. Improvements in organ allocation networks and coordination among transplant professionals are increasing the importance of reliable containers that help protect organs throughout the transportation process.
Growing attention to organ safety, transportation reliability, and healthcare quality is also contributing to market growth. Manufacturers are focusing on durable materials, improved insulation, ergonomic designs, and monitoring features. In addition, investments in healthcare logistics and the expansion of transplantation services across emerging economies may create new opportunities for transplant box suppliers.
Transplant Box Market: Regional Outlook
North America represents an important region in the Transplant Box Market because of its established transplant infrastructure, organ procurement networks, and advanced healthcare facilities. Hospitals and transplant centers in the region require specialized equipment to support organ preservation and time-sensitive transportation. Continued developments in organ preservation technology and transplant coordination are contributing to demand for reliable transport solutions.
Europe is supported by established transplantation programs, clinical research, and cross-border healthcare coordination. Meanwhile, Asia Pacific offers growth opportunities as organ donation awareness increases and healthcare systems expand their transplantation capabilities. Investments in specialized medical facilities and improvements in organ transportation networks may support adoption across emerging economies. Regional growth will depend on organ donation rates, regulatory requirements, healthcare investment, and access to advanced preservation technologies.
Transplant Box Market: Competitive Landscape
The competitive landscape includes medical device manufacturers and organ preservation technology providers that develop transportation containers, preservation systems, and related transplant logistics solutions. Companies focus on improving preservation performance, container durability, temperature control, and compatibility with different organ transportation requirements.
Companies and technology providers active in the broader organ preservation and transplantation solutions landscape include:
-
TransMedics, Inc.
-
Organ Recovery Systems
-
XVIVO Perfusion AB
-
Paragonix Technologies, Inc
-
OrganOx Limited
-
IGL
-
HIbernicor
These companies operate across different segments of organ preservation, perfusion, and medical equipment. Not all specialize exclusively in transplant boxes. Competition in the broader market is influenced by preservation performance, product reliability, ease of use, monitoring capabilities, regulatory compliance, and cost.
Transplant Box Market: Future Outlook
The Transplant Box Market is expected to benefit from continued demand for organ transplantation, improvements in preservation technologies, and increasing emphasis on reliable medical logistics. Innovations in insulation, temperature monitoring, tracking systems, and specialized preservation containers may improve the management of organs during transportation. The expansion of transplant centers and organ donation programs may further support demand for dependable transport solutions.
Future market development will depend on advances in organ preservation, healthcare infrastructure, regulatory standards, and coordination between organ procurement organizations and transplant centers. The integration of digital monitoring technologies and the development of specialized containers for different organ types may create additional opportunities. Continued innovation will remain important for supporting organ quality, transportation safety, and successful transplantation procedures.
About US
The Insight Partners provides comprehensive syndicated and tailored market research services across the healthcare, technology, and industrial sectors. The company delivers market intelligence and strategic insights to help organizations understand emerging trends, identify growth opportunities, and make informed business decisions in rapidly evolving markets.
Contact Us
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Also Available in : Korean German Japanese French Chinese Italian Spanish
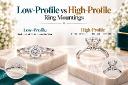
When customers describe the ring they want, they rarely say "profile." They say things like "something that won't catch on my sweaters" or "I want it to really stand out." Both comments are about the same design variable: how high the stone sits above the finger. Low-profile vs high-profile ring mountings is one of the most practical distinctions in ring design, and understanding it helps jewellers recommend the right piece the first time.
This guide explains what profile means, how each type performs in security, brilliance, comfort and style, and how to match the right mounting to the right wearer.
What "Profile" Means in a Ring Mounting
Profile describes how far the center stone, or the main design element, rises above the finger. A high-profile mounting lifts the stone well above the band, usually on a taller basket with longer prongs. A low-profile mounting seats the stone close to the finger, sometimes almost flush with the band.
There is no official measurement that separates the two. In practice, the difference is easy to see from the side. High-profile rings show a visible gap between the band and the base of the stone. Low-profile rings look compact and grounded.
High-Profile Ring Mountings
High-profile mountings are the classic look many people picture for an engagement ring. Cathedral settings, tall prong baskets and elevated halos all fall into this group.
Advantages
- Maximum brilliance. A raised stone receives light from more angles, including from the sides, which boosts sparkle.
- Greater visual presence. Height makes the stone look bigger and more dramatic on the hand.
- Easier cleaning. Open space beneath the stone makes it simpler to clean away oils and dust.
- Room for design detail. The raised gallery can carry hidden halos, filigree or detailed metalwork.
Trade-offs
- More exposure to knocks. A tall setting is more likely to catch on clothing, gloves or surfaces.
- Higher risk of prong wear. Longer prongs experience more leverage and may need more frequent inspection.
- Less suited to active hands. Hands-on work and sport can be harder on a raised setting.
Low-Profile Ring Mountings
Low-profile mountings sit closer to the hand. Bezel settings, flush settings, channel settings and compact prong baskets typically fall into this category.
Advantages
- Better protection. A stone seated close to the band is less exposed to impact.
- Snag resistance. The smooth profile slides under sleeves and gloves with little catching.
- Comfort for daily wear. Less height means less bulk, which many wearers prefer.
- Stacking-friendly. Low rings pair easily with wedding bands and other stacked rings.
Trade-offs
- Slightly less brilliance. With more metal around the stone and less light entering from the sides, sparkle can be a little more subdued.
- Harder to clean underneath. Tight construction can trap residue.
- A quieter look. Customers wanting a bold statement may find it understated.
Side-by-Side Comparison
|
Factor |
Low-Profile |
High-Profile |
|
Stone security |
Higher, more protected |
Good, but more exposed |
|
Brilliance |
Moderate to good |
Maximum |
|
Snagging risk |
Low |
Higher |
|
Everyday comfort |
Excellent |
Good |
|
Visual impact |
Subtle |
Dramatic |
|
Cleaning access |
More limited |
Easier |
|
Stacking with other rings |
Easy |
Can be awkward |
Matching Profile to Lifestyle
The best way to choose is to ask about daily life, not just style. Someone who works with their hands, exercises often, or wears gloves regularly will usually be happier with a low-profile mounting. Someone with a lower-impact routine, who wants a ring that makes a statement, is better placed to enjoy a high-profile design.
A quick question such as "What does a normal day look like for your hands?" usually reveals more than a long conversation about design preferences.
Matching Profile to Stone Shape
Stone shape also affects the decision. Elongated stones such as marquise and pear have vulnerable points, and a lower, well-protected seat can help guard those tips. Large stones carry more weight and leverage, so very tall settings need especially solid construction. Round and cushion cuts are more forgiving and work comfortably at either height.
Profile in Ladies and Gents Collections
The two categories lean in different directions. Ladies engagement rings often favour higher profiles, since a raised stone maximises sparkle and presence. A well-chosen Ladies Ring Mounting range should therefore include both elevated cathedral and halo styles and lower, more protective options for active wearers.
Gents rings lean the other way. Durability and everyday comfort usually matter most, so flush, bezel and channel-style designs dominate. A focused Gents Ring Mounting collection built around low-profile construction serves the majority of men's jewellery buyers well, with a few raised options for those who want more presence.
What to Check When Sourcing Either Type
- Prong strength on tall settings. Longer prongs need adequate thickness and precise finishing.
- Seat accuracy on low settings. A stone sitting close to the band must be seated precisely to stay secure.
- Underside finishing. Check the gallery and base on both styles.
- Stone-size tolerance for semi-mounts. Settings should accept normal variation in stone dimensions.
- Consistency across the batch. Height and proportions should match from piece to piece.
Frequently Asked Questions
1. Is a low-profile ring mounting safer for the stone?
Generally yes. Because the stone sits closer to the finger, it is less exposed to knocks and snagging, which makes low-profile settings a good choice for active wearers.
2. Do high-profile settings make a diamond look bigger?
They can. Raising the stone gives it more presence and lets in more light, so it often appears larger and brighter than the same stone in a low seat.
3. Can a ring be both low-profile and sparkly?
Yes. Halo and pavé details, and well-cut stones in compact prong settings, can deliver strong sparkle while keeping a low, comfortable height.
Final Thoughts
Low-profile vs high-profile is not a question of better or worse. It is a trade-off between protection and drama, and the right answer depends on how the ring will be worn. Jewellers who ask about daily life, match profile to stone shape, and stock both styles across ladies and gents collections give customers a ring that looks right and stays right for years.
Silicon Photonics Transceiver Market Forecast 2034: Strong Growth at a CAGR of 14.49%
By nitinbbb, 2026-10-21
Silicon Photonics Transceiver technology is expected to play an important role in next-generation optical networking. Continued advances in integration and production could expand its use in high-speed communication systems.
The silicon photonics transceiver market is gaining momentum as demand for high-speed data transmission, cloud computing, artificial intelligence (AI), and advanced networking infrastructure continues to increase. Silicon photonics transceivers use optical technology integrated with silicon-based components to transmit and receive data through light signals. These devices support high-bandwidth communication and are increasingly relevant to data centers, telecommunications networks, and high-performance computing environments.
The Silicon Photonics Transceiver Market size is expected to reach US$ 4.55 Billion by 2034 from US$ 1.35 Billion in 2025. The market is estimated to record a CAGR of 14.49% from 2026 to 2034. According to The Insight Partners, growing demand for high-speed data transmission and advancements in data center infrastructure are important factors supporting market growth.
Market Drivers
The increasing volume of digital information is a major driver of the silicon photonics transceiver market. Businesses and consumers depend on cloud applications, online services, video streaming, and connected platforms that require reliable, high-speed data transfer. Conventional electrical interconnects face challenges related to power consumption and signal transmission as data rates increase. Silicon photonics technology offers an optical alternative for supporting high-bandwidth communication.
Get Access Report Sample: https://www.theinsightpartners.com/sample/TIPRE00014541
The expansion of data centers is another important growth factor. Cloud service providers and hyperscale data center operators need efficient connections between servers, switches, storage systems, and computing accelerators. Silicon photonics transceivers can support high-speed optical links while helping address space and power constraints in modern facilities.
Artificial intelligence and high-performance computing are also creating new opportunities. AI workloads require substantial data movement between processors, accelerators, and memory systems. As computing infrastructure expands, demand for efficient optical interconnects is likely to increase.
Technological Developments and Market Opportunities
Advancements in photonic integration are shaping product development. Silicon photonics platforms can integrate components such as modulators, photodetectors, and optical waveguides into compact designs. This integration can reduce component complexity and support higher levels of functionality.
Manufacturers are also working to improve data rates, energy efficiency, reliability, and manufacturing scalability. These developments are important for data centers and telecommunications operators seeking to increase network capacity without proportionally increasing energy requirements.
The expansion of fifth-generation (5G) networks, cloud computing, and emerging AI applications may further support market opportunities. Silicon photonics transceivers may also find applications in advanced sensing, medical technologies, and selected automotive systems as optical integration capabilities develop.
Regional Market Overview
North America is an important market due to its established technology industry, data center investments, cloud infrastructure, and demand for high-speed connectivity. Continued investment in AI computing infrastructure may create additional opportunities for optical transceiver suppliers.
Europe offers growth potential through telecommunications modernization, digital infrastructure investment, and research into photonic technologies. Adoption will depend on network upgrades, enterprise requirements, and investment in advanced computing systems.
Asia Pacific is also significant because of its electronics manufacturing capabilities, expanding telecommunications networks, and investment in data centers. China, Japan, South Korea, and India are relevant markets for optical communication technologies. South and Central America, along with the Middle East and Africa, may present opportunities as digital infrastructure and connectivity investments expand.
Key Players in the Silicon Photonics Transceiver Market
The competitive landscape includes semiconductor manufacturers, optical communication suppliers, and technology companies. Key players identified in the market include:
- Acacia Communications, Inc.
- Cisco Systems, Inc.
- II-VI Incorporated
- GlobalFoundries
- Hamamatsu Photonics K.K.
- IBM
- Intel Corporation
- Juniper Networks, Inc.
- NVIDIA Corporation
- STMicroelectronics
These companies operate across various parts of the semiconductor, optical communication, and networking industries. Competition may focus on optical performance, power efficiency, product integration, manufacturing capacity, reliability, and compatibility with next-generation networking equipment.
Market Challenges
Despite its growth potential, the silicon photonics transceiver market faces several challenges. Integrating optical and electronic components can involve complex design, packaging, testing, and manufacturing processes. Companies must maintain reliable performance while meeting increasingly demanding data-rate and power-efficiency requirements.
Manufacturing scalability and production costs can also influence adoption. Compatibility with existing network infrastructure, thermal management, and dependable component supply are additional considerations for equipment manufacturers and data center operators. Continued advances in design and production processes will be important to address these challenges.
Future Outlook
The silicon photonics transceiver market is expected to benefit from growing AI workloads, expanding cloud infrastructure, rising data traffic, and the modernization of telecommunications networks. Continued development of integrated photonic circuits may improve performance and enable more efficient optical communication systems. Data centers and high-performance computing facilities are likely to remain important application areas, while emerging medical, defense, and automotive uses could create additional opportunities. With the market projected to reach US$ 4.55 billion by 2034 at a CAGR of 14.49% during 2026–2034, investment in innovation, scalable manufacturing, and energy-efficient optical technologies will be important to future market development.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in :
The Trocars Market is expanding as healthcare providers increasingly adopt minimally invasive surgical techniques to improve procedural precision, reduce patient recovery time, and minimize surgical trauma.
Trocars Market Overview
The Trocars Market size is expected to reach US$ 1.17 Billion by 2031. The market is anticipated to register a CAGR of 5.6% during 2025-2031. Trocars are medical devices used to create access ports through the body wall, allowing surgeons to introduce instruments and cameras during laparoscopic and other minimally invasive procedures. Growing demand for laparoscopic surgeries, advancements in surgical technologies, and increasing preference for procedures associated with smaller incisions are supporting market development.
Download Sample Report: https://www.theinsightpartners.com/sample/TIPRE00003480
Trocars Market Growth Drivers
The rising adoption of minimally invasive surgery is a major factor driving the Trocars Market. Procedures such as laparoscopic cholecystectomy, bariatric surgery, gynecological surgery, and colorectal surgery frequently require trocar systems to establish access to the surgical site. Compared with conventional open surgery, minimally invasive approaches can offer benefits such as smaller incisions, reduced postoperative discomfort, and shorter hospital stays in appropriate clinical situations.
Technological advancements in trocar design are also contributing to market growth. Manufacturers are developing devices with improved sealing mechanisms, ergonomic designs, enhanced visualization, and safety features intended to reduce tissue trauma and gas leakage. The growing use of disposable and specialized trocar systems is further supporting demand as healthcare facilities focus on infection prevention, procedural efficiency, and consistent device performance.
Trocars Market Trends and Growth Analysis
One of the key trends shaping the Trocars Market is the increasing integration of trocar systems with advanced minimally invasive surgical platforms. The expansion of laparoscopic and robotic-assisted procedures is encouraging demand for devices that provide reliable access, maintain pneumoperitoneum, and support precise instrument movement. Compatibility with different surgical instruments and procedural requirements is becoming an important consideration for healthcare providers.
Another significant trend is the growing emphasis on patient safety and infection control. Single-use trocars are used in many surgical settings to reduce concerns associated with instrument reprocessing, while reusable systems remain relevant in facilities with established sterilization protocols. Manufacturers are also improving trocar tip configurations, valve systems, and access-port designs to support safe insertion and reliable performance across different surgical procedures.
Key Factors Driving Market Expansion
The increasing number of minimally invasive surgical procedures is supporting demand for trocars across hospitals, ambulatory surgical centers, and specialty clinics. Growing healthcare expenditure, improved access to surgical treatment, and the expansion of specialized surgical facilities are contributing to the adoption of trocar-based procedures. As surgical teams seek to improve procedural efficiency and patient outcomes, demand for dependable access devices continues to develop.
The expansion of robotic-assisted surgery and ongoing innovation in surgical instruments are creating additional opportunities for the Trocars Market. Advanced procedures often require specialized access systems designed to accommodate instrument movement and maintain stable operating conditions. Product development, surgeon training, regulatory compliance, and collaboration between medical device manufacturers and healthcare providers are expected to remain important factors influencing market growth.
Trocars Market: Regional Outlook
North America represents an important region in the Trocars Market due to its established healthcare infrastructure, high adoption of minimally invasive surgical procedures, and access to advanced surgical technologies. Hospitals and ambulatory surgical centers increasingly use laparoscopic and robotic-assisted techniques across several specialties. The presence of medical device manufacturers and ongoing investment in surgical innovation further support regional demand.
Europe is supported by established surgical care systems, increasing adoption of minimally invasive techniques, and continued development of advanced medical devices. Asia Pacific offers growth opportunities as healthcare infrastructure expands, surgical capabilities improve, and access to minimally invasive procedures increases. Rising healthcare investment and growing awareness of the benefits associated with minimally invasive surgery are supporting demand across emerging economies. Regional growth will depend on healthcare spending, device affordability, training, and access to advanced surgical equipment.
Trocars Market: Competitive Landscape
The competitive landscape includes medical device companies that manufacture laparoscopic access devices, trocar systems, and related minimally invasive surgical instruments. Market participants focus on product innovation, safety mechanisms, improved ergonomics, and compatibility with evolving surgical technologies.
Key companies operating in the broader trocar and minimally invasive surgical device landscape include:
-
Applied Medical Resources Corporation
-
B. Braun Melsungen AG
-
Conmed Corporation
-
Genicon, Inc.
-
Johnson & Johnson Services, Inc. (Ethicon, Inc.)
-
Laprosurge
-
Medtronic
-
Purple Surgical
-
The Cooper Companies, Inc.
-
Teleflex Incorporated
Competition is influenced by device reliability, safety features, ease of use, product range, pricing, regulatory compliance, and relationships with hospitals and surgical centers.
Trocars Market: Future Outlook
The Trocars Market is expected to benefit from the continued adoption of minimally invasive surgery, advancements in surgical instrument design, and growing demand for efficient surgical access solutions. Improvements in trocar safety features, sealing technologies, and ergonomic designs may support more reliable use across laparoscopic and robotic-assisted procedures. Expansion of surgical infrastructure in developing healthcare markets may also create new opportunities for manufacturers.
Future market development will depend on continued technological innovation, surgeon training, regulatory requirements, and healthcare providers' ability to invest in advanced surgical equipment. Manufacturers may increasingly focus on specialized trocar systems designed for specific procedures and surgical platforms. The ongoing shift toward minimally invasive approaches is likely to remain an important factor shaping demand for trocar devices.
About US
The Insight Partners provides comprehensive syndicated and tailored market research services across the healthcare, technology, and industrial sectors. The company delivers market intelligence and strategic insights to help organizations understand emerging trends, identify growth opportunities, and make informed business decisions in rapidly evolving markets.
Contact Us
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Also Available in : Korean German Japanese French Chinese Italian Spanish
Underground Mining Equipment Market Growth Analysis: From US$ 43.6 Billion in 2025 to US$ 61.14 Billion by 2034
By pratikblogsdata, 2026-10-21
The underground mining equipment industry is also focusing on sustainability and energy efficiency. Manufacturers are developing machines that reduce emissions, improve energy utilization, and support environmentally responsible mineral extraction practices.
Underground Mining Equipment Market Overview
The global Underground Mining Equipment Market is experiencing steady growth due to increasing demand for minerals, metals, and coal across various industries. Underground mining equipment plays a vital role in extracting valuable resources from beneath the earth's surface while improving operational efficiency, worker safety, and productivity. These machines are widely used in mining operations where surface mining is impractical or where mineral deposits are located deep underground.
The global Underground Mining Equipment market was valued at US$ 43.6 billion in 2025 and is expected to reach US$ 61.14 billion by 2034 , recording a CAGR of 3.83% during 2026–2034 . The market's expansion is supported by growing industrialization, rising infrastructure investments, and increasing demand for essential minerals used in construction, manufacturing, energy production, and advanced technologies.
Get a PDF Sample: https://www.theinsightpartners.com/sample/TIPRE00005953
Key Factors Driving the Underground Mining Equipment Market
One of the major factors driving the underground mining equipment market is the increasing demand for metals and minerals. Copper, gold, iron ore, and other valuable resources are essential for infrastructure development, renewable energy systems, electric vehicles, and electronic products. As easily accessible mineral deposits become more limited, mining companies are increasingly investing in underground operations to access deeper reserves.
Technological advancements are also contributing to market growth. Automation, remote-controlled machinery, digital monitoring systems, and advanced drilling technologies are helping mining operators improve productivity and reduce operational risks. Electric and battery-powered underground mining equipment is gaining attention because it can reduce diesel emissions, improve underground air quality, and potentially lower ventilation requirements.
Additionally, mining companies are focusing on equipment modernization to enhance worker safety, minimize downtime, and optimize resource extraction. These developments are expected to create opportunities for equipment manufacturers throughout the forecast period.
Underground Mining Equipment Market Segmentation
The underground mining equipment market is segmented by mining type and application.
By Mining Type
-
Strip Pillar Mining: This method involves extracting mineral resources while leaving selected pillars to support the surrounding rock structure. Equipment used in these operations helps maintain stability and improve extraction efficiency.
-
Room and Pillar Mining: This technique creates a network of rooms separated by supporting pillars. It is commonly used in suitable coal and mineral deposits, requiring specialized cutting, loading, and transportation equipment.
-
Thickness-Limited Extraction: This approach focuses on extracting resources from deposits with specific thickness constraints. Specialized equipment can help improve precision and reduce unnecessary material removal.
By Application
-
Coal: Underground mining equipment is widely used for coal extraction, transportation, and material handling to support industrial and energy requirements.
-
Metal: Metal mining operations depend on drilling rigs, loaders, haulage systems, and other machinery to extract valuable ores such as copper, gold, and zinc.
-
Mineral: Equipment used in mineral mining supports the extraction of industrial minerals and other resources required by manufacturing, construction, and related industries.
Key Players in the Underground Mining Equipment Market
Major companies operating in the underground mining equipment market include:
-
Atlas Copco (India) Ltd
-
Boart Longyear
-
Caterpillar Inc.
-
Epiroc Finland Oy Ab
-
J.H. Fletcher and Co.
-
Komatsu Mining Corp
-
Sandvik AB
-
thyssenkrupp AG
-
Liebherr
-
FLSmidth
These companies focus on equipment innovation, automation, product development, and customer support to strengthen their market positions. Investments in efficient machinery, advanced safety features, and sustainable mining solutions are important competitive strategies.
Future Outlook of the Underground Mining Equipment Market
The future of the underground mining equipment market is expected to be shaped by automation, electrification, digitalization, and growing demand for critical minerals. Mining operators are likely to increase investments in autonomous vehicles, remote-operated drilling systems, predictive maintenance technologies, and connected equipment to improve productivity and reduce equipment downtime.
The transition toward cleaner mining operations may also accelerate the adoption of battery-electric machinery and energy-efficient equipment. At the same time, stricter safety requirements and the need to access deeper mineral deposits are expected to encourage further technological improvements.
Although high initial equipment costs, maintenance expenses, and fluctuations in commodity prices may challenge market growth, ongoing investments in mining infrastructure are expected to support demand. With the market projected to reach US$ 61.14 billion by 2034, manufacturers that prioritize operational efficiency, safety, and sustainable technologies are well positioned to capitalize on emerging opportunities.
Overall, the underground mining equipment market is anticipated to maintain steady growth through 2034, supported by resource demand, technological innovation, and the modernization of mining operations worldwide.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The Industrial Salt Market was valued at USD 17.02 billion in 2025 and is projected to surge to nearly USD 24.94 billion by 2034 , registering a robust compound annual growth rate (CAGR) of 4.34% during the forecast period.
As chemical manufacturing ecosystems expand and municipal authorities grapple with extreme winter weather variability, industrial salt—primarily sodium chloride extracted via rock salt mining, natural brining, and solar evaporation—has cemented its position as a critical raw material for global heavy industry.
The industrial salt landscape is experiencing a renaissance propelled by heavy chemical processing requirements and rigorous public safety mandates. At the heart of this market transformation is the chlor-alkali process, where industrial salt serves as the essential baseline compound for manufacturing chlorine, caustic soda, and hydrogen. These derivatives feed directly into rapidly growing downstream sectors, including polymers, glass, paper, water treatment, and metallurgy.
Key Findings from the Report
-
Market Valuation & Trajectory: The global industrial salt market reached USD 17.02 billion in 2025 and is on track to hit USD 24.94 billion by 2034, scaling at a 4.34% CAGR.
-
Dominant Application Segment: Chemical processing—anchored by chlor-alkali manufacturing—remains the leading revenue contributor, driven by escalating global demand for caustic soda and chlorine derivatives.
-
Source Segmentation: Rock salt extraction and solar evaporation methods capture the lions-share of volume, with solar salt favored for cost-effectiveness and rock salt prized for heavy industrial and de-icing applications.
-
Regional Dominance: Asia-Pacific stands as the undisputed global leader, propelled by massive manufacturing output in China (53 million tons produced in 2025) and India (30 million tons, anchored by Gujarat).
-
Export & Trade Hubs: Germany leads global export volumes with over 14,750 recorded shipments, closely followed by India as the second-largest global exporter with nearly 13,800 shipments.
-
Major Import Destinations: Vietnam and the Netherlands register as the primary global import hubs, feeding domestic processing and packaging industries.
-
Investment Relevance: Heightened volatility in maritime freight and localized supply shortages are encouraging long-term offtake agreements and localized near-shoring strategies among chemical giants.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/industrial-salt-market/2450
Market Drivers and Restraints
Drivers
-
Expansion of the Chlor-Alkali Industry: The continuous global buildout of chemical plants requiring stable, high-purity sodium chloride inputs directly accelerates base demand.
-
Unpredictable Winter Weather and De-Icing Mandates: Severe seasonal weather patterns across North America and Europe dictate heavy, inelastic year-round storage and purchasing by departments of transportation.
-
Growth in Water Treatment and Industrial Applications: Surging municipal investments in water softening, oil and gas well drilling, and metal processing expand the utility footprint of specialized industrial salt grades.
Restraints
-
Supply Chain and Logistical Vulnerabilities: Natural disasters, inland freight blockages, and geopolitical friction frequently disrupt maritime shipping routes, causing localized price spikes and inventory delays.
-
Stringent Environmental and Extraction Regulations: Growing regulatory scrutiny over brine discharge, ecosystem preservation around solar evaporation ponds, and carbon-intensive logistics constrain unbridled mining expansion.
Technology, Regulation, and Sustainability Trends
Modern industrial salt operations are undergoing an operational overhaul driven by automated crystallization monitoring, advanced solar-pond hydro-dynamics, and digital supply chain tracking. Regulatory pressures, particularly regarding industrial effluent management and carbon taxation on maritime shipping, are forcing Tier-1 salt producers to invest in low-emission logistics and eco-friendly harvesting practices. Furthermore, adherence to strict chemical purity standards (ISO and ASTM certifications) is redefining quality benchmarks, separating low-grade commodity suppliers from high-value industrial refiners.
Regional Insights
-
Asia-Pacific (Leading Region): Asia-Pacific dominates the global market landscape, powered by China’s staggering 53 million tons of annual production and India’s robust output centered in Gujarat. Rapid industrialization, favorable coastal evaporation climates, and aggressive infrastructure investments position APAC as both the largest producer and consumer.
-
North America and Europe (Established & High-Demand Hubs): Driven by stringent winter road maintenance and advanced chemical manufacturing clusters, these regions maintain steady demand. Germany anchors European trade strength as the world's leading exporter.
-
Emerging Markets (Middle East & Latin America): These regions are witnessing accelerated exploration of underground salt domes and brine reserves to supply localized petrochemical complexes.
Recent Industry Developments
-
K+S AG (2025): Deployed advanced automated logistics tracking across its European mining network, reducing delivery turnaround times by 12% for core chemical clients.
-
Cargill Inc. (2025): Invested in sustainable solar-salt purification upgrades at key North American processing facilities, curbing freshwater consumption intensity by 15%.
-
Compass Minerals (2024): Secured a multi-year municipal de-icing supply contract extension in North America valued at over USD 45 million, stabilizing regional inventory buffers.
-
Archean Chemical Industries (2025): Expanded bromine and industrial salt production capacity in Western India by 20%, capitalizing on robust regional chlor-alkali demand.
-
Government of India (2024): Introduced modernized coastal salt-pan modernization policies under state industrial frameworks to streamline logistics for export-bound maritime shipments.
Competitive Landscape
The global industrial salt market features a consolidated yet intensely competitive ecosystem dominated by major multinational players. Leading corporations such as Cargill, K+S AG, Compass Minerals, Tata Chemicals, and Archean Chemical Industries are actively expanding their operational footprints through strategic cross-border acquisitions, long-term supply contracts, and capacity optimization. Competitors are heavily differentiating through high-purity product lines tailored for specialized pharmaceutical and advanced chemical synthesis.
Analyst Commentary
"Industrial salt is no longer viewed merely as a low-margin bulk commodity; it has evolved into a strategic anchor for the global chemical and infrastructure supply chains," said a Senior Research Analyst at Stellar Market Research. "As chemical processing plants scale up in Asia-Pacific and supply chain resilience dictates procurement strategies, producers that leverage automation, sustainable brine management, and diversified logistics will capture disproportionate market value through 2034."
Future Outlook
Through the 2034 forecast horizon, the industrial salt market will experience a definitive shift toward premiumization, high-purity standardization, and green logistics. While traditional de-icing will maintain a predictable baseline, exponential growth in chlor-alkali derivatives and clean-energy infrastructure inputs will propel market values higher. Stakeholders that successfully integrate digital supply chain transparency and carbon-efficient transport will lead the next generation of industrial growth.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/industrial-salt-market/2450
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656
Asteroid Mining Market Forecast: Valuation to Touch US$ 13.85 Billion by 2034 at a CAGR of 20.22%
By Sam Karan, 2026-10-21
Asteroid mining operations will rely entirely on advanced autonomous robotics and artificial intelligence. Because communication delays make real-time human control impossible, automated rovers and drills must perform delicate extraction tasks independently. These resilient machines will need to withstand extreme temperature fluctuations and harsh cosmic radiation. Developing such robust technology pushes the boundaries of modern engineering.
The global Asteroid Mining Market , valued at US$ 2.64 billion in 2025 , is entering an era of unprecedented expansion. Driven by breakthrough innovations in deep-space exploration, reusable launch vehicles, and automated extraction technologies, the market is projected to reach US$ 13.85 billion by 2034 , recording a robust Compound Annual Growth Rate (CAGR) of 20.22% during the forecast period from 2026 to 2034 .
As terrestrial resources face increasing supply strain and costs, public and private entities are looking beyond Earth's atmosphere to secure vital minerals, precious metals, and water ice essential for sustained space infrastructure.
Key Drivers Fueling Market Expansion
The rapid trajectory of the global asteroid mining sector is bolstered by several technological and strategic catalysts:
-
Technological Advancements in Autonomous Spacecraft: Innovations in autonomous navigation, AI-driven prospectors, and miniaturized robotics have dramatically reduced mission failure risks and deployment overhead.
-
Emergence of Reusable Launch Systems: The commercial availability of heavy-lift, reusable rockets has significantly lowered cargo payload costs per kilogram, rendering commercial deep-space reconnaissance economically viable.
-
Resource In-Situ Utilization (ISRU): Extraction of water ice from Near-Earth Asteroids (NEAs) provides life support and propellant fuel (hydrogen and oxygen), creating orbital refueling depots that reduce the cost of deep-space journeys.
-
High-Value Precious Metals: Metallic asteroids (Type M and Type S) contain dense deposits of platinum-group metals (PGMs), gold, rare earths, and high-purity iron-nickel, attracting immense investment from commercial space venture funds.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPRE00022347
Competitive Landscape: Key Market Players
Industry pioneers and visionary space technology enterprises are driving strategic partnerships, technology demonstrations, and satellite constellation deployments. Leading market players shaping the future of off-world resource extraction include:
-
Asteroid Mining Corporation Limited
-
Bradford
-
iSpace, Inc.
-
Kleos Space
-
Moon Express
-
ConsenSys
-
Spacefab.US
-
Sierra Nevada Corporation
-
OffWorld
-
Virgin Galactic
These industry key players are actively collaborating with national space agencies, research institutions, and defense organizations to pioneer satellite systems, deep-space probes, and surface robotics suited for microgravity extraction environments.
Future Outlook: A New Horizon for the Off-World Economy
The future of the Asteroid Mining market extends far beyond simple earthbound commodity harvesting. Between 2026 and 2034, the sector is set to evolve into the foundational layer of a broader off-world economy.
Over the next decade, market analysts predict:
-
Public-Private Frameworks: Stronger international legal frameworks under international space accords will provide greater regulatory certainty for private property rights on celestial bodies.
-
In-Space Manufacturing: Extracted resources will increasingly be refined and utilized in situ , manufacturing orbital solar arrays, satellites, and structural components directly in microgravity.
-
Cross-Industry Synergies: Traditional mining behemoths, defense contractors, and energy conglomerates are anticipated to form strategic alliances with space tech startups, bridging terrestrial mining experience with aerospace engineering.
As humanity steps further into commercial space utilization, the Asteroid Mining market stands at the threshold of transforming resource scarcity into infinite orbital abundance.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person : Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
Global Variable Frequency Drive Market to Register 5.6% CAGR During 2023–2031
By nitinbbb, 2026-10-21
Variable Frequency Drive technology is expected to remain important as industrial facilities modernize equipment and adopt connected automation systems. Improvements in energy efficiency, monitoring, and control capabilities may support future demand.
The variable frequency drive market is gaining importance as industries increasingly focus on energy efficiency, industrial automation, and reliable motor control. Variable frequency drives (VFDs) regulate the speed of electric motors by adjusting the frequency and voltage of the supplied electrical power. These systems are widely used in manufacturing, infrastructure, oil and gas, power generation, and commercial building applications.
The variable frequency Drive market size is projected to reach US$ 34.01 billion by 2031 from US$ 22.03 billion in 2023. The market is expected to register a CAGR of 5.6% during 2023–2031. Increasing industrial modernization, demand for energy-efficient equipment, and the expansion of automated production processes are important factors supporting market development.
Market Drivers
Energy efficiency is one of the major factors driving the variable frequency drive market. Electric motors operate pumps, fans, compressors, conveyors, and industrial machinery. When motors run continuously at fixed speeds, they may consume more electricity than necessary under changing operating conditions. VFDs allow motor speed to be adjusted according to actual demand, helping improve energy utilization and control operating expenses.
Get Access Report Sample: https://www.theinsightpartners.com/sample/TIPTE100000488
The growing adoption of industrial automation is another significant driver. Manufacturers are investing in automated equipment to improve productivity, reduce process interruptions, and maintain consistent product quality. Variable frequency drives provide precise motor control, supporting flexible production operations across different industries.
Increasing construction and infrastructure development also create opportunities for VFD adoption. Commercial buildings, hospitals, industrial facilities, and public infrastructure use HVAC systems that require efficient control of pumps and fans. VFDs help these systems respond to changing temperature and airflow requirements.
Technological Developments and Opportunities
Technological advancements are expanding the capabilities of modern variable frequency drives. Manufacturers are developing solutions that support digital communication, remote monitoring, and integration with industrial automation platforms. These features help operators monitor drive performance and identify potential equipment problems.
The adoption of the Industrial Internet of Things is creating opportunities for connected drive systems. When integrated with monitoring platforms, VFDs can provide operational information that helps maintenance teams assess equipment performance and identify irregularities. This approach can support predictive maintenance and reduce unplanned downtime.
Energy management programs are also encouraging businesses to evaluate motor-driven equipment. VFDs can contribute to improved energy performance when applied to suitable variable-load systems. Industries with extensive pumping, ventilation, and material-handling operations represent important areas of potential demand.
Regional Market Overview
Asia Pacific represents an important market for variable frequency drives because of its manufacturing activity, infrastructure investment, and industrial automation initiatives. Countries such as China, India, Japan, and South Korea offer applications across manufacturing, building systems, and industrial equipment.
North America benefits from industrial modernization, energy management initiatives, and investment in automated manufacturing. Demand may also be supported by upgrades to existing industrial facilities and the integration of connected control systems.
Europe offers opportunities through energy efficiency measures, advanced manufacturing, and building automation. Meanwhile, infrastructure development and industrial investment in other regions may create additional opportunities for VFD suppliers.
Key Players in the Variable Frequency Drive Market
The competitive landscape includes established electrical equipment suppliers and industrial automation companies. Key players include:
- Fuji Electric Co. Ltd
- Mitsubishi Electric Corporation
- Siemens AG
- ABB Ltd.
- American Electric Technologies Inc. (AETI)
- General Electric Company
- Hitachi Limited
- Honeywell International Inc.
- Rockwell Automation Inc.
- Johnson Controls Inc.
These companies participate in the broader industrial control and electrical equipment market. Competition is influenced by product reliability, energy efficiency, control capabilities, system compatibility, technical support, and the ability to serve different industrial requirements.
Market Challenges
Despite the benefits of variable frequency drives, implementation can involve challenges. Initial equipment costs, installation expenses, integration with existing systems, and the need for skilled technicians may affect adoption, particularly among smaller businesses.
VFD installations can also introduce harmonics and electromagnetic interference if systems are not appropriately designed. Selecting compatible equipment, using suitable filtering solutions, and following recommended installation practices can help address these concerns. Businesses must also consider maintenance requirements and the operating conditions of their motor-driven equipment.
Future Outlook
The variable frequency drive market is expected to benefit from continued industrial automation, energy efficiency initiatives, and investment in modern manufacturing and infrastructure. Demand for connected motor control solutions may increase as businesses adopt digital monitoring and improve equipment performance. Manufacturers are likely to focus on reliable, energy-efficient, and digitally integrated products for industrial and commercial applications. With the market projected to reach US$ 34.01 billion by 2031 and register a CAGR of 5.6% during 2023–2031, opportunities are expected across several end-user industries. Future market development will depend on capital investment, technology adoption, energy management priorities, and the ability of businesses to achieve operational benefits from VFD installations.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in :