

Blogs
Lab Glassware Market 2026: The 4.7% CAGR Trajectory and What It Reveals
By PW Consulting, 2026-09-21
Navigating the Laboratory Glassware Market: Strategic Trends and Commercial Imperatives
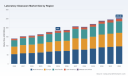
The laboratory glassware market is entering a phase of structural transformation, driven by technological refinement, evolving regulatory expectations, and shifting procurement behaviors across end-user segments. Valued at approximately USD 185.0 million in 2025, the market has expanded from USD 140.5 million in 2020, reflecting steady compounding growth over the post-pandemic period. Forward projections indicate a trajectory toward USD 253.28 million by 2032, with a compound annual growth rate of 4.7 percent across the forecast horizon. This expansion is not merely incremental; it reflects a market responding to heightened precision requirements, supply chain recalibration, and the integration of traceability and standardization into routine laboratory operations. For executives, investors, and procurement leaders, the window to align product portfolios, capital allocation, and sourcing strategies with these underlying shifts is opening now.
Market Snapshot: Growth Trajectory and Structural Realities
The market’s historical performance from 2020 through 2025 demonstrates a consistent upward curve, with annual revenue crossing the USD 160 million threshold in 2022 and accelerating into the USD 170–185 million range by mid-decade. The forecast period from 2026 to 2032 projects continued expansion, though the growth path is not uniform. The transition from USD 185.0 million in 2025 to the projected USD 253.28 million in 2032 implies that demand generation will increasingly depend on application-specific precision, regulatory compliance, and regional capacity dynamics rather than broad volume expansion alone.
At the structural level, the market operates with moderate concentration. The top three participants collectively command roughly 45 percent of total revenue, while the top five extend that share to approximately 60 percent. This concentration pattern indicates that established manufacturers retain meaningful pricing power and distribution leverage, yet the remaining 40 percent of the market remains fragmented across regional players, specialty suppliers, and cost-focused producers. Such a landscape creates both defensive moats for incumbents and entry points for well-positioned challengers, particularly where customization, compliance documentation, or supply chain reliability becomes a differentiating factor rather than a baseline expectation.
The market is also characterized by a clear hierarchy of product and application relevance. Volumetric measurement tools and general containment vessels continue to anchor demand, while pipettes and precision dispensing instruments represent a growing precision segment. In application terms, pharmaceutical and biotechnology workflows consume the largest share of glassware volumes, followed by academic and research environments, clinical diagnostic settings, and ancillary use cases. This distribution indicates that demand is increasingly tied to regulated, high-throughput, or quality-sensitive environments where measurement accuracy, material consistency, and documentation traceability carry direct operational and compliance implications.
Defining Challenges and Inflection Points
Despite the favorable growth baseline, the industry faces several interconnected challenges that will shape competitive outcomes over the next three to five years.
Precision Standards and Calibration Expectations
The laboratory glassware sector is moving toward tighter standardization for measurement-critical items, particularly in one-mark volumetric instruments. Updated international requirements are reinforcing calibration consistency, marking accuracy, and manufacturing repeatability. For producers, this translates into higher compliance costs, more rigorous quality control protocols, and the need to align product specifications with evolving normative references. Laboratories and procurement teams, in turn, are placing greater weight on certification documentation and conformance assurance, raising the barrier for sellers that cannot demonstrate consistent specification integrity across batches.
Material Consistency and Thermal Performance Requirements
Borosilicate glass remains the dominant material foundation because of its thermal shock resistance and chemical durability. While this dominance provides stability, it also constrains rapid material substitution and heightens sensitivity to raw material quality, melting consistency, and forming precision. Variability in feedstock composition or furnace control can affect wall thickness uniformity, dimensional tolerance, and long-term reliability in temperature-cycling applications. Manufacturers that treat material consistency as a core process capability rather than a commodity input will be better positioned to capture demand from environments where thermal stress and chemical exposure are routine.
Traceability, Documentation, and Procurement Digitalization
A quiet but consequential shift is underway in how laboratories track, verify, and manage glassware inventory. The introduction of QR-coded product items, enhanced batch traceability, and digital catalog integration reflects growing demand for item-level identification and audit-ready documentation. This trend is especially relevant in regulated environments where lot traceability, usage history, and replacement scheduling influence both operational efficiency and compliance reviews. Suppliers that enable faster verification, clearer product identification, and smoother integration with laboratory inventory systems can reduce friction in the procurement cycle while strengthening supplier-of-choice positioning.
Core Drivers Reshaping the Market
Regulatory Alignment and Standardization Momentum
The push toward harmonized international standards is one of the most consequential forces in the market. Updated normative references for one-mark volumetric flasks are establishing clearer expectations for dimensional accuracy, marking, and conformity testing. Rather than treating standards as static compliance checkboxes, leading manufacturers are using them as product development anchors, aligning tooling, inspection routines, and documentation with anticipated certification expectations. For buyers, the practical implication is that specification sheets and conformity evidence are becoming more comparable across suppliers, which can compress differentiation based solely on branding and shift attention toward reliability, lead-time consistency, and technical support.
Innovation in Safety and Durability Features
Product-level innovation is increasingly focused on reducing breakage risk, improving handling safety, and extending service life in demanding workflows. Coated laboratory bottles with enhanced shatter protection illustrate this direction, addressing both workplace safety and total cost of ownership concerns. In settings where glassware is handled frequently, moved across benches, or used in environments with vibration, temperature variation, or incidental impact, safety-oriented design features can differentiate a product line and influence purchasing decisions beyond base price comparisons. Innovation is also extending to interchangeability, filtration-compatible configurations, and specialized vessel geometries that reduce workflow adaptation time.
Demand-Side Shifts in Regulated and Research Workflows
End-user behavior is evolving as laboratory workflows become more standardized, auditable, and throughput-sensitive. Pharmaceutical and biotechnology environments continue to absorb the largest share of demand because measurement precision, contamination control, and reproducibility carry direct implications for development timelines and quality outcomes. Academic and research institutions remain a substantial demand base, but their procurement patterns are increasingly influenced by budget cycles, shared instrumentation models, and the need for broad compatibility across teaching and research labs. Clinical diagnostic settings add another layer of complexity, where glassware usage is tied to laboratory service delivery and reimbursement frameworks that do not always map cleanly onto individual product codes. This fragmentation in reimbursement and procurement pathways means that suppliers must navigate both technical specifications and institutional purchasing logic.
Supply Chain and Cost Structure Pressures
Cost dynamics in the market are influenced by raw material availability, energy intensity in glass melting and forming, and logistics complexity across regions. Borosilicate glass production requires controlled high-temperature processing, which makes energy pricing and furnace utilization relevant to cost structure. At the same time, regional demand patterns are reshaping sourcing strategies. North American and European markets maintain substantial demand bases, while Asia Pacific represents a growing volume center supported by expanding research infrastructure, manufacturing capacity, and domestic consumption. The result is a supply environment in which regional presence, export capability, and inventory positioning increasingly matter for competitive responsiveness. Companies that can combine consistent production output with dependable distribution and clear compliance documentation are gaining an advantage in tenders and recurring procurement programs.
Competitive Landscape and Strategic Positioning
The competitive environment blends incumbent scale, regional manufacturing strength, and niche specialization. Companies with established brand portfolios and broad product ranges are using brand trust, specification consistency, and application coverage to defend share. At the same time, regional manufacturers are gaining relevance by offering competitive cost profiles, adaptable production runs, and growing conformity to local certification expectations. This dual dynamic creates a market where scale and reputation matter, but they no longer guarantee automatic preference if a competitor can match specifications and improve traceability, lead time, or safety features.
Differentiation Patterns Among Leading Players
Several strategic positioning patterns are evident across the competitive set.
-
Brand-led premium positioning: Multi-brand manufacturers leverage well-known product lines and long-standing laboratory recognition to anchor trust in precision measurement and material quality. Their differentiation often rests on specification consistency, broad application coverage, and established distribution relationships.
-
Customization and specialty systems: Some suppliers emphasize custom configurations, reaction systems, and application-specific geometries. This approach is particularly relevant for research environments that require non-standard vessel dimensions, specialized port configurations, or integrated handling solutions.
-
Standards-aligned volume manufacturing: Regional producers focus on USP, ASTM, and local certification alignment, offering general laboratory glassware and consumables at competitive cost points. Their relevance grows where procurement teams prioritize specification compliance, batch consistency, and pricing predictability.
Glassware Market -
Traceability and catalog modernization: Suppliers introducing QR-coded items, updated catalogs, and improved identification systems are reducing friction in inventory verification and lot tracking. This is becoming a practical value-add, especially for repeat purchasers managing large SKU counts or regulated usage environments.
-
Safety-enhanced product extensions: Manufacturers introducing shatter-protection coatings, coated bottles, and handling-safety features are targeting total cost of ownership and workplace risk reduction. This positioning resonates in environments where breakage-related disruptions, cleanup, and replacement frequency influence operating costs.
PW Consulting
Evolution of the Competitive Structure
The market is unlikely to consolidate into a single dominant configuration over the near term. Instead, the structure appears to be evolving through selective integration, regional capacity expansion, and specialization by workflow. Incumbents are defending core positions by strengthening product reliability, demonstration value at major industry events, and application-aligned product launches. Regional producers are expanding relevance by combining cost efficiency with growing conformity to certification and standards expectations. At the same time, new entrants and expanders can gain traction by addressing unmet needs in traceability, safety, specialized geometries, or regional service responsiveness. The practical outcome is a landscape where competitive advantage is increasingly defined by the intersection of specification integrity, documentation readiness, and operational convenience rather than by brand alone.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend 1: Standards-Driven Harmonization of Precision Glassware
Over the next several years, the emphasis on harmonized requirements for measurement-critical items is likely to intensify. One-mark volumetric instruments will continue to serve as a focal point for calibration discipline, and suppliers that proactively align manufacturing controls, inspection protocols, and documentation with evolving normative expectations will face fewer friction points in regulated procurement. The commercial implication is that quality documentation and specification consistency will become more central to supplier selection, and companies that treat conformance as a design and process priority rather than an after-the-fact certification activity will be better positioned for repeat business in quality-sensitive environments.
Trend 2: Safety, Durability, and Total-Cost-of-Ownership Framing
Demand for safety-enhanced and durability-oriented products is expected to grow as laboratories and procurement teams evaluate glassware not only by unit price but by handling risk, breakage frequency, replacement cycles, and workflow interruption. Coated bottles, protective designs, and improved handling characteristics can shift purchasing conversations toward operational outcomes. This trend creates opportunity for manufacturers that can demonstrate measurable benefits in safety and lifecycle performance, especially where laboratory staffing constraints, training variability, or high-throughput handling increase exposure to breakage and handling errors.
Trend 3: Digital Traceability and Procurement System Integration
QR-enabled identification, updated product catalogs, and improved traceability are early indicators of a broader move toward inventory digitization and audit-readiness. As laboratories seek faster verification, clearer lot history, and easier integration with procurement and inventory systems, suppliers that provide machine-readable identification and well-structured product data will reduce administrative burden and improve buyer confidence. This trend is particularly relevant for recurring procurement programs, multi-site institutions, and regulated settings where documentation continuity matters. The opportunity lies not only in labeling, but in supporting buyers with data consistency, clear product hierarchy, and compatibility with modern procurement workflows.
Risks and Uncertainties to Monitor
Several risks could temper or redirect these trends. Regulatory and standards implementation can vary by region and by procurement cycle, creating uneven adoption timelines. Raw material and energy cost volatility may pressure margins, particularly for producers with limited pricing flexibility or high exposure to energy-intensive forming processes. Reimbursement and procurement structures in diagnostic and clinical service settings remain complex, which can obscure demand signals and slow purchasing decisions. In addition, the fragmented portion of the market can intensify price competition, especially where differentiation is limited to specification parity and brand recognition. Companies that fail to strengthen traceability, documentation, and safety value propositions may find themselves competing primarily on price in an increasingly demanding specifications environment.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Owners
Strengthen the link between product design and compliance readiness. Where measurement-critical items are concerned, investment in process control, inspection discipline, and conformity documentation can reduce friction in regulated procurement and improve repeat-order reliability. Equally important is the differentiation path beyond base specifications: safety coatings, handling improvements, traceability features, and application-specific geometries can shift purchasing conversations toward operational value. Manufacturers should also evaluate regional certification expectations and determine where local compliance, service responsiveness, or cost-positioning can open access to growing demand centers. Participation in major industry exhibitions and consistent product demonstration can reinforce visibility, but the durable advantage will come from repeatable conformance, clear documentation, and the ability to reduce buyer risk across the ordering and use cycle.
For Investors and Strategic Allocators
Evaluate exposure through the lens of specification integrity, regional capacity, and value-added differentiation rather than aggregate volume alone. Segments tied to precision measurement, safety-enhanced products, and traceability-enabled catalog systems are likely to see stronger demand resilience because they address compliance, handling risk, and procurement efficiency. It is also important to assess the regional balance of demand and production capacity, since energy intensity, raw material access, and logistics can shape margin durability. Companies that combine stable production quality with clear documentation and differentiated product features may offer more defensible positioning than those reliant on undifferentiated commodity supply. In addition, investors should monitor how reimbursement and procurement structures evolve in diagnostic-linked settings, since those frameworks influence demand timing even when the product itself is not directly coded.
For Procurement Leaders and Laboratory Operators
Expand evaluation criteria beyond unit price to include specification conformance, documentation completeness, handling safety, and traceability support. In precision-sensitive workflows, the cost of measurement uncertainty, replacement delays, and compliance friction can outweigh small differences in list price. Suppliers that provide clearer product identification, reliable conformity evidence, and efficient replenishment processes can reduce administrative burden and improve continuity. Procurement teams should also consider total cost of ownership when breakage, handling risk, and replacement frequency are material, since safety-enhanced options may lower downstream disruptions even if upfront pricing differs. Where multi-site or regulated environments are involved, standardized product data and traceable lot management can simplify audit preparation and inventory control.
From Insight to Execution
The laboratory glassware market is moving from a period of steady expansion to one where differentiation is increasingly determined by precision discipline, safety enhancement, traceability readiness, and regional execution. The baseline growth trajectory remains constructive, but the more valuable question for decision-makers is not whether the market will continue to grow, but which capabilities will earn preference as specifications tighten and procurement becomes more documentation-driven. Manufacturers that align product development with standards expectations, reinforce material and process consistency, and reduce operational friction for buyers can convert market-wide growth into share gains. Investors and procurement leaders, meanwhile, can use these signals to prioritize exposure, negotiate with clearer evaluation criteria, and reduce hidden cost risks in precision-sensitive workflows.
Worldwide Laboratory Glass Container Market
For organizations that need a granular view of regional demand splits, product-type dynamics, application-level consumption patterns, and company-specific competitive positioning, a more detailed research view can help translate these high-level trends into segment-specific strategy. Access to the full breakdown supports scenario planning, sourcing decisions, and portfolio prioritization with finer granularity than is possible in a market overview alone.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LPO Market at 22.91% CAGR: What’s Really Driving the $125.85B Surge to 2032
By PW Consulting, 2026-09-21
The Legal Process Outsourcing Market: Strategic Shifts and Growth Horizons (2025–2032)
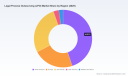
The legal process outsourcing (LPO) sector has transitioned from a cost-arbitrage experiment into a core operational function for corporations, law firms, and compliance teams worldwide. Over the past five years, the market has demonstrated consistent expansion, with revenues climbing from approximately 11.0 billion USD in 2020 to nearly 30 billion USD by 2025. The trajectory continues upward, with annual growth momentum expected to push the sector past 125 billion USD by 2032. At a compound annual growth rate of roughly 22.9 percent across the 2026–2032 forecast window, LPO is outpacing many adjacent professional services categories, reflecting a structural recalibration of how legal work is sourced, managed, and delivered.
This growth is not merely a function of volume expansion. It reflects a deeper transformation in how organizations approach legal capacity, regulatory complexity, and technology integration. For executives, investors, and procurement leaders, the LPO landscape now offers a mix of established scale players, specialized capability providers, and emerging technology-driven models. Navigating this environment requires a clear understanding of where value is being created, where operational friction persists, and which strategic moves are separating consistent performers from the rest of the field.
Healthcare BPO Market
Market Realities and Core Challenges
The LPO market has reached a scale where traditional outsourcing playbooks no longer apply uniformly. Organizations today are leveraging external legal operations for everything from high-volume document review to regulatory monitoring, contract lifecycle management, and specialized intellectual property support. The breadth of services has expanded significantly, and the revenue base now spans multiple service categories with varying maturity levels. Litigation support and e-discovery workflows remain a substantial portion of the service mix, while contract management, regulatory and compliance services, and legal research functions have grown in strategic importance as internal legal teams face increasing workloads and tighter budgets.
Despite the strong growth profile, the industry faces several structural challenges that will shape its next phase of development.
- Quality and consistency at scale. As volumes increase and service delivery crosses multiple jurisdictions, maintaining consistent quality standards becomes more difficult. Legal work is inherently high-stakes, and errors in contract review, compliance monitoring, or discovery processes can carry significant financial and reputational consequences. Vendors must balance speed and cost efficiency with rigorous quality controls, which often requires layered review processes, specialized training, and robust performance metrics.
- Data security, privacy, and cross-jurisdictional compliance. Legal outsourcing frequently involves transferring sensitive information across borders, which introduces regulatory complexity. Data protection requirements, industry-specific confidentiality obligations, and evolving cross-border data transfer rules create operational hurdles for providers and clients alike. Delivery models must be designed with security architecture, access controls, and compliance monitoring built in from the start rather than treated as add-ons.
- Talent availability and capability gaps. The LPO sector depends on a blend of legal knowledge, process discipline, and increasingly technical skills. Demand for professionals who can operate across legal workflows, data analytics, and AI-assisted tools is rising, but supply remains uneven across regions. Provider organizations that can develop, retain, and continuously upskill talent gain a meaningful advantage, while those relying on purely labor-cost arbitrage face growing pressure as automation absorbs more routine tasks.
These challenges are not static barriers; they are becoming strategic differentiators. Providers that design their operating models around quality assurance, secure data handling, and talent development are better positioned to capture higher-value work, while those that compete primarily on price are likely to face margin compression and client churn as buyers become more sophisticated.
Core Drivers Reshaping the Market
The expansion of the LPO sector is being driven by a combination of technological, regulatory, demand-side, and cost-structure forces. These drivers interact with one another, creating feedback loops that accelerate adoption in certain segments while reshaping competitive expectations across the broader market.
Technology Innovation as a Core Enabler
Artificial intelligence and automation are no longer peripheral tools in legal operations; they are increasingly embedded in how work is scoped, executed, and reviewed. Machine-assisted document review, contract analysis, legal research, and compliance monitoring are reducing turnaround times and allowing provider teams to focus on higher-judgment tasks. The shift is not simply about replacing manual effort. It is about re-architecting workflows so that technology handles the repetitive, high-volume components while human expertise is applied where nuance, interpretation, and client-specific context matter most.
Recent industry activity illustrates how seriously providers are investing in this direction. Several leading firms have moved to strengthen their AI-enabled service lines and data capabilities, integrating legal operations support with more advanced analytics, contract management platforms, and compliance workflows. In parallel, partnerships aimed at deploying end-to-end platforms with stronger security and compliance controls are becoming more common, particularly where cross-border data handling is involved. These moves signal that technology is now a competitive baseline rather than a differentiator reserved for a few early adopters.
Regulatory Complexity and Monitoring Demands
The regulatory environment for large corporations and regulated industries continues to become more demanding. Environmental, social, and governance expectations, data privacy regimes, sector-specific compliance obligations, and cross-border operational requirements have all increased the volume and urgency of legal and compliance work. This is pushing organizations to seek external support not only for episodic litigation or transaction work, but also for ongoing monitoring, reporting, and risk management.
A notable example is the introduction of managed services focused on ESG compliance, including real-time regulatory monitoring and reporting. Such offerings reflect a broader trend: clients increasingly want continuous, structured support rather than ad hoc project-based assistance. As regulatory expectations become more dynamic, providers that can combine legal knowledge with operational monitoring and reporting capabilities are well placed to capture recurring revenue streams.
Demand-Side Shifts in Legal Capacity and Procurement
Internal legal departments are under growing pressure to manage expanding workloads with constrained headcount and budgets. At the same time, corporate procurement and legal operations teams are becoming more deliberate about how they source external support. The conversation has evolved from simple cost reduction to total value, including speed, quality, predictability, security, and the ability to scale up or down as needs change. This has encouraged a shift toward managed services and longer-term partnerships rather than one-off engagements.
The result is a more diverse buyer profile. Some organizations are building hybrid models in which internal teams oversee strategy and high-judgment work while external providers handle volume-driven processes. Others are using LPO providers to fill capability gaps in specialized areas, such as multilingual litigation support, intellectual property analytics, or jurisdiction-specific compliance. In both cases, the common theme is flexibility: buyers want providers who can adapt to changing caseloads, regulatory demands, and internal priorities without sacrificing control or consistency.
Cost Structure and Delivery Model Evolution
Cost remains a foundational driver, but the way cost advantage is achieved is changing. Pure labor-cost arbitrage is increasingly insufficient in segments where quality, turnaround speed, and technology integration matter most. Providers are restructuring delivery around a blend of onshore, nearshore, and offshore locations, with secure facilities and specialized centers supporting specific legal domains or jurisdictional requirements. This geographic diversification helps manage cost while also addressing data residency, language, and legal system familiarity.
At the same time, operational efficiency is being improved through process standardization, workflow automation, and better portfolio management. Organizations that treat legal outsourcing as a managed operation—complete with governance, performance tracking, and continuous improvement—are more likely to realize durable savings and service reliability than those that rely on transactional, project-by-project purchasing.
Competitive Landscape and Leading Strategies
The LPO market remains moderately fragmented, with the top three providers accounting for a combined share in the high twenties and the top five reaching just over a third of total market revenue. This structure implies that while scale players have meaningful presence, there is still substantial room for specialization, regional strength, and capability-based differentiation. The competitive dynamic is less about a single dominant model and more about how providers combine scale, technology, domain expertise, and delivery footprint.
Strategic Positioning Among Key Players
Several established providers illustrate different pathways to competitive advantage.
- Integreon Managed Solutions has focused on AI-powered legal operations support spanning contract management, document review, legal research, and compliance services. Its recent strategic collaboration with PwC for legal managed services in the EMEA region, along with the opening of a new secure delivery center in Cape Town to support offshore outsourcing with an emphasis on English common law jurisdictions, reflects a strategy centered on both geographic expansion and partnership-driven scale.
- Elevate Services has positioned itself around AI-powered legal services that include litigation support, contract management, legal operations consulting, and managed services. Its acquisition of a specialist in Chinese, Japanese, and Korean language support for litigation, together with a legal data and AI consulting company, demonstrates a push to deepen multilingual capability and data/AI advisory strength in a single move.
- QuisLex has built its offering on managed services for document review, contract management, compliance, litigation support, and legal spend optimization. Its launch of a managed service focused on ESG compliance with real-time regulatory monitoring and reporting shows an effort to move beyond traditional litigation-support work into recurring, compliance-driven engagements.
- Epiq Global continues to emphasize technology-enabled legal and compliance services, including e-discovery, class actions, bankruptcy, and outsourcing for law firms and corporations. Its profile reflects the importance of scale infrastructure and specialized case-type expertise in high-volume, process-intensive work.
- Axiom Law has carved out a position around on-demand legal talent, secondments, and AI-enabled services supporting in-house legal teams and complex projects. This model highlights the value of flexible talent deployment and close integration with internal legal functions, especially for organizations that want external support without fully handing off operational control.
- UnitedLex has focused on data-driven legal and litigation support services, including e-discovery, patent analytics, and case management. Its strategic partnership with a major cloud provider to deploy an advanced end-to-end e-discovery platform with enhanced data security and cross-border compliance capabilities underscores the increasing importance of secure technology infrastructure in competitive positioning.
How the Landscape Is Evolving
Three patterns are evident in the current competitive environment.
- Capability-driven consolidation. M&A and strategic partnerships are being used to add multilingual capacity, data and AI consulting, and broader managed-service portfolios. This suggests a market in which buyers increasingly want integrated solutions rather than narrow point services.
- Geographic and jurisdictional specialization. Providers are expanding or refining delivery centers to align with common law frameworks, language requirements, and regional compliance expectations. This reflects a recognition that legal outsourcing is not a uniform global service; jurisdictional familiarity and data handling rules shape where and how work can be performed.
- Platform and security as competitive foundations. Partnerships and platform investments focused on secure, end-to-end processing are becoming more prominent, particularly for e-discovery and other data-sensitive workflows. In a market where information security and regulatory compliance are central concerns, technology infrastructure is increasingly part of the value proposition rather than a back-office utility.
For new entrants, the bar is rising. Pure cost-based entry is harder to sustain as automation reduces the advantage of low-cost labor alone, and buyers are more capable of evaluating quality, security, and service design. New players that can bring specialized domain expertise, strong technology integration, or a clear regional and jurisdictional fit have a more credible path than those offering only generalized volume services.
Forward Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape how the LPO market develops and where commercial opportunities emerge.
AI-Embedded Legal Operations Become Standard Configuration
The integration of AI and automation into legal workflows is expected to deepen, moving from selected use cases to broader operational baselines. Document review, contract abstraction, legal research, compliance monitoring, and matter management are all candidates for increased automation, with human reviewers focusing on exception handling, strategic judgment, and client-specific interpretation. For providers, this trend creates opportunities to redesign service offerings around technology-assisted efficiency, predictable turnaround times, and measurable quality outcomes. For buyers, it opens the possibility of scaling legal support without proportionally increasing headcount, provided vendor selection emphasizes workflow design and governance rather than tool presence alone.
Compliance and ESG-Linked Services Grow as Recurring Revenue Engines
As regulatory expectations continue to expand, managed services tied to regulatory monitoring, compliance reporting, and ESG-related obligations are likely to become more prominent. Unlike episodic litigation or transaction support, these engagements can create more predictable, recurring demand. Providers that can combine real-time monitoring, structured reporting, and cross-functional coordination with legal and compliance teams are well positioned to capture this demand. For enterprises, the opportunity lies in moving from reactive compliance support to continuous operational oversight, reducing the risk of late responses to regulatory changes and improving internal accountability.
Regional Rebalancing and Jurisdiction-Focused Delivery Models
The geographic distribution of LPO activity is expected to remain dynamic. While some regions already account for a substantial share of market activity, others are positioned for faster growth during the forecast period as legal demand, regulatory complexity, and delivery infrastructure evolve. Western Europe, for example, is widely expected to emerge as one of the fastest-growing regions during the forecast window, reflecting expanding compliance needs and increasing adoption of external legal operations support. At the same time, Asia Pacific continues to hold a leading share, underscoring the region’s established role in global legal service delivery. For providers, this environment favors deliberate investment in regional capabilities, language coverage, and jurisdiction-specific expertise. For buyers, it creates options for aligning delivery location with legal framework familiarity, data residency requirements, and cost considerations.
Legal Practice Management Software Market
Risks and Uncertainties to Monitor
Despite the strong growth outlook, several uncertainties could affect the pace and shape of market development. Regulatory changes around data transfer, privacy, and cross-border operations may increase compliance costs and slow certain delivery models if requirements become more restrictive. Security incidents or quality failures in high-stakes legal work could also shift buyer caution and raise due-diligence requirements. In addition, rapid automation could compress margins for providers that have not reinvested in workflow redesign, talent development, or higher-value service capabilities. Finally, macroeconomic fluctuations may influence how aggressively organizations expand external legal support, even if the underlying structural drivers remain intact.
Implications for Decision-Makers
The current LPO environment rewards deliberate strategy over reactive purchasing. Executives, investors, and procurement leaders each face a distinct set of priorities, but all benefit from a clearer view of where the market is heading and how to position accordingly.
For Corporations and Legal Operations Leaders
- Move from project-based buying to managed service design. Where possible, structure engagements around governance, service-level expectations, quality metrics, and continuous improvement. This reduces variability and makes it easier to scale support as workload fluctuates.
- Define security and compliance requirements before sourcing. Data handling, jurisdiction, access controls, and reporting expectations should be part of the initial scoping process, not negotiated after the fact. Providers with built-in secure infrastructure and cross-border compliance capabilities will be easier to integrate into sensitive workflows.
- Use external support to build capability, not just capacity. The most valuable engagements often combine volume handling with knowledge transfer, process improvement, and access to specialized expertise. This helps internal teams evolve while maintaining strategic control over high-judgment work.
For Investors and Strategic Allocators
- Focus on models with durable differentiation. Sustainable advantage is increasingly tied to technology integration, quality systems, multilingual and jurisdiction-specific capability, and recurring compliance-oriented services rather than labor-cost advantage alone.
- Watch consolidation and partnership activity as signals. Acquisitions and collaborations that add language coverage, data and AI advisory strength, or platform security capabilities often indicate where the market is heading and which capability gaps are being closed.
- Evaluate exposure to regulatory-driven demand. Segments tied to ongoing compliance monitoring, ESG reporting, and data-sensitive discovery workflows may offer more predictable demand profiles, though they also carry higher expectations for security, accuracy, and operational discipline.
For Procurement and Sourcing Professionals
- Evaluate total value, not just unit cost. Speed, quality, security, scalability, and the ability to manage changing requirements can matter as much as price, especially in complex or high-volume legal work.
- Build vendor portfolios by capability, not by brand alone. Different providers are stronger in different areas, such as litigation support, contract management, IP analytics, or compliance monitoring. A diversified sourcing approach can match work types to the most suitable providers.
- Embed performance management into ongoing relationships. Regular review of quality, turnaround, cost predictability, and security compliance helps maintain alignment and reduces the risk of service drift over time.
Conclusion
The legal process outsourcing market is entering a phase defined by greater technological integration, more demanding compliance expectations, and a growing preference for managed, scalable service models. Growth momentum remains strong, but the competitive edge is shifting toward providers that can combine secure infrastructure, quality assurance, jurisdictional awareness, and AI-enabled workflows with the ability to support recurring legal and compliance needs. For organizations seeking to use LPO strategically, the priority is no longer simply finding lower-cost support. It is selecting partners and service designs that improve speed, control, and resilience while allowing internal teams to focus on the work that most requires judgment and accountability.
PW Consulting
For decision-makers needing a more detailed view of service-line dynamics, regional trajectories, competitive positioning, and custom sourcing implications, the full research report provides a deeper breakdown of market segments, company-level developments, and forward scenarios. It is designed to support more granular planning, from service portfolio design and vendor evaluation to investment prioritization and risk assessment.
For detailed analysis of this topic, please visit the official page: Legal Process Outsourcing (LPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fresh Meat Packaging Market: How 5.12% CAGR and Plastic Dominance Are Redefining the $5.79B Landscape
By PW Consulting, 2026-09-21
The Fresh Meat Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Defining Challenges
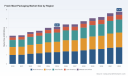
The global fresh meat packaging market has evolved from a commoditized segment into a strategically contested arena where material science, regulatory compliance, and supply chain resilience intersect. Historical trajectory from 2020 through 2025 demonstrates consistent expansion, anchored by steady volume growth in developed retail channels and accelerating modernization in emerging distribution networks. The baseline year value reached approximately 4.09 billion USD, representing a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast horizon. This trajectory projects revenue climbing toward 5.79 billion USD by 2032, signaling a market that is expanding at a measured but structurally significant pace.
Several structural headwinds define the current inflection point. First, the gap between conventional plastic-dependent formats and rapidly evolving recyclability mandates creates a compliance-cost squeeze. Processors and converters must balance shelf-life performance with design-for-recyclability requirements that increasingly dictate fee structures and market access. Second, raw material volatility has shifted from a cyclical nuisance to a persistent margin pressure. Limited availability of key polymer resins has elevated input costs for trays and films, pushing converters and brand owners to evaluate alternative material pathways that can maintain barrier properties while improving end-of-life outcomes. Third, retail and foodservice procurement models are fragmenting. Case-ready and centralized packaging specifications vary significantly across geographies and retailer tiers, forcing suppliers to navigate a maze of performance, sustainability, and footprint requirements simultaneously.
Vacuum Skin Packaging Market
These challenges are not isolated. They interact to reshape cost structures, dictate formulation and tooling investments, and influence where competitive advantage can be sustained. Companies that treat packaging as a performance and compliance layer rather than a disposable cost center are better positioned to navigate the transition ahead.
Core Drivers Reshaping the Market
Material and design innovation remains the primary engine of differentiation. Mono-material architectures and recyclable polymer structures are advancing rapidly, driven by the need to maintain oxygen and moisture barriers while simplifying downstream sorting and recycling streams. Vacuum skin packaging continues to evolve with tighter film tolerances and integrated equipment logic, enabling retailers to standardize display readiness while extending case life. The shift toward paper-based and fiber-reinforced formats is gaining commercial traction where fresh meat applications demand reduced plastic load and clearer recyclability claims. Innovations in heat-sealable membranes, die-cut lids, and preformed trays are narrowing the historical performance gap between conventional and sustainable formats, creating more options for processors seeking to balance cost, protection, and compliance.
Regulatory momentum is accelerating the pace of change. Extended producer responsibility frameworks are expanding across multiple jurisdictions, with several U.S. states now embedding recycled content and recyclability-based fee schedules that directly affect packaging economics. In parallel, European requirements are reinforcing design-for-recyclability expectations and minimum recycled content thresholds for plastic packaging. These mandates are not static footnotes; they alter the total cost of ownership for packaging portfolios and create financial incentives for early adopters of compliant materials and designs. Producer fees tied to recyclability performance are increasingly influencing sourcing decisions, particularly for high-volume formats such as trays and films used in beef, poultry, and seafood categories.
Pet Food Packaging Market
Demand-side behavior is reinforcing the material transition. Consumers continue to prioritize freshness visibility, portion clarity, and label legibility, while retailers are under growing pressure to demonstrate shelf-level sustainability credentials without compromising product integrity. Processors are responding by standardizing case-ready formats that reduce handling and improve throughput, while also aligning packaging specifications with retailer sustainability scorecards. The result is a more demanding specification environment where protection, presentation, and post-consumer outcomes must be optimized together rather than in sequence.
Cost and supply chain dynamics are reshaping sourcing strategies. Resin availability constraints have elevated film and tray costs, accelerating evaluation of recycled content and alternative materials. At the same time, processing-side efficiency opportunities are attracting attention; adjustments to slaughter line speeds and throughput logistics can unlock meaningful cost savings for meat operations over multi-year horizons, indirectly influencing the packaging specification conversation by altering the cost context in which packaging decisions are made. Companies are increasingly weighing packaging investments against broader operational levers, recognizing that packaging performance and processing efficiency are linked in total landed cost and service reliability.
Competitive Landscape and Leading Strategies
The competitive field is concentrated but diverse, with leaders differentiating through material portfolios, equipment integration, and regional manufacturing footprints. Amcor has built a position around responsible and recyclable flexible and rigid solutions, emphasizing mono-material films and trays tailored to fresh meat applications. Sealed Air maintains a strong presence through specialized vacuum skin packaging, preformed trays, and integrated automation that supports case-ready workflows for beef, pork, lamb, and poultry. Berry Global pursues next-generation vacuum skin and sustainable flexible solutions, focusing on shelf-life extension and improved recyclability profiles.
Regional and fiber-oriented players are expanding the strategic options available to buyers. Pactiv Evergreen continues to serve processors and retailers with foam trays, films, and case-ready solutions that prioritize display readiness and throughput. Huhtamaki emphasizes sustainable fiber-based and flexible packaging, aligning fresh meat applications with evolving recyclability expectations. Mondi has moved aggressively in paper-based mono-material and pulp solutions, pairing tray and film innovations with targeted partnerships and acquisitions that expand production capacity in key regions. Winpak rounds out the flexible segment with heat-sealable membranes, die-cut lids, and processing-focused flexible formats. Sonoco contributes paperboard trays, tubes, and composite packaging, while Coveris has expanded its portfolio across paper-based and flexible sustainable solutions, including dedicated fresh meat ranges and new vacuum skin packaging capacity. Edelmann rounds out the landscape with high-performance packaging solutions and facilities oriented toward fresh meat products.
Recent moves highlight how incumbents are translating strategy into capability. Mondi partnered with Scan Sverige to advance recyclable polypropylene-based mono-material food packaging for fresh meat, signaling a collaborative approach to compliance and performance. In parallel, Mondi completed the acquisition of a pulp mill in Alberta to strengthen sustainable paper-based packaging capacity for North America, illustrating how vertical capacity can be used to secure supply and regional relevance. Coveris introduced a fully recyclable paper-based flexible packaging range for fresh meat and expanded a vacuum skin packaging facility in the UK, reflecting coordinated investment in both material innovation and manufacturing scale. These actions suggest a market where differentiation is increasingly built on material architecture, regional capacity, and the ability to deliver compliant solutions without sacrificing barrier or presentation performance.
The landscape is evolving through both consolidation and specialization. Large converters are broadening portfolios to capture cross-category volume and compliance advantages, while focused players are carving out niches around fiber-based solutions, advanced vacuum skin systems, and regional case-ready formats. New entrants are likely to appear where material innovation intersects with recycling infrastructure readiness, but scale, tooling, and qualification timelines continue to favor established players with proven supply reliability and retail relationships. Concentration among the top firms remains notable, yet the diversity of material pathways and regional demand patterns creates room for differentiated positioning rather than pure price competition.
Forward-looking Trends to 2030 and Beyond
The first trend is the broadening commercial viability of mono-material and recyclable structures for fresh meat. As design-for-recyclability expectations become embedded in procurement and compliance frameworks, formats that simplify sorting and improve recovery outcomes will gain preference in high-volume channels. This favors suppliers that can deliver barrier performance in mono-material architectures, supported by film and tray designs that meet both protection and circularity criteria. The commercial opportunity lies in standardizing these formats across retail ready lines and processor specifications, reducing complexity while improving compliance economics.
A second trend is the growing role of fiber-based and paper-forward solutions in select applications where plastic reduction and recyclability communication provide commercial value. These formats are advancing in areas where presentation, protection, and end-of-life messaging align with retailer and consumer expectations. The opportunity is not universal replacement; it is targeted deployment where fiber-based trays, films, and flexible ranges can meet performance thresholds and simplify sustainability narratives without compromising shelf life or handling efficiency. Success will depend on matching format to application, ensuring that barrier and structural requirements are met while leveraging recyclability positioning where it truly matters.
A third trend is the tightening linkage between packaging strategy and regional compliance economics. Producer responsibility fees, recycled content mandates, and recyclability rules are increasingly shaping total cost profiles and market access. Companies that anticipate these shifts and align material choices with local regulatory trajectories can reduce future rework, avoid fee exposure, and secure preferential positioning with sustainability-conscious buyers. The risk is regulatory fragmentation, where differing requirements across regions complicate portfolio standardization and increase qualification overhead. Firms that manage this tension through modular material platforms and region-specific compliance mapping will navigate the transition more efficiently.
PW Consulting
Potential uncertainties include raw material availability, which can shift the economics of polymer-based versus alternative formats faster than expected, and processing-side changes that alter the cost context of packaging decisions. If resin constraints persist or intensify, the pace of migration toward paper and recycled content could accelerate, while in a more benign supply environment the transition may unfold more gradually. Retail specification volatility and regional recycling infrastructure readiness also remain variables, meaning that the timing and scale of adoption will differ by market and application.
Implications and Action Points for Decision Makers
For packaging manufacturers and converters, the priority is to build material and format flexibility that can absorb regulatory and cost shifts without disrupting supply. Invest in mono-material and recyclable film and tray architectures that maintain barrier performance, and develop modular designs that can be tuned to regional recyclability rules and retailer specifications. Strengthen regional production or sourcing options where compliance economics and resin availability are likely to diverge, and align equipment and lines with formats that reduce qualification friction for case-ready and retail-ready workflows. Validate performance claims with rigorous shelf-life, sealing, and handling data so that sustainability positioning is credible and defensible.
For investors and corporate strategists, the market rewards exposure to companies with clear material-transition roadmaps, credible compliance positioning, and the capacity to execute across regions. Assess portfolios for diversification across plastic, paper-based, and flexible formats, and evaluate the quality of recent partnerships and capacity investments that secure supply and regional relevance. Weigh concentration dynamics against the opportunity set created by material innovation and regional compliance divergence. Focus on players that demonstrate both technical performance and the operational discipline to scale compliant formats without sacrificing service reliability.
For procurement leaders and retail or foodservice buyers, the strategic task is to align specifications with total cost, compliance exposure, and shelf impact rather than unit price alone. Standardize where possible to reduce complexity, but maintain application-specific flexibility for formats where protection and presentation requirements differ. Incorporate recyclability and recycled content expectations into sourcing criteria early, and map those expectations to supplier capability and regional infrastructure readiness. Communicate specifications clearly to reduce rework and qualification delays, and coordinate with suppliers on pilot programs that validate performance and compliance before broad rollout.
The trajectory of the fresh meat packaging market will be shaped by how effectively companies integrate material innovation, compliance strategy, and supply chain resilience. Detailed segmentation, regional dynamics, and scenario-level cost modeling can sharpen these decisions further, and the full PW Consulting research report provides the granular data and tailored analysis needed to translate these trends into concrete plans for specific business contexts.
For detailed analysis of this topic, please visit the official page: Fresh Meat Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Denim Jeans Market 2026: 5.8% CAGR and Strategic Shifts Reshaping Global Growth
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Denim Jeans Market: A 2025–2032 Outlook
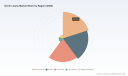
The global denim jeans market continues to demonstrate measured resilience, growing from 131.0 million USD in 2020 to an estimated 170.0 million USD in 2025. Over the historical period from 2020 to 2025, the category navigated pandemic-era disruptions, inventory corrections, and shifting consumer preferences, ultimately stabilizing at a pace that reflects both the durability of denim as a wardrobe staple and the structural adjustments taking place across sourcing and manufacturing. Looking toward the 2026–2032 forecast window, the market is projected to expand at a CAGR of 5.8 percent, reaching 252.0 million USD by 2032. This trajectory is not merely a function of population growth or rising disposable incomes; it reflects deeper changes in how denim is designed, produced, regulated, and valued by end users. For executives and investors, the central question is no longer whether denim will grow, but where value will crystallize in a market that is increasingly shaped by raw material volatility, regulatory scrutiny, and divergent consumer expectations across regions.
Market Snapshot and Core Challenges
The current market size reflects a category that has moved past the acute volatility of the early 2020s and is now operating in a more normalized but still complex environment. Revenue growth has been underpinned by steady end-use demand in casual wear, where denim remains a default choice for consumers seeking versatility, durability, and relative affordability. At the same time, the segment has seen gradual expansion in more structured applications and specialized fits, indicating that denim is no longer confined to a single occasion or silhouette. The 2025 baseline of 170.0 million USD sets the stage for a forecast period in which growth will increasingly depend on the ability of companies to manage cost pressures, navigate trade policy shifts, and respond to sustainability expectations without eroding margin or brand equity.
Three challenges stand out as particularly consequential for commercial planning. First, raw material dynamics are introducing renewed cost uncertainty. Each kilogram of cotton is projected to cost up to 1.75 USD in 2026, a 2.9 percent increase from prior forecasts, against a backdrop of a global cotton production contraction of up to 2 percent during the 2025–2026 season. This tightening supply environment pressures both fabric suppliers and finished-goods manufacturers, particularly those with thin pricing flexibility or limited access to alternative fibers. Second, trade policy and enforcement are reshaping sourcing calculus. Tariffs on denim jeans imports from Vietnam and Turkey face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses, creating a landscape where incremental cost adjustments can quickly alter the economics of established supply chains. Third, compliance risk is becoming a material commercial factor rather than a back-office concern. U.S. Customs and Border Protection issued a Withhold Release Order against Firemount Group Ltd. in November 2025, directing detention of denim jeans and apparel produced in Mauritius due to indicators of forced labor. This action, along with broader enforcement trends, signals that sourcing visibility and documented labor practices are now integral to market access, especially for companies selling into high-value Western markets.
Denim Market
Key Drivers Reshaping the Category
Technical innovation and product differentiation
Product-level innovation is moving from a peripheral creative exercise to a core commercial lever. The introduction of heavier, selvedge-inspired denim and customizable fits reflects a broader shift toward premiumization, where consumers are willing to pay for construction quality, longevity, and a more deliberate sense of style. In November 2025, Levi Strauss & Co. expanded availability of its Blue Tab premium line, featuring Japanese selvedge-inspired heavier denim jeans, to more stores for fall 2026. This move illustrates how established brands are using product architecture to protect margin and reinforce brand distinctiveness in a category that can easily slip into commodity competition. Alongside signature fits and heavier constructions, innovation is also occurring in fabric technology, where stretch formulations, regenerative inputs, and lower-impact processing are becoming differentiated selling points rather than niche add-ons.
At the fabric and materials level, circularity and regenerative approaches are increasingly embedded in commercially available offerings. Candiani Denim has built its positioning around high-end denim fabrics and jeans with a focus on regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans, while maintaining supply chain relationships for fashion brands. In September 2025, Alberto Candiani x Velasca launched a new made-in-Italy denim capsule collection with customizable Millesimo fits, showing how premium Italian fabric competence can be paired with consumer-facing customization. Meanwhile, MUD Jeans specializes in premium circular denim jeans produced from post-consumer recycled jeans and emphasizes lower-impact production for men and women. These examples suggest that sustainability in denim is no longer a single message but a set of product and process choices that can be tailored to different price points, regions, and brand identities.
Regulatory and policy environment
Policy dynamics are exerting a direct influence on sourcing decisions, cost structures, and market access. The Withhold Release Order against Firemount Group Ltd. demonstrates how enforcement actions can alter the viability of specific suppliers and geographies in a short period. For vertically integrated manufacturers and importers alike, the implication is that documented supply chain transparency is becoming a commercial prerequisite, not just a reputational preference. This is reinforced by the broader regulatory environment around import duties. Tariffs on denim jeans imports from Vietnam and Turkey face potential baseline rates of 46 percent and 10 percent respectively following 2025 policy changes and any 90-day pauses, meaning that sourcing diversification and tariff-aware inventory planning are now central to operational resilience.
These regulatory pressures are interacting with the structural reality that many leading players already operate distributed, contract-based manufacturing models. Gap Inc. sources and offers denim jeans under Gap and Old Navy brands while diversifying contract manufacturing to Vietnam and Bangladesh for denim and woven bottoms. H&M Group operates as an outsourced manufacturer of denim jeans for H&M and other brands, maintaining quarterly-updated supplier lists across 969 tier-1 factories primarily in Asia. In this context, regulatory exposure is not uniform across the industry; it varies by geography, tier of supplier, and the level of visibility a company has into its upstream operations. The practical effect is that policy risk is increasingly a selection criterion, influencing which partners are viable over a multi-year horizon.
Demand-side behavior and category evolution
Consumer demand in denim is bifurcating along two overlapping axes: value-driven volume and premiumized differentiation. Casual wear remains the dominant application, absorbing a large share of category revenue and providing a stable base for everyday fits, durable construction, and accessible pricing. Yet demand is also expanding in more formal and specialized applications, where denim is being repositioned for smarter occasions, structured silhouettes, and premium finishes. This is visible in the growth of formal wear applications and the increasing relevance of tailored denim within broader menswear and womenswear assortments. The commercial takeaway is that denim is no longer a monolithic segment; it is a set of sub-categories with different frequency patterns, margin profiles, and innovation requirements.
A second demand-side dynamic is the growing importance of transparency as a purchasing heuristic. Consumers and retail partners are increasingly attentive to where and how denim is made, particularly as sustainability claims become more scrutinized and as regulatory enforcement raises the stakes of opaque sourcing. This is not simply a matter of marketing language; it affects product design, material selection, factory relationships, and even the cadence of supplier disclosure. Companies that can credibly connect product attributes to process choices are better positioned to command price integrity and reduce the risk of reputational friction.
Supply chain and cost structure shifts
The cost environment is being reshaped by the combination of raw material projections, tariff exposure, and labor-related enforcement. With cotton projected to reach up to 1.75 USD per kilogram in 2026 amid a contraction in global production, fabric procurement will likely place upward pressure on input costs unless offset by efficiency gains, blend strategies, or alternative fiber adoption. At the same time, tariff conditions on key sourcing countries create a need for dynamic scenario planning. A 46 percent baseline scenario for Vietnamese imports and a 10 percent scenario for Turkish imports are not trivial adjustments; they can reallocate cost competitiveness across regions and alter the relative attractiveness of nearshore, offshore, and multi-country sourcing models.
Supply chain structure itself is also a strategic variable. Vertically integrated manufacturers such as Firemount Group Ltd. have historically offered the advantage of integrated control over production and logistics, with documented supply chain details supporting operational coordination. However, vertical integration does not insulate a company from enforcement actions or policy risk, as the November 2025 Withhold Release Order against Firemount Group Ltd. illustrates. For importers and distributors such as Denim and Beyond LLC, which handles U.S. distribution and import logistics for lines including Levi Strauss and Banana Republic, the challenge is to manage flow, visibility, and compliance without over-concentrating exposure in any single geography or supplier. The broader trend is toward more deliberate sourcing architectures, where redundancy, documentation, and trade-aware planning are treated as value drivers rather than overhead.
Competitive Landscape and Leading Strategies
The competitive structure of the denim jeans market remains relatively fragmented at the top, with no single company dominating total category revenue. The CR3 and CR5 concentration levels indicate that while large global players are influential, the market still accommodates a wide range of models, from premium brands and fabric specialists to vertically integrated manufacturers and circular denim specialists. This fragmentation is important because it suggests that leadership will be defined less by scale alone and more by the ability to combine product differentiation, supply chain resilience, and credible sustainability positioning.
Levi Strauss & Co. exemplifies a brand-led strategy built around design, marketing, and global sourcing, with contract manufacturers operating across more than 32 countries and supply chain transparency supported by an interactive supplier map. Its recent move to expand the Blue Tab premium line for fall 2026 underscores a strategy of using signature product tiers to reinforce brand equity and price integrity. Gap Inc. competes through brand portfolio breadth, using Gap and Old Navy to address a wide consumer base while diversifying contract manufacturing to Vietnam and Bangladesh for denim and woven bottoms. This diversification is strategically meaningful because it provides flexibility in cost and geography, though it also requires disciplined supplier oversight. H&M Group operates at scale through outsourced manufacturing, maintaining quarterly-updated supplier lists across a large base of tier-1 factories primarily in Asia, which allows agility in assortment and production but also places a premium on continuous compliance monitoring.
Denim Fabric Market
A different set of strategies is emerging among specialists. MUD Jeans focuses on premium circular denim jeans produced from post-consumer recycled jeans, emphasizing lower-impact production for men and women. Candiani Denim has positioned itself at the fabric and premium jeans level, with emphasis on regenerative cotton, post-consumer recycled denim, and biodegradable stretch jeans, while supplying fashion brands through its fabric capability. Firemount Group Ltd. has pursued a vertically integrated model with production in Mauritius and documented supply chain details, a structure that can support coordination and quality control but also concentrates regulatory exposure. Denim and Beyond LLC operates on the distribution and import side, handling U.S. logistics for established denim lines, which makes it sensitive to tariff and enforcement dynamics but less directly exposed to production-level sourcing decisions.
PW Consulting
These profiles point to a market that is simultaneously consolidating around scale and brand power while also fragmenting around specialization. New and specialist entrants can compete by owning a clear point of differentiation, whether that is circularity, premium fabric quality, customizable fits, or specific regional production advantages. At the same time, larger players are using product architecture, supplier diversification, and transparency tools to defend share and manage cost and policy risk. The most consequential evolution is not a single wave of consolidation, but a broadening of what “competitive advantage” means in denim: product credibility, sourcing visibility, tariff-aware cost design, and the ability to translate sustainability into tangible product attributes.
A practical illustration of the innovation ecosystem is the Denim Show, which returned to Pragati Maidan in New Delhi, India, offering a platform for denim brands to launch new products and explore innovation trends. Events of this kind matter because they concentrate fabric innovation, product launches, and supplier connections in one place, accelerating the spread of new fits, finishes, and process ideas across a globally connected supply base. For companies seeking to stay ahead of product cycles, these nodes of industry interaction are increasingly important complements to internal R&D and supplier development.
Outlook for the Next Three to Five Years
The first major trend is continued premiumization paired with fit and construction specialization. Heavier denim, customizable fits, and signature construction details are likely to become more important as brands search for ways to differentiate beyond price. This trend favors companies that can control quality, manage longer production runs of specialty items, and communicate product value in a way that resonates with consumers who view denim as an investment garment rather than a disposable commodity. The commercial opportunity lies in building product hierarchies that protect entry-level volume while creating higher-margin tiers with fewer direct comparability points.
The second trend is the institutionalization of circularity and lower-impact production as commercial norms rather than niche initiatives. As post-consumer recycled denim, regenerative cotton, and biodegradable stretch options become more available through suppliers such as Candiani Denim and MUD Jeans, brands will have more options to align product claims with demonstrable process choices. The opportunity here is twofold: brands can use material and process transparency to support price integrity, and fabric and mill specialists can become preferred partners for brands seeking credible differentiation. The risk is that consumer skepticism and regulatory scrutiny will increase alongside the number of sustainability claims, making verification, traceability, and consistent disclosure essential rather than optional.
The third trend is a more complex sourcing and compliance environment driven by tariff uncertainty and enforcement actions. Import duty dynamics affecting Vietnam and Turkey, together with enforcement measures such as the Withhold Release Order against Firemount Group Ltd., suggest that companies will need to treat trade and compliance planning as a continuous operational discipline. Over the next three to five years, sourcing portfolios that balance cost, geography, and documentation are likely to outperform those optimized primarily for unit cost. The associated opportunity is for suppliers and service providers that can help brands manage multi-country sourcing, audit readiness, and import logistics with greater predictability. The primary risk is that rapid policy shifts or enforcement actions can disrupt established supply paths faster than a company can replan, especially if visibility into tier-1 and upstream suppliers is incomplete.
A broader uncertainty to monitor is raw material supply. With cotton projected at up to 1.75 USD per kilogram in 2026 and global production contraction of up to 2 percent during the 2025–2026 season, the denim market could face periodic cost pressure that tests margin discipline and accelerates the adoption of blends, recycled content, or alternative sourcing strategies. The direction of this pressure will depend on weather, harvest outcomes, and broader commodity dynamics, but the prudent planning assumption is that input volatility will remain a recurring factor rather than a one-time event.
Actionable Priorities for Decision-Makers
For manufacturers and fabric producers, the immediate priority is to strengthen the link between product innovation and cost resilience. This means investing in specialty fits, premium constructions, and lower-impact material options while also building flexibility into sourcing and production planning. Companies that can offer regenerative cotton, recycled denim, or biodegradable stretch options with verifiable documentation will be better positioned to serve brands under pressure to demonstrate credible sustainability. Equally important is scenario planning for cotton costs and tariff exposure, so that pricing and capacity decisions are not made on the assumption of a stable input environment.
For investors, the opportunity is to evaluate denim businesses on the basis of differentiation quality, sourcing resilience, and compliance readiness rather than revenue scale alone. Brands and manufacturers with clear premium product tiers, documented supplier visibility, and diversified sourcing footprints are better equipped to navigate enforcement actions and tariff volatility. Specialist players with defensible circular or regenerative positioning can also offer attractive exposure to the growing demand for lower-impact denim, provided their claims are operationalized through product, process, and disclosure. The risk to watch is over-concentration in any single geography or supplier model without the documentation and contingency planning needed to respond to enforcement or trade changes.
For procurement and sourcing leaders, the priority is to treat transparency and geographic diversification as value-protecting disciplines. Tariff scenarios affecting Vietnam and Turkey, along with enforcement actions such as the Withhold Release Order against Firemount Group Ltd., make it prudent to map exposure, strengthen supplier documentation, and maintain alternatives across regions. Procurement teams should also align fabric and product decisions with consumer-facing claims, because the commercial value of sustainability positioning will increasingly depend on the credibility of the underlying process and supply chain evidence. In practical terms, this means more disciplined supplier audits, clearer traceability, and closer coordination between merchandising, compliance, and logistics functions.
For organizations seeking a deeper operational view, the full research report provides additional segmentation detail, company-level sourcing profiles, and scenario analysis that can support more precise planning. The market trajectory is clear enough to justify strategic action now, but the value of that action will depend on how well it is calibrated to product strategy, sourcing architecture, and regulatory exposure. Denim is entering a phase in which durable growth will belong to companies that can combine product credibility, resilient sourcing, and verifiable sustainability with disciplined cost management.
For detailed analysis of this topic, please visit the official page: Denim Jeans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polymer Capacitor Market at 8.2% CAGR: What 2032 Growth and Consumer Electronics Demand Really Signal
By PW Consulting, 2026-09-21
The Polymer Capacitor Market: Strategic Trends and Commercial Opportunities Through 2032
The global polymer capacitor market stands at a pivotal inflection point. From 2020 to 2025, total market revenue expanded from approximately 163.15 million to 215.0 million, reflecting steady growth across multiple end-use sectors. Looking ahead, the trajectory accelerates, with the market projected to reach 344.8 million by 2032, delivering a compound annual growth rate of 8.2 percent over the 2026 to 2032 forecast period. These numbers signal more than incremental expansion; they reflect a structural shift in how electronics manufacturers, automotive system designers, and industrial equipment engineers approach power management and signal integrity.
Beneath the headline figures lies a fragmented yet increasingly strategic competitive arena. The top three players collectively account for 24.6 percent of market revenue, while the top five capture 26.2 percent. This moderate concentration suggests room for differentiation, regional specialization, and technology-led positioning rather than pure scale dominance. For executives and investors evaluating the space, the question is no longer whether polymer capacitors will grow, but which sub-segments, applications, and supply chain strategies will capture disproportionate value as the market matures.
Market Dynamics and Structural Challenges
The polymer capacitor sector operates within a broader passive component ecosystem that is simultaneously experiencing demand surges, material constraints, and tightening qualification standards. Three interconnected challenges define the current landscape and will shape competitive outcomes over the next several years.
Balancing Miniaturization With Reliability Expectations
Design engineers across consumer electronics, automotive, and industrial applications continue pushing for smaller form factors while demanding higher ripple current tolerance, lower ESR, and extended operational lifespans. Polymer capacitors inherently address many of these requirements through conductive polymer electrolyte technology, but the pressure to reduce profile dimensions without compromising thermal stability or moisture resistance creates genuine engineering tension. Manufacturers that can deliver low-profile solutions while maintaining certification-ready performance metrics gain a clear advantage in qualification cycles and design-in opportunities.
PW Consulting Information & Electronics Research Center
Material Cost Volatility and Pricing Pressures
Cost structures across the passive component supply chain have faced sustained upward pressure, particularly in tantalum-based polymer lines. Industry pricing adjustments took effect in mid-2024 as manufacturers cited rising material input costs, and those dynamics have persisted into subsequent quarters. For product planners and procurement teams, this translates into longer hedging windows, tighter inventory buffers, and increased sensitivity to raw material availability. Suppliers with vertically integrated material strategies or diversified polymer formulations are better positioned to manage margin erosion while maintaining competitive pricing.
Qualification Rigor and Customer-Specific Validation Cycles
Automotive and high-reliability industrial applications now require stricter validation protocols. Compliance with AEC-Q200 qualification remains a baseline expectation for automotive polymer capacitors, ensuring consistent performance in electric vehicle power systems and related subsystems. Beyond automotive, industrial-grade polymer products increasingly face moisture-resistance benchmarking at elevated temperature and humidity conditions over extended durations. These qualification thresholds extend time-to-market for new part numbers and raise the barrier for generic commodity players. Companies that invest early in robust qualification dossiers and maintain transparent reliability data shorten customer design cycles and strengthen long-term supply agreements.
Supply chain timing further complicates planning. Across all capacitor technologies, average lead times have hovered around 19 weeks as of late 2025, reinforcing the importance of stable production scheduling and proactive capacity alignment. For buyers, this means demand forecasting and supplier diversification are no longer optional procurement best practices; they are operational necessities.
Core Drivers Shaping Market Trajectory
Several overlapping forces explain why polymer capacitors are capturing growing share across multiple end markets. Understanding these drivers helps decision-makers distinguish structural growth from cyclical demand swings.
Technology Innovation and Form-Factor Engineering
The most visible product-level evolution centers on profile reduction, thermal endurance, and ripple current performance. Recent commercial introductions illustrate how manufacturers are aligning advanced materials with application-specific constraints. In late 2025, Panasonic Industry began commercial production of conductive polymer tantalum solid capacitors with an industry-leading 3 mm profile, targeting USB Type-C power delivery architectures where space and current handling are equally critical. Around the same period, Taiyo Yuden commercialized hybrid aluminum electrolytic capacitor series engineered for higher rated ripple current and reduced profile, specifically addressing automotive ADAS and power steering applications. These launches reflect a broader pattern: manufacturers are not simply scaling existing designs, they are engineering product families around real-world system constraints such as board space, thermal environment, and power delivery topology.
Nichicon’s recent activity reinforces this trend from a thermal-reliability angle. The company introduced a highly heat-resistant conductive polymer hybrid aluminum electrolytic series capable of sustaining 4000 hours at 135°C, alongside automotive-rated hybrid capacitor series distributed across EMEA channels. High-temperature endurance directly supports automotive under-hood and near-power-electronics placements, where long-term degradation profiles determine component selection. Similarly, Nichicon’s broader portfolio emphasis on conductive polymer hybrid aluminum electrolytic and solid capacitors with elevated temperature ratings signals a strategy centered on reliability differentiation rather than cost-only competition.
Application-Side Demand Transformation
Consumer electronics remain the largest application anchor for polymer capacitors, driven by compact power systems, wireless charging, high-density motherboard designs, and ever-increasing power conversion requirements in portable devices. However, the most strategically significant demand shift is occurring in automotive electrification and advanced driver-assistance architectures. As vehicle power systems become more complex and electronics content per platform rises, polymer capacitors are increasingly integrated into DC-DC conversion stages, noise filtering networks, and decoupling arrangements that must tolerate fluctuating thermal and vibration environments.
Industrial automation, renewable energy inverters, and high-reliability infrastructure equipment also contribute to demand diversification. These sectors prioritize long service life, stability under continuous load, and qualification documentation over lowest-unit-cost sourcing. The result is a demand landscape that rewards suppliers capable of matching application-specific performance profiles, not merely volume capacity.
Regulatory, Qualification, and Standardization Pressure
Qualification frameworks and environmental reliability benchmarks increasingly shape purchasing decisions. AEC-Q200 continues to serve as the foundational reliability standard for automotive-grade polymer capacitors, while industrial product expectations have evolved toward stricter moisture and thermal endurance testing. These standards create a two-tier market dynamic: commodity-grade applications tolerate broader performance variance, while automotive and industrial buyers reward proven qualification records and traceable reliability data.
Standardization also influences supply chain behavior. When qualification requirements become more uniform across tier customers, manufacturers with established validation infrastructure gain efficiencies in documentation, testing throughput, and customer onboarding. Those without dedicated qualification capabilities face longer approval timelines and higher rejection risk, particularly in safety-related or mission-critical subsystems.
Supply Chain Resilience and Material Strategy
Recent pricing actions across tantalum-based polymer capacitors underscore the importance of material resilience. Rising input costs have prompted manufacturers to reassess sourcing strategies, formulation alternatives, and inventory positioning. At the same time, lead time elongation across capacitor technologies has reinforced the value of multi-source arrangements and forecast-aligned production planning.
For incumbent suppliers, the response has included hybrid capacitor architectures that combine conductive polymer benefits with aluminum electrolytic structural familiarity, offering a balance of performance and manufacturability. For buyers, this environment emphasizes the need to evaluate not only unit price but also manufacturing continuity, qualification coverage, and the supplier’s ability to sustain availability through cost cycles.
Competitive Landscape and Strategic Positioning
The polymer capacitor market features a mix of established Japanese manufacturers, U.S.-based specialty players, European component specialists, and Taiwan-based producers with regional manufacturing advantages. Despite moderate top-tier concentration, competitive differentiation is increasingly driven by product architecture, application targeting, and qualification readiness rather than broad commoditization.
KYOCERA AVX Components Corporation has positioned itself around conductive polymer solid electrolytic capacitors with notable attention to automotive and high-reliability segments. Its portfolio includes TCO and TCQ automotive series, high-reliability hermetically sealed polymers, and COTS+ military-grade tantalum polymer lines. This mix suggests a strategy that leans into reliability-grade differentiation and application-specific series development rather than volume-only competition.
Panasonic Industry Co., Ltd. maintains a broad polymer capacitor portfolio spanning conductive polymer aluminum electrolytic, tantalum solid, aluminum solid, and hybrid aluminum electrolytic capacitors. Its recent product activity emphasizes profile reduction for power delivery applications, aligning with consumer and computing trends that prize compact form factors without sacrificing current-handling capability.
Murata Manufacturing Co., Ltd. continues to leverage its broader passive component ecosystem, offering conductive polymer aluminum electrolytic and solid capacitors for automotive, industrial, and high-reliability applications. The company’s positioning benefits from integration with adjacent component categories and a strong design-in support structure across multiple end markets.
Nippon Chemi-Con Corporation has expanded its polymer capacitor emphasis through high-voltage series, liquid immersion cooling-oriented series, and hybrid models. The inclusion of high-voltage and cooling-specific product lines indicates attention to power electronics and industrial applications where voltage stress and thermal management are key selection criteria.
Nichicon Corporation has pursued a reliability-led strategy, highlighting conductive polymer hybrid aluminum electrolytic and solid capacitors with high-temperature ratings. Its recent automotive-rated series and heat-resistant product introductions reinforce a focus on application-grade durability, particularly relevant for automotive and industrial environments with sustained thermal exposure.
Rubycon Corporation and Lelon Electronics Corp. provide conductive polymer aluminum electrolytic solutions for general and automotive use. Their market roles illustrate how regional and mid-tier manufacturers compete by combining cost-competitiveness with targeted application support, rather than attempting to match the broadest portfolio breadth of larger incumbents.
Vishay Intertechnology, Inc. extends its presence through polymer tantalum and aluminum solid electrolytic capacitors for industrial, automotive, and aerospace applications. Its positioning reflects the demands of sectors where qualification rigor, material traceability, and reliability documentation carry significant commercial weight.
Würth Elektronik GmbH & Co. KG competes with aluminum polymer electrolytic capacitors and radial series, aligning with the broader European component distribution and design ecosystem. ROHM Co., Ltd. rounds out the competitive field with polymer tantalum and aluminum solid electrolytic capacitors following integration of related business assets, indicating continued consolidation and portfolio rationalization across the sector.
Several competitive themes emerge from this landscape. First, differentiation is shifting from generic capacitance ranges toward application-optimized families with defined thermal, profile, and ripple current characteristics. Second, hybrid architectures are gaining prominence because they combine polymer-level ESR and ripple performance with structural and manufacturing familiarity. Third, the market is unlikely to consolidate rapidly into a single dominant structure; instead, it will likely evolve into a tiered ecosystem where automotive and high-reliability applications favor qualified incumbents, while consumer and general-purpose segments remain more price-sensitive and accessible to multiple suppliers.
Recent product introductions also suggest that regional channel strategies matter. Automotive-rated series launched across EMEA channels highlight the importance of localized qualification support, distribution partnerships, and application engineering availability. Suppliers that can demonstrate consistent technical support across geographies are better positioned to secure design wins in regions where automotive and industrial sourcing decisions are highly relationship and qualification driven.
Forward Outlook: Trends and Opportunities Through 2032
Extrapolating current growth dynamics, qualification momentum, and product innovation patterns points to several interrelated trends that will shape commercial opportunities over the next three to five years.
Trend 1: Application-Specific Polymer Capacitor Families Will Displace One-Size-Fits-All Sourcing
As system designers face tighter thermal envelopes, higher power densities, and more demanding reliability thresholds, generic capacitor specifications will become less persuasive. Buyers will increasingly evaluate parts against application-level benchmarks such as thermal endurance, ripple current capability, profile constraints, and qualification documentation. Suppliers that publish clear application 매핑 and maintain robust reliability data will capture more design-ins, particularly in automotive and industrial segments where failure cost is high.
Commercial opportunity: Companies that invest in application engineering, reference designs, and qualification-ready documentation can shorten customer evaluation cycles and build longer-term supply relationships. This creates a defensible position even in a moderately concentrated market.
Trend 2: Hybrid and Advanced Polymer Formulations Will Broaden Performance Windows
Hybrid aluminum electrolytic structures and advanced conductive polymer formulations will continue to expand the balance between ESR reduction, temperature stability, and manufacturability. These architectures are particularly relevant where designers need polymer-level electrical performance without abandoning aluminum-based mechanical or cost advantages. The ongoing appearance of hybrid-oriented product launches supports the view that this direction is not a niche experiment but a mainstream performance strategy.
Commercial opportunity: Product planners should monitor hybrid and advanced polymer lines as potential candidates for next-generation power delivery, noise filtering, and decoupling designs. Early engagement with suppliers offering these architectures can provide first-mover advantages in demanding applications.
Trend 3: Automotive Electrification and High-Reliability Industrial Demand Will Drive Sustained Volume Growth, With Qualification as the Gatekeeper
Conductive Polymer Aluminum Solid Capacitors Market
The 8.2 percent CAGR projected through 2032 reflects more than cyclical replacement demand; it reflects a structural increase in electronics content across vehicles, industrial equipment, and energy-related infrastructure. Automotive platforms in particular will continue placing higher capacitor content per vehicle as power management architectures grow more decentralized and more performance-critical. At the same time, qualification requirements will remain the commercial gatekeeper, meaning that volume growth will disproportionately flow to suppliers with credible reliability records and efficient validation processes.
Commercial opportunity: Suppliers that build automotive and industrial qualification capabilities early can secure longer design cycles and multi-program visibility. For buyers, prioritizing qualification readiness and supply continuity over short-term unit cost can reduce downstream risk in safety-related or mission-critical designs.
Vacuum Capacitor Market
Risk and Uncertainty Considerations
Several uncertainties could alter this trajectory. Material cost volatility may persist, affecting tantalum-based and other polymer lines unevenly. Lead time normalization is not guaranteed; supply disruptions, capacity constraints, or sudden demand shifts could reintroduce planning friction. Qualification expectations may continue to tighten, compressing timelines for new entrants and rewarding incumbents with established testing infrastructure. Finally, competitive overcapacity in certain commodity-grade segments could pressure pricing, even as qualified automotive and industrial segments remain more resilient. Decision-makers should therefore treat the polymer capacitor market as a portfolio of differentiated sub-segments rather than a single homogeneous opportunity.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities in this environment. The following actions are designed to translate market dynamics into executable planning.
For Manufacturers and Component Suppliers
- Prioritize application-specific product families that address profile, thermal endurance, and ripple current requirements simultaneously rather than competing solely on capacitance range or unit cost.
- Strengthen qualification documentation and reliability data packages, especially for automotive and industrial customers where AEC-Q200 and extended environmental testing are baseline expectations.
- Evaluate hybrid and advanced polymer formulations as a way to expand performance differentiation while maintaining manufacturability and cost discipline.
- Align production planning and inventory strategy with current lead-time realities, and consider multi-source options where qualification and performance allow.
For Investors and Strategic Allocators
- Focus due diligence on suppliers with credible automotive and high-reliability qualification footprints, because those segments are likely to capture disproportionate value even in a moderately concentrated market.
- Assess exposure to material cost sensitivity and pricing actions across tantalum and aluminum polymer lines, and weigh vertical integration or formulation diversification as risk-mitigation indicators.
- Watch for portfolio consolidation and asset integration activity that may reshape competitive positioning, especially where adjacent business assets are combined to strengthen polymer capacitor capabilities.
For Procurement, Engineering, and Supply Chain Leaders
- Treat qualification status, thermal performance, profile constraints, and supply continuity as core evaluation criteria alongside price, particularly for automotive and industrial designs.
- Diversify approved sources where application requirements permit, while maintaining clear qualification thresholds to avoid fragmented validation burden.
- Engage suppliers early in the design phase to align on reliability testing, documentation, and lead-time expectations, reducing the risk of late-stage redesign or sourcing disruption.
The polymer capacitor market is expanding with clarity in direction but complexity in execution. Growth will continue toward 344.8 million by 2032, but the value capture will depend on how well companies align product engineering, qualification readiness, and supply resilience with the application needs that matter most. For organizations seeking deeper segmentation data, regional positioning detail, and tailored strategy recommendations, the full PW Consulting research report provides the granular breakdown and scenario analysis needed to convert these trends into actionable plans.
For detailed analysis of this topic, please visit the official page: Polymer Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Textile Chemicals Market 2026: Beyond the 4.8% CAGR and Asia Pacific’s $15.4B Pull
By PW Consulting, 2026-09-21
The Textile Chemicals Market: Strategic Shifts and Commercial Opportunities Through 2032
The textile chemicals sector has entered a phase of structural recalibration. After a decade of steady volume growth underpinned by expanding apparel production and industrial fabric consumption, the market is now being reshaped by tighter environmental mandates, evolving consumer expectations, and technological breakthroughs that are redefining how fibers are treated, dyed, and finished. For executives, investors, and procurement leaders, the central question is no longer whether demand will grow, but where value will concentrate and which capabilities will separate winners from laggards in the coming years.
The global market for textile chemicals has reached a valuation of approximately 30 billion USD in 2025, representing a measured acceleration from roughly 21.5 billion USD in 2020. Over the 2020 to 2025 period, revenue expanded at a compound trajectory that reflects both post-pandemic recovery and the steady integration of chemical solutions across garment, home textile, and technical fabric supply chains. Looking ahead to 2032, the market is projected to surpass 41 billion USD, driven by a compound annual growth rate averaging 4.8 percent. While this growth rate signals resilience, it also indicates that the era of unconstrained volume expansion is giving way to a more selective, regulation-aware, and performance-driven landscape. Value creation will increasingly depend on how effectively companies navigate compliance complexity, capture premium segments, and align product portfolios with sustainability and circularity mandates.
Market Reality and Critical Inflection Points
The headline growth figures mask underlying tensions that are already reshaping competitive dynamics. Three interlocking challenges define the current inflection point for the sector.
First, regulatory intensity is shifting from voluntary best practices to enforceable, auditable standards. Chemical input approval criteria, substance restriction lists, and wastewater discharge targets are no longer confined to niche certifications. They are cascading through procurement contracts, brand compliance programs, and regional market access requirements. Companies that treat compliance as a retrospective documentation exercise are finding themselves locked out of premium accounts or forced into costly reformulation cycles. The regulatory wave is compressing margins for undifferentiated products while rewarding firms that have built formulation transparency and substitution capability into their R&D workflows.
Second, the cost and availability of conventional chemical building blocks remain structurally uncertain. Feedstock volatility, energy price swings, and shifting trade flows have disrupted the predictability that many formulators relied on for cost planning. At the same time, the transition toward lower-impact and bio-based alternatives introduces new input economics that can be higher in the short term. The practical consequence is that pricing strategies based solely on historical material costs are increasingly brittle. Businesses that succeed are those that combine multi-source sourcing, formulation flexibility, and service-level agreements that share risk more intelligently across the value chain.
Textile Dyes Market
Third, customer expectations are bifurcating the market. Mass-market segments continue to pressure suppliers for cost efficiency and reliable delivery, while premium and performance-oriented segments demand demonstrable environmental attributes, functional performance in demanding applications, and traceability. This polarization makes portfolio strategy decisive. Suppliers that attempt to serve all segments with a uniform offering risk being commoditized in the low end while failing to capture the margin in the high end. Those that can clearly segment their value proposition, back claims with verified data, and align service models accordingly are better positioned to defend pricing and deepen customer relationships.
Key Drivers Reshaping the Landscape
Understanding where growth and margin will concentrate requires looking past top-line volume to the forces that are changing how textile chemicals are developed, approved, and deployed.
Technological innovation and formulation breakthroughs. Advances in low-temperature dyeing, enzyme-assisted pretreatment, waterless or reduced-water finishing, and digital color matching are steadily reducing resource intensity while improving reproducibility. Digital tools are also enabling faster formula optimization and more precise dosing, which directly lowers wastewater load and chemical waste. These innovations matter commercially because they translate environmental performance into operational savings that customers can verify. Suppliers that embed these capabilities into ready-to-adopt process packages, rather than offering only raw ingredients, are building stickier relationships and gaining pricing power.
Policy and regulatory environment. The regulatory framework is tightening across multiple jurisdictions, with substance restrictions, organic textile chemical criteria, and endocrine disruptor limits all moving toward stricter thresholds and broader coverage. Recent updates to major standards have introduced lower limits for certain substances, expanded the list of regulated compounds, and added mandatory due diligence expectations for chemicals used in organic fiber production. In parallel, regional legislation targeting specific chemical families in textiles, clothing, footwear, and waterproofing agents has moved into force or toward implementation, with exemptions limited to specific recycled or industrial use cases. For suppliers, the strategic implication is clear: product stewardship is now a market-access requirement. Formulation roadmaps must anticipate substitution needs, documentation must meet audit expectations, and technical support must help customers navigate compliance without disrupting production.
Demand-side behavior. Brands and manufacturers are increasingly tying procurement decisions to measurable sustainability outcomes and risk reduction. Consumer-facing claims are being scrutinized more closely, which pushes upstream suppliers to provide credible, standardized evidence rather than marketing narratives. At the same time, the rise of technical textiles and high-performance applications is expanding demand for chemicals that deliver specific functionalities such as durability, moisture management, antimicrobial action, or flame resistance, often with tighter environmental profiles. This dual pressure rewards suppliers that can combine performance with verifiable attributes and that can support customers in meeting both internal targets and external claims.
Supply chain and cost structure realignment. Geographic concentration of production, logistics bottlenecks, and evolving trade dynamics have encouraged buyers to diversify sources and favor suppliers with regional presence or strong distribution networks. Distributors and integrated suppliers that can guarantee continuity, offer technical troubleshooting, and consolidate multiple chemical needs into a single interface are gaining importance, particularly for smaller and mid-sized processors. The cost structure is also being reshaped by the premium attached to compliant, lower-impact chemistries and by the operational savings that come from more efficient application processes. Businesses that can articulate total cost of ownership rather than unit price are better equipped to navigate these shifts.
The Competitive Field: Positioning, Differentiation, and Evolution
The market remains moderately concentrated, with the largest players holding a meaningful share of total revenue while significant space remains for specialized and regional players. This structure favors a dual strategy: scale players compete on broad portfolios, global reach, and technical service infrastructure, while specialists compete on deep application knowledge, niche performance attributes, and agility in formulation.
Fine Chemicals Market
Archroma occupies a prominent position as a global provider of sustainable dyes, colorants, and performance chemicals tailored to dyeing, finishing, and printing applications. Its differentiation rests on a strong sustainability narrative backed by product development focused on reduced environmental impact and process efficiency, combined with the ability to serve large, multi-site customers with consistent standards.
Huntsman Textile Effects, with operations spanning Switzerland and Germany, focuses on functional dyes, finishing chemicals, and performance solutions. Its strength lies in blending application expertise with high-performance outcomes, allowing it to address demanding end-use requirements while supporting customers in meeting quality and compliance expectations.
CHT Group, based in Germany, specializes in textile chemicals, auxiliaries, and dyeing solutions for printing, finishing, and processing. Its positioning emphasizes depth in application know-how and a focused specialty portfolio, which enables close collaboration with processors seeking tailored solutions rather than broad commodity offerings.
Azelis operates as a distributor and integrated supplier across dyes, bleaching agents, pretreatment chemicals, and finishing solutions. Its competitive advantage comes from network reach, inventory continuity, and the ability to bundle technical support with supply reliability, an increasingly valuable proposition for customers managing complex compliance and sourcing requirements.
On the Asia-centric side, NICCA Chemical stands as Japan's leading developer and manufacturer of scouring, dyeing, and finishing chemicals, leveraging strong process expertise and a reputation for quality and reliability. Sarex Chemicals and Fineotex Chemical, both based in India, contribute specialist coverage across auxiliaries, pretreatment, dyeing, printing, and finishing. Their relevance lies in serving full value-chain needs with regional cost structures, local technical presence, and the ability to support high-volume production environments that demand consistent availability and practical process support.
The competitive landscape is evolving along three trajectories. Consolidation continues to favor larger players that can integrate R&D, compliance documentation, and global service delivery, particularly as customers seek fewer, more accountable partners. At the same time, fragmentation remains viable for specialists that can dominate specific application niches, offer differentiated performance, or provide rapid regional responsiveness. A third dynamic is the growing role of events and platforms that concentrate the industry's attention on chemicals and dyes. The launch of a dedicated Textile Chemicals and Dyes product segment at a major international trade fair, featuring more than 30 exhibitors across dyes, auxiliaries, functional finishes, and polymer technologies, signals that chemical solutions are being elevated from supporting inputs to strategic showcase categories. Early booking windows and confirmed participation from established players further indicate that the segment is becoming a focal point for partnership formation, product launches, and market signaling. Regional expos centered on textile chemicals and auxiliaries continue to reinforce the importance of Asia as both a manufacturing base and a sourcing hub, where proximity, cost, and technical support intersect.
Forward Outlook: Three Trends Shaping 2026 to 2032
The combination of regulation, technology, and demand evolution points to a set of trends that will define commercial opportunities over the next several years.
Compliance-driven reformulation will become a recurring revenue stream rather than a one-time project. As substance restrictions tighten, due diligence expectations expand, and wastewater guidelines grow more prescriptive, processors will need ongoing support to maintain market access. This creates sustained demand for alternative chemistries, testing support, documentation services, and process adjustments. The commercial opportunity lies not only in new molecules but in service architectures that help customers stay ahead of change. Suppliers that anticipate regulatory trajectories and pre-develop substitute portfolios will capture switching demand before competitors react. The risk is that compliance becomes a reactive cost center if firms lack foresight, leading to rushed substitutions, production disruptions, and eroded trust.
Performance and sustainability will increasingly converge in premium segments. Functional finishes, durable properties, and reduced-impact processing are moving from separate considerations to combined requirements. Customers want chemicals that deliver specific end-use performance without undermining environmental targets, and they expect evidence that can satisfy both internal procurement criteria and external claims. This convergence favors suppliers that can bundle functional chemistry with application engineering and verified attribute data. The upside is margin expansion in segments where differentiation is defensible. The uncertainty is that verification standards and claim scrutiny will continue to rise, which raises the bar for substantiation and can slow adoption if proof points are weak.
Regional service models and distribution strength will matter as much as product formulations. As procurement teams diversify sourcing and tighten continuity requirements, the ability to deliver reliably, troubleshoot locally, and consolidate multiple needs into a coherent package becomes a differentiator. Distributors and integrated suppliers with strong regional footprints can reduce risk for processors that cannot manage complex multi-supplier relationships across borders. This trend supports growth for players that invest in local technical presence, inventory resilience, and responsive service. The downside is that building and maintaining such networks requires capital and operational discipline, and players that over-extend geographically without adequate support infrastructure may struggle to convert reach into profitable relationships.
Strategic Imperatives for Decision-Makers
The choices made over the next twelve to twenty-four months will shape competitiveness through the end of the decade. The following actions are most relevant across the main stakeholder groups.
PW Consulting Information & Electronics Research Center
For manufacturers and formulators. Build a reformulation pipeline that maps current product portfolios against anticipated regulatory thresholds and customer sustainability expectations. Prioritize formulations that lower water, energy, and waste intensity while maintaining or improving performance, because these solutions convert environmental goals into operational savings that customers can measure. Strengthen documentation, testing, and traceability so that claims can withstand audit scrutiny. Segment the portfolio clearly between cost-competitive essentials and premium performance or sustainability-led offerings, and align sales and technical service teams accordingly so that each segment is supported with the right value narrative and service model.
For investors. Favor business models with defensible differentiation: proprietary formulations paired with verified attributes, strong compliance capability, and regional service reach. Assess exposure to regulatory risk by examining how dependent revenue is on substances likely to face tighter limits, and evaluate whether the company has substitution roadmaps and credible alternatives. Look for evidence that environmental performance is being integrated into product design rather than treated as a separate initiative, since this integration increasingly determines access to premium accounts. Monitor distribution partnerships and technical service capacity, because continuity and support can be the deciding factor in procurement decisions for processors facing compliance and sourcing complexity.
For procurement and buying organizations. Treat chemical selection as a risk-management and total-cost decision rather than a unit-price exercise. Evaluate suppliers on formulation transparency, compliance readiness, substitution capability, and the ability to support process efficiency improvements that reduce resource use and waste. Encourage multi-year collaboration with key suppliers so that reformulation, testing, and documentation can be planned in advance rather than triggered by emergency compliance events. Prioritize suppliers that can provide standardized evidence packages aligned with the certifications and standards relevant to your markets, because this reduces downstream verification friction and strengthens your own claims.
Timely, granular intelligence is essential for executing these actions with precision. Market-level growth rates and segment sizes provide useful context, but the decisions that determine competitive advantage depend on how specific regulations will affect product lines, where substitution demand is emerging earliest, which applications are capturing premium margins, and how distribution and service models are shifting in key regions. A complete research report offers the detailed segmentation, company benchmarking, regulatory mapping, and scenario-based forecasts needed to translate these dynamics into concrete plans. It also provides the granular data and customized recommendations that allow decision-makers to prioritize initiatives, assess risk exposure, and identify the most actionable opportunities for their specific portfolio and geography.
For detailed analysis of this topic, please visit the official page: Textile Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nel mercato attuale dei dispositivi monouso a grande autonomia, la soglia delle decine di migliaia di boccate è diventata il nuovo standard per gli utenti che cercano praticità e lunga durata. Tuttavia, quando si parla di cifre elevate come le 60.000 boccate pubblicizzate, è utile comprendere che tali stime si basano generalmente su modalità di utilizzo a basso consumo energetico. Due dei modelli più discussi in questa categoria offrono prestazioni e filosofie costruttive profondamente differenti, pensate per soddisfare aspettative e stili di svapo del tutto peculiari.
Da un lato, il modello Vozol Neon 60k punta con decisione sull'equilibrio tra autonomia energetica e controllo del liquido. Grazie a una batteria capiente da 1100mAh e a un serbatoio fisico trasparente che permette di tenere sempre sotto controllo il livello residuo, questo dispositivo assicura una gestione molto regolare. L'integrazione di tre livelli di regolazione e di una doppia bobina a rete intelligente consente di passare facilmente da uno stile di tiro più chiuso a uno più aperto, ottimizzando i consumi e avvicinando l'esperienza complessiva al limite massimo dichiarato.
Dall'altro lato, Al Fakher Crown Bar 60k adotta un approccio orientato alla potenza e alla tradizione del fumo denso. Equipaggiato con una batteria da 850mAh compatibile con la ricarica rapida e un sistema progettato per offrire un tiro polmonare diretto in stile narghilè, questo dispositivo privilegia l'intensità aromatica e la corposità del vapore. La struttura a bassissima resistenza assicura una resa eccezionale in termini di sapore, sebbene l'uso continuo di svapo profondo possa incidere in modo più marcato sulla durata effettiva complessiva rispetto a un profilo più moderato.
La scelta tra questi due giganti dipende interamente dalle abitudini personali: chi predilige la durata prolungata della batteria e un controllo visivo costante troverà nel primo un ottimo compagno quotidiano, mentre chi cerca densità di vapore e richiami al gusto tradizionale preferirà la spinta del secondo. Per valutare nel dettaglio quale soluzione si adatti meglio alle tue esigenze di portabilità e selezione dei gusti, ti invitiamo a scoprire di più sulle schede tecniche dei prodotti. Leggi di più sui test di autonomia e sulle caratteristiche delle novità del settore.
Mit Kapazitäten von bis zu 50.000 Zügen erreichen moderne Einweg-E-Zigaretten eine neue Dimension der Langlebigkeit. Für erwachsene Nutzer bringt diese enorme Ausdauer jedoch oft eine praktische Herausforderung mit sich: die sogenannte Geschmacksmüdigkeit, wenn wochenlang dasselbe Aroma gedampft wird. Genau hier setzt die Vozol Gear Ice & Sweet 50k an. Das kompakte Gerät richtet sich an Dampfer, die im Alltag und auf Reisen nicht auf Portabilität verzichten möchten, aber gleichzeitig hohe Ansprüche an geschmackliche Flexibilität stellen.
Individuelle Aromen dank Dual-Achsen-Steuerung
Das herausragendste Merkmal dieses Modells ist das innovative Anpassungssystem für den Geschmack. Nutzer können über eine einfache Mechanik am Gerät zwischen vier verschiedenen Frische-Stufen (Ice) und zwei Süße-Graden (Sweet) wählen. Durch diese clevere Kombination ergeben sich acht völlig unterschiedliche Geschmacksprofile aus ein und demselben Liquid-Tank. So lässt sich das Dampferlebnis je nach Stimmung oder Tageszeit individuell anpassen, wodurch selbst bei einer extrem langen Nutzungsdauer keine Langeweile aufkommt.
Triple-Mesh und smarte Anzeige-Technologie
Im Inneren überzeugt das Gerät durch fortschrittliche Technik, die auf Langlebigkeit ausgelegt ist. Die verbaute Triple-Mesh-Technologie mit spezieller Geschmacksversiegelung verteilt die thermische Belastung gleichmäßig auf drei Spulen. Das schützt effektiv vor unangenehmem Kokeln (Dry Hits) und sorgt für einen beständigen Geschmack vom ersten bis zum letzten Zug. Zudem liefert ein modernes 3D-Curved-Display jederzeit klare Echtzeitdaten zum aktuellen Akkustand sowie zur gewählten Frische und Süße. Für die nötige Leistung sorgt eine großzügige 1100-mAh-Batterie, die zwei wählbare Ausgabemodi (Regular und Surge) zuverlässig mit Energie versorgt.

Robustes Design für den Alltag
Neben der starken technischen Ausstattung punktet die Vozol Gear Ice & Sweet 50k durch ihr äußerst robustes Gehäuse. Ganz in der Tradition der bekannten Gear-Serie verfügt auch dieses Modell über eine praktische Staubschutzkappe für das Mundstück sowie eine widerstandsfähige Außenhülle. Diese Eigenschaften machen die E-Zigarette zu einem idealen Begleiter für Outdoor-Aktivitäten oder längere Ausflüge. Eine stufenlos verstellbare Luftzufuhr (Airflow) an der Unterseite rundet das nutzerfreundliche Gesamtpaket ab.
Zusammenfassend kombiniert dieses Modell eine außergewöhnliche Kapazität mit einer nie dagewesenen geschmacklichen Anpassungsfähigkeit in einem äußerst tragbaren Format. Es löst das Problem eintöniger Aromen auf clevere Weise und bietet ein langanhaltendes Premium-Erlebnis. Möchten Sie mehr über die neuesten E-Zigaretten-Trends, innovative Features und praktische Tipps für Ihren Alltag erfahren? Entdecken Sie jetzt weitere spannende Beiträge in unserem Blog und lesen Sie mehr!
Sie könnten auch Folgendes mögen:
Vozol Star 50k
Nexa Vape 50000
Fumot 50k
Wet Flue Gas Desulfurization Systems Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-19
Wet Flue Gas Desulfurization Systems Market
Overview
The Wet Flue Gas Desulfurization Systems Market encompasses advanced pollution control technologies designed to remove sulfur dioxide (SO₂) from industrial exhaust gases. These systems are vital for reducing environmental emissions, ensuring compliance with stringent regulations, and supporting sustainable industrial operations. Core functionalities include the absorption of SO₂ using a liquid scrubbing process, typically involving limestone or lime slurry, which converts sulfur compounds into by-products like gypsum.
The market plays a crucial role in supporting modern industries such as power generation, cement manufacturing, and chemical processing. The Wet Flue Gas Desulfurization Systems Market is central to mitigating air pollution and minimizing environmental impact, making it indispensable for industries aiming to meet environmental standards and enhance operational sustainability.
Market Size and Growth
The current market value for Wet Flue Gas Desulfurization Systems is estimated at approximately USD 8 billion. It is projected to grow to around USD 15 billion by 2030, reflecting a compound annual growth rate (CAGR) of roughly 7%. Factors driving this growth include stricter emission regulations, increasing adoption of clean coal technologies, and expanding industrial infrastructure in emerging economies.
The ongoing demand for effective sulfur oxide removal solutions sustains steady market expansion, with technological innovations further boosting adoption rates across various sectors. As environmental policies tighten globally, the market for wet flue gas desulfurization systems is expected to maintain a robust growth trajectory over the next decade.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2082
Key Drivers
• Stringent environmental regulations and emission standards
• Rising demand for clean coal and fossil fuel power plants
• Increasing industrialization in emerging markets
• Technological advancements improving system efficiency
• Growing environmental awareness and corporate sustainability commitments
Restraints
• High capital and operational costs of systems
• Technical complexity and maintenance requirements
• Regulatory delays and compliance uncertainties
• Limited availability of suitable raw materials in some regions
• Operational challenges in retrofitting existing plants
Segmentation
• By Type: Wet scrubbers, spray tower systems, venturi scrubbers
• By Deployment: In-situ, modular, mobile units
• By Enterprise Size: Large enterprises, SMEs, government agencies
• By End User: Power plants, cement plants, chemical industries, refineries
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits mature adoption driven by stringent environmental policies and technological innovation. Europe’s market growth is fueled by strong regulatory frameworks and industrial modernization efforts. In the Asia-Pacific region, rapid industrial growth and urbanization are key factors, with China and India leading demand. Latin America shows emerging opportunities as industries upgrade pollution control systems. The Middle East & Africa are gradually adopting these systems to comply with environmental standards amid expanding energy sectors.
Opportunities
• Expansion in emerging markets such as India and Southeast Asia
• Adoption of hybrid systems integrating wet and dry technologies
• Innovation in membrane and filtration technologies
• Increasing use of automation and IoT for system monitoring
• Growing demand from renewable energy and decarbonization initiatives
Key Companies
Babcock & Wilcox Enterprises, GE Power, Mitsubishi Power, ANDRITZ, FLSmidth, Thermax Limited, Hamon Group, Doosan Group, Hitachi Zosen Inova, Sulzer, Veolia, Alstom
Conclusion
The overall outlook for the Wet Flue Gas Desulfurization Systems Market remains positive, driven by evolving environmental regulations and industrial modernization. With long-term growth potential, the market is strategically important for industries seeking sustainable emission control solutions. As global emphasis on air quality intensifies, the market for wet flue gas desulfurization systems is poised for continued expansion and technological innovation.
Related Reports
Industrial Drone Technology Market , Size Share and Analysis | Report 2033
Automatic Degas And Sealing Machine Market , Size Share and Analysis | Report 2033
Fiber Fineness Tester Market , Size Share and Analysis | Report 2033
Iot Industrial Controller Market , Size Share and Analysis | Report 2033
Mobile Apple Cabin House Market , Size Share and Analysis | Report 2033
Vertical Stack Fan Coil Market , Size Share and Analysis | Report 2033
Dome Star Rooms Market , Size Share and Analysis | Report 2033
High Purity Germanium Gamma Spectrometer Market , Size Share and Analysis | Report 2033
Rtk Survey Systems Market , Size Share and Analysis | Report 2033
Flat Membrane Pressure Sensor Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Wave Buoy Market
Overview
The Wave Buoy Market encompasses the development and deployment of advanced wave measurement devices designed to monitor oceanic and sea conditions. These buoys serve critical functions such as measuring wave height, frequency, and direction, providing essential data for maritime navigation, coastal management, and renewable energy projects. Their core functionalities support industries that rely on accurate oceanic data, including offshore drilling, shipping, and wave energy generation.
The importance of the Wave Buoy Market lies in its ability to facilitate safer maritime operations and optimize renewable energy extraction. As the demand for sustainable energy sources grows, wave energy conversion becomes increasingly vital. The market for wave buoys is central to these efforts, enabling precise data collection to support innovative technological solutions and industry growth. The Wave Buoy Market is thus integral to advancing ocean-based industries and environmental monitoring systems.
Market Size and Growth
The current value of the Wave Buoy Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 3.5 billion, reflecting a compound annual growth rate (CAGR) of approximately 11%. Growth is driven by rising investments in renewable energy, increased maritime safety regulations, and expanded offshore infrastructure. Technological advancements in buoy design and data analytics further propel market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2120
Key Drivers
- Increasing demand for renewable wave energy solutions
- Growing maritime safety and navigation requirements
- Expansion of offshore oil and gas exploration
- Technological innovations in buoy sensors and data transmission
- Government incentives for sustainable energy projects
Restraints
- High operational and maintenance costs
- Technical challenges in harsh ocean environments
- Regulatory hurdles and compliance complexities
- Limited standardization across different regions
- Environmental impact concerns and ecological restrictions
Segmentation
• By Type: Fixed, moored, drifting
• By Deployment: Coastal, deep-sea, offshore
• By Enterprise Size: Large corporations, SMEs
• By End User: Marine research, energy, defense, shipping, government agencies
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
In North America, the market benefits from extensive offshore energy projects and advanced maritime infrastructure, fostering steady demand. Europe’s focus on renewable energy and stringent safety standards drive adoption, especially in the North Sea. Asia-Pacific shows rapid growth due to expanding offshore exploration and emerging wave energy initiatives. Latin America’s market remains emerging, with increasing interest in coastal management. The Middle East & Africa are gradually adopting wave buoy technology, primarily for offshore oil and renewable projects.
Opportunities
- High-growth potential in offshore renewable energy sectors
- Adoption of IoT and AI for real-time ocean monitoring
- Innovation in durable, cost-effective buoy designs
- Expanding applications in climate change research and disaster prevention
- Strategic partnerships between technology providers and energy companies
Key Companies
ABB, Teledyne Marine, Oceanographic Instruments, Kongsberg Maritime, Datawell, Fugro, RBR, Nortek, Xylem, McMurdo, NOAA, Sea & Land Technologies
Conclusion
The overall outlook for the Wave Buoy Market remains optimistic, with long-term growth driven by the global shift toward sustainable energy and enhanced maritime safety. As industries increasingly rely on precise oceanic data, the market’s strategic importance will continue to rise. The Wave Buoy Market offers substantial potential for innovation and expansion, making it a vital component in future ocean and energy infrastructure development.
Related Reports
Candy Pouring Mold Market , Size Share and Analysis | Report 2033
Fully Automatic Lithium Battery Pressing Machine Market , Size Share and Analysis | Report 2033
Cordless Mitre Saw Market , Size Share and Analysis | Report 2033
Molded Transformers Market , Size Share and Analysis | Report 2033
Soft Candy Boiling Machine Market , Size Share and Analysis | Report 2033
Cassette Membrane Ultrafiltration System Market , Size Share and Analysis | Report 2033
Hybrid Aircraft Propulsion Propeller Market , Size Share and Analysis | Report 2033
Open Cycle Aero Engine Market , Size Share and Analysis | Report 2033
Dark Box Uv Analyzer Market , Size Share and Analysis | Report 2033
Multi Stage Ultrasonic Cleaners Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher