

Blogs
PW Consulting: Raised Access Floor Market Hits $1.66B in 2025, Projected to Reach $2.4B by 2032
By PW Consulting, 2026-09-16
Strategic Foundations Beneath the Surface: Why the Raised Access Floor Market Demands Executive Attention in 2026
Modern enterprise infrastructure is undergoing a quiet but irreversible transformation. As data centers scale to accommodate artificial intelligence workloads, commercial offices reconfigure around hybrid work models, and clean room facilities tighten environmental controls, the raised access floor has evolved from a passive architectural element into a critical enabler of operational resilience. At PW Consulting, we recognize that leaders who understand the structural shifts in this market gain a decisive advantage in capital allocation, vendor selection, and long-term facility planning. This introduction to our newly released Raised Access Floor Market research study outlines the strategic rationale behind our analysis, previews the actionable intelligence embedded in the full report, and explains why 2026 represents a pivotal inflection point for stakeholders across real estate, IT infrastructure, and construction sectors.
The Macro Trajectory: A Market Built on Sustained Expansion
The raised access floor sector has demonstrated remarkable consistency through cycles of supply chain volatility, shifting construction demand, and evolving technical specifications. Historical tracking from 2020 through 2025 reveals a steady revenue progression, moving from just over USD 1.27 billion to approximately USD 1.66 billion by the base year. This trajectory reflects more than incremental growth; it signals a structural recalibration of how organizations design indoor environments to support power distribution, airflow management, and modular reconfiguration. Looking forward, our forecast model projects the market to surpass USD 1.8 billion in 2026 and continue its upward path toward USD 2.4 billion by 2032. The compound annual growth rate of 5.41 percent underscores a mid-to-high single-digit expansion phase that is neither speculative nor overly aggressive, but rather anchored in tangible facility modernization requirements and sustained commercial construction activity.
For decision-makers, this growth pattern carries immediate implications. It suggests that demand is not concentrated in a single vertical or geography, but rather distributed across multiple end-use environments that are simultaneously upgrading their physical infrastructure. It also indicates that procurement strategies relying on short-term price optimization may overlook the broader value of system longevity, maintainability, and compatibility with next-generation cooling and networking architectures. Our analysis is designed to help executives distinguish between temporary market fluctuations and durable investment themes.
What the Full Study Delivers: Operational Intelligence, Not Just Headlines
Market summaries often stop at top-line figures, but effective strategy requires granular visibility into how value is created, captured, and contested. The complete PW Consulting report is structured to provide exactly that depth. Readers will find a methodical dissection of product architectures, including steel encapsulated platforms, calcium sulphate board systems, aluminum variants, chipboard encapsulated options, and other specialized constructions. Each material pathway presents distinct trade-offs in load capacity, acoustic performance, moisture resistance, and installation logistics. The study maps these characteristics against real-world deployment scenarios so that procurement leaders and facility architects can align specification choices with operational priorities rather than defaulting to legacy standards.
Equally critical is the application-layer analysis. Data centers, commercial offices, clean rooms, institutional buildings, and other use cases each impose unique performance thresholds. Our research evaluates how raised access flooring systems are specified, tested, and maintained across these environments, highlighting where design flexibility matters most and where standardization yields measurable cost efficiencies. Regional demand patterns are examined through the lens of construction pipelines, regulatory environments, and local supply chain maturity, enabling multinational corporations and regional developers alike to calibrate their market entry or expansion strategies with precision. The report also integrates competitive benchmarking, pricing architecture reviews, and supply chain sensitivity assessments that translate directly into tender preparation, vendor negotiations, and lifecycle cost modeling.
Competitive Posture: How Leading Players Are Shaping the Landscape
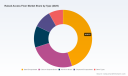
The raised access floor market is characterized by a balanced concentration structure, with the top three participants accounting for approximately forty percent of revenue and the top five collectively holding around half of total market share. This dispersion signals a competitive arena where scale, technical differentiation, and regional execution capability all matter. Several established and emerging players have carved out recognizable positions by emphasizing distinct value propositions, and our study tracks how these strategic postures are evolving in response to customer demands and macroeconomic pressures.
Tate Global, headquartered in the United Kingdom, has built recognition around innovative raised access flooring solutions tailored for commercial offices and data centers, emphasizing configuration adaptability and integration with modern workplace layouts. DIRTT, based in Canada, addresses the growing need for low-profile access floors with integrated power and data distribution, effectively converging flooring infrastructure with structured cabling and power management. In the high-load segment, Rhino Technologies Co., Ltd. of the United States has focused on engineered steel panel systems designed specifically for demanding data center environments, where structural integrity and load distribution are non-negotiable. Across the Asia-Pacific manufacturing base, Polygroup has emphasized adjustable pedestal systems that streamline installation and enable precise height calibration, while Titanflor has positioned its offerings for broader industrial and commercial projects that require durable, repeatable floor systems. Huilian Flooring, also based in China, has pursued a differentiated path by combining raised access flooring systems with ceramic finishes, targeting environments where surface durability and cleanability are paramount. Meanwhile, Access Floors Distribution in the United Kingdom continues to serve specification-driven projects with a focus on raised floor tiles and integrated systems that align with architectural and engineering workflows.
Raised Access Floor Market
Strategic momentum in this sector is not static. Recent developments illustrate how competition is intensifying through both product innovation and service model expansion. In January 2026, Huilian highlighted its R&D commitment by showcasing more than seventy patents, including ten invention patents focused on raised access flooring systems. This level of intellectual property activity suggests a deliberate push toward proprietary design features that can create specification lock-in and improve margin resilience. In November 2025, The Access Flooring Company introduced an AI-powered chatbot service intended to provide immediate expert assistance on raised access flooring systems, reflecting a wider industry trend toward digital support channels that reduce specification friction and accelerate project decision cycles. On the project delivery side, Strut Systems Installation carried out a custom Unistrut framing support system for raised access floors at a major university in May 2025, illustrating how specialized framing solutions are being deployed to increase load capacity in high-traffic institutional settings. These examples are not isolated news items; they are indicators of how companies are competing on engineering depth, service accessibility, and application-specific performance.
Market Dynamics: Raw Material Economics and Regulatory Tailwinds
Infrastructure markets rarely move in isolation from input costs and standards evolution, and the raised access floor sector is no exception. Steel pricing, a fundamental driver of material economics for encapsulated and structural panel systems, has shown notable regional divergence. In May 2026, steel plate prices in Northeast Asia reached approximately USD 1.83 per kilogram, representing an 8.3 percent increase from the prior month, while North American prices stood at roughly USD 2.74 per kilogram, down 7.4 percent over the same period. This divergence matters because it influences regional manufacturing cost structures, export competitiveness, and the relative attractiveness of locally sourced versus imported components. Procurement leaders who monitor these shifts can time commitments more effectively, structure contracts with appropriate escalators, and evaluate supplier stability with greater foresight.
On the regulatory and standards front, recent updates to ASHRAE Standard 62.1 have explicitly referenced underfloor air distribution as a best-practice ventilation strategy, reinforcing the specification of raised access floors in new commercial construction projects. This kind of standards-level recognition does more than validate an existing technology; it shapes designer behavior, influences building certification pathways, and creates a durable preference signal for systems that support controlled air movement and energy-efficient ventilation. As sustainability mandates and indoor environmental quality requirements continue to tighten, specification advantages tied to recognized standards can meaningfully affect tender outcomes and architectural preference. Our report weaves these dynamics into a broader framework, helping readers understand not only what is happening, but why it matters for specification strategy, cost planning, and long-term asset performance.
Worldwide Reinforced Concrete Floor Market
Why This Research Is Positioned for 2026 Decision-Making
The 2026 planning cycle presents a convergence of operational pressures and strategic opportunities. Organizations are simultaneously managing data center expansion, office space realignment, and stricter environmental and safety expectations. In that environment, raised access flooring is no longer a commoditized line item; it is a design decision that affects airflow performance, cabling flexibility, maintenance access, load resilience, and future retrofit costs. Executives who treat it as a strategic variable rather than a passive procurement category will be better positioned to control total cost of ownership and reduce specification risk.
The full PW Consulting study is built to support that shift in mindset. It provides a clear analytical bridge from macro growth patterns to segment-level decision logic, from competitive positioning to supplier evaluation criteria, and from raw material volatility to contracting strategy. Readers will find frameworks that can be applied directly to capital planning, vendor shortlisting, specification development, and regional market assessment. The report is also structured to help leadership teams ask sharper questions: Which material and construction types align with anticipated load and environmental requirements? Where do integration benefits justify premium specifications? How do regional cost structures and standards environments shape supplier selection? What early indicators suggest shifts in competitive advantage or pricing power?
Accessing the Complete Intelligence
This article is intended as a strategic prelude rather than a standalone briefing. The growth trajectory, competitive behaviors, and market dynamics described here reflect the analytical foundation of our broader study, but the full report contains the detailed segmentation logic, company evaluations, specification guidance, and forward-looking scenario analysis needed to translate insight into action. For executives, project leaders, and investment planners navigating infrastructure decisions in 2026 and beyond, the complete PW Consulting Raised Access Floor Market research offers a structured, evidence-based pathway to more confident decision-making. We invite you to explore the full study for the comprehensive data, segmentation depth, and competitive intelligence that will support your next planning cycle.
For detailed analysis of this topic, please visit the official page: Raised Access Floor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Packaged Substation Market to Reach $338M by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
Executive Summary: Navigating the Packaged Substation Market Opportunity
The global energy landscape is undergoing a structural transformation. As electrification accelerates across industrial, infrastructure, and utility sectors, the demand for reliable, scalable, and rapidly deployable power distribution solutions has never been more critical. At PW Consulting, we recognize that the packaged substation market represents a pivotal intersection of grid modernization, smart infrastructure development, and operational efficiency. Our latest market research report on the Packaged Substation Market delivers a comprehensive, data-driven analysis designed to equip executive teams, investors, and strategic planners with the intelligence required to navigate this evolving landscape through 2032 and beyond.
This report is not merely a retrospective of historical performance. It is a forward-looking strategic instrument built on rigorous quantitative modeling, primary research validation, and deep competitive intelligence. Drawing on historical tracking from 2020 through the base year of 2025, and extending our forecasts across an eight-year period from 2026 to 2032, the study captures both the trajectory that has shaped the market and the inflection points that will define its next phase of growth. The overarching narrative is one of sustained expansion, where market valuation has demonstrated consistent upward momentum and is projected to reach new milestones as deployment cycles accelerate across multiple geographies and application verticals.
What sets this analysis apart is its emphasis on actionable strategic insight. We do not simply report numbers; we contextualize them within operational realities, regulatory shifts, supply chain dynamics, and technological adoption curves. The following sections outline the core components of the research, the competitive forces at play, the regulatory and macro-environmental drivers reshaping procurement and deployment strategies, and the strategic decisions that industry leaders must address in 2026 and beyond.
Market Trajectory and Structural Growth Dynamics
The packaged substation sector has transitioned from a niche, project-driven segment to a mainstream component of modern power distribution architecture. Historical tracking over the past half-decade reveals a market that has steadily expanded in both volume and strategic importance, reflecting broader electrification trends, grid reliability mandates, and the growing preference for prefabricated, modular deployment models over traditional on-site construction approaches. Our baseline assessments place the market at a substantial valuation in the base year, with continuous year-over-year progression underscoring the durability of underlying demand drivers.
The growth trajectory extends well beyond short-term cyclical recovery. Forecast modeling across the 2026–2032 horizon indicates a compound annual growth rate that reflects sustained momentum rather than a temporary surge. This expansion is not evenly distributed; it is shaped by differentiated adoption curves across regional markets, varying procurement timelines in industrial and infrastructure development programs, and the phased integration of new substation technologies into legacy grid architectures. Early forecast years already demonstrate incremental value gains, with growth compounding as manufacturing scale, supply chain localization, and deployment experience reduce lead times and improve project economics.
Packaged Substation Market
A critical element of the forecast methodology is its sensitivity to real-world constraints. Material cost fluctuations, labor availability, permitting frameworks, and the pace of renewable integration all exert measurable influence on deployment pacing and value realization. By incorporating these variables into scenario-based modeling, the report equips stakeholders with a realistic framework for capital allocation, inventory planning, and partnership positioning. The result is a market outlook that balances optimism with operational pragmatism, enabling decision-makers to plan for both baseline growth and upside opportunities tied to accelerated infrastructure programs and technology adoption.
Competitive Landscape and Strategic Positioning
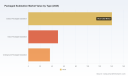
The competitive architecture of the packaged substation market is defined by a blend of global technology leaders, specialized electrical equipment manufacturers, and regional players with deep integration into local infrastructure and utility ecosystems. Market concentration metrics indicate a moderately fragmented environment, where the top three and top five players collectively hold meaningful but not dominating shares, leaving substantial room for differentiated positioning through technology, service models, and regional execution capability.
At the forefront of the market are organizations that have aligned their product portfolios with broader grid modernization priorities. ABB Ltd, headquartered in Zurich, has positioned itself around advanced compact and modular substation designs engineered for smart grid applications, high-reliability power distribution, and optimized operational performance across diverse electrical networks. Siemens Energy AG, based in Munich, has developed prefabricated substation solutions tailored for metro rail, EV charging, and renewable energy integration, aligning its offerings with mobility electrification and clean energy transitions. Schneider Electric SE, operating from Rueil-Malmaison, focuses on medium-voltage and low-voltage package substations designed for industrial and utility distribution, emphasizing integration, protection, and control architectures that support distributed energy resources.
Eaton Corporation, headquartered in Dublin, brings electrical distribution solutions that span package substations for industrial facilities and infrastructure, with an emphasis on operational resilience and system-level efficiency. In Asia, a strong cohort of manufacturers has expanded its footprint through integrated electrical solutions and scaled production. Larsen & Toubro Ltd, Kirloskar Electric Company Ltd, CG Power and Industrial Solutions Ltd, and C&S Electric Limited each contribute distinct capabilities across power distribution, industrial projects, and utility applications, reinforcing the region's role as both a major demand center and an increasingly competitive manufacturing base.
Global technology and heavy electrical players also maintain significant relevance. Hyundai Electric, Toshiba Corporation, and Hitachi Energy Ltd offer medium-voltage and low-voltage packaged substations, transmission and distribution equipment, and eco-efficient modular products that support renewable integration and higher-voltage applications. CHINT Group, based in Ningbo, has emerged with modular prefabricated substations featuring integrated components designed for rapid deployment and reliability, while Lucy Electric contributes switchgear and packaged substation solutions for power distribution networks.
Recent corporate and project activity illustrates how competitive differentiation is being executed in practice. In mid-2025, State Grid Anyang Power Supply Company commissioned Linzhou's first 110 kV mobile substation, a 50 MVA prefabricated unit installed within a ten-day window and deployed to supply industrial load alongside new-energy charging stations. That same year, CHINT Group introduced modular prefabricated substations emphasizing factory assembly, third-party type testing, and customized designs for extreme environments, followed by a later delivery of an integrated MV skid solution for the MASDAR Bukhara 250 MW Solar PV Plant in Uzbekistan. Hitachi Energy announced plans to deliver the world's first SF6-free 550 kV GIS, signaling a broader shift toward eco-efficient substation advancements, while Schneider Electric initiated localization of modular substation production in Asia to strengthen supply chain reliability and reduce lead times. These developments underscore a competitive environment in which speed, certification, environmental performance, and regional manufacturing capability are becoming decisive advantages.
Technological, Regulatory, and Macroeconomic Drivers
The packaged substation market does not evolve in isolation. Its growth profile is closely tied to a cluster of technological, regulatory, and macroeconomic forces that are reshaping how power is generated, transmitted, distributed, and consumed. Understanding these drivers is essential for mapping both near-term procurement behavior and longer-term portfolio strategy.
From a technological standpoint, modularization and factory-based fabrication have become central value propositions. Prefabricated, box-type, and skid-mounted substation designs offer measurable reductions in overall project cost and installation time compared with traditional brick-and-mortar construction approaches. Factory-built configurations also reduce on-site labor requirements by substantial margins through pre-testing and modular assembly, which is particularly relevant in markets experiencing skilled labor constraints or where rapid commissioning is required to support industrial expansion and infrastructure timelines. In parallel, the push toward eco-efficient substation technologies is accelerating, with high-voltage gas-insulated switchgear innovations and SF6-free agendas moving from research emphasis to commercial readiness.
Regulatory frameworks are exerting both standardizing and enabling effects. International standards such as IEC 62271-202:2022 define service conditions, rated characteristics, general structural requirements, and test methods for enclosed high-voltage prefabricated substations, providing a common technical baseline that supports cross-border procurement, interoperability, and quality assurance. On the policy front, European Commission guidance issued in mid-2025 emphasizes ensuring electricity grids are fit for the future, offering incentives for anticipatory investments in grid reinforcements and substation capacity. In the United States, executive action from mid-2025 prioritizes accelerating federal permitting for data center infrastructure, including substations and switchgear, directly linking substation deployment to the rapid expansion of digital infrastructure and computational load.
Emergency Mobile Substation Market
Material and labor economics further influence adoption decisions. The financial case for packaged substations is strengthened by demonstrable cost avoidance in site construction, shortened deployment schedules, and reduced exposure to on-site execution risk. These advantages are especially pronounced in industrial and infrastructure applications where downtime minimization, spatial constraints, and schedule certainty carry significant operational and financial implications. As a result, procurement strategies are increasingly shifting from lowest-unit-price evaluations toward total-lifecycle and total-project-value assessments, in which reliability, lead time, commissioning speed, and environmental compliance all contribute to the final decision calculus.
Core Report Framework and Strategic Deliverables
The Packaged Substation Market report is structured to translate complex market data into clear strategic guidance. It is designed for executives who require both breadth and precision without being overwhelmed by undifferentiated data tables. The report integrates historical analysis, forward-looking forecasts, segmentation insights, competitive profiling, and scenario-based interpretation into a cohesive analytical framework.
At the core of the study is a detailed market size and growth analysis anchored in historical performance from 2020 through 2025 and extended across the forecast period to 2032. Revenue trends are examined in a standardized global currency, enabling consistent comparison across periods and supporting financial planning, demand forecasting, and investment scenario modeling. The analysis captures how value has accumulated over time and how it is expected to compound as deployment activity broadens across regions and end-use environments.
Segmentation is treated as a strategic lens rather than a static taxonomy. The report examines the market across multiple dimensions that matter to procurement, manufacturing, and distribution planning. This includes an evaluation of deployment configurations and engineering forms, reflecting the differing requirements of outdoor, indoor, and underground applications; a geographic breakdown that illuminates relative market weight and growth pacing across major regions; and an application-level analysis that differentiates demand patterns across industrial environments, infrastructure programs, and power generation and utility operations. Each segmentation view is contextualized with demand drivers, adoption constraints, and strategic implications, allowing readers to identify where opportunity is concentrated and where execution risk may be elevated.
Competitive intelligence is developed through company-level profiling that goes beyond headline positioning. Profiles capture each organization's specific offering logic, technological emphasis, and application focus, providing a basis for benchmarking, partnership evaluation, and threat assessment. The report also incorporates recent developments that illustrate how companies are translating strategy into action through product launches, project deliveries, supply chain localization, and technology announcements. This dynamic view of competition helps stakeholders anticipate vendor behavior, pricing pressure, and differentiation trends rather than reacting to them after the fact.
Beyond structure and segmentation, the report includes practical tools for strategic planning. These encompass demand-side interpretation for capital and capacity planning, supply-side considerations for manufacturing and sourcing strategy, and environmental and regulatory mapping for compliance and ESG alignment. Scenario framing supports sensitivity analysis around lead times, cost structures, and deployment pacing, giving decision-makers a way to test assumptions before committing resources.
Strategic Implications for 2026 Decision-Making
As organizations enter 2026, the packaged substation market presents a set of strategic choices that extend well beyond traditional procurement considerations. The convergence of grid modernization mandates, renewable integration requirements, digital infrastructure expansion, and modular deployment economics is reshaping how value is created and captured across the value chain. Companies that approach this environment with a clear strategic posture will be better positioned to convert market growth into durable advantage.
One immediate implication concerns portfolio and capacity alignment. With growth forecasts indicating steady expansion over the forecast horizon, organizations must evaluate whether current production capacity, sourcing arrangements, and service capabilities are sufficient to meet accelerating demand without compromising reliability or margin. For manufacturers, this raises questions about factory throughput, component standardization, certification pathways, and regional localization. For distributors and system integrators, it raises questions about inventory positioning, lead-time management, and the ability to offer integrated solutions rather than standalone equipment.
A second implication relates to competitive differentiation. In a market where top-tier concentration remains moderate, differentiation increasingly depends on technology integration, deployment speed, environmental performance, and regional execution quality. Firms that can demonstrate credible advantages in factory-based testing, modular configuration, rapid commissioning, and eco-efficient design are better placed to compete on total project value rather than price alone. Recent moves toward localized production and advanced substation technologies illustrate how manufacturers are attempting to secure both cost and credibility advantages simultaneously.
A third implication centers on demand-side planning. Industrial operators, infrastructure developers, and utility organizations must assess how substation deployment timing interacts with broader project schedules, permitting pathways, and load growth expectations. The availability of prefabricated options that reduce on-site labor, accelerate installation, and align with recognized international standards can materially affect project feasibility and risk profiles. Decision-makers should therefore evaluate substation sourcing not merely as an equipment purchase but as a schedule, reliability, and compliance decision that influences downstream operational outcomes.
Finally, regulatory and environmental trends warrant proactive strategy development. Standards development, incentives for grid reinforcement, permitting acceleration for critical infrastructure, and the broader transition toward lower-impact substation technologies are all shaping future procurement requirements. Organizations that integrate these considerations into product roadmaps, sourcing strategies, and project planning will be better prepared to navigate compliance expectations and capture incentives tied to anticipatory investment.
Conclusion and Call to Action
The packaged substation market is at a point where structural demand, technological maturation, and policy support are aligning to sustain a multi-year growth trajectory. Historical performance establishes a credible foundation, and forward-looking modeling suggests that the momentum will continue as deployment models become more efficient, regional manufacturing expands, and grid modernization priorities intensify. Yet the strategic value of this market lies not only in its size and growth rate but in the way it intersects with broader energy, industrial, and infrastructure decisions.
PW Consulting's Packaged Substation Market report is designed to help leaders navigate that complexity with confidence. It combines rigorous quantitative analysis with practical competitive and regulatory context, enabling organizations to identify where to invest, how to differentiate, and which risks to manage proactively. The full report provides detailed segmentation interpretation, competitive benchmarking, scenario analysis, and development tracking that go beyond the executive overview presented here.
For executives, investors, and strategy teams seeking a complete view of market sizing, segmentation dynamics, competitive positioning, and forward-looking implications through 2032, we invite you to access the full research on our website. The complete intelligence package is structured to support capital planning, market entry evaluation, partnership strategy, and operational decision-making with the depth and precision required for high-stakes 2026 planning.
For detailed analysis of this topic, please visit the official page: Packaged Substation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Incident Response Market Hits $35.2B in 2025, Poised for 18.52% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the New Reality: Strategic Imperatives in the 2026 Incident Response Landscape
The cybersecurity landscape has undergone a fundamental transformation. No longer viewed merely as a technical contingency, incident response (IR) has emerged as a core business continuity function and a critical component of enterprise risk management. As organizations grapple with increasingly sophisticated attack vectors, regulatory pressures, and the operational complexities of hybrid work environments, the ability to detect, contain, and recover from security incidents with speed and precision has become a defining competitive advantage.
This article serves as an introduction to the latest market research publication from PW Consulting, designed to equip executive leaders, security architects, and investment strategists with the comprehensive intelligence needed to navigate the Incident Response market through 2032. The following analysis highlights the market trajectory, structural dynamics, and strategic considerations that will shape decision-making in 2026 and beyond. Readers seeking the full granular segmentation, regional revenue breakdowns, competitive benchmarking matrices, and actionable investment roadmaps are invited to access the complete report through our dedicated source page.
Worldwide Information Security Market
Market Trajectory: A Sector Defined by Accelerated Expansion
The Incident Response market has demonstrated remarkable resilience and growth over the past half-decade, transitioning from a reactive cost center to a proactive strategic investment. Historical data from 2020 through 2025 illustrates a consistent upward trajectory, with the overall market expanding from approximately 22.41 billion USD in 2020 to 35.2 billion USD by 2025. This growth reflects a broader industry recognition that traditional perimeter defenses are insufficient against modern threat actors, driving enterprises to allocate significant capital toward integrated response capabilities.
Projecting forward into the forecast period spanning 2026 to 2032, the market is poised for sustained momentum. The sector is expected to reach 40.7 billion USD in 2026, with growth accelerating steadily to approximately 50.71 billion USD by 2027, 59.83 billion USD by 2028, and continuing through to an estimated 116.17 billion USD by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of 18.52 percent, signaling one of the most robust growth profiles within the broader cybersecurity ecosystem.
Such momentum is not merely a function of increased spend; it reflects a structural shift in how organizations value resilience. The compounding effect of this growth trajectory suggests that incident response will increasingly intersect with board-level discussions around digital transformation, insurance underwriting, and regulatory compliance. Decision-makers operating without a clear view of this trajectory risk misallocating resources or falling behind competitors who are already embedding IR capabilities into their enterprise architecture.
Structural Dynamics: What Is Driving Demand in 2026
Regulatory and Compliance Imperatives
The regulatory environment has become a primary catalyst for incident response adoption. In May 2026, the Cybersecurity and Infrastructure Security Agency (CISA) rescheduled virtual town hall meetings regarding the proposed rule for the Cyber Incident Reporting for Critical Infrastructure Act of 2022, with proceedings set to begin on June 15, 2026. The proposed rule mandates that critical infrastructure organizations report cyber incidents to CISA within 72 hours and ransom payments within 24 hours. These tightening timelines create an acute operational requirement for organizations to have established response protocols, forensic capabilities, and communication frameworks ready before an incident occurs, rather than improvising under pressure.
For enterprises across critical sectors, compliance is no longer a checkbox exercise. It demands documented playbooks, trained response teams, and integrated tooling that can capture evidence and execute containment in real time. Organizations that treat IR as a compliance function alone will find themselves exposed; those that treat it as a strategic capability will gain both regulatory alignment and operational resilience.
The Multi-Vector Threat Reality
Threat actor methodology has evolved significantly. According to the 2026 Unit 42 Global Incident Response Report from Palo Alto Networks, which analyzed over 750 major cyber incidents investigated in 2025, 87 percent of intrusions involved activity across multiple attack surfaces. This finding underscores a critical reality: organizations can no longer afford siloed security operations where endpoint, network, cloud, and identity domains operate in isolation.
The implication for the incident response market is profound. Response capabilities must be orchestrated across the entire attack surface, integrating telemetry, automation, and human expertise into a unified workflow. This multi-vector reality is pushing enterprises toward managed detection and response arrangements, platform-based analytics, and retainer-based professional services that can scale during active incidents. The market is responding accordingly, with growth distributed across containment, mitigation, remediation, recovery, digital forensics, and analytics functions.
The Preparedness Gap
Despite increased investment, a troubling disconnect persists between planning and operational readiness. Sygnia's 2026 CISO Survey, titled The State of Incident Response Readiness, highlighted that many organizations maintain documented incident response plans that do not translate into effective execution during real-world events. This gap between theoretical preparedness and practical capability represents both a risk and an opportunity. It creates demand for services that bridge the divide: tabletop exercises, retainer engagements, rapid deployment forensics teams, and technology that reduces the cognitive load on responders during high-pressure situations.
Market Scope and Segmentation: A High-Level View
The Incident Response market encompasses a diverse set of services and solutions, reflecting the multifaceted nature of modern threat response. At a high level, the market can be understood through several structural dimensions that collectively define how organizations procure and consume IR capabilities.
- Response and Recovery Functions: The market is anchored by containment and mitigation capabilities, complemented by remediation and recovery services that restore operational integrity after an incident. Managed detection and response arrangements have gained significant traction, offering organizations continuous monitoring and rapid intervention without the need to build fully in-house capabilities. Digital forensics and analytics provide the evidentiary and investigative backbone necessary for both internal decision-making and external reporting obligations.
- Application Across Sectors: Incident response demand is broad-based, spanning highly regulated industries such as financial services and government and defense organizations, as well as technology and telecommunications providers, energy and utilities operators, and a range of other sectors. Each vertical brings distinct compliance requirements, threat profiles, and operational constraints that shape how response capabilities are deployed.
- Geographic Distribution: Demand is distributed across major global regions, with North America representing a substantial share, followed by Europe and Asia Pacific. Latin America and the Middle East and Africa represent emerging growth zones where regulatory maturation and threat landscape evolution are driving incremental investment.
The complete report provides detailed revenue distributions across each segmentation dimension, including regional breakdowns, service-type allocations, and vertical-specific demand patterns. These granular insights are essential for organizations seeking to benchmark their own positioning, identify underserved niches, or evaluate partnership opportunities within specific market pockets.
Competitive Landscape: Leaders, Specialists, and Emerging Models
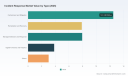
The Incident Response market is characterized by a mix of platform-centric technology vendors, professional services firms, and specialized response boutiques. Market concentration data indicates that the top three competitors command approximately 48 percent of total market revenue, while the top five collectively represent around 68 percent. This concentration reflects the dominance of large, integrated players who offer end-to-end capabilities spanning detection, response, forensics, and managed services. However, significant opportunity remains for specialized firms that deliver deep expertise, retainer-based engagements, and sector-specific knowledge.
Platform Leaders and Integrated Ecosystems
Several prominent organizations define the current competitive landscape. CrowdStrike, headquartered in San Francisco, offers the Falcon platform with managed detection and response capabilities, integrating advanced incident response functions within a unified endpoint and cloud security ecosystem. SentinelOne, based in Mountain View, provides the Singularity Platform and Vigilance Respond services, leveraging AI-powered endpoint detection and response to support incident response workflows. Palo Alto Networks, located in Santa Clara, delivers Unit 42 global incident response services alongside Cortex XDR and Prisma Access solutions, combining threat intelligence with operational response capabilities.
IBM, headquartered in Armonk, provides IBM Security QRadar alongside professional incident response services, offering enterprises a combination of SIEM-driven analytics and expert intervention. Cisco Systems, based in San Jose, delivers incident response capabilities through the Cisco SecureX platform, emphasizing integration across network, endpoint, and cloud security domains. Rapid7, located in Boston, offers InsightIDR and automated incident response automation tools, focusing on reducing mean time to respond through orchestrated workflows. Sophos, also headquartered in Boston, provides MDR and incident response through its Sophos MDR and EDR solutions, targeting mid-market and enterprise customers with managed security offerings.
Specialized Services and Retainer-Based Models
Alongside platform providers, a cohort of professional services and specialized response firms plays a critical role in the ecosystem. NCC Group, based in London, offers professional incident response retainer and investigation services, providing clients with pre-arranged access to expert teams during active incidents. Kroll, headquartered in New York, delivers comprehensive digital forensics and global incident response recovery services, serving organizations that require deep investigative capabilities and cross-border response support. Beazley, also based in London, delivers cyber incident response services as part of broader cyber and data resilience offerings, often intersecting with insurance and risk transfer frameworks.
Optiv Security, located in Reston, offers managed security services and incident response retainer programs, helping organizations bridge the gap between technology deployment and operational execution. Check Point Software Technologies, headquartered in Tel Aviv, provides incident response through its solution portfolio and professional services, supporting organizations that seek integrated threat prevention alongside response capabilities.
Recent Market Movements and Strategic Shifts
The competitive landscape continues to evolve through partnerships, publications, and market recognition. In March 2026, LevelBlue announced an expanded global strategic partnership with SentinelOne to deliver AI-powered managed security operations and incident response, signaling a trend toward combining managed service delivery with advanced platform capabilities. In April 2026, Palo Alto Networks published the 2026 Unit 42 Global Incident Response Report, providing detailed insights from over 750 major cyber incidents investigated in 2025 and reinforcing the importance of cross-surface visibility.
Sygnia made notable strides in April 2026, releasing the 2026 CISO Survey that highlighted gaps between incident response planning and operational readiness, while also being named a Representative Vendor in the 2026 Gartner Market Guide for Cybersecurity Incident Response Retainer Services. These developments underscore a market that is maturing in its understanding of what effective response requires: not just technology, but validated processes, trained personnel, and pre-established relationships that can be activated at a moment's notice.
Strategic Considerations for 2026 Decision-Makers
As organizations evaluate their incident response strategy for 2026 and beyond, several strategic considerations merit focused attention. These considerations extend beyond technology procurement to encompass organizational design, vendor selection, regulatory alignment, and investment prioritization.
Build, Buy, or Partner: Defining the Operating Model
One of the most consequential decisions facing enterprises is the structure of their incident response capability. Some organizations pursue a fully in-house model, building internal teams, acquiring platform tools, and developing internal playbooks. Others rely heavily on managed detection and response providers or professional services retainers. The optimal approach is rarely binary. Most mature organizations adopt a hybrid model: maintaining internal oversight, governance, and critical decision-making authority while leveraging external partners for surge capacity, specialized forensics, and 24/7 monitoring coverage.
Determining the right mix requires a clear understanding of internal maturity, risk tolerance, budgetary constraints, and the specific threat profile of the organization. The complete report provides frameworks for evaluating these trade-offs, including comparative analyses of service models, cost structures, and performance outcomes across different operating approaches.
Incident Response Market
Integrating Response with Broader Security Architecture
Incident response cannot function effectively in isolation. It must be integrated with preventive controls, threat intelligence, identity management, and data protection programs. Organizations that treat response as a standalone function often encounter friction during incidents: telemetry is siloed, containment actions are delayed by cross-team dependencies, and recovery processes conflict with business continuity requirements.
A more effective approach embeds response capabilities within a layered security architecture, ensuring that detection signals flow seamlessly into response workflows, that containment actions are coordinated across endpoint, network, and cloud domains, and that recovery processes are aligned with organizational resilience objectives. This integration also supports compliance objectives, particularly as reporting timelines tighten under emerging regulatory frameworks.
The Role of Automation and AI in Response Operations
Automation and artificial intelligence are increasingly central to incident response effectiveness. AI-powered endpoint detection, automated triage, and orchestrated response playbooks can significantly reduce the time between detection and containment, which is critical given the speed at which modern threats propagate across multiple attack surfaces. However, technology alone is insufficient. Automation must be paired with clear escalation paths, human judgment for complex decision-making, and regular testing to ensure that automated actions produce the intended outcomes.
The market is seeing growing demand for solutions that combine AI-driven detection with human-led investigation and response, particularly in scenarios that require contextual understanding, legal considerations, or coordination with law enforcement and regulators. Organizations evaluating technology investments should prioritize platforms that support this human-machine collaboration rather than treating automation as a wholesale replacement for expert response.
Preparedness as a Continuous Discipline
The gap between planning and operational readiness identified in recent industry surveys points to a broader truth: incident response is not a one-time project but a continuous discipline. Organizations that treat response readiness as a static deliverable, such as a documented plan filed away after an initial assessment, will find themselves ill-prepared when an actual incident occurs. Effective readiness requires regular testing through tabletop exercises and simulated incidents, ongoing training for response teams, periodic review of playbooks against evolving threat intelligence, and established relationships with external responders that can be activated under pressure.
For organizations operating in regulated sectors, readiness also encompasses documentation, evidence preservation, and reporting workflows that align with legal and regulatory obligations. Treating these elements as integral components of response capability, rather than afterthoughts, will differentiate resilient organizations from those that struggle during incidents.
Why This Research Matters: Turning Intelligence into Action
Market research in the incident response space must go beyond high-level growth figures and surface-level trend summaries. Decision-makers need actionable intelligence that connects market dynamics to concrete strategic choices: where to invest, how to structure partnerships, which capabilities to prioritize, and how to position an organization for both risk mitigation and competitive advantage.
The full PW Consulting Incident Response Market report delivers this depth. It provides comprehensive segmentation analysis across regions, service types, and application verticals, enabling readers to benchmark their own market positioning and identify growth opportunities. It offers detailed competitive profiling of key market participants, including technology capabilities, service offerings, recent strategic moves, and market share dynamics. It examines regulatory developments, threat landscape evolution, and operational challenges that are shaping demand, with a particular focus on implications for 2026 and the forecast period through 2032.
For enterprise leaders, the report serves as a decision-support tool for aligning security investments with business objectives. For investors and market analysts, it provides a data-rich view of market structure, growth drivers, and competitive positioning. For vendors and service providers, it offers insights into demand patterns, customer priorities, and emerging opportunities across different segments of the incident response ecosystem.
Accessing the Complete Intelligence
This article has provided a strategic overview of the Incident Response market, highlighting growth trajectory, structural dynamics, competitive landscape, and key considerations for 2026 decision-making. However, the full scope of intelligence available in the complete PW Consulting report extends well beyond this summary. Detailed revenue breakdowns by region, type, and application; competitive benchmarking across all profiled companies; granular analysis of regulatory impacts and threat trends; and actionable recommendations for investment and operational planning are all contained within the full publication.
To access the complete dataset, competitive matrices, segmentation deep-dives, and strategic frameworks, visit the dedicated source page for the Incident Response Market research. The full report is designed to support executive briefings, investment committee discussions, vendor evaluation processes, and long-term strategic planning, providing the comprehensive intelligence needed to navigate a market defined by rapid growth, evolving threats, and increasing regulatory complexity.
The incident response landscape will continue to evolve at a pace that demands informed, proactive decision-making. Organizations that invest in understanding the market's structure, dynamics, and trajectory will be best positioned to build resilience, meet compliance obligations, and turn incident response from a reactive necessity into a strategic capability. The complete PW Consulting report provides the foundation for that understanding.
For detailed analysis of this topic, please visit the official page: Incident Response Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The AR/VR market in China has demonstrated strong revenue expansion since 2020, with an estimated market size of USD 2,300 million in 2025 and a projected CAGR of 21% through 2035. The revenue chart indicates a steady upward trajectory, driven by technological advances, expanding consumer usage, and significant enterprise adoption across industries. By 2035, the market is anticipated to reach USD 15,600 million, highlighting the long-term investment potential and transformative impact of AR/VR technologies in the Chinese landscape.
Read More - https://bussinessinsights.com/research-report/china-augmented-and-virtual-reality-market
The application landscape in 2025 is led by the gaming segment, which holds a commanding 41% market share. Healthcare follows at 21%, reflecting strong adoption for training, surgery, and diagnostics. Education is the third-largest application, making up 18% of the market, driven by the increasing use of AR/VR tools in classrooms and training modules. Retail, manufacturing, and automotive collectively make up the remainder, each showing steady gains but not surpassing the top three applications. This distribution confirms the dominance of entertainment and essential services in driving AR/VR technology adoption across China.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-augmented-and-virtual-reality-market
Frequently Asked Questions
Who are the key players in China Augmented and Virtual Reality Market industry?
The top five players in China’s AR and VR market are Huawei, Xiaomi, Nreal, DPVR, and Tencent. Huawei leads in hardware innovation, Xiaomi focuses on affordable smart devices, Nreal is known for lightweight AR glasses, DPVR specializes in immersive VR headsets, and Tencent advances gaming and social AR/VR platforms.
What is the China Augmented and Virtual Reality Market growth?
The China AR and VR market is experiencing rapid growth, with double-digit annual expansion. In 2023, the market saw significant investment and soaring consumer adoption, especially with companies like Nreal launching mass-market AR glasses and Huawei introducing new VR devices, driving strong year-on-year market growth.
Which segment accounted for the largest China Augmented and Virtual Reality Market share?
Gaming and entertainment applications hold the largest market share in China’s AR and VR market. Popular platforms like Tencent VR and NetEase have witnessed widespread adoption as consumers increasingly use AR/VR for immersive gaming, interactive live streaming, and virtual social experiences, outpacing education and industrial applications.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
China's XR market revenue demonstrates a strong upward trajectory between 2020 and 2035. The sector, valued at USD 7,200 Million in 2020, is projected to reach USD 46,800 Million by 2035. Growth accelerates rapidly post-2025, when 5G expansion and large-scale adoption across multiple sectors catalyze market penetration. Leading tech players' heavy investment in product development and XR content ecosystem further sustains the revenue surge, positioning China as a global powerhouse in the extended reality arena.
Read More - https://bussinessinsights.com/research-report/china-extended-reality-market
Gaming & entertainment remains the core application for XR in China, making up the largest market share in 2025, given the strong e-sports ecosystem and rising demand for immersive content. Healthcare follows, leveraging XR for advanced diagnostics and medical training. Education is a fast-growing sector, with widespread use of AR/VR in remote learning and interactive classrooms. Retail, industrial manufacturing, and automotive collectively form a substantial segment, adopting XR for product visualization, process optimization, and in-vehicle infotainment. This diverse application landscape highlights XR's transition from gaming-centric to a multi-sectoral tool driving digital transformation.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-extended-reality-market
Frequently Asked Questions
Who are the key players in China Extended Reality Market industry?
Key players in the China Extended Reality market include Tencent, Alibaba Group, HTC Corporation, Huawei Technologies, and Baidu. These companies invest heavily in XR research and development, offering a range of products from VR headsets to AR platforms and content ecosystems, thus driving innovation and adoption across industries.
What is the China Extended Reality Market growth?
The China Extended Reality market has witnessed robust growth, with market size expected to surpass USD 14 billion by 2025. Recent growth factors include Alibaba’s investments in AR-powered online retail experiences, which have accelerated adoption and contributed to the market’s double-digit compound annual growth rate.
Which segment accounted for the largest China Extended Reality Market share?
The gaming and entertainment segment holds the largest market share in China’s Extended Reality market. Driven by immersive applications and consumer demand, companies like Tencent have launched VR and AR-enabled games, making this segment the primary revenue generator among all XR applications.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Commercial Ice Machine Market to Hit $332M by 2032 on 7.45% CAGR
By PW Consulting, 2026-09-16
Beyond Thermal Output: Strategic Intelligence for the 2026 Commercial Ice Machine Market
The commercial ice machine sector has quietly transitioned from a commoditized utility play to a capital-intensive, regulation-sensitive infrastructure decision. Across foodservice, healthcare, and retail environments, ice systems are no longer evaluated solely on daily production capacity. Facility managers, procurement officers, and capital equipment planners now weigh energy compliance, refrigerant transitions, sanitation certification, and total cost of ownership against volatile supply chain conditions. As we move deeper into the 2026–2032 forecast window, the organizations that will secure margin protection and operational continuity are those making their ice equipment decisions with granular, forward-looking intelligence rather than historical benchmarks.
PW Consulting’s newly released Commercial Ice Machine Market research is structured as a decision-grade intelligence asset. It moves past surface-level market commentary to deliver executable procurement roadmaps, competitive positioning frameworks, and regulatory readiness checklists. The following overview outlines what the study covers, why the 2026 decision window is structurally distinct, and how leadership teams can translate market velocity into risk-adjusted capex and opex strategy. The core segment valuations, regional breakouts, and proprietary forecasting layers are reserved for the full report, where the complete analytical architecture can be navigated without dilution.
A Market in Structural Expansion: Why 2026 Is a Pivotal Inflection Point
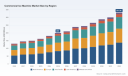
The commercial ice machine market has demonstrated consistent expansion over the past half-decade, with revenue compounding from approximately USD 130.5 million in 2020 to an estimated USD 200.0 million in 2025. The trajectory reflects more than post-pandemic normalization. It signals a durable alignment between hospitality recovery, healthcare sanitation mandates, retail cold-chain sophistication, and industrial cold processing requirements. Looking forward, the forecast period extends through 2032, with market revenue projected to surpass the USD 330 million threshold by the close of the outlook window. This expansion is supported by a CAGR of 7.45 percent, a pace that places ice equipment alongside other commercial kitchen and facility infrastructure categories experiencing sustained institutional demand.
Commercial Ice Machine Market
Ice Cream Machine Market
For enterprise planners, a double-digit compound growth trajectory carries a specific strategic implication: delay is expensive. Capacities installed in 2026 will remain in operation well into the next decade, and the operating environment those machines face will be shaped by tightening energy expectations, evolving refrigerant policy, and heightened sanitation enforcement. The report uses the full 2020–2032 timeline to frame not just where the market has been, but which cohorts of demand are structurally permanent versus which are cyclical. Decision-makers are given a calibrated view of how near-term procurement cycles interact with long-lived asset exposure, enabling more disciplined budgeting across multi-year capex programs.
Competitive Architecture: Concentration, Positioning, and the Strategic Playbook
The commercial ice equipment landscape is not a fragmented free-for-all. Market concentration metrics underscore a consolidated environment in which a relatively small group of manufacturers commands the majority of share. The report examines this structure through the lens of competitive moats, channel leverage, and innovation cadence rather than simple shipment rankings. With CR3 levels at 65.0 percent and CR5 levels at 85.0 percent, competitive dynamics are defined by brand trust in sanitation-critical environments, dealer and service network density, and the ability to deliver certified, energy-optimized platforms across multiple ice formats.
Several established players anchor this ecosystem. Hoshizaki America, headquartered in Fayetteville, Georgia, manufactures commercial ice machines across flaker, nugget, and cube configurations, with a consistent emphasis on NSF-listed models and energy-efficient options. The company’s recent 2026 product calendar reinforces this positioning: an updated commercial product brochure released in April highlighted improved energy efficiency and hygiene options across 2026 model years, followed in May by an expanded cube ice portfolio under the new IM CUBE series, which incorporates UV sanitization alongside energy and water savings. Such moves illustrate a broader industry pattern in which premium differentiation is increasingly tied to integrated sanitation and resource efficiency rather than production volume alone.
Manitowoc Ice, based in Manitowoc, Wisconsin, focuses on engineered commercial ice machines for foodservice, hospital environments, and high-volume applications, supported by dealer networks that extend service reach and installation fidelity. In May 2026, the company continued its refrigerant transition toward R290 while advancing supply chain optimizations designed to enhance commercial ice machine performance. This trajectory reflects the operational reality that after-sales reliability, parts availability, and service responsiveness often matter as much as the hardware specification itself.
Scotsman Ice Systems, operating from South Carolina, is recognized globally as a leading manufacturer of commercial ice machines, offering modular and countertop models with a clear focus on foodservice reliability. Ice-O-Matic, also U.S.-based, specializes in commercial ice machines and dispensers built around modular designs tailored to restaurants and institutions. Grant Ice Systems manufactures industrial and commercial units, including nugget and flake types designed for high-capacity requirements. Follett Ice delivers commercial ice machines and dispensers with integrated technology aimed at foodservice operations, while Maxx Ice offers self-contained and premium indoor/outdoor commercial ice machines, several with Energy Star listings. Summit Appliance produces commercial ice makers certified to NSF-12, with production ranges spanning from 55 lb to 210 lb. Outside the U.S. incumbent core, Naixer Ice, based in China, serves as a global supplier of commercial ice makers with NSF certification and product catalogs designed for international distribution. Morris Thermal rounds out the competitive field by producing custom industrial ice makers with Tube-Cube and Nugget technologies suited to food processing and high-volume use.
The report does not stop at company profiles. It maps how these players compete across product families, service architectures, and compliance readiness, and it highlights where concentration creates pricing discipline versus where niche innovation can still open addressable pockets. This structure is especially valuable for procurement teams evaluating not only unit cost but the strategic risk of vendor lock-in, parts dependency, and long-term service support across dispersed locations.
Regulatory Dynamics, Certification Realities, and the 2026 Compliance Landscape
One of the most consequential layers of the 2026 decision environment is regulatory and certification pressure. Commercial ice machines sit at the intersection of energy policy, refrigerant mandates, and food safety standards, making compliance a design constraint rather than an optional add-on. As of May 2026, commercial ice machines must meet ENERGY STAR performance specifications or equivalent performance thresholds if not labeled as such. In parallel, Florida Water Star has required these standards for appliances, tying water and energy efficiency into broader building and equipment approval frameworks. For multi-site operators with exposure to these jurisdictions, the implication is straightforward: efficiency performance is becoming a purchasing prerequisite, not merely a sustainability talking point.
Refrigerant transitions are equally influential. In November 2025, Hoshizaki transitioned 66 of its ice maker models to R-600a and R-290 refrigerants, achieving over a 99 percent reduction in global warming potential. This shift reflects a wider industry migration toward lower-GWP alternatives and demonstrates how OEMs are redesigning platforms to align with both federal direction and customer expectations around environmental footprint. The EPA SNAP rule further shapes the market by allowing specific refrigerants, including HFC-32, R-454A, R-454B, R-454C, R-455A, R-457A, and R-516A, for use in new commercial ice machines under defined conditions. Compliance with these pathways requires vendors and buyers alike to track approval conditions and equipment eligibility, especially as state-level timelines and federal requirements interact.
Certifying bodies add another layer of non-negotiable scrutiny. NSF/ANSI Standard 12 certification is mandatory for all U.S. commercial ice machines sold in foodservice to ensure sanitation and food safety compliance. This requirement creates a structural barrier to entry for unverified equipment and makes certification status a baseline procurement filter. On the regulatory timing side, the Washington Department of Ecology issued an interpretive statement in December 2024 delaying the HFC prohibition effective date for automatic commercial ice machines to align with federal 2026–2027 requirements. The interplay of federal and state regulatory calendars means that what appears to be a single compliance decision often requires multi-jurisdiction validation. The report organizes these dynamics into actionable categories so that facility and procurement leaders can map equipment selection to the specific standards that govern their locations and use cases.
What the Report Delivers: An Operational Intelligence Framework
PW Consulting’s Commercial Ice Machine Market study is designed for teams that need more than directional market commentary. The deliverable combines macroeconomic trajectory, product-form dynamics, application-driven demand behavior, regional performance context, and competitive profiling into a coherent planning tool. The research architecture is built around several practical components.
- Historical baseline and forecast modeling spanning 2020 through 2032, providing a continuous revenue view that supports budgeting, capacity planning, and trend validation across multiple forecast vintages.
- Product-form analysis across cube, flake, nugget, and other configurations, examining how production footprint, ice characteristics, and operational use cases drive adoption across foodservice, healthcare, retail, and industrial settings.
- Application-based demand mapping that distinguishes between high-volume commercial foodservice requirements, healthcare sanitation-sensitive environments, retail point-of-use needs, and broader institutional or industrial deployments.
- Regional context that situates market performance across major geographies without forcing simplistic generalizations, helping multinational operators and domestic chains calibrate rollout priorities based on infrastructure maturity, regulatory exposure, and demand density.
- Competitive profiling of leading manufacturers and emerging suppliers, including product positioning, certification posture, and recent innovation or catalog activity, enabling side-by-side evaluation of vendor options and service implications.
- Regulatory and certification tracking that consolidates ENERGY STAR expectations, SNAP-listed refrigerant pathways, state-level interpretive actions, and NSF/ANSI Standard 12 requirements into a usable compliance overview for procurement teams.
- Decision-support frameworks that translate market information into purchasing criteria, replacement-cycle logic, and vendor-selection checklists aligned to operational continuity and total cost of ownership.
This structure is intentionally practical. It is not a static market snapshot but a tool that supports recurring decisions: whether to replace aging units now or stage the transition; how to weigh efficiency-certified platforms against upfront cost; which product formats align with specific site profiles; and how to interpret competitive moves such as refrigerant migrations, UV sanitization integration, and modular design refinements. By tying these considerations to a single research baseline, the report reduces the risk of fragmented decision-making across departments that often evaluate equipment from different angles.
Why the Full Intelligence Set Matters for 2026 Procurement and Planning
Strategic procurement in a market growing at a mid-to-high single-digit CAGR is not simply a matter of identifying the cheapest compliant unit. The real decision space includes service network coverage, spare-parts availability, energy-cost exposure over the machine’s service life, regulatory drift, and the operational consequences of choosing a platform that may not align with future certification or efficiency expectations. In a market where a concentrated group of manufacturers controls a substantial share, vendor selection also carries concentration risk and dependency considerations that should be weighed explicitly rather than inferred from spec sheets alone.
The report is built to support that level of evaluation. It gives teams a structured way to interpret market momentum, segment behavior, competitive responses, and compliance shifts without relying on fragmented sources or outdated assumptions. The full study preserves the detailed segment valuations, regional performance context, application-level demand breakdowns, and forward forecasting layers that enable scenario-based planning. Those components are essential for organizations that need to justify capex against auditable market evidence, compare vendors on a consistent basis, and anticipate how regulation and technology will reshape operating economics through 2032.
Navigating the Market with Proven Strategic Intelligence
The commercial ice machine market in 2026 rewards teams that plan with precision. Growth is real, concentration is high, and the regulatory environment is actively reshaping product design and procurement criteria. In that context, the difference between reactive replacement and strategic deployment is information quality. PW Consulting’s Commercial Ice Machine Market research is intended to provide that information in a form that procurement, operations, and finance leaders can use immediately.
The complete report includes the full market sizing arc, segment-level insight, regional performance context, competitive analysis, and the compliance and certification frameworks that define viable equipment selection in the current period. For organizations preparing multi-site deployments, lifecycle replacements, or technology refresh cycles, the full intelligence set offers the depth required to make decisions with confidence rather than approximation. The core data, scenario-ready forecasts, and category-specific evaluations are available through the complete study, where the analytical detail and proprietary market architecture can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Commercial Ice Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Market revenue is projected to grow from USD 275 Million in 2020 to USD 634 Million by 2035, signifying robust adoption and technological progress. Growth is underpinned by rapid industrial automation, increased safety requirements, and product innovations. Mid-decade projections show steady compound annual growth rates, as leading industrial players invest in equipment upgrades and China maintains its manufacturing leadership position. The market's upward momentum is sustained by both regulatory factors and the ongoing expansion of automation across sectors, reinforcing the critical role of safety light curtains.
Read More - https://bussinessinsights.com/research-report/china-safety-light-curtain-market
Press machines lead application segments for safety light curtains in China, comprising 40% of the market due to high-risk and high-volume metalworking operations in the country. Material handling follows closely with 25%, supporting logistics automation. Robotics and packaging applications are growing segments, driven by increased automation and e-commerce fulfillment demand. The expanding use in assembly lines and diverse manufacturing processes underlines the importance of tailored safety solutions aligned with varied industrial needs in China, emphasizing flexibility and compliance with evolving standards.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-safety-light-curtain-market
Frequently Asked Questions
Who are the key players in China Safety Light Curtain Market industry?
The top five players in the China Safety Light Curtain Market include Omron Corporation, SICK AG, Keyence Corporation, Panasonic Corporation, and Schneider Electric. These companies are known for innovative product development, extensive distribution networks, and strong after-sales support, helping drive market penetration and technological advancements across manufacturing and automation sectors.
What is the China Safety Light Curtain Market growth?
The China Safety Light Curtain Market has experienced notable growth in recent years, primarily driven by increasing industrial automation and safety regulations. For instance, Omron reported increased sales in the safety component segment in 2023, highlighting the rapid adoption of automation solutions among key Chinese industries.
Which segment accounted for the largest China Safety Light Curtain Market share?
The largest market share is held by the manufacturing and automotive application segment. These sectors rely extensively on safety light curtains to ensure the safety of personnel working alongside automated machinery, thus driving substantial adoption across automotive assembly lines and component manufacturing plants in China.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Industrial Shredder Market Hits $1.27B in 2025, Projected to Reach $1.77B by 2032 at 4.9% CAGR
By PW Consulting, 2026-09-16
Industrial Shredder Market Outlook 2026: Strategic Intelligence for Capital Allocation and Competitive Positioning
Executive Summary
The industrial shredder sector is entering a phase of disciplined, technology-led expansion. As organizations across recycling, waste management, and secure destruction verticals navigate tightening compliance mandates, input cost volatility, and accelerating decarbonization requirements, capital deployment decisions require more than top-line growth projections. They demand granular visibility into demand drivers, equipment segmentation, regional adoption patterns, and the competitive maneuvers shaping pricing and innovation velocity. Our latest Industrial Shredder Market study delivers that visibility, mapping the trajectory from 2020 through 2032 with a forecasting architecture calibrated to the operational realities of procurement cycles, plant retrofits, and OEM capacity planning.
For decision-makers operating on a 2026 timeline, this research functions as a strategic filter. It separates structural growth from cyclical noise, identifies where margin expansion is realistically achievable, and highlights the operational and regulatory variables that will determine whether a capital investment translates into long-term competitive advantage. Below, we outline the scope of the analysis, the market architecture it reveals, and the actionable intelligence it provides for enterprise strategy teams, equipment procurement leaders, and investment stakeholders.
Market Trajectory: A Multi-Year Expansion Built on Structural Demand
Over the historical window from 2020 to 2025, the industrial shredder market established a consistent upward arc, reflecting sustained investment in material recovery infrastructure, confidential waste processing, and volume-reduction systems across industrial and municipal environments. The base year closes at a revenue level of approximately 1,268 million USD, representing a meaningful step beyond the pre-2023 baseline. That momentum carries into 2026, with the market positioned at roughly 1,295 million USD as operational budgets normalize, replacement cycles accelerate, and new compliance-driven procurement enters the pipeline.
Looking ahead across the 2026–2032 forecast window, the trajectory compounds at a steady pace. The overall market is projected to reach close to 1,773 million USD by 2032, translating to a forecast-period CAGR of 4.9 percent. This growth profile does not suggest a speculative surge; rather, it reflects compounding demand from end-use sectors that depend on size-reduction equipment as core operational infrastructure. For strategic planners, the implication is clear: industrial shredders are no longer peripheral tools but critical assets whose selection, procurement timing, and technology configuration have direct consequences for throughput efficiency, total cost of ownership, and downstream compliance performance.
The research emphasizes that the growth curve will not be uniform across all equipment classes or end-use categories. Instead, it is being shaped by diverging requirements around material hardness, particle-size outcomes, energy intensity, and regulatory documentation standards. As a result, the strategic question for 2026 is not simply where the market is heading, but which segments are best positioned to capture disproportionate value and which operational parameters should govern capital allocation.
Strategic Segmentation: Why Configuration and Application Matter More Than Ever
A central contribution of this study is its detailed breakdown of demand by equipment configuration and application context. These dimensions matter because they directly influence capacity selection, maintenance intensity, throughput consistency, and return-on-investment timelines. The findings show that double-shaft systems have emerged as a dominant configuration within the overall equipment base, reflecting their widespread applicability for metals, plastics, wood, tires, and mixed waste streams. Single-shaft and three-shaft designs continue to play specialized roles where controlled particle sizing, material separation, or operational flexibility is prioritized. Four-shaft configurations occupy a narrower but strategically important niche where high consistency and intensive volume reduction are required.
On the application side, the market is shaped by several core demand streams. Scrap metal recycling remains the largest end-use driver, underpinned by the ongoing need for efficient downsizing of ferrous and non-ferrous scrap prior to melting and reprocessing. WEEE recycling represents a significant and expanding application, reflecting both regulatory pressure and the materials recovery value embedded in electronic and electrical waste. Wood waste recycling, paper waste recycling, and a range of additional applications round out the demand base, each with distinct operational requirements around output grading, contamination handling, and equipment wear.
What this segmentation reveals for 2026 strategy is that purchasing decisions cannot be made on a single specification sheet. A facility prioritizing high-volume scrap processing may benefit from robust multi-shaft configurations with high wear-resistance characteristics, while an operation focused on confidential document destruction or specialized material recovery may need different installation profiles, control architectures, and documentation-capable output standards. The study quantifies these dynamics and links them to demand share, equipment value distribution, and the practical implications for capacity planning—details that procurement teams can translate directly into specification requirements and vendor evaluation criteria.
Competitive Dynamics and the Battle for Differentiation
The industrial shredder landscape is moderately concentrated, with the leading firms commanding a meaningful share of total revenue and leveraging established engineering capabilities, service networks, and regional presence. The report profiles a competitive set that includes Shred-Tech, Vecoplan, SSI Shredding Systems, Franklin Miller, UNTHA, BCA Industries, Zato North America, Williams Patent Crusher & Pulverizer Co., SatrindTech Srl, and Allegheny Shredders. These organizations are not competing on price alone; they are contesting the market through product architecture, application specialization, service responsiveness, and the ability to align equipment performance with the operational constraints of each end-use segment.
Recent developments make the competitive rhythm especially visible. In 2025, SSI Shredding Systems introduced a new SR900F shredder designed for high-volume RDF production, reinforcing the continued link between shredding capacity and alternative fuel feedstock preparation. That same year, SSI exhibited at PPRC 2025 in Chicago, underscoring the importance of trade channels in shaping buyer expectations and technology diffusion. In 2026, UNTHA showcased two new machine designs alongside the latest evolution of its XR series at IFAT Munich, signaling continued investment in design refinement and application versatility. Meanwhile, Franklin Miller completed a notable TASKMASTER TM4000 shredder installation, highlighting the operational relevance of high-capacity systems in real-world processing environments.
Industrial Shredder Market
Worldwide kitchen Waste Shredder Market
These events are more than product announcements; they are indicators of where the market is moving. OEMs are increasingly orienting development toward energy efficiency, material compatibility, throughput reliability, and ease of integration into broader recycling or destruction workflows. For enterprises evaluating suppliers, that shift changes the evaluation framework. Technical specifications still matter, but so do control-system intelligence, service accessibility, parts availability, and the vendor’s ability to support compliance documentation and long-term operating efficiency. The study examines these competitive levers in detail, connecting them to pricing posture, installed-base considerations, and the strategic positioning of each major player.
Operational Realities Shaping Demand and Procurement Decisions
Behind the headline growth figures lies a set of operational variables that directly influence equipment selection and total cost of ownership. One of the most practical considerations is cutter and blade material performance. High-wear alloy cutters used in industrial shredder blades typically cost 15–30 percent more than baseline D2 steel, but they deliver materially longer service life in impact-prone applications. For facilities running mixed loads, abrasive waste streams, or high-throughput metal processing, that upfront premium can substantially reduce downtime and maintenance frequency. The report assesses when such premium components are strategically justified and how they affect lifecycle cost modeling.
Energy performance is another increasingly decisive factor. New industrial shredder models are delivering up to 15 percent energy savings through smart control technologies, a substantial improvement for installations where power intensity and operating hours drive recurring costs. As organizations face both economic and sustainability targets, control-system intelligence, load optimization, and process automation are becoming key differentiators in vendor selection. The study analyzes how these efficiency gains influence operating economics and whether they are sufficient to alter the evaluation calculus for new installations versus retrofits.
Safety and compliance also remain critical inputs to procurement strategy. OSHA incident records underscore the operational risk environment, documenting an amputation of an employee’s hand caused by an industrial shredder. That kind of incident reinforces the importance of engineered safeguards, operator training, interlock design, and site-specific risk management protocols. At the same time, confidentiality and destruction standards are tightening in specific application areas. The UNE EN 15713 standard establishes recommendations for the management and control of confidential document destruction processes using industrial shredders, while UNE 15713 provides post-destruction information confirming the type of industrial shredder used to divide documents into portions barely containing two letters. These standards matter not only for compliance teams but also for equipment specification, because they influence output requirements, traceability expectations, and the documentation capabilities buyers demand from their shredding systems.
Taken together, these dynamics mean that the 2026 procurement process is increasingly multidisciplinary. Engineering teams must consider wear performance and energy optimization; environmental and compliance teams must factor in destruction documentation and recycling output requirements; and operations leaders must integrate safety, maintenance access, and service reliability into the final selection. The report is structured to support that cross-functional decision-making by aligning equipment analysis with the operational realities buyers face on the plant floor.
What the Study Delivers: Practical Intelligence for 2026 Decision-Making
This Industrial Shredder Market research is designed to convert macroeconomic and competitive signals into a usable decision framework. Rather than offering a single aggregate number, it builds a layered picture of demand, equipment configuration, application distribution, regional structure, and competitive performance. The analytical scope includes historical size evolution, forecast modeling through 2032, and segmentation that shows how value and volume are distributed across equipment types and end-use applications.
Key practical outputs include:
- A structured view of market size progression from 2020 through the 2026–2032 forecast horizon, enabling planners to benchmark internal expectations against the broader industry trajectory.
- Segment-level demand architecture across equipment configurations and application categories, helping procurement teams match specifications to actual operating conditions rather than generic requirements.
- Competitive profiles and recent development tracking for major OEMs, giving strategy and sourcing teams context on product evolution, installation activity, trade-show presence, and technology direction.
- Operational and regulatory context that influences equipment performance, maintenance, safety, and compliance documentation, supporting more realistic total cost of ownership models.
- Insights into efficiency trends, material-handling requirements, and the cost-performance trade-offs that affect whether a buyer should prioritize throughput, particle-size control, energy savings, or wear resistance.
Importantly, the study is built to support scenario planning. Because market growth is shaped by multiple variables—material recovery demand, regulatory tightening, energy and input cost dynamics, and technology adoption—decision-makers need the ability to test assumptions against different operational contexts. The report provides that flexibility by connecting aggregate market structure to the practical choices that determine project success, whether the priority is secure destruction, scrap preparation, WEEE processing, wood waste reduction, paper recovery, or broader mixed-waste downsizing.
How to Use This Research in 2026 Planning Cycles
For executives and analysts entering 2026 planning, this study is useful in several concrete ways. It supports capital budgeting by clarifying where demand is structurally strongest and how equipment classes align with those demand centers. It strengthens vendor evaluation by situating supplier activity within a competitive landscape defined by recent launches, installations, and application-specific development. It improves risk management by integrating safety incidents, compliance standards, wear-material economics, and energy-efficiency improvements into the equipment selection conversation. And it sharpens strategic positioning by revealing where concentration, specialization, and technology differentiation are likely to influence pricing and service competitiveness over the forecast period.
The full analysis contains the detailed segmentation structures, regional breakdowns, application-level market values, and competitive assessments needed to convert strategic objectives into procurement, investment, and sourcing decisions. Because the granular figures, subsegment allocations, and proprietary interpretations are central to the report’s value proposition, this preview intentionally highlights the analytical framework and the decision-relevant themes without reproducing the full dataset.
Whether your objective is to evaluate new equipment investment, reassess existing shredding capacity, benchmark supplier options, or align sustainability and compliance targets with operational realities, the complete study provides the depth required to move from market awareness to informed action.
Next Steps
To access the full market sizing, segmentation detail, competitive analysis, and forecast interpretation, readers are encouraged to explore the complete Industrial Shredder Market report. The complete version delivers the underlying figures, regional and application-level intelligence, and strategic context needed to support 2026–2032 planning with precision.
For detailed analysis of this topic, please visit the official page: Industrial Shredder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China OLED market is projected to witness substantial revenue growth from 2020 to 2035. Starting at USD 8,300 Million in 2020, the market is forecast to reach around USD 27,900 Million by 2035. This surge is fueled by rising consumer electronics production, greater penetration of OLED panels, and expanding applications in automotive and industrial spaces.
Read More - https://bussinessinsights.com/research-report/china-oled-market
Smartphones continue to be the largest application sector within China's OLED market in 2025, capturing over half the market share. Televisions and wearables, driven by surging consumer demand for higher display quality, also hold significant portions. Automotive displays and lighting are on an upward trajectory, propelled by new use cases and smart car production.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-oled-market
Frequently Asked Questions
Who are the key players in China OLED Market industry?
The China OLED market is led by top players such as BOE Technology Group, TCL CSOT, Visionox, Everdisplay Optronics (EDO), and Tianma Microelectronics. These companies dominate the market by investing in R&D, expanding production capacities, and supplying OLED displays for smartphones, TVs, and wearable devices.
What is the China OLED Market growth?
The China OLED market has experienced robust growth, particularly due to BOE Technology’s rapid capacity expansion and increased demand in consumer electronics. In 2023, the market witnessed double-digit growth, driven by rising adoption of OLED panels in smartphones and advanced display applications across multiple industries.
Which segment accounted for the largest China OLED Market share?
Smartphones accounted for the largest share in the China OLED market. With major brands such as Huawei, Xiaomi, and Oppo increasingly incorporating OLED screens into their flagship devices, the smartphone segment dominates, representing a significant portion of total OLED display demand in the country.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
China's security solutions market is projected to grow from USD 19,200 million in 2020 to USD 51,600 million by 2035. This remarkable rise is propelled by ongoing digitalization, mounting security challenges, and strong investments in both public and private sectors. The compound annual growth rate (CAGR) for the period 2025 to 2035 is estimated at approximately 10.1%, reflecting sustained technology adoption, urban expansion, and robust demand for advanced surveillance, access management, and integrated platforms.
Read More - https://bussinessinsights.com/research-report/china-security-solutions-market
Commercial applications hold the lion’s share (36%) of China’s security solutions market by application in 2025, as businesses prioritize safety against theft and cyber risks. Government and infrastructure projects contribute 21%, benefiting from large-scale public safety initiatives. Residential adoption stands at 18%, driven by smart home devices and rising urban incomes. Industrial (12%), transportation (8%), and healthcare (5%) complete the landscape. The dominance of the commercial and government segments highlights the country’s emphasis on robust security for public spaces, critical infrastructure, and corporate facilities.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-security-solutions-market
Frequently Asked Questions
Who are the key players in China Security Solutions Market industry?
The top five players in the China Security Solutions Market are Hikvision, Dahua Technology, Huawei, Uniview, and Zkteco. Hikvision and Dahua dominate in surveillance products, Huawei specializes in integrated security and network solutions, Uniview is a leader in IP video surveillance, and Zkteco is a top provider of biometric access control.
What is the China Security Solutions Market growth?
The China Security Solutions Market has experienced robust growth, with a CAGR of over 10% in recent years. In 2023, companies like Hikvision reported increased revenues driven by higher demand for smart surveillance and AI-based security systems across government, commercial, and residential sectors.
Which segment accounted for the largest China Security Solutions Market share?
Video surveillance remains the largest segment by application in the China Security Solutions Market, accounting for significant market share. This dominance is attributed to the mass adoption of CCTV, AI analytics, and network video monitoring in urban security, transportation, and critical infrastructure protection.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com