

Blogs
PW Consulting: English Language Learning Market to Hit $344.8M by 2032, 6.98% CAGR from $215M in 2025
By PW Consulting, 2026-09-16
Strategic Intelligence for the ELT Sector: Why the 2026 Language Learning Market Report Is Essential for Executive Decision-Making
The English Language Learning market is undergoing a structural transformation that few organizations are equipped to navigate with confidence. Between historical fluctuations and compound growth trajectories, the sector has moved from fragmented experimentation to consolidated demand patterns. For corporate leaders, investors, and institutional strategists operating in 2026, surface-level market headlines are no longer sufficient. What matters is a disciplined reading of how technology adoption, regulatory shifts, learner behavior, and competitive positioning intersect to shape revenue pipelines, product roadmaps, and regional expansion strategies.
PW Consulting has prepared a comprehensive research study designed specifically for decision-makers who require actionable intelligence rather than generic market summaries. This article outlines the strategic architecture of that research, demonstrates how macro-level market dynamics inform 2026 planning cycles, and explains why the granular segmentation, competitive profiling, and scenario-based analysis contained in the full report are critical for organizations seeking durable advantage in a rapidly evolving sector.
The 2026 Market Context: Growth With Complexity
Over the past half-decade, the English Language Learning sector has progressed from a post-pandemic recovery phase into a more mature expansion cycle. The market reached an estimated 205.57 million USD in 2024, advanced to 215.0 million USD in 2025, and is projected to continue its upward path through the 2026-2032 forecast window. This trajectory reflects sustained demand across professional upskilling, academic preparation, migration-driven language acquisition, and enterprise training programs. Yet the headline trajectory alone masks the strategic tensions that matter most to executives.
A compound annual growth rate of 6.98 percent during the forecast period signals healthy expansion, but growth at this pace rarely distributes evenly across products, geographies, or buyer segments. The real strategic question for 2026 is not whether the market is growing, but where value is concentrating, which distribution channels are capturing disproportionate share, and how the mix between institutional procurement and individual self-directed spending is reshaping customer acquisition economics. Organizations that treat the market as monolithic risk misallocating capital toward channels or product formats that may be structurally disadvantaged in the next cycle.
The full research study breaks down these dynamics with a level of segmentation precision that allows leadership teams to distinguish between broad sector tailwinds and specific commercial opportunities. Rather than relying on generalized growth narratives, the report maps how structural demand drivers interact with format preferences, regional purchasing environments, and application-type adoption patterns, giving strategists a practical framework for prioritizing investments and adjusting go-to-market assumptions.
What the Research Delivers: Operational Content for Decision-Makers
This study is constructed as a decision-support instrument, not an academic survey. Its architecture is designed to help executives, product leaders, and market-entry teams answer concrete questions about positioning, resource allocation, and competitive exposure. The report integrates both historical reconstruction and forward-looking scenario analysis so that readers can test strategic assumptions against a range of plausible market outcomes.
The core content areas include:
- A detailed market sizing and trajectory analysis that reconstructs past performance and extends the outlook across the full forecast horizon, enabling leaders to benchmark internal expectations against sector-wide momentum.
- A multi-dimensional segmentation framework that separates the market by region, product type, and end-user application, allowing teams to evaluate where demand is most structurally supported and where growth may be more volatile or contingent on external factors.
- A competitive landscape assessment that profiles major participants, examines their strategic orientations, and identifies how differing business models—digital-first platforms, blended academy models, assessment-driven offerings, and enterprise-focused programs—compete for the same learner pools.
- An analysis of market concentration and consolidation signals, helping stakeholders assess whether the sector is fragmenting toward niche specialization or consolidating around platforms that can combine content, technology, and distribution at scale.
- A regulatory and policy environment review that places recent institutional changes within the broader context of language education governance, student support frameworks, and multilingual service guidance, all of which can influence procurement behavior, compliance requirements, and program design assumptions.
In addition to these structural analyses, the report incorporates recent industry developments that directly affect planning assumptions. Signals ranging from federal administrative adjustments to regional program guidance are evaluated for their potential impact on institutional funding flows, learner demand patterns, and the operating environment for service providers. This contextual layer is essential for organizations that need to anticipate how policy recalibration may alter demand concentration or shift purchasing authority within education and enterprise channels.
The full document is organized to support rapid executive consumption as well as deeper cross-functional alignment. Strategists can use it to pressure-test market-entry theses, product leaders can use it to assess whether existing feature sets align with emerging buyer expectations, and finance teams can use the segmentation structure to refine revenue forecasts with more defensible assumptions about where growth is most likely to materialize.
Competitive Landscape: How Strategic Positioning Is Evolving
The English Language Learning market is contested by a diverse set of players whose strategic postures differ not only in scale but in underlying value propositions. The research evaluates the competitive environment through the lens of commercial model, distribution reach, learner engagement strategy, and institutional vs. individual orientation. This approach matters because competition in the sector is increasingly defined by how effectively companies integrate content quality, technology-enabled personalization, assessment infrastructure, and brand trust across distinct buyer segments.
Several large, established organizations anchor the market with multi-layered offerings that span curriculum, assessment, and proficiency certification. Pearson, based in London, competes through a broad suite of English Language Teaching courseware, assessment services, and proficiency testing solutions that address institutions, governments, and individual learners. Its positioning reflects an orientation toward structured institutional procurement and credibility-driven evaluation tools, making it a relevant benchmark for organizations assessing how assessment and credentialing capabilities influence purchasing decisions.
English Language Learning Market
International immersion and cultural-exchange-focused operators occupy a different strategic space. EF Education First, headquartered in Baar, Switzerland, has built its identity around immersive English programs and cross-cultural learning experiences. Berlitz, operating from the United States, emphasizes immersive instruction built around its signature teaching method, serving individuals, businesses, and government clients. These companies illustrate how experiential and instructor-mediated models continue to compete against purely digital approaches, particularly in segments where outcomes depend heavily on speaking confidence, cultural familiarity, or enterprise credibility.
The digital learning frontier is represented by a cluster of platform-driven companies with distinct user acquisition and engagement strategies. Duolingo, based in Pittsburgh, has popularized mobile and web-based bite-sized lessons that lower the barrier to habitual practice for English and other languages. Rosetta Stone, headquartered in Harrisonburg, Virginia, focuses on immersive computer-assisted learning with speech recognition capabilities that aim to strengthen pronunciation and listening proficiency. Babbel, based in Germany, pursues online subscription-based lessons structured around scientific learning methods for English. Wall Street English, with its base in Italy, differentiates through guaranteed-results course models supported by coaches and teachers, blending digital convenience with human accountability.
In parallel, network-based and infrastructure-oriented providers shape the operational environment for institutions and training centers. inlingua International, headquartered in Switzerland, operates through blended and online language training centers, while Sanako Corporation, based in Finland, focuses on language lab software and hardware that support classroom pronunciation and speaking-skill development. These offerings matter because they influence the technical backbone available to institutions seeking to standardize instruction, track learner progress, and scale language practice in structured settings.
Taken together, these competitive profiles reveal a market in which advantage is increasingly tied to the ability to combine scalable technology with credible outcomes signaling. The research explores how different players are attempting to capture value across the Learner journey—acquisition, practice, assessment, certification, and institutional adoption—and where overlaps in target segments create pressure on pricing, retention, and differentiation. The complete report provides deeper comparisons of business-model resilience, channel dependencies, and the strategic implications of recent product and market developments, without reducing the analysis to simple market-share statements.
Why This Report Matters for 2026 Strategy
Strategic decisions made in 2026 will be judged not by whether they aligned with last year’s assumptions, but by whether they anticipated how the market is reorganizing itself around format preferences, buyer motivation, and regulatory reality. A growth environment of this nature rewards organizations that can distinguish durable demand from temporary hype, and that can identify which customer segments are expanding their willingness to pay for structured learning, assessment, or enterprise-language solutions.
The report is designed to support that kind of judgment. It enables leadership teams to evaluate whether current expansion plans reflect genuine segment traction or simply broad sector optimism. It helps product and operations leaders assess whether their offerings are aligned with the channels and application types that are capturing the most sustainable demand. It also provides investors and corporate strategy teams with a structured way to think about concentration risk, competitive response patterns, and the likelihood that certain subsegments may consolidate faster than others.
Equally important, the research places recent policy and institutional developments in context so that executives can incorporate regulatory uncertainty into scenario planning rather than treating it as an external distraction. Shifts in federal administrative structures, changes in language-access guidance, and state-level adjustments to English learner program frameworks can all influence demand visibility, procurement timelines, and program-design constraints. Organizations that integrate these variables into strategic planning are better positioned to manage risk and identify emerging opportunities before competitors do.
Online Language Learning Market
The full study goes further than the overview presented here. It supplies the segmentation detail, company-level profiling, and forward-looking analysis needed to convert market awareness into concrete action. For teams that require defensible assumptions about where growth is concentrated, which business models are most exposed, and how the competitive field is likely to evolve, the complete research package provides the depth necessary to support board-level discussion, investment committee review, and cross-functional planning cycles.
Conclusion: Moving From Market Awareness to Strategic Precision
The English Language Learning market in 2026 is not simply expanding; it is reconfiguring. Demand continues to grow, but the strategic value of that growth depends on how precisely organizations can interpret segmentation signals, competitive behavior, and policy-driven changes in the operating environment. PW Consulting’s English Language Learning Market research is built to help executives make that interpretation with confidence, offering a structured, evidence-based foundation for decisions that will shape growth, positioning, and resilience over the coming years.
Organizations that want to move beyond high-level market narratives and into the detail that supports concrete strategy should review the complete report. The full analysis provides the segmentation clarity, competitor context, and forward-looking assessment needed to turn market movement into informed strategic action.
For detailed analysis of this topic, please visit the official page: English Language Learning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UPVC Window And Door Market Hits $28.4B In 2025, Projected 6.4% CAGR To $43.61B By 2032
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the UPVC Window and Door Market in 2026 and Beyond
Executive Overview
The global construction and renovation landscape is undergoing a significant transformation, driven by stringent energy efficiency regulations, urbanization trends, and a growing emphasis on sustainable building materials. Within this evolving ecosystem, Unplasticized Polyvinyl Chloride (UPVC) windows and doors have emerged as a cornerstone solution for manufacturers, contractors, and homeowners alike. Our latest market intelligence report offers a comprehensive deep dive into this sector, providing the strategic clarity necessary for informed decision-making throughout the 2026-2032 forecast period.
This analysis serves as a strategic preview of our full market research publication. While we highlight the macro-economic trajectories and competitive forces shaping the industry, the complete dataset—including granular segmentation splits, precise regional revenue shares, and detailed financial modeling—remains an exclusive resource for our clients. Understanding the broad contours of the market is the first step; mastering the specific data points is where competitive advantage is forged.
Market Trajectory and Macro Economic Indicators
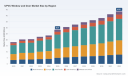
The UPVC window and door market has demonstrated robust resilience and growth over the past five years. Historical data from 2020 through 2025 indicates a consistent upward trend, reflecting the material's increasing adoption in both replacement markets and new construction projects. The market valuation, expressed in USD billions, has progressed steadily, signaling strong underlying demand fundamentals.
Looking ahead, the forecast period from 2026 to 2032 projects a continued expansion phase. Industry analysts anticipate a Compound Annual Growth Rate (CAGR) that underscores the sector's vitality. This growth is not merely linear but is influenced by shifting demographic patterns, infrastructure spending, and regulatory pushes toward energy conservation. The trajectory suggests that by the early 2030s, the market will reach significantly higher valuation thresholds, presenting substantial opportunities for stakeholders who position themselves correctly during the current cycle.
Key macro indicators suggest that the industry is moving past a phase of volatility into a period of structured growth. However, realizing the full potential of this growth requires more than just observing top-line numbers. It demands an understanding of how different product types, application sectors, and geographic regions contribute to the aggregate figure. Our full report dissects these layers, providing the specificity needed to allocate capital efficiently and identify high-yield segments.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of established global players and agile regional specialists. Concentration metrics indicate a moderately consolidated environment where top-tier manufacturers hold significant influence. The CR3 and CR5 ratios suggest that while a few key players dominate the landscape, there remains ample room for differentiation through technology, design, and regional presence.
UPVC Window and Door Market
Leading manufacturers are actively maneuvering to secure their positions through capacity expansion, strategic partnerships, and innovation in profile systems. Major entities such as VEKA Group, Rehau, aluplast, and Deceuninck continue to set benchmarks in PVC profile systems and energy-efficient solutions. These companies are not merely competing on price but are engaging in sophisticated value-chain integrations. For instance, recent collaborations have focused on sustainability initiatives, such as partnerships aimed at promoting green construction practices and enhancing the lifecycle efficiency of window systems.
Regional dynamics also play a crucial role in competitive strategy. In North America, companies like United Window & Door are expanding production capacities to meet local demand, reducing reliance on imported profiles and strengthening supply chain resilience. Simultaneously, in Asia Pacific, manufacturers like Fenesta and LG Hausys are leveraging local manufacturing advantages to cater to booming residential and commercial sectors. TWR Group in the UK and other fabricators are also adapting their offerings to meet specific trade and commercial requirements.
Recent developments highlight the pace of change. Facility expansions involving significant capital investment have been announced to accommodate growing order books. Product launches introducing new systems, such as tilt-turn solutions and triple-track patio doors, indicate a focus on diversifying portfolios to capture niche demands. Furthermore, partnerships regarding finishes and materials suggest an industry-wide push toward aesthetic customization and performance enhancement. Understanding the specific timing and impact of these moves is critical for benchmarking one's own strategy against the market leaders.
Industry Dynamics: Cost Structures and Regulatory Pressures
One of the most critical factors influencing margin stability and pricing strategies is the cost of raw materials. UPVC profile costs account for a substantial portion of manufacturing expenses, making resin price fluctuations a key risk variable. Recent market intelligence indicates divergent trends across major regions. In Europe, PVC resin prices have seen upward pressure, impacting cost structures for profile manufacturers. Conversely, in markets like India, price adjustments have followed global supply chain realignments, presenting a different cost environment. These disparities create complex challenges for multinational strategists who must navigate varying input costs while maintaining competitive pricing.
Regulatory frameworks are equally influential. Government initiatives aimed at affordable housing and energy efficiency are acting as primary demand drivers. In the European Union, plans emphasizing renovation-first approaches and stringent energy efficiency standards are accelerating the replacement of old fenestration systems with high-performance UPVC alternatives. Industry associations have welcomed these developments, recognizing the potential for increased market volume. However, regulatory shifts also bring compliance complexities. For example, changes in logistics schemes regarding PVC window profile transport pallets require operational adjustments.
In emerging markets, protectionist measures are gaining traction. Industry bodies in regions like India have appealed for import controls on uPVC profiles to safeguard domestic manufacturing interests. Such policy developments can alter competitive dynamics overnight, favoring local producers while potentially restricting supply options for assembled goods. Monitoring these regulatory signals is essential for risk mitigation. Our detailed report provides a nuanced analysis of how these dynamics vary across sectors and regions, offering actionable insights on navigating the regulatory maze.
Segmentation and Application Opportunities
The market is multifaceted, segmented by window and door types, applications, and geography. While the aggregate market size provides a high-level view, the real strategic value lies in understanding the performance of specific segments. Product diversity ranges from casement and sliding systems to tilt and turn configurations and French doors. Each type serves different functional and aesthetic needs, commanding different market shares and growth rates. For example, energy-efficient tilt-turn systems are gaining traction in markets with strict thermal performance codes, while sliding systems remain popular in space-constrained residential settings.
Application-wise, the residential sector typically constitutes the largest share of demand, driven by housing starts and renovation activities. Commercial applications follow, fueled by office complexes, hospitality projects, and institutional buildings. Industrial applications, while smaller in volume, offer specialized requirements regarding durability and security. The interplay between these segments determines the overall health of the market. A slowdown in residential construction might be offset by a surge in commercial retrofitting, depending on economic conditions.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities. Developed markets may focus on replacement cycles and energy upgrades, while developing markets might see higher volume from new infrastructure projects. Our complete analysis breaks down these regional nuances without relying on broad generalizations, providing the specific intelligence needed to tailor go-to-market strategies.
Strategic Value for 2026 Decision Making
For executives and strategists, the ability to anticipate market shifts is paramount. The 2026 landscape offers both risks and rewards. On one hand, rising raw material costs and regulatory changes pose challenges to margin management and compliance. On the other hand, government incentives for energy efficiency and housing create clear demand pull. Navigating this environment requires more than intuition; it requires data-backed precision.
PVC Window Profile Market
Our market research report is designed to equip leaders with the tools necessary to make decisive moves. Whether it is evaluating potential mergers and acquisitions, planning capacity expansions, or refining product portfolios, the data provided serves as a foundational asset. The report goes beyond static numbers to offer context on how competitive moves, such as new facility openings or strategic partnerships, are reshaping the battlefield.
Furthermore, understanding the concentration of market power helps in assessing barriers to entry and the viability of niche strategies. Companies can identify gaps where innovation can disrupt incumbent players or where consolidation might be beneficial. The insights into recent developments—such as specific product launches and investment rounds—provide a real-time view of where competitors are placing their bets. This intelligence allows organizations to align their own roadmaps with emerging trends rather than reacting to them after the fact.
The forecast period through 2032 offers a long-term horizon for planning. Stakeholders can model various scenarios based on the projected CAGR and market valuation trends. This long-view perspective is crucial for capital-intensive decisions in manufacturing and distribution. By integrating macro trends with segment-specific data, organizations can build robust strategies that are resilient to short-term volatility while capitalizing on long-term growth vectors.
Conclusion
The UPVC window and door market stands at a pivotal juncture. The convergence of economic recovery, regulatory support for energy efficiency, and technological innovation in profile systems creates a fertile ground for growth. However, realizing this potential requires a sophisticated understanding of the market's inner workings.
This article has provided a high-level overview of the market's trajectory, competitive forces, and dynamic pressures. To access the complete landscape of intelligence discussed herein—including precise segmentation data, detailed regional breakdowns, and exhaustive company profiles—we invite you to explore our full market research report. The detailed intelligence contained within is designed to transform uncertainty into strategic clarity, empowering your organization to lead rather than follow in the years ahead.
For detailed analysis of this topic, please visit the official page: UPVC Window and Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ursodeoxycholic Acid Market to Reach $1.1B by 2032 with 10.2% CAGR
By PW Consulting, 2026-09-16
Navigating the Ursodeoxycholic Acid Drug Product Market: Strategic Intelligence for 2026 and Beyond
The global landscape for hepatology therapeutics is undergoing a period of significant recalibration, driven by evolving regulatory frameworks, patent expirations, and a growing prevalence of chronic liver conditions. At the center of this shift stands Ursodeoxycholic Acid (UDCA), a compound that has long maintained its position as a foundational therapy. For pharmaceutical executives, investors, and strategic planners, understanding the trajectory of this market is no longer optional; it is a critical component of portfolio optimization and competitive positioning. Our latest comprehensive market research report offers a granular examination of the UDCA drug product landscape, designed specifically to equip decision-makers with the actionable intelligence required to navigate the complexities of 2026 and the subsequent forecast period through 2032.
A Market on a Defined Growth Trajectory
The macroeconomic signals for the UDCA drug product market are unmistakable. Drawing on historical data spanning from 2020 through 2025, our analysis tracks a consistent upward arc in global revenue, measured in millions of US dollars. The baseline established in recent years reflects a compound annual growth rate that underscores sustained demand across multiple therapeutic areas. As we pivot into the forecast window of 2026 to 2032, the projection indicates a robust expansion that will reshape revenue pools and alter the calculus for market entry, capacity planning, and partnership strategies.
This growth is not merely a function of population expansion or generic substitution. It is being propelled by a confluence of factors: the chronic nature of primary biliary cholangitis, which demands long-term patient adherence and stable reimbursement pathways, and the ongoing utilization of UDCA as a first-line intervention under established FDA guidelines. Furthermore, the anticipated dominance of the generics segment, expected to command a substantial share of the market in 2026 following a wave of patent expirations, introduces a new dynamic of price pressure and volume-driven economics. Understanding how these forces interact requires more than top-line figures; it demands a dissection of the underlying structural drivers that our report meticulously maps out.
What Is Inside: A Blueprint for Operational and Strategic Execution
Our market research is structured to move beyond abstract trends and deliver concrete, operational utility. The report provides a multi-dimensional view of the UDCA drug product ecosystem, encompassing historical performance, forward-looking projections, and a detailed breakdown of the competitive and regulatory environment. Below is a preview of the core components that will enable your organization to translate market intelligence into decisive action.
- Historical and Forecast Revenue Analysis: A year-by-year examination of global revenue performance from 2020 through 2032, highlighting inflection points, growth acceleration, and the projected scale of the market as it approaches the end of the decade. Readers will gain clarity on the magnitude of the opportunity and the temporal windows most relevant to investment and capacity decisions.
- Segmentation Dynamics: A deep dive into the primary axes that define the market: dosage form, therapeutic application, and geographic distribution. The report evaluates how tablets and capsules compete for share, how indications such as gallstones and primary biliary cholangitis drive distinct demand profiles, and how regional markets are evolving in response to local regulatory, reimbursement, and supply chain conditions.
- Competitive Landscape and Corporate Profiles: An in-depth assessment of the leading integrated producers, generic suppliers, and specialized manufacturers shaping the market. Each profile includes geographic footprint, product positioning, and strategic implications for partnership, acquisition, or competitive defense.
- Recent Developments and Regulatory Intelligence: A curated timeline of pivotal events, including accelerated approvals for combination therapies targeting primary biliary cholangitis, new generic product launches, and updates to reimbursement and standard-of-care guidance. These developments are analyzed for their near-term and medium-term impact on market dynamics.
- Industry Context and Structural Forces: An examination of the reconcentration metrics that reveal the degree of market consolidation, alongside an assessment of supply chain considerations, raw material dynamics, and the reimbursement environment that underpins long-term patient access.
The Competitive Arena: Key Players and Strategic Positioning
The UDCA drug product market is characterized by a mix of established integrated manufacturers, global generic giants, and regional specialists. Our report provides detailed profiles of the companies that are actively shaping supply, pricing, and innovation within this space, offering a framework for evaluating competitive threats and partnership opportunities.
Among the most prominent participants is ICE Pharma, an Italy-based integrated producer that has built a significant presence in UDCA bile acid derivatives. With manufacturing capabilities spanning Europe, Latin America, Asia, and Oceania, and a distribution network that reaches over fifty countries, ICE Pharma exemplifies the globalized, vertically integrated model that can command respect in both branded and generic segments. For organizations evaluating supply chain resilience or seeking regional market access, ICE Pharma's footprint offers a case study in scale and geographic diversification.
Teva Pharmaceuticals, headquartered in Israel, represents a major force in the generic UDCA space, with an active supply of USP tablets and capsules. As one of the world's largest generic pharmaceutical companies, Teva's involvement signals both the maturity of the UDCA market and the ongoing relevance of high-volume, cost-competitive manufacturing. Similarly, Sun Pharmaceutical Industries Ltd, a leading Indian generic supplier, has reinforced its commitment to the market through recent product launches, underscoring the strategic importance of India as a production hub and the intensifying competition among generic manufacturers.
Daewoong Pharmaceutical, based in South Korea, adds another dimension to the competitive landscape as a supplier of UDCA drug products, including once-daily formulations. Formulation innovation and patient-centric dosing regimens are increasingly important differentiators, and Daewoong's presence highlights the potential for regional manufacturers to compete on convenience and adherence. In India, Mankind Pharma and Octavius Pharma Pvt. Ltd continue to be active manufacturers and suppliers of UDCA tablets, capsules, and API, reflecting the dense and competitive Indian manufacturing ecosystem that plays a critical role in global supply. Meanwhile, in the United States, Willow Birch Pharma and Lannett Company serve as active suppliers and manufacturers of generic UDCA products, catering to domestic demand and navigating the nuances of the US regulatory and reimbursement environment.
Ursodeoxycholic Acid Drug Product Market
Our report goes beyond company descriptions to analyze how these players interact within a market that, based on our concentration metrics, exhibits a moderate level of consolidation. With a focused analysis of market share distribution and the strategic implications of competitive density, decision-makers can better assess barriers to entry, the feasibility of niche positioning, and the potential for consolidation or partnership-driven growth.
Market Dynamics: Regulation, Reimbursement, and Supply Chain Forces
The structural underpinnings of the UDCA market are defined by a set of regulatory and reimbursement realities that create both stability and pressure. UDCA remains the standard first-line therapy for primary biliary cholangitis under FDA guidance, with no substantive changes reported through 2025. This continuity reinforces the compound's central role in treatment protocols and supports predictable demand over the long term. At the same time, the chronic nature of the disease drives sustained patient adherence, which in turn bolsters the case for consistent reimbursement coverage. For market participants, this dynamic translates into a durable revenue base, but also into heightened scrutiny of pricing, access, and the value proposition relative to emerging adjunct therapies.
On the supply side, the generics segment is anticipated to hold a significant majority share of the market in 2026, a shift driven by patent expirations on branded products and the resulting price pressure. This transition has profound implications for manufacturing strategy, margin expectations, and competitive differentiation. Companies that can optimize production efficiency, secure reliable API sourcing, and navigate regulatory compliance with agility will be best positioned to capture volume in a increasingly price-sensitive environment. Our report explores these supply chain and raw material dynamics in detail, offering insights into the operational levers that can determine success as the market tilts further toward generics.
Recent regulatory and commercial developments add further texture to the landscape. In 2024, the FDA granted accelerated approval for elafibranor for primary biliary cholangitis in combination with ursodeoxycholic acid, and shortly thereafter, accelerated approval for seladelpar in combination with ursodeoxycholic acid. These milestones, achieved by major pharmaceutical companies, signal a growing emphasis on combination and adjunct treatment paradigms for primary biliary cholangitis. While UDCA remains the foundational therapy, the emergence of combination approaches could reshape treatment pathways, create new co-marketing opportunities, and influence the competitive positioning of standalone UDCA products over time. Additionally, the recent launch of generic UDCA drug products by Sun Pharmaceutical Industries Ltd in late 2024 illustrates the ongoing pace of generic entry and the need for continuous monitoring of product availability, pricing shifts, and geographic rollout strategies.
Strategic Implications for 2026 Decision-Making
As organizations prepare for 2026, the UDCA drug product market presents a blend of opportunity and complexity that demands a disciplined strategic approach. The forecast period through 2032 suggests a market that will continue to expand materially, but the distribution of that growth across dosage forms, indications, and regions will not be uniform. Companies that rely on aggregate market figures alone risk missing the granular shifts that determine whether a product, a market entry, or a partnership will succeed or underperform.
Ursodeoxycholic Acid Market
For manufacturers, the anticipated dominance of the generics segment in 2026 underscores the importance of cost leadership, supply chain robustness, and regulatory agility. For branded and specialized players, the opportunity may lie in formulation differentiation, patient support programs, combination strategies, or targeted regional expansion where competitive density is lower. For investors and strategic advisors, the concentration metrics and competitive profiles provide a lens through which to evaluate market access, barriers to entry, and the potential for consolidation or vertical integration.
Reimbursement dynamics and the chronic disease context further emphasize the need for a long-term perspective. Patient adherence and sustained coverage create a relatively stable demand floor, but they also heighten the importance of demonstrating value, managing pricing expectations, and aligning with payer and provider priorities. The introduction of combination therapies and the evolving treatment landscape for primary biliary cholangitis add another layer of strategic consideration, as organizations must anticipate how new regimens may complement, compete with, or redefine the role of UDCA in standard care.
Why Comprehensive Intelligence Matters
The decisions that will shape your organization's position in the UDCA drug product market over the next several years depend on a clear, evidence-based understanding of the forces at play. Aggregate trends provide direction, but they do not replace the need for detailed segmentation, competitive profiling, regulatory tracking, and scenario analysis. Our full market research report delivers that depth, equipping stakeholders with the data and context required to make informed choices about capacity, product strategy, geographic focus, partnership structures, and competitive responses.
We invite you to access the complete report to explore the full scope of our analysis, including the specific regional and application-level insights, detailed company assessments, and forward-looking projections that will support your strategic planning for 2026 and beyond. In a market defined by both continuity and change, the organizations that thrive will be those that invest in the intelligence needed to act with precision, anticipate shifts before they become disruptive, and align their capabilities with the most promising avenues for growth.
For detailed analysis of this topic, please visit the official page: Ursodeoxycholic Acid Drug Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: VLM Market Hits $1.6B in 2025, Surges to $2.6B by 2032 at 9.25% CAGR
By PW Consulting, 2026-09-16
Strategic Vertical Lift Module Market Assessment 2026: Capitalizing on Automation Momentum
The operational landscape for automated storage and retrieval systems is undergoing a definitive structural shift. As supply chain resilience becomes a board-level priority, the Vertical Lift Module Market is emerging as a critical lever for enterprise efficiency. Our latest research publication, Vertical Lift Module Market 2026, provides a comprehensive strategic roadmap for navigating this high-growth sector. This analysis is designed to equip decision-makers with the intelligence required to optimize capital allocation, mitigate supply chain risks, and capitalize on the accelerating adoption of high-density automated storage solutions.
Vertical Lift Module (VLM) Market
Based on rigorous historical analysis and forward-looking modeling, the global market for Vertical Lift Modules has demonstrated robust expansion over the past five years. Historical revenue figures from 2020 through 2025 show a consistent upward trajectory, culminating in a strong baseline entering the forecast period. Projections for the forecast window extending to 2032 indicate sustained momentum, driven by the urgent need for space optimization and labor efficiency in modern logistics and manufacturing environments. The market is expected to grow from a substantial 2025 baseline to a significantly larger valuation by the end of the forecast period, underpinned by a compound annual growth rate reflecting high single-digit expansion. This growth trajectory signals that demand for automated vertical storage is not cyclical but structural, influenced by long-term operational imperatives rather than short-term fluctuations.
Operational Imperatives Driving Market Expansion
The fundamental drivers of this market growth are deeply rooted in the operational constraints facing modern enterprises. As urbanization increases and industrial real estate costs escalate, the economic pressure to maximize cubic space utilization has intensified. Vertical Lift Modules offer a compelling solution by reclaiming significant floor space and leveraging ceiling height for storage density. Industry analysis highlights that these systems support broader sustainability initiatives by reducing energy waste through efficient vertical space utilization in warehouse operations. Furthermore, the economic case for adoption is strengthening. Automated VLM systems deliver a compelling return on investment within a relatively short timeframe through labor savings derived from increased picking efficiency. With modern systems capable of delivering picking rates exceeding several hundred picks per hour, the labor productivity gains are substantial, directly impacting bottom-line performance in sectors facing chronic labor shortages.
Competitive Dynamics and Strategic Positioning
The competitive landscape for the Vertical Lift Module Market is characterized by a moderate level of concentration, with established players leveraging technological differentiation and regional manufacturing footprints to secure market share. Our research provides detailed profiles of key market participants, analyzing their specific value propositions, geographic strengths, and technological focus areas.
Leading Market Participants:
- Modula (Casalgrande, Reggio Emilia Province, Italy): A recognized leader in automated vertical storage, focusing on their specific offering for the Vertical Lift Module Market with Modula Lift and Modula Slim fully automated vertical storage systems. Their solutions are engineered to reclaim up to 90% floor space by utilizing ceiling height, offering a distinct advantage in space-constrained environments. Their recent product developments highlight a focus on specialized configurations; in October 2025, Modula released a comparison highlighting differences between traditional Vertical Lift Modules and their Modula Flexibox specialized bin-based configuration for high-volume picking, underscoring their strategy to address diverse throughput requirements.
- White Systems (Hamilton, Ohio, USA): White Systems emphasizes robust, US-manufactured enclosed automated storage and retrieval systems, including the PowerColumn 3 and Compact Lift models. These heavy-duty and compact solutions are engineered for demanding applications, offering up to 99% picking accuracy. A significant strategic development occurred in February 2026, when SencorpWhite, the parent company of White Systems, established a new US headquarters in Hamilton, Ohio. This move is designed to support continued investment in American-made VLM manufacturing, signaling a commitment to localized supply chains and potentially influencing regional market dynamics and lead times for North American clients.
- Kardex (Switzerland): Kardex brings a global footprint with a focus on tray-based enclosed automated storage systems, specifically the Kardex Shuttle. Their strategy centers on the Total Intelligence Concept control system, designed for operator-centric picking, enhancing usability and integration with broader warehouse workflows. In January 2025, Kardex introduced an upgraded Kardex Shuttle Vertical Lift Module with the Total Intelligence Concept control system featuring an intuitive user interface, demonstrating a continuous investment in user experience and control system sophistication to maintain competitiveness.
- Vidir Solutions (Arborg, Manitoba, Canada): Vidir Solutions provides high-density automated vertical storage systems tailored for industrial and healthcare applications. Their VLM and VLM Mini solutions are focused on reclaiming up to 85% floor space, positioning them as a key player in sectors where space efficiency and hygiene or safety standards are paramount. Their emphasis on industrial and healthcare applications suggests a strategic niche focus within the broader VLM ecosystem.
The concentration of the market remains notable, with leading entities commanding a significant share of global revenue. This concentration fosters an environment where technological innovation and specialized application focus are key differentiators. Our research dissects these competitive interactions, providing insights into how incumbents are defending their positions and where new entrants might find opportunity gaps.
Macro-Economic Variables and Regulatory Considerations
Strategic planning in this sector requires a nuanced understanding of macro-economic variables and regulatory frameworks that influence both supply and demand. Our report integrates critical external factors that impact project feasibility and total cost of ownership.
Supply Chain and Raw Material Dynamics
Cost structures for VLM manufacturing are sensitive to raw material fluctuations. For instance, hot-rolled coil steel prices have shown variability, averaging approximately $1,109 per ton as of June 2026, with upward trending futures into mid-2026. These commodity price movements directly affect the cost of construction for steel-intensive automated storage units. Decision-makers must account for these input cost trends when evaluating procurement strategies and long-term contracts, as price volatility can impact project timelines and budget allocations.
Intelligent Automatic Warehouse And Logistic Equipment Market
Regulatory Compliance and Certification
Compliance requirements add a layer of complexity to market entry and product deployment, particularly in regulated regions. VLM units require CE certification to meet strict European safety, efficiency, and compliance guidelines for automated storage systems. Adherence to these standards is not merely a legal formality but a critical enabler for market access and customer trust in Europe. Our analysis examines how regulatory landscapes shape product specifications and the competitive advantages derived from early compliance and certification readiness.
Deep Dive into Research Methodology and Content Architecture
The Vertical Lift Module Market 2026 report is structured to provide actionable intelligence at multiple levels of strategic planning. The research leverages a multi-tiered analytical framework, synthesizing historical performance data with forward-looking indicators to construct a reliable outlook through 2032.
- Market Sizing and Trajectory Analysis: The report provides detailed revenue valuations for the historical period and the forecast horizon. By analyzing year-over-year growth patterns from 2020 to 2025, the study establishes a robust baseline that accounts for market corrections and acceleration phases. The forecast period projections isolate key drivers to estimate market size evolution, offering a clear view of the total addressable market and growth velocity.
- Segmentation Insights: Understanding the heterogeneity of demand is essential for targeted strategy development. The research segments the market based on key dimensions, allowing stakeholders to identify high-growth niches and volume drivers. While specific regional and application splits are detailed within the full report, the analysis highlights how different segments are evolving in response to industry-specific needs. For example, the dominance of certain material types and application areas points to where technological standardization and scale economies are most pronounced, while other segments may represent emerging opportunities requiring tailored approaches.
- Competitive Intelligence: Beyond company profiles, the report examines strategic moves, product launches, and expansion activities. Recent developments, such as Kardex's control system upgrade, Modula's configuration differentiation, and White Systems' manufacturing footprint expansion, are analyzed not just as isolated events but as indicators of broader competitive strategies. These developments reveal how companies are responding to market pressures, whether through enhanced functionality, supply chain localization, or product versatility.
- Market Concentration and Power Dynamics: The research quantifies market concentration levels, providing context for negotiation leverage and partnership opportunities. A moderately concentrated market suggests that while key players hold significant influence, there remains room for specialized integrators and regional service providers to capture value. Understanding these power dynamics is crucial for vendors seeking distribution partnerships and for end-users evaluating supplier stability and support capabilities.
Strategic Implications for 2026 Decision-Makers
As organizations evaluate automation investments in 2026, the Vertical Lift Module Market presents both opportunities and complexities. The convergence of labor economics, real estate constraints, and technological maturity creates a favorable environment for VLM adoption. However, the diversity of available solutions and the influence of external factors such as raw material costs and regulatory requirements demand a disciplined evaluation process.
Our research serves as a decision-support tool to navigate this environment. It enables stakeholders to benchmark potential solutions against market standards, assess the viability of deployment in specific operational contexts, and anticipate competitive responses. For investors and analysts, the detailed market sizing and segmentation offer a foundation for valuation and risk assessment. For manufacturers and system integrators, the competitive landscape analysis provides insights into positioning, differentiation, and potential areas for strategic collaboration or innovation.
The forecast period through 2032 suggests that the current growth trajectory will persist, though the rate and composition of growth may shift as technology matures and new applications emerge. Early movers who align their strategies with the structural drivers identified in this research are likely to secure competitive advantages in efficiency and market share. Conversely, organizations that overlook the nuances of this market risk suboptimal capital deployment and missed opportunities to enhance operational resilience.
Conclusion and Access to Full Intelligence
The Vertical Lift Module Market is poised for sustained expansion, driven by the imperatives of space optimization, labor efficiency, and automation integration. The strategic value of this market extends beyond immediate productivity gains, touching on broader themes of supply chain agility and sustainability. Our comprehensive research report, Vertical Lift Module Market 2026, delivers the depth of analysis required to make informed decisions in this dynamic environment.
To fully leverage these insights, we invite stakeholders to access the complete report. The full publication contains detailed regional and application breakdowns, granular competitor benchmarking, and extensive data tables that support precise scenario planning. By exploring the complete dataset, decision-makers can uncover the specific growth vectors and competitive signals that are most relevant to their strategic objectives. Visit our source page to download the full market intelligence and equip your organization with the knowledge needed to lead in the automated storage sector.
For detailed analysis of this topic, please visit the official page: Vertical Lift Module (VLM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fullerene Market to Reach $600M by 2032 Amid 7.8% CAGR Growth
By PW Consulting, 2026-09-16
Strategic Intelligence for the Fullerene Market: Navigating Growth, Supply Constraints, and Competitive Shifts Through 2032
The global fullerene market stands at a pivotal inflection point. What began as a niche materials segment has matured into a cross-industry enabler spanning high-purity electronics, advanced cosmetics, pharmaceutical formulations, and next-generation energy systems. For executives and strategy teams operating in 2026, the decisions made today around feedstock security, purity validation, and application diversification will define competitive positioning over the next half-decade. This market research report delivers a structured, data-grounded blueprint for navigating that complexity.
Our analysis traces the market trajectory from its historical baseline through a forward-looking forecast window. The sector reached an estimated valuation of 358.91 million USD in the 2025 base year, building on consistent growth momentum since 2020 when the market was evaluated at 250.0 million USD. The compound annual growth rate of 7.8 percent projects the market toward approximately 600.0 million USD by 2032. This trajectory is not merely a numerical forecast; it reflects structural shifts in manufacturing capability, regulatory evolution, and the migration of fullerene materials into higher-value applications. Understanding where growth concentrates, which purity thresholds are becoming commercially non-negotiable, and how supply-side constraints are reshaping cost structures is essential for capital allocation, partnership strategy, and product roadmapping.
Market Trajectory and Structural Drivers
The historical series from 2020 to 2025 demonstrates a compounding expansion pattern. Revenue scaled from 250.0 million USD in 2020 to 275.27 million USD in 2021, continued to 298.41 million USD in 2022, advanced to 316.88 million USD in 2023, reached 342.75 million USD in 2024, and closed at 358.91 million USD in 2025. This steady progression signals a market that has moved beyond early-stage volatility into a more predictable growth rhythm. The forecast horizon extends that momentum through 2032, with projected annual valuations climbing from 386.43 million USD in 2026 to 406.58 million USD in 2027, 446.49 million USD in 2028, 473.23 million USD in 2029, 506.52 million USD in 2030, 568.88 million USD in 2031, and 600.0 million USD in 2032.
Several interlocking forces underpin this expansion. First, the migration of fullerene-based materials from laboratory-scale research into validated commercial processes is broadening the addressable market. High-purity grades are increasingly specified in optical and electronic formulations where performance thresholds demand consistent molecular quality. Second, regulatory scrutiny around nanomaterials has intensified, reshaping validation requirements and elevating the commercial premium for materials that meet stringent purity benchmarks. Third, feedstock dynamics are introducing new cost and availability considerations that reward manufacturers and buyers who secure resilient supply chains. These drivers do not operate in isolation; they interact to create both margin pressure and differentiation opportunities for organizations that align procurement, R&D, and compliance strategies early.
Supply-Side Realities and Regulatory Headwinds
Graphite remains the foundational feedstock for fullerene production, anchoring the entire value chain to upstream carbon material economics. Recent years have seen tighter export controls on natural graphite, particularly from China, which has constrained global feedstock availability and contributed to elevated supply-chain costs. For procurement and operations leaders, this is not a transient disruption. It represents a structural recalibration that favors diversified sourcing strategies, long-term offtake agreements, and manufacturers with integrated purification capabilities. Companies that rely on single-source feedstock exposure face heightened vulnerability to price volatility and lead-time variability, while those that hedge across geographies and grades can stabilize input costs and protect margin profiles.
On the regulatory front, the FDA has ramped up risk assessments and validation requirements for nanomaterials, a shift that directly influences fullerene procurement specifications. The practical outcome is rising demand for ultra-high-purity fullerene materials at thresholds of 99.5 percent and 99.9 percent or higher, alongside validated purification techniques that can withstand scrutiny in regulated end markets. This trend is especially relevant for pharmaceutical and cosmetic applications, where traceability, batch consistency, and documented purification pathways increasingly determine whether a material qualifies for advanced formulation pipelines. Organizations that treat purity validation as a strategic capability rather than a compliance checkbox will be better positioned to capture premium segments and reduce time-to-market for next-generation products.
The Competitive Landscape and Strategic Positioning
The fullerene market exhibits meaningful concentration, with the top three players accounting for approximately 57.0 percent of market share and the top five expanding that footprint to roughly 63.0 percent. This concentration underscores the importance of understanding not just who the incumbents are, but how their technological capabilities, certification milestones, and application focus shape competitive dynamics. The following companies anchor the current landscape and illustrate the strategic diversity within the sector.
Nano-C, Inc.
Headquartered in Westwood, Massachusetts, United States, Nano-C operates as the leading US manufacturer of high-purity C60, C70 fullerenes, and functionalized derivatives via combustion synthesis. Its product and process orientation is tightly aligned with organic photovoltaics, electronics, and nanotechnology applications. In May 2026, the company achieved ISO 9001:2015 certification for advanced electronic materials including fullerenes, a milestone that reinforces its credibility in quality-sensitive electronic supply chains and signals a deliberate focus on manufacturing consistency and customer qualification requirements.
SES Research Inc.
Based in Houston, Texas, United States, SES Research functions as a manufacturer and distributor of premium C60 fullerenes and derivatives, with a commercial emphasis on wellness, supplements, and research-grade applications. Its positioning highlights the divergence within the market between high-specification industrial materials and consumer-facing or research-oriented product lines, where branding, purity communication, and application-specific testing play outsized roles in commercial success.
Frontier Carbon Corporation
Located in Tokyo, Japan, Frontier Carbon specializes in high-volume combustion-synthesis fullerenes and derivatives designed for cosmetics, pharmaceuticals, and electronics. The company's application breadth reflects a strategic emphasis on scale and multi-segment relevance, aligning volume production with the purity and consistency requirements that regulated and performance-driven end markets demand.
MER Corporation
Operating from Tucson, Arizona, United States, MER Corporation supplies mixed fullerenes including C60 and C70, along with higher-order fullerenes, for research and materials applications. Its portfolio orientation illustrates the continuing importance of research-grade supply and specialty material variants that support R&D pipelines, prototype development, and materials science discovery.
BuckyUSA, Inc.
Also based in the United States, BuckyUSA operates as a market-driven producer of fullerene materials for science and industrial uses. Its commercial model highlights the role of flexible, application-responsive production in serving diverse buyer requirements across academic, industrial, and specialized materials contexts.
Solenne BV
Headquartered in Groningen, the Netherlands, Solenne produces high-quality fullerene derivatives including PCBM grades at scales up to the kilogram level. This capability is particularly relevant for customers that require derivative-grade materials with controlled specifications and scalable batch production, bridging the gap between laboratory research and pilot-scale or early commercial deployment.
Together, these players demonstrate that the competitive landscape is not monolithic. Differentiation emerges through purity thresholds, certification status, production scale, application specialization, and geographic positioning. For buyers and investors alike, understanding which capabilities align with specific end-use requirements is critical to selecting partners, structuring supply agreements, and identifying white-space opportunities where incumbent coverage remains incomplete.
Report Scope and Practical Value for Decision-Makers
This market research report is designed to translate macro trends into actionable intelligence. It provides a comprehensive analytical framework that covers market sizing, growth decomposition, segmentation dynamics, competitive profiling, and forward-looking scenario considerations. Rather than presenting numbers in isolation, the report embeds them within the operational and regulatory contexts that determine how those numbers translate into real-world strategy.
Readers will gain clarity on how the market evolved from 2020 through 2025, why the projected 7.8 percent CAGR is grounded in observable demand and supply dynamics, and which structural factors are likely to accelerate or moderate growth through 2032. The analysis examines how purity requirements, feedstock availability, and application migration interact to shape margin structures and procurement strategies. It also maps the competitive landscape in a way that highlights not just market share, but the strategic implications of certification milestones, geographic footprints, and application-specific capabilities.
For corporate strategy, R&D leadership, procurement, and investment teams, the report serves as a decision-support tool. It helps identify where to prioritize supplier qualification, how to assess the commercial implications of tightening nanomaterial regulations, and which application pathways offer the most credible growth potential. It also provides a structured basis for evaluating partnership opportunities, capacity investments, and market-entry timing.
Cucurbituril Market
What the Full Analysis Delivers
To support robust strategic planning, the complete report goes beyond headline figures and offers granular, segment-level intelligence. The full analysis includes detailed regional performance trends, type-specific valuation and growth patterns across C60, C70, C76, and other fullerene variants, and application-level demand trajectories spanning cosmetics, semiconductor and electronics, pharmaceuticals, energy and power, and aerospace and defense. These breakdowns are essential for understanding where value creation is concentrated and how growth diverges across end markets with different purity, scale, and regulatory profiles.
The report also incorporates competitive benchmarking, recent corporate developments such as Nano-C's ISO 9001:2015 certification achievement in May 2026, and a forward-looking assessment of supply-chain risk factors tied to graphite availability and export-control dynamics. By connecting these operational developments to broader market outcomes, the analysis equips decision-makers with a more durable basis for scenario planning and investment prioritization.
Why This Research Matters for 2026 Strategy
2026 is a year in which intuition alone will not suffice. Feedstock constraints, regulatory validation demands, and the migration of fullerene materials into higher-value applications are reshaping the commercial terrain at a pace that rewards organizations with disciplined market intelligence. The projected expansion toward 600.0 million USD by 2032 is significant, but the strategic question is not simply how large the market will become. It is who will capture disproportionate value within it, under what purity and supply conditions, and through which application pathways.
Accessing the full market research report provides the depth required to answer those questions with confidence. It delivers the segment-level breakdowns, competitive context, and supply-and-regulation dynamics that executives need to align product roadmaps, procurement strategies, and partnership decisions with where the market is actually headed. For teams evaluating capital allocation, supplier qualification, or market-entry timing, this research offers a structured, evidence-based foundation for the decisions that will shape performance through 2032 and beyond.
Fullerene Market
For detailed analysis of this topic, please visit the official page: Fullerene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Carpet Tiles Market to Reach $17.29B by 2032, Growing at 5.12% CAGR
By PW Consulting, 2026-09-16
Navigating the Modular Carpet Tiles Market: Strategic Intelligence for 2026 and Beyond
The global flooring landscape is undergoing a structural transformation, driven by evolving workplace requirements, stringent sustainability mandates, and a renewed emphasis on circular material flows. Within this complex environment, modular carpet tiles have emerged as a critical solution for facility managers, architectural specifiers, and commercial real estate developers. As organizations align their procurement strategies with 2026 operational targets, understanding the precise trajectory of this segment is no longer optional. This executive overview introduces our latest market research on the Modular Carpet Tiles Market, outlining why a data-driven, forward-looking intelligence framework is essential for overcoming near-term volatility and capturing long-term value.
A Market Reaching a Strategic Inflection Point
Drawing on six years of historical tracking and a seven-year forward projection, our analysis reveals a market exhibiting consistent, compounding expansion. Between 2020 and 2025, global revenue crossed significant thresholds, with the baseline year registering $12.15 billion. The momentum continues unabated: 2026 is positioned at $13.01 billion, followed by a steady climb that places the market at $17.29 billion by 2032. This trajectory translates to a forecast compound annual growth rate of 5.12 percent, a figure that underscores durable demand rather than cyclical recovery.
For executives, these numbers carry more than macroeconomic relevance. They signal a market where growth is being unevenly distributed, shaped by product architecture, regional procurement policies, and the accelerating institutionalization of environmental product declarations. The reality is that aggregate expansion masks divergent performance across flexible and rigid formats, across commercial and residential end-use channels, and across regulatory jurisdictions that increasingly dictate which suppliers can scale efficiently. Navigating this landscape requires a granular comprehension of where capital is being deployed, which specifications are winning specification approvals, and how trade frameworks are recalibrating cost structures.
What Our Research Delivers: Operational Intelligence for 2026 Decision-Making
The full study is structured to convert macro indicators into actionable strategic playbooks. Rather than presenting static snapshots, the report maps the operational levers that will define competitive positioning over the 2026–2032 horizon. Key components include:
- A comprehensive sizing and forecasting model that decomposes historical performance and projects forward revenue across the entire modular carpet tiles ecosystem, enabling demand planning and capacity allocation with precision.
- Deep-dive segmentation analysis that evaluates product architecture, end-use deployment patterns, and regional consumption profiles, allowing leadership teams to isolate the highest-yield growth corridors and adjust portfolio emphasis accordingly.
- A competitive benchmarking framework that profiles major manufacturers, dissects their product pipelines, sustainability positioning, and commercial execution strategies, giving executives a clear view of where market share is being contested.
- A regulatory and certification tracker that monitors environmental product declarations, cross-border duty structures, and countermeasure tariffs, helping procurement and compliance teams anticipate cost shifts and specification friction before they impact margins.
- Sustainability and circularity mapping that evaluates advances in bio-based backings, recycled content integration, and take-back programs, aligning product development roadmaps with the specifications now dominating institutional tenders.
- Scenario-based guidance for 2026, offering leadership teams tested frameworks to adapt pricing, supply chain routing, and regional market entry strategies amid shifting trade policies and evolving end-user expectations.
Each section is engineered to support concrete decisions: whether evaluating a manufacturing expansion, repositioning a commercial sales force, adjusting logistics partnerships, or preparing for tender specifications that now require verified lifecycle documentation.
Carpet Tiles Market
Competitive Landscape: How Leading Players Are Positioning for the Next Cycle
The modular carpet tiles arena is characterized by a concentrated but highly dynamic competitive field. Our analysis tracks a core cohort of established manufacturers whose product architectures, sustainability commitments, and regional footprints actively shape market directionality. Understanding their strategic posture is essential for any organization planning capacity, pricing, or specification targeting in 2026.
Interface, headquartered in Atlanta, Georgia, continues to anchor its portfolio on modular carpet tiles featuring TacTiles installation systems and CQuest Bio backing technologies. The company’s operational philosophy is tightly coupled with its Mission Zero commitments and the ReEntry recycling program, positioning environmental accountability as a core commercial differentiator rather than a compliance add-on. Mohawk Industries, also based in Calhoun, Georgia, deploys modular offerings across the EcoFlex ONE, Matrix, and NXT lines, pairing commercial resilient flooring expertise with multiple optimized environmental product declarations that streamline specification in regulated procurement environments. Tarkett, operating from Méru, France, extends its modular carpet tile and plank portfolio with the Quiet Edit collection and circular solutions incorporating DESSO backing, specifically engineered for open-plan commercial spaces where acoustic performance and material circularity intersect.
EF Contract Flooring, based in the United States, manufactures the Advance and Nexus modular carpet tile families, utilizing PVC backing systems while maintaining EPD-compliant sustainable pathways that align with institutional procurement thresholds. Tapibel, headquartered in Belgium, emphasizes design flexibility and standardized 50x50 cm formats, delivering sustainable collections that bridge commercial and residential applications without sacrificing specification versatility. Shaw Contract, rooted in Dalton, Georgia, complements its modular carpet tile product line with broadloom options, reinforcing a USA-made performance flooring narrative that resonates with commercial buyers prioritizing supply chain reliability and localized manufacturing.
Recent corporate activity underscores how rapidly competitive positioning is evolving. In mid-2025, EF Contract Flooring refreshed the Nexus modular carpet tile environmental product declaration, updating version and validity dates to maintain compliance through 2029. Shortly thereafter, Interface issued a tufted modular carpet tile declaration for CQuest Bio backing, securing validity through 2030 under a recognized European certification body. EF Contract Flooring also advanced its Advance modular carpet tile documentation with an EPD appendix that remained active well into 2025. By early 2026, Tapibel published its 2026–2027 collection catalog, reinforcing its focus on sustainable modular formats and forward-looking design portfolios.
These movements are not isolated product announcements. They reflect a broader industry recalibration where documented lifecycle performance, material transparency, and portfolio agility are becoming decisive factors in specification wins and regional expansion. The full report quantifies how these developments influence share shifts, pricing tolerance, and the speed at which competitors can capture high-value commercial tenders.
Market Dynamics: Regulation, Certification, and the Redefinition of Trade Flows
The operational environment for modular carpet tiles is being reshaped by a convergence of policy instruments and certification requirements that directly affect cost structures, market access, and specification velocity. Our research integrates these dynamics into a cohesive framework so that executives can anticipate disruption rather than react to it.
Trade policy has emerged as a particularly sensitive variable for North American and cross-border supply chains. Current guidance confirms that US-origin modular carpet tiles classified under HS 5704 can qualify for a zero percent duty rate when imported into Canada under CUSMA/USMCA provisions, provided they satisfy applicable rules of origin. Yet this advantage operates alongside countermeasure measures: Canada has applied a temporary 25 percent tariff on certain US carpets, effective from March 2025. For manufacturers and distributors, this dual reality creates a complex compliance overlay where product classification, country of origin documentation, and final destination routing can materially alter landed cost and margin predictability.
Modular Carpet Tiles Market
Simultaneously, environmental product declarations have transitioned from voluntary differentiation to baseline expectation. Multiple manufacturers updated or issued EPDs throughout 2025, including Interface’s CQuest Bio backing declaration and EF Contract Flooring’s Nexus modular documentation. In Europe, Interface modular carpet tiles are now declared under EN 15804+A2, with issue dates tracked through September 2025. This regulatory and certification cadence matters because it determines which suppliers can efficiently participate in public tenders, institutional fit-outs, and corporate sustainability programs that increasingly demand verified environmental data as a precondition for evaluation.
Beyond compliance, product innovation continues to align with changing spatial requirements. Tarkett’s Quiet Edit carpet tile collection, for example, leverages repurposed materials aesthetics to serve commercial open spaces, reflecting a broader shift where visual identity, acoustic performance, and circular content are evaluated together during specification. These dynamic layers—trade rules, certification timelines, and product narrative evolution—are mapped in detail within the report, with scenario analysis illustrating how shifts in any one variable can cascade through pricing, share, and regional allocation strategies.
Why 2026 Demands a Different Decision Framework
The 2026 outlook is not simply another year in a growth curve. It represents a period in which historical assumptions about demand uniformity, sourcing flexibility, and specification tolerance are being tested simultaneously. Organizations that rely on aggregated market narratives will miss the structural divergences that determine actual performance. The modular carpet tiles market is expanding, but the value creation is increasingly tied to identifiable drivers: documented environmental performance, adaptive product formats, and supply chains capable of navigating overlapping trade and certification requirements.
This report is designed to give leadership teams a clear, quantitative, and strategically actionable foundation. It connects the $13.01 billion entry point of 2026 to the broader 2032 trajectory of $17.29 billion through a disciplined analytical lens, while deliberately preserving the detailed regional, application, and product-level breakdowns for the full intelligence package. That intentionality reflects how high-stakes decisions are made: executives need the directional confidence that the headline numbers provide, but they also require the granular evidence that supports resource allocation, partnership selection, and market-entry sequencing.
Access the Complete Strategic Intelligence
For senior executives, procurement leaders, and strategy teams preparing for the 2026–2032 cycle, the full study delivers the depth required to move from observation to execution. It provides the segmented forecasting detail, competitive scenario mapping, regulatory and certification tracking, and sustainability alignment analysis needed to shape pricing strategy, portfolio prioritization, and regional expansion plans with confidence.
To request the complete Modular Carpet Tiles Market research and gain access to the full dataset, segmentation breakdowns, and proprietary competitive assessments, visit the official research portal. The complete report is structured to serve as a decision-ready intelligence asset, enabling your organization to act on the market’s direction with precision rather than assumption.
For detailed analysis of this topic, please visit the official page: Modular Carpet Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: RF Filters Market Hits $12B in 2025, Poised for 15.7% CAGR Through 2032
By PW Consulting, 2026-09-16
Unlocking the $32.93 Billion Opportunity: A 2026 Strategic Outlook for the RF Filter Market
Radio frequency filters have evolved from passive components to strategic linchpins in the global electronics ecosystem. As we enter 2026, the industry stands at the convergence of explosive connectivity demands and geopolitically driven supply chain restructuring. Our latest research, PW Consulting's Radio Frequency Filters Market Analysis, provides executives with the definitive roadmap to navigate this complex landscape. By examining the trajectory from $12.0 billion in 2025 to a projected $32.93 billion by 2032, this report informs critical investment decisions in manufacturing capacity, supply chain resilience, and product portfolio prioritization.
The Macro Trajectory: A CAGR-Driven Growth Story
The market's expansion over the past five years has been characterized by relentless upward momentum, driven by the rollout of 5G infrastructure and the proliferation of connected devices. Current valuations build upon a historical foundation where revenue grew from $6.2 billion in 2020 to $12.0 billion in 2025, reflecting accelerated adoption rates across critical sectors. Looking forward, our forecast model projects a compound annual growth rate of 15.7% for the 2026-2032 forecast period, signaling a phase of structural expansion rather than transient hype. This growth engine is powered by multi-faceted demand signals, yet the specific allocation of capital across regions and application verticals reveals complex investment vectors that generic trade publications often overlook.
Segmentation Dynamics: Technology, Geography, and Application Vectors
Technology Displacement and Portfolio Shifts
The competitive battlefield is defined by the interplay between surface acoustic wave (SAW) dominance and the rising prominence of bulk acoustic wave (BAW) technologies in high-frequency bands. Ceramic and other specialized topologies continue to serve niche but indispensable roles in aerospace and defense applications. Understanding the precise revenue contribution and growth velocity of each technology type is essential for R&D allocation.
Regional Scrutiny and Localization Trends
Global revenue streams are distributed across major economic zones, with North America and Asia Pacific currently commanding significant share, while Europe and Latin America present distinct growth profiles. However, recent years have seen a tactical pivot toward regional supply-chain diversification, particularly in response to trade friction and export control mechanisms. This localization drive is reshaping procurement strategies for multinational OEMs, moving beyond pure cost optimization to ensure compliance and continuity.
Application Diversification Beyond Consumer Electronics
While consumer electronics remains a substantial revenue driver, the telecommunications infrastructure sector leads in terms of volume, fueled by base station deployments and backhaul upgrades. Automotive applications are experiencing a structural inflection point with the integration of advanced driver-assistance systems and in-vehicle connectivity, while aerospace and defense maintain high barriers to entry but offer lucrative, long-cycle contracts. Identifying the precise growth rates within these segments is vital for resource allocation.
Competitive Landscape: Market Concentration and Strategic Positioning
The market exhibits high concentration, with the top three players controlling over 55% of total revenue and the top five capturing approximately 75%. This oligopolistic structure necessitates careful competitor analysis for any firm seeking to gain share or defend position. Key incumbents such as Microchip Technology Inc. leverage comprehensive portfolios spanning aerospace, defense, communications, IoT, and automotive sectors, utilizing both SAW and discrete filter technologies. Microchip's footprint in Chandler, Arizona, underscores a U.S.-based manufacturing presence that aligns with onshoring trends.
In contrast, companies like Spectrum Control in Fairview, Pennsylvania, specialize in highly customizable RF solutions—including bandpass, lowpass, notch, cavity, ceramic, SAW, and glass filter topologies—that address demanding defense, aerospace, medical, and industrial requirements. TEMWELL Corporation, headquartered in Taipei, focuses on custom 5G RF microwave filters using helical, cavity, SMD, and SAW types to serve wireless communications, drones, automotive, aerospace, and military systems, representing the Asia Pacific manufacturing capability. Microwave Filter Company, Inc. (MFC) in East Syracuse leverages decades of heritage since 1967, producing cavity, coaxial, and waveguide filters tailored for satellite communications and defense. Qorvo, Inc., based in Greensboro, North Carolina, provides SAW and BAW filters supporting cellular, GPS, ISM, Bluetooth, and 5G bands, featuring proprietary LowDrift and NoDrift temperature compensation technologies.
Tuning Ingest for Recent Developments
Recent product and portfolio expansions illustrate the pace of innovation. In June 2024, Spectrum Control launched a new high-Q RF filter family utilizing wafer-scale manufacturing on glass substrates for surface-mount applications covering 500 MHz to 10 GHz, addressing the need for miniaturization and performance in next-generation systems. In October 2024, Qorvo expanded its BAW filter portfolio to support global 5G base station deployments, reinforcing the infrastructure boom. These moves signal that incumbents are aggressively capturing the demand wave, and new entrants or investors must anticipate the technical specifications and supply commitments being locked in by these initiatives.
Regulatory and Geopolitical Headwinds: The New Risk Matrix
No strategic assessment of the RF filter market in 2026 is complete without integrating the regulatory and geopolitical environment. In May 2024, the U.S. Department of Commerce revoked the export license under which Qorvo previously sold 4G and certain integrated circuit products to Huawei, marking a pivotal shift in technology transfer controls. This action has reverberated through supply chains, impacting component availability and end-market strategies for players reliant on specific regional demand. Furthermore, the FCC Second Report and Order in October 2025 prohibits authorization of any modular transmitter listed on the Covered List, tightening regulatory oversight on equipment integration and pushing manufacturers toward certified component architectures. The FCC online Table of Frequency Allocations was updated in April 2026, continuously reshaping spectrum management and filter design requirements for international compliance.
Beyond North America, U.S.-China trade tensions have prompted increased localization and supply-chain diversification efforts for RF filter components, compelling both buyers and suppliers to reassess sourcing strategies that were previously optimized solely for efficiency. Geopolitical tensions and export restrictions are also increasing vulnerability to regional trade barriers for critical materials such as gallium nitride (GaN) and ferroelectric compounds used in RF filter production, introducing raw material risk into the cost and availability models. These dynamics are not abstract; they directly influence capital allocation, inventory planning, and partnership ecosystems.
Inside the Market Research: What Decision-Makers Will Gain
This comprehensive study is designed to provide actionable intelligence rather than superficial market summaries. Executive stakeholders will find detailed breakdowns of market sizing across historical and forecast periods, including granular insights into revenue contributions by technology type, geography, and application segment—data that remains shielded here to encourage focused evaluation through our full report. Readers will also gain access to a thorough competitive benchmarking section, profiling major players with headquarters, technological focus areas, and product offerings, alongside an analysis of recent developments that highlight product launches, portfolio expansions, and strategic shifts.
Radio Frequency Filters Market
Radio Frequency Front-end Module Market
The report includes dedicated sections on market dynamics that untangle the impact of regulatory mandates, trade policies, and material supply constraints, providing a risk assessment framework for supply chain resilience. Furthermore, it maps out the concentration metrics and fragmentation trends that inform M&A potential and entry barriers. Professionals can utilize this intelligence to stress-test investment scenarios, benchmark their portfolio against high-growth niches, and align timing for capacity expansion or technology transitions with the 2026–2032 forecast window.
Conclusion: The Strategic Imperative for 2026
As the RF filter market accelerates from $14.19 billion in 2026 toward $32.93 billion by 2032, the window for decisive strategic positioning is open but narrowing. Companies that fail to integrate macro growth signals with granular segmentation intelligence, competitive maneuvers, and regulatory foresight risk misallocating resources in a market where concentration is high and margins are influenced by complex geopolitical variables. Our research equips leaders with the data-backed clarity needed to navigate this inflection point. We invite you to access the full PW Consulting Radio Frequency Filters Market Analysis to uncover the precise numerical insights, regional breakdowns, and application-specific projections that will anchor your 2026 strategy and beyond.
For detailed analysis of this topic, please visit the official page: Radio Frequency Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non-invasive Ventilation Masks Market Hits $215M in 2025, Projected 7.07% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Non-invasive Ventilation Masks Market: A 2026 Outlook
The global healthcare landscape is undergoing a profound transformation in respiratory care delivery. As hospitals face mounting pressure to optimize patient outcomes while managing resource constraints, Non-invasive Ventilation (NIV) masks have emerged as a critical interface between patients and life-sustaining therapy. The strategic importance of this market segment cannot be overstated, particularly as we navigate the complex regulatory, clinical, and competitive dynamics of 2026.
Recent market analysis reveals a trajectory of steady expansion that demands attention from executive leadership teams across the medical device ecosystem. The Non-invasive Ventilation Masks Market has demonstrated consistent growth over the historical period from 2020 through 2025, progressing from a valuation of USD 163.15 million to USD 215.0 million by the base year. Looking ahead to the forecast period spanning 2026 through 2032, the market is projected to reach USD 345.24 million, reflecting a compound annual growth rate of 7.07 percent. This sustained upward momentum signals more than mere market expansion—it represents a fundamental shift in how healthcare systems approach respiratory intervention, with significant implications for manufacturers, distributors, and healthcare providers alike.
Understanding the Market Architecture
The structural composition of the NIV masks market reveals distinct segments that each present unique strategic opportunities and challenges. In terms of product typology, the market encompasses nasal masks, full face masks, and total face masks, with each category serving specific clinical requirements and patient comfort parameters. The full face mask segment, including innovations such as bridge-free designs and vented/non-vented options compatible with both single-limb and dual-limb circuits, has garnered particular attention from manufacturers seeking to differentiate their portfolios through enhanced clinical efficacy and user experience.
Application-wise, the market addresses critical therapeutic areas including sleep apnea, chronic obstructive pulmonary disease, and acute respiratory distress syndrome. Each application domain carries distinct clinical priorities, reimbursement considerations, and adoption timelines that shape the competitive landscape. The sleep apnea segment represents a substantial portion of market activity, driven by growing awareness of sleep-disordered breathing and the expanding role of non-invasive ventilation in both home and hospital settings. Meanwhile, the chronic obstructive pulmonary disease and acute respiratory distress syndrome segments reflect the increasing integration of NIV therapy into acute care protocols and long-term respiratory management strategies.
Geographic distribution adds another layer of complexity to market analysis. The North American region has established a significant presence, supported by mature healthcare infrastructure and favorable reimbursement frameworks. European markets continue to demonstrate steady demand, while the Asia Pacific region represents a particularly dynamic growth arena characterized by expanding healthcare access, rising chronic disease prevalence, and increasing adoption of advanced respiratory technologies. Latin America and the Middle East and Africa markets, though currently smaller in scale, present emerging opportunities for organizations with the right strategic positioning and regional expertise.
Navigating Regulatory and Reimbursement Dynamics
The operational environment for NIV mask manufacturers and suppliers in 2026 is defined by an evolving regulatory framework and shifting reimbursement policies that directly impact market access and commercial viability. In the United States, the Centers for Medicare and Medicaid Services has taken notable steps to clarify coverage parameters for non-invasive interfaces. Under the June 2025 CMS policy, masks for home mechanical ventilators are covered when used for more than eight hours in any twenty-four-hour period in volume-targeted mode, or at night with an oronasal mask. Furthermore, the Medicare National Coverage Determination published on June 9, 2025, explicitly covers home respiratory assist devices and home mechanical ventilators with non-invasive interfaces for COPD patients, with NIV masks now included as eligible non-invasive interfaces for respiratory assist devices and home mechanical ventilators in home settings for chronic respiratory failure.
On the regulatory compliance front, single-patient use NIV masks must satisfy a rigorous set of requirements. Manufacturers are expected to secure FDA 510(k) clearance, achieve CE marking under the EU Medical Device Regulation, comply with ISO 10993 biocompatibility standards, and meet applicable sterilization requirements. These compliance obligations create both barriers to entry and competitive moats for established players with the resources and expertise to navigate complex regulatory pathways efficiently.
These dynamics have direct implications for product development roadmaps, go-to-market strategies, and partnership decisions. Organizations that proactively align their innovation pipelines with regulatory expectations and reimbursement realities will be better positioned to capture market share as the policy environment continues to mature.
Competitive Landscape and Innovation Trajectories
The competitive landscape in the NIV masks market is characterized by a mix of global medtech leaders, specialized respiratory care companies, and emerging innovators from diverse geographic markets. The market concentration metrics indicate a moderately fragmented environment, with the top three players accounting for approximately 24.6 percent of market revenue and the top five representing around 26.2 percent. This structure suggests that while scale players hold meaningful positions, there remains substantial room for differentiation, niche leadership, and technology-driven disruption.
Non-invasive Ventilation Masks Market
Fisher & Paykel Healthcare, headquartered in New Zealand, has established a prominent position through its focused portfolio of NIV mask solutions. The company's F&P Visairo bridge-free full face mask and F&P Nivairo full face mask, available in both vented and non-vented configurations and compatible with single- and dual-limb circuits, reflect a deliberate emphasis on clinical versatility and patient comfort. In September 2025, Fisher & Paykel Healthcare received FDA 510(k) clearance for its OptiNIV Vented Full Face Masks in sizes A through C, featuring an optional expiratory filter and compatibility with single-limb circuits for hospital NIV applications. Earlier that year, in February 2025, the company also secured FDA clearance for the Mariana Minerva and Mariana Nimbus ventilators, which provide non-invasive ventilation support for patients above 13 kilograms. These regulatory milestones underscore the company's commitment to expanding its respiratory care ecosystem through iterative innovation and strategic regulatory engagement.
ResMed, based in the United States, continues to leverage its strong brand recognition and clinical reputation in the respiratory device space. Its AirFit F20 NV non-vented full face mask, designed specifically for NIV therapy, exemplifies the company's focus on delivering reliable, clinically validated solutions for hospital and home care environments. In January 2026, REMSleep—a related entity within the ResMed ecosystem—submitted a supplemental 510(k) to the FDA to expand the DeltaWave CPAP mask indications for use with BiPAP and other positive pressure ventilation devices, as well as for institutional single-patient hospital use. This move signals a strategic push to broaden the therapeutic applications of existing mask platforms and strengthen the company's footprint in the NIV mask segment.
Philips, also headquartered in the United States, offers the AF541 NIV mask for hospital NIV applications, featuring interchangeable under-the-nose and over-the-nose options that provide clinicians with flexibility in fitting and therapy delivery. The company's broader ventilation portfolio and global distribution capabilities position it as a significant contender in the market, particularly in scenarios where integrated device ecosystems and multi-product account relationships are valued by procurement decision-makers.
Sleepnet Corporation and Intersurgical, operating from the United States and the United Kingdom respectively, collaborate on the VariFit NIV mask platform, which is available in both non-vented and vented configurations and incorporates AIR gel cushion technology for single-patient hospital use. This partnership model highlights how strategic alliances can accelerate product development, expand geographic reach, and combine complementary manufacturing and commercial capabilities.
Worldwide Non-invasive Ventilation (NIV) Masks Market
Additional players such as ApneaSeal in Australia and Inspirate in Singapore are exploring the custom NIV mask segment, addressing the clinical need for personalized fitting solutions that can improve seal integrity, patient compliance, and therapeutic outcomes. GaleMed Corporation, based in China, provides a broad range of NIV masks for non-invasive ventilation therapy, reflecting the growing presence of manufacturers from the Asia Pacific region in the global respiratory device market.
Strategic Considerations for Executive Decision-Makers
As organizations evaluate their positioning for the 2026 to 2032 forecast period, several strategic priorities merit careful consideration. First, the integration of regulatory intelligence into product planning cycles is no longer optional. The convergence of FDA clearance requirements, EU MDR compliance, biocompatibility standards, and evolving sterilization expectations demands a proactive compliance infrastructure that can anticipate changes and adapt product portfolios accordingly. Second, reimbursement dynamics will continue to shape demand patterns, particularly in home care segments where coverage policies directly influence patient access and purchase volumes. Organizations that develop deep expertise in reimbursement navigation and actively engage with payer stakeholders will gain a competitive advantage in markets where coverage uncertainty persists.
Third, the competitive environment rewards companies that can articulate clear clinical differentiation. Whether through bridge-free mask designs, advanced cushion technologies, customizable fitting options, or compatibility across diverse ventilator circuits, the ability to demonstrate measurable improvements in patient outcomes, caregiver efficiency, or total cost of care will be essential in securing formulary placements, hospital procurement approvals, and diagnostic channel partnerships. Fourth, geographic expansion strategies must be tailored to regional market characteristics, including regulatory maturity, reimbursement infrastructure, distribution channel dynamics, and local competitive intensity. A one-size-fits-all approach to international growth is unlikely to yield optimal returns in a market as heterogeneous as the NIV masks segment.
Finally, the moderate market concentration observed in the current landscape suggests that consolidation, strategic partnerships, and technology licensing agreements may reshape the competitive structure over the forecast period. Organizations should assess their M&A readiness, evaluate potential collaboration opportunities with complementary technology providers, and consider how emerging innovators might disrupt established value chains through novel approaches to mask design, material science, or digital integration.
Why Comprehensive Market Intelligence Matters
The executive decisions required to capture value in the Non-invasive Ventilation Masks Market extend far beyond high-level market sizing and headline growth rates. Successful strategic planning demands granular insights into segment-specific demand drivers, competitive positioning metrics, pricing and reimbursement trends, regulatory pathway nuances, and emerging technology adjacencies that could reshape the market over the next several years. It requires a detailed understanding of how leading manufacturers are structuring their product portfolios, which clinical indications are gaining traction in different care settings, and how procurement dynamics vary across hospital, home care, and sleep clinic channels.
The full market research report provides a comprehensive, data-driven analysis that goes well beyond the macro-level overview presented here. It delivers detailed segmentation analysis, forward-looking forecasts across multiple dimensions, in-depth company profiles that map strategic positioning and recent product and regulatory developments, and a thorough examination of the regulatory and reimbursement frameworks that will govern market access through 2032. The report also includes actionable recommendations for market entry, portfolio optimization, partnership strategy, and competitive response in an environment where technological innovation and regulatory agility are increasingly decisive factors.
For organizations seeking to make informed, confident decisions in the Non-invasive Ventilation Masks Market, the depth and granularity of available intelligence can be the difference between reactive positioning and proactive market leadership. Access the complete research to explore the full scope of market dynamics, competitive insights, and strategic pathways that will define respiratory care innovation in the years ahead.
For detailed analysis of this topic, please visit the official page: Non-invasive Ventilation Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Signage Market Hits $31.09B in 2025, Projected to Reach $53.98B by 2032 at 8.2% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the 2026 Digital Signage Landscape: Why This Market Report Matters
The digital signage market has crossed a critical inflection point. Between 2020 and 2025, global revenues scaled from 18.0 billion USD to 31.09 billion USD, marking a compound trajectory that reflects both post-pandemic recovery and the accelerating digitization of physical spaces. As enterprises map out their capital allocation and technology roadmaps for the 2026 to 2032 forecast period, understanding the underlying mechanics of this expansion is no longer optional. This market research report dissects the structural forces, competitive maneuvers, and regulatory shifts that will define portfolio decisions, vendor partnerships, and deployment strategies for the next seven years. Written to function as a decision-support instrument rather than a superficial market overview, the analysis is engineered to help leadership teams separate durable trends from short-lived hype.
Digital Signage Market
Market Architecture: Growth Patterns and Structural Edges
The headline trajectory is compelling, but the strategic value lies in the distribution of growth across the forecast horizon. Following a base year valuation of 32.82 billion USD in 2026, the market is projected to compound at an annualized rate of 8.2 percent, reaching 53.98 billion USD by 2032. This pace indicates that the sector is moving beyond early-adopter saturation into a phase where enterprise-grade reliability, content orchestration, and network scalability become the primary differentiators. The report frames this expansion through multiple analytical lenses, including hardware versus software mix shifts, deployment latency across commercial verticals, and the growing influence of infrastructure economics on total cost of ownership.
A deliberate omission of granular regional or application-level splits in this overview is intentional. Those splits are where procurement strategies, localization constraints, and channel dynamics create asymmetric opportunities. The full report isolates high-velocity pockets and slow-growth zones so that readers can align budget cycles, pilot programs, and channel partnerships with markets that match their risk tolerance and execution capacity. Rather than treating the market as a monolith, the study decomposes it into actionable layers that reveal where vendors are consolidating share, where pricing pressure is emerging, and where new entrants can still compete on differentiation instead of scale.
Competitive Arena: How Differentiated Capabilities Are Reshaping the Field
The competitive landscape is defined by a concentration ratio that leaves substantial room for specialization. With the top three players holding approximately 25 percent of market revenue and the top five controlling roughly 30 percent, the ecosystem remains broadly contested, allowing firms with focused value propositions to carve out defensible positions. The report profiles ten core companies whose strategic postures illustrate the range of approaches currently shaping buyer expectations and deployment models.
BrightSign continues to anchor its position through an end-to-end architecture centered on proprietary BrightSignOS players, integrated network management, and cloud services tailored for commercial and professional AV applications. Daktronics leverages its heritage in LED and LCD displays, networked public signage, and transportation-focused deployments to address environments where durability and visibility are non-negotiable. Scala has built its reputation on a scalable enterprise software platform that unifies content management with commerce integrations, a positioning that has only grown more relevant as signage networks are asked to perform as revenue-facing touchpoints rather than pure out-of-home displays.
Omnivex Corporation remains distinctive for software that manages and presents real-time information across signage networks in corporate and organizational settings, an approach that emphasizes operational messaging and data-driven scenario handling. Cisco Systems brings networking infrastructure, software-defined solutions, and integration expertise to the category, enabling deployments where connectivity, security, and room-level orchestration determine success. Samsung Electronics contributes commercial displays, spatial signage, and smart ecosystems aimed at retail and public applications, while LG Electronics extends the field with LED, OLED, and indoor/outdoor signage solutions that pair visual quality with Google Cast integration for hospitality and commercial environments.
Panasonic Corporation and Sony Corporation reinforce the professional display tier with signage technologies designed for demanding commercial and public spaces, and NEC Display Solutions rounds out the competitive set with display and signage solutions for enterprise and public applications. The report does not simply catalog product portfolios. It evaluates how each player is positioning against the same procurement requirements, where their roadmaps converge or diverge, and what their recent moves signal about the coming wave of buyer expectations.
2026 Signals: Recent Moves That Hint at the Next Cycle
Recent developments in early 2026 already illustrate the kind of capability escalation that buyers should track before committing to multi-year deployments. In January, BrightSign launched an enhanced BrightSign Control Plus device management solution ahead of InfoComm 2026, extending premium-tier remote management for its signage players and reinforcing the industry tilt toward centralized control and reduced field maintenance overhead. In February, Cisco Systems enabled digital signage functionality on Room Schedulers for Board, Desk, and Room Series devices, supporting non-booking activation and integration with Microsoft Teams Panel modes, a move that expands the addressable surface for signage within collaborative workplace environments.
In April, Scala announced a major release of its core digital signage platform, Scala Enterprise v13.60, enhancing capabilities for content management and enterprise deployments, while Daktronics introduced the Fuelight 5000 fuel price display product at its Sales Expo 2026 alongside product showcases for Galaxy LED signs and LCD networks. These releases are not isolated product updates. They reflect a broader pattern in which software manageability, real-time data integration, and vertical-specific hardware variants are becoming the levers that separate commodity deployments from sticky, long-term contracts. The full report maps each development to its likely impact on procurement cycles, integration requirements, and competitive displacement risk.
Digital Signage Design Services Market
Industry Dynamics: The External Pressures That Will Shape Deployment Economics
Market growth does not happen in a vacuum. Several external conditions are actively reshaping the cost base and compliance environment for digital signage networks. One of the most immediate pressures comes from infrastructure expense. Deployment costs for fiber-optic broadband infrastructure have increased by more than ten percent, with materials and labor driving the increase. Because digital signage performance, latency, and reliability are tightly coupled to network quality, this dynamic has direct implications for site readiness, rollout pacing, and total project economics. The report examines how procurement teams can anticipate these cost curves and adjust deployment sequencing accordingly.
Regulatory and tariff developments add another layer of uncertainty. A February 2026 U.S. Supreme Court ruling invalidated prior IEEPA-based tariffs, resulting in new ten percent global tariffs that affect digital signage hardware imports and deployments. For organizations planning international sourcing, multi-region rollouts, or long-lead hardware procurement, this shift alters landed-cost assumptions and inventory strategies. At the same time, the FDA updated guidance in 2026 to loosen regulatory requirements for certain digital health tools, expanding exemption scopes for low-risk digital signage applications in healthcare settings. This change opens the door to broader use of signage in clinical communication and patient-facing environments, but it also introduces new expectations around content governance and compliance documentation.
Broader infrastructure funding dynamics are also influencing the installation environment. FCC compliance requirements for digital infrastructure, including broadband equity funding under the IIJA, have driven state-level investments exceeding 628 million dollars in Montana alone for network deployments. While this figure reflects a single state, it illustrates the scale of public-sector network activity that can affect site availability, connectivity readiness, and the competitive landscape for commercial signage integrators. The study translates these moving parts into a structured view of risk and opportunity so that decision-makers can model scenarios rather than react after the fact.
What the Report Delivers: A Practical Toolkit for 2026 Decision-Making
This research is designed to support concrete planning rather than abstract observation. The full study combines quantitative forecasting with qualitative assessment of vendor strategy, buyer behavior, and operational constraints. It provides a structured basis for evaluating where digital signage investments can improve customer engagement, streamline communications, and support revenue-facing touchpoints, while also highlighting the operational realities that determine whether deployments scale cleanly or stall in pilot mode.
Readers will find detailed attention to segmentation dynamics, competitive positioning, and deployment feasibility across commercial environments. The analysis is built to answer the questions that typically surface during budget reviews and technology selection: which capability areas are becoming table stakes, which segments are likely to see the most intense pricing or differentiation pressure, and which external factors should be incorporated into risk-adjusted planning. The report also connects market evolution to vendor roadmaps, recent product releases, and regulatory developments so that leaders can assess not only what the market will look like, but what will be required to compete effectively within it.
To preserve analytical precision without overloading this introduction, the overview intentionally refrains from publishing the full set of regional and application-level figures. Those details are central to the report's differentiation because they expose where concentration is greatest, where growth is most defensible, and where specific buyer profiles are likely to dictate procurement terms. The complete intelligence is available on the source page, where the full segmentation analysis, competitive benchmarking, and scenario modeling can be reviewed in context.
Why This Matters for Executive Planning in 2026
The strategic imperative for 2026 is not simply to recognize that digital signage continues to expand. It is to understand how the market's composition, competitive intensity, and external cost environment are changing the terms of participation. The forecast period through 2032 suggests a market large enough to reward disciplined positioning, but only if organizations can align technology selection, deployment economics, and compliance awareness with the realities on the ground.
This report provides the framework to do that with greater confidence. It connects macro growth to the operational details that actually determine outcomes: hardware ecosystem choices, software manageability, network readiness, vendor differentiation, and regulatory exposure. For executives evaluating capital allocation, channel strategy, or product integration roadmaps, the research is structured to reduce uncertainty and support defensible decisions. The complete market intelligence, including segmented forecasts and embedded competitor analysis, is available on the source page for teams that want to move from high-level awareness to actionable planning.
For detailed analysis of this topic, please visit the official page: Digital Signage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Adiabatic Coolers Market to Hit $872M by 2032, 7% CAGR (2026-2032)
By PW Consulting, 2026-09-16
Navigating the Adiabatic Coolers Market: Strategic Intelligence for 2026 and Beyond
The global industrial and commercial cooling landscape is undergoing a fundamental shift. As energy costs rise and environmental regulations tighten, organizations are increasingly turning to adiabatic cooling technologies to balance thermal management requirements with sustainability mandates. PW Consulting's latest market research on the Adiabatic Coolers Market provides a comprehensive strategic roadmap for decision-makers navigating this evolving sector. This analysis synthesizes historical performance data, forward-looking projections, and competitive dynamics to equip stakeholders with actionable intelligence for the 2026-2032 forecast period.
Understanding the trajectory of this market requires more than surface-level observations. The transition from traditional evaporative systems to adiabatic solutions represents a structural change in how industries approach heat rejection, water conservation, and energy efficiency. Our research delves into the underlying drivers, constraints, and opportunities that will define competitive positioning over the next several years.
Market Trajectory and Growth Dynamics
The adiabatic coolers market has demonstrated consistent expansion over the past half-decade, reflecting broader trends in industrial automation, data center proliferation, and commercial building optimization. Historical analysis from 2020 through 2025 reveals a market that has matured significantly, with revenue scaling from approximately 385 million USD to 542 million USD. This growth trajectory underscores the accelerating adoption of water-saving cooling technologies across multiple sectors.
Looking forward, our forecasts indicate sustained momentum through 2032. The market is projected to reach 595.48 million USD in 2026, continuing its upward path to approximately 872.0 million USD by the end of the forecast horizon. This progression reflects a compound annual growth rate of 7.0 percent, signaling robust demand underpinned by technological advancements and regulatory tailwinds. However, growth is not uniform across all segments or regions, and strategic allocation of resources requires nuanced understanding of where value is being created.
Several macroeconomic and operational factors are converging to accelerate this expansion:
- Rising energy prices are driving facility managers to prioritize systems that reduce electrical consumption while maintaining cooling capacity
- Water scarcity concerns in key industrial regions are making low-water-use cooling solutions increasingly attractive compared to conventional evaporative alternatives
- Environmental regulations, including California's Title 24 requirements for CO2 CDUs in supermarket systems effective 2026, are introducing compliance considerations that influence equipment selection and system design
- The Cooling Technology Institute's development of thermal performance certification programs for adiabatic fluid coolers, anticipated to launch under CTI Standard 201, is expected to enhance transparency and standardization in performance claims
Competitive Landscape and Key Players
The adiabatic coolers market exhibits notable concentration, with the top three firms capturing approximately 65 percent of total revenue and the top five accounting for roughly 75 percent. This consolidated structure suggests mature competitive dynamics where scale, technological differentiation, and regional presence play critical roles in market share retention. Our research provides detailed profiling of the companies shaping this landscape, examining their product portfolios, strategic positioning, and recent developments.
In the United States, several established players continue to drive innovation in adiabatic cooling solutions. SPX Cooling Technologies, headquartered in Overland Park, Kansas, offers the Marley and Recold Adiabatic Series, which combines water-saving benefits with energy efficiency for commercial and industrial refrigeration applications. Baltimore Aircoil Company, based in Jessup, Maryland, has gained attention for its TrilliumSeries Adiabatic Cooler and hybrid systems designed for efficient cooling with reduced water and energy consumption. EVAPCO, also located in Baltimore, Maryland, has expanded its eco-Air Series with the Titan, recognized as the largest adiabatic cooler in its lineup, featuring pumpless recirculation and pre-cooling capabilities for process cooling applications.
European manufacturers are equally active in advancing adiabatic cooling technology. MITA Cooling Technologies, based in Italy, provides adiabatic dry coolers with pre-cooling systems tailored for industrial HVAC and energy-efficient operation across Europe and the Americas. Kelvion, headquartered in Germany, offers adiabatic condensers and dry coolers utilizing spray or pad systems capable of achieving 10°C air cooling. Torraval Cooling, from Spain, focuses on compact adiabatic coolers and subcooler series designed to deliver quick return on investment for refrigeration applications. Frigel, based in Florence, Italy, specializes in intelligent process cooling equipment, including adiabatic systems for plastics and broader industrial applications. GEA Group, located in Düsseldorf, Germany, provides process cooling systems with adiabatic solutions for food processing and industrial heat rejection.
Alfa Laval, headquartered in Lund, Sweden, rounds out the competitive field with its Abatigo Adiabatic Liquid Coolers, which incorporate patented pre-cooling sections suitable for data centers and industrial use. These companies represent the vanguard of adiabatic cooling innovation, and our report includes in-depth assessments of their strategic moves, product launches, and market activities.
Recent developments highlight the pace of innovation in this sector. EVAPCO released the Titan in September 2025 as the largest adiabatic cooler in its eco-Air Series, signaling continued investment in scaling capacity for demanding applications. Baltimore Aircoil Company demonstrated its TrilliumSeries Adiabatic Cooler at the 2025 AHR Expo, reinforcing its commitment to showcasing hybrid cooling solutions at major industry events. Meanwhile, the Cooling Technology Institute has been developing a thermal performance certification program for adiabatic fluid coolers, with anticipated launch in the first half of 2025 under CTI Standard 201, covering forced and induced draft adiabatic fluid coolers for water or aqueous glycol solutions. These milestones illustrate the dynamic nature of the market and the importance of staying informed about product evolution and standardization efforts.
Segmentation Insights and Application Trends
The adiabatic coolers market spans multiple technology types and application verticals, each with distinct growth drivers and adoption patterns. Our research segments the market by type, application, and region to provide a granular view of where demand is concentrated and how it is evolving.
Worldwide Adiabatic Demagnetization Refrigerators (ADR) Market
By technology type, the market includes dry air coolers and liquid coolers, both of which serve critical roles in industrial and commercial cooling architectures. Dry air coolers have gained prominence in applications where water conservation is a priority, while liquid coolers remain essential for processes requiring precise temperature control and high thermal capacity. The segmentation analysis reveals how these technologies are being deployed across different end-use scenarios and what factors influence procurement decisions.
In terms of application, industrial and commercial sectors represent the primary demand drivers. Industrial applications, encompassing process cooling, manufacturing heat rejection, and large-scale facility management, account for the dominant share of market revenue. Commercial applications, including data centers, commercial buildings, and retail refrigeration systems, are expanding as organizations seek to comply with energy codes and reduce operating expenses. The interplay between these application segments and regional deployment patterns provides valuable context for market entry strategies and product positioning.
Regional dynamics further shape the competitive environment. North America and Europe represent mature markets with established infrastructure and regulatory frameworks that favor energy-efficient cooling solutions. Asia Pacific, Latin America, and the Middle East and Africa present emerging opportunities where industrialization, data center growth, and climate conditions are driving demand for advanced cooling technologies. Our report examines these regional variations in detail, identifying where growth is accelerating and what barriers exist to adoption.
Strategic Value for 2026 Decision-Making
In an environment characterized by rapid technological change, regulatory uncertainty, and intensifying competition, access to reliable market intelligence is not a luxury—it is a strategic necessity. PW Consulting's Adiabatic Coolers Market report is designed to support decision-makers across multiple functions, from product development and investment planning to competitive positioning and risk assessment.
For executives evaluating market entry or expansion opportunities, the report provides a foundational understanding of market size, growth trajectories, and segmentation dynamics. This macro-level perspective enables informed resource allocation and helps identify the most promising avenues for investment. For product managers and engineering teams, detailed technology assessments and competitive benchmarking offer insights into feature differentiation, performance standards, and emerging customer requirements. Procurement and supply chain leaders can leverage the analysis to anticipate price trends, evaluate supplier landscapes, and mitigate risks associated with raw material costs and component availability.
The report also addresses the regulatory and compliance dimensions that are increasingly shaping purchasing decisions. With standards such as CTI Standard 201 gaining prominence and regional requirements like California's Title 24 imposing new constraints on adiabatic gas coolers in supermarket systems, organizations must navigate a complex compliance landscape. Our research synthesizes these regulatory developments and their implications for product design, system integration, and market access.
Key areas where this research delivers strategic value include:
- Identifying high-growth segments and regions where competitive intensity is still developing, enabling first-mover advantages
- Understanding the technological differentiators that matter most to customers, from pre-cooling capabilities to material specifications such as 304L stainless steel tubing and aluminum fins
- Assessing the impact of water-use considerations on equipment selection, as adiabatic models use water only when ambient conditions and load require it, offering flexibility in operating modes for utility savings
- Evaluating the competitive positioning of key players based on their product portfolios, geographic reach, and recent strategic initiatives
- Anticipating the effects of certification programs and regulatory changes on market dynamics and compliance costs
Why This Research Matters Now
The adiabatic coolers market is at an inflection point. Technological improvements, regulatory shifts, and evolving customer expectations are converging to create both opportunities and challenges for market participants. Organizations that proactively understand these dynamics will be better positioned to capitalize on growth, manage risks, and build sustainable competitive advantages.
Adiabatic Coolers Market
Our report goes beyond high-level summaries to deliver the depth and granularity required for confident decision-making. It integrates historical data, current market conditions, and forward-looking projections into a cohesive analytical framework. By examining the strategies of leading companies, the evolution of technology types, and the forces shaping regional demand, the research provides a comprehensive view of the market ecosystem.
Stakeholders who rely on fragmented information or outdated assumptions risk misallocating resources, missing emerging opportunities, or underestimating competitive threats. PW Consulting's market research equips organizations with the intelligence needed to make informed choices about product development, market expansion, partnership strategies, and investment priorities.
Accessing the Full Intelligence Package
This article provides a strategic overview of the adiabatic coolers market and highlights the core themes explored in our comprehensive research report. However, the full depth of our analysis—including detailed segmentation data, regional breakdowns, competitive assessments, and methodological rigor—requires access to the complete publication. The nuanced insights that drive strategic decisions are embedded throughout the report, and we encourage stakeholders to obtain the full document to ensure they have the most complete picture of market dynamics.
As the adiabatic cooling sector continues to evolve, staying ahead of trends and understanding the competitive landscape will be essential for sustained success. PW Consulting is committed to delivering market intelligence that meets the highest standards of accuracy, relevance, and actionable value. For organizations seeking to navigate the complexities of the 2026-2032 period with confidence, our adiabatic coolers market research offers the foundation for informed, strategic action.
For detailed analysis of this topic, please visit the official page: Adiabatic Coolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com