

Blogs
PW Consulting Proline Market Report: $595.9M in 2025, Projected $907.91M by 2032, 6.65% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the L-Proline Market: Navigating Growth and Complexity in 2026 and Beyond
The global amino acid landscape is undergoing a structural transformation, driven by shifting consumer preferences, evolving pharmaceutical demands, and increasingly complex supply chain economics. At the center of this evolution lies L-proline, a non-essential amino acid that has quietly transitioned from a specialized biochemical intermediate to a strategic commodity with broad industrial, nutritional, and therapeutic applications. As enterprises recalibrate their market positioning and supply chain resilience strategies for the coming years, decision-makers require more than surface-level industry commentary. They need granular, forward-looking intelligence grounded in rigorous primary research and validated market modeling.
Our newly released Proline Market report delivers precisely that. Designed for executives, strategy planners, procurement leaders, and investment analysts, this study maps the trajectory of the global L-proline sector across a comprehensive historical and forecast horizon. The findings illuminate not only where the market has been, but where it is structurally headed, providing a decision-ready framework for navigating volatility, capturing emerging demand, and executing competitive positioning with precision.
The 2026 Decision Imperative: Why Timing and Context Matter
Market entry, capacity expansion, partnership formation, and procurement strategy all depend on accurate contextual awareness of macroeconomic and sector-specific dynamics. For L-proline, the convergence of several forces creates a uniquely critical planning window for 2026. Post-pandemic supply chain recalibration has forced manufacturers to reevaluate sourcing dependencies, while rising demand for non-animal-derived ingredients, sports nutrition formulations, and pharmaceutical intermediates has accelerated product development cycles across multiple downstream industries.
The structural shift toward plant-based and fermentation-derived amino acid production continues to reshape cost architectures and competitive moats. Simultaneously, regulatory scrutiny around raw material sourcing, manufacturing transparency, and quality standardization is elevating compliance from a back-office function to a boardroom priority. In this environment, strategic decisions made without a clear view of market velocity, concentration patterns, and application-level demand trajectories carry heightened risk.
Our analysis is calibrated to this reality. By anchoring projections in a multi-year historical baseline and extending the forecast through 2032, the report provides a disciplined, evidence-based pathway for leaders who must act decisively rather than speculate.
Proline Market
Market Trajectory and Structural Signals
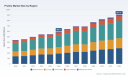
The global L-proline market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately $441 million in 2020 to an estimated $596 million in 2025. This growth reflects sustained demand across health and dietary supplement formulations, animal feed nutrition, and pharmaceutical synthesis pathways. Looking ahead, the market is projected to advance at a compound annual growth rate of 6.65 percent, reaching a valuation of roughly $643 million in 2026 and continuing its upward trajectory toward approximately $908 million by 2032.
Several structural signals underpin this momentum. First, downstream demand for amino acid-enabled formulations has broadened beyond traditional food and beverage applications. Nutritional science advancements, clinical research into amino acid metabolism, and consumer wellness trends have collectively expanded the addressable market for proline-based compounds. Second, manufacturing innovation—particularly in fermentation efficiency, strain optimization, and downstream purification—has improved yield economics and expanded grade flexibility for industrial buyers. Third, manufacturing geography continues to evolve, with production capacity increasingly distributed across major industrial corridors to mitigate single-region risk exposure.
For strategic planners, these trends carry actionable implications. Procurement teams must assess whether incumbent suppliers can sustain cost competitiveness as fermentation technology scales. Product developers need visibility into grade availability, purity specifications, and regulatory status across target applications. Investors and corporate development teams require clarity on concentration dynamics, capacity expansion signals, and the pace at which emerging players can scale. Our report addresses each of these dimensions with targeted analysis designed for execution.
Worldwide Prolactin Market
What the Proline Market Report Delivers
This study is engineered for practical use, not academic abstraction. It provides a complete analytical architecture that organizations can integrate directly into forecasting models, market entry evaluations, competitive benchmarking, and supply chain planning workflows. The report covers:
- Historical performance tracking (2020–2025): Year-over-year revenue progression, volume and value trends, and macroeconomic demand drivers that shaped the baseline period.
- Forward-looking forecast (2026–2032): Market size projections, growth rate trajectories, and structural inflection points that decision-makers should monitor as planning horizons extend.
- Type segmentation analysis: A detailed comparison of plant-based and animal-based proline supply streams, including production methodology distinctions, grade suitability, cost structures, and demand migration patterns across end-use sectors.
- Application-level demand mapping: Cross-sector evaluation of how proline is deployed in health and dietary supplements, animal feed, and pharmaceutical formulations, with emphasis on consumption drivers, formulation trends, and regional purchasing behavior.
- Regional market intelligence: Assessment of demand concentration, supply chain geography, trade dynamics, and localization trends across key industrial markets, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive landscape profiling: Detailed company profiles, operational focus areas, production capabilities, and strategic positioning of leading manufacturers and emerging participants.
- Concentration and competitive intensity metrics: Structured analysis of market share distribution among top-tier players, indicating where consolidation pressure exists and where fragmentation creates entry or disruption opportunities.
Each section is designed to enable direct integration with internal strategy processes. Whether your team is evaluating supplier diversification, assessing a potential M&A target, modeling product launch scenarios, or stress-testing cost assumptions against raw material volatility, the report provides a defensible foundation for those decisions.
Competitive Dynamics and the Manufacturing Frontier
The L-proline competitive landscape reflects a blend of established multinational amino acid producers, specialized fermentation manufacturers, and regional players with strong downstream integration. The market’s top three participants collectively account for approximately 48.5 percent of revenue, while the top five extend their combined share to roughly 62.3 percent. This concentration profile indicates a market with clear incumbency advantages in scale, process know-how, and downstream customer relationships, but also suggests room for competitive repositioning as regional capacity expands and application-specific demand fragments.
Leading manufacturers demonstrate distinct strategic orientations. Ajinomoto Co., Inc., headquartered in Tokyo, Japan, has built its proline capability around industrial-scale fermentation processes designed for bulk amino acid supply across food, pharmaceutical, and nutrition channels. Evonik Industries AG, based in Essen, Germany, positions L-proline as a non-animal-derived, non-essential amino acid available in multiple industrial grades, serving feed, pharmaceutical, and specialty applications. Meihua Holdings Group Co., Ltd., operating from China, leverages corn fermentation routes to supply proline as an upstream raw material for human medical purposes, sports nutrition food, and special medical applications. KYOWA HAKKO BIO CO., LTD., also based in Tokyo, focuses on amino acid manufacturing including related proline compounds through innovative industrial fermentation methods.
Regional production capability continues to deepen. Sichuan Tongsheng Amino Acid Co., Ltd. manufactures L-proline as part of a broader amino acid portfolio targeting food, pharmaceutical, and animal nutrition markets. Zhejiang NHU Co., Ltd. produces L-proline through fermentation for use in the food industry, human medical purposes, and pharmaceutical intermediates. Shijiazhuang Jirong Pharmaceutical Co., Ltd. supplies L-proline as upstream raw material for drugs treating chronic diseases and related pharmaceutical applications. Together, these participants illustrate how proline manufacturing is not only a commodity play but also a capability-dependent business where fermentation efficiency, grade versatility, and downstream integration shape competitive durability.
Strategic buyers and competitors should pay close attention to how these manufacturers differentiate on grade availability, scale economics, supply reliability, and regulatory alignment. In a market where certain amino acids have become increasingly problematic due to high inclusion rates, elevated pricing, limited global production volumes, or manufacturing complexity, proline’s relative positioning depends on continued process optimization and supply chain transparency. The report provides structured evaluations that help organizations determine which suppliers can support long-term contractual commitments and which represent tactical sourcing options under specific demand scenarios.
Raw Material Pressures and the Cost Architecture Reality
No analysis of the L-proline market is complete without addressing input-side economics. Amino acid manufacturing remains highly sensitive to feedstock pricing, fermentation yield variability, downstream purification costs, and logistics exposure. Industry assessments have highlighted that six amino acids—serine, glutamine, asparagine, histidine, proline, and arginine—have emerged as particularly challenging due to a combination of high inclusion rates, elevated prices, low global production volumes, and manufacturing complexity.
This context matters because cost pressure is rarely uniform across the amino acid portfolio. For proline specifically, competitive advantage increasingly hinges on production efficiency, feedstock flexibility, and the ability to deliver consistent grade quality at scale. Organizations that rely on proline as an upstream input for pharmaceutical synthesis or nutrition formulations must understand how cost volatility transmits through their supply chain and where strategic buffers, alternative sourcing arrangements, or specification adjustments can preserve margin integrity.
Our report integrates these dynamics into the broader market framework, examining how raw material exposure, production complexity, and regional capacity trends interact with pricing behavior and buyer negotiation leverage. Rather than offering static cost snapshots, the analysis maps the structural variables that will shape procurement economics and manufacturing competitiveness over the forecast period.
Why This Report Is Built for 2026 Strategy Execution
Decision-making in 2026 will be shaped by the intersection of demand expansion, supply chain recalibration, technological advancement in fermentation, and increasing transparency requirements across food, nutrition, and pharmaceutical value chains. In that environment, organizations need intelligence that is simultaneously broad enough to capture macro momentum and precise enough to guide category-level actions.
The Proline Market report is structured to meet that standard. It combines historical validation with forward-looking forecasting, maps competitive and application-level dynamics, and provides the analytical scaffolding necessary to translate trend observation into strategic action. More importantly, it preserves strategic discretion: by identifying where the largest decision-relevant opportunities and risks reside, it helps leaders prioritize the questions that matter most before committing capital, capacity, or commercial resources.
Access the Full Intelligence Architecture
The complete Proline Market report extends well beyond the strategic overview presented here. It contains detailed segmentation breakdowns, regional demand and supply mappings, company-level capability assessments, and forecast scenarios designed for internal planning, investment evaluation, and procurement strategy. For teams that require defensible numbers, structured competitive context, and actionable market direction, the full study is the necessary reference point.
To access the complete dataset, segmentation detail, and full competitive profiles, visit the Proline Market research page on the PW Consulting platform. There, you can review the full scope of the analysis, evaluate the report against your internal planning requirements, and secure the intelligence needed to make 2026 and beyond decisions with confidence.
For detailed analysis of this topic, please visit the official page: Proline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China Optical Sensing Market has exhibited consistent revenue growth from 2020 to 2025, driven by surge in demand for industrial automation, healthcare diagnostics, and smart city projects. Market revenue is forecast to accelerate further as smart manufacturing and digital health trends advance, surpassing USD 5,200 Million by 2025 and potentially reaching over USD 14,800 Million by 2035 amidst continuous technology adoption and production innovation.
Read More - https://bussinessinsights.com/research-report/china-optical-sensing-market
Healthcare remains the dominant application segment in China’s optical sensing market, propelled by rising deployment of biosensors and photonic devices in hospitals and research settings. The automotive sector is rapidly closing in, leveraging optical sensing for ADAS and autonomous vehicle technologies. Industrial applications are seeing accelerated adoption of distributed sensing solutions for process optimization. Consumer electronics contribute a significant share, emphasizing integration of miniature image sensors, while aerospace and defense applications maintain a niche but stable presence.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-optical-sensing-market
Frequently Asked Questions
Who are the key players in China Optical Sensing Market industry?
The top 5 players in the China Optical Sensing Market are Finisar Corporation, Oclaro Inc., Honeywell International Inc., Hamamatsu Photonics K.K., and Vishay Intertechnology, Inc. These companies excel in innovation, broad product portfolios, and strategic partnerships, driving advancements in optical sensors across telecommunications, healthcare, and automotive sectors.
What is the China Optical Sensing Market growth?
The China Optical Sensing Market is projected to grow at a CAGR of over 10% from 2023 to 2028, driven by increasing adoption of smart sensors in industrial automation and IoT devices. Recent investments by Honeywell in optical sensor manufacturing have further contributed to robust market growth.
Which segment accounted for the largest China Optical Sensing Market share?
Telecommunications applications hold the largest share of the China Optical Sensing Market. Growing demand for high-speed data transmission and expansion of 5G networks have led to increased deployment of optical sensors, especially for fiber optic communication and network monitoring solutions.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The China 3D Printing Market has demonstrated remarkable growth, starting from USD 940 Million in 2020 and projected to reach USD 5,800 Million by 2035. This expansion is fueled by continuous advancements in technology, regulatory support, and a surge in applications across diverse industries. The period from 2025 to 2030 is expected to contribute the fastest growth, coinciding with large-scale digital transformation in Chinese manufacturing, and the mainstream adoption of 3D printing in healthcare and education.
Read More - https://bussinessinsights.com/research-report/china-3d-printing-market
The application landscape for China's 3D printing market in 2025 is dominated by the Industrial sector with 32%, driven by widespread adoption in manufacturing and tooling. Automotive applications secure a 25% share, followed by Healthcare at 18%, reflecting rising medical device and dental solutions. Aerospace & Defense account for 12%, benefitting from advanced material developments. Consumer Electronics and Education segments represent 9% and 4%, respectively, as accessibility to 3D printing in schools and consumer product prototyping increases.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-3d-printing-market
Frequently Asked Questions
Who are the key players in China 3D Printing Market industry?
The top 5 players in the China 3D Printing Market are Shining 3D, Farsoon Technologies, UnionTech, Shenzhen Kings 3D Printing Technology, and Hanbang 3D. These companies are industry leaders, offering advanced solutions in additive manufacturing, including dental, industrial, and prototyping applications across diverse sectors in China.
What is the China 3D Printing Market growth?
The China 3D Printing Market has experienced robust growth, with a CAGR over 20% in recent years. Key drivers include expanding adoption in automotive and healthcare, with UnionTech reporting record revenues through its industrial-grade 3D printers, reflecting rapid market penetration and scaling production capacities.
Which segment accounted for the largest China 3D Printing Market share?
The largest market share is held by the industrial and manufacturing segment. Driven by demand for rapid prototyping and complex part production, companies such as Farsoon Technologies support automotive and aerospace industries, enabling mass customization and efficient product development cycles using additive manufacturing technologies.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Combustion Controls, Equipments & Systems Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
Revenue for China’s Combustion Controls, Equipments & Systems market is projected to grow steadily from USD 3,700 Million in 2020 to USD 7,150 Million in 2035. The growth is driven by widespread industrial upgrades, strict emission standards, and adoption of digital technologies. In 2025, market revenue is estimated at USD 4,750 Million, underlining the country’s strong pace of modernization and investments in advanced control equipment.
Read More - https://bussinessinsights.com/research-report/china-combustion-controls,-equipments-and-systems-market
By application, Power Generation is the leading segment, accounting for nearly a third of the market as utilities modernize their combustion equipment for efficiency and emission control. The Cement Industry is next, reflecting the sector’s energy-intensive nature and need for regulatory compliance. Metal & Mining, Chemical Industry, and Food & Beverages represent significant shares, with increasing automation and energy-saving initiatives. The data underscores China’s industrial transformation and its push towards cleaner, smarter manufacturing.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-combustion-controls,-equipments-and-systems-market
Frequently Asked Questions
Who are the key players in China Combustion Controls, Equipments & Systems Market industry?
The top five key players in the China Combustion Controls, Equipments & Systems Market are Honeywell International Inc., Siemens AG, ABB Ltd., Mitsubishi Hitachi Power Systems Ltd., and Yokogawa Electric Corporation. These companies lead through advanced technology offerings, extensive distribution networks, and ongoing investments in R&D for combustion solutions.
What is the China Combustion Controls, Equipments & Systems Market growth?
The China Combustion Controls, Equipments & Systems Market is witnessing robust growth, driven by a focus on energy efficiency and strict emission regulation policies. For instance, Honeywell has reported significant project wins in China due to growing industrial demand for modern combustion optimization and emissions control.
Which segment accounted for the largest China Combustion Controls, Equipments & Systems Market share?
The industrial segment, particularly the power generation application, accounted for the largest market share. This is attributed to China’s large-scale investments in electricity infrastructure and modernization of existing thermal power plants requiring advanced combustion control systems for efficiency and emissions compliance.
Thanks & Regards,
priya
sales@bussinessinsights.com
China’s 5G chipsets market is set for exponential growth, with revenue expected to rise from $5,200 Million in 2020 to approximately $38,500 Million by 2035. The trajectory is supported by aggressive nationwide 5G deployments, government subsidies for R&D, and robust demand for next-generation connected devices. A sharp acceleration is expected from 2025 onwards as large-scale applications in automotive, industrial, and IoT domains gain commercial traction. Local champions and joint ventures with international players are key to scaling ecosystem capabilities and sustaining double-digit revenue growth rates through the forecast period.
Read More - https://bussinessinsights.com/research-report/china-5g-chipsets-market
Smartphones remain the leading application for 5G chipsets in China in 2025, representing the widest adoption base as the country continues leading in 5G-enabled mobile devices. The industrial automation segment is rapidly emerging as the second-largest category, driven by the expansion of smart factories and manufacturing digitization. Connected vehicles and IoT devices each hold a considerable share, underscoring China's ambition to lead globally in intelligent transportation, automotive innovations, and pervasive connectivity for smart cities and enterprises. The market’s application diversity highlights its foundational role in China’s digital transformation agenda.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-5g-chipsets-market
Frequently Asked Questions
Who are the key players in China 5G Chipsets Market industry?
The top 5 players in China's 5G chipsets market are Huawei Technologies, Qualcomm, MediaTek, UNISOC, and Samsung. Huawei leads innovation and large-scale deployment; Qualcomm and MediaTek offer advanced commercial 5G solutions; UNISOC provides competitive domestic alternatives; Samsung supplies chipsets for high-end 5G devices.
What is the China 5G Chipsets Market growth?
The China 5G chipsets market is experiencing rapid growth, with CAGR exceeding 25% from 2021 to 2024. Factors include heavy investments by Huawei in R&D, and rising 5G smartphone penetration. MediaTek reported record shipments in H2 2023, showcasing active market expansion and adoption.
Which segment accounted for the largest China 5G Chipsets Market share?
The smartphone segment holds the largest share in the China 5G chipsets market. With the launch of affordable 5G phones by brands like Xiaomi and Oppo, demand has surged. Smartphone integration of 5G chipsets fuels market share, reflecting China's ambitious 5G device rollout in 2023.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The market revenue for explosion-proof lighting in China is projected to increase steadily from 2020 through 2035. In 2025, the market is estimated at $766 million, rising to $1,325 million by 2030, and reaching approximately $2,280 million in 2035. Growth is fueled by industrial expansion, stricter safety protocols, and the transition from traditional systems to advanced LED and smart lighting. Consistent investments from key sectors including energy and chemicals ensure a strong growth trajectory, underpinned by technological advances and sectoral modernization.
Read More - https://bussinessinsights.com/research-report/china-explosion-proof-lighting-market
Oil & gas remains the primary application sector for explosion-proof lighting in China, accounting for more than a third of market share in 2025. The mining industry follows, supported by ongoing resource extraction activities, while manufacturing and processing facilities increasingly adopt explosion-proof solutions amid evolving safety mandates. Other application areas—energy, pharmaceutical, and miscellaneous industries—collectively show growing adoption as awareness of regulatory and insurance policies increases. This robust demand from high-risk sectors provides a stable foundation for continued market expansion over the next decade.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-explosion-proof-lighting-market
Frequently Asked Questions
Who are the key players in China Explosion-proof Lighting Market industry?
The top five key players in the China Explosion-proof Lighting Market include Ocean's King Lighting, Shenzhen Nibbe Technology, Hongyuan Photonics, CNLIGHT, and Feice Explosion-proof Electric. These companies are renowned for delivering high-quality explosion-proof lighting solutions across industrial, oil & gas, and mining sectors, driving innovation and safety standards.
What is the China Explosion-proof Lighting Market growth?
The China Explosion-proof Lighting Market has experienced significant growth, projected to expand at a CAGR of over 7% from 2023 to 2028. This growth is driven by increasing industrial safety regulations and large-scale manufacturing investments, with leading companies like Ocean's King Lighting spearheading technological advancements.
Which segment accounted for the largest China Explosion-proof Lighting Market share?
The oil & gas industry segment accounts for the largest share in the China Explosion-proof Lighting Market. Due to extensive demand for safe lighting solutions in hazardous environments, explosion-proof lighting is extensively deployed in oil refineries, petrochemical plants, and related applications to ensure workplace safety.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The market revenue of the China Telecom Power System sector is set for significant growth, with revenues estimated at USD 4,200 million in 2025, up from USD 2,950 million in 2020 and projected to reach approximately USD 9,800 million by 2035. This robust increase is attributed to ongoing infrastructure upgrades, widespread 5G and fiber rollout, and the adoption of energy-efficient and renewable solutions. Leading vendors are intensifying investments in innovation to cater to rising power loads and sustainability requirements, ensuring the market’s upward trajectory over the forecast period.
Read More - https://bussinessinsights.com/research-report/china-telecom-power-system-market
Wireless Communication remains the leading application category in 2025, reflecting the rapid proliferation of mobile networks, especially with 5G’s expansion. Enterprise Networks and Data Centers follow, with the surge in digital services, cloud computing, and edge processing driving robust power requirements. Broadband/Data Communication and other applications maintain significant roles as telecom infrastructure broadens to support high-speed internet and new use-cases. This diverse application landscape emphasizes the need for versatile and reliable power solutions tailored to different telecom environments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-telecom-power-system-market
Frequently Asked Questions
Who are the key players in China Telecom Power System Market industry?
The top 5 players in the China Telecom Power System Market include Huawei Technologies, Delta Electronics, ZTE Corporation, Vertiv Co., and Emerson Electric Co. These companies are recognized for their innovative power solutions, comprehensive product portfolios, and strong distribution networks serving China's rapidly expanding telecom sector.
What is the China Telecom Power System Market growth?
The China Telecom Power System Market is experiencing significant growth, driven by the increasing deployment of 5G infrastructure. In 2023, Huawei Technologies saw a surge in demand for efficient power systems as telecom operators upgraded networks, supporting double-digit market growth rates.
Which segment accounted for the largest China Telecom Power System Market share?
The wireless communication base station segment accounted for the largest market share. Driven by massive investments in upgrading 4G/5G base stations, major telecom operators increasingly relied on advanced power systems to ensure reliable and efficient operations in urban and rural deployments.
Thanks & Regards,
priya
sales@bussinessinsights.com
From 2020 to 2035, China’s SCR Power Controller market showcases consistent growth, starting at USD 370 million in 2020 and projected to reach USD 900 million by 2035. This upward trajectory is fueled by industrial policy support for automation, large investments in high-tech manufacturing such as semiconductors, and rising adoption of energy-efficient process controls. The CAGR of 6.4% reflects both organic expansion and incremental penetration into new applications, with revenue jumps from 2025 onward driven by digital transformation and Industry 4.0 adoption.
Read More - https://bussinessinsights.com/research-report/china-scr-power-controller-market
The SCR power controller market in China in 2025 is primarily dominated by applications in the plastics industry, followed closely by semiconductors, and food & beverage sectors. The plastics sector’s focus on precise heat control and automation has resulted in significant investments, while the surge in semiconductor fabrication plants increased controller deployments, especially in advanced manufacturing clusters. Food & beverage maintain steady adoption, with further potential from quality assurance and process optimization demands. Other verticals such as textiles, glass, and metals contribute smaller, but steadily rising shares as they modernize operations.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-scr-power-controller-market
Frequently Asked Questions
Who are the key players in China SCR Power Controller Market industry?
The key players in the China SCR Power Controller Market include Schneider Electric, Honeywell, Advanced Energy Industries, Watlow Electric Manufacturing, and ABB. These companies lead through innovative product offerings, strong distribution networks, and extensive experience in industrial automation and power control solutions across diverse sectors.
What is the China SCR Power Controller Market growth?
China’s SCR Power Controller Market has witnessed robust growth, driven by the rapid expansion of manufacturing and automation sectors. In 2023, companies like Schneider Electric reported increased investments in advanced SCR controllers to meet the rising demand for energy-efficient processes across industries.
Which segment accounted for the largest China SCR Power Controller Market share?
The industrial furnaces and ovens application segment accounted for the largest market share in China’s SCR Power Controller Market. These controllers are essential for maintaining precise temperature control in manufacturing processes, particularly in industries such as metals, ceramics, and glass, driving adoption across the segment.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China Industrial Cloud Platform market revenue grew from $5,200 million in 2020 to $7,190 million in 2025 and is projected to reach $19,800 million by 2035. This strong upward trajectory reflects increasing digitalization and adoption of advanced industrial IoT, AI, and cloud-native technologies across core manufacturing industries. Policy support, maturing cloud infrastructure, and rising competitiveness among leading vendors further stimulate exponential market growth.
Read More - https://bussinessinsights.com/research-report/china-industrial-cloud-platform-market
Manufacturing leads the application segments for industrial cloud platforms in China, representing 41% of market demand in 2025. The energy and automotive industries follow, leveraging cloud for process automation, predictive analytics, and enhanced supply chain integration. Pharmaceuticals and electronics are rapidly adopting cloud to streamline R&D cycles and enable real-time production monitoring. This shift is transforming efficiency standards across multiple sectors and driving significant innovation in industrial processes.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-industrial-cloud-platform-market
Frequently Asked Questions
Who are the key players in China Industrial Cloud Platform Market industry?
Major players include Alibaba Cloud, Huawei Cloud, Tencent Cloud, Siemens, and Inspur. Alibaba Cloud is renowned for its robust IoT and Big Data solutions. Huawei Cloud offers comprehensive industrial support. Tencent Cloud drives smart manufacturing. Siemens focuses on industrial automation, and Inspur is strong in AI-driven cloud services.
What is the China Industrial Cloud Platform Market growth?
The China Industrial Cloud Platform Market is experiencing rapid growth, with annual growth rates exceeding 20%. In 2023, Huawei Cloud reported a significant increase in customer adoption, particularly within manufacturing and energy sectors, due to digital transformation initiatives supported by governmental and industry partnerships.
Which segment accounted for the largest China Industrial Cloud Platform Market share?
The manufacturing segment held the largest share in the China Industrial Cloud Platform Market. Demand from automotive, electronics, and equipment industries is driving this trend, as these sectors increasingly adopt cloud-based solutions for real-time monitoring, predictive maintenance, and operational efficiency enhancements.
Thanks & Regards,
priya
sales@bussinessinsights.com
North America Wireless Sensor Network Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The wireless sensor network market in North America is expected to expand from USD 5,200 Million in 2020 to USD 12,900 Million by 2025, reaching USD 36,400 Million by 2035. This growth is propelled by escalating IoT deployments, smart infrastructure investments, and automation across sectors. The market’s robust CAGR reflects the continued need for real-time monitoring, operational efficiency, and connected device intelligence. Sustained investment in R&D and cybersecurity is set to support further expansion.
Read More - https://bussinessinsights.com/research-report/north-america-wireless-sensor-network-market
Industrial applications account for the largest share (33%) of the wireless sensor network market in North America for 2025, underscoring the region’s leadership in advanced manufacturing and automation. Healthcare secures 18% as connected devices become essential for patient care, while consumer electronics holds 15% aided by connected home devices. Automotive & transportation and oil & gas represent strategic sectors with significant WSN integration. This distribution highlights the multi-industry significance and diverse growth paths for WSN solutions.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/north-america-wireless-sensor-network-market
Frequently Asked Questions
Who are the key players in North America Wireless Sensor Network Market industry?
Key players include Texas Instruments, Honeywell International Inc., STMicroelectronics, Cisco Systems, and Analog Devices, Inc. These companies are renowned for their robust wireless sensor network solutions, continual R&D investment, and strategic collaborations, driving innovation and widespread deployment in sectors such as manufacturing, healthcare, and smart cities.
What is the North America Wireless Sensor Network Market growth?
The North America Wireless Sensor Network Market has exhibited strong growth in recent years, propelled by rising adoption in IoT and smart infrastructure projects. In 2023, Cisco Systems reported significant expansion in deploying wireless sensors for industrial automation, highlighting increasing demand across diverse end-user industries.
Which segment accounted for the largest North America Wireless Sensor Network Market share?
Industrial Automation remains the largest application segment, fueled by the need for real-time data monitoring and enhanced operational efficiency. Companies like Honeywell International are implementing wireless sensor networks to streamline processes and improve safety standards, which has significantly contributed to the segment's dominant market share.
Thanks & Regards,
priya
sales@bussinessinsights.com