

Blogs
PW Consulting: Fused Magnesia Sales Hit $1.89B in 2025, Projected to Grow at 5.6% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Decade Ahead: Why the 2026 Fused Magnesia Outlook Demands Immediate Executive Attention
The global fused magnesia market is entering a phase of structural redefinition. As industries grapple with tightening supply chains, evolving regulatory frameworks, and shifting demand vectors, the need for precise, forward-looking intelligence has never been more critical. Our newly released 2026 Fused Magnesia Market Research Report delivers exactly that: a comprehensive, data-grounded, and strategically actionable analysis designed to equip corporate leaders, procurement directors, and market strategists with the clarity required to navigate the forecast period from 2026 through 2032.
This executive preview outlines the foundational insights embedded in our study, demonstrates how historical trajectories and forward-looking indicators converge to shape near-term decision-making, and reveals the analytical architecture that will guide your organization through an increasingly complex market landscape. We deliberately reserve granular segmentation forecasts and proprietary modeling outputs for the full report, because strategic success depends not only on knowing where the market is heading, but on understanding the underlying mechanics that will determine competitive advantage.
The Macro Trajectory: Historical Resilience Meets Forecasted Expansion
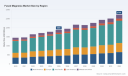
Over the past half-decade, the global fused magnesia sector has demonstrated remarkable resilience, outpacing several downstream commodity benchmarks while absorbing geopolitical friction, energy price volatility, and downstream capacity realignments. Historical data from 2020 through 2025 captures a market that steadily rebuilt momentum after initial pandemic-era disruptions, translating structural demand from core industrial applications into consistent revenue growth. By the close of the base year, the market reached an estimated valuation of approximately 1.885 billion USD, reflecting a compound trajectory that underscores the material's entrenched role across heavy industry, advanced ceramics, and specialized refractory systems.
Looking forward, our analysis projects that this expansion will continue its upward cadence, with the market advancing toward a valuation of roughly 2.730 billion USD by the terminal year of our forecast window. Driving this progression is a forecasted compound annual growth rate of 5.6 percent, a figure that encapsulates both baseline industrial demand and the incremental pull from capacity optimization initiatives, high-performance material substitution, and regional supply chain restructuring. The growth curve is neither linear nor uniform. It is shaped by the interplay of raw material consolidation, trade policy recalibration, and the steady migration toward higher-purity specifications in applications that demand superior thermal stability and chemical inertness.
For decision-makers, the implication is clear: the market is large enough to attract sustained capital allocation, yet dynamic enough to reward organizations that anticipate structural inflection points rather than react to them after they materialize.
Structural Drivers and Market Concentration Dynamics
The fused magnesia ecosystem is characterized by a concentrated yet increasingly competitive landscape. Our assessment indicates that the top three participants command approximately 52 percent of total market share, while the top five collectively represent around 68 percent. This concentration level signals an industry where scale, integrated supply chains, and technical differentiation remain decisive competitive moats. Yet it also suggests that mid-tier producers, regional specialists, and vertically aligned operators are actively carving out defensible positions through application-specific grading, logistics optimization, and strategic partnerships with downstream users.
Several macroeconomic and industrial forces are reinforcing demand durability. The steel and iron sector continues to anchor a substantial portion of consumption, driven by sustained production requirements, refractory lining upgrades, and the broader push toward extended campaign life in high-temperature processing environments. At the same time, emerging applications across advanced ceramics and glass manufacturing are reshaping specification requirements, with end-users increasingly prioritizing consistency, purity thresholds, and customized particle profiles over commoditized bulk supply. Construction-related utilization, though comparatively smaller in absolute terms, continues to provide baseline demand stability as infrastructure programs and building material formulations evolve in response to performance and regulatory considerations.
The market is therefore not merely expanding; it is bifurcating. High-purity segments are attracting premium valuation dynamics and long-term supply commitments, while medium-purity grades remain essential for cost-sensitive bulk applications. Understanding how these layers interact, where substitution risks emerge, and how pricing architecture responds to energy and feedstock variability is central to any credible strategic forecast. Our report isolates those dynamics and maps them against actionable procurement and capacity-planning scenarios.
Policy, Trade, and Supply-Side Realignment: A Landscape in Motion
No contemporary market assessment can be complete without grappling with the regulatory and trade environment shaping input costs, market access, and competitive positioning. Recent developments underscore that fused magnesia is no longer a purely commercial commodity; it is also a product of policy intervention, trade defense measures, and localized consolidation mandates.
One of the most consequential supply-side trends involves the ongoing consolidation of magnesite mining operations in key producing regions. Between 2020 and 2024, the number of active magnesite-mining enterprises in Liaoning declined from 114 to 63, with further consolidation anticipated to bring the total to approximately 56 operators by the end of 2025. This trajectory reflects a deliberate move toward operational scale, environmental compliance, and output coordination. In parallel, provincial guidance in China has emphasized sector-wide output consolidation, signaling that future supply will be increasingly determined by a smaller number of coordinated producers with enhanced control over feedstock availability and pricing.
Trade policy is equally transformative. The U.S. Department of Commerce initiated an antidumping investigation on imported dead burnt magnesite, while the U.S. International Trade Commission voted unanimously to continue the existing antidumping duty order on fused magnesia originating from China. Meanwhile, the Magnesite Association of India filed a petition alleging dumping of dead burnt magnesite from the People's Republic of China, highlighting how trade remedies are becoming a recurring feature of the global refractory raw material landscape. These actions are not isolated; they form a pattern that will influence sourcing strategies, regional cost structures, and the geography of competitive advantage.
Organizations that treat trade measures as peripheral risk factors will likely encounter costly supply disruptions or margin erosion. Those that integrate policy trajectories into procurement diversification, inventory architecture, and regional capacity planning will be better positioned to absorb shocks and capture relative pricing power.
Competitive Architecture: Who Shapes the Market and How
The competitive environment surrounding fused magnesia is defined by a blend of globally integrated incumbents, regionally anchored specialists, and application-focused producers. Our report examines the strategic postures, operational footprints, and positioning strategies of key market participants, including:
Fused Magnesia Market
- RHI Magnesita , headquartered in Vienna, Austria, which operates as a global leader in high-grade refractory products. With fused magnesia production and system-level solutions spanning more than 35 sites, the company serves steel, cement, glass, and non-ferrous metals industries. Its scale and integrated product portfolio make it a benchmark for downstream alignment and technical service differentiation.
- Grecian Magnesite S.A. , based in Athens, Greece, which specializes in magnesite products and grades including fused magnesia for refractories, electrical applications, and industrial uses. Its positioning reflects a focus on specialty-grade consistency and export-oriented distribution networks.
- Kumas Manyezit Sanayi A.Ş. , operating from Kütahya, Turkey, which manufactures refractory materials including fused magnesia and magnesite for industrial applications. Its regional manufacturing footprint provides supply agility and proximity advantages for European and nearby downstream markets.
- Baymag Inc. , headquartered in Calgary, Alberta, Canada, which acts as an integrated producer of magnesium oxide, including fused magnesia derived from its Canadian magnesite deposit. This vertical integration from deposit to processed output supports supply reliability and specification control for refractory and industrial uses.
- Premier Magnesia, LLC , located in Gabbs, Nevada, United States, which is recognized as a global leader in magnesia-based products with natural magnesia supply and processing capabilities for industrial applications. Its North American footprint and feedstock access provide strategic relevance in the context of trade flows and domestic sourcing initiatives.
- Nedmag B.V. , based in the Netherlands, which produces high-purity magnesium oxide products including dead-burned and fused magnesia for refractories and specialty uses. Its emphasis on purity and specialty-grade output aligns with high-value application requirements.
- Martin Marietta Magnesia Specialties , operating in the United States, which supplies high-purity magnesium oxide products including specialty grades for refractory and industrial applications. Its portfolio reflects a focus on performance-grade differentiation and downstream technical support.
- Niche Fused Magnesia Ltd , based in Hull, United Kingdom, which supplies fused magnesia for industrial and refractory applications. As a more specialized participant, its role illustrates how targeted market niches can sustain viable competitive positions without relying solely on scale.
Beyond company profiles, our analysis evaluates the strategic logic underpinning each player's positioning: where integration confers resilience, where geographic proximity drives logistics advantage, and where technical service capabilities create switching costs for end-users. The report also examines how these participants are likely to respond to consolidation pressures, trade remedy developments, and evolving purity requirements. In a market where the top five players already account for a substantial share of revenue, competitive differentiation increasingly depends on supply security, application engineering, and the ability to align product specifications with downstream process optimization.
What the Full Report Delivers: Operational Intelligence, Not Just Forecasts
Market data alone does not generate competitive advantage. The value of a research study lies in how effectively it translates complex signals into executable strategy. Our 2026 Fused Magnesia Market Report is built around that principle. It goes beyond headline growth figures to provide a structured toolkit for decision-makers across procurement, production planning, investment evaluation, and market entry analysis.
The report is organized to support multiple strategic use cases. It maps the historical performance of the market from 2020 through the 2025 base year, establishing a credible baseline against which forecast assumptions are tested. It then extends the analysis through 2032, incorporating segment-level demand patterns, purity-grade evolution, application-driven specification shifts, and regional supply chain considerations. Importantly, it connects these elements to operational implications rather than leaving them as abstract projections.
Readers will find detailed coverage of:
- The structural composition of demand across major application categories, including the relative weight of steel and iron processing, ceramics and glass manufacturing, and construction-related utilization, along with the qualitative drivers that determine how these shares evolve over time.
- How purity segmentation shapes pricing behavior, customer loyalty, and capacity allocation, with attention to the diverging requirements of high-purity and medium-purity value chains.
- Regional demand architecture and the strategic significance of geographic concentration, logistics corridors, and cross-border trade flows, analyzed in a way that helps organizations evaluate sourcing options without relying on static rankings.
- The competitive posture of leading producers and the operational levers that differentiate them, including integration depth, specialty-grade capabilities, and downstream application support.
- Regulatory and trade developments that alter cost structures and market access, with scenario-based considerations for procurement and supply continuity planning.
- Material consolidation trends and their implications for raw material availability, pricing volatility, and long-term contract strategy.
- Forward-looking indicators that signal where demand intensity is likely to intensify, where substitution pressures may emerge, and where investment or capacity decisions carry the highest strategic payoff.
By aligning quantitative trajectory analysis with qualitative industry mechanics, the report is designed to be referenced repeatedly throughout planning cycles. It supports budgeting precision, supplier evaluation, risk mitigation, and competitive positioning without requiring readers to reconstruct the underlying logic from disparate sources.
White Fused Alumina Market
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 window is not simply a continuation of past trends. It is a period in which the fused magnesia market will be shaped by simultaneous forces: sustained industrial demand, increasing emphasis on material performance, policy-driven consolidation, and trade measures that redraw sourcing maps. Organizations that treat these forces as background noise will likely find themselves reacting late, paying premium prices, or committing to supply arrangements that no longer match market realities.
Conversely, firms that ground their strategies in a rigorous, scenario-aware analysis will be better equipped to negotiate long-term contracts from a position of understanding, diversify sourcing without sacrificing reliability, and identify where purity upgrades or application-specific support can command favorable commercial terms. The strategic question is no longer whether the market will grow; it is how each organization will position itself to capture value as growth unfolds unevenly across segments, regions, and competitive tiers.
Our full report provides the depth, structure, and actionable framing required to answer that question with confidence. It is intended for leaders who need a single, coherent reference point that integrates market sizing, competitive assessment, regulatory context, and forward-looking demand logic into one analytical platform.
Access the Complete Intelligence
This preview has outlined the strategic rationale, high-level market trajectory, competitive architecture, and policy environment that form the foundation of our analysis. It has also made clear that the market's future is not defined by a single metric, but by the interaction of purity requirements, application dynamics, consolidation patterns, and trade policy. To move from directional understanding to decision-ready intelligence, however, organizations need the full scope of segmentation logic, scenario detail, and competitive evaluation that only the complete study can provide.
We invite executives, strategy teams, and procurement leaders to access the full 2026 Fused Magnesia Market Report for comprehensive data, detailed forecasting architecture, and the operational insights required to translate market momentum into competitive advantage. In a sector where timing, specification alignment, and supply resilience determine outcomes, the right intelligence is not an accessory to strategy. It is the foundation of it.
For detailed analysis of this topic, please visit the official page: Fused Magnesia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China LNA market generated approximately $980 million in 2025 and is projected to reach $2,350 million by 2035. Growth is fueled by widespread 5G deployment, increasing demand for advanced consumer electronics, and expanded use in ADAS systems. Annual revenue growth is reinforced by investments in R&D, government incentives for local chip manufacturing, and the expansion of automotive and healthcare applications. The upward revenue trend underscores the market’s robust potential and its strategic role in the global semiconductor ecosystem.
Read More - https://bussinessinsights.com/research-report/china-low-noise-amplifier-(lna)-market
Telecom applications dominate the China LNA market in 2025, accounting for the largest share as network operators upgrade infrastructure for wider 5G adoption. Consumer electronics, including smartphones, wearables, and smart home devices, remain critical growth drivers thanks to ongoing digitalization and IoT expansion. Automotive applications, such as ADAS and connected vehicles, show steady growth, while industrial and healthcare segments are expanding their footprint, leveraging LNAs for telemetry and imaging. Defense retains a smaller but stable share. The overall application mix underscores the diverse and evolving needs of the Chinese electronics ecosystem.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-low-noise-amplifier-(lna)-market
Frequently Asked Questions
Who are the key players in China Low Noise Amplifier (LNA) Market industry?
The top 5 key players in the China LNA market are Skyworks Solutions, Qorvo Inc., NXP Semiconductors, Analog Devices Inc., and Shenzhen Microgate Technology. These companies lead in technological innovation and provide a broad portfolio of LNAs for wireless communication, automotive, and IoT applications across China.
What is the China Low Noise Amplifier (LNA) Market growth?
The China LNA market has experienced robust growth, driven by the expanding 5G networks and IoT infrastructure. In 2023, Qorvo Inc. announced a 15% increase in sales of LNAs for mobile networks, reflecting a regional surge in demand due to continued telecom investments and device proliferation.
Which segment accounted for the largest China Low Noise Amplifier (LNA) Market share?
The wireless communication segment accounted for the largest share of the China LNA market. This dominance is attributed to increasing smartphone penetration, 5G network rollout, and continuous upgrades in telecommunications infrastructure, creating sustained demand for high-performance LNAs in base stations and user devices.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
From 2020 to 2035, the China wearable sensors market exhibits robust growth, expanding from $320 million in 2020 to a projected $1,850 million by 2035. Much of this acceleration is attributed to increased wearable adoption, product innovation, and integration of advanced sensing technologies. Notably, the market witnessed an inflection point post-2023, with revenue nearly doubling within five years as consumer and enterprise demand surged.
Read More - https://bussinessinsights.com/research-report/china-wearable-sensors-market
Smartwatches dominate wearable sensor applications in China, accounting for a significant portion of the market. The adoption of fitness bands remains strong due to growing health consciousness, while implantables represent an emerging opportunity amid advances in biosensor miniaturization. The ecosystem is shaped by product innovation from local tech giants, rapid urbanization, and shifting consumer lifestyles focused on health and productivity.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-wearable-sensors-market
Frequently Asked Questions
Who are the key players in China Wearable Sensors Market industry?
The top 5 players in the China wearable sensors market are Huawei Technologies (leading in smart devices with innovative sensor integration), Xiaomi Corporation (affordable and popular fitness trackers), Fitbit (now part of Google, with a growing Chinese presence), Apple Inc. (premium wearables with advanced sensors), and Sensirion (sensor solutions for wearables).
What is the China Wearable Sensors Market growth?
The China wearable sensors market is experiencing robust growth, expected to record a double-digit CAGR through 2028. Factors such as increased health awareness and product launches, such as Huawei’s Watch GT series with advanced health sensors, are driving significant market expansion.
Which segment accounted for the largest China Wearable Sensors Market share?
The healthcare and fitness segment holds the largest market share in the China wearable sensors market. Applications like heart rate monitoring, activity tracking, and health diagnostics have seen high adoption, especially in smartwatches and wristbands from brands like Xiaomi and Huawei.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The market revenue for China LED Light Engines is projected to rise from USD 1,320 Million in 2020 to USD 5,760 Million in 2035. Technological advancements, government policies, and the proliferation of smart lighting are the principal revenue drivers. Strong year-on-year growth is especially evident from 2025 onwards, aligning with intensified smart city deployments, increased commercial real estate investments, and rising urban population.
Read More - https://bussinessinsights.com/research-report/china-led-light-engine-market
Indoor lighting remains the leading application for LED light engines, making up nearly half the total demand due to rapid urbanization, office upgrades, and the influence of energy-saving regulations. Outdoor and automotive lighting applications exhibit strong growth, benefiting from public infrastructure projects and expanding EV manufacturing. Industrial and horticultural uses are gaining share driven by the need for energy-efficient, controlled environment solutions.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-led-light-engine-market
Frequently Asked Questions
Who are the key players in China LED Light Engine Market industry?
The top five players in the China LED Light Engine Market are Philips Lighting (Signify), Osram, Cree Inc., Nichia Corporation, and Samsung Electronics. These companies are renowned for their innovation, extensive product portfolios, and strong distribution networks, playing pivotal roles in both domestic and global lighting industries.
What is the China LED Light Engine Market growth?
The China LED Light Engine Market has seen robust growth, with recent estimates indicating a CAGR of over 12% from 2021 to 2024. Growth is driven by increased urbanization and infrastructure projects, with companies like Philips (Signify) reporting significant expansion in smart lighting solutions.
Which segment accounted for the largest China LED Light Engine Market share?
The commercial lighting segment holds the largest share of the China LED Light Engine Market. This dominance is attributed to high adoption rates in offices, shopping malls, and retail stores, as businesses increasingly shift to energy-efficient and smart lighting solutions for cost savings and sustainability.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Specialty Carbon Black Market to Reach $400M by 2032, Driven by 6.5% CAGR
By PW Consulting, 2026-09-16
Specialty Carbon Black Market Strategic Outlook 2026: Navigating Growth, Volatility, and Competitive Shifts
The specialty carbon black sector is entering a defining phase. As industrial formulations grow more complex and sustainability mandates tighten across major economies, decision-makers require more than backward-looking summaries. They need a forward-looking, data-grounded view of where value is shifting, which applications will absorb incremental capacity, and how leading producers are repositioning their portfolios against feedstock volatility and regulatory pressure. Our latest Specialty Carbon Black Market study is built precisely for that moment. Covering the historical window from 2020 through 2025 and extending forecasts to 2032, the analysis gives procurement leaders, strategy teams, and investors a structured lens on a market projected to reach a 2026 valuation of 270.77 million USD, up from 255.0 million USD in 2025, and to expand steadily toward 400.0 million USD by 2032. This translates to a forecast-period CAGR of 6.5 percent, a pace that signals durable demand but also rewards players who can read the fine print behind the headline numbers.
The report is designed as a decision-support instrument rather than a static market snapshot. It maps how historical inflection points between 2020 and 2025 set the stage for the current cycle, then translates those patterns into actionable scenarios for 2026 and beyond. Readers will find a disciplined breakdown of market architecture by region, type, and application, alongside a focused competitive profile of the organizations shaping pricing, capacity, and product differentiation. Equally important, the study embeds the operational realities that now govern margin outcomes: feedstock cost dynamics, compliance expenditures, and the strategic moves producers are already making to protect or expand their positions.
Why This Study Matters for 2026 Decision-Making
2026 is not a typical baseline year. Companies are operating in an environment where raw material volatility, environmental compliance, and regional capacity shifts are interacting at the same time. The specialty carbon black market reflects that convergence. Over the historical period, the sector moved from 180.0 million USD in 2020 to 255.0 million USD in 2025, a trajectory that underscores consistent expansion but also hides the uneven pace of growth across end-use sectors and geographies. The forward view shows continued uplift, with the market expected to reach 287.83 million USD in 2027, 311.24 million USD in 2028, and 335.4 million USD in 2029 before crossing toward 376.68 million USD in 2031 and 400.0 million USD in 2032.
For executives, the strategic question is not whether the market is growing, but where the growth is structurally concentrated and how to position for it. The study helps answer that by separating signal from noise. It shows how overall momentum is being shaped by a handful of high-value application areas and by regional demand centers that differ in both scale and maturity. It also highlights the competitive reality that market share is not evenly distributed: the top three players account for approximately 55.0 percent of the market, while the top five reach about 68.0 percent. That concentration has real implications for pricing power, contract negotiation, and supply security, especially when leading producers adjust their commercial terms or introduce surcharge mechanisms.
This is exactly why the report is framed around operational relevance. Rather than presenting isolated figures, it connects market size and growth to the decisions that matter in 2026: how to plan for feedstock uncertainty, which product families deserve closer evaluation, how regional demand centers compare in absolute scale, and where competitive intensity is likely to rise as new capacity and import-substitution dynamics take hold.
Market Architecture at a Glance
A clear view of market structure is essential for prioritizing resource allocation and risk management. The study organizes the landscape across three core dimensions, giving readers a structured way to interpret demand, supply, and segmentation without obscuring the differences that drive strategic advantage.
Regional Scale and Demand Patterns
The regional view places absolute market scale in context. Asia Pacific stands as the largest regional market at 96.05 million USD, followed by North America at 66.87 million USD, Europe at 46.51 million USD, Latin America at 30.43 million USD, and the Middle East and Africa at 15.14 million USD. These figures make the geographic hierarchy explicit while leaving room for the report's deeper discussion of growth rates, demand drivers, and local supply conditions. In practice, that means procurement and expansion planning can be anchored in relative market size while still accounting for the distinct regulatory, manufacturing, and logistics realities that differ from one region to another.
Product Families and Value Positioning
On the type side, conductive carbon black leads at 101.31 million USD, with food contact carbon black at 78.81 million USD, fiber carbon black at 50.18 million USD, and other specialty grades at 24.7 million USD. This structure matters because each family serves different performance requirements and end-market expectations. Conductive grades, for example, are tied to functionality in electronics, battery-related formulations, and advanced polymer applications, while food-contact and fiber-oriented grades carry their own regulatory and processing considerations. The report uses these categories to show where value is being created today and where product development is likely to open additional room for premium positioning.
Application Demand and Portfolio Implications
By application, the market is anchored by plastics at 95.27 million USD, printing inks at 69.51 million USD, paints and coatings at 60.04 million USD, and batteries at 30.18 million USD. These segments collectively illustrate how specialty carbon black has moved beyond traditional bulk uses into formulation-intensive areas where dispersion, conductivity, UV protection, pigmentation, and consistency are critical. The study examines each application cluster not as a simple revenue line, but as a set of performance requirements, substitution risks, and specification sensitivities that influence purchasing behavior and supplier selection. For teams evaluating expansion, reformulation, or dual-sourcing strategies, that application-level clarity is often the difference between a generic market thesis and an executable plan.
Competitive Landscape: Leaders, Moves, and Meaning
The competitive environment is defined by established global players, regional specialists, and emerging producers pursuing higher-value grades and import substitution. The report profiles the organizations that are most influential in shaping pricing, product breadth, and capacity strategy, with a focus on how their offerings map to the specialty carbon black segments that matter most to buyers.
Global Incumbents and Portfolio Breadth
Orion S.A., headquartered in Spring, Texas, is positioned as a global leader in specialty carbon black grades for paints, coatings, inks, toners, plastics, adhesives, polymers, batteries, and tires. With 15 production facilities and a stated emphasis on sustainable and circular solutions, Orion illustrates how scale can be paired with a sustainability narrative that increasingly matters to downstream customers. Cabot Corporation, based in Boston, Massachusetts, is described as the world's largest producer of specialty carbons, with its BLACK PEARLS, EMPEROR, REGAL, and MONARCH lines supporting UV protection, pigmentation, and conductivity across plastics, coatings, toners, and printing inks. Birla Carbon, headquartered in Mumbai, India, is presented as a leading manufacturer of sustainable carbon black additives, with Raven, Conductex, and Ultra brands targeting high-performance applications in paints, coatings, inks, plastics, adhesives, and tires.
Specialty Carbon Black Market
These profiles are not simply corporate summaries. They are used in the study to show how product naming, grade breadth, and application coverage influence customer choice in specification-driven markets. When buyers compare suppliers, they are often evaluating more than price; they are weighing consistency, technical support, regulatory readiness, and the ability to support reformulation or sustainability goals.
Regional Players and Emerging Capacity Strategies
The competitive picture also includes regionally anchored producers and newer entrants that are altering the market's center of gravity. Tokai Carbon Co., Ltd., based in Tokyo, produces ASTM blacks and specialty carbon blacks for tire, rubber goods, plastics, coatings, and inks, with recent Southeast Asia capacity expansion reinforcing its regional presence. PCBL Chemical Ltd., headquartered in Kochi, India, manufactures seven specialty carbon black grades and has moved to enhance capacity for high-margin grades in rubber and industrial applications. In China, Anhui Black Cat Material Science Co., Ltd. is noted as a leading supplier of specialty carbon black that is realizing import substitution in medium and high-value grades for the paint industry, while Shandong Huibaichuan New Materials Co., Ltd., based in Jinan, Shandong Province, produces pigment and conductive carbon black for coatings, inks, plastics, master batches, sealants, and other applications.
Together, these companies highlight a broader trend: competition is intensifying not only through capacity additions, but through grade specialization, regional proximity, and the pursuit of higher-value niches. The study translates these developments into a practical competitive map, helping readers understand where incumbency is strongest, where import substitution is advancing, and where new capacity may alter supply conditions over the forecast period.
Industry Dynamics Shaping Margin and Strategy in 2026
The market does not move in a vacuum. Several concurrent forces are reshaping cost structures, compliance burdens, and commercial behavior, and the report integrates them into a single operational lens rather than treating them as separate side notes.
Feedstock Pressure and Price Environment
Crude oil price volatility in 2026 has intensified feedstock pressure for specialty carbon black production, with coal tar and oil-based inputs rising sharply due to disruptions in the Strait of Hormuz and higher energy costs. This matters because feedstock economics sit at the center of margin stability, inventory planning, and pricing negotiation. The study examines how this pressure is propagating through production costs and how leading producers are responding, including through commercial mechanisms that transfer part of the volatility into contract terms.
Regulatory Tightening and Compliance Costs
On the regulatory front, stringent environmental regulations in the EU and US have imposed stricter air emission standards and workplace exposure rules on carbon black production, raising compliance costs for specialty grades. At the same time, stricter carbon taxes and emissions trading schemes in key markets are constraining traditional carbon black production methods that release particulate matter, NOx, and sulfur compounds. These forces do more than add cost; they influence which production routes remain competitive, how suppliers justify premium grades, and where sustainable or circular solutions gain commercial traction.
Recent Commercial and Strategic Moves
Recent developments make these dynamics concrete. In March 2026, Orion S.A. announced that it will raise prices and introduce a variable surcharge for specialty carbon black products, a move that directly reflects the feedstock and cost environment while signaling how incumbents are protecting margins. In April 2026, Birla Carbon showcased advanced sustainable carbon black solutions at Chinaplas 2026 for high-performance applications in plastics, electronics, cables, and fibers, underlining the growing linkage between sustainability and performance claims in demanding end markets. In May 2026, Orion S.A. launched circular carbon black production in China, and also announced plans to showcase award-winning bio-circular carbon black plus high-jet grades for automotive coatings at the 2026 American Coatings Show. These events are not isolated news items; they illustrate how product innovation, circular production, and targeted application messaging are being used to navigate a more complex operating environment.
What the Report Delivers: A Practical Toolkit for Strategy Teams
The study is organized to support real decision cycles, not just high-level observation. It blends market sizing, segmentation, competitive profiling, and industry dynamics into a single framework that can be used for sourcing strategy, product planning, investment screening, and risk assessment.
Carbon Black Market
- Historical trajectory and forecast structure covering 2020 through 2032, anchored in consistent market sizing and a 6.5 percent forecast-period CAGR
- Clear segmentation views by region, type, and application, with absolute scale provided to support prioritization and comparison
- Competitive profiles that connect product offerings, production footprints, and strategic positioning to the segments most relevant to specialty carbon black buyers
- Integration of feedstock volatility, regulatory pressure, and recent corporate moves into a working view of margin and supply risk
- Focused analysis of concentration dynamics, with top-three and top-five share context that informs supplier dependence and negotiation strategy
- Practical orientation toward 2026 decision-making, including how to interpret price actions, capacity shifts, and sustainability-driven product launches
In short, the report is built to help teams move from awareness to action. It gives readers a defensible basis for evaluating where demand is strongest, which grades and applications warrant closer attention, how competitors are shaping the commercial environment, and what operational pressures are likely to influence cost and availability in the near term.
How to Use This Intelligence
For procurement and supply chain leaders, the study offers a structured way to assess supplier options, anticipate pricing pressure, and understand where concentration and recent price actions may affect contract strategy. For product and formulation teams, it provides context on how application requirements and regulatory trends are influencing grade selection and substitution risk. For corporate strategy and investment functions, it frames the market in terms of structural growth, competitive positioning, and the regions and product families that are likely to define the next phase of expansion.
The full study goes further than the overview presented here. It contains the deeper segmentation detail, company-level analysis, and scenario-based interpretation needed to turn market visibility into concrete decisions. For teams that need the complete picture—region-by-region scale, application-level demand context, type-level value positioning, and the competitive moves that are actively reshaping the market—the source report is the appropriate next step.
The specialty carbon black market is expanding, but the value of that growth will depend on how well organizations can read its structure, anticipate its pressures, and respond to the moves of a concentrated and increasingly adaptive competitive set. This report is designed to give decision-makers exactly that vantage point for 2026 and the years that follow.
For detailed analysis of this topic, please visit the official page: Specialty Carbon Black Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China ToF Sensor market demonstrates a strong upward trajectory, beginning at USD 1,800 Million in 2020, rising to USD 3,100 Million in 2025, and projected to surpass USD 11,500 Million by 2035. This exponential growth is fueled by large-scale deployment across sectors including consumer electronics, automotive, industrial automation, and smart healthcare. Key investments, robust local manufacturing, and continuous innovation are sustaining this momentum. With ongoing urbanization and technology adoption, the market is expected to maintain double-digit CAGR throughout the forecast period, positioning China as the global leader in ToF sensor production and application.
Read More - https://bussinessinsights.com/research-report/china-time-of-flight-(tof)-sensor-market
Consumer Electronics dominate the application segments for ToF sensors in China, accounting for 31% of the market in 2025, propelled by widespread integration in smartphones, VR/AR devices, and smart wearables. Automotive sector follows at 22%, as advanced safety features and autonomous vehicles gain traction. Industrial applications capture 18% share, benefiting from the nation’s focus on smart manufacturing and robotics. Healthcare and Smart Devices are emerging segments with rapid YoY growth, reflecting increased use in touchless detection, medical imaging, and IoT. Robotics, accounting for 11%, is projected to accelerate as industrial automation expands nationwide.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-time-of-flight-(tof)-sensor-market
Frequently Asked Questions
Who are the key players in China Time-of-Flight (ToF) Sensor Market industry?
The top five players in the China ToF Sensor Market are Sony Corporation, Keyence, Infineon Technologies, Panasonic Corporation, and Shenzhen Anitoa Systems. These companies lead with innovations in sensor technology and supply high-performance 3D sensing solutions tailored for industrial, automotive, and consumer electronics applications.
What is the China Time-of-Flight (ToF) Sensor Market growth?
The China ToF Sensor Market has experienced robust growth, driven by increasing adoption in smartphones and automotive sectors. For example, in 2023, Huawei integrated advanced ToF sensors into its flagship smartphones, boosting market demand and paving the way for widespread application across multiple industries.
Which segment accounted for the largest China Time-of-Flight (ToF) Sensor Market share?
The consumer electronics segment, particularly smartphones, accounts for the largest market share in China’s ToF Sensor Market. Growing usage of ToF sensors in facial recognition, AR/VR applications, and gesture control by brands like Huawei and Xiaomi has propelled demand in this applications segment.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
Between 2020 and 2035, China’s wireless charging market revenue shows a strong upward trajectory. In 2021, the market generated USD 1,200 Million and is projected to grow to USD 2,400 Million in 2025, eventually reaching USD 8,200 Million by 2035. This growth is fueled by surging adoption across consumer and automotive sectors, ongoing product innovation, and policy support for wireless infrastructure.
Read More - https://bussinessinsights.com/research-report/china-wireless-charging-market
Consumer electronics remain the primary application for wireless charging in China, holding a commanding 60% market share in 2025. Automotive usage captures 20%, driven by EV charging infrastructure advancements, while healthcare, industrial, and others collectively account for 20%. The dominance of mobile devices and wearables underlines ongoing demand, but diversified uptake in electric vehicles and healthcare equipment is expanding the market’s footprint beyond personal devices.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-wireless-charging-market
Frequently Asked Questions
Who are the key players in China Wireless Charging Market industry?
The top 5 players in the China wireless charging market are Xiaomi Corporation, Huawei Technologies Co. Ltd., ZTE Corporation, Shenzhen Avidsen Technology Co. Ltd., and Energizer Holdings Inc. These companies lead through advanced R&D, large-scale production capacity, and robust product portfolios targeting consumer electronics and automotive sectors.
What is the China Wireless Charging Market growth?
The China wireless charging market is experiencing robust growth, driven by technological innovations and rising smartphone demand. For instance, Xiaomi reported strong sales of its wireless charging devices in 2023, showcasing year-on-year market expansion fueled by consumer electronics adoption and growing prominence in the automotive industry.
Which segment accounted for the largest China Wireless Charging Market share?
Consumer electronics represent the largest application segment in the China wireless charging market. This dominance is due to high adoption rates of wireless charging-enabled smartphones, tablets, and wearables, especially from leading brands like Huawei and Xiaomi, who integrate wireless charging technologies across multiple flagship product lines.
Thanks & Regards,
priya
sales@bussinessinsights.com
The market exhibits robust revenue growth from USD 1,350 Million in 2020 to an expected USD 2,400 Million by 2025. Continuing its strong momentum, the market is anticipated to reach USD 6,800 Million by 2035, underpinned by policy-led sustainability initiatives, increased commercial builds, and a shift towards smart VRF upgrades. This growth trajectory demonstrates China’s commitment to modernizing its built environment with high-performance climate control solutions.
Read More - https://bussinessinsights.com/research-report/china-vrf-system-market
The commercial segment leads with 48% of the China VRF System market in 2025, reflecting widespread upgrades in offices, retail, and hospitality. The residential segment follows at 32%, riding a wave of urban multi-family and premium housing projects. Industrial and institutional applications constitute 20%, underlining the growing relevance of VRF solutions for factories, educational campuses, and hospitals. As real estate growth tilts towards smarter, greener infrastructure, the commercial sector will maintain its position as the primary adopter of VRF systems.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-vrf-system-market
Frequently Asked Questions
Who are the key players in China VRF System Market industry?
The top five key players in the China VRF System Market are Daikin Industries, Gree Electric Appliances, Midea Group, Johnson Controls-Hitachi, and Mitsubishi Electric. These companies are recognized for their innovative HVAC solutions, strong market presence, extensive product portfolios, and continuous investment in research and development to meet China's burgeoning building needs.
What is the China VRF System Market growth?
The China VRF System Market is experiencing significant growth, with a projected CAGR of over 10% from 2023 to 2028. Growth is fueled by increasing urbanization and energy efficiency policies. For example, Midea Group recently expanded its smart VRF offerings, driving market demand for advanced cooling solutions.
Which segment accounted for the largest China VRF System Market share?
The commercial segment holds the largest share in the China VRF System Market. VRF systems are widely adopted in commercial buildings such as offices, shopping malls, and hotels due to their superior energy efficiency and flexibility in temperature control, meeting the diverse climate management needs of large structures.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Microgrid as a Service (MaaS) Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The China MaaS market reveals strong revenue growth momentum from 2020 through 2035, with the market estimated at $2,320 Million in 2025 and projected to exceed $11,400 Million by 2035. The growth trajectory is supported by policy reforms, renewable energy mandates, and technology upgrades. Post-2027, the market is expected to witness accelerated growth due to rural and new energy integration projects, with revenues surging year-on-year. Investment from both public and private sectors continues to strengthen long-term prospects.
Read More - https://bussinessinsights.com/research-report/china-microgrid-as-a-service-(maas)-market
Government and utilities lead microgrid adoption at 32%, benefitting from policy incentives and public infrastructure upgrades. Commercial and industrial applications follow closely at 28%, driven by demand for efficient, reliable power supply. Residential, education, and healthcare segments collectively account for about 40% of the market, reflecting increasing penetration of MaaS models in smart buildings, campuses, and critical service facilities. The sector diversification highlights the evolving landscape and broad growth potential of MaaS in China.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-microgrid-as-a-service-(maas)-market
Frequently Asked Questions
Who are the key players in China Microgrid as a Service (MaaS) Market industry?
The key players in the China Microgrid as a Service (MaaS) market include ABB Ltd., Siemens AG, Schneider Electric SE, General Electric Company, and Huawei Technologies Co., Ltd. These companies offer innovative microgrid solutions, integration services, and advanced technologies to enhance resilience, energy management, and grid flexibility across China.
What is the China Microgrid as a Service (MaaS) Market growth?
The China Microgrid as a Service (MaaS) market has experienced robust growth, with rising investments in renewable energy and decentralized power. For instance, Huawei reported increased adoption of its microgrid solutions in 2023, driven by government incentives, smart grid development, and the need for resilient energy infrastructure.
Which segment accounted for the largest China Microgrid as a Service (MaaS) Market share?
Commercial and industrial applications accounted for the largest market share, as businesses seek reliable backup power, energy cost optimization, and sustainability. This segment has witnessed rapid uptake of MaaS solutions for manufacturing plants, data centers, and business parks, supported by energy-saving goals and demand for uninterrupted power.
Thanks & Regards,
priya
sales@bussinessinsights.com
From 2020 to 2025, the China 5G Industrial IoT market revenue climbed sharply from USD 2,100 Million to USD 7,800 Million, supported by large-scale pilots and commercial deployments in key industries. Strong projected CAGR above 13% through 2035 signals steady adoption, with revenue expected to reach USD 27,300 Million by 2035. Expansion is primarily powered by 5G infrastructure maturation, legislative clarity, and an increased number of industry-specific digital transformation projects.
Read More - https://bussinessinsights.com/research-report/china-5g-industrial-iot-market
In 2025, Manufacturing holds the majority market share with 39%, reinforcing the sector's commitment to smart factory transformation. Energy & Utilities follows at 22%, leveraging 5G for smart grid and asset automation. Transportation & Logistics captures 16%, reflecting significant advancements in real-time fleet management and supply chain automation. Healthcare and Smart Cities account for 13% and 7% respectively, while other emerging applications contribute 3%, showcasing the diverse adoption of 5G IoT across China’s industrial landscape.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-5g-industrial-iot-market
Frequently Asked Questions
Who are the key players in China 5G Industrial IOT Market industry?
Key players include Huawei Technologies, ZTE Corporation, China Mobile, China Unicom, and Ericsson China. Huawei and ZTE lead in building end-to-end 5G IoT solutions. China Mobile and China Unicom drive network adoption, while Ericsson supplies advanced networking technologies for smart factories and industrial automation.
What is the China 5G Industrial IOT Market growth?
China's 5G Industrial IoT Market has been growing rapidly, with annual double-digit growth rates. In 2023, partnerships such as Huawei and China Mobile’s deployment of private 5G networks in manufacturing drove expanded adoption, accelerated by the demand for digital transformation and government-backed industrial upgrades.
Which segment accounted for the largest China 5G Industrial IOT Market share?
The manufacturing segment accounts for the largest share of the China 5G Industrial IoT market. Applications like smart factories, real-time equipment monitoring, and automated production lines leverage 5G’s low latency and high reliability, driving efficiency and productivity across industries such as automotive, electronics, and heavy machinery.
Thanks & Regards,
priya
sales@bussinessinsights.com