

Blogs
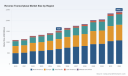
The global electric boom lifts market shows a strong upward trajectory through 2020-2035. Market revenue is estimated at $2,350 Million in 2025, up from $1,720 Million in 2020, and projected to reach $6,720 Million by 2035. This robust growth is fueled by rapid infrastructure development, urbanization in key markets, and stringent emission standards pushing the transition from diesel to electric models. Major market players are continually investing in R&D, product line expansions, and strategic partnerships to capture new opportunities and optimize revenue streams across regions.
Read More - https://bussinessinsights.com/research-report/global-electric-boom-lifts-market
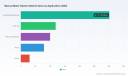
Construction remains the dominant application for electric boom lifts, representing over one-third of market demand in 2025, due to increased infrastructure projects and urban redevelopment. Utilities and industrial applications are also substantial, as maintenance, energy, and logistics sectors emphasize safety, productivity, and sustainability. The ongoing shift towards automation and eco-compliance in logistics and warehousing is expected to further amplify market penetration for electric-powered lifts in these domains.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-electric-boom-lifts-market
Frequently Asked Questions
Who are the key players in Global Electric Boom Lifts Market industry?
The key players in the Global Electric Boom Lifts Market include JLG Industries, Genie (Terex Corporation), Haulotte Group, Dingli, and Sinoboom. These companies focus on innovation, safety features, and expanding their electric boom lift product portfolios to cater to the growing demand for environmentally friendly and efficient aerial work platforms worldwide.
What is the Global Electric Boom Lifts Market growth?
The Global Electric Boom Lifts Market has shown significant growth in recent years, driven by the increasing adoption of green construction equipment. In 2023, companies like Genie (Terex Corporation) reported higher sales due to growing infrastructure projects and rising preference for electric-powered machinery, projecting a healthy CAGR through 2030.
Which segment accounted for the largest Global Electric Boom Lifts Market share?
The construction segment accounted for the largest market share in the Global Electric Boom Lifts Market. Driven by rapid urbanization and increasing investments in commercial and residential infrastructure projects, electric boom lifts are widely used for tasks such as building maintenance, installation, and finishing work at heights.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global hydraulic cylinder market is projected to reach $22,130 Million by 2025, up from $16,300 Million in 2020. By 2035, revenues are anticipated to climb to $41,750 Million, driven by technological advances and broadening industrial applications. The revenue growth trajectory reflects ongoing modernization in construction, agriculture, and heavy machinery sectors worldwide, alongside widespread adoption of energy-efficient and smart hydraulic systems. Robust demand is expected to continue across both mature and emerging economies as the focus on automation, digitalization, and sustainability increases investment and replacement cycles for hydraulic equipment.
Read More - https://bussinessinsights.com/research-report/global-hydaulic-cylinder
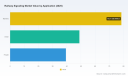
In 2025, the construction sector dominates hydraulic cylinder application share due to substantial infrastructure development and heavy equipment upgrades globally. Agriculture and industrial automation collectively represent over a third of market utilization, fueled by farm mechanization and manufacturing digitalization. Mobile and mining equipment applications are also key, as innovative cylinder technologies support modernization and safer, more efficient work in demanding environments. Aerospace & defense hold a niche but technologically advanced segment, leveraging high-precision, lightweight cylinders. This distribution demonstrates substantial reliance on hydraulic cylinders for both traditional heavy industries and advanced automation processes.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-hydaulic-cylinder
Frequently Asked Questions
Who are the key players in Global Hydraulic Cylinder industry?
The top five players in the global hydraulic cylinder industry include Bosch Rexroth, Parker Hannifin, Eaton Corporation, Caterpillar Inc., and Enerpac. These companies are leading due to their extensive product portfolios, innovative technologies, strong distribution networks, and key strategic partnerships across various industrial sectors.
What is the Global Hydraulic Cylinder growth?
The global hydraulic cylinder market has been experiencing steady growth, with a notable surge driven by the rising demand in construction and mining. For example, Parker Hannifin reported increased orders in 2023, attributing growth to infrastructural projects and increased automation adoption in developing regions.
Which segment accounted for the largest Global Hydraulic Cylinder share?
Mobile applications, particularly in construction and agriculture machinery, accounted for the largest share of the global hydraulic cylinder market. The demand for powerful, reliable hydraulic systems in equipment like excavators, loaders, and tractors continues to fuel segment dominance due to ongoing development projects worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting Report: Manual Motor Starters Market Hits $630M in 2025, Projected 4.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Decade: Strategic Insights into the Global Manual Motor Starters Market (2026-2032)
The industrial landscape is undergoing a profound transformation, driven by the dual engines of automation and electrification. At the heart of this shift lies the fundamental infrastructure of motor control. For enterprise decision-makers, understanding the trajectory of the Manual Motor Starters Market is not merely an exercise in supply chain management; it is a strategic imperative that influences capital expenditure planning, safety compliance, and operational resilience. PW Consulting is proud to introduce our latest comprehensive market research study, designed to equip leadership teams with the actionable intelligence needed to thrive in the forecast period of 2026 through 2032.
This report serves as a critical navigational tool for stakeholders ranging from procurement directors to strategic planners. By analyzing historical performance from 2020 to 2025 and projecting forward, we uncover the underlying currents shaping the industry. The market, valued at approximately 630.0 Million USD in the base year of 2025, is poised for steady expansion. Our forecast models indicate a trajectory moving toward 857.0 Million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5 percent, signaling a mature yet consistently evolving sector where reliability and compliance drive demand rather than volatile speculation.
For organizations operating within or alongside the industrial manufacturing, oil and gas, water management, and mining sectors, these figures represent more than just top-line revenue. They reflect the ongoing replacement cycles of aging infrastructure, the integration of new safety standards, and the increasing complexity of motor protection requirements. This introduction provides a high-level overview of the strategic landscape, but the full depth of this intelligence is contained within the full report. The following analysis highlights the key themes our research unpacks in detail.
Macroeconomic Trajectory and Market Stability
The Manual Motor Starters Market has demonstrated remarkable resilience over the past five years. From 2020 to 2025, the market navigated global supply chain disruptions and economic fluctuations while maintaining a positive growth curve. The jump from 582.19 Million USD in 2024 to 630.0 Million USD in 2025 highlights a period of recovery and accelerated adoption. As we look toward 2026, the market is expected to reach 659.77 Million USD, setting the stage for a decade of incremental but significant growth.
This stability is crucial for long-term planning. Unlike high-volatility technology sectors, the demand for manual motor starters is tied to fundamental industrial output. The forecast period suggests that while the percentage growth may not be explosive, the absolute value addition is substantial. Companies that align their inventory and product development strategies with this steady 4.5 percent CAGR can optimize cash flow and reduce the risk of overstocking or undercapacity. However, realizing these benefits requires a nuanced understanding of where the growth is originating, which varies significantly by technology type and application vertical.
Manual Motor Starters Market
Segmentation Dynamics: Type and Application
A superficial view of the market hides the complex interplay between different product types and end-use applications. Our research dives deep into these segmentation splits to reveal where the highest value opportunities lie. The market is broadly categorized by technology, with AC Manual Motor Starters continuing to dominate the revenue share due to their widespread use in standard industrial power systems. However, the nuances within DC and other types offer specific niches for specialized engineering firms.
Similarly, the application landscape is diverse. Industrial manufacturing remains a primary driver, reflecting the need for cost-effective motor control in high-volume environments. Yet, sectors such as Oil and Gas and Water and Wastewater are critical growth engines due to stringent safety regulations and the harsh operating conditions that require robust starter solutions. Mining operations also contribute a significant portion of demand, particularly in regions undergoing infrastructure development.
Understanding the revenue contribution of each segment is vital for targeting. For instance, knowing which application vertical is expanding fastest can help manufacturers tailor their sales strategies and technical support teams. However, the specific percentage allocations and exact valuation figures for each region and application are proprietary data points that require the full report to access. This level of granularity allows competitors to benchmark their performance against the market average and identify untapped potential in specific verticals.
Regional Landscape and Distribution Channels
Geography plays a pivotal role in market dynamics. The global footprint of manual motor starters is uneven, reflecting the varying stages of industrialization and infrastructure investment across continents. Our analysis covers key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of challenges and opportunities, from regulatory compliance in Europe to cost-sensitive competition in Asia Pacific.
Motor Control Centers Mcc Market
Europe, for example, often leads in terms of advanced safety standards and premium product adoption, while other regions may prioritize volume and affordability. The distribution of market revenue across these geographies influences where companies should focus their marketing spend and logistical hubs. Supply chain localization is becoming increasingly important as trade policies shift and customers demand faster delivery times.
Our report provides a detailed breakdown of regional market sizes and growth rates. This information is essential for multinational corporations deciding on regional expansion strategies or local distributors looking to partner with global brands. The specific revenue values and growth contributions for each geographic zone are detailed within the full study, enabling precise market entry planning without the guesswork.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate level of concentration, with the top three players holding approximately 35.5 percent of the market share, while the top five control around 48.2 percent. This structure indicates a competitive environment where dominant players coexist with agile regional specialists. Understanding the strategies of these key competitors is essential for maintaining market position.
Leading global entities such as ABB, headquartered in Zurich, continue to strengthen their portfolio with specific series like MS116 and MS132, focusing on compact units that integrate protection and control. Schneider Electric, based in France, maintains a strong presence with the TeSys Deca GV2 and GV3 series, recently updating their catalog with TeSys Deca Advanced solutions in late 2025. Eaton, from Dublin, offers robust options like the PKZM and Cutler-Hammer B100 series, catering to diverse machinery control needs.
Siemens remains a key player with their 3RV2 series, serving the high-standard European and global markets. Meanwhile, specialized players are carving out niches. NOARK Electric, based in California, recently expanded their offering with the Ex9S80 Manual Motor Starter in mid-2025, emphasizing built-in fault indication. Fuji Electric in Tokyo continues to innovate with their Duo Series, while Appleton Electric, part of Emerson in Illinois, focuses on factory-sealed starters for hazardous locations. LS Electric in South Korea contributes with their Metasol MMS series, highlighting the global nature of this supply chain.
Competitive strategy in this market is not just about price. It is about compliance, reliability, and product features. Companies must navigate specifications such as short-circuit breaking capacity up to 100 kA at 400 VAC. Failure to meet these technical benchmarks can disqualify a product from key tenders. Our analysis examines the recent developments and product launches of these key companies to identify trends in innovation and market share shifts. The full report details the specific strategic moves and product portfolios that are defining the competitive edge in 2026.
Regulatory Environment and Technical Standards
Compliance is a non-negotiable aspect of the manual motor starter business. These electromechanical devices serve as the first line of defense for manual isolation, control, and overcurrent protection. They must adhere to rigorous international standards, including IEC and UL certifications. The regulatory landscape is tightening, particularly in hazardous environments.
For instance, starters designed for use in hazardous locations, such as Class I, Division 1 and 2 areas, require specific factory-sealed designs to prevent ignition sources. This creates a barrier to entry for lower-quality manufacturers and rewards established brands with proven certification histories. Furthermore, the average selling price of industrial-grade manual motor starters typically ranges from 150 to 450 USD, depending on current ratings between 10A and 100A and the complexity of protection features.
This pricing structure reflects the cost of compliance and engineering quality. Procurement teams must balance budget constraints with the inherent risks of non-compliance. Our research evaluates how regulatory changes are impacting product design and pricing strategies across the industry. We analyze the compliance requirements that are becoming key differentiators in procurement bids. Detailed regulatory impact assessments for specific regions and application types are included in the comprehensive study.
Investment and Procurement Outlook for 2026
As organizations move into the 2026 fiscal year, capital allocation decisions must be informed by data. The forecast growth to 768.22 Million USD by 2030 suggests a sustained demand environment. For procurement leaders, this means securing supply chains early to mitigate potential shortages or lead time extensions. For manufacturers, it means scaling production capabilities in line with the 4.3 percent to 4.5 percent growth corridors identified in our models.
The period from 2026 to 2032 will likely see consolidation among smaller players and increased investment in product features that enhance safety and diagnostics. Companies that adapt to these trends will capture greater market share. Those that rely on legacy designs without adapting to newer safety standards risk obsolescence.
Strategic planning also involves understanding the cyclical nature of the industries served. While manufacturing may fluctuate with economic cycles, utilities and water management often provide stable, recurring revenue. A diversified portfolio approach is recommended for market players. Our report provides the scenario planning tools necessary to model revenue under different economic conditions.
Why This Report is Essential for Decision Makers
In an era of information overload, clarity is the most valuable commodity. This report cuts through the noise to provide verified data, expert analysis, and forward-looking insights. It is not just a collection of numbers; it is a strategic framework for understanding the Manual Motor Starters Market.
By utilizing this research, your organization can:
- Benchmark your internal forecasts against independent market projections for the 2026-2032 period.
- Identify high-growth segments and regions before competitors do.
- Understand the competitive moves of key players like ABB, Schneider Electric, and Eaton to anticipate market shifts.
- Navigate regulatory complexities with confidence, ensuring product compliance and market access.
- Optimize supply chain strategies based on regional demand nuances and historical performance data from 2020 to 2025.
The market size data provided in the introduction offers a glimpse into the potential, but the actionable intelligence lies in the segmentation, competitive analysis, and regional breakdowns that are fully detailed in our complete study. The specific revenue splits by type, application, and region, along with the in-depth company profiles and recent development timelines, are critical for forming a precise strategy.
Access to the full report unlocks the detailed segmentation splits, such as the specific contributions of AC versus DC starters and the exact market valuation for industrial manufacturing versus other applications. It also provides the granular regional data necessary for local market planning. In a market projected to reach 857.0 Million USD by 2032, knowing exactly where to focus resources is the difference between average performance and market leadership.
Conclusion
The Manual Motor Starters Market offers a landscape of steady opportunity for those equipped with the right intelligence. As the industry moves past the base year of 2025 and into the forecast horizon, the convergence of regulatory pressure, technological refinement, and industrial demand will define the winners. PW Consulting's latest research provides the lens through which to view this future. We invite stakeholders to leverage this comprehensive analysis to drive informed decision-making and secure a competitive advantage in the years to come.
For those ready to transform data into strategy, the full market intelligence report is available for review. Engage with our detailed findings to align your organizational roadmap with the definitive market trajectory.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Smart Elevators And Escalators Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
Global Smart Elevators And Escalators Market: by Type (Smart Elevators, Smart Escalators), Application (Residential, Commercial, Industrial, Institutional, Mixed-use Buildings, Others), Distribution Channels (Direct Sales, Distributors, Online, Retail, Value Added Resellers, Others), Technology (Automation, Control Systems, Security & Access Systems, Energy Efficiency Solutions, IoT Integration, Advanced Display Systems), Organization Size (Small, Medium, Large) and By Global – Historical & Forecast Period (2020-2035) Comprehensive Study 2025
Read More - https://bussinessinsights.com/research-report/global-smart-elevators-and-escalators-market
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-smart-elevators-and-escalators-market
Frequently Asked Questions
Who are the key players in Global Smart Elevators And Escalators Market industry?
The top five players in the industry are Otis Elevator Company, KONE Corporation, Schindler Group, Thyssenkrupp AG, and Mitsubishi Electric Corporation. These companies lead the market through technological innovation, extensive global presence, strategic partnerships, and a wide portfolio of smart, energy-efficient elevator and escalator solutions.
What is the Global Smart Elevators And Escalators Market growth?
The Global Smart Elevators and Escalators Market is experiencing robust growth, driven by rising urbanization and demand for energy-efficient transport in buildings. In 2023, KONE Corporation reported significant new installations supported by smart digital services, reflecting the sector’s above-average annual growth rate of over 6%.
Which segment accounted for the largest Global Smart Elevators And Escalators Market share?
The largest market share in smart elevators and escalators is held by the commercial segment. Increased deployment in office buildings, commercial complexes, and malls is driving demand, as these applications benefit from advanced access control and energy-saving technologies, optimizing traffic flow and ensuring enhanced user safety and convenience.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting Forecasts Railway Signaling Market to Hit $243.2M by 2032, 5.6% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Railway Signaling Market: Navigating Growth, Competition, and Digital Transformation Through 2032
Executive Overview: Why 2026 Demands a Renewed Strategic Lens
The global railway signaling sector stands at a critical inflection point. As infrastructure operators modernize aging networks, freight corridors expand capacity, and urban mobility systems demand higher throughput, signaling technology has evolved from a compliance-driven utility into a core enabler of operational efficiency and safety. Our latest market research provides a comprehensive, data-grounded assessment of this landscape, tracing market trajectories from the historical baseline of 2020 through 2025 and projecting forward across a seven-year forecast window ending in 2032. For executives, investors, and technology leaders, the study translates macroeconomic momentum into actionable strategic intelligence tailored to 2026 decision cycles.
Over the past half-decade, the market has consolidated steady growth, reaching a total revenue base of 166.8 million USD in 2025. The trajectory reflects not only incremental capacity additions but also the gradual migration toward digitally integrated control-command architectures. Looking ahead, the forecast period is anchored by a compound annual growth rate of 5.6 percent, a figure that captures sustained modernization spending, regulatory-driven upgrades, and expanding deployment across mainline, urban, and freight applications. Importantly, the projected revenue progression outlines a market that will cross the 170 million USD threshold in 2026 and continue scaling toward materially higher valuation levels by the close of the decade, positioning signaling as a durable, long-cycle investment theme rather than a fleeting capital-expenditure cycle.
Market Trajectory and Structural Dynamics
Understanding where the market is heading requires more than top-line numbers. Our research dissects the momentum behind growth by examining the interplay of technology transitions, procurement models, and regional demand patterns, while deliberately focusing on the strategic implications rather than premature data disclosure. Several structural dynamics shape the outlook for 2026 and beyond:
- Technology migration and interoperability mandates are accelerating investment in communications-based and computer-based train control architectures, as operators seek to reduce headways, improve scheduling precision, and align with harmonized European and national safety frameworks.
- Upgrading legacy wayside infrastructure remains a persistent cost consideration. High upfront implementation expenses for hardware, trackside installations, and integration work continue to influence project pacing, financing structures, and vendor selection, especially in capital-constrained environments.
- Public-sector investment commitments are creating visible demand pull. Government programs focused on signaling modernization are prioritizing safety enhancements, capacity release, and digital readiness, reinforcing a procurement environment where long-term service agreements and phased modernization plans compete with traditional asset replacement models.
- Regulatory harmonization is tightening the specification landscape. Evolving standards and safety-rule assessments for control-command and signaling subsystems are reshaping technical requirements, compliance pathways, and validation cycles, which in turn affect deployment timing and vendor differentiation.
- Operational digitization is blurring traditional boundaries between onboard and wayside systems. As operators pursue end-to-end visibility, predictive maintenance, and data-driven traffic management, signaling increasingly integrates with broader rail digital ecosystems, creating opportunities for solution providers that can bridge signaling, computing, and communications domains.
These dynamics do not operate in isolation. They interact with procurement calendars, fleet renewal cycles, and regional infrastructure priorities, producing a market in which growth is real but unevenly distributed across time horizons and project pipelines. The research unpacks these interactions so that leadership teams can anticipate where demand will crystallize, how procurement criteria are likely to shift, and which capability sets will be rewarded in competitive tenders.
Competitive Landscape: Leaders, Niches, and Strategic Positioning
The signaling market is defined by a concentrated set of established global players alongside specialized and regional participants that compete on technology depth, delivery capability, and local regulatory familiarity. Market concentration remains significant, with the top three participants collectively accounting for a substantial share of revenue and the top five extending that footprint further. This concentration indicates that scale, installed-base leverage, and multi-system expertise continue to matter, but it also leaves room for targeted differentiation through proprietary platforms, regional execution strength, and integration of acquired capabilities.
Several firms illustrate the strategic diversity shaping the competitive field:
- Knorr-Bremse has advanced its signaling presence through KB Signaling, combining conventional CCS platforms with wayside and onboard solutions acquired from Alstom North America. The group has emphasized integration of these assets into its broader portfolio, with a stated focus on market expansion and smart innovation.
- Siemens Mobility continues to push integrated signaling offerings, including its Signaling X suite and ETCS/Level 2 systems. Recent live demonstrations in metro operations have highlighted the practical maturation of its next-generation solution set in real operational environments.
- Alstom remains closely associated with ETCS Level 2 and digital signaling systems, reinforcing its role in mainline modernization programs where European interoperability and legacy migration are central procurement considerations.
- Hitachi Rail has strengthened its digital interlocking, ETCS, and train control capabilities, underlined by a framework agreement for digital signaling technology within a major Swiss railway digitalization program, signaling commitment to large-scale, multi-year deployments.
- Wabtec Corporation has expanded its digital intelligence and wayside signaling footprint through acquisition activity, notably incorporating Frauscher capabilities in train detection and wayside signaling, broadening its ability to serve integrated detection and control requirements.
- Thales Group maintains a strong position in control-command and signaling systems, competing on safety-critical integration, centralized traffic management, and compliance with regional specification frameworks.
- China Railway Signal and Communication Co. Ltd. continues to scale onboard and wayside signaling solutions, with recent financial disclosures and market-access developments highlighting progress in offering EU-compliant onboard solutions that can engage core European markets.
- Nippon Signal, Kyosan Electric, and Toshiba Infrastructure Systems and Solutions represent the depth of Japanese engineering capability in railway signal safety systems, interlocking, electromechanical solutions, and infrastructure signaling and control, each bringing specialized execution strengths in demanding operational contexts.
- L&T Technology Services contributes signaling and control systems solutions with an engineering-services orientation, supporting design, implementation, and system integration requirements across complex projects.
- Progress Rail Services extends signaling capabilities through its ECM/Progress Rail Signaling activities, aligning signaling systems with broader rail service and equipment ecosystems in specific operational segments.
Beyond the incumbents, the competitive map includes active market participation from technology and component specialists that support the signaling value chain. Recent trade show activity and product showcases have featured railway-ready computing platforms, onboard gateways designed for rail environmental and safety compliance, and advanced signaling technologies presented to industry audiences, reflecting a broader ecosystem in which silicon, computing, and communications providers increasingly intersect with traditional signaling vendors. This expanded ecosystem matters because signaling deployments are no longer purely electromechanical or standalone control systems; they depend on ruggedized onboard computing, deterministic communications, cybersecurity postures, and lifecycle software support.
Railway Equipment Market
Competitive positioning is therefore shifting from individual product superiority to integrated value propositions. Operators increasingly evaluate vendors on their ability to deliver interoperable architectures, manage multi-year upgrade roadmaps, support workforce transition, and provide assured aftermarket and service capabilities. In this environment, firms that can combine proven safety certification records with flexible deployment models and digital service offerings are best placed to convert technical capability into long-term contractual relationships.
What the Research Delivers: An Actionable Intelligence Framework
Our Railway Signaling Market research is structured to support concrete management decisions rather than general market awareness. The study moves from macro trajectory to operational detail, providing a decision-ready framework across multiple dimensions of the market. The report introduces:
- A historical and forecast revenue trajectory that contextualizes growth across the base year, the recent historical period, and the full forecast horizon, giving leadership teams a defensible basis for scenario planning, capacity modeling, and long-cycle investment appraisal.
- A technology and application lens that examines how distinct signaling categories and deployment contexts contribute to overall market structure, enabling readers to understand where value creation is concentrated and how demand drivers differ across mainline, urban, and freight operating environments.
- A regional demand map that profiles how market activity is distributed across major geographic zones, highlighting the relative scale of opportunity without reducing the analysis to narrow point estimates, and allowing executives to align go-to-market priorities with regional procurement calendars and infrastructure programs.
- A competitive profiling section that assesses the strategic posture, offering focus, and recent activity of key participants, including integration moves, framework agreements, product demonstrators, and market-access developments, so that readers can benchmark their position and identify where consolidation, partnership, or capability investment may be warranted.
- A market dynamics synthesis that addresses the constraints and accelerants shaping deployment velocity, including upfront implementation economics, government investment signals, regulatory specification trends, and the evolving role of digitalization in signaling architectures.
- Recent development tracking that contextualizes the latest financial releases, exhibition activity, framework contracts, and integration updates within the broader competitive narrative, providing a current-events anchor for strategic planning.
Throughout, the research emphasizes practical interpretation over raw enumeration. Rather than leaving readers with isolated statistics, the study connects market structure to procurement behavior, technology adoption timing, and competitive positioning. The objective is to equip stakeholders with a clear mental model of where the market is headed, what is driving movement, and how to prioritize actions in 2026 and the subsequent planning cycles.
Implications for 2026 Decision-Making
For organizations active in or adjacent to railway signaling, 2026 presents a year in which strategic clarity can convert into durable advantage. The research is designed to support several categories of decision-making:
- Capacity and investment planning: Leadership teams can use the forecast trajectory to align internal resource allocation, R&D emphasis, and regional business development with the periods and segments most likely to generate demand, while avoiding overcommitment to speculative near-term spikes.
- Portfolio and technology prioritization: By understanding which signaling approaches and deployment contexts are gaining traction, technology and product leaders can sharpen development roadmaps, rationalize legacy support commitments, and sequence innovation investments in line with operator migration pathways.
- Competitive positioning and partnership strategy: The profiling of leading and specialized participants helps identify where consolidation, selective acquisition, channel partnerships, or joint delivery models may strengthen market access, particularly in regions or application segments where local execution and compliance familiarity are decisive.
- Risk and constraint management: Recognizing the cost profile of hardware and infrastructure deployment, the influence of financing structures, and the role of safety certification and regulatory alignment allows executives to design more resilient project models and to anticipate objections in procurement processes.
- Market-entry and expansion timing: For firms evaluating new regions or application areas, the regional and application context provided in the study supports more disciplined entry sequencing, reducing the risk of premature commitments and enabling better alignment with public investment cycles and modernization roadmaps.
These implications are not abstract. They affect bidding strategies, workforce planning, supplier selection, system integration partnerships, and service-model design. The research is intended to reduce uncertainty in exactly those areas where ambiguity most often leads to delayed decisions, misallocated capital, or missed windows of competitive opportunity.
Conclusion: Turning Market Intelligence into Execution
The railway signaling market is expanding against a backdrop of modernization urgency, digital integration, and evolving safety and interoperability expectations. The combination of a solid recent historical base, a measured long-term growth rate, and a competitive field that blends global scale with specialized capability creates both opportunity and complexity. Success in 2026 will depend less on generic market awareness than on a precise understanding of where demand is forming, how procurement criteria are changing, and which capabilities will differentiate participating firms over the full forecast horizon.
This research is designed to provide that understanding. It offers a comprehensive view of market size, growth dynamics, competitive positioning, and operational context while preserving the depth of segment-level intelligence for stakeholders who require it for detailed planning. To access the complete dataset, regional and application breakdowns, and full company profiles that underpin the strategic conclusions summarized here, we invite you to explore the full report on our website. In a market where timing, specification alignment, and execution credibility shape outcomes, the additional granularity available in the complete study can make the difference between reactive positioning and deliberate strategic advantage.
Railway Signaling Market
For detailed analysis of this topic, please visit the official page: Railway Signaling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From 2020 to 2035, the global concrete pump market is projected to grow steadily, with revenue increasing from $3,950 Million in 2020 to $7,200 Million by 2035. This upward trend illustrates the strong and sustained demand for automated and high-efficiency concrete placement equipment across all major regions. The growth trajectory is supported by rising construction activities, technological innovation, and the increasing tendency toward sustainable, high-performance machinery in infrastructure and urban development projects.
Read More - https://bussinessinsights.com/research-report/global-concrete-pump-market
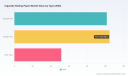
In 2025, the industrial and commercial segments collectively represent the largest shares of application within the global concrete pump market. Industrial applications, including infrastructure and manufacturing, utilize concrete pumps for foundational work, while commercial applications benefit from the quick, efficient placement of concrete in retail and office building projects. Domestic and real estate usage continues to rise, notably in urbanizing regions, reflecting increased investment in residential development. The diversification of end-use applications is expected to intensify with further investments into real estate and infra development.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-concrete-pump-market
Frequently Asked Questions
Who are the key players in Global Concrete Pump Market industry?
The top five players in the Global Concrete Pump Market include SANY Group, Zoomlion Heavy Industry, SCHWING Stetter, Putzmeister, and XCMG. These companies are recognized for their advanced technology, extensive distribution networks, and strong presence in both emerging and developed regions, helping shape the competitive landscape of the market.
What is the Global Concrete Pump Market growth?
The Global Concrete Pump Market has exhibited strong growth, driven by infrastructure and urbanization projects. For instance, in 2023, SANY Group reported a significant increase in international sales, reflecting heightened global demand. The industry is expected to expand at a CAGR of around 5% over the next five years.
Which segment accounted for the largest Global Concrete Pump Market share?
The largest market share within the Global Concrete Pump Market is held by the Commercial Construction segment. This is due to the high demand for concrete pumps in projects like high-rise buildings, bridges, and commercial complexes, where efficient and large-scale concrete placement is essential for timely project execution.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Cigarette Rolling Paper Market to Hit $328M by 2032, 3.5% CAGR
By PW Consulting, 2026-09-16
Cigarette Rolling Paper Market Strategic Outlook 2026: Navigating Volatility and Growth
Executive Summary: The 2026 Decision Point
The global cigarette rolling paper market stands at a critical juncture as we move through 2026. For stakeholders in the tobacco supply chain, packaging sector, and investment community, understanding the nuanced shifts in this industry is no longer optional—it is a strategic imperative. Our latest comprehensive market research report offers a detailed examination of the forces shaping the landscape from 2026 through 2032. This document serves as an introduction to the depth of intelligence available, designed to equip leadership teams with the foresight needed to navigate regulatory changes, material shifts, and competitive pressures.
Cigarette Rolling Paper Market
While the market has experienced a period of contraction in the immediate past, the forecast period suggests a stabilization and eventual recovery driven by innovation and regulatory mandates. This article outlines the strategic value of our research, highlighting key dynamics, competitive structures, and growth vectors without disclosing the granular data required for precise modeling. To access the specific valuations and segment breakdowns necessary for financial planning, stakeholders are encouraged to utilize the full report.
Market Trajectory and Valuation Overview
Understanding the historical context is vital for projecting future performance. The market has undergone a notable correction over the last five years, reflecting broader shifts in smoking habits, regulatory tightening, and economic pressures on disposable income. Our analysis covers historical data from 2020 through the base year of 2025, establishing a robust baseline for forecasting.
In 2025, the market revenue was recorded at approximately USD 258.0 Million. This figure represents a culmination of downward pressure seen in previous years, where valuations dipped from higher levels observed in the early 2020s. However, the forecast period from 2026 to 2032 indicates a shift in momentum. The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 3.5% over this forecast window.
This growth trajectory is not linear. It suggests a market that is finding its footing through premiumization and regulatory compliance rather than volume expansion alone. By 2032, the market valuation is projected to reach new highs, driven by specific catalysts that our report dissects in detail. For business leaders, relying on historical decline rates without accounting for these upcoming inflection points could lead to suboptimal capital allocation. The transition from the 2025 baseline to the 2032 endpoint underscores the importance of timing investments in product portfolios and regional expansions.
Segmentation Dynamics and Material Shifts
The composition of the market is changing faster than the top-line revenue figures suggest. Traditionally, the industry has been categorized by material types and production methods. However, 2026 introduces new complexities in how these segments are valued and prioritized. Our report segments the market by type, application, and region, providing a multi-dimensional view of where value is being created.
Material and Type Evolution
The market is primarily divided into polyolefin films, polyester films, and other types. While traditional synthetic materials maintain a significant presence, the share of value attributed to these segments is under scrutiny due to environmental concerns and regulatory shifts. The report analyzes how manufacturers are balancing cost-efficiency with the demand for newer material specifications. It is no longer just about functionality; it is about compliance and brand perception.
Application Splits
Demand is driven largely by machine-made cigarettes, which continue to represent the bulk of volume. However, the handmade and other application segments offer unique insights into consumer behavior shifts, particularly among roll-your-own (RYO) demographics. Understanding the revenue contribution of each application type is crucial for suppliers targeting specific manufacturing clients or retail consumers. Our analysis details the dependency ratios between these applications and how vulnerabilities in one segment can be offset by strength in another.
Regional Performance
Geographically, the market is dispersed across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Each region presents a distinct risk-return profile. Europe and Asia Pacific hold significant portions of the market value, but growth rates vary considerably. Latin America and Africa, while smaller in current valuation, are identified as regions with high potential for incremental value addition due to specific regulatory changes. The report provides a comparative analysis of these regions, highlighting where infrastructure, demand stability, and regulatory environments favor investment.
Regulatory Dynamics and Premiumization Trends
One of the most potent drivers of market value in 2026 is regulation. Specifically, Low Intensity Paper (LIP) mandates are reshaping the cost structure and revenue potential of the industry. LIP papers are designed to reduce smoke intensity, and their adoption is becoming a requirement in several key markets.
- Price Premiums: Industry data indicates that LIP papers command a price premium of 15-25% over standard papers. This margin expansion is critical for manufacturers able to adapt their production lines to the specialized banding technology required.
- Natural Fiber Alternatives: Consumer preference for sustainability is translating into price tolerance. Natural fiber alternatives, such as hemp, bamboo, and rice-fiber variants, command retail price premiums of 30-50% over standard wood pulp papers. This creates a high-margin niche that is increasingly attractive despite lower volumes.
- Market Value Impact: New LIP mandates in Latin America, Southeast Asia, and Sub-Saharan Africa are expected to add significant incremental market value by 2030. This regulatory-driven demand provides a clear growth vector that is less sensitive to consumer volume fluctuations than traditional smoking rates.
Furthermore, product launches are reflecting this shift. In 2024, a substantial portion of new product launches were eco-friendly and organic rolling papers. This trend is accelerating into 2026, signaling that R&D departments must prioritize sustainability to remain competitive. Our report evaluates which companies are leading this transition and what the barrier to entry looks like for new players.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three players holding a combined share of approximately 38.4% and the top five reaching 45.6%. This concentration suggests that while there is room for niche players, the bulk of market power resides with established specialty paper producers and tobacco product portfolio owners. Success in this environment requires more than just capacity; it requires brand equity, technical capability, and supply chain resilience.
Key Market Participants
Our report provides detailed profiles of the leading companies shaping the industry. These profiles include headquarters, product portfolios, and strategic focus areas.
Cigarette Market
- SWM International (Switzerland): A specialty paper producer offering conventional and LIP cigarette papers. They provide light/ultra-light weight rolling papers in various finishes, positioning themselves as a technical partner for high-specification requirements.
- Julius Glatz GmbH (Germany): A fine paper manufacturer producing Cigla cigarette paper, including LIP versions optimized for high-speed tobacco applications. Their focus is on efficiency and compliance for industrial manufacturing.
- Miquel y Costas & Miquel (Spain): A leading cellulose paper supplier providing cigarette paper and textile pulps. Their vertical integration into pulp supply offers a competitive advantage in cost and quality control.
- OCB (France): A historic manufacturer of premium rolling papers and cones. They have diversified into hemp, bamboo, and rice-fiber variants, catering strongly to the roll-your-own premium segment.
- PDL Papeteries du Léman (France): Produces lightweight rolling papers and cones using certified wood pulp and sustainable fibers. They target the RYO/MYO markets with a strong emphasis on certified materials.
- Republic Brands (United States): A portfolio owner producing and representing brands including OCB, e-z Wider, JOB, DRUM, and PREMIER. Their strategy leverages brand diversity across cigarette and rolling paper categories.
- Moondust Paper Pvt. Ltd. (India): A manufacturer and exporter of premium unbleached brown rolling papers. They serve brands in North America, Europe, and Mexico, highlighting the global nature of niche supply chains.
- Delfort Group (Czech Republic): Offers a complete portfolio of cigarette papers, plug wrap, tipping base, and rolling papers. Their breadth of product allows them to serve multiple segments of the tobacco packaging value chain.
Understanding the specific strengths of these competitors is vital for benchmarking. Our report analyzes their recent developments, production capacities, and strategic moves to help clients identify white space opportunities or potential partnership avenues.
Actionable Intelligence Within the Report
To move from general awareness to specific strategy, stakeholders need granular data. Our full report is structured to provide actionable intelligence across several dimensions:
- Demand Forecasting: Detailed volume and value forecasts broken down by segment and region, allowing for precise revenue modeling.
- Supply Chain Analysis: Examination of raw material availability, cost structures, and logistics challenges affecting production margins.
- Regulatory Impact Assessment: A country-by-country breakdown of upcoming mandates and their estimated financial impact on production costs and pricing strategies.
- Competitive Benchmarking: Deep-dive profiles that go beyond public information, offering insights into market positioning, product development pipelines, and strategic alliances.
- Investment Risks: Identification of key risk factors, including regulatory volatility, raw material price fluctuation, and shifting consumer preferences, with mitigation strategies.
This comprehensive approach ensures that whether you are a manufacturer looking to expand capacity, a supplier seeking to enter new regions, or an investor evaluating portfolio performance, you have the data required to make informed decisions.
Conclusion: The Path Forward
The cigarette rolling paper market in 2026 is defined by a tension between contractionary pressures and value-accretive innovations. While the headline revenue figures show a market stabilizing after a period of decline, the underlying dynamics tell a story of premiumization, regulatory compliance, and material innovation. Companies that fail to adapt to LIP mandates or ignore the premium potential of natural fibers risk being left behind in a market that rewards differentiation.
Our research provides the clarity needed to navigate this complexity. By combining historical analysis with forward-looking forecasts, we offer a roadmap for the 2026-2032 period. The data contained within the full report will enable you to quantify these opportunities, assess competitive threats, and align your strategic roadmap with market realities. We invite you to access the complete market study to unlock the detailed segment data, regional valuations, and company-specific intelligence necessary to secure your position in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Cigarette Rolling Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reverse Transcriptase Market Hits $1,530M in 2025, Projects 6.69% CAGR to $2.4B by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Reverse Transcriptase Market: Navigating Growth and Consolidation Through 2032
The global reverse transcriptase market stands at a critical inflection point. As molecular biology techniques become increasingly central to pharmaceutical development, clinical diagnostics, and academic research, the enzymes that enable RNA-to-DNA conversion are no longer commodities but strategic assets. For executives, procurement leaders, and R&D directors operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for informed capital allocation, partnership formation, and competitive positioning. PW Consulting's latest comprehensive study of the reverse transcriptase sector delivers precisely the analytical rigor required to navigate this evolving landscape.
Reverse Transcriptase Market
Macro Trajectory and Investment Context
Historical revenue patterns indicate a sector that has consistently expanded, with global market size rising from approximately 1.1 billion USD in 2020 to an estimated 1.53 billion USD by 2025. This sustained momentum reflects broader shifts in life sciences funding, accelerated adoption of next-generation diagnostic platforms, and the persistent demand for high-fidelity enzymatic solutions across both developed and emerging markets. The forecast horizon through 2032 projects continued appreciation, with the market expected to surpass the 2.4 billion USD threshold by the end of the period. The compound annual growth rate of 6.69 percent underscores a mid-single-digit expansion profile that balances steady demand with selective premiumization in specialized applications.
For strategic planners, these figures translate into more than aggregate growth. They signal a market where volume expansion is increasingly coupled with value migration toward differentiated product lines, integrated workflow solutions, and regions experiencing rapid infrastructure modernization. The base year of 2025 and the forward-looking window through 2032 provide decision-makers with a sufficiently granular temporal framework to model capital deployment, capacity planning, and technology roadmap alignment.
Structural Segmentation and Demand Drivers
Type-Based Demand Dynamics
Reverse transcriptase demand is structured around distinct enzyme categories that serve different therapeutic, diagnostic, and research endpoints. A substantial portion of revenue continues to originate from HIV reverse transcriptase applications, driven by enduring needs in antiretroviral development, resistance profiling, and global public health initiatives. Hepatitis C virus reverse transcriptase and Hepatitis B reverse transcriptase segments contribute meaningful additional volume, reflecting sustained investment in viral characterization, vaccine research, and diagnostic assay standardization. A smaller but strategically important share is allocated to other reverse transcriptase variants that serve specialized laboratory workflows and emerging biotechnology pipelines.
The relative weighting of these categories is not static. Shifts in funding priorities, regulatory approvals, and the emergence of novel therapeutic modalities continuously reshape which enzyme applications command the greatest commercial attention. Understanding the interplay between these segments requires more than headline figures; it demands an appreciation of how procurement cycles, clinical trial pipelines, and academic grant structures influence long-term demand elasticity.
Application Channels and Workflow Integration
The application landscape reveals how reverse transcriptase enzymes are embedded into downstream workflows. Molecular diagnostics remains a dominant channel, underpinned by the expansion of point-of-care testing, centralized laboratory automation, and the growing reliance on nucleic acid amplification techniques. Viral load analysis constitutes a significant secondary pathway, essential for monitoring treatment efficacy and disease progression in chronic viral conditions. Gene expression analysis and DNA sequencing applications, while representing smaller revenue shares, are critical to high-value research programs, transcriptomics, and advanced genomic characterization. RNA analysis, though currently a niche application, carries strategic significance as laboratories increasingly focus on transcriptome profiling and non-coding RNA discovery.
The strategic implication for 2026 and beyond is clear: procurement decisions are no longer driven solely by unit pricing. Laboratories and diagnostic providers evaluate enzyme performance in the context of workflow compatibility, batch-to-batch consistency, scalability, and total cost of ownership across integrated platforms. Suppliers that align their reverse transcriptase offerings with these broader workflow priorities are positioned to capture premium positioning and longer-term contract commitments.
Competitive Landscape and Strategic Positioning
The reverse transcriptase market exhibits a moderately concentrated structure, with a small group of established life sciences and diagnostics companies commanding the majority of revenue. The top three players collectively represent a significant share of overall market activity, while the top five extend that concentration further, reflecting the high barriers associated with quality certification, global distribution networks, regulatory compliance, and sustained R&D investment. In such an environment, competitive differentiation depends less on broad categorization and more on the precision of product offerings, the strength of technical support, and the ability to integrate enzymatic solutions into larger instrument and assay ecosystems.
Several core companies anchor this competitive landscape. New England Biolabs, headquartered in Ipswich, Massachusetts, maintains a strong reputation for specialized enzyme portfolios and is recognized for its focus on tailored reverse transcriptase offerings that serve both research and applied molecular biology workflows. Thermo Fisher Scientific, based in Waltham, Massachusetts, leverages its expansive instrumentation and consumables ecosystem to position reverse transcriptase products within integrated diagnostic and laboratory automation platforms, appealing to large-scale clinical and industrial laboratories. QIAGEN, located in Hilden, Germany, brings deep expertise in sample preparation and molecular testing, aligning its reverse transcriptase capabilities with standardized diagnostic workflows and global laboratory operations. Merck KGaA, with its headquarters in Darmstadt, Germany, operates across life science research and industrial segments, deploying reverse transcriptase solutions within broader reagent and bioprocessing portfolios. Promega Corporation, in Madison, Wisconsin, is known for its emphasis on reliable enzymatic reagents and focused product development, catering to both academic and commercial research environments. Takarabio, based in Otsu, Japan, delivers specialized reverse transcriptase products that serve Asian and global research markets, with particular attention to performance characteristics relevant to high-precision applications.
The competitive calculus among these firms is increasingly shaped by their ability to offer not just an enzyme, but a validated solution. Product performance, supply chain resilience, regional regulatory alignment, and the depth of customer technical engagement all influence purchasing decisions at the organizational level. In a market where concentration is significant but innovation remains continuous, companies that can demonstrate measurable workflow advantages and maintain consistent quality standards are better positioned to defend and expand their share.
Market Dynamics and Industry Context
Several macro-level dynamics inform the reverse transcriptase market's trajectory. The broader life sciences sector continues to benefit from sustained investment in molecular diagnostics, infectious disease research, and precision medicine initiatives. Public health priorities, particularly those related to chronic viral conditions, have reinforced the importance of reliable enzymatic tools in both clinical and surveillance contexts. Simultaneously, the research community's expanding focus on transcriptomics, viral evolution, and therapeutic discovery sustains demand for high-quality reverse transcriptase enzymes across academic, governmental, and commercial laboratories.
Supply chain considerations also play an increasingly prominent role. As laboratories seek to reduce operational risk and ensure uninterrupted access to critical reagents, vendor reliability, regional sourcing options, and logistical stability have become important evaluation criteria. This trend favors suppliers that can combine technical performance with dependable fulfillment and localized support structures. In addition, the growing standardization of diagnostic workflows and the push toward regulatory conformity in certain application areas create both opportunities and compliance considerations for manufacturers and distributors alike.
For enterprises operating in 2026, these dynamics necessitate a strategic posture that balances cost efficiency with resilience. Short-term procurement optimization must be weighed against the long-term implications of supplier dependence, workflow integration, and the pace of technological change. The most effective strategies will be those that incorporate market intelligence at the level of product trends, regional demand shifts, and competitive capability mapping rather than relying solely on historical purchasing patterns.
Inside the Report: Analytical Depth and Decision-Ready Frameworks
PW Consulting's reverse transcriptase market study is structured to deliver actionable intelligence rather than static observation. The report provides a detailed mapping of revenue trends across the forecast period, contextualized within historical performance to highlight growth inflection points and structural shifts. Segmentation analysis examines how demand is distributed across enzyme types and application channels, enabling readers to identify where commercial emphasis is strengthening and which workflows are driving sustained procurement activity.
The competitive assessment component profiles the strategic posture of leading suppliers, with attention to their market positioning, product focus, and the operational advantages that support their standing. By analyzing the concentration structure and the capabilities of incumbent players, the report provides a framework for evaluating partnership opportunities, competitive threats, and potential whitespace for differentiated offerings.
Real-Time PCR Machines Market
Geographic analysis within the report examines regional market dynamics without reducing the picture to superficial aggregates. It explores the factors that influence demand intensity, including laboratory infrastructure development, diagnostic program expansion, and the maturity of local life sciences ecosystems. This regional lens helps organizations understand where growth is likely to be volume-driven versus value-driven, and where market entry or expansion may require tailored technical or commercial approaches.
Operational and strategic readers will also benefit from the report's synthesis of demand-side considerations, including the influence of workflow integration, quality expectations, and supply chain reliability on purchasing behavior. The study connects these operational realities to broader market trends, offering a coherent basis for scenario planning, capacity forecasting, and investment prioritization. Throughout, the analysis is designed to support executive discussion, cross-functional alignment, and evidence-based decision-making rather than to function as a disconnected data repository.
Why This Study Matters for 2026 Decision-Making
As organizations plan their initiatives for 2026 and look beyond to the remainder of the decade, the reverse transcriptase market presents both opportunity and complexity. A mid-single-digit growth trajectory suggests that the sector will continue to expand, but the distribution of that growth across enzyme categories, application workflows, and regions is uneven and subject to shifting priorities. Market concentration among established players raises the importance of understanding competitive moves, while evolving laboratory expectations around reliability, integration, and total cost of ownership reshape the criteria by which suppliers are judged.
PW Consulting's study is built to address these realities with precision. It translates macro-level market data into strategic context, connects segmentation patterns to operational decision-making, and frames the competitive landscape in terms of capability, positioning, and long-term relevance. For executives evaluating product portfolio direction, procurement strategy, partnership options, or regional expansion, the report supplies a foundation of structured insight that can be applied directly to planning processes.
The full depth of the analysis, including detailed segmentation interpretations, competitive positioning assessments, and forward-looking scenario considerations, is available in the complete report. Readers seeking to translate market intelligence into actionable strategy will find that the study goes beyond headline figures to provide the analytical clarity required for confident decision-making throughout the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Reverse Transcriptase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LSA Market Hits $606M in 2025, Forecast to Reach $845M by 2032 at 4.85% CAGR
By PW Consulting, 2026-09-16
The Light Sport Aircraft Market: Strategic Horizons for 2026 and Beyond
The Light Sport Aircraft (LSA) sector is currently navigating a transformative period defined by regulatory evolution, shifting consumer preferences, and a steady expansion of market boundaries. For stakeholders operating within general aviation, aviation manufacturing, or flight training ecosystems, understanding the trajectory of this market is no longer optional—it is a strategic imperative. Our latest market research publication, the Light Sport Aircraft (LSA) Market report, offers a comprehensive examination of the industry’s past performance and future potential, designed specifically to inform high-stakes decision-making in 2026 and onwards.
This article serves as a strategic preview of the research, outlining the broader economic narrative, the regulatory forces reshaping the competitive landscape, and the practical intelligence contained within the full study. By exploring the structural dynamics of the LSA market, we aim to highlight why precise, data-backed intelligence is critical for capital allocation, product development, and market entry strategies in the coming years.
Market Trajectory: Steady Growth Amid Evolving Demand
The LSA market has demonstrated consistent resilience over the past half-decade. Between 2020 and 2025, the market navigated the complexities of a post-pandemic aviation landscape while maintaining a clear upward revenue trajectory. Historical data indicates that the market size in 2020 stood at approximately 482.35 million, gradually climbing through the subsequent years to reach an estimated 606.25 million by 2025. This growth pattern reflects a steady, compounding expansion rather than volatile spikes, suggesting a maturing market base with sustained demand drivers.
Our forecast analysis projects this positive momentum to continue through the end of the decade and into the early 2030s. We anticipate the market to reach roughly 640.4 million in 2026 and continue its ascent, with projected figures exceeding 844.73 million by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 4.85 percent. Such a trajectory signals a healthy, long-term expansion phase. However, for strategic planners, the aggregate numbers only tell part of the story. The true value lies in understanding the underlying velocity, the regional drivers, and the application segments that are contributing most significantly to this aggregate growth. The full report dissects these components with granular precision, offering a level of detail essential for targeted strategic planning.
The MOSAIC Rule and the Regulatory Paradigm Shift
No discussion of the LSA market in 2026 can proceed without addressing the profound regulatory changes introduced by the Federal Aviation Administration (FAA). In July 2025, the FAA finalized the MOSAIC rule, a landmark decision that fundamentally alters the definition and eligibility criteria for Light Sport Aircraft. Historically, LSA classifications were heavily constrained by fixed weight and performance metrics. The MOSAIC rule shifts this framework to performance-based criteria, such as stall speed, effectively expanding the scope of eligible aircraft. This includes allowances for higher maximum weights and configurations accommodating up to four seats, provided they meet specific performance thresholds.
The effective dates of this rule create a phased implementation environment. Pilot privileges associated with the new criteria began on October 22, 2025, while the full certification requirements for new make and model combinations will come into force on July 24, 2026. This staggered timeline is of critical importance to manufacturers and operators. It creates a window of adaptation for existing manufacturers while setting a new compliance bar for future entrants. The market impact of MOSAIC is multifaceted: it could stimulate demand by offering aircraft with greater utility and capacity, potentially attracting new demographics of pilots and recreational users. Conversely, it imposes new certification burdens and compliance costs on Special Light Sport Aircraft (SLSA) manufacturers, who must now demonstrate adherence to accepted industry consensus standards for design, production, and airworthiness under 14 CFR §22.100.
Light Sport Aircraft (LSA) Market
Our research provides a detailed analysis of how this regulatory shift is anticipated to redistribute market share, influence type certification strategies, and alter the risk profiles of various aircraft categories. We examine the operational implications of these changes, including the requirement for new make/model combinations to notify the FAA AIR-842 before special airworthiness certificates can be issued. The interplay between expanded market opportunity and heightened regulatory compliance is a central theme of our analysis, offering decision-makers a clear view of the landscape they will operate in.
Competitive Landscape: A Diverse and Fragmented Ecosystem
The LSA market is characterized by a broad and geographically diverse competitive landscape. The industry features a multitude of manufacturers ranging from established aerospace entities to specialized niche producers. This fragmentation contributes to a dynamic environment where innovation and differentiation are key competitive advantages. Our report includes a comprehensive roster of key companies that are actively shaping the market, detailing their operational bases, manufacturing specializations, and compliance profiles.
Prominent participants include entities such as Aero Adventure, based in Deland, Florida, which offers the Aventura II model under FAA 14 CFR 21.190 compliance. AERO AT Sp. z o.o., located in Mielec, Poland, produces the AT-4 LSA series, often utilizing Rotax engine options. Similarly, AeroJones Aviation USA LLC in Zephyrhills, Florida, specializes in the AJ Sport model with Rotax 912 iS engine compliance. The landscape also encompasses manufacturers like Aeropilot SRO in Čáslav, Czech Republic, offering the Legend 600 Amphib series with multiple engine configurations, and Aeroprakt Manufacturing Sp. z o.o. in Zakliczyn, Poland, known for the A-22LS and A32 Vixxen models.
Other significant players include Aeropro CZ in Hluk, Czech Republic, producing Aerotrek and Eurofox models; Aerospool SRO in Prievidza, Slovakia, with the Dynamic WT9; and Aerosport Ltd in Hohentengen, Germany, manufacturing Ikarus C42 series models. The list extends to Air Creation in Aubenas, France, with Tanarg models; Air Elite Aviation in Three Rivers, Michigan, offering the Storm Rally LSA; and Airborne Windsports PTY LTD in Redhead, Australia, producing weight-shift-control EDGE series models.
Manufacturers such as Aircraft Mfg & Development Co in Eastman, Georgia, offer CH series models licensed from Zenair. AirMax Construcoes Aeronauticas in São Paulo, Brazil, produces the SeaMax M-22, while Airtime Aircraft Inc. in Fort Walton Beach, Florida, offers the Cygnet model. The market also includes the American Legend Aircraft Company in Sulphur Springs, Texas, known for AL series models with Continental and Lycoming engines, and Apollo Aircraft Inc in Zephyrhills, Florida, with the Apollo LSA Fox and Delta Jet series.
Further diversity is seen with Arion Aircraft LLC in Shelbyville, Tennessee, offering the Lightning LS-1 with Jabiru engines; Atec VOS in Libice nad Cidlinou, Czech Republic, with the Atec 321 Faeta; and Aveko SRO in Brno, Czech Republic, producing the VL-3C-1. Other notable entities include Bilsam Aviation in Poznań, Poland, with the Sky Cruiser; Breezer Aircraft GmbH in Bredstedt, Germany; and BRM Aero in Kunovice, Czech Republic, offering Bristell series models. Bushcaddy International Inc. in Summerstown, Ontario, produces the BushCaddy Explorer. The list continues with Cessna Aircraft Co in Wichita, Kansas, historically associated with the 162 Skycatcher; CGS Aviation in Mulberry, Florida, with the Hawk Arrow II; Colyaer SL in Spain, offering the Freedom S100; and Composite Aeronautic Group SL in Zaragoza, Spain, with the Toxo SLSA.
Costruzioni Aeronautiche Tecnam S.p.A. in Capua, Italy, offers a wide range of models including the Astore and P92/Echo series, P2002 Sierra, P2004 Bravo, and P2008. Criquet Aviation in DeLand, Florida, produces the Storch FI-156. CubCrafters Inc. in Yakima, Washington, offers the Sport Cub and Carbon Cub models with various engine options. Czech Aircraft Works in Kunovice, Czech Republic, produces models like the CH 601 XL RTF and SportCruiser. Czech Sport Aircraft and Czech Sportplanes SRO also operate in Kunovice, offering SportCruiser and Dynamic WT9 models. Finally, Delta Trikes Aviation SARL in Montélimar, France, offers Voyageur II and other weight-shift-control models.
This diverse roster reflects the global nature of LSA manufacturing and the variety of product offerings available. Our research goes beyond mere enumeration. We analyze the competitive positioning of these firms, their strategic responses to regulatory changes, and their potential for market share expansion or consolidation. The report examines how companies are adapting their product lines, engine selections, and compliance strategies to maintain relevance and competitiveness in a market that is becoming increasingly performance-oriented.
Segmentation Dynamics and Value Creation Opportunities
While the aggregate market size and growth rate provide a macro-level view, strategic success often depends on a nuanced understanding of market segmentation. The LSA market is segmented across multiple dimensions, including geographic regions, aircraft types, and application areas. Each segment exhibits distinct growth characteristics, demand drivers, and competitive intensities.
For instance, certain regions demonstrate significantly higher concentration and revenue generation, reflecting established general aviation infrastructures, regulatory maturity, and higher disposable income levels. Other regions show emerging potential, driven by increasing aviation awareness, infrastructure development, and regulatory harmonization efforts. The full report provides a rigorous breakdown of these regional dynamics, identifying where opportunities for market penetration or partnership may be most viable.
Similarly, segmentation by aircraft type reveals preferences for different configurations, ranging from two-seat to four-seat models. The distribution of revenue across these types is not uniform and is subject to change as the MOSAIC rule potentially shifts demand toward higher-capacity aircraft. Understanding the current revenue contributions and growth trajectories of each type category allows manufacturers and investors to assess product portfolio alignment and future development priorities.
Application-based segmentation further illuminates how LSAs are being utilized. Personal recreation remains a dominant application, driven by the appeal of accessible flying and leisure travel. Flight training represents another critical segment, where LSAs are valued for their lower operating costs and suitability for initial pilot instruction. Commercial transport applications, while smaller in relative terms, offer specialized opportunities for niche operations such as aerial survey, patrol, or cargo delivery in remote areas. The interplay between these applications and the evolving regulatory environment creates distinct value propositions for different stakeholders. Our research delineates these application-specific trends, helping clients identify the most promising use cases and tailor their strategies accordingly.
Operational Safety and Regulatory Compliance as Strategic Assets
In the current LSA market environment, operational safety and regulatory compliance are not merely administrative requirements; they are strategic assets that influence customer confidence, insurance costs, and market reputation. The FAA's continued focus on safety monitoring is evident in reports such as the 2024 SLSA Continued Operational Safety (COS) Report, which documents trends in fatal and non-fatal accidents and incidents across SLSA classes. This report includes analysis by manufacturer fleet size and occurrence categories, providing valuable feedback loops for manufacturers and operators.
Furthermore, SLSA manufacturers are required to maintain a Partnership for Safety Plan (PSP) with the FAA to demonstrate continued compliance. This ongoing engagement with regulatory bodies ensures that safety remains a central pillar of the LSA ecosystem. The April 2026 SLSA Make/Model Directory highlights these requirements and specifies that only assigned Aviation Safety Inspectors (ASI) may issue special airworthiness certificates for new make/model combinations not appearing in the directory. These procedural details underscore the importance of maintaining rigorous compliance standards and building robust relationships with regulatory authorities.
Our market research integrates these safety and compliance dynamics into the broader market analysis. We evaluate how safety records and compliance reputations impact competitive positioning and market access. For potential entrants or existing manufacturers seeking to expand their fleet, understanding the nuances of the COS reporting framework, PSP requirements, and the certification process for new models is essential. The report provides actionable insights into navigating this regulatory landscape, mitigating risk, and leveraging safety performance as a differentiator.
Strategic Imperatives for 2026 Decision-Makers
As the market moves forward, several strategic imperatives emerge for stakeholders operating in the LSA sector. First, agility in response to regulatory change is paramount. The MOSAIC rule presents both opportunities and challenges, and companies must be prepared to adapt their product development cycles, certification strategies, and marketing messages to align with the new performance-based criteria. Early movers who can effectively navigate the transition to the July 2026 certification deadline may gain a competitive advantage.
Second, the fragmented nature of the competitive landscape suggests that differentiation through innovation, quality, and service will remain key success factors. With a wide array of manufacturers offering diverse models and engine configurations, customers have numerous choices. Companies must clearly articulate their value proposition, whether through advanced avionics integration, superior performance characteristics, lower total cost of ownership, or specialized support networks. The full report includes a competitor benchmarking analysis that helps identify white spaces and areas where differentiation can be most effective.
Third, understanding the demand drivers across different segments is critical for resource allocation. Investing in product lines or market expansion initiatives that align with high-growth segments or underserved applications can yield higher returns. The detailed segmentation analysis in our report enables clients to prioritize initiatives based on empirical data rather than assumptions.
Low Speed Vehicle Market
Finally, the importance of safety and compliance cannot be overstated. In an industry where trust is built on reliability and adherence to standards, a strong safety culture and transparent compliance practices are indispensable. The report highlights how leading companies are integrating safety into their operational DNA and how this contributes to long-term sustainability and brand equity.
Unlocking the Full Intelligence: Access the Complete Report
This article has provided a high-level overview of the key themes, market dynamics, and strategic considerations shaping the Light Sport Aircraft market in 2026. We have explored the steady growth trajectory, the transformative impact of the MOSAIC rule, the diverse competitive landscape, and the critical role of segmentation and compliance. However, this preview only scratches the surface of the actionable intelligence contained within our comprehensive market research study.
The full Light Sport Aircraft (LSA) Market report offers a depth of analysis that is essential for making informed, high-stakes decisions. It provides precise market size estimates for specific regions, detailed revenue breakdowns by aircraft type and application, and nuanced forecasts that account for the interplay of regulatory, economic, and technological factors. The report also includes in-depth profiles of key companies, an assessment of competitive strategies, and a thorough examination of the regulatory environment, including the latest FAA directives and their implications.
For executives, investors, and strategic planners, access to this level of detail is invaluable. It enables the formulation of data-driven strategies, the identification of high-potential opportunities, and the mitigation of risks associated with market volatility and regulatory complexity. We invite you to explore the complete findings of our research. Visit our website to download the full report and gain the comprehensive market intelligence needed to navigate the future of the LSA sector with confidence.
For detailed analysis of this topic, please visit the official page: Light Sport Aircraft (LSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Biosolids Processing Equipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global biosolids processing equipment market demonstrates impressive revenue growth from 2020 to 2035. In 2025, the market stands at approximately USD 9,800 Million, propelled by new municipal projects, stricter environmental regulations, and innovations in resource recovery. Consistent investments in emerging regions and the uptake of advanced treatment technologies sustain a positive trajectory, with revenues anticipated to surpass USD 16,900 Million by 2035. This growth is underpinned by robust demand across public and private sectors, coupled with expanding applications in agriculture and energy generation.
Read More - https://bussinessinsights.com/research-report/global-biosolids-processing-equipment
The municipal segment dominates application shares in the biosolids processing equipment market for 2025, driven by increasing investments in public wastewater infrastructure and compliance targets. Industrial applications followed, especially in food and beverage and chemical sectors, where stringent effluent norms necessitate efficient sludge management. Agricultural use of processed biosolids is gaining traction due to its value in soil conditioning, while commercial and energy generation applications collectively contribute a notable share, reflecting growing interest in waste-to-energy projects and sustainable urban planning strategies.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-biosolids-processing-equipment
Frequently Asked Questions
Who are the key players in Global Biosolids Processing Equipment industry?
The top five players in the global biosolids processing equipment market are Veolia Water Technologies, SUEZ, Alfa Laval, HUBER SE, and Andritz AG. These companies are recognized for their strong portfolios, technological innovation, global presence, and comprehensive wastewater treatment solutions tailored to municipal and industrial clients.
What is the Global Biosolids Processing Equipment growth?
The global biosolids processing equipment market has experienced robust growth, driven by rising environmental regulations and sustainable waste management needs. In 2023, Andritz AG reported significant order volume growth in biosolids drying systems, reflecting greater investment in advanced treatment and recycling applications worldwide.
Which segment accounted for the largest Global Biosolids Processing Equipment share?
Municipal wastewater treatment applications held the largest share of the global biosolids processing equipment market in 2023. Increasing urbanization, stricter environmental regulations, and investments in upgrading municipal sewage infrastructure have further propelled demand for efficient biosolids management solutions in urban areas.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com