

Blogs
PW Consulting: Monofilament Line Market Reaches $427M in 2025, Set for 4.2% CAGR Through 2032
By PW Consulting, 2026-09-16
The Monofilament Fishing Line Market in 2026: Strategic Imperatives Amid Regulatory Shifts and Material Volatility
The global outdoor recreation sector continues to evolve under the influence of shifting consumer preferences, tightening environmental regulations, and volatile raw material economics. Within this landscape, the monofilament fishing line industry occupies a critical niche where durability, cost-efficiency, and compliance increasingly dictate competitive positioning. As we move through 2026, enterprises operating across manufacturing, distribution, retail, and specialty retail channels must navigate a complex matrix of demand drivers, formulation constraints, and supply chain dynamics. Our latest market research report delivers a comprehensive, decision-ready analysis of this industry, structured to inform product strategy, capacity planning, sourcing decisions, and competitive positioning for the 2026–2032 horizon.
This article serves as a strategic preview of the full study. It outlines the structural forces shaping market trajectories, highlights the operational content embedded in the report, and demonstrates why forward-looking enterprises require granular, multi-dimensional intelligence rather than high-level aggregates. The underlying research combines historical reconstruction, forward-looking forecasting, competitive profiling, and regulatory impact mapping to produce a cohesive intelligence framework. Readers seeking precise regional valuations, segment-level revenue splits, and application-specific penetration metrics will find those details reserved for the complete publication, where they are presented alongside demand elasticity models, supplier concentration analysis, and scenario-based forecasting tools.
Macro Trajectory: Structural Growth and the 2026–2032 Outlook
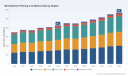
The market has demonstrated consistent expansion over the past half-decade, with total industry revenue progressing from approximately USD 350.0 million in 2020 to an estimated USD 427.0 million in 2025. This historical arc reflects steady demand from recreational anglers, commercial operators, and specialty retail channels, supported by product innovation and gradual market maturation. Looking ahead, the forecast period spans 2026 through 2032 and is anchored by a projected compound annual growth rate of 4.2 percent. Under this trajectory, industry revenue is expected to reach roughly USD 450.72 million in 2026 and continue its upward progression toward approximately USD 568.0 million by 2032.
Several structural factors underpin this growth path. First, recreational fishing participation in key markets has stabilized above pre-pandemic levels, with anglers increasingly investing in higher-quality line systems that balance tensile strength, knot integrity, and abrasion resistance. Second, the broader outdoor equipment ecosystem is benefiting from sustained consumer spending on leisure activities, which indirectly supports accessory categories such as monofilament lines, leaders, and replacement spools. Third, ongoing improvements in polymer processing and extrusion consistency have enabled manufacturers to deliver more predictable performance characteristics, reinforcing brand loyalty and repeat purchases.
At the same time, the forecast is not linear. The 2026–2032 window includes years where supply-side pressures, regulatory transitions, and material cost fluctuations may compress margins or shift demand toward alternative formulations. The full report models these inflection points explicitly, separating baseline growth from sensitivity scenarios that account for crude oil-driven resin pricing, regional compliance deadlines, and competitive product launches. Rather than presenting a single deterministic curve, the analysis maps a range of plausible outcomes, giving decision-makers the ability to stress-test capacity plans, inventory strategies, and pricing models against multiple external conditions.
Raw Material Volatility and Formulation Realities
Monofilament fishing line production is inherently tied to petrochemical feedstock economics. Crude oil price movements since early 2022 have introduced pronounced cost variability for nylon polymer resins, which remain the dominant feedstock for the category. Prices reached a 14-year peak near USD 140 per barrel in March 2022 before retreating to a low of approximately USD 75 per barrel in March 2023, and this volatility has directly influenced input costs throughout the manufacturing chain. Even as feedstock curves stabilize, producers must manage the indirect effects on energy usage, logistics, and downstream pricing expectations.
Within this material environment, nylon-based monofilament continues to command the largest share of industry demand, reflecting its balance of durability, versatility, and cost-effectiveness. Its strength-to-flexibility profile makes it suitable for a wide range of fishing conditions, from freshwater angling to targeted saltwater applications. The category’s performance characteristics have also facilitated steady adoption among both novice and experienced users, reinforcing its central position in product portfolios and retail assortments.
However, material selection is no longer determined by performance and cost alone. Environmental scrutiny of per- and polyfluoroalkyl substances has accelerated reformulation efforts across the industry. Several jurisdictions have already imposed restrictions on PFAS-containing products, prompting manufacturers to evaluate alternative coatings, surface treatments, and polymer blends. The full report examines how these formulation shifts affect production economics, quality assurance protocols, and time-to-market for compliant product lines. It also maps the interaction between raw material volatility and regulatory compliance, helping enterprises anticipate where cost pressures may intensify and where reformulation investments may yield long-term differentiation.
Regulatory Dynamics and Compliance Trajectories
Regulatory developments are reshaping the competitive baseline for monofilament fishing line suppliers and downstream distributors. In the United States, the Environmental Protection Agency adopted a one-time reporting requirement covering per- and polyfluoroalkyl substances manufactured or imported between January 1, 2011, and December 31, 2022, including imported articles that contain these substances. This reporting framework increases transparency across supply chains and encourages manufacturers to document material inputs with greater precision. Beyond reporting, state-level actions are introducing direct market constraints. California prohibits the manufacture, distribution, sale, and offer for sale of PFAS-containing textile articles, including fishing line, beginning January 1, 2025. In parallel, the Minnesota Pollution Control Agency banned the sale of PFAS-containing products, including fishing line, starting January 1, 2026.
These measures affect both product availability and formulation strategy. Manufacturers with broad multi-state distribution must now navigate heterogeneous compliance timelines, assess legacy inventory exposure, and determine whether to accelerate regional reformulation or consolidate around compliant product families. Distributors and retailers face parallel responsibilities, particularly around assortment planning, shelf-life management, and customer communication. The full report breaks down these obligations by jurisdiction, mapping the operational implications for sourcing, inventory rotation, labeling, and channel strategy. It also evaluates how proposed federal adjustments to broader environmental standards may indirectly influence feedstock availability and production scheduling.
Importantly, regulatory pressure is not purely a compliance burden; it is also a catalyst for innovation. Companies that proactively invest in non-PFAS formulations and recycled-content options can convert regulatory risk into market differentiation. The report evaluates this dynamic in detail, linking compliance pathways to brand positioning, customer segmentation, and retail partner expectations. Readers who require precise regional compliance calendars and product-category coverage will find those specifics in the full analysis, where they are integrated with sourcing recommendations and reformulation feasibility frameworks.
Competitive Landscape and Strategic Positioning
The industry features a concentrated set of active manufacturers that compete across product performance, brand recognition, distribution reach, and increasingly, sustainability credentials. Berkley Fishing, headquartered in Columbia, South Carolina, remains a prominent producer of monofilament lines, with its Trilene series serving as a widely recognized reference point for reliability and broad application coverage. Sufix Fishing Line, based in Minnetonka, Minnesota, continues to expand its monofilament offerings while responding to sustainability-driven demand through product innovation. Momoi Fishing Line, operating from Kobe, Japan, is known for specialized series such as Hi-Catch and Diamond, which emphasize consistent performance characteristics for targeted angling use cases.
Other notable participants include Seaguar, with headquarters in Louisville, Kentucky, and a product lineup that encompasses monofilament options alongside its broader line portfolio; Spiderwire, also based in Columbia, South Carolina, which markets monofilament variants such as Ultracast Ultimate within its broader product ecosystem; Sunline Fishing Line, operating from Torrance, California, with monofilament products positioned for both retail and specialty channels; and Daiwa Corporation, headquartered in Foothill Ranch, California, which integrates monofilament lines into a wider range of fishing equipment offerings. Together, these firms illustrate a market where brand heritage, product consistency, and channel access remain central to competitive success.
Monofilament Fishing Line Market
Market concentration metrics indicate that the top three companies collectively account for approximately 35 percent of industry revenue, while the top five firms reach roughly 50 percent. This concentration suggests that scale advantages in production, distribution, and brand investment continue to matter, but it also leaves meaningful room for specialization, regional strength, and niche positioning. The full report profiles each core company’s product architecture, geographic footprint, recent strategic moves, and competitive vulnerabilities. It also assesses how product launches, reformulation initiatives, and distribution partnerships are reshaping share dynamics across retail and specialty channels.
Recent activity underscores the strategic importance of sustainability-aligned innovation. In June 2026, Sufix Fishing Line launched the Sufix Recycline brand, featuring 100 percent recycled fishing line, including monofilament options, targeting sustainability-focused consumers. This move highlights how environmental messaging, material circularity, and product performance must be integrated to resonate with modern buyers. The report situates such launches within broader competitive trends, evaluating how sustainability claims influence retailer assortment decisions, customer perception, and long-term portfolio strategy.
Report Architecture and Operational Utility
The full market research report is designed as a decision-support toolkit rather than a static summary. It opens with market sizing and forecasting, presenting total industry revenue across historical and forecast periods, along with growth decomposition that isolates the contributions of volume dynamics, pricing behavior, and product-mix evolution. From there, the analysis transitions into segmentation structures that organize demand by geography, product type, and application, enabling readers to identify where growth concentrates, where performance differs, and where strategic investment is most likely to generate returns.
The competitive section provides company-level profiles, recent development tracking, and concentration analysis. It explores how leading manufacturers differentiate through product architecture, brand positioning, and channel strategy, while also mapping the operational impact of regulatory and material conditions on production planning. In parallel, the report examines market dynamics such as supply chain dependencies, raw material pricing exposure, and compliance-driven reformulation requirements. These sections are linked so that readers can trace how upstream cost shifts and regulatory changes propagate through product design, pricing, and competitive response.
To support practical decision-making, the study includes forward-looking scenario analysis, demand sensitivity considerations, and strategic recommendations tailored to manufacturers, distributors, and retail operators. It identifies where capacity expansion, portfolio rebalancing, supplier diversification, and compliance investment are likely to create the strongest strategic advantage. The full publication also includes detailed regional and segment-level data that are not disclosed in this preview, allowing clients to build localized plans with confidence. Readers who require direct access to those figures, along with the underlying methodology and forecasting assumptions, are encouraged to consult the complete report.
Why This Research Matters for 2026 Decision-Making
Enterprises operating in the monofilament fishing line market face a rare combination of challenges and opportunities in 2026. Raw material volatility continues to complicate cost planning, while regulatory timelines are compressing the window for formulation adjustments and inventory transitions. At the same time, consumer interest in durable, high-performance lines remains solid, and sustainability-oriented innovation is creating new avenues for differentiation. In this environment, strategic decisions cannot rely on broad trends alone. They require a clear view of where demand is strengthening, how regulatory obligations differ by market, which competitive moves are reshaping share, and how material conditions will influence margin structures over the forecast period.
The full report delivers that view. It connects macro growth patterns with segment-level demand behavior, links regulatory developments to operational consequences, and places competitive activity in the context of shifting customer expectations. For manufacturers, it supports product roadmap planning, sourcing strategy, and compliance investment prioritization. For distributors and retailers, it informs assortment decisions, inventory forecasting, and regional merchandising approaches. For investors and strategic partners, it provides a structured basis for evaluating growth potential, concentration risk, and the durability of competitive advantages.
Monofilament Market
This preview has outlined the strategic logic behind the study and the categories of insight it contains. The complete publication expands each area with detailed data, scenario modeling, and actionable recommendations designed for 2026 planning cycles and beyond. Organizations that integrate this intelligence into their decision processes will be better positioned to manage volatility, meet compliance expectations, and capture growth in a market that rewards both operational discipline and forward-looking innovation. The full report is available through the source page, where readers can access the complete dataset, methodology notes, and executive recommendations needed to translate market intelligence into concrete strategic action.
For detailed analysis of this topic, please visit the official page: Monofilament Fishing Line Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E-Liquids Market Hits $1.125B in 2025, Projects 12.58% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Vapor Shift: Strategic Intelligence for the 2026 E-Liquids Market
The global e-liquids market stands at a critical inflection point. As regulatory frameworks tighten and consumer preferences evolve, understanding the precise trajectory of this sector is no longer optional—it is a prerequisite for sustainable growth. Our latest market research publication offers a comprehensive roadmap for navigating the complexities of the e-liquids landscape from 2026 through 2032. This report is designed not merely as a data repository, but as a strategic asset for decision-makers who need to anticipate shifts rather than react to them.
For industry stakeholders, the difference between market participation and market leadership often comes down to the quality of intelligence available at the point of decision. The following analysis outlines the macro-economic environment, the competitive architecture, and the regulatory currents shaping the sector, demonstrating why deep-dive research is essential for capital allocation, product development, and market entry strategies in the coming year.
Macro-Economic Trajectory and Growth Fundamentals
The historical performance of the e-liquids market demonstrates a robust upward trend, reflecting the continued shift away from traditional combustion products toward vaporized nicotine delivery systems. Between 2020 and 2025, the sector experienced consistent expansion, building a substantial revenue base that sets the stage for the forecast period. Current estimates place the total market valuation at USD 1,125.0 Million in 2025, marking a significant increase from the 2020 baseline.
Looking forward, the growth momentum is projected to accelerate. Our forecast models indicate that the market will reach USD 1,265.53 Million in 2026, continuing to climb steadily toward a projected valuation of USD 2,470.0 Million by 2032. This trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 12.58 percent during the 2026-2032 forecast period. Such a rate suggests that the e-liquids sector will continue to outpace many traditional consumer goods categories, driven by innovation in device compatibility, flavor profiling, and evolving regulatory approvals that legitimize specific product categories.
For strategic planners, these figures represent more than just top-line growth; they indicate a maturing market where consolidation and specialization are becoming key drivers. The sheer scale of the projected revenue unit expansion over the next six years implies significant opportunities for players who can secure supply chain stability and navigate the varying compliance landscapes across different jurisdictions.
Market Structure and Concentration Dynamics
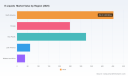
One of the most critical aspects of strategic planning in this sector is understanding the competitive density. The market is not uniformly distributed; rather, it exhibits a high degree of concentration among key players. Current analysis reveals a CR3 (Concentration Ratio of the top three firms) of 62.0 percent, while the CR5 extends to 78.0 percent. This level of concentration highlights the dominance of established tobacco giants and specialized nicotine technology firms that have secured significant market share through brand recognition, regulatory approvals, and distribution networks.
This concentration has profound implications for new entrants and existing mid-sized players. It suggests that while the total addressable market is growing, the pathway to capturing share requires distinct differentiation. Companies cannot simply rely on volume; they must offer unique value propositions, whether through proprietary flavor technologies, superior hardware integration, or specialized OEM/ODM manufacturing capabilities. The gap between the top-tier concentrated firms and the long tail of the market is where strategic agility becomes most valuable.
Our research delves into the specific structural dynamics that allow certain entities to maintain these high concentration levels while others struggle to gain footholds. Understanding the barriers to entry, the cost structures of compliant manufacturing, and the distribution leverage held by incumbents is vital for any organization considering M&A activity or organic expansion.
Competitive Landscape and Key Players
The competitive environment is a mix of established multinational tobacco corporations and specialized e-liquid manufacturers. This duality creates a complex ecosystem where traditional smoke-free portfolios intersect with agile, niche liquid producers. Our report profiles the strategies and operational focuses of the industry's pivotal companies.
Major multinational entities such as Philip Morris International Inc., British American Tobacco PLC, Imperial Brands PLC, and Japan Tobacco International are heavily invested in the e-vapor space. These companies integrate e-liquids into broader smoke-free business portfolios, leveraging their existing distribution channels and regulatory expertise to maintain market presence. Their approach often focuses on standardized, compliant products that align with global regulatory trends.
On the other side of the spectrum are specialized manufacturers and technology developers. JUUL Labs Inc. and Logic Technology Development LLC have historically focused on specific delivery systems and cartridge formats, emphasizing authorized variants and specific flavor profiles. NJOY LLC continues to push pod formats designed for ease of use and nicotine delivery efficiency. Meanwhile, specialized manufacturers like Hangsen have carved out a significant role as world-leading OEM/ODM partners, providing solutions to markets across over 86 countries. This highlights a crucial supply-side dynamic: the reliance of many brands on specialized manufacturing partners to scale production while adhering to quality guidelines.
Independent premium brands such as Ruthless Vapor, Mister-E-Liquid, and Vape Base Ltd also play a crucial role in shaping consumer preferences, particularly in the flavored e-liquid segment. These companies often lead in flavor innovation and community engagement, setting trends that larger conglomerates may later adopt or regulate around. Our analysis examines how these different tiers of competitors interact, compete for shelf space, and navigate the varying regulatory requirements that define their respective operational zones.
Regulatory Environment and Industry Dynamics
No strategic discussion of the e-liquids market is complete without addressing the regulatory environment, which remains the single most significant variable affecting market access and profitability. As of May 2026, the regulatory landscape is characterized by a patchwork of authorizations and duties that vary significantly by region.
In the United States, the FDA continues to be the gatekeeper. As of May 2026, the FDA has authorized 45 ENDS products, representing the only ones legally marketed in the United States. This tight control over market entry creates a high barrier for new products but provides stability for those who secure authorization. Recent developments underscore this reality; in June 2025, the FDA granted premarket authorizations to Swedish Match North America, Inc. for tobacco-flavored e-liquid products. Furthermore, in May 2026, the FDA authorized the marketing of four Glas ENDS products featuring e-liquid pods with non-tobacco and non-menthol flavors. This authorization is particularly significant as it signals a potential pathway for flavor diversity under strict compliance conditions, a key area of interest for consumer growth.
Across the Atlantic, the UK has introduced new fiscal measures. On 01 April 2026, the UK HMRC opened applications for the Vaping Products Duty of £2.20 per 10ml on all vaping liquids. This duty imposes a direct cost on production and distribution, which will inevitably influence pricing strategies and margin structures for companies operating in or exporting to the UK market. Strategic budgeting for 2026 and beyond must account for these duty implications to avoid margin erosion.
State-level actions also contribute to the complexity. The Virginia Annual Report on Liquid Nicotine and Nicotine Vapor Products, published in February 2026, records 13 manufacturers certified and $380,000 in revenue collected, indicating active state-level monitoring and taxation. Similarly, Arkansas requires manufacturers to certify compliance with directory rules for vapor products and e-liquid products, with penalties for non-compliance starting November 2025. These fragmented regulatory requirements necessitate a robust compliance infrastructure that our report details extensively.
Industry Activity and Capacity Expansion
Despite regulatory headwinds, industry activity remains vigorous. Corporate strategies reflect a commitment to growth and capacity building. In February 2026, VPZ announced a multi-million-pound investment to expand e-liquid manufacturing capacity and launch new retail locations. This move signals confidence in the long-term demand for compliant vaping products and highlights the importance of physical retail presence alongside manufacturing scalability.
Trade activity also continues to facilitate commercial connections. The Total Product Expo in April 2026 featured a dedicated e-liquids and vapes category with significant commercial activity for independent retailers. Such events are critical nodes in the supply chain, where manufacturers connect with distributors and retailers to secure shelf space and negotiate terms for the upcoming fiscal year. Our market research captures the sentiment and transaction trends observed at these key industry gatherings, providing qualitative context to the quantitative data.
E-cigarette Market
Strategic Value of the 2026 Market Research
Given the interplay of high market concentration, rapid growth projections, and a shifting regulatory moat, generic market data is insufficient for high-stakes decision-making. This report provides the granular intelligence required to transform uncertainty into strategy.
Our analysis goes beyond surface-level metrics to explore the segmentation splits that drive revenue. We examine the performance of different product types, including Pre-Filled and Bottled E-Liquids, and analyze how application preferences such as Tobacco, Fruit, and Menthol flavors influence purchasing behavior in different regions. However, the specific weightings and regional revenue distributions are detailed within the full report to maintain competitive confidentiality and ensure that subscribers receive the most actionable, non-public insights.
The core value of this research lies in its operational applicability. For investors, it offers a clear view of where capital is flowing and which segments offer the highest risk-adjusted returns. For manufacturers, it identifies gaps in the supply chain and opportunities for OEM/ODM expansion. For distributors and retailers, it highlights the flavor profiles and product formats that are gaining traction in compliant markets.
Readers are encouraged to access the full source webpage to retrieve the complete segmentation data, detailed company profiles, and specific regional forecasts. Only through the comprehensive dataset can organizations build the precise financial models and market entry plans required to succeed in this high-growth, high-regulation environment. The summary provided here establishes the strategic necessity of the research; the full document delivers the executional intelligence.
Conclusion
The e-liquids market is poised for substantial expansion over the next six years, but the path to capturing this value is fraught with regulatory and competitive challenges. With a projected market size nearing USD 2,470.0 Million by 2032 and a CAGR of 12.58 percent, the opportunity is significant. However, success will belong to those who can navigate the FDA authorization landscape, adapt to duties like the UK Vaping Products Duty, and compete effectively within a market where the top five players already control 78.0 percent of the share.
E-Liquids Market
PW Consulting's latest market research equips stakeholders with the necessary tools to make informed decisions. By integrating historical performance data, current regulatory facts, and competitive profiles, this report serves as a foundational document for strategic planning in 2026. We invite you to review the complete findings on our website to fully leverage this intelligence for your organization's growth objectives.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Calcium Sulfate Market Hits $288.9M in 2025, Poised for 4.2% CAGR Growth to 2032
By PW Consulting, 2026-09-16
Strategic Outlook: Navigating the Calcium Sulfate Market Through 2026 and Beyond
The global industrial landscape for calcium sulfate is undergoing a nuanced transformation, driven by shifting construction demands, evolving regulatory frameworks, and the strategic repositioning of key material suppliers. For executives and portfolio managers operating within the industrial minerals, agriculture, and specialty chemicals sectors, 2026 represents a pivotal inflection point. Decisions made today regarding supply chain diversification, grade-specific sourcing, and regional expansion will directly determine competitive positioning through the end of the decade. Our latest research initiative examines the structural forces shaping this market, providing a decision-ready architecture for navigating both near-term volatility and long-term growth trajectories.
Market Architecture and Macro Trajectory
Calcium sulfate continues to anchor a multifaceted value chain that spans construction infrastructure, agricultural soil management, food and pharmaceutical formulation, and broad industrial processing. Historical movement from 2020 through 2025 illustrates a market that has demonstrated steady resilience despite macroeconomic headwinds, raw material supply constraints, and regional policy realignments. Revenue expanded from approximately 235.18 Million USD in 2020, reached 246.45 Million by 2021, fluctuated marginally at 246.44 Million in 2022, and then accelerated to 269.81 Million in 2023 as construction and industrial activity rebounded across major economies. By 2024, the figure climbed to 278.75 Million, and the current baseline for 2025 sits at 288.90 Million USD.
Magnesium Sulfate Market
These sequential expansions reflect more than incremental demand; they signal the maturation of application ecosystems and the gradual integration of calcium sulfate into higher-value manufacturing and processing workflows. Looking forward, the forecast window extending to 2032 maps a clear upward pathway. Revenue is projected to advance toward 302.82 Million in 2026, followed by sustained growth across subsequent years, ultimately approaching 385.32 Million by the close of the decade. This trajectory corresponds to a compound annual growth rate of 4.2 percent, a figure that underscores moderate but structurally reliable expansion.
For strategic planners, this pace of growth carries distinct implications. A 4.2 percent CAGR suggests a market that is neither volatile nor speculative, but rather characterized by methodical procurement cycles, grade-driven pricing premiums, and regional supply-demand mismatches. Companies that align procurement calendars with forecast inflection points, rather than reacting to annual spot fluctuations, will be better positioned to manage working capital and secure favorable contract terms. The underlying forecast also reveals where capacity planning, inventory optimization, and downstream application development will yield the highest returns, and our full report isolates those leverage points with granular timeline mapping.
Segmentation Dynamics and Application Realities
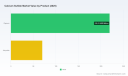
The calcium sulfate market is inherently multi-dimensional, spanning variations in mineral forms, grade specifications, and end-use applications. Gypsum and anhydrite represent the two foundational product categories, each with distinct handling characteristics, processing requirements, and downstream suitability. Technical-grade, food-grade, and pharmaceutical-grade specifications further fragment procurement strategies, as material purity, trace element limits, and certification pathways vary significantly across industries. The construction sector remains the dominant application anchor, drawing substantial volume for wallboard manufacturing, cement conditioning, and specialty finishing products. Agricultural applications constitute another meaningful demand stream, particularly where calcium sulfate serves as a soil amendment and secondary nutrient carrier. Food and beverage formulation, pharmaceutical and personal care manufacturing, and broader industrial processing round out a diversified application matrix.
Understanding how these segments interact is essential. Industrial buyers do not simply purchase a homogenous material; they navigate a tiered landscape where grade purity, origin traceability, moisture content, and particle morphology directly influence processing efficiency and final product quality. The construction industry's volume requirements often create baseline demand floors, while food-grade and pharmaceutical-grade channels operate on tighter specification windows and command differentiated pricing structures. Agricultural demand, meanwhile, fluctuates with planting cycles, regional soil conditions, and the availability of competing amendments. Our detailed analysis dissects these interdependencies and maps where procurement teams should prioritize grade flexibility versus specification rigidity, but the exact volume distributions, regional consumption allocations, and application-level revenue splits are reserved for the complete intelligence package. The objective of this overview is to establish the structural logic; the report delivers the operational quantification needed to act on it.
Competitive Landscape and Strategic Postures
The competitive environment in calcium sulfate is defined by a blend of industrial mineral processors, regional suppliers, and specialized formulators who serve distinct end markets. Several established players illustrate the strategic diversity within this space. One prominent supplier headquartered in Mamaroneck, New York, offers calcium sulfate in dihydrate, hemihydrate, and anhydrous forms, sourcing from both domestic and international origins while targeting industrial and agricultural buyers. Another U.S.-based processor, operating out of Mentor, Ohio, functions as a supplier and industrial mineral extender, distributing anhydrous and dihydrate forms for additive and formulation applications. In China, a manufacturer and exporter based in Xingtai, Hebei, processes food-grade, anhydrous, and specialized calcium sulfate products used in baking ingredients, tofu coagulation, and pharmaceutical contexts. Separately, a U.S. operation headquartered in Illinois has focused on granular calcium sulfate fertilizer blends designed to deliver secondary nutrients such as calcium and sulfur for agricultural use.
The strategic postures of these companies reveal broader market dynamics. Some entrants emphasize multi-origin sourcing to mitigate supply disruptions and maintain price competitiveness, while others concentrate on grade specialization to capture higher-margin formulation and food-adjacent channels. Agricultural-focused producers increasingly differentiate through nutrient delivery formats and soil-health positioning. These approaches reflect a market where scale alone is insufficient; sourcing reliability, specification consistency, regulatory compliance, and application-specific technical support increasingly determine purchasing decisions. The report includes a structured competitive assessment that maps these differentiation vectors across the leading participants, including recent operational milestones such as new facility openings and capacity expansions that reshape regional supply availability. Full competitor benchmarking, sourcing footprints, and strategic capability comparisons are available within the published intelligence, enabling procurement and strategy teams to calibrate vendor selection with precision.
Regulatory, Supply-Side, and Operational Headwinds
Beyond demand-side growth, calcium sulfate markets are being shaped by regulatory evolution and supply-side constraints that carry direct operational consequences. Government agencies in key regions have begun issuing handling and management guidance for by-product gypsum derived from flue gas desulfurization processes, aiming to facilitate agricultural and industrial reuse while strengthening environmental compliance standards. These guidance frameworks influence how secondary calcium sulfate streams can be processed, certified, and commercialized, adding both opportunity and compliance complexity for processors and end users.
Simultaneously, the raw material environment is experiencing structural adjustments. Synthetic gypsum production has declined as coal-fired power facilities continue to close, reducing the availability of a historically important secondary feedstock for calcium sulfate processing. This shift affects cost structures, supply continuity, and regional sourcing strategies, particularly for industrial buyers who have relied on recovered gypsum streams to balance procurement economics. The intersection of cleaner environmental standards and reduced synthetic feedstock availability is prompting a recalibration of primary versus secondary sourcing mixes. Organizations that anticipate these supply-side transitions, evaluate primary deposit access, and build qualification pathways for alternative feedstocks will face less disruption than those depending on legacy synthetic supply networks. The complete report examines these regulatory and supply dynamics in context, including their projected impact on pricing behavior, processing investments, and regional availability throughout the forecast window.
Strategic Implications for Corporate Decision-Making
For executives evaluating market entry, capacity investment, sourcing strategy, or product portfolio development, the calcium sulfate landscape offers both predictable growth and targeted risk. The 4.2 percent CAGR indicates that expansion will be driven by steady industrial and agricultural demand rather than speculative cycles, which favors disciplined long-term planning. However, the segmentation complexity means that growth opportunities are uneven across grades, applications, and geographies. Companies that treat calcium sulfate as a single commodity risk missed margin opportunities in higher-specification channels, while organizations that over-specialize without securing diversified supply may face cost volatility when regulatory or feedstock conditions shift.
Effective positioning requires a multi-layered strategy. Procurement teams must evaluate supplier qualification frameworks that account for both origin traceability and grade reliability. Operations leaders should assess whether existing facilities can accommodate shifts in feedstock composition and specification requirements as synthetic gypsum volumes change. Market development teams need to identify where food-grade and pharmaceutical-grade applications offer margin premiums and where agricultural channels provide volume stability. Regulatory affairs functions should monitor handling and reuse guidance that may expand downstream utilization of by-product streams while introducing new compliance obligations. Each of these considerations carries distinct return profiles and implementation timelines, and our research isolates where strategic capital and operational attention will generate the strongest outcomes.
Calcium Sulfate Market
How the Full Report Supports Your Next Move
This overview establishes the strategic contours of the calcium sulfate market and the rationale for informed, forward-looking decision-making in 2026. The complete market research publication extends this foundation into a fully operational intelligence framework. It delivers a detailed segmentation analysis across product types, grade specifications, and application channels, alongside regional market sizing and consumption trajectories. It maps the competitive landscape with structured company profiles, recent operational developments, and capability comparisons that help procurement and strategy teams evaluate vendor alignment. It integrates regulatory and supply-side developments into scenario-based implications, allowing decision-makers to test sourcing and pricing assumptions under changing feedstock and compliance conditions.
Most importantly, the report translates market structure into actionable milestones. It identifies where demand acceleration is most likely, which grade channels merit specification investment, and where sourcing diversification will provide the greatest resilience. For leaders responsible for capital allocation, supply chain design, or market expansion, the publication functions as a single-source reference for aligning commercial strategy with market reality. To access the complete segmentation data, regional breakdowns, competitive benchmarking, and forecast pathways, readers are invited to explore the full research publication. The detailed intelligence contained within is designed to support precise, confident decisions as the calcium sulfate market continues its measured ascent through the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Calcium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epoxidized Soybean Oil Market to Hit $825M by 2032 Growing at 7.58% CAGR
By PW Consulting, 2026-09-16
Navigating the Epoxidized Soybean Oil Market: Strategic Intelligence for 2026 and Beyond
The global chemical landscape is undergoing a structural shift where sustainability, regulatory compliance, and supply chain resilience converge. For stakeholders in the polymer additives sector, Epoxidized Soybean Oil (ESBO) has emerged as a critical component, bridging the gap between performance requirements in PVC formulations and the escalating demand for bio-based alternatives. As we enter 2026, the market stands at a pivotal juncture. PW Consulting's latest comprehensive study on the Epoxidized Soybean Oil Market is designed not merely as a data repository, but as a strategic compass for executive decision-making in this evolving environment.
This research provides a granular look at the forces shaping revenue trajectories from the base year of 2025 through the forecast period extending to 2032. By synthesizing historical performance with forward-looking indicators, this report equips leadership teams with the insights necessary to navigate volatility, capitalize on regional opportunities, and understand the competitive intensity defining the sector.
Market Trajectory and Growth Dynamics
Understanding the macroeconomic pulse of the ESBO market is the foundational step for any strategic planning process. The historical data from 2020 to 2025 reveals a consistent upward trend, reflecting the material's entrenched role in various industrial applications. The market valuation witnessed steady expansion, moving from approximately 392.15 million USD in 2020 to an estimated 496.5 million USD in 2025. This historical resilience sets the stage for the forecast period, where growth is projected to accelerate.
Our analysis indicates that the market is poised to reach significant milestones by the end of the forecast window. Starting from a projected 534.71 million USD in 2026, the trajectory points toward a valuation of 825.27 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 7.58 percent. Such growth is not accidental; it is driven by the dual engines of increasing PVC demand in emerging economies and the regulatory push away from phthalate-based plasticizers in developed markets.
However, raw growth figures only tell part of the story. The strategic value lies in understanding the velocity of this growth across different horizons. Early forecast years suggest a period of consolidation and capacity adjustment, while the latter half of the decade indicates a potential surge driven by downstream industry adoption. Decision-makers must distinguish between short-term cyclical fluctuations and long-term secular trends to allocate capital effectively.
Competitive Landscape and Strategic Positioning
The ESBO market is characterized by a moderately concentrated competitive environment. Our concentration analysis reveals that the top three players hold a combined market share of 55.0 percent, while the top five entities command 65.0 percent. This structure suggests that while market leaders possess significant influence over pricing and supply standards, there remains sufficient fragmentation to allow for niche specialization and regional agility.
Waterborne Epoxy Resin Market
Several key corporations define the current operational landscape, each leveraging distinct strategic advantages:
- Cargill, Incorporated (Minneapolis, Minnesota, United States): A dominant force leveraging scale and integration. Cargill produces Vikoflex and Vikoflex High IV grades, positioning them as primary plasticizers and co-stabilizers for flexible and semi-rigid PVC formulations. Their recent capacity expansion and modernization of the facility in Sidney, Ohio, demonstrates a commitment to scaling production to meet growing demand.
- Valtris Specialty Chemicals (Chicago, Illinois, United States): Focuses on specialized grades such as Plas-Chek and Lankroflex. Their value proposition heavily emphasizes compliance, offering secondary heat stabilizers and plasticizers with food-contact and Kosher certifications. This focus was reinforced in late 2024 when they promoted these grades for flexible PVC, highlighting renewable and food-safe features.
- Galata Chemicals LLC (Ewing, New Jersey, United States): Competes on performance metrics, manufacturing plasticizers that emphasize heat stability. Their February 2024 product launch of an advanced ESBO plasticizer with superior heat stability targets high-performance PVC applications, signaling a strategy focused on technical differentiation.
- CHS Inc. (Inver Grove Heights, Minnesota, United States): Utilizes vertical integration as a competitive moat. By leveraging soybean crushing operations, CHS secures a cost-effective supply chain for PVC and polymer markets, insulating themselves somewhat from upstream commodity volatility.
- ADEKA Corporation (Tokyo, Japan): Operates as a global supplier, ensuring geographic diversification and serving PVC stabilization needs across international markets.
- Acme-Hardesty (New Haven, Connecticut, United States): Supplies Jenkinol 680 grades, catering to specific PVC production requirements as both plasticizer and stabilizer.
- ChemCeed (Cary, North Carolina, United States): Plays a crucial role in distribution, offering technical-grade ESO in various quantities from drums to bulk, facilitating accessibility for smaller-scale or specialized users.
- Interstate Chemical Company (Hermitage, Pennsylvania, United States): Manufactures Interflex ESO for general PVC and plastics formulations, maintaining a steady presence in the domestic manufacturing sphere.
Beyond the incumbents, the landscape is dynamic. Recent developments indicate ongoing innovation and market entry. For instance, J-Oil Mills launched an enhanced liquid epoxidized soybean oil variant in March 2025 with improved compatibility for PVC stabilizers. Such moves highlight that the barrier to entry relies heavily on technical formulation capabilities and certification compliance rather than just raw production capacity. Understanding the specific strategic moves of these players—from capacity expansion to product promotion—is essential for benchmarking one's own market position.
Segmentation Insights and Demand Drivers
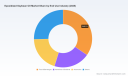
A core strength of this research lies in its detailed segmentation analysis. While aggregate numbers provide the trend line, the real strategic opportunities are often hidden within specific application and end-use verticals. The market revenue is distributed across several key applications, with Plasticizers representing the largest share of consumption. This is followed by significant contributions from Pigment Dispersion Agents and other specialized uses. Fuel Additives also constitute a notable segment, reflecting the versatility of ESBO beyond traditional polymer stabilization.
From an end-use industry perspective, the Food & Beverages sector emerges as a critical demand driver, largely due to stringent safety regulations requiring non-toxic additives. Adhesives & Sealants and Automotive industries also represent substantial consumption bases. The Automotive sector, in particular, faces pressure to reduce weight and improve interior air quality, driving the adoption of non-phthalate plasticizers like ESBO.
It is important to note that while regional dynamics vary, the interplay between local manufacturing capabilities and import dependencies creates unique market structures in different geographies. North America, Europe, and Asia Pacific represent major hubs of activity, each with distinct regulatory frameworks and supply chain characteristics. Latin America and the Mideast and Africa regions, while smaller in current valuation, offer growth potential as industrialization accelerates. Our report dissects these regional nuances without exposing the specific revenue splits, ensuring that clients uncover the precise opportunity magnitudes through the full analysis.
Industry Context and External Volatility Factors
Strategic planning in the chemical sector cannot occur in a vacuum. External factors regarding raw materials and regulation exert profound influence on profitability and supply security. One of the most significant cost drivers is soybean oil, which accounts for approximately 58.6 percent of the raw material share in epoxidized soybean oil production. Fluctuations in soybean oil prices directly impact production margins. According to recent USDA forecasts, soybean oil season-average prices are projected at 0.59 per lb for the 2025/26 marketing year. Furthermore, USDA economic data suggests soybean crush demand is forecast to reach a record 2.75 billion bushels, with soybean oil used as feedstock in biomass-based diesel production. This competition for feedstock between the biodiesel and chemical sectors introduces a layer of complexity to supply forecasting.
Regulatory developments also pose both risks and opportunities. In September 2024, Mexico launched an antidumping probe into ESBO imports from Brazil and China covering 85–99 percent pure content. Such trade measures can disrupt established supply chains, alter cost structures, and shift sourcing strategies for manufacturers operating in or exporting to the Latin American market. Additionally, global trends favoring bio-based and renewable materials continue to tighten regulations around traditional phthalates, effectively creating a protective moat for ESBO producers who can certify compliance with food-contact and safety standards.
These externalities require a proactive rather than reactive stance. Companies must model scenarios where raw material costs spike due to biodiesel demand or where trade barriers redirect flow volumes. Our report integrates these macroeconomic and regulatory variables into the forecast model to provide a robust range of outcomes.
Tactical Applications of the Research
PW Consulting's Epoxidized Soybean Oil Market report is structured to support diverse strategic functions within an organization. For strategic planners, the historical and forecast data provides the baseline for long-term capacity planning and investment appraisal. For sales and marketing teams, the segmentation breakdown offers insights into which application verticals are growing fastest, allowing for targeted promotional efforts.
Epoxidized Soybean Oil Market
Supply chain managers will find value in the analysis of raw material dependencies and regional supply dynamics, enabling better negotiation strategies with suppliers and logistics partners. Competitive intelligence teams can utilize the company profiles and recent developments sections to track rival maneuvers, such as new product launches or capacity expansions, and adjust positioning accordingly.
The report also serves as a vital tool for risk management. By highlighting regulatory probes and commodity price forecasts, it allows leadership to stress-test their operational models against potential disruptions. Whether the goal is to enter a new geographic market, launch a specialized grade, or consolidate market share through acquisition, the data herein provides the evidentiary support needed to justify initiatives to stakeholders.
Conclusion: The Imperative for Deep Intelligence
As the Epoxidized Soybean Oil market moves toward a valuation exceeding 825 million USD by 2032, the window for strategic advantage is open but narrowing. The convergence of regulatory tailwinds, raw material volatility, and competitive intensification means that generic market knowledge is no longer sufficient. Organizations need precise, data-backed intelligence to navigate the complexities of this sector.
This overview has highlighted the macroeconomic trajectory, the key players defining the competitive space, and the external factors influencing market dynamics. However, the specific revenue splits by region, the detailed growth rates per application segment, and the granular competitive benchmarking data are reserved for the full report. These details are the levers that drive specific tactical decisions.
To access the complete dataset, including detailed segmentation splits, proprietary competitive analysis, and comprehensive regional forecasts, we invite you to explore the full study. Equip your organization with the depth of insight required to lead in the Epoxidized Soybean Oil market throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Dairy Market to Hit $344.8M by 2032 with 6.6% CAGR
By PW Consulting, 2026-09-16
Navigating the Dairy Ingredients Horizon: Strategic Imperatives for 2026 and Beyond
The global dairy ingredients sector stands at a critical inflection point as it moves through the mid-2020s. For executives, procurement leaders, and strategic planners, the decisions made in 2026 will define competitive positioning throughout the decade. Understanding where the market has been, where it is heading, and who is shaping its trajectory is no longer a matter of routine monitoring. It requires a rigorous, forward-looking intelligence framework. PW Consulting’s latest Dairy Ingredients Market study delivers that framework, translating complex supply dynamics, shifting demand patterns, and rapidly evolving trade conditions into actionable strategy.
Dairy Ingredients Market
Over the past five years, the industry has experienced a period of measured expansion punctuated by supply chain recalibration, regulatory shifts, and changing end-user expectations. Total industry revenue climbed from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting steady consolidation of demand across multiple application verticals. The trajectory points toward continued growth, with market valuation projected to reach 237.36 million USD in 2026 and advance to 344.8 million USD by 2032. This progression corresponds to a compound annual growth rate of 6.6 percent across the 2026 through 2032 forecast window. Such a macro outlook signals a fundamentally resilient category, but the real strategic value lies beneath the headline figures: in how value is distributed across ingredient types, how regional supply balances interact with trade policy, and which application segments are generating the strongest margin discipline.
Why 2026 Demands a Recalibrated Strategic View
The year 2026 is not a simple continuation of recent patterns. Several structural forces are converging to reshape how dairy ingredients are sourced, formulated, priced, and distributed. On the regulatory front, the Food and Drug Administration’s July 2025 proposal to revoke 18 standards of identity for dairy products, including multiple cheese and milk variants, has introduced new considerations around labeling, formulation compliance, and ingredient substitution. For manufacturers and formulators, this creates both flexibility and ambiguity, requiring closer coordination between regulatory affairs, R&D, and procurement teams.
At the same time, trade dynamics are shifting quickly. Recent reporting from the International Dairy Foods Association in February 2026 highlighted landmark new trade agreements with Taiwan that fully eliminate dairy tariffs, materially expanding U.S. dairy ingredients market access. The same reporting noted additional accords with Argentina, El Salvador, Guatemala, Bangladesh, and North Macedonia, collectively boosting export potential. These developments are unfolding alongside U.S. Dairy Export Council data from January 2026 showing that 2024 U.S. dairy exports recorded increased volumes on a milk-fat basis while experiencing declines on a skim-solids basis. The divergence underscores a nuanced export environment where composition, destination, and commodity mix matter as much as total shipment volume.
On the demand side, a McKinsey dairy industry survey from April 2026 found rising demand for dairy ingredients even as cost pressures and margin challenges persist across the value chain. This combination of resilient demand and compressed profitability is precisely the environment in which granular market intelligence becomes indispensable. Executives cannot rely on aggregate growth narratives alone; they must understand which ingredient categories are absorbing volume, which applications are commanding premium positioning, and how competitive intensity is evolving among established producers and specialized suppliers.
Inside the Research: What This Study Delivers
PW Consulting’s Dairy Ingredients Market report is structured to move beyond surface-level forecasts and into the operational detail that decision-makers actually use. The study is built around several core analytical pillars:
- Historical reconstruction and forward modeling covering the 2020 to 2025 historical window and a detailed 2026 to 2032 forecast period, with revenue expressed in million USD and a documented 6.6 percent CAGR.
- Segment-level analysis across ingredient types, end-use applications, and regional markets, designed to reveal where growth is concentrated and where competitive saturation is most pronounced.
- Competitive landscape assessment profiling leading producers and suppliers, evaluating their product portfolios, geographic reach, formulation capabilities, and strategic positioning within the broader ingredients ecosystem.
- Market structure evaluation examining concentration metrics and the balance between diversified global players and specialized regional operators, helping buyers and investors gauge pricing power, supply resilience, and partnership options.
- Regulatory, trade, and standards context integrating developments such as FDA identity standard revisions, ADPI-maintained industry standards for U.S.-produced dairy ingredients including whey, lactose, and milk proteins, and the latest trade agreement outcomes that affect market access and cost structures.
- Recent industry milestones capturing events such as the April 2026 ADPI Annual Conference in Chicago and other sector gatherings that shape innovation direction, foodservice application trends, and cross-functional collaboration across the ingredients community.
The report is deliberately built for practical use. Rather than stopping at high-level trends, it connects demand signals to ingredient functionality, links regional supply dynamics to trade policy outcomes, and frames competitive moves within the context of margin discipline and formulation innovation. This integrated approach allows readers to assess not only where the market is going, but how their own sourcing strategies, product development roadmaps, and partnership decisions should adapt in response.
Competitive Landscape: Who Is Shaping the Market
The dairy ingredients arena is populated by a mix of large, globally active dairy organizations and focused ingredient specialists. The competitive field spans North American producers with strong domestic supply chains, European exporters with broad international distribution, and formulation-oriented companies that provide custom concentrates and blended powders tailored to specific food and beverage applications. Rather than a single dominant architecture, the market operates as a layered ecosystem in which scale, specialization, and application expertise create distinct competitive advantages.
Several organizations stand out through the breadth of their ingredient portfolios and their presence across multiple end markets. Agropur, headquartered in Montreal, Canada, focuses on dairy ingredient production including whey, milk protein, and casein for food and beverage applications. Arla Foods, based in Viby J, Denmark, provides dairy ingredients such as milk powders, whey proteins, and lactose for global food and nutrition markets. Lactalis, located in Bourgbarre, France, offers dairy ingredients including milk powders, whey, and casein for global food and beverage industries. Saputo Cheese USA, with operations linked to Montreal, Canada, supplies whey powders, milk proteins, and other dairy ingredients for food production. These organizations illustrate how major dairy groups leverage ingredient divisions to serve a wide range of industrial and consumer-facing applications.
Alongside these broader players, a set of specialized suppliers adds critical depth to the market. Bluegrass Ingredients, Inc., based in Kentucky, United States, specializes in custom dairy concentrates, blended powders, and whey-based ingredients for food formulation. California Dairies, Inc., in Tulare, California, produces and supplies milk powders, whey products, and other dairy ingredients for industrial and food applications. Dairy Farmers of America, headquartered in Roseville, Illinois, supplies milk powder, whey, casein, and other dairy ingredients for dairy products, food manufacturing, and nutrition. Glanbia Nutritionals, located in La Crosse, Wisconsin, manufactures whey protein isolates, concentrates, and other dairy protein ingredients for sports nutrition and food products. Land O’Lakes, based in Arden Hills, Minnesota, provides milk powders, whey products, and functional dairy ingredients for food processing and nutrition. Leprino Foods, in Denver, Colorado, produces cheese powders, whey, and other dairy ingredients used in food manufacturing and baked goods. MCT Dairies, based in Millburn, New Jersey, distributes and supplies dairy ingredients across global markets for food and beverage applications. Proliant Dairy Ingredients, in Ames, Iowa, specializes in dairy protein ingredients, whey products, and milk proteins for food and industrial use. Schreiber Foods, headquartered in Green Bay, Wisconsin, manufactures dairy ingredients such as milk powders, whey, and casein for beverage and food industries.
Together, these companies represent the operational core of an industry that must continuously balance scale efficiency with formulation precision. Their product ranges, application focus, and geographic footprints shape how buyers evaluate supply reliability, technical support, and long-term partnership potential. The full report provides a more detailed competitive mapping, assessing how these organizations are positioned relative to one another across ingredient types, end-use segments, and regional markets, while preserving the analytical depth needed to support sourcing strategy, partnership evaluation, and competitive benchmarking.
Market Dynamics: Regulation, Trade, and Demand Signals
A durable understanding of dairy ingredients requires attention to the forces that alter cost structures, market access, and formulation choices. The July 2025 FDA proposal to revoke 18 standards of identity for dairy products has introduced a meaningful regulatory variable. For ingredient suppliers and end-product manufacturers alike, changes to identity standards can affect labeling requirements, ingredient substitution pathways, and the competitive positioning of specific product forms. The strategic implication is not simply compliance; it is the opportunity to reconsider formulation architectures and ingredient blending strategies in light of broadened flexibility.
Worldwide Infant Dairy Ingredients Market
Trade policy is equally consequential. The February 2026 announcement of new agreements with Taiwan, alongside expanded collaboration with Argentina, El Salvador, Guatemala, Bangladesh, and North Macedonia, signals a widening aperture for export-oriented growth. These agreements can reduce tariff barriers, improve destination-market competitiveness, and reshape the relative attractiveness of different sourcing origins. At the same time, the U.S. Dairy Export Council’s January 2026 data reminds the market that export performance is not uniform. Increased milk-fat basis volumes alongside skim-solids declines indicate that commodity composition, end-use demand, and pricing dynamics differ significantly by product stream. Organizations that treat dairy ingredients as a single homogeneous category risk misreading both opportunity and exposure.
On the demand side, the April 2026 McKinsey survey’s finding of rising ingredient demand amid cost and margin pressure captures the current tension. Buyers are seeking functional reliability, consistent supply, and formulation versatility, while suppliers are navigating input volatility and the need to protect profitability. In this environment, industry standards maintained by organizations such as the American Dairy Products Institute play an important role in anchoring quality expectations for U.S.-produced dairy ingredients including whey, lactose, and milk proteins. The June 2026 reinforcement of those standards, alongside the April 2026 ADPI Annual Conference’s focus on innovation and foodservice applications, suggests that technology, consistency, and application performance remain central competitive differentiators.
What Strategic Decision-Makers Need to Know Next
The macro picture is clear enough to establish confidence in continued growth, but the strategic decisions that matter most are segmental, operational, and partnership-driven. Which ingredient categories are expanding fastest in value terms? Where are application segments generating the strongest demand pull, and which are facing substitution risk or margin compression? How do regional supply balances interact with the new trade agreements to alter sourcing geography? Which competitors are building advantage through formulation capability, and which are competing primarily on scale and distribution?
These are the questions that determine whether an organization simply rides broad market growth or actively captures disproportionate value from it. The answers require a detailed view of segmentation splits, regional performance patterns, application-level demand intensity, and competitive positioning that cannot be responsibly compressed into a single summary. PW Consulting’s full Dairy Ingredients Market study is built to provide exactly that depth, enabling procurement teams, R&D leaders, and corporate strategists to align their plans with the most current structural reality of the market.
For executives preparing 2026 initiatives and longer-range plans through 2032, the study offers a structured intelligence base: historical trajectory, forward projections anchored to a 6.6 percent CAGR, segment and regional breakdowns, competitive profiling, and dynamic context drawn from the latest regulatory, trade, and industry developments. The objective is not to overwhelm with data, but to give decision-makers the clarity needed to prioritize investments, manage supply risk, and position products where demand and margin discipline intersect.
The full report is available for review and acquisition through PW Consulting’s market research portal. Readers seeking a complete segment-by-segment view, detailed competitive mapping, and region-specific growth pathways are encouraged to access the source page for the complete intelligence package. In a market where aggregate growth can mask important local and segmental shifts, that level of detail is what turns insight into advantage.
For detailed analysis of this topic, please visit the official page: Dairy Ingredients Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Guitar Amp Market Hits $142M in 2025, 2.11% CAGR to $182.7M by 2032
By PW Consulting, 2026-09-16
Guitar Amplifier Market Outlook 2026: Strategic Insights for Industry Leaders
The global guitar amplifier market stands at a critical inflection point as it moves through the 2026–2032 forecast period. Characterized by steady expansion, evolving technological paradigms, and a shifting regulatory landscape, the sector demands rigorous strategic planning from manufacturers, distributors, and investors alike. This article outlines the foundational dynamics captured in our latest market research, demonstrating why actionable intelligence is no longer optional for competitive positioning. Readers seeking granular segmentation matrices, regional deployment forecasts, and proprietary competitive scoring frameworks are encouraged to access the full report at our source webpage, where complete analytical datasets are available.
Market Trajectory and Historical Momentum
Understanding the trajectory of the guitar amplifier market begins with a clear assessment of its historical performance and forward-looking projections. Over the past five years, the industry has navigated supply chain recalibrations, shifting consumer preferences, and incremental technological adoption. Our analysis tracks consolidated revenue performance from 2020 through 2025, establishing a baseline that informed our 2026–2032 forecast model. The market demonstrated resilient top-line growth through the early part of the decade, with consolidated revenue reflecting both post-pandemic consumption patterns and sustained demand from professional audio ecosystems.
As we enter 2026, the market is positioned to reach an estimated consolidated revenue threshold of approximately 147.85 million USD. This figure represents a deliberate continuation of an upward arc, though the pace of growth reflects a more measured annualized rate of 2.11 percent across the entire forecast window. Rather than signaling stagnation, this moderated expansion underscores a maturing industry where value creation increasingly stems from product differentiation, channel optimization, and premium tier positioning rather than pure volume acceleration. Stakeholders who anchor their planning to this nuanced growth profile will be better equipped to allocate capital efficiently, time product launches strategically, and manage inventory risk across volatile macroeconomic cycles.
Guitar Effects Market
Our forecast model further maps the revenue pathway through 2032, with projected figures advancing steadily toward a terminal value near 182.7 million USD. This horizon provides decision-makers with a multi-year planning framework that aligns product roadmaps, capacity investments, and market entry strategies. The full report dissects the inflection points, demand catalysts, and potential headwinds that could alter this trajectory, enabling scenario-based planning that goes beyond single-point estimates.
Structural Dynamics Shaping Competitive Posture
The contemporary guitar amplifier market is influenced by a confluence of structural forces that redefine how manufacturers approach product design, sourcing, and geographic positioning. At the forefront of these dynamics are regulatory adjustments that directly impact landed costs and margin structures. Recent trade policy shifts have introduced heightened tariffs on imported components and finished units, with certain cross-border flows now subject to additional surcharges that reverberate through boutique and professional-grade amplifier segments. These policy-driven cost structures are not uniform; their impact varies by origin, classification, and end-market destination, making tariff-aware sourcing strategies essential for maintaining price competitiveness.
Guitar Amplifier Market
Simultaneously, the European market has seen the application of targeted duties on specific amplifier-related components, adding another layer of complexity for firms with transatlantic supply chains. Companies that fail to model these cost layers into their pricing architecture risk margin compression or, conversely, alienating price-sensitive downstream buyers. Our research evaluates how leading manufacturers are reconfiguring their manufacturing footprints and distribution strategies in response to these regulatory realities.
Beyond trade policy, raw material and component availability has become a defining constraint. Transformer pricing for power and output units has experienced substantial escalation, with lead times for high-voltage models stretching considerably longer than historical norms. This bottleneck affects everything from boutique hand-wired builds to higher-volume production lines, forcing manufacturers to balance inventory commitments against working capital efficiency. The report assesses how different operational models are absorbing these constraints and which procurement strategies are proving most resilient under extended lead-time conditions.
Competitive Landscape and Innovation Vectors
The market's competitive architecture is anchored by a mix of legacy brands, technology-first manufacturers, and boutique specialists, each pursuing distinct value propositions. Fender Musical Instruments Corporation continues to leverage its comprehensive amplifier portfolio, spanning tube, modeling, and digital platforms, including recognized series that have long defined professional and semi-professional reference points. Recent product announcements have reinforced its commitment to heritage positioning while integrating modern enhancements, such as limited-edition commemorative releases that capitalize on brand equity and collector demand.
Gibson Brands, Inc. brings a historically rooted amplifier lineage to the market, complemented by contributions through affiliated product lines. With announced revitalization plans for amplifier offerings, the company is signaling renewed emphasis on this category, an approach that could reshape competitive dynamics in segments where brand heritage and tonal familiarity remain decisive purchase drivers. Marshall Amplification, headquartered in the United Kingdom, maintains its reputation for high-gain tube and hybrid designs that continue to influence professional stage and studio setups. Its product philosophy emphasizes tonal character and stage-ready durability, reinforcing its position within a segment where performance consistency carries outsized brand value.
PRS Guitars contributes to the competitive mix through signature and combo amplifier models that align with its broader instrument ecosystem. Its recent activity, including collaborations with performing artists, highlights a strategy of leveraging performer credibility to differentiate within a crowded product landscape. Friedman Amplification represents the boutique tier with hand-crafted tube and hybrid amplifiers, where limited production runs and signature partnerships create premium positioning. Its launch of compact-wattage designs incorporating modern load technology demonstrates how boutique manufacturers are integrating digital-ready features without abandoning analog-centric identities.
BOSS Corporation’s modeling and tube-logic amplifier offerings illustrate the growing relevance of versatile, technology-forward platforms, including compact formats that appeal to mobile players and content creators. Orange Amplification reinforces the British-style tube and solid-state lineage, catering to players who prioritize distinct voicing and aesthetic identity. Peavey Electronics Corporation continues to serve professional-grade requirements while expanding production capacity in key regions to improve supply reliability and cost structure. Benson Amps focuses on hand-wired all-tube designs that appeal to discerning buyers seeking artisanal construction and tonal specificity. Hammond Manufacturing occupies a specialized niche by supplying replacement transformers for tube amplifiers, an essential enablement role that supports the broader repair, customization, and longevity ecosystem.
The full report provides a detailed competitive assessment covering market concentration indicators, strategic positioning, and relative execution patterns across these players. By mapping how each organization balances heritage, innovation, and cost structure, the analysis supports benchmarking exercises and competitive response planning.
Product Architecture and Application-Driven Demand
Guitar amplifier demand is shaped by a diverse set of use cases, from professional performance and studio recording to educational environments and home practice. The market's product architecture divides along lines that reflect both functional requirements and buyer preferences. Combo amplifiers continue to hold substantial relevance given their integrated convenience and broad accessibility across skill levels. Head amplifier configurations remain important for professional workflows where separate cabinet selection and system modularity are valued. The interplay between these configurations influences channel strategies, SKU rationalization, and accessory ecosystems.
Demand patterns also vary by application context. Commercial environments, including venues, studios, rental operations, and educational programs, sustain consistent procurement cycles driven by equipment aging, replacement cycles, and performance reliability standards. Household demand reflects a different set of purchase triggers, including entry-level learning, home recording setups, and hobbyist engagement. The research examines how these application streams interact with regional purchasing behaviors, retail channel dynamics, and seasonal demand fluctuations, providing planners with a practical view of where volume concentrates and where premium positioning may yield stronger returns.
Rather than presenting static allocation figures, the report translates these structural patterns into decision-ready implications. This includes guidance on portfolio balancing, pricing architectures, and channel mix adjustments that align with the distinct economics of each demand stream.
Strategic Implications for 2026 Decision-Makers
For executives and strategy teams operating in or adjacent to the guitar amplifier market, the 2026 landscape calls for disciplined positioning across several dimensions. First, product planning must reconcile tonal heritage with modern convenience features. Players increasingly expect flexible signal paths, improved connectivity, and formats that adapt to both stage and content-creation workflows. Companies that can integrate these features without diluting core tonal identity are likely to capture share in premium categories.
Second, supply chain strategy requires active restructuring. The combination of tariff exposure, component cost escalation, and extended lead times means that sourcing diversification, inventory segmentation, and regional production planning are now strategic imperatives rather than operational afterthoughts. Organizations that model cost pass-through scenarios and stress-test margin resilience will be better prepared to maintain pricing integrity under volatile conditions.
Third, competitive differentiation is increasingly achieved through ecosystem thinking. Amplifier purchases often intersect with instrument branding, accessories, digital signal tools, and after-sales service. Strategic partnerships, signature product lines, and integrated support offerings can strengthen retention and expand wallet share within target customer groups. The report evaluates which ecosystem strategies are generating measurable traction and where white space remains for new entrants or incumbents seeking reinvigoration.
Finally, scenario planning should incorporate regulatory and macroeconomic variables as dynamic inputs rather than static assumptions. Tariff regimes, component availability, and regional demand shifts can alter the relative attractiveness of specific geographies or segments over short time horizons. A flexible planning framework allows organizations to reallocate resources quickly when conditions change, preserving optionality in uncertain environments.
What the Full Report Delivers
Beyond the strategic overview presented here, the complete market research provides a comprehensive analytical toolkit designed for operational and executive use. The report integrates consolidated market sizing, forward-looking projections, and structural segmentation analysis that connects product types, application contexts, and regional dynamics to actionable planning parameters. It includes competitive profiling that maps strategic positioning, recent product activity, and operational emphasis for key market participants, along with an assessment of market concentration indicators that contextualize rivalry intensity and consolidation risk.
The research also examines demand-side patterns, channel considerations, and pricing architecture implications, offering guidance on how to interpret evolving buyer priorities and translate them into portfolio and commercial strategy. In addition, the report assesses regulatory and supply-side developments, including trade policy effects and component cost dynamics, presenting their strategic implications in a format that supports risk assessment and scenario planning. To ensure practical usability, the study is structured around clear analytical sections, comparative frameworks, and decision-oriented commentary that allows readers to extract relevant insights without navigating unstructured data.
Granular segmentation data, detailed regional breakdowns, and full quantitative matrices are available in the complete version of the study. These components are intentionally reserved for the full report to provide subscribing organizations with a differentiated intelligence advantage and to support precise internal modeling, investment evaluation, and competitive benchmarking.
Accessing the Complete Intelligence Package
For teams that require detailed segmentation values, regional demand pathways, and proprietary competitive scoring to support 2026 planning cycles, the full report offers the depth necessary for confident execution. The complete study is available through our source webpage, where decision-makers can review the full dataset, access supporting analytical frameworks, and integrate the findings directly into strategic planning processes. In a market defined by steady growth, evolving product expectations, and an increasingly complex operating environment, access to comprehensive, decision-ready intelligence is a critical enabler of sustainable advantage.
For detailed analysis of this topic, please visit the official page: Guitar Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steel Powder Market Hits $291M in 2025, 6.4% CAGR to 2032
By PW Consulting, 2026-09-16
Steel Powder Market Outlook 2026: Navigating Growth, Constraints, and Competitive Shifts
The global steel powder market stands at a pivotal inflection point as it enters the 2026–2032 forecast window. After tracking steady expansion from 2020 through 2025, the sector has now crossed the three-hundred-million-dollar threshold in annual revenue, positioning itself for a growth trajectory that projects a compound annual rate of 6.4 percent through the end of the decade. This is not merely a cyclical rebound. It reflects structural demand shifts across high-value manufacturing, evolving feedstock economics, and a regulatory environment that is actively redrawing trade and compliance boundaries. For executives, procurement leaders, and strategy teams, the coming year will reward those who move beyond headline growth figures and build operational playbooks rooted in granular market intelligence.
PW Consulting’s newly released Steel Powder Market research was designed precisely for that moment. Rather than functioning as a static data repository, the study translates historical momentum, forward-looking projections, and competitive signaling into decision-ready frameworks. As organizations calibrate capital allocation, supply chain resilience, and product roadmap priorities for 2026, the report offers a calibrated view of where value is being created, where margin pressure is intensifying, and which strategic moves will separate category leaders from followers.
A Market Crossing the Threshold: From Recovery to Structural Expansion
Over the past half-decade, steel powder revenue has demonstrated consistent upward movement, with annual figures climbing from the mid-two-hundred-million range into the high two hundreds before decisively breaking through three hundred million. This progression reflects more than recovered demand after earlier market softening. It underscores the deepening integration of powder metallurgy and additive manufacturing into core production strategies across multiple industrial verticals. The 6.4 percent forward CAGR embedded in our forecast model signals that momentum will not plateau; instead, it will be shaped by competing forces of capacity investment, feedstock optimization, and regional regulatory recalibration.
Importantly, headline growth masks divergent underlying dynamics. The transition from raw volume expansion to quality- and application-specific differentiation is already underway. Suppliers that can align particle morphology, purity thresholds, and metallurgical consistency with the exacting requirements of advanced manufacturing processes are capturing disproportionate value. Meanwhile, traditional commodity-oriented segments face margin compression as input cost volatility and export control mechanisms reshape cost structures. Understanding where these shifts are concentrated—and how they interact with regional demand patterns—is essential for building resilient sourcing and pricing strategies in 2026.
What the Research Delivers: Actionable Intelligence, Not Just Data
Strategic research earns its place on the executive dashboard when it converts complexity into action. Our Steel Powder Market study is structured to serve that purpose across multiple decision layers. The report opens with a detailed market sizing and forecasting architecture that traces historical performance and projects forward through the end of the forecast horizon, allowing readers to test sensitivity scenarios against base, optimistic, and constrained demand pathways. Segmentation analysis is organized around product type, application vertical, and geographic footprint, with each dimension evaluated through the lens of demand drivers, substitution risks, and pricing behavior rather than isolated share percentages.
The competitive landscape section moves beyond roster mapping to assess how key players position themselves across technology platforms, capacity footprints, and end-market focus. Recent corporate activity is examined not as isolated news items but as strategic signals: capacity expansions that target high-purity grades for demanding applications, product launches that bridge material categories, and business model shifts that redirect feedstock strategies toward recycled scrap integration. These developments are contextualized within broader industry dynamics, including regional shipment trends, feedstock dependency patterns, and the evolving relationship between traditional powder metallurgy and additive manufacturing roadmaps.
Readers will also find dedicated analysis of the regulatory and trade environment that is actively reshaping market access and cost structures. Starting in early 2026, new export licensing requirements in China, the operational rollout of EU carbon border adjustment mechanisms, and ongoing tariff developments affecting specialized inputs have introduced fresh compliance layers and cost variability. The report evaluates how these measures intersect with supply chain geography, sourcing alternatives, and margin defense strategies, providing a structured view of which exposures are manageable and which require proactive redesign.
Competitive Landscape: Strategic Positioning and Capability Divergence
The steel powder market is characterized by a concentrated core of globally active specialists alongside regional and application-focused participants. The top tier commands meaningful share, with the three largest firms accounting for roughly forty-five percent of total revenue and the five largest approaching sixty percent. That concentration does not imply uniformity; it reflects a market where capability depth, technology licensing, and end-market specialization increasingly determine competitive advantage.
Höganäs continues to anchor its global presence through a broad portfolio spanning iron, steel, and stainless steel powders tailored for powder metallurgy, additive manufacturing, and automotive applications. Recent operational moves underscore a deliberate focus on high-purity grades for demanding end markets, including announced capacity expansion at its Swedish gas atomization facility to boost output of stainless steel and nickel-based powders serving aerospace and medical applications. Outokumpu has taken a distinctly circular-economy-aligned path, developing customizable stainless steel and nickel-based alloy powders derived from recycled scrap generated by its flat products operations. Its recent expansion into aerospace and aviation, marked by the first delivery of a specialized stainless steel powder grade for advanced 3D printing, signals a push into higher-specification segments where traceability and material consistency command premium positioning.
Carpenter Technology Corporation maintains a premium orientation across stainless steels, alloy steels, and tool steel powders, serving additive manufacturing, powder forging, metal injection molding, and hot isostatic pressing workflows. Its emphasis on application-engineered materials positions it at the intersection of performance requirements and advanced processing. Sandvik’s Osprey series, encompassing tool and stainless steel powders, reinforces its focus on additive manufacturing and powder metallurgy, with recent introductions such as the Osprey MAR 55 bridging maraging steels and tool steels to offer greater versatility across demanding component designs. Kobe Steel and Laiwu Iron & Steel Group Powder Metallurgy Co., Ltd. continue to serve powder metallurgy applications with established production capabilities, while Rio Tinto has extended its materials portfolio into steel powders developed for additive manufacturing at its RTFT facility. Kymera International and Pometon SpA round out the landscape with stainless steel and metal powder offerings that support powder metallurgy workflows across diverse industrial contexts.
The strategic implication is clear: the market is fragmenting along lines of technology specificity, feedstock strategy, and end-market certification requirements. Companies that treat steel powder as a commoditized input are encountering structural headwinds; those that invest in grade customization, process consistency, and application-specific qualification are converting technical capability into pricing power and customer lock-in.
Forces Reshaping the 2026 Operating Environment
The 2026 decision environment is defined by the intersection of demand evolution, regulatory recalibration, and feedstock economics. On the demand side, advanced manufacturing continues to expand the addressable base for engineered powders, yet regional shipment data from recent industry reporting indicates that not all segments are moving in lockstep. North American iron and steel powder shipments declined by approximately six percent in the prior year amid a market downturn affecting metal injection molding and additive manufacturing volumes, a reminder that aggregate growth narratives can obscure localized softness and segment-specific volatility. This divergence reinforces the need for localized demand assessment rather than reliance on global averages when planning procurement and production schedules.
Regulatory and trade dynamics are adding new layers of complexity. The implementation of an export licensing system in China for certain steel products, including powders, introduces compliance friction and potential supply reconfiguration for buyers dependent on transboundary material flows. Simultaneously, the EU carbon border adjustment mechanism is operationalizing a certificate-based cost structure that will affect steel and aluminum import economics, prompting a reassessment of sourcing geography and total landed cost calculations. In parallel, tariff actions on specialized inputs such as tungsten products have continued to evolve, influencing cost structures for alloyed powder formulations that rely on such additions. These developments are not peripheral; they are becoming central variables in supplier qualification, contract structuring, and inventory strategy.
Feedstock strategy is emerging as a critical differentiator. With recycled scrap serving as the primary feedstock base for steel powder production, companies that can secure consistent scrap streams, control impurity profiles, and integrate scrap sourcing with existing product lines are building durable cost and quality advantages. The linkage between flat products operations and powder output, exemplified by scrap-derived powder development, illustrates how vertical integration and material circularity can reinforce both margin stability and sustainability positioning. In a market where compliance documentation, traceable feedstock, and metallurgical consistency increasingly influence procurement decisions, feedstock strategy is shifting from operational detail to strategic lever.
Why This Report Matters for 2026 Decision-Making
As organizations step into the 2026 planning cycle, the steel powder market presents a paradox: broad growth visibility coexists with sharp divergence in segment performance, regulatory exposure, and competitive capability. Navigating that paradox requires more than top-line forecasts. It demands a clear map of where demand is becoming application-specific, where cost pressures are intensifying, and where strategic positioning is creating defensible advantage.
Metal Powder Market
PW Consulting’s Steel Powder Market research is built to bridge that gap. It equips leadership teams with a structured view of market sizing and trajectory, a nuanced breakdown of segmentation dynamics across product types, applications, and regions, and a competitive analysis that connects corporate moves to underlying strategic logic. It also integrates the regulatory and feedstock forces that are actively reshaping cost structures and supply options, ensuring that strategy discussions are grounded in the operating realities of the current year.
The full report contains the detailed segmentation architectures, forecast sensitivities, competitive capability assessments, and regional demand analyses that turn high-level trends into executable plans. For executives evaluating capacity commitments, sourcing diversification, product roadmap investments, or market entry timing, the complete dataset and accompanying analytical frameworks provide the necessary resolution to move from assumption to evidence-based action.
How to Apply the Findings
- Align procurement and inventory strategy with regional demand divergence and regulatory exposure, rather than relying on global averages or historical shipment patterns alone.
- Evaluate supplier partnerships through the lens of grade customization, feedstock consistency, and certification readiness, recognizing that application-specific qualification is increasingly the primary source of pricing resilience.
- Incorporate trade and compliance variables into total cost modeling, including export licensing implications, carbon adjustment mechanics, and tariff-sensitive input dependencies that affect alloyed powder formulations.
- Use the segmentation and forecasting architectures to stress-test capacity and capital allocation decisions against base, upside, and constrained scenarios, ensuring flexibility in a market where segment performance is decoupling from aggregate growth.
- Leverage competitive capability analysis to identify white-space opportunities in high-purity, aerospace, medical, and advanced additive manufacturing segments where material consistency and traceability command strategic premium.
The steel powder market is not simply expanding; it is restructuring around quality, traceability, regulatory resilience, and application-specific engineering. The organizations that best understand those shifts will be positioned to secure supply, protect margins, and capture growth where it is most durable. PW Consulting’s full Steel Powder Market research provides the depth required to execute that strategy with confidence.
Steel Powder Market
For detailed analysis of this topic, please visit the official page: Steel Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Greenhouse Soil Market to Grow at 5.5% CAGR, Reaching $6,856.6 Million by 2032
By PW Consulting, 2026-09-16
Cultivating Resilience: Inside the Greenhouse Soil Market of 2026
Executive Overview
The global greenhouse soil market stands at a definitive inflection point. As controlled environment agriculture matures from a niche practice into a foundational pillar of modern food and ornamental production, the substrate systems that support root health, nutrient delivery, and water retention have never commanded greater strategic attention. Our latest market research publication dissects this rapidly evolving landscape, offering enterprise leaders a rigorous, forward-looking blueprint for capital allocation, product positioning, and supply chain resilience through the end of the decade.
Drawing on validated historical data spanning 2020 through 2025 and extending into a comprehensive forecast window that runs through 2032, this analysis quantifies the trajectory of an industry transitioning from incremental expansion to structurally accelerated growth. The narrative is clear: greenhouse soil is no longer a commodity input. It is a performance-critical variable where formulation science, regulatory compliance, and regional sourcing economics converge. Organizations that treat it as such will capture disproportionate share; those relying on legacy assumptions will face margin compression, compliance risk, and competitive displacement.
This preview outlines the strategic architecture of our full report. It highlights how the market has evolved, what forces are actively reshaping competitive dynamics, and which analytical frameworks decision-makers need to navigate 2026 with precision. The complete study contains granular segmentation breakdowns, regional demand profiles, channel distribution insights, and detailed competitor scorecards. Every dataset, model, and executive recommendation has been engineered for immediate application in product roadmapping, procurement strategy, partnership evaluation, and market entry planning.
Potting Soil Market
Market Trajectory and Structural Evolution
The commercial foundation of the market has demonstrably expanded over the past half-decade. Historical revenue progression from 2020 through 2025 reflects sustained growth driven by intensified horticultural output, shifting consumer preferences toward greenhouse-propagated produce, and the steady professionalization of containerized growing operations. The momentum does not plateau at the current baseline. Our forecasting framework projects continued revenue expansion across the 2026 to 2032 window, anchored by a compound annual growth rate of 5.5 percent. By the close of the forecast period, total industry revenue is positioned to approach its largest scale yet, reflecting both volume acceleration and value migration toward higher-performance substrate formulations.
This growth curve is not uniform. The market is being pulled forward by a convergence of agronomic innovation, regulatory realignment, and operational cost pressures that are simultaneously expanding opportunity pools and compressing traditional margin structures. Understanding where value pools will concentrate, which product architectures will command premium pricing, and which geographic corridors will experience the steepest demand inflection requires a granular view that our full research delivers. What can be stated with confidence is that the structural drivers behind the forecast are durable, interconnected, and unlikely to reverse in the short to medium term.
For corporate strategy teams, this trajectory presents two immediate imperatives. First, historical performance must be disaggregated to identify which product categories, distribution channels, and application environments are genuinely expanding versus those merely riding broader market sentiment. Second, forward-looking models must incorporate the cost and compliance variables that will redefine substrate economics well before 2030. The complete report provides the analytical scaffolding to do both, enabling leaders to separate signal from noise and align investment horizons with realistic demand pathways.
Forces Reshaping the Competitive Landscape
Industry dynamics in 2026 are being dictated by an unusually dense cluster of external pressures. Regulatory action is accelerating across multiple jurisdictions, fundamentally altering raw material availability and formulation requirements. In the United Kingdom, the nursery sector is executing a government-mandated peat reduction pathway that targets complete phase-out for the hobby segment by 2025 and extends a 100 percent peat reduction mandate to professional greenhouse media by 2030. Across the North Sea, a Finnish greenhouse cooperative has already enforced a threshold requiring less than 30 percent peat content across all production soil mixes, a threshold that has displaced legacy suppliers from established vendor lists and forced rapid rebalancing of sourcing portfolios.
These regulatory shifts are intersecting with environmental policy at scale. Broader European peatland protection frameworks are actively accelerating the substitution of traditional peat inputs with alternative substrates such as wood fiber and coir within greenhouse applications. The transition is not merely compositional; it reshapes procurement logistics, processing requirements, quality control standards, and end-user performance expectations. At the same time, operational cost pressures are mounting. Rising fuel and transportation expenses tied to peat moss and perlite supply chains have elevated both labor and material costs associated with preparing greenhouse soil blends, squeezing operators that lack diversified input strategies or localized processing capabilities.
Greenhouse Soil Market
Counterbalancing these pressures is a policy environment that increasingly rewards climate-aligned soil practices. Funding mechanisms structured under the USDA Inflation Reduction Act are supporting climate-smart agricultural practices, with greenhouse soil amendments explicitly positioned within programs targeting soil carbon sequestration and emission reduction. This creates a strategic opening for suppliers and growers who can document verifiable environmental benefits, align with measurement and reporting standards, and articulate substrate choices within broader sustainability reporting frameworks. The market is no longer pricing soil purely on agronomic performance; compliance posture, input traceability, and carbon impact narratives are becoming material differentiators.
Opportunities and Strategic Pivot Points for Enterprises
The intersection of regulation, input economics, and policy support is generating a set of actionable strategic openings for organizations prepared to act with precision.
- Alternative substrate leadership: The regulatory trajectory away from peat-heavy formulations is creating durable demand for engineered blends that maintain water retention, aeration, and nutrient stability while meeting compliance thresholds. Suppliers that can validate performance parity or superiority with lower-peat or peat-free architectures will capture premium positioning as professional growers recalibrate their purchasing criteria.
- Sustainability-linked procurement: As greenhouse operators face increasing scrutiny from downstream retail, food service, and ornamental distribution channels, substrate sourcing decisions are becoming embedded in broader environmental compliance and reporting obligations. Documented carbon impact, responsible sourcing credentials, and transparent input provenance are transitioning from marketing attributes to procurement requirements.
- Formulation and processing innovation: The cost escalation observed in traditional input transport and preparation is rewarding organizations that can localize blending operations, optimize substrate particle morphology, and reduce dependency on volatile logistics corridors. Operational efficiency in media preparation is emerging as a direct margin lever, not merely an operational convenience.
- Policy-aligned product architecture: Climate-smart funding pathways are expanding the addressable economic rationale for certain soil amendments and substrate strategies. Companies that design product portfolios compatible with sequestration objectives and emission-reduction frameworks can unlock incentive-aligned demand that is less sensitive to pure commodity pricing cycles.
Capturing these opportunities requires more than product iteration. It demands a disciplined assessment of which customer segments are most exposed to regulatory change, which distribution networks can accelerate reformulation adoption, and where competitive moats can be built through certification, consistency, and technical support. The full study maps these decision vectors against quantified demand pathways so that leadership teams can prioritize initiatives with the highest probability of return.
Competitive Ecosystem and Strategic Positioning
The competitive field is anchored by a cohort of established producers with deep formulation expertise, extensive substrate manufacturing capabilities, and long-standing relationships across professional horticulture and commercial greenhouse channels. Scotts Miracle-Gro Company operates at scale as a major producer of organic and conventional greenhouse soil mixes and potting substrates tailored for professional growers. Sun Gro Horticulture maintains its position as the largest North American producer of horticultural peat moss and bark-based growing media blends designed for greenhouse environments. In Europe, Klasmann-Deilmann GmbH has built a leading profile in peat-based and alternative growing media substrates optimized for controlled cultivation, while Premier Tech Ltd. supplies specialized growing media and greenhouse substrates engineered for commercial horticulture applications.
The broader ecosystem extends across organic-focused formulators, regional performance specialists, and European substrate manufacturers. FoxFarm Soil and Fertilizer Co. produces organic greenhouse soil amendments and ready-to-use potting mixes, while Michigan Peat Company remains a key producer of peat-based greenhouse soil mixes and custom horticultural substrates. Espoma Company manufactures natural and organic greenhouse soil products and blends, and Good Earth Horticulture provides high-performance greenhouse soil solutions directed at commercial growers. Florentaise supplies specialized greenhouse and nursery growing media substrates, and ASB Greenworld contributes European production of peat and bark-based growing media for greenhouse use.
Strategic activity among these players is intensifying, reflecting both the opportunity set and the compliance-driven urgency to secure reliable input channels and differentiated product architectures. In April 2025, Griffin Greenhouse Supplies announced a master distributor agreement with Hortus U.S.A. covering growing media products including greenhouse soil substrates, a move that expands channel reach and consolidates distribution leverage for participating partners. In September 2025, HydraFiber introduced HydraTerra, a new formulation combining HydraFiber Advanced Substrate with Sunterra Canadian Sphagnum Peat for greenhouse growers, signaling continued investment in engineered blends that balance performance characteristics with evolving input preferences.
The market concentration profile indicates a moderately fragmented but strategically consolidating landscape. Competitive advantage is increasingly determined not only by volume capacity but by the ability to navigate peat reduction mandates, secure alternative input supply, and deliver consistent blend quality across diverse regional requirements. The complete report provides detailed competitor profiling, strategic posture assessment, and supply chain positioning analysis that enables procurement, product, and corporate development teams to benchmark their standing and identify displacement or partnership opportunities with precision.
What the Full Research Delivers
This preview is designed to establish the substantive depth of our analysis while preserving the granular intelligence that decision-makers require for execution. The complete Greenhouse Soil Market research study expands every dimension introduced here into an actionable intelligence framework. It delivers validated market sizing and forward projections across the full forecast horizon, supported by methodology-transparent modeling that can be integrated into internal planning processes. It disentangles demand by product architecture, application environment, and regional corridor without relying on superficial aggregates, enabling teams to identify where growth is structurally rooted versus cyclically inflated.
The study also provides operational and strategic content built for immediate application:
- Comprehensive segmentation analysis that isolates demand drivers, pricing dynamics, and substitution risk across core product categories and use environments
- Regional demand profiles that map growth intensity, regulatory exposure, and input sourcing realities to support capacity planning and channel strategy
- Competitor benchmarking and strategic posture mapping that clarify where incumbents are reinforcing positions, where vulnerabilities are opening, and where partnership or acquisition logic is most compelling
- Supply chain and raw material assessments that quantify exposure to peat reduction mandates, alternative substrate transitions, transportation cost volatility, and processing constraints
- Regulatory and policy scenario analysis that frames how peat bans, emission-focused directives, and climate-smart funding pathways will reshape procurement criteria and product requirements through 2032
- Actionable strategic recommendations designed for product roadmapping, market entry evaluation, supplier diversification, and commercial positioning in a compliance-sensitive procurement environment
Every section of the report is structured to answer the questions that sit at the center of enterprise planning: Where is durable demand forming? Which formulation strategies will remain viable under tightening input regulations? How should organizations balance cost pressure with performance and sustainability expectations? And which competitive moves will create defensible positioning in a market where regulatory and environmental variables are no longer peripheral concerns?
How Leaders Can Use This Intelligence in 2026
The strategic value of this research lies in its capacity to convert complex market movement into executable direction. In 2026, substrate procurement and product strategy cannot be managed as static line items. They are dynamic decisions shaped by regulatory timing, input substitution velocity, regional demand divergence, and the growing premium on verifiable sustainability performance. Organizations that treat greenhouse soil as a strategic variable rather than a standardized input will be better positioned to protect margins, secure reliable supply, and align product portfolios with the procurement criteria that professional growers are actively revising.
The full study is built for executive review, category management, R&D planning, and commercial strategy. It provides the quantification required for budgeting and forecasting, the competitive context needed for positioning and partnership evaluation, and the regulatory framing necessary to anticipate compliance-driven shifts before they become cost events. For organizations evaluating market entry, regional expansion, formulation diversification, or supplier consolidation, the report offers a structured basis for scenario planning and risk-adjusted decision-making.
The market trajectory is clear, the pressure points are identifiable, and the competitive stakes are rising. What remains is disciplined interpretation and timely execution. Our complete Greenhouse Soil Market research closes the gap between high-level trend awareness and the operational intelligence required to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Greenhouse Soil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Sunglasses Market to Hit $310M by 2032, 6.5% CAGR Drives Fashion Demand
By PW Consulting, 2026-09-16
Beyond the Lens: Strategic Imperatives in the 2026 Sunglasses Market
The global sunglasses market is undergoing a period of structural acceleration. As consumer behavior shifts toward health-conscious eyewear, outdoor recreation, and expressive fashion, industry stakeholders face a complex matrix of growth opportunities, supply chain friction, and intensifying competitive dynamics. At PW Consulting, we have synthesized multi-year historical tracking with forward-looking modeling to deliver a comprehensive market research report designed explicitly for executive decision-making in 2026 and beyond. This article outlines the strategic architecture of our analysis, demonstrates how macroeconomic and competitive forces are reshaping the landscape, and highlights the actionable intelligence packaged within the full study.
The Growth Trajectory: What the Numbers Reveal
Historical tracking from 2020 through 2025 illustrates a market that has consistently outpaced broader consumer goods benchmarks. Revenue climbed from approximately 120.0 million USD in the early part of the decade to 190.0 million USD by the 2025 base year, reflecting a compound trajectory that signals durable demand rather than cyclical spikes. Looking ahead, our forecast window extends through 2032, projecting continued expansion with a 6.5 percent compound annual growth rate. By the close of the forecast period, market revenue is expected to surpass 310.0 million USD, driven by sustained polarization adoption, lifestyle integration of performance eyewear, and expanding accessibility in emerging consumer segments.
These figures are not abstract indicators. They represent a市场 that is maturing in its segmentation logic, where premiumization, functional utility, and sustainability are converging to redefine purchasing behavior. Yet the aggregate numbers only tell the first layer of the story. The real strategic value lies in understanding how value is distributed across product architectures, consumer applications, and geographic corridors—and where intervention points exist for brands, distributors, and private-label operators.
Why 2026 Demands a Strategic Reset
Several concurrent pressures make this an inflection point for industry leadership. On the regulatory front, tariff revisions and material duties have introduced immediate cost volatility. The Vision Council has documented additional 20 percent duties on Chinese-origin materials that took effect in early 2025, directly impacting eyewear production expenses and forcing supply chain recalibration. Alongside these, 25 percent tariffs on goods originating from Mexico and Canada, effective in March 2025, are reshaping cross-border sourcing economics for optical products. Further compounding the landscape, steel and aluminum duties at 25 percent, implemented in mid-March 2025, have increased input costs for frame manufacturing, prompting manufacturers to evaluate material substitution, regional sourcing shifts, and inventory buffering strategies.
Simultaneously, the competitive field is consolidating around premium brand portfolios, polarized lens differentiation, and sustainability narratives. Industry participants are no longer competing solely on price or style; they are competing on lens technology performance, brand equity depth, and the ability to align product development with evolving outdoor and lifestyle use cases. These dynamics require decision-makers to move beyond static market snapshots and adopt scenario-aware planning that accounts for tariff exposure, raw material innovation, and partnership realignment.
What Our Report Delivers: A Framework for Action
The PW Consulting Sunglasses Market research report is engineered to translate macro trends into operational clarity. It provides a rigorous examination of the competitive hierarchy, product segmentation evolution, application-driven demand shifts, and regional momentum patterns. The study is structured to support multiple enterprise use cases, from portfolio optimization and go-to-market positioning to supply chain risk assessment and M&A targeting.
Key components of the report include:
- Historical baseline analysis spanning 2020 to 2025, establishing growth patterns and structural breakpoints
- Forward-looking revenue projections through 2032, anchored by a 6.5 percent CAGR and calibrated for demand continuity and price architecture shifts
- Segment-by-segment evaluation across product type, application category, and regional distribution, revealing where value concentration and growth acceleration intersect
- Competitive profiling of leading manufacturers and brand custodians, with emphasis on portfolio strategy, lens technology positioning, and channel orientation
- Supply chain and regulatory dynamics analysis, mapping tariff impacts, material cost pressures, and sustainability-driven product mix changes
- Actionable strategic recommendations for brand builders, contract manufacturers, distributors, and retail operators
Importantly, the report does not merely describe the market. It stress-tests strategic choices against the forces that will define the next planning cycle. Readers will gain visibility into where polarization and photochromic technologies are expanding functional relevance, where luxury and lifestyle applications anchor the revenue core, and how outdoor and sports segments are carving out differentiated demand pathways. The analysis also tracks how leading players are responding through acquisitions, campaign launches, and trade-show innovations that signal the direction of industry investment.
Competitive Architecture: Leaders, Niche Players, and Strategic Moves
The competitive landscape is characterized by a concentrated top tier and a dynamic field of specialized operators. Established groups anchor the market through portfolio breadth, brand licensing strength, and global distribution networks. EssilorLuxottica, headquartered in France, leverages signature names including Ray-Ban, Oakley, Costa, and Oliver Peoples, while maintaining extensive production of polarized and photochromic lenses worldwide. Its scale and brand architecture position it as a central force in both fashion-driven and performance-oriented segments.
Kering Eyewear, based in Italy, operates a complementary luxury and performance-oriented model under Maui Jim, Gucci, and other premium brands, with strong emphasis on polarized lenses and adventure-aligned collections. The group’s recent activity underscores its focus on experiential brand storytelling: in early 2026, Maui Jim unveiled a global advertising campaign for its spring-summer collection, reinforcing themes of adventure and connection while highlighting polarized lens differentiation for outdoor use.
Luxury Sunglasses Market
Safilo Group, also Italian, produces and distributes sun and optical frames with a pronounced focus on lifestyle, sport, and performance sunglasses. In May 2026, the company announced a binding agreement to acquire Spy+ and Serengeti, a move that expands its sunglasses portfolio and signals a clear intent to strengthen its foothold in performance and specialty categories. This type of portfolio expansion is particularly instructive for market observers, as it illustrates how incumbents are consolidating capability to capture higher-value demand pools.
De Rigo Vision stands out for its sustainability-forward product development. The company specializes in eco-friendly and high-performance sunglasses, with frames incorporating recycled inputs and lifestyle collections designed to align with environmentally conscious consumer preferences. Industry data indicates that its eco-frame collections, built with over 60 percent recycled inputs, achieved a 12 percent unit mix shift toward sustainable SKUs in EMEA retailers during peak seasons. This suggests that sustainability is no longer a peripheral differentiator; it is becoming a measurable driver of assortment composition and retailer acceptance.
Marcolin, also headquartered in Italy, manufactures sunglasses for licensed brands including Tom Ford, Adidas, and Timberland, balancing fashion credibility with performance relevance. Its business model highlights the strategic importance of licensing partnerships in scaling brand presence while maintaining manufacturing discipline.
On the specialized end of the spectrum, companies such as Maui Jim and goodr illustrate how focused product strategies can capture distinct demand niches. Maui Jim provides polarized sunglasses for fishing, outdoor sports, and adventure, supported by proprietary lens technology that emphasizes visual clarity and glare reduction. goodr, meanwhile, targets the accessible performance segment with affordable, polarized active sunglasses designed for no-slip and no-bounce stability, demonstrating that functional reliability can drive loyalty even in price-sensitive environments. Bajio Sunglasses rounds out this category with a premium polarized focus on fishing and water sports, reinforcing the value of adventure-oriented positioning and specialized use-case marketing.
These competitive profiles are not static. They reflect an industry where brand architecture, lens technology, and channel alignment are being continuously re-weighted. By mapping these players and their recent strategic actions, the report reveals where capability gaps exist, where acquisition opportunities may arise, and how differentiation pathways are evolving.
Market Dynamics: Regulation, Materials, and the Cost of Doing Business
The sunglasses market in 2026 is being shaped as much by external policy and material realities as by consumer preferences. Tariff actions have introduced immediate and medium-term cost pressure. The additional 20 percent duties on Chinese-origin materials are disrupting eyewear production costs and supply chains, forcing manufacturers and import-dependent operators to reconsider sourcing exposure and inventory posture. At the same time, 25 percent tariffs on goods from Mexico and Canada are elevating production costs and prompting supply chain adjustments for optical products. The steel and aluminum duties at 25 percent further complicate frame manufacturing economics, especially for brands that rely on metal components or mixed-material constructions.
In response, industry participants are evaluating a range of mitigation strategies. Some are accelerating material substitution programs, others are diversifying supplier geographies, and still others are recalibrating product mix toward SKUs with better margin resilience. The regulatory environment is likely to remain a decision variable rather than a transient disruption, which means strategic planning must incorporate tariff sensitivity as a core assumption rather than an exceptional scenario.
Materials innovation is proceeding in parallel. Sustainability-driven frame development is moving from pilot initiatives to commercial scaling, with recycled content, lightweight performance polymers, and eco-conscious finishing processes gaining retailer and consumer acceptance. Where these initiatives succeed, they do more than improve environmental positioning; they create product differentiation that can support premium pricing, enhance assortment distinctiveness, and align with procurement requirements in increasingly sustainability-conscious retail channels.
How to Use This Research for 2026 Decision-Making
The strategic utility of this report lies in its multi-lens design. For brand and portfolio leaders, the segmentation analysis clarifies where demand is accumulating and which product attributes are driving repeat purchase behavior. For supply chain and operations teams, the regulatory and materials discussion provides context for cost modeling, sourcing diversification, and inventory strategy. For corporate development and investment teams, the competitive profiling and recent industry developments offer a basis for evaluating partnership structures, acquisition targets, and white-space positioning.
The report is built to support scenario-based planning. Decision-makers can use the forecast framework to test revenue assumptions against different price, mix, and channel strategies. They can assess how tariff-related cost changes might influence margin structures across product types and applications. They can also evaluate whether sustainability-oriented product development is likely to translate into measurable assortment advantages in specific retail environments. In each case, the goal is not to provide a single forecast line, but to equip leaders with the analytical architecture needed to make defensible, forward-looking choices.
The full study goes further still. It details the structural logic behind demand concentration, traces how product type and application categories interact with regional momentum, and identifies the strategic implications of recent competitive activity. It also contextualizes the market within broader consumer trends, including the growing importance of eye protection, the blending of fashion and function, and the role of outdoor recreation as a durable demand engine. Together, these elements form a decision-ready intelligence package for organizations that need to act with precision in a market where the stakes are rising.
Conclusion: Turning Market Visibility into Strategic Advantage
The sunglasses market is expanding with clarity and complexity. Revenue is climbing, product categories are evolving, and competitive players are reshaping their portfolios in response to both consumer demand and external pressure. In this environment, generic market summaries are insufficient. What leaders need is a structured, evidence-based view of where growth is originating, how competitive advantage is being built, and which operational adjustments will protect margins while enabling expansion.
PW Consulting’s Sunglasses Market research report is designed for exactly that purpose. It combines historical rigor, forward-looking projection, competitive intelligence, and dynamic context into a single analytical framework. The insights within are intended to inform product strategy, sourcing decisions, brand positioning, and investment prioritization throughout 2026 and the extended forecast horizon. To access the complete segmentation detail, company profiles, forecast breakdowns, and strategic recommendations, we invite you to explore the full report on our website.
Sunglasses Market
For detailed analysis of this topic, please visit the official page: Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
L-Carnitine Market Hits $216.4M in 2025, Forecasts 5.2% CAGR to Surpass $307.8M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the L-Carnitine Market: Navigating Growth and Compliance in 2026 and Beyond
The global landscape for L-Carnitine is undergoing a subtle but significant transformation. As stakeholders across pharmaceuticals, nutraceuticals, and animal nutrition evaluate their positioning for 2026, the need for precise, forward-looking intelligence has never been more critical. Our latest market research report offers a comprehensive examination of this evolving sector, delivering actionable insights designed to support strategic decision-making in an environment defined by steady expansion and shifting regulatory parameters.
Market Trajectory and Growth Dynamics
The L-Carnitine market has demonstrated consistent resilience over the past half-decade, with historical performance from 2020 through 2025 establishing a foundation of incremental yet reliable growth. Valuations have progressed from approximately 178.5 million USD in 2020 to an estimated 216.4 million USD by 2025, reflecting a compound annual growth rate of 5.2 percent across the forecast horizon extending to 2032. This trajectory suggests that the market will reach roughly 307.8 million USD by the close of the projection period, indicating sustained demand drivers rather than episodic spikes.
For enterprise leaders, this growth profile carries important implications. A moderate CAGR of this magnitude typically signals a mature but still expanding category, where competitive advantage is increasingly derived from operational efficiency, regulatory preparedness, and product differentiation rather than pure volume play. The forecast period through 2032 provides sufficient runway for organizations to calibrate capacity investments, assess supply chain vulnerabilities, and align product portfolios with emerging application trends. Readers seeking a complete breakdown of segment-level performance, regional distributions, and application-specific revenue splits are encouraged to review the full report, where granular data tables and analytical commentary provide the granularity required for precise planning.
Structural Forces Shaping the Industry
Several structural dynamics are actively reshaping how value is created and captured within the L-Carnitine ecosystem. On the supply side, synthesis pathways involving fermentation or chemical processes remain cost-intensive, introducing persistent pressure on pricing architectures across global markets. Raw material price fluctuations have emerged as a recurring obstacle for manufacturers operating within complex international supply chains, compelling producers to adopt more sophisticated hedging strategies, diversify sourcing arrangements, and optimize production yields to protect margins.
Regulatory developments are simultaneously redefining market access parameters. In October 2025, Lonza Sales AG received an EFSA scientific opinion renewal for the authorization of L-Carnitine and L-Carnitine L-tartrate as feed additives for all animal species, a decision that reinforces the regulatory legitimacy of carnitine-based feed applications within European markets and provides downstream assurance for feed-grade manufacturers. More recently, in January 2026, the EU Commission enacted Regulation (EU) 2026/140, revising Maximum Residue Levels for carnitine derivatives. This regulatory adjustment concentrates market access among active pharmaceutical ingredient manufacturers that maintain documented safety verification infrastructure, effectively raising the compliance bar for exporters seeking to serve European downstream customers.
On the demand and therapeutic side, the FDA has approved both oral and intravenous L-Carnitine specifically for the treatment of primary and secondary carnitine deficiency resulting from inborn errors of metabolism, reinforcing a clinically validated application base that anchors pharmaceutical-grade demand. Meanwhile, product innovation continues to broaden the commercial footprint: in January 2025, Otsuka Pharmaceutical launched the ENSOLID clinical nutrition formula incorporating L-Carnitine, illustrating how established players are integrating carnitine into specialized nutritional formulations that bridge medical and wellness positioning.
These intersecting forces create a landscape where regulatory literacy, supply chain resilience, and application diversification converge as decisive competitive factors. The full report dedicates substantial analysis to each of these dynamics, offering scenario-based commentary and mapping their implications across different business models and geographic contexts.
Competitive Landscape and Strategic Positioning
The competitive architecture of the L-Carnitine market reflects a diversified set of participants spanning pharmaceutical manufacturing, nutritional ingredient supply, research reagent distribution, and animal nutrition specialization. Market concentration metrics indicate that the top three firms command approximately 25.4 percent of total revenue, while the top five collectively account for roughly 31.7 percent. This moderate concentration suggests that while leading players hold meaningful share, the market remains sufficiently fragmented to allow new entrants and regional specialists to carve out differentiated positions through quality assurance, regulatory compliance, and application-specific expertise.
Worldwide Pharmaceutical Grade L-Carnitine Market
Among the prominent incumbents, Lonza Ltd., headquartered in Basel, Switzerland, stands out for its specialization in L-Carnitine production under the Carnipure® brand, serving pharmaceutical, nutraceutical, and animal feed applications with a recognized quality signature. Biosint S.p.A., based in Italy, produces L-Carnitine as an active pharmaceutical ingredient and feed additive, positioning itself at the intersection of clinical-grade and agricultural-grade demand. In China, Northeast Pharmaceutical Group Co., Ltd., located in Shijiazhuang, Hebei, manufactures L-Carnitine and derivatives for pharmaceutical and supplement use, reflecting the growing capability of regional producers to serve both domestic and export markets.
Additional participants broaden the competitive mosaic. Cayman Chemical Co., based in Ann Arbor, Michigan, supplies L-Carnitine for research, diagnostics, and nutritional products, catering to precision-oriented downstream users. Kaiyuan Hengtai Nutrition Co., Ltd. and ChengDa Medicines Co., Ltd., both operating from China, produce L-Carnitine for animal nutrition and human health supplements, as well as pharmaceutical and veterinary applications, respectively. Huanggang Huayang Medicines Co. Ltd. supplies L-Carnitine for pharmaceutical and feed markets, while AdvaCare Pharma USA LLC, headquartered in Cheyenne, Wyoming, offers L-Carnitine in OTC supplements and formulations. Tokyo Chemical Industry Co., Ltd. provides L-Carnitine as a fine chemical and research reagent, and Merck KGaA and Sigma-Aldrich contribute to the laboratory and industrial supply chain, distributing and supplying L-Carnitine for research and manufacturing contexts.
These firms illustrate the breadth of the value chain and the varied strategic priorities that define success in this market. For competitive intelligence purposes, our report examines each profiled company with a structured assessment encompassing geographic footprint, product architecture, regulatory posture, and recent strategic moves. The objective is to equip clients with the comparative context required to evaluate partnership opportunities, assess competitive threats, and identify whitespace where brand positioning or application focus can be sharpened. Detailed competitive profiles, including URL references and operational summaries, are provided in the complete publication.
L-Carnitine Market
Report Architecture and Practical Utility
Our market research is designed as an operational tool rather than a static data repository. The report integrates multiple analytical dimensions that collectively support strategic planning across commercial, operational, and regulatory functions. Core components include a comprehensive market overview grounded in historical performance and forecast modeling, regional and segment-level analyses that map opportunity distribution without diluting methodological rigor, and an application-based evaluation that distinguishes demand patterns across dietary supplements, sports nutrition, functional beverages, animal feed, and pharmaceutical formulations.
The competitive landscape section delivers structured company profiles, share distribution insights, and an assessment of concentration dynamics that help stakeholders gauge the intensity of rivalry and the potential for consolidation. Recent developments are tracked chronologically and contextualized within broader industry trends, ensuring that regulatory renewals, product launches, and policy adjustments are interpreted not as isolated events but as signals within an evolving market architecture. Supply-side considerations, including synthesis cost structures and raw material volatility, are examined alongside demand-side drivers to provide a balanced view of margin risk and pricing strategy levers.
Importantly, the report avoids superficial aggregation. Where segment splits, regional valuations, and application revenue figures exist, they are presented with sufficient depth to enable scenario planning, yet the publication intentionally directs readers to the full dataset for precise percentage breakdowns and detailed tabulations. This approach ensures that the executive summary establishes analytical credibility while preserving the incentive to access the complete research deliverable for decision-grade detail.
Strategic Implications for 2026 Decision-Making
For organizations formulating strategy in 2026, several priorities emerge from the intersection of growth trends, regulatory evolution, and competitive structure. First, compliance infrastructure is no longer a back-office function but a market access determinant. The January 2026 EU regulation on Maximum Residue Levels means that exporters and API manufacturers must demonstrate robust safety verification capabilities to maintain eligibility in European channels. Companies that treat regulatory documentation as a strategic asset will be better positioned to secure supply agreements and differentiate from competitors with weaker compliance postures.
Second, supply chain design requires renewed attention. Cost-intensive synthesis pathways and raw material volatility demand proactive inventory management, multi-source procurement strategies, and continuous yield optimization. Firms that integrate these considerations into their operational planning can convert supply-side pressure into a margin defense advantage, particularly in price-sensitive segments where pass-through mechanisms are constrained.
Third, application diversification offers a pathway to resilience. While dietary supplements and sports nutrition continue to represent substantial demand centers, functional beverages, animal feed, and pharmaceutical formulations each present distinct growth drivers and regulatory contexts. Understanding the revenue contribution and growth characteristics of each application stream enables portfolio managers to balance exposure, align R&D priorities, and tailor marketing messaging to the expectations of different downstream audiences.
Fourth, competitive awareness must extend beyond headline market shares. The moderate concentration profile of this market means that regional specialists, research-grade suppliers, and formulators can exert meaningful influence within niche channels. Monitoring the activities of firms such as Lonza, Biosint, Northeast Pharmaceutical, Cayman Chemical, and the broader set of Chinese and American participants provides early warning of capacity expansions, regulatory milestones, and product launches that may reshape regional pricing or availability.
Accessing the Full Intelligence Package
This article offers a high-level orientation to the forces shaping the L-Carnitine market and the strategic questions that organizations should be addressing as they move through 2026. However, the density of market activity, the granularity of segment performance, and the specificity of regulatory developments require a more detailed analytical apparatus than a summary can provide. The complete report delivers exhaustive market sizing across the full forecast horizon, segment- and region-level revenue distributions, application-based growth narratives, and structured competitive profiles that collectively support rigorous planning.
Decision-makers who require precise percentage splits, detailed regional valuations, and comprehensive company assessments will find the full publication essential. We invite you to access the complete market research deliverable to obtain the data depth and analytical context necessary for confident strategic execution.
For detailed analysis of this topic, please visit the official page: L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com