

Blogs
PW Consulting: Body Composition Analyzers Market to Hit $847.35M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-07
Unlocking Strategic Value in the Body Composition Analyzers Market: Why 2026 Demand a Deeper Intelligence
The body composition analysis sector is undergoing a structural transformation that goes far beyond incremental growth. As healthcare systems shift toward preventive and personalized medicine, fitness ecosystems digitize their member journeys, and academic research demands higher reproducibility, the instruments measuring lean mass, fat distribution, and segmental composition have become strategic assets rather than isolated diagnostics. For executives planning capital allocation, product roadmaps, and market entry in 2026, surface-level reading of top-line numbers is no longer sufficient. A rigorous, data-grounded intelligence framework is required to separate durable demand drivers from transient noise.
Mica Cloth Market
Our latest market research on the Body Composition Analyzers Market is designed precisely for this decision environment. It maps the evolution of the industry from 2020 through 2025, establishes a firm base year of 2025, and projects forward across 2026 to 2032. The study translates historical revenue progression into a disciplined forecast, while deliberately preserving the analytical depth that procurement leaders, R&D directors, and venture investors need to act with confidence. This article previews the strategic architecture of the report, demonstrates how the macro trajectory informs 2026 decision-making, and explains why the full document remains an essential instrument for anyone serious about competitive positioning.
Worldwide Negatively Refractive Material Market
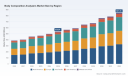
The market has already demonstrated a consistent upward path. From 388.32 million USD in 2020, revenue climbed to 402.92 million USD in 2021, then accelerated to 454.21 million USD in 2022 as institutional buyers restarted procurement cycles. The expansion continued through 2023 at 468.96 million USD and 2024 at 499.04 million USD, before reaching 535.64 million USD in 2025. That momentum carries into the early forecast window, with 567.17 million USD in 2026, 591.88 million USD in 2027, and 652.58 million USD in 2028. By 2030, the trajectory points to 760.16 million USD, advancing to 787.05 million USD in 2031 and 847.35 million USD in 2032. Across the full projection period, the compound annual growth rate settles at 6.98 percent, reflecting a market that is expanding at a measured but durable pace rather than relying on speculative spikes. For strategy teams, this shape matters as much as the endpoint: it signals a market where share gains, technology differentiation, and channel execution will determine winners, not merely a rising tide.
Sterile Transparent Dressing Market
What the Research Delivers: From Macro Trajectory to Actionable Architecture
A robust market study does more than report figures; it builds a decision scaffold. This report structures its intelligence so that leadership teams can connect revenue trends with operational realities. The analytical framework is built around three interdependent pillars that matter directly to 2026 planning cycles: segmentation logic that reveals where demand concentrates, competitive profiling that decodes how incumbents protect and extend their positions, and regulatory and reimbursement context that determines which solutions can scale commercially.
The segmentation architecture examines the market across multiple dimensions without reducing the story to a single axis. By mapping the landscape through product categories, application environments, and regional deployment patterns, the study shows how different buyer groups prioritize accuracy, portability, connectivity, and total cost of ownership. This matters because a device strategy that performs in one setting may misfire in another. A hospital procurement committee evaluating clinical-grade reproducibility will weigh evidence and certification differently from a wellness chain optimizing member engagement and throughput, even when both are buying body composition analyzers. The report teases these decision pathways apart so that product leaders can align feature sets, pricing, and go-to-market tactics with the realities of each buying center.
Equally important is the report’s treatment of the competitive field. The industry is not a flat landscape; it is shaped by a handful of established players whose portfolios, clearances, and channel relationships create real barriers for newcomers. The research profiles the organizations that are actively defining standards for professional use, including their distinct technological orientations and deployment strengths. Tanita Corporation has built its reputation around FDA-cleared professional multi-frequency bioelectrical impedance analyzers designed for segmental assessment in both clinical and fitness environments. InBody Co., Ltd. has expanded its footprint with a professional BIA family spanning the 270, 380, 580, 770, and 970 series, emphasizing reproducibility across hospitals, clinics, and sports applications. Hologic, Inc. anchors its offering in the Horizon DXA system, which supports whole-body composition, bone density, and lean and fat mass analysis in clinical settings. OMRON Corporation contributes Bluetooth-connected body composition monitors that apply bioelectrical impedance for segmental analysis across wellness and clinical programs. Seca GmbH & Co. KG provides medical-grade BIA devices in its mBCA series, integrating ultrasonic height measurement to support precise hospital and clinical assessment. Bodystat Ltd. focuses on portable BIS and BIA analyzers built for quick, accurate segmental and whole-body measurements in fitness and medical contexts. RJL Systems, Inc. continues to advance its Quantum series for whole-body and segmental composition analysis with a foundation in clinical validation.
These profiles are not static company summaries. They are used to illuminate how product architecture, certification status, and application focus shape market access. The study explains where each player’s differentiation creates leverage, where their coverage is strongest, and what gaps may remain for challengers or new entrants. For 2026 strategists, this is the difference between guessing which competitor might move next and understanding the structural incentives behind their likely moves.
Regulatory and Reimbursement Signals That Reshape Commercial Calculus
Technology alone does not determine adoption; the rules of the market do. One of the most valuable contributions of this research is its integration of regulatory and reimbursement context into the broader market narrative. Rather than treating compliance as an afterthought, the report uses these signals to explain where demand can legitimately scale and where friction may persist.
On the regulatory side, the United States has registered 430 body composition analyzers with the FDA, a figure that underscores both the breadth of product activity and the importance of clearance status in professional procurement. At the same time, specific devices continue to secure milestone approvals that open or reinforce market pathways. The Seca mBCA 514 body composition analyzer obtained FDA 510(k) clearance, reinforcing the viability of medical-grade bioimpedance platforms in hospital and clinic workflows. In parallel, the Hologic Horizon DXA system received CE Mark approval for body composition analysis, broadening its addressable footprint in settings that recognize European conformity standards. These approvals are not isolated accolades; they are commercial enablers that influence purchasing confidence, integration into care pathways, and acceptance by institutional buyers.
Reimbursement dynamics add another layer of strategic relevance. CPT code 0358T remains available for whole-body bioelectrical impedance analysis body composition assessment, preserving a billing pathway that can improve the economic case for clinical adoption. For healthcare providers weighing capital equipment decisions, the presence of a usable reimbursement code can shift the cost-benefit calculus and alter the speed at which a technology moves from pilot use to routine deployment. The research places these reimbursement realities in context, showing how they interact with workflow fit, evidence requirements, and purchasing cycles across care settings.
For a strategist in 2026, these dynamics are not background color. They define where the addressable opportunity is most liquid, which product characteristics are likely to be rewarded, and how quickly a new offering can gain traction. The report translates these regulatory and reimbursement signals into practical implications for market entry timing, sales enablement, and partnership choices.
Interpreting the 2026–2032 Trajectory for Strategic Planning
The forecast period is where intelligence becomes usefulness. A market growing from 567.17 million USD in 2026 toward 847.35 million USD by 2032 at a 6.98 percent compound annual growth rate is expanding steadily, but steady growth rewards disciplined strategy more than brute-force investment. The report frames this trajectory as a planning tool for capacity decisions, R&D prioritization, channel expansion, and M&A evaluation.
Several strategic questions naturally emerge when the numbers are read alongside the competitive and regulatory context. Which applications are likely to absorb new capacity fastest, and what evidence or integration capabilities will those buyers demand? Which product categories offer the clearest route to differentiation without triggering a race to the bottom on price? Where do regional procurement cultures and regulatory environments create uneven adoption curves that require localized market approaches rather than a uniform global rollout? The study addresses these questions by connecting the macro forecast to the structural factors that actually drive purchasing behavior.
The report also places market concentration in strategic context. With the top three competitors accounting for 47.8 percent of market revenue and the top five reaching 62.1 percent, the industry reflects a meaningful degree of consolidation among leading players. This concentration matters for 2026 strategy because it shapes the bargaining power of distributors, the expectations of institutional buyers, and the realistic pathways for challengers. A new entrant cannot assume that a technically competent device will automatically gain traction in a field where incumbents already command a large share of revenue and have established validation narratives, service networks, and recurring customer relationships. The research helps leaders assess whether to compete on a narrow advantage, pursue partnership-based distribution, or target underserved application environments where concentration is less protective.
Why the Full Report Is Essential for 2026 Decision-Making
An executive summary can point toward direction, but it cannot replace the granular architecture required for real commitments. The full report extends well beyond the macro outlook and company profiles previewed here. It delivers a working view of how the market segments in practice, where buyer preferences are converging or diverging, and how the competitive set is likely to evolve as clearances, reimbursement realities, and technology upgrades reshape buying criteria. It gives strategy teams a basis for scenario planning rather than a single-point guess.
For product leaders, the study supports decisions about feature emphasis, clinical validation, connectivity, and form factor by tying them to the settings where they will be evaluated. For commercial teams, it informs channel design, pricing architecture, and value proposition framing by revealing how different buyer groups justify investment. For investors and corporate development teams, it provides a structured lens on where concentration is high, where whitespace may still exist, and where regulatory momentum could accelerate adoption. For operations and supply planning, it offers a forecast shape that can be stress-tested against different assumption sets.
Crucially, the report is built to remain useful as conditions change. By grounding conclusions in historical data from 2020 to 2025 and extending them through 2032, it gives decision-makers a reference frame that can be revisited as new clearances emerge, reimbursement policies shift, and competitor moves alter the field. That continuity is what turns a market overview into a strategic asset.
How to Use This Intelligence in 2026 Planning Cycles
The most effective use of this research is not passive reading but active integration. We recommend that leadership teams approach the full document as a decision toolkit. Start by aligning the forecast with internal capacity and investment horizons, then test whether current product and channel assumptions still fit the segmentation pattern revealed in the study. Use the competitive profiles to challenge hidden assumptions about barriers, substitution risk, and the realistic scope of differentiation. Bring the regulatory and reimbursement context into procurement and clinical advocacy conversations so that product value is framed in terms that institutional buyers can act on.
The report also supports more disciplined external messaging. When speaking with partners, distributors, or prospective customers, teams can anchor claims in a coherent view of market structure rather than isolated stats. That matters because credibility in this sector depends on demonstrating that a solution fits a real adoption pathway, not merely that it exists. The more precisely a company can connect its offering to the application environment, evidence expectations, and purchasing logic described in the research, the stronger its position becomes in 2026 negotiations and pilots.
Closing Perspective
The body composition analysis market is entering a phase where durable growth and competitive separation depend on the same thing: a clear understanding of how technology, regulation, reimbursement, and buyer behavior intersect. The numbers tell part of the story, but the strategic value lies in the structure beneath them. From the 2020 baseline of 388.32 million USD through the 2025 base year of 535.64 million USD and into the 2032 projection of 847.35 million USD, the market is expanding at a pace that rewards precision over speculation. The 6.98 percent compound annual growth rate across the forecast window reinforces the need for planning discipline rather than reactive optimism.
This research is designed to give executives that discipline. It preserves the analytical depth required to guide product, commercial, and investment decisions while keeping the most actionable segmentation and competitive insights intact for the full document. For teams preparing for 2026, the opportunity is not simply to note that the market is growing, but to decide where to position, how to justify adoption, and which competitive moves are most likely to pay off. The complete report provides the intelligence needed to make those choices with confidence. To access the full dataset, segmentation logic, and executive recommendations, visit the source page and secure the complete market intelligence package.
For detailed analysis of this topic, please visit the official page: Body Composition Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Stem Cell Therapy Market Hits $232.5M in 2025, 7.05% CAGR to $375.1M by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Next Frontier: Inside the Animal Stem Cell Therapy Market 2026–2032
The animal health sector is undergoing a paradigm shift. For decades, veterinary medicine relied heavily on pharmacological interventions and surgical procedures to manage chronic conditions, degenerative diseases, and complex injuries in companion and livestock animals. Today, a new therapeutic class is redefining the standard of care: stem cell therapy. What was once confined to experimental research laboratories and elite specialty clinics has matured into a structured commercial landscape, driven by advances in regenerative biology, evolving regulatory frameworks, and an expanding willingness among pet owners and producers to invest in long-term animal health outcomes.
Hot Water Heating Cable Market
PW Consulting’s latest market research report on the Animal Stem Cell Therapy Market captures this inflection point with precision. Designed for executive leadership, R&D directors, commercial strategists, and investment committees, this study maps the trajectory of a market that has moved from nascent curiosity to measurable revenue momentum. The following analysis previews the strategic lens, structural insights, and decision-making utility embedded in the full report, while preserving the granular intelligence that will be delivered in the complete publication.
Shooting Earmuff Market
A Market That Has Crossed the Proof-of-Concept Threshold
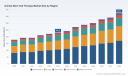
Regenerative therapies for animals are no longer a speculative storyline. The data tells a clear story of consolidation and acceleration. Between 2020 and 2025, the market expanded from a modest baseline to a multi-hundred-million-dollar revenue pool, reflecting sustained adoption across veterinary practices, specialty clinics, and emerging commercial partnerships. The trajectory has not been linear, but it has been durable. Fluctuation in early years gave way to steadier growth as clinical applications broadened, practitioner awareness deepened, and supply-side capabilities improved.
Worldwide Pipe Grouting Service Market
Looking forward, the forecast window through 2032 indicates continued expansion at a compound annual growth rate that underscores the sector’s structural momentum. This is not a bubble built on hype; it is a commercial pathway shaped by tangible therapeutic demand, incremental regulatory clarity, and a growing number of players transitioning from investigational products toward commercialized offerings. For decision-makers evaluating market entry, partnership structures, or portfolio reallocation, the growth curve offers both opportunity and timing risk. The window for strategic positioning is open, but it is narrowing as more competitors validate the commercial viability of stem cell–based veterinary solutions.
The report situates these figures within a broader narrative of adoption maturity. It examines how early clinical enthusiasm has been tempered by operational realities, how pricing models are stabilizing around practitioner workflows, and how the balance between autologous procedures and off-the-shelf allogeneic products is reshaping the economics of veterinary regenerative medicine. Readers will find that the headline growth numbers are only the starting point; the strategic value lies in understanding the forces that will determine which business models scale and which remain confined to niche applications.
Segmentation as a Strategic Compass
Understanding where demand is concentrated, and why, is essential for resource allocation. The report dissects the market across multiple axes without reducing it to static percentage tables. Instead, it examines the structural logic behind each segmentation dimension so that executives can align their go-to-market strategy with the underlying drivers of adoption.
At the application level, the therapy landscape is anchored by orthopedic and degenerative conditions, with osteoarthritis representing the dominant clinical use case. Tendon and joint disorders, wound healing, bone repair, and inflammatory conditions each contribute distinct demand profiles, while emerging applications in oncology and complex systemic diseases illustrate the long-tail potential that will shape later-stage commercialization. The report analyzes how clinical evidence maturity, practitioner familiarity, and reimbursement or out-of-pocket willingness vary across these indications, and how those variables influence volume, margin, and cycle time for therapy developers.
Animal type segmentation reveals a market that is currently anchored by companion animals but with meaningful structural relevance from livestock applications. Companion animal segments benefit from higher owner spending capacity, emotional decision-making dynamics, and direct-to-consumer awareness channels. Livestock applications, while smaller in current revenue contribution, carry different economic logic: herd-level outcomes, production efficiency, and veterinary economics that reward scalable, cost-effective regenerative interventions. The report examines how these two segments diverge in purchasing behavior, clinical workflow requirements, and commercial scaling strategies, enabling readers to identify where their capabilities best align with end-market economics.
Geographic segmentation further illuminates the commercial map. North America currently represents the largest revenue concentration, supported by established veterinary specialty networks, advanced laboratory infrastructure, and early regulatory engagement. Europe follows with its own distinct demand patterns shaped by regional practice structures and differing attitudes toward regenerative modalities. Asia Pacific reflects an emerging but accelerating footprint, driven by expanding pet ownership, growing veterinary specialization, and increasing investment in animal health innovation. Latin America and the Middle East and Africa represent additional zones of potential expansion, each with unique access, pricing, and distribution dynamics. Rather than presenting raw regional splits, the report translates these patterns into actionable intelligence about where infrastructure, partnerships, and regulatory readiness create viable entry points, and where caution is warranted.
The Competitive Arena: Differentiated Strategies in a Contested Space
The animal stem cell therapy market is not a winner-take-all environment, but it is increasingly defined by differentiated positioning. Companies are competing along multiple dimensions: product format, regulatory status, clinical indication focus, delivery logistics, and veterinarian engagement models. The report provides a structured competitive landscape analysis that goes beyond company descriptions to examine how each player’s strategic choices shape their commercial prospects.
Gallant has emerged as a notable example of a company pursuing allogeneic, ready-to-use therapies for companion animals. Its focus on refractory feline chronic gingivostomatitis and osteoarthritis reflects a strategy centered on unmet clinical need and regulatory ambition, including advancement toward FDA conditional approval. In early 2026, Gallant announced a first-of-its-kind partnership with MWI Animal Health to establish ultra-low temperature cold chain logistics for delivery of ready-to-use stem cell therapies into veterinary clinics. This move highlights a critical commercial challenge: the requirement for reliable storage and distribution at very low temperatures can become a barrier to adoption if not solved at scale. By investing in cold chain infrastructure, the company is addressing a bottleneck that affects not only its own product pathway but also signals broader operational expectations for off-the-shelf regenerative therapies in veterinary medicine.
VetStem, Inc. represents a different strategic posture, with deep experience in autologous stem cell therapies derived primarily from adipose tissue for canine osteoarthritis, equine joint disorders, and chronic pain management. At the same time, the company is expanding toward allogeneic off-the-shelf products, including precise regenerative solutions and orthopedics-focused pipelines. Additional funding secured in early 2025 is being directed toward advancing StemStat Ortho toward FDA conditional approval, signaling a dual-track strategy that pairs established practitioner relationships with next-generation product development. The report examines how VetStem’s positioning illustrates the broader industry tension between customization and standardization, and how companies are attempting to capture value across both paradigms.
Ardent Animal Health operates with a strong in-clinic autologous regenerative therapy model, offering stromal vascular fraction–based treatments and platelet-rich plasma solutions for dogs and cats with orthopedic conditions. Its approach reflects the commercial reality that many veterinary practices prefer point-of-care procedures that integrate directly into existing clinic workflows. VETherapy, with development operations spanning San Francisco and Coimbra, Portugal, emphasizes cost-effective and time-efficient regenerative solutions for complex pet diseases, underscoring the importance of operational efficiency in a market where adoption depends heavily on practitioner convenience and case throughput.
Magellan Stem Cells, based in Australia, contributes a regional perspective by supplying autologous and donor-derived mesenchymal stem cells for osteoarthritis treatment in companion animals, with clinical trial planning underway. Its presence illustrates how market activity is distributed across geographies and how companies in emerging hubs are building capabilities that may eventually intersect with larger global commercialization pathways.
The competitive analysis in the report does not treat these players as isolated profiles. It evaluates them within the context of market concentration, showing that the sector remains moderately consolidated, with a meaningful share held by a relatively small group of active commercial and development-stage companies. This concentration pattern matters for M&A strategy, partnership targeting, and barrier-to-entry assessment. It also signals that the field is still open enough for new entrants with differentiated technology or business models, but increasingly crowded enough that undifferentiated plays will face pressure on pricing, clinical differentiation, and practitioner loyalty.
Regulatory Realities and Industry Dynamics
No assessment of this market is complete without confronting the regulatory environment, which remains one of the most important variables shaping commercial timelines, risk exposure, and strategic planning. The report dedicates substantial attention to the current state of oversight, the practical implications for product developers, and the signals that indicate where the regulatory trajectory is heading.
As of early 2025, no FDA-approved animal cells, tissues, and cell- and tissue-based products were available for veterinary use in the United States. This absence is not a marginal detail; it defines the current commercial landscape. Companies are navigating a space where therapeutic promise and investigator interest are substantial, but formal approval pathways remain incomplete. That reality creates both urgency and caution. For developers, it means clinical data generation, quality systems, and regulatory engagement must be advanced with precision. For veterinary practices and distributors, it means procurement, communication, and compliance strategies must account for the distinction between approved therapeutics and investigational or unregulated offerings.
Regulatory pressure has already begun to manifest in enforcement activity. In 2025, the FDA issued warning letters to companies including Ardent Animal Health, LLC and Safari Stem Cell, LLC for marketing unapproved stem cell and regenerative products. These actions signal a more active oversight posture and highlight the compliance risks facing organizations that move faster than regulatory frameworks can accommodate. The report examines what these enforcement patterns imply for market discipline, how they may influence practitioner confidence, and why companies with robust regulatory strategies may gain competitive advantage as the field matures.
At the same time, there are signs of constructive progress. Regulatory engagement is not uniformly obstructive. For example, the FDA Center for Veterinary Medicine completed the Reasonable Expectation of Effectiveness technical section letter for Gallant’s lead feline chronic gingivostomatitis stem cell therapy candidate in September 2025, a milestone that reflects a pathway toward conditional approval and a more structured interface between innovators and regulators. VetStem’s additional funding and advancement of StemStat Ortho toward FDA conditional approval further illustrate how companies are converting regulatory engagement into forward momentum. These developments are not guarantees of success, but they provide a realistic basis for scenario planning.
Beyond regulation, the report analyzes other industry dynamics that influence commercial execution. Supply chain architecture is one critical area. The cold chain requirements for certain stem cell products, including ultra-low temperature storage and transport, create logistical complexity that affects cost, reach, and clinic-level feasibility. The recent move by Gallant to establish the first ultra-low temperature cold chain in veterinary medicine for therapies requiring -80°C storage is a tangible example of how operational innovation can become a strategic differentiator. Distribution partnerships, storage equipment availability, training requirements, and clinic workflow integration all become variables that determine whether a product is theoretically promising or practically adoptable.
The report also explores practitioner adoption patterns, clinic economics, and the role of education and professional advocacy in accelerating uptake. Stem cell therapies do not sell themselves through traditional pharmaceutical channels alone; they require engagement with veterinarians who must understand indications, collection or delivery procedures, patient selection, expected outcomes, and realistic limitations. Companies that invest in veterinary education, clinical support, and evidence dissemination are better positioned to build durable demand than those that rely solely on product availability.
What the Report Delivers for Decision-Makers
This study is designed as an operational intelligence asset rather than a high-level overview. It translates market trajectory into concrete strategic inputs across multiple functional areas. The full report includes detailed analysis and structured content intended to support planning, prioritization, and risk assessment.
- A comprehensive market sizing and forecast framework that connects historical performance with the 2026–2032 outlook, enabling readers to benchmark internal projections and test growth assumptions against sector-wide trends.
- Application-level analysis that maps demand concentration, clinical maturity, and commercial implication across major therapeutic areas, helping R&D and commercial teams align pipeline focus with adoption readiness.
- Segmentation insights across animal type and geography, presented with strategic interpretation rather than raw splits alone, so that executives can evaluate where to invest, partner, or stage market entry.
- Competitive landscape profiling that examines company strategies, product formats, regulatory posture, and operational models, providing context for partnership screening, benchmarking, and positioning decisions.
- Regulatory and compliance analysis that addresses the current absence of FDA-approved veterinary cell- and tissue-based products, recent enforcement actions, and the implications of conditional approval pathways for product planning and market timing.
- Supply chain and distribution considerations, including cold chain requirements, clinic-level logistics, and the operational prerequisites for scaling off-the-shelf regenerative therapies.
- Strategic scenario inputs that support M&A evaluation, investment prioritization, and market-entry planning by identifying where concentration, differentiation, and execution risk converge.
By integrating these elements, the report enables readers to move from general market awareness to specific decision support. It is structured to help leadership answer practical questions: Which indications and animal segments offer the strongest commercial logic for a given capability set? How should a company respond to a regulatory environment that is simultaneously restrictive and progressively clarifying? What operational capabilities must be built or sourced before a therapy can be reliably delivered at scale? Where does market concentration create both partnership opportunity and competitive vulnerability? The full publication provides the structured evidence and interpretive framework needed to address these questions with confidence.
Why 2026 Is a Strategic Inflection Point
The years ahead will reward organizations that act on informed timing rather than reactive adaptation. In 2026, the market is positioned at a point where early adoption patterns are becoming clearer, regulatory engagement is intensifying, and operational infrastructure for regenerative veterinary therapies is beginning to take shape. Companies that treat these shifts as background noise risk being outpaced by competitors who are already aligning product strategy, compliance planning, and distribution design with the market’s emerging structure.
For therapy developers, the strategic priority is to connect clinical ambition with regulatory realism and commercial feasibility. For veterinary service providers and distributors, the priority is to understand which therapies are approaching credible regulatory and operational readiness, and how to integrate them into practice workflows without overcommitting to unproven or non-compliant offerings. For investors and corporate strategists, the priority is to distinguish sustainable differentiation from short-term promotional momentum, and to assess the operational and regulatory moats that will determine long-term value creation.
PW Consulting’s Animal Stem Cell Therapy Market research is built to support these decisions with depth, discipline, and a clear line of sight from market data to strategic action. The macro trajectory, segmentation logic, competitive dynamics, and regulatory context are all essential inputs, but the real value lies in how they are synthesized into an actionable view of where the market is going and what it will take to compete successfully within it.
The full report expands on every dimension previewed here, offering the detailed segmentation intelligence, competitive benchmarking, regulatory framing, and scenario-based strategic recommendations that enterprise decision-makers require. To access the complete analysis and the proprietary data that underpin it, readers are invited to visit the source page and retrieve the full market research package. In a market defined by rapid evolution and contested positioning, comprehensive intelligence is not a luxury; it is a prerequisite for confident strategy.
For detailed analysis of this topic, please visit the official page: Animal Stem Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glucagon Market to Reach $505M by 2032, Growing at 5.25% CAGR
By PW Consulting, 2026-09-07
The Glucagon Market at an Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The global glucagon market stands at a critical juncture where decades of steady therapeutic reliance are colliding with structural shifts in manufacturing capacity, regulatory clarity, and next-generation delivery formats. For pharmaceutical executives, investors, and healthcare strategists, the numbers alone tell only a fraction of the story. What matters now is the operational architecture behind those numbers: how concentrated supply chains are adapting, how dose-ready innovations are reshaping emergency care, and how macro policy signals are re-tuning metabolic supply networks that indirectly support glucagon diagnostics and rescue use. Our newly released Glucagon Market research report was designed to translate these layered dynamics into actionable intelligence for 2026 planning cycles and beyond.
Transparent PI Hard Coating Film Market
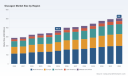
From a top-line perspective, the market has demonstrated resilient growth through the second half of the decade, with base-year valuation at USD 368.5 million in 2025 and a projected trajectory climbing toward USD 400.49 million in 2026. Over the historical window from 2020 to 2025, the segment moved from USD 288.5 million through a series of incremental expansions, reflecting both steady diabetes prevalence and gradual adoption of emergency hypoglycemia management tools. Looking forward, the forecast period from 2026 through 2032 maps a compound annual growth rate of 5.25 percent, with endpoint valuation approaching USD 505.0 million. These figures are not merely a backward-looking summary; they serve as the scaffold for a more granular examination of where value is being created, which product architectures are gaining share, and how regional demand curves are diverging under regulatory and reimbursement pressure. The full segmentation architecture, pricing sensitivity ranges, and regional volume splits are detailed within the report, because surface-level totals cannot reveal the operational logic decision-makers need.
Tunnel Jet Fans Market
What makes this edition distinct is its focus on decision readiness. Rather than simply charting historical trajectories, the research converts market momentum into a structured toolkit for capacity planning, portfolio prioritization, partnership evaluation, and risk calibration. Below is a preview of the analytical depth and operational content embedded in the full study.
Worldwide Silver Coated FEP Film Market
Competitive Architecture and the reshaped Supplier Landscape
The glucagon sector remains moderately concentrated, with the top three competitors accounting for roughly 55 percent of revenue and the top five capturing closer to 78 percent. That concentration is not a static relic; it reflects deliberate investments in manufacturing scale, differentiated formulation strategies, and territory-specific commercialization strengths. The report profiles the core participants shaping this environment, mapping their technical positioning, supply footprints, and recent strategic moves so that readers can assess not only who holds share today but which entities are structurally positioned to capture the next wave of demand.
Eli Lilly and Company, headquartered in Indianapolis, continues to anchor part of the emergency rescue segment through its recombinant rDNA-origin glucagon for injection, positioned both for severe hypoglycemia treatment and as a diagnostic aid to inhibit gastrointestinal motility. Its operational posture has recently been reinforced by a USD 3 billion commitment to U.S. injectable-drug manufacturing capacity for metabolic treatments, including glucagon signaling products, signaling a long-term view of domestic supply resilience and broader metabolic portfolio integration. Novo Nordisk A/S, based in Bagsværd, maintains its established position with GlucaGen rDNA glucagon injection for severe hypoglycemia in diabetes patients and diagnostic applications. The company's May 2026 announcement of a USD 4.1 billion expansion of its North Carolina manufacturing facility to boost injectable production lines, including glucagon, underscores a capacity build that extends well beyond incremental volume gains and into structural supply assurance.
Amphastar Pharmaceuticals, Inc., operating from Rancho Cucamonga, remains an active producer of generic glucagon for injection that is bioequivalent to established branded products, packaged within emergency kits for severe hypoglycemia treatment. This generic presence is strategically important because it defines the price-accessibility floor of the market and influences how branded players defend differentiation through convenience, stability, and device experience. Fresenius Kabi USA, LLC, based in Lake Zurich, continues as an active supplier of synthetic glucagon for injection for severe hypoglycemia treatment across pediatric and adult diabetes populations, reinforcing the hospital and clinical channels where reliability and compatibility with institutional procurement systems matter as much as product architecture.
The competitive frontier is increasingly defined by formulation and device innovation. Xeris Biopharma Holdings, Inc., from Austin, has built its identity around Gvoke, a ready-to-use stable liquid glucagon, alongside the Gvoke HypoPen autoinjector for severe hypoglycemia rescue in patients aged two and older. Its March 2025 FDA approval of a supplemental New Drug Application for Gvoke VialDx, expanding use as a diagnostic aid for glucagon, broadens the commercial and clinical footprint beyond rescue alone. More recently, the company's exclusive partnership with Beta Bionics to co-develop pump-ready liquid glucagon for dual-hormone artificial pancreas systems points toward an ecosystem where glucagon is no longer only an emergency fallback but an integrated component of automated metabolic management. Zealand Pharma A/S, headquartered in Copenhagen, advances the differentiated analog path with dasiglucagon under the ZEGALOGUE injection brand for severe hypoglycemia in diabetes patients. Its regulatory journey also illustrates the complexity that persistent innovation can encounter, including a second Complete Response Letter in October 2024 for pediatric congenital hyperinsulinism dosing, with data resubmission expectations by the end of 2025 for continued approval progress.
The strategic implication is that competitive advantage is migrating from pure volume toward delivery reliability, formulation stability, device usability, and ecosystem integration. The report's competitive section goes beyond biographical summaries to evaluate how these profiles interact with supply constraints, procurement cycles, and regulator-facing milestones. Readers who need to assess partnership opportunities, competitive response scenarios, or territory entry feasibility will find the comparative framework built for that purpose.
Market Dynamics: Supply Realities, Regulatory Signals, and the Stabilization Effect
A robust market view requires more than competitor mapping; it requires an honest accounting of the forces that can accelerate or disrupt the trajectory. One of the most consequential dynamics in the recent period has been the persistence of API and fill-finish supply constraints for synthetic glucagon products, driven in part by limited pre-filled syringe capacity and broader manufacturing capacity bottlenecks. These constraints are not abstract; they affect time-to-market, batch reliability, hospital stocking patterns, and the economics of emergency kit distribution. The report translates these constraints into commercial implications, distinguishing between temporary friction and structural capacity gaps, and identifies which product formats and supplier configurations are most exposed.
Regulatory stabilization in adjacent metabolic categories has also begun to re-tune the operating environment. The FDA's determination that the shortage of semaglutide injection products was resolved as of February 2025, followed by the resolution of tirzepatide injection shortages as of October 2024, has helped stabilize related metabolic supply chains. While these are GLP-1 receptor agonist products rather than glucagon therapies, the stabilization matters because it indirectly supports the broader diabetes management infrastructure within which glucagon diagnostics and emergency use operate. When surrounding supply networks are less volatile, procurement teams, distributors, and clinical protocols can plan with greater confidence, and that confidence tends to flow into more consistent demand realization for rescue and diagnostic glucagon applications.
At the same time, regulatory pathways for newer formulations remain iterative. The experience of dasiglucagon development demonstrates how promising innovation can still face gatekeeping milestones that alter commercialization timing, especially in pediatric and specialty indications. Conversely, the expansion of Gvoke VialDx into diagnostic use reflects how existing platforms can unlock additional use cases without requiring an entirely new product architecture. The dynamics section of the report traces these regulatory interactions carefully, not to predict every outcome, but to equip strategists with scenario-aware planning frameworks. In an environment where one Complete Response Letter or one supplemental approval can reshape a product's addressable market, organizations need more than a headline; they need a structured read on probability, timing, and downstream commercial impact.
Report Contents: What Decision-Makers Will Find Inside
The Glucagon Market research report is organized to support multiple workstreams simultaneously. It is not a single-view dashboard but a modular intelligence package that can be deployed for portfolio review, supply chain strategy, competitive benchmarking, investment screening, and market-entry evaluation. The following elements are developed in depth throughout the document.
- Historical performance reconstruction from 2020 through 2025, with base-year grounding and a clear explanation of the demand and supply factors that shaped year-over-year movement across the segment.
- A ten-year forecast window spanning 2026 to 2032, built around a CAGR of 5.25 percent and endpoint valuation near USD 505.0 million, with scenario sensitivity that accounts for formulation adoption, supply normalization, and regulatory pacing.
- Segment-level analysis by region, product type, and application, presented in a way that highlights structural drivers instead of isolated percentages. The full regional and format splits, including volume and value architecture, are provided in the report so teams can identify where relative opportunity is concentrating without relying on second-order estimates.
- A competitive landscape review that connects company profiles to recent operational events, including manufacturing expansions and partnership announcements, so readers can assess not only current share but forward capacity and ecosystem positioning.
- Market concentration metrics that show how the top three and top five competitors frame the pricing, supply, and innovation environment, with interpretation of what that concentration means for entry barriers, negotiation leverage, and differentiation requirements.
- Industry dynamics covering API and fill-finish constraints, pre-filled syringe capacity limitations, regulatory stabilization in adjacent metabolic supply chains, and the educational and clinical infrastructure trends that influence emergency hypoglycemia management.
- Regulatory and development milestone tracking, including diagnostic-use expansions, pediatric indication complexity, and the implications of approval timing on commercial readiness.
- Practical recommendations for capacity planning, portfolio sequencing, partnership targeting, and risk monitoring, tailored for teams that must convert market signal into operational decisions during 2026.
The report is built with an explicit understanding that different stakeholders consume intelligence differently. Commercial leaders may prioritize segment momentum and differentiation pathways; operations teams may focus on capacity constraints and supply normalization timing; investors may want the concentration structure and forward CAGR mapped against milestone risk; and market-access teams may need the regulatory and application context that shapes hospital and payer adoption. The content architecture accommodates those needs without forcing every reader into a single narrative.
Why This Research Matters for 2026 Decisions
The 2026 planning environment is defined by a tension that is familiar but unusually acute in this sector: demand fundamentals are strengthening, yet supply and regulatory complexity are preventing straightforward extrapolation. A 5.25 percent CAGR over the forecast period is meaningful, but the strategic value lies in understanding what drives that growth, which formats capture disproportionate value, how regional demand diverges under local reimbursement and clinical practice patterns, and which competitors are converting capital expenditure into durable supply advantage. Organizations that treat the forecast as a flat line will miss the operational inflection points that determine margin, reliability, and market access.
Three decision themes stand out. First, capacity is becoming a competitive variable, not just a cost variable. The recent manufacturing commitments from leading players reflect an understanding that injectable supply security, fill-finish throughput, and syringe/vial availability can determine who can reliably serve emergency and diagnostic demand. Second, formulation and device experience are increasingly the battleground for differentiation, especially where generic options establish a price floor and branded players must justify convenience, stability, and usability. Third, the regulatory environment is stabilizing in adjacent metabolic categories while remaining iterative for novel glucagon applications, creating a dual dynamic where some operational uncertainty is receding even as product-level approval pathways continue to require careful scenario planning.
For companies evaluating market entry, portfolio extension, or partnership strategy, the report's segmentation and competitive sections provide the necessary scaffold to test assumptions before committing resources. For incumbent players, the same material supports defensive planning: where concentration is high, where supply bottlenecks are most likely to affect service levels, and where adjacent use cases such as diagnostic aids can extend platform value. For investors, the research frames the market not as a single growth curve but as a set of overlapping trajectories with distinct risk and reward profiles tied to formulation maturity, regulatory status, and manufacturing scale.
How to Use the Intelligence: From Signal to Action
The most valuable market research does not simply describe what is happening; it helps teams decide what to do next. In practice, that means connecting market-wide trends to specific operational questions. For example, if a manufacturer is considering an expansion of emergency kit distribution, the report's segmentation logic helps identify which application and format dynamics are most relevant without relying on blunt aggregate figures. If a strategist is evaluating partnership opportunities around automated delivery or dual-hormone systems, the competitive and development event sections provide context on who is moving toward ecosystem integration and what recent partnerships suggest about the direction of travel. If a supply chain leader is mapping exposure to fill-finish constraints, the dynamics section helps distinguish intermittent friction from longer-term structural limits and highlights why pre-filled syringe capacity is a meaningful variable in product availability and commercialization pacing.
The report also supports more disciplined scenario planning. Because macro figures such as the 2025 base valuation, the 2026 projected size, and the 2032 endpoint are presented as part of a broader analytical framework, readers can stress-test their own assumptions against the underlying drivers rather than treating the forecast as a fixed outcome. That discipline matters in a market where regulatory milestones, manufacturing expansions, and formulation adoption can shift the timing and composition of growth even when the overall trajectory remains constructive.
Closing Perspective
The glucagon market is entering a period in which strategic advantage will be defined less by broad visibility and more by precise, actionable understanding. The top-line numbers establish that demand is expanding and that the segment is moving toward a mid-half-billion-dollar valuation by the end of the forecast window. But the operational story is richer: concentration is reshaping bargaining dynamics, manufacturing investments are altering supply assurance, formulation and device innovation are widening the definition of value, and regulatory signals in adjacent metabolic categories are stabilizing the broader infrastructure within which glucagon emergency and diagnostic use operates. Our Glucagon Market research report captures that full complexity in a form designed for 2026 decision-making. It offers the depth required to build confidence and the structure needed to convert insight into planning. For teams that need the regional splits, application and type architecture, concentration interpretation, and company-specific strategic context in detail, the complete report provides the comprehensive intelligence necessary to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: Glucagon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Fountain Machines Market Hits $215M in 2025, Projects 33% Growth by 2032
By PW Consulting, 2026-09-07
Navigating the Future of Beverage Dispensing: Strategic Insights from the 2026 Fountain Machines Market Report
A Critical Intelligence Brief for Decision-Makers in Foodservice and Equipment Manufacturing
The global beverage landscape is undergoing a subtle but profound transformation. For executives in the foodservice sector, equipment manufacturing, and supply chain management, understanding the trajectory of fountain machines is no longer optional—it is a strategic imperative. As we move through 2026, the inflection points in market volume, technological integration, and regulatory pressure are reshaping how convenience and customization intersect in commercial venues.
O-Tolidine Diisocyanate (TODI) Market
PW Consulting has completed an exhaustive analysis of the Fountain Machines Market, synthesizing historical performance from 2020 through 2025 with a detailed forecast extending to 2032. This introduction serves as a strategic primer, outlining the macro-economic realities and competitive pressures that define this sector. While we offer a high-level view of the landscape here, the granular data required to build precise business cases resides within the full report.
Worldwide Outdoor Camping Cookware Market
The objective of this briefing is to contextualize why immediate engagement with this data is vital for 2026 planning. The market is not merely growing; it is evolving in complexity. Leaders who rely on outdated assumptions about dispensing hardware risk capital misallocation and competitive obsolescence.
Worldwide Distributed Direct Acting Solenoid Valve Market
Macro Market Trajectory: Resilient Growth Amidst Economic Flux
The fountain machines market has demonstrated remarkable resilience over the past half-decade. Historical data indicates a steady climb in global revenue, reflecting the enduring demand for efficient beverage service solutions. From a baseline of approximately 163.15 Million USD in 2020, the market expanded consistently to reach an estimated 215.0 Million USD in 2025. This progression underscores a fundamental truth: despite supply chain disruptions and inflationary pressures during the early 2020s, the underlying demand for commercial dispensing infrastructure remained robust.
Looking forward, the forecast period from 2026 to 2032 suggests a continuation of this upward trend, albeit at a measured pace. The market is projected to reach approximately 237.44 Million USD in 2026, signaling a healthy start to the forecast window. By 2032, valuations are anticipated to approach 344.8 Million USD. This trajectory reflects a Compound Annual Growth Rate (CAGR) of roughly 2.6 percent over the forecast period.
While a 2.6 percent CAGR might appear moderate compared to high-growth technology sectors, it is significant within the context of mature hardware markets. It suggests steady replacement cycles, incremental upgrades, and adoption in emerging foodservice categories. For strategic planners, this stability offers a predictable environment for CAPEX planning, provided that regional and segment-specific nuances are accounted for. It is crucial to note that aggregate figures mask significant variations across geography and application, which are detailed fully in the proprietary sections of our analysis. However, the overarching message is clear: the total addressable market is expanding, creating opportunities for those positioned to capture value across the value chain.
Competitive Landscape: Innovation as the Primary Divisor
The fountain machines market is characterized by a blend of global beverage giants and specialized equipment manufacturers. Market concentration metrics indicate a moderately fragmented environment, with the top three players holding a combined share of approximately 24.6 percent and the top five reaching 26.2 percent. This structure implies that while major brands exert significant influence, there is ample room for specialized innovators to differentiate through technology and service models.
Several key companies are defining the trajectory of this sector. The Coca-Cola Company, headquartered in Atlanta, continues to leverage its Coca-Cola Freestyle platform, offering post-mix dispensing systems with extensive flavor combinations. Their recent moves highlight a shift toward connected innovations and data-driven service. Similarly, PepsiCo, based in Purchase, NY, maintains a strong presence with self-serve and manned dispensers tailored for QSR operators under their core brands.
On the manufacturing side, Lancer Worldwide in San Antonio, TX, remains a pivotal player with their Lancer CED and high-performance tower systems. Metro Fountain Service in Houston, TX, focuses on premium frozen and ice-based systems for institutional applications, while Cornelius Company supplies countertop IDC Pro dispensers with advanced touchscreen and carbonation features. In the Asia Pacific region, Tianwan (Shanghai) Intelligent Equipment Co., Ltd. is manufacturing soda fountain machines and ice-beverage combos for global brands, indicating the growing importance of cross-border equipment supply chains.
Coke Solutions (Coca-Cola Equipment) rounds out the landscape by providing a variety of counter electric, drop-in, and combo systems. The interplay between these entities creates a dynamic where hardware capability is increasingly tied to software integration and service reliability. Companies that fail to integrate with broader POS ecosystems or lack robust maintenance networks risk losing ground to more agile competitors.
Technology and Innovation: The Shift Toward Intelligence and Efficiency
The traditional view of fountain machines as static hardware is obsolete. The 2026 landscape is defined by intelligence, connectivity, and user experience. Recent developments underscore this shift. In May 2026, The Coca-Cola Company unveiled next-generation Freestyle dispensing equipment, including the Freestyle Equinox with a new user interface and the Freestyle Mini designed for compact venues. These launches emphasize real-time pour data, enabling custom drink creation and faster deployment cycles—sometimes as few as 90 days. Such innovations were showcased at the National Restaurant Show in Chicago, providing attendees with hands-on experience of the evolving interface between consumer and machine.
Beyond brand-specific launches, the industry is seeing a broader trend toward automation and integration. As of January 2026, various manufacturers introduced automated models with POS integration capable of handling cup, ice, and drink dispensing simultaneously. This convergence reduces labor friction and enhances throughput, addressing one of the critical pain points for high-volume venues.
Operational efficiency is another driving force. Technical service visits for soda fountain machines typically range from 150 to 300 USD per visit, making annual maintenance a critical factor for peak efficiency and cost control. Organizations that invest in systems with predictive maintenance capabilities or superior durability can significantly reduce total cost of ownership over the lifecycle of the equipment.
Regulatory and Environmental Dynamics
Compliance and sustainability are no longer peripheral concerns; they are central to market access and consumer perception. Regulatory frameworks are tightening around food safety and electrical standards. For instance, NSF and UL certifications are required for commercial fountain dispensers to meet these mandates. Manufacturers must ensure their equipment aligns with these standards to operate in regulated markets, adding a layer of complexity to product development and sourcing.
Hygiene protocols remain paramount. Regular nozzle and diffuser sanitization is mandated to comply with food safety standards, a practice that has been active since standards were established years ago and remains enforced today. Non-compliance can result in operational shutdowns or reputational damage, making equipment design that facilitates easy cleaning a competitive advantage.
Environmental efficiency is also reshaping procurement strategies. New environmental efficiency standards are driving adoption of energy-efficient dispensing systems, particularly in North America. This regulatory pressure aligns with broader corporate sustainability goals, pushing buyers toward solutions that minimize energy consumption without sacrificing performance. Furthermore, the use of syrup concentrates in fountain machines offers ancillary benefits, reducing single-use packaging waste and lowering beverage costs by up to 50 percent compared to pre-packaged alternatives.
Segmentation Nuances and Strategic Implications
While the macro growth figures provide a reliable baseline, the true strategic value of market intelligence lies in understanding the segmentation splits. The market is divided across distinct regions, types, and applications, each with unique growth drivers and barriers.
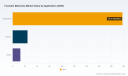
In terms of equipment type, tower fountain machines represent a significant portion of the market, reflecting their prevalence in large-scale foodservice operations where volume and visibility are key. Drop-in fountain machines constitute another substantial segment, often favored for their integration flexibility in existing countertops. Other types, including specialized countertop units, round out the mix. Understanding the specific demand elasticity for each type is crucial for manufacturers planning product line extensions and for buyers evaluating CAPEX portfolios.
Application-wise, restaurants dominate the consumption landscape, driven by the need for consistent, high-quality beverage service in high-traffic environments. Cinemas represent another key application, where fountain systems are integral to concession revenue models. Other applications, including institutional and corporate settings, offer niche but growing opportunities.
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents distinct challenges regarding supply chain logistics, regulatory environments, and consumer preferences. For example, while North America sees push for energy efficiency, Asia Pacific may offer faster volume growth linked to expanding QSR chains. Detailed regional revenue breakdowns and growth rates are essential for determining where to allocate sales resources or manufacturing capacity, but these specifics require access to the full segmentation data to avoid strategic missteps.
Why the 2026 Report is Indispensable for Decision-Makers
In an environment where margin pressure is high and technology cycles are accelerating, generic market summaries are insufficient. The PW Consulting Fountain Machines Market Report provides the depth required to execute with confidence. The report goes beyond high-level valuations to offer operational content that directly informs business strategy.
Stakeholders will find detailed profiles of key companies, analyzing their product portfolios, strategic moves, and market positions. This includes analysis of recent developments such as product launches and trade show presence, allowing readers to anticipate competitor moves. For instance, understanding the timing of new UI launches or compact venue equipment can inform procurement timing or competitive positioning.
The report also integrates industry context noise—critical operational facts that impact profitability. Insights on labor costs associated with service visits, the cost benefits of syrup concentrates, and the specifics of NSF/UL certification requirements are woven into the analysis. This ensures that financial models built from the report data reflect real-world operational constraints rather than idealistic assumptions.
Furthermore, the forecast methodology accounts for historical volatility and future drivers, providing a range of scenarios rather than a single static number. This is vital for risk management. Whether you are a manufacturer planning capacity, a distributor evaluating inventory, or a foodservice operator budgeting for 2027 renovations, the granularity of this data supports more accurate financial modeling.
Connecting Macro Trends to Micro Actions
The convergence of stable market growth, technological innovation, and regulatory pressure creates a unique window for strategic action in 2026. Firms that act now can secure advantages in supply chain positioning, technology adoption, and market share retention.
For equipment manufacturers, the emphasis on POS integration and energy efficiency suggests a roadmap for R&D investment. Aligning product development with these trends can open doors to customers seeking compliance and operational efficiency. For distributors and service providers, understanding the maintenance costs and certification requirements allows for more competitive service contracts and value-added offerings. For end-users in restaurants and cinemas, selecting the right type of fountain machine—whether tower, drop-in, or countertop—based on specific application needs can optimize both customer experience and backend costs.
However, executing these strategies requires precise data. Knowing the overall market size is helpful, but knowing which region offers the highest ROI for a new product launch, or which application segment is most sensitive to labor cost savings, requires the detailed segmentation splits and regional analysis contained in the full study. The differences between market segments can determine the success or failure of a specific initiative.
Conclusion: Accessing the Full Intelligence Picture
The Fountain Machines Market is on a steady growth path, supported by enduring demand in foodservice and a shift toward smarter, more efficient dispensing solutions. The projected revenue growth from 237.44 Million USD in 2026 to nearly 344.8 Million USD by 2032 offers a compelling backdrop for investment and strategy. Yet, the aggregate numbers only tell part of the story.
The true competitive edge lies in the details: the specific regional dynamics, the precise application splits, the granular company profiles, and the operational cost factors that influence net profitability. The macro trends highlighted here—resilience in revenue, the rise of connected equipment, and the tightening of regulatory standards—signal a market that rewards informed, data-driven decision-making.
PW Consulting's full market research report delivers this depth. It transforms broad industry observations into actionable intelligence, enabling leaders to navigate the complexities of the fountain machines ecosystem with precision. We invite you to explore the complete analysis to unlock the specific data points, forecasts, and strategic recommendations necessary to optimize your position in this evolving market. Detailed segmentation values, regional revenue specifics, and comprehensive competitor benchmarking are available within the full report to support your 2026 and beyond planning.
For detailed analysis of this topic, please visit the official page: Fountain Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wheat Germ Oil Market Hits $649M in 2025, Poised for 5.81% CAGR Growth Through 2032
By PW Consulting, 2026-09-07
Strategic Horizons in the Global Wheat Germ Oil Market: A 2026 Leadership Brief
The global wheat germ oil market stands at a critical inflection point in 2026. What began as a niche ingredient confined largely to dietary supplements and traditional cosmetics has evolved into a multi-dimensional commodity intersecting pharmaceuticals, functional foods, premium personal care, and specialized animal nutrition. As supply chains recalibrate following years of input volatility, regulatory recalibration, and shifting consumer preferences, corporate leadership requires more than surface-level forecasts. They need a structured, granular understanding of where value is being created, which segments are expanding fastest, which manufacturers are building durable competitive moats, and how external forces such as raw material pricing and trade logistics will reshape margin profiles over the next strategic cycle.
Orange Peel Scrap Grapples Market
This market study was constructed to answer those questions with precision. Drawing on comprehensive historical tracking, forward-looking modeling, and primary-level industry intelligence, the analysis maps the trajectory of wheat germ oil from 2020 through the end of the forecast horizon in 2032. The resulting dataset is engineered not merely to describe where the market has been, but to equip executives, R&D leads, procurement directors, and strategy teams with the decision architecture needed to allocate capital, refine product portfolios, negotiate supply agreements, and anticipate regulatory shifts before they become market-wide constraints.
Worldwide Silicone Pressure Sensitive Adhesives Market
The Strategic Imperative of 2026 Market Intelligence
Corporate planning in 2026 demands a clear distinction between historical momentum and forward-looking inflection. The wheat germ oil sector has already absorbed significant volatility across its value chain, from fluctuating feedstock pricing to evolving pharmaceutical and cosmetic regulatory standards. Yet the underlying demand architecture remains resilient and structurally expanding. The broader market has demonstrated consistent upward progression, with measured scale moving from approximately $562.0 million in 2020 to a projected $665.85 million in 2026. This progression is not accidental. It reflects sustained adoption across health and wellness channels, growing integration into premium cosmetic formulations, and increasing recognition of wheat germ oil’s functional profile in specialized nutrition applications.
Worldwide Organic Preservatives Market
The forward trajectory outlined in the study projects continued expansion beyond 2026, with the market size anticipated to reach $714.04 million in 2027, $787.05 million in 2028, and $824.77 million in 2029, before advancing toward $862.83 million in 2030 and $928.68 million in 2031. By 2032, the modeled market size reaches $957.0 million. These projections are derived through a composite methodology that balances historical pattern recognition with structural demand drivers, competitive capacity shifts, and adoption curves across core usage categories. Importantly, the study does not treat these figures as static endpoints. Instead, it embeds them within scenario-aware planning frameworks that allow leadership teams to assess growth sensitivity, margin exposure, and segment reallocation under changing conditions.
The implied compound annual growth rate across the forecast period is approximately 5.81%, a pace that positions wheat germ oil as a steady, structurally supported category rather than a speculative one. For strategic planners, this level of growth carries specific implications. It suggests sustained demand pull across multiple downstream industries, but it also reinforces the necessity of supply-side discipline, ingredient traceability, and formulation differentiation. Growth at this scale does not automatically translate into margin expansion unless companies understand the underlying segmentation dynamics, regional demand intensity, and competitive density that shape pricing power and customer retention.
What This Study Reveals: Operational Intelligence Across the Value Chain
A credible market study must move beyond aggregate sizing and deliver actionable intelligence that can be operationalized within product development, procurement, sales strategy, and investor communication. This research is structured to serve each of those functions. At its foundation, the report establishes a rigorous baseline for market sizing, historical performance review, and forward modeling, but its differentiation lies in the depth of its applied analysis.
Readers will find a detailed breakdown of how the market is organized across product configurations and end-use channels. The report examines liquid oil formats alongside softgel-ready variants, mapping the distinct manufacturing requirements, formulation considerations, and downstream demand profiles associated with each. It further explores how wheat germ oil is deployed across dietary supplements, cosmetics and personal care, food and beverages, and animal feed, identifying the specific value drivers, adoption barriers, and formulation sensitivities that define each channel. Because each application area carries its own regulatory expectations, consumer perception dynamics, and purchasing behavior, the study isolates where integration is most mature and where emerging demand signals suggest opportunity for expanded penetration.
Equally important is the report’s treatment of regional demand architecture. The analysis maps how demand is distributed across major geographic corridors, highlighting where consumption intensity, manufacturing presence, import-export patterns, and formulation preferences diverge. Rather than presenting oversimplified regional snapshots, the research provides the structural logic behind regional performance, enabling companies to evaluate distribution partnerships, capacity placement, market entry sequencing, and cross-border sourcing strategies with greater confidence. This is particularly relevant in an environment where trade flows, export constraints in major wheat-producing countries, and logistics bottlenecks can materially affect ingredient availability and cost structures.
Competitive Landscape and Strategic Positioning
The wheat germ oil market is shaped by a concentration of established producers and specialized manufacturers, each pursuing distinct positioning strategies across pharmaceutical, nutraceutical, cosmetic, and functional food channels. The report provides a structured competitive assessment that examines how leading companies are aligning product grade, extraction methodology, capacity, and distribution strategy to capture share in a market where differentiation is becoming increasingly important.
Among the companies analyzed, Viobin operates as a producer of cold-processed wheat germ oil sourced from North American wheat, supplied in bulk formats and prepared for softgel integration in supplements and personal care. Connoils LLC functions as a bulk supplier and manufacturer of wheat germ oil and powders for supplement and nutraceutical applications, emphasizing scale and ingredient versatility. In Europe, Gustav Heess GmbH supplies pharmaceutical-grade wheat germ oil with specifications oriented toward purity and cross-application use in food, cosmetics, and nutraceuticals. NOW Foods manufactures cold-pressed wheat germ oil in both liquid and softgel formats, positioned around allergen-conscious consumer expectations. Henry Lamotte Oils GmbH produces high-purity wheat germ oil for pharmaceutical and cosmetic applications and has pursued recent capacity expansions to support growing demand. Th. Geyer GmbH focuses on gentle extraction processes aimed at clean-label food ingredients and organic quality options, reinforcing the importance of process transparency in premium segments. Hebei Jiafeng Plant Oils Co., Ltd. operates as a refined and odorless wheat germ oil producer serving functional foods and export markets, with a product emphasis suited to industrial formulation requirements.
The competitive structure of the market reflects meaningful concentration. The study notes that the top three firms collectively account for approximately 52.0% of market share, while the top five firms extend that concentration to roughly 65.0%. This level of concentration signals a market where scale, quality certification, and supply reliability can serve as durable advantages, but it also indicates that innovation, specification differentiation, and channel specialization remain essential for challengers seeking to expand share without engaging directly in low-margin commodity competition.
Recent Developments Reshaping Market Dynamics
Market dynamics in 2026 are being actively reshaped by operational moves, product launches, regulatory signals, and supply-side constraints. These developments are not peripheral noise; they are indicators of where strategic value is migrating. The report integrates these events into a forward-looking interpretation of market trajectory, rather than treating them as isolated headlines.
One of the most telling capacity signals comes from Henry Lamotte Oils GmbH, which expanded production capacity by 30% in September 2024 to meet growing European demand for pharmaceutical-grade wheat germ oil. This expansion underscores the premiumization trend within the sector and illustrates how quality-graded supply is becoming a strategic bottleneck for manufacturers targeting pharmaceutical and high-end cosmetic applications. In parallel, Hebei Jiafeng Plant Oils Co., Ltd. launched a refined, odorless wheat germ oil tailored for food manufacturers in November 2024, with particular relevance to Asia’s expanding functional food sector. The move highlights how formulation refinement and odor management are becoming critical enablers for broader food and beverage adoption.
Innovation in extraction technology is also reshaping competitiveness. In January 2025, Herbal Biosolutions unveiled a patented extraction technology designed to significantly improve the yield and purity of wheat germ oil for use in Ayurvedic medicine. Such technological advances can alter cost structures and specification boundaries, especially where traditional medicine and nutraceutical formulation intersect. At the same time, regulatory and quality events continue to influence market confidence. In February 2025, the USA FDA posted a voluntary nationwide recall by Brassica Pharma involving ophthalmic ointments containing wheat germ oil, including Equate Stye Lubricant Eye Ointment and CVS Health Lubricant Eye Ointment. Incidents of this nature reinforce the importance of supply chain integrity, specification control, and compliance documentation, particularly for companies operating across pharmaceutical-adjacent categories.
Beyond individual company actions, broader market dynamics are being shaped by raw material pricing, regulatory notices, and trade disruptions. In 2024, wheat germ oil export and import prices ranged from approximately $5.70 to $17.84 per kg, reflecting significant variability tied to grade, origin, and supply conditions. Meanwhile, the USDA projected the 2025/26 USA all-wheat season-average farm price at USD 4.90 per bushel, down from USD 5.52 per bushel in 2024/25, a shift with implications for feedstock cost expectations and upstream pricing leverage. Regulatory attention is also intensifying in select regions; for example, India’s CDSCO issued a public notice in February 2025 related to a soft gelatin capsule formulation containing refined wheat-germ oil BP 10 mg. More broadly, major wheat-producing countries such as India, Russia, and Ukraine continue to face export restrictions and logistical bottlenecks that affect wheat germ supply availability. These forces collectively shape procurement strategies, inventory planning, and price negotiation timelines across the value chain.
Why This Research Matters for Decision-Makers in 2026
For executives and strategy teams, the central challenge is not simply whether the market is growing, but how growth is distributed, where competitive risk is concentrated, and which operational decisions will determine margin resilience in the years ahead. This study is designed to support that decision-making process at multiple levels.
First, it provides a validated baseline for strategic forecasting. Rather than relying on heuristic assumptions or fragmented secondary indicators, the report grounds projections in a continuous historical series and a forward framework that accounts for adoption dynamics, capacity shifts, and regulatory evolution. This allows companies to benchmark internal plans against a defensible market trajectory and adjust investment timing accordingly.
Second, the report enables segment-level strategic prioritization. Because growth is not uniform across applications or product formats, companies need clarity on where specification requirements, consumer expectations, and volume potential align most favorably with their capabilities. The analysis helps identify which channels are likely to reward premium positioning, which formats are gaining manufacturing traction, and where formulation or packaging innovation may unlock additional demand.
Third, the competitive assessment supports realistic positioning strategy. In a market where top players already hold meaningful share and where capacity expansion, grade certification, and extraction quality influence customer selection, new entrants and incumbent competitors alike must define their value proposition with precision. The report helps organizations understand how peer companies are competing on purity, format readiness, organic positioning, and regional specialization, enabling more informed decisions about partnership, acquisition, capacity investment, and channel focus.
Finally, the study integrates supply-side and regulatory signals into a practical risk lens. With raw material pricing variability, evolving regulatory notices, and trade logistics constraints all capable of affecting ingredient availability and cost, procurement and supply chain leaders require early-warning context rather than retrospective data. This research surfaces those factors in a structured way so that companies can stress-test sourcing plans, assess alternative supply routes, and align product claims with compliance realities.
How to Use This Report for Planning and Execution
The research is organized to support multiple internal workflows. Product and formulation teams can use the segmentation and application analysis to evaluate where wheat germ oil can be integrated more effectively into existing portfolios or where new variants may address unmet specification needs. Procurement and supply chain teams can leverage the pricing context, regional demand patterns, and competitive capacity developments to refine sourcing strategies and anticipate timing constraints. Commercial leaders can use the competitive landscape and demand distribution analysis to sharpen positioning, prioritize geographic or channel expansion, and align marketing claims with category expectations. Executive teams can rely on the consolidated market sizing, growth trajectory, and concentration analysis to inform capital allocation, scenario planning, and investor communication.
Because the study balances breadth with depth, it can serve both high-level strategic review and more detailed operational planning. It is structured to help organizations distinguish between near-term tactical issues and longer-term structural shifts, ensuring that decisions are anchored in evidence rather than short-term market noise.
Closing Perspective: The Path Ahead
The wheat germ oil market in 2026 is not defined by a single driver, but by the interaction of demand expansion, competitive specialization, regulatory evolution, and supply-side variability. That complexity is precisely why leadership teams require a comprehensive, structured, and forward-looking research foundation. The market’s progression from a measured 2020 base toward a projected 2032 scale reflects durable interest in wheat germ oil’s functional and formulation value, but capturing the full strategic benefit of that growth will depend on how well companies understand the segment dynamics, competitive relationships, and external pressures that shape commercial outcomes.
This study offers that understanding in a form designed for action. It provides the market architecture, competitive intelligence, and contextual analysis needed to make informed decisions across product, supply, commercial, and governance functions. For organizations seeking to move beyond general market awareness into precise strategic planning, the full report delivers the deeper segmentation data, regional breakdowns, application-level analysis, and competitive benchmarking required to build a confident path forward. The complete dataset and detailed strategic assessment can be accessed through the full market research page, where the full scope of the analysis, underlying structure, and actionable detail is presented for review and planning use.
For detailed analysis of this topic, please visit the official page: Wheat Germ Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railway Equipment Market Set for 6.45% CAGR, Reaching $535.08 Million by 2032
By PW Consulting, 2026-09-07
Railway Equipment Market Outlook 2026: Strategic Intelligence for Executive Decision-Making
The global railway equipment market stands at a critical inflection point in 2026. As infrastructure spending accelerates across continents and digital transformation reshapes operational paradigms, industry leaders require more than superficial trend analysis—they need precise, actionable intelligence to navigate capital allocation, regulatory compliance, and competitive positioning. This comprehensive market research publication delivers the depth required to make informed strategic decisions throughout the forecast period extending to 2032.
Worldwide Housekeeping Trolley Market
The railway sector has demonstrated remarkable resilience and growth momentum over the past half-decade. From a base of 225.0 million USD in 2020, the market has progressed through consistent expansion to reach an estimated 345.46 million USD by 2025. This trajectory reflects sustained investment in modernization programs, passenger transport demand recovery, and freight logistics optimization initiatives worldwide. Looking ahead, the market is projected to climb to 378.25 million USD in 2026, continuing its ascent toward 535.08 million USD by 2032. These figures represent more than incremental growth—they signal a structural transformation in how rail infrastructure and equipment are designed, manufactured, and integrated into broader transportation ecosystems.
Elevating Parking Robot Market
Understanding the compound annual growth rate of 6.45 percent across the forecast horizon is essential for executives evaluating long-term investment theses. This growth rate places railway equipment in a favorable position relative to broader industrial equipment categories, driven by unique tailwinds including decarbonization mandates, urbanization pressures, and government stimulus programs targeting sustainable mobility. However, capturing value in this expanding market requires nuanced understanding of segment dynamics, regional variations, and the competitive strategies employed by leading equipment manufacturers.
Worldwide Manual Tool Changer Market
Market Structure and Segment Dynamics
The railway equipment landscape encompasses multiple interconnected segments, each presenting distinct opportunities and challenges for equipment suppliers, operators, and investors. Rolling stock dominates the equipment mix, reflecting the capital-intensive nature of train manufacturing and fleet renewal programs globally. The track infrastructure segment follows, driven by network expansion, maintenance rehabilitation cycles, and safety enhancement projects. Signaling systems, while representing a smaller portion of the overall equipment expenditure, carry disproportionate strategic importance due to their role in capacity optimization, safety certification, and digital rail transformation initiatives.
Application-wise, the market divides between passenger transport and freight transport, both representing substantial and roughly comparable demand centers. This balance underscores the dual importance of commuter and intercity rail modernization alongside freight logistics efficiency improvements. Operators in both domains face common pressures: aging asset bases requiring replacement or upgrade, workforce transitions as experienced personnel retire, and the imperative to integrate digital solutions that improve asset utilization and maintenance predictability.
Regional dynamics vary considerably, with mature markets in Europe and North America focusing on replacement cycles and performance upgrades, while Asia Pacific markets exhibit stronger expansion characteristics driven by new network construction and high-speed rail deployment. Latin America and the Middle East and Africa regions present emerging opportunities tied to development finance initiatives and infrastructure modernization programs. Each regional context carries specific regulatory frameworks, procurement practices, and competitive conditions that demand localized understanding rather than generalized assumptions.
Competitive Landscape: Key Players and Strategic Positioning
The railway equipment market exhibits significant concentration, with the top three firms commanding approximately 65 percent of market share and the top five collectively representing 82.5 percent. This oligopolistic structure reflects the high barriers to entry inherent in railway equipment manufacturing: stringent certification requirements, long qualification cycles, complex supply chain integration, and the need for sustained service and maintenance relationships spanning decades. For new entrants, partnership strategies and niche specialization represent more viable pathways than broad-based market entry attempts.
Several organizations define the competitive frontier through their product portfolios, geographic reach, and strategic moves. Wabtec Corporation, headquartered in Pittsburgh, Pennsylvania, operates as a leading global supplier spanning pantographs, electronic braking systems, couplers, and digital solutions for both freight and passenger rail applications. The company has pursued an aggressive strategic agenda in early 2026, including the completed acquisition of Dellner Couplers, a Sweden-based specialist in safety-critical train connection systems for passenger rolling stock. This acquisition strengthens Wabtec's coupling technology portfolio and expands its European manufacturing footprint. Simultaneously, the company secured multiple contracts to supply over 680 pantographs for six major commuter rail and metro projects in India, demonstrating execution capability in high-volume emerging market deployments. In a significant development for freight interoperability, Wabtec collaborated with more than twenty industry partners including Siemens, Alstom, and ÖBB on joint testing of Digital Automatic Coupler technologies, validating interoperable communication protocols. The company also signed a 670 million USD deal with CSX for 100 new Evolution Series locomotives, 50 modernized units, and integrated digital solutions, reinforcing its freight locomotive market position.
Alstom SA, based in Paris, France, stands as a major provider of signaling systems, rolling stock equipment, and integrated railway solutions serving global rail operators. The company's strategic focus in 2026 includes accelerating digital rail transformation in Queensland, Australia, where its first mainline ETCS contract supports the broader "The Wave" program aligned with Brisbane 2032 Olympics infrastructure preparation. Additionally, Alstom's TGV-M high-speed train received marketing authorization from the European Union Agency for Railways, advancing the product toward passenger service deployment. These developments illustrate the company's dual emphasis on signaling technology leadership and rolling stock innovation for premium high-speed corridors.
Hitachi Rail, headquartered in Tokyo, Japan, supplies signaling, rolling stock, and smart rail solutions including ETCS systems and high-speed train components. The organization combines engineering heritage with digital capability, positioning itself across both traditional equipment categories and next-generation connected rail solutions. Siemens Mobility, based in Munich, Germany, maintains a key position in railway signaling, train control, and high-speed rail equipment, notably advancing ETCS Level 2 systems and Velaro family trains. The company's June 2026 strategic partnership with VinSpeed for comprehensive high-speed rail development in Vietnam, encompassing Velaro Novo train supply, ETCS Level 2 signaling, and electrification systems, signals continued expansion of European technology standards into Southeast Asian markets.
CRRC Corporation Limited, headquartered in Beijing, China, operates as a global manufacturer of locomotives, rolling stock, and railway equipment with particular focus on high-speed and mainline systems. The company benefits from China's extensive domestic rail construction program while pursuing international project participation. Progress Rail, based in Albertville, Alabama, provides signaling systems, locomotives, and rail infrastructure equipment tailored to North American freight and passenger operators, representing a strong regional presence with specific market knowledge. CAF, Construcciones y Auxiliar de Ferrocarriles, headquartered in Beasain, Spain, manufactures rolling stock and railway equipment including trains and maintenance systems, maintaining a strong European manufacturing base with international project execution capability.
Regulatory Dynamics and Technical Standards Evolution
The regulatory environment for railway equipment is undergoing significant updates that will influence product design, certification timelines, and competitive positioning throughout the forecast period. EN 50155:2026, which became valid on 18 May 2026, defines updated requirements for the design, manufacturing, documentation, testing, and integration of all electronic equipment installed on-board rolling stock. This standard applies comprehensively to control, regulation, protection, diagnostic, and energy supply systems, representing a substantial revision from the preceding EN 50155:2021 edition.
The updated standard covers environmental and electrical operating conditions for railway electronic equipment, with specific requirements encompassing temperature tolerance, humidity resistance, shock and vibration resilience, operating voltage parameters, and electromagnetic compatibility testing. Critically, EN 50155:2026 applies to any electronic equipment for rolling stock subsystems, including external doors and wheel slide protection mechanisms. For equipment manufacturers and system integrators, this means that product development cycles must account for revised testing protocols and documentation requirements. Suppliers who proactively adapt their engineering processes and quality management systems will secure competitive advantages in qualification speed, while those with legacy designs may face extended re-certification timelines and potential market access delays.
Beyond product-level standards, the broader regulatory landscape continues to evolve around safety certification, interoperability mandates, and environmental compliance. Operators and equipment procurement teams must navigate these requirements while balancing cost constraints and delivery schedules. The interplay between national regulatory bodies, European standardization organizations like CENELEC, and industry consortiums creates a complex compliance environment that demands specialized expertise. Market participants who invest in regulatory intelligence and maintain active engagement with standards development processes will be better positioned to anticipate changes and manage transition risks.
Strategic Implications for 2026 Decision-Makers
The convergence of market growth, competitive concentration, technological transformation, and regulatory evolution creates a decision environment where informed strategic choices carry significant long-term consequences. For equipment manufacturers, the question is not merely whether to participate in a growing market, but how to position product portfolios, geographic presence, and partnership architectures to capture disproportionate value. Key considerations include:
- Portfolio alignment with high-growth segments: Understanding which equipment categories and application domains are expanding most rapidly enables targeted R&D investment and manufacturing capacity allocation decisions.
- Geographic strategy calibration: Regional market characteristics vary substantially, requiring nuanced approaches to pricing, localization, after-sales service, and partnership models rather than uniform global strategies.
- Certification and standards readiness: Proactive adaptation to evolving technical standards like EN 50155:2026 protects market access and creates differentiation against competitors who react more slowly to regulatory change.
- M&A and partnership evaluation: The acquisition activity visible in early 2026, particularly in specialized components and digital technology domains, signals ongoing industry consolidation. Organizations must continually assess whether organic development or external acquisition offers faster path to strategic objectives.
- Digital integration capability: As signaling, train control, and operational data systems become increasingly integral to equipment value propositions, manufacturers need to demonstrate integration expertise alongside traditional hardware competencies.
For rail operators, infrastructure owners, and public sector procurement entities, the strategic calculus centers on total cost of ownership, reliability, interoperability, and alignment with long-term network plans. Equipment selection decisions made in 2026 will influence operational performance, maintenance burdens, and upgrade pathways for decades. Access to comprehensive market intelligence that illuminates supplier capabilities, technology trajectories, and pricing dynamics supports more effective procurement and partnership strategies.
For investors and financial stakeholders, understanding market concentration patterns, growth segmentation, and competitive moats informs valuation frameworks and risk assessments. The high market concentration levels suggest that established players possess durable competitive advantages, but targeted analysis of segment-level dynamics, regional exposure, and technology transition risks remains essential for accurate investment judgment.
What This Market Research Publication Delivers
This comprehensive Railway Equipment Market research report provides the analytical depth and practical content required to support confident strategic decisions through 2032 and beyond. The publication encompasses detailed segment analysis across equipment types, application domains, and geographic regions, with quantitative projections that enable scenario planning and resource allocation modeling. Readers will find:
- Historical market performance analysis covering the 2020 to 2025 period, establishing baseline trajectories and identifying inflection points that inform forward-looking assumptions.
- Forecast projections through 2032 with granular segment-level data that supports detailed business planning, capacity investment analysis, and competitive benchmarking.
- Comprehensive competitive profiling of leading market participants, including organizational capabilities, strategic positioning, recent developments, and competitive strengths and vulnerabilities.
- Regulatory and standards landscape assessment, translating technical requirements into business implications for product development, certification, and market access strategies.
- Industry dynamics analysis identifying key drivers, restraints, opportunities, and challenges that shape market evolution and create differential outcomes across participants.
- Strategic recommendation frameworks that translate analytical findings into actionable guidance for various stakeholder types, from equipment manufacturers to operators to investors.
The report draws on rigorous research methodologies, primary source analysis, and expert interpretation to deliver insights that go beyond readily available summary statistics. While public information may provide headline market size figures or broad trend descriptions, the complete publication offers the structured detail, segment breakdowns, company-level intelligence, and forward-looking analysis that executives need to move from awareness to action.
Access the Complete Strategic Intelligence
The railway equipment market presents substantial opportunity for organizations positioned to navigate its complexities effectively. Realizing this opportunity requires more than general market awareness—it demands detailed segment intelligence, competitive benchmarks, regulatory foresight, and strategic frameworks tailored to specific decision contexts. This research publication is designed to provide that comprehensive foundation.
Readers seeking the full depth of analysis, complete segment data, detailed company profiles, and actionable strategic recommendations are encouraged to access the complete report through our official publication channel. The full version delivers the quantitative detail, methodological transparency, and interpretive depth necessary to support confident decision-making across the 2026 to 2032 forecast horizon and beyond.
For detailed analysis of this topic, please visit the official page: Railway Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Dichromate Market to Reach $2,176 Million by 2032 at 5.2% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence in a Regulated Chromium Market: Navigating the Sodium Dichromate Landscape Through 2032
The global sodium dichromate market stands at a critical inflection point where industrial demand, supply chain reconfiguration, and intensifying regulatory scrutiny intersect. For senior executives, procurement leaders, and strategic planners, understanding the trajectory of this specialty chemical is no longer optional—it is a prerequisite for capital allocation, sourcing strategy, and long-term risk mitigation. PW Consulting’s latest market research delivers a structured, forward-looking assessment designed to translate complex market signals into actionable corporate strategy.
Fiber Glass PLY Yarn Market
This report is built for decision-makers who need more than historical snapshots. It maps the evolution of a market that has demonstrated consistent expansion while simultaneously confronting structural pressures from environmental legislation, feedstock volatility, and geopolitical supply chain shifts. By aligning quantitative forecasting with qualitative competitive and regulatory analysis, the study provides a comprehensive framework for evaluating market entry, capacity planning, vendor qualification, and compliance readiness through the end of the decade.
Worldwide Natural Piperonal Market
Market Trajectory and Structural Growth Dynamics
The sodium dichromate sector has followed a measured but uninterrupted growth path over the past half-decade, reflecting its entrenched role in metal treatment, surface finishing, pigment manufacturing, and specialized industrial processes. Historical revenue progression from 2020 through 2025 illustrates a steady upward curve, with market valuation expanding from approximately 1,217.0 million USD to 1,524.0 million USD. This five-year progression underscores the compound’s continued relevance despite mounting regulatory attention and the broader industry push toward alternative chemistries.
Casual Sneakers Market
Looking ahead, the forecast window extends through 2032 and captures a market environment shaped by both incremental demand expansion and periodic supply-side recalibration. The projected compound annual growth rate of 5.2 percent frames a landscape where volume growth is moderated by compliance costs, regional regulatory divergence, and shifting application priorities. Forecasts indicate the market will cross the 1,562.75 million USD threshold in 2026, followed by continued expansion toward the 1,730.26 million USD range by 2027 and further upward movement in subsequent years. The trajectory is not uniformly linear; it reflects the interplay of capacity adjustments, regional demand redistribution, and the gradual impact of authorization requirements on legacy usage patterns.
Importantly, the growth narrative is not simply a function of end-user consumption. It is increasingly influenced by feedstock availability, manufacturing efficiency, logistics constraints, and the strategic response of producers to regulatory timelines. Chromite ore remains the foundational input for sodium dichromate production, and any disruption in mining output, export policy, or processing capacity reverberates through pricing, availability, and regional supply balance. This linkage between raw material markets and downstream chemical demand is a central theme woven throughout the analysis.
Regulatory Pressures and the Changing Compliance Landscape
One of the most consequential forces reshaping the sodium dichromate market is the evolving regulatory framework around hexavalent chromium substances. The European Chemicals Agency has signaled its intent to propose restrictions under REACH targeting hexavalent chromium compounds, including sodium dichromate. This development, announced in April 2025, introduces a new layer of strategic uncertainty for manufacturers and downstream users operating in or supplying European markets.
Beyond the proposed restriction, sodium dichromate is already subject to authorization requirements under REACH Annex XIV, and it appears on the EU candidate list of substances of very high concern. These designations do not automatically eliminate usage, but they impose authorization burdens, supply-chain documentation requirements, and strategic planning obligations that affect procurement cycles, product design, and regional market access. For companies with European exposure, the compliance timeline becomes a strategic variable rather than a distant administrative concern.
Simultaneously, the broader Chromium VI restriction proposal continues to shape industry expectations. The practical effect is a market in which regulatory divergence between regions creates uneven competitive conditions. Markets with stricter authorization frameworks may experience slower volume growth or accelerated substitution, while regions with more permissive regulatory environments may see continued reliance on established chromium-based processes. Understanding where and how these regulatory pressures will concentrate is essential for formulating sourcing strategies, evaluating alternative chemistries, and anticipating shifts in regional demand patterns.
Competitive Landscape and Strategic Positioning
The sodium dichromate market is characterized by a moderately concentrated supplier base, with a limited number of established producers commanding meaningful share. The report’s competitive analysis highlights a group of companies whose manufacturing footprints, product specifications, and distribution strategies shape the overall market architecture. Market concentration metrics indicate that the top three players account for approximately 33.0 percent of revenue, while the top five represent roughly 35.2 percent. This level of concentration suggests a market in which scale, technical capability, and regulatory compliance infrastructure provide meaningful competitive advantages, yet it also leaves room for regional specialists and integrated producers to compete on efficiency, purity standards, and supply reliability.
Vishnu Chemicals Limited, headquartered in Hyderabad, India, operates as a primary manufacturer of sodium dichromate with a strong emphasis on high-purity grades and versatile application support. Its product portfolio spans metal passivation, pigments, electroplating, wood preservation, and organic synthesis, with packaging configurations designed to serve both standard industrial buyers and larger volume users. The company’s expansion of production capacity reflects a broader trend among key suppliers to reinforce supply resilience and strengthen global availability.
Nippon Chemical Industrial Co., Ltd., based in Japan, represents the high-purity, quality-assurance segment of the market. Its focus on metal treatment, aerospace applications, and specialized chemical uses positions it within supply chains where specification reliability and consistent quality are critical. The company’s Asian distribution network further illustrates how regional reach and technical reputation interplay in competitive positioning.
In China, Hubei Zhenhua Chemical Co., Ltd. and Yinhe Group operate as active participants in the regional supply landscape. Hubei Zhenhua’s profile reflects a supplier emphasis on chromium compounds with competitive positioning in Asian markets, while Yinhe Group approaches sodium dichromate as a core chromium product within a broader industrial chemistry framework. Both entities underscore the importance of modern production technology, export-oriented supply strategies, and regional cost dynamics in shaping competitive outcomes.
Soda Sanayii A.S., located in Turkey, adds another dimension to the competitive map by emphasizing production efficiency and product purity for domestic and regional markets. Its presence highlights how geographically positioned manufacturers can serve as important supply nodes for nearby industrial demand centers, particularly where logistics and regional trade flows influence procurement decisions.
Together, these companies exemplify the strategic diversity within the market: integrated producers, purity-focused specialists, regional supply providers, and capacity-expanding manufacturers. The report evaluates these competitive dynamics not merely as a roster of players, but as a system of interdependencies, capacity constraints, and differentiation levers that influence pricing behavior, supply security, and long-term market structure.
Application Demand and Regional Demand Architecture
Sodium dichromate demand is distributed across a range of industrial applications, each with distinct growth drivers, regulatory exposure, and substitution risk. Metal finishing remains a substantial demand center, supported by continued need for corrosion resistance, surface treatment, and passivation processes across manufacturing sectors. Pigments represent another significant application segment, where the compound’s chemical properties continue to support specific coloration and industrial coating requirements. Wood preservation and leather tanning also contribute to base demand, though these segments are increasingly influenced by environmental standards, consumer-facing product requirements, and regional regulatory posture.
Beyond these established uses, a broader set of industrial applications sustains additional demand. The cumulative effect is a demand structure that is diversified enough to provide resilience, yet sensitive enough to regulatory and substitution dynamics that no single application can be treated in isolation. The analysis frames these application segments as interdependent components of a demand ecosystem, where changes in one area—whether from compliance deadlines, process redesign, or material substitution—can influence overall procurement patterns and supplier planning.
On the regional side, the market exhibits a clear geographic hierarchy in which Asia Pacific carries substantial demand weight, North America and Europe represent mature, regulation-intensive markets, and Latin America and the Middle East and Africa function as smaller but strategically relevant demand centers. This regional distribution matters because it shapes where regulatory momentum will have the greatest impact, where capacity expansion is most likely to be absorbed, and where supply chain diversification strategies will yield the highest strategic value. The report examines these regional dynamics as part of a wider framework that connects demand geography with supplier location, logistics feasibility, and compliance exposure.
Strategic Value of the Report for 2026 Decision-Making
The 2026 decision environment demands more than retrospective market data. It requires a forward-looking synthesis that connects market size, growth trajectory, competitive structure, regulatory timelines, and application demand into a coherent strategic narrative. PW Consulting’s Sodium Dichromate Market research is designed to serve that need by offering a structured, evidence-based foundation for planning across multiple corporate functions.
For procurement and supply chain leaders, the report provides context for evaluating supplier reliability, regional sourcing trade-offs, and the implications of regulatory divergence on contract structuring and inventory strategy. For manufacturing and operations executives, it offers insight into demand stability, capacity trends, and the potential impact of compliance obligations on input availability and cost planning. For strategy and corporate development teams, it frames the market in terms of competitive positioning, regional opportunity, and the strategic implications of a moderately concentrated supplier base.
The research also supports scenario-aware planning. Because the forecast period spans 2026 through 2032, it allows decision-makers to assess not only near-term conditions but also the medium-term evolution of market size, demand redistribution, and regulatory pressure. This temporal breadth is particularly valuable in a market where authorization requirements, restriction proposals, and feedstock dynamics can alter the operating environment over multiple planning cycles.
Beyond macro-level insight, the report translates analysis into operational relevance. It details the components needed to evaluate market participation, supplier qualification, application-level demand behavior, and regulatory exposure in a manner that can be integrated into internal strategy workflows. The objective is not simply to describe the market, but to equip organizations with the analytical structure required to make informed decisions under uncertainty.
Why This Research Matters Now
The sodium dichromate market is entering a phase in which growth, regulation, and competition will interact more intensely than in previous years. The expansion trajectory projected through 2032 suggests continued commercial relevance, but it also coincides with an environment in which regulatory scrutiny on hexavalent chromium substances is becoming more structured and more consequential. In such a setting, strategic advantage will belong to organizations that can anticipate change, interpret its implications, and adjust sourcing, production, and planning accordingly.
This report is intended to serve as a practical intelligence asset for that purpose. It consolidates market sizing, growth expectations, competitive dynamics, regulatory context, and demand architecture into a single analytical framework. By doing so, it helps decision-makers move from generalized awareness to targeted action—whether that means reassessing supplier portfolios, preparing for compliance timelines, evaluating regional demand shifts, or refining long-range capital and capacity strategies.
The complete study provides the depth, segmentation context, and structured analysis required for detailed planning. It is designed for leaders who need to understand not only where the market is going, but how to respond with discipline and strategic clarity. For organizations navigating a market defined by both opportunity and regulatory complexity, this research offers the foundation needed to make better-informed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sodium Dichromate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ring Laser Gyroscope Market to Hit $10.9B by 2032, Driven by 9.2% CAGR
By PW Consulting, 2026-09-07
Navigating the Inertial Horizon: Strategic Imperatives in the Ring Laser Gyroscope Market (2026-2032)
The global landscape for inertial navigation is undergoing a profound transformation. As platform autonomy, precision guidance, and resilient navigation architectures become non-negotiable across aerospace, defense, and commercial transport, Ring Laser Gyroscopes (RLG) continue to occupy a critical position in the high-stability inertial sensor ecosystem. Our latest market research, spanning historical analysis from 2020 through 2025 and a forward-looking forecast window extending to 2032, maps the trajectories, structural shifts, and competitive fault lines that will define this market in the years ahead.
Deionized Water Heating System for semiconductor Market
For executives, investors, and engineering leaders making 2026 portfolio, procurement, and capacity decisions, this report is not a retrospective overview. It is an operational intelligence framework designed to convert macroeconomic momentum into actionable strategy. The market has already demonstrated significant expansion, with global revenue climbing from 3.15 billion USD in 2020 to 5.29 billion USD in 2025. This progression reflects more than cyclical demand recovery. It signals a structural re-rating of RLG technology as platforms demand lower drift, higher reliability, and tighter integration with software-defined navigation stacks.
Axial Needle Bearings Market
The forward trajectory reinforces this inflection. The forecast period through 2032 projects sustained growth at a Compound Annual Growth Rate (CAGR) of 9.2 percent, advancing the overall market from 5.73 billion USD in 2026 to 10.9 billion USD by 2032. These figures are not abstract indicators. They represent the cumulative effect of technology maturation, platform modernization, and strategic procurement patterns that will shape supply-demand dynamics for the next several years. Crucially, the real decision-making value lies beneath these top-line numbers. The research disaggregates demand drivers, regional deployment patterns, application-specific adoption curves, and technology segmentation pathways so that leadership teams can align capital allocation with the segments where competitive advantage will be forged.
Phosphated Coatings Market
The Strategic Value of Preemptive Market Intelligence
A market growing at a high-single-digit rate over a seven-year horizon does not reward reactive planning. The 9.2 percent CAGR projected from 2026 through 2032 is best understood as the output of multiple reinforcing forces: the continued prioritization of autonomous and semi-autonomous navigation, the modernization of legacy airframes and naval platforms, and the expanding use of precision inertial sensors in environments where GPS-denied or degraded navigation is a mission-critical requirement. Each of these forces creates a distinct set of procurement, engineering, and partnership decisions that must be sequenced correctly.
The report’s core value proposition is timing. A leadership team evaluating RLG-related investments in 2026 must understand not just where the market size is headed, but how the growth composition is shifting beneath it. Revenue progression from 5.73 billion USD in 2026 to 6.36 billion USD in 2027, 6.97 billion USD in 2028, 7.8 billion USD in 2029, 8.81 billion USD in 2030, 9.93 billion USD in 2031, and 10.9 billion USD in 2032 reflects an acceleration pattern that will reward early positioning in the right applications, the right regional ecosystems, and the right supplier relationships. This is where top-line forecasts become decision utility: they frame the window in which manufacturing scale, qualification cycles, and integration partnerships must be secured.
Equally important, the research situates the RLG market within broader inertial navigation competition. While newer sensor modalities continue to advance, RLG remains preferred for applications demanding long-term stability, proven ruggedization, and mature calibration methodologies. Understanding where RLG maintains structural advantage—and where substitution risk is real—is essential for product roadmaps, supplier qualification, and M&A screening. The report does not treat the market as a monolith. It breaks down the decision logic that determines which segment participants capture margin, which customers accelerate adoption, and which technology splits will define the next phase of the category.
Report Architecture and Actionable Contents
The research is structured to move from strategic framing to operational detail without forcing readers to assemble insights from disconnected datasets. The architecture is designed for cross-functional use, giving strategy, engineering, procurement, and investor-relations teams a shared evidence base.
- Historical and Forecast Series: A continuous revenue sequence from 2020 through 2032 establishes the baseline for demand growth and enables scenario testing around procurement cycles, platform delivery schedules, and inventory strategies.
- Segmentation Framework: The analysis separates the market by region, by type, and by application so that decision-makers can evaluate where concentration risk exists, where growth momentum is strongest, and where supply chain diversification will matter most. Rather than presenting isolated percentages, the report links segment structure to procurement logic, qualification requirements, and deployment cadence.
- Technology and Product Type Analysis: Differences in performance, packaging, and integration complexity across RLG configurations are examined in relation to platform requirements. This allows engineering and sourcing teams to assess trade-offs between form factor, stability, and manufacturing readiness.
- Application Pathways: The report evaluates how RLG demand materializes across end-use domains, including aerospace and defense, marine and naval systems, automotive programs, and adjacent application areas. Each pathway is discussed in terms of qualification intensity, volume variability, and the strategic implications of demand timing.
- Competitive Positioning and Supplier Capability Mapping: Vendor profiles are assessed not only by scale, but by component specialization, manufacturing discipline, optical performance, and regulatory compliance posture. This gives buyers and partners a practical reference for evaluating supply resilience and technology fit.
- Regulatory, Standards, and Supply Chain Context: The analysis captures the compliance environment and manufacturing certification frameworks that shape sourcing options, export-control considerations, and qualification lead times.
This structure is intentionally practical. For example, when evaluating type segmentation, the report does not simply rank configurations. It examines how single-axis and three-axis architectures map to distinct platform needs, integration requirements, and performance thresholds. When analyzing regional dynamics, the emphasis is on where demand ecosystems, supplier footprints, and program pipelines intersect, creating both opportunity and concentration exposure. The goal is to give leaders a decision map, not a static snapshot.
Competitive Landscape and the Geometry of Supplier Advantage
Market concentration remains a defining feature of the RLG ecosystem. The report assesses a competitive structure in which the top three firms collectively account for approximately 45.0 percent of market revenue, while the top five firms reach roughly 55.0 percent. This level of concentration has direct implications for procurement strategy, pricing leverage, and supply continuity. In a market where qualification cycles are long and platform integration is demanding, concentration can translate into both reliability and dependency. Understanding which suppliers control which capabilities is therefore central to risk management.
The research maps this landscape through the lens of differentiated supplier capabilities rather than generic company descriptions. Several participants stand out for specialized contributions to the RLG value chain:
- G&H Products operates from California, United States, and designs and manufactures RLG frames and optical components by hand, supplying complete RLG component packages. The firm’s manufacturing discipline is reinforced by ISO9001 and AS9100D: 2009 Rev.C certification, and its operations comply with ITAR legislation and are registered with the US government. For buyers, this profile signals a supplier that can provide integrated component-level support while meeting the regulatory and quality expectations associated with defense-adjacent and high-reliability programs. The company also supplies the entire RLG component package, including Zerodur frames and precision mirrors, making it relevant for customers seeking consolidated sourcing for critical subcomponents.
- Excelitas Technologies Corp. is based in Pittsburgh, Pennsylvania, United States, and supplies precision mirrors, optics, and optical components optimized for RLG applications. Its components are engineered for micro-roughness below 0.5 Å and low scattering, with reported cavity performance reaching finesse of 200,000, scattering loss under 5 ppm, and micro-roughness below 0.5 Å. For RLG programs where cavity optical quality directly affects performance, this level of component specialization represents a material sourcing consideration.
- Micro Magic , headquartered in the United States, develops and produces complete RLG-based inertial navigation systems (INS), including high-precision models for defense and aerospace platforms. Its vertically oriented positioning—from RLG technology to system-level INS integration—makes it especially relevant for customers seeking shortened integration paths and platform-ready solutions rather than discrete component procurement.
Recent developments illustrate how these capability profiles translate into market momentum. In November 2025, Micro Magic launched new G-R90, G-R70, and G-R50 solid-state RLG models targeted at high-precision INS for defense and unmanned platforms. This kind of product cycle matters because it shows where performance, form factor, and platform applicability are being pushed simultaneously. The report situates such launches within broader adoption dynamics, helping readers interpret whether new introductions expand the addressable market, intensify competition in specific sub-segments, or shift procurement timing for adjacent programs.
Beyond individual profiles, the competitive analysis addresses the strategic question every buyer and investor must answer: where does differentiation actually come from in this market? In RLG, differentiation is rarely only about headline specifications. It is the combination of optical quality, mechanical stability, manufacturing repeatability, certification posture, integration readiness, and the ability to support customers through qualification and fielding. The report evaluates these dimensions across the leading firms, giving readers a structured way to compare suppliers for risk, performance, and long-term fit.
Market Dynamics Shaping the 2026 Decision Environment
The RLG market does not evolve in a vacuum. It is shaped by the interplay of technology readiness, program pipelines, regulatory expectations, and supply chain design. The research integrates these forces into a forward-looking dynamics framework that supports 2026 planning in several concrete ways.
First, the convergence of platform autonomy and navigation resilience continues to raise the strategic value of inertial sensors. As platforms increasingly operate in contested, contested-degraded, or GPS-denied environments, the demand for stable, reliable gyroscopic navigation intensifies. RLG’s established reputation for long-term stability positions it as a core element in architectures that cannot tolerate high drift or frequent recalibration. The report evaluates where this dynamic accelerates adoption and where competing sensor strategies may alter procurement preferences.
Second, supply chain geometry is becoming a more decisive competitive factor. The increasing complexity of qualifying high-reliability inertial subsystems means that buyers must assess not only component performance, but the stability and traceability of the supplier base. Suppliers with integrated manufacturing footprints, strong quality certifications, and regulatory compliance structures occupy a distinct position in this environment. For example, the combination of hand-built frame and optical component manufacturing, ISO and AS certification, and ITAR registration can reduce friction in defense- and aerospace-related procurement cycles. Similarly, vendors capable of delivering complete component packages or finished INS configurations alter the cost and time dynamics of system integration.
Third, optical and mechanical precision remain central to performance differentiation. RLG performance is tightly coupled to cavity quality, mirror surface characteristics, and the repeatability of critical assemblies. The report examines how these technical parameters influence both supplier selection and end-use performance expectations. When optical components achieve micro-roughness below 0.5 Å, scattering loss under 5 ppm, and finesse of 200,000 for RLG cavities, the implication is not simply technical prestige. It is a practical determinant of how manufacturers compete on stability, calibration consistency, and long-term reliability.
Fourth, regulatory and compliance context affects both market access and sourcing strategy. In sectors where export control, quality assurance, and government registration matter, the compliance posture of a supplier can be as important as its product specification. The research incorporates these considerations into the competitive and segmentation analysis so that decision-makers can evaluate the strategic cost of sourcing from suppliers with different certification and registration profiles.
Taken together, these dynamics create a market environment in which timing, supplier choice, and application focus determine outcomes. The forecast growth to 10.9 billion USD by 2032 does not imply uniform opportunity across all players or all segments. It implies expanding value for those who position themselves in the right intersection of demand, capability, and compliance. The report’s dynamics section is built to help leaders identify that intersection before competitors lock in preferred relationships and program positions.
Strategic Takeaways for 2026 Decision-Makers
The research is organized around a simple premise: market size alone does not create strategy, but it can validate it when paired with the right structural insight. For organizations making 2026 decisions, several implications emerge from the broader market profile.
- Sequence procurement and capacity decisions early. A market advancing from 5.73 billion USD in 2026 toward 10.9 billion USD in 2032 will pressure qualification pipelines, supplier capacity, and integration resources. Waiting until demand is fully visible often means paying a premium in lead time and supplier leverage.
- Treat supplier capability as strategy, not procurement detail. In a market with meaningful concentration and demanding performance requirements, the choice of supplier affects more than price. It affects qualification risk, integration speed, compliance exposure, and long-term roadmap flexibility.
- Align application focus with demand timing and volume reality. Different end-use domains present different qualification burdens, volume characteristics, and competitive intensity. The report’s application and segmentation analysis helps leaders match investment and sourcing posture to the practical shape of demand rather than to generalized expectations.
- Use concentration as a lens for both risk and opportunity. A market in which the top five firms account for roughly 55.0 percent of revenue can support efficient sourcing, but it can also create dependency. The research helps buyers and investors understand where dual-sourcing, alternative configurations, or system-level integration partners can improve resilience.
- Watch product launches as signals of segment direction. Developments such as new solid-state RLG models for defense and unmanned platforms are not isolated events. They are indicators of where performance thresholds, platform fit, and commercial opportunity are converging.
These takeaways are not meant to be exhaustive conclusions. They are orientation points for deeper analysis. The full report builds on them with segment-level interpretation, supplier capability comparisons, and forecast-supported planning scenarios that allow leadership teams to test assumptions before committing resources.
Why This Research Belongs in Your 2026 Planning Cycle
The RLG market is at a stage where strategic advantage will be determined by the quality of decision-making, not by access to headline growth figures alone. The overall revenue progression from 3.15 billion USD in 2020 to 5.29 billion USD in 2025, followed by forecast growth to 10.9 billion USD by 2032 at a CAGR of 9.2 percent, establishes a clear directional signal. But the operational questions that matter in 2026—where to allocate sourcing risk, which applications to prioritize, how to evaluate supplier concentration, and how to interpret new product introductions—require a more granular and integrated evidence base.
This report is designed to provide that evidence base while preserving analytical discipline. It presents macro momentum without reducing the market to a single number, and it describes structural detail without exposing every segmentation figure in isolation. That balance is intentional. The goal is to give decision-makers enough rigor to trust the analysis, while preserving the full segmentation architecture, regional deployment logic, application-level interpretation, and advanced scenario detail for the complete report.
In a market where platform timing, qualification lead times, and supplier differentiation converge, intelligence must be both credible and actionable. The research behind this overview was built for exactly that purpose: to help executives, engineering leaders, and investors interpret growth not just as a forecast curve, but as a map of strategic choices. For those preparing 2026 commitments, the complete report offers the depth needed to convert market trajectory into competitive advantage.
For detailed analysis of this topic, please visit the official page: Ring Laser Gyroscope (RLG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AIM Market to Grow at 5.7% CAGR to USD 4.13 Billion by 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for 2026: Navigating the Acrylic Impact Modifier Market
The global materials landscape is entering a decisive phase for polymer additives, and nowhere is this more evident than in the Acrylic Impact Modifier (AIM) sector. As downstream manufacturers face mounting pressure to balance performance, cost, and regulatory compliance, the ability to anticipate market shifts before they materialize has become a critical competitive advantage. Our latest market research initiative, the AIM (Acrylic Impact Modifier) Market intelligence report, is designed specifically to equip strategic decision-makers with the forward-looking visibility required to navigate the 2026 horizon and the years beyond. This preview outlines the analytical rigor, structural insights, and actionable frameworks embedded in the full study, while underscoring why proprietary depth matters when capital allocation and product strategy are on the line.
Worldwide Wall Mounted Hand Dryer Market
Why 2026 Demands a Reset in AIM Strategy
For much of the past half-decade, the AIM market operated within a relatively predictable trajectory, supported by steady demand from rigid PVC applications and consistent expansion in core manufacturing geographies. Historical records trace a clear upward path from 2020 through 2025, reflecting a sector that has steadily embedded itself into architectural profiles, piping systems, and exterior-grade polymer compounds. Looking forward, the forecast window captures an inflection point rather than a mere continuation of past trends. The projected growth path through 2032 signals a market that continues to expand, yet the pace and composition of that expansion will be shaped by new product introductions, capacity realignments, raw material volatility, and evolving regulatory expectations.
Worldwide Industrial Fiberscope Market
Strategic planners in 2026 cannot rely on static growth assumptions. The transition from historical momentum to forecast behavior reveals periods where growth rates may reconfigure as capacity additions, product substitutions, and regional demand shifts interact. In such an environment, decision-makers need more than headline trajectories; they require a granular understanding of where value is concentrating, which product architectures are gaining traction, and how external cost signals could compress or expand margins. This is precisely the space our research intends to illuminate.
Worldwide Corporate Media Production Services Market
The Macro Picture: Resilience Tempered by Structural Realignment
The overall market size trajectory tells a story of enduring demand backed by broad-based industrial usage. From the 2020 baseline through the most recent historical year, the sector advanced in measured steps, reflecting the ongoing integration of acrylic impact modifiers into high-volume PVC value chains. Entering the forecast period, the market is positioned to sustain growth, with the scale expected to rise meaningfully by the close of the decade. The implied compound annual growth rate across the full forecast horizon reinforces a market that remains structurally attractive, even as individual years may exhibit uneven momentum depending on capacity cycles and application mix.
What makes this trajectory strategically significant is not just the direction of growth, but the underlying concentration of activity. A market of this scale cannot be treated as monolithic. Demand is distributed across multiple end-use domains, each with distinct performance requirements, cost sensitivities, and regulatory exposure. Likewise, regional consumption patterns reflect divergent construction cycles, infrastructure investment priorities, and local manufacturing capabilities. Recognizing this dispersion is essential for any enterprise attempting to align production planning, distribution strategy, and product development with the most rewarding opportunities. The complete report unpacks these layers without reducing them to simplistic rankings, instead mapping where volume, value, and growth velocity intersect.
Segmentation That Matters: Type, Application, and Regional Nuance
A central strength of this analysis lies in its segmentation architecture. Rather than presenting broad aggregates, the report examines how the market divides across product types, downstream applications, and geographies, allowing readers to isolate the segments most relevant to their commercial objectives. On the product side, the market spans ordinary acrylic impact modifiers alongside low-temperature resistance variants engineered for more demanding service conditions. This distinction is not cosmetic; it reflects real differences in formulation strategy, performance thresholds, and end-user expectations, particularly where PVC components must withstand thermal cycling or mechanical stress in exterior environments.
The application perspective adds an equally important dimension. Window profiles, door frames, pipelines, outdoor furniture, and assorted specialty uses each draw on the AIM supply base with different intensity and different specification requirements. Architectural and infrastructure segments, for instance, typically prioritize durability, UV stability, and long-term weatherability, while consumer-facing applications may place greater weight on processing ease and final aesthetic quality. By analyzing these application streams in context, the report helps users understand where performance differentiation creates pricing resilience and where commoditization pressures are more likely to emerge.
Regional segmentation further sharpens the strategic picture. Consumption is not evenly dispersed; it concentrates in markets with established PVC processing ecosystems as well as in regions where construction activity and industrial development continue to expand. Each geography carries its own logistics footprint, feedstock access, competitive density, and regulatory backdrop. The full study maps these regional dynamics in detail, enabling businesses to evaluate where to anchor sales efforts, where to monitor import competition, and where local content expectations or trade dynamics may alter market access.
Competitive Landscape: A Concentrated Arena with Differentiated Playbooks
The AIM market is characterized by a meaningful degree of concentration, with leading participants holding substantial share and exercising significant influence over pricing norms, product standards, and innovation cadence. Yet concentration does not imply uniformity. The competitive field includes multinational specialty chemical players, regional manufacturers with strong domestic positioning, and focused producers that compete through niche formulations or cost-optimized manufacturing. Understanding how these actors differ is vital for any company evaluating supplier relationships, partnership opportunities, or market entry pathways.
A review of the principal companies active in this space highlights a diverse array of strategic approaches. Some participants emphasize broad product portfolios that span multiple polymer applications, using established technical service networks and global reach as differentiators. Others concentrate on specific grades or performance attributes, such as enhanced fusion, UV resistance, core-shell architecture, or tailored formulations for rigid PVC processing. Several producers have built their identity around specialized impact modifier families designed for profiles, pipes, sheets, conduits, and engineered plastics, while others have expanded into synergistic combinations that pair acrylic chemistry with complementary additives to improve processing efficiency and final property profiles.
Geographic origin also shapes competitive posture. Manufacturers based in major industrial regions often benefit from proximity to downstream converters and integrated supply chains, while global-scale players leverage research capabilities, brand equity, and multi-region distribution to sustain presence across varied market conditions. The report profiles these companies with an emphasis on their specific offering logic, giving readers a clearer sense of who competes on performance breadth, who competes on application specificity, and who competes on cost and availability. Such distinctions matter when selecting suppliers, benchmarking alternatives, or assessing the credibility of potential collaborators.
Beyond the static roster of competitors, recent activity shows that the market is by no means static. Product launches, certification updates, capacity expansions, and grade enhancements have all been documented during the recent period, each carrying implications for supply reliability, performance standards, and competitive positioning. A new acrylic impact modifier introduced for engineering plastics, for example, can open adjacent opportunities beyond traditional PVC uses. Capacity expansion in a key production location may alter regional supply balances and shift sourcing calculations for converters. Updated compliance certifications can reduce friction for customers navigating regulatory requirements, effectively improving a product's market viability. Enhanced core-shell grades targeting PVC profiles demonstrate how formulation refinement can reinforce a manufacturer's standing in high-value architectural applications. The report tracks these developments and interprets them not as isolated headlines, but as signals of where capability and momentum are accumulating.
Operating Conditions: Raw Materials, Regulation, and the Cost Equation
No strategy for the AIM market can be built in isolation from the cost and compliance environment. Raw material trends are a persistent force shaping producer economics and, by extension, the price expectations of downstream buyers. During recent periods, feedstock dynamics have displayed notable variability across regions. In Asia, certain key input prices have trended soft to stable, reflecting a combination of demand conditions and supply balance. In parallel, other essential feedstocks have moved lower in global assessments, with consistent declines recorded in CFR China benchmarks and downward movement observed in European pricing through the latter part of the year. These patterns matter because they influence production cost structures, margin flexibility, and the relative competitiveness of different manufacturing bases.
Equally important are the regulatory currents reshaping demand behavior. In Europe, ongoing debate around restrictions on certain stabilizers used in PVC introduces potential disruption risk for related additive demand, including impact modifiers that are part of broader formulation systems. At the same time, policy frameworks in multiple jurisdictions are increasingly incentivizing bio-based and recyclable solutions, encouraging investment in sustainable polymer technologies. This dual pressure creates a strategic paradox: some conventional demand pathways may face headwinds, while new opportunities emerge for additives that align with sustainability agendas and evolving compliance expectations. Companies that track these dynamics early can adapt formulation roadmaps, supplier selection, and customer messaging before shifts become consensus.
The interaction between raw material flexibility and regulatory direction also affects segmentation dynamics. In a softer input cost environment, producers may have more room to compete on price or to fund product improvement without immediate margin erosion. Under stricter regulatory scrutiny, customers may prioritize grades with documented compliance, predictable performance, and reduced reliance on restricted substances. The full report integrates these factors into its market dynamics assessment so that readers can gauge how external conditions may influence competitive outcomes over the forecast window.
What the Full Report Delivers: Operational Intelligence, Not Just Data
This market research is structured to support practical decision-making rather than passive observation. It is built around a set of actionable modules that translate market structure into strategic insight. Readers can expect detailed coverage of scope and methodology, historical performance tracking, and forecast construction that clarifies the assumptions behind forward estimates. Segmentation is presented in a way that supports segment-level evaluation of demand drivers, competitive intensity, and growth potential, while preserving the analytical discipline needed to avoid overgeneralization.
The competitive analysis extends beyond company identification. It connects product offerings, manufacturing footprints, and recent corporate actions to a broader assessment of how the market is likely to evolve. By examining who is expanding, who is refining grades, and who is responding to regulatory or sustainability pressures, the report helps clients anticipate shifts in supply reliability, differentiation opportunities, and potential partnership targets. Recent developments are woven into this narrative to show how near-term actions influence longer-term positioning.
Cost and dynamics analysis deserves particular emphasis. Because AIM purchasing decisions often hinge on the balance between performance gains and total formulation cost, the report incorporates feedstock trends, regional price posture, and regulatory risk into a coherent operating context. This allows users to evaluate margin exposure, sourcing strategy, and inventory planning with a clearer view of the forces that will shape price formation and availability through the forecast period.
In addition, the study is designed to support scenario thinking. Markets of this kind rarely move in straight lines, and effective strategy requires understanding how different combinations of demand growth, capacity response, raw material movement, and regulatory change could alter outcomes. The report provides the analytical scaffolding for that kind of assessment, helping organizations test assumptions and prepare for multiple plausible paths rather than a single baseline.
How to Use This Research for 2026 Decision-Making
For executive teams, procurement leaders, product developers, and commercial strategists, the practical value of this research lies in its ability to connect macro signals to operational choices. A supplier evaluating capacity allocation can use the segmentation and regional analysis to prioritize the most resilient demand pools. A converter assessing additive sourcing can benchmark competitors and recent product launches to understand where performance differentiation may justify premium positioning or where cost competition is intensifying. A strategist monitoring regulatory exposure can align formulation direction with compliance trajectories before customer requirements harden into mandates.
The report also serves as a reference point for investor and partnership conversations. In a market with measurable concentration and active corporate development, stakeholders need credible structure to evaluate where value is generated and how defensible particular positions may be. By providing a disciplined overview of shares, concentration, product families, application breadth, and recent momentum, the study gives decision-makers a stronger basis for negotiation, investment appraisal, and strategic planning.
Next Steps: Accessing the Full Intelligence Package
This preview has outlined the analytical framework and strategic intent behind the AIM (Acrylic Impact Modifier) Market research, but it cannot replicate the granularity, comparability, and segment-level insight contained in the full report. The complete study goes further into historical trends, forecast construction, segmentation behavior, competitive positioning, and the operating dynamics that influence cost and demand. Those details are essential for organizations that need to convert market awareness into procurement strategy, product planning, regional expansion decisions, or supplier evaluation.
For leaders preparing for 2026 and the forecast window beyond, the most effective next step is to engage with the full dataset and analysis directly. The complete report is available through our official research portal, where clients can access the comprehensive market model, company profiles, segmentation breakdowns, and the supporting context needed to operationalize the findings. In a market shaped by concentration, formulation innovation, raw material variability, and regulatory evolution, deeper intelligence is not a luxury; it is a prerequisite for confident action.
For detailed analysis of this topic, please visit the official page: AIM (Acrylic Impact Modifier) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heart Defect Closure Devices Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Heart Defect Closure Devices Market: A 2026 Outlook
The landscape of structural heart intervention is undergoing a defining transformation. As minimally invasive techniques continue to displace traditional surgical approaches, heart defect closure devices have emerged as a critical category within the broader cardiovascular device ecosystem. For executive leadership teams, capital allocators, and market access strategists, understanding the trajectory of this market is no longer optional—it is a prerequisite for informed decision-making in 2026 and beyond.
Worldwide Sleeper Truck Market
Our latest research publication, Heart Defect Closure Devices Market, delivers a multidimensional analysis designed specifically to support enterprise-level strategy formulation. This article serves as an executive preview, outlining the structural forces, competitive architecture, and regulatory currents shaping the sector. It is not a substitute for the full report, which contains the granular segmentation, historical revision pathways, and forward-looking scenario modeling required for precise commercial planning.
Handheld Massage Shower Head Market
The Market Trajectory: From Recovery to Sustained Expansion
Over the past half-decade, the heart defect closure devices market has demonstrated a consistent upward trajectory, reflecting both the maturation of transcatheter closure technologies and the widening clinical acceptance of percutaneous interventions across multiple defect types. Historical valuation patterns from the early 2020s through the mid-2020s reveal a market that has steadily rebuilt momentum following procedural volume adjustments and supply chain recalibrations. By 2025, the market reached a baseline valuation of USD 215.00 Million, establishing a firm foundation for the forecast cycle that extends through 2032.
Mobile Instant Photo Printers Market
Looking ahead, the forward-looking horizon indicates sustained expansion. The market is projected to advance to approximately USD 233.77 Million in 2026, with sequential growth continuing through the late 2020s and into the early 2030s. By the close of the forecast period, the category is expected to approach a valuation of USD 344.8 Million. This progression translates to a compound annual growth rate of 6.98 percent across the 2026 to 2032 forecast window. While the headline figures signal a healthy growth environment, the underlying drivers are what matter most for strategic planning. Procedural volume expansion, the broadening of clinical indications, device iteration cycles, and geographic diffusion all interact to shape the pace and composition of revenue generation.
Importantly, market growth is not uniform across all pathways. Certain closure categories benefit from more established clinical workflows and higher procedural frequencies, while others remain in earlier stages of adoption or face more complex reimbursement considerations. The interplay between these categories determines how incremental growth is distributed across the product landscape, a nuance that enterprise planners must account for when modeling pipeline returns, capacity investments, or partnership opportunities.
Competitive Architecture: Concentration, Positioning, and Strategic Optionality
One of the most strategically relevant features of the heart defect closure devices market is its moderately concentrated structure. The top three competitors collectively account for roughly 24.6 percent of market revenue, while the top five firms capture approximately 26.2 percent. This concentration profile indicates that leadership positions are meaningful but far from absolute. The market remains sufficiently open to allow focused innovators, regionally advantaged manufacturers, and well-positioned distribution partnerships to capture meaningful share, particularly as new indications mature and geographic access expands.
Within this competitive field, several enterprises stand out for their portfolio depth, technological differentiation, and market access capabilities. Abbott Laboratories continues to anchor its structural heart presence through the Amplatzer line of septal occluders, including devices designed for atrial septal defect closure, patent foramen ovale closure, and ventricular septal defect interventions. The breadth of this platform provides Abbott with a recognizable clinical footprint and a foundation for iterative product refinement. W. L. Gore & Associates has carved out a differentiated position with the GORE CARDIOFORM Septal Occluder and GORE CARDIOFORM ASD Occluder, offering clinicians alternative design geometries and delivery characteristics for ostium secundum ASD and PFO closure.
Occlutech Holding AG has recently reinforced its strategic relevance through a notable expansion of its US footprint. The company’s ASD Occluder, including the Figulla Flex series, and its Pistol Pusher delivery technology have gained regulatory traction and commercial momentum in the United States, marking a significant step in the company’s transcatheter closure ambitions. Medtronic plc contributes to the competitive landscape with the CardioFlex ASD closure device and related structural heart occluders aimed at congenital heart defect closure. Boston Scientific Corporation maintains a presence through structural heart occlusion systems and portfolio products that support ASD and related defect closure pathways.
The competitive field also extends beyond the largest multinational incumbents. Lifetech Scientific Corporation, based in Shenzhen, offers the Lifestar line of congenital heart defect occluders spanning ASD, PFO, and VSD closure applications. Lepu Medical Technology, headquartered in Beijing, provides additional manufacturing capacity and product offerings in the septal occluder segment. The presence of these firms introduces important competitive dynamics, particularly around cost structure, regional market access, and the ability to serve high-volume clinical environments with appropriate product availability.
From a strategic standpoint, this competitive configuration matters because it shapes the terms of market engagement. Firms with broad platforms can pursue indication expansion and cross-selling within existing clinical workflows. Firms with specialized device characteristics can target underserved procedural niches or clinician preference segments. And firms with strong regional manufacturing or distribution capabilities can compete aggressively on access, service, and price in geographies where procedural growth is accelerating. The full report examines these positioning dynamics in greater depth, including the strategic implications of recent commercial milestones and regulatory clearances.
Regulatory and Clinical Dynamics as Strategic Variables
Regulatory architecture is not merely a compliance concern in this category; it is a strategic variable that directly influences launch timing, market access, clinician adoption, and competitive sequencing. Recent years have underscored how pivotal regulatory milestones can be in reshaping the commercial landscape for structural heart closure technologies.
In late 2023, FDA PMA approval was granted for the Occlutech ASD Occluder and Occlutech Pistol Pusher, an approval that opened the door for a more active US commercial trajectory. That momentum continued into 2024, when Occlutech initiated US commercialization through an exclusive partnership with B. Braun Interventional Systems and subsequently progressed to first commercial US implantations. These developments illustrate a broader pattern in which regulatory clearance and partnership execution can create step-change opportunities, especially for companies expanding beyond established geographic strongholds.
Regulatory evolution is also visible across the broader device field. Multiple devices are currently marketed for PFO and ASD closure, including the Amplatzer Talisman PFO Occluder, GORE CARDIOFORM Septal Occluder, GORE CARDIOFORM ASD Occluder, and the Occlutech ASD Occluder. At the same time, the commercial environment reflects ongoing product lifecycle adjustments, with certain legacy devices such as the GORE HELEX Septal Occluder having been discontinued. This kind of portfolio turnover is strategically significant because it alters the competitive set available to clinicians and health systems, shifts procurement considerations, and creates room for newer entrants or updated device generations to influence purchasing behavior.
Additional regulatory activity continues to shape the category’s trajectory. The Abbott Amplatzer Talisman PFO Occluder received FDA PMA approval in 2021, reinforcing the long-term importance of PFO-related closure pathways within the broader market structure. More recently, Abbott’s Amplatzer Piccolo Delivery System received FDA clearance in late 2025 for use with congenital heart defect closure devices, highlighting how delivery systems and companion technologies can expand the practical utility of closure platforms and improve procedural flexibility.
For enterprise strategists, the strategic implication is clear. Regulatory sequencing influences not only which devices are available, but also how quickly new options can be integrated into clinical pathways, how procurement teams evaluate alternatives, and how competitors reposition their portfolios in response to newly approved technologies. Companies that track these regulatory shifts proactively can anticipate changes in demand patterns, adjust market access plans, and align R&D or partnership priorities with emerging opportunities before the wider market reacts.
Why This Research Matters for 2026 Decision-Making
The strategic relevance of the heart defect closure devices market in 2026 lies in the intersection of demand expansion, technological maturation, and competitive recalibration. Organizations operating in, adjacent to, or in partnership with this market must make decisions under conditions of real uncertainty: Which procedural pathways will accelerate most rapidly? How will clinician preference evolve as device options diversify? Where will geographic adoption create the most attractive near-term opportunities? How should portfolios be structured to balance leadership categories with higher-upside segments?
This research is designed to support those decisions with a structured, evidence-based framework. Rather than offering a static snapshot, the report builds a forward-looking view that connects historical performance to forecast trajectories and then ties those trajectories to the operational questions that executives actually face. The analysis integrates demand-side drivers, supply-side competition, and regulatory developments into a coherent market story, allowing decision-makers to test assumptions and evaluate strategic options with greater confidence.
For organizations assessing market entry, expansion, or repositioning, the study provides context on how market value is distributed across the forecast period and how the growth profile evolves over time. For manufacturers and device innovators, it offers a basis for evaluating portfolio priorities, commercialization sequencing, and the relative attractiveness of different closure categories. For healthcare strategists, reimbursement specialists, and procurement leaders, it supports a more informed understanding of the broader device environment in which purchasing decisions and clinical adoption decisions are made.
Equally important, the research is structured to help organizations avoid the most common strategic error in fast-moving device markets: over-reliance on top-line market size figures without sufficient attention to the segmentation, competitive, and regulatory context underneath them. A market can grow steadily while still producing very different outcomes for different participants, depending on product mix, indication focus, geographic exposure, and access to clinicians and health systems. The full report is built to illuminate those distinctions.
What the Full Report Delivers
The complete Heart Defect Closure Devices Market study is structured to serve as a practical decision-support instrument rather than a purely descriptive overview. It combines historical context, forecast modeling, segmentation analysis, and competitive profiling into a single integrated reference. The report is intended to be used by strategy, corporate development, commercial planning, and market intelligence teams that need a defensible basis for planning in a category where clinical, regulatory, and competitive variables interact closely.
The study includes a detailed examination of the market’s historical development, establishing how recent performance sets the stage for the 2026 to 2032 forecast period. It then presents forward-looking analysis that connects the market’s growth path to the strategic questions most relevant to enterprises planning investments, launches, partnerships, or competitive responses. Because the report is designed for decision use, it emphasizes not just what the market is doing, but what that means for positioning, prioritization, and risk management.
The competitive analysis component goes beyond company mentions. It situates key participants within the broader market structure, helping readers understand how portfolio scope, regulatory status, and commercial execution influence competitive strength. The report also provides context on the types of closure technologies and clinical applications that shape market demand, allowing readers to interpret growth patterns with a clearer sense of where value is being generated and where future expansion may emerge.
Regulatory and industry context are integrated throughout the analysis where relevant, ensuring that the market view reflects not only commercial momentum but also the approval, adoption, and product lifecycle dynamics that influence real-world execution. This integrated approach is especially important in a market where a single regulatory event or partnership announcement can meaningfully alter the competitive landscape.
Using This Intelligence to Shape Strategy
A market study of this kind is most valuable when it is translated into concrete strategic actions. For executive teams, that translation begins with clarifying the questions that matter most. Is the organization seeking to defend an existing position, pursue incremental growth in established segments, or prepare for upside in emerging indications and geographies? Does the strategy depend on product differentiation, delivery system optimization, regional access, or commercial partnership? The more precisely an organization can define its strategic objective, the more effectively it can use market intelligence to support that objective.
One practical application is scenario planning. Because the heart defect closure devices market is influenced by procedural adoption patterns, regulatory developments, and competitive moves, organizations benefit from evaluating multiple plausible paths rather than a single forecast. The report’s forecast structure supports this approach by providing a market framework within which different assumptions can be tested. That capability is particularly useful for companies making capacity, launch, or partnership decisions where timing and sequencing are critical.
Another application is competitive positioning. Understanding how market value is shared among leading participants, and how that share structure may evolve, helps organizations anticipate where competition will intensify and where differentiation remains possible. It also helps identify where incumbent advantages are strongest and where newer entrants or regional manufacturers may be able to compete effectively. The full report provides the kind of structural detail needed to make those assessments with greater precision.
A third application involves market access and commercialization alignment. In device categories where clinician preference, procedural workflow, and regulatory status all influence adoption, commercial strategy must be closely aligned with the clinical and regulatory environment. Market research that integrates these factors can inform message positioning, partnership selection, launch sequencing, and regional prioritization. It can also help organizations avoid misaligned assumptions about how quickly a new device or indication will translate into commercial traction.
Moving from Awareness to Action
The heart defect closure devices market presents a compelling combination of growth, clinical relevance, and competitive dynamism. Its 2026 to 2032 trajectory suggests continued expansion, while its regulatory and competitive history demonstrates that market leadership is shaped as much by execution, access, and product strategy as by underlying demand. For organizations operating in this environment, the strategic question is not simply whether the market is growing, but how to participate in that growth with discipline and foresight.
This preview has outlined the broad contours of the market story: the historical baseline, the forecast direction, the competitive concentration structure, the significance of recent regulatory and commercial developments, and the strategic use cases that make this research relevant for 2026 planning. What it has not done is replace the full market study. The detailed segmentation, the precise historical and forecast construction, the company-level competitive interpretation, and the context-specific strategic implications are all developed more fully in the complete report.
For leaders who need to move from general awareness to specific action, that deeper level of detail is essential. The full Heart Defect Closure Devices Market research is available through PW Consulting and is designed to provide the precision, structure, and strategic context required for confident decision-making. We encourage executive teams, strategy functions, and market intelligence units to review the complete study as part of their 2026 planning process, particularly where investment timing, portfolio prioritization, or competitive positioning will have a material impact on near-term performance and longer-term optionality.
In a market where the pace of clinical adoption and the sequence of regulatory events can change the competitive landscape quickly, timely and well-structured intelligence is not just an information asset. It is a strategic advantage.
For detailed analysis of this topic, please visit the official page: Heart Defect Closure Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com