

Blogs
Employee Scheduling Software Market 2026: Why 11.2% CAGR Redefines Growth Strategy
By PW Consulting, 2026-09-21
The Employee Scheduling Software Market: Navigating Growth, Fragmentation, and the AI Inflection Point
The employee scheduling software market has transitioned from a tactical admin utility to a strategic operational layer that directly shapes labor costs, compliance exposure, and service continuity. Revenue across the sector expanded from approximately USD 148.5 million in 2020 to an estimated USD 225.0 million by 2025, reflecting a compound annual growth rate of 11.2% over the 2020–2025 period. Forward projections indicate the market will reach roughly USD 250.7 million in 2026 and continue expanding toward USD 367.0 million by 2032, sustained by the same structural tailwinds that drove the earlier acceleration. This trajectory signals more than incremental software adoption; it reflects a fundamental rethinking of how organizations translate demand volatility into shift coverage while controlling overtime, reducing compliance risk, and preserving employee experience.
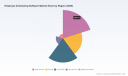
The growth curve is not uniform. Cloud-based deployment continues to dominate new implementations, while on-premises footprints are shrinking as organizations migrate toward integrated platforms that connect scheduling with payroll, time tracking, and workforce analytics. Mid-size enterprises and small businesses together account for the largest share of adoption volume, driven by the need for affordable, mobile-first tools that can scale without dedicated HRIT teams. Large enterprises are pursuing fewer but deeper deployments, prioritizing forecasting accuracy, multi-site orchestration, and integration with broader HCM ecosystems. Geography also matters: North America remains the largest revenue center, Europe follows with strong compliance-led demand, and Asia Pacific is emerging as the fastest-expanding region as service-sector digitization and flexible staffing models accelerate.
Defining the Current Inflection Points
Despite the expansion, the market sits at a series of crossroads. First, legacy schedulers that rely on static templates and manual overrides are increasingly misaligned with demand patterns characterized by seasonal spikes, last-minute absenteeism, and customer-facing fluctuations. Organizations that continue to manage shifts through spreadsheets or siloed tools face mounting labor mismatches that translate directly into overtime leakage, understaffed service windows, and scheduling friction for employees. Second, compliance complexity is intensifying. Meal-and-rest mandates, overtime thresholds, union rules, and region-specific labor regulations are proliferating, making manual enforcement error-prone and legally risky. Platforms that cannot automate policy enforcement and audit trails are losing relevance in regulated environments. Third, integration expectations are rising. Buyers now assume that a scheduling tool will connect with time and attendance, payroll, demand signals, and workforce analytics without custom middleware. Vendors that remain point solutions risk being bypassed in favor of platforms that can reduce integration debt and administrative fragmentation.
Key Drivers Reshaping the Market
Three to four forces are converging to redefine the value proposition of employee scheduling software, shifting it from convenience to operational leverage.
Technology Innovation and the AI Forecasting Shift
Artificial intelligence has moved from a feature promise to a core differentiator. Modern platforms combine historical attendance, demand signals, seasonality, and employee availability to generate shift forecasts and coverage recommendations that adjust in real time. This matters because scheduling accuracy directly affects labor cost and service quality. Organizations using AI-driven planning and real-time analytics report meaningful reductions in overstaffing and overtime, with customer-reported outcomes pointing to an average 21% decrease in labor costs. At the same time, automated shift planning paired with mobile self-service has been associated with roughly 30% higher shift coverage and 23% lower overtime costs in typical deployments. The strategic implication is clear: scheduling software is increasingly a cost-control and continuity tool, not merely a shift calendar. The vendors winning attention are those that translate forecasting into actionable coverage plans, flag compliance conflicts early, and let employees swap or pick shifts without creating coverage gaps.
Policy and Regulatory Pressure as a Catalyst for Automation
Labor regulation is no longer a static backdrop; it is becoming one of the most powerful adoption drivers. Platforms increasingly embed rules for meal breaks, rest periods, overtime limits, union requirements, and state-specific mandates so that schedule generation and adjustments automatically respect policy boundaries. This reduces legal exposure and administrative burden while giving managers a defensible scheduling process. In parallel, data privacy expectations have hardened, especially for cloud-based tools serving European and regulated markets. Maintaining GDPR and SOC 2 compliance is now table stakes for enterprise buyers, and platforms that can demonstrate consistent controls around data handling, access, and auditability enjoy a shorter sales cycle in sensitive environments. The practical outcome is that compliance automation and privacy assurance are becoming competitive moats, particularly for vendors serving multi-jurisdiction workforces.
Demand-Side Change: Frontline Work Patterns and Employee Expectations
The shape of hourly and frontline work continues to evolve. Service sectors, retail, logistics, healthcare support, and hospitality face demand that fluctuates with weather, seasons, local events, and consumer behavior. Employees, meanwhile, expect greater visibility and control over their schedules, faster shift confirmation, and simpler swap mechanisms. This dual pressure pushes organizations toward scheduling tools that are mobile-first, self-service enabled, and capable of balancing business coverage needs with employee preferences. Mobile clock-in, shift templates, real-time notifications, and team communication features are increasingly expected rather than optional. Companies that ignore the employee experience dimension tend to see higher attrition and last-minute coverage gaps, which in turn inflate labor costs and degrade service consistency.
Worldwide Field Service Software Market
Cost Structure and SaaS Economics Favoring Cloud Deployment
The cost equation favors cloud-based delivery, especially for small and mid-size organizations that lack large internal IT footprints. Subscription economics reduce upfront capital barriers, accelerate deployment, and make it easier to add locations, users, and modules as needs evolve. For larger enterprises, the cloud transition is less about affordability and more about integration and analytics. Centralized data from scheduling, time tracking, and payroll creates visibility into labor cost trends, coverage efficiency, and overtime patterns, enabling more informed workforce planning. This dynamic reinforces the dominance of cloud models in new revenue and explains why on-premises installations are increasingly limited to specialized or legacy environments with strict data residency or operational constraints.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three providers holding roughly 24.6% of revenue and the top five near 26.2%. That leaves substantial room for specialization, regional strength, and segment-focused differentiation. The field spans global HCM-scale platforms, workforce-management specialists, and SMB-oriented mobile tools, each pursuing distinct strategic positions.
Strategic Positioning Among Leading Providers
ADP has built a broad workforce management footprint with ADP Workforce Now, integrating scheduling, time tracking, shift optimization, and compliance tools aimed at hourly and frontline workers. Its strength lies in scale, payroll linkage, and the ability to serve a wide range of organization sizes with a single platform. UKG has pushed enterprise-grade capabilities through UKG Pro and Kronos Workforce Central, emphasizing AI forecasting, real-time coverage planning, labor cost optimization, and multi-site shift management. The recent expansion of UKG’s integration ecosystem underscores a platform strategy: in March 2026, it introduced 15 Workforce Management APIs to streamline connections with scheduling and time-tracking platforms, reflecting a recognition that interoperability now shapes buying decisions. Ceridian Dayforce positions around a unified platform for global enterprises, combining scheduling, shift assignment, workforce analytics, and automated compliance within a single system, appealing to organizations that want consistency across regions and functions.
Rippling targets growing businesses with an integrated HR and workforce management suite that links scheduling, AI demand forecasting, shift planning, and payroll, reducing the friction of juggling separate tools. Deputy remains focused on shift-based industries with AI labor forecasting, mobile apps, and compliance automation, a model that resonates in retail, hospitality, and light industrial settings. Connecteam and Homebase emphasize SMB usability through app-based scheduling, shift swapping, mobile clock-in, labor cost tracking, and compliance alerts, competing on ease of adoption and day-to-day usability. Paychex Flex and Paycor extend mid-market reach by tying scheduling to payroll and HCM dashboards, providing labor cost visibility and shift management within broader HR processes. When I Work emphasizes employee self-scheduling and real-time reporting, a straightforward value proposition for teams that want flexibility without administrative overhead. Workday brings enterprise HCM depth with advanced scheduling, demand forecasting, and compliance-driven workforce planning for large organizations. Finally, TCP Software and Shiftboard highlight highly operational niches: automated forecasting, mobile management, fatigue management, contingent labor tools, and labor cost reduction for mission-critical environments, where coverage assurance and risk control outweigh convenience alone.
Nurse Scheduling Software Market
How the Landscape Is Evolving
Three trends are reshaping the competitive structure. Integration is becoming a default expectation rather than a differentiator, pushing vendors to offer APIs, prebuilt connectors, and data flows that tie scheduling into payroll, analytics, and demand systems. At the same time, specialization is intensifying in high-stakes segments such as healthcare support, logistics, manufacturing, and other environments where fatigue management, compliance enforcement, and contingent labor coordination carry direct operational and safety implications. A third dynamic is the steady arrival of well-funded new entrants that lean into mobile-first design, AI forecasting, and SMB affordability, expanding choice but also fragmenting attention for buyers. The net result is a market that rewards clear positioning: platforms that can demonstrate measurable coverage improvements, labor cost control, and compliance automation within a buyer’s existing technology stack are gaining traction, while undifferentiated schedulers are facing longer evaluation cycles and stricter comparison criteria.
Forward-Looking Trends and Commercial Opportunities
Looking across the next three to five years, several trends are likely to determine where value accrues and where new opportunities emerge.
AI-First Scheduling Becomes the Operational Standard
Forecasting and real-time adjustment will become embedded baseline capabilities rather than premium add-ons. As models improve with richer attendance history, demand signals, and policy constraints, organizations will expect scheduling systems to anticipate coverage gaps, recommend shift fills, and flag labor cost risks before shifts are published. The commercial opportunity lies in solutions that connect forecasting with execution: auto-suggested shifts, mobile acceptance flows, and manager dashboards that make actionable decisions fast. Vendors that can show defensible improvements in coverage and overtime—with clear measurement frameworks—will find it easier to justify expansion and renewals.
Compliance Automation as a Core Buying Criterion
The regulatory environment will continue to reward platforms that can encode rules, enforce them at schedule creation, produce audit-ready documentation, and adapt quickly to changing requirements. This is particularly relevant for multi-state, multi-jurisdiction, and unionized workforces. The opportunity for providers is to package policy guidance, rule templates, and document support as part of the workflow rather than as separate services. Organizations that treat compliance automation as a design principle—rather than a retroactive fix—will reduce legal exposure and administrative effort while strengthening employee trust in the scheduling process.
Integration Ecosystems and Workforce Data Platforms
The future value chain is increasingly interoperable. Scheduling will connect more tightly with time and attendance, payroll, labor analytics, and demand planning, creating a more complete view of workforce costs and coverage. Buyers will favor solutions that minimize custom integration work and enable data to move cleanly between functions. This opens opportunities for platforms that act as orchestration layers, standardize data models, and provide APIs that accelerate deployments and reduce total cost of ownership. For enterprises, the prize is workforce visibility that supports planning beyond individual shifts: staffing models, labor budgets, and service-level commitments aligned with realistic demand.
These trends carry uncertainty. AI adoption depends on data quality and change management; inaccurate inputs or poorly governed models can erode trust and limit realized savings. Compliance expectations can shift quickly, requiring vendors and buyers alike to keep pace with new rules and interpretations. Integration depth can also become a double-edged sword: over-engineaging ecosystems may complicate deployments, while under-integrated tools may fail to meet enterprise expectations. Finally, pricing pressure is likely to intensify as more competitors offer AI features at competitive price points, making it essential for providers to differentiate on outcomes, not just feature lists.
Strategic Actions for Decision-Makers
The market’s direction suggests several practical moves, tailored to different roles in the value chain.
PW Consulting Information & Electronics Research Center
-
For enterprise and mid-market buyers evaluating scheduling software: prioritize platforms that link scheduling with payroll and time tracking, enforce compliance rules automatically, and provide measurable coverage and labor-cost outcomes. Run pilots that test forecasting accuracy under real demand variability, not just idealized scenarios. Confirm that the solution supports mobile self-service, shift swaps, and rapid manager overrides without creating policy violations. Assess integration effort early, because hidden middleware and data cleanup can turn a low-cost tool into a high-friction deployment.
-
For investors and strategic partners: focus on providers with credible AI forecasting, strong compliance automation, and clear integration roadmaps, especially those demonstrating repeatable labor-cost reductions and coverage improvements in target verticals. The highest-conviction opportunities are likely in platforms that can serve shift-based and mission-critical environments at scale while maintaining data-privacy assurance for regulated markets. Watch for consolidation signals, since interoperability demands and integration fatigue may drive buyers toward platforms that can unify functions and reduce vendor count.
- For vendors and product leaders: invest in measurable outcome claims, not just feature breadth. Make compliance automation, auditability, and privacy controls visible and easy to validate. Build integration pathways that reduce deployment time and data fragmentation, and design mobile self-service experiences that improve employee adoption while protecting coverage integrity. Differentiation will increasingly come from how well a platform reduces overtime leakage, improves shift coverage, and keeps schedules within policy boundaries without adding manager workload.
The employee scheduling software market is moving from incremental digitization to a more outcome-driven phase in which forecasting accuracy, compliance automation, and integration maturity determine competitive strength. For organizations navigating shifting labor patterns and rising regulatory complexity, the question is no longer whether to adopt scheduling software, but which platform can convert schedule planning into lower labor costs, fewer compliance risks, and more reliable coverage. Detailed segmentation data, vendor-by-vendor benchmarks, and customized adoption roadmaps can sharpen those decisions further; PW Consulting’s full research report provides that deeper breakdown for teams preparing investment, procurement, or product strategy choices in this space.
For detailed analysis of this topic, please visit the official page: Employee Scheduling Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Soy Sauce Market Beyond the 5.4% CAGR: Strategic Shifts Reshaping Asia Pacific Dynamics
By PW Consulting, 2026-09-21
The Strategic Soy Sauce Market: Navigating the Next Wave of Growth
The global condiments sector has long relied on soy sauce as a foundational ingredient, but the current market trajectory suggests a more sophisticated evolution than simple volume expansion. As the industry moves through a period of steady revenue growth and shifting consumption patterns, strategic decision-makers must look beyond headline numbers to understand the structural forces reshaping supply chains, competitive positioning, and consumer expectations. The market has demonstrated consistent momentum over the past half-decade, with revenue figures climbing steadily and a projected compound annual growth rate signaling continued expansion through the early 2030s. Yet this growth masks underlying complexities that demand careful navigation.
From a macro perspective, the industry has transitioned from a mature, regionally concentrated category into a more globally integrated space where premiumization, geographic diversification, and operational scale intersect. Total market revenue has grown from the high twenty-nines billion range in 2020 to surpass the forty-one billion mark by 2025, and forward projections indicate continued upward movement, with the market expected to approach the sixty-billion threshold by 2032. This trajectory reflects more than population growth or basic culinary adoption; it points to a category gaining relevance in modern food preparation, ethnic cuisine globalization, and industrial food formulation. For executives and investors, the headline growth rate of approximately 5.4 percent annually provides a useful baseline, but the real strategic value lies in understanding where growth concentrates, what threatens it, and how incumbents are adapting.
Several structural tensions currently define the industry's inflection point. First, the sector operates within a moderately concentrated environment where a limited number of large producers command meaningful share, yet smaller specialty manufacturers continue to carve out profitable niches through authenticity, craftsmanship, and geographic specificity. This coexistence of scale and specialization creates both competitive friction and partnership opportunities. Second, raw material cost dynamics introduce volatility that can compress margins or force pricing strategies that risk alienating price-sensitive buyers. Third, regulatory divergence across key markets means that compliance requirements, labeling rules, and ingredient transparency expectations differ sharply depending on where a product is manufactured, distributed, or consumed. These three forces, market concentration, input cost variability, and regulatory asymmetry, form the backdrop against which strategic choices must be made.
Understanding the Market Landscape and Its Pressures
The global soy sauce market has matured into a multi-regional industry where cultural familiarity, foodservice integration, and retail convenience collectively drive demand. Asia Pacific remains the dominant revenue contributor, reflecting both deep culinary tradition and large population bases, but growth is increasingly visible in regions where Asian cuisine adoption continues to expand among mainstream consumers. The category is no longer confined to traditional home cooking; it now flows through packaged food manufacturing, restaurant operations, and cross-cultural food experimentation. This broader application footprint has helped stabilize demand even as certain mature markets face slower household penetration growth.
Three challenges stand out as particularly consequential for strategic planning:
Soy Milk Market
- Margin pressure from input cost volatility: Soybeans and fermentation inputs are subject to agricultural cycles, weather disruptions, and commodity trading dynamics. When harvest forecasts shift or trade flows adjust, producers must decide whether to absorb cost increases, renegotiate supplier agreements, or pass changes through to customers, each path carrying commercial risk.
- Regulatory fragmentation: Labeling, nutritional disclosure, and ingredient transparency rules vary across jurisdictions. A product positioned for global distribution must comply with differing standards on GMO disclosure, nutritional labeling, and processing classifications, which can complicate packaging, marketing, and market-entry sequencing.
- Competitive differentiation in a crowded category: Traditional large-scale brewing, accelerated production methods, and artisanal fermentation all compete for shelf space and foodservice contracts. Consumers and professional buyers increasingly evaluate flavor complexity, sodium content, authenticity claims, and sourcing ethics, raising the bar for what constitutes competitive advantage.
These challenges are not insurmountable, but they do require a more deliberate approach to product architecture, supply chain resilience, and geographic prioritization. Companies that treat the category as a single homogeneous proposition risk missing the opportunities hidden in regional taste preferences, application-specific formulations, and regulatory arbitrage where compliant positioning can become a market-access advantage.
Core Drivers Shaping the Next Growth Cycle
The market's forward momentum is not accidental; it is being propelled by a combination of technological advancement, shifting consumer behavior, supply-side restructuring, and evolving regulatory frameworks. Each driver interacts with the others, creating a landscape where advantages compound for organizations that align product strategy with operational readiness.
Innovation in Production and Product Architecture
Fermentation science and process control have progressed beyond the traditional binaries of naturally brewed versus chemically accelerated production. Modern manufacturers are investing in controlled fermentation environments, strain selection, and analytical quality systems that improve consistency while preserving the flavor profiles consumers associate with authenticity. At the same time, product architecture has expanded to include reduced-sodium formulations, cleaner-label variants, and flavor-specialized offerings tailored to specific culinary applications. This innovation is not merely technical; it is commercial. Producers that can deliver consistent taste, adaptable viscosity, and stable shelf performance gain advantages in both retail and industrial food service settings.
Regulatory Divergence as a Strategic Variable
Regulatory environments are not moving in unison, and this divergence has become a meaningful factor in market strategy. In some markets, soy sauce benefits from exemptions or lighter labeling burdens, while in others, GMO disclosure, nutritional labeling, or deeply processed product classification introduces additional compliance steps. These differences shape where companies choose to launch first, how they design packaging, and which ingredient claims they can safely make. For global players, the capability to modularize compliance by region, rather than treating labeling as a single global template, can reduce time-to-market friction and avoid costly reformulation cycles. For smaller brands, understanding regulatory thresholds early can determine whether a product can scale internationally or remains regionally constrained.
Demand-Side Shifts Toward Authenticity and Application Versatility
Consumer and buyer behavior continues to tilt toward products that signal authenticity, craftsmanship, and culinary specificity. This does not mean every segment seeks premium pricing; rather, it means that trust, origin narrative, and flavor reliability increasingly influence purchase decisions. At the same time, foodservice operators and packaged food manufacturers demand ingredients that perform consistently across large batches and varied recipes. The dual demand for artisanal credibility and industrial reliability pushes manufacturers to build portfolios that serve both ends of the spectrum. Brands that can articulate a clear position, whether as a heritage fermented product or a dependable industrial ingredient, are better placed to secure shelf space, contract stability, and repeat procurement.
Pasta Sauce Market
Supply Chain and Cost Structure Realignment
Soy sauce production depends on soybean supply, brewing infrastructure, logistics, and regional labor and energy costs. Agricultural price forecasts for the coming marketing years point to higher season-average soybean prices compared with the prior year, which signals potential cost pressure for upstream inputs. This does not automatically translate into market-wide margin erosion, but it does reward organizations that secure forward contracts, diversify sourcing, and optimize plant utilization. Companies with geographically distributed production footprints can shift volume among facilities, hedge against localized disruptions, and respond more flexibly to currency or logistics shocks. In practical terms, supply chain resilience is becoming a competitive differentiator rather than a back-office function.
Competitive Dynamics and Strategic Positioning
The industry's competitive field is shaped by a mix of long-established brewing specialists, large regional manufacturers, and smaller innovators pursuing distinctive flavor profiles or niche market positions. The largest producers combine scale, export capability, and multi-plant infrastructure, while others compete through premium positioning, regional brand equity, or specialized product development. This structure supports a market where share is contestable but not easily overturned, because scale advantages in brewing capacity, distribution relationships, and ingredient procurement are difficult to replicate quickly.
Several strategic postures are visible across the leading set. One is geographic expansion through local production, which reduces shipping costs, shortens lead times, and signals commitment to a market. A second is premiumization through naturally brewed positioning and taste differentiation, which targets consumers and foodservice buyers willing to pay for perceived quality and culinary authenticity. A third is portfolio breadth across light, dark, and specialty variants, allowing a manufacturer to serve multiple culinary applications and capture demand across different cooking traditions. A fourth is innovation in small-batch, distinctive flavor profiles that can command premium pricing and build loyal following among chefs, specialty retailers, and consumer enthusiasts.
Recent operational developments illustrate how these strategies are playing out in practice. A major Japanese producer with significant U.S. manufacturing presence has been progressing a new American production facility, with first shipments anticipated in the fall of 2026 after groundwork laid in 2024. This kind of investment signals confidence in sustained demand and a desire to deepen local supply capability rather than relying solely on export flows. Meanwhile, in the Chinese market context, leading domestic brands have continued to showcase light, dark, and standard varieties through major trade platforms, reinforcing the importance of category breadth and export visibility for manufacturers seeking broader international reach.
Market structure appears likely to evolve along two parallel paths. Consolidation pressure will persist where scale economics, distribution leverage, and sourcing advantages favor larger operators, especially in price-competitive segments and high-volume foodservice channels. At the same time, fragmentation will remain viable in premium, regional, and specialty segments where authenticity, craft narrative, and differentiated flavor profiles create defensible positions. New entrants that can combine a clear brand story with disciplined production quality, or that can serve an underserved application such as a specific culinary format or a clean-label requirement, can still gain traction without directly challenging the largest incumbents on volume alone.
Forward-Looking Trends for the 2026 to 2032 Window
Looking ahead, several trends are likely to shape how growth is captured and where value accrues. These trends are grounded in current market data, recent operational moves, and the regulatory and demand environment already in motion.
PW Consulting
Local Production and Regional Capacity Expansion
As demand broadens beyond traditional strongholds, the economics of long-distance export versus local manufacturing become more consequential. Additional production capacity in key markets can improve responsiveness, reduce logistics exposure, and support labeling or formulation adaptation to regional requirements. Over the next several years, more manufacturers are likely to evaluate where to place capacity based on demand density, input availability, and regulatory clarity. The strategic implication is that presence in a market will increasingly be judged not just by brand recognition but by supply reliability and local compliance readiness.
Premiumization Paired with Functional Positioning
Premium products will continue to grow in relevance, but premiumization alone will not define success. The most durable growth will likely come from products that combine authentic fermentation or distinctive flavor with practical benefits such as lower sodium, cleaner ingredient lists, or application-specific performance. This pairing allows manufacturers to address both consumer-facing premium demand and buyer-facing formulation needs. Brands that can communicate flavor quality while meeting functional expectations will have a stronger chance of commanding price resilience and repeat usage.
Regulatory Clarity as a Market Access Multiplier
Because regulatory requirements differ across markets, companies that proactively align product design and labeling with local rules can turn compliance into a market-entry advantage. In regions where nutritional labeling is not required, simpler packaging and broader claim flexibility may be available; in regions with stricter disclosure, early adaptation can prevent reformulation delays and protect brand consistency. Over time, the ability to navigate multiple regulatory regimes efficiently will become part of the competitive baseline for companies pursuing international distribution.
These trends carry uncertainty. Cost volatility in soybean supply could compress margins for producers with less flexible sourcing or pricing strategies. Regulatory changes could shift faster than anticipated in some markets, altering labeling obligations or ingredient disclosure expectations. Consumer taste preferences may evolve toward lower-sodium or plant-forward alternatives, requiring manufacturers to innovate without diluting the category's core identity. Each of these risks is manageable with the right data, scenario planning, and operational agility.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with both flavor differentiation and operational resilience. That means evaluating whether portfolio breadth, premium positioning, or local production offers the best return in each target market, and ensuring that sourcing and facility strategy can absorb input cost variability without sacrificing consistency. For investors, the opportunity lies in identifying organizations that combine credible brand equity with scalable production and a clear regional expansion plan, while monitoring where margin exposure to raw material costs and regulatory complexity may create downside risk or require additional capital discipline. For procurement and foodservice buyers, the practical focus should be on supplier reliability, formulation consistency, and compliance alignment, since these factors increasingly determine whether a soy sauce supplier can support large-scale operations across multiple markets without disruption.
Access to detailed segmentation data, regional revenue splits, and granular competitive movement can sharpen each of these decisions. Broad market trajectories provide direction, but precise allocation decisions require clearer visibility into where growth concentrates, how share is shifting among product types, and which operational investments are likely to yield durable advantage. The full research report offers that level of detail, including segmented data, company-level developments, and market-access considerations that support tailored commercial planning.
The soy sauce market is entering a phase where growth is real, but competitive advantage will depend on how well organizations align innovation, compliance, and supply chain readiness with the specific markets and applications they choose to serve. Companies that treat the category as a strategic platform rather than a routine ingredient business are better positioned to convert steady industry expansion into defensible share and healthier margins.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oil Mist Separator Market: Why 5.3% CAGR and Asia Pacific Lead the 2032 Growth
By PW Consulting, 2026-09-21
Strategic Trajectories and Commercial Opportunities in the Global Oil Mist Separator Market
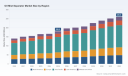
The global market for oil mist separators has entered a phase of measured but steady expansion, reflecting broader shifts in industrial air quality standards, manufacturing precision requirements, and energy efficiency mandates. Valued at approximately 140.5 million USD in 2020, the market climbed to 180.8 million USD by 2025, and is projected to reach 259.9 million USD by 2032. This trajectory translates to a compound annual growth rate of 5.3 percent across the forecast horizon, signaling a maturing yet increasingly dynamic sector. Growth is no longer driven solely by incremental equipment replacement; it is being reshaped by tighter emissions controls, smarter filtration architectures, and cross-regional industrial modernization programs. The market remains moderately concentrated, with a handful of established players capturing a dominant share of contract wins, technology patents, and regional distribution networks. This concentration underscores both the barrier to entry for newcomers and the strategic importance of partnerships, licensing, and targeted product modernization for mid-tier manufacturers. As industrial operators balance compliance obligations with productivity targets, the oil mist separator segment is evolving from a commoditized component category into a value-added system integration opportunity.
Mist Eliminator Market
Market Landscape and Core Challenges
Regulatory Pressure and Performance Verification
The industry is navigating a period where compliance and verification requirements are tightening across multiple jurisdictions. Without listing regional revenue splits or application-specific dollar figures, it is clear that manufacturing footprints in both mature and emerging economies are confronting stricter exposure limits for mineral oil aerosols and particulate matter. Occupational safety frameworks now mandate continuous monitoring approaches and defined time-weighted average thresholds for workplace air quality, forcing plant operators to treat filtration not as an optional add-on but as a baseline operational requirement. At the same time, engine and compressor standards are increasingly calling for uniform testing procedures that cover dust collection efficiency, dust capacity, and oil carry-over measurements. These requirements create a dual challenge: manufacturers must demonstrate consistent performance under standardized test conditions, while end users must integrate separator systems that meet verifiable benchmarks rather than nominal specifications.
Technical Complexity Versus Installation Practicality
A second structural challenge lies in balancing filtration performance with physical integration constraints. Oil mist separators are deployed across diverse machine environments, from compact machining centers to large compressor halls, and each deployment presents distinct airflow, space, and maintenance profiles. Mounted configurations dominate volume applications where direct integration with existing equipment is preferred, while standalone units address centralized extraction and facility-wide air cleaning. The challenge for designers is to maintain high capture efficiency without imposing excessive pressure drops, frequent media replacement cycles, or complex ductwork modifications. Operators increasingly favor solutions that can be retrofitted into legacy lines without extensive downtime, yet they also demand filtration performance that aligns with precision tolerances in food-grade, medical, or high-finish machining contexts. Bridging this gap requires material engineering, flow optimization, and service-friendly filter media designs to advance in tandem.
Consolidating Competition and the Cost of Differentiation
A third challenge is the competitive dynamic shaped by market concentration. When a limited group of firms accounts for more than half of total market activity, incumbents benefit from established distribution channels, reference installations, and long-term service contracts. New entrants or smaller regional manufacturers must therefore compete on niche performance attributes, localized support, or total cost of ownership rather than price alone. This environment rewards companies that can articulate measurable operational savings, energy reduction, or maintenance interval extension, while penalizing those that compete purely on hardware cost. As procurement teams become more technical in their evaluation criteria, the burden on suppliers to provide verifiable performance data, installation guidance, and lifecycle cost models grows heavier.
Key Drivers Shaping Market Evolution
Technology Innovation and Energy-Conscious Filtration Design
Innovation in filtration media, airflow control, and system intelligence is a leading catalyst for change. Recent product introductions highlight a clear shift toward energy-aware extraction systems and higher-precision filter units designed for demanding machining environments. Smart energy-saving devices integrated into oil mist extraction systems are gaining traction, reflecting operational priorities around electricity usage, fan load optimization, and variable airflow demand. In parallel, advanced filter units built for high-precision machining environments emphasize finer aerosol capture, stable performance under variable load conditions, and simplified media replacement. These developments matter because they connect directly to two persistent operator concerns: running costs and process consistency. When a separator can reduce parasitic energy consumption while maintaining capture efficiency, the value proposition extends beyond compliance into operational economics. Manufacturers that embed control logic, condition monitoring, or modular media architectures into their offerings are positioning filtration as an active system component rather than a passive accessory.
Regulatory and Standards Evolution
Policy and standardization activity continues to shape purchasing behavior and engineering requirements. Compressed air quality classifications that define strict oil aerosol limits for the highest cleanliness tiers are reinforcing demand in food-grade, pharmaceutical, and precision industrial applications, where even minimal contamination can affect product integrity or process reliability. At the same time, occupational safety expectations for mineral oil mist exposure are pushing facility managers to adopt continuous monitoring and better containment strategies, particularly in environments where multiple machines contribute to cumulative aerosol loads. In parallel, industrial emissions frameworks in major markets are tightening limits on volatile organic compounds and particulate matter from manufacturing facilities, which indirectly accelerates replacement cycles and upgrades for older separator installations. The net effect is a market where regulations do not merely constrain operations; they actively redirect capital toward more capable filtration and air cleaning architectures. Companies that can map their product capabilities to specific regulatory benchmarks, and document compliance through standardized testing, gain a meaningful advantage in specification-driven procurement processes.
Shifts in End-User Behavior and Operational Priorities
Demand-side behavior is changing as plant operators look beyond immediate compliance and evaluate filtration through the lens of productivity, worker comfort, and equipment longevity. Oil mist that escapes containment can affect visibility, housekeeping frequency, coolant loss, and downstream component reliability, all of which influence total operating cost. As a result, purchasing decisions are increasingly influenced by facility managers and engineering teams who weigh filtration performance alongside ease of maintenance, noise reduction, and integration with existing extraction infrastructure. The emphasis on fog-free environments, clearer workstation conditions, and reduced cleaning cycles reflects a broader operational mindset: air quality is not an isolated environmental metric but a contributor to throughput and labor efficiency. This behavioral shift creates opportunities for suppliers who can present separator systems as part of a holistic air management strategy rather than as standalone compliance devices. Case documentation and field references are becoming more influential in this context, since they translate technical specifications into observable operational outcomes.
Supply Chain Structure and Cost Considerations
Cost structures in the filtration sector are being influenced by material availability, manufacturing precision, and the economics of distribution across regions. High-performance filter media, housing materials, and sealing components must meet durability expectations under continuous operation, while suppliers also face pressure to keep lead times predictable and service parts accessible. In a moderately concentrated market, cost leadership is often less about unit price and more about lifecycle economics: how often media must be replaced, how much pressure loss accumulates over time, and how easily a unit can be serviced without specialized labor. These factors are especially relevant as operators reassess capital expenditure against operating expenditure, particularly in facilities facing rising energy costs or tighter maintenance windows. Suppliers that can standardize core assemblies while offering application-specific customizations tend to manage cost and flexibility more effectively than those pursuing fully bespoke designs for every project. This balance between standardization and adaptation is becoming a defining feature of competitive cost positioning.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Leading Strategies
Dominant Players and Strategic Positioning
The competitive field features a mix of long-established manufacturers and specialized filtration providers, each leveraging distinct strengths in engineering heritage, application coverage, and service ecosystems. Companies with multi-decade experience in oil mist collectors and workplace air cleaning solutions have built brand recognition around reliability, broad application familiarity, and continued product iteration. Their strategy often centers on maintaining a wide reference base, expanding into adjacent air quality applications, and reinforcing regional service presence. Other firms emphasize industrial mist collection for compressed air and machine tool environments, using application-specific engineering and standardized performance documentation to win specification-driven projects. A further group focuses on advanced oil mist elimination and industrial air purification, differentiating through modular product families, precision filtration architectures, and integration with broader air management systems.
Additional suppliers contribute to the landscape by targeting specific operational niches. Some specialize in oil mist separation for manufacturing plant compressor and turbine systems, where reliability under continuous duty and resistance to oil carry-over are critical. Others concentrate on ecological and application-tailored separator designs for rotating machines and turbines, positioning around sustainability messaging and customized extraction solutions. There is also a cohort of providers that emphasize universal separator coverage across wide engine power ranges or offer industrial mist separators and collectors optimized for machine tool use. Together, these players illustrate a market where differentiation comes from application alignment, engineering documentation, and the ability to support both centralized and distributed installation strategies.
Oil Water Separator Market
Differentiation Levers in a Concentrated Market
In a market where a small group of firms holds a substantial share, differentiation tends to emerge through several recurring levers. First, product intelligence and energy optimization are increasingly central. The introduction of smart energy-saving devices for extraction systems demonstrates how incremental controls can reduce operating burden while preserving capture performance. Second, application specialization matters. Filter units developed for high-precision machining environments reflect an understanding that contamination limits and process tolerances vary significantly by sector, and that generic solutions may not satisfy the strictest cleanliness classifications. Third, ecosystem support and reference building influence procurement confidence. Trade show participation, case study dissemination, and documented installations help translate technical claims into practical credibility. Fourth, standardization of performance verification is becoming a competitive asset. As testing procedures for inlet air cleaning equipment become more uniform and compressor or engine standards increasingly specify measurement approaches for collection efficiency and oil carry-over, suppliers that proactively align with these protocols gain visibility in specification reviews.
Evolution of the Competitive Structure
Looking at recent developments, the market appears to be moving through a phase of selective consolidation in capability rather than purely in corporate structure. Established players are expanding their portfolios through product line extensions, energy-efficiency features, and targeted applications, while also strengthening visibility through exhibitions, case publications, and regional engagement. At the same time, specialized manufacturers continue to compete by focusing on particular machine types, precision cleanliness requirements, or custom extraction configurations. This creates a landscape where scale advantages coexist with niche strength. New entrants face the challenge of overcoming reference inertia, but they can still gain traction by addressing underserved machine configurations, offering more flexible integration options, or providing superior service and documentation. The likely trajectory is not a wholesale shakeout, but a gradual stratification in which broad-line suppliers dominate volume segments and specialized firms secure positions in high-value or technically demanding applications. For decision makers, this means vendor selection is increasingly about matching system architecture to operational profile rather than choosing from a single category of equivalent products.
Forward Trends and Commercial Implications
Smarter, Energy-Optimized Filtration Systems
Over the next three to five years, one of the most consequential trends will be the deepening integration of energy optimization and control logic into oil mist separation systems. As operating cost sensitivity rises and extraction equipment runs for longer periods across multiple shifts, even modest reductions in fan load or airflow waste can create meaningful savings. Systems that adapt output to actual contamination levels, support easier servicing, and provide clearer performance feedback will be better positioned than static, fixed-performance units. Commercial opportunity lies in bundling filtration hardware with controls, service contracts, and documentation that simplify lifecycle management for plant teams. The upside is real, but it depends on manufacturers delivering measurable savings in field conditions, not just in laboratory benchmarks. If promised energy benefits fail to materialize consistently, buyer confidence in smart features may erode.
Stricter Compliance and Cleanliness-Driven Demand
A second trend is the continuing alignment of separator demand with stricter cleanliness and exposure expectations. As occupational exposure limits, compressed air quality classifications, and industrial emissions expectations become more rigorously enforced or more widely adopted in procurement specifications, facilities will face stronger incentives to replace aging equipment and upgrade filtration performance. This creates a sustained upgrade cycle in sectors where product integrity, worker exposure, or emissions reporting carry direct financial or regulatory consequences. The commercial opportunity is in providing verifiable cleanliness performance, standardized test alignment, and documentation that procurement teams can use in specification and audit processes. The uncertainty is that regulatory implementation pace can differ by region and by facility type, which may create uneven demand timing. Suppliers that assume uniform acceleration across all markets risk misjudging where near-term investment will actually appear.
Service-Led Models and Regional Expansion
A third trend is the shift toward service-oriented commercial models and more deliberate regional execution. As installed bases grow and equipment ages, maintenance intervals, media availability, and local technical support will increasingly influence repeat purchasing and system longevity. Companies that build reliable parts supply, clear replacement procedures, and application-specific guidance can convert initial sales into long-term relationships. Regional expansion also remains relevant, especially where industrial modernization, machining capacity growth, and compressor utilization are increasing. Here, success depends on more than product availability; it requires localized engineering support, understandable installation guidance, and a credible service response timeframe. The opportunity is in building trusted regional presence and repeatable deployment models. The risk is that overextension into too many territories without adequate support infrastructure can dilute reliability and weaken the performance reputation that underpins premium positioning.
Actionable Insights for Decision Makers
For Manufacturers and System Suppliers
Differentiation should be anchored in verifiable performance and operational economics rather than product claims alone. Prioritize control features and filtration designs that reduce energy burden and simplify maintenance, then document those benefits in real installation contexts. Align product language with the testing and cleanliness expectations that procurement teams increasingly reference, and build a portfolio that balances standardized assemblies with application-specific adaptations. Invest in reference deployments and case documentation, because credibility in this market is often earned through observable outcomes in actual facilities. Finally, treat service and parts availability as part of the product, since lifecycle reliability frequently determines whether a sale becomes a repeat contract.
For Investors and Corporate Strategists
The market’s moderate concentration and steady growth profile suggest that value creation will come from companies that can combine technical credibility with cost-aware design and strong service execution. Evaluate exposure not only by installed unit volume but by how well a supplier is positioned for the trends shaping the next decade: energy optimization, stricter clean air expectations, and service-led retention. Watch for firms that can demonstrate consistent field performance, clear compliance alignment, and disciplined regional expansion rather than broad but shallow market claims. Be mindful that demand timing may vary by region and by application, so portfolio resilience matters more than betting on a single growth narrative.
For Procurement Teams and End-User Operators
Selection criteria should extend beyond upfront equipment cost to include pressure drop behavior over time, media replacement frequency, service accessibility, and evidence of compliance with relevant exposure or cleanliness expectations. Where precision, food-grade, or auditoried environments are involved, prioritize suppliers that can provide standardized performance documentation and clear installation guidance. Consider total operational impact, including worker visibility, housekeeping burden, coolant retention, and integration with existing extraction infrastructure. When evaluating newer smart or energy-saving features, request field-oriented performance evidence and confirm that control logic will not add complexity without measurable operational benefit. A disciplined evaluation framework reduces the risk of purchasing a nominally compliant system that creates higher maintenance or energy costs downstream.
Conclusion
The oil mist separator market is advancing along a path defined by tighter compliance expectations, smarter filtration design, and a competitive field that rewards both scale and application focus. Steady growth supported by industrial modernization and cleaner air requirements provides a durable backdrop, but the real commercial differentiation will come from how well suppliers translate performance, energy efficiency, and service reliability into measurable operational value. For manufacturers, the opportunity lies in credible innovation and lifecycle economics. For investors, it lies in backing players with disciplined execution and alignment to the compliance and efficiency trends ahead. For operators, it lies in choosing systems that perform under real conditions, not just in specification sheets. Detailed segmentation data, regional demand patterns, and customized scenario analysis can sharpen these decisions further, and organizations seeking that level of granularity are well positioned to explore the full research depth available on PW Consulting for this market.
For detailed analysis of this topic, please visit the official page: Oil Mist Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Clinical Mass Spectrometry Market: Why 9.35% CAGR and LC-MS Dominance Redefine Growth
By PW Consulting, 2026-09-21
The Clinical Mass Spectrometry Market: Strategic Trends and Commercial Opportunities Through 2032
Market Status and Core Challenges
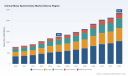
The clinical mass spectrometry market has transitioned from a specialized scientific instrument segment into a mainstream clinical diagnostic modality over the past half-decade. Market valuation moved from approximately 785.0 million USD in 2020 to 1260.0 million USD in 2025, representing a compound annual growth rate of roughly 8.2 percent across the historical window. Current trajectory models indicate expansion to 1346.99 million USD in 2026 and continued acceleration toward 2360.0 million USD by 2032, with a forecast-period CAGR of 9.35 percent. This growth profile reflects a market that has crossed the chasm from research-grade adoption into routine clinical workflows, driven by the superior specificity and multiplex capability of mass-based quantification compared with traditional immunoassays.
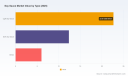
The regional distribution of demand reveals a mature anchor in North America, which accounts for the largest revenue share at 562.22 million USD, followed by Europe at 319.65 million USD and Asia Pacific at 234.95 million USD. Latin America and the Middle East and Africa together represent a combined base of 143.18 million USD, signaling early-stage penetration with substantial room for expansion as healthcare infrastructure and reimbursement frameworks mature. By technology type, liquid chromatography-mass spectrometry dominates installed value at 801.16 million USD, while gas chromatography-mass spectrometry holds 212.76 million USD and matrix-assisted laser desorption/ionization time-of-flight contributes 198.12 million USD, with other modalities rounding out the remainder. Across applications, therapeutic drug monitoring represents the largest clinical use case at 555.11 million USD, newborn screening follows at 315.55 million USD, and hormonal testing, hemoglobin testing, and other indications collectively account for the balance. The market remains moderately concentrated, with the top three players capturing 52.0 percent of revenue and the top five holding 62.0 percent, a structure that preserves room for differentiated entrants while rewarding scale incumbents.
Despite the favorable growth backdrop, the industry faces three structural challenges that will define capital allocation and product strategy in the near term.
Challenge 1: The Complexity-Reimbursement Gap
Mass spectrometry delivers analytical performance that routine immunoassays cannot match, but that performance often carries operational complexity that limits throughput and increases per-test cost. Many clinical laboratories still treat mass spectrometry as a specialized, limited-access service requiring highly trained operators, dedicated sample preparation, and careful method validation. When reimbursement structures do not commensurately reward this complexity, laboratories hesitate to expand mass-based panels, and manufacturers face pressure to simplify platforms without sacrificing analytical rigor. The gap between what the technology can do and what payers and laboratory economics will sustain remains the central friction point in market expansion.
MALDI-TOF Mass Spectrometer Market
Challenge 2: Regulatory Fragmentation Across Indications and Jurisdictions
Clinical mass spectrometry spans diverse indications, each with distinct evidentiary requirements, validation expectations, and regulatory pathways. A system cleared for microorganism identification does not automatically translate into a cleared workflow for therapeutic drug monitoring or hormone quantification. This fragmentation slows portfolio scale-up, increases time-to-market for new assays, and creates uneven competitive advantages across regions. Companies that can navigate a multi-indication, multi-jurisdiction regulatory landscape more efficiently than peers will capture disproportionate share in high-value applications.
Challenge 3: Workflow Integration and Standardization
As clinical mass spectrometry moves from reference laboratories into decentralized hospital and multi-site networks, standardization becomes a binding constraint. Variability in sample handling, chromatography conditions, ionization performance, and data interpretation can undermine comparability across sites and erode confidence in results. The market is increasingly rewarding vendors that offer integrated hardware-software-reagent systems, simplified operator interfaces, and traceable quality controls, while penalizing those that require extensive in-house method development for routine testing.
Key Drivers of Market Change
Technological Innovation and the Push Toward Automation
The most consequential technical shift is the move from manually intensive, laboratory-developed workflows toward automated, integrated platforms that reduce operator dependence and improve reproducibility. Quantitative software suites purpose-built for clinical analysis now accompany single quadrupole and tandem mass spectrometry systems, enabling biomarker verification, precision medicine workflows, and routine quantification with less hands-on intervention. In microorganism identification, software and sample handling innovations are compressing turnaround time and improving the reliability of organism differentiation directly from clinical specimens. These advances directly address the complexity-reimbursement gap by making high-performance mass spectrometry more compatible with high-volume clinical operations.
A concrete illustration of this trajectory is the broad expansion of reagent and assay menus on automated clinical mass spectrometry platforms. Recent milestones include CE Mark approval for an antibiotics drug monitoring reagent pack that broadens an automated mass spectrometry menu to 39 tests covering immunosuppressants, antibiotics, steroids, and vitamin D metabolites. In parallel, regulatory classification progress has lowered operational barriers: steroid assays for mass spectrometry have been classified as moderate complexity under CLIA, which expands the population of laboratories and operators able to run these tests without specialized staffing. Together, these developments demonstrate how regulatory easing and workflow automation can unlock routine clinical access for assays that previously required limited, expert-run environments.
Regulatory and Reimbursement Environment as an Accelerant and a Gatekeeper
Regulatory and coding dynamics are reshaping the commercial landscape for clinical mass spectrometry on two fronts. On the access side, moderate-complexity classification for selected mass spectrometry assays is expanding the addressable laboratory base by removing the requirement for highly specialized operators in routine settings. On the coding side, revisions to CPT codes for mass spectrometry-based testing are influencing reimbursement mechanics. Updated codes such as CPT 82542 for quantitative column chromatography/mass spectrometry reflect ongoing efforts to align coding with current practice, while reimbursement continues to vary by payer and analyte. For manufacturers and laboratory customers alike, the direction of travel matters: clearer, more predictable coding and broader complexity allowances reduce adoption friction, but analyte-specific reimbursement variability still demands careful health-economic justification for each test menu.
These dynamics also create a differentiated advantage for companies that pursue regulatory clearance proactively across multiple indications and regions. A vendor that secures clearance for therapeutic drug monitoring reagents, hormone panels, and microorganism identification systems in sequence can cross-sell across clinical departments, increase installed-base stickiness, and establish reference standards that competitors must match. The regulatory environment is thus not merely a compliance backdrop; it is increasingly a competitive moat.
Demand-Side Shifts in Clinical Practice and Patient Management
Clinical demand is being reshaped by three interrelated forces. First, precision medicine workflows are increasing the need for accurate quantification of biomarkers, drug concentrations, and metabolic markers that mass spectrometry is uniquely suited to measure. Second, the management of complex medication regimens, including antibiotics and immunosuppressants, is driving sustained demand for therapeutic drug monitoring in hospital and specialty settings. Third, early detection programs and screening protocols, including newborn screening, continue to provide a stable and high-volume demand base that rewards throughput, reliability, and standardized workflows.
At the same time, healthcare delivery is shifting toward consolidated networks and standardized testing protocols. Larger laboratory systems are seeking platforms that can support multiple indications on a single instrument footprint, reduce training burden, and provide traceable quality controls across sites. This demand-side consolidation is pushing vendors toward modular, software-centric architectures and multi-test menus, and away from single-application, laboratory-developed approaches that are difficult to scale across a health system.
PW Consulting
Supply Chain and Cost Structure Evolution
Cost structure is becoming a more explicit competitive variable as installed bases grow and laboratories compare total cost of ownership across platforms. The economics of clinical mass spectrometry depend not only on instrument price but on reagent costs, consumables durability, calibration frequency, service coverage, and the labor required to maintain compliance. Vendors that can reduce per-test operating cost through automation, longer calibration intervals, integrated reagents, and remote diagnostics are increasingly favored in procurement decisions, particularly in cost-sensitive environments.
Supply chain resilience is also under scrutiny. Platforms that reduce dependence on highly customized sample preparation steps and that offer standardized reagent packs tend to be more resilient to staffing volatility and consumable supply disruptions. As a result, the market is rewarding designs that prioritize workflow robustness and predictable consumable economics over maximal analytical flexibility alone.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
Thermo Fisher Scientific continues to anchor its strategy in quantitative clinical analysis and precision medicine workflows. Its LCQUAN quantitative software paired with ISQ EM/EC single quadrupole LC-MS systems is positioned for quantitative clinical analysis, biomarker verification, and precision medicine applications. The strategic emphasis is on software-driven quantification and a platform that supports accurate routine workflows and biomarker work, appealing to laboratories that want a credible quantitative foundation with room to extend into precision medicine use cases.
Waters Corporation leans into therapeutic drug monitoring and biomarker applications with its MassTrak LC-MS/MS platform and related solutions. A distinguishing element is the availability of FDA-cleared systems for TDM and biomarker workflows, which directly addresses the regulatory-access driver in the market. This clearance-centric approach is strategically important because it shortens the path for laboratories seeking validated, regulatorily recognized workflows rather than building laboratory-developed methods from scratch.
Bruker Daltonics differentiates through microorganism identification and differentiation, with MBT Compass HT CA software, MBT FAST Shuttle US IVD, and clinical microorganism mass spectrometry systems. The FDA clearance of its microorganism identification and differentiation system as Class II under special controls formalizes a regulatory pathway and supports adoption in clinical microbiology workflows. Bruker's positioning reflects the value of a focused application with clear clinical identity, which can be expanded within microbiology departments and integrated with broader laboratory information systems.
Roche Diagnostics International AG is pursuing a broad multi-indication IVD strategy on an automated clinical mass spectrometry platform. Its cobas Mass Spec solution with Ionify reagent packs spans therapeutic drug monitoring for antibiotics, steroid hormones, and vitamin D metabolites, supported by the Cobas i601 analyzer and an expanding IVD menu. The strategic signal is clear: Roche is using automation, a wide test menu, and regulatory milestones to position mass spectrometry as a routine clinical workhorse rather than a niche specialty tool.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three vectors. First, consolidation pressure is rising among scale incumbents that can cross-sell across applications and leverage installed bases to lower service and consumable costs. The top-three concentration near 52.0 percent and top-five near 62.0 percent indicates that leading players already hold meaningful share, but the remaining 38.0 percent is large enough to support specialized entrants with differentiated applications or regional strengths.
Second, differentiation is shifting from raw analytical capability toward integrated, regulatory-cleared, workflow-friendly solutions. In this environment, a vendor's ability to deliver cleared assays, simplified operator experience, and multi-test menus on a single platform is becoming as important as instrument performance alone. This favors companies that can orchestrate hardware, software, reagents, and regulatory clearance as a unified clinical solution.
Third, new entrants and regional players are finding openings in specific applications or geographies. Lower-concentration regions such as Latin America and the Middle East and Africa present early-stage demand where localized service, pricing, and workflow simplicity can be decisive. Similarly, application niches with clear clinical identity and regulatory clarity, such as microorganism identification or antibiotic TDM, can support focused entrants who build depth rather than breadth.
Future Trends and Commercial Opportunities
Trend 1: Routine Clinical Access Will Expand as Complexity Barriers Lower
Over the next three to five years, regulatory classification progress and automation will continue to broaden the laboratory base able to run mass spectrometry assays. Moderate-complexity classification for selected steroid and other assays is an early indicator of a broader shift toward routine access. The commercial opportunity lies in panels and platforms that can scale across diverse laboratory types without requiring specialized operators, supported by clear coding pathways and defensible health economics. Vendors and laboratory customers that invest early in these accessible workflows will capture utilization before the market consolidates around a smaller set of standardized platforms.
Trend 2: Multi-Indication, Software-Centric Platforms Will Become the Default Architecture
Healthcare systems increasingly prefer platforms that support multiple indications on one footprint with consistent software, quality controls, and data management. This favors architectures that separate application expansion from hardware replacement, allowing laboratories to add tests through software and reagent updates rather than capital upgrades. The commercial opportunity is for vendors that can package multi-test menus, traceable QC, and integration with laboratory information workflows as a cohesive solution, while laboratory buyers can reduce capital intensity and standardize operations across departments.
Worldwide High Resolution Mass Spectrometry System Market
Trend 3: Therapeutic Drug Monitoring and Steroid/Immunosuppressant Panels Will Remain Central Growth Engines
Therapeutic drug monitoring is already the largest application segment, and the strategic rationale is strong: managing antibiotics, immunosuppressants, and steroid-related markers requires precise quantification with clinical turnaround that mass spectrometry can provide. As automated reagent packs and cleared workflows expand, these panels can move from specialized use into more routine hospital and specialty settings. The commercial opportunity lies in full-panel strategies that bundle antibiotics, steroids, immunosuppressants, and vitamin D metabolites around a single platform, creating cross-department utilization and stronger laboratory retention.
Risks and Uncertainties
Several risks temper the outlook. Reimbursement variability by payer and analyte can slow adoption for specific tests even when analytical performance is strong. Regulatory timelines and classification outcomes remain uncertain across indications and regions, meaning portfolios that depend on a single clearance event face concentration risk. In addition, if automation and software do not deliver the expected reduction in operating cost and training burden, the complexity-reimbursement gap will persist and limit throughput gains. Finally, coding and reimbursement updates can shift the economics of specific assays, requiring continuous health-economic monitoring rather than one-time justification.
Strategic Recommendations for Decision Makers
For Manufacturers and Platform Providers
- Prioritize integrated, software-centric architectures that allow multi-test expansion without hardware replacement, and pair them with cleared or clearly regulatory-tracked workflows for high-value indications such as TDM, steroid panels, and microorganism identification.
- Design for operational simplicity and total cost of ownership, not just analytical performance. Reduce training burden, automate sample preparation where feasible, and offer predictable reagent and calibration economics to win procurement decisions in consolidated laboratory networks.
- Build multi-indication, multi-region regulatory strategies in advance. Early and sequential clearances across applications and jurisdictions can become a defensible competitive moat and accelerate cross-sell within health systems.
For Investors and Strategic Partners
- Focus on companies that convert regulatory and workflow advantages into installed-base growth and recurring consumable revenue, particularly where moderate-complexity classification, cleared assays, and broad test menus expand the addressable laboratory base.
- Evaluate exposure to reimbursement and coding risk at the analyte level. Investments tied to panels with clearer coding pathways and stronger health-economic support are less exposed to reimbursement variability than narrow, single-test offerings.
- Watch for consolidation opportunities in regional markets where service capability, pricing, and workflow simplicity matter more than cutting-edge analytical novelty. Localized execution can be a durable advantage in earlier-stage regions.
For Procurement and Laboratory Decision Makers
- Evaluate platforms based on total cost of ownership, regulatory status of assays, and the ability to standardize across multiple indications and sites, rather than instrument specifications alone. A platform that supports several cleared panels with integrated QC and data management can reduce operational risk and capital intensity.
- Assess training burden, staffing resilience, and service coverage as part of the sourcing decision. Workflows that lower dependency on specialized operators and offer predictable maintenance are better suited to high-throughput environments and decentralized networks.
- Monitor coding and reimbursement developments for the specific analytes you plan to run, and align test menu expansion with clear reimbursement pathways and health-economic justification to avoid adoption friction later.
The clinical mass spectrometry market is moving from specialist adoption to routine clinical integration, and the winners will be those who align analytical performance with workflow simplicity, regulatory clarity, and defensible economics. For decision makers who need granular segmentation, region-by-region dynamics, per-application growth drivers, and customized strategic scenarios, a detailed research report can provide the depth required to translate these trends into concrete plans. To access the full segmentation breakdown, competitive benchmarking, and tailored recommendations, request the complete PW Consulting report on the Clinical Mass Spectrometry Market.
For detailed analysis of this topic, please visit the official page: Clinical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tax Software Market: Why Cloud Adoption and 9% CAGR Shift the Competitive Landscape
By PW Consulting, 2026-09-21
Navigating the Tax Software Market: Strategic Trends and Commercial Opportunities
The global tax software market is undergoing a structural transformation driven by technological advancement, regulatory complexity, and shifting user expectations. Valued at approximately $17.6 billion in 2025, the market has expanded steadily from $10.2 billion in 2020, reflecting a compound annual growth rate of 9.0 percent through 2032. By the end of the forecast horizon, total market revenue is projected to approach $32.3 billion, underscoring sustained institutional and consumer demand for digital tax solutions. This growth trajectory is not merely a function of population expansion or inflation; it represents a fundamental shift in how tax compliance, reporting, and advisory services are delivered. Organizations that understand the underlying drivers, competitive dynamics, and emerging friction points will be best positioned to capture value in the coming years.
Market Landscape and Core Challenges
The market's expansion has been broad-based, with cloud-based solutions now representing the largest share of revenue, reflecting a decisive migration away from legacy on-premises deployments. Individual tax filing continues to anchor volume, while business and corporate tax management segments contribute meaningful but more specialized revenue streams. Geographically, adoption patterns vary significantly, with mature markets showing high penetration and emerging regions accelerating digital onboarding as regulatory frameworks modernize and internet infrastructure improves.
Despite the favorable growth backdrop, the industry faces several structural challenges that will shape competitive outcomes over the next five years. First, regulatory fragmentation and compliance velocity are intensifying. Tax authorities across jurisdictions are updating filing formats, validation rules, and electronic submission requirements at an accelerating pace. Software vendors must continuously align their platforms with IRS Modernized e-File standards, state-level franchise tax mandates, and error-checking protocols. The operational burden of maintaining compliance across multiple jurisdictions creates a high barrier to entry and rewards vendors with robust regulatory monitoring and rapid update cycles.
Second, user experience expectations are rising faster than legacy architectures can accommodate. Both individual filers and professional preparers increasingly expect intuitive interfaces, guided workflows, automated data ingestion, and real-time error feedback. Platforms that rely on manual form entry or fragmented dataflows risk losing adoption to solutions that reduce cognitive load and accelerate filing turnaround. This shift is particularly pronounced among self-employed professionals and small business owners who prioritize simplicity and predictable pricing.
Third, cost structure pressures are reshaping procurement decisions. Professional-grade tax software typically carries annual licensing costs in the range of $700 to $1,275 for multi-user access, a meaningful expense for smaller firms and independent preparers. While these investments deliver compliance assurance and workflow efficiency, margins remain sensitive to pricing models, update frequency, and the perceived value of advanced features. Vendors must balance feature richness with affordability, particularly as free or low-cost guided filing options expand for eligible taxpayers and raise expectations for baseline functionality across the market.
These challenges intersect at a critical inflection point: the market is moving from a compliance-centric model toward an experience- and outcomes-centric model. The winners will be those that convert regulatory complexity into simplified user journeys, maintain update reliability at scale, and deliver clear return on investment for both professional firms and end users.
Key Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand and redefining value propositions across the tax software ecosystem.
Technological Innovation and Workflow Automation
Cloud-native architectures, automated form population, and integration with financial data sources are reducing manual effort and error rates. Guided preparation workflows, predictive error checks, and rapid e-filing feedback loops are becoming table stakes rather than differentiators. For professional preparers, annual software updates that incorporate new tax laws, form revisions, and validation enhancements are essential to maintaining throughput and compliance accuracy. The release cadence and update transparency of leading platforms directly influence user retention and referral momentum within accounting and tax practices.
Policy and Regulatory Environment
Regulatory modernization is both a constraint and a catalyst. Tax authorities are progressively mandating electronic submissions, enhanced error validation, and structured data formats to improve processing efficiency and reduce rejection rates. Providers must demonstrate compliance with assurance testing systems and maintain approved status to operate within official filing channels. At the same time, tiered access models, such as no-cost guided preparation for eligible income brackets, expand the addressable user base while pressuring vendors to offer clear differentiation for premium features. The net effect is a more standardized compliance baseline, with competitive advantage shifting toward usability, advisory extensions, and multi-jurisdiction coverage.
Demand-Side Behavior Shifts
End users are increasingly treating tax software as an annual operating tool rather than a one-time filing utility. Individuals and small business owners value continuity, data portability, and time savings. Professional firms seek platforms that scale across seasons, support diverse client profiles, and integrate with broader practice management workflows. The preference for cloud delivery amplifies these expectations by enabling remote access, collaborative preparation, and centralized document management. As a result, switching costs are rising for users who have invested in historical data, trained workflows, and integrated ecosystems, favoring vendors that can deepen lifetime value through reliability and extensibility.
Cost Structure and Procurement Dynamics
The economics of tax software procurement are evolving as firms weigh licensing fees against labor costs, error remediation, and seasonal capacity constraints. Multi-user access models, update subscriptions, and support expectations shape total cost of ownership. For smaller practices, predictable annual pricing and straightforward update processes can be decisive, while larger firms prioritize scalability, role-based access, and audit-ready documentation. The market is gradually rewarding vendors that offer transparent pricing, efficient update delivery, and demonstrable time savings, particularly in environments where preparer labor remains a significant cost driver.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core of established vendors alongside a long tail of specialized providers serving distinct user segments. Intuit maintains a prominent position in the individual and self-employed segments, leveraging broad brand recognition, guided filing experiences, and a wide distribution footprint. H&R Block complements this landscape with a strong retail and digital presence, emphasizing accessible filing pathways and small business support. In the professional segment, Wolters Kluwer and Thomson Reuters serve accounting firms and tax practitioners with comprehensive preparation and practice management tools, focusing on regulatory update cadence, multi-form coverage, and workflow integration. Smaller but focused providers, including Drake Software, TaxAct, TaxSlayer, On-Line Taxes, CFS Tax Software, and Advanced Tax Solutions, differentiate through niche functionality, pricing clarity, or specialized professional workflows.
Accounting Software Market
Strategic differentiation is increasingly defined by three dimensions: compliance reliability, user experience, and ecosystem fit. Leading vendors invest heavily in maintaining approved e-filing status, delivering timely updates aligned with tax law changes, and providing error validation that reduces rework. Equally important is the design of preparation workflows, including guided prompts, document capture, and transcript integration that lower the skill threshold for complex filings. Finally, ecosystem fit matters as firms evaluate how well a platform aligns with existing practice management, client communication, and data storage preferences. Vendors that excel across all three dimensions tend to retain multi-year loyalty, while laggards face churn when competitors demonstrate faster update cycles or smoother user journeys.
The competitive landscape is evolving through both consolidation and fragmentation. Larger platforms are expanding their feature sets to serve adjacent user segments, blurring the line between individual and professional tools. At the same time, specialized providers continue to carve out defensible positions by focusing on specific form sets, regional compliance requirements, or price-sensitive professional markets. New entrants face a steep climb given the importance of approval status, historical data accumulation, and trusted update cycles, but they can gain traction by targeting underserved workflows, offering transparent pricing, or delivering superior onboarding experiences. Overall, the market is moving toward a bifurcated structure in which broad-platform leaders compete on scale and integration while focused providers compete on specificity and cost clarity.
PW Consulting
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, three trends are likely to determine where value concentrates and how competitive advantage is built.
Trend One: Compliance-as-a-Service and Continuous Update Models
Regulatory change will continue to accelerate, and the ability to deliver reliable, audited updates will become a core commercial asset. Platforms that institutionalize continuous compliance monitoring, automated test suites, and rapid deployment pipelines will reduce the risk of filing rejections and user friction. This trend creates opportunities for vendors to monetize update assurance, compliance documentation, and proactive regulatory alerts as part of premium service tiers. For buyers, the commercial implication is clearer visibility into total compliance risk and a stronger basis for vendor selection based on update reliability rather than feature count alone.
Trend Two: Guided Experiences and Tiered Offerings
User expectations will keep shifting toward guided, low-friction preparation, particularly among individuals and small business owners who value speed and certainty. Tiered pricing models will likely deepen, with no-cost or low-cost guided pathways for eligible users coexisting alongside premium advisory and comprehensive preparation features. Vendors that design seamless handoffs between free, guided, and professional-grade workflows can expand reach while preserving margin through upsell into data continuity, multi-state filing, and practice-oriented tools. The strategic opportunity lies in using guided experiences as an entry point that builds trust and historical data retention, then converting that engagement into recurring, higher-value relationships.
Worldwide Tax & Revenue Collection Software Market
Trend Three: Integration with Broader Financial Workflows
Tax preparation is increasingly viewed as one node within a larger financial operations workflow. Connections to accounting data, bank and payment records, payroll information, and document storage reduce duplicate entry and improve accuracy. Platforms that enable secure data exchange, standardized imports, and role-based collaboration will capture additional stickiness and reduce seasonal onboarding costs. This trend opens commercial pathways for vendors to position tax software as part of a year-round financial toolkit, rather than a seasonal utility, potentially expanding cross-sell opportunities and lengthening the customer lifecycle.
These trends carry inherent uncertainties. Regulatory decisions can alter filing requirements or reimbursement structures, shifting demand patterns unexpectedly. Rapid update cycles can strain support resources if error validation or form coverage is incomplete. Pricing pressure from free or low-cost guided options may compress margins in volume-driven segments. And integration ambitions can collide with data privacy expectations and interoperability constraints. Organizations that monitor these variables closely and maintain flexible product roadmaps will be better equipped to pivot as conditions evolve.
Strategic Actions for Decision Makers
The following recommendations are intended to help different stakeholder groups translate market dynamics into practical actions.
For Software Vendors and Product Leaders
Prioritize update reliability and compliance assurance as foundational differentiators. Invest in automated testing, transparent release notes, and rapid remediation processes to reduce filing rejections and user friction. Simultaneously, refine user journeys to lower the cognitive burden of complex forms, and design tiered offerings that preserve accessibility while creating clear paths to premium features. Evaluate integration points with accounting, document management, and client communication tools to strengthen year-round relevance and reduce seasonal switching risk.
For Investors and Strategic Allocators
Focus due diligence on vendors with durable update cycles, approved filing status, and evidence of user retention beyond a single season. Assess whether a company's pricing model aligns with the cost sensitivities of its target segment, and whether its roadmap anticipates regulatory complexity rather than reacting to it. Favor platforms demonstrating clear product-led growth signals, such as multi-year data continuity, expanding form coverage, and measurable time savings for professional preparers. Monitor consolidation potential among specialized providers whose workflows could be absorbed into broader platforms.
For Procurement Teams and Practice Owners
Evaluate tax software based on total compliance risk, update cadence, and workflow fit rather than headline pricing alone. Ask vendors how they validate form changes, how quickly updates reach users, and how error feedback is delivered during filing windows. Consider the long-term value of data portability, role-based access, and integration with existing practice tools. Where eligible, explore guided filing options to reduce preparation time for straightforward returns, while reserving professional-grade platforms for complex cases that require multi-state coverage, entity-level filings, or advisory extensions.
Market conditions in tax software are being reshaped by the intersection of regulatory modernization, cloud adoption, and rising user expectations. The organizations that thrive will be those that treat compliance reliability as a product foundation, design for sustained user engagement, and position their offerings within broader financial workflows. Detailed segmentation data, vendor scorecards, regional demand patterns, and customized strategic recommendations are available in the full research report, which provides the granular evidence base needed to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Tax Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Center Busway Market 2026: 9% CAGR Means the Competition Just Changed
By PW Consulting, 2026-09-21
Data Center Busway Market 2025–2032: Strategic Shifts, Power Density, and the Path to Sustainable Scalability
The data center busway market has entered a phase of accelerated structural transformation, driven by the convergence of artificial intelligence workloads, hyperscale expansion, and evolving power distribution requirements. Valued at approximately USD 215.0 million in 2025, the market has grown from USD 163.15 million in 2020, reflecting a compound annual growth rate of 9.0 percent across the forecast horizon through 2032, when revenues are projected to reach USD 344.8 million. This trajectory is not merely a function of incremental capacity additions. It reflects a fundamental rethinking of how power is routed, tapped, and managed within increasingly dense and modular computing environments. For executives, investors, and procurement leaders, the busway segment represents both a direct response to next-generation infrastructure demands and a lens through which broader shifts in data center design, material economics, and regulatory compliance can be understood.
The market’s expansion has been relatively consistent in recent years, yet the composition of growth is shifting. Historical performance from 2020 to 2025 illustrates steady upward movement, with particular acceleration in the most recent intervals as AI-driven deployment cycles matured. The forward outlook suggests that the pace will be sustained, though not uniformly distributed across all end-use contexts or product configurations. Rather than treating busway systems as commoditized electrical distribution components, industry participants are increasingly positioning them as integral elements of high-density, rapidly deployable, and energy-aware data center architectures. This reframing is reshaping competitive dynamics, procurement criteria, and long-term investment theses.
Market Landscape and Core Challenges
The current market environment is characterized by robust demand signals, but also by structural frictions that will define competitive outcomes over the next several years. Three intersecting challenges stand out as particularly consequential for operators, suppliers, and capital allocators alike.
Power Density and Architectural Compression
The transition toward high-density computing environments is compressing traditional layout assumptions. As rack power densities increase and AI clusters demand higher amperage distribution, legacy cable-based or fixed-tray approaches are encountering spatial, thermal, and installation constraints. Busway systems are gaining relevance because they offer modular tap-off flexibility, shorter deployment cycles, and the ability to adapt to evolving white-space configurations. However, this shift is not automatic. Integrating high-ampacity busway into prefabricated or containerized data center pods requires coordinated engineering across power, cooling, and structural dimensions. The challenge for suppliers is to deliver systems that balance current-carrying capacity, footprint efficiency, and ease of modification without introducing complexity that undermines the very speed advantages busway is meant to provide.
Material Cost Volatility and Conductor Selection
Raw material dynamics are becoming a more prominent factor in busway economics. Copper prices moved to 15-month highs in 2025 amid supply disruptions and sustained data center demand, placing upward pressure on manufacturing costs for copper-dependent systems. At the same time, aluminum conductor options are gaining attention for their weight and installation labor advantages in high-density deployments. This creates a strategic tension: copper remains the default expectation for many mission-critical specifications, while aluminum-based designs can reduce weight and installation effort when properly engineered and certified. Manufacturers and procurement teams must navigate performance expectations, total installed cost, and long-term reliability rather than relying on material conventions alone.
PW Consulting
Regulatory and Compliance Pressures
Regulatory expectations are increasingly shaping infrastructure upgrade decisions. In Europe, the Energy Efficiency Directive has drawn attention to the need for data center operators to modernize infrastructure, including busway replacement and upgrades in certain contexts, to support compliance objectives. In parallel, safety and reliability expectations in mission-critical facilities continue to elevate the importance of certified solutions. For example, UL listing requirements for specific busway offerings have become a meaningful differentiator for operators seeking assured reliability in data center applications. These dynamics do not simply add cost; they reshape the value proposition of busway systems by linking power distribution decisions to broader energy, safety, and operational resilience goals.
Key Drivers Reshaping the Market
The growth trajectory of the data center busway market is being propelled by a set of reinforcing drivers that extend beyond simple capacity expansion. Understanding how these forces interact is essential for anticipating where demand will concentrate and which product strategies will gain traction.
Technology Innovation in High-Ampacity, Modular Distribution
Product development is increasingly focused on scalable, high-current busway architectures that can adapt to rapidly changing white-space layouts. One of the most notable shifts is the move toward systems capable of supporting amperage levels well beyond conventional server room distributions, including solutions designed for environments where high-ampacity busway systems exceeding 4000A are required. This trend is closely tied to hyperscale AI data center construction, where power distribution must accommodate dense compute clusters while preserving flexibility for future expansion.
Innovation is also evident in toolless tap-off designs, double-stack configurations, and integrated monitoring capabilities. Double-stack busway systems, for instance, are being introduced to support growing AI data center demands while preserving white space, effectively enabling higher power density without proportionally increasing the floor footprint. At the same time, modular plug-in tap designs are reducing installation friction and enabling faster reconfiguration as workloads evolve. These advances are not isolated product features; they collectively support a broader architectural shift toward busway as a dynamic distribution layer rather than a static electrical accessory.
AI-Driven Demand and Hyperscale Deployment Patterns
The most powerful demand-side force is the proliferation of AI-focused infrastructure. Hyperscale AI data center construction is driving demand for high-ampacity busway systems, particularly in environments where power distribution must scale in lockstep with accelerated compute density. This is altering procurement priorities: speed of deployment, modularity, and compatibility with prefabricated modules are increasingly valued alongside raw current-carrying capacity.
The trend is visible in recent product and exhibition activity. New EcoStruxure Pod Data Center solutions have been introduced with high-power busway integrated alongside liquid cooling and prefabricated modules for AI cluster deployments, illustrating how busway is being embedded into broader pod-level architectures. Similarly, scalable high-capacity double-stack track-style busway systems have been announced to address growing AI data center demands while preserving white space. At major industry gatherings, multiple manufacturers have showcased modular data center solutions that emphasize busway power distribution as a core element of next-generation AI infrastructure. These developments suggest that busway is no longer a peripheral consideration; it is becoming a defining component of AI-ready data center design.
Policy, Efficiency Mandates, and Certification-Driven procurement
Policy and regulatory frameworks are influencing both retrofit and greenfield decisions. Efficiency mandates and energy-related directives are pushing operators to evaluate infrastructure upgrades more holistically, including busway replacement where it contributes to compliance or operational improvement. At the same time, certification and listing requirements are becoming more salient in procurement processes for mission-critical facilities. This is especially relevant where reliability, safety, and interoperability must be demonstrable through recognized standards.
The practical effect is a more discerning buyer environment. Operators are not simply seeking the lowest upfront cost; they are increasingly weighing lifecycle performance, compliance readiness, and integration with broader facility systems. For suppliers, this means that product leadership is increasingly defined by the ability to provide certified, monitored, and easily integrated solutions rather than by volume alone. In this context, busway systems that combine protection, metering, monitoring, and modular tap-off functionality are well positioned to align with evolving procurement criteria.
Supply Chain and Cost Structure Considerations
Supply chain conditions and material economics continue to shape product strategy and pricing dynamics. Copper price movements have introduced cost variability that affects both manufacturers and end users, particularly in segments where copper remains the dominant conductor choice. This has reinforced interest in aluminum conductor options, which can reduce weight and installation labor in high-density deployments. The strategic implication is that conductor selection is becoming a more explicit trade-off analysis, balancing electrical performance, mechanical handling, certification requirements, and installed cost.
In parallel, the broader supply chain emphasis on modularity and prefabrication is encouraging busway designs that can be shipped, assembled, and commissioned with minimal on-site customization. This aligns with the pace demands of hyperscale and colocation projects, where schedule certainty is often as valuable as technical performance. Suppliers that can standardize high-value configurations while maintaining flexibility for site-specific requirements are likely to capture disproportionate advantage in a market where deployment speed is a critical success factor.
Competitive Landscape and Leading Strategies
The competitive environment in the data center busway market is moderately concentrated, yet it is evolving quickly as suppliers differentiate around architecture, integration, and application-specific engineering. With a combined share held by the top three players at approximately 24.6 percent and the top five at about 26.2 percent, the market remains relatively fragmented at the top, leaving room for specialized positioning, regional strength, and targeted innovation. The strategic question is not simply who holds the largest share today, but which companies are building durable advantages in high-growth subsegments tied to AI, modularity, and compliance-driven upgrades.
Leading Players and Strategic Positioning
Several established manufacturers are defining the market’s direction through product architectures that explicitly address high-density AI workloads, modular deployment, and integrated monitoring. Their approaches illustrate how busway is being repositioned from a utility product to a strategic infrastructure component.
Schneider Electric has emphasized integrated pod-level solutions that combine high-power busway with prefabricated modules and liquid cooling for AI cluster deployments. Its recent product launch of EcoStruxure Pod Data Center solutions featuring high-power busway integrated with liquid cooling and prefabricated modules reflects a strategy centered on holistic, rapid-deployment architectures. The company’s exhibition activity has also highlighted busway integration with power shelf concepts for 48V AI systems, signaling attention to evolving power architectures as well as traditional distribution.
Eaton Corporation has focused on modular tap-off flexibility and scalable white-space optimization through track-style busway systems. Its Pow-R-Way III and PowerWave 2 platforms are positioned around modular tap-off for scalable white-space and high-density power distribution. By showcasing modular data center solutions including busway power distribution at Data Center World 2026, Eaton reinforced a strategy that aligns busway with adaptable facility layouts and repeatable deployment patterns.
Vertiv has advanced high-capacity, space-efficient designs with its PowerBar Track and double-stack busway systems. Its offerings support high current levels with copper and aluminum options and emphasize toolless tap-offs for AI data center white-space optimization. The recent announcement of a scalable high-capacity double-stack PowerBar Track busway system for growing AI data center demands illustrates a clear focus on density, scalability, and space preservation.
ABB Ltd has concentrated on integrated protection, metering, and monitoring within low-voltage busway systems for server room distribution. Its Lmax-T systems are designed to support data center server room distribution with integrated protection, metering, and monitoring up to 86 kW per rack. This positions ABB around operational visibility and localized power management, which is increasingly valued in environments where granular monitoring supports efficiency and reliability objectives.
Siemens AG has pursued smart monitoring and strategic power distribution partnerships, with aluminum-based busway systems designed for high-density AI data centers. Its approach underscores the growing importance of monitoring-enabled systems and collaborative ecosystem positioning in high-value segments.
LS Cable & System has built a differentiated presence around modular plug-in taps and UL listing for high-capacity AI and energy-efficient data center power distribution. Its Data-way™ busway with modular plug-in taps and UL listing emphasizes mission-critical reliability and readiness for next-generation AI data centers, a positioning reinforced by its exhibition presence at Data Center World 2026.
Other notable participants contribute additional variety to the competitive field. Legrand offers data center busway solutions for modular power distribution in mission-critical facilities. nVent provides custom medium- and high-voltage bus systems for industrial and data center power applications, expanding the scope beyond standard low-voltage distribution. EAE Electric offers busway systems up to 6300A with data center-specific solutions for power distribution, highlighting the persistent demand for very high-current configurations in specialized environments.
Strategic Differentiation and Evolving Market Structure
Across these players, differentiation is increasingly rooted in four dimensions: current capacity and conductor flexibility, modularity and deployment speed, integration with monitoring and protection, and certification or listing readiness for mission-critical use. Companies that can combine these attributes within repeatable, prefabrication-friendly architectures are gaining leverage in a market where AI-driven projects reward both performance and schedule certainty.
The market structure appears likely to evolve through a mix of consolidation, specialization, and ecosystem positioning rather than through a single dominant wave of unification. Large, globally integrated suppliers benefit from breadth, engineering resources, and cross-selling potential across power management portfolios. At the same time, specialized or regionally strong players can compete effectively by emphasizing certification, customized high-current solutions, or rapid responsiveness to local procurement requirements. New entrants and adjacent players may also find openings by targeting specific niches such as very high-ampacity systems, aluminum-based designs, or modular pod-integrated busway solutions. The overall trend is toward a more application-aware competitive landscape, where Winning strategies depend on how well a product aligns with the operational, regulatory, and architectural priorities of the end facility.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape the data center busway market and create distinct commercial opportunities. These trends are interconnected, and their combined effect will determine which product categories, geographies, and use cases capture the most value.
Trend 1: High-Ampacity, AI-Optimized Busway as a Default Consideration
As AI workloads continue to drive higher power densities, high-ampacity busway systems will become less of a specialized option and more of a baseline consideration for new hyperscale and large colocation builds. The practical opportunity lies in designing for scalability from the outset: systems that can accommodate future power increases, support modular tap expansion, and integrate with cooling and prefabricated infrastructure will command stronger interest than fixed, single-purpose configurations. Commercially, this favors suppliers that can offer proven high-current performance, conductor flexibility, and documented compatibility with AI cluster layouts. The risk is that demand may become concentrated in a narrower set of high-specification systems, intensifying competition among suppliers that can meet those requirements at scale.
Trend 2: Material Strategy and Total Installed Cost as Competitive Levers
Material economics will continue to influence product design and procurement decisions. Copper price volatility and the practical benefits of aluminum conductor options in high-density deployments will encourage more explicit total cost evaluations, including weight, handling, installation labor, and long-term maintainability. This creates an opportunity for manufacturers to differentiate through engineered solutions that justify material choices with measurable installation and operational advantages. It also introduces a risk: if certification, customer familiarity, or application-specific performance requirements strongly favor one conductor type in certain segments, the ability to substitute may be limited. The most resilient strategies will likely involve offering credible options across conductor types while clearly mapping each to specific use cases and total cost profiles.
Busway-Bus Duct Market
Trend 3: Compliance, Monitoring, and Lifecycle Value as Procurement Differentiators
Regulatory efficiency expectations and mission-critical reliability standards are likely to elevate the importance of compliance-ready, monitored busway systems. As operators align infrastructure upgrades with energy efficiency and operational resilience goals, busway solutions that incorporate protection, metering, and monitoring will be better positioned to support both compliance and operational management objectives. The commercial opportunity here extends beyond hardware sales to includes integrated value propositions that reduce lifecycle risk, support audits or reporting, and simplify future modifications. A key uncertainty is the pace and uniformity of regulatory adoption across regions, which could create uneven demand patterns and require suppliers to remain agile in different compliance environments.
Data Center Rack Market
Actionable Implications for Decision Makers
The data center busway market is evolving from a component-level discussion into a strategic infrastructure question. The following implications are most relevant for manufacturers, investors, and procurement leaders seeking to act on current dynamics rather than react to them.
For Manufacturers and Solution Providers
- Prioritize architectures that combine high-current capability with modular tap flexibility and toolless or low-friction installation, especially where AI-driven white-space optimization is a priority.
- Develop clear conductor strategies that address both copper and aluminum use cases, supported by certification, testing, and documented total installed cost arguments rather than relying on convention alone.
- Strengthen integration narratives around monitoring, protection, and prefabricated module compatibility, since these attributes increasingly align with procurement criteria for mission-critical and efficiency-focused facilities.
For Investors
- Focus on companies with credible positioning in high-ampacity, AI-related deployments and evidence of product momentum through launches, trade presence, or qualified project pipelines.
- Assess exposure to material cost dynamics and supply chain resilience, particularly where product portfolios depend heavily on a single conductor type or limited sourcing pathways.
- Look for differentiation that is difficult to replicate quickly, such as certified solutions, integrated monitoring capabilities, or strong alignment with modular/pod-based data center architectures.
For Procurement and Infrastructure Leaders
- Evaluate busway options against total lifecycle criteria, including deployment speed, reconfiguration flexibility, monitoring and protection integration, and compliance readiness, rather than basing decisions solely on initial price.
- Plan for future power density increases by specifying systems that can scale in amperage and tap capacity without requiring wholesale redesign of the distribution layer.
- Verify certification and listing status early in the selection process, especially where mission-critical reliability and regulatory alignment are explicit project requirements.
The breadth of forces shaping this market—from AI-driven power density and material economics to efficiency mandates and modular deployment models—makes detailed, up-to-date segmentation and company-level intelligence highly valuable. For decision makers evaluating market entry, capacity expansion, product roadmap priorities, or procurement strategies, a fuller view of subsegment dynamics, regional variation, and competitive movements can materially improve planning accuracy. More comprehensive data and tailored analysis are available through the complete PW Consulting market report, which provides deeper segmentation detail and customized strategic guidance for specific business contexts.
For detailed analysis of this topic, please visit the official page: Data Center Busway Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Real Drivers Behind Chlorogenic Acid’s 5.69% Growth Trajectory Through 2032
By PW Consulting, 2026-09-21
Chlorogenic Acid Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The chlorogenic acid market has evolved from a niche botanical ingredient into a structurally important segment within the broader functional ingredients landscape. Over the past five years, the market has demonstrated steady expansion, moving from a baseline above 160 million USD in 2020 to an estimated 215 million USD in 2025. Looking ahead through 2032, the trajectory points toward continued growth, with values projected to exceed 315 million USD by the end of the forecast period. This translates to a compound annual growth rate of approximately 5.69 percent, a pace that reflects durable demand rather than a short-lived hype cycle. The growth profile suggests an ingredient that is gradually moving from specialized applications into mainstream formulations, supported by both consumer interest and formulator confidence.
Despite this favorable growth backdrop, the market faces several structural challenges that will shape how companies compete and where value is captured. First, raw material exposure remains a persistent vulnerability. Global coffee production has consistently exceeded 11 million tons, with roughly 8 million tons traded internationally and Brazil and Viet Nam accounting for nearly half of total output. This concentration creates a supply chain that is inherently sensitive to weather events, crop disease, logistics bottlenecks, and shifting trade dynamics. For chlorogenic acid processors, the consequence is not simply a pricing issue but a structural dependency on a commodity ecosystem that can swing quickly from surplus to constraint.
Second, regulatory divergence across key markets is adding complexity to formulation and market access strategies. In Europe, specific food products such as coffee substitutes have faced limits on chlorogenic acid content set below 100 mg/L, creating a compliance framework that differs materially from other regions. In the United States, chlorogenic acid is recorded as a dietary substance with no specific quantity restrictions identified in the latest database, reflecting a more permissive posture. This asymmetry means that global ingredient suppliers and finished product manufacturers must manage distinct formulation rules, documentation requirements, and labeling considerations depending on where products are sold. The regulatory gap is not necessarily a barrier to growth, but it does reward companies that can navigate multiple compliance regimes efficiently while disadvantaging those that rely on a single-market assumption.
Third, the market is entering a phase where differentiation is becoming more difficult to sustain through generic claims alone. As awareness of chlorogenic acid spreads across nutraceutical, food and beverage, cosmetics, and pharmaceutical applications, the risk increases that the ingredient becomes a commoditized specification rather than a strategic differentiator. Suppliers that compete primarily on price or broad availability may find margins compressing as the market matures. The strategic question is whether companies can build defensible positions through purity standards, clinical validation, traceability, application-specific functionality, or proprietary processing methods before the market settles into a more homogeneous competitive structure.
Key Drivers Reshaping the Market
Technological Innovation and Processing Precision
A central driver of market evolution is the maturation of extraction and purification technologies that enable higher consistency and purity levels. The ability to deliver high-purity chlorogenic acid extracts, including HPLC 98 percent grades, has shifted the ingredient from a broadly characterized botanical to a defined functional input with repeatable specifications. For formulators, that precision matters because it reduces batch-to-batch variability, supports more accurate dosing, and simplifies regulatory and quality documentation. It also creates room for premium positioning, particularly in applications where bioactive consistency is tied directly to performance claims or clinical credibility.
At the same time, extraction innovation is increasingly linked to supply security and traceability rather than purity alone. Recent capacity and sourcing expansions in key raw-material hubs have demonstrated how processors are tightening control over upstream supply chains. By strengthening relationships with producing regions and improving traceability systems, leading suppliers are attempting to reduce the risk of disruption while also reinforcing the quality narrative that premium buyers increasingly expect. This combination of technical precision and supply accountability is becoming a meaningful competitive lever, especially in applications where ingredient provenance is part of the product story.
Policy and Regulatory Environment
Regulatory dynamics are influencing both the pace and the shape of market growth. The divergence between mature markets and emerging markets means that product developers cannot assume a uniform pathway for chlorogenic acid-rich formulations. European limits in certain food categories require careful application engineering, while the U.S. posture allows more flexibility in dietary and supplement contexts. This landscape encourages companies to invest in regulatory intelligence and application-specific formulation strategies rather than treating chlorogenic acid as a universally interchangeable ingredient.
Trade policy adds another layer of influence. Recent adjustments in U.S. green coffee tariffs have begun to alter import expenditures for key producing regions, affecting cost structures and sourcing decisions for downstream processors. For companies that rely on imported green coffee beans or related botanical inputs, these shifts can affect landed costs, working capital, and the economics of regional sourcing strategies. The implication is that regulatory and trade monitoring is no longer a peripheral activity; it is becoming a strategic input into sourcing, pricing, and market-entry decisions.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being shaped by a broader move toward functional wellness, metabolic health, and plant-based formulation preferences. In nutraceutical and dietary supplement contexts, chlorogenic acid is often associated with metabolic and weight-management narratives, which continue to attract consumer attention and drive product development. In food and beverage, the ingredient is increasingly evaluated for flavor-compatible functional benefits, especially in formats that seek to combine taste with a health-oriented positioning. In cosmetics and personal care, botanical actives with antioxidant and skin-care relevance continue to support interest in chlorogenic acid as part of multi-functional ingredient systems.
Importantly, the demand story is not limited to end consumers. Business buyers are increasingly asking for documented functionality, application support, and supply reliability. This shift raises the bar for ingredient suppliers. Companies that can offer more than raw material, such as formulation guidance, consistency data, and application-specific performance context, are better positioned to secure long-term contracts and defend pricing. The market is therefore rewarding suppliers that treat chlorogenic acid as part of a solutions offering rather than a standalone commodity.
Supply Chain and Cost Structure Dynamics
Cost structures in the chlorogenic acid market are influenced by a mix of agricultural supply conditions, processing complexity, and logistics. The concentration of coffee output among a small number of producing countries heightens the sensitivity of input availability to regional disruptions. When supply is tight, processors face not only higher raw material costs but also the challenge of maintaining consistent specifications. When supply is ample, competition can intensify and pricing pressure can increase, particularly for standard-grade material. This cyclicality means that effective cost management requires more than negotiating favorable purchase prices; it depends on portfolio diversification, inventory strategy, and the ability to shift between supply sources without compromising quality.
The market also benefits from diversified botanical sources beyond green coffee beans. Honeysuckle and eucommia-based inputs contribute additional supply options and can help reduce single-commodity dependency. However, the strategic use of alternative sources is not simply about substitution. It requires understanding how each source compares in terms of yield, purity potential, regulatory acceptance, and application fit. Suppliers that can integrate multiple raw material pathways with consistent processing standards are better equipped to manage volatility while preserving specification integrity.
Ellagic Acid Market
Competitive Landscape and Leading Strategies
The competitive environment in the chlorogenic acid market reflects a blend of globally established botanical ingredient specialists and high-scale producers with strong regional footprints. The market is moderately concentrated, with a meaningful share of activity captured by a limited set of leading suppliers. This concentration suggests that scale, technical capability, and supply-chain control are important determinants of competitive advantage, while also leaving room for differentiated niches in application-specific formulations and premium-grade extracts.
Naturex, part of Givaudan, illustrates a strategy centered on standardized green coffee bean extracts with strong emphasis on traceability and quality compliance. Its focus spans nutraceutical, functional beverage, and cosmetic applications, where consistent specification and documented sourcing are valued by formulators. Recent capacity and sourcing expansions in Ecuador and Viet Nam signal a deliberate effort to strengthen raw-material security and improve traceability across key producing regions. Alongside that, the introduction of high-concentration bioactive solutions for beverage applications shows a push to connect chlorogenic acid more directly with flavor-compatible functional formats. This dual approach, supply resilience paired with application-driven innovation, positions the company to serve buyers who want both reliability and product development support.
Applied Food Sciences has built a distinct positioning around branded green coffee bean extracts with defined chlorogenic acid content, particularly for dietary supplements, weight-management, and metabolic health formulations. This brand-and-specification strategy is well aligned with the demand-side shift toward clear functional claims and repeatable ingredient profiles. By emphasizing defined content and usage clarity, the company appeals to customers who need a recognizable ingredient identity for marketing and formulation purposes. In a market where generic botanical ingredients can be harder to differentiate, branded and specification-led offerings can create stronger customer loyalty and more defensible pricing.
EUROMED SA represents a pharmaceutical- and clinical-grade orientation, emphasizing high-purity botanical extracts for APIs, dietary supplements, and clinical-grade nutraceutical formulations. This positioning places the company closer to regulated and quality-intensive end uses, where documentation, purity, and process control carry greater weight. The strategic value of this approach lies in its alignment with higher-specification applications that often tolerate less price competition and more value on compliance and consistency. As the broader market expands into more demanding use cases, suppliers with credible high-purity capabilities may capture a disproportionate share of value relative to volume.
Sabinsa Corporation rounds out the competitive picture with a science-backed herbal and botanical API focus, including chlorogenic acid extracts supported by clinical validation. Its relevance lies in the intersection of pharmaceutical, nutraceutical, and preventive healthcare markets, where evidence and credibility are central to adoption. Companies operating in this space benefit when the market moves toward more substantiated claims and more rigorous buyer expectations, because clinical backing and scientific positioning become tangible differentiators rather than generic marketing language.
A notable feature of the competitive landscape is the presence of large-scale producers, particularly in China, that have built substantial export-oriented capacity for high-purity chlorogenic acid extracts. Some of these players have established meaningful global market shares and supply footprints across multiple countries. Their strength typically comes from scale, process efficiency, and the ability to serve a wide range of international buyers with defined purity grades. This creates a two-tier competitive dynamic: on one side, suppliers competing on volume, consistency, and price accessibility; on the other, companies competing on branding, clinical narrative, regulatory positioning, and application-specific value. The market is likely to continue supporting both tiers, but with increasing pressure on scale players to demonstrate more than cost leadership if they want to protect margins as the market matures.
The competitive evolution is also being shaped by a broader trend toward integration and specialization. Some suppliers are expanding upstream into sourcing hubs to reduce exposure and improve traceability. Others are developing application-focused product lines to capture more value in specific formats such as beverages or clinical nutraceuticals. At the same time, new entrants can still find opportunities if they bring a clearly defined niche, whether that is a particular purity standard, a specialized botanical source, or a targeted application competency. The most durable strategies appear to be those that combine operational reliability with a specific value proposition, rather than attempting to compete across every segment at once.
Forward Outlook: Three Trends to Watch
One likely trend over the next three to five years is the continued shift from generic chlorogenic acid supply to application-tailored solutions. As the ingredient becomes more familiar, buyers will increasingly expect support for specific formulation challenges, including stability, sensory compatibility, dosage clarity, and regulatory fit. Suppliers that invest in application development and provide practical formulation support are more likely to secure recurring demand and reduce vulnerability to price-based competition. The commercial opportunity here lies in creating defensible relationships with formulators and brands that value solutions over mere material supply.
A second trend is the growing importance of traceability, purity assurance, and documentation as baseline expectations rather than premium extras. This is being reinforced by both regulatory asymmetry and buyer behavior. As more companies sell into multiple markets, the ability to demonstrate consistent quality and clear sourcing becomes a commercial necessity. Suppliers that can standardize quality systems, provide reliable specification data, and maintain transparent sourcing pathways will be better positioned to serve international customers and reduce the friction associated with multi-market compliance. The upside is stronger customer trust and longer contract cycles; the risk is that any lapse in quality or documentation can spread quickly through a tightly connected buyer network.
A third trend is the potential for regional supply-chain reconfiguration as trade dynamics and sourcing economics evolve. Tariff adjustments, logistics costs, and production concentration all influence where and how chlorogenic acid inputs are sourced and processed. Over time, some suppliers may pursue more diversified sourcing strategies or regional processing arrangements to reduce exposure to any single origin or trade channel. For buyers, this could create both opportunities and risks: more sourcing flexibility can improve resilience, but frequent shifts in supply routes can also affect consistency and commercial terms. Companies that proactively monitor these shifts and build flexible sourcing strategies will be better prepared to manage cost and continuity.
Each of these trends carries embedded uncertainty. Regulatory frameworks may tighten in some markets or remain permissive in others, altering where the most attractive growth opportunities appear. Agricultural conditions could disrupt input availability and create pricing volatility that tests the resilience of weaker operators. And as the market expands, competitive intensity may increase in the most accessible segments, compressing the room for undifferentiated suppliers. The companies most likely to benefit will be those that treat these uncertainties as strategic variables to manage rather than external events to simply react to.
Strategic Actions for Decision-Makers
For ingredient manufacturers and suppliers, the priority is to strengthen the link between technical capability and commercial positioning. This means investing in consistent high-purity outputs, reliable traceability systems, and application-relevant support that helps buyers integrate chlorogenic acid more effectively into their products. Companies should also evaluate whether they are overly dependent on a single raw material pathway or a single geographic source, and consider whether portfolio diversification or upstream sourcing relationships can reduce vulnerability. In a market where scale alone is increasingly difficult to monetize, differentiation through quality assurance, formulation support, and application focus is likely to offer better long-term protection.
PW Consulting Health Care Research Center
For investors and strategic capital allocators, the relevant question is where value is likely to accumulate as the market matures. Volume growth is expected to continue, but the most attractive opportunities may lie in suppliers with credible differentiation in purity, clinical or scientific positioning, traceability, or application ownership. It is also worth distinguishing between businesses that depend primarily on commodity-style throughput and those that can capture more value through branded or specification-led offerings. Monitoring regulatory changes, trade policy shifts, and raw material concentration risk should be part of any investment thesis, because these factors can alter cost structures and market access faster than volume trends alone would suggest.
Ferulic Acid Market
For procurement and formulation teams, the practical focus should be on reducing exposure to inconsistency and compliance friction. This includes evaluating suppliers not only on price but also on specification reliability, documentation quality, and the ability to support multi-market requirements. Long-term supply agreements may be more valuable when paired with performance expectations around consistency and traceability. Procurement teams may also benefit from maintaining a diversified supplier base that includes both scale-oriented and specialty-oriented partners, allowing them to balance cost efficiency with resilience and application fit.
For all of these stakeholders, the strategic value of deeper intelligence is clear. The chlorogenic acid market is large enough to matter and dynamic enough to reward informed decisions, but its nuances, from regulatory asymmetry to raw material concentration and competitive differentiation, are difficult to navigate with high-level summaries alone. More detailed segmentation data, company-level positioning, and application-specific dynamics can materially improve sourcing, investment, and product development decisions. A comprehensive research report can provide that granularity, offering a more precise view of where demand is building, how competitive positions are evolving, and which supply and formulation strategies are most likely to withstand market volatility.
For detailed analysis of this topic, please visit the official page: Chlorogenic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Kitchen Ventilation Systems Market: Why 6.8% CAGR Signals Major Shifts
By PW Consulting, 2026-09-21
Commercial Kitchen Ventilation Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The commercial kitchen ventilation systems market is entering a phase of structural transformation, driven by tightening environmental mandates, accelerating energy-efficiency expectations, and a fundamental shift in how foodservice operators approach kitchen infrastructure. Valued at approximately $1.63 billion in 2025, the market is projected to expand at a compound annual growth rate of 6.8 percent through 2032, crossing the $2.58 billion threshold by the end of the forecast period. The growth trajectory reflects more than incremental replacement demand; it signals a rebalancing of how commercial kitchens are designed, regulated, and optimized for operational cost and compliance performance.
Historical momentum has been steady rather than explosive, with annual revenue progressing from $1.15 billion in 2020 toward the mid-$1.6 billion range by 2025. The acceleration in the 2025-2032 window is rooted in a confluence of regulatory upgrades, retrofit activity in aging foodservice footprints, and manufacturer-level innovation that is converting ventilation from a passive exhaust utility into an active energy and air-quality management asset. For executives, planners, and capital allocators, the strategic question is no longer whether the market will grow, but which sub-segments, geographies, and competitive positions will capture disproportionate value as standards tighten and operating economics shift.
Navigating the Current Inflection Point
Three structural challenges are reshaping how commercial kitchen ventilation markets evolve and how players position themselves within them.
The first is the regulatory ratchet. Kitchen ventilation has historically been governed by a patchwork of fire-safety, mechanical, and food-code requirements. The current trajectory moves beyond containment toward active performance standards. Recent proposals from the California Energy Commission point toward code changes designed to improve energy efficiency and reduce greenhouse gas emissions in commercial kitchens, including the potential introduction of mandatory Demand Control Kitchen Ventilation (DCKV) requirements as the next progression beyond existing standards. When jurisdictional frameworks begin to tie ventilation performance to energy usage and emissions, the market shifts from discretionary spend to compliance-driven investment, which changes the sales cycle, specification logic, and competitive differentiation for manufacturers and service providers alike.
The second challenge is the growing gap between installed base reality and modern performance expectations. Many commercial kitchens continue to operate with legacy exhaust hoods, fixed-speed fans, and non-integrated air management systems that were specified under older mechanical codes and pre-efficiency cost assumptions. Retrofitting these environments requires more than equipment swaps; it demands airflow engineering, grease management coordination, fire suppression compatibility, and controls integration. This elevates project complexity and favors suppliers that can deliver engineered solutions rather than commodity components. It also raises the stakes for installers and service networks, since performance guarantees increasingly depend on proper commissioning and ongoing maintenance.
The third challenge is cost structure volatility interacting with energy economics. Electrical pricing, refrigeration loads, cooking equipment heat output, and building envelope performance all influence the total cost of ownership for kitchen ventilation. A system that performs adequately from a compliance standpoint may still impose avoidable energy expenditure if airflow is not modulated to actual cooking load. As operators face sustained pressure on margins, the economic case for smarter ventilation becomes more compelling, but it also demands clearer quantification of savings, more credible performance data, and integration with broader kitchen energy strategies. The market is therefore moving toward solutions that can demonstrate a measurable link between ventilation control and operating cost reduction.
Key Drivers Behind Market Expansion
Technology Innovation and Demand-Controlled Ventilation
The most consequential technology trend in commercial kitchen ventilation is the shift toward demand-controlled operation. Instead of running exhaust and makeup air at fixed capacities, DCKV systems adjust airflow based on real-time cooking activity, thermal load, or contaminant detection. This approach directly addresses the energy penalty of over-ventilation, which has long been an overlooked source of waste in commercial kitchens. By matching ventilation output to operational demand, facilities can reduce fan energy consumption, lower heating and cooling losses, and improve hood capture efficiency under variable cooking conditions.
This innovation is not occurring in isolation. It is converging with broader building controls, digital commissioning tools, and smarter air-flow management architectures. Providers such as Systemair and Melink illustrate the direction of travel with offerings that combine exhaust performance with smart flow controls and demand-controlled ventilation solutions, while companies with DCKV-focused portfolios such as Gaylord and Melink emphasize modulation as a core value proposition. The strategic implication is clear: ventilation hardware is increasingly evaluated not only by capture area, material durability, and fire-safety conformance, but also by how effectively it integrates with controls that minimize idle energy use.
Residential Ventilation Systems Market
Regulatory Pressure as a Market Accelerator
Regulation is becoming a primary catalyst for both new construction specifications and retrofit programs. The FDA Food Code requires commercial kitchen exhaust systems to capture and contain heat, smoke, grease, and vapors to protect public health, while NFPA 96 sets mandatory requirements for ventilation control and fire protection in commercial cooking operations. These frameworks establish the floor for safe ventilation design. The emerging layer is the energy and emissions dimension, where jurisdictions are exploring requirements that go beyond containment and address efficiency performance.
At the installation and mechanical design level, updated model codes such as the 2021 Uniform Mechanical Code provide the baseline requirements for safe installation of commercial kitchen ventilation and exhaust systems. As local jurisdictions adopt, modify, or layer additional performance expectations on top of these standards, the specification environment becomes more formalized and more consequential. For manufacturers, this creates a dual opportunity: compliance assurance remains a licensing requirement for market participation, but added-value solutions that help operators meet evolving efficiency expectations can command stronger positioning and more resilient demand.
Demand-Side Shifts in Foodservice Operations
The application landscape reflects a broad, diversified demand base rather than reliance on a single end-use channel. Restaurants and cafes continue to represent the largest application share, supported by ongoing build-out, refresh cycles, and the need to upgrade older ventilation installations. Hotels and hospitality facilities contribute a substantial secondary demand stream, where ventilation is tied not only to kitchen safety but also to guest-facing comfort, indoor air quality, and multi-use facility performance. Corporate and industrial canteens, educational institutes, and hospitals and healthcare facilities each bring distinct operating requirements and procurement cycles, broadening the market’s resilience and reducing dependence on any single sector’s investment timing.
Operationally, the demand story is being shaped by labor, throughput, and risk management considerations. Kitchens are under pressure to improve consistency, reduce downtime, and simplify maintenance. Ventilation systems that are easier to commission, cleaner to service, and better aligned with variable cooking loads can improve day-to-day reliability while reducing the operational burden on kitchen staff and facility teams. In institutional and healthcare settings, the air-quality and containment rationale is especially strong, reinforcing ventilation as part of broader facility safety and environmental control strategies.
Supply Chain and Cost Structure Dynamics
Cost structures in commercial kitchen ventilation are influenced by material inputs, fabrication complexity, ratings and certification requirements, and the labor associated with installation and service. For hoods and ducting assemblies, material selection, fabrication tolerances, and fire-rated components can materially affect both pricing and delivery timelines. For controls and makeup air systems, value is increasingly determined by integration capability, sensor reliability, and software-mediated performance optimization rather than by hardware alone.
This changing cost-and-value equation is nudging the market toward more bundled and engineered offers. Suppliers that can coordinate hood design, exhaust and supply airflow, grease management, fire suppression coordination, and controls into a coherent specification are better positioned to manage total project risk and capture more of the value chain. At the same time, component-level suppliers that can deliver certified, cost-competitive hardware with reliable lead times retain an important role, especially in retrofit and maintenance-driven demand. The competitive edge is moving toward coordination, specification support, and documented performance.
Competitive Landscape and Positioning Strategies
The market is characterized by a concentrated set of established manufacturers and a broader tier of regional and application-focused players. Concentration at the top reflects the importance of scale, certification depth, engineered product portfolios, and service reach in winning specification-driven projects. At the same time, fragmentation persists because commercial kitchen ventilation is not a single product category; it spans exhaust hoods, fans and ducting systems, makeup air units, controls and accessories, and installation services, with different competitors leading in different slices.
CaptiveAire Systems stands out as a broad-line manufacturer of commercial kitchen ventilation systems, including exhaust hoods, fans, grease management, and complete HVAC solutions for foodservice operations. Its positioning emphasizes a full-system capability that can address the integrated nature of modern kitchen design, where exhaust, makeup air, and grease handling must work together. Greenheck Fan Corporation similarly occupies a wide portfolio position, offering exhaust hoods, fans, make-up air units, and energy recovery ventilation for restaurants and foodservice. The strategic significance of this breadth is that it allows specification of complementary components under a more unified performance logic, which can reduce integration risk and simplify procurement for larger projects.
Systemair AB brings an advanced-exhaust and air-purification orientation, with high-performance air purifiers, smart air flow controls, and demand-controlled ventilation solutions. This places the company closer to the efficiency and controls frontier, where value is created through modulation, filtration, and system intelligence rather than through hardware volume alone. Gaylord Industries focuses on Demand Control Kitchen Ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice, reinforcing a differentiated stance around active ventilation control and custom engineering. FAST Kitchen Hoods contributes a more specialized, regionally anchored presence as a Canadian manufacturer of cULus-rated commercial kitchen hoods, exhaust systems, island hoods, and low-ceiling hoods for restaurants, illustrating how rating compliance and form-factor specialization can anchor a defensible niche.
Chef’s Deal Restaurant Equipment operates with a service-intensive model as a supplier and installer of comprehensive commercial kitchen ventilation systems, including engineered hoods, make-up air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. Its recent expansion of its Commercial Kitchen Hood Service portfolio to include fully engineered ventilation systems, professional consultation, customized hood packages, make-up air units, ventless exhaust, Type 1 grease hoods, Type 2 condensate hoods, food truck hoods, pizza oven hoods, fire suppression, and exhaust hood filters and accessories for restaurants, food trucks, retailers, and institutional kitchens reflects a deliberate move toward broader solution coverage and consultative specification support. North American Kitchen Solutions maintains a multi-site U.S. footprint with manufacturing of commercial kitchen hoods, exhaust and supply fans, fire suppression, and portable ventless hood systems, showing how geographic and product diversification can support both project-based and supply-driven demand.
How Leaders Differentiate
Across these players, differentiation tends to cluster around several strategic levers. The first is portfolio breadth versus specialization. Full-line providers compete on integration, specification ease, and project-scale capability. Specialists compete on performance depth, rating expertise, or application fit. The second lever is controls and efficiency capability. As energy and emissions expectations rise, manufacturers that can demonstrate meaningful demand-controlled operation, reliable airflow modulation, and credible energy outcomes are better positioned for specification advantage. The third lever is installation and service reach. Ventilation performance depends heavily on proper sizing, duct routing, commissioning, and ongoing maintenance, so providers with strong field capacity can convert product capability into realized performance. The fourth lever is compliance and ratings fluency. In a market shaped by mechanical codes, fire-safety standards, and food-code requirements, the ability to navigate certification and demonstrate conformance is a basic but essential competitive precondition.
Market Structure Evolution
The competitive structure is likely to evolve along three lines. First, integration pressure will increase as operators and specifiers seek fewer interfaces between hood, fan, makeup air, controls, and suppression. This favors companies that can deliver coordinated designs and may encourage selective partnerships or acquisitions that close capability gaps. Second, the controls and efficiency layer will become more valuable, creating openings for players that can bring software-mediated ventilation management, better sensor integration, and verifiable savings narratives into the market. Third, regional and application-focused specialists will continue to find room to compete, especially where local code interpretation, rating requirements, or niche form factors such as low-ceiling or mobile-food applications create specificity that larger portfolios do not automatically address.
Future Trends and Commercial Opportunities
Efficiency Mandates Will Move From Optional to Expected
The most consequential near-to-medium-term trend is the normalization of demand-controlled and efficiency-oriented ventilation as a standard expectation rather than a premium option. With regulatory discussions increasingly pointing toward mandatory DCKV-style requirements in leading jurisdictions, and with model codes and food-safety standards already establishing the containment baseline, the market is heading toward a two-layer framework: safe capture and fire protection as the foundation, and active efficiency performance as the differentiating expectation. Commercial opportunity lies in products and services that can make demand-controlled operation reliable, easy to commission, and simple to verify after installation. Manufacturers and integrators that can reduce the friction of controls adoption—through clearer specification tools, more robust sensor performance, and stronger field support—will be well placed to convert regulatory momentum into specification share.
Retrofit and Performance Upgrades Will Outpace Pure New-Construction Demand
Given the size and age of existing foodservice footprints, a significant portion of future demand will come from upgrading or replacing ventilation systems that no longer meet current performance, safety, or efficiency expectations. Retrofit demand is more fragmented and more service-intensive than new construction, but it also creates opportunities for engineered assessments, phased replacement programs, and controls retrofits that improve energy performance without full kitchen rebuilds. The commercial opportunity here is in bundled upgrade packages that pair hood or fan replacement with airflow rebalancing, controls integration, and grease management review. Providers that can quantify pre- and post-upgrade performance and reduce operational disruption will have an advantage in this segment.
PW Consulting Automotive & Machinery Research Center
Smart Air Management and Integrated Kitchen Energy Design Will Gain Share
Ventilation is increasingly being evaluated as part of the broader kitchen energy and air-quality system rather than as a standalone exhaust function. This creates a trend toward tighter integration between exhaust, makeup air, temperature control, and demand modulation, with controls acting as the connective tissue. The opportunity is for suppliers that can position kitchen ventilation as an energy-management asset with measurable impact on fan power, thermal load, and indoor comfort. It also opens the door to more sophisticated service models, including performance monitoring, scheduled commissioning checks, and data-informed maintenance. As operators look for ways to manage operating costs and meet internal sustainability expectations, integrated air management solutions will become more relevant and more defensible.
Risks and Uncertainties
The outlook carries meaningful uncertainty. Code adoption is uneven across jurisdictions, so the pace and shape of mandatory efficiency requirements will vary, creating a patchwork rather than a uniform transition. Economic conditions can shift the timing of restaurant build-outs, hospitality renovations, and institutional procurement cycles, affecting demand volatility. Supply chain and input cost pressures can influence hardware pricing and project economics, particularly for fabrication-intensive components. Finally, the promised energy and operational savings from controls-based ventilation depend on correct design, installation, and ongoing calibration; if realized performance falls short of expectations, trust in efficiency narratives can erode. Participants should therefore treat performance validation, service quality, and transparent specification as strategic necessities rather than supporting functions.
Actionable Recommendations for Decision-Makers
For Manufacturers and Solution Providers
Position around integration, not just equipment. The market is rewarding providers that can coordinate hood design, airflow balance, controls, grease management, and fire protection into a coherent offer. Invest in specification support, commissioning expertise, and post-installation performance validation so that efficiency claims are credible and repeatable. Where portfolio breadth is not achievable, build clear differentiation around a specialized strength such as demand-controlled control logic, rating compliance for a specific form factor, or a service model that reduces install and maintenance friction. Monitor regulatory signals closely, especially jurisdictional moves toward efficiency-oriented kitchen ventilation requirements, and prepare specification tools and product configurations that align with the next code progression.
Worldwide Commercial Kitchen Fire Suppression System Market
For Investors and Capital Allocators
Evaluate exposure to the efficiency and controls layer as a distinct value driver. Pure hardware volume plays may continue to perform, but the higher-margin, higher-differentiation opportunity is increasingly tied to demand-controlled ventilation, integration services, and performance verification. Consider the mix of new-construction exposure versus retrofit and service exposure in any target, since retrofit-heavy models can be more resilient to construction-cycle volatility while demanding stronger field and service capabilities. Assess regulatory sensitivity as part of the investment thesis: companies aligned with the direction of tightening efficiency expectations are better positioned than those dependent on discretionary, low-performance specifications. In due diligence, probe installation quality, commissioning processes, and the evidence base for energy or operating-cost claims, because these factors increasingly determine whether a product wins repeat specification.
For Procurement and Facility Decision-Makers
Treat kitchen ventilation as a total-cost and compliance asset, not merely a capex line item. Specify with attention to demand-controlled capability, proper airflow design, grease management integration, and fire-safety conformance, and require clear commissioning and performance verification before project closeout. Evaluate suppliers on their ability to deliver engineered solutions and documented post-installation performance, not only on unit pricing. Where existing systems are underperforming, consider targeted retrofits that improve modulation and control before committing to full replacements, and align ventilation decisions with broader kitchen energy and maintenance strategies to capture operational savings over time.
The commercial kitchen ventilation market is moving from a compliance-and-commodity orientation toward a performance-and-integration orientation. That shift creates winners among companies that can combine certification strength, engineering depth, controls capability, and service reliability, while leaving narrower or purely transactional models exposed to margin and specification pressure. As efficiency expectations mature and retrofit demand expands, the strategic value of timely, granular market intelligence becomes harder to overstate. Decision-makers who understand where regulation is heading, how controls are reshaping operating economics, and which competitive positions are gaining specification advantage will be better equipped to allocate capital, prioritize product roadmaps, and structure procurement around the next phase of market growth.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isoparaffin Solvents Market: Why 3.5% CAGR and $1.14B Trajectory Mask Hidden Shifts
By PW Consulting, 2026-09-21
Isoparaffin Solvents Market: Navigating the Strategic Crossroads of Sustainability, Compliance, and Growth
The isoparaffin solvents market has entered a phase of measured maturation, shaped by tightening environmental mandates, evolving application demands, and a competitive landscape that rewards precision and compliance. After reaching a valuation of approximately 905.16 million USD in 2025, the sector is projected to expand at a compound annual growth rate of 3.5 percent through 2032, culminating in a market size near 1,144.78 million USD. This trajectory reflects more than steady demand growth; it signals a structural shift in how formulators, manufacturers, and regulators evaluate solvent performance, safety, and sustainability.
While the broader market moves forward on a moderate growth curve, the underlying dynamics are anything but uniform. Revenue distribution across regions and applications reveals a market that is geographically diversified but application-concentrated, with heavy reliance on industrial and specialty formulations that demand high-purity, low-odor hydrocarbon solvents. The competitive field remains moderately fragmented, with the top three players capturing roughly 28.3 percent of market share and the top five holding about 32.1 percent. Such concentration suggests that scale, technical differentiation, and regional capacity positioning matter significantly, yet they also leave space for niche players and innovative entrants to compete on performance, compliance, and supply reliability.
As 2025 transitions into the forecast period, the isoparaffin solvents market is being reshaped by environmental compliance, feedstock economics, and application-specific performance requirements. These forces are not isolated; they intersect to create both constraints and openings for companies that can align product portfolios with emerging regulatory and operational realities.
Market Landscape: Performance, Pressure Points, and the 2026-2032 Trajectory
A Market Defined by Steady Expansion and Structural Complexity
The isoparaffin solvents market has demonstrated consistent expansion across the 2020-2025 period, supported by enduring demand in paints and coatings, metalworking fluids, agrochemicals, cleaning formulations, pharmaceuticals, and personal care. This breadth of use underscores the versatility of isoparaffinic hydrocarbons as low-aromatic, low-odor alternatives to traditional solvent systems. However, breadth does not imply uniformity. Demand patterns vary by end-use performance requirements, regional manufacturing footprints, and regulatory exposure, creating a market where growth is unevenly distributed across segments and geographies.
Forecasting through 2032 suggests continued expansion, but also highlights a market that must balance volume growth with margin discipline. Feedstock-linked cost volatility and regulatory compliance costs place pressure on producer economics, while downstream customers increasingly prioritize product consistency, purity, and documentation. In this environment, market growth is less a simple function of demand volume and more a result of value capture through differentiated grades, technical support, and supply reliability.
Critical Challenges and Inflection Points
Several structural challenges are reshaping the competitive and operational landscape for isoparaffin solvent producers and users.
- Feedstock volatility and margin sensitivity: The production economics of isoparaffin solvents are closely tied to hydrocarbon feedstock dynamics. Price swings, availability constraints, and energy cost fluctuations can compress margins and complicate long-term pricing strategies. This sensitivity forces producers to manage cost structures carefully while maintaining product quality that meets stringent application specifications.
- Regulatory tightening on VOCs and aromatic content: Environmental regulation continues to redefine the acceptable boundary for solvent use. In multiple regions, including parts of South America, restrictions on volatile organic compound emissions and aromatic content have become more rigorous, especially for paints, coatings, and adhesives. These rules accelerate the shift toward high-purity isoparaffin grades but also increase compliance burdens and formulation complexity for downstream users.
- Performance versus sustainability trade-offs: Downstream formulators face a dual mandate. They need solvents that deliver consistent dissolution, evaporation, and rheological behavior, while also meeting sustainability goals and regulatory limits. Balancing performance, odor, toxicity perception, and carbon footprint is becoming a core product selection criterion rather than a secondary consideration.
These challenges are not merely obstacles. They are inflection points that reward players with strong technical portfolios, dependable supply, and clear regulatory alignment. Companies unable to navigate these pressures risk margin erosion, substitution risk, or loss of share in applications where compliance is a prerequisite.
Key Drivers Reshaping the Isoparaffin Solvents Market
Regulatory and Environmental Mandates as a Growth Accelerator
Environmental regulation is one of the most influential forces behind current market dynamics. In the United States, EPA VOC limits and in Europe, the Solvent Emissions Directive continue to steer formulators away from higher-aromatic solvent systems toward high-purity, low-aromatic alternatives. Isoparaffin solvents, with their low odor and reduced aromatic content, are increasingly positioned as compliant substitutes in applications where emissions limits and workplace safety requirements are tightening.
This regulatory pressure is particularly visible in regions where paint, coating, and adhesive manufacturers must meet stricter emission thresholds. In South America, for example, countries such as Brazil and Argentina have moved to tighten VOC emission standards between 2023 and 2025, mandating reduced aromatic content in solvents used across paints, coatings, and adhesives. Such measures do not simply constrain the market; they redirect it. Demand flows toward solvent grades that can satisfy compliance requirements without sacrificing application performance, and isoparaffins are well placed to benefit from that redirection.
Product Innovation Centered on Purity, Odor, and Application Fit
Technological progress in isoparaffin solvents is increasingly focused on refining product attributes rather than simply expanding volume. Leading suppliers are updating technical documentation, emphasizing low odor, low aromatic content, and narrow boiling ranges, and aligning products with specific formulation needs in coatings, cleaning, metalworking, and personal care. This is not cosmetic repositioning; it reflects a real shift in market expectations. Formulators want solvents that reduce odor complaints, improve workplace conditions, and enable cleaner formulations while preserving solvency performance.
Recent product and documentation updates from major players illustrate this direction. ExxonMobil Chemical updated the technical datasheet for Isopar M, highlighting low aromatic content. Shell Chemicals released an updated product datasheet for ShellSol, emphasizing low odor and suitability for surface coatings. These actions signal that competitive advantage is increasingly linked to grade-level differentiation and technical clarity, not just brand recognition. When downstream customers compare solvent options, the ability to demonstrate purity, consistency, and application-specific fit can be decisive.
Demand-Side Shifts in Coatings, Metalworking, and Specialty Formulations
Demand for isoparaffin solvents is being reshaped by changing expectations in major application categories. Paints and coatings remain a central use case, but the drivers within this segment are evolving. Coatings formulators are under pressure to reduce VOC emissions, improve indoor air quality, and support sustainability claims. Metalworking fluids and industrial cleaning applications continue to value low-odor, effective hydrocarbon solvents that support degreasing, parts cleaning, and process consistency. Agrochemical formulations also contribute to demand, where solvent choice can influence product stability, handling, and regulatory acceptability.
At the same time, personal care and pharmaceutical applications, while smaller in absolute terms, represent high-value segments where purity, odor control, and regulatory documentation matter disproportionately. In these markets, even modest volume growth can be strategically meaningful because the margin and differentiation potential is higher. The broader implication is that demand growth is not only a volume story; it is increasingly a value story, with certain applications generating stronger pull for premium, high-purity grades.
Capacity Adjustments and Regional Supply Positioning
Supply-side dynamics are also influencing market direction. Recent capacity actions by major producers point to a focus on regional availability and application-oriented supply reliability. In February 2025, Shell Chemicals inaugurated a new isoparaffin solvent production plant in Brazil, increasing local capacity by 30 percent. In March 2025, Chevron Phillips Chemical increased its manufacturing capacity for isoparaffin solvents. These developments matter because regional production can shorten supply chains, reduce logistical risk, and better serve local regulatory and application requirements.
For buyers, the practical implication is greater importance placed on supply continuity and regional support. For producers, the lesson is that capacity deployment is most effective when aligned with local demand intensity, compliance conditions, and distribution capabilities. As capacity expands in key regions, competition may intensify on service level, formulation support, and availability rather than price alone.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
How Leading Players Are Shaping the Field
The competitive landscape in isoparaffin solvents is shaped by large chemical and energy-linked companies with broad hydrocarbon portfolios and strong technical reputations. These players compete not only on scale, but on product clarity, application support, and regulatory alignment. Several firms stand out for distinct positioning.
Solvent Naphtha Market
- Shell Chemicals has built a strong identity around ShellSol isoparaffins, emphasizing high-purity synthetic hydrocarbon solvents with narrow boiling ranges and low impurities. The brand is associated with coatings, inks, dry cleaning, and industrial applications, and recent updates have reinforced low-odor performance and surface coating suitability. Its February 2025 plant inauguration in Brazil also demonstrates a strategy of strengthening regional supply and local capacity.
- Chevron Phillips Chemical Company is recognized for Soltrol isoparaffin solvents, including Soltrol 130, which are positioned as low-odor and compatible with parts cleaning, degreasing, paints, inks, and agrochemical formulations. The March 2025 capacity increase signals continued investment in meeting demand for versatile, compliant solvent grades.
- ExxonMobil Chemical markets Isopar fluids with a focus on high purity, low aromatic content, and odorless properties for personal care, coatings, cleaning, and metalworking. The July 2025 technical datasheet update for Isopar M underscores a strategy of reinforcing product differentiation through documented purity and application-specific attributes.
- Braskem S.A. and TotalEnergies SE both participate in the market through broader hydrocarbon and chemical portfolios, supplying isoparaffin solvents for industrial and specialty applications, including paints and coatings. Their relevance lies in portfolio breadth and the ability to integrate solvent offerings within larger supply relationships.
- INEOS Group, Idemitsu Kosan, Calumet Specialty Products Partners, Sasol Limited, and SK Global Chemical each bring regional or specialized strengths. INEOS focuses on industrial cleaning, coatings, and personal care; Idemitsu Kosan supplies IP Clean and IP Solvent products; Calumet emphasizes industrial cleaning and coatings; Sasol participates through its chemical portfolio; and SK Global Chemical offers ISOL isoparaffins for industrial solvents and formulations.
What connects these players is a shared recognition that isoparaffin solvents are no longer commoditized cleaning or dissolving agents alone. They are increasingly evaluated as engineered chemical inputs with specific performance, safety, and compliance profiles. In this context, technical documentation, application expertise, and consistent quality become central competitive tools.
Strategic Positioning and Differentiation Levers
Leading companies are pursuing differentiation through several interlocking levers.
De-Aromatic Solvents Market
- Purity and low-aromatic positioning: In markets where VOC limits and aromatic content restrictions are tightening, high-purity grades gain an advantage. Suppliers that can clearly document low aromatic content and odor performance strengthen their relevance for compliant formulations.
- Application-focused product architecture: Rather than offering a single generic solvent, successful players tailor grades to specific uses such as coatings, metalworking, cleaning, personal care, and agrochemicals. This application alignment improves customer fit and reduces substitution risk.
- Regional capacity and supply visibility: Local production and reliable logistics reduce vulnerability to freight volatility and can improve responsiveness to regional regulatory changes. Brazil’s capacity expansion and broader capacity increases elsewhere illustrate the strategic value of placing supply closer to demand.
- Technical communication and datasheet clarity: Updated datasheets and product documentation are not administrative tasks; they are market-facing signals. Clear specifications help formulators validate compliance, compare alternatives, and justify solvent selection to internal and external stakeholders.
Together, these levers create a competitive environment where advantage is built through reliability, specificity, and compliance readiness rather than through broad volume claims alone.
Market Evolution: Consolidation, Fragmentation, and Entrant Dynamics
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. On one hand, large integrated players benefit from scale, feedstock access, and portfolio breadth, which can support pricing resilience and global reach. On the other hand, the presence of multiple capable regional and specialty suppliers means that differentiation by region, application, and grade remains viable.
Over the next several years, the landscape may evolve along three directions. First, selective consolidation could occur as players seek to strengthen geographic coverage, product ranges, or application expertise. Second, fragmentation may persist or deepen in high-value specialty niches where purity, odor, and documentation command premiums. Third, new entrants or expanding regional producers may gain ground by addressing local compliance needs and supply reliability more nimbly than global incumbents. The outcome will depend on how well companies align capacity, product grades, technical support, and regulatory preparedness with regional demand patterns.
Future Outlook: Three Trends Shaping the 2026-2032 Window
Trend 1: Compliance-Driven Grade Migration Toward High-Purity Isoparaffins
As VOC limits and aromatic content rules continue to tighten across multiple regions, a clear trend is the migration toward high-purity isoparaffin grades that can satisfy regulatory requirements while maintaining formulation performance. This shift is not just a regulatory response; it is becoming a procurement and product development preference. Formulators are increasingly choosing solvents that reduce compliance risk, lower odor concerns, and support sustainability narratives.
The commercial implication is that demand may grow more strongly for specific premium grades than for the market as a whole. Producers and buyers alike should expect a bifurcation in which high-purity, well-documented products capture disproportionate value, while undifferentiated grades face greater substitution pressure. The opportunity lies in aligning product portfolios with the grades that regulatory and performance trends are pulling toward.
Trend 2: Regional Supply Diversification and Near-Market Capacity
Another likely trend is continued regional diversification of supply. Recent capacity expansions in South America and capacity increases elsewhere suggest that producers are looking to reduce exposure to long supply chains and better serve local demand and compliance conditions. Over the forecast period, regional availability may become a more important purchase criterion, especially in markets where logistics cost, lead time, and regulatory context vary significantly.
For buyers, this trend creates opportunities to diversify supply sources and reduce dependency on a single route. For producers, it emphasizes the value of localized capacity, distribution partnerships, and application support that match regional market conditions. The risk is that overexpansion in one region could create localized oversupply, while underinvestment in another could leave demand underserved and open the door to imports or competitor entry.
Trend 3: Application-Specific Value Creation in Coatings, Cleaning, and Specialty Use
A third trend is the growing importance of application-specific value creation. Paints and coatings will remain a dominant demand pool, but the most strategic growth may come from tailored solutions that address odor, purity, and regulatory documentation in coatings, metalworking fluids, cleaning, and specialty formulations such as personal care and pharmaceuticals. These segments reward precision, consistency, and technical support, and they can generate stronger margins than bulk-oriented applications.
This trend opens opportunities for suppliers that can provide not just solvent volume, but formulation guidance, compliance documentation, and grade optimization. It also creates risk for players that compete primarily on price without offering the technical assurance that formulators increasingly require. In practice, the market is likely to reward those who treat isoparaffins as part of a broader solution rather than as a standalone commodity.
Strategic Implications and Action Guidance for Decision Makers
For Manufacturers and Producers
Producers should prioritize grade-level differentiation and regulatory readiness. As compliance becomes a stronger purchase driver, the ability to provide high-purity, low-aromatic, low-odor solvents with clear documentation will matter more than broad product claims. Capacity investments should be evaluated not only for volume potential but also for regional fit, feedstock exposure, and the ability to serve compliance-sensitive applications. Technical communication, including updated datasheets and application guidance, should be treated as a competitive asset that helps customers justify solvent selection and reduce formulation risk.
For Investors and Financial Stakeholders
Investors should look beyond aggregate market growth and focus on where value is concentrating. Segments and grades tied to regulatory compliance, odor reduction, and high-purity requirements are more likely to deliver durable demand and margin resilience than undifferentiated bulk solvent exposure. Regional supply dynamics also matter: capacity expansions and local production can strengthen competitive positioning, but they also create execution risk if demand growth is uneven. A careful assessment of feedstock exposure, regulatory alignment, and application mix is essential when evaluating companies in this space.
For Procurement and Formulation Teams
Procurement and formulation decision-makers should treat isoparaffin selection as a strategic variable rather than a tactical purchase. Compliance documentation, aromatic content, odor profile, and supply reliability should be weighted alongside price. Because regulatory requirements and application performance needs differ by region and formulation, it is wise to validate supplier capability across the specific grades and use cases that matter most. Diversifying supply sources and seeking suppliers with strong regional presence can reduce vulnerability to logistics disruptions and regulatory shifts.
Why Timely, Granular Intelligence Matters
The isoparaffin solvents market is moving through a period in which aggregate growth numbers tell only part of the story. Regulatory pressure, grade-level differentiation, regional capacity shifts, and application-specific demand are creating a landscape where timing, specificity, and supply positioning determine outcomes. For companies making investment, production, or procurement decisions, access to detailed segmentation data, regional breakdowns, and company-level movement tracking can materially improve decision quality. Broad directional awareness is useful, but the real advantage lies in understanding which grades, regions, and applications are gaining or losing traction, and how competitors are adjusting capacity and product positioning in response.
For organizations that need deeper coverage of market size by segment, regional demand patterns, competitive activity, and customized strategic recommendations, a comprehensive market research report can provide the structured detail required to move from general insight to concrete action. Detailed data, scenario-ready segmentation, and forward-looking assessment are particularly valuable when planning capacity, evaluating suppliers, or positioning product portfolios for compliance-led demand shifts.
Conclusion
The isoparaffin solvents market is not experiencing a sudden disruption; it is undergoing a deliberate restructuring shaped by environmental compliance, product purity expectations, regional supply strategy, and application-specific performance needs. The forecast growth path through 2032 suggests a market that continues to expand, but the more important story is where value is being created and where competitive advantage is being built. High-purity, low-odor, compliance-aligned grades are gaining relevance, regional capacity is becoming a strategic differentiator, and technical clarity is increasingly part of the commercial battleground.
PW Consulting Automotive & Machinery Research Center
For executives, investors, and procurement leaders, the practical question is no longer whether isoparaffin solvents remain important, but how to position for the next phase of demand migration, regulatory pressure, and supplier competition. Companies that align their strategies with these trends, and that invest in the intelligence needed to track them closely, are better placed to capture value in a market where growth and differentiation are increasingly inseparable.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PRP Market Analysis: How 10.5% CAGR to $1B Reshapes Orthopedics and Aesthetics
By PW Consulting, 2026-09-21
The Platelet-Rich Plasma Market: Strategic Trends and Commercial Opportunities in Autologous Biologics
The global platelet-rich plasma (PRP) market has evolved from a niche regenerative modality into a structured commercial ecosystem, driven by clinical adoption across orthopedics, sports medicine, aesthetics, and wound care. With historical revenue expanding from approximately $236.5 million in 2020 to $512.0 million in 2025, and a projected trajectory toward $1,032.3 million by 2032, the sector reflects a compound annual growth rate of 10.5 percent. This growth is neither uniform nor accidental. It emerges from a convergence of technological maturation, shifting reimbursement pathways, regulatory clarification, and demand-side preferences that favor autologous, minimally processed biologics. For executives, investors, and procurement leaders, the current moment represents a transition from early experimentation to scaled commercialization. The challenge lies in navigating a fragmented supply base, inconsistent coverage models, and evolving clinical evidence while capturing value in segments where efficacy, workflow integration, and reimbursement alignment intersect.
The market structure reveals a moderately concentrated landscape, with the top three players accounting for roughly 47.2 percent of revenue and the top five reaching 52.8 percent. This concentration suggests that scale, regulatory clearance, and system integration confer meaningful advantages, yet substantial runway remains for differentiated technologies and regional expansion. Growth is not evenly distributed across applications or geographies. Orthopedic and sports medicine use cases continue to anchor demand, while aesthetic and wound care applications present distinct reimbursement and clinical-evidence dynamics. The following analysis examines the forces shaping this transition, the strategic postures of leading participants, and the practical implications for decision-makers seeking to capitalize on the next phase of market development.
Plasma Protein Therapeutics Market
Market Snapshot: Growth Trajectory and Structural Realities
Over the 2020–2025 period, the PRP market expanded at a pace that outpaced many adjacent medical device and biologics segments. Revenue climbed from $236.5 million to $512.0 million, and forward projections indicate continued expansion through 2032, with annual figures moving from $579.7 million in 2026 to $1,032.3 million in 2032. This trajectory implies a sustained 10.5 percent CAGR, reflecting both underlying volume growth and incremental adoption of point-of-care preparation systems. The market’s composition spans multiple product formats, including pure PRP, leukocyte-rich variants, platelet-rich fibrin, and ancillary systems, alongside application breadth that covers orthopedic reconstruction, sports injury management, cosmetic procedures, and chronic wound care.
Despite the favorable headline numbers, the market operates within a set of structural constraints that shape commercial strategy. First, clinical evidence remains uneven across indications, with stronger data in select musculoskeletal and wound applications and more limited consensus in aesthetic and certain orthopedic injection contexts. Second, reimbursement pathways are partial and indication-specific, creating adoption friction in settings where providers cannot reliably pass through preparation costs. Third, regulatory classification creates a dual-track environment: FDA-cleared preparation devices enable compliant autologous use, while off-label applications depend on provider discretion and often lack broad coverage. Together, these realities mean that market growth is increasingly tied to workflow efficiency, evidence generation, and reimbursement alignment rather than to scientific novelty alone.
Key Challenges and Inflection Points
The PRP sector stands at several inflection points that will determine which participants capture durable value. One central challenge is the evidence-to-reimbursement gap. While point-of-care systems have improved consistency and reduced preparation variability, payers and institutions increasingly require indication-specific data, standardized protocols, and transparent cost accounting. Without these, adoption remains concentrated in cash-pay, sports medicine, and high-income aesthetic segments, limiting broader institutional uptake.
A second challenge involves cost structure and sterilization logistics. Single-use processing components, hemapheresis kits, and point-of-care consumables depend on gamma sterilization and small-batch manufacturing, which elevate unit costs and constrain margin flexibility. Suppliers must balance clinical-grade reliability with economic scalability, particularly as volume expectations rise and hospital procurement teams normalize total-cost-of-ownership assessments.
A third inflection point is regulatory clarity versus clinical flexibility. Autologous PRP devices are classified as Class II under 21 CFR 864.9245 and require 510(k) clearance, while PRP itself is regulated as a blood product by FDA CBER and is generally considered investigational for most non-wound applications. This framework ensures compliance for cleared autologous use but leaves many orthopedic and aesthetic injections in a provider-discretion zone without broad insurance coverage. The result is a market where device clearance, coding specificity, and clinical protocol design are increasingly intertwined commercial variables rather than purely regulatory checkboxes.
Core Drivers of Market Change
Technology Innovation and Workflow Integration
The most consequential technological shift is the move toward point-of-care systems that combine high platelet yields, customizable formulations, and rapid preparation workflows. Automated separation platforms, double-syringe kits, and single-spin systems have reduced preparation time and improved reproducibility, making PRP more viable in busy clinical environments. Systems that enable up to 18x platelet concentration at the point of care, or that deliver supraphysiologic concentrating with customizable formulations, address two practical barriers: clinical consistency and operational throughput. These capabilities matter because adoption in orthopedics and sports medicine often hinges on whether preparation can be embedded into existing procedure workflows without disrupting scheduling or staffing.
Technology differentiation is also moving toward application-specific optimization. In wound care, fibrin-based matrices and gel preparations that support exuding cutaneous wounds represent a distinct value proposition from injection-focused systems used in musculoskeletal settings. This specialization is creating a broader ecosystem in which device architecture, kit composition, and preparation protocol are increasingly matched to clinical use cases rather than sold as generic autologous blood products.
Policy and Regulatory Environment
Regulatory and coding developments are reshaping commercial viability. FDA clearance of PRP preparation systems establishes a compliance pathway for autologous use, while the broader classification of PRP as a blood product under FDA CBER keeps many non-wound applications in an investigational category. This duality means that device-level clearance does not automatically translate into coverage for every indication. Instead, commercial success increasingly depends on aligning cleared indications with coding structures and payer policies.
Worldwide Platelet Rich Plasma (PRP) Kit Market
Reimbursement dynamics are evolving in parallel. For chronic non-healing diabetic wounds, Medicare covers autologous PRP prepared with FDA-cleared devices under HCPCS G0465, with required invoice documentation for the PRP supply kit and an in-house processing fee. This creates a structured, if narrow, coverage pathway that rewards cleared devices and documented supply chains. At the same time, Category III coding such as 0232T applies to PRP injections across sites, including image guidance, harvesting, and preparation, with some payers requiring separate billing for supplies. These coding nuances affect provider economics and influence which systems are preferred in outpatient and institutional settings.
Demand-Side Shifts in Provider and Consumer Behavior
Demand is being reshaped by a preference for autologous biologics that minimize immunogenicity concerns and align with regenerative care models. In sports medicine and orthopedics, providers seek options that can be deployed during same-session procedures, reducing reliance on off-site processing and supporting rapid turnaround. In aesthetics, consumer interest in minimally invasive rejuvenation continues to drive volume, though this segment remains more sensitive to evidence messaging, pricing transparency, and outcomes consistency. In wound care, the demand driver is clinical necessity: chronic ulcers and non-healing wounds create a persistent care burden, and autologous PRP-based matrices offer a biologically aligned adjunct where standard dressings and therapies may be insufficient.
Across these settings, the common thread is a growing expectation that PRP should be reproducible, documented, and economically legible. Providers and procurement teams increasingly evaluate systems not only on platelet concentration claims but also on sterility assurance, kit reliability, ease of use, and compatibility with existing billing and documentation workflows.
Supply Chain and Cost Structure Evolution
Supply chain economics are becoming a strategic variable. Gamma sterilization requirements and small-batch manufacturing for single-use kits raise input costs, which can compress margins for manufacturers and increase total cost for providers. This environment favors participants that can standardize kit architectures, secure reliable sterilization pathways, and design systems that minimize waste or redundant consumables. It also rewards vertical alignment between device platforms and consumable supply, since fragmentation can introduce variability in both cost and clinical performance.
At the same time, distribution partnerships are altering market access. Agreements that place PRP systems under established brand channels can accelerate reach in specific clinical segments, particularly where wound care or orthopedic procurement is consolidated. Such arrangements can reduce the commercial burden on smaller manufacturers while expanding the availability of cleared systems within trusted distribution networks.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Participants
The competitive set reflects a mix of device-focused manufacturers, biologics integrators, and specialty developers pursuing differentiated preparation architectures. Several participants have built their positioning around point-of-care concentration performance and workflow reliability. EmCyte Corporation emphasizes a supraphysiologic concentrating system for point-of-care autologous PRP preparation with customizable formulations and high platelet yields, appealing to settings that value concentration control and formulation flexibility. Arthrex, Inc. focuses on an automated PRP system and double-syringe kits designed for orthopedic applications, enabling high platelet concentration at the point of care and integrating preparation into procedure workflows. Zimmer Biomet emphasizes integrated PRP systems and biologics kits that support orthopedic reconstruction and soft-tissue procedures, leveraging the advantages of an established orthopedic portfolio. Terumo BCT targets point-of-care PRP systems and related kits for rapid autologous preparation, with an emphasis on workflow speed and clinical usability.
PW Consulting
In parallel, several developers have pursued application-specific differentiation. Regen Lab S.A. focuses on PRP kits and systems optimized for clinical use in regenerative medicine applications, aligning product design with practitioner workflows. Royal Biologics has concentrated on fibrin-based PRP and PRF systems for wound management and bone graft handling, including a PRF wound matrix that recently received FDA clearance for management of exuding cutaneous wounds, including diabetic and venous ulcers. Nuo Therapeutics, Inc. has built a wound care and biodynamic therapy focus, with its PRP system distributed through private-label arrangements to Smith+Nephew in the U.S. wound care market. Gale Force Aesthetics, LLC emphasizes a single-spin system designed for high-volume platelet capture and rapid preparation, while Forever Labs, Inc. focuses on an automated separator for safe, rapid autologous PRP preparation at the point of care. Royal Wound-X, Inc. concentrates on a PRF-matrix system for rapid PRP gel preparation from peripheral blood for wound management.
These positions illustrate two strategic paths. One path concentrates on concentration performance, automation, and orthopedic or sports medicine integration, where procedural efficiency and reproducibility are paramount. The other path emphasizes wound care and regenerative applications, where matrix properties, clearance status, and reimbursement compatibility can create more defined commercial pathways. Both paths require disciplined alignment between device capability, kit economics, and clinical protocol design.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is evolving along multiple axes. Consolidation pressure is rising where scale, distribution reach, and regulatory clearance create advantages, particularly in segments where procurement is centralized or where private-label distribution can rapidly expand availability. Differentiation is intensifying around workflow integration, concentration consistency, and indication-specific design, as generic autologous blood preparation becomes less distinctive in a maturing market. At the same time, new entrants continue to appear, often bringing novel spin architectures, automated separation concepts, or niche wound care formulations that challenge established incumbents on speed, yield, or use-case fit.
A notable dynamic is the increasing importance of commercial alignment beyond pure product performance. Recent developments such as exclusive private-label distribution agreements in wound care and FDA clearances for specific wound matrix indications demonstrate how regulatory milestones and channel partnerships can reshape market access. In wound care especially, clearance for exuding cutaneous wounds and diabetic or venous ulcers can materially change the commercial profile of a system by enabling more defensible positioning within reimbursement-eligible pathways. In orthopedics and aesthetics, the absence of broad coverage for many off-label applications means that competitive advantage often depends on provider education, protocol standardization, and total cost management rather than on clearance alone.
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend 1: Indication-Specific Commercialization Becomes the Norm
The next phase of growth will likely reward participants that align device design, coding strategy, and clinical evidence with specific indications rather than treating PRP as a single homogeneous category. Wound care offers a concrete example: where cleared devices and defined coverage pathways exist, commercialization can be structured around documented supply chains, processing fees, and matrix-based protocols. In musculoskeletal and aesthetic settings, growth may remain stronger in cash-pay and sports medicine channels unless evidence and coding evolve further. The commercial implication is clear: companies that build indication-specific value propositions, including protocol support and billing compatibility, are better positioned to convert adoption into repeatable revenue.
Trend 2: Automation and Workflow Integration Will Separate Leaders from Laggards
Point-of-care automation, rapid preparation, and high-yield concentration are increasingly baseline expectations rather than differentiators. The next competitive frontier is end-to-end workflow integration: systems that minimize hands-on time, reduce variability, and fit cleanly into existing clinical routines. This matters because clinical adoption is often constrained by operational friction as much as by clinical interest. Manufacturers that can demonstrate reliable kit performance, straightforward preparation steps, and compatibility with institutional procurement and documentation requirements will have an advantage in converting trial use into sustained adoption.
Trend 3: Reimbursement Architecture and Cost Transparency Will Shape Segment Economics
As payers, institutions, and providers scrutinize cost, the economics of PRP will depend more heavily on coding clarity, supply-chain documentation, and processing-fee structures. Narrow coverage pathways can be commercially attractive where they are well-defined, but they also demand rigorous invoice and kit documentation. In segments where coverage is limited, cost transparency and predictable kit economics will influence whether providers continue to adopt PRP or redirect spend to alternative biologics or procedures. The risk is that uneven reimbursement and variable sterilization-driven costs create instability in margin planning and adoption forecasting.
Opportunities and Uncertainties
These trends open several commercial opportunities. There is room for differentiated systems that combine automation with application-specific performance, particularly where wound care clearance or orthopedic workflow integration can be clearly demonstrated. Distribution partnerships and private-label arrangements can accelerate access in consolidated procurement environments. There is also opportunity in standardizing kit economics and sterilization pathways to improve margin resilience. At the same time, uncertainties remain: evidence gaps in select indications, reliance on provider discretion for many off-label applications, and cost pressures from gamma sterilization and small-batch manufacturing can all temper growth expectations. Participants should also monitor regulatory developments, since device clearance does not automatically broaden coverage, and coding practices may continue to diverge across payers and regions.
Strategic Implications for Decision-Makers
For Manufacturers and Technology Developers
- Align product development with indication-specific workflow needs, prioritizing automation, reproducibility, and kit reliability over concentration claims alone.
- Invest in documentation-ready supply chains and clear billing compatibility, especially where coverage pathways such as wound care codes create structured economic models.
- Pursue distribution partnerships or private-label channels where procurement is consolidated, using cleared indications and proven reproducibility to gain entry into institutional workflows.
- Plan for cost structure resilience by standardizing single-use components, securing reliable sterilization pathways, and reducing consumable waste wherever possible.
For Investors
- Evaluate companies on the strength of their regulatory positioning, reimbursement alignment, and workflow integration rather than on market-level growth narratives alone.
- Favor business models that can convert clinical interest into repeatable economics, including recurring kit demand, stable sterilization and manufacturing pathways, and defensible channel access.
- Monitor segment-specific dynamics closely, since wound care, orthopedics, sports medicine, and aesthetics each face different evidence, coverage, and pricing constraints.
- Assess whether a company’s differentiation is durable in the face of automation becoming a baseline expectation, and whether its cost structure can withstand single-use kit economics.
For Procurement and Clinical Leaders
- Evaluate PRP systems against total cost of ownership, including kit reliability, preparation time, sterility assurance, and billing documentation requirements.
- Match system selection to the intended indication and clinical protocol, recognizing that wound care, orthopedic, and aesthetic applications often require different performance and coverage considerations.
- Require transparent documentation for supply kits, processing fees, and device clearance status to support compliance and reimbursement where applicable.
- Prioritize vendor support that includes protocol guidance, staff training, and consistent kit availability, since workflow friction can undermine adoption even when clinical interest is strong.
The PRP market is moving from broad enthusiasm to disciplined commercialization. Growth is increasingly determined by the intersection of cleared device pathways, reimbursement compatibility, workflow integration, and cost transparency. In that environment, the most valuable intelligence is segment-specific: how clearance status interacts with coding, how kit economics behave under sterilization and small-batch constraints, and where distribution partnerships can open durable access. Detailed segmentation data, competitive benchmarking, and customized scenario planning can help decision-makers translate these dynamics into concrete investment, product, and procurement choices. For leaders seeking a fuller view of the market’s subsegments, regional trajectories, and company-level positioning, accessing the complete research dataset and methodology notes provides the granularity needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Platelet Rich Plasma (PRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com