

Blogs
Market revenue is set for significant growth, from USD 11,500 million in 2020 to USD 17,800 million in 2025, and projected to reach USD 41,200 million by 2035. The consistent rise in revenues reflects ongoing investments in smart infrastructure, increasing camera deployments across multiple sectors, and the rapid adoption of advanced video analytics. The market’s upward trajectory highlights China's strategic role in global video surveillance innovation.
Read More - https://bussinessinsights.com/research-report/china-global-video-surveillance-market
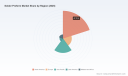
Government applications make up the largest segment, accounting for 32% of total market revenue in 2025. Transportation security follows at 22%, driven by major smart mobility projects. Retail represents 18%, reflecting ongoing digitalization and theft prevention efforts. The distribution highlights the strategic focus on public safety initiatives and the growing integration of video surveillance in critical urban infrastructure.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-global-video-surveillance-market
Frequently Asked Questions
Who are the key players in China Global Video Surveillance Market industry?
The top five players in China’s global video surveillance market are Hikvision, Dahua Technology, Uniview, Huawei Technologies, and Tiandy Technologies. These companies lead due to their technological innovation, wide product portfolios, and strong distribution networks, consistently driving market expansion both domestically and internationally.
What is the China Global Video Surveillance Market growth?
The China global video surveillance market has seen robust growth, with a CAGR above 10% in recent years. Hikvision and Dahua Technology have been pivotal to this trend, leveraging AI and IoT integration to enhance surveillance capabilities, increasing adoption across government, commercial, and residential sectors.
Which segment accounted for the largest China Global Video Surveillance Market share?
The public sector segment, particularly city surveillance and public safety applications, accounted for the largest market share. With the Chinese government's continued investment in Safe City projects, demand for video surveillance solutions is surging across urban management and transportation systems.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Solder Preform Market Hits $440M in 2025, Projected 7.4% CAGR to Reach $718M by 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for a Transforming Market: Inside the 2026 Solder Preform Landscape
The solder preform market is entering a decisive inflection point. As manufacturers navigate tighter tolerances, evolving material standards, and shifting supply chain architectures, strategic foresight has become a competitive necessity rather than an analytical luxury. PW Consulting’s latest Solder Preform Market research was designed to meet that exact moment. This study does not merely document historical performance; it translates structural market signals into actionable decision frameworks for 2026 and beyond. For executives, procurement leaders, and product strategists, the report functions as a navigational instrument, aligning capacity planning, sourcing strategy, and innovation roadmaps with the trajectory of a rapidly consolidating industry.
The foundation of this analysis rests on a rigorous examination of market expansion across the recent historical window and into the forward-looking forecast horizon. From 2020 through 2025, the industry demonstrated consistent upward momentum, reflecting steady demand absorption and incremental capacity investments. Looking ahead to the 2026–2032 forecast period, the market is projected to sustain a compound annual growth rate of 7.4 percent, anchored in U.S. dollars and measured in millions of revenue units. This trajectory signals more than simple volume growth; it reflects a structural reallocation toward higher-performance material solutions, precision-form geometries, and application-specific alloy formulations. The reported market valuation has already climbed from 320.0 million in 2020 to 440.0 million in 2025, with the forward estimates extending toward 718.0 million by 2032. These figures establish a clear macro narrative: the solder preform space is expanding, but the drivers of that expansion are increasingly concentrated in specialized segments, stringent certification requirements, and advanced thermal and electrical performance mandates.
Strategic value emerges not from the headline numbers alone, but from understanding how those numbers are distributed across the operational realities that shape procurement, pricing, and capacity decisions. The market structure reflects a moderately fragmented competitive environment, with CR3 concentration at 22.0 percent and CR5 concentration at 32.0 percent. This distribution indicates that no single entity controls the entire value chain, while simultaneously suggesting that scale advantages, tooling libraries, and certification portfolios are becoming meaningful differentiators. For buyers, this means sourcing strategies must balance reliability, technical capability, and resilience. For incumbents, it means the window to expand share through precision manufacturing, custom alloy development, and application-specific preform engineering remains active but increasingly contested. The report unpacks these structural dynamics without reducing them to superficial rankings, instead positioning concentration metrics as indicators of where negotiation leverage, supplier diversification, and partnership models will be most effectively deployed.
What the Research Delivers: Operational Content for Execution-Focused Teams
A market study earns its place on the executive shelf when it converts data into operational clarity. This report is built around that principle. Rather than offering abstract commentary, the analysis maps directly onto the categories that determine day-to-day sourcing and planning decisions. The segmentation architecture examines how product classifications, regional footprints, and end-use application contexts interact to shape demand volatility, lead-time expectations, and qualification pathways. Procurement teams will find structured visibility into the material categories that dominate current procurement flows, while R&D and engineering groups will gain context around the geometry and alloy considerations that influence attachment reliability, thermal management, and bond-line control. The study deliberately avoids presenting segmentation as a static table of proportions; instead, it frames each segment through the operational implications that matter most to decision-makers, including certification requirements, tooling compatibility, and the cost implications of transitioning between material classes.
Equally important is the report’s treatment of supply-side realities. The analysis incorporates the manufacturing and technical capabilities that distinguish leading preform producers, drawing attention to the practical dimensions of die libraries, custom alloy development, thickness control methodologies, and quality system certifications. These are not ornamental details; they determine which suppliers can meet tight tolerance specifications, which can support rapid design changes, and which can sustain consistent output under high-mix production requirements. The study also integrates recent organizational and strategic developments that signal shifting priorities within the competitive field. For example, the June 2025 appointment of a Division Vice President of Sales and Marketing at AMETEK Specialty Metal Products reflects an explicit push toward market expansion and accelerated new product introductions in solder preforms and related custom alloys. Such movements matter because they shape commercial velocity, technical support capacity, and the pace at which new preform configurations reach qualified production status. By tracking these developments, the report helps leaders anticipate where supplier capabilities are likely to strengthen, where commercial engagement models may evolve, and where differentiation will increasingly hinge on technical responsiveness rather than base material availability alone.
Worldwide Composite Preform Market
Competitive Architecture and the Rising Cost of Differentiation
The competitive landscape is defined by a blend of established specialty manufacturers and regional producers, each pursuing distinct positioning strategies within the broader market. Several organizations have built reputations around high-precision preform geometries, broad tooling inventories, and customized alloy solutions intended for demanding end-use environments. One U.S.-based advanced materials group has emphasized ultra-clean preform production across shapes that include squares, rectangles, discs, washers, frames, and custom designs, offering lead-free alloys, gold-tin, and silver-based formulations for microelectronic packaging in aerospace, defense, semiconductor, and high-power applications. Another large-scale manufacturer has positioned itself around the broadest preform range in the industry, supported by an extensive tooling library and specialization in custom alloy configurations for aerospace, defense, high-performance electronics, photonics, automotive, and medical devices. A Japanese producer has focused on versatile geometries such as ribbon, washer, pellet, disc, and chip formats, incorporating design features for bond-line thickness control and optional flux-integrated configurations for simultaneous solder and flux delivery across electronics, automotive, aerospace, and medical contexts. A U.S. materials supplier has advanced preform and thermal management solutions with fixture-stabilizing technologies and certified quality systems aligned to automotive, medical, defense, and power electronics requirements. Historical manufacturers with long operating pedigrees continue to serve industrial, plumbing, electronics, and precision applications through integrated solder and flux portfolios, while specialty electronics solution providers have emphasized sustainability-aligned production environments and metal waste recycling alongside their preform offerings.
Regional manufacturing presence also plays a meaningful role in shaping availability, pricing logic, and qualification pathways. Several dedicated OEM-oriented producers operate around standard and custom preform shapes along with complementary soldering materials such as wires, balls, fluxes, pastes, and powders. Other firms extend their portfolios across electronics and industrial applications as part of broader soldering material ecosystems. These regional capabilities affect not only unit economics but also lead-time predictability, engineering support models, and the practical feasibility of qualification for highly regulated end-markets. The report examines these competitors not as isolated profiles but as strategic reference points within an ecosystem where technical differentiation, certification depth, and customization capacity increasingly determine commercial positioning. Leaders who understand where each supplier concentrates its strengths can structure multi-source arrangements more effectively, align internal qualification roadmaps with supplier readiness, and avoid over-reliance on capabilities that may be vulnerable to capacity constraints or material volatility.
Supply Chain Realities, Material Economics, and Regulatory Friction
The strategic usefulness of a market study depends heavily on its ability to reflect the forces that distort pricing, constrain throughput, and reshape sourcing assumptions. In the solder preform market, material economics have become a central concern. Sustained increases in LME tin pricing have translated into higher preform costs across categories, forcing procurement functions to reinterpret cost forecasts, negotiate contract structures with greater flexibility, and evaluate the trade-offs between alloy selection, geometry standardization, and application performance. At the same time, geopolitical disruption and supply chain concentration in the processing of ultra-high-purity silver powders and related critical materials have surfaced vulnerabilities that extend beyond short-term price movement. These concentration risks affect upstream feedstock availability and can influence lead times, qualification continuity, and the practical resilience of suppliers that depend on narrowly sourced inputs.
Regulatory and trade dynamics add a further layer of complexity. Executive actions affecting ad valorem tariff duties have altered the calculus for cross-border procurement and inventory positioning, especially for organizations balancing regional supply against qualification and compliance requirements. Meanwhile, export controls on gallium and germanium products have implications for upstream feedstock used in certain indium and silver-based preform formulations. Such developments do not simply create headlines; they influence the feasibility of specific alloy pathways, the stability of cost assumptions, and the speed at which alternative material strategies can be validated. The report integrates these macro-level disturbances into the market narrative so that readers can better anticipate where cost pressure may persist, where substitution or qualification efforts will be necessary, and where supplier concentration may create exposure that requires mitigation through diversification or inventory strategy.
Why This Research Matters for 2026 Decision-Making
For organizations operating in or adjacent to the solder preform market, the 2026 planning cycle demands more than retrospective trend analysis. It requires a clear view of where growth is structurally concentrated, which supplier capabilities will determine qualification speed and production reliability, and how material and regulatory forces will reshape cost and risk assumptions. The PW Consulting study is designed to provide that decision-grade context. It enables procurement teams to evaluate sourcing models with greater precision, helps R&D groups align material and geometry exploration with realistic market readiness, and supports executive teams in prioritizing capital, capacity, and partnership investments where the growth trajectory is strongest.
The report also serves as a practical bridge between macro momentum and segment-level realities. By connecting overall market expansion to the operational implications of segmentation, concentration, tooling breadth, certification depth, and material volatility, it helps leaders convert trend awareness into execution strategy. This is particularly valuable in a market where the most consequential decisions often hinge on details that generic analysis overlooks: the availability of specific preform shapes, the flexibility of custom alloy development, the resilience of upstream feedstock channels, and the commercial significance of recent leadership and product-introduction moves within key manufacturing organizations.
Solder Preform Market
Strategic advantage in 2026 will belong to organizations that can align their internal capabilities with the market’s directional signals before those signals become fully priced into competition. The full research delivers the depth required to make that alignment possible. It presents a structured, evidence-based view of market size, growth trajectory, competitive positioning, and operational sensitivities, while preserving the granular intelligence that procurement, engineering, and executive teams need to act with confidence. To access the complete segmentation breakdowns, competitive capability assessments, regional and application-level context, and forward-looking scenario implications, readers are encouraged to visit the source page for PW Consulting’s Solder Preform Market research and obtain the full report.
For detailed analysis of this topic, please visit the official page: Solder Preform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tall Oil Derivative Market Hits $2,650 Million in 2025, Poised to Reach $3,439 Million by 2032
By PW Consulting, 2026-09-16
Strategic Intel for 2026: Navigating Growth and Volatility in the Crude Tall Oil Derivative Market
As industrial demand shifts toward biobased inputs and regulatory frameworks tighten around renewable feedstocks, the crude tall oil derivative market stands at a critical inflection point. For executives, procurement leaders, and strategy teams planning the 2026 cycle, isolated data points will not suffice. Decision-making requires a clear line of sight into structural supply dynamics, competitive realignments, and the pricing mechanisms that will shape margins across the value chain. Our latest research on the Crude Tall Oil Derivative Market delivers that visibility.
Recent headlines have touched on price actions and asset transactions across the sector, but the underlying forces are far more structural. Trade policy adjustments, biofuel mandates, and biomass regulation are simultaneously reshaping feedstock availability and end-use demand. In this environment, a disciplined, evidence-based view of the market is no longer optional. It is the foundation for capital allocation, product portfolio design, and risk management.
Why 2026 Demands a Deeper Read on Tall Oil Derivatives
The market has expanded steadily over the past half-decade, and the trajectory through the end of the decade points to continued, albeit measured, growth. From a base year perspective anchored in 2025, the industry has moved from a 2020 starting point near 2.18 billion USD to an estimated 2.65 billion USD in 2025. Looking ahead, the forecast period from 2026 through 2032 signals a steady climb, with the market projected to exceed 3.4 billion USD by 2032. This path implies a compound annual growth rate of approximately 3.88 percent, a pace that reflects durable demand from adhesives, coatings, and surfactant applications alongside emerging pull from renewable fuel streams.
Crude Tall Oil Derivative Market
Growth at this pace is not uniform. It is being filtered through a set of intersecting pressures: tightening pulp capacity in certain North American corridors due to lumber tariff effects, supply-side yield improvements at mills in Europe driven by biomass restriction rules, and demand-side substitution dynamics created by duties on alternative feedstocks. For firms that depend on tall oil fatty acids, rosin derivatives, or tall oil pitch, these forces translate into a nonlinear pricing and availability environment. The strategic question for 2026 is not whether the market is growing, but where margins will crystallize and how to secure position before structural advantages harden.
Crude Tall Oil (CTO) Market
Our analysis is built to answer that question. Rather than offering surface-level trend statements, the report maps the causal chain from regulation to mill yield, from trade policy to regional supply balance, and from competitive transactions to pricing power. This approach gives leaders a practical framework for scenario planning and for identifying where to invest, where to hedge, and where to reposition.
What the Report Delivers: An Executable View of the Value Chain
The research is designed around operational usefulness. It combines macro market sizing with a structured examination of the segments that matter most to commercial decisions, while preserving enough granularity to support product-level and application-level planning. The report content is organized to help teams move quickly from insight to action.
- Market sizing and forward outlook anchored to a 2025 base year, with a forecast window spanning 2026 through 2032, enabling multi-year budgeting, capacity planning, and long-cycle procurement strategy.
- Product-level decomposition across fatty acids, rosin derivatives, and tall oil pitch, with context on how each stream is positioned relative to demand from industrial formulations and biobased applications.
- Application-driven insights covering adhesives, coatings, and surfactants, including the demand drivers, formulation shifts, and substitution dynamics that are reshaping consumption patterns.
- Regional framing that situates North American, European, Asian Pacific, Latin American, and Middle East and Africa markets within the broader supply and demand architecture, with attention to trade flows, feedstock availability, and regulatory exposure.
- Competitive landscape assessment that profiles the leading producers, refiners, and biorefiners shaping price formation, capacity additions, and market access.
- Event-driven updates that connect recent pricing actions and asset transactions to the broader strategic narrative, helping readers interpret what is signal and what is noise.
Each section is written for application, not just observation. The goal is to give strategy, finance, and commercial teams a shared vocabulary and a consistent evidence base for cross-functional decisions. By integrating market structure with company-level developments and regulatory context, the report supports decisions about vendor selection, long-term supply agreements, product mix adjustments, and regional prioritization.
Competitive Landscape: Consolidation, Capacity, and Pricing Power
The crude tall oil derivative market is characterized by a concentrated set of active producers and refiners, with a meaningful share of revenue held by a relatively small group of companies. This concentration matters because it shapes how quickly pricing adjusts, how capacity constraints propagate, and how new supply enters the system. The leading participants span biorefining, distillation, and downstream formulation, with strong positions in fatty acids and a growing presence in renewable fuel pathways.
Several firms define the strategic center of gravity. In the United States, Kraton Corporation operates a biorefinery focused on converting crude tall oil into tall oil fatty acids and other pine-based derivatives, and it has a visible footprint as a supplier of biobased specialty chemicals and resins. Eastman Chemical Company also contributes to the market through refining and supply of tall oil fatty acids and pine chemicals for coatings, adhesives, and industrial applications. In Europe, UPM-Kymmene Oyj and Stora Enso Oyj both play foundational roles: UPM produces crude tall oil at its Lappeenranta biorefinery for conversion into renewable fuels and tall oil fatty acids, while Stora Enso extracts and supplies crude tall oil from Nordic softwood kraft pulping as a renewable feedstock for pine-based derivatives. Forchem Oyj and Fintoil Oy round out the Nordic processing landscape, with Forchem specializing in distillation and processing of crude tall oil into tall oil fatty acids and other biobased derivatives, and Fintoil operating a large-capacity biorefinery producing tall oil fatty acids and distilled tall oils for industrial use.
Outside this core cluster, the market includes additional regional specialists and integrated players. Ilim Group JSC produces and supplies crude tall oil from its Russian mills and refines it into tall oil fatty acids, adding capacity and supply reach in its operating footprint. Harima Chemicals Group, Inc. distills crude tall oil into tall oil fatty acids, rosin, and other pine-based derivatives, serving paper chemicals and electronics end markets in Japan. SunPine AB extends the value chain into raw tall diesel and other crude tall oil-derived bio-based products, linking the feedstock to renewable diesel and heating oil applications. Together, these participants illustrate the breadth of the market and the variety of routes through which crude tall oil is converted into commercial value.
Recent activity underscores how dynamic this landscape has become. Over the past year, there have been notable pricing actions and asset transactions that signal both supply tightening and portfolio realignment. In late 2025, Kraton Corporation announced a general price increase of 10 percent or higher on tall oil fatty acid products in the EMEA region. That move was followed in early 2026 by a broader global price increase of 10 to 20 percent across its crude tall oil refinery and derivatives portfolio. These adjustments reflect the interplay of demand strength, feedstock conditions, and the pricing latitude that comes with a concentrated supply base.
On the asset side, Ingevity Corporation moved to reshape its portfolio. In September 2025, it signed an agreement to sell its North Charleston crude tall oil refinery and the majority of its industrial specialties product line. The transaction was completed in January 2026, with the assets transferring to Mainstream Pine Products, LLC. This type of transaction matters because it repositions capacity and changes the competitive map, particularly in regions where refinery access and logistical reach influence commercial outcomes. For buyers and competitors alike, such moves alter availability, potential supply routes, and the negotiation dynamics that govern long-term contracts.
These developments are not isolated events. They are symptoms of a market in which access to consistent feedstock, processing capacity, and downstream market access can create durable advantages. Understanding who holds those advantages, and how they are changing, is essential for any firm that depends on tall oil derivatives as a raw material or a growth platform.
Market Dynamics: Regulation, Trade, and Feedstock Realignments
The backdrop for 2026 is defined by regulatory and trade forces that are simultaneously shaping demand and constraining or expanding supply. These dynamics do not operate in isolation; they interact, and their combined effect is what leaders need to anticipate.
On the demand side, the U.S. policy environment has introduced a notable pull factor. An EPA proposal to increase the biodiesel mandate by 56 percent for 2026 would accelerate crude tall oil consumption in U.S. biofuel blends. If implemented, this type of mandate expands the addressable market for tall oil-derived inputs and increases competition for available feedstock. At the same time, trade policy is influencing where demand migrates. EU anti-dumping duties on Chinese biodiesel, set in a range of 23.7 to 36.4 percent, have increased demand for crude tall oil as an alternative feedstock. This substitution effect redirects flows and can raise utilization at producers positioned to serve European buyers.
On the supply side, the picture is equally active. Lumber tariffs of 25 percent applied in U.S.-Canada and U.S.-Mexico trade contexts have reduced North American pulp production capacity in certain corridors, tightening crude tall oil supply where pulp operations are a primary source of the feedstock. This tightening does not simply raise prices; it changes the calculus for long-term supply agreements and for product planning in regions that depend on North American volumes. In parallel, EU RED III biomass restrictions have forced a reduction in pulp industry biomass burning, which has increased crude tall oil yields by an estimated 8 to 12 percent at mills. This yield effect partially offsets supply pressure by improving the amount of tall oil recovered per unit of pulp output, but its benefits are uneven across regions and operating models.
The strategic implication is that 2026 is a year of dual movement: demand is being amplified by biofuel policy and trade-driven substitution, while supply is being reshaped by tariffs and yield changes that are themselves policy-driven. Navigating this environment requires more than a snapshot of current pricing. It requires a forward-looking view of how mandates, duties, and biomass rules will interact with mill economics, refinery throughput, and downstream formulation needs. The report provides that view by connecting each dynamic to likely commercial outcomes and by identifying the regions and product streams where these forces will be felt first and most intensely.
Using This Research to Frame 2026 Decisions
For executives and analysts, the value of the report lies in its ability to convert complex, moving parts into a coherent decision framework. The research supports several practical uses. It can inform sourcing strategy by clarifying where feedstock availability is likely to tighten and where yield improvements or alternative supply routes may provide relief. It can guide portfolio planning by highlighting how demand is shifting across adhesives, coatings, and surfactants, and by indicating where renewable fuel pathways may create additional pull. It can support pricing strategy by contextualizing recent increases within the broader competitive and regulatory environment, helping teams distinguish structural pricing power from temporary adjustments. It can also inform capital and M&A thinking by mapping where capacity is being repositioned and where consolidation may continue.
Importantly, the report is structured to preserve analytical precision without overwhelming the reader with a wall of figures. High-level market size, growth trajectory, and concentration metrics are presented to frame the landscape, while the deeper segmentation detail is reserved for the full study. This design reflects how senior teams actually work: they need the strategic picture first, then the granular data to support specific plans. The complete research delivers that depth, including regional and application-level breakdowns, product-level context, and company profiles that together form a comprehensive intelligence package.
What the Full Study Unlocks
The summary view presented here establishes the strategic terrain, but the complete Crude Tall Oil Derivative Market research goes further. It provides the segmentation detail needed to translate market direction into product and regional plans, the competitive context needed to interpret pricing and capacity moves, and the dynamic analysis needed to anticipate the next shift in policy or trade. For teams preparing for 2026, that combination is what turns uncertainty into a manageable set of choices.
If your organization is evaluating supply commitments, product positioning, regional exposure, or investment in biobased chemical value chains, the full report offers the structured evidence required to move with confidence. The market is expanding, but expansion is being routed through a narrow set of competitive and regulatory choke points. Understanding those choke points is the difference between reacting to change and shaping your position ahead of it.
To access the complete market sizing, segmentation analysis, competitive profiles, and dynamic scenario guidance, explore the full research on the source page. The detailed intelligence there is designed to support concrete 2026 planning across commercial, procurement, and strategy functions.
For detailed analysis of this topic, please visit the official page: Crude Tall Oil Derivative Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China LED Driver market shows a sustained upward trajectory from USD 3,500 Million in 2020 to an estimated USD 8,200 Million by 2035. The consistent annual growth is attributed to increased adoption in smart cities, EV infrastructure, and industrial automation. Innovative solutions and government initiatives facilitate the expansion of this high-potential market, making China a global leader in LED driver deployment.
Read More - https://bussinessinsights.com/research-report/china-led-driver-market
General lighting accounts for the largest share of the China LED Driver market at 40% in 2025, reflecting robust demand across residential, commercial, and public sectors. Automotive lighting follows with a 30% share, supported by the rapid growth of China's electric and smart vehicle segments. Industrial lighting captures a 20% market share, highlighting increased investments in smart manufacturing and energy management. Other applications including outdoor and backlighting represent the remaining 10%.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-led-driver-market
Frequently Asked Questions
Who are the key players in China LED Driver Market industry?
Top players in the China LED Driver Market include Inventronics, Osram, Philips (Signify), Mean Well, and Lifud. These companies are recognized for their innovation, extensive product portfolios, and wide distribution networks in LED driver solutions, catering to commercial, industrial, and residential lighting applications across the Chinese market.
What is the China LED Driver Market growth?
The China LED Driver Market has witnessed steady growth, supported by increasing adoption of energy-efficient lighting. For example, Inventronics reported revenue growth in 2023, driven by rising demand for smart and connected lighting solutions in urban projects and government-led infrastructure modernization initiatives.
Which segment accounted for the largest China LED Driver Market share?
The outdoor lighting segment holds the largest share in the China LED Driver Market, driven by government investments in smart street lighting and public infrastructure projects. Outdoor applications are prioritized due to large-scale deployment in urban development and city beautification, contributing significantly to overall market revenues.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The China Flexible Battery Market has shown robust revenue growth from USD 350 million in 2020 to an anticipated USD 1,800 million by 2035. This significant uptrend is attributed to technology advancements, market expansion in consumer electronics and medical devices, and supportive government policies. Continuous product innovations are expected to propel the annual revenue further as demand for flexible power solutions grows across diverse applications including IoT devices and electric vehicles.
Read More - https://bussinessinsights.com/research-report/china-flexible-battery-market
Consumer electronics continue to lead the application segment for flexible batteries in China, driven by the surging demand for lightweight and compact devices. Wearable devices like smartwatches and health trackers constitute the second largest market segment, benefitting from the integration of ultra-flexible, safe batteries. Medical devices, leveraging the ultra-thin and biocompatible nature of these batteries, also account for a notable share, reflecting growing healthcare investments and remote monitoring trends.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-flexible-battery-market
Frequently Asked Questions
Who are the key players in China Flexible Battery Market industry?
Key players in the China Flexible Battery Market include Panasonic Corporation, Samsung SDI Co., Ltd., LG Chem Ltd., Guangzhou Fullriver Battery New Technology Co., Ltd., and Enfucell Oy. These companies are recognized for their innovation, advanced product portfolios, and strong supply chains, driving industry growth through strategic collaborations and technology investments.
What is the China Flexible Battery Market growth?
The China Flexible Battery Market has experienced substantial growth, with factors like rising adoption in wearable electronics and flexible devices. In 2023, Samsung SDI reported increased flexible battery shipments due to partnerships with China's major electronics manufacturers, thereby fueling the market expansion.
Which segment accounted for the largest China Flexible Battery Market share?
Wearable devices accounted for the largest market share in the China Flexible Battery Market. The increasing consumer demand for smartwatches, fitness bands, and health monitoring devices, combined with miniaturized, lightweight battery technology, has propelled this segment's dominance across the country.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Wine Glass Market to Hit $220.73M by 2032, Growing at 2.8% CAGR
By PW Consulting, 2026-09-16
Why the Global Wine Glass Market Report Is the Strategic Compass Your Business Needs for 2026
The global wine glass market stands at a quiet but decisive inflection point. Between 2020 and 2025, the sector moved from a post-pandemic recovery phase into steady, compounding growth, with baseline revenues climbing from USD 151.0 million to USD 183.0 million. Projections extending through 2032 outline a market trajectory that approaches USD 220.73 million by the end of the forecast window, supported by a compound annual growth rate of 2.8 percent. These numbers are not abstract industry statistics. They are the raw signals that separate companies that react defensively to margin compression and supply chain shocks from those that position their portfolios in advance. Our newly released market research is engineered to transform those signals into executable strategy for 2026 and beyond.
For executives, procurement leaders, and category managers, the value of this study lies in its decision-ready architecture. Rather than offering a retrospective data dump, the report maps the operational terrain that will shape pricing, sourcing, product mix, and competitive positioning over the next six years. It is a reference document designed for boardroom discussions, capital allocation calls, and commercial planning cycles where precision matters and guesswork must be minimized.
What the Research Delivers: A Practical Operating Framework
The study is structured around the actionable information that decision-makers actually need when they are under pressure to justify line extensions, renegotiate supplier contracts, or evaluate new distribution channels. It moves beyond headline figures to equip leaders with a repeatable analytical process they can apply directly to their own business units.
- Historical baseline and forward trajectory: The report anchors every forecast in a rigorously tracked historical sequence and then maps a forward path that captures the subtle shifts expected across the 2026 to 2032 horizon.
- Segment-level structural insight: Readers receive a clear dissection of product architecture and consumption contexts, helping identify where value is accumulating and where structural bottlenecks are forming.
- Regional demand mapping: Geographic performance is presented as a comparative landscape rather than a static list, enabling teams to understand which territories are driving momentum and which are moderating growth.
- Competitive positioning and concentration metrics: The study examines how market share is distributed among leading manufacturers and what that concentration implies for pricing leverage, entry barriers, and partnership opportunities.
- Regulatory, material, and labor dynamics: External forces are analyzed as active variables, not background noise, so that supply strategy and compliance planning can be integrated rather than bolted on after the fact.
- Recent corporate developments and launch patterns: Fresh on-the-ground activity is synthesized to show how market leaders are adjusting designs, materials, and consumer engagement strategies in real time.
This is not a report meant to sit on a shelf. It is built to guide questions such as where to concentrate innovation spend, how to think about volume versus premiumization, and which operational risks deserve immediate mitigation. The full dataset behind these frameworks is available in the complete study, where the granular breakdowns can be filtered, compared, and applied to your own internal models.
Market Size, Growth Trajectory, and the Real Meaning of a 2.8 Percent CAGR
A compound annual growth rate of 2.8 percent might appear modest at first glance, but in a mature consumer goods category it carries distinct strategic weight. It signals a market that is still expanding, yet doing so in a measured way that rewards disciplined execution over aggressive volume chasing. The revenue progression from 2025 through the early forecast years suggests that growth will not be evenly distributed. Some product families and consumption contexts will advance more quickly, while others will stabilize or face cost-driven friction. The study isolates those divergent paths so that leadership can allocate resources where incremental returns are most defensible.
The implication for 2026 planning is straightforward: a moderate CAGR demands sharper segmentation and more selective sourcing. Companies that treat the entire category as a single growth opportunity risk diluting focus. Those that understand where the structural pull is strongest, and which consumer or commercial channels are expanding faster than the category baseline, can build a more resilient revenue mix. The report gives you the scaffolding to make those distinctions without relying on intuition alone.
Wine Glass Market
Analyzing the Competitive Layer Without Getting Lost in Rhetoric
Strategic advantage in wine glass manufacturing is rarely determined by a single product launch. It comes from understanding who controls what kind of position in the value chain, how differentiated those positions are, and where consolidation or substitution could alter the balance. The research profiles the companies that shape category standards today, including Riedel Tiroler Glashutte GmbH, Libbey Inc., Bormioli Rocco, Schott AG, Josephinenhütte, Gabriel-Glas, and Spiegelau.
These organizations represent different strategic archetypes. Some compete on varietal specificity and sensory optimization, building recognition around performance-driven stemware. Others anchor themselves in durability, commercial service reliability, or universal design philosophies that simplify product ranges. A few emphasize lightweight construction, thermal resistance, or premium hand-finished lines. The study does more than summarize brand narratives. It evaluates how each player's positioning interacts with the broader demand environment, where their approaches converge, and where they deliberately diverge to protect margin or defend distribution.
What recent activity tells us about the near-term direction
Recent corporate actions already signal how the category is being reshaped. Riedel, for example, has continued expanding its consumer engagement footprint with high-profile tasting experiences and new collections that emphasize thinner, machine-blown designs alongside hand-crafted premium lines. Parallel activity in the retail and experiential channel, such as exclusive stemless souvenir introductions at regional wine expos, points to a mindset shift: packaging and vessel design are increasingly treated as part of the tasting moment rather than as passive serving items.
For strategy teams, the practical value lies in pattern recognition. When leading manufacturers adjust material profiles, refine product aesthetics, and invest directly in consumer-facing events, they are testing which value propositions still resonate. The report distills these developments into comparable strategic signals so your organization can judge whether you are aligned with the direction the market is taking or still responding to yesterday's assumptions.
The Regulatory and Supply-Side Reality: Why 2026 Demands Scenario Planning
External pressures are no longer side considerations. They are central inputs into pricing, sourcing, and product design decisions. The study incorporates the most consequential industry dynamics currently affecting the wine glass and broader wine service ecosystem, including regulatory proposals, energy-intensive production realities, tariff exposure, and labor-side capacity adjustments.
- Labeling and transparency pressure: Proposed changes to mandatory alcohol facts statements, including calorie and nutrient disclosures, have the potential to reshape how product information is presented and how consumer expectations evolve around beverage service.
- Production energy intensity: Glass manufacturing remains a high-temperature, energy-heavy process, which has direct implications for cost stability, sustainability narratives, and long-term supply resilience.
- Import cost exposure: Tariff actions affecting imported wine create downstream pressure on packaging and service costs for importers, altering the economics of the broader wine service chain.
- Capacity and labor adjustments: Significant facility closures and workforce reductions among major glass producers highlight how sensitive the supply base can be to demand shifts and cost structures, reinforcing the need for diversified sourcing strategies.
This is exactly why the report includes scenario-oriented analysis rather than a single static forecast. Decision-makers need to understand how an increase in compliance complexity, a change in import economics, or a disruption in production capacity might interact with their own operating model. The research helps translate those external variables into concrete planning questions about supplier redundancy, cost pass-through feasibility, and product design flexibility.
Why the Complete Study Matters for 2026 Decision-Making
Macro indicators and executive summaries can inform a conversation, but they rarely replace the kind of detailed intelligence required to set budgets, choose priorities, or defend a go-to-market plan. The complete market research provides the working-level detail that turns high-level insight into operational readiness. It enables you to compare structural opportunities across product categories, consumption settings, and regional contexts without having to reconstruct the analysis from fragments.
More importantly, the study preserves analytical integrity. It distinguishes what is supported by evidence from what is merely plausible, and it organizes that distinction in a way that is useful for cross-functional teams. Commercial leaders can use it to sharpen assortment thinking. Procurement teams can use it to frame sourcing resilience. Strategy and executive teams can use it to benchmark concentration, competitive behavior, and the likelihood of margin pressure in specific segments.
The report is also designed with a clear purpose: to make your next decision faster and better informed. Whether your team is evaluating a new premium line, analyzing the durability of a commercial channel, or preparing for regulatory cost implications, the research supplies a shared evidence base that reduces internal friction and shortens the path from question to answer.
Looking Ahead: Use This Intelligence to Shape 2026 With Confidence
The wine glass market is not defined by sudden disruption. It is defined by cumulative choices: what to produce, what to source, where to emphasize design, and how to respond when regulatory and supply conditions shift. In that environment, strategic clarity is a competitive asset. The companies that outperform will be the ones that understand the category's growth logic, read competitive signals early, and build operating flexibility into their plans before pressure arrives.
Glassware Market
This market research is intended to give you that clarity at the moment you need it. It provides the structure to assess where the market is heading between 2026 and 2032, the competitive context to interpret who is winning and why, and the external dynamics to stress-test your assumptions against real-world variables. To access the full segmentation detail, comparative regional insight, and company-level intelligence that support these strategic conclusions, refer to the complete PW Consulting market research. The comprehensive dataset is where the operational specifics live, and where your 2026 decisions can be grounded with confidence.
For detailed analysis of this topic, please visit the official page: Wine Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Revenue in the China Portable Battery Pack Market reached USD 4,200 Million in 2025 and is projected to grow steadily, reaching USD 8,900 Million by 2030 and surpassing USD 13,800 Million by 2035. The robust growth reflects increased power requirements from proliferating smart devices and EVs, continuous advancements in battery technology, and expansive distribution across both online and offline retail channels. This upward trajectory underscores the market’s resilience to shifting consumer patterns and technological disruption.
Read More - https://bussinessinsights.com/research-report/china-portable-battery-pack-market
Smartphones remain the largest application segment, accounting for 45% of market share in 2025. Tablet and laptop use follows, comprising 25%, as remote work and e-learning accelerate electronics usage. Automotive applications, such as EV accessories and onboard electronics, capture 16%, while wearables and other segments represent 14%. This distribution highlights the market’s core dependence on personal electronics, with gradual diversification driven by automotive innovation and growth in IoT devices.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-portable-battery-pack-market
Frequently Asked Questions
Who are the key players in China Portable Battery Pack Market industry?
The top five players in the China Portable Battery Pack Market are Xiaomi, Anker Innovations, Romoss, Pineng, and Yoobao. Xiaomi is renowned for its innovative products; Anker excel in battery technology; Romoss is popular for high-capacity models; Pineng focuses on affordable, reliable packs; Yoobao offers versatile charging solutions.
What is the China Portable Battery Pack Market growth?
The China Portable Battery Pack Market is witnessing steady growth, primarily driven by increased smartphone and smart device penetration. In 2023, Xiaomi reported a surge in portable battery sales as consumers demanded faster, higher-capacity options. The market is projected to grow at a CAGR of around 9% during 2024-2029.
Which segment accounted for the largest China Portable Battery Pack Market share?
The smartphones and tablets application segment dominates the China Portable Battery Pack Market, accounting for the largest share. With the widespread use of mobile devices and growing reliance on continuous connectivity, demand for portable battery packs supporting mobile charging has risen significantly across urban and rural areas.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The China Hall-Effect current sensor market revenue has seen consistent growth, beginning at $350 million in 2020 and projected to reach $1,175 million by 2035. The compound annual growth rate (CAGR) reflects rising demand across varied sectors: automotive, renewable energy, and industrial modernization. By 2025, market value is estimated at $540 million, with strong momentum expected as China’s electrification and automation initiatives broaden.
Read More - https://bussinessinsights.com/research-report/china-hall-effect-current-sensor-market
Automotive remains the leading application for Hall-Effect current sensors in China for 2025, with a 38% share driven by EV and hybrid market expansion. Industrial applications occupy 34% as factories modernize for energy efficiency and automation. Consumer electronics, thanks to miniaturized and energy-efficient sensors, make up 18%. Renewable energy and telecom contribute the remaining 10%, with the growing infrastructure demanding constant power monitoring and management.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-hall-effect-current-sensor-market
Frequently Asked Questions
Who are the key players in China Hall-Effect Current Sensor Market industry?
The key players in the China Hall-Effect Current Sensor Market include Allegro MicroSystems, LEM International, Asahi Kasei Microdevices, TDK Corporation, and Honeywell International. These companies lead the market by focusing on innovation, strategic partnerships, extensive distribution networks, and a broad portfolio catering to automotive, industrial, and energy sectors.
What is the China Hall-Effect Current Sensor Market growth?
The China Hall-Effect Current Sensor Market has witnessed significant growth, with an estimated CAGR of over 9% during 2022-2024. Recent growth is attributed to increasing adoption of electric vehicles and industrial automation, with Allegro MicroSystems expanding its production and collaborations in China to meet surging demand.
Which segment accounted for the largest China Hall-Effect Current Sensor Market share?
The automotive application segment accounted for the largest market share in China, driven by rising electric vehicle (EV) and hybrid vehicle production. Hall-Effect current sensors are extensively used for battery management, powertrain, and charging infrastructure, supported by government energy-saving initiatives and industry electrification trends.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Benefits Admin Software Market Hits $200M in 2025, Forecasts 10.23% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Modern Benefits Administration Software Market: A 2026 Outlook
The benefits administration software market is undergoing a structural transformation driven by regulatory complexity, workforce expectations, and the rapid infusion of artificial intelligence into core HR technology stacks. As organizations navigate post-pandemic benefits redesign, rising healthcare inflation, and evolving compliance requirements, the strategic function of benefits administration software has expanded far beyond enrollment and payroll reconciliation. It now sits at the intersection of employee experience, financial stewardship, and risk management. Our latest Benefits Administration Software Market research was commissioned to cut through the noise and provide enterprise decision-makers with a rigorous, forward-looking framework for evaluating vendor selection, technology investment, and competitive positioning through 2032.
This article previews the strategic architecture of that study. Rather than offering surface-level vendor lists or incremental trend commentary, the report delivers a disciplined market model, competitive intelligence, and operational benchmarking designed to inform capital allocation, digital transformation roadmaps, and compliance strategy. What follows is a guided introduction to the market forces, segmentation logic, competitive dynamics, and content architecture embedded in the full research package. The core quantitative estimates, granular regional and application splits, and detailed company scoring matrices are intentionally reserved for the complete deliverable, ensuring that executives who engage with the source report receive actionable, decision-grade intelligence rather than recycled summary data.
The Macro Trajectory: Why Benefits Administration Software Is Entering a New Growth Cycle
The global benefits administration software market has demonstrated durable expansion over the past half-decade, with total revenue climbing steadily as enterprises migrated from manual, spreadsheet-driven processes to integrated, cloud-enabled platforms. Looking across the historical tracking window and forward forecast horizon, the market has entered a phase of accelerated monetization tied to digital transformation mandates, compliance automation, and payroll-to-HR system consolidation. The research models a compound annual growth rate of 10.23 percent across the forecast period, reflecting sustained demand for platforms that can simultaneously manage enrollment, eligibility verification, carrier connectivity, and regulatory reporting at enterprise scale.
Several structural drivers underpin this trajectory. First, regulatory complexity continues to raise the cost of non-compliance. Employers face escalating exposure to penalties tied to minimum essential coverage, HIPAA-mandated data security controls, and state-level continuation coverage requirements. These obligations are not static; they intensify with inflation indexing and evolving enforcement expectations, creating a persistent need for software that can automate compliance logic rather than rely on manual interpretation. Second, the financial burden of administering benefits through generalized HRIS platforms has prompted organizations to evaluate dedicated benefits solutions that deliver greater workflow precision, carrier integration depth, and ROI clarity. Third, employee expectations around self-service, mobile accessibility, and personalized benefit selection have shifted administrative software from a back-office utility into a frontline retention and engagement tool.
Within the forecast timeline, market expansion is projected to accelerate in the latter years, with total revenue expected to surpass the 300 million threshold by the close of the decade and approach the 400 million mark by 2032. This growth path reflects more than incremental adoption. It signals a maturation cycle in which mid-market and large enterprise buyers are consolidating fragmented vendor relationships, upgrading legacy systems, and embedding benefits workflows into broader workforce management architectures. The strategic implication for 2026 decision-makers is clear: the window for optimizing benefits technology is narrowing, and the cost of deferred modernization is rising in both compliance risk and operational friction.
Market Segmentation Logic and Strategic Dimensions
Effective vendor evaluation and investment planning require a segmentation framework that aligns with how buyers actually purchase, deploy, and scale benefits technology. The research structures the market across multiple strategic axes, each designed to illuminate distinct purchasing behaviors, technology adoption patterns, and operational priorities.
- Organizational scale continues to be a defining determinant of technology strategy. Large enterprises typically prioritize comprehensive integration, multi-carrier connectivity, and advanced compliance automation, while small and medium enterprises often seek streamlined onboarding, predictable pricing, and packaged self-service capabilities. The division of revenue between these segments reflects contrasting purchasing velocity, implementation complexity, and vendor preference.
- Deployment architecture remains a critical selection factor as buyers weigh agility against control. Cloud-based platforms dominate contemporary procurement decisions because they reduce infrastructure burden, accelerate feature updates, and enable broader user accessibility. However, on-premises and hybrid configurations retain relevance for organizations with stringent data governance requirements, legacy system dependencies, or specialized security protocols.
- Geographic distribution shapes both vendor strategy and buyer expectations. Regional dynamics influence compliance regimes, carrier ecosystems, compensation structures, and the maturity of digital benefits adoption. The research captures these variations to help organizations assess market opportunity, competitive intensity, and localization requirements across major economic zones.
Rather than presenting segmentation as a static data table, the report analyzes how these dimensions intersect. For example, it examines how cloud adoption compounds differently across organization sizes, how regional compliance burdens reshape feature prioritization, and how buyers typically sequence implementation priorities when migrating from HRIS-embedded benefits to dedicated administration platforms. This layered approach enables buyers to map their own operating profiles against broader market behavior and identify where their deployment strategy may expose them to inefficiency or competitive lag.
Competitive Dynamics and the Battle for Platform Relevance
The competitive landscape is concentrated yet diverse, with a mix of large HCM incumbents, specialized benefits administration providers, and emerging all-in-one workforce platforms competing on integration depth, compliance automation, user experience, and intelligent feature sets. The research provides detailed company profiles, capability assessments, and strategic positioning analysis to help buyers distinguish between vendors that offer genuine differentiation and those that rely primarily on brand recognition or bundled pricing.
Benefits Administration Software Market
Several established players anchor the market through broad HCM ecosystems that embed benefits administration within wider payroll, time, talent, and HR workflows. These platforms appeal to organizations seeking operational consolidation and unified data models. Their value proposition centers on end-to-end continuity, carrier integrations at scale, and compliance workflows designed to reduce manual oversight. At the same time, dedicated benefits administration specialists compete by emphasizing enrollment optimization, eligibility precision, member-facing self-service, and regulatory reporting rigor. Their advantage often lies in workflow specificity, carrier connectivity breadth, and the ability to tailor benefits experiences without forcing buyers into a full HCM replacement cycle.
A third competitive current is being shaped by platform companies that treat benefits as one module within a broader operational stack spanning IT provisioning, workforce management, and employee services. These offerings attract organizations pursuing operational simplification and unified dashboards, particularly when benefits administration must connect tightly to payroll, devices, access management, and cross-functional employee data flows. The strategic question for buyers is not whether a platform is broad or specialized, but whether its architecture aligns with the organization's implementation capacity, compliance risk profile, and long-term system consolidation plans.
The report also incorporates competitive intelligence around recent product momentum and innovation signals. For instance, the market has seen heightened activity around AI-driven personalization, mobile self-service enhancements, billing visibility improvements, and expanded carrier and partner connectivity. Recent updates from leading providers underscore a shift toward smarter administrative guidance, more transparent financial tracking, and conversational or recommendation-based tools that help employees navigate complex plan options. Separately, new market entrants and adjacent platform launches announced in early 2026 extend the competitive perimeter, particularly around AI-powered benefits administration targeting insurance agencies and healthcare operations contexts. These developments matter because they indicate where vendors are placing bets on differentiation and where buyers should expect feature escalation in the next procurement cycle.
Market concentration remains notable, with a substantial share of revenue held by a limited set of leading providers. This concentration has practical implications for negotiation leverage, integration roadmaps, and platform switching costs. Buyers must assess not only current capability but also the likelihood that a vendor will continue to invest in the specific workflows, compliance logic, and data interoperability their organization requires. The research addresses these issues through structured evaluation criteria that go beyond feature checklists and into strategic fit, scalability, and innovation cadence.
Regulatory Pressure, Cost Economics, and Operational Reality
No benefits administration technology evaluation is complete without a clear view of the regulatory and economic forces that shape both platform requirements and total cost of ownership. The research treats compliance not as a feature footnote but as a core design constraint that influences product architecture, implementation effort, and long-term administrative burden.
On the regulatory side, employers must contend with overlapping obligations that vary by organization size, workforce composition, and jurisdiction. Compliance workflows increasingly demand automated tracking for coverage adequacy, secure handling of protected health information, encryption standards, role-based access controls, and ongoing reporting for continuation coverage mandates at the state level. For applicable large employers, the financial stakes of coverage noncompliance can be substantial and are subject to inflation-indexed adjustments. These realities elevate the importance of software that embeds regulatory logic directly into enrollment, eligibility, and reconciliation processes rather than requiring manual monitoring outside the platform.
Worldwide Financial Wellness Benefits Market
On the cost side, the operational economics of benefits administration are prompting organizations to reassess how much administrative overhead is acceptable when benefits are processed through generalized HRIS environments. Dedicated benefits solutions are increasingly evaluated on their ability to reduce manual intervention, streamline carrier billing reconciliation, and improve the accuracy of deductions and eligibility determinations. The research incorporates this economic dimension by examining how buyers justify technology investment through efficiency gains, risk reduction, and improved employee experience outcomes, rather than treating software spend as an isolated administrative expense.
Together, these dynamics shape a market in which buyers are less interested in incremental feature expansion than in platforms that deliver measurable operational improvement, compliance assurance, and scalable employee engagement. The report's analysis reflects that shift, positioning benefits administration software as a strategic system rather than a tactical utility.
What the Report Delivers: A Framework for 2026 Decision-Making
The full Benefits Administration Software Market research was constructed to support concrete executive and procurement decisions. Its contents are organized to move from market structure to competitive reality to implementation planning, providing a comprehensive basis for investment strategy, vendor comparison, and digital roadmapping.
- Executive market overview and growth trajectory analysis that situates current market size within a multi-year forecast, giving leadership a calibrated view of where the market is heading and how quickly adoption is expected to evolve.
- Segmentation analysis across organization size, deployment model, and regional dynamics, designed to help buyers benchmark their own profile against market behavior and identify where their procurement priorities align with broader demand patterns.
- Competitive landscape assessment covering core providers, platform positioning, capability emphasis, and recent product developments, enabling side-by-side evaluation without relying on marketing narratives.
- Regulatory and operational context that frames compliance obligations, data security expectations, and cost-efficiency pressures as central selection criteria rather than peripheral considerations.
- Practical intelligence for vendor evaluation, including the types of workflow, integration, and automation capabilities that distinguish leading platforms in real implementation settings.
Throughout the report, data is used to support judgment rather than replace it. The analysis emphasizes where market momentum is strongest, which capabilities are becoming table stakes, and how competitive differentiation is increasingly tied to personalization, mobile usability, carrier connectivity, and AI-assisted administration. This framing helps organizations prioritize what to evaluate, what to negotiate, and what to validate during proof-of-concept or implementation planning.
Why 2026 Is a Pivotal Year for Benefits Technology Strategy
For 2026 planning cycles, benefits administration software decisions carry heightened strategic weight. The convergence of regulatory exposure, employee experience expectations, and platform consolidation economics means that organizations can no longer treat benefits technology as a static purchase. The market's growth trajectory, competitive intensity, and innovation cadence are all pointing toward a smaller number of platforms achieving outsized relevance for enterprises seeking efficiency, compliance assurance, and differentiated employee engagement.
At the same time, the abundance of vendor claims makes disciplined evaluation more important than ever. Buyers need a clear framework for separating integrated convenience from genuine benefits administration depth, for understanding where deployment architecture affects long-term cost, and for anticipating how regulatory and cost pressures will influence platform requirements over the forecast horizon. The research was designed to provide that framework.
The preview above outlines the analytical orientation, market logic, and competitive context embedded in the study. The full report expands on these themes with detailed market sizing, segmentation evaluation, vendor profiling, and forward-looking scenario analysis intended to support procurement strategy, budgeting, and enterprise technology planning. For decision-makers seeking a precise, evidence-based basis for allocating benefits technology investment in 2026 and beyond, the complete research offers the depth required to move from general awareness to confident action.
For detailed analysis of this topic, please visit the official page: Benefits Administration Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tape Measures Market Hits USD 215M in 2025, Projected 4.75% CAGR Through 2032
By PW Consulting, 2026-09-16
Beyond the Blade: Strategic Intelligence for the 2026 Tape Measures Market
The global tape measure industry is a deceptively complex sector where incremental engineering, material science, and compliance considerations converge to shape purchasing decisions across construction, woodworking, and industrial trade ecosystems. What appears at the surface as a simple hand tool is in reality a performance-critical instrument calibrated to exacting tolerances, evolving material standards, and regional compliance frameworks. For executives, procurement leaders, and market strategists navigating the 2026 landscape, understanding the underlying mechanics of demand, competitive positioning, and regulatory influence is no longer optional. It is a strategic imperative.
As organizations recalibrate their go-to-market strategies and supply chain investments for the coming decade, this market intelligence briefing offers a structured, forward-looking view of the tape measures industry. Drawing on rigorous historical analysis and calibrated forecasting through 2032, our latest research unpacks the forces that will determine volume trajectories, category rotation, and competitive intensity across mature and emerging trading environments. The findings are designed to inform product road-mapping, channel prioritization, compliance readiness, and merger or acquisition screening with a level of precision that generic industry summaries cannot deliver.
Market Trajectory and Structural Momentum
The tape measures market has evolved through a period of disciplined expansion, shaped by steady reconstruction activity, sustained professional trade demand, and gradual material substitution trends that reward durability and measurement reliability. Historical data spanning the past half-decade reveals a resilient revenue base that has absorbed cyclical fluctuations while maintaining a consistent upward trajectory. From a global revenue perspective measured in USD millions, the industry recorded sequential growth through 2020 to 2025, with 2025 closing at approximately 215.0 million. Looking ahead, the forecast window from 2026 through 2032 projects continued expansion, with 2026 establishing an opening baseline of roughly 225.5 million and forward estimates extending well past the 290 million threshold by the close of the decade.
This growth profile is underpinned by a compound annual growth rate projected at 4.75 percent across the 2026–2032 horizon. Such a rate signals more than steady-state expansion; it reflects shifting adoption patterns, incremental premiumization in professional-grade tooling, and expanding commercial and industrial measurement requirements that reward precision-engineered products. The forecast environment also reflects a market that is neither purely commodity-driven nor fully insulated from price competition. Instead, it is a segment where differentiated blade technology, ergonomic design, reinforced housings, and certification-backed accuracy create defensible positioning for brands that can consistently deliver on job-site performance standards.
Importantly, the structural momentum observed in the historical series does not guarantee uniform distribution across the forecast period. Cyclical construction activity, raw material cost dynamics, and regulatory refreshes can alter the pace of demand migration between product categories and end-use channels. Our analysis accounts for these variables by mapping growth drivers against material constraints and compliance milestones, enabling decision-makers to anticipate where volume concentration and margin exposure are likely to intensify.
Competitive Architecture and Strategic Positioning
The competitive landscape of the tape measures market is defined by a concentrated group of established tool manufacturers alongside specialized producers that compete on precision, material innovation, and professional-grade durability. Industry concentration metrics indicate that the top three participants command approximately 34.5 percent of total market revenue, while the top five extend their combined share to roughly 45.2 percent. This level of concentration suggests meaningful brand equity, established distribution relationships, and sustained investment in product differentiation, but it also leaves considerable room for regional specialists and performance-focused entrants to capture share through targeted engineering or niche application alignment.
At the center of this arena, Stanley Black & Decker operates as a foundational force, leveraging its LEVERLOCK platform and NIST-traceable certifications to anchor professional trade credibility. Its DeWalt portfolio extends this positioning through durable standout-blade designs built for construction and trade environments where visibility, reliability, and ruggedization drive repeat purchase behavior. Milwaukee Electric Tool reinforces the professional segment with its STUD series and wide-blade formats, pairing reinforced bodies with job-site durability that appeals to contractors seeking reduced failure rates under demanding use conditions.
Tape Measures Market
Parallel to these global-scale players, a second tier of competitive differentiation emerges from firms that emphasize material-specific advantages and ergonomic control. Crescent Lufkin has built a distinctive identity around its Shockforce series, incorporating diamond-coated hooks and high-contrast blades to improve grip, hook retention, and reading clarity under variable site conditions. Tajima Tool Corporation advances its GS-LOCK and GS-25 offerings with SIGMA STOP functionality and compatible clip systems, expanding accessory interoperability and user consistency across structured measuring workflows. Komelon USA contributes to this ecosystem through fiberglass and True Control tape measures, emphasizing dual-sided printing and intuitive retraction behavior that supports faster, more accurate field use.
Irwin Tools enters the conversation with Strait-Line tape measures that utilize finger-brake retraction for more controlled blade management, addressing the fine motor requirements of precision layout work. Keson Industries supplies open-reel and professional fiberglass formats tailored to industrial and construction applications where extended reach and durability intersect. Ullman Devices Corporation focuses on precision measuring tools for trades and survey-oriented workflows, reinforcing the market’s dependence on accuracy assurance beyond basic consumer applications. Great Wall Precision Industrial Co., Ltd. supports broader segment needs with steel tape measures and measuring tools aligned to ISO 9001 and CE standards, reflecting the growing relevance of standardized manufacturing discipline in globally sourced tooling. Stabila Measuring Tools contributes ergonomic BM series and professional-grade formats designed to maintain measurement fidelity while reducing user fatigue. The Perfect Measuring Tape Company, with assembly heritage dating back to 1912, continues to serve surveyor and construction segments through precision-focused domestic manufacturing. Hoechstmass adds a complementary dimension through flexible and roller tape measures, including digital options for tailoring and industrial contexts. Empire Level rounds out the competitive mosaic with reinforced safety and underground tape measures integrated into broader hand-tool assortments.
Recent commercial activity underscores how competition is intensifying through product refreshes, catalog expansion, and performance benchmarking. Tajima Tool Corporation released its E-Catalog 2026, highlighting GS-LOCK compatible clips and SIGMA STOP tape measures, signaling continued investment in accessory interoperability. Crescent Lufkin introduced second-generation Shockforce series tape measures with 360-degree diamond-coated hooks, demonstrating a clear focus on hook durability and field usability. Komelon USA launched its True Control tape measure, assigning emphasis to an intuitive retraction disc and a compact case form factor. Meanwhile, Pro Tool Reviews published a head-to-head evaluation of leading 2026 tape measures spanning Milwaukee, DeWalt, Stanley, Irwin, Tajima, Komelon, and Crescent Lufkin, reinforcing the market’s increasing reliance on comparative performance validation as a purchasing influence.
Regulatory Forces Shaping the Demand Environment
Regulatory specifications are becoming a more visible filter in the tape measures market, especially where measurement accuracy intersects with commercial transactions and professional trade standards. NIST Handbook 44-2026, approved in December 2025, establishes specifications and tolerances for weighing and measuring devices used in commerce, extending the compliance conversation beyond industrial metrology into everyday trade tooling. Within this framework, a 1.82-meter tape used for buying and selling goods must meet accuracy requirements of within 0.79 millimeters, equivalent to 1/32 inch, and maintain that tolerance as a baseline for commercial use.
For manufacturers, distributors, and procurement teams, these specifications are more than technical footnotes. They influence claim substantiation, product positioning, and the perceived risk profile of lower-cost alternatives that may struggle to consistently meet tolerance thresholds under field conditions. As buyers become more attentive to certification, traceability, and measurement reliability, products with documented accuracy alignment can command stronger positioning in professional and compliance-sensitive channels. At the same time, regulatory evolution introduces a dual dynamic: it can consolidate demand for certified, repeatable products while pressuring manufacturers to validate design choices, quality control processes, and labeling claims across regional market entry points.
In parallel, raw material composition remains central to product differentiation and cost structure. Steel and fiberglass continue to serve as the primary raw materials for tape measures, with each material pathway carrying distinct trade-offs in flexibility, ruggedness, weight, and application suitability. Steel-dominant formats typically reinforce durability and blade rigidity for construction and heavy-duty use cases, while fiberglass alternatives address corrosion-sensitive environments and extended-reach scenarios where non-conductive or lighter-weight properties matter. The interplay between these material choices and end-user requirements continues to shape segment preferences and influences how manufacturers balance performance claims against input cost volatility.
What the Full Study Delivers for 2026 Decision-Making
This market research goes beyond headline sizing and top-line forecasts to build an operational intelligence framework for companies making investment, sourcing, and product strategy decisions in 2026 and beyond. The study is structured to help leadership teams answer practical questions about where demand is expanding, which product attributes are gaining commercial weight, and how competitive forces are likely to shift under evolving compliance and material conditions.
At the analytical core, the report combines historical market reconstruction with a forecast model stretching from 2026 to 2032. It situates the overall revenue progression within a broader set of segmentation lenses, enabling readers to understand how growth is distributed across product types, application environments, and regional markets without reducing the analysis to static averages. This framing is essential because aggregate growth can obscure important variance: one segment may be consolidating around premium features, another may be responding to material substitution, and another may be expanding based on construction activity or industrial maintenance cycles.
Equally important, the study examines the competitive field through company-level profiling and recent commercial moves, allowing readers to assess not only who competes but how they compete. Product architecture, certification posture, blade engineering, retraction control, hook design, case durability, and accessory compatibility are treated as strategic variables rather than marketing claims. By connecting these product-level attributes to broader market concentration patterns, the report helps executives evaluate where brand strength is likely to persist and where disruption opportunities may emerge for new entrants or channel-focused challengers.
The research also integrates regulatory and material context into the demand narrative, so that strategic planning reflects the compliance environment as a market force rather than a separate legal consideration. Readers will find structured assessment of how tolerance expectations, commercial-use requirements, and material inputs interact with product positioning, market entry, and buyer decision criteria. This integrated approach is particularly valuable for companies evaluating new product introductions or regional expansion, where misalignment with compliance expectations or material demand realities can quickly erode anticipated returns.
From an operational standpoint, the report is designed to support:
Measuring Tape Market
- Product portfolio decisions that align engineering priorities with segment-level demand signals and competitive gaps
- Commercial planning that anticipates where professional trade buyers and industrial purchasers are likely to prioritize durability, accuracy, and certification-backed confidence
- Supply chain and sourcing review informed by material dependency patterns and the broader raw material mix shaping cost and performance differentiation
- Competitive benchmarking grounded in product launches, catalog activity, and performance evaluations that influence buyer perception in 2026
- Strategic scenario planning that translates forecast trends into practical considerations for capacity, assortment, and channel emphasis
Every section is built to function as a decision-support asset rather than a static market description. The objective is to give executives, category leaders, and strategy teams a clearer line of sight into where value is being created, what attributes are paying off in the field, and how the market is likely to evolve under the combined influence of construction activity, trade professionalism, compliance tightening, and product innovation.
Why This Intelligence Matters Now
The tape measures market is entering a period in which performance differentiation, certification awareness, and material-driven value propositions will increasingly determine competitive outcomes. A 4.75 percent CAGR across the forecast period indicates sustained expansion, but the strategic value lies in understanding which sub-segments, product attributes, and commercial channels will absorb that growth most effectively. For suppliers and distributors operating in 2026, the difference between average execution and superior positioning will often come down to insight: knowing where precision matters most, where hook and blade engineering drives loyalty, and where regulatory expectations are reshaping buyer preferences.
This is precisely the space the full study is designed to fill. It converts historical momentum, forecast trajectory, competitive activity, and regulatory context into a coherent strategic map for the years ahead. The report does not simply describe the market; it equips decision-makers with the analytical structure needed to interpret change before it becomes visible in quarterly results.
For those responsible for product strategy, channel development, competitive positioning, or regional expansion, the complete findings provide the depth required to move from observation to action. The detailed segmentation analysis, company profiles, and market dynamics assessment are available through the full market research report. Accessed in its entirety, the study offers the comprehensive intelligence needed to plan with confidence in a market where small differences in measurement performance can translate into measurable differences in commercial outcomes.
For detailed analysis of this topic, please visit the official page: Tape Measures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com