

Blogs
PW Consulting: B2B E-commerce Sales Hit $32.11T in 2025, Surge to $70T by 2032 at 16.64% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the B2B E-commerce Era: Navigating the 2026 Market Landscape
The business-to-business e-commerce sector has evolved from a transactional convenience into a strategic imperative for enterprises seeking scalable, data-driven procurement and sales ecosystems. As organizations confront shifting supply chain architectures, rising digital expectations, and complex regulatory environments, decision-makers require more than surface-level market summaries. They need precise, actionable intelligence that maps technological adoption patterns, competitive positioning, and structural growth trajectories. Our latest B2B E-commerce Market study delivers exactly that: a rigorously validated analysis designed to inform capital allocation, platform selection, and long-term commercial strategy across 2026 and beyond.
This market research does not merely track headline figures. It decodes the operational and structural forces driving commercial transformation, offering executives a clear lens through which to evaluate platform investments, partnership opportunities, and market entry strategies. By synthesizing historical performance with forward-looking projections, the report equips procurement leaders, IT architects, and revenue operations teams with the clarity needed to navigate an increasingly fragmented and fast-moving commercial landscape.
A Trajectory of Sustained Expansion: Market Scale and Context
The B2B e-commerce market has demonstrated remarkable resilience and growth momentum over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward curve, reflecting accelerated digital adoption across manufacturing, wholesale distribution, and enterprise services. This trajectory has positioned the sector at a pivotal inflection point as it moves into the 2026-2032 forecast window. The projected compound annual growth rate underscores a market that is not simply recovering from post-pandemic digitization, but actively restructuring how businesses discover, evaluate, and purchase commercial goods and services.
Our analysis captures the full arc of this expansion, tracking how foundational adoption phases have given way to more sophisticated commercial architectures. Enterprises are no longer treating B2B e-commerce as an isolated sales channel. Instead, they are embedding digital procurement and wholesale ordering into broader operational frameworks, demanding platforms that can handle complex pricing structures, multi-tier account management, and integrated financial workflows. The report contextualizes these shifts within broader macroeconomic and technological trends, providing decision-makers with a grounded understanding of why growth is accelerating and where it is likely to concentrate.
What the Report Delivers: Actionable Intelligence for Executives
Market intelligence only creates value when it translates into executable strategy. This study is structured to bridge the gap between high-level market observation and on-the-ground operational planning. The report provides a comprehensive mapping of platform capabilities, procurement workflow requirements, and technological integration patterns that define modern B2B commercial environments. Readers will find detailed examinations of how leading solutions address order complexity, custom quoting, inventory synchronization, and account hierarchy management, along with practical guidance on evaluating platform fit against organizational scale and industry-specific procurement models.
- Platform evaluation frameworks that align technical architecture with commercial objectives, including headless and composable deployment models
- Workflow optimization insights covering purchase order automation, approval routing, and self-service buyer portals
- Integration readiness assessments that examine ERP connectivity, quote-to-cash processes, and cross-channel inventory visibility
- Adoption roadmaps that differentiate between rapid-deployment solutions and enterprise-grade customization requirements
- Risk and compliance considerations tied to data governance, pricing transparency, and multi-region operational constraints
Beyond platform comparisons, the report dissects the structural dynamics influencing buyer behavior and seller readiness. It examines how procurement teams are redefining vendor selection criteria, how wholesalers and distributors are balancing digital self-service with relationship-driven sales, and how technological investments are reshaping margin structures and order fulfillment timelines. Every section is designed to support concrete decision-making, whether the objective is platform migration, market expansion, or competitive repositioning.
Competitive Dynamics and Platform Evolution
The B2B e-commerce platform landscape is defined by a concentrated yet highly differentiated group of technology providers. Market concentration metrics indicate that a small cohort of dominant players controls a substantial share of enterprise deployments, yet the competitive environment remains intensely active as vendors race to capture specialized use cases and regional demand. Leading platforms have moved beyond generic storefront functionality, investing heavily in features that address the unique friction points of business procurement: tiered pricing, negotiated contracts, multi-purchaser account structures, and seamless financial reconciliation.
Shopify has expanded its B2B capabilities to support unified commerce operations, offering manufacturers, wholesalers, and distributors self-serve purchasing, volume-based pricing, and structured account management. BigCommerce has positioned its B2B Edition around headless and composable architectures, emphasizing corporate account management, advanced pricing logic, purchase order automation, and approval workflows tailored to wholesale and distribution operations. Adobe Commerce provides an optimization suite built for large enterprises, featuring personalized catalogs, hierarchical buyer accounts, multi-purchaser roles, and self-service portals that accommodate complex organizational buying structures.
commercetools has pursued a composable approach with pre-built solutions for manufacturing environments and custom purchasing journeys, leveraging API-first flexibility to support enterprise B2B sales at scale. Oracle NetSuite Commerce integrates its B2B offering directly with ERP systems, enabling business buyer sites, quote requests, account management, and invoice payment workflows within a unified financial ecosystem. OroCommerce targets distributors, wholesalers, and manufacturers with enterprise-grade functionality that supports custom pricing, high-SKU catalogs, and multi-model licensing spanning B2B, B2C, and B2B2X scenarios. NuORDER, operating under Lightspeed, delivers a closed-loop wholesale platform that connects brands and retailers through POS and e-commerce integration, real-time inventory visibility, and automated ordering. Shopware rounds out the competitive field with B2B components designed for customized commerce platforms, supporting complex workflows, B2B and direct-to-consumer unification, and automated business processes for distributors and manufacturers.
The competitive environment has also been shaped by recent strategic developments that signal where the market is heading. In mid-2026, Shopware partnered with Smart Solutions to deliver compliance, strategy, and seamless B2B/B2C e-commerce solutions for complex business models, reflecting a broader industry push toward integrated consulting and technology delivery. Earlier that year, Shopware released its B2B Ecommerce Compass 2026 whitepaper and hosted the B2B Future Forum, highlighting automation pressures and the challenges of managing complex system landscapes. In late 2025, Go Autonomous introduced Execution Fabric, an autonomous execution layer designed to unify B2B commerce channels across sales and procurement processes. Around the same period, PROS and Commerce announced a strategic partnership combining AI-powered pricing and quoting with BigCommerce's B2B digital commerce platform to accelerate intelligent B2B transactions. These developments illustrate how platform providers are responding to demand for greater automation, pricing intelligence, and cross-functional integration.
Macro Forces and Infrastructure Realities Shaping Commercial Strategy
B2B e-commerce does not operate in a vacuum. Platform decisions, deployment architectures, and growth expectations are increasingly influenced by infrastructure constraints, regulatory shifts, and operational cost dynamics. Decision-makers evaluating digital commerce investments must account for the broader environment in which these systems will run, particularly as workload intensity, data residency requirements, and integration complexity continue to rise.
B2B Debt Collection Services Market
Infrastructure cost considerations have become a central factor in platform and hosting strategy. Comparisons between colocation and public cloud environments for steady-state B2B e-commerce workloads reveal that colocation can offer meaningful total cost advantages once sustained utilization clears certain utilization thresholds. At the same time, power constraints are affecting data center expansion timelines, with a significant share of new projects facing delays as electricity availability becomes a binding constraint. These realities are prompting enterprises to reassess where and how commerce workloads are deployed, balancing performance, latency, and long-term cost predictability against flexibility and scalability expectations.
Regulatory and policy environments are also evolving in ways that affect digital commerce infrastructure and wholesale connectivity. Shifts in broadband program policy, including moves toward technology-neutral competition and open access models for wholesale providers, are reshaping how multi-service connectivity is delivered and monetized. As standardized marketplace models gain traction among major communications providers, the underlying connectivity landscape is becoming more modular and competitive. For B2B e-commerce operators, these changes influence site performance expectations, multi-region deployment strategies, and the feasibility of tightly integrated supply chain and procurement networks.
These macro forces are not abstract background conditions. They directly affect platform selection, hosting commitments, integration timelines, and the economics of scaling digital commerce operations. The report situates these dynamics within the broader market narrative, helping executives anticipate operational risks and align technology decisions with realistic infrastructure and regulatory trajectories.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle demands a clear-eyed assessment of where B2B e-commerce is heading and what it will take to compete effectively. Organizations that treat digital procurement and wholesale commerce as strategic capabilities rather than tactical sales channels will be better positioned to manage complexity, protect margins, and accelerate buyer onboarding. This study provides the analytical foundation needed to make those judgments with confidence.
By combining validated market sizing, structural segmentation insights, competitive profiling, and infrastructure-aware context, the report enables executives to evaluate platform investments, partnership strategies, and operational roadmaps against a realistic view of market momentum. The analysis is designed to support a range of decision contexts, from enterprise platform migrations and distributor network modernization to new market entry and pricing architecture redesign. Rather than offering generic recommendations, it delivers the kind of granular, scenario-aware intelligence that procurement, IT, and commercial leadership teams can apply directly to their planning processes.
Market growth at this scale is never uniform. It is shaped by adoption readiness, technological maturity, regulatory conditions, and the competitive intensity of the platform ecosystem. Understanding those layers is essential for avoiding costly missteps and capturing the opportunities that come with digital commerce transformation. This research gives decision-makers the clarity to separate short-term noise from long-term structural shifts, ensuring that 2026 investments are aligned with where the market is actually moving.
Next Steps: Turning Insight into Execution
Comprehensive market intelligence is only as valuable as its application. Organizations ready to move from awareness to action will find this report structured to support that transition, with practical evaluation criteria, competitive context, and forward-looking market mapping that can be integrated into existing strategic planning workflows. The full study provides the depth required to validate assumptions, benchmark platform options, and strengthen commercial decision-making across the enterprise.
For executives and strategy teams seeking a complete picture of B2B e-commerce market dynamics, platform positioning, and operational implications, the full report offers the detailed data and analysis necessary to guide confident, evidence-based decisions. Accessing the complete intelligence will provide the specificity needed to translate market momentum into measurable strategic advantage throughout 2026 and the forecast period ahead.
Business-to-Business (B2B) E-commerce Market
For detailed analysis of this topic, please visit the official page: Business-to-Business (B2B) E-commerce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Products Market to Hit $66.2M by 2032, Reflecting 4.7% CAGR Amid Regional Shifts
By PW Consulting, 2026-09-16
Strategic Intelligence for Blood Products Leaders: Navigating the 2026 Market Landscape
Executive Overview
The global blood products market is entering a critical inflection point. With historical momentum carrying the industry from 38.15 billion USD in 2020 to an estimated 48.0 billion USD in 2025, and a projected trajectory toward 66.2 billion USD by 2032, the sector is poised for sustained, measured expansion. Our newly released research framework dissects this evolution with precision, delivering the analytical depth required for enterprise-level strategy, capital allocation, and competitive positioning in the coming cycle.
For executives, investors, and operational leaders, the years ahead will not be defined by simple top-line growth. Instead, success will hinge on understanding structural shifts in donor economics, reimbursement architectures, regulatory cadence, and manufacturing capacity deployment. This report is engineered to translate macro trends into actionable intelligence, allowing decision-makers to stress-test strategies against realistic demand scenarios, supply constraints, and competitive maneuvering.
The 2026–2032 Trajectory: A Market Built on Stable Demand, Shaped by Execution
The forecast window reflects a compound annual growth rate of 4.7 percent, a figure that signals resilience rather than volatility. Demand fundamentals remain anchored in clinical necessity: surgical interventions, trauma response, oncology protocols, and chronic hematologic management continue to drive consistent consumption. Yet growth is no longer a passive outcome of population aging or procedural volume alone. It is increasingly contingent on operational efficiency, fractionation throughput, cold-chain integrity, and the ability to scale plasma-derived therapies without compromising quality or compliance.
Notably, the projection curve does not follow a linear stretch. The data anticipates a period of consolidation and recalibration, where capacity investments, regulatory approvals, and donor recruitment dynamics will differentiate high-performing players from those merely riding baseline demand. Companies that align manufacturing footprints, collection networks, and product portfolios with regional healthcare financing models will capture disproportionate value. Those that rely solely on historical utilization patterns will face margin compression, supply bottlenecks, or competitive displacement.
Our analysis maps these inflection points across the full forecast horizon, isolating the operational levers that determine whether volume growth translates into sustainable profitability. The report does not stop at aggregate figures; it examines how pricing structures, procurement consolidation, and clinical adoption pathways interact to shape realizable revenue in each phase of the cycle.
Decoding the Competitive Arena: Integrated Networks, Specialized Technologies, and Strategic Capacity Plays
The competitive landscape is defined by a mix of vertically integrated plasma manufacturers, specialized technology providers, and large-scale blood services organizations. Each group occupies a distinct strategic position, and the dynamics between them are shifting as capacity investments accelerate and pathogen reduction technologies gain broader clinical adoption.
Grifols and CSL Behring continue to anchor the upper tier of plasma-derived therapies, leveraging vertically integrated collection and fractionation networks to supply hematology, critical care, and rare disease portfolios. Their scale advantages are counterbalanced by the operational complexity of maintaining donor throughput, fractionation yield, and regulatory compliance across multiple jurisdictions. Terumo Blood and Cell Technologies, meanwhile, operates at the intersection of automation and component production, providing apheresis platforms, processing systems, and storage technologies that influence how blood centers and hospitals manage collection efficiency and product consistency.
On the services and distribution side, Vitalant exemplifies the large-scale U.S. blood services model, delivering whole blood, platelets, plasma, cryoprecipitate, and specialty products across hospital networks. Its operational footprint highlights the importance of regional supply resilience, donor engagement, and logistics optimization in a market where inventory management and shelf-life constraints remain perennial challenges.
Specialized technology and plasma-focused players add another layer of strategic complexity. Cerus Corporation’s pathogen reduction systems address a persistent vulnerability in transfusion medicine, inactivating viruses and bacteria in platelets and plasma to enhance safety margins. Octapharma, Biotest, and Kedrion Biopharma each emphasize plasma-derived medicines and collection infrastructure, with product portfolios spanning coagulation factors, immunoglobulins, and therapies for rare and chronic conditions. Their strategies illustrate a broader industry pattern: differentiation is increasingly achieved through specialized protein fractionation, targeted disease areas, and ownership or control of collection assets.
Recent corporate activity reinforces the strategic stakes. Kedrion Biopharma’s allocation of substantial investment to expand production capacity in Italy signals confidence in regional plasma throughput and fractionation scale. Grifols has moved forward with new manufacturing construction in Spain, reinforcing its commitment toEuropean capacity and supply continuity. Cerus Corporation’s multi-year supply agreement with a major French blood establishment underscores the commercial traction of pathogen reduction platforms in institutional procurement. Additionally, the 2026 International Plasma Protein Congress, held with record participation, reflects intensifying industry focus on plasma protein therapeutics, regulatory alignment, and cross-border supply coordination. Together, these developments illustrate a market where capacity, safety technology, and institutional partnerships are converging as decisive competitive variables.
Operational Realities That Shape Margins: Donor Economics, Reimbursement, and Regulatory Discipline
Behind every market projection lies a set of operational realities that determine whether growth is profitable, sustainable, and defensible. Donor economics remain one of the most consequential cost drivers. In the United States and select markets, donor compensation commonly falls within a range of 50 to 100 USD per visit, and collection-related expenses can represent more than half of finished plasma-derived product costs. This structure means that collection efficiency, donor retention, center utilization, and labor deployment are not back-office concerns; they are direct determinants of cost of goods and margin resilience.
At the same time, hospital reimbursement models introduce a distinct pricing dynamic. Many healthcare systems operate under fixed bundled reimbursement rates for patient care episodes, which encompass blood products as part of hospitalization without separate product-level billing. This architecture compresses direct price visibility for manufacturers and distributors, while shifting commercial emphasis toward reliability, quality assurance, inventory availability, and total cost-of-care efficiency. For suppliers, the implication is clear: competitive advantage arises from demonstrating consistent supply, minimizing waste, and aligning product offerings with clinical pathways rather than pursuing isolated list-price leverage.
Regulatory oversight adds another layer of discipline. Blood establishments are required to register and list products under FDA frameworks, with inspections occurring at least every two years to verify compliance with collection, testing, and processing standards. Updated clinical usage guidance, such as revisions to red blood cell preparation and component handling specifications, further shapes how products are manufactured, stored, and deployed. These requirements elevate the importance of quality systems, audit readiness, and documentation rigor. In practice, they reward organizations that embed compliance into operational design rather than treating it as a periodic checkpoint.
Labor intensity compounds these factors. Plasma collection networks rely on large workforce deployments across hundreds of centers to sustain high-frequency donor operations and fractionation throughput. The operational implication is twofold: scaling capacity requires careful workforce planning, training, and center-level productivity management, while disruptions in staffing or donor availability can quickly propagate into fractionation schedules and supply continuity. The companies that manage these variables most effectively will be best positioned to convert demand into revenue without eroding margins.
Blood Plasma Derivatives Market
What’s Inside the Research: Practical Intelligence for Strategy and Execution
This report is designed as an operational companion for executive decision-making, not a static market snapshot. It integrates demand trajectories, competitive positioning, regulatory context, and cost-structure dynamics into a coherent strategic framework. The analysis spans the forecast period from 2026 through 2032 and is anchored in a historical baseline that captures the market’s evolution from 2020 to 2025.
The research delivers detailed segmentation intelligence across product categories, application areas, and regional demand patterns, allowing readers to identify where growth concentrates, where throughput constraints emerge, and where procurement behavior differs by healthcare system. It examines product-level demand drivers, including red blood cell utilization in trauma and surgical care, platelet requirements in supportive treatment protocols, and the broader category of specialty and plasma-derived components. It also maps application-level consumption patterns across trauma and surgery, cancer treatment, and blood disorders, linking clinical utilization to supply planning and commercial strategy.
Beyond volume and segmentation, the report provides actionable competitive analysis. It evaluates the strategic posture of leading manufacturers, plasma collection organizations, technology suppliers, and blood services providers, highlighting how vertical integration, automation, pathogen reduction, and capacity expansion shape market positioning. The competitive framework is paired with recent corporate developments, regulatory milestones, and industry gathering activity to show how strategic intent is translating into infrastructure investment, supply agreements, and institutional partnerships.
A distinct emphasis is placed on operational economics and market mechanics. The analysis addresses donor compensation structures, collection cost weight within finished product economics, hospital reimbursement architecture, regulatory inspection cadence, and the labor footprint required to sustain high-frequency plasma collection and fractionation. These factors are integrated into a broader assessment of margin sensitivity, supply resilience, and procurement behavior, enabling readers to evaluate not just where the market is going, but how value is created and defended along the way.
Blood Products Market
To support practical decision-making, the report also includes scenario-based interpretation tools that help leadership teams test strategic assumptions against changing demand intensity, capacity deployment timelines, and competitive response patterns. The goal is to provide clarity on priorities: where to invest, where to optimize, where to partner, and where to differentiate.
Why This Report Matters for 2026 Decision-Making
The 2026 decision environment demands more than high-level forecasts. It requires an understanding of how donor economics, reimbursement models, regulatory oversight, and capacity investments interact to shape competitive outcomes. It requires clarity on which product and application segments will absorb incremental demand, which regions will see the most pronounced shifts in procurement behavior, and which strategic moves will separate market leaders from followers.
This research is built for that purpose. It provides the structural insight needed to align product strategy, supply chain planning, and commercial positioning with realistic market conditions. It helps organizations anticipate where margin pressure may emerge, where safety technology and compliance rigor will influence purchasing decisions, and where capacity expansion will alter supply dynamics. It also serves as a reference point for investment evaluation, partnership assessment, and long-range planning in a market where execution quality increasingly determines returns.
The full report contains the detailed segmentation breakdowns, regional demand mapping, competitive profiles, operational cost analysis, and strategic scenario interpretation needed to convert market intelligence into concrete action. For teams responsible for portfolio strategy, operations, procurement, or investment planning, the complete dataset and interpretive framework are essential for building resilient 2026 and beyond strategies.
Explore the full research suite to access the complete segmentation intelligence, competitive landscape analysis, and operational dynamics assessment that underpin the findings outlined here.
For detailed analysis of this topic, please visit the official page: Blood Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Venting Membrane Market to Hit $1.46M by 2032, 4.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Industrial Venting Membrane Market: Strategic Intelligence for 2026 Decision-Makers
The industrial landscape in 2026 is defined by increasingly stringent performance requirements for enclosure protection, breathing capability, and contamination control. As equipment becomes more sophisticated and operating environments more volatile, the demand for reliable pressure compensation and moisture management solutions has accelerated. Industrial venting membranes have emerged as a critical enabler across sectors ranging from automotive and electronics to medical devices and chemical packaging. Understanding where this market is heading, which forces are shaping its trajectory, and how competitive dynamics are evolving is no longer optional for C-suite leaders, product development teams, and investment strategists.
For organizations making capital allocation, product roadmap, and supply chain decisions in 2026, access to granular, forward-looking intelligence is essential. Our newly published Industrial Venting Membrane Market research delivers exactly that: a structured, evidence-based view of market size, growth momentum, segmentation patterns, competitive positioning, and the regulatory and cost pressures that will define the next several years. This article provides a strategic preview of what the full report covers, why it matters for 2026 planning, and how decision-makers can translate these insights into actionable advantage.
Market Trajectory: What the Numbers Signal for 2026 and Beyond
The industrial venting membrane market has demonstrated a pattern of measured expansion, punctuated by periods of recalibration as end-use demand, raw material conditions, and regional adoption cycles interact. Historical data from 2020 through 2025 shows the market progressing from an estimated 0.84 million USD in 2020 to 1.06 million USD in 2025, reflecting a maturing but still growing supply-demand equilibrium. Into the forecast window of 2026 through 2032, the market is projected to continue its upward path, moving from an estimated 1.15 million USD in 2026 toward approximately 1.46 million USD by 2032, supported by a compound annual growth rate of 4.7 percent.
For strategists, the significance of this trajectory lies not only in the headline figures but in what they imply about momentum. A mid-single-digit CAGR in a specialized component market indicates steady, structural demand rather than speculative hype. The expansion from 2026 to 2032 suggests that adoption is widening across applications and geographies even as mature segments stabilize. Decision-makers should interpret this as a signal to prioritize long-term readiness: aligning product architectures with venting requirements, evaluating supplier partnerships that can scale with demand, and building regulatory compliance into design cycles before market expectations tighten further.
The full report unpacks these trends with a detailed year-by-year view, enabling readers to test assumptions about near-term demand, mid-period inflection points, and longer-term growth ceilings. Rather than relying on aggregated summaries, the analysis provides a clear temporal map of where growth is likely to concentrate and how external shocks—such as raw material price movements or regulatory shifts—could alter the pace of adoption.
Strategic Value of the Report for 2026 Enterprise Planning
Market intelligence becomes valuable only when it is directly usable. This research is designed to support multiple enterprise functions simultaneously. For product strategy teams, the report provides a structured breakdown of how venting membranes are categorized by type and applied across end-use sectors, helping teams map technical specifications to real-world demand patterns without getting lost in fragmented supplier claims. For supply chain and procurement leaders, the analysis illuminates the cost environment, including raw material dynamics that affect pricing strategies and sourcing decisions. For competitive intelligence and business development units, the report maps the participant landscape and highlights recent moves that signal where capacity, innovation, and regional focus are shifting.
Industrial Venting Membrane Market
The report also addresses the compliance dimension, which has become a decisive factor in many industrial purchasing decisions. Regulatory expectations around medical-grade applications and food-contact safety are shaping specification requirements and vendor qualification processes. By integrating these requirements into the market context, the research enables teams to anticipate qualification timelines, avoid specification mismatches, and structure product development in a way that aligns with evolving safety and performance standards.
Most importantly, the full report is built to support decision-making rather than merely describe the market. It identifies where concentration exists, where fragmentation creates opportunity, and how recent developments—such as capacity expansions and product introductions—may influence competitive intensity in specific segments. Readers can use these insights to prioritize markets, assess risk exposure, and prepare for shifts in supplier bargaining power or customer specification requirements.
Inside the Research: What the Full Report Delivers
The complete study is organized to move from macro context to operational detail, giving readers a comprehensive view while allowing them to focus on the areas most relevant to their role. The core components include:
- Historic market sizing and forecast data spanning 2020 to 2032, presented in a way that supports scenario planning and demand modeling for multiple operating assumptions.
- Segmentation analysis by region, type, and application, giving a structured picture of where usage concentrates and how different market slices are positioned relative to one another.
- Competitive landscape assessment covering leading participants, their areas of specialization, and the strategic implications of recent launches, facility investments, and product enhancements.
- Regulatory and compliance context relevant to industrial venting membranes, including considerations for medical applications, food packaging safety, and chemical packaging use, as well as the increasing importance of PFOA-free and APFO-free certifications.
- Raw material and cost environment observations, including recent pricing signals in key input markets that can affect margin planning and sourcing strategies.
- Market concentration data indicating the extent to which leading participants share the landscape, helping readers gauge competitive intensity and evaluate entry or expansion feasibility.
Each section is written with a practical lens. The segmentation analysis, for example, helps teams understand which product architectures and application contexts are driving adoption, while the competitive section supports supplier evaluation, partnership strategy, and benchmarking. The regulatory discussion is not treated as a side note; it is integrated into market dynamics so that compliance requirements can be evaluated alongside demand growth and cost pressures.
Readers who engage with the full report will also find recent developments mapped into the competitive narrative. These include capacity investments aimed at meeting demand in specific regional markets and product introductions designed to expand performance envelopes under demanding operating conditions. By placing such events in context, the research helps organizations interpret whether these moves are incremental or indicative of broader shifts in supply strategy and end-use focus.
Competitive Landscape: Leading Participants and Recent Moves
The industrial venting membrane market features a set of established participants with distinct technical emphases and geographic footprints. Several companies stand out for their focus on ePTFE and PTFE-based venting solutions, each bringing different strengths in adhesive formats, hydrophobic and oleophobic treatments, pressure compensation sealing, and integration with filtration or housing systems. GERGONNE, based in France, specializes in ePTFE adhesive venting membranes for industrial pressure compensation, moisture removal, and protection across automotive, electronics, and technical applications. Membrane Solutions LLC, headquartered in the United States, produces PTFE hydrophobic and oleophobic venting membranes used in industrial chemical packaging, electronics, and gas or vent filter housings. Porex Corporation, also U.S.-based, offers PTFE hydrophobic venting membranes and adhesive solutions for industrial enclosures, container venting, diagnostics, and medical applications. Schreiner Group, a German participant, develops waterproof venting membranes and pressure compensation seals for industrial housings, protecting against liquids and dirt while enabling air exchange.
Broader global players also shape the market. W. L. Gore & Associates, based in the United States, provides ePTFE membranes for industrial venting in automotive, electronics, and battery protection applications. Donaldson Company, Inc., another U.S. participant, supplies ePTFE membranes integrated into filtration and venting systems for industrial and off-highway applications. Saint-Gobain Performance Plastics, headquartered in France, offers advanced PTFE-based venting membranes for industrial packaging, chemical resistance, and pressure equalization. Nitto Denko Corporation, based in Japan, manufactures functional ePTFE venting membranes for industrial electronics, automotive, and process applications. Together, these participants illustrate the breadth of technical approaches and application coverage that characterize the competitive environment.
Recent developments underscore how actively the landscape is evolving. In mid-2026, a dedicated venting-membrane production line was inaugurated in Chennai, India, by Porvair Filtration Group, reflecting an expansion of capacity aimed at meeting demand for lightweight outdoor equipment venting solutions. Around the same time, GERGONNE introduced its VM16 ePTFE venting membrane with enhanced resistance to extreme hydrodynamic stresses and conditions. These moves are more than isolated news items; they signal where participants are placing bets on capacity, performance, and regional demand. For enterprises evaluating suppliers or planning product architectures, such developments provide early indicators of where supply flexibility, technical differentiation, and regional support may strengthen or weaken over the forecast period.
Market concentration data adds another layer to this picture. With a combined share held by the top three participants at approximately 25 percent and the top five at around 35 percent, the market remains relatively dispersed. This level of concentration suggests both opportunity and complexity. On one hand, no single player dominates to the point of constraining choice across all applications; on the other, competition is active enough that differentiation depends on technical performance, compliance readiness, and regional capability. The full report examines these dynamics in greater detail, helping readers interpret how concentration interacts with segment-specific demand and supplier specialization.
Market Dynamics: Regulation, Cost, and Shifting Demand Signals
Several forces are actively shaping how industrial venting membranes are specified, sourced, and priced in 2026. Regulation is one of the most consequential. For medical applications, venting membranes must align with expectations associated with ISO 13485, while food packaging safety considerations are governed by frameworks such as EU Regulation (EC) 1935/2004. These requirements influence material selection, certification pathways, and vendor qualification timelines. At the same time, chemical safety standards are becoming increasingly important across industrial packaging and enclosure applications. Membrane Solutions has emphasized APFO-free certification for its PTFE venting membranes used in industrial chemical packaging per EPA guidelines, and Porex has indicated that its Virtek PTFE membranes require PFOA-free certification to meet global chemical safety standards. Schreiner Group has incorporated oleophobic properties into its pressure compensation seals to meet industrial housing standards for liquid ingress prevention. Taken together, these compliance positions show that certification is no longer a background consideration; it is becoming a deciding factor in supplier selection and application design.
Cost dynamics also play a central role in strategic planning. Raw material conditions, particularly for PTFE, directly affect input economics and can influence pricing strategies, margin planning, and sourcing timing. Recent pricing signals have shown PTFE raw material prices in Northeast Asia at approximately 8.35 USD per kg, with a modest month-over-month increase. For procurement and product cost teams, such movements matter because they can shift the balance between alternative material choices, adhesive formats, and venting architectures. The research places these cost signals within the broader market context so that teams can assess whether pricing pressure is likely to be temporary, structural, or regionally uneven.
Demand-side dynamics continue to evolve as well. The application landscape spans electric and electronics, automotive, medical, chemical packaging, food and beverages packaging, and other uses, each with different performance priorities and compliance expectations. The type landscape includes adhesive venting formats and vent solutions without backing material, each serving different integration needs. Rather than treating these categories as isolated silos, the report evaluates how they interact with regional demand patterns and competitive positioning. This integrated approach helps readers see where specification requirements are converging, where cost sensitivity may shape adoption, and where performance differentiation will be most valuable.
PTFE Venting Membrane Market
Using the Research to Strengthen 2026 Decisions
The strategic value of this research lies in its ability to connect market structure with operational choice. For leaders planning product development, the segmentation and application analysis provides a basis for prioritizing venting requirements in next-generation designs. For procurement and sourcing teams, the combination of cost dynamics, compliance context, and competitive positioning supports more informed supplier evaluation and risk assessment. For business development and strategy teams, the concentration data and recent market moves offer a framework for evaluating entry points, partnership opportunities, and regional expansion priorities.
In a market where growth is steady but competitive intensity is real, the organizations that gain advantage will be those that act on precise, forward-looking information rather than on assumptions or fragmented inputs. The full report is built for that purpose: it provides the depth required to support decisions, while keeping the focus on implications rather than description alone.
For a complete view of market sizing, segmentation detail, competitive profiles, regulatory considerations, and the year-by-year forecast that underpins the 2026 to 2032 outlook, access the full Industrial Venting Membrane Market research. The complete study provides the data, analysis, and strategic context needed to translate market intelligence into confident decision-making throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Industrial Venting Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aluminum Electrolytic Capacitor Market to Hit $8,020M by 2032, CAGR 3%
By PW Consulting, 2026-09-16
Strategic Intelligence for the Aluminum Electrolytic Capacitors Market: Navigating the 2026 Landscape
The global aluminum electrolytic capacitors market stands at a critical inflection point as industries transition from legacy power architectures to high-efficiency, miniaturized electronic systems. At PW Consulting, we recognize that capacitor selection is no longer a procurement formality but a strategic lever influencing product reliability, supply chain resilience, and long-term margin structures. Our latest market research offers a comprehensive, decision-grade blueprint tailored for executives, product engineers, and supply chain strategists operating in 2026 and beyond.
This introductory overview outlines the methodological rigor, structural depth, and strategic applicability embedded within the full report. While macro-trends are presented here to establish baseline context, granular segmentation data, proprietary forecasting models, and competitive benchmarking matrices remain exclusive to our published deliverables. The objective is clear: equip leadership teams with the analytical framework necessary to anticipate disruption, optimize sourcing strategies, and capture sustainable growth in a consolidating component landscape.
Macro Trajectory and Structural Market Dynamics
Over the past half-decade, the aluminum electrolytic capacitors market has demonstrated steady expansion, driven by sustained demand across consumer electronics, automotive electrification, industrial automation, and telecommunications infrastructure. Historical revenue trends through 2025 reflect a mature but resilient ecosystem, with global market valuation progressing from mid-2020 levels to approximately $6.5 billion by 2025. This trajectory underscores the component's enduring relevance despite persistent substitution pressures from ceramic and film alternatives in high-frequency applications.
Looking forward, the forecast horizon extends through 2032, with market size projected to exceed $8.0 billion by the terminal year. The annualized growth rate across this period stabilizes at a 3.0% compound trajectory, reflecting a balanced interplay between volume expansion in emerging applications and price normalization in legacy supply chains. This moderate but consistent growth profile signals a market that has matured past speculative volatility, now entering a phase defined by efficiency-driven procurement, material cost optimization, and strategic capacity allocation.
Several structural forces will dictate the pace and distribution of future demand. First, the ongoing electrification of vehicle platforms continues to elevate requirements for high-reliability, long-life electrolytic solutions in auxiliary power distribution, battery management circuits, and motor drive filtering. Second, telecommunications infrastructure upgrades—particularly in 5G baseband units, remote radio heads, and edge computing power supplies—sustain steady consumption of both radial and surface-mount variants. Third, industrial automation and renewable energy conversion systems are driving renewed engineering focus on electrolytic capacitors capable of enduring elevated ripple currents, extended thermal cycling, and prolonged operational lifespans without degradation.
Material constraints remain an equally decisive variable. The etched foil supply chain, dominated by a tightly controlled oligopoly, has historically experienced lead time compression during demand surges, with high-purity foil procurement cycles extending to twenty-four weeks in peak scenarios. This bottleneck introduces critical upstream risk for manufacturers reliant on standardized foil grades, particularly as automotive and industrial specifiers demand tighter tolerance envelopes and lower ESR profiles. The 3-micron manufacturing threshold currently represents a technological and capacity constraint that will shape supplier selection criteria and pricing negotiations throughout the forecast window.
Consolidation dynamics further complicate the competitive landscape. The top three players command approximately 40% of aggregate market share, while the top five collectively account for roughly half of global revenue. This concentration reflects decades of vertical integration, proprietary electrolyte formulation expertise, and entrenched design-in relationships across power supply and consumer electronics OEMs. Yet, the remaining market share is fragmented across specialized regional players, polymer-focused innovators, and hybrid-technology adopters, creating both partnership opportunities and competitive pressure points for incumbents seeking to defend margin structures.
Comprehensive Report Architecture and Operational Utility
PW Consulting's Aluminum Electrolytic Capacitors Market report is structured to translate macro-level intelligence into actionable decision pathways. The deliverable is organized across multiple analytical layers, each calibrated to address specific executive functions, from portfolio strategy to procurement risk mitigation.
- Historical Baseline and Forecast Modeling: The report anchors its projections on a five-year historical dataset spanning 2020 through 2025, establishing revenue baselines, cyclical demand patterns, and technology adoption curves. These foundations feed into a forward-looking forecast extending through 2032, utilizing scenario-weighted modeling that accounts for material price volatility, capacity expansion timelines, and application-specific substitution risks.
- Segmentation by Product Architecture: A detailed breakdown by capacitor configuration examines radial leaded, surface mount, axial leaded, and other specialized formats. The analysis evaluates form-factor migration trends, mounting reliability considerations, thermal dissipation characteristics, and design-in preferences across power supply and consumer electronics applications, enabling engineering teams to align component selection with long-term manufacturing and assembly strategies.
- Application-Driven Demand Mapping: The report isolates consumption patterns across consumer electronics, automotive systems, industrial machinery, telecommunications hardware, and energy and power infrastructure. Each application vertical is evaluated through the lens of reliability thresholds, voltage and capacitance requirements, thermal stress profiles, and procurement cycles, providing procurement leaders with sector-specific sourcing frameworks and risk assessments.
- Regional Market Dynamics: Geographic analysis covers North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The report evaluates regional capacity distribution, import dependency structures, local manufacturing incentives, logistics constraints, and end-market growth trajectories, enabling multinational stakeholders to optimize regional supply footprints and mitigate geopolitical or trade-related disruption risks.
- Competitive Intelligence and Strategic Positioning: The report delivers a multi-dimensional competitive assessment, mapping incumbent portfolios, technology roadmaps, regional footprint strategies, and partnership ecosystems. Rather than relying on superficial revenue rankings, the analysis evaluates design-win momentum, polymer and hybrid technology adoption rates, automotive qualification pipelines, and supply chain flexibility as indicators of future market share transfer.
- Material and Supply Chain Risk Assessment: Upstream vulnerability analysis examines etched foil production constraints, electrolyte formulation dependencies, polymer precursor availability, and lead-time sensitivity across high-reliability grades. The report integrates raw material market signals to help procurement and engineering teams anticipate pricing fluctuations, secure qualification pipelines, and diversify supplier bases ahead of demand surges.
Each section is cross-referenced with executive decision matrices, allowing readers to isolate the data streams most relevant to their functional mandates. The report avoids generic market commentary, prioritizing instead granular trend interpretation, scenario-based forecasting, and supplier evaluation frameworks designed for immediate operational deployment.
Competitive Landscape: Strategic Positioning and Innovation Vectors
The aluminum electrolytic capacitors market features a concentrated group of established manufacturers whose technological roadmaps and regional supply footprints directly influence pricing dynamics, qualification timelines, and end-market availability. Several core players define the current competitive architecture, each pursuing distinct specialization pathways that shape their strategic relevance in 2026 and beyond.
Japan remains the epicenter of electrolytic capacitor innovation, with multiple firms leveraging decades of electrolyte chemistry expertise, manufacturing precision, and automotive qualification capabilities. Leading manufacturers have expanded their portfolios to include polymer and solid variants optimized for power supplies and consumer electronics, while simultaneously advancing high-reliability grades for industrial and automotive use cases. Specialist producers continue to refine polymer-type architectures for consumer applications, emphasizing extended lifespan, lower impedance, and enhanced ripple current tolerance. Others have positioned themselves around general electronics reliability, leveraging legacy design-in relationships and volume production efficiency to maintain competitive parity in mainstream segments.
Worldwide Miniature Aluminum Electrolytic Capacitors Market
Across the Pacific, North American and European entities have strengthened their positioning through targeted technology acquisitions, polymer and organic variant development, and long-life series engineering. Major manufacturers operating under broader component conglomerates have integrated aluminum electrolytic offerings into broader passive component portfolios, utilizing organic polymer variants to address power electronics applications where thermal stability and longevity are paramount. European producers have emphasized long-life application suitability through dedicated series engineering, catering to industrial control, telecommunications, and medical-grade power supplies where failure tolerance is exceptionally low. Meanwhile, Taiwanese ownership structures have enabled global market expansion through acquired manufacturing platforms, aligning regional production capacity with international distribution networks and cross-market qualification strategies.
Recent industry activity underscores the pace of technological refinement. At NEPCON Japan 2026, notable participant initiatives highlighted precision manufacturing advancements and material qualification protocols for surface-mount aluminum electrolytic capacitors. Emphasis was placed on inline inspection methodologies, collaborative validation frameworks for long-life performance, and low ESR automotive-grade component development. These developments signal a market-wide shift toward process-controlled manufacturing, tighter tolerance verification, and application-specific qualification pathways that directly impact supplier selection criteria for automotive and industrial OEMs.
The competitive environment is further shaped by consolidation pressures and vertical integration strategies. Firms that control or secure stable access to high-purity etched foil, proprietary electrolyte formulations, and advanced winding and impregnation capabilities maintain structural advantages in cost efficiency and volume scalability. Conversely, manufacturers without secured upstream positioning face heightened exposure to lead-time volatility, pricing compression, and qualification bottlenecks during peak demand cycles. For procurement leaders and product strategists, evaluating competitor positioning requires more than revenue comparison; it demands scrutiny of technology roadmaps, automotive certification pipelines, polymer adoption trajectories, and regional supply flexibility.
Strategic Decision Implications for 2026
For executives navigating the aluminum electrolytic capacitors market in 2026, strategic decision-making must balance short-term procurement stability with long-term technology positioning. The moderate but consistent growth trajectory suggests a market that rewards disciplined supplier diversification, application-specific qualification planning, and proactive material risk management. Organizations that treat capacitor sourcing as a static purchasing function risk exposing product roadmaps to lead-time shocks, specification mismatches, and margin erosion as upstream constraints intensify.
Aluminum Electrolytic Capacitors Market
Several priority actions emerge from the broader market context. Product engineering teams should evaluate surface-mount and polymer variant integration pathways where design constraints allow, particularly for applications demanding lower ESR, extended thermal endurance, or compact form factors. Procurement leaders should establish dual-sourcing frameworks that account for regional capacity distribution, automotive qualification status, and upstream foil availability, rather than defaulting to single-vendor dependency in high-volume programs. Supply chain strategists should incorporate raw material lead-time sensitivity into inventory planning models, particularly for high-reliability automotive and industrial grades where qualification cycles are lengthy and substitution options are constrained.
Additionally, market participants should monitor technology crossover risk. While aluminum electrolytic capacitors retain clear advantages in high-capacitance, cost-effective energy storage and ripple filtering, ceramic and film alternatives continue to encroach on specific high-frequency and compact-power applications. Understanding the precise threshold at which substitution becomes economically or technologically viable requires application-level analysis that generic market commentary cannot provide. Our full report delivers the segmented modeling, competitive benchmarking, and scenario-weighted forecasts necessary to evaluate these crossover dynamics with precision.
Access the Full Strategic Intelligence
The overview presented here establishes the macro trajectory, structural dynamics, and competitive realities shaping the aluminum electrolytic capacitors market through 2032. However, the decision-grade granularity required for portfolio planning, supplier qualification, pricing strategy, and regional supply optimization resides within the complete PW Consulting research deliverable. Detailed segmentation valuations, regional demand distributions, application-specific revenue allocations, concentration thresholds, and proprietary competitive matrices are intentionally reserved for the full publication to preserve analytical exclusivity and ensure that subscribing organizations receive uncompromised strategic advantage.
Accessing the complete report enables executives and engineering leaders to convert macro awareness into targeted action: aligning component selection with application reliability thresholds, securing upstream material pathways ahead of demand tightening, evaluating competitor technology roadmaps with precision, and positioning procurement strategies to withstand lead-time volatility and pricing compression. In a market where material bottlenecks, consolidation dynamics, and automotive qualification pipelines increasingly dictate competitive outcomes, comprehensive intelligence is not a supplementary resource—it is a strategic imperative.
For organizations operating in consumer electronics, automotive systems, industrial automation, telecommunications infrastructure, or energy and power conversion, the 2026 market landscape rewards those who prepare with discipline. PW Consulting's full market research delivers the structured intelligence, scenario modeling, and competitor evaluation frameworks necessary to navigate the next phase of industry evolution with confidence.
For detailed analysis of this topic, please visit the official page: Aluminum Electrolytic Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Remote Patient Monitoring Market Hits $39.97B in 2025, Forecasts $92.3B by 2032
By PW Consulting, 2026-09-16
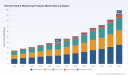
Unlocking the Future of Care: Strategic Intelligence for the Remote Patient Monitoring Products Market Through 2032
The healthcare landscape is undergoing a seismic shift, driven by an aging global population, the escalating burden of chronic diseases, and an uncompromising demand for cost-effective care delivery. At the forefront of this transformation is Remote Patient Monitoring (RPM), a sector that has moved rapidly from a niche convenience to a fundamental pillar of modern healthcare infrastructure. As organizations prepare their strategic roadmaps for 2026 and beyond, understanding the nuances of this high-growth market is no longer optional—it is imperative for sustained competitive advantage.
PW Consulting is pleased to introduce our latest comprehensive market research report, designed specifically to equip industry leaders, investors, and healthcare strategists with the actionable intelligence needed to navigate the complexities of the Remote Patient Monitoring Products Market. This deep-dive analysis moves beyond surface-level trends to offer a granular, data-driven exploration of where the market stands today, where it is heading, and how stakeholders can position themselves to capture value in a rapidly evolving ecosystem.
Remote Patient Monitoring Products Market
A Trajectory of Unstoppable Growth: Defining the Scale of Opportunity
The momentum behind remote patient monitoring is quantifiable and formidable. Our analysis traces the market's evolution from 2020 through 2025, capturing a period of accelerated adoption, before projecting a robust forecast period extending to 2032. The historical data reveals a consistent upward trajectory, with the market steadily expanding as healthcare providers integrate continuous monitoring into standard care protocols. This foundation of growth sets the stage for the forecast period, where the convergence of technological maturity, favorable regulatory developments, and shifting reimbursement models is expected to catalyze an even more aggressive expansion.
Looking toward the horizon, the market is positioned for substantial capital deployment. The projected revenue figures for the forecast period underscore a market that is not merely growing, but scaling exponentially. By 2026, the market is anticipated to cross a significant inflection point, driven by increasing adoption across diverse therapeutic areas and regions. As we move through the latter half of the decade, the cumulative revenue potential points toward a market that will redefine the economics of chronic care management. The compound annual growth rate (CAGR) of 12.7% over the forecast period serves as a powerful indicator of sustained investment viability, signaling to stakeholders that the RPM sector offers lucrative opportunities for those who can execute with precision.
Liquid Biopsy Products Market
The Anatomy of the Market: Segmentation Drives Strategic Clarity
While the aggregate numbers tell a compelling story of growth, true strategic advantage lies in understanding how the market is fractured and specialized. The Remote Patient Monitoring Products Market is not a monolith; it is a complex tapestry of devices, services, and clinical applications, each with distinct growth drivers, competitive dynamics, and adoption barriers. Our report deconstructs these segments to reveal where value is being created and where the highest margins can be secured.
At the core of the product landscape, the market bifurcates into distinct categories involving hardware and software-enabled solutions. The interplay between physical monitoring devices—such as biosensors, wearables, and cellular gateways—and the services that orchestrate data flow, clinical alerts, and integration with electronic health records forms the backbone of the RPM economy. We delve deeply into the revenue contribution and growth velocities of each segment, analyzing how vendors are bundling devices with service platforms to create sticky, recurring revenue models that resonate with healthcare systems seeking streamlined, end-to-end solutions.
Beyond product types, the application landscape presents a rich array of clinical verticals. The demand for RPM is being fueled by a diverse set of disease states, each requiring tailored monitoring protocols and device specifications. Cardiovascular diseases remain a dominant force, leveraging the need for continuous rhythm monitoring and post-discharge care. Diabetes management continues to be a high-volume application, driven by the proliferation of continuous glucose monitors and the integration of metabolic data into chronic care workflows. Meanwhile, oncology and other emerging indications are carving out specialized niches, creating opportunities for targeted innovation. Our segmentation analysis enables readers to identify the highest-velocity application areas, assess the competitive intensity within each vertical, and discover whitespace opportunities where unmet clinical needs intersect with technological capability.
Regional Dynamics: Navigating a Global Patchwork of Adoption
Geographical expansion is a critical component of any growth strategy, yet the RPM market does not unfold uniformly across the globe. Regional variations in healthcare infrastructure, reimbursement policies, regulatory frameworks, and patient demographics create a complex map of opportunity. North America has historically anchored the market, supported by mature telehealth infrastructures and proactive reimbursement environments. However, the dynamics are shifting as other regions accelerate their digital health agendas.
Europe continues to embrace RPM through a combination of national health initiatives and cross-border data harmonization efforts. The Asia Pacific region, with its vast patient populations and rapidly modernizing healthcare systems, is emerging as a theater of intense innovation and adoption. Latin America and the Middle East & Africa present nuanced challenges and opening windows, where targeted partnerships and localized solutions can yield outsized returns. Rather than offering generic regional summaries, our report provides a nuanced assessment of regional market sizing and growth trajectories, explaining the underlying drivers that differentiate one geography from another. By understanding these regional idiosyncrasies, strategists can prioritize market entry, allocate resources efficiently, and mitigate the risks associated with cross-border expansion.
Competitive Landscape: Navigating a Field of Specialized Innovators and Healthcare Giants
The competitive arena in remote patient monitoring is characterized by a mix of nimble, technology-focused innovators and established medical device conglomerates, each pursuing distinct value propositions. The market is moderately concentrated, creating a dynamic environment where both differentiation and scale are rewarded. Our report provides an in-depth profiling of key companies that are shaping the market, examining their product portfolios, go-to-market strategies, and recent strategic moves.
Among the specialized players driving innovation, VitalConnect has carved a strong position in wireless multiparameter monitoring, offering biosensors and platforms that capture vital signs and ECG data with high fidelity. Their recent FDA 510(k) clearance for the VitalRhythm biosensor marks a significant milestone, enabling continuous monitoring of ECG, heart rate, and respiratory rate, thereby expanding the clinical utility of their offering in remote settings. Similarly, Hexoskin has pioneered the realm of smart medical garments, providing systems capable of long-term continuous ECG and respiratory monitoring. The recent FDA clearance for their medical system underscores the regulatory validation of wearable form factors in delivering actionable clinical data.
HealthSnap represents the growing importance of integrated software platforms that bridge devices with clinical workflows. Their cellular-connected RPM and chronic care management platforms, which feature automated alerts and seamless EHR integration, are being deployed at scale. A notable enterprise agreement with Sentara Health to roll out RPM programs across 389 providers and 85,000 patients exemplifies how platform-centric vendors are securing large-scale institutional commitments. Tenovi complements this ecosystem by providing the connective tissue—offering cellular gateways and software platforms that integrate Bluetooth RPM devices, lowering the barrier for providers to adopt diverse hardware without building complex infrastructure. Sotera Wireless demonstrates a focus on continuous, non-invasive vital signs monitoring with their ViSi Mobile system, catering to both hospital and remote use cases with an emphasis on real-time data transmission.
On the industrial scale end of the spectrum, Medtronic and Abbott Laboratories bring decades of clinical expertise and manufacturing prowess to the RPM space. Medtronic's portfolio spans implantable and wearable devices for cardiac monitoring, glucose tracking, and multiparameter monitoring, leveraging its global distribution network and established relationships with healthcare providers. Abbott Laboratories, with its leadership in continuous glucose monitors and vital signs devices, continues to expand its footprint in RPM for diabetes and chronic conditions, effectively turning metabolic and physiological data into continuous streams of care management. Together, these companies illustrate the breadth of approaches—from specialized niche solutions to broad-based cardiac and metabolic monitoring—that coexist and compete within the market.
The Catalysts: Regulatory Advances and Reimbursement Evolution Accelerate Adoption
No discussion of the RPM market would be complete without addressing the external forces that are actively reshaping its trajectory. Regulatory clearances and reimbursement policies act as powerful accelerants, turning clinical potential into commercial reality. The recent regulatory landscape has been particularly favorable, with key developments reinforcing the clinical legitimacy and economic viability of remote monitoring.
In April 2025, VitalConnect secured FDA 510(k) clearance for the VitalRhythm biosensor, a development that enables continuous monitoring of ECG, heart rate, and respiratory rate. This clearance not only validates the device's safety and effectiveness but also expands the scope of remote monitoring to include more comprehensive vital signs tracking, a critical enabler for managing complex patients at home. By November 2025, Hexoskin also achieved FDA 510(k) clearance for its medical system, reinforcing the acceptance of smart garments for long-term continuous ECG and respiratory monitoring. These regulatory milestones are symptomatic of a broader trend where the FDA and other bodies are increasingly recognizing the value of novel form factors and continuous data streams in remote care, thereby opening new avenues for innovation.
Equally transformative is the evolution of reimbursement frameworks. The CMS final rule for the 2026 Medicare Physician Fee Schedule introduced pivotal CPT codes—99445 and 99470—that significantly enhance the financial infrastructure supporting RPM. Code 99445 provides reimbursement for device supply on a flexible short-duration basis of 2 to 15 days, addressing a previous gap in the reimbursement model that hindered the use of shorter-term monitoring strategies. Code 99470 covers the first 10 minutes of treatment management, complementing existing codes and allowing providers to be compensated for the critical initial phase of patient engagement and data review. These updates, effective January 1, 2026, signal a shift toward more flexible, granular reimbursement that aligns with the varied needs of clinical workflows and patient populations. For market participants, this means a more predictable and expansive revenue environment, encouraging providers to invest in RPM programs with greater confidence.
Data-Driven Insights and Operational Tools for Strategic Decision Making
This report is engineered to be more than a market overview; it is a strategic toolkit designed for execution. We have synthesized complex datasets into actionable insights, providing readers with a granular understanding of market sizing, segmentation, competitive positioning, and growth vectors. The analysis is grounded in historical data spanning 2020 to 2025, ensuring that projections are built on verified trends rather than speculative assumptions. The forecast period from 2026 to 2032 is modeled with careful consideration of technological trajectories, regulatory impacts, and adoption curves.
Readers will find a detailed breakdown of market sizes across key dimensions, enabling them to quantify the opportunity within specific segments, applications, and regions. The competitive analysis goes beyond company profiles to assess market positioning, product differentiation, and the implications of recent partnerships and regulatory wins. We also examine the interplay between market concentration and the dispersion of opportunities, helping strategists identify where fragmentation offers entry points and where consolidation rewards scale. Furthermore, the report integrates the latest industry developments, ensuring that the strategic context reflects the most current realities of the market.
Importantly, this document serves as a precursor to the full intelligence suite. While the insights presented here illuminate the macro dynamics and highlight the key themes shaping the RPM market, the complete report contains the detailed quantitative breakdowns, segment-level projections, company benchmarking data, and regional analyses that are essential for precise strategic planning. The depth of data required to make informed decisions—such as subsegment growth rates, device-level adoption patterns, and granular regional revenue flows—is contained within the full report, providing a level of detail that general summaries cannot replicate.
Seizing the Moment: Strategic Imperatives for 2026 and Beyond
As the Remote Patient Monitoring Products Market enters a phase of accelerated expansion, the window for strategic positioning is open but narrowing. Organizations that will thrive in this environment are those that move beyond passive observation and actively align their capabilities with the market's structural shifts. Whether you are a device manufacturer seeking to expand your footprint, a service provider looking to integrate RPM into a broader care continuum, an investor evaluating the next wave of healthcare technology, or a healthcare system planning the deployment of monitoring programs, the intelligence contained in our report is tailored to inform your critical decisions.
The convergence of favorable reimbursement, regulatory validation of innovative devices, and the relentless push toward value-based care is creating a fertile ground for growth. Yet, this environment also demands sophistication. Success will depend on selecting the right segments, understanding the competitive nuances, leveraging regional opportunities, and staying ahead of the regulatory and reimbursement curve. Our report provides the foundational knowledge and data-driven perspective necessary to navigate these complexities with confidence.
We invite you to explore the full findings of our Remote Patient Monitoring Products Market research. By accessing the complete report, you will gain the granular data, detailed segmentation analysis, and comprehensive competitive intelligence required to craft strategies that are not only responsive to the market but anticipatory of its future trajectory. The insights within are designed to turn market awareness into strategic action, empowering you to capture the substantial value that the RPM market will generate in the years ahead. The future of remote care is being written now, and the organizations equipped with the right intelligence will be the ones that define it.
For detailed analysis of this topic, please visit the official page: Remote Patient Monitoring Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Raised Access Floor Market Hits $1.66B in 2025, Projected to Reach $2.4B by 2032
By PW Consulting, 2026-09-16
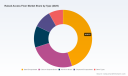
Strategic Foundations Beneath the Surface: Why the Raised Access Floor Market Demands Executive Attention in 2026
Modern enterprise infrastructure is undergoing a quiet but irreversible transformation. As data centers scale to accommodate artificial intelligence workloads, commercial offices reconfigure around hybrid work models, and clean room facilities tighten environmental controls, the raised access floor has evolved from a passive architectural element into a critical enabler of operational resilience. At PW Consulting, we recognize that leaders who understand the structural shifts in this market gain a decisive advantage in capital allocation, vendor selection, and long-term facility planning. This introduction to our newly released Raised Access Floor Market research study outlines the strategic rationale behind our analysis, previews the actionable intelligence embedded in the full report, and explains why 2026 represents a pivotal inflection point for stakeholders across real estate, IT infrastructure, and construction sectors.
The Macro Trajectory: A Market Built on Sustained Expansion
The raised access floor sector has demonstrated remarkable consistency through cycles of supply chain volatility, shifting construction demand, and evolving technical specifications. Historical tracking from 2020 through 2025 reveals a steady revenue progression, moving from just over USD 1.27 billion to approximately USD 1.66 billion by the base year. This trajectory reflects more than incremental growth; it signals a structural recalibration of how organizations design indoor environments to support power distribution, airflow management, and modular reconfiguration. Looking forward, our forecast model projects the market to surpass USD 1.8 billion in 2026 and continue its upward path toward USD 2.4 billion by 2032. The compound annual growth rate of 5.41 percent underscores a mid-to-high single-digit expansion phase that is neither speculative nor overly aggressive, but rather anchored in tangible facility modernization requirements and sustained commercial construction activity.
For decision-makers, this growth pattern carries immediate implications. It suggests that demand is not concentrated in a single vertical or geography, but rather distributed across multiple end-use environments that are simultaneously upgrading their physical infrastructure. It also indicates that procurement strategies relying on short-term price optimization may overlook the broader value of system longevity, maintainability, and compatibility with next-generation cooling and networking architectures. Our analysis is designed to help executives distinguish between temporary market fluctuations and durable investment themes.
What the Full Study Delivers: Operational Intelligence, Not Just Headlines
Market summaries often stop at top-line figures, but effective strategy requires granular visibility into how value is created, captured, and contested. The complete PW Consulting report is structured to provide exactly that depth. Readers will find a methodical dissection of product architectures, including steel encapsulated platforms, calcium sulphate board systems, aluminum variants, chipboard encapsulated options, and other specialized constructions. Each material pathway presents distinct trade-offs in load capacity, acoustic performance, moisture resistance, and installation logistics. The study maps these characteristics against real-world deployment scenarios so that procurement leaders and facility architects can align specification choices with operational priorities rather than defaulting to legacy standards.
Equally critical is the application-layer analysis. Data centers, commercial offices, clean rooms, institutional buildings, and other use cases each impose unique performance thresholds. Our research evaluates how raised access flooring systems are specified, tested, and maintained across these environments, highlighting where design flexibility matters most and where standardization yields measurable cost efficiencies. Regional demand patterns are examined through the lens of construction pipelines, regulatory environments, and local supply chain maturity, enabling multinational corporations and regional developers alike to calibrate their market entry or expansion strategies with precision. The report also integrates competitive benchmarking, pricing architecture reviews, and supply chain sensitivity assessments that translate directly into tender preparation, vendor negotiations, and lifecycle cost modeling.
Competitive Posture: How Leading Players Are Shaping the Landscape
The raised access floor market is characterized by a balanced concentration structure, with the top three participants accounting for approximately forty percent of revenue and the top five collectively holding around half of total market share. This dispersion signals a competitive arena where scale, technical differentiation, and regional execution capability all matter. Several established and emerging players have carved out recognizable positions by emphasizing distinct value propositions, and our study tracks how these strategic postures are evolving in response to customer demands and macroeconomic pressures.
Tate Global, headquartered in the United Kingdom, has built recognition around innovative raised access flooring solutions tailored for commercial offices and data centers, emphasizing configuration adaptability and integration with modern workplace layouts. DIRTT, based in Canada, addresses the growing need for low-profile access floors with integrated power and data distribution, effectively converging flooring infrastructure with structured cabling and power management. In the high-load segment, Rhino Technologies Co., Ltd. of the United States has focused on engineered steel panel systems designed specifically for demanding data center environments, where structural integrity and load distribution are non-negotiable. Across the Asia-Pacific manufacturing base, Polygroup has emphasized adjustable pedestal systems that streamline installation and enable precise height calibration, while Titanflor has positioned its offerings for broader industrial and commercial projects that require durable, repeatable floor systems. Huilian Flooring, also based in China, has pursued a differentiated path by combining raised access flooring systems with ceramic finishes, targeting environments where surface durability and cleanability are paramount. Meanwhile, Access Floors Distribution in the United Kingdom continues to serve specification-driven projects with a focus on raised floor tiles and integrated systems that align with architectural and engineering workflows.
Raised Access Floor Market
Strategic momentum in this sector is not static. Recent developments illustrate how competition is intensifying through both product innovation and service model expansion. In January 2026, Huilian highlighted its R&D commitment by showcasing more than seventy patents, including ten invention patents focused on raised access flooring systems. This level of intellectual property activity suggests a deliberate push toward proprietary design features that can create specification lock-in and improve margin resilience. In November 2025, The Access Flooring Company introduced an AI-powered chatbot service intended to provide immediate expert assistance on raised access flooring systems, reflecting a wider industry trend toward digital support channels that reduce specification friction and accelerate project decision cycles. On the project delivery side, Strut Systems Installation carried out a custom Unistrut framing support system for raised access floors at a major university in May 2025, illustrating how specialized framing solutions are being deployed to increase load capacity in high-traffic institutional settings. These examples are not isolated news items; they are indicators of how companies are competing on engineering depth, service accessibility, and application-specific performance.
Market Dynamics: Raw Material Economics and Regulatory Tailwinds
Infrastructure markets rarely move in isolation from input costs and standards evolution, and the raised access floor sector is no exception. Steel pricing, a fundamental driver of material economics for encapsulated and structural panel systems, has shown notable regional divergence. In May 2026, steel plate prices in Northeast Asia reached approximately USD 1.83 per kilogram, representing an 8.3 percent increase from the prior month, while North American prices stood at roughly USD 2.74 per kilogram, down 7.4 percent over the same period. This divergence matters because it influences regional manufacturing cost structures, export competitiveness, and the relative attractiveness of locally sourced versus imported components. Procurement leaders who monitor these shifts can time commitments more effectively, structure contracts with appropriate escalators, and evaluate supplier stability with greater foresight.
On the regulatory and standards front, recent updates to ASHRAE Standard 62.1 have explicitly referenced underfloor air distribution as a best-practice ventilation strategy, reinforcing the specification of raised access floors in new commercial construction projects. This kind of standards-level recognition does more than validate an existing technology; it shapes designer behavior, influences building certification pathways, and creates a durable preference signal for systems that support controlled air movement and energy-efficient ventilation. As sustainability mandates and indoor environmental quality requirements continue to tighten, specification advantages tied to recognized standards can meaningfully affect tender outcomes and architectural preference. Our report weaves these dynamics into a broader framework, helping readers understand not only what is happening, but why it matters for specification strategy, cost planning, and long-term asset performance.
Worldwide Reinforced Concrete Floor Market
Why This Research Is Positioned for 2026 Decision-Making
The 2026 planning cycle presents a convergence of operational pressures and strategic opportunities. Organizations are simultaneously managing data center expansion, office space realignment, and stricter environmental and safety expectations. In that environment, raised access flooring is no longer a commoditized line item; it is a design decision that affects airflow performance, cabling flexibility, maintenance access, load resilience, and future retrofit costs. Executives who treat it as a strategic variable rather than a passive procurement category will be better positioned to control total cost of ownership and reduce specification risk.
The full PW Consulting study is built to support that shift in mindset. It provides a clear analytical bridge from macro growth patterns to segment-level decision logic, from competitive positioning to supplier evaluation criteria, and from raw material volatility to contracting strategy. Readers will find frameworks that can be applied directly to capital planning, vendor shortlisting, specification development, and regional market assessment. The report is also structured to help leadership teams ask sharper questions: Which material and construction types align with anticipated load and environmental requirements? Where do integration benefits justify premium specifications? How do regional cost structures and standards environments shape supplier selection? What early indicators suggest shifts in competitive advantage or pricing power?
Accessing the Complete Intelligence
This article is intended as a strategic prelude rather than a standalone briefing. The growth trajectory, competitive behaviors, and market dynamics described here reflect the analytical foundation of our broader study, but the full report contains the detailed segmentation logic, company evaluations, specification guidance, and forward-looking scenario analysis needed to translate insight into action. For executives, project leaders, and investment planners navigating infrastructure decisions in 2026 and beyond, the complete PW Consulting Raised Access Floor Market research offers a structured, evidence-based pathway to more confident decision-making. We invite you to explore the full study for the comprehensive data, segmentation depth, and competitive intelligence that will support your next planning cycle.
For detailed analysis of this topic, please visit the official page: Raised Access Floor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Packaged Substation Market to Reach $338M by 2032 with 6.5% CAGR
By PW Consulting, 2026-09-16
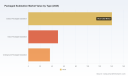
Executive Summary: Navigating the Packaged Substation Market Opportunity
The global energy landscape is undergoing a structural transformation. As electrification accelerates across industrial, infrastructure, and utility sectors, the demand for reliable, scalable, and rapidly deployable power distribution solutions has never been more critical. At PW Consulting, we recognize that the packaged substation market represents a pivotal intersection of grid modernization, smart infrastructure development, and operational efficiency. Our latest market research report on the Packaged Substation Market delivers a comprehensive, data-driven analysis designed to equip executive teams, investors, and strategic planners with the intelligence required to navigate this evolving landscape through 2032 and beyond.
This report is not merely a retrospective of historical performance. It is a forward-looking strategic instrument built on rigorous quantitative modeling, primary research validation, and deep competitive intelligence. Drawing on historical tracking from 2020 through the base year of 2025, and extending our forecasts across an eight-year period from 2026 to 2032, the study captures both the trajectory that has shaped the market and the inflection points that will define its next phase of growth. The overarching narrative is one of sustained expansion, where market valuation has demonstrated consistent upward momentum and is projected to reach new milestones as deployment cycles accelerate across multiple geographies and application verticals.
What sets this analysis apart is its emphasis on actionable strategic insight. We do not simply report numbers; we contextualize them within operational realities, regulatory shifts, supply chain dynamics, and technological adoption curves. The following sections outline the core components of the research, the competitive forces at play, the regulatory and macro-environmental drivers reshaping procurement and deployment strategies, and the strategic decisions that industry leaders must address in 2026 and beyond.
Market Trajectory and Structural Growth Dynamics
The packaged substation sector has transitioned from a niche, project-driven segment to a mainstream component of modern power distribution architecture. Historical tracking over the past half-decade reveals a market that has steadily expanded in both volume and strategic importance, reflecting broader electrification trends, grid reliability mandates, and the growing preference for prefabricated, modular deployment models over traditional on-site construction approaches. Our baseline assessments place the market at a substantial valuation in the base year, with continuous year-over-year progression underscoring the durability of underlying demand drivers.
The growth trajectory extends well beyond short-term cyclical recovery. Forecast modeling across the 2026–2032 horizon indicates a compound annual growth rate that reflects sustained momentum rather than a temporary surge. This expansion is not evenly distributed; it is shaped by differentiated adoption curves across regional markets, varying procurement timelines in industrial and infrastructure development programs, and the phased integration of new substation technologies into legacy grid architectures. Early forecast years already demonstrate incremental value gains, with growth compounding as manufacturing scale, supply chain localization, and deployment experience reduce lead times and improve project economics.
Packaged Substation Market
A critical element of the forecast methodology is its sensitivity to real-world constraints. Material cost fluctuations, labor availability, permitting frameworks, and the pace of renewable integration all exert measurable influence on deployment pacing and value realization. By incorporating these variables into scenario-based modeling, the report equips stakeholders with a realistic framework for capital allocation, inventory planning, and partnership positioning. The result is a market outlook that balances optimism with operational pragmatism, enabling decision-makers to plan for both baseline growth and upside opportunities tied to accelerated infrastructure programs and technology adoption.
Competitive Landscape and Strategic Positioning
The competitive architecture of the packaged substation market is defined by a blend of global technology leaders, specialized electrical equipment manufacturers, and regional players with deep integration into local infrastructure and utility ecosystems. Market concentration metrics indicate a moderately fragmented environment, where the top three and top five players collectively hold meaningful but not dominating shares, leaving substantial room for differentiated positioning through technology, service models, and regional execution capability.
At the forefront of the market are organizations that have aligned their product portfolios with broader grid modernization priorities. ABB Ltd, headquartered in Zurich, has positioned itself around advanced compact and modular substation designs engineered for smart grid applications, high-reliability power distribution, and optimized operational performance across diverse electrical networks. Siemens Energy AG, based in Munich, has developed prefabricated substation solutions tailored for metro rail, EV charging, and renewable energy integration, aligning its offerings with mobility electrification and clean energy transitions. Schneider Electric SE, operating from Rueil-Malmaison, focuses on medium-voltage and low-voltage package substations designed for industrial and utility distribution, emphasizing integration, protection, and control architectures that support distributed energy resources.
Eaton Corporation, headquartered in Dublin, brings electrical distribution solutions that span package substations for industrial facilities and infrastructure, with an emphasis on operational resilience and system-level efficiency. In Asia, a strong cohort of manufacturers has expanded its footprint through integrated electrical solutions and scaled production. Larsen & Toubro Ltd, Kirloskar Electric Company Ltd, CG Power and Industrial Solutions Ltd, and C&S Electric Limited each contribute distinct capabilities across power distribution, industrial projects, and utility applications, reinforcing the region's role as both a major demand center and an increasingly competitive manufacturing base.
Global technology and heavy electrical players also maintain significant relevance. Hyundai Electric, Toshiba Corporation, and Hitachi Energy Ltd offer medium-voltage and low-voltage packaged substations, transmission and distribution equipment, and eco-efficient modular products that support renewable integration and higher-voltage applications. CHINT Group, based in Ningbo, has emerged with modular prefabricated substations featuring integrated components designed for rapid deployment and reliability, while Lucy Electric contributes switchgear and packaged substation solutions for power distribution networks.
Recent corporate and project activity illustrates how competitive differentiation is being executed in practice. In mid-2025, State Grid Anyang Power Supply Company commissioned Linzhou's first 110 kV mobile substation, a 50 MVA prefabricated unit installed within a ten-day window and deployed to supply industrial load alongside new-energy charging stations. That same year, CHINT Group introduced modular prefabricated substations emphasizing factory assembly, third-party type testing, and customized designs for extreme environments, followed by a later delivery of an integrated MV skid solution for the MASDAR Bukhara 250 MW Solar PV Plant in Uzbekistan. Hitachi Energy announced plans to deliver the world's first SF6-free 550 kV GIS, signaling a broader shift toward eco-efficient substation advancements, while Schneider Electric initiated localization of modular substation production in Asia to strengthen supply chain reliability and reduce lead times. These developments underscore a competitive environment in which speed, certification, environmental performance, and regional manufacturing capability are becoming decisive advantages.
Technological, Regulatory, and Macroeconomic Drivers
The packaged substation market does not evolve in isolation. Its growth profile is closely tied to a cluster of technological, regulatory, and macroeconomic forces that are reshaping how power is generated, transmitted, distributed, and consumed. Understanding these drivers is essential for mapping both near-term procurement behavior and longer-term portfolio strategy.
From a technological standpoint, modularization and factory-based fabrication have become central value propositions. Prefabricated, box-type, and skid-mounted substation designs offer measurable reductions in overall project cost and installation time compared with traditional brick-and-mortar construction approaches. Factory-built configurations also reduce on-site labor requirements by substantial margins through pre-testing and modular assembly, which is particularly relevant in markets experiencing skilled labor constraints or where rapid commissioning is required to support industrial expansion and infrastructure timelines. In parallel, the push toward eco-efficient substation technologies is accelerating, with high-voltage gas-insulated switchgear innovations and SF6-free agendas moving from research emphasis to commercial readiness.
Regulatory frameworks are exerting both standardizing and enabling effects. International standards such as IEC 62271-202:2022 define service conditions, rated characteristics, general structural requirements, and test methods for enclosed high-voltage prefabricated substations, providing a common technical baseline that supports cross-border procurement, interoperability, and quality assurance. On the policy front, European Commission guidance issued in mid-2025 emphasizes ensuring electricity grids are fit for the future, offering incentives for anticipatory investments in grid reinforcements and substation capacity. In the United States, executive action from mid-2025 prioritizes accelerating federal permitting for data center infrastructure, including substations and switchgear, directly linking substation deployment to the rapid expansion of digital infrastructure and computational load.
Emergency Mobile Substation Market
Material and labor economics further influence adoption decisions. The financial case for packaged substations is strengthened by demonstrable cost avoidance in site construction, shortened deployment schedules, and reduced exposure to on-site execution risk. These advantages are especially pronounced in industrial and infrastructure applications where downtime minimization, spatial constraints, and schedule certainty carry significant operational and financial implications. As a result, procurement strategies are increasingly shifting from lowest-unit-price evaluations toward total-lifecycle and total-project-value assessments, in which reliability, lead time, commissioning speed, and environmental compliance all contribute to the final decision calculus.
Core Report Framework and Strategic Deliverables
The Packaged Substation Market report is structured to translate complex market data into clear strategic guidance. It is designed for executives who require both breadth and precision without being overwhelmed by undifferentiated data tables. The report integrates historical analysis, forward-looking forecasts, segmentation insights, competitive profiling, and scenario-based interpretation into a cohesive analytical framework.
At the core of the study is a detailed market size and growth analysis anchored in historical performance from 2020 through 2025 and extended across the forecast period to 2032. Revenue trends are examined in a standardized global currency, enabling consistent comparison across periods and supporting financial planning, demand forecasting, and investment scenario modeling. The analysis captures how value has accumulated over time and how it is expected to compound as deployment activity broadens across regions and end-use environments.
Segmentation is treated as a strategic lens rather than a static taxonomy. The report examines the market across multiple dimensions that matter to procurement, manufacturing, and distribution planning. This includes an evaluation of deployment configurations and engineering forms, reflecting the differing requirements of outdoor, indoor, and underground applications; a geographic breakdown that illuminates relative market weight and growth pacing across major regions; and an application-level analysis that differentiates demand patterns across industrial environments, infrastructure programs, and power generation and utility operations. Each segmentation view is contextualized with demand drivers, adoption constraints, and strategic implications, allowing readers to identify where opportunity is concentrated and where execution risk may be elevated.
Competitive intelligence is developed through company-level profiling that goes beyond headline positioning. Profiles capture each organization's specific offering logic, technological emphasis, and application focus, providing a basis for benchmarking, partnership evaluation, and threat assessment. The report also incorporates recent developments that illustrate how companies are translating strategy into action through product launches, project deliveries, supply chain localization, and technology announcements. This dynamic view of competition helps stakeholders anticipate vendor behavior, pricing pressure, and differentiation trends rather than reacting to them after the fact.
Beyond structure and segmentation, the report includes practical tools for strategic planning. These encompass demand-side interpretation for capital and capacity planning, supply-side considerations for manufacturing and sourcing strategy, and environmental and regulatory mapping for compliance and ESG alignment. Scenario framing supports sensitivity analysis around lead times, cost structures, and deployment pacing, giving decision-makers a way to test assumptions before committing resources.
Strategic Implications for 2026 Decision-Making
As organizations enter 2026, the packaged substation market presents a set of strategic choices that extend well beyond traditional procurement considerations. The convergence of grid modernization mandates, renewable integration requirements, digital infrastructure expansion, and modular deployment economics is reshaping how value is created and captured across the value chain. Companies that approach this environment with a clear strategic posture will be better positioned to convert market growth into durable advantage.
One immediate implication concerns portfolio and capacity alignment. With growth forecasts indicating steady expansion over the forecast horizon, organizations must evaluate whether current production capacity, sourcing arrangements, and service capabilities are sufficient to meet accelerating demand without compromising reliability or margin. For manufacturers, this raises questions about factory throughput, component standardization, certification pathways, and regional localization. For distributors and system integrators, it raises questions about inventory positioning, lead-time management, and the ability to offer integrated solutions rather than standalone equipment.
A second implication relates to competitive differentiation. In a market where top-tier concentration remains moderate, differentiation increasingly depends on technology integration, deployment speed, environmental performance, and regional execution quality. Firms that can demonstrate credible advantages in factory-based testing, modular configuration, rapid commissioning, and eco-efficient design are better placed to compete on total project value rather than price alone. Recent moves toward localized production and advanced substation technologies illustrate how manufacturers are attempting to secure both cost and credibility advantages simultaneously.
A third implication centers on demand-side planning. Industrial operators, infrastructure developers, and utility organizations must assess how substation deployment timing interacts with broader project schedules, permitting pathways, and load growth expectations. The availability of prefabricated options that reduce on-site labor, accelerate installation, and align with recognized international standards can materially affect project feasibility and risk profiles. Decision-makers should therefore evaluate substation sourcing not merely as an equipment purchase but as a schedule, reliability, and compliance decision that influences downstream operational outcomes.
Finally, regulatory and environmental trends warrant proactive strategy development. Standards development, incentives for grid reinforcement, permitting acceleration for critical infrastructure, and the broader transition toward lower-impact substation technologies are all shaping future procurement requirements. Organizations that integrate these considerations into product roadmaps, sourcing strategies, and project planning will be better prepared to navigate compliance expectations and capture incentives tied to anticipatory investment.
Conclusion and Call to Action
The packaged substation market is at a point where structural demand, technological maturation, and policy support are aligning to sustain a multi-year growth trajectory. Historical performance establishes a credible foundation, and forward-looking modeling suggests that the momentum will continue as deployment models become more efficient, regional manufacturing expands, and grid modernization priorities intensify. Yet the strategic value of this market lies not only in its size and growth rate but in the way it intersects with broader energy, industrial, and infrastructure decisions.
PW Consulting's Packaged Substation Market report is designed to help leaders navigate that complexity with confidence. It combines rigorous quantitative analysis with practical competitive and regulatory context, enabling organizations to identify where to invest, how to differentiate, and which risks to manage proactively. The full report provides detailed segmentation interpretation, competitive benchmarking, scenario analysis, and development tracking that go beyond the executive overview presented here.
For executives, investors, and strategy teams seeking a complete view of market sizing, segmentation dynamics, competitive positioning, and forward-looking implications through 2032, we invite you to access the full research on our website. The complete intelligence package is structured to support capital planning, market entry evaluation, partnership strategy, and operational decision-making with the depth and precision required for high-stakes 2026 planning.
For detailed analysis of this topic, please visit the official page: Packaged Substation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Incident Response Market Hits $35.2B in 2025, Poised for 18.52% CAGR to 2032
By PW Consulting, 2026-09-16
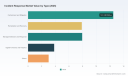
Navigating the New Reality: Strategic Imperatives in the 2026 Incident Response Landscape
The cybersecurity landscape has undergone a fundamental transformation. No longer viewed merely as a technical contingency, incident response (IR) has emerged as a core business continuity function and a critical component of enterprise risk management. As organizations grapple with increasingly sophisticated attack vectors, regulatory pressures, and the operational complexities of hybrid work environments, the ability to detect, contain, and recover from security incidents with speed and precision has become a defining competitive advantage.
This article serves as an introduction to the latest market research publication from PW Consulting, designed to equip executive leaders, security architects, and investment strategists with the comprehensive intelligence needed to navigate the Incident Response market through 2032. The following analysis highlights the market trajectory, structural dynamics, and strategic considerations that will shape decision-making in 2026 and beyond. Readers seeking the full granular segmentation, regional revenue breakdowns, competitive benchmarking matrices, and actionable investment roadmaps are invited to access the complete report through our dedicated source page.
Worldwide Information Security Market
Market Trajectory: A Sector Defined by Accelerated Expansion
The Incident Response market has demonstrated remarkable resilience and growth over the past half-decade, transitioning from a reactive cost center to a proactive strategic investment. Historical data from 2020 through 2025 illustrates a consistent upward trajectory, with the overall market expanding from approximately 22.41 billion USD in 2020 to 35.2 billion USD by 2025. This growth reflects a broader industry recognition that traditional perimeter defenses are insufficient against modern threat actors, driving enterprises to allocate significant capital toward integrated response capabilities.
Projecting forward into the forecast period spanning 2026 to 2032, the market is poised for sustained momentum. The sector is expected to reach 40.7 billion USD in 2026, with growth accelerating steadily to approximately 50.71 billion USD by 2027, 59.83 billion USD by 2028, and continuing through to an estimated 116.17 billion USD by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of 18.52 percent, signaling one of the most robust growth profiles within the broader cybersecurity ecosystem.
Such momentum is not merely a function of increased spend; it reflects a structural shift in how organizations value resilience. The compounding effect of this growth trajectory suggests that incident response will increasingly intersect with board-level discussions around digital transformation, insurance underwriting, and regulatory compliance. Decision-makers operating without a clear view of this trajectory risk misallocating resources or falling behind competitors who are already embedding IR capabilities into their enterprise architecture.
Structural Dynamics: What Is Driving Demand in 2026
Regulatory and Compliance Imperatives
The regulatory environment has become a primary catalyst for incident response adoption. In May 2026, the Cybersecurity and Infrastructure Security Agency (CISA) rescheduled virtual town hall meetings regarding the proposed rule for the Cyber Incident Reporting for Critical Infrastructure Act of 2022, with proceedings set to begin on June 15, 2026. The proposed rule mandates that critical infrastructure organizations report cyber incidents to CISA within 72 hours and ransom payments within 24 hours. These tightening timelines create an acute operational requirement for organizations to have established response protocols, forensic capabilities, and communication frameworks ready before an incident occurs, rather than improvising under pressure.
For enterprises across critical sectors, compliance is no longer a checkbox exercise. It demands documented playbooks, trained response teams, and integrated tooling that can capture evidence and execute containment in real time. Organizations that treat IR as a compliance function alone will find themselves exposed; those that treat it as a strategic capability will gain both regulatory alignment and operational resilience.
The Multi-Vector Threat Reality
Threat actor methodology has evolved significantly. According to the 2026 Unit 42 Global Incident Response Report from Palo Alto Networks, which analyzed over 750 major cyber incidents investigated in 2025, 87 percent of intrusions involved activity across multiple attack surfaces. This finding underscores a critical reality: organizations can no longer afford siloed security operations where endpoint, network, cloud, and identity domains operate in isolation.
The implication for the incident response market is profound. Response capabilities must be orchestrated across the entire attack surface, integrating telemetry, automation, and human expertise into a unified workflow. This multi-vector reality is pushing enterprises toward managed detection and response arrangements, platform-based analytics, and retainer-based professional services that can scale during active incidents. The market is responding accordingly, with growth distributed across containment, mitigation, remediation, recovery, digital forensics, and analytics functions.
The Preparedness Gap
Despite increased investment, a troubling disconnect persists between planning and operational readiness. Sygnia's 2026 CISO Survey, titled The State of Incident Response Readiness, highlighted that many organizations maintain documented incident response plans that do not translate into effective execution during real-world events. This gap between theoretical preparedness and practical capability represents both a risk and an opportunity. It creates demand for services that bridge the divide: tabletop exercises, retainer engagements, rapid deployment forensics teams, and technology that reduces the cognitive load on responders during high-pressure situations.
Market Scope and Segmentation: A High-Level View
The Incident Response market encompasses a diverse set of services and solutions, reflecting the multifaceted nature of modern threat response. At a high level, the market can be understood through several structural dimensions that collectively define how organizations procure and consume IR capabilities.
- Response and Recovery Functions: The market is anchored by containment and mitigation capabilities, complemented by remediation and recovery services that restore operational integrity after an incident. Managed detection and response arrangements have gained significant traction, offering organizations continuous monitoring and rapid intervention without the need to build fully in-house capabilities. Digital forensics and analytics provide the evidentiary and investigative backbone necessary for both internal decision-making and external reporting obligations.
- Application Across Sectors: Incident response demand is broad-based, spanning highly regulated industries such as financial services and government and defense organizations, as well as technology and telecommunications providers, energy and utilities operators, and a range of other sectors. Each vertical brings distinct compliance requirements, threat profiles, and operational constraints that shape how response capabilities are deployed.
- Geographic Distribution: Demand is distributed across major global regions, with North America representing a substantial share, followed by Europe and Asia Pacific. Latin America and the Middle East and Africa represent emerging growth zones where regulatory maturation and threat landscape evolution are driving incremental investment.
The complete report provides detailed revenue distributions across each segmentation dimension, including regional breakdowns, service-type allocations, and vertical-specific demand patterns. These granular insights are essential for organizations seeking to benchmark their own positioning, identify underserved niches, or evaluate partnership opportunities within specific market pockets.
Competitive Landscape: Leaders, Specialists, and Emerging Models
The Incident Response market is characterized by a mix of platform-centric technology vendors, professional services firms, and specialized response boutiques. Market concentration data indicates that the top three competitors command approximately 48 percent of total market revenue, while the top five collectively represent around 68 percent. This concentration reflects the dominance of large, integrated players who offer end-to-end capabilities spanning detection, response, forensics, and managed services. However, significant opportunity remains for specialized firms that deliver deep expertise, retainer-based engagements, and sector-specific knowledge.
Platform Leaders and Integrated Ecosystems
Several prominent organizations define the current competitive landscape. CrowdStrike, headquartered in San Francisco, offers the Falcon platform with managed detection and response capabilities, integrating advanced incident response functions within a unified endpoint and cloud security ecosystem. SentinelOne, based in Mountain View, provides the Singularity Platform and Vigilance Respond services, leveraging AI-powered endpoint detection and response to support incident response workflows. Palo Alto Networks, located in Santa Clara, delivers Unit 42 global incident response services alongside Cortex XDR and Prisma Access solutions, combining threat intelligence with operational response capabilities.
IBM, headquartered in Armonk, provides IBM Security QRadar alongside professional incident response services, offering enterprises a combination of SIEM-driven analytics and expert intervention. Cisco Systems, based in San Jose, delivers incident response capabilities through the Cisco SecureX platform, emphasizing integration across network, endpoint, and cloud security domains. Rapid7, located in Boston, offers InsightIDR and automated incident response automation tools, focusing on reducing mean time to respond through orchestrated workflows. Sophos, also headquartered in Boston, provides MDR and incident response through its Sophos MDR and EDR solutions, targeting mid-market and enterprise customers with managed security offerings.
Specialized Services and Retainer-Based Models
Alongside platform providers, a cohort of professional services and specialized response firms plays a critical role in the ecosystem. NCC Group, based in London, offers professional incident response retainer and investigation services, providing clients with pre-arranged access to expert teams during active incidents. Kroll, headquartered in New York, delivers comprehensive digital forensics and global incident response recovery services, serving organizations that require deep investigative capabilities and cross-border response support. Beazley, also based in London, delivers cyber incident response services as part of broader cyber and data resilience offerings, often intersecting with insurance and risk transfer frameworks.
Optiv Security, located in Reston, offers managed security services and incident response retainer programs, helping organizations bridge the gap between technology deployment and operational execution. Check Point Software Technologies, headquartered in Tel Aviv, provides incident response through its solution portfolio and professional services, supporting organizations that seek integrated threat prevention alongside response capabilities.
Recent Market Movements and Strategic Shifts
The competitive landscape continues to evolve through partnerships, publications, and market recognition. In March 2026, LevelBlue announced an expanded global strategic partnership with SentinelOne to deliver AI-powered managed security operations and incident response, signaling a trend toward combining managed service delivery with advanced platform capabilities. In April 2026, Palo Alto Networks published the 2026 Unit 42 Global Incident Response Report, providing detailed insights from over 750 major cyber incidents investigated in 2025 and reinforcing the importance of cross-surface visibility.
Sygnia made notable strides in April 2026, releasing the 2026 CISO Survey that highlighted gaps between incident response planning and operational readiness, while also being named a Representative Vendor in the 2026 Gartner Market Guide for Cybersecurity Incident Response Retainer Services. These developments underscore a market that is maturing in its understanding of what effective response requires: not just technology, but validated processes, trained personnel, and pre-established relationships that can be activated at a moment's notice.
Strategic Considerations for 2026 Decision-Makers
As organizations evaluate their incident response strategy for 2026 and beyond, several strategic considerations merit focused attention. These considerations extend beyond technology procurement to encompass organizational design, vendor selection, regulatory alignment, and investment prioritization.
Build, Buy, or Partner: Defining the Operating Model
One of the most consequential decisions facing enterprises is the structure of their incident response capability. Some organizations pursue a fully in-house model, building internal teams, acquiring platform tools, and developing internal playbooks. Others rely heavily on managed detection and response providers or professional services retainers. The optimal approach is rarely binary. Most mature organizations adopt a hybrid model: maintaining internal oversight, governance, and critical decision-making authority while leveraging external partners for surge capacity, specialized forensics, and 24/7 monitoring coverage.
Determining the right mix requires a clear understanding of internal maturity, risk tolerance, budgetary constraints, and the specific threat profile of the organization. The complete report provides frameworks for evaluating these trade-offs, including comparative analyses of service models, cost structures, and performance outcomes across different operating approaches.
Incident Response Market
Integrating Response with Broader Security Architecture
Incident response cannot function effectively in isolation. It must be integrated with preventive controls, threat intelligence, identity management, and data protection programs. Organizations that treat response as a standalone function often encounter friction during incidents: telemetry is siloed, containment actions are delayed by cross-team dependencies, and recovery processes conflict with business continuity requirements.
A more effective approach embeds response capabilities within a layered security architecture, ensuring that detection signals flow seamlessly into response workflows, that containment actions are coordinated across endpoint, network, and cloud domains, and that recovery processes are aligned with organizational resilience objectives. This integration also supports compliance objectives, particularly as reporting timelines tighten under emerging regulatory frameworks.
The Role of Automation and AI in Response Operations
Automation and artificial intelligence are increasingly central to incident response effectiveness. AI-powered endpoint detection, automated triage, and orchestrated response playbooks can significantly reduce the time between detection and containment, which is critical given the speed at which modern threats propagate across multiple attack surfaces. However, technology alone is insufficient. Automation must be paired with clear escalation paths, human judgment for complex decision-making, and regular testing to ensure that automated actions produce the intended outcomes.
The market is seeing growing demand for solutions that combine AI-driven detection with human-led investigation and response, particularly in scenarios that require contextual understanding, legal considerations, or coordination with law enforcement and regulators. Organizations evaluating technology investments should prioritize platforms that support this human-machine collaboration rather than treating automation as a wholesale replacement for expert response.
Preparedness as a Continuous Discipline
The gap between planning and operational readiness identified in recent industry surveys points to a broader truth: incident response is not a one-time project but a continuous discipline. Organizations that treat response readiness as a static deliverable, such as a documented plan filed away after an initial assessment, will find themselves ill-prepared when an actual incident occurs. Effective readiness requires regular testing through tabletop exercises and simulated incidents, ongoing training for response teams, periodic review of playbooks against evolving threat intelligence, and established relationships with external responders that can be activated under pressure.
For organizations operating in regulated sectors, readiness also encompasses documentation, evidence preservation, and reporting workflows that align with legal and regulatory obligations. Treating these elements as integral components of response capability, rather than afterthoughts, will differentiate resilient organizations from those that struggle during incidents.
Why This Research Matters: Turning Intelligence into Action
Market research in the incident response space must go beyond high-level growth figures and surface-level trend summaries. Decision-makers need actionable intelligence that connects market dynamics to concrete strategic choices: where to invest, how to structure partnerships, which capabilities to prioritize, and how to position an organization for both risk mitigation and competitive advantage.
The full PW Consulting Incident Response Market report delivers this depth. It provides comprehensive segmentation analysis across regions, service types, and application verticals, enabling readers to benchmark their own market positioning and identify growth opportunities. It offers detailed competitive profiling of key market participants, including technology capabilities, service offerings, recent strategic moves, and market share dynamics. It examines regulatory developments, threat landscape evolution, and operational challenges that are shaping demand, with a particular focus on implications for 2026 and the forecast period through 2032.
For enterprise leaders, the report serves as a decision-support tool for aligning security investments with business objectives. For investors and market analysts, it provides a data-rich view of market structure, growth drivers, and competitive positioning. For vendors and service providers, it offers insights into demand patterns, customer priorities, and emerging opportunities across different segments of the incident response ecosystem.
Accessing the Complete Intelligence
This article has provided a strategic overview of the Incident Response market, highlighting growth trajectory, structural dynamics, competitive landscape, and key considerations for 2026 decision-making. However, the full scope of intelligence available in the complete PW Consulting report extends well beyond this summary. Detailed revenue breakdowns by region, type, and application; competitive benchmarking across all profiled companies; granular analysis of regulatory impacts and threat trends; and actionable recommendations for investment and operational planning are all contained within the full publication.
To access the complete dataset, competitive matrices, segmentation deep-dives, and strategic frameworks, visit the dedicated source page for the Incident Response Market research. The full report is designed to support executive briefings, investment committee discussions, vendor evaluation processes, and long-term strategic planning, providing the comprehensive intelligence needed to navigate a market defined by rapid growth, evolving threats, and increasing regulatory complexity.
The incident response landscape will continue to evolve at a pace that demands informed, proactive decision-making. Organizations that invest in understanding the market's structure, dynamics, and trajectory will be best positioned to build resilience, meet compliance obligations, and turn incident response from a reactive necessity into a strategic capability. The complete PW Consulting report provides the foundation for that understanding.
For detailed analysis of this topic, please visit the official page: Incident Response Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The AR/VR market in China has demonstrated strong revenue expansion since 2020, with an estimated market size of USD 2,300 million in 2025 and a projected CAGR of 21% through 2035. The revenue chart indicates a steady upward trajectory, driven by technological advances, expanding consumer usage, and significant enterprise adoption across industries. By 2035, the market is anticipated to reach USD 15,600 million, highlighting the long-term investment potential and transformative impact of AR/VR technologies in the Chinese landscape.
Read More - https://bussinessinsights.com/research-report/china-augmented-and-virtual-reality-market
The application landscape in 2025 is led by the gaming segment, which holds a commanding 41% market share. Healthcare follows at 21%, reflecting strong adoption for training, surgery, and diagnostics. Education is the third-largest application, making up 18% of the market, driven by the increasing use of AR/VR tools in classrooms and training modules. Retail, manufacturing, and automotive collectively make up the remainder, each showing steady gains but not surpassing the top three applications. This distribution confirms the dominance of entertainment and essential services in driving AR/VR technology adoption across China.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-augmented-and-virtual-reality-market
Frequently Asked Questions
Who are the key players in China Augmented and Virtual Reality Market industry?
The top five players in China’s AR and VR market are Huawei, Xiaomi, Nreal, DPVR, and Tencent. Huawei leads in hardware innovation, Xiaomi focuses on affordable smart devices, Nreal is known for lightweight AR glasses, DPVR specializes in immersive VR headsets, and Tencent advances gaming and social AR/VR platforms.
What is the China Augmented and Virtual Reality Market growth?
The China AR and VR market is experiencing rapid growth, with double-digit annual expansion. In 2023, the market saw significant investment and soaring consumer adoption, especially with companies like Nreal launching mass-market AR glasses and Huawei introducing new VR devices, driving strong year-on-year market growth.
Which segment accounted for the largest China Augmented and Virtual Reality Market share?
Gaming and entertainment applications hold the largest market share in China’s AR and VR market. Popular platforms like Tencent VR and NetEase have witnessed widespread adoption as consumers increasingly use AR/VR for immersive gaming, interactive live streaming, and virtual social experiences, outpacing education and industrial applications.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
China's XR market revenue demonstrates a strong upward trajectory between 2020 and 2035. The sector, valued at USD 7,200 Million in 2020, is projected to reach USD 46,800 Million by 2035. Growth accelerates rapidly post-2025, when 5G expansion and large-scale adoption across multiple sectors catalyze market penetration. Leading tech players' heavy investment in product development and XR content ecosystem further sustains the revenue surge, positioning China as a global powerhouse in the extended reality arena.
Read More - https://bussinessinsights.com/research-report/china-extended-reality-market
Gaming & entertainment remains the core application for XR in China, making up the largest market share in 2025, given the strong e-sports ecosystem and rising demand for immersive content. Healthcare follows, leveraging XR for advanced diagnostics and medical training. Education is a fast-growing sector, with widespread use of AR/VR in remote learning and interactive classrooms. Retail, industrial manufacturing, and automotive collectively form a substantial segment, adopting XR for product visualization, process optimization, and in-vehicle infotainment. This diverse application landscape highlights XR's transition from gaming-centric to a multi-sectoral tool driving digital transformation.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-extended-reality-market
Frequently Asked Questions
Who are the key players in China Extended Reality Market industry?
Key players in the China Extended Reality market include Tencent, Alibaba Group, HTC Corporation, Huawei Technologies, and Baidu. These companies invest heavily in XR research and development, offering a range of products from VR headsets to AR platforms and content ecosystems, thus driving innovation and adoption across industries.
What is the China Extended Reality Market growth?
The China Extended Reality market has witnessed robust growth, with market size expected to surpass USD 14 billion by 2025. Recent growth factors include Alibaba’s investments in AR-powered online retail experiences, which have accelerated adoption and contributed to the market’s double-digit compound annual growth rate.
Which segment accounted for the largest China Extended Reality Market share?
The gaming and entertainment segment holds the largest market share in China’s Extended Reality market. Driven by immersive applications and consumer demand, companies like Tencent have launched VR and AR-enabled games, making this segment the primary revenue generator among all XR applications.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com