

Blogs
The market revenue for battery monitoring systems in China is set for robust growth between 2020 and 2035. The sector is forecast to expand from $900 Million in 2021 to $2,200 Million by 2035, reflecting rapid adoption in mobility, infrastructure, and renewables. Government policy support, urban electric vehicle deployment, and ongoing grid modernization projects are central to this momentum. Periodic surges in investment and new technological introductions contribute to a stable upward trajectory in annual revenues.
Read More - https://bussinessinsights.com/research-report/china-battery-monitoring-system-market
Automotive applications are projected to account for the largest portion of the China Battery Monitoring System Market by 2025, reflecting the explosive growth of electric vehicles and hybrid powertrains in the region. Telecommunications and energy storage also command notable shares, as reliable backup and uninterrupted power remain paramount. Data centers and industrial uses are driving the adoption of advanced BMS, driven by expanding digital and manufacturing infrastructure. These trends highlight the strategic transition of battery monitoring from legacy utilities toward next-generation mobility and digital industries.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-battery-monitoring-system-market
Thanks & Regards,
priya
sales@bussinessinsights.com
The China Ultraviolet Analyzer Market is poised for notable expansion with revenues projected to increase from $453 million in 2020 to approximately $1,145 million by 2035, reflecting a compound annual growth rate of around 6.5%. This upward trajectory is attributed to increased investments in environmental infrastructure, rising adoption across various industries, and a steady stream of technological innovation. Significant revenue increments are expected especially during 2027–2031 as several government-led green and safety initiatives materialize.
Read More - https://bussinessinsights.com/research-report/china-ultraviolet-analyzer-market
By application, water quality monitoring is expected to dominate the China Ultraviolet Analyzer Market in 2025, accounting for the highest share as municipal and industrial demands surge under new regulatory mandates. Chemical analysis follows, underpinned by the chemical sector's modernization, while environmental monitoring is increasingly relevant given green initiatives. The food and beverage and pharmaceutical analysis segments are also growing rapidly as producers seek rapid, non-destructive testing solutions to ensure safety and compliance.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-ultraviolet-analyzer-market
Frequently Asked Questions
Who are the key players in China Ultraviolet Analyzer Market industry?
Key players in the China Ultraviolet Analyzer Market include Thermo Fisher Scientific, Shimadzu Corporation, ABB Ltd, Hach Company, and Focused Photonics Inc (FPI). These companies lead the market with advanced analytical technologies, strong distribution networks, and innovative UV analyzer solutions tailored for environmental, industrial, and research applications.
What is the China Ultraviolet Analyzer Market growth?
The China Ultraviolet Analyzer Market is experiencing robust growth, driven by increasing environmental monitoring regulations and demand for improved analytical tools. For instance, Thermo Fisher Scientific has reported increased sales in UV analyzers, attributing growth to stricter pollution control policies and industrial upgrades in China.
Which segment accounted for the largest China Ultraviolet Analyzer Market share?
The environmental monitoring segment accounted for the largest market share in the China Ultraviolet Analyzer Market. Applications such as air and water quality analysis are in high demand due to regulatory focus, prompting significant investments from local governments and industries to deploy advanced UV analyzers for compliance.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China 4K Display Resolution market revenue demonstrates a robust growth trajectory, expanding from $3,500 Million in 2020 to an estimated $11,500 Million by 2025. Sustained growth is projected, with revenues reaching approximately $28,000 Million by 2035. This upward trend reflects increasing demand across consumer electronics, business, and public sectors, driven by technological advancement and the proliferation of ultra-high definition content.
Read More - https://bussinessinsights.com/research-report/china-4k-display-resolution-market
In 2025, consumer electronics represent the dominant application segment, accounting for the majority share of the China 4K Display Resolution market. This is followed by retail & advertisement and business & education. The demand for 4K displays in entertainment devices and smart devices is the primary growth driver, while their increasing use in digital signage and educational scenarios further underpins market expansion.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-4k-display-resolution-market
Frequently Asked Questions
Who are the key players in China 4K Display Resolution Market industry?
The top 5 players in the China 4K Display Resolution Market are BOE Technology Group, TCL Corporation, Hisense Group, Samsung Electronics, and LG Display. These companies are recognized for their innovation, large-scale production, and extensive distribution networks, enabling widespread adoption of 4K display technology across China.
What is the China 4K Display Resolution Market growth?
The China 4K Display Resolution Market is experiencing robust growth, with a CAGR of over 12% in recent years. Companies like BOE Technology Group have reported increased production capacity, driven by demand for high-definition displays in smart TVs and monitors across both consumer and commercial applications.
Which segment accounted for the largest China 4K Display Resolution Market share?
The consumer electronics segment, particularly smart TVs, accounted for the largest market share. The rapid adoption of 4K TVs in Chinese households, led by brands like TCL and Hisense, is driving demand as consumers seek immersive entertainment experiences in home environments.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China compound semiconductor market size is projected to grow from USD 4,300 Million in 2020 to approximately USD 18,950 Million by 2035, registering significant CAGR over the forecast period. The revenue trajectory reflects intensifying domestic production, rising applications in electric mobility, 5G, and industrial automation. A steady escalation in demand and technological innovation is expected, with double-digit growth rates observed particularly from 2025 onwards as government and private sector investments bear fruit.
Read More - https://bussinessinsights.com/research-report/china-compound-semiconductor-market
The primary applications of compound semiconductors in China’s 2025 market landscape are consumer electronics, automotive, and telecommunications. Consumer electronics leads due to robust demand for high-speed, compact devices, followed closely by automotive, underpinned by the surge of EVs adopting SiC for power efficiency. Telecommunications maintains a significant share, driven by 5G infrastructure and related device proliferation. This application distribution showcases the versatile and expanding nature of compound semiconductor technologies across both traditional and emerging industries.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-compound-semiconductor-market
Frequently Asked Questions
Who are the key players in China Compound Semiconductor Market industry?
Key players in the China Compound Semiconductor Market include Sanan Optoelectronics, China Resources Microelectronics, Silan Microelectronics, HGTECH, and JCET Group. These companies are recognized for advanced manufacturing capabilities, strong R&D investments, and extensive distribution networks, positioning them as industry leaders in compound semiconductor solutions for multiple applications.
What is the China Compound Semiconductor Market growth?
The China Compound Semiconductor Market is experiencing significant growth, driven by increased demand for power electronics and 5G infrastructure. For example, Sanan Optoelectronics reported strong year-on-year revenue growth for GaN (gallium nitride) and SiC (silicon carbide) products in 2023, reflecting the market's robust expansion.
Which segment accounted for the largest China Compound Semiconductor Market share?
The automotive and consumer electronics segment accounted for the largest market share. The increasing adoption of compound semiconductors in electric vehicles, advanced driver assistance systems (ADAS), and high-speed mobile devices has been a key driver, with companies like Silan Microelectronics providing power devices for major automotive manufacturers.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China Image Sensors market revenue demonstrates an upward trajectory from 2020 through 2035, reflecting a compound annual growth rate (CAGR) of nearly 10.5% over the forecast period. Starting from approximately USD 5,400 Million in 2020, the market is expected to reach around USD 15,800 Million by 2035. Growth is led by the expanding deployment of imaging solutions in consumer electronics, automotive, healthcare imaging, and industrial automation sectors, with leaps in technology fostering new use cases and market entrants.
Read More - https://bussinessinsights.com/research-report/china-image-sensors-market
Consumer electronics stand out as the largest application area for image sensors in China in 2025, powered by massive smartphone and smart device production. Automotive follows on continued integration of cameras for ADAS and driver monitoring. Security & surveillance is also a dynamic growth sector, as investments in public safety and smart cities continue unabated. Healthcare, industrial, and aerospace applications collectively form a significant portion, driven by digitization initiatives and advancements in machine vision.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-image-sensors-market
Frequently Asked Questions
Who are the key players in China Image Sensors Market industry?
The top 5 players in China Image Sensors Market are Sony Corporation, Samsung Electronics, OmniVision Technologies, ON Semiconductor, and Panasonic Corporation. These companies lead the market through continuous innovation, extensive R&D, and strategic partnerships, supplying image sensors to smartphones, automotive, and industrial sectors in China.
What is the China Image Sensors Market growth?
The China Image Sensors Market is witnessing robust growth, with recent estimates indicating a CAGR of over 8% from 2023 to 2028. Companies like OmniVision are expanding production capacities and introducing advanced CMOS image sensors, driving market expansion especially in automotive and surveillance applications.
Which segment accounted for the largest China Image Sensors Market share?
The consumer electronics segment, particularly smartphones, accounted for the largest share in the China Image Sensors Market. High demand for high-resolution cameras in smartphones and tablets, driven by brands like Huawei and Xiaomi, fuels significant adoption of advanced image sensors.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China smart camera market is projected to experience strong revenue growth, expanding from 3,300 Million USD in 2020 to 11,900 Million USD by 2035. The period between 2025 and 2030 is expected to witness particularly rapid growth, fueled by AI, IoT, and government-led infrastructure upgrades. The average CAGR for this period stands at around 9.4%. As smart cameras find increased deployment across industrial, urban, and consumer segments, revenue streams diversify, further enhancing market expansion. By 2035, China will lead globally in the production and adoption of networked, AI-enabled camera solutions.
Read More - https://bussinessinsights.com/research-report/china-smart-camera-market
Surveillance continues as the predominant application for smart cameras in China, capturing 48% of the 2025 market share, a testament to government and enterprise investments in public safety and intelligent monitoring. Industrial automation occupies the second-largest share at 21%, as manufacturers automate quality control, defect inspection, and process monitoring. Traffic monitoring contributes 12%, benefiting from smart city traffic management initiatives using AI-powered cameras. Consumer electronics and healthcare together make up 13% as cameras integrate into daily-use devices and medical infrastructure. The diverse application base highlights the versatility of smart camera technologies and growing reliance on analytics-driven solutions beyond traditional security.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-smart-camera-market
Frequently Asked Questions
Who are the key players in China Smart Camera Market industry?
The top five key players in the China Smart Camera Market are Hikvision, Dahua Technology, Xiaomi, Huawei, and Uniview. Hikvision and Dahua lead in security and surveillance, Xiaomi integrates smart cameras with broader IoT solutions, Huawei leverages AI-based technologies, while Uniview excels in network video surveillance innovations.
What is the China Smart Camera Market growth?
The China Smart Camera Market has experienced rapid growth, with a CAGR exceeding 15% in recent years. Companies like Hikvision have reported significant revenue jumps due to increased adoption of smart surveillance driven by urbanization and smart city initiatives.
Which segment accounted for the largest China Smart Camera Market share?
The security and surveillance application segment holds the largest market share in the China Smart Camera Market. Driven by public safety regulations and increased demand for smart monitoring in both commercial and residential sectors, the segment dominates market adoption, especially by enterprises and government agencies.
Thanks & Regards,
priya
sales@bussinessinsights.com
PW Consulting: Compressor Type Car Refrigerator Market Hits $212.5M in 2025, 14.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Cold Chain Revolution: Strategic Intelligence for the 2026 Compressor Type Car Refrigerator Market
The global transportation and mobile cooling landscape is undergoing a structural shift, driven by evolving consumer lifestyles, stringent environmental regulations, and rapid electrification across automotive and recreational sectors. For executives, investors, and product strategists, the compressor type car refrigerator market represents a high-growth intersection of thermal engineering and mobile mobility. This article previews the strategic horizons outlined in our latest comprehensive market research, designed to equip decision-makers with the foresight required to navigate the forecast period through 2032.
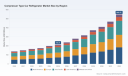
Drawing on a rigorous historical analysis spanning 2020 to 2025 and projecting forward to 2032, our research captures the velocity of this transformation. The market has demonstrated consistent resilience and expansion, with total revenues climbing from 138.75 million USD in 2020 to an estimated 212.5 million USD in the base year of 2025. This trajectory underscores a sustained adoption curve that is far from plateauing. As we look ahead, the forecast model indicates a robust compound annual growth rate of 14.5 percent, signaling that the industry is poised to scale significantly beyond its current baseline. By the close of the forecast window, the aggregate revenue landscape is expected to undergo a profound expansion, presenting both unprecedented opportunities and complex operational challenges for market participants.
However, macro-level growth figures alone do not constitute a winning strategy. The true value of this study lies in its granular dissection of the forces shaping competitive positioning, supply chain dynamics, and regional demand drivers. This preview offers a strategic teaser of the methodology and insights contained within the full report, emphasizing why accessing the complete intelligence framework is critical for 2026 decision-making.
Decoding the Growth Architecture: Beyond Aggregate Projections
Sustained market expansion is rarely uniform. It is the product of intersecting technological advancements, shifting application preferences, and geographically uneven regulatory adoption. The compressor type car refrigerator segment is no exception. Over the past half-decade, the industry has moved from niche automotive accessories to essential components in recreational vehicle ecosystems, commercial transport cooling, and high-performance outdoor mobility. This functional diversification has been accelerated by innovations in compressor miniaturization, improved energy efficiency, and the integration of advanced refrigerants that comply with tightening emissions standards.
Our analysis maps how these technological and application shifts are redistributing market share and value creation across different product architectures. While the broad category continues to grow, the allocation of demand across portable and built-in configurations reveals distinct usage patterns and consumer priorities. Portable units are capturing significant attention due to their flexibility and alignment with the growing mobility and outdoor recreation economy. Simultaneously, built-in solutions are seeing sustained integration in premium vehicle platforms and fixed RV installations, where reliability, space optimization, and continuous cooling performance command higher value propositions.
Similarly, application-level demand is being reconfigured by lifestyle evolution and commercial logistics requirements. Recreational vehicle deployments represent a major demand center, reflecting the broader global trend toward leisure travel and home-on-wheels lifestyles. Commercial and passenger vehicle applications form another substantial pillar, driven by fleet operators, transport companies, and passenger comfort mandates. A residual category of specialized use cases further diversifies the demand base, though it remains comparatively smaller in scale. Understanding the relative weight, growth pace, and strategic implications of these application streams is essential for manufacturers prioritizing product roadmaps and go-to-market strategies.
Regulatory Realignment and Supply Chain Pressures: The New Operating Environment
The competitive arena for compressor-based mobile refrigeration is no longer defined solely by performance metrics and price competition. Regulatory frameworks and raw material economics are actively reshaping cost structures, design specifications, and market entry barriers. A defining characteristic of the current cycle is the accelerated transition toward low-global-warming-potential refrigerants, with R1234YF now establishing itself as a standard across major compressor refrigerator models. This shift is not merely a technical specification; it is a direct response to emissions reduction mandates and evolving environmental compliance requirements that are reshaping product development timelines and component sourcing strategies.
Parallel regulatory pressures are emerging from energy efficiency mandates. Authorities in key markets, including the European Union and China, have instituted standards requiring substantially lower power consumption for new generations of compressor refrigerators. These directives force manufacturers to rethink thermal management architectures, optimize compressor cycles, and invest in next-generation control systems. For companies still relying on legacy designs, the compliance gap represents a material risk. For innovators, it offers a differentiation pathway that aligns sustainability with performance.
On the supply side, raw material volatility has introduced new cost management imperatives. Copper price fluctuations, exacerbated by import tariff dynamics in the United States, have directly impacted bill of materials costs for compressor windings and refrigeration tubing. These input cost pressures ripple through manufacturing margins and require strategic hedging, supplier diversification, and engineering efficiency improvements. Companies that treat supply chain resilience as a secondary concern will find themselves vulnerable to margin compression, while those that embed procurement agility into their product planning will protect profitability in an increasingly unpredictable materials environment.
Competitive Landscape and Strategic Positioning Dynamics
The market exhibits a moderately concentrated competitive structure, with a handful of established players commanding significant share and a broader field of regional and niche manufacturers competing on specialization, cost efficiency, and application-specific innovation. Concentration levels indicate that scale, brand recognition, and technological leadership remain powerful advantages, but they do not preclude agile entrants from capturing value in targeted segments. The presence of both globally recognized brands and regionally focused producers creates a multidimensional competitive matrix where differentiation is increasingly tied to refrigerant compatibility, energy performance, durability, and ecosystem integration.
Industry leaders are actively reinforcing their positions through product launches and catalog expansions that reflect the regulatory and performance trends shaping the market. Recent developments highlight how companies are aligning their innovation pipelines with the dual imperatives of compliance and efficiency. For example, the release of expanded compressor refrigerator catalogs featuring models with enhanced energy efficiency and next-generation refrigerant compatibility demonstrates how incumbents are leveraging portfolio breadth to address varying capacity requirements and vehicle integration needs. At the same time, the introduction of compact, high-performance portable units built around advanced micro compressors illustrates how manufacturers are targeting the demand for lightweight, versatile cooling solutions without sacrificing cooling power.
Regional and application-specific players are pursuing complementary strategies. Some focus on specialized DC compressor systems designed for trucks, recreational vehicles, and camping deployments, often with strong OEM partnership capabilities. Others concentrate on commercial vehicle and coach applications, where continuous operation, ruggedness, and fleet-level reliability are paramount. A further subset of manufacturers emphasizes off-road and outdoor use cases, integrating durable construction and lithium-compatible power options to serve demanding mobile environments. This fragmentation of strategic focus means that competitive advantage is rarely about being the largest player in every dimension; instead, it is about aligning product capabilities with the most attractive demand pockets while maintaining compliance readiness and supply chain flexibility.
What the Full Study Delivers: An Executive Toolkit for 2026 and Beyond
While the trends outlined above establish the strategic context, they only scratch the surface of the actionable intelligence required to make informed capital allocation, product development, and market entry decisions. The complete market research provides a multi-layered analytical architecture designed to convert high-level trends into executable strategy. At its core, the study delivers a detailed segmentation analysis that quantifies demand distribution across regions, product types, and application categories, enabling stakeholders to identify the highest-value opportunities and assess relative market saturation.
The report also constructs a comprehensive competitive profiling framework that goes beyond corporate descriptions to evaluate positioning, product portfolio strategy, recent development trajectories, and likely response patterns to regulatory and cost pressures. By mapping how leading companies are adapting their offerings and where gaps remain, the study helps manufacturers and investors anticipate competitor moves and identify whitespace for differentiation.
In addition to market sizing and competitive analysis, the research integrates a deep examination of market dynamics, including regulatory timelines, refrigerant transition pathways, energy efficiency mandates, and raw material cost drivers. These dynamics are analyzed not as isolated events but as interconnected forces that influence design cycles, sourcing strategies, pricing power, and regional competitiveness. The study further incorporates historical trend analysis to validate growth assumptions and provide a robust basis for forecasting, ensuring that projections are grounded in demonstrated market behavior rather than speculative extrapolation.
Operational and strategic utility is enhanced through coverage of demand drivers, constraints, and emerging use cases. The report explores how lifestyle shifts, vehicle electrification, fleet modernization, and outdoor recreation growth are reshaping end-user expectations. It also addresses barriers to adoption, including cost sensitivity, technical integration complexity, and compliance-related redesign requirements, offering a balanced view of where growth is most sustainable and where caution is warranted.
Compressor Type Car Refrigerator Market
Why This Intelligence Matters Now: Strategic Imperatives for 2026 Decision-Makers
The forecast window ahead will reward organizations that act on precise, forward-looking intelligence rather than reactive assumptions. With a projected growth trajectory that points toward substantial market expansion by the early 2030s, companies must decide where to invest, how to configure product portfolios, and which compliance and cost strategies will preserve margins. The temperature of competition is rising, and the window for establishing a differentiated position is narrowing as regulatory standards tighten and supplier cost structures evolve.
Access to the full report enables leadership teams to move from awareness to action. It supports scenario planning around refrigerant adoption, energy efficiency compliance, and raw material cost fluctuations. It informs portfolio prioritization by clarifying which product architectures and application segments offer the most compelling growth-to-risk ratios. It also strengthens competitive preparedness by revealing how incumbents and challengers are shaping their strategies in response to the same macro forces.
For investors and strategic partners, the study provides the evidentiary foundation needed to assess market attractiveness, competitive durability, and the scalability of participating firms. For manufacturers, it offers a roadmap for aligning engineering investments, supplier negotiations, and regional rollout plans with the most credible demand outlook available. In an environment where regulatory, technological, and economic variables are shifting simultaneously, such integrated insight is not optional; it is a strategic necessity.
Worldwide Miniature Refrigeration Compressor Market
Conclusion: Act on Intelligence, Not Assumption
The compressor type car refrigerator market is entering a phase of accelerated transformation, shaped by regulatory mandates, efficiency demands, material cost pressures, and expanding application diversity. The broad growth trajectory is clear, but the strategic winners will be those who understand the underlying structure of that growth and position themselves accordingly. This market research has been designed to deliver exactly that level of clarity, combining historical validation, forward-looking forecasting, competitive mapping, and dynamic risk analysis into a single decision-ready framework.
To fully leverage these insights for 2026 planning and beyond, stakeholders are encouraged to access the complete report, where detailed segment quantification, competitive profiles, regulatory impact assessments, and actionable strategic recommendations are presented in full. The macro currents are strong, but the precise navigation required to capitalize on them demands the depth and granularity that only the full study provides.
For detailed analysis of this topic, please visit the official page: Compressor Type Car Refrigerator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Power System Market Reaches $18.5M in 2025, Projected 6.1% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Resilience: Navigating the Emergency Power System Market Through 2032
In an era where operational continuity is non-negotiable, the Emergency Power System Market stands as a critical infrastructure pillar for industries ranging from telecommunications to defense. As organizations face increasing volatility in grid stability and rising demands for uninterrupted power, the strategic allocation of capital toward emergency power solutions has shifted from a contingency plan to a core component of long-term business resilience. This article outlines the strategic landscape of the market, drawing on comprehensive research that tracks performance from 2020 through the forecast horizon of 2032.
For decision-makers operating in 2026, understanding the trajectory of this market is not merely about observing growth figures; it is about anticipating supply chain shifts, regulatory pressures, and the competitive maneuvers of key incumbents. The data indicates a steady upward trajectory, reflecting a global consensus on the necessity of robust backup power. Our latest market research provides the granular intelligence required to navigate this complex environment, offering a roadmap for stakeholders who must balance immediate procurement needs with long-term strategic positioning.
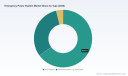
Emergency Power System Market
Market Trajectory: A Decade of Expansion
The market has demonstrated consistent resilience and growth over the past half-decade. Valued at approximately 13.76 billion USD in 2020, the sector has expanded steadily, reaching an estimated 18.5 billion USD by 2025. This historical performance underscores a compound annual growth rate that signals sustained investor and industrial confidence. Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with revenue expected to climb toward 28.0 billion USD by the end of the forecast window.
This growth is not linear but is driven by specific macroeconomic and technological catalysts. The transition toward a 6.1 percent CAGR over the forecast period suggests that while the market is maturing, it remains far from saturation. Key drivers include the exponential increase in data center construction, stricter regulatory compliance regarding safety and continuity in industrial sectors, and the ongoing modernization of aging infrastructure in developed regions. For enterprise leaders, this trajectory implies that delaying investment in emergency power capabilities may result in higher costs and supply chain constraints later in the decade.
Segmentation Dynamics and Strategic Priorities
Understanding where value is generated within the Emergency Power System Market is crucial for targeted investment. The market is broadly categorized by type, application, and region, each presenting unique opportunities and challenges.
Technology and Application Drivers
In terms of technology, UPS Systems continue to dominate the landscape, reflecting the critical need for immediate, clean power protection for sensitive electronic infrastructure. Generator Systems remain a vital component, particularly for long-duration backup needs in industrial and commercial settings. The interplay between these technologies is evolving, with hybrid solutions gaining traction as organizations seek to optimize efficiency and reliability.
Application-wise, the Industrial sector represents the largest share of demand, driven by manufacturing plants that cannot afford production halts. Closely following is the demand from Data Centre and Telecommunication sectors, which is accelerating due to the digital transformation initiatives and the proliferation of cloud computing. Government and Defense applications also constitute a significant portion, where reliability is paramount and often dictated by stringent procurement standards. Commercial Construction Building projects are increasingly integrating emergency power systems at the design phase, influenced by green building codes and risk management protocols.
Regional dynamics further complicate the landscape. While established markets in North America and Europe maintain substantial share due to mature infrastructure and high replacement cycles, the Asia Pacific region is witnessing rapid adoption rates fueled by industrialization and urbanization. Emerging regions in Latin America and the Mideast and Africa are also beginning to prioritize emergency power infrastructure, albeit at a different pace, creating new avenues for expansion for companies with global reach.
Competitive Landscape and Recent Industry Movements
The market is characterized by a moderately concentrated competitive environment. The top three players hold a combined market share of approximately 25.4 percent, while the top five account for roughly 32.6 percent. This structure suggests that while dominance is held by major incumbents, there is sufficient space for specialized players and regional leaders to thrive.
Key Incumbents and Strategic Posturing
Several global corporations define the competitive edge in this sector. Eaton Corporation plc remains a central figure, offering leading backup power UPS and critical power solutions for data centers and enterprise applications. Their recent activity underscores a commitment to expanding capacity; in April 2026, Eaton broke ground on a new 50 million USD manufacturing facility in Henrico County dedicated to producing critical power management equipment. This move signals a long-term bet on infrastructure growth and supply chain localization.
Cummins Inc. continues to strengthen its position as a provider of robust power generation solutions. With a strong North American and international reach, Cummins reported record performance in its Power Systems segment in May 2026, citing increased demand for data center backup power and power generation solutions. Their Power Systems segment sales reached 2.0 billion USD, reflecting a 19 percent year-over-year increase, highlighting the surging demand for industrial-grade backup capabilities.
Generac Power Systems is another pivotal player, known for leading in home standby and commercial standby generators. In April 2026, Generac purchased a new facility in Sussex, WI to expand manufacturing of commercial and industrial backup power solutions, specifically targeting data centers and large-scale applications. This capacity expansion aligns with the broader market trend of scaling up to meet larger infrastructure requirements.
Other notable entities include Schneider Electric SE, which offers Smart-UPS and APC battery backup systems for IT and critical infrastructure protection, and Vertiv Holdings Co., which manufactures Liebert UPS systems and integrated critical power solutions for data centers. Kohler Co. specializes in durable commercial and industrial standby generators, while Atlas Copco provides efficient modular generators for data center and industrial emergency standby power. CyberPower Systems designs professional-grade UPS systems for IT professionals, and Myers Emergency Power Systems, LLC focuses on advanced backup power solutions including battery energy storage systems. Additionally, legacy brands like Powerware, now integrated into Eaton's portfolio, continue to influence the network and data center UPS solutions space. Firman Power Equipment also maintains a presence with portable generators for home and commercial emergency power needs.
Industry Dynamics and Operational Considerations
Navigating this market requires an understanding of the underlying dynamics that influence pricing, availability, and technology adoption. Regulatory frameworks play a significant role; for instance, as of December 2025, Eaton maintained the broadest range of ATS available in the critical power market for emergency power systems, setting a benchmark for compliance and interoperability that competitors must match.
Infrastructure development is another critical factor. The aforementioned manufacturing expansions by key players indicate a response to supply chain pressures and a desire to reduce lead times. However, labor costs and raw material availability remain variables that can impact production timelines and final pricing structures. The dependency on specific raw materials for generator and UPS production means that fluctuations in commodity markets can ripple through to the end user.
Furthermore, customer concentration is a notable aspect of the supply chain. As of December 2025, a significant portion of sales in the electrical segments was made to a concentrated group of large customers. This dynamic suggests that strategic partnerships and long-term contracts with major industrial or utility clients are essential for vendors seeking stability and volume growth.
Strategic Value for 2026 Decision-Makers
Why does this level of detail matter for your 2026 strategy? In a market projected to grow steadily but with complex segmentation and competitive maneuvering, generic market intelligence is insufficient. Decision-makers need to know not just the size of the market, but the velocity of specific segments, the capacity constraints of suppliers, and the strategic intent of competitors.
Our comprehensive research report goes beyond these high-level overviews. It provides detailed breakdowns of revenue streams by specific regions and application verticals, allowing you to benchmark your own performance against market averages. It analyzes the supply chain vulnerabilities that could impact procurement in the next 12 to 24 months. It also offers a deep dive into the financial health and strategic roadmaps of the key companies mentioned, helping you anticipate M&A activity or technology shifts that could alter the competitive landscape.
For investors, the report highlights the valuation implications of the 6.1 percent CAGR and the concentration risks associated with the top five players. For procurement managers, it identifies potential bottlenecks in UPS versus Generator supply chains. For strategists, it maps the expansion trajectories of players like Eaton and Cummins to predict where new capacity—and therefore potential market entry points—will emerge.
Worldwide Backup Power Market
Conclusion: Securing Power, Securing Future
The Emergency Power System Market is poised for significant growth through 2032, driven by the indispensable need for continuity in a digital and industrialized world. The data from 2020 to 2025 establishes a strong foundation, while the forecast period suggests that the demand curve will steepen rather than flatten. Companies that proactively align their strategies with these trends—whether through capacity investment, technology adoption, or strategic partnerships—will be better positioned to manage risk and capture value.
However, the nuances of regional performance, specific application growth rates, and the detailed financial metrics of competitors are critical pieces of the puzzle that require further examination. To access the full depth of this analysis, including the specific segmentation splits, detailed competitor profiles, and actionable recommendations tailored to your organization's needs, we invite you to explore the complete market research report. In a landscape where power equates to continuity, having the right intelligence is the first step toward ensuring resilience.
For detailed analysis of this topic, please visit the official page: Emergency Power System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Face Recognition Market Hits $3.65B in 2025, Projects 14.5% CAGR to $9.36B by 2032
By PW Consulting, 2026-09-16
Navigating the Face Recognition Systems Market: Strategic Intelligence for Enterprise Decision-Makers in 2026
Executive Perspective
The face recognition systems market has transitioned from an emerging technology category into a foundational infrastructure layer for enterprise security, identity verification, and operational efficiency. As organizations across sectors reassess their technology portfolios in the wake of shifting regulatory frameworks and accelerated AI maturity, the need for precise, forward-looking market intelligence has never been more critical. This industry insight introduces our latest comprehensive study on the Face Recognition Systems Market, a research product designed specifically for executives who must align technology investment with strategic growth trajectories through 2032.
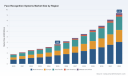
The macroeconomic trajectory underscores the magnitude of this opportunity. From a base valuation of $3.65 billion in 2025, the market is projected to exceed $9.36 billion by 2032, expanding at a compound annual growth rate of 14.5 percent. These figures represent more than raw revenue projections; they signal a structural shift in how enterprises deploy biometric identification, allocate capital toward hardware-software integration, and navigate an increasingly complex competitive landscape. The research accompanying this overview translates these high-level trends into actionable intelligence, enabling leadership teams to separate signal from noise and make informed commitments in a crowded technology ecosystem.
Macro Demand Landscape and Growth Drivers
Market expansion over the past half-decade has been consistently robust. Revenue climbed from $1.8 billion in 2020 through successive annual increases, surpassing the $3 billion threshold by 2024 and reaching $3.65 billion at the 2025 mark. The momentum is expected to maintain its upward trajectory, with forward estimates indicating sustained double-digit growth each year through the end of the forecast window. This growth profile reflects the compounding effect of multiple reinforcing demand drivers rather than reliance on a single deployment vertical.
Enterprise adoption is being accelerated by the convergence of three core catalysts. First, organizations are prioritizing physical access control and identity verification as part of broader zero-trust security architectures. Second, public sector programs continue to expand facial recognition deployments for border management, law enforcement support, and national identity initiatives, creating durable procurement pipelines that stimulate both hardware and software innovation. Third, algorithmic accuracy improvements, supported by standardized evaluation frameworks and computational advances, are lowering the perceived risk profile for enterprise consumers who previously hesitated due to performance or demographic bias concerns.
Hardware and computational requirements add another layer of strategic consideration for procurement teams. High-accuracy identification workflows increasingly depend on GPU or NPU acceleration to sustain performance at scale, while CPU-only configurations are generally constrained to lightweight models with reduced matching fidelity. Understanding where a given deployment falls on this hardware spectrum directly affects total cost of ownership, integration timelines, and long-term scalability. Our research examines these technical interdependencies in detail, providing IT architects and procurement leaders with the context needed to evaluate vendor proposals against realistic infrastructure assumptions.
Regulatory Architecture and Compliance Realities
Any forward-looking market strategy must account for the evolving regulatory environment that shapes procurement approvals, deployment boundaries, and data governance obligations. Regulatory activity across major jurisdictions has intensified, and the cumulative effect is reshaping how vendors position their platforms and how enterprises structure their risk assessments.
In the United States, the Facial Recognition Act of 2025 requires law enforcement agencies using facial recognition technology to undergo annual accuracy and bias testing conducted by NIST, establishing a new baseline for accountability in public sector deployments. State-level mandates add further complexity, such as Virginia law requiring approval for facial recognition technology utilization by local governments, effective July 1, 2026. These domestic requirements create a patchwork that enterprise vendors must navigate carefully, particularly when offering cross-jurisdictional services or multi-agency platforms.
International frameworks introduce additional compliance dimensions. The European Union AI Act classifies real-time facial recognition in public spaces for law enforcement as high-risk, with prohibitions unless authorized for important public security reasons, effectively shaping market participation rules for vendors operating in or serving EU territories. Meanwhile, China's Provisions on Security Management in the Application of Facial Recognition Technology took effect June 1, 2025, establishing data security requirements that influence product design, data handling protocols, and partnership structures within one of the world's largest deployment markets.
Our analysis treats regulatory dynamics not as peripheral background information but as strategic variables that affect pricing power, go-to-market timelines, and competitive differentiation. Companies that integrate compliance readiness into their product roadmaps and contract structures can convert regulatory complexity into barriers to entry, while those that treat it as an afterthought risk stalled deployments and reputational exposure.
Competitive Field and Differentiation Vectors
The competitive environment reflects a mix of specialized biometric technology providers, large industrial technology firms, and AI-native algorithm developers. Market concentration remains pronounced, which has direct implications for procurement leverage, partnership options, and the feasibility of vendor diversification strategies. Understanding the positioning of leading players helps organizations assess where consolidation pressure is strongest and where niche differentiation still creates room for specialized suppliers.
Several firms illustrate the diversity of competitive strategies currently shaping the market. Clearview AI provides facial recognition platforms and commercial access to large-scale image databases for law enforcement, border control, and investigative applications. Its recent track record includes a one-year contract valued at $225,000 with U.S. Customs and Border Protection for facial recognition services in border screening and tactical targeting, alongside a SOC 2 attestation with zero exceptions validating data security and privacy standards. These developments reflect a dual emphasis on operational scale and compliance credibility.
Face Recognition Device Market
NEC Corporation offers NeoFace facial recognition systems and platforms for public safety, law enforcement, and national ID programs. Its technology has been recognized as ranked the world's most accurate in the latest NIST FRTE 1:N identification test using a 12 million person database, an achievement that highlights the competitive importance of benchmark performance in government and high-stakes enterprise procurement. IDEMIA, headquartered in Paris, delivers biometric identification solutions including facial recognition for border control, law enforcement, and government identity programs, while Thales Group provides facial recognition and biometric systems for law enforcement, aviation security, and public safety applications. These two European-based organizations underscore the strategic role of government-adjacent identity infrastructure in sustained demand.
On the industrial and machine vision side, Cognex Corporation manufactures and sells machine vision and 3D vision systems integrated with facial recognition for industrial, security, and access control uses, demonstrating how recognition capability is increasingly embedded within broader automation ecosystems. Panasonic supplies facial recognition hardware and software solutions for surveillance, access control, and border security, reinforcing the hardware-software integration thesis across multiple deployment settings.
AI-native companies are pursuing differentiation through algorithmic precision and responsible deployment framing. Paravision develops and commercializes AI-powered facial recognition algorithms optimized for accuracy and ethical deployment in enterprise and security sectors, a positioning that aligns with growing procurement emphasis on bias performance and governance assurances. On the Asia-Pacific side, SenseTime Group offers facial recognition and AI vision systems deployed in smart cities, law enforcement, and public security applications, while Megvii Technology develops Face++ facial recognition technology and platforms for identity verification, security, and commercial use. Both illustrate how regional deployment ecosystems and large-scale public security programs shape product roadmaps and commercial scale.
Testing Benchmarks and Performance Standards as Market Signals
Independent evaluation frameworks increasingly function as market signals that influence purchasing decisions, vendor comparisons, and product development priorities. NIST activity in 2026 underscores the centrality of standardized testing to market confidence. In January 2026, NIST issued an FRTE 1:1 report with comprehensive accuracy metrics including demographic performance and provisional duration updates for algorithms submitted since September 2025. In May 2026, NIST released an updated FRTE 1:1 Verification report with participation statistics and performance benchmarks across algorithms. These recurring updates give procurement teams and technical evaluators a structured basis for comparing vendor claims against reproducible performance data.
For enterprise strategists, benchmark performance is not merely a technical metric; it is a procurement catalyst that can shorten evaluation cycles, support internal approval processes, and reduce perceived deployment risk. At the same time, performance claims must be evaluated in the context of specific use cases, population demographics, environmental conditions, and matching configurations. Our research dissects how testing outcomes translate into commercial messaging, where benchmark leadership translates into procurement advantage, and where gaps between test conditions and operational realities create opportunities for differentiated positioning.
Applied Deployment Domains and Segment Considerations
Demand is distributed across multiple functional applications, each with distinct performance requirements, procurement rhythms, and integration constraints. Access control remains a dominant use case, driven by organizations seeking to replace or augment physical credentialing systems with biometric verification that reduces credential leakage and streamlines entry workflows. Security and surveillance applications extend recognition capability into broader monitoring and situational awareness contexts, where throughput, false-positive tolerance, and operator support requirements shape system selection. Face identification use cases, including 1:1 verification and 1:N identification workflows, introduce different computational demands and accuracy expectations, and they often intersect with compliance frameworks that vary by jurisdiction and end-user type.
Technology architecture choices further influence competitive positioning and procurement decisions. Decision-makers must evaluate the trade-offs across recognition modalities and understand how each maps to cost, accuracy, and deployment environment. The shift from single-modality deployments to multi-layered recognition strategies is becoming more visible as organizations seek redundancy, improved resilience, and broader coverage across lighting, distance, and pose variation conditions. Segmentation choices also affect hardware procurement, integration complexity, and long-term maintenance commitments, all of which should be factored into enterprise budgeting and vendor evaluation.
What the Research Delivers
This study is structured to provide executive and technical audiences with actionable intelligence rather than abstracted trend summaries. The report combines quantified market sizing, forward forecasts, and segment-level analysis with qualitative assessments of competitive behavior, regulatory exposure, and technology adoption patterns. Readers will find detailed coverage of demand drivers, deployment contexts, hardware and algorithmic considerations, and the strategic implications of benchmark performance and compliance requirements.
The analysis is designed to support multiple decision contexts. Product leaders can use the findings to align roadmaps with demand concentration and performance expectations. Procurement teams can leverage the competitive and segment analysis to sharpen evaluation criteria and negotiation positioning. Investment and strategy functions can draw on the forecast trajectory and market concentration insights to assess growth pathways and consolidation risk. Policy-aware organizations can use the regulatory mapping to anticipate approval friction, data handling obligations, and the operational implications of jurisdiction-specific mandates.
Strategic Imperatives for 2026 and Beyond
The face recognition systems market presents a rare combination of expanding demand, performance-driven competition, and regulatory recalibration. For enterprises planning capital allocation and technology strategy in 2026, the strategic question is not whether facial recognition will continue to gain adoption, but how to engage with the market in a way that balances growth opportunity against compliance exposure, integration complexity, and competitive dependency.
Face Recognition Systems Market
Organizations that approach this market with structured intelligence can make more disciplined choices about vendor selection, deployment sequencing, hardware investment, and compliance readiness. They can also better anticipate where consolidation, benchmark leadership, and regulatory pressure will reshape supplier dynamics over the next several years. The full study expands on these themes with detailed market projections, segment analysis, competitive profiling, and scenario considerations intended to support concrete planning decisions.
This overview has been crafted to provide a credible, professional foundation for understanding the market's direction and the strategic stakes involved. To access the complete dataset, segment-level breakdowns, competitive mapping, and forward forecasts that support enterprise planning through 2032, we invite decision-makers to consult the full market research publication.
For detailed analysis of this topic, please visit the official page: Face Recognition Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Current Sensing Resistor Market to Reach $265.1 Million by 2032, CAGR 5.59%
By PW Consulting, 2026-09-16
Strategic Intelligence Report: The Current Sensing Resistor Market Outlook 2026–2032
As the global electronics industry accelerates toward electrification and smarter power distribution, the role of precision current sensing has evolved from a passive compliance requirement to a critical enabler of system efficiency, safety, and performance. PW Consulting presents this executive briefing on the Current Sensing Resistor Market, drawing on comprehensive historical tracking from 2020 through 2025 and detailed forward-looking projections spanning 2026 to 2032. This analysis is designed to equip strategic leaders, procurement directors, and R&D planning teams with the contextual depth needed to navigate supply chain complexities, technology transitions, and competitive shifts in the coming years.
Market Trajectory and Structural Growth Signals
The historical record from 2020 to 2025 reveals a consistent upward trajectory in global revenue for current sensing resistors, reflecting sustained capital investment in power electronics, automotive electrification, and industrial automation. After reaching a baseline level in 2020, the market steadily expanded through 2022 and 2023, driven by early-cycle adoption in automotive battery management systems and data center power infrastructure. By 2024, demand acceleration entered a more pronounced phase, with 2025 closing the historical window at a significantly elevated revenue mark.
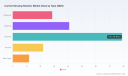
Our forecasting model projects continued expansion through 2032, with a compound annual growth rate of 5.59 percent across the full forecast horizon. The progression from the 2025 baseline into the mid-2020s suggests that incremental capacity additions, alongside the phasing in of next-generation powertrain architectures and industrial motor drives, will sustain revenue momentum. As the timeline extends further toward the early 2030s, the growth curve reflects the compounding effect of platform migrations in electric vehicles, the scaling of renewable energy inverters, and the continuous miniaturization of high-power shunt elements. It is important to note that these are structural, ecosystem-level signals: the detailed breakdown of how this growth distributes across specific regional corridors, product architectures, and end-use verticals remains a core deliverable of the full report.
Technology Transitions and the Shift Toward High-Density Shunt Architectures
A defining theme of the 2026–2032 period is the ongoing migration from conventional thick-film platforms toward higher-performance metal-based and sintered shunt technologies. Industry data points to sintered metal current sense chip resistors achieving power dissipation levels significantly above traditional thick-film equivalents while preserving low temperature coefficient of resistance. This material-level advancement allows designers to increase current-carrying capacity within shrinking board footprints, a constraint that has become central to automotive module packaging and compact industrial power supplies.
At the same time, metal foil and metal strip architectures continue to hold relevance where ultra-low TCR and long-term stability are non-negotiable, particularly in precision instrumentation and high-reliability automotive traction environments. Wirewound and thin-film solutions occupy adjacent niches, each carrying distinct trade-offs in inductance, power handling, and manufacturing economics. The strategic question for component engineers is no longer which technology dominates in absolute terms, but rather which platform aligns with a given application's thermal, electrical, and qualification requirements at acceptable total cost of ownership. The complete study maps these technology trade-offs against actual design requirements and quantifies the relative revenue share each type commands across the broader product landscape.
Competitive Landscape: Differentiation Through Qualification and Platform Strategy
The current sensing resistor market remains moderately fragmented, with top-three concentration levels indicating that while scale players exert meaningful influence, specialized mid-tier manufacturers retain significant footholds through technical differentiation and regional distribution strength. The competitive battleground has shifted decisively from pure price competition toward qualification readiness, power-density innovation, and application-specific portfolio breadth.
Bourns, Inc. has reinforced its automotive and power electronics positioning with the launch of its CSS4C-1216 Series 4-terminal current sense resistors, designed to meet AEC-Q200 expectations with up to 5 watts of power handling, low inductance, and a compact form factor. This family complements the company's Riedon shunt portfolio, which spans metal strip and thick-film elements tailored for EV battery management and industrial power conversion. In parallel, Vishay Intertechnology, Inc. has expanded its Power Metal Strip lineage with the WSLF1206 and WSBE families, delivering 5-watt capability within a 1206 footprint while maintaining low resistance values optimized for high-efficiency EV power systems and board-space-sensitive designs.
ROHM Co., Ltd. has drawn attention with its UCR10C Series sintered metal shunt resistors, which push rated power to 1.25 W within a 2012 metric size and carry AEC-Q100 qualification for automotive motor control and power electronics applications. This product direction underscores a broader industry trend toward sintered metal platforms as credible alternatives to traditional thick-film offerings in thermally constrained environments. TT Electronics has similarly advanced its SMT shunt portfolio with the LRMAK Series, a 4-terminal family qualified to AEC-Q200 standards, offering resistances down to 500 µΩ and up to 2 watts of power for automotive motor control and industrial current sensing.
Beyond these headline developments, the competitive fabric includes Ohmite Manufacturing Co., whose LVK and PCS Series address low-resistance, high-power, and chip current sense applications with precision thick-film and metal implementations. TE Connectivity Ltd. contributes CGS Series metal chip resistors and high-current shunts positioned for automotive and industrial sensing architectures. KOA Speer Electronics, Inc. maintains a focus on precision low-ohm applications through its KDV and PSJ2 Series metal film and power shunt offerings, while Caddock Electronics, Inc. emphasizes accuracy and stability in precision thick-film current sense resistors intended for instrumentation and power monitoring. In the European precision segment, Isabellenhütte Heusler GmbH & Co. KG supplies precision shunt resistors and metal-based current sensors engineered for high-accuracy demands in EV and power electronics environments.
Collectively, these players illustrate a market where product qualifications, package density, and application-specific support are becoming the primary vectors of differentiation. The full report provides a deeper comparative assessment of competitive positioning, recent product cadence, and the strategic implications of these launches for procurement prioritization and second-source planning.
Regulatory, Qualification, and Supply Chain Considerations as Strategic Filters
Automotive-grade qualification has emerged as one of the most consequential filters shaping demand patterns in the current sensing resistor segment. AEC-Q200 compliance is no longer a peripheral bonus; it is increasingly a prerequisite for participation in EV battery management, traction inverter, and frequency converter designs. This qualification dynamic is visible across multiple recent product introductions, from Bourns' CSS4C-1216 family to TT Electronics' LRMAK Series and Vishay's Power Metal Strip platforms, all of which are positioned with explicit automotive reliability expectations.
Environmental and material compliance further shapes the competitive field. Recent sintered metal shunt introductions, including ROHM's UCR10C Series, are fully lead-free and RoHS compliant, with automotive-grade temperature cycle durability integrated into the product claim set. For supply chain and compliance teams, these specifications reduce integration risk in regions with stringent environmental mandates and simplify multi-source qualification where suppliers must demonstrate equivalent regulatory alignment.
On the commercial side, material cost dynamics are beginning to influence device selection decisions. The emergence of sintered metal current sense chips capable of delivering up to 2x higher power dissipation than traditional thick-film equivalents while maintaining low TCR is prompting a reevaluation of thermal derating margins and board-area budgets. As these products mature into volume production, the cost-per-watt-per-cubic-millimeter calculus may tilt in favor of advanced shunt architectures in high-power applications, even if initial unit pricing remains elevated. The complete study dissects these shifting cost-performance trade-offs and their implications for make-versus-buy, design-in prioritization, and inventory strategy.
Current Sensing Resistor Market
Worldwide Precision Resistors Market
Findings and the Strategic Case for Detailed Market Intelligence
A market growing at a mid-single-digit CAGR over a seven-year horizon does not move by accident. It is propelled by interlocking forces: electrification roadmaps in automotive original equipment manufacturing, the scaling of industrial motor drives and renewable inverters, the push for higher power density in consumer and telecommunications power supplies, and the relentless requirement for more accurate current measurement in closed-loop control architectures. Each of these forces exerts a distinct pull on product type selection, qualification requirements, and regional sourcing patterns.
Yet the headline market trajectory only tells part of the story. The strategic decisions that separate resilient portfolios from vulnerable ones depend on operational intelligence: which product types are gaining share in which applications, how regional demand differs in cadence and qualification emphasis, which manufacturers are converting product launches into validated design wins, and how material and qualification constraints will reshape total cost structures. These are precisely the dimensions that our full Current Sensing Resistor Market research unpacks with granular segmentation, revenue allocations, and forward-looking scenario modeling.
For procurement leaders, the value lies in anticipating qualification shifts, identifying credible second sources before supply constraints materialize, and understanding where thermal-performance breakthroughs are likely to displace incumbents. For R&D and application engineering teams, the value lies in mapping technology trade-offs to actual system requirements and avoiding over-investment in architectures that are losing share in key verticals. For executive planning teams, the value lies in aligning capacity, tooling, and supplier relationships to the demand waves that the forecast period will bring.
PW Consulting's full market study transforms these strategic questions into structured answers. It integrates historical performance, projected revenue paths, segmentation detail across resin types, applications, and regional demand centers, and a competitive profile of the manufacturers reshaping the segment. The report is designed to be immediately usable: a reference foundation for design-in strategy, supplier evaluation, pricing negotiations, and long-range capacity planning.
To access the complete segmentation detail, competitive benchmarking, and full forecast tables that underpin this briefing, please visit the PW Consulting market research portal. The full edition extends well beyond these introductory findings, providing the quantitative and qualitative depth required to convert market trajectory into actionable corporate strategy.
For detailed analysis of this topic, please visit the official page: Current Sensing Resistor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com