

Blogs
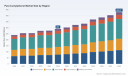
The global multi-joint robot market demonstrates robust revenue growth from 2020 through 2035. Valued at approximately $7,800 million in 2025, the market is projected to reach $22,450 million by 2035, reflecting the accelerating pace of industrial automation and adoption across new sectors. Year-over-year gains are powered by technological advancements, lower implementation costs, and expanding applicability in both developed and developing markets. The forecasted trajectory indicates sustained momentum as manufacturers continue to prioritize automation for efficiency, resilience, and competitiveness.
Read More - https://bussinessinsights.com/research-report/global-multi-joint-robots
Automotive remains the leading application segment for multi-joint robots worldwide in 2025, comprising 28% of the total market due to established automation practices in vehicle manufacturing. Electrical & electronics follows closely, accounting for 25%, driven by surging demand for precise assembly in high-volume production lines. Metals & machinery, plastics & chemicals, and food & beverages round out the top segments, highlighting the broadening utilization of robotics technology beyond traditional manufacturing. The diversification of robot use cases into new verticals speaks to the ongoing optimization and versatility offered by multi-joint platforms, with future growth expected in food, healthcare, and logistics.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-multi-joint-robots
Frequently Asked Questions
Who are the key players in Global Multi-joint Robots industry?
The top five players in the Global Multi-joint Robots industry include FANUC, ABB, YASKAWA, KUKA, and Kawasaki. These companies are pioneering in robotics technology and offer advanced multi-joint robots for a variety of industrial applications, maintaining robust global presence, innovation leadership, and comprehensive service networks.
What is the Global Multi-joint Robots growth?
The Global Multi-joint Robots market has witnessed steady growth, driven by rising automation adoption, especially in automotive and electronics sectors. In 2023, FANUC reported double-digit sales growth due to increased demand for flexible automation solutions, highlighting robust market expansion.
Which segment accounted for the largest Global Multi-joint Robots share?
The automotive segment accounted for the largest share in the Global Multi-joint Robots market, fueled by high demand for precision assembly, welding, and painting. Automakers worldwide rely on multi-joint robots for efficient production lines, with top manufacturers continually expanding their automotive robotics portfolios.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Automatic Pool Cleaning Equipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The market has shown a robust upward trajectory, with global revenue rising from $1,500 million in 2020 to an estimated $2,350 million in 2025. The sustained growth is attributed to evolving consumer preferences, increasing pool construction, and greater penetration of smart and energy-efficient equipment. With continuous innovation and geographical expansion, the market is expected to surpass $4,550 million by 2035, demonstrating a strong CAGR and underscoring its resilience and capacity for innovation.
Read More - https://bussinessinsights.com/research-report/global-automatic-pool-cleaning-equipment
Residential segment dominates the market in 2025, capturing the largest share, driven by increasing adoption among homeowners seeking automated cleaning solutions for their pools. Commercial applications, including hotels and sports complexes, are also significant contributors, spurred by the need for efficient, hygienic, and cost-effective pool maintenance. Public and specialty facilities constitute a smaller yet notable portion, reflecting institutional modernization and health regulations enforcement.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-automatic-pool-cleaning-equipment
Frequently Asked Questions
Who are the key players in Global Automatic Pool Cleaning Equipment industry?
The top five players in the global automatic pool cleaning equipment industry are Maytronics, Zodiac Pool Systems, Pentair, Hayward Industries, and Waterco. These companies lead the market with advanced robotic technologies, extensive product portfolios, reliable after-sales support, and strong international presence to meet the growing demand for automated pool maintenance.
What is the Global Automatic Pool Cleaning Equipment growth?
The global automatic pool cleaning equipment market has seen robust growth, with a CAGR of around 7% from 2021 to 2024. Factors like increasing adoption of smart and energy-efficient pool cleaners, spearheaded by companies such as Maytronics and Hayward, have driven recent industry expansion.
Which segment accounted for the largest Global Automatic Pool Cleaning Equipment share?
The residential application segment accounted for the largest share in the global automatic pool cleaning equipment market. Growing urbanization and increased spending on home leisure amenities have fueled demand. Manufacturers like Zodiac Pool Systems target residential users with innovative robotic pool cleaners, boosting this segment's dominance.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Visual Effects Services Market to Reach $344.8M by 2032, Growing at 7.12% CAGR from 2026-2032
By PW Consulting, 2026-09-16
The Visual Effects Services Market in 2026: Strategic Intelligence for Enterprise Decision-Making
Navigating a Transformative Era in Visual Storytelling
The global Visual Effects Services Market has entered a defining phase where artistic ambition, technological acceleration, and financial engineering converge. As production pipelines evolve and audience expectations shift toward immersive, photorealistic storytelling, enterprises across film, television, gaming, and advertising must look beyond creative intuition and ground their strategies in rigorous market intelligence. This new research publication from PW Consulting provides a comprehensive, data-driven examination of the Visual Effects Services Market, offering executives a strategic blueprint for navigating the opportunities and pressures that will shape the industry through the end of the decade.
The market has demonstrated consistent momentum across the historical review period, reflecting sustained demand for high-end visual content and expanding investment in digital production capabilities. Our analysis traces this trajectory from 2020 through the base year of 2025, capturing the structural shifts that have redefined competitive positioning, service delivery models, and revenue generation across the sector. The data underscores a market that has not merely grown but fundamentally restructured itself around new workflows, platform diversification, and the integration of advanced computation into creative processes.
For enterprise leaders, the critical question is no longer whether visual effects will play a central role in content strategy, but how to allocate capital, select partners, and position operations in a landscape characterized by rapid technological change, evolving incentive frameworks, and intensifying competition for specialized talent. This research is designed to answer that question with precision, offering actionable intelligence that supports investment planning, vendor selection, geographic expansion, and long-term portfolio management.
Forecasting Framework: Aligning 2026 Decisions with the 2026–2032 Outlook
The forecast period covered in this report spans from 2026 through 2032, a window that coincides with pivotal developments in production technology, distribution economics, and regulatory incentives. By anchoring strategic planning in a disciplined forward-looking framework, organizations can anticipate demand shifts, assess the ROI of capability investments, and identify the inflection points where competitive advantage will be won or lost.
The report integrates historical demand patterns with forward projections to deliver a coherent view of market evolution. This approach enables decision-makers to stress-test assumptions against multiple scenarios, evaluate the timing of capacity expansions, and understand how macro-level growth translates into sector-specific opportunities. Rather than presenting growth as a monolithic trend, the analysis disentangles the underlying drivers—content volume, platform fragmentation, technological adoption, and regional production migration—to reveal where value is being created and how it is likely to redistribute over time.
Strategic alignment with this forecast horizon is essential for organizations that must commit resources today to capabilities that will mature over the next several years. Whether the objective is to internalize certain production functions, form strategic alliances with specialized vendors, or reallocate budget toward higher-value service tiers, the report provides the contextual foundation needed to make those choices with confidence. The emphasis throughout is on decision relevance: every dataset, every segmentation lens, and every competitive observation is framed to support operational and financial planning in the current fiscal cycle and beyond.
Report Architecture: Operational Depth Across Segments, Competition, and Dynamics
To support rigorous strategic analysis, this research is structured around a set of operational modules that together provide a complete picture of the market environment. The segmentation framework examines the market through multiple dimensions, allowing readers to isolate the demand characteristics, service configurations, and growth profiles that are most relevant to their specific business context. By analyzing the market across type-based and application-based lenses, the report illuminates how different service categories and end-use channels contribute to overall demand patterns and where structural advantages are emerging.
The regional dimension of the analysis adds further granularity, mapping how production activity, vendor ecosystems, and incentive environments vary across major geographic corridors. This regional perspective is particularly valuable for organizations evaluating location strategy, outsourcing partners, or international expansion, as it surfaces the interplay between local production capacity, talent availability, and policy support. Importantly, the report maintains a disciplined focus on strategic interpretation rather than exhaustive enumeration, ensuring that the data serves decision-making rather than overwhelming it.
Complementing the segmentation analysis is a detailed competitive landscape assessment that profiles the leading operators shaping the market. The research examines the positioning, capability strengths, and strategic moves of prominent firms, including Industrial Light & Magic, Weta Digital, Framestore, DNEG, Pixomondo, Animal Logic, Rodeo FX, Cinesite, Method Studios, Deluxe, Digital Domain, The Mill, and Scanline VFX. These profiles are not static company summaries; they are structured to reveal how each organization competes on technology, service breadth, artistic reputation, and operational scale, and how recent consolidation, investment, and partnership activity is reshaping the hierarchy.
The report also incorporates a dedicated dynamics module that captures the forces currently redefining market behavior. This includes an examination of labor cost structures and talent availability, with attention to median compensation levels and employment growth trajectories for visual effects artists and animators in the context of sustained demand across gaming, film, and television. The regulatory landscape receives equal attention, with analysis of incentive programs and policy initiatives that are actively influencing production location decisions and cost structures. Recent developments illustrate how these forces are unfolding in real time, including significant investment activity, acquisitions that consolidate animation and VFX operations, award-recognized creative campaigns, and organizational rebranding efforts that reflect evolving workflow integration.
By integrating these content streams, the report functions as both a reference document and a planning tool. Readers will find a clear path from high-level market context to granular operational insight, enabling them to draw connections between market structure, competitor behavior, and their own strategic priorities.
Competitive Intensity and Strategic Positioning in a Consolidating Landscape
The competitive environment in the Visual Effects Services Market is characterized by a combination of creative differentiation, technological capability, and ongoing consolidation. With a moderately concentrated market structure, the leading firms compete not only on artistic quality but also on their ability to deliver end-to-end solutions that span visual effects, animation, virtual production, and post-production support. This breadth of capability has become increasingly important as producers seek to streamline workflows, reduce integration risk, and maintain consistency across complex, multi-platform projects.
Several of the most prominent operators have pursued strategic moves that signal how they intend to strengthen their competitive position. Investment activity has provided selected companies with the capital to expand technology pipelines, deepen AI-driven workflows, and scale content production capacity. Acquisitions have been used to consolidate complementary capabilities, particularly where animation and visual effects operations can be integrated to offer more complete service offerings. At the same time, high-profile creative recognition continues to serve as a powerful differentiator, reinforcing brand equity and attracting premium client relationships.
For enterprise buyers and investors, this dynamic landscape raises important questions about vendor stability, service continuity, and the long-term implications of consolidation. The report addresses these concerns by evaluating how recent transactions and investments are likely to affect pricing, capacity, and service specialization. It also examines how firms are positioning themselves around emerging capability areas, including simulation, creature work, motion capture, immersive media, and AI-assisted production. Understanding these strategic vectors is essential for organizations that must select partners capable of supporting both current production needs and future content ambitions.
Regulatory and Cost Dynamics: Incentives, Labor, and Operational Strategy
Market behavior in the Visual Effects Services Market is increasingly shaped by the interaction between labor economics and policy incentives. On the labor side, specialized creative and technical roles command significant compensation, and employment growth in animation and visual effects is projected to remain positive over the coming decade, driven by ongoing demand across entertainment and interactive media. This sustained demand places pressure on talent availability and reinforces the strategic importance of workforce planning, retention, and productivity-enhancing technology adoption.
Worldwide CG Visual Service Market
At the same time, a range of incentive programs is actively reshaping where and how visual effects work is performed. Recent policy developments have expanded or clarified credit structures in key production markets, giving producers new options for optimizing cost structures while maintaining access to high-quality service providers. In some jurisdictions, tax credit frameworks have been updated to increase eligible spend or streamline application and audit processes, reducing administrative friction and making incentive capture more predictable. In others, advocacy efforts are pushing for standalone post-production incentives that would better align support with the specific economics of visual effects work.
Visual Effects Services Market
These dynamics create both opportunities and risks for enterprises. Advantages can be gained by aligning production footprints with favorable incentive environments, but such strategies must be balanced against considerations of talent quality, vendor capability, delivery timelines, and long-term relationship strength. The report provides a structured examination of these trade-offs, helping decision-makers evaluate how regulatory and cost factors should inform location strategy, vendor selection, and budget allocation. Rather than treating incentives as isolated financial benefits, the analysis situates them within the broader operational context in which content is produced and delivered.
Strategic Imperatives for 2026 and Beyond
As enterprises move through 2026, the most successful organizations will be those that treat visual effects not as a discretionary enhancement but as a core component of content strategy and operational planning. That shift requires a clear understanding of where the market is heading, which capabilities will command premium value, and how competitive and regulatory forces will influence cost and access over time. This research is designed to provide that understanding in a form that can be directly applied to investment decisions, partnership strategies, and organizational planning.
Among the strategic imperatives highlighted in the report are the need to evaluate vendor partners against long-term capability roadmaps rather than short-term project requirements, the importance of monitoring consolidation and investment activity for signals about market concentration and service availability, and the value of integrating incentive and labor considerations into location and sourcing decisions from the outset. The report also emphasizes the growing relevance of technology adoption, particularly where advanced workflows can improve efficiency, quality, and scalability without compromising artistic integrity.
For executives seeking to translate market intelligence into action, the full study offers a more detailed evidentiary base, including deeper segmentation analysis, competitive profiling, and scenario-based interpretation of demand drivers. The complete research package is available through the source publication, where readers can access the full range of data, analysis, and strategic recommendations that support enterprise decision-making across the 2026–2032 horizon.
In a market defined by rapid change and high creative stakes, disciplined intelligence is the foundation of confident strategy. This report provides the context, structure, and insight needed to make that strategy durable, responsive, and aligned with the realities of the Visual Effects Services Market as it enters its next phase of growth.
For detailed analysis of this topic, please visit the official page: Visual Effects Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Box Making Machines Market Projected to Hit USD 344.8M by 2032 at 4.5% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence in the Box Making Machines Market: Navigating Growth Through 2032
The global packaging automation landscape is undergoing a decisive transformation. As supply chains demand faster turnaround times, greater customization, and tighter sustainability compliance, manufacturers are shifting from conventional batch production toward on-demand, right-sized box fabrication. Our latest market research delivers a comprehensive, data-backed examination of the Box Making Machines Market, offering executives the strategic clarity required to allocate capital, select equipment partners, and engineer resilient production architectures through 2032.
This report is not an academic exercise. It is an operational intelligence asset designed for procurement leaders, automation engineers, C-suite strategists, and investors seeking to align capital expenditure with measurable efficiency gains. By tracing historical performance, modeling forward trajectories, and dissecting competitive positioning, the study equips decision-makers with the frameworks needed to separate market noise from structural opportunity.
The Market Trajectory: From Historical Baselines to 2032 Forecasts
Understanding the Box Making Machines Market requires a clear view of its momentum. Drawing on historical performance from 2020 through 2025 and extending rigorous projections across the 2026-2032 forecast window, the analysis maps a market that has consistently expanded and is positioned for continued upward movement. The sector has crossed prominent valuation thresholds in recent years, reflecting sustained demand for flexible packaging lines, shorter production runs, and automated right-sizing capabilities.
Projected revenue growth through the end of the forecast period underscores the durability of this expansion. At the core of the modeling is a compound annual growth rate of 4.5 percent, a figure that translates historical resilience into forward visibility. For enterprise planners, this trajectory is not merely a headline statistic; it is a calibration tool. It informs facility expansion timelines, validates automation investments, and helps leadership distinguish between cyclical demand spikes and structural adoption curves.
The reports forecast architecture connects past performance to future scenarios using transparent, multi-factor modeling. Readers gain insight into how macroeconomic indicators, equipment adoption curves, and packaging-line modernization cycles converge to shape the medium-term outlook. Crucially, the analysis isolates the variables that matter for operational planning, allowing teams to build scenario plans around realistic growth envelopes rather than speculative extremes.
What distinguishes this research is its focus on decision-useful granularity beneath the aggregate numbers. Rather than leaving executives with a single growth figure, the study breaks down the market into the operational dimensions that actually drive procurement behavior, equipment selection, and regional deployment strategies. The objective is to convert macro-level momentum into concrete capital allocation logic.
Structural Drivers Reshaping Equipment Demand
The Box Making Machines Market is accelerating because the pain points it solves are becoming more acute across industries. Several interconnected dynamics are reshaping procurement priorities and redefining what operations teams expect from automated box fabrication equipment.
- On-Demand Right-Sizing as a Competitive Imperative : The traditional practice of boxing products into pre-set formats is giving way to precise, order-level box creation. Operations teams are prioritizing machines that can produce custom dimensions without excessive changeover time, reducing void fill, cutting material waste, and improving downstream logistics efficiency.
- Sustainability and Resource Recovery Compliance : Environmental regulation is no longer a peripheral concern. Compliance with resource recovery standards and broader sustainability mandates is actively steering buyers toward energy-efficient machines and corrugated box making systems designed to minimize waste streams. Equipment that supports lean material usage and streamlined production is increasingly viewed as a regulatory risk-mitigation asset, not simply a productivity tool.
- Material Complexity and Processing Requirements : Heavy-duty corrugated cardboard processing, including multi-ply configurations, demands specialized handling, creasing, and cutting technology. As converters and end-users work with thicker, more robust board grades, machine capability in vibration-based cutting, precision creasing, and material feeding becomes a decisive purchase criterion.
- Digital Integration and Workflow Automation : The boundary between box fabrication and broader packaging digitization is dissolving. Buyers are evaluating systems based on their ability to integrate with digital print workflows, automated sheet feeding, and centralized line control. End-to-end efficiency gains now depend on equipment that can operate as a coordinated node within a smart packaging cell.
These forces converge to create a market where equipment selection is increasingly strategic. Procurement is no longer about purchasing a standalone machine; it is about securing a flexible production capability that can adapt to changing order profiles, regulatory expectations, and material specifications. The report examines these dynamics in depth, linking each driver to the measurable purchasing behaviors and operational priorities they generate.
Competitive Architecture: Leading Players and Strategic Positioning
The competitive landscape for box making machines is defined by a blend of specialized automation providers, established packaging equipment manufacturers, and regional innovators tailoring solutions to specific production models. Our research evaluates key participants not simply by brand presence, but by technology orientation, application fit, and deployment footprint.
Several companies stand out for how they position their engineering philosophies around distinct production needs. AOPACK has built a portfolio around fully automatic on-demand corrugated box making machines, with model variations designed to support digital printing integration, vibrating knife cutting and creasing, and male-female creasing for short-run custom production. Their recent activity reflects a continued push into customized corrugated applications and broader market exposure through major exhibition platforms.
T-ROC Equipment LLC has positioned itself around heavy-duty on-demand automated box making systems, including automated box gluers and automatic sheet feeders, designed and manufactured in the United States for custom cardboard boxes. With a significant global installation base, the company demonstrates that durability and on-demand flexibility can be packaged together for operations that require consistent, high-stress throughput.
SCM Group emphasizes right-size box making machines with fanfold cardboard magazines, supporting single, multiple, and multi-layer configurations for just-in-time custom cardboard boxes in furniture and packaging applications. Bobst Group SA takes a different approach, focusing on high-volume flexo folder gluer systems that bring automation, digitalization, and end-to-end efficiency to corrugated and folding carton production. Panotec Srl contributes a modular, form-oriented perspective through automatic box forming machines built for standard model production and precise bottom flap folding, while also advancing flexible line integration.
Worldwide Straight Line Box Gluing Machines Market
Additional players such as Kraft Paper Systems extend the ecosystem with automatic box making and cutting solutions capable of processing endless corrugated material for on-demand output. The overall competitive picture reflects a fragmented, capability-driven market rather than a single dominant paradigm. Concentration metrics indicate a moderate level of consolidation, with top-tier players holding meaningful but not overwhelming share, leaving room for technology differentiation and application-specific specialization.
Recent corporate activity reinforces the speed of this evolution. Over the last year, the sector has seen a sequence of installation milestones, product launches, and exhibition debuts that signal accelerating commercialization. New machine releases have targeted small-lot production, modular line integration, and complex corrugated box handling, while field deployments have validated on-demand approaches in real converter environments. These developments are cataloged and contextualized in the report to help readers understand which product directions are gaining commercial traction and how competitors are translating engineering advances into market presence.
Report Architecture: What the Analysis Delivers
A market study is only as valuable as its usability. This report is structured to move from macro intelligence to operational guidance, ensuring that executives can extract concrete decision inputs rather than abstract trends. The analysis combines market sizing, segmentation evaluation, competitive profiling, technology mapping, and regulatory context into a single integrated reference.
At the structural level, the study presents detailed sizing across the full historical period and forecast window, with modeling that supports both baseline planning and sensitivity testing. Segmentation is explored across the dimensions most relevant to equipment evaluation, including type distinctions, application drivers, and regional deployment patterns. This segmentation is not presented as isolated percentages for casual browsing; it is framed as a strategic map that explains where demand concentration, purchasing priorities, and adoption barriers differ across use cases and geographies.
The report also provides company-level evaluations that go beyond descriptive profiling. Each key participant is assessed for product strategy, application emphasis, and operational relevance, giving readers a clearer sense of which suppliers align with specific production requirements. Technology discussions examine the mechanical and digital features that shape purchase decisions, from cutting and creasing methods to automation architecture and integration flexibility.
Equally important, the analysis embeds industry context where it actually affects buying behavior. Material handling requirements, sustainability mandates, and environmental compliance pressures are examined as market dynamics, not as background commentary. This approach helps leadership understand why certain machine specifications are becoming non-negotiable and how regulatory trajectories may influence total cost of ownership calculations over the forecast period.
To support execution, the report incorporates practical reference elements designed for direct business use. Decision-makers can leverage the study to evaluate equipment roadmaps, benchmark supplier capabilities, identify high-fit application segments, and plan regional deployment logic. The emphasis throughout is on actionable intelligence: reducing the distance between market data and operational decision-making.
Strategic Takeaways for 2026 Decision-Makers
For organizations planning capital investment, production-line modernization, or supplier selection in 2026, the Box Making Machines Market presents both opportunity and complexity. Growth is robust, but the value lies in identifying where that growth is most accessible and most aligned with operational objectives. The research equips leaders to make those judgments with greater precision.
The first strategic priority is aligning equipment capability with real production profiles. Companies that continue to evaluate box making machines solely on throughput may overlook the larger efficiency gains available through on-demand, right-sized production. The second priority is factoring sustainability and regulatory compliance into equipment economics early, rather than treating them as downstream concerns. Machines that support energy efficiency, waste reduction, and compliant material usage can materially improve the long-term viability of a packaging operation.
Box Making Machines Market
The third priority is vendor strategy. With multiple capable participants pursuing different engineering philosophies, procurement teams need a structured basis for comparison. The report supports that process by connecting company profiles to application fit, technology differentiation, and deployment track record. Instead of evaluating suppliers in isolation, decision-makers can assess them against the specific production scenarios they intend to serve.
Finally, the market trajectory suggests that timing matters. As adoption accelerates and equipment portfolios expand, organizations that establish clear automation requirements, integration standards, and material-handling specifications will be better positioned to secure fit-for-purpose solutions and avoid overinvestment in misaligned technology.
Access the Full Strategic Assessment
This overview highlights the scope, methodology, and strategic value of the full market research, but the complete intelligence architecture extends well beyond this introduction. The full report delivers detailed market sizing, extended forecast scenarios, segmentation analysis, competitive evaluation, technology mapping, and the operational context needed to turn data into decision-ready strategy.
For executive teams, procurement units, and investment stakeholders, the complete study provides the depth required to validate assumptions, compare pathways, and build credible medium-term plans. We invite you to access the full Box Making Machines Market research to obtain the comprehensive intelligence necessary for informed, forward-looking decisions through 2032.
For detailed analysis of this topic, please visit the official page: Box Making Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cast Film Market to Reach $14.47B by 2032, 4.5% CAGR Amid Food Packaging Demand
By PW Consulting, 2026-09-16
Strategic Imperatives in the Cast Film Market: Navigating Growth and Complexity Through 2032
The global cast film market stands at a critical juncture where material science, regulatory pressure, and sustainability mandates converge. For strategic planners and category leaders, understanding the trajectory of this sector is no longer optional. It is a prerequisite for resilient supply chain design, product portfolio optimization, and long-term competitive positioning. Our latest comprehensive study on the Cast Film Market translates years of historical performance and forward-looking modeling into an executable intelligence framework. This article outlines the structural forces shaping the industry, highlights the operational content embedded in the full report, and demonstrates how executives can leverage these insights to de-risk decisions across the 2026 to 2032 horizon.
Market Trajectory and the Momentum Behind Sustained Expansion
Over the past five years, the cast film sector has demonstrated consistent upward movement, underpinned by expanding packaging demand, continuous extrusion technology improvements, and the material's inherent versatility across food, pharmaceutical, agricultural, and industrial applications. Historical revenue patterns from 2020 through 2025 reflect a steady climb, with the market surpassing the nine-figure million threshold and closing the base year at a level that signals durable commercial relevance. The forward projection reinforces this trajectory. Our forecast modeling indicates that the global market will continue its measured expansion through 2032, supported by volume growth, product innovation, and the gradual penetration of advanced mono-material structures. The compound annual growth rate anchored at 4.5 percent reflects a market that is neither overheated nor stagnant, but rather evolving at a pace that rewards organizations capable of aligning production capacity, feedstock strategy, and downstream application development with shifting end-user requirements.
For decision-makers, this growth profile carries nuanced implications. A mid-single-digit expansion rate suggests that headline market size alone will not differentiate winners. Instead, margin capture, application-level specialization, and regional execution precision will determine which participants convert industry-wide growth into outsized financial returns. The full research deliverable dissects these dynamics across multiple analytical lenses, allowing clients to isolate high-conviction opportunities without getting lost in aggregate figures that mask structural variation.
Segmentation Architecture and Where Strategic Value Actually Resides
Cast film demand does not move uniformly. The market is inherently multi-dimensional, shaped by resin chemistry, end-use performance specifications, and geographic manufacturing footprints. Understanding how these layers interact is essential for capacity planning, pricing strategy, and customer targeting. The study examines the primary segmentation axes that matter most to commercial and operational leaders, focusing on how resin categories, application verticals, and regional ecosystems each present distinct risk-return profiles.
On the material side, polyethylene-based structures continue to anchor a substantial portion of industry volume, reflecting their balanced mechanical properties, processability, and cost competitiveness across broad packaging formats. Polypropylene variants serve a strategically important but more specialized slice of the market, often favored where flexural strength, thermal stability, or specific barrier characteristics are prioritized. Polyester-based cast films occupy a narrower but high-performance niche, typically linked to demanding graphics, labeling, and specialty conversion environments. Rather than treating these categories as static share buckets, the report evaluates how resin selection is increasingly driven by downstream regulatory compliance, recyclability objectives, and converter-level processing economics.
Application-level analysis reveals equally important divergence. Food packaging remains the dominant demand engine, shaped by freshness preservation, print fidelity, and stringent safety standards. Pharmaceutical packaging introduces a different calculus, where consistency, traceability, and regulatory alignment take precedence over pure cost optimization. Agricultural uses add complexity through exposure conditions, durability requirements, and seasonal demand cycles. Automotive and industrial applications, while smaller in aggregate volume, often function as high-specification adoption pathways that influence broader material innovation. The report maps these application environments to operational implications, helping clients anticipate where technical service, qualification lead times, and supply reliability will matter more than price alone.
Geographic dispersion further complicates the picture. Demand concentration varies by manufacturing maturity, export orientation, packaging infrastructure investment, and regional sustainability policy tempo. Instead of presenting narrow regional breakdowns that can obscure strategic context, the study evaluates how macro-regional demand patterns interact with local compliance frameworks, logistics constraints, and competitive density. This approach allows executives to assess where near-term volume growth is most likely to materialize and where longer-term positioning requires patience, partnership, or localized product adaptation.
What the Full Report Delivers Beyond Top-Line Figures
Aggregated market size and growth rates are only the starting point. The research is built around an operational architecture designed to support real decision-making. Inside the full study, clients gain access to a structured set of analysis modules that connect market behavior to executable strategy. The report incorporates:
- A multi-year historical reconstruction that validates trend assumptions and isolates structural shifts from cyclical noise
- Forward-looking demand modeling through the end of the decade, with scenario-aware forecasts that account for feedstock volatility, regulatory acceleration, and technology adoption pacing
- Application-specific demand logic that explains why certain verticals expand faster, resist downturns more effectively, or respond differently to material substitution
- Resin and processing-technology assessments that clarify the commercial relevance of downgauging, mono-material transition, and high-performance extrusion advances
- Competitive profiling that evaluates participant positioning across material supply, film conversion, equipment provision, and specialty application expertise
- Regulatory and compliance mapping that ties policy developments to substrate selection, recycled content requirements, and converter-level risk exposure
- Strategic implication summaries that translate data patterns into capacity, procurement, partnership, and go-to-market recommendations
This structure is intentionally designed to avoid the common trap of presenting data without decision context. Each section is linked to practical questions facing production leaders, procurement teams, R&D groups, and commercial strategists. The objective is to help organizations move from awareness to action, whether that means adjusting resin procurement timing, prioritizing regional expansion,qualifying new mono-material formats, or repositioning product offerings around recyclability and performance.
Competitive Landscape: Diversification of Capability and the Rise of Ecosystem Play
The cast film environment is not defined by a single business model. Instead, it comprises a blend of film converters, resin suppliers, extrusion-technology providers, and specialty solution developers. This diversity matters because competitive advantage increasingly depends on how well an organization can integrate upstream material capability with downstream application performance and regulatory alignment.
Several established participants illustrate the range of strategic postures now shaping the market. Avery Dennison operates with a strong orientation toward professional-grade cast films serving graphics and labeling applications, where print reliability, conformance, and converter usability are central to product value. Profol Group is recognized for custom cast film manufacturing across polypropylene and polyethylene formats, reflecting a conversion-focused model that emphasizes specification flexibility and customer-specific film design. Windmöller & Hölscher contributes from the equipment and process side, producing high-speed cast film extrusion lines and supporting CPP cast film production, which positions the company as an enabler of capacity and throughput improvements across the value chain. SML extends this technology-driven logic further, specializing in high-performance cast film extrusion technology and MDO-PE cast films, where dimensional performance and process efficiency are closely intertwined.
Material suppliers add another critical layer. TotalEnergies provides polymers that support downgauging initiatives for MDO-PE cast films, linking resin development directly to lightweighting and material efficiency objectives. LyondellBasell develops and supplies resins tailored to cast film grades, reinforcing the importance of feedstock-level innovation in achieving targeted mechanical and processing outcomes. Amcor rounds out the landscape as a manufacturer and supplier of cast films for packaging applications, combining conversion capability with broad commercial reach across end-use sectors.
The strategic lesson is clear: competitiveness is increasingly multidimensional. A company may compete on specification customization, extrusion efficiency, resin innovation, or application-oriented service. The full report maps these postures against market demand patterns, enabling clients to identify where partnerships, vertical alignment, or product portfolio adjustments can create defensible positioning.
Recent Innovation Signals and What They Reveal About Market Direction
Recent product activity confirms that the industry is moving toward thinner structures, improved material efficiency, and digitally enabled application formats. These developments are not isolated launches; they reflect a broader shift in how performance, sustainability, and processing economics are being optimized simultaneously.
TotalEnergies and SML collaborated on the development of two innovative downgauging films, including an unlaminated MDO-PE cast film designed for deep-freeze bags with a 35 to 50 percent thickness reduction. This kind of advancement illustrates how resin and technology alignment can deliver measurable material savings without sacrificing functional performance, a theme that will likely intensify as cost pressure and sustainability expectations rise together.
Avery Dennison reinforced the graphics and labeling trajectory by launching MPI 1903, a professional-grade cast film developed for digitally printable applications. This move highlights the growing importance of print compatibility, workflow integration, and specification reliability in higher-value conversion environments.
Amcor introduced Stratos cast film for ultra-lightweight packaging solutions, underscoring the continued emphasis on material efficiency and packaging optimization. Taken together, these developments suggest that the market's next phase of value creation will come less from raw volume expansion and more from engineered improvements that reduce material input, enhance processing performance, and satisfy evolving application requirements.
Industry Dynamics: Raw Material Pressure, Regulatory Acceleration, and Structural Reorientation
No strategic assessment of the cast film market is complete without addressing the external forces that can reshape margins, product design, and procurement timing. Two interlinked dynamics are particularly consequential in the current environment.
First, raw material volatility has become a defining operational challenge. Polypropylene prices rose 34 percent year-to-date through April 2026, driven by feedstock shortages and crude oil and naphtha volatility. For cast film producers and converters, this level of input fluctuation affects cost structures, pricing negotiations, inventory strategy, and product mix decisions. Organizations that rely on rigid procurement models or single-resin dependence face heightened exposure. The study examines how material price sensitivity interacts with application economics and identifies where feedstock diversification, hedging discipline, and product engineering can mitigate risk.
Cast Film Market
Second, regulatory and sustainability frameworks are actively restructuring demand logic. The EU Green Deal and single-use plastic reduction mandates are driving demand for recyclable mono-material cast films, shifting attention away from multi-layer complexity toward structures that are easier to recover and reprocess. At the same time, Extended Producer Responsibility schemes in Europe are requiring higher recycled content in cast films, placing additional pressure on material sourcing, quality consistency, and compliance documentation. REACH chemical restrictions are also tightening substrate compliance for cast film converters, adding another layer of technical and administrative scrutiny.
These forces are not separate noise; they are converging into a structural reorientation of the market. Recyclability, recycled content, chemical compliance, and material efficiency are increasingly embedded in purchasing criteria and product qualification processes. Companies that treat sustainability as a peripheral initiative risk losing relevance in segments where compliance and circularity are becoming commercial gatekeepers. The report integrates these dynamics into the forecast narrative and competitive analysis, ensuring that strategic recommendations reflect the regulatory reality facing the industry.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle requires more than retrospective review. It demands forward visibility into where demand will intensify, which material transitions will accelerate, how regulatory pressures will alter qualification cycles, and where competitive differentiation will be won or lost. The Cast Film Market study is built to support that moment of decision. It provides a calibrated view of market size evolution, segmentation behavior, technology relevance, and competitive positioning, while intentionally preserving room for scenario-based interpretation rather than fixed predictions.
For executives, the practical value lies in connection. The research links macro trends to segment-level logic, connects innovation signals to commercial outcomes, and translates raw material volatility and regulatory change into operational implications. Whether the objective is to evaluate capacity expansion, optimize resin sourcing, prioritize application development, or refine regional market entry, the study is designed to reduce ambiguity and sharpen resource allocation.
Casters Market
To access the complete segmentation detail, competitive profiles, forecast tables, regulatory mapping, and strategic recommendation sets, readers are encouraged to explore the full report. The aggregate trends outlined here establish the strategic frame; the full research delivers the execution-level intelligence required to act on it with confidence.
For detailed analysis of this topic, please visit the official page: Cast Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AI in Agriculture Market to Hit $13.9B by 2032, Growing at 22.85% CAGR
By PW Consulting, 2026-09-16
Navigating the Harvest of Intelligence: Strategic Imperatives in the AI Agriculture Market (2026–2032)
Executive Preview: The Inflection Point for Agricultural Intelligence
The global agricultural sector is undergoing a structural transformation driven by artificial intelligence, shifting from incremental automation to foundational decision intelligence. As we move through 2026, the Artificial Intelligence (AI) in Agriculture market has crossed a critical adoption threshold. Recent market research indicates that the sector generated approximately $2.6 billion in revenue during the base year of 2025, reflecting a maturation phase where pilot deployments are rapidly transitioning into enterprise-grade agricultural operations. This trajectory is projected to accelerate through the end of the forecast period in 2032, with the market expanding to $13.9 billion. This represents a compound annual growth rate (CAGR) of 22.85%, signaling sustained capital allocation and accelerated commercialization across the agri-tech ecosystem.
Artificial Intelligence (AI) in Agriculture Market
For executive leadership, investors, and strategic planners, these aggregate figures represent more than macroeconomic momentum. They reflect a fundamental reordering of competitive advantage in food production. Organizations that treat AI as an operational utility rather than a discretionary technology investment are capturing disproportionate margins in yield optimization, input efficiency, and supply chain resilience. This market intelligence briefing outlines the strategic architecture of the AI agriculture landscape, equipped to guide resource allocation, partnership strategies, and risk mitigation in the 2026–2032 horizon.
Market Architecture and Growth Trajectory
The historical progression from 2020 to 2025 demonstrates a market that has consistently expanded despite macroeconomic headwinds and transitional supply chain constraints. Revenue climbed from $1.8 billion in 2020 to $2.6 billion by 2025, with minor cyclical fluctuations reflecting regional deployment pacing and platform maturity cycles. The forward-looking trajectory through 2032 indicates sustained expansion, with revenue scaling past $3.04 billion in 2026 and continuing to accelerate through the latter half of the forecast window.
This growth is underpinned by converging operational pressures and technological enablement. Agricultural operators are increasingly deploying AI to address structural labor constraints, input cost volatility, and climate-related yield unpredictability. The market is simultaneously being shaped by enterprise digitization initiatives, subsidies for precision technologies, and the standardization of agricultural machine learning datasets. Strategic decision-makers must recognize that the revenue expansion is not uniform across use cases or geographies; rather, it is concentrated in high-value application domains and regions with advanced digital infrastructure, creating distinct monetization pathways and competitive moats.
Core Application Domains and Technological Enablers
The AI agriculture ecosystem is organized around several foundational technological pillars and application segments that collectively drive value creation across the farm-to-market continuum. The dominant deployment patterns reflect a shift from isolated automation tools to integrated decision platforms that combine sensing, predictive modeling, and operational execution.
- Machine Learning continues to serve as the core analytical engine, enabling adaptive modeling for crop performance, input optimization, and risk forecasting across variable environmental conditions.
- Computer Vision has become critical for real-time field-level perception, supporting weed identification, crop health assessment, and automated guidance systems that reduce chemical usage and operational waste.
- Predictive Analytics is increasingly embedded in agronomic planning workflows, allowing growers and agribusinesses to anticipate weather impacts, soil conditions, and yield variability with greater temporal precision.
On the application side, Precision Farming remains the most extensively deployed category, integrating data-driven field management, variable-rate application, and equipment interoperability. Parallel growth is evident in Agriculture Robots and Livestock Monitoring, where AI-enabled automation addresses labor scarcity, animal welfare, and operational consistency. The strategic implication for enterprise buyers is clear: the highest near-term returns are emerging where AI is embedded directly into operational workflows rather than deployed as standalone analytics. Organizations evaluating market entry or capability expansion should prioritize integration depth, data interoperability, and measurable operational impact over feature breadth alone.
Competitive Landscape and Strategic Positioning
The market remains moderately fragmented, with a concentrated core of established players and a dynamic periphery of specialized innovators. Industry concentration metrics indicate that the top three competitors command approximately 24.6% of total market revenue, while the top five collectively account for 26.2%. This structure reflects an environment where scale advantages in data networks, platform ecosystems, and equipment integration coexist with niche differentiation in imaging, sensing, and agronomic intelligence.
Several incumbents and platform leaders define the current competitive architecture. John Deere continues to anchor its strategy in precision agriculture platforms that combine AI-driven autonomous equipment, computer vision for weed and crop identification, and centralized farm management data operations. Microsoft leverages its Azure FarmBeats ecosystem to unify machine learning, IoT sensing, drone imagery, and satellite data for precision farming insights and resource optimization. IBM contributes through its Watson Decision Platform for Agriculture, integrating AI, weather intelligence, and IoT streams to generate predictive crop health, soil, and weather insights. Bayer Crop Science extends its digital farming footprint via the Climate FieldView platform, applying AI-powered analytics for crop recommendations, risk management, and yield optimization. Trimble supports the space with AI-powered precision agriculture tools and connected solutions designed for machine guidance, data analysis, and operational efficiency.
Worldwide Agricultural Nanotechnology Market
Beyond the platform and equipment incumbents, a robust wave of specialized innovators is reshaping field-level intelligence. Valmont Industries applies integrated AI and machine learning to irrigation systems, crop monitoring, and anomaly detection through center-pivot technology. Taranis has built an AI-powered crop intelligence platform that uses machine learning and leaf-level imagery for disease detection, nutrient analysis, and agronomic recommendations. Gamaya combines hyperspectral imaging and remote sensing within an AI platform for crop health monitoring, yield prediction, and sustainability optimization. Ag Leader Technology focuses on precision farming technology for machine guidance, planting, and harvest optimization with integrated field operation data. Corteva Agriscience continues to expand digital tools and AI solutions for precision agriculture, including seed genetics and input recommendations.
Recent corporate activity underscores the velocity of this competitive evolution. In February 2026, John Deere announced its 2026 Startup Collaborator program, aligning with six ag-tech startups focused on AI, robotics, satellite analytics, and advanced sensing to strengthen precision farming capabilities. In October 2025, Taranis disclosed a strategic AI partnership with Syngenta Group to integrate generative AI-powered agronomic intelligence for crop advisors and growers. In July 2025, Gamaya merged with Terraview to unlock new opportunities for sustainable food systems through AI-powered agronomic intelligence. These moves reflect a broader pattern: incumbents are increasingly acquiring, partnering, or collaborating to accelerate data network effects, expand application coverage, and reduce time-to-market for advanced agronomic capabilities.
Industry Dynamics, Regulation, and Infrastructure Realities
Market expansion is not occurring in a vacuum. Strategic planners must account for an evolving regulatory and operational environment that directly shapes deployment economics and adoption pacing. Public-sector frameworks are increasingly directing how AI is governed, standardized, and integrated into agricultural operations. The USDA Fiscal Year 2025–2026 AI Strategy mandates ethical, transparent, and accountable governance for AI deployment in agricultural operations, establishing expectations for data use, model accountability, and operational oversight. In parallel, the European Union Coordinated Plan on Artificial Intelligence includes targeted implementation progress for AI applications in precision agriculture and intelligent spraying, indicating heightened attention to compliance, environmental outcomes, and technology verification in mature regulatory markets.
Standardization efforts are also gaining traction. The AgML framework is working to standardize agricultural machine learning datasets and benchmarks for AI model development and evaluation, an initiative that should reduce fragmentation in training data quality and improve cross-platform comparability. For enterprise buyers and technology developers alike, these standardization and governance trends create both operational clarity and new compliance obligations. Organizations that build governance-ready architectures and auditable model workflows will face lower regulatory friction and stronger stakeholder trust as adoption scales.
Infrastructure and labor dynamics further define the practical boundaries of market growth. IoT sensors and solar-powered connectivity systems require significant upfront investment in farm-level data collection infrastructure for AI applications, meaning that deployment economics can vary sharply by operation size, connectivity availability, and capital access. At the same time, AI integration is increasingly positioned as a structural response to labor shortages, automating weed identification, spraying, and harvest operations through computer vision and robotics. This dual pressure—higher upfront infrastructure cost alongside labor cost mitigation—creates a nuanced investment calculus. Strategic decision-makers should evaluate AI adoption not solely on technology capability, but on total cost of ownership, infrastructure readiness, and the scalability of automation benefits across seasons and field conditions.
Strategic Priorities for 2026 Decision-Making
The 2026–2032 forecast window rewards organizations that align AI strategy with operational reality, data readiness, and ecosystem positioning. Several priority axes emerge for leadership teams evaluating market participation, investment, or capability development.
- Prioritize workflow-embedded AI over standalone analytics. Solutions that integrate directly into planting, spraying, irrigation, and harvest decisions are more likely to deliver measurable return and stickier adoption.
- Assess infrastructure readiness before scaling deployment. Farm-level connectivity, sensor coverage, and data ingestion capacity will determine whether AI initiatives translate into repeated operational gains or remain constrained pilot programs.
- Monitor partnership and consolidation signals. The mix of startup collaboration programs, platform partnerships, and mergers indicates that capability gaps are increasingly being closed through ecosystem alliances rather than internal build-only strategies.
- Embed governance and data standards early. With regulatory expectations rising and dataset standardization advancing, organizations that adopt transparent, auditable AI practices will be better positioned for cross-market expansion and partner integration.
- Evaluate concentration risk and differentiation opportunities. While leading platforms hold meaningful share, the market remains open to specialized solutions in imaging, irrigation intelligence, livestock monitoring, and agronomic advisory. Targeted differentiation can create defensible positions even in a fast-scaling market.
How to Use This Intelligence
This overview is designed to establish the strategic frame for deeper operational planning. It highlights the direction of market growth, the structure of competition, and the regulatory and infrastructure realities that shape deployment outcomes. However, actionable market entry, investment allocation, and capability planning require granular segmentation, use-case-level revenue splits, regional deployment differentials, and competitive benchmarking that exceeds the scope of a high-level briefing.
For organizations that need precise allocation models, segment-level growth decomposition, application-specific adoption curves, and detailed competitor capability mapping, the complete market research report provides the structured intelligence necessary to convert strategic direction into executable plans. The full analysis isolates the segments, regions, and deployment models that matter most to your operating context, enabling decision-makers to move from directional confidence to specific, data-backed action.
Closing Perspective
The AI in Agriculture market has entered a phase where technological promise is being converted into operational impact at scale. The combination of sustained double-digit growth, expanding platform ecosystems, and intensifying competitive collaboration suggests that the decisive question for 2026 is no longer whether AI will reshape agricultural operations, but how quickly organizations can integrate it into the economics of production. Leaders who align strategy with workflow reality, data infrastructure, and governance readiness will be best positioned to capture value as the market advances toward 2032.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence (AI) in Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Para-Cumylphenol Market to Hit $429.87M by 2032 with 5.8% CAGR from $290M in 2025
By PW Consulting, 2026-09-16
Para-Cumylphenol Market Strategic Outlook 2026: Navigating Growth, Consolidation, and Application Diversification
The global chemical intermediates sector is entering a decisive phase where precision, supply chain resilience, and formulation agility separate market leaders from passive participants. Within this landscape, para-cumylphenol (PCP) has emerged as a foundational building block across multiple high-value downstream industries. Our latest market research delivers a comprehensive, data-driven assessment of the para-cumylphenol market, designed specifically to equip corporate strategists, procurement leaders, and R&D directors with the analytical clarity required for sound 2026 decision-making. This report does not merely track historical volume; it maps the structural forces, competitive pressures, and application shifts that will define commercial trajectories through the end of the decade.
Firms operating in specialty chemicals, advanced materials, and formulation science cannot afford to rely on fragmented supplier briefings or outdated industry snapshots. The para-cumylphenol value chain is experiencing measurable evolution in capacity deployment, grade differentiation, and regional demand pacing. Our analysis integrates verified historical tracking from 2020 through 2025 with a forward-looking projection window spanning 2026 to 2032. The overarching revenue trajectory reflects a compound annual growth rate of 5.8 percent, moving from a baseline valuation of approximately 290.0 million USD in the base year to a projected 429.87 million USD by 2032. These figures are not abstract indicators; they represent the cumulative impact of resin engineering upgrades, adhesive formulation modernization, coating performance mandates, and expanding pharmaceutical intermediate requirements. For executives planning capital allocation, vendor qualification, or geographic footprint adjustments, understanding the pace and composition of this expansion is indispensable.
Why 2026 Demands a Refined Strategic Lens
The current operating environment requires more than top-line forecasting. Companies must evaluate how grade specifications, regional supply dynamics, and end-use substitution patterns interact to shape pricing power, availability, and long-term contract viability. Our research framework is built to surface those linkages without obscuring the operational realities that drive them.
4-Cumylphenol Market
First, the transition from generic chemical sourcing to specification-aligned procurement has intensified. Manufacturers are no longer selecting para-cumylphenol solely on cost; they are evaluating purity thresholds, impurity profiles, batch consistency, and downstream compatibility. Second, the concentration of supply among established producers has created a market structure where relationship management, technical support, and continuity assurance carry substantial commercial weight. Third, application-side innovation is accelerating requirements for tailored intermediate performance, pushing suppliers to align production capabilities with formulation roadmaps rather than treating PCP as a commoditized feedstock. These dynamics converge in 2026, making structured market intelligence a strategic asset rather than an optional reference document.
Report Architecture: What Decision-Makers Will Find Inside
This study is engineered for immediate operational relevance. Rather than presenting isolated statistics, the report constructs a connected analytical narrative that spans market sizing, segmentation logic, competitive positioning, and forward risk mapping. The structure is intended to support multiple decision contexts, from board-level strategic reviews to procurement planning and R&D prioritization.
Readers will encounter a meticulously documented historical reconstruction covering the 2020 to 2025 period, establishing a transparent baseline against which future projections are calibrated. The forecast component extends through 2032 and translates macro-growth signals into actionable directional intelligence. The segmentation architecture dissects the market along multiple commercial dimensions, including product grade classification, application end-use categories, and regional demand distribution. Each segmentation layer is analyzed not as a standalone table, but as an interactive variable that influences pricing behavior, capacity utilization, and supplier selection criteria.
Para-Cumylphenol Market
Beyond sizing and segmentation, the report delivers practical operational content designed to support execution. This includes:
- Detailed assessment of grade differentiation dynamics, with emphasis on how high-purity and low-purity streams serve distinct downstream requirements and pricing environments
- Application-side evaluation that traces how resins, adhesives, coatings, pharmaceutical intermediates, and other industrial uses shape demand stability, substitution risk, and formulation trends
- Regional demand profiling that identifies where consumption momentum is building, which markets are maturing, and how logistical or regulatory factors influence supply routing
- Supply-side structural review that examines capacity deployment patterns, production concentration, and the strategic implications of a consolidated supplier base
- Forward-looking scenario framing that helps organizations stress-test assumptions around volume growth, specification upgrades, and competitive re-alignment through the late 2020s
Every section is cross-referenced to ensure that sizing logic, segmentation behavior, and competitive context reinforce one another. The result is a cohesive intelligence package that allows strategy teams to move from high-level market awareness to targeted commercial action.
Competitive Landscape: Consolidation, Capability, and Commercial Positioning
The para-cumylphenol market is characterized by a notably concentrated supplier environment. Market structure indicators point to a high degree of consolidation, with the top three participants accounting for approximately 80 percent of industry revenue and the top five reaching roughly 82 percent. This concentration is not simply a statistical footnote; it shapes bargaining dynamics, technical service expectations, and supply continuity planning for downstream buyers. In a market where a limited number of producers control the majority of output, relationship durability, specification reliability, and responsiveness to customization requests become central competitive differentiators.
SI Group, Inc., headquartered in Albany, New York, operates as one of the primary large-scale industrial producers of para-cumylphenol. Its commercial relevance extends across multiple downstream pathways, serving as a key intermediate for surfactant production, a monomer for phenolic resins, and a chain terminator in polycarbonate applications. This multi-role positioning gives the company broad exposure to formulation trends and allows it to align production capabilities with diverse end-use requirements.
Dover Chemical, operating through ICC Industries in Findlay, Ohio, manufactures para-cumylphenol as a phenol-based monomer focused on polymer industry applications. Its production orientation reflects the ongoing importance of PCP in polymer engineering, where intermediate quality and consistency directly influence downstream material performance. Suppliers with this profile typically compete on technical reliability, batch control, and the ability to support polymer developers seeking predictable intermediate behavior.
On the Asia Pacific side, Shanghai ShengShan Chemical Technology Co., Ltd. stands out as a major manufacturing presence, recognized as one of China's largest producers of 4-cumylphenol with substantial monthly capacity. Its output supports a wide spectrum of downstream uses, including chemicals, pharmaceuticals, washing products, surfactants, fungicides, preservatives, stabilizers, and electronic-related applications. The breadth of this application base illustrates how a single intermediate supplier can anchor a diversified demand profile, reducing dependence on any single end-use cycle while increasing sensitivity to cross-sector regulatory and formulation shifts.
Beijing Xing Li Gong Mao Co., Ltd. operates as another important supplier within the hydroxybenzene, ketone, aether, and related product spectrum, offering p-cumylphenol as part of a broader intermediates portfolio. Suppliers of this type often compete through portfolio integration, technical documentation support, and supply flexibility, enabling downstream formulators to consolidate vendor relationships while maintaining access to multiple chemical inputs.
Together, these companies illustrate a competitive environment where scale, grade control, application breadth, and geographic positioning intersect. The report examines how such players manage capacity, respond to specification demands, and position themselves relative to regional consumption patterns. Understanding these competitive mechanics is essential for buyers assessing supplier resilience, for investors evaluating market entry or consolidation potential, and for producers benchmarking their strategic posture against established incumbents.
Market Dynamics Shaping Commercial Behavior
The para-cumylphenol market does not evolve in isolation. Its trajectory is influenced by interrelated forces that span raw material economics, downstream formulation priorities, regulatory expectations, and regional industrial development patterns. Our analysis frames these dynamics as actionable considerations rather than abstract trends.
One of the most consequential shifts is the increasing emphasis on performance specification over basic availability. As downstream industries seek improved durability, processing stability, and functional consistency, the value of higher-grade intermediates rises relative to lower-specification alternatives. This does not eliminate demand for standard purity streams, but it reorders commercial priorities and creates a two-tier market environment in which grade alignment, impurity control, and technical support increasingly influence purchasing decisions.
Another defining factor is the concentration of supply and its implications for continuity planning. In a market where a small number of producers command the majority of revenue, procurement teams must look beyond unit pricing and evaluate supplier stability, capacity commitment, and responsiveness to custom grade requests. This environment rewards long-term supplier alignment and makes supplier diversification strategies more complex, since meaningful alternatives may not always be available at comparable specification levels.
Regional demand behavior also plays a central role. Consumption patterns differ by industrial maturity, formulation adoption rates, and local manufacturing footprints. Some markets are driven by established resin and coating production ecosystems, while others are expanding through pharmaceutical intermediate needs, surfactant development, and specialized chemical applications. The report maps these regional variation patterns without reducing them to simplistic rankings, instead highlighting how local industrial structure, logistics, and demand composition influence purchasing rhythm and supply strategy.
How Organizations Can Use This Intelligence in 2026
The strategic value of this report lies in its ability to convert market complexity into structured decision support. For procurement and supply chain leaders, the analysis clarifies where specification requirements are tightening, which supplier relationships merit deeper due diligence, and how regional demand momentum may affect lead times and availability. For R&D and formulation teams, the segmentation and application discussion provides context on how intermediate quality, purity thresholds, and downstream compatibility expectations are evolving across resins, adhesives, coatings, pharmaceutical uses, and other industrial categories.
For executive strategists and corporate planners, the forward projection framework supports scenario planning around volume growth, grade migration, and competitive re-alignment. The report enables organizations to test assumptions about capacity expansion, pricing behavior, and application substitution without relying on unverified industry anecdotes. Investors and market entry teams can use the competitive structure and concentration analysis to evaluate barriers, supplier leverage, and the realistic scope for new capacity or partnership strategies.
Importantly, the study is designed to function as a living reference point for cross-functional alignment. When procurement, technical, and commercial teams share a common evidence base, decisions become faster, risk assessment becomes more disciplined, and supplier negotiations gain strategic context. That is the core purpose of this research: to provide a reliable foundation for 2026 planning and beyond.
What Is Reserved for the Full Report
This overview demonstrates the analytical depth, structural clarity, and commercial relevance of the full study. At the same time, the most operationally sensitive details are intentionally reserved for the complete report. The full version provides the precise segmentation values, regional breakdown figures, application-level revenue distribution, grade-specific sizing, and supplier-level competitive metrics that strategy teams need for concrete planning. Those data points are essential for building procurement models, capacity forecasts, and vendor evaluation matrices, but they are most effective when accessed in full context rather than in isolation.
The complete report also includes the integrated forecasting logic, historical calibration notes, supply-side structural interpretation, and application-side trend mapping that connect high-level market size to practical commercial action. For teams that require defensible numbers, supplier comparisons, and forward-looking scenario support, the full document delivers the granularity needed to move from directional insight to executable strategy.
Para-cumylphenol is no longer a background intermediate; it is a strategically significant input whose market structure, specification demands, and application breadth will increasingly shape downstream competitiveness. Organizations that equip themselves with rigorous, well-structured intelligence will be better positioned to manage supply continuity, align procurement with formulation roadmaps, and anticipate the commercial shifts that define the 2026 to 2032 window. The full report provides the complete evidentiary foundation for that undertaking.
For detailed analysis of this topic, please visit the official page: Para-Cumylphenol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Between 2020 and 2035, the global skewers machine market is projected to grow robustly, with revenues increasing from $570 Million in 2020 to an estimated $2,010 Million by 2035. The market’s expansion is fueled by rising demand in commercial food preparation and innovative automation technologies. Key regions such as North America and Asia-Pacific are experiencing accelerated adoption. Yearly revenue growth reflects ongoing investments from food service companies and continuous product upgrades by leading manufacturers.
Read More - https://bussinessinsights.com/research-report/global-skewers-machine
The commercial segment remains the primary application of skewers machines, capturing the largest share in 2025. Food processing units and quick service restaurants heavily rely on automated solutions to scale up production and meet consumer demands for convenience food. Industrial usage also contributes substantially, driven by large scale meat and vegetable processing. The trend is supported by the rise of global food service chains, increased food safety awareness, and a shift towards centralized kitchen operations.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-skewers-machine
Frequently Asked Questions
Who are the key players in Global Skewers Machine industry?
The key players in the Global Skewers Machine industry include Autec Inc., Foodline Systems, Anko Food Machine Co., Ltd., Nuova Era, and MIMASA. These companies dominate the market with advanced automation, global distribution networks, robust aftersales support, and consistent investment in R&D to fulfill varied food processing needs.
What is the Global Skewers Machine growth?
The Global Skewers Machine market has witnessed significant growth, driven by increasing demand for automated food processing in restaurants and food factories. For example, Autec Inc. reported notable sales increases in 2023, attributed to their innovative skewering solutions catering to rising fast-food and convenience food trends.
Which segment accounted for the largest Global Skewers Machine share?
Commercial foodservice applications account for the largest share of the Global Skewers Machine market. Machines designed for high-volume kebab, satay, yakitori, and similar products enable restaurants and catering businesses to increase output and consistency, fueling extensive adoption across hospitality and large-scale food preparation sectors.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global home air purifier market is projected to see substantial revenue growth from 2020 to 2035. After standing at $5,800 Million in 2020, it reached $7,100 Million by 2025. Projections expect the market to achieve $18,900 Million in 2035. This robust expansion is attributed to increasing public health awareness, higher pollution levels in developing economies, rapid smart home adoption, and ongoing innovation in filtration technologies. The steady CAGR indicates a healthy shift in consumer priorities.
Read More - https://bussinessinsights.com/research-report/global-home-air-purifier
Residential use remains the dominant application segment for home air purifiers in 2025, as consumers increasingly invest in indoor wellness post-pandemic. Commercial spaces such as offices and retail establishments show notable growth, driven by hygiene and regulatory compliance trends. The healthcare segment is also expanding, spurred by infection control protocols and a need for cleaner patient environments, especially in urban medical centers.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-home-air-purifier
Frequently Asked Questions
Who are the key players in Global Home Air Purifier industry?
The top five players in the global home air purifier industry include Dyson, Philips, Honeywell, Panasonic Corporation, and Sharp Corporation. These companies are renowned for their innovation, diverse product portfolios, and strong global distribution networks, enabling them to maintain significant market shares and continuously introduce advanced air purification technologies.
What is the Global Home Air Purifier growth?
The global home air purifier market is experiencing robust growth, driven by increased awareness of indoor air quality post-COVID-19. In 2023, companies like Dyson reported double-digit sales growth as demand surged in urban areas, especially in Asia-Pacific and North America, fueled by rising pollution and health concerns.
Which segment accounted for the largest Global Home Air Purifier share?
The residential segment held the largest share in the global home air purifier market. Growing urbanization, coupled with rising health consciousness among consumers, has led to increased adoption of air purifiers for home use, especially in bedrooms and living rooms to reduce allergens, dust, and harmful particulates.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Fiber Optic Cable Assembly Market to Reach $11.13B by 2032 at 6.9% CAGR
By PW Consulting, 2026-09-16
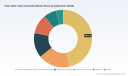
Fueling High-Velocity Networks: The Strategic Imperative Behind the 2026 Fiber Optic Cable Assembly Market Outlook
As global digital infrastructure accelerates toward 2032, leaders across telecommunications, data center development, aerospace, and public-sector engineering are navigating a market defined by compounding demand, evolving regulatory frameworks, and intensifying competitive maneuvering. The Fiber Optic Cable Assembly Market has transitioned from a purely operational procurement category to a strategic leverage point for enterprises seeking bandwidth resilience, latency optimization, and future-proof connectivity architectures. Our newly released research offering provides a comprehensive, decision-oriented exploration of this landscape, mapping historical trajectories, forward-looking growth corridors, and the operational realities that will shape purchasing, positioning, and partnership strategies throughout the 2026–2032 forecast horizon.
For executives evaluating capacity planning, vendor consolidation, or geographic expansion in the coming fiscal year, the underlying market signals warrant close attention. Drawing on a rigorous analytical framework anchored in historical performance through 2025 and extending across the 2026–2032 forecast window, this research translates macro-level momentum into actionable strategic context. Rather than offering static snapshots, the study is designed to help leadership teams anticipate inflection points, stress-test assumptions, and align capital allocation with the structural drivers reshaping fiber connectivity value chains.
Decoding the Macro Trajectory: Why the Growth Curve Matters for 2026 Planning
The market has demonstrated consistent expansion across the historical review period, reflecting a steady escalation in demand for high-performance cable assemblies that support increasingly data-intensive networks. By the close of the base year, total market revenue had climbed to a substantial milestone, underscoring the durability of fiber-based connectivity as a foundational infrastructure layer. The forecast period projects continued upward momentum, with the overall market expected to advance at a compound annual growth rate of 6.9 percent through 2032. For strategists, this trajectory is more than a headline figure; it signals a sustained demand environment in which capacity missteps, overly conservative sourcing models, or delayed technology adoption can create competitive disadvantages that compound over multiple planning cycles.
Importantly, the growth profile reflects more than incremental volume increases. It encapsulates shifting end-user expectations around reliability, signal integrity, deployment speed, and lifecycle durability. As enterprises and public institutions push bandwidth requirements higher while tightening tolerance for failure points, the cable assembly segment sits at the intersection of physical-layer performance and strategic network design. Decision-makers evaluating product roadmaps, inventory strategies, and supply commitments in 2026 must therefore interpret growth not merely as a sizing exercise, but as an indicator of where performance specifications, qualification standards, and application-specific requirements will become increasingly binding.
Inside the Research: What Decision-Makers Will Find
This study is structured to support practical, executive-level decision-making rather than abstract market commentary. It delivers a layered analytical architecture that connects high-level sizing context with granular structural insights, enabling readers to isolate the drivers most relevant to their operating environment. The report examines the market through multiple strategic lenses, including:
- Structural segmentation analysis that clarifies how demand patterns diverge across cable assembly formats, end-use applications, and regional deployment realities, helping teams pinpoint where specification requirements and procurement cycles differ most sharply.
- Competitive positioning and profiling of leading and emerging participants, including operational footprints, product focus areas, and the strategic moves that are reshaping share dynamics and customer value propositions.
- Regulatory and standards-driven dynamics that assess how qualification frameworks, customs and trade policy developments, and infrastructure-era procurement practices are influencing sourcing risk, compliance planning, and regional competitiveness.
- Deployment and production context covering the operational prerequisites that distinguish high-precision assembly environments, including cleanroom-class manufacturing considerations, testing rigor, and the practical implications for lead times, customization, and reliability assurance.
- Recent event intelligence tied to corporate collaborations, product catalog evolution, major infrastructure rollouts, and regulatory updates, providing a real-time anchor for interpreting how the competitive and operating landscape is shifting on the ground.
Each section is designed to feed directly into commercial assessment, procurement strategy, and forward planning. The goal is not simply to show what the market has been, but to equip leadership with the context needed to evaluate where to invest, where to standardize, and where to differentiate in a segment that rewards both technical precision and strategic timing.
Competitive Landscape and Strategic Positioning Signals
The fiber optic cable assembly market remains structurally fragmented, with a top-three concentration that reflects meaningful but not dominant consolidation among leading manufacturers and solution providers. This competitive configuration creates a distinctive environment: large-scale incumbents can leverage established manufacturing capabilities, broad product portfolios, and long-standing customer relationships, while specialized players compete on precision, customization, qualification readiness, and application-specific engineering. For procurement leaders and strategy teams, the implication is clear. Vendor evaluation cannot be reduced to unit pricing alone; total value increasingly depends on qualification support, delivery predictability, design flexibility, and the supplier's ability to align with the technical and regulatory demands of the target deployment environment.
Several market participants illustrate the range of strategic postures now shaping the segment. Optical Cable Corporation has built its profile around military, tactical, and commercial enterprise fiber optic cable assemblies and connectivity solutions, spanning both pre-terminated and custom variants. In mid-2025, the company entered a strategic collaboration agreement with Lightera, LLC, including an investment component, aimed at expanding offerings for data center and enterprise applications. That move signals a deliberate pivot toward higher-growth infrastructure end-markets and reflects a broader industry pattern in which traditional manufacturers are reinforcing capabilities where bandwidth demand and deployment velocity are most acute.
Diamond SA exemplifies the precision-engineering orientation that increasingly differentiates suppliers serving demanding use cases. Based in Switzerland, the company specializes in high-precision fiber optic interconnects and assemblies and maintains cleanroom production environments tailored to enterprise, space, and other stringent applications. In a market where signal integrity and contamination control can directly affect qualification success, this production philosophy highlights the operational premium attached to controlled-assembly environments. Meanwhile, L-com Global Connectivity continues to emphasize ruggedized and pre-terminated fiber optic cable assemblies, patch cords, and custom connectivity solutions for networking and industrial applications, reinforcing the importance of durability and field-readiness in industrial and critical-infrastructure settings.
Cable Assembly Market
On the distribution and customization side, Fiber Instruments Sales, Inc. provides a broad catalog of fiber optic cable assemblies, including fusion-spliced and field-installable options, bridging manufacturing output with practical deployment flexibility. fiberone, llc has similarly emphasized customer-specific design in its custom multi-fiber cable assemblies, adjusting lengths, breakouts, and pulling eyes to meet precise project requirements. Recent activity from fiberone, llc in early 2026, including an updated product catalog and refreshed emphasis on customer-specific designs, illustrates how tailored specification support remains a competitive differentiator for projects where off-the-shelf configurations are insufficient. Taken together, these profiles show a market in which competitive advantage is being constructed through a blend of manufacturing discipline, application specialization, partnership strategy, and responsiveness to project-level engineering requirements.
Regulatory Currents, Trade Realities, and Deployment Economics
Strategic sourcing in fiber optic cable assemblies cannot be separated from the regulatory and policy environment shaping cross-border trade, safety qualification, and public infrastructure procurement. One of the most consequential developments for safety-critical deployments came from the Nuclear Regulatory Commission, which issued Regulatory Guide RG 1.257 in August 2025. The guide addresses the qualification of fiber-optic cables, connections, and optical fiber splices for use in safety systems within production and utilization facilities. For organizations operating in or supplying to regulated environments, this type of guidance directly affects validation pathways, documentation expectations, and the burden of demonstrating long-term reliability under defined operating conditions.
Trade policy remains another critical variable. Implementation of Section 301 tariffs on optical fiber cables from China continues to impose a 25 percent additional duty, and industry commentary submitted to BIS in late 2025 noted that these measures remain in effect without coverage under Section 232 tariffs. For sourcing teams, the practical consequence is a persistent cost and supply-chain consideration that can influence origin decisions, inventory timing, and supplier diversification strategies. Executives evaluating total landed cost, qualification continuity, and geopolitical exposure must factor these duties into scenario planning rather than treating them as transient conditions.
At the infrastructure level, fiber deployment economics remain highly project-dependent. Recent cost-plot updates from U.S. Department of Transportation ITS KRS, including revisions to roadside telecommunications fiber optic cable installation costs, highlight the sensitivity of project budgets to installation context, geography, and operational constraints. Public-sector and private infrastructure programs alike must contend with cost variability that can reshape feasibility assessments and phased rollout plans. In parallel, legislative interest in fiber infrastructure security has continued to gain visibility, including the introduction of the Bipartisan Strategic Subsea Cables Act of 2026, which proposes expanded U.S. government engagement around subsea fiber-optic cable security, maintenance, and repair. While subsea systems represent a distinct layer of the broader connectivity ecosystem, the policy direction reinforces a widening recognition of fiber infrastructure as a strategic asset worthy of heightened oversight and coordinated response frameworks.
These overlapping forces illustrate why the market cannot be understood through sizing alone. Regulatory qualification, tariff exposure, installation cost variability, and infrastructure security priorities all influence how quickly projects move, which suppliers are eligible, and how procurement teams balance cost efficiency with resilience. The research incorporates these dynamics as active variables in the market outlook, helping readers connect policy and operational realities to commercial planning.
Why 2026 Is a Decision Pivot Point
The current forecast window places unusual importance on early-cycle decisions. With market value projected to rise materially from the 2026 base estimate toward the end of the decade, organizations that define their sourcing architectures, qualification strategies, and application focus early are better positioned to manage cost structures, secure supply continuity, and align product capabilities with the most attractive demand pools. Conversely, teams that defer structural decisions risk entering a more crowded, more regulated, and more cost-sensitive environment with less flexibility.
Several practical imperatives follow from this outlook. First, demand planning should be anchored in application-specific requirements rather than aggregate volume alone. The growth trajectory is being shaped by differing needs across telecom and datacom environments, broadcasting and CATV deployments, military and aerospace specifications, power and new energy applications, healthcare installations, and other specialized use cases. Each of these segments carries its own performance thresholds, qualification expectations, and purchasing rhythms, making segmented insight essential for accurate forecasting and effective product positioning.
Fiber Optic Cable Assembly Market
Second, supply-chain strategy should account for both performance assurance and policy exposure. Cleanroom-class production environments, precision assembly practices, and rigorous testing protocols are not merely operational details; they are increasingly central to winning qualification-sensitive work and differentiating from lower-spec alternatives. At the same time, tariff structures and sourcing origins can materially affect total cost and supply predictability, requiring scenario-based procurement planning rather than single-path sourcing assumptions.
Third, competitive strategy should recognize that the market rewards a blend of scale, specialization, and adaptability. Some participants compete by expanding into high-growth data center and enterprise segments through collaboration and investment. Others compete by deepening precision manufacturing and application-specific engineering. Still others compete through catalog breadth, distribution reach, or customization capability. Understanding where a company’s own strengths align with these competing logics is essential for positioning, partnership selection, and long-term share capture.
From Intelligence to Action: What the Full Study Enables
The overview presented here is intended to demonstrate the analytical rigor and strategic relevance of the full report, while deliberately preserving the deeper segmentation data, quantification detail, and comparative frameworks that justify the complete study. Enterprise teams that rely on a high-level summary alone risk missing the structural nuance that determines where growth is concentrated, how competitive pressure is distributed, and which operational requirements will most influence sourcing outcomes in specific deployment contexts.
The complete research offering expands on every dimension introduced here, providing the detailed market sizing breakdown, segmentation insight, and competitive profiling required to support precise planning. It enables readers to move from general market confidence to targeted decision support by revealing how demand is distributed across cable assembly types, application areas, and regional dynamics, and by placing those patterns in the context of recent corporate moves, regulatory developments, and infrastructure activity. For organizations preparing budgets, product strategies, qualification roadmaps, or expansion plans for 2026, that level of detail is not optional; it is the difference between reactive planning and strategically informed execution.
The market is expanding, but expansion alone does not create advantage. Advantage is created by understanding where the growth is structurally grounded, which requirements will become non-negotiable, and how competitive and regulatory forces will reshape the cost and capability equation over the next several years. Our full market research is designed to deliver exactly that level of intelligence. We invite decision-makers to access the complete study to obtain the comprehensive segmentation data, comparative analysis, and forward-looking strategic context needed to translate this market outlook into concrete, high-confidence action throughout the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Fiber Optic Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com