

Blogs
Strategic Intelligence Brief: 2-Hydroxyethyl Methacrylate Market Outlook 2026–2032
The global chemical landscape is undergoing a structural recalibration. For industry leaders operating in specialty monomers, the window for strategic positioning is narrowing as regulatory frameworks tighten and downstream applications demand ever-higher material performance. Our latest market research study on 2-Hydroxyethyl Methacrylate (HEMA) delivers a comprehensive, data-grounded assessment of how this critical building block will evolve through 2032—and what it means for procurement, R&D, and competitive strategy in 2026 and beyond.
This briefing preview synthesises the foundational findings of the full report. It is designed to demonstrate analytical rigor, map the terrain of critical decision variables, and illustrate why a deeper, segmented intelligence package is indispensable for executives navigating the next investment and sourcing cycles. Core numerical breakdowns by region, purity tier, and end-use vertical are intentionally held back; they are available in their complete, modelled form within the published study.
Macro Trajectory: A Market in Steady Expansion
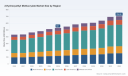
Historical reconstructions from 2020 through 2025 reveal consistent top-line growth for HEMA, with global revenue climbing from approximately 432.19 million USD to a recent base-year level of 531.0 million USD. The momentum does not plateau. Our forecast horizon extends through 2032, projecting a continued upward arc that carries the market past the 700-million-dollar threshold by the close of the period. The compound annual growth rate across this forecast window is modelled at 4.2 percent, a figure that reflects resilient demand across established application sectors and emerging high-value segments.
Several structural forces underpin this trajectory. The shift toward electric mobility has intensified requirements for advanced thermal-management coatings and protective resin systems. Biomedical and dental material innovation continues to drive demand for ultra-high-purity grades that meet stringent regulatory and biocompatibility thresholds. Simultaneously, optical clarity requirements in consumer and medical hydrogels, along with specialty adhesive formulations, create incremental pull from purity-sensitive applications. These demand vectors are not evenly distributed; they concentrate value in specific purity windows and regional supply nodes, a dynamic that is unpacked in granular detail in the full study.
The Purity Paradigm: How Specification Drives Commercial Value
Not all HEMA is commercially equivalent. Purity thresholds act as powerful pricing and demand filters, and the market has bifurcated around three dominant specification tiers. Producers and buyers alike must understand where value accrues, where margin pressure exists, and how technical requirements translate into procurement premiums.
High-purity grades command particular attention in sectors where impurity profiles directly affect end-product performance. Biomedical, pharmaceutical, and optical applications mandate rigorous distillation, repeated testing, and adherence to ISO-aligned quality protocols for material designated at or above 99 percent purity. These specifications are not optional extras; they are preconditions for market entry in regulated verticals. Slightly lower purity bands still hold substantial commercial relevance, particularly in coatings and reactive resin formulations where cost-performance balances differ. The full report maps exactly how each purity tier contributes to value creation and identifies which downstream customers are willing to pay for specification upgrades versus those optimising on grade cost.
Application Segmentation: Where Demand Is Concentrated
HEMA flows into a diverse but unevenly weighted set of end markets. Coatings represent a major consumption hub, leveraging the monomer’s contributions to gloss, adhesion, and film integrity. Reactive resins form another substantial pillar, particularly where cross-linking behaviour and interfacial compatibility matter. Adhesives capture a meaningful share, benefiting from HEMA’s ability to fine-tune tack, flexibility, and bond durability. A residual category encompasses specialised and niche deployment scenarios that, while individually smaller, collectively represent innovation frontiers.
The strategic significance of this segmentation lies in its asymmetry. A relatively small shift in specification requirements within a high-value application can disproportionately impact overall margin profiles. Likewise, regional demand patterns differ markedly, shaped by local manufacturing intensity, regulatory stance, and the maturity of downstream processing clusters. Our analysis isolates the precise contribution of each application vertical and each geography, but the full breakdown—with scenario-tested sensitivities—is reserved for the complete intelligence package.
Competitive Landscape: Capability, Geography, and Moves
The HEMA market is characterised by a moderately concentrated supplier base, with a limited number of players controlling a substantial share of throughput. Competitive positioning depends on a combination of manufacturing footprint, purity capability, application-specific technical support, and responsiveness to regulatory shifts.
2-Hydroxyethyl Methacrylate Market
2-Ethylhexyl Methacrylate (2-EHMA) Market
Several active participants illustrate the current market architecture. Shakti Chemicals, headquartered in Mumbai, operates as a trader and supplier supporting polymer chemistry applications across Asia, emphasising regional distribution reach. Qingdao RENAS Polymer Material Co., Ltd., based in Qingdao, China, focuses on HEMA as part of a broader specialty chemicals and polymer materials portfolio. Nantong Chem-land Co., Ltd., also in China, supplies high-purity grades for industrial and specialty use, aligning product range with specification-sensitive buyers. Yancheng Green Chemicals Co., Ltd., likewise situated in China, manufactures HEMA for polymer synthesis and advanced chemical applications, reinforcing the country’s role as a production anchor.
Beyond these named participants, the competitive field includes larger diversified chemical firms that deploy HEMA in more complex value chains. Recent activity underscores how innovation and compliance shape the battlefield. In mid-2025, Chemical United introduced HEMA HISS, an ultra-pure 99.5 percent grade engineered for high-clarity applications spanning soft contact lenses, 3D-print resins, medical hydrogels, and high-gloss formulations. This launch signals intensifying competition at the premium purity end and the growing importance of application-tailored product architecture.
In October 2024, Dow collaborated with an automotive manufacturer on a new HEMA-based coating for electric vehicle batteries, with demonstrated improvements in thermal management and battery-life extension. Such application-led co-development points toward a future where monomer value is co-created with downstream partners rather than sold as a commodity specification. In January 2024, Evonik launched VISIOMER HEMA-P 100, a phosphate methacrylate monomer derived from HEMA, aimed at enhancing flame retardancy, adhesion, and corrosion resistance in coatings and composites. This type of derivative innovation expands the functional envelope of HEMA chemistry and creates adjacent opportunity spaces.
Regulatory and Environmental Constraints as Strategic Variables
Regulation is no longer a background condition; it is a direct driver of market structure. The EU Cosmetics Regulation (EC 1223/2009) restricts HEMA in nail cosmetics to professional use only, mandating specific labelling and barring non-compliant products from market entry since September 2021. In contrast, the United States continues to permit HEMA in dental adhesives, medical tapes, and wound dressings without equivalent professional-use limitations, preserving broader access for medical and dental applications. This transatlantic divergence creates distinct compliance pathways and affects how multinational suppliers design portfolio strategies for Western markets.
Environmental and safety considerations further embed operational constraints. HEMA is hydrolysed to methacrylic acid and ethylene glycol, and producers are expected to monitor and treat effluent to limit release to roughly 0.02 tonnes per year per plant. These abatement expectations shape capital planning and regional siting decisions. Meanwhile, upstream feedstock exposure remains significant: HEMA production depends on ethylene glycol, with prices exhibiting high volatility linked to crude oil and natural gas cycles. Margin management therefore requires forward-looking procurement strategies and, where feasible, integration or hedging mechanisms that reduce exposure to energy-linked input swings. ISO standards for high-purity grades (99 percent and above) add another compliance layer, mandating rigorous distillation and testing protocols for biomedical and pharmaceutical applications.
Why 2026 Calls for Decision-Ready Intelligence
The coming year will test companies on multiple fronts at once. Feedstock volatility will continue to complicate cost forecasting. Regulatory divergence will force region-specific packaging, labelling, and distribution decisions. Premium-purity demand will accelerate where biomedical, optical, and high-performance coatings converge. At the same time, capital allocation decisions on capacity, purification capability, and technical service infrastructure must be made with a view toward 2032, not merely the next quarter.
Executives need more than headline numbers. They require a decision architecture that connects macro trajectory to segment-level economics, maps competitive capability to application opportunity, and quantifies how regulatory and environmental constraints alter viable market access. The full report is built for exactly this purpose.
What the Full Study Delivers
Beyond the macro arcs and competitive snapshots previewed here, the complete market research package provides:
- A fully segmented revenue model by region, purity tier, and application, capturing both current sizing and forecast evolution through 2032 without exposing sensitive breakdowns until accessed in full.
- Scenario-tested sensitivity analysis around feedstock price volatility, enabling procurement and finance teams to stress-test margin assumptions under alternative energy-price pathways.
- A detailed regulatory matrix covering EU cosmetics restrictions, US medical and dental permissions, environmental effluent expectations, and ISO-grade quality protocols, with implications mapped to product strategy and market entry.
- Company-level profiles and recent development tracking for active market participants, including product launches, application co-development, and derivative innovation that signal where competitive advantage is being built.
- Strategic recommendations aligned to sourcing, capacity planning, specification upgrades, and regional compliance positioning, calibrated to different organisational roles from R&D to commercial leadership.
The complete dataset, including region-by-region and application-by-application contributions along with the precise revenue figures underpinning each segment, is available in the published report. Accessing the full study provides the granular intelligence required to translate market direction into concrete commercial and operational decisions.
Conclusion: Position Now or Pay Later
The HEMA market is expanding, but growth is uneven and increasingly governed by specification, compliance, and application-specific performance requirements. A 4.2 percent compound annual growth rate through 2032 is meaningful, yet the real strategic question is not how large the market becomes—it is which segments, which purity tiers, and which geographies will capture disproportionate value. Companies that act in 2026 with precise, segment-aware intelligence will be better placed to secure feedstock resilience, align product portfolios with regulatory realities, and capture premium demand where performance thresholds create pricing power.
This briefing has outlined the terrain. The full report delivers the detailed map. For procurement leaders, R&D strategists, and commercial executives, the study provides the decision-grade foundation needed to move from awareness to action before the window narrows further.
For detailed analysis of this topic, please visit the official page: 2-Hydroxyethyl Methacrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Niobium Carbide Market Hits $58.9M in 2025, Growing at 5.1% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: Navigating the Niobium Carbide Market Landscapes in 2026
As industries pivot toward advanced materials that offer superior hardness, thermal stability, and chemical resistance, Niobium Carbide (NbC) has emerged as a critical component in high-performance manufacturing. For strategic planners, investors, and procurement leaders, understanding the trajectory of this market is no longer optional—it is a necessity for maintaining competitive advantage. PW Consulting presents our latest comprehensive analysis, designed to equip decision-makers with the actionable intelligence required to navigate the complexities of the Niobium Carbide Market between 2026 and 2032.
Market Trajectory and Economic Outlook
The global Niobium Carbide Market is demonstrating steady resilience, characterized by consistent growth driven by demand in aerospace, defense, and cutting tool industries. Our analysis, grounded in historical data from 2020 through 2025, projects a robust forecast period extending to 2032. The market has evolved from a valuation of approximately 46.5 million USD in 2020 to an anticipated 58.9 million USD in the base year of 2025.
Looking forward, the market is expected to reach 62.43 million USD in 2026, climbing steadily toward 83.69 million USD by 2032. This growth trajectory reflects a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast period. Such stability suggests that while the market is niche, it is insulated from volatile shocks due to the essential nature of niobium carbide in critical applications. However, revenue projections are only the surface layer of our findings. The real value lies in understanding the drivers behind these numbers and the specific segments poised for accelerated expansion.
Structural Segmentation and Material Specifications
The market is not monolithic. It is differentiated by purity levels, physical forms, and application verticals, each carrying distinct margin profiles and supply chain requirements. Our report dissects these segments to reveal where value is being created and where commoditization risks exist.
Purity and Form Factors
Purity remains a primary differentiator in the Niobium Carbide Market. The segmentation spans from 2N purity levels to 5N high-purity grades. Higher purity grades, such as 5N Niobium Carbide, cater to specialized sectors including aerospace and defense, where impurity levels must be minimized to ensure material integrity under extreme conditions. Conversely, lower purity grades find utility in bulk metallurgical applications and carbide alloys where cost efficiency is prioritized over extreme performance characteristics.
In terms of physical form, the market is divided into flakes, powder, and sputtering targets. Powder represents a significant portion of the market volume, driven by its versatility in powder metallurgy and coating processes. Sputtering targets are critical for thin-film deposition in electronics and protective coatings, while flakes serve specific industrial manufacturing needs. Understanding the supply dynamics of each form is essential for manufacturers seeking to secure reliable feedstock without compromising on quality specifications.
Application Verticals
The utilization of Niobium Carbide is concentrated across several key application areas. Carbide alloys constitute a major share, leveraging the material's hardness to enhance the durability of hardmetals used in machining. Coating materials represent another vital segment, where NbC is applied to protect components from wear, corrosion, and high-temperature degradation. Other significant applications include cutting and machining tools, which rely on the material's wear resistance to extend tool life, and metallurgical processes where niobium compounds act as grain growth inhibitors or strengthening agents. Each application vertical faces unique regulatory and technical hurdles that influence market entry barriers and pricing power.
Competitive Landscape and Strategic Positioning
The competitive environment is moderately concentrated, with the top five players holding a significant share of the market, while the top three companies account for over half of the total revenue. This concentration indicates a mature market structure where established players dominate supply chains, but there remains room for specialized entrants focusing on high-purity or niche applications.
Key Industry Players
Several global entities define the current competitive landscape. H.C. Starck Tungsten Powders, based in Germany, is recognized for its high-purity NbC and mixed carbide offerings, specifically tailored for cutting tools and cermets with precise grain size control. Their presence underscores the importance of quality consistency in European manufacturing sectors.
Niobium Carbide Market
CBMM, headquartered in Brazil, stands as a primary producer of niobium-based carbides. Their recent launch of a new high-purity NbC powder line specifically for aerospace and defense applications highlights the trend toward specialized material grades in strategic sectors. This move signals a deeper integration of niobium carbide into supply chains requiring certified high-performance materials.
In the Americas, China Molybdenum Co., Ltd. manufactures niobium carbide products tailored for electronics and high-performance applications, linking the material to the broader technology supply chain. NioCorp Developments Ltd., operating out of Nebraska, is advancing integrated processing for niobium compounds, including carbides, as part of their Elk Creek project. This development is particularly significant given the regulatory environment surrounding domestic production.
Additionally, companies such as American Elements, Edgetech Industries LLC, Ottokemi, and Materion Corporation contribute to the diverse supply base. American Elements focuses on high-purity powder with small grain sizes for advanced applications, while Materion Corporation produces advanced materials for aerospace and industrial uses. Ottokemi and Edgetech ensure supply availability from India and the United States respectively, offering high-purity options with international shipping capabilities. These players collectively ensure that supply meets the varied demands of global industries, though geographic diversification remains a strategic priority for many buyers.
Regulatory Dynamics and Supply Chain Risks
A critical component of our 2026 market research is the analysis of the regulatory framework governing Niobium Carbide. The strategic value of this material is amplified by its designation as a critical mineral by the U.S. Government. This designation triggers specific Department of Defense programs aimed at funding domestic exploration and processing projects. For instance, NioCorp Developments' Elk Creek niobium-scandium-titanium project in Nebraska has received attention within these programs as of early 2026, highlighting the intersection of resource security and industrial policy.
Compliance requirements vary significantly by jurisdiction. In Canada, the Export Control List includes niobium carbide under controlled items for strategic applications, necessitating careful adherence to Global Affairs Canada regulations. In the United States, manufacturers producing niobium carbide products for defense or aerospace applications must comply with International Traffic in Arms Regulations (ITAR). Additionally, the Toxic Substances Control Act (TSCA) requires registration of niobium carbide as a chemical substance with the EPA for U.S. manufacturers. These regulatory layers create a compliance burden that acts as a barrier to entry, reinforcing the position of established players who have the infrastructure to manage such requirements.
Worldwide Nb Alloys Market
On the raw material side, niobium oxide serves as the primary feedstock for niobium carbide production. The global production value of niobium supports downstream processing, meaning that any disruption in niobium mining or refining directly impacts carbide availability and pricing. Strategic planners must monitor upstream commodity trends to anticipate cost fluctuations in the carbide market.
Strategic Implications for 2026 Decision Makers
The data and analysis presented in our full report point to several key strategic imperatives for organizations operating in or adjacent to the Niobium Carbide Market in 2026.
- Supply Chain Resilience: Given the regulatory scrutiny and the concentration of supply among top-tier producers, diversifying sourcing channels is essential. Relying on a single region or supplier exposes firms to geopolitical risks and regulatory delays.
- Compliance Investment: With ITAR, TSCA, and export control regulations in play, compliance is not merely a legal formality but a strategic asset. Companies that streamline regulatory adherence can secure contracts in defense and aerospace more effectively than those that lag.
- Purity-Driven Value Capture: As seen in recent product launches by key players, the premium lies in high-purity grades for specialized applications. Manufacturers capable of delivering 5N purity or specialized grain sizes can command better margins than those competing on volume alone.
- Long-Term Planning: The forecast period extends to 2032, indicating a long investment horizon. Capital allocation decisions made in 2026 regarding production capacity or technology adoption will influence market position for the better part of a decade.
Accessing Comprehensive Market Intelligence
While this overview provides a snapshot of market size, key players, and regulatory dynamics, the full depth of our research offers the granular detail required for execution. Our complete market research report delivers a granular breakdown of revenue shares across regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. It further quantifies the specific market value assigned to each purity level, form factor, and application segment, providing the exact numbers needed for bottom-up forecasting.
Furthermore, the full report includes a detailed competitive benchmarking analysis, assessing the strategic positioning, product portfolios, and recent developments of each key company. It also contains an exhaustive review of regulatory frameworks across multiple jurisdictions, ensuring that your compliance strategy is robust and up-to-date.
For organizations aiming to secure their position in the Niobium Carbide Market, access to this level of detail is indispensable. To download the full report and gain complete access to the segmentation data, historical trends, and forecast models, please visit the PW Consulting research portal. Equip your team with the intelligence needed to navigate 2026 and beyond with confidence.
For detailed analysis of this topic, please visit the official page: Niobium Carbide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railcar Leasing Market Hits $187.5M in 2025, Projects 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Rails: Strategic Intelligence for the 2026 Railcar Leasing Market
Setting the Stage for the Next Decade of Growth
The global railcar leasing market stands at a critical inflection point as we move through 2026. Following a trajectory of steady expansion from 2020 through 2025, the industry is positioned to deliver consistent value creation for investors, operators, and logistical partners over the forecast period extending to 2032. This phase of maturation is not merely about volume growth; it is about strategic alignment, regulatory compliance, and the optimization of asset lifecycles in an increasingly complex geopolitical and economic environment.
Our latest market research provides a comprehensive lens through which stakeholders can view these dynamics. The data indicates a robust baseline, with the overall market revenue reaching significant milestones in recent years and continuing to ascend. The forecast period suggests a compound annual growth rate that underscores the resilience of rail transport as a backbone of industrial logistics. For decision-makers, understanding the velocity of this growth is essential for capital allocation, fleet expansion planning, and risk mitigation strategies.
This article serves as a strategic overview of the insights contained within our full report. It highlights the macroeconomic trends, competitive maneuvers, and regulatory frameworks that will define success in this sector. However, to truly capitalize on these insights, leaders need access to the granular segmentation, specific regional valuations, and detailed operational metrics that only the complete study provides.
Market Trajectory and Macroeconomic Indicators
The historical data from 2020 to 2025 reveals a market that has navigated volatility with remarkable stability. After a slight contraction in the early stages of the forecast window, the sector rebounded strongly, culminating in a substantial revenue base by 2025. Looking forward, the projection from 2026 to 2032 outlines a path of sustained upward momentum.
Our analysis forecasts that the market will continue to expand, driven by the increasing demand for efficient freight transport solutions and the modernization of aging fleets. The revenue projections indicate a clear upward trend, suggesting that railcar leasing will remain a vital component of the broader transportation infrastructure. For enterprises planning long-term investments, aligning with this growth trajectory is paramount. The data suggests that those who position their assets and contracts strategically during this window will secure a competitive advantage as the market matures toward the end of the decade.
Understanding the scale of this opportunity is the first step. The total revenue figures projected for the late 2020s and early 2030s represent a significant expansion from the baseline established in the early 2020s. This growth is not uniform; it is fueled by specific operational needs and regional developments that are dissected in depth within our full report. Stakeholders requiring precise valuation models for their portfolios will find the detailed forecasts indispensable for securing financing and justifying expansion initiatives.
Competitive Landscape and Strategic Maneuvers
The competitive environment in railcar leasing is characterized by a mix of established giants and agile regional specialists. Our research profiles key players who are actively shaping the market through acquisitions, partnerships, and fleet modernization. The concentration of market share among top firms remains a critical metric for understanding barriers to entry and potential consolidation opportunities.
In North America, GATX Corporation continues to solidify its position as a premier leasing company. Based in Chicago, GATX offers diverse tank and freight railcar fleets with comprehensive maintenance support. A significant move in early 2026 saw GATX complete the acquisition of a Wells Fargo rail operating lease portfolio, comprising approximately 101,000 railcars. This strategic acquisition nearly doubled its North American lease fleet, signaling a aggressive push to capture market share and expand asset availability in a key region.
Similarly, TrinityRail, headquartered in Dallas, stands as a leading integrated provider with a vast leased railcar inventory supported by manufacturing and logistics services. Their strategy extends beyond leasing into manufacturing and lifecycle management. A notable development in mid-2026 involved TrinityRail Global acquiring a significant stake in a venture with Touax Group and Texmaco Rail & Engineering Ltd. This partnership aims to form India's first global railcar leasing platform, integrating manufacturing, leasing, financing, and lifecycle management. This move highlights a strategic push into emerging markets and vertical integration.
In Europe, the landscape is equally dynamic. VTG Aktiengesellschaft, based in Hamburg, remains Europe's largest private freight wagon leasing operator, offering modal logistics and digital solutions. Beacon Rail Leasing, operating across 18 European countries from the United Kingdom, provides full-service leasing for locomotives and freight wagons. Meanwhile, RAILPOOL GmbH in Munich focuses on electric locomotives and rail vehicles across 19 countries, emphasizing flexible contracts. EUROWAGON Sp. z o.o., based in Warsaw, specializes in modern freight wagons and intermodal solutions across pan-European regions. These companies illustrate the diverse approaches to fleet management and service delivery that define the European sector.
Container Leasing Market
Our report analyzes how these companies interact, compete, and collaborate. It examines the implications of their recent developments on market pricing, availability, and service standards. For clients evaluating potential partners or competitors, these profiles offer a foundational understanding of the strategic priorities driving the industry leaders.
Operational Dynamics and Regulatory Influence
The operational framework of the railcar leasing market is heavily influenced by regulatory environments that vary significantly by region. These regulations impact manufacturing, content sourcing, and leasing transparency, creating both compliance challenges and strategic opportunities for lessors who can adapt quickly.
In the United States, recent implementation of the Freight Car Safety Standards under the Infrastructure Investment and Jobs Act has introduced strict content requirements. Freight cars manufactured on or after December 19, 2025, face limitations on the percentage of content originating from countries of concern or state-owned enterprises. This limit is set to tighten further by December 19, 2028. Manufacturers and lessors must ensure compliance with these content limitation requirements, excluding sensitive technology components. This regulatory shift necessitates a review of supply chains and procurement strategies for any entity operating within the U.S. general railroad system.
Across the Atlantic, the Office of Rail and Road in the United Kingdom has reviewed the competition remedies in the rolling stock leasing market. Their conclusion reaffirms the appropriateness of the Transparency Order, though updates are recommended to align with legislative changes. This ongoing monitoring ensures that the leasing market remains fit for purpose amid broader rail reform efforts. The requirement for transparency continues to shape how leasing terms are negotiated and reported, influencing strategic planning for lessors operating in the UK and European domains.
These regulatory dynamics are not static; they evolve with geopolitical tensions and domestic policy priorities. Our market research integrates these factors into the broader analysis of market dynamics, helping stakeholders anticipate compliance costs and operational adjustments. Understanding the interplay between regulation and lease duration strategies is crucial for maintaining asset utility and legal standing.
Strategic Value for 2026 Decision Makers
Why does this detailed intelligence matter for your organization in 2026? The answer lies in the ability to move from reactive adjustments to proactive strategy. The railcar leasing market is not just about moving goods; it is about optimizing capital intensity, managing risk, and ensuring supply chain reliability.
For investors, the growth trajectory and competitive consolidation suggest a market ripe for strategic capital deployment. Understanding which segments are driving growth allows for targeted investment in fleets that match demand patterns. For operators, knowing the regulatory landscape helps in planning fleet acquisitions that will remain compliant and operable for the duration of their useful life. For logistics managers, insights into lessor strategies and fleet availability assist in negotiating favorable lease terms and securing reliable transport capacity.
The report digs deeper into application-specific demands, examining how different industries utilize leased railcars. Whether for agricultural transport, industrial and energy sectors, or bulk commodity movement, the requirements for railcar specifications and lease durations vary. Our analysis covers these operational nuances, providing a blueprint for matching fleet assets to end-user needs. This granularity is essential for minimizing downtime and maximizing asset utilization rates.
Furthermore, the geographic distribution of demand plays a pivotal role in strategic planning. While global growth is evident, regional nuances dictate where opportunities are most potent. Understanding the specific market sizes and growth rates across North America, Europe, Asia Pacific, and other regions allows for a balanced portfolio approach. It helps organizations avoid over-concentration in saturating markets while identifying high-potential areas for expansion.
Railcar Leasing Market
Accessing the Full Intelligence
This overview provides a snapshot of the strategic landscape, highlighting the key players, regulatory pressures, and growth trends that define the railcar leasing market today. However, the complexity of the market requires a depth of analysis that goes beyond high-level summaries. To make informed decisions regarding fleet composition, lease structuring, and market entry or expansion, you need the complete dataset and expert analysis contained in our full market research report.
The full study delivers detailed segmentation data, precise revenue projections for specific regions and applications, and an exhaustive examination of the competitive environment. It offers the actionable intelligence necessary to build robust business cases, negotiate from a position of strength, and anticipate market shifts before they become industry-wide trends.
We invite you to explore the comprehensive findings of our Railcar Leasing Market study. By accessing the full report, you will equip your leadership team with the precise tools needed to navigate the complexities of 2026 and beyond. Ensure your strategy is built on data, not assumptions. Visit our source page to download the complete intelligence and secure your organization's position in the evolving rail economy.
For detailed analysis of this topic, please visit the official page: Railcar Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Serial Device Server Market to Reach $317.3M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Beyond Connectivity: Unlocking Strategic Value in the Serial Device Server Market (2026–2032)
The Critical Infrastructure Layer in a Legacy-Heavy World
Serial device servers sit at the intersection of legacy industrial hardware and modern IP networks—a position that makes them indispensable for enterprises managing brownfield automation, remote telemetry, and multi-vendor equipment integration. As industries accelerate their transition toward secure, centralized, and cloud-ready architectures, the devices that bridge RS-232, RS-422, and RS-485 endpoints to Ethernet and Wi-Fi backbones are experiencing sustained demand. Our newly released Serial Device Server Market research provides a comprehensive commercial and technical intelligence layer designed to inform capital allocation, product roadmap decisions, and competitive positioning through 2032.
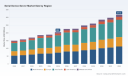
The market’s trajectory reflects a structural shift rather than a temporary cycle. Revenue reached an estimated 205.0 million USD in the base year of 2025, up from approximately 188.99 million USD in 2024 and 185.99 million USD in 2023, following a consistent upward path from 150.0 million USD in 2020. This growth curve underscores the durability of serial-to-Ethernet conversion in industrial control, data acquisition, remote management, and point-of-sale ecosystems, even as IT departments invest heavily in all-IP alternatives. The forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5 percent, with total revenue anticipated to rise from roughly 225.84 million USD in 2026 to 317.3 million USD by 2032. These figures are not merely projections—they form the foundation for capacity planning, vendor negotiation, and risk-adjusted investment strategies.
For decision-makers navigating procurement cycles, product development, or market entry, this research delivers what high-level summaries cannot: a granular view of demand drivers, technology migration patterns, regulatory touchpoints, and the competitive behaviors shaping pricing, feature sets, and channel influence. The analysis is deliberately structured to support executive-level prioritization while preserving the depth required by engineering, supply chain, and regulatory teams.
Structural Demand Drivers: Why Serial Device Servers Remain Strategically Resilient
A central theme emerging from our analysis is the persistence of serial protocols in environments where reliability, determinism, and cost-effective interoperability outweigh the pull of full IP replacement. Industrial control systems, data acquisition networks, remote management deployments, and point-of-service infrastructure all rely on serial interfaces for legacy compatibility, field-hardened performance, and simplified wiring topologies. Rather than displacing these devices, modernization initiatives are increasing their strategic value by demanding secure gateways, centralized fleet management, and protocol-agnostic bridging.
Several dynamics are reinforcing this demand profile. First, the coexistence of operational technology and information technology stacks means that serial endpoints must be integrated into network architectures without disrupting uptime or requiring wholesale equipment replacement. Second, security expectations have evolved from basic connectivity to encrypted serial-to-IP tunnels, centralized authentication, and audit-ready management interfaces. Third, environmental and transportation-grade certifications are becoming gating factors in bidding processes for public infrastructure, manufacturing automation, and outdoor telemetry deployments. These factors collectively elevate the serial device server from a simple connectivity add-on to a programmable gateway component within broader edge networks.
The research also examines how network infrastructure economics influence deployment velocity. Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in serial device server network deployments, which means total cost of ownership is shaped not only by the gateway hardware itself, but by the surrounding physical layer, cabling, and integration labor. This reality has important implications for procurement strategy, vendor bundling, and the evaluation of modular platforms such as SFP-based hot-swappable designs that can delay or reduce physical-layer reinvestment.
Market Size, Growth Trajectory, and What the Numbers Really Signal
The macro-level trajectory provides a reliable anchor for strategic planning. After expanding from 158.23 million USD in 2021 and 170.18 million USD in 2022, the market crossed the 185 million USD threshold in 2023 and continued its ascent to 205.0 million USD in 2025. The short-term forecast indicates 225.84 million USD in 2026, followed by a slight moderation in year-over-year momentum before resuming steady growth to 227.25 million USD in 2027, 248.41 million USD in 2028, 260.47 million USD in 2029, 285.73 million USD in 2030, 298.04 million USD in 2031, and 317.3 million USD in 2032.
For strategy teams, the more important takeaway is the shape of this curve. The data suggests a market that is not only growing but maturing in its demand patterns: growth is increasingly tied to secure management, ruggedized industrial form factors, modular network compatibility, and certification readiness. Companies that treat serial device servers as commoditized pass-through hardware risk underpricing value-added features and missing higher-margin opportunities in industrial automation, remote fleet management, and hazardous-location deployments. Conversely, organizations that align product roadmaps with the specific integration requirements of brownfield environments can capture disproportionate share in segments where interoperability and compliance create meaningful barriers to substitution.
Our research deliberately avoids oversimplified regional or application-level breakdowns in this overview because the strategic value lies in how those segments interact with pricing, certification requirements, and channel dynamics. The full report details how demand clusters across geographies and application types, which subsegments are growing fastest in absolute and relative terms, and where saturation risk or substitution pressure is most likely to emerge.
Competitive Landscape: Differentiated Platforms in a Concentrated Environment
Market concentration provides an early signal of competitive intensity. The three largest players account for approximately 52.8 percent of revenue, while the five largest reach about 64.7 percent. This distribution indicates a market with established incumbents, meaningful product differentiation, and room for specialized challengers that compete on security, ruggedization, or form-factor innovation. Understanding how the leading vendors position their offerings is essential for both competitive benchmarking and partnership evaluation.
Pepperl+Fuchs, headquartered in Mannheim, Germany, emphasizes serial device server solutions aimed at industrial automation and transportation integration. Its ICDM-RX/TCP series delivers DIN-rail mounted RS-232/422/485 to Ethernet conversion with TCP/UDP socket services, and the inclusion of NEMA TS2 certification options expands its relevance for transportation-grade and industrial Ethernet environments. A product update in August 2025 extended this family with additional NEMA TS2 certification options, reinforcing the company’s focus on compliance-sensitive deployments.
Comtrol, operating as Pepperl+Fuchs Comtrol with headquarters in Twinsburg, Ohio, USA, focuses on secure serial-to-IP gateways. The DeviceMaster PRO/RTS/Serial Hub family supports COM/TTY/TCP configurations and has been strengthened with enhanced SSL/SSH encryption. In March 2025, the company updated the series with SSL/SSH management and serial data stream encryption for secure serial-to-IP connectivity, a move that reflects rising security expectations in industrial and enterprise edge contexts.
Digi International, based in Minneapolis, Minnesota, USA, continues to position its Digi Connect EZ TS and Connect SP series as secure serial device servers for legacy-to-IP conversion. The portfolio’s RealPort drivers and centralized management capabilities support organizations seeking to standardize remote access and device administration across distributed installations. In May 2026, Digi launched Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management for modern IP network transitions, signaling continued investment in fleet management and migration-friendly architectures.
Moxa, headquartered in Taipei, Taiwan, targets industrial RS-232/422/485 to Ethernet conversion with the NPort 5100/5110 and IA5000 series. These platforms emphasize surge protection and hazardous-location certifications, making them relevant for demanding field environments. A February 2025 update improved the NPort IA5000-G2 DIN-rail and IA5000A industrial series with enhanced surge protection for hazardous environments, reinforcing Moxa’s focus on durability and compliance in industrial settings.
Advantech, also based in Taipei, Taiwan, offers the EKI-1521/1522/1524 series of industrial Ethernet/serial device servers with virtual COM support and LAN redundancy. This positioning speaks to customers who prioritize operational resilience, seamless device emulation, and network failover in automation and control environments.
Patton, headquartered in Gaithersburg, Maryland, USA, introduced a notable infrastructure-oriented product in April 2025 with the launch of the Connect-IT CIT-SFP SFP-based hot-swappable RS-232/422/485 serial device server for legacy-to-IP bridging. The SFP-based approach addresses network flexibility and physical-layer economics by enabling modular fiber or copper connectivity without full hardware replacement, an increasingly important consideration as deployment costs are scrutinized.
Silex Technology, based in Tokyo, Japan, provides the SD-300/SD-320 series of wired and wireless RS-232 serial device servers for Ethernet and Wi-Fi network connectivity. This wireless extension broadens the addressable use cases for serial endpoints where cabling constraints or temporary deployments make Wi-Fi connectivity advantageous.
Sealevel Systems, headquartered in Liberty, South Carolina, USA, focuses on the SeaLINK series of Ethernet serial servers supporting up to 16 RS-232/422/485 ports for industrial data acquisition and control systems. The multi-port architecture is particularly relevant for centralized monitoring and control applications that must aggregate many serial endpoints without proliferating gateway devices.
PLANET Technology, also headquartered in Taipei, Taiwan, offers the ICS-2100T/2200T/2400T series of industrial 1/2/4-port RS-232/422/485 to Fast Ethernet serial device servers with wide-temperature operation. This wide-temperature capability supports deployment in environments where thermal extremes would disqualify commercial-grade hardware.
The competitive picture is not just about product portfolios; it is about how vendors translate certification readiness, security, modularity, and environmental hardening into defensible pricing and customer lock-in. The research maps these positioning strategies and identifies the operational implications for buyers evaluating total cost of ownership, support requirements, and lifecycle compatibility.
Regulatory, Certification, and Deployment Dynamics That Shape Commercial Outcomes
Regulations and certifications are not side conditions; they are commercial gating factors that influence bid eligibility, deployment timelines, and regional expansion feasibility. In the United States, all active manufacturers of serial device server products must comply with FCC Part 15 rules for unintentional radiators to prevent harmful interference, a requirement that can affect design choices, testing cycles, and market entry sequencing. In the European Economic Area, serial device server equipment sold into the market requires CE marking under relevant EMC and safety directives, adding conformity assessment obligations that influence product planning and documentation.
Serial Device Server Market
Safety and industrial-use certifications further shape procurement and engineering decisions. Industrial serial device server models are commonly UL 61010-1 listed for safety in laboratory and industrial use, an assurance that matters in environments where equipment must meet recognized electrical safety standards. For transportation and public infrastructure applications, NEMA TS2 certification addresses spectrum and environmental compliance requirements, making it a strategic differentiator for vendors pursuing bids in transit and municipal deployments.
Together, these regulatory and certification layers contribute to a market in which product compliance is a source of competitive advantage rather than a back-office task. The report integrates these dynamics into the broader analysis of market behavior, showing how certification roadmaps, testing lead times, and regional conformity requirements interact with product launches, distributor selection, and customer segment prioritization.
What the Report Delivers: Operational Intelligence for 2026 Decisions
This research is designed as a decision-support instrument rather than a static market summary. It combines market sizing and growth projections with actionable qualitative analysis across segmentation, competitive behavior, and deployment dynamics. The core deliverable includes a structured assessment of external and embedded serial device server categories, an exploration of application-side demand patterns across industrial control systems, data acquisition, remote management, point-of-sale systems, and other use cases, and a detailed view of regional demand distribution without reducing the analysis to simplistic percentage tables.
Beyond segmentation, the report examines product evolution patterns, including secure serial-to-IP gateways, DIN-rail industrial form factors, multi-port aggregation platforms, SFP-based hot-swappable bridging, wide-temperature operation, surge protection for hazardous environments, and wireless serial connectivity. It also addresses the commercial significance of centralized management, virtual COM compatibility, LAN redundancy, RealPort-style driver ecosystems, and encryption frameworks such as SSL/SSH. These feature dimensions are analyzed in relation to pricing architecture, differentiation potential, and customer acceptance in regulation-sensitive or environment-sensitive deployments.
Competitive analysis extends beyond product descriptions to include launch timing, update cadence, and strategic intent. Recent developments illustrate how the market is evolving: Patton’s April 2025 launch of the CIT-SFP SFP-based hot-swappable serial device server for legacy-to-IP bridging; Digi International’s May 2026 launch of Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management; Comtrol’s March 2025 update to the DeviceMaster PRO/RTS series with SSL/SSH management and serial data stream encryption; Pepperl+Fuchs’ August 2025 extension of the ICDM-RX/TCP family with NEMA TS2 certification options; and Moxa’s February 2025 update to the NPort IA5000-G2 and IA5000A series with enhanced surge protection for hazardous environments. These events are not isolated product news; they reflect broader strategic bets on security, modularity, ruggedization, and compliance-enabled market access.
How to Use This Research for 2026 Planning
For executives and analysts, the report offers a practical framework for several high-stakes decisions. Procurement leaders can use the segmentation and competitive analysis to structure vendor evaluations around security, management, ruggedization, and certification readiness rather than unit price alone. Product and engineering teams can reference the technology migration patterns to prioritize virtual COM, centralized management, encryption, and modular network compatibility in roadmaps. Business development teams can identify where certification requirements and environmental hardening create entry barriers that protect incumbents or where wireless and multi-port platforms open new addressability. Risk and compliance teams can integrate FCC Part 15, CE marking, UL 61010-1, and NEMA TS2 considerations into market-entry and sourcing plans with a clearer view of lead times and documentation requirements.
The analysis also supports scenario planning by connecting market growth, concentration levels, and infrastructure cost realities to potential shifts in pricing, bundling, and channel influence. Because Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in network deployments, total project economics often depend on how serial device server platforms align with existing or planned physical-layer investments. The report provides the context needed to evaluate whether modular, hot-swappable, or multi-port solutions offer better lifecycle economics in specific deployment profiles.
Conclusion: From Market Data to Decision Advantage
The Serial Device Server Market is growing within a 6.5 percent CAGR framework and is projected to move from 225.84 million USD in 2026 to 317.3 million USD by 2032, but the strategic opportunity lies in understanding why that growth is happening, where value is being captured, and how competitive and regulatory forces shape customer choices. This research translates those dynamics into an actionable intelligence base for procurement, product strategy, market entry, and competitive positioning.
SerDes Market
The overview above establishes the analytical direction and the breadth of coverage, while the full report provides the structured detail required to support discrete decisions across regions, applications, product types, and competitive scenarios. For teams preparing for 2026 planning cycles, the complete analysis offers the missing layer between high-level market narratives and operational execution—enabling more confident capital allocation, vendor selection, and roadmap prioritization in a market where connectivity, compliance, and industrial reliability all converge.
For detailed analysis of this topic, please visit the official page: Serial Device Server Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heart Defect Closure Devices Market to Hit $344.8M by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for 2026: Navigating the Heart Defect Closure Devices Market Landscape
In the rapidly evolving landscape of structural heart interventions, the market for heart defect closure devices represents a critical nexus of clinical innovation, regulatory dynamics, and commercial opportunity. As we move through 2026, healthcare providers, investors, and competitive strategists require a granular understanding of where value is being created, how regulatory frameworks are reshaping market access, and which technological trajectories will define the next wave of growth. This executive briefing serves as an introduction to PW Consulting's comprehensive market research report on the Heart Defect Closure Devices Market, designed to equip leadership teams with the actionable intelligence necessary for robust strategic planning.
The Macro Trajectory: Growth Foundations and Forecast Horizon
Understanding the scale and momentum of this market is the foundational step for any strategic assessment. The industry has demonstrated consistent resilience and expansion over the recent historical period. Analyzing performance from 2020 through the base year of 2025 reveals a market that has steadily climbed in revenue terms, reflecting the increasing adoption of minimally invasive percutaneous solutions over traditional surgical approaches. This historical expansion sets the stage for a forecast period extending from 2026 through 2032, where the market is projected to continue its upward trajectory.
Our analysis indicates a compound annual growth rate (CAGR) of approximately 6.98 percent across the forecast horizon. This growth rate suggests a mature yet expanding market, driven by factors such as the rising prevalence of congenital heart defects, an aging population requiring interventions for conditions like patent foramen ovale, and continuous advancements in device delivery systems and materials. By the end of the forecast period in 2032, the total revenue size is anticipated to reach significant milestones, underscoring the enduring commercial relevance of this therapeutic area. For stakeholders, this macro view provides the essential context for evaluating pipeline investments, capacity planning, and long-term market entry strategies. The revenue unit is tracked in USD Millions, offering a standardized metric for global comparison and financial modeling.
The Strategic Value of Granular Segmentation in 2026 Decision-Making
While the top-line figures establish the market's magnitude, the true strategic leverage lies in dissecting the market across its dimensional layers. Our research delves deep into the segmentation architecture, categorizing the market by device type, clinical application, and geographic footprint. This multi-dimensional approach allows organizations to move beyond generic growth narratives and identify specific pockets of opportunity or vulnerability.
For device manufacturers and investors, understanding the breakdown by device type—encompassing atrial septal defect (ASD) closure devices, patent ductus arteriosus (PDA) closure devices, and ventricular septal defect (VSD) closure devices—is crucial for portfolio prioritization. The dominance of certain segments often reflects clinical preferences, reimbursement landscapes, and the concentration of specific patient populations. Our report quantifies these internal dynamics, revealing which device categories are driving the bulk of revenue and which are emerging as high-growth niches due to technological breakthroughs or unmet clinical needs.
Similarly, the segmentation by clinical application provides a lens into the therapeutic drivers. The market encompasses congenital heart defect closure, patent foramen ovale closure, and left atrial appendage closure, among other applications. Each application area carries distinct regulatory pathways, procedural volumes, and competitive intensities. For instance, the dynamics in PFO closure have been heavily influenced by recent regulatory shifts and guideline updates, while left atrial appendage closure continues to evolve alongside anticoagulant alternatives. Our analysis pinpoints the revenue contribution of each application, helping strategists align product development and marketing resource allocation with the most potent clinical demand signals.
Geographically, the market exhibits distinct regional characteristics. We examine performance across key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Regional analysis is indispensable for global players assessing market penetration barriers, reimbursement variability, and the impact of local manufacturing or distribution partnerships. The data unpacks the relative weight of each region, highlighting where volume is concentrated and where growth rates may diverge from the global average due to healthcare infrastructure development or policy changes. This regional granularity enables precise tailoring of go-to-market strategies and risk mitigation plans for each territorial unit.
Regulatory Currents and Industry Dynamics Shaping Competitive Advantage
The regulatory environment acts as a powerful force multiplier in this market, influencing product lifecycles, competitive positioning, and speed to revenue. Recent years have witnessed significant activity within the FDA and other global regulatory bodies, particularly regarding Premarket Approval (PMA) pathways for structural heart devices. Our report integrates these regulatory milestones into the strategic narrative, demonstrating how approvals and clearances create windows of opportunity for innovators and disruptors.
A notable example of regulatory-driven market dynamics involves the recent PMA approvals for Occlutech Holding AG's ASD Occluder and Pistol Pusher system. Following the FDA's approval on December 29, 2023, and the subsequent commercialization efforts that accelerated in 2024, Occlutech has entered a phase of active US market implementation. The execution of the first commercial US cases in mid-2024 marks a critical inflection point, validating the device in the world's largest medical device market and establishing a foothold through exclusive partnerships, such as the collaboration with B. Braun Interventional Systems. This sequence of events illustrates how targeted regulatory success can rapidly translate into commercial traction, altering the competitive equilibrium.
The landscape is further defined by the ongoing presence and evolution of established players. Abbott Laboratories continues to leverage its Amplatzer line, with the Talisman PFO Occluder maintaining a prominent position following its 2021 approval. Additionally, recent clearances, such as the Abbott Amplatzer Piccolo Delivery System cleared in late 2025 for use with congenital heart defect closure devices, highlight continuous innovation in delivery mechanics that can enhance procedural efficacy and user adoption. Meanwhile, W. L. Gore & Associates maintains a relevant footprint with the GORE CARDIOFORM series for ASD and PFO closure, although the discontinuation of the GORE HELEX Septal Occluder underscores the iterative nature of product portfolios where legacy devices may be phased out in favor of next-generation solutions.
Analysis of current medical policy frameworks, such as those from Blue Cross Blue Shield of North Carolina in August 2025, confirms the specific devices currently marketed for PFO and ASD closure. This regulatory snapshot serves as a vital reference for understanding the eligible product set and the reimbursement environment that governs patient access. Strategists must monitor these policy documents closely, as they can dictate the commercial viability of devices within specific health systems and payer networks. Our report contextualizes these regulatory facts within broader industry trends, helping clients anticipate how policy changes might affect their product pipelines or competitor pipelines.
Competitive Architecture: Incumbents, Challengers, and Strategic Positioning
The competitive landscape of the heart defect closure devices market is characterized by a mix of global medtech giants and specialized players with deep clinical focus. Our comprehensive profiling of key companies provides a detailed view of the strengths, headquarters, and strategic focus areas of the major participants shaping the market.
Abbott Laboratories, headquartered in Chicago, Illinois, stands as a pivotal force with its extensive Amplatzer family of septal occluders. Their portfolio covers ASD, PFO, and VSD closure, representing a broad-based capability that addresses multiple defect types. Abbott's ability to integrate device innovation with delivery system advancements creates a holistic value proposition for interventional cardiologists and surgeons.
W. L. Gore & Associates, based in Flagstaff, Arizona, contributes with its GORE CARDIOFORM Septal Occluder and GORE CARDIOFORM ASD Occluder. These devices are specifically engineered for percutaneous closure of ostium secundum ASD and PFO, reflecting a targeted design philosophy focused on conformability and deliverability. The presence of Gore in this segment introduces a competitive alternative to traditional nitinol-based devices, appealing to clinicians seeking specific performance characteristics.
Occlutech Holding AG, headquartered in Schaffhausen, Switzerland, represents a dynamic challenger that has successfully navigated rigorous regulatory pathways. With FDA PMA approval for its ASD Occluder and Pistol Pusher, Occlutech has demonstrated the ability to bring novel transcatheter solutions to the US market. Their Figulla Flex series and specialized delivery tools indicate a focus on refining procedural control and device placement accuracy. The recent commercial implantation milestones in the US highlight their trajectory from regulatory clearance to real-world utilization.
Medtronic plc, with its global headquarters in Dublin, Ireland, brings the weight of a diversified structural heart portfolio. The CardioFlex ASD closure device and related occluders position Medtronic to capture volume across congenital heart defect closure indications. Medtronic's infrastructure and commercial reach provide significant advantages in distribution, physician education, and market coverage.
Boston Scientific Corporation, located in Marlborough, Massachusetts, offers structural heart occlusion systems and portfolio products addressing ASD and related defects. As a major player in the broader interventional cardiology space, Boston Scientific's involvement brings cross-portfolio synergies and a robust sales network capable of supporting device adoption.
From the Asia Pacific region, Lifetech Scientific Corporation in Shenzhen, China, and Lepu Medical Technology in Beijing, China, represent growing manufacturers with portfolios including the Lifestar line and various septal occluders for ASD, PFO, and VSD closure. These companies highlight the increasing innovation and manufacturing capacity emerging from China, which can influence global pricing dynamics and provide alternatives in cost-sensitive markets. Their presence also underscores the importance of monitoring non-US/EU competitors who are expanding their international footprints.
The market concentration data further illuminates the competitive structure. With a CR3 of approximately 24.6 percent and a CR5 of roughly 26.2 percent, the market does not exhibit extreme oligopolistic concentration. This relatively fragmented top-tier concentration suggests that while major players hold significant share, there is room for specialized entrants and regional players to compete effectively. It also implies that competitive advantage often derives from product differentiation, clinical evidence, regulatory agility, and strategic partnerships rather than pure scale dominance. Our report analyzes these concentration metrics to help firms assess the intensity of rivalry and the potential for market share erosion or consolidation.
Heart Defect Closure Devices Market
Inside the Report: Actionable Frameworks for Execution
This market research report is designed not merely as a repository of data points but as a strategic toolkit for execution. The report contents are structured to guide decision-makers through complex choices with clarity and confidence. Beyond the quantitative segmentation, the document provides qualitative assessments of market drivers, restraints, and opportunities. We analyze the factors accelerating adoption, such as the shift toward minimally invasive procedures, improvements in device safety profiles, and the expansion of eligible patient populations. Simultaneously, we identify headwinds, including reimbursement uncertainties, the learning curve associated with new delivery systems, and the competitive pressure from emerging technologies.
The report also incorporates a detailed examination of the value chain, mapping the roles of manufacturers, distributors, healthcare providers, and regulatory bodies. This holistic view enables clients to identify leverage points within the ecosystem. For example, understanding the nuances of FDA PMA requirements versus CE marking processes can inform product launch sequencing and resource allocation for regulatory affairs teams. Insights into recent industry developments, such as the specific timelines of Occlutech's US commercialization or Abbott's delivery system clearances, are synthesized to reveal patterns in how innovation translates to market share.
Worldwide Hernia Mesh Devices Market
Strategic frameworks within the report assist in evaluating potential M&A targets, assessing partnership opportunities, and benchmarking internal performance against market leaders. The inclusion of company profiles allows for direct comparison of product portfolios, geographic coverage, and strategic moves. By integrating the regulatory context with competitive analysis, the report helps organizations anticipate competitor responses to market shifts and prepare counter-strategies. Whether the objective is entering a new geographic market, launching a new device variant, or defending existing market share, the insights provided are tailored to support those specific use cases.
Conclusion: Securing Strategic Advantage in 2026 and Beyond
The heart defect closure devices market is at a juncture where clinical innovation, regulatory evolution, and competitive maneuvering converge to create significant strategic implications. For organizations operating in or adjacent to this space, the ability to make informed decisions quickly is a critical differentiator. The macro trends indicate sustained growth, but the distribution of that growth across segments, applications, and regions requires deep analysis to exploit effectively.
Regulatory milestones, such as the recent FDA approvals and clearances, are reshaping the roster of available devices and influencing payer policies. Companies that can navigate these pathways efficiently and bring differentiated products to market stand to gain substantial rewards. The competitive landscape, with its mix of global leaders and agile specialists, demands a nuanced understanding of where each player is positioned and how they are likely to move. Market concentration levels suggest that innovation and execution can outweigh sheer size in capturing value.
PW Consulting's comprehensive report offers the depth and precision required to thrive in this environment. It transforms raw data and industry observations into a coherent strategic narrative, empowering leadership teams to align their resources, mitigate risks, and capitalize on emerging opportunities. To access the full suite of segmentation data, detailed forecasts, competitor intelligence, and actionable recommendations, we invite you to explore the complete market research report. The complete intelligence package is essential for building a resilient strategy that delivers results in the dynamic years ahead.
For detailed analysis of this topic, please visit the official page: Heart Defect Closure Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LGF-PP Market Hits $7.67B in 2025, Projects 6.8% CAGR to $11.12B by 2032
By PW Consulting, 2026-09-16
Navigating the Long Glass Fiber Reinforced Polypropylene Landscape: Strategic Intelligence for 2026 and Beyond
Executive Overview
The long glass fiber reinforced polypropylene market stands at a critical inflection point. As manufacturers across automotive, aerospace, electrical, construction, and consumer goods sectors confront tightening emissions standards, escalating raw material volatility, and an accelerating demand for lightweight structural materials, the ability to make data-driven decisions has never been more consequential. Our latest Long Glass Fiber Reinforced Polypropylene Market report delivers a comprehensive, forward-looking intelligence framework designed specifically to equip executives, procurement leaders, and strategy teams with the analytical rigor required to navigate 2026 and the decade ahead.
Drawing on a five-year historical baseline spanning 2020 through 2025 and a robust seven-year forecast horizon extending to 2032, this research translates macro-level market trajectories into actionable strategic guidance. The global market, valued at approximately 5,745.2 million USD in 2020, has demonstrated a consistent upward trajectory, reaching an estimated 7,674.32 million USD by 2025. Looking ahead, the analysis projects a compound annual growth rate of 6.8 percent through 2032, positioning the sector for sustained expansion as material performance advantages converge with regulatory tailwinds and manufacturing innovation. This article outlines the strategic architecture of our research, previews the analytical dimensions that will inform your 2026 planning cycles, and demonstrates why this intelligence is indispensable for organizations seeking to capture growth, mitigate risk, and secure competitive advantage.
Market Trajectory and Forecasting Architecture
Our forecasting methodology is built on a multi-layered analytical foundation that integrates historical revenue patterns, demand elasticity modeling, supply-side capacity tracking, and scenario-based macroeconomic adjustments. The historical dataset captures the market's evolution through periods of raw material price fluctuation, shifting end-use demand, and regional manufacturing realignments. By anchoring projections to this empirically validated baseline, our forecast framework isolates growth drivers from transient market noise, enabling readers to distinguish between structural expansion and cyclical variation.
The 2026 to 2032 forecast period is segmented into phased growth trajectories that reflect the interplay of technological adoption curves, regulatory implementation timelines, and regional manufacturing capacity expansion. Rather than presenting a single linear projection, our analysis maps multiple demand pathways, allowing decision-makers to stress-test their strategies against divergent macroeconomic and policy environments. This approach is particularly valuable in a market where material substitution dynamics, automation-driven production efficiencies, and cross-industry application migration continuously reshape competitive positioning.
Segmentation Analysis: Navigating Application and Type Dynamics
Understanding where growth concentrates and how performance requirements diverge across end-use sectors is essential for resource allocation and product development prioritization. Our segmentation analysis dissects market demand across major application verticals, examining how structural performance thresholds, cost constraints, and regulatory mandates shape adoption patterns. Automotive structural components continue to represent a substantial share of demand, driven by the imperative to reduce vehicle weight while maintaining crashworthiness, fatigue resistance, and dimensional stability. Aerospace and electrical and electronics applications introduce distinct performance criteria, where thermal stability, electrical insulation properties, and long-term durability under stress become primary selection factors. Construction and consumer goods segments further illustrate the material's versatility, though each vertical presents unique procurement cycles, certification requirements, and price sensitivity profiles.
On the type dimension, the market splits between continuous fiber and chopped fiber configurations, each serving different engineering objectives. Continuous fiber architectures deliver superior tensile strength and stiffness, making them the preferred choice for load-bearing structural replacements where metal displacement is the strategic goal. Chopped fiber formulations offer distinct processing advantages, balancing mechanical reinforcement with manufacturing flexibility, shorter cycle times, and enhanced surface finish characteristics. Our research maps how these type-level preferences interact with application-specific performance requirements, production volume scales, and regional manufacturing capabilities, providing a granular view of where each configuration is likely to gain or lose share over the forecast horizon.
Regional Dynamics and Demand Localization
Geographic demand distribution reflects the interplay of industrial base maturity, regulatory environments, automotive production footprints, and infrastructure development cycles. North America and Europe maintain strong demand foundations, supported by established automotive supply chains, stringent emissions frameworks, and advanced manufacturing ecosystems. Asia Pacific represents a dynamic growth engine, characterized by expanding production capacity, diversifying end-use adoption, and increasing localization of compound manufacturing. Latin America and the Middle East and Africa markets continue to evolve, with demand trajectories influenced by infrastructure investment patterns, cost-competitive manufacturing shifts, and gradual adoption of advanced polymer composites in regional automotive and industrial applications.
Rather than relying on static regional snapshots, our analysis tracks how cross-border supply chain reconfigurations, tariff environments, and localized content requirements reshape regional demand pathways. This geographic intelligence is critical for organizations evaluating production footprint decisions, inventory positioning, and market entry or expansion strategies in 2026 and beyond.
Competitive Landscape and Strategic Positioning
The market's competitive structure is defined by a concentrated core of global polymer and compound manufacturers, complemented by specialized providers with deep application engineering expertise. With a combined market share held by the top three players reaching 59.0 percent and the top five firms accounting for 70.0 percent, the landscape rewards scale, technical differentiation, and long-term customer integration. Our competitive analysis examines how leading organizations leverage proprietary resin formulations, fiber impregnation technologies, and application-specific grading systems to secure positioning in high-value structural and technical segments.
SABIC has built a strong footprint through its STAMAX LGF PP resin platform, targeting automotive lightweighting and structural performance applications where consistent mechanical properties and process reliability are paramount. BASF SE advances its position through the Ultramid portfolio, delivering long glass fiber reinforced polypropylene solutions tailored for demanding technical applications that require precise control over fiber-matrix interaction and thermal performance. LyondellBasell Industries N.V. contributes to the competitive mix by supplying polypropylene compounds that integrate proprietary resin architectures with long glass fiber grades, serving automotive and structural use cases that demand balanced cost-performance profiles.
Japan Polypropylene Corporation distinguishes itself through proprietary melt impregnation processes, delivering FUNCSTER and WAYMAX compound platforms that emphasize fiber dispersion quality and mechanical consistency. RTP Company focuses on custom compound engineering, aligning its long glass fiber reinforced polypropylene offerings with specific automotive compliance requirements across major OEMs, including GM, Stellantis, Tesla, and Ford. Avient Corporation supports structural replacement strategies through its OnForce composite line, targeting high-stiffness applications where weight reduction and mechanical reliability intersect. Celanese Corporation extends the competitive field through Celstran grades, positioning long glass fiber reinforced polypropylene within broader engineered polymer portfolios for automotive and industrial applications. Mitsui Chemicals, Inc. reinforces its regional and global reach by producing long glass fiber reinforced polypropylene across facilities in Japan, the United States, and China, enabling supply chain flexibility and localized customer support.
Long Glass Fiber Reinforced Polypropylene Market
Our report moves beyond corporate profiles to examine how these players compete on technology differentiation, customer co-development, capacity utilization, and regional supply commitments. The analysis identifies where consolidation pressure may intensify, where niche specialization can defend margin, and how integrated material solutions are reshaping sourcing relationships across end-use industries.
Regulatory Tailwinds and Macroeconomic Dynamics
Regulatory frameworks are accelerating material substitution decisions across multiple industries, and long glass fiber reinforced polypropylene is directly benefiting from emissions-driven lightweighting mandates. In the European Union, the 2019/631 directive established average CO2 emission targets of 93.6 grams per kilometer by 2025, creating immediate incentives for weight reduction in structural automotive components. This trajectory extends further with the EU's requirement for a 55 percent CO2 reduction by 2030 compared to 2021 levels, reinforcing the strategic relevance of high-performance polymer composites in vehicle architecture planning. In the United States, EPA standards calling for an average fleet CO2 reduction to 162.5 grams per mile by 2030 are driving similar adoption patterns in North American automotive underbody and structural applications.
Worldwide Reinforced Polypropylene Material Market
Alongside regulatory momentum, raw material price dynamics play a decisive role in cost modeling and margin management. Recent industry data indicates that glass fiber prices in the United States reached approximately 1,458 USD per metric ton in December 2025, trending lower as domestic construction demand eased in the fourth quarter. Meanwhile, broader resin pricing pressures have emerged in other regions; in the United Kingdom, propylene price increases pushed compounded PP resin prices higher throughout the first quarter of 2025, with increases holding steady across the period. These dynamics underscore the importance of anticipatory procurement strategies, flexible sourcing frameworks, and scenario planning that accounts for commodity volatility, energy cost shifts, and regional supply imbalances.
Our report integrates these regulatory and input-cost signals into a unified market dynamics framework, helping organizations translate policy mandates and price movements into concrete procurement, pricing, and product development decisions.
What the Report Delivers: Operational Intelligence for Decision-Makers
This research is designed as an operational decision-support tool rather than a static market summary. It provides structured analytical modules that can be directly applied to strategic planning, investment prioritization, and competitive positioning. Key deliverables include:
- A full historical and forecast revenue timeline that maps market growth across multiple horizons, enabling baseline validation and scenario modeling.
- Segment-level demand analysis that connects application requirements and fiber type preferences to volume trajectories and performance-driven adoption patterns.
- Regional demand and supply assessments that illuminate manufacturing localization trends, capacity expansions, and cross-border trade dynamics.
- Competitive benchmarking that evaluates technology differentiation, product portfolio breadth, and market share concentration among leading global and regional players.
- Regulatory and macroeconomic impact mapping that ties emissions mandates, raw material pricing trends, and policy implementation timelines to material demand pathways.
- Strategic implication frameworks that help leadership teams assess sourcing risks, capacity planning needs, and market entry or expansion opportunities in 2026 and beyond.
Each section is structured to support both board-level strategic review and operational planning functions. The report is intended for use by executives evaluating portfolio direction, product managers developing next-generation compound grades, procurement teams modeling cost and supply resilience, and analysts building market entry or competitive response strategies.
Strategic Imperatives for 2026 Planning
As organizations move into 2026 planning cycles, several strategic priorities will determine whether they capture growth or risk being outpaced by more agile competitors. First, aligning product development roadmaps with regulatory-driven lightweighting mandates will be essential, particularly in automotive and aerospace applications where emissions targets continue to tighten. Second, building pricing and sourcing resilience against raw material volatility requires anticipatory procurement models that incorporate regional price trends, supplier diversification, and inventory optimization. Third, competitive differentiation will increasingly depend on application engineering capabilities, co-development relationships with OEMs, and the ability to deliver consistent fiber dispersion and mechanical performance at scale.
Fourth, geographic strategy must account for shifting manufacturing footprints and localized content expectations, especially in regions where capacity expansion and supply chain reconfiguration are reshaping demand access. Finally, organizations that integrate macroeconomic scenario planning into their material strategy will be better positioned to navigate policy shifts, energy cost fluctuations, and sudden demand reallocations across end-use verticals. Our report provides the analytical foundation needed to operationalize these imperatives with confidence.
How to Use This Intelligence
The value of this research lies not only in the data it presents, but in how it enables decision-makers to convert complex market signals into coherent strategy. For executives, the report offers a consolidated view of growth trajectories, competitive intensity, and regulatory momentum, supporting capital allocation and portfolio prioritization. For strategy and business development teams, it provides segmentation and regional intelligence that can inform partnership selection, market targeting, and go-to-market sequencing. For procurement and supply chain leaders, it delivers context on input-cost trends and supplier concentration, helping to structure resilient sourcing frameworks. For R&D and product teams, the analysis connects application requirements with fiber architecture choices, guiding grade development and performance optimization efforts.
By maintaining a consistent focus on actionable insight rather than descriptive overview, the report is designed to integrate directly into planning workflows, risk assessments, and competitive response models. Readers will leave with a clear understanding of where the market is moving, which forces are accelerating or constraining growth, and how to position their organizations for sustained relevance in a rapidly evolving materials landscape.
Conclusion: The Case for Deeper Intelligence
The long glass fiber reinforced polypropylene market is being reshaped by a convergence of regulatory pressure, lightweighting demand, raw material volatility, and technological differentiation among leading compound manufacturers. Organizations that rely on surface-level market narratives risk misallocating resources, underestimating competitive intensity, or overlooking regional and application-level opportunities that could define their next phase of growth. This report is built to close that gap.
By combining a rigorously constructed historical baseline, a forward-looking forecast framework, segmentation depth, competitive benchmarking, and regulatory-macro integration, the research equips decision-makers with the intelligence required to act decisively in 2026 and prepare for the trajectory toward 2032. The full analysis provides the detailed regional breakdowns, application-level demand mappings, type-specific growth pathways, and competitive assessments necessary to translate strategic direction into execution. For teams seeking to move beyond general market awareness and into precise, defensible decision-making, the complete report offers the depth and structure required to lead with confidence.
For detailed analysis of this topic, please visit the official page: Long Glass Fiber Reinforced Polypropylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motorcycle Gear Market to Hit $27.4M by 2032 at 5.6% CAGR
By PW Consulting, 2026-09-16
Navigating the Motorcycle Gear Market: Strategic Intelligence for 2026 and Beyond
The global motorcycle gear market stands at a critical inflection point. Between 2020 and 2025, the sector experienced a period of structural contraction, with revenues declining from approximately 23.73 million USD to 16.15 million USD. This downward trajectory reflects a combination of post-pandemic demand normalization, supply chain recalibration, and shifting consumer spending patterns across rider demographics. However, the forecast period from 2026 through 2032 signals a decisive recovery. Market projections anticipate a compound annual growth rate of 5.6 percent, with revenues expected to climb steadily toward 27.4 million USD by the end of the decade. For executives, procurement leaders, and product strategists, these figures are not merely backward-looking indicators. They are early-warning signals that demand proactive positioning before the next growth cycle fully materializes.
Understanding why the market compressed, what is now catalyzing its rebound, and how competitive dynamics are reorganizing requires more than headline numbers. It requires a disciplined examination of type-level demand shifts, application-specific usage patterns, regional procurement behaviors, and the regulatory-material landscape that is actively reshaping product development pipelines. This report translates macro-level trajectories into operational intelligence. It is designed to help leadership teams validate product roadmaps, allocate inventory with precision, anticipate compliance exposure, and identify whitespace before competitors institutionalize their advantages.
The following analysis outlines the structural forces defining 2026 decision-making, previews the scope of our primary research, and demonstrates how competitive and regulatory intelligence can be converted into measurable strategic advantage.
Market Trajectory and the Strategic Meaning of the 2026 Inflection
The historical arc of the market carries a clear operational message. The contraction observed from 2020 through 2025 was not uniform across categories or user segments. Rather, it masked divergent behaviors: certain protective categories experienced faster erosion, while on-road application demand retained a structurally larger footprint than off-road usage. By 2026, the market begins its recovery at 16.63 million USD, a baseline that sets the stage for a multi-year expansion curve. The forecast steady climb toward 19.04 million USD in 2027, 19.32 million USD in 2028, and progressively higher figures through 2032 indicates that the sector is not simply rebounding. It is re-composing around new material priorities, evolving rider preferences, and tighter safety expectations.
For corporate strategists, the essential insight is that timing matters more than ever. Entering or expanding in this market after the recovery becomes visible to the broader industry often means accepting compressed margins and elevated competitive intensity. Companies that use 2026 to restructure product assortments, realign supply commitments, and benchmark regional demand behavior will be positioned to capture disproportionate share as the growth curve accelerates. The forecast horizon up to 2032 provides a sufficiently long runway to evaluate capacity investments, product lifecycle planning, and channel strategy without overcommitting to short-term volatility.
Core Report Scope: From High-Level Data to Operational Decision Support
This market research is structured to serve executives who need both strategic context and actionable breakdowns. Rather than stopping at aggregate market sizing, the report decomposes demand across multiple dimensions that directly influence product planning, sourcing, and go-to-market execution.
- Historical performance tracking from 2020 through 2025, enabling retrospective analysis of contraction drivers and category resilience.
- Forward-looking projections across the 2026-2032 window, giving strategy teams a consistent basis for capacity, pricing, and portfolio planning.
- Category-level analysis across helmets, jackets, gloves, protective gear, and other product types, allowing product leaders to identify where demand momentum is building and where saturation risk is rising.
- Application-based evaluation separating on-road and off-road usage contexts, which is critical for understanding rider behavior, feature prioritization, and seasonal or regional demand variability.
- Regional demand distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, supporting market entry assessments and localized inventory strategy.
- Competitive concentration metrics that illuminate market share dynamics and help benchmark the balance between established incumbents and emerging challengers.
The report is deliberately built to avoid the trap ofabstract market narratives. Each section connects data to operational implications. For example, rather than presenting a single aggregate figure and moving on, the research situates that figure within type-level and application-level behavior so that sourcing teams can anticipate where volume is likely to concentrate. Rather than offering generic growth commentary, it ties expansion trajectories to the product and regional contexts that leadership teams actually manage day to day.
Competitive Landscape: Concentration, Positioning, and Strategic Differentiation
Market concentration remains a defining feature of the industry. With the top three players accounting for 44.5 percent of market share and the top five firms commanding 56.2 percent, the competitive environment is neither fragmented nor fully consolidated. This mid-range concentration creates a dual strategic reality. Incumbents benefit from scale, brand equity, and established distribution relationships, while smaller or regionally focused players can still win through specialization, agile product iteration, and segment-focused positioning.
The competitive set spans a broad geographic and product footprint. Italian manufacturers such as Alpinestars and Dainese continue to exert strong influence across premium protective and apparel categories, while Dutch brand REV'IT! Sport International has carved out a distinct position through functional rider apparel and modular gear design. On the American side, Fox Racing and Klim represent performance-oriented and adventure-touring segments respectively, each reinforcing different rider identities and usage contexts. Additional players including Leatt, Aerostich, FLY Racing, Rynox Gears, Sedici, Aether, Just1, Icon Motosports, Kushitani, Rukka, Sidi, Held, and Spidi contribute further variation in product specialization, regional reach, and price-tier positioning.
This diversity matters because the market is not being won on brand recognition alone. Competitive advantage increasingly derives from how effectively companies integrate protection performance, material innovation, rider comfort, and compliance assurance into a cohesive product story. Some manufacturers are widening their lead through heritage and scale. Others are gaining traction by targeting specific riding disciplines or by re-engineering product lines around emerging material and sustainability expectations. The report maps these positioning strategies in greater detail, providing a comparative lens that helps companies evaluate where they are exposed, where they can differentiate, and where partnership or acquisition logic may be warranted.
Dynamics Shaping 2026: Regulation, Sustainability, and Live Market Signals
The market is being reshaped by several concurrent forces. Regulatory scrutiny is one of the most immediate. In early 2026, NHTSA issued recalls affecting multiple helmet models, including Allwin Powersports Corp. LS2 Rebellion helmets in sizes XL and XXL produced between July 1, 2024 and July 30, 2025, as well as Micro DOT Helmet Co. Blister Original, Twister Original, and Twister 2.0 ABS helmets for non-conformance with FMVSS No. 218 impact protection standards. These actions are not isolated quality incidents. They reflect an intensifying compliance environment in which safety certification, component integrity, and production consistency are becoming strategic liabilities for manufacturers that underinvest in quality control.
Riding Gear Market
At the same time, the product frontier is shifting toward material innovation and sustainability. In late 2025, Dainese introduced a new line of eco-friendly motorcycle gear built from sustainable materials, signaling that environmental performance is moving from peripheral branding to core product architecture. Broader 2026 industry analysis reports a rising trend toward recycled membranes and biobased textiles in technical motorcycle gear, suggesting that material sourcing decisions will increasingly influence both cost structures and product differentiation.
Trade show activity reinforces the sense that the market is actively re-inventing itself. At EICMA 2025, multiple companies presented new motorcycle gear lines and apparel concepts. Klim showcased all-new protection and redesigned GORE-TEX gear alongside adventure and touring offerings with an integrated armor package. Bajwa Vision exhibited premium riding apparel and safety-compliant gear, while A-PRO SRL presented motorcycle clothing concepts. These live product disclosures indicate that innovation pipelines are active across both premium and mid-tier segments, and that companies are preparing for a period in which protection performance, weather management, and comfort are being redesigned in tandem.
Strategic Implications for 2026 Decision Makers
Taken together, the trajectory, competitive structure, and emerging dynamics point to several priorities for leadership teams operating in this space during 2026.
Motorcycle Gear Market
- Align product portfolio decisions with category-level momentum rather than relying on aggregate market narratives, especially as certain product types and application contexts demonstrate stronger recovery potential than others.
- Strengthen quality assurance and compliance readiness across helmet and protective categories, given the heightened regulatory attention and the financial and reputational risk associated with certification failures.
- Incorporate material innovation into near-term sourcing and design planning, as recycled membranes and biobased textiles are becoming relevant not only to sustainability messaging but also to differentiation and long-term cost strategy.
- Evaluate regional demand behavior with operational granularity, since market expansion will not unfold uniformly and inventory deployment, channel focus, and pricing strategy should reflect local rider profiles and purchasing conditions.
- Benchmark competitive positioning against both scaled incumbents and specialized challengers, recognizing that the 2026 environment rewards companies that can combine protection credibility with targeted product storytelling and agile line development.
These implications are not theoretical. They are the practical consequences of a market that has just emerged from contraction and is now entering a forecasted growth cycle with new regulatory, material, and competitive conditions. Companies that treat 2026 as a planning year rather than a reactive year will be far better positioned to convert growth into durable advantage.
Why This Report Matters Now
Market research is most valuable when it reduces uncertainty at the exact moment decisions are being made. This report is designed for that purpose. It gives executives a structured view of how the motorcycle gear market has behaved, how it is projected to evolve through 2032, and what competitive and regulatory forces are actively reshaping product strategy. More importantly, it translates those insights into a decision-ready framework that can inform portfolio planning, sourcing commitments, compliance investment, and regional expansion logic.
The full study goes further still. It provides the detailed segmentation context, comparative competitive profiling, and forward-looking scenario framing that leadership teams need to move from awareness to action. If your organization is preparing product launches, reassessing channel strategy, evaluating supplier relationships, or building a defensible position ahead of the next growth phase, the complete report offers the depth required to make those choices with confidence.
The market trajectory is becoming clearer. The strategic window is open now. For the full segmentation detail, competitive analysis, and 2026-2032 forecast intelligence that supports high-stakes decisions, access the complete Motorcycle Gear Market research report and turn market visibility into operational advantage.
For detailed analysis of this topic, please visit the official page: Motorcycle Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bollards Market to Grow at 7.95% CAGR, Reaching $4,852.89 Million by 2032
By PW Consulting, 2026-09-16
Strategic Insights: The Bollards Market in 2026 and Beyond
As urban infrastructure evolves and security threats become increasingly sophisticated, the global bollards market stands at a critical inflection point. Our latest market research report delivers a comprehensive analysis of this dynamic landscape, providing enterprise decision-makers with the intelligence required to navigate opportunities and risks through 2032. This article serves as a strategic overview of the findings, highlighting the macroeconomic trajectory, competitive forces, and operational dynamics that will define the sector in the coming years.
Executive Summary: A Trajectory of Sustained Growth
The global bollards market has demonstrated remarkable resilience and expansion over the past five years. From a baseline valuation in 2020, the market has climbed steadily, reaching an estimated 2,865.57 million USD by 2025. This growth reflects more than simple cyclical recovery; it represents foundational shifts in urban planning, security investment, and infrastructure hardening. Our forecast model projects the market to reach 4,852.89 million USD by 2032, driven by a compound annual growth rate of 7.95 percent.
This performance underscores a clear strategic reality: bollards are no longer viewed merely as passive boundary markers. They are becoming active components of integrated security ecosystems, traffic management systems, and aesthetic urban design. For stakeholders evaluating market entry, capacity expansion, or product portfolio diversification, this growth trajectory suggests a expanding total addressable market with room for differentiated value propositions.
Market Dynamics: Drivers, Restraints, and Emerging Opportunities
Several interconnected forces are shaping the current market environment. On the demand side, the persistent prioritization of public safety infrastructure continues to drive adoption across municipal, commercial, and institutional sectors. The integration of bollards into broader perimeter protection strategies has elevated their importance in risk mitigation frameworks.
However, the operational landscape is also being influenced by external cost pressures. Industry data from early 2026 indicates that steel prices continue to rise, as reported by manufacturers. This trend directly impacts production costs and margin structures across the value chain. Furthermore, supply chain disruptions and raw material fluctuations are affecting bollard steel pipe prices, introducing volatility that procurement and finance teams must carefully manage. These dynamics create a dual challenge: meeting growing demand while controlling input costs.
Worldwide Roof Bolters Market
Regulatory frameworks are also tightening, creating both compliance requirements and standardization opportunities. The introduction of standards such as ASTM F3016 has established measurable performance criteria for bollards intended to protect pedestrians, storefronts, and public spaces. This regulatory environment rewards manufacturers and suppliers who can demonstrate verified performance, while potentially raising barriers for those unable to meet evolving specifications.
Segmentation Dynamics: Understanding Demand Architecture
Our analysis dissects the market across multiple dimensions, revealing distinct demand drivers and consumption patterns. The typological split between fixed and retractable bollards highlights a market that balances permanent security installations with flexible access control solutions. Fixed bollards continue to represent a significant share of revenue, reflecting their established role in permanent infrastructure projects. Retractable bollards, meanwhile, address the growing need for adaptable access management in environments where controlled entry and exit is critical. Additional types further contribute to the diversity of available solutions.
From an application perspective, the market is anchored by two primary pillars: traffic control and security and perimeter protection. Traffic control applications leverage bollards to manage vehicle flow, define boundaries, and enhance roadway safety. Security and perimeter protection applications deploy bollards as defensive barriers against ram-raiding, vehicle intrusion, and unauthorized access. These two application areas together dominate revenue generation, though other applications provide niche opportunities for specialized deployments.
Regional analysis further illuminates where growth is concentrated and where localization strategies will be most effective. Different geographic markets exhibit varying levels of infrastructure spend, regulatory maturity, and security awareness, requiring tailored approaches rather than one-size-fits-all market entry strategies.
Competitive Landscape: Fragmented and Innovating
The bollards market is characterized by a moderate level of concentration, with the top three companies accounting for 29.4 percent of revenue and the top five firms capturing 34.1 percent. This structure suggests a competitive environment where established players hold meaningful share, but a long tail of specialized manufacturers and regional suppliers continues to compete effectively through product differentiation, service quality, and price positioning.
Several key companies exemplify the diverse strategies shaping the industry. Vestil Manufacturing Corp., based in Indianapolis, Indiana, focuses on removable ornamental steel bollards and steel pipe safety bollards, emphasizing versatility and safety in industrial and commercial settings. Reliance Foundry Co. Ltd., headquartered in Surrey, British Columbia, offers a broad portfolio that includes concrete bollards, contemporary bollards, crash-rated bollards, steel bollards, and steel pipe bollards, positioning itself across both aesthetic and high-performance segments.
Justrite Manufacturing Company LLC, located in Chicago, Illinois, addresses safety-critical needs with steel safety bollard posts available in round or square configurations, finished in yellow and high-density polyethylene plastic. The Bollard Company provides a wide variety of bollard covers and steel bollards in all sizes, styles, and colors, catering to projects where visual integration and customization are paramount. Ameristar Security Products contributes to the security segment with its Bulwark Security Bollards and Titan Security Bollards, reinforcing the focus on protection-grade solutions.
Barrier1 Systems, LLC competes in the high-performance security niche with its Hercules M30 Set & Pour Bollard, Hercules M50 Set & Pour Bollard, and Hornet M30 Shallow Mount Bollard, targeting applications that demand verified crash resistance. Beacon Industries Inc. rounds out the offering spectrum with steel bollards, removable bollards, bollard posts, flexible bollards, and bollard covers, supporting both rigid and adaptive use cases.
Additional players further enrich the competitive fabric. L.K. Goodwin Co. specializes in concrete bollards, offering durability and cost-effectiveness for certain installation contexts. Frontier Pitts Ltd., based in Crawley, West Sussex, United Kingdom, delivers standard and automated security bollards, as well as anti-ram anti-terrorist vehicle blockers, aligning with high-threat protection requirements. BollardsUSA provides fabricated steel and cast iron bollards, including decorative and coated steel options, serving markets that value finish quality and material variety. Post Guard offers bolt down bollards, collapsible bollards, concrete bollards, and removable bollards, expanding the toolkit for flexible and semi-permanent installations. Dark Horse Metals supplies American-made steel bollards, appealing to procurement preferences that emphasize domestic production. Bollards Plus contributes bolt down, removable, inground, and bollard cover solutions, while Selcom Manufacturing Inc. focuses on stainless steel security bollards, addressing corrosion-resistant and premium aesthetics requirements.
These companies operate in an environment where recent developments signal both collaboration and competition. In May 2025, crash-tested bollards were exhibited at the International Security Expo, highlighting the industry's emphasis on verified performance. By June 2025, Post Guard released an ASTM F3016 bollards guide addressing traditional bollards performance, contributing to the broader standardization conversation. In September 2025, the City of New Orleans completed an upgrade of the Bourbon Street bollard system, installing new removable stainless-steel bollards, a project that illustrates the convergence of aesthetics, security, and modern access control in real-world deployments.
Practical Applications: How Buyers Are Deploying Bollards
Understanding how bollards are applied in practice is essential for aligning product development, marketing, and sales strategies. Traffic control deployments are increasingly integrated with smart city initiatives, where bollards serve not only as physical barriers but also as visual cues that complement sensor networks, signage, and dynamic traffic management systems. In this context, the form factor, visibility, and durability of bollards directly impact their effectiveness within layered traffic management plans.
Security and perimeter protection applications demand rigorous performance validation. Buyers in this segment are prioritizing crash-rated and tested solutions that can withstand vehicle impact and deter unauthorized entry. The emphasis on measurable criteria, driven by standards such as ASTM F3016, means that suppliers must be prepared to provide documentation, test data, and installation guidance that supports compliance and risk management objectives. Permanent installations require robust anchoring and structural design, while temporary or flexible applications rely on removable, collapsible, or shallow-mount solutions that allow for rapid reconfiguration.
Beyond these core applications, other use cases continue to emerge, driven by specific industry requirements, aesthetic mandates, and specialized environmental conditions. These opportunities often reward suppliers who can offer tailored fittings, custom finishes, or application-specific engineering support.
Strategic Implications for 2026 Decision-Making
The market landscape outlined in our report carries clear implications for enterprise strategy. Companies operating in or entering this space should consider several focal points. First, cost structure management is paramount given the ongoing pressure from rising steel prices and supply chain volatility. Businesses that can secure stable sourcing relationships, optimize manufacturing efficiency, or offer value-engineered alternatives will be better positioned to protect margins while remaining competitive on price.
Second, performance verification and regulatory alignment are becoming critical differentiators. As buyers increasingly demand evidence of crash performance and compliance with recognized standards, firms that invest in testing, certification, and transparent documentation will gain a competitive edge. This is particularly relevant for security and perimeter protection applications, where liability and risk profiles are heightened.
Third, flexibility in product offerings is a strategic asset. The coexistence of fixed, retractable, removable, and specialized bollard types reflects a market that values choice. Suppliers who can provide a range of installation methods, materials, and configurations are better equipped to address diverse project requirements and expand their addressable share across both traffic control and security segments.
Fourth, regional nuance matters. The distribution of market revenue across geographies indicates that growth opportunities are not uniform. Companies must assess local infrastructure budgets, security policies, procurement practices, and competitive intensity to determine where to allocate sales and marketing resources, how to position pricing, and which product lines to emphasize.
What the Full Report Delivers
This overview captures the strategic contours of the bollards market, but the complete research study provides the depth required for precise decision-making. The full report delivers granular market size and forecast data, segmentation analysis across types, applications, and regions, and detailed competitive profiling that maps company positions, product portfolios, and recent developments. It includes an in-depth examination of market dynamics, covering drivers, restraints, opportunities, and the impact of regulatory and material cost trends. The study also explores pricing behavior, supply chain considerations, and the implications of key industry events and project deliveries.
By synthesizing these elements, the report equips stakeholders with actionable intelligence for capacity planning, product strategy, market entry evaluation, competitive positioning, and risk assessment. Readers will gain a clear picture of where demand is heading, which segments offer the most attractive growth profiles, and how leading companies are adapting to the evolving environment.
Bollards Market
Conclusion: Navigating the Next Phase of Growth
The bollards market in 2026 presents a compelling combination of growth momentum, evolving customer requirements, and operational challenges. Demand continues to expand as infrastructure projects, security investments, and traffic management needs converge. At the same time, cost pressures, material volatility, and regulatory expectations require disciplined strategy and operational agility. Companies that understand these dynamics, differentiate through performance and flexibility, and align their offerings with regional and application-specific needs will be best positioned to capture value in the years ahead. Our full market research study provides the comprehensive intelligence needed to turn these insights into decisive action.
For detailed analysis of this topic, please visit the official page: Bollards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulphur Recovery Market to Hit $118M in 2025 with 2.51% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Imperatives in the Global Sulphur Recovery Market: A 2026 Outlook
The global energy and petrochemical landscape is undergoing a profound transformation, driven by tightening environmental regulations, evolving feedstock characteristics, and the relentless pursuit of operational efficiency. Within this complex ecosystem, sulphur recovery stands as a critical operational pillar for refineries and gas processing facilities. As we move through 2026, the ability to navigate the sulphur recovery market with precision is not merely a technical requirement but a strategic imperative for long-term viability and competitive advantage.
PW Consulting is pleased to introduce our latest comprehensive market research study, designed to equip decision-makers with the intelligence needed to thrive in this evolving environment. This article serves as a strategic preview, outlining the macroeconomic trajectory, competitive intensity, and regulatory currents that will define the sector over the coming years.
Macroeconomic Trajectory and Market Resilience
The sulphur recovery market has demonstrated remarkable resilience and volume growth over the past half-decade. Our analysis of historical data from 2020 to 2025 reveals a significant expansion in market revenue, driven by sustained investment in gas processing infrastructure and stricter compliance mandates across major operating regions. The market reached a substantial valuation in the base year of 2025, reflecting the industry's commitment to mitigating sulfur emissions while maximizing resource utilization.
Looking forward, the forecast period from 2026 to 2032 suggests a continued path of measured growth. The projected Compound Annual Growth Rate (CAGR) stands at 2.51 percent, indicating a steady expansion trajectory rather than volatile spikes. This moderate growth rate underscores the maturity of the market while highlighting consistent demand drivers. By the end of the forecast horizon in 2032, the market is expected to reach new revenue milestones, maintaining its status as a vital component of the downstream energy value chain.
It is important to note that market valuation fluctuations observed during the late 2020s reflect broader economic adjustments, supply chain recalibrations, and shifts in capital expenditure priorities among major operators. However, the underlying demand for reliable sulphur recovery solutions remains robust. Investors and stakeholders must understand that while top-line revenue may experience minor contractions in specific interim years, the strategic necessity of sulphur recovery infrastructure ensures long-term market stability.
Regulatory Dynamics and Environmental Pressures
One of the most potent forces shaping the sulphur recovery landscape is the regulatory environment. Governance regarding sulfur dioxide emissions has tightened considerably across key jurisdictions. In the United States, regulations under 40 CFR set specific emission limits for sulfuric acid manufacturing and sulfur recovery operations, compelling facilities to adopt advanced abatement technologies. Similarly, state-level bodies such as the Texas Commission on Environmental Quality govern permitting for sulfur recovery units under strict air quality standards, adding layers of compliance complexity for operators in major production hubs.
Internationally, the impact of International Maritime Organization (IMO) amendments continues to reverberate through the industry. The Mediterranean Sea Emission Control Area mandated a marine fuel sulfur limit of 0.10 percent effective May 2025, reinforcing the need for high-purity sulphur products and efficient recovery processes. Furthermore, the global implementation of IMO 2020 fuel sulfur restrictions and the expansion of Emission Control Areas continue to drive demand for advanced SRU tail gas treating solutions. These regulatory pressures are not temporary hurdles but structural shifts that require ongoing capital investment and technological adaptation.
Feedstock variability also plays a crucial role in shaping operational requirements. Hydrogen sulfide concentrations in acid gas streams range from 5 to 30 percent in gas processing plants requiring sulphur recovery. This variability demands flexible recovery technologies capable of handling fluctuating inlet compositions without compromising efficiency or environmental compliance. Understanding the interplay between feedstock characteristics and regulatory limits is essential for designing future-proof facilities.
Competitive Landscape and Technology Leadership
The sulphur recovery market is characterized by a moderately concentrated competitive structure. Our analysis indicates that the top three companies account for approximately 65.0 percent of market share, while the top five players command around 85.0 percent. This concentration highlights the high barriers to entry associated with proprietary technologies, engineering capabilities, and global service networks required to succeed in this sector.
Leading incumbents continue to leverage their technological portfolios to maintain market dominance. Shell Catalysts & Technologies offers a comprehensive suite of solutions including Claus, SCOT, sulphur degassing, and THIOPAQ O&G sulphur recovery technologies for refineries and gas processing. Similarly, Worley (Comprimo) provides Comprimo SRU and advanced tail gas treatment units designed for high-efficiency sulphur recovery, positioning them as a key partner for large-scale energy projects.
Worldwide Industrial Sulfur Market
European players also hold significant sway in the market. Linde AG supplies LO-CAT sulphur recovery units utilizing low-temperature oxidation processes, while Air Liquide Engineering & Construction licenses the Lurgi Claus process for sulphur recovery from acid gas streams. Technip Energies licenses SmartSulf and Sulphur Recovery processes specifically tailored for the oil and gas industries. These technology licensors play a pivotal role in setting performance standards across the globe.
In the Asia Pacific region, Chiyoda Corporation provides Superclaus and SRU technology with exclusive contracts for advanced sulphur recovery, catering to the region's robust demand. Meanwhile, US-based firms like Fluor Corporation deliver EconoClaus sulphur recovery units integrated with refinery operations, and GTC Technology US offers advanced Claus process and tail gas treating solutions. McDermott engages in SRU design and engineering for gas processing facilities, further diversifying the engineering capability pool.
Specialized players such as Sulfur Recovery Engineering (SRE) in Canada focus on optimization, maintenance, and services for SRU, TGTU, and sour water stripping units, highlighting the growing importance of lifecycle services. Sunway Petrochemical Engineering in Malaysia delivers modular sulphur recovery units for regional refineries, addressing the need for scalable and rapid deployment solutions. KT-Kinetics Technology SpA and Heurtey Petrochem round out the competitive field with their respective low-temperature oxidation units and integrated petrochemical refining solutions.
Recent Industry Developments and Strategic Momentum
Recent project awards and completions illustrate the active engagement of major players in expanding capacity and upgrading existing infrastructure. In December 2025, Worley won a front-end engineering and design contract from ADNOC Gas for the Bab Gas Cap project, including dedicated sulphur recovery units. This underscores the continued investment in large-scale gas processing developments in the Middle East.
In April 2025, KBR-AMCDE secured a Saudi Aramco contract for the modernization of Haradh and Hawiyah Gas Plants, upgrading sulphur recovery efficiency to 99.9 percent. This milestone highlights the industry's focus on maximizing recovery rates to meet stringent environmental targets. Additionally, OMV Petrom completed an investment of 45 million euro in a new sulphur recovery unit at the Petrobrazi refinery in December 2025, signaling strong capital commitment within the European refining sector.
These developments reflect a broader trend where operational efficiency and environmental compliance converge. Companies are not just building capacity; they are upgrading existing assets to achieve higher efficiency thresholds. This shift favors technology providers who can demonstrate proven performance in achieving near-complete sulfur conversion and minimal tail gas emissions.
Operational Segmentation and Strategic Focus Areas
To navigate this market effectively, stakeholders must understand the primary segmentation drivers without getting lost in granular data. The market is broadly defined by technology type, application, and geography. By technology, the Claus Process remains the dominant methodology, accounting for the largest share of recovery operations due to its established reliability and widespread adoption. Tail gas treatment represents a critical complementary segment, increasingly essential as regulatory standards demand near-zero emissions from the overall recovery system.
In terms of application, the Petroleum and Coke sector represents the primary demand driver, utilizing sulphur recovery to manage acid gas streams generated during crude oil processing. The Natural Gas segment follows as a significant contributor, reflecting the growth in gas processing activities globally. Other applications also contribute to the market mix, supporting diverse industrial processes that generate sulfur-bearing streams.
Geographically, the market distribution reflects global energy production patterns. Asia Pacific remains a heavyweight region due to its massive refining and gas processing capacity. North America and Europe maintain substantial market presence driven by strict environmental compliance and mature infrastructure. Latin America and the Middle East and Africa regions also contribute to the global footprint, with project activity in these areas often tied to major oil and gas developments. Detailed regional breakdowns and specific application splits are available in our full report.
Value Proposition of the PW Consulting Report
Our latest Sulphur Recovery Market report is designed to be a practical tool for strategic planning. It goes beyond high-level statistics to provide actionable intelligence on market sizing, growth trajectories, and competitive positioning. The report covers the historical period from 2020 to 2025 and offers a detailed forecast through 2032, all expressed in USD millions.
Key contents include a deep dive into market dynamics influenced by regulations, feedstock variations, and techno-economic factors. We analyze the strengths, weaknesses, opportunities, and threats for key market participants, providing a clear view of where value is being created. The study also examines recent developments and contract awards to identify momentum shifts among industry leaders.
Furthermore, the report addresses the nuances of technology licensing, engineering services, and aftermarket support, recognizing that the revenue model in this sector often extends beyond initial CAPEX into long-term OPEX relationships. Understanding the revenue concentration among top players helps inform partnership strategies and competitive benchmarking.
Sulphur Recovery Market
Conclusion: Navigating the Future
As the sulphur recovery market progresses through 2026 and beyond, success will depend on the ability to balance regulatory compliance, operational efficiency, and technological innovation. The steady CAGR of 2.51 percent suggests a market that is stable yet demanding, where incremental improvements in efficiency and reliability can yield significant competitive gains.
Stakeholders must remain vigilant regarding regulatory updates, such as evolving EPA standards and international maritime emission controls, which continuously reshape the operational baseline. Simultaneously, the concentration of market share among top-tier technology providers and engineering firms underscores the importance of selecting the right partners for long-term projects.
This strategic overview provides a foundation for understanding the market's direction, but the full depth of data, segmentation analysis, and competitive intelligence is essential for precise decision-making. We invite industry leaders, investors, and consultants to access the complete PW Consulting Sulphur Recovery Market report to obtain the detailed insights necessary to formulate robust strategies for the 2026-2032 period. The complete intelligence package includes granular segmentation data, detailed company profiles, and comprehensive forecast models that will empower your organization to lead in this critical sector.
For detailed analysis of this topic, please visit the official page: Sulphur Recovery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Home Security Market Hits $67M in 2025, Projects 8.92% CAGR Growth Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Modern Defender: Inside the 2026 Home Security Market
The residential security landscape has fundamentally shifted. Where once the market was defined by simple alarm panels and reactive monitoring, it is now a complex ecosystem of AI-driven surveillance, interconnected smart home automation, and nuanced consumer preferences between professional installation and do-it-yourself flexibility. For executives, investors, and strategic planners, navigating this evolution requires more than surface-level observation. It demands rigorous, data-backed intelligence that connects historical momentum with forward-looking forecasting. Our newly released Home Security Market research report provides exactly that blueprint, offering a comprehensive lens into the forces shaping the industry from 2026 through 2032.
This analysis is not merely a collection of figures. It is a strategic decision-making framework designed to help organizations anticipate demand shifts, evaluate competitive positioning, and allocate capital with precision. By synthesizing historical performance data with projected growth trajectories, the report equips stakeholders with the contextual depth required to operate confidently in an increasingly automated and regulation-sensitive market.
A Market in Structured Expansion
Over the past five years, the home security sector has demonstrated consistent, compounding growth. Historical revenue data from 2020 through 2025 reveals a steady upward trajectory, with the market expanding from a baseline of 42.36 million USD to a projected 67.32 million USD by the close of 2025. This growth reflects sustained consumer investment in residential protection, driven by rising urbanization, increased connectivity, and a broader cultural shift toward proactive home management.
Looking ahead, the forecast period from 2026 to 2032 indicates that this momentum will not only continue but accelerate in strategic pockets. The market is projected to reach 73.17 million USD in 2026, with annual figures climbing steadily toward a projected 122.8 million USD by 2032. Underlying this expansion is a compound annual growth rate of 8.92%, a metric that signals durable, long-term demand rather than cyclical volatility. For corporate strategists, this growth curve translates into clear implications: sustained product development cycles, expanding go-to-market opportunities, and the necessity of agile infrastructure planning to accommodate scaling consumer adoption.
Structural Composition and Application Realities
Beneath the aggregate growth figures lies a layered segmentation structure that defines how value is distributed across the market. Hardware-centric categories continue to anchor the industry, with cameras and monitoring systems representing the largest share of market activity. This dominance is logical, as visual verification remains the cornerstone of modern threat detection and consumer confidence. Alarms and sensors form the second major pillar, providing the foundational layer of intrusion detection and environmental monitoring that complements camera networks. A smaller but strategically significant segment is occupied by locks and access control, a category whose relevance is expanding as smart entry solutions integrate seamlessly with broader residential automation ecosystems.
On the application side, the market reflects distinct residential deployment patterns. Independent homes continue to represent the primary adoption channel, capturing the majority of system installations and upgrade cycles. Multi-family housing constitutes a meaningful secondary segment, driven by property management requirements, centralized monitoring demands, and the growing emphasis on tenant safety in dense urban environments. Understanding how these application dynamics interact with regional deployment realities and pricing sensitivities is essential for any organization designing targeted product bundles or channel strategies.
While the structural outline is clear, the precise allocation of market share across regions, product types, and end-use applications contains critical nuance that can only be fully leveraged through the complete dataset. The report's detailed segmentation breakdowns reveal the exact magnitude of regional performance, the proportional weight of each product category, and the application-level demand patterns that inform inventory planning, pricing architecture, and geographic expansion priorities. These granular insights are deliberately reserved for the full publication, ensuring that stakeholders who require actionable precision have a direct pathway to the complete intelligence.
Competitive Architecture and Strategic Positioning
The home security market is characterized by a concentrated competitive landscape, with the top three firms accounting for approximately 62 percent of total market share and the top five firms collectively commanding roughly 72 percent. This concentration underscores the strategic importance of differentiation, technological innovation, and service integration in maintaining or expanding market position. The leading participants operate across a spectrum of business models, ranging from professionally installed, fully monitored residential systems to flexible, consumer-centric DIY platforms that emphasize no-contract flexibility and wireless deployment.
ADT, headquartered in Florham Park, New Jersey, continues to lean into professional monitoring, professional installation, and AI-powered smart home security systems. Its market approach emphasizes end-to-end service delivery and continuous enhancement of intelligent detection capabilities. Vivint, based in Lehi, Utah, competes through professionally installed, fully integrated smart home security and automation systems paired with ongoing monitoring, positioning itself at the intersection of security and holistic home automation. Ring LLC, operating from San Jose, California, has carved a distinct niche with video doorbells, cameras, and AI-powered alarm systems that serve both DIY users and customers seeking professional monitoring options.
SimpliSafe, headquartered in Boston, Massachusetts, has built its identity around DIY wireless security systems with professional monitoring options and no-contract plans, appealing directly to consumers who prioritize flexibility and uncomplicated deployment. Alarm.com, based in Reston, Virginia, operates as a platform and software backbone for professional monitoring, video security, and integrated alarm systems, enabling a broad ecosystem of service providers and residential deployments. Brinks Home Security, located in Scottsdale, Arizona, delivers professional home security systems with monitoring and smart home integrations, reinforcing the traditional service-led model with modern connectivity features.
Further down the competitive field, Abode Systems in San Francisco focuses on wireless DIY smart home security systems with Apple Home integration, catering to users embedded in specific smart ecosystem environments. Eufy Security, based in San Diego, California, emphasizes battery-powered AI cameras, doorbells, and all-in-one security kits, targeting consumers who value portability, low-maintenance hardware, and integrated detection intelligence. Johnson Controls, headquartered in San Antonio, Texas, brings institutional-grade engineering to the residential space through upgraded security panels and integrated residential systems with monitoring, bridging commercial-grade reliability with home-use scalability.
Recent Developments Shaping Market Trajectory
The strategic posture of these market participants is actively evolving, and several high-impact developments from early 2026 illustrate how quickly the competitive battlefield is shifting. In February 2026, ADT acquired Origin AI to expand its smart home capabilities, leveraging AI-based Wi-Fi sensing technology that detects motion without cameras or wearables. This move signals a clear strategic intent to diversify detection modalities, reduce hardware dependency, and embed intelligence into the ambient environment of the home.
Home Security Market
Alarm.com executed a series of platform-level enhancements in the first quarter of 2026. In March, the company expanded its video security portfolio with new AI capabilities and flexible camera solutions, broadening its addressable use cases for professional installers and end users alike. Earlier in April, Alarm.com modernized legacy security systems by introducing an enhanced Universal Communicator designed to improve interoperability across heterogeneous device ecosystems. These initiatives reflect a broader industry theme: the transition from isolated, single-point installations toward unified, interoperable platforms that simplify monitoring, reduce integration friction, and increase system lifespan.
Johnson Controls reinforced its residential and small business security positioning in March 2026 by launching upgrades to its DSC PowerSeries Neo 5 and IQ Panel 5 systems, demonstrating continued investment in panel modernization and user interface refinement. Meanwhile, Ring LLC expanded its consumer hardware lineup in March with a new battery-powered smart doorbell series featuring 2K and 4K video models, highlighting the ongoing demand for high-resolution, wire-free entry-point monitoring. Collectively, these actions reveal a market in which incumbents and specialists alike are racing to enhance detection sophistication, improve deployment flexibility, and extend the functional boundaries of residential security.
Infrastructure, Regulation, and the Broader Operating Environment
Strategic planning in home security cannot occur in isolation from the external conditions that shape deployment economics and regulatory compliance. Infrastructure dynamics are exerting measurable pressure on expansion models. Recent assessments indicate that deployment costs for fiber-to-the-home networks have increased by more than 10 percent, driven by rising materials and labor expenses. With operation and maintenance averaging around 53 USD annually per home passed, connectivity-dependent security solutions must account for escalating back-end cost structures when evaluating service scalability, monitoring reliability, and long-term pricing assumptions.
Regulatory context adds another layer of strategic complexity. Recent judicial and administrative developments have reshaped the broadband classification debate, with a 2025 appellate ruling holding that the FCC lacks authority to classify broadband as a telecommunications service under Title II. This legal landscape intersects with earlier regulatory actions, including the April 2024 FCC vote on service reclassification, and carries implications for how connectivity-dependent security products, cloud-based monitoring, and video transmission services are governed, priced, and delivered. In parallel, global data transmission realities remain heavily reliant on subsea fiber-optic infrastructure, which carries an overwhelming share of intercontinental and transoceanic digital communications. These structural dependencies remind market participants that residential security is increasingly intertwined with the resilience, latency, and regulatory status of broader communication networks.
These environmental factors do not simply represent background noise. They influence vendor selection, monitoring architecture, consumer adoption thresholds, and the cost profile of networked security solutions. The full report integrates these dynamics into actionable scenarios, helping decision-makers model how infrastructure cost shifts and regulatory uncertainty could affect product roadmaps, channel economics, and service-level commitments over the forecast horizon.
What the Full Report Delivers for Enterprise Decision-Makers
This market study is structured to move beyond high-level trends and into the operational detail that executives, product leaders, and investment teams require. The complete report delivers a multi-dimensional view of the home security market, combining quantitative forecasting with qualitative competitive assessment and environmental context. It provides the analytical foundation needed to answer pressing strategic questions: which deployment models are gaining traction, how intelligent detection capabilities are reshaping consumer expectations, where regional demand intensity is concentrated, and how leading players are positioning their portfolios against one another.
The publication includes detailed segmentation analysis, historical and projected revenue trajectories, competitive profiling, recent corporate and product developments, and a structured examination of the regulatory and infrastructure variables that influence market execution. Each section is designed to support specific decision functions, from product roadmap prioritization and channel strategy refinement to M&A screening and market entry evaluation. By connecting macro-level growth signals with micro-level competitive intelligence, the report offers a single, coherent reference point for organizations operating across the residential security value chain.
For strategists who need precise regional performance figures, exact product-type valuations, and granular application-level breakdowns to inform investment committees or executive briefings, the full dataset is essential. These detailed splits are compiled within the complete report and are intended to provide the specificity required for scenario modeling, pricing strategy, and targeted geographic expansion planning.
Strategic Next Steps
The home security market is entering a phase in which growth, technology integration, and external operating conditions will increasingly determine which organizations capture durable share and which are left reacting to market shifts. With a projected compound annual growth rate of 8.92 percent and a clear trajectory toward sustained expansion through 2032, the opportunity landscape is substantial, but it will be captured by those who plan with precision.
Smart Home Security System Market
Our full Home Security Market research report is now available for leaders who require complete intelligence rather than summary-level conclusions. It provides the detailed segmentation, competitive profiling, and environmental analysis needed to convert market momentum into executable strategy. For decision-makers ready to move from observation to action, the complete report offers the depth, clarity, and strategic framing necessary to navigate one of the most dynamic residential technology sectors in the current market environment.
For detailed analysis of this topic, please visit the official page: Home Security Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com