

Blogs
The global bubble water market revenue has demonstrated consistent growth from 2020 to 2025, with projections indicating continued momentum through 2035. Revenues climbed from USD 5,100 Million in 2020 to USD 8,750 Million in 2025, driven by product innovation and market expansion. By 2035, the market is forecasted to reach USD 15,800 Million, reflecting CAGR trends of rising consumer demand, emerging applications, and broadening distribution reach. Leading companies continue to invest in technology and sustainability, further cementing bubble water’s robust market position for the next decade.
Read More - https://bussinessinsights.com/research-report/global-bubble-water
Beverages account for the largest share at 54%, illustrating bubble water’s core usage in the drink segment. Culinary applications represent 16%, driven by the adoption of sparkling water in recipes and food preparation for added texture and sensory appeal. Pharmaceuticals and cosmetics (10% and 8%) are emerging application areas, as formulators tap into bubble water for specialized health and beauty products. Household usage, making up 7%, includes cleaning and home wellness, while 5% falls into other niche applications, underlining the market’s adaptability and potential for further innovation.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-bubble-water
Frequently Asked Questions
Who are the key players in Global Bubble Water industry?
The leading companies in the Global Bubble Water industry include PepsiCo (Bubly), Nestlé (San Pellegrino), The Coca-Cola Company (AHA, Schweppes), National Beverage Corp. (LaCroix), and Spindrift. These companies drive innovation, product variety, and global distribution in the sparkling or seltzer water market segment.
What is the Global Bubble Water growth?
The Global Bubble Water market has shown significant growth, with a CAGR exceeding 10% from 2020-2023. This surge is attributed to increasing health awareness and demand for sugar-free drinks. PepsiCo's launch of new Bubly flavors in 2023 further accelerated growth in North America and Europe.
Which segment accounted for the largest Global Bubble Water share?
The largest share in the Global Bubble Water market is held by the flavored sparkling water segment. Consumer preference for fruity and natural flavors, combined with zero-calorie appeal, has pushed flavored varieties—like those from LaCroix and San Pellegrino—to dominate supermarket shelves and online sales platforms worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Women's Gym & Sport Leggings Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global women’s gym & sport leggings market generated $9,800 Million in 2020 and is projected to reach $24,600 Million by 2035. The market shows a consistent upward trajectory, fueled by fitness adoption, product innovation, and the rise of digital retail platforms. Major brands' expansion, technology integration, and athleisure’s mainstream presence further propel growth, with revenues anticipated to grow at a CAGR of roughly 7-8% over the period.
Read More - https://bussinessinsights.com/research-report/global-women's-gym-and-sport-leggings
Yoga is the largest application segment, reflecting the ongoing boom in wellness and studio-based workouts, and accounting for over 35% of demand. Running and Training & Gym collectively make up a significant proportion as consumers seek high-performance stretch and moisture management. Casual wear, meanwhile, is gaining traction, highlighting the ongoing athleisure trend. The market’s broad application base supports its growth, providing opportunities for brands to tailor products for diverse activities ranging from athletic to everyday use.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-women's-gym-and-sport-leggings
Frequently Asked Questions
Who are the key players in Global Women's Gym & Sport Leggings industry?
The top 5 players in the global women's gym and sport leggings market are Nike, Adidas, Under Armour, Lululemon Athletica, and Puma. These brands lead in innovation, sustainable materials, and activewear technologies, leveraging strong distribution networks and global reach to maintain substantial market share and customer loyalty.
What is the Global Women's Gym & Sport Leggings growth?
The global women's gym & sport leggings market has witnessed notable growth, with Lululemon reporting over 20% sales increase in 2023, driven by evolving fitness trends, demand for athleisure, and product innovation. The market is projected to grow at a CAGR above 6% through 2028.
Which segment accounted for the largest Global Women's Gym & Sport Leggings share?
The fitness and training segment accounted for the largest market share in global women's gym and sport leggings, owing to increased participation in gyms, yoga, aerobics, and fitness classes. The popularity of active lifestyles and wellness activities has driven higher demand for comfortable, performance-oriented leggings.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Micromanipulators Market Hits $81.5M in 2025, Projected 9.3% CAGR to $152.8M by 2032
By PW Consulting, 2026-09-07
Precision at the Microscale: Strategic Imperatives in the 2026 Micromanipulators Market
The micromanipulation landscape is undergoing a decisive transformation. As laboratory workflows grow more complex and industrial tolerances tighten, the demand for sub-micron positioning accuracy has shifted from a niche requirement to a foundational capability. Our latest market research on the Micromanipulators Market provides a comprehensive, data-grounded lens into how this sector is evolving through 2032. For executives navigating capital allocation, R&D prioritization, and competitive positioning, this report delivers the strategic clarity required to act with confidence in 2026 and beyond.
Algae Based Plastics Market
The Macro Trajectory: Velocity, Scale, and Structural Shift
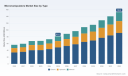
Over the past half-decade, the global micromanipulators market has demonstrated consistent, compounding growth. Revenue expanded from approximately USD 56.5 million in 2020 to an estimated USD 81.5 million in 2025, reflecting a sector that has not only recovered from pandemic-era supply chain friction but has accelerated into a new growth phase. Looking ahead, the forecast period from 2026 through 2032 projects a robust compound annual growth rate of 9.3 percent, with market revenue anticipated to cross the USD 150 million threshold by the end of the decade. These figures are not merely historical retrospectives; they are leading indicators of structural demand drivers that will shape procurement strategies, partnership decisions, and innovation roadmaps across life sciences, semiconductor fabrication, and advanced materials research.
Low Voltage LED Explosion Proof Light Market
Several converging forces explain this momentum. Sustained investment in neurology and cell biology research has intensified the need for repeatable, high-fidelity manipulation workflows. Simultaneously, the semiconductor and microelectronics sectors continue to push dimensional tolerances downward, requiring positioning subsystems that can operate with minimal drift and exceptional repeatability. The normalization of assisted reproductive technologies and the formalization of micro-operative protocols have further embedded micromanipulation into regulated clinical pipelines. Together, these dynamics create a multi-application demand base that is less vulnerable to single-sector downturns than earlier market cycles suggested.
Hydrogen Electronic Pressure Regulators Market
From Linear Growth to Compounding Value
The growth trajectory observed between 2020 and 2025 was not accidental. It was built on a foundation of iterative product refinement, expanding end-user training programs, and the gradual migration from legacy manual setups toward motorized and electric architectures. As research institutions and commercial laboratories scale their throughput, the total cost of ownership calculus has shifted. Buyers now weigh precision stability, integration compatibility, calibration drift, and service responsiveness alongside initial purchase price. This recalibration of buyer priorities is a critical insight for suppliers evaluating product roadmaps and for procurement leaders structuring multi-year equipment budgets.
Equally important is the market's increasing sensitivity to regulatory and standardization developments. Recent definitions and clinical guidance documents have formalized micro-operative techniques that rely on micromanipulation for procedures such as intracytoplasmic sperm injection and assisted hatching. While these standards do not dictate device specifications directly, they influence laboratory procurement policies, quality management expectations, and the documentation burden placed on equipment vendors. Organizations that anticipate these compliance trends will secure smoother adoption cycles and reduce time-to-deployment for new instrumentation.
Competitive Architecture: Focused Leaders, Regional Depth, and Consolidation Signals
The micromanipulators market remains characterized by a concentrated yet highly specialized competitive field. Industry data indicates that the top three participants collectively account for roughly 38.5 percent of total market revenue, while the top five expand that share to approximately 45.2 percent. This concentration pattern reflects the technical barriers inherent in precision mechanical design, sensor integration, and application-specific calibration. At the same time, the remaining market share is distributed among a long tail of capable manufacturers, regional integrators, and application-focused specialists, creating a landscape where differentiation is achieved through expertise rather than scale alone.
Several companies exemplify the strategic posture now required to compete effectively. Sensapex Oy, headquartered in Oulu, Finland, has built its reputation on patented ultraprecise micromanipulators and automated microscope workstations designed for electrophysiology and imaging, with in-house manufacturing supporting tight control over performance consistency. Sutter Instrument, based in Novato, California, continues to serve a broad electrophysiology and cell manipulation customer base through precision manual and motorized platforms that emphasize reliability and practical usability. Scientifica Ltd, operating from East Sussex, United Kingdom, has focused on the PatchStar micromanipulator line and electromechanical systems tailored for patch clamp and electrophysiology workflows, reinforcing a strategy of deep application specialization.
In the United States, Siskiyou Corporation, located in Grants Pass, Oregon, has maintained a strong reputation for high-precision micromanipulators and micropositioners used in microscopy and research applications, where customization and engineering responsiveness remain key differentiators. Narishige Group, headquartered in Tokyo, Japan, offers a distinct product philosophy through its NTX series hydraulic and motorized micromanipulators, addressing cell manipulation and microinjection requirements with a balance of mechanical robustness and fine positional control. World Precision Instruments, based in Sarasota, Florida, remains closely associated with manual micromanipulators for electrode positioning in electrophysiology and neuroscience, a segment where familiarity, service networks, and practical ergonomics continue to drive repeat purchases.
Larger systems players also shape the market's direction. Leica Microsystems, from Wetzlar, Germany, delivers integrated micromanipulator systems that align precision positioning with advanced microscopy and cell research environments, benefiting from cross-platform integration and brand trust in imaging ecosystems. Eppendorf SE, headquartered in Hamburg, Germany, contributes high-precision micromanipulation and injection systems that serve broad life science applications, reinforcing a portfolio strategy that connects sample handling, manipulation, and downstream processing in a cohesive workflow.
Recent Moves That Signal Strategic Direction
Recent corporate activity illustrates how quickly product portfolios and deployment models are evolving. In mid-2024, Sensapex released a revised manual for its uMp micromanipulation system, incorporating the uMp-TSC2 controller alongside uMp-3 and uMp-4 micromanipulators, a move that underscores a continued emphasis on usability upgrades and controller-level integration. By late 2024, New Scale Technologies completed delivery of a Modular Insertion System to the Allen Institute for Neural Dynamics, enabling order-taking for next-generation silicon probe micromanipulation and highlighting the growing importance of modular, research-grade insertion workflows in neuroscience. More recently, planning for SLAS Europe 2026 has featured sessions examining manual micromanipulation in an era of lab automation, signaling a broader industry conversation about where manual control still adds value and where automation is reshaping protocols.
These developments matter because they reveal how incumbents and innovators are responding to the same underlying pressure: laboratories want higher throughput, better repeatability, and clearer integration paths without sacrificing the fine control required for delicate procedures. Companies that can bridge that gap through modular architecture, improved controller interfaces, or application-tuned mechanical designs are likely to capture disproportionate attention from advanced research groups and commercial testing organizations.
Operational Content: What the Report Delivers for Decision-Makers
This market research is designed as an operational instrument, not a static summary of figures. The report is structured to help strategy, product, and commercial teams translate market signals into concrete actions. It provides a detailed examination of product architectures across electric, hydraulic, and manual configurations, mapping each category to the performance trade-offs, maintenance profiles, and application fit that drive adoption decisions. Rather than treating these segments as isolated statistical buckets, the analysis situates them within the purchasing logic of end users who must balance precision, throughput, training burden, and lifecycle cost.
The report also traces application-level demand patterns in a way that is actionable for go-to-market planning. Cell micromanipulation remains a dominant use environment, driven by life science research, reproductive medicine workflows, and advanced cellular engineering. Industrial micromanipulation applications form a distinct and growing demand base, shaped by micro-assembly, inspection, and precision handling requirements in manufacturing-adjacent settings. Additional use cases extend the market's reach into specialized research and imaging workflows. By examining how these application clusters interact with product type preferences, procurement cycles, and regional laboratory infrastructure, the study helps companies identify where to concentrate sales engineering resources and where to adapt messaging for different operational realities.
Regional Context Without Overgeneralization
Geographic analysis in the report is framed around deployment density, institutional demand profiles, and the practical realities of supply and support networks rather than simplistic share rankings. North America continues to reflect a mature buyer base with strong exposure to neuroscience, electrophysiology, and advanced imaging research. Europe maintains a substantial footprint shaped by established academic institutions, clinical research infrastructure, and a strong tradition of precision instrumentation. Asia Pacific's trajectory is gaining attention as research investment, semiconductor-related precision needs, and expanding laboratory capacity reinforce demand across multiple application domains. Latin America and the Middle East and Africa, while smaller in absolute scale, represent targeted opportunities where specialized support, affordability, and application training can influence adoption more than headline market size alone.
By maintaining this contextual framing, the report helps clients avoid the trap of treating all regions as homogeneous. Regional strategy requires understanding what local laboratories prioritize, how procurement cycles differ, and which service and calibration capabilities are expected as baseline requirements. The analysis provides the qualitative scaffolding needed to translate market potential into realistic entry or expansion plans.
Industry Dynamics: Cost Pressure, Standards, and Cross-Sector Pull
One of the most important dynamics shaping procurement behavior is the tension between precision expectations and total cost of ownership. Industry commentary has noted that certain low-cost electric micromanipulator assemblies can materially undercut the price of commercial hydraulic alternatives while eliminating the need for regular maintenance. This cost dynamic does not uniformly displace premium systems, but it does reshape comparison sets, especially in laboratories balancing performance requirements against budget constraints. For vendors, this environment rewards clarity about where value is created: in stability, in integration, in service responsiveness, or in application-specific calibration that lower-cost alternatives cannot easily replicate.
Regulatory and standards developments are exerting a parallel influence. Recent consensus definitions and clinical guidance have formalized the role of micromanipulation within micro-operative assisted reproductive techniques, including ICSI and assisted hatching. These references may appear clinical on the surface, but they have commercial implications. They influence laboratory purchasing criteria, documentation expectations, and the degree of procedural justification required for equipment selection. Suppliers that understand how such standards filter into procurement checklists and internal validation processes are better positioned to support customers through adoption and to avoid friction in regulated environments.
On the demand side, a broader macro trend continues to accelerate interest in high-precision micromanipulation across neurology, biology, and semiconductor-adjacent sectors. The rise in R&D activity is not simply expanding the user base; it is changing the sophistication of the user base. More laboratories now expect repeatable positioning, better integration with imaging or automation peripherals, and clearer documentation for method reproducibility. That shift increases the strategic importance of product reliability and supplier support, while also expanding the addressable market for systems that can serve multi-application labs without sacrificing specialized performance.
Why This Study Matters for 2026 Decision-Making
2026 is a planning year in which many organizations must reconcile near-term budget constraints with long-term capability needs. The micromanipulators market is at a point where historical growth, product evolution, and application expansion are aligning in ways that reward informed strategic positioning. Companies that delay analysis risk overindexing to legacy product assumptions, misallocating sales coverage, or underestimating the importance of integration and service in buyer decisions. Organizations that act early can align product development, pricing architecture, channel strategy, and customer education with the demand patterns that are already shaping procurement behavior.
The strategic value of this research lies in its ability to connect multiple layers of evidence into a single decision framework. It grounds narrative insight in verified market sizing and forecast direction, integrates competitive profiles with recent product and deployment developments, and contextualizes those findings within the practical realities of laboratory and industrial purchasing. For executives evaluating market entry, portfolio expansion, partnership opportunities, or competitive response, the report offers a disciplined starting point that reduces uncertainty without oversimplifying a technically complex sector.
What Is Reserved for the Full Report
To preserve the analytical integrity and commercial utility of the study, this preview intentionally omits the detailed segmentation breakdowns, region-specific share figures, application-level revenue distributions, and type-level quantitative splits that support the broader narrative. Those data are essential for building precise financial models, sizing submarket opportunities, and benchmarking competitive exposure. They are also the core reason the full report functions as a working intelligence asset rather than a high-level overview. Clients who rely on top-line macro signals alone risk missing the structural differences that determine where value is created and where competition is most intense.
The complete study unpacks those layers in a format designed for internal strategy discussions, product planning sessions, and commercial forecasting. It connects market size movement to segment-level dynamics, maps competitive positioning to product and application fit, and provides the granularity needed to assess which opportunities are large enough to justify investment and which require a more targeted approach. For teams planning 2026 initiatives, that level of detail is not optional; it is the difference between directional confidence and decision-grade evidence.
How to Use This Intelligence
Organizations derive the most value from this research when they treat it as a strategic framework rather than a single-use reading. Product leaders can use the analysis to pressure-test roadmap assumptions against application demand and buyer cost sensitivity. Commercial teams can align territory plans and value propositions with the segments and use cases most likely to drive near-term growth. Corporate development and partnership teams can identify where interoperability, service networks, or application expertise create more advantage than raw manufacturing scale. Executive leadership can use the forecast trajectory and market concentration context to frame investment timing and risk tolerance with a clearer view of where growth is structural rather than cyclical.
In a market defined by precision, repeatability, and increasing application complexity, the organizations that outperform will be those that understand not just that demand is growing, but why it is growing, where it is concentrating, and what buyers now expect from the equipment they trust with critical workflows. This study is built to provide exactly that understanding.
To access the full segmentation detail, competitive benchmarking, application analysis, and forecast scenarios that support planning-level decisions, we invite you to review the complete Micromanipulators Market research on the source page. The complete dataset and proprietary analysis are available there for teams that need to move from market awareness to actionable strategy.
For detailed analysis of this topic, please visit the official page: Micromanipulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Motion Picture Visual Effects Service Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The motion picture VFX service market is witnessing a robust revenue trajectory, rising from $6,500 million in 2020 to $11,400 million in 2025 and projected to reach $23,800 million by 2035. This steady increase demonstrates the sector’s resilience and capacity for growth, even amid economic shifts and pandemic recovery. Factors such as global expansion, innovative production techniques, and surging demand for high-quality content on streaming and theatrical platforms are fueling revenue generation across all regions.
Read More - https://bussinessinsights.com/research-report/global-motion-picture-visual-effects-service
Feature films remain the dominant application for VFX services in 2025, representing 40% of the global market, as blockbuster releases and high-budget franchises continue to prioritize state-of-the-art visual storytelling. Television constitutes 26%, spurred by premium series on streaming platforms demanding top-tier effects. Commercials and online media account for 14% and 11% respectively, reflecting the digital transformation in advertising and content creation. The remaining 9% comprises animation movies and other applications, showcasing the market’s diversification. This trend illustrates the universal relevance of VFX across diverse entertainment and content segments.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-motion-picture-visual-effects-service
Frequently Asked Questions
Who are the key players in Global Motion Picture Visual Effects Service industry?
The top five players in the global motion picture visual effects (VFX) service industry include Industrial Light & Magic, Weta FX, Framestore, DNEG, and Sony Pictures Imageworks. These companies are renowned for delivering groundbreaking VFX for blockbuster films and television, continuously setting industry standards with innovative technology and creative artistry.
What is the Global Motion Picture Visual Effects Service growth?
The Global Motion Picture Visual Effects Service market has seen robust growth, driven by high demand for visually intensive films and streaming content. In 2023, companies like DNEG reported revenue increases due to major projects with Netflix and Marvel Studios, highlighting the industry's expansion and increasing investment in visual effects.
Which segment accounted for the largest Global Motion Picture Visual Effects Service share?
Feature films remain the largest application segment for VFX services, accounting for a significant market share. Blockbuster movies such as 'Avatar: The Way of Water' and Marvel franchise entries drive massive demand, as studios seek advanced digital effects to enhance visual storytelling and attract large global audiences.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global smart appliances market revenue demonstrates robust growth throughout the forecast period. In 2020, total revenue stood at $58,300 Million, surging to $74,800 Million by 2025, supported by rapid urbanization and evolving consumer tech preferences. Proliferation continues at an accelerated pace, with expected revenues reaching $178,200 Million in 2035 as smart appliance uptake expands rapidly in Asia-Pacific, North America, and Europe. The growth trajectory is characterized by successive waves of product innovation, energy-aware regulations, and escalating consumer demand for smart, connected living environments, with both residential and commercial sectors driving volume and value.
Read More - https://bussinessinsights.com/research-report/global-smart-appliances
The residential sector maintains the largest share of the global smart appliances market in 2025, constituting approximately 56% due to increased household adoption of smart ecosystems. Commercial segments, including retail and hospitality, represent the next highest share, driven by the need for operational efficiency and enhanced customer experiences. Healthcare and industrial applications, while smaller in market share, are experiencing the fastest growth as IoT-enabled appliances facilitate better process management and patient safety. The integration of smart appliances into everyday operations demonstrates their significance beyond homes, marking them as essential assets for future-ready business environments.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-smart-appliances
Frequently Asked Questions
Who are the key players in Global Smart Appliances industry?
The top 5 players in the global smart appliances industry are Samsung Electronics, LG Electronics, Whirlpool Corporation, Haier Group, and Bosch (BSH Home Appliances). These companies are recognized for their innovation, extensive product portfolios, and robust global distribution networks, making them leaders in smart home technology solutions.
What is the Global Smart Appliances growth?
The global smart appliances market is experiencing significant growth, projected to expand at a CAGR of over 15% from 2023 to 2028. This growth is driven by rising smart home adoption, with companies like Samsung investing heavily in IoT-enabled appliances and AI-driven functionalities.
Which segment accounted for the largest Global Smart Appliances share?
The residential application segment holds the largest share in the global smart appliances market. Driven by increased smart home penetration and consumer preference for convenience, products like smart refrigerators and washing machines dominate residential adoption, accounting for a substantial portion of industry revenue.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Electronic Educational Toys Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global electronic educational toys market is projected to grow from USD 7,800 Million in 2020 to USD 16,450 Million by 2035. Steady year-over-year growth is underpinned by rising STEM education demand, technological innovations, and expanding global access. Notably, APAC and North America drive substantial revenue, supported by digital transformation in education. As manufacturers upscale investments in AI, AR/VR, and sustainable designs, revenue growth is expected to remain strong throughout the forecast period.
Read More - https://bussinessinsights.com/research-report/global-electronic-educational-toys
The primary school segment leads the global electronic educational toys market by application in 2025, accounting for a significant market share. This surge is attributed to increased adoption of curriculum-aligned edutainment solutions across schools and at home. The pre-school and home use segments also witness robust growth, driven by parental demand for early learning and at-home educational engagement. Special education and secondary school applications, while comparatively smaller, are benefitting from inclusivity trends and individualized learning technologies, broadening the market’s reach across diverse learner profiles.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-electronic-educational-toys
Frequently Asked Questions
Who are the key players in Global Electronic Educational Toys industry?
Key players include LEGO Group, Mattel Inc., Hasbro Inc., VTech Holdings Limited, and LeapFrog Enterprises. These companies lead with innovative learning products, strong brand recognition, and broad distribution networks. LEGO enhances STEM skills, while VTech and LeapFrog focus on interactive, technology-driven educational toys globally.
What is the Global Electronic Educational Toys growth?
The Global Electronic Educational Toys market has experienced steady growth, driven by increased e-learning adoption. For example, VTech Holdings reported double-digit growth in 2023, propelled by demand for tech-integrated toys and digital learning solutions as parents and schools deepen investments in interactive, educational play tools.
Which segment accounted for the largest Global Electronic Educational Toys share?
The pre-school segment accounted for the largest share in the Global Electronic Educational Toys market. Products targeting ages 3-5 dominate due to heightened demand for cognitive development tools. Brands like Fisher-Price and LeapFrog offer innovative solutions that support early learning, literacy, and numeracy through interactive play.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Barcode Label Printer Market to Reach $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-07
Executive Brief: Navigating the Barcode Label Printer Market 2026-2032
In an era where supply chain resilience and data integrity dictate competitive advantage, the barcode label printer has evolved from a peripheral utility to a strategic asset. As enterprises across logistics, healthcare, manufacturing, and retail confront mounting regulatory pressures and volatile input costs, the need for precise, forward-looking intelligence has never been greater. The updated Barcode Label Printer Market Research offered by PW Consulting delivers exactly that: a comprehensive, data-grounded examination of where the market stands, how it is shifting, and what decision-makers must anticipate through the end of the decade. This article serves as a strategic preview of the full report, outlining the executive value proposition and highlighting the analytical frameworks embedded within our latest publication.
Food Preservative Sodium Benzoate Market
The global landscape for barcode label printers is undergoing a phase of structural redefinition. Demand is no longer driven solely by volume replacement cycles; it is being reshaped by compliance mandates, automation trends, edge computing integration, and sustainability expectations. Understanding these forces requires more than a snapshot of current sales. It demands a disciplined look at historical trajectories, near-term inflection points, and the competitive architecture that will determine market share allocation in the years ahead. PW Consulting’s assessment is built to support exactly that level of strategic foresight.
PCB Automated Visual Inspection(AVI) System Market
Market Trajectory and Strategic Context: 2020-2032
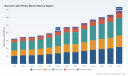
The baseline figures in our analysis trace a clear upward arc across the historical window from 2020 through 2025, establishing a foundation of consistent expansion even amid macroeconomic disruptions. That momentum carries forward into the forecast horizon extending to 2032, with a projected compound annual growth rate (CAGR) reinforcing the market’s resilience and long-term relevance. For leadership teams evaluating capital allocation, operational readiness, or vendor partnerships, the scale of this expansion is meaningful. A market that crosses multiple hundred-million-dollar thresholds over the forecast window signals sustained demand for label printing solutions across both mature and emerging use cases.
Industrial Low-Temperature Heat Pump Systems Market
More important than any single headline figure is the rhythm of growth itself. The trajectory reflects a market that is not merely recovering but recalibrating around new operational priorities: higher print reliability at the edge of the warehouse floor, compact and ruggedized devices for mobile workflows, and printer portfolios aligned with connected inventory systems. The data narrative in the full report connects these demand-side shifts to revenue growth patterns, enabling readers to align procurement planning, product roadmaps, and regional expansion strategies with realistic quantitative expectations. Because the complete breakdown of regional contributions, technology preferences, application weightings, and device-type distributions is detailed within the report itself, this preview intentionally retains the macro-level framing. That approach preserves the analytical gravity of the dataset while directing readers to the source for the precise figures required to model their own scenarios.
What the Report Delivers: Operational Intelligence Beyond the Numbers
A strong market study does more than summarize past performance; it equips stakeholders with a usable framework for action. PW Consulting’s Barcode Label Printer Market research has been constructed with that standard in mind. The publication is organized to serve a range of internal functions, from procurement and supply chain leadership to product strategy, competitive intelligence, and financial planning. Each section is designed to reduce ambiguity around market structure and to clarify where investment and procurement decisions should be prioritized.
Core Components of the Report
- Historical sizing and forecast modeling spanning the full analysis window, enabling year-by-year context for revenue evolution and growth pacing.
- Structural segmentation analysis that maps the market across device categories, printing technologies, key application environments, and geographic regions, providing the scaffolding needed to understand where value concentrates and where opportunities are emerging.
- Competitive profiling of leading participants, including positioning summaries and technology focus areas, so that buyers and competitors alike can benchmark capability sets and strategic intent.
- Documentation of recent corporate developments, such as product launches, line extensions, and trade-show activations, offering a timely view of how major players are translating strategy into market-facing moves.
- Assessment of market concentration indicators, giving readers a sense of fragmentation, consolidation risk, and bargaining dynamics within the supplier base.
- Industry context review covering regulatory updates, raw-material cost pressures, and logistics disruptions that are reshaping manufacturing economics and lead-time reliability for printer hardware.
This structure is deliberate. By combining quantitative market sizing with qualitative event tracking and external factor analysis, the report functions as a decision-support tool rather than a static reference. Readers can use it to validate assumptions, pressure-test expansion plans, and identify which operational variables merit closer monitoring. For organizations that depend on label printing as part of broader identification, traceability, or fulfillment workflows, that blend of data and context is indispensable.
Competitive Landscape: Established Leaders and Specialized Challengers
The competitive environment in barcode label printing is defined by a blend of global automation incumbents, specialized identification technology providers, and regional specialists with strong cost-performance positioning. The report profiles a broad cross-section of these companies, capturing how each is shaping its offering for distinct operational environments. This matters because procurement decisions are increasingly tied not only to unit price but to integration readiness, durability, connectivity features, and alignment with sector-specific compliance requirements.
Major Participants and Strategic Positioning
- Zebra Technologies Corporation remains deeply embedded in the high-volume identification space, with printer solutions extending across industrial, desktop, mobile, and RFID-enabled formats for logistics, retail, and healthcare environments. Recent activity underscores a continued push toward faster print speeds, hygiene-conscious device design, and advanced RFID integration for warehouse and clinical settings.
- Honeywell International Inc. emphasizes rugged desktop and portable printers with integrated scanning functionality, targeting industrial and warehouse use cases where durability and hands-free data capture matter. Its recent portable printer series highlights an interest in embedding AI-assisted data processing functions for healthcare and retail workflows.
- SATO Holdings Corporation focuses on industrial and mobile thermal label printers optimized for high-speed output in manufacturing, logistics, and healthcare, reinforcing the importance of throughput and reliability in mission-critical environments.
- TSC Auto ID Technology Co., Ltd. positions cost-effective industrial and mobile printers for demanding warehouse and logistics conditions, appealing to operators that need robust performance without premium price structures.
- Brother Industries, Ltd. serves high-volume and point-of-sale applications with industrial desktop and mobile thermal barcode label printers, reflecting a balance between commercial print density and operational simplicity.
- Seiko Epson Corporation offers label printers and dedicated barcode printing devices for retail, shipping, and industrial applications, extending its imaging heritage into operational identification workflows.
- Toshiba Tec Corporation contributes industrial desktop barcode and label printers tailored to manufacturing and logistics, aligning printer capability with material handling and production-line identification needs.
- DYMO (Newell Brands) concentrates on compact desktop and portable label printers and label makers for office, retail, and shipping use, while also expanding toward eco-friendly label materials in response to sustainability-driven demand.
- Citizen Systems Japan Co., Ltd. delivers high-performance desktop and portable printers for POS and industrial use, supporting environments that require consistent output and quick deployment.
- BIXOLON Co., Ltd. brings mobile, desktop, and industrial label and barcode printers into retail, logistics, and healthcare contexts, with recent visibility at international retail technology events signaling continued portfolio expansion.
- GoDEX International Co., Ltd. offers high-resolution desktop and mobile barcode label printers for industrial and commercial applications, targeting users that prioritize print clarity and versatility across commercial workflows.
These profiles are not mere company summaries. They are structured to help readers understand how each participant competes: through ruggedization, integrated scanning, RFID readiness, cost-efficient industrial output, compactness for office and shipping use, or sustainability features. For procurement leaders comparing vendor shortlists, or for strategists tracking possible consolidation and capability migration, this competitive mapping offers a practical lens. The full report broadens this view with additional market context and development tracking, allowing users to connect corporate moves to the broader growth pattern described earlier in the analysis.
Industry Dynamics: Regulation, Materials, and Supply Chain Pressures
Market growth does not occur in a vacuum. The current cycle is heavily influenced by external forces that affect both demand and the economics of supplying hardware. The report integrates several of these dynamics so that readers can anticipate friction points and compliance-driven opportunities rather than react to them after the fact.
Regulatory and Standards Developments
In North America, updated industry guidance for standard case code labeling has reinforced best practices for GS1-128 barcode compliance in grocery and foodservice sectors. This type of standardization typically raises the baseline expectation for print quality, label durability, and data formatting consistency, which in turn influences equipment selection and integration planning for distributors and retailers. At the same time, the U.S. Drug Supply Chain Security Act continues to drive mandatory adoption of barcode-enabled tracking systems in healthcare and pharmaceutical distribution. For printer suppliers and end users alike, these regulatory currents increase the strategic importance of reliable, traceable, compliant printing equipment.
Input Costs and Trade Constraints
Hardware economics are being pressured by a combination of material cost escalation and export-control dynamics. Rising U.S.-China technology trade tensions, including restrictions on semiconductor-related exports, have contributed to higher costs for rare earth elements used in printer hardware components. This input-cost environment is a reminder that pricing stability in the barcode printer market can be influenced as much by global trade policy and material availability as by end-market demand. Organizations planning multi-year printer deployments should factor such volatility into total cost of ownership assumptions and inventory timing.
Logistics Disruptions and Lead-Time Exposure
Supply chain conditions remain a practical concern for hardware sourcing. Prolonged transit delays in key maritime routes have extended shipping timelines and increased per-container costs, disrupting component imports for barcode printers. For buyers, this translates into longer lead times, potential deployment schedule slippage, and a stronger case for risk-buffered procurement strategies. For suppliers, it reinforces the value of regional inventory positioning and demand forecasting discipline. These dynamics are not short-term anomalies to be wished away; they are part of the operating reality that the report’s market outlook incorporates when framing the path toward 2032.
Strategic Implications for 2026 Decision-Making
What does this body of analysis mean for executives making decisions in 2026? First, it confirms that the barcode label printer market remains a growth-relevant category with broad cross-industry demand. The scale of the forecast trajectory and the underlying growth rate indicate that label printing infrastructure should be treated as a long-duration capability rather than a discretionary purchase. Second, the competitive landscape shows that no single device category or supplier profile fits every environment. Industrial throughput, mobile flexibility, desktop simplicity, integration with scanning and RFID, and sustainability-oriented materials all represent distinct value propositions that must be matched to operational requirements.
Third, external pressures—regulatory compliance, raw-material cost exposure, and logistics disruptions—make timing, sourcing strategy, and vendor reliability more important than ever. Organizations that evaluate printer portfolios with these factors in mind can reduce procurement risk, improve deployment predictability, and align hardware choices with compliance expectations in healthcare, retail, and food distribution workflows. Fourth, recent product activity from major participants signals that the market is moving toward faster, more connected, and in some cases more hygiene- or sustainability-conscious devices. Keeping pace with these developments requires ongoing monitoring, which is precisely the role the full report is designed to serve.
Leaders in finance, operations, procurement, and product strategy can use the research to address questions that often remain under-examined until a disruption forces attention: Where is demand expanding most reliably? Which device types and technologies dominate different parts of the market? How concentrated is supplier power, and what does that imply for negotiation and roadmap flexibility? What external shocks could alter cost structures or delivery timelines? The report is built to support that level of internal discussion with documented data and current event context, while leaving the detailed segment-level breakdowns available for deeper modeling within the full publication.
Final Word: Why This Research Belongs on the 2026 Planning Agenda
The barcode label printer market may appear, on the surface, to be a mature hardware category. In practice, it is a bellwether for how well organizations are adapting to traceability mandates, edge-level automation, mobile operational models, and supply chain cost pressures. PW Consulting’s updated market research offers a rigorous, current, and decision-oriented view of that landscape, bridging historical performance, forward-looking growth, competitive positioning, and external dynamics in a single structured assessment.
This article has outlined the macro framework and the report’s practical value without exposing the full segment-level intelligence that makes the study actionable for specific planning scenarios. For teams that need exact market sizing by region, device type, technology, and application, along with the accompanying competitive and industry-context detail, the complete Barcode Label Printer Market report is the appropriate next step. It is designed to convert high-level awareness into procurement confidence, portfolio strategy, and risk-informed planning. In a market where compliance, cost, and continuity all matter at once, that level of clarity is not optional—it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Barcode Label Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DDoS Protection Market Hits $2.15B in 2025, Projects 13.83% CAGR to $5.38B by 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the 2026 DDoS Protection and Mitigation Landscape
Executive Overview
The cybersecurity ecosystem in 2026 is defined by a relentless arms race between defenders and adversaries. As digital transformation accelerates across every industry sector, the surface area for attack expands in parallel. Among the most persistent and disruptive threats facing Chief Information Security Officers today is the Distributed Denial of Service (DDoS) attack. What was once considered a nuisance has evolved into a sophisticated instrument of geopolitical coercion, extortion, and competitive sabotage. PW Consulting presents this comprehensive market research to dissect the economic and technological architecture of DDoS Protection and Mitigation, offering enterprise leaders the intelligence required to navigate a high-stakes environment.
Mini LED Vehicle Display Market
This analysis serves not merely as a snapshot of current expenditures but as a strategic roadmap for the forecast period spanning 2026 through 2032. By understanding the trajectory of capital allocation, technology adoption, and competitive maneuvering, organizations can transform their security posture from reactive survival to proactive resilience. The following insights distill the core findings of our latest study, highlighting the macroeconomic drivers, the shifting competitive dynamics, and the operational considerations that will define success in this domain.
TFT Liquid Crystal Materials Market
Market Trajectory and Financial Performance
The VDDOS Protection and Mitigation market has demonstrated robust and consistent growth over the past half-decade, reflecting the essential nature of these services. Historical data from 2020 to 2025 indicates a steady upward climb in revenue, driven by increasing awareness of threat vectors and the tangible costs associated with downtime. The market has progressed from a valuation of approximately 1.61 billion USD in 2020 to an estimated 2.15 billion USD by the base year of 2025. This progression underscores a fundamental shift: security budgets are no longer discretionary but are instead foundational to business continuity.
Hollow Glass Window Market
Looking toward the forecast horizon, the momentum shows no signs of deceleration. Projections indicate the market will reach 2.42 billion USD in 2026, continuing its expansion to exceed 5 billion USD by 2032. This growth is underpinned by a compound annual growth rate (CAGR) of 13.83 percent through the end of the forecast period. Such a rate places DDoS mitigation among the faster-growing segments within the broader cybersecurity infrastructure landscape. For financial planners and IT strategists, this trajectory suggests that sustained investment will be necessary to keep pace with the evolving sophistication of attack mechanisms. The integration of these services into broader cloud architectures and the rising frequency of volumetric attacks ensure that demand will remain inelastic relative to economic fluctuations.
It is important to note that these figures represent the aggregate global market. The distribution of this value across different geographical zones and deployment models reveals further complexity. Organizations must look beyond the headline numbers to understand how specific regional dynamics and operational preferences influence total cost of ownership and efficacy. Detailed breakdowns of regional revenue contributions and specific deployment splits are critical for tailoring local strategies, and these granular insights are fully elaborated within the complete market research publication.
Market Dynamics: Drivers Forces and Restraints
Several interrelated factors are propelling the expansion of the DDoS protection market. The primary driver remains the escalating scale and frequency of attacks. Adversaries are leveraging larger botnets composed of compromised Internet of Things devices and cloud instances, enabling them to generate traffic volumes that threaten even well-engineered network perimeters. Furthermore, the motivation behind these attacks has diversified. Nation-state actors utilize DDoS as a tool of hybrid warfare, while criminal syndicates employ it for ransomware extortion and smokescreening during data breaches. This diversity in threat origin requires enterprises to adopt protection strategies that are equally versatile.
Infrastructure evolution is another critical driver. As enterprises migrate workloads to public and hybrid cloud environments, the traditional perimeter dissolves. This necessitates a shift from hardware-centric mitigation to scalable, software-defined protection that can span multiple environments without introducing significant latency. The requirement for always-on availability, particularly for digital-native businesses and critical service providers, mandates that mitigation capabilities be integrated directly into the content delivery and application layers. Consequently, the market is seeing a convergence of DDoS protection with broader web application firewall (WAF) and bot management services, creating bundled solutions that offer unified threat management.
However, the market does face headwinds that warrant strategic consideration. Operational costs associated with high-throughput scrubbing centers and the energy consumption of data center infrastructure are rising. Recent analysis suggests that data center electricity demand could potentially affect electricity rates if that demand leads to a meaningful change in the local utility's costs. This creates a secondary financial pressure on service providers, which may trickle down to pricing models for enterprise customers. Additionally, cybercrime-related DDoS attacks have caused unplanned data center outages, highlighting the physical realities of digital threats. These events serve as reminders that mitigation is not just about software rules but also about physical infrastructure resilience and redundancy.
Regulatory environments are also reshaping the landscape. In the European Union, the European Union Agency for Cybersecurity mandates operators in 18 critical sectors to meet resilience and 24-hour reporting requirements. Such mandates compel organizations to adopt certified mitigation capabilities and maintain rigorous incident response protocols. Compliance is no longer optional; it is a license to operate for many critical industries. To explore how these regulatory pressures vary by region and how they impact specific vertical market segmentations, stakeholders are encouraged to review the detailed sector analysis provided in the full report.
Technology Architecture Segmentation
The market is broadly categorized by how protection is deployed and the layer at which mitigation occurs. Deployment models have evolved as organizations seek to balance control, scalability, and cost. Cloud-based solutions currently represent a significant portion of the market, reflecting the industry-wide shift toward cloud-native architectures. These solutions offer the advantage of elastic scalability, allowing mitigation capacity to expand instantly in the face of massive volumetric attacks without requiring customers to procure additional hardware.
Hybrid models remain relevant for organizations with specific regulatory or latency requirements. These approaches combine the scalability of the cloud with the immediate response capabilities of on-premises appliances. On-premises deployment, while representing a smaller share of the market, persists in environments where data sovereignty or ultra-low latency is paramount. The choice between these models often depends on the specific risk profile of the organization and its architectural maturity. Detailed analysis of the revenue distribution across cloud-based, hybrid, and on-premises segments, along with the implications for procurement strategy, is available in the comprehensive segmentation chapter of the study.
Protection type segmentation further refines the market view. Network-based protection focuses on the infrastructure layer, filtering malicious traffic before it reaches application servers. This is essential for mitigating volumetric attacks that aim to saturate bandwidth. Application-based protection operates at the Layer 7 level, distinguishing between legitimate user requests and sophisticated application-layer attacks. Host-based solutions provide a final line of defense at the operating system level. As attacks become more targeted, the reliance on a single protection type is diminishing. Multi-layered strategies that integrate network, application, and host-based defenses are becoming the standard for high-security environments. The specific revenue attributable to each protection type and the growth rates associated with each layer are detailed within the full research document, providing clarity on where innovation spending is concentrated.
Competitive Landscape and Strategic Positioning
The competitive environment in the DDoS Protection and Mitigation market is characterized by a mix of established security vendors, cloud hyperscalers, and specialized network defense firms. Market concentration metrics indicate a moderately concentrated industry, where the top three companies hold a CR3 of 34.5 percent and the top five companies account for a CR5 of 42.0 percent. This structure suggests that while there are dominant players, there is still ample room for niche players and regional specialists to compete on differentiation.
Akamai Technologies continues to leverage its extensive distributed network to offer robust defense. Their Prolexic DDoS protection platform emphasizes behavioral defense and offers flexible deployment options including in-cloud, on-premise, and hybrid configurations. With dedicated infrastructure for both network and application layer attacks, Akamai positions itself as a comprehensive solution for large enterprises requiring global reach and deep expertise.
Cloudflare has carved out a strong position by integrating DDoS protection directly into its global anycast network. Their approach relies on automated L3/L4/L7 mitigation rulesets and CDN-integrated scrubbing, which allows for real-time bot and botnet defense. This integration simplifies operations for customers who already utilize Cloudflare for content delivery, creating a sticky ecosystem where security and performance are managed through a single pane of glass.
Imperva focuses on a multi-layered doctrine that covers networks, applications, APIs, and DNS. Their services emphasize automated mitigation backed by threat intelligence, appealing to organizations that need to secure complex application architectures including microservices and API gateways. Radware offers a distinct value proposition through its hybrid on-premise appliances and cloud scrubbing centers. Their adaptive real-time mitigation for L3/L4/L7 attacks and application security is supported by continuous innovation, such as the recent partnership expansion with Chief Telecom to launch the Godshield Pro DDoS protection service in Taiwan. This move highlights the industry trend toward regional partnerships to deliver high-performance, low-latency mitigation for local enterprises.
NETSCOUT Systems brings a legacy of network visibility to the table with their Arbor DDoS protection portfolio. Including Arbor Edge Defense, Arbor Cloud, and Threat Mitigation System, their suite is designed for perimeter and enterprise-scale volumetric attacks. F5 Networks contributes to the competitive field with Silverline DDoS protection and F5 Distributed Cloud Services, offering an integrated WAF and bot mitigation capabilities within a multi-cloud SaaS platform. Corero Network Security targets service providers and enterprises with their SmartWall real-time DDoS mitigation solutions, focusing on high-performance distributed defense.
Recent developments illustrate the dynamism of this competitive arena. Amazon Web Services launched a DDoS Protection feature for game developers via Amazon GameLift Servers, providing UDP-based proactive mitigation without manual byte matching and negligible latency. This demonstrates how cloud providers are embedding security into specific developer tools to capture niche markets. GTT Communications expanded global DDoS scrubbing capacity to 4 Tbps with new mitigation centers in São Paulo, Hong Kong, and Miami, signaling a race to increase capacity and reduce latency geographically. Radware also introduced Alteon Protect, an expansion of their AI-driven cloud security platform for scalable application security enforcement. These moves highlight a market where companies are constantly expanding capacity, entering new regions, and integrating AI to stay ahead of threat actors. Corero Network Security expanded real-time DDoS protection services into Pakistan and nearby regions via partnership with Beyond Technology MEA, exemplifying the push for global coverage. Stakeholders seeking a complete competitive benchmarking analysis, including detailed profiles of all key companies and their specific strategic moves, should refer to the full competition chapter of this report.
Forward Outlook 2026 to 2032
As we look toward the remainder of the decade, the DDoS Protection and Mitigation market is poised for continued evolution. The forecast period through 2032 suggests a market valuation trajectory that will likely reshape procurement strategies. The convergence of security and network functions, driven by the adoption of SASE and secure access service edge architectures, will likely blur the lines between traditional DDoS mitigation and broader network security operations.
Innovation in mitigation technology will likely focus on reducing the human burden of management. Automated response systems that can distinguish between legitimate traffic spikes and malicious floods without manual intervention will become a baseline requirement. Additionally, the integration of threat intelligence feeds that anticipate attack patterns before they materialize will add value to premium service tiers. As the threat landscape incorporates more artificial intelligence on the attacker's side, defenders will need equally sophisticated AI-driven defense mechanisms to maintain parity.
For enterprise decision-makers, the implications are clear. Continuing to rely on fragmented security tools will increase risk and operational overhead. The strategic value lies in selecting partners and platforms that offer integrated visibility and scalable mitigation capacity. Investing in education and incident response planning is equally critical, as technology alone cannot prevent all disruptions. The detailed scenario analysis and forecast models contained in our full study provide the quantitative backing needed to justify these investments and allocate resources effectively across the 2026 to 2032 timeline.
Conclusion
The DDoS Protection and Mitigation market represents a critical component of the modern cybersecurity infrastructure. With a robust growth trajectory, evolving competitive dynamics, and increasing regulatory pressures, the sector offers both challenges and opportunities for industry participants. Understanding the macro trends and the specific capabilities of market leaders is essential for crafting a resilient security strategy.
This overview provides a glimpse into the depth of analysis available in the complete PW Consulting market research report. To access granular data on regional revenue splits, detailed segmentation percentages, specific company market shares, and comprehensive sales channel analysis, we invite you to explore the full publication. The complete intelligence gathered here is designed to empower your organization with the actionable insights necessary to thrive in an increasingly hostile digital environment.
For detailed analysis of this topic, please visit the official page: DDoS Protection and Mitigation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Natural Stone Tiles Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
Between 2020 and 2025, the global natural stone tiles market witnessed a healthy growth trajectory, with revenue increasing from $32,500 million in 2020 to an estimated $45,800 million in 2025. Continued growth is projected, reaching around $72,000 million by 2035. This steady climb is largely attributed to surging demand from the construction sector, urbanization in developing countries, premiumization, and growing investments in advanced processing technology. Innovations in production, distribution, and varied applications are anticipated to further fuel market expansion throughout the forecast period.
Read More - https://bussinessinsights.com/research-report/global-natural-stone-tiles
Residential applications constitute the largest share of the global natural stone tile market at 41% in 2025, reflecting robust demand for luxury and durable surfaces in homes. Commercial use accounts for 29%, with offices, hotels, and retail spaces increasingly favoring high-quality stone tiles for ambience and resilience. Institutional and industrial sectors comprise about 18%, with a focus on long-term investment in public and utility spaces. The remaining segments are infrastructure and others, accounting for a combined 12%. Residential leadership highlights the sector’s fundamental role in driving overall market expansion.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-natural-stone-tiles
Frequently Asked Questions
Who are the key players in Global Natural Stone Tiles industry?
The top five players in the Global Natural Stone Tiles industry are Levantina, Polycor, Dal-Tile, Antolini, and Temmer Marble. These companies are recognized for their extensive product portfolios, innovative manufacturing techniques, strong global distribution networks, and strategic acquisitions that bolster their market positions.
What is the Global Natural Stone Tiles growth?
The Global Natural Stone Tiles market has demonstrated steady growth, driven by rising construction activity and renovation trends. For instance, Polycor’s recent capacity expansion in 2023 helped meet growing demand for sustainable building materials, marking a significant factor boosting overall market growth.
Which segment accounted for the largest Global Natural Stone Tiles share?
The flooring application segment holds the largest share of the Global Natural Stone Tiles market. High durability, aesthetic appeal, and increasing usage in both residential and commercial infrastructure projects have accelerated demand, making floors the dominant application in the natural stone tiles market.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global AI Speech Recognition Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
From 2020 to 2035, the global market revenue for AI speech recognition is expected to rise sharply. In 2025, the revenue stands at $11,240 Million, marking robust year-on-year expansion driven by digital transformation and increased enterprise adoption across industries. The continuous shift to cloud-based solutions, expansion of virtual assistant capabilities, and more widespread applications in both developed and emerging markets underline this growth. The USD Million market revenue trajectory reflects not only technological advancement but also evolving business priorities where voice interactions and automation are paramount.
Read More - https://bussinessinsights.com/research-report/global-ai-speech-recognition
The healthcare sector leads the way in adopting AI speech recognition, accounting for the largest share in 2025, followed by automotive and banking & finance. Healthcare's use of AI-powered dictation, transcription, and voice-mediated patient care reflects ongoing digitization and adoption of electronic health records. The automotive industry's focus on hands-free control and in-vehicle assistants boosts AI speech investment. Banking & finance prioritize speech-based authentication and customer engagement, while retail and education sectors accelerate use for customer support and personalized learning. The trend toward diverse applications highlights the market’s expanding impact on day-to-day business operations.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-ai-speech-recognition
Frequently Asked Questions
Who are the key players in Global AI Speech Recognition industry?
The top 5 players in the global AI speech recognition market are Google, Microsoft, Amazon Web Services, IBM, and Apple. These companies continually innovate, offering robust speech-to-text APIs and digital assistants, leveraging advanced AI algorithms and cloud infrastructure to power scalable and accurate speech recognition solutions worldwide.
What is the Global AI Speech Recognition growth?
The global AI speech recognition market is experiencing significant growth, with a projected CAGR exceeding 20% from 2023 to 2028. Recent growth is driven by rising adoption in automotive and healthcare sectors, alongside advancements by Microsoft in integrating AI speech capabilities into Azure Cognitive Services.
Which segment accounted for the largest Global AI Speech Recognition share?
The consumer application segment holds the largest share in the Global AI Speech Recognition market. Widespread use of voice assistants like Amazon Alexa, Apple Siri, and Google Assistant in smartphones and smart home devices has accelerated market penetration and consumer adoption globally.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com