

Blogs
PW Consulting: Capsule Filling Machines Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-07
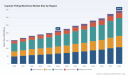
Strategic Imperatives in the Capsule Filling Machines Market: Navigating Growth Through 2032
The global pharmaceutical and nutraceutical manufacturing landscape is undergoing a profound transformation, driven by accelerating demand for precise, compliant, and high-throughput encapsulation technologies. As industry leaders confront tightening regulatory frameworks, evolving product formulations, and intensifying competitive pressures, the Capsule Filling Machines Market has emerged as a critical nexus of operational efficiency and strategic investment. This analysis draws from PW Consulting’s latest comprehensive market research to illuminate the structural forces shaping the sector, offer actionable intelligence for 2026 decision-making, and frame the strategic questions that forward-looking organizations must address to secure long-term competitive advantage.
Adhesion Prevention Gel Market
Macro Trajectory and The Architecture of Growth
The sector’s historical performance reflects a sustained expansion trajectory. From a baseline valuation of approximately 153.44 million USD in 2020, market revenue climbed steadily through the mid-2020s, reaching 215.0 million USD by 2025. This upward momentum is projected to continue, with the market anticipated to attain 226.24 million USD in 2026 and accelerate toward 344.8 million USD by 2032. The compound annual growth rate of 6.98 percent underscores a moderate yet resilient expansion profile, one that is neither speculative nor saturated, but rather anchored in structural demand drivers across regulated manufacturing ecosystems.
Angular Contact Axial Bearing Market
This growth architecture is not uniform. It is shaped by divergent regional adoption curves, varying capital expenditure cycles, and the gradual migration of production capacity toward markets with expanding domestic pharmaceutical and supplement manufacturing bases. While specific regional revenue contributions and application-level breakdowns are detailed within the full research repository, the overarching narrative is clear: the market is consolidating around mature demand centers while simultaneously cultivating high-growth corridors that reward early-mover capital allocation and localized technical partnerships. Organizations that map their investment horizons to these geographic and application-specific inflection points will be best positioned to capture disproportionate share gains.
Piston Ring Wire Market
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The competitive environment exhibits moderate market concentration, with the top three players collectively commanding approximately 24.6 percent of global revenue and the top five holding roughly 26.2 percent. This fragmented-yet-consolidating structure creates a dynamic arena where scale, technological differentiation, and regulatory compliance capabilities determine market access and pricing power. A diverse cohort of manufacturers operates across this spectrum, each pursuing distinct value propositions tailored to specific production volumes, formulation complexities, and compliance requirements.
European engineering firms continue to anchor the high-end segment, leveraging decades of precision dosing expertise and advanced rotary or suction bowl architectures. One prominent German-based provider offers a flagship capsule filling series optimized for high-volume pharmaceutical and nutraceutical production, emphasizing precision dosing and high throughput. In Italy, multiple manufacturers have established strong footholds by delivering rotary and advanced dosing systems capable of processing up to 200,000 capsules per hour, while others focus on flexible E Series and IN-CAP platforms that accommodate powders, pellets, tablets, mini-tablets, and capsule-in-capsule configurations, all engineered to meet CE and cGMP compliance standards. A separate Italian manufacturer has expanded its automatic capsule filling portfolio with machines specifically engineered for pharmaceutical and supplement production, reinforcing the region’s reputation for high-accuracy encapsulation hardware.
Asia-Pacific and transcontinental players are increasingly shaping the mid-to-high volume segments through integrated solutions that balance operational simplicity, safety, and efficiency. An Indian-headquartered global supplier delivers integrated capsule filling systems tailored for pharmaceutical and nutraceutical applications, emphasizing reliability and streamlined operational workflows. In Japan, a Tokyo-based technology provider delivers encapsulation solutions and capsule filling equipment designed for global pharmaceutical manufacturers, reinforcing the importance of geographic proximity to advanced drug delivery research ecosystems. Meanwhile, United States-based manufacturers contribute to the domestic supply chain with USA-made capsule filling equipment and service capabilities, while a New Jersey-based firm specializes in encapsulation equipment for pharmaceutical and nutraceutical applications.
French and German packaging specialists further diversify the competitive field. A France-based entity under the Lonza Group umbrella specializes in hard capsule filling machines and encapsulation systems focused on advanced drug delivery applications. In Germany, another engineering firm develops high-efficiency capsule filling and packaging systems designed for integrated pharmaceutical production lines. Chinese and hybrid-market manufacturers also play a growing role, with several firms offering semi-automatic and industrial-grade capsule filling machines that bridge manual-automation workflows, alongside laboratory-scale and mass-production units designed for pharmaceutical and supplement manufacturing. These providers continuously refine their product portfolios, as evidenced by recent equipment upgrades aimed at improving precision and efficiency in pharmaceutical manufacturing environments.
2025–2026 Innovation Cycles and Product Lifecycle Acceleration
The past several months have witnessed a noticeable acceleration in product launches and technology showcases, signaling an industry-wide push toward human-centered design, advanced dosing combinations, and tighter weight control systems. In late 2025, one European manufacturer introduced a new platform within its E Series, featuring human-centered design principles, advanced dosing combinations, and integrated weight control systems designed to reduce batch variability and streamline operator workflows. Shortly thereafter, the same company debuted an automatic capsule filling machine at a major European trade fair, showcasing support for multiple fill types with throughput capabilities reaching 3,000 capsules per hour, alongside full CE and cGMP compliance alignment. These releases reflect a broader industry pattern: manufacturers are not merely iterating on mechanical performance but are increasingly engineering for flexibility, operator ergonomics, and real-time quality feedback.
Concurrently, other players have advanced their equipment modernization roadmaps. A notable equipment upgrade launched in mid-to-late 2025 targeted precision and efficiency improvements for a widely deployed capsule filling model, reinforcing the competitive imperative to reduce downtime, enhance dosing repeatability, and support faster changeover cycles. Such innovation cycles are particularly consequential for 2026 capital planning, as they introduce new benchmarking criteria for total cost of ownership, maintenance predictability, and integration readiness with existing packaging and inspection lines. Organizations evaluating equipment refresh cycles or capacity expansions must assess not only baseline throughput figures but also the trajectory of software-driven control systems, modular dosing adaptability, and vendor-supported compliance documentation.
Regulatory Dynamics as a Strategic Filter
Regulatory compliance has evolved from a baseline operational requirement into a strategic filter that shapes procurement decisions, vendor selection criteria, and market entry pathways. In 2026, capsule filling equipment deployed in pharmaceutical and nutraceutical production must align with stringent sanitation, reliability, calibration, inspection, and maintenance expectations codified under FDA cGMP regulations. Equipment intended for dietary supplement manufacturing must additionally satisfy compliance frameworks specific to supplement production, while pharmaceutical-grade systems must adhere to broader cGMP expectations for equipment safety, sanitation, and operator protection. These requirements do not merely influence equipment design; they dictate documentation rigor, validation protocols, and the ability to demonstrate consistent quality management across production runs.
Beyond domestic regulatory frameworks, international market access increasingly depends on standardized certification pathways. ISO 9001 and ISO 22000 certifications are expected for capsule filling machine manufacturers seeking to assure consistent quality management and food safety in regulated production environments. For pharmaceutical applications, CE marking and cGMP compliance have become de facto prerequisites for market access in regulated regions, meaning that procurement teams must evaluate not only mechanical performance but also the completeness of compliance portfolios, audit readiness, and the vendor’s capacity to support lifecycle documentation. Furthermore, equipment transactions involving domestic, import, and export flows are subject to mandatory electronic reporting requirements, adding an administrative compliance layer that procurement, legal, and logistics functions must coordinate. These regulatory dynamics collectively raise the bar for vendor qualification and reinforce the strategic value of partnering with manufacturers that maintain robust quality management systems and transparent compliance documentation.
Operational and Strategic Implications for 2026 Capital Allocation
For manufacturing executives, R&D leaders, and procurement strategists, the Capsule Filling Machines Market in 2026 presents a window of calculated investment. The combination of moderate but steady market growth, a moderately concentrated competitive field, and an accelerating product innovation cycle creates a favorable environment for strategic equipment selection, capacity planning, and vendor partnership development. Several operational implications warrant particular attention.
- Total cost of ownership extends beyond purchase price. Organizations must evaluate dosing precision, changeover flexibility, maintenance predictability, and compliance documentation as integral components of long-term value. Equipment that reduces batch variability and supports faster sanitation or reconfiguration cycles can yield measurable gains in throughput consistency and quality assurance.
- Compliance readiness is a procurement differentiator. As regulatory expectations intensify across pharmaceutical and nutraceutical production lines, vendors that provide comprehensive CE and cGMP alignment, robust quality management certifications, and transparent lifecycle support will command preferential positioning in supplier evaluations.
- Flexibility is increasingly tied to formulation complexity. The ability to handle powders, pellets, tablets, mini-tablets, and specialized fill configurations is no longer a niche requirement. Manufacturers developing multi-SKU production strategies or transitioning between dosage forms will prioritize machines that offer advanced dosing combinations and modular adaptability.
- Innovation cycles demand forward-looking refresh planning. Recent product launches and technology showcases indicate that equipment performance benchmarks are shifting toward operator-centered design, weight control precision, and higher throughput efficiency. Procurement teams should align capital planning horizons with vendor roadmaps to avoid stranded investments in rapidly evolving equipment categories.
- Regional demand divergence rewards localized strategy. While mature markets continue to drive stable demand, emerging manufacturing corridors are cultivating distinct procurement rhythms, regulatory nuances, and service expectations. Organizations that tailor their equipment sourcing, service agreements, and compliance strategies to regional operating conditions will gain agility in market expansion and supply chain resilience.
What the Full Research Delivers: A Practical Intelligence Framework
PW Consulting’s comprehensive Capsule Filling Machines Market research is structured to translate macro-level market dynamics into actionable, segment-specific intelligence. The report provides a detailed examination of revenue trajectories, segmentation architectures, competitive positioning, regulatory impact pathways, and innovation timelines, all calibrated to support 2026 strategic planning and multi-year forecasting. Rather than offering static snapshots, the analysis maps the structural relationships between equipment type adoption, application demand patterns, regional deployment trends, and vendor competitive strategies, enabling readers to model investment scenarios, assess supplier qualification criteria, and anticipate shifts in procurement prioritization.
The research framework is designed for cross-functional application. Manufacturing and operations leaders can leverage the segmentation and equipment-type analysis to benchmark capacity planning and changeover requirements. Procurement and supply chain teams can use competitive landscape and compliance data to refine vendor scoring matrices and total cost of ownership models. Executive strategists and investors can draw on the market trajectory, concentration metrics, and innovation cycle synthesis to evaluate market entry timing, partnership opportunities, and long-term sector resilience. By maintaining a disciplined focus on decision-ready intelligence—not merely descriptive market narration—the report equips stakeholders to convert market complexity into structured strategic action.
Conclusion: Positioning for Deliberate Growth
The Capsule Filling Machines Market is at an inflection point where steady expansion, regulatory rigor, and accelerating technological differentiation converge. The projected trajectory from 226.24 million USD in 2026 toward 344.8 million USD by 2032, supported by a compound annual growth rate of 6.98 percent, reflects a market that is expanding through structural demand rather than transient cycles. In this environment, the organizations that thrive will be those that treat equipment selection, compliance alignment, vendor partnership, and innovation readiness as interconnected strategic levers rather than isolated procurement tasks.
The full market research provides the granular segmentation data, competitive benchmarking, regulatory impact mapping, and scenario-based forecasting required to operationalize these decisions with precision. For executives and strategic planners seeking to align capital allocation with long-term manufacturing resilience, the report offers a comprehensive foundation for evidence-based action. We invite you to access the complete research repository to examine the detailed regional, application, and equipment-type breakdowns, competitive profiles, and forward-looking analysis that will further sharpen your 2026 strategic roadmap.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From 2020 to 2035, the Asia-Pacific train seat market displays a consistent upward trajectory, with revenue expanding from $2,050 Million in 2020 to an estimated $5,830 Million by 2035. Recovery from pandemic lows, surging public investment in new transit projects, and rapid urbanization contribute to an accelerating CAGR post-2025. The mid-2020s mark a turning point, as mega-project rollouts in China, India, and Southeast Asia accelerate replacement cycles and foster multi-year procurement contracts. Sophisticated seat technologies and sustainability mandates further push average selling prices and overall market value higher.
Read More - https://bussinessinsights.com/research-report/asia-pacific-train-seat-market
The application landscape in 2025 is dominated by Metro Trains, which account for the largest market share regionally, highlighting the focus on rapid transit in urban environments. High-Speed Trains form the next largest segment, reflecting substantial government investments in cross-country rail corridors. Light Rail and Trams are gaining traction as cities seek efficient, lower-emission alternatives for medium-capacity transit routes. Locomotives and Passenger Coaches continue to represent steady demand, especially in nations with large rural networks, though they are overshadowed by rapid transit system investments directed at decongesting megacities.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-train-seat-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Train Seat Market industry?
Key players include Faurecia, Grammer AG, Fainsa, Freedman Seating Company, and Qingdao TransAsia Railway Equipment Co., Ltd. These companies lead the market with advanced seat designs, passenger comfort innovation, and robust supply chains, supporting high-speed rail and urban transit projects across major Asia-Pacific economies.
What is the Asia-Pacific Train Seat Market growth?
The Asia-Pacific Train Seat Market is witnessing strong growth, driven by extensive rail network expansions, particularly in China and India. For instance, Faurecia recently secured contracts to provide ergonomic seating solutions for new bullet trains, contributing significantly to the region's modernization and overall market growth.
Which segment accounted for the largest Asia-Pacific Train Seat Market share?
The passenger trains segment accounted for the largest share in the Asia-Pacific Train Seat Market. This dominance is attributed to extensive deployment of seating solutions in high-speed and commuter trains, where comfort, durability, and safety are prioritized to accommodate growing intercity and metropolitan ridership.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Electronics Conformal Coating Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific Electronics Conformal Coating Market is projected to exhibit consistent revenue growth, with revenue rising from $2,340 million in 2020 to $3,320 million in 2025 and reaching approximately $6,950 million by 2035. This trajectory is underpinned by expanding electronics manufacturing, widening applications, and adoption of advanced technologies across key countries like China, Japan, and India. The robust CAGR reflected in this period underscores increasing investments in electronics reliability and regulatory compliance.
Read More - https://bussinessinsights.com/research-report/asia-pacific-electronics-conformal-coating-market
Consumer electronics claim the largest segment share in the Asia-Pacific conformal coating market in 2025, propelled by rising device production. Automotive applications follow, reflecting increasing electronic content per vehicle and stricter standards, while industrial and aerospace & defense sectors demand robust protection due to critical environment conditions. Medical device applications, though smaller in volume, demonstrate rapid growth as regulatory and reliability requirements rise. The market's diversity is underpinned by the ongoing digitization across segments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-electronics-conformal-coating-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Electronics Conformal Coating Market industry?
The top five players in the Asia-Pacific Electronics Conformal Coating Market are Dow, Henkel AG & Co. KGaA, H.B. Fuller Company, Chase Corporation, and MG Chemicals. These companies are recognized for their technological innovation, diverse product portfolios, and extensive regional distribution, maintaining strong positions across key electronics manufacturing hubs in Asia-Pacific.
What is the Asia-Pacific Electronics Conformal Coating Market growth?
The Asia-Pacific Electronics Conformal Coating Market is experiencing robust growth, driven by rising electronics production and miniaturization trends. In 2023, major players like Henkel reported increased demand from automotive electronics and consumer electronics sectors, propelling estimated market growth at a CAGR of over 7% through 2028.
Which segment accounted for the largest Asia-Pacific Electronics Conformal Coating Market share?
Consumer electronics accounted for the largest market share in the Asia-Pacific conformal coating market. The segment benefits from escalating demand for mobile devices, wearables, and home appliances that require enhanced circuit protection, with manufacturers rapidly adopting advanced coatings to ensure reliability and product longevity.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Self-Organizing Network Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
Asia-Pacific’s SON market revenue is projected to exhibit sustained growth from USD 2,250 Million in 2020 to USD 8,720 Million by 2035. The market’s upward trajectory is fueled primarily by swift 5G adoptions, increased mobile subscriber base, and mounting demand for automation solutions in telecom networks. The transition from 4G/LTE to 5G, coupled with digital transformation in enterprises, continually broadens the addressable market. Revenue acceleration is especially notable from 2025 onwards, coinciding with major regional rollouts, network densification, and cloud-based SON expansion across public and private network domains.
Read More - https://bussinessinsights.com/research-report/asia-pacific-self-organizing-network-market
Performance Management commands the largest share of SON applications in Asia-Pacific for 2025, followed by Network Optimization and Network Security. Performance management’s leading role reflects operators’ commitment to delivering consistent, high-quality user experiences as network demand escalates. Network optimization applications underpin efforts to maximize efficiency, reduce congestion, and manage costs, while security is increasingly prioritized due to evolving threat landscapes and automation risks. As 5G scales, other applications like configuration management and reliable service assurance will see further adoption.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-self-organizing-network-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Self-Organizing Network Market industry?
The top five players in the Asia-Pacific Self-Organizing Network Market are Huawei Technologies, Nokia Corporation, Ericsson, ZTE Corporation, and Samsung Electronics. These companies offer advanced SON solutions, leveraging AI and automation to optimize complex telecom networks for improved efficiency, reliability, and reduced operational costs.
What is the Asia-Pacific Self-Organizing Network Market growth?
The Asia-Pacific Self-Organizing Network Market is experiencing significant growth, with a CAGR exceeding 10% in recent years. For instance, Huawei announced new AI-driven SON deployments in 2023, accelerating 5G rollouts and enhancing network automation, which has contributed to overall market expansion.
Which segment accounted for the largest Asia-Pacific Self-Organizing Network Market share?
The mobile operators application segment held the largest market share in the Asia-Pacific SON market. With the surge in mobile data and 5G adoption, telecom operators are extensively deploying SON solutions to optimize networks, improve performance, reduce manual intervention, and deliver superior user experiences.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Thin Film and Printed Battery Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
Asia-Pacific thin film and printed battery market revenue grew from USD 298 Million in 2020 to USD 470 Million in 2025. Continued demand across high-growth end-use sectors is forecast to drive a robust uptrend, surpassing USD 2,150 Million by 2035. Key industry players’ investment in advanced battery chemistries, streamlining of supply chains, and product miniaturization are expected to accelerate revenue momentum throughout the forecast period.
Read More - https://bussinessinsights.com/research-report/asia-pacific-thin-film-and-printed-battery-market
Consumer Electronics represent the largest application segment with 38% share in the 2025 Asia-Pacific thin film and printed battery market, fuelled by integration in smartphones, wearables, and wireless accessories. Medical Devices account for 25%, enabled by ongoing innovation in ultra-slim battery technology for implants, diagnostics, and home monitoring. IoT Devices follow at 17%, reflecting rapid deployment in smart cities and industrial automation. Other applications, including smart packaging and cards, showcase nascent yet promising market potential driven by technological breakthroughs and new business models from leading enterprises.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-thin-film-and-printed-battery-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Thin Film and Printed Battery Market industry?
The top 5 players in the Asia-Pacific Thin Film and Printed Battery Market are Panasonic Corporation, Enfucell Oy, Samsung SDI, Blue Spark Technologies, and LG Chem. These companies focus on innovations in miniaturized, flexible, and high-efficiency battery technologies to meet the rising demand from consumer electronics and IoT applications.
What is the Asia-Pacific Thin Film and Printed Battery Market growth?
The Asia-Pacific Thin Film and Printed Battery Market is experiencing notable growth, projected to exhibit a double-digit CAGR through 2028. Recently, Samsung SDI expanded production capacity in South Korea, leveraging growing adoption of wearables and smart medical devices to cater to the region's increasing demand.
Which segment accounted for the largest Asia-Pacific Thin Film and Printed Battery Market share?
Consumer electronics held the largest application share in the Asia-Pacific Thin Film and Printed Battery Market. The segment benefits from rising usage of smart cards, fitness bands, and wearable devices, driving demand for compact, flexible, and lightweight battery solutions across Japan, China, and South Korea.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Over the 2020–2035 period, the Asia-Pacific audio amplifier market exhibits robust growth. Starting from an estimated USD 4,800 Million in 2021, market revenues surge past USD 8,000 Million by 2025, driven by escalating electronics adoption and automotive development. By 2030, market revenues are expected to exceed USD 13,400 Million, with projections reaching over USD 18,500 Million by 2035 as digital transformation deepens in both consumer and industrial sectors.
Read More - https://bussinessinsights.com/research-report/asia-pacific-audio-amplifier-market
Consumer electronics command the largest share of the market in 2025, affirming the significance of smart TVs, personal audio, and wearables. Automotive applications are rapidly rising, supported by vehicle connectivity and infotainment trends, while home audio systems hold substantial ground driven by the smart home wave. Professional, commercial, and industrial uses represent a diversified but less dominant segment, collectively making up the remaining share.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-audio-amplifier-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Audio Amplifier Market industry?
The top five players in the Asia-Pacific Audio Amplifier Market include Texas Instruments, STMicroelectronics, Yamaha Corporation, Infineon Technologies, and Maxim Integrated. These companies offer a wide range of innovative audio amplifier solutions, focusing on efficiency, product reliability, and integration for consumer electronics, automotive, and industrial applications.
What is the Asia-Pacific Audio Amplifier Market growth?
The Asia-Pacific Audio Amplifier Market is experiencing robust growth, driven by rising demand for high-quality audio in consumer electronics. For instance, in 2023, Texas Instruments reported strong sales growth due to increasing adoption of infotainment systems and portable audio devices in the region.
Which segment accounted for the largest Asia-Pacific Audio Amplifier Market share?
The consumer electronics segment, led by applications in smartphones, televisions, and portable devices, accounts for the largest market share. This growth is attributed to the surge in demand for high-fidelity audio experiences and the continuous innovation in audio technologies across major Asia-Pacific countries.
Thanks & Regards,
priya
sales@bussinessinsights.com
The global aluminium ladder market is projected to scale from USD 2,800 million in 2020 to approximately USD 5,400 million by 2035, reflecting a steady CAGR. Growth is propelled by higher construction spending, industrial expansion, and increased adoption in residential renovations. The revenue trend indicates consistent year-on-year upward movement, especially post-2025 as smart and multipurpose ladders gain ground.
Read More - https://bussinessinsights.com/research-report/global-aluminium-ladder
As of 2025, industrial applications dominate the aluminium ladder market, reflecting the need for robust and safe climbing equipment in factories and warehouses. The construction sector remains a significant consumer, driven by new building projects worldwide. Residential applications are on the rise, fueled by increasing DIY activities and home renovations. Commercial and institutional use, while smaller, continues to show steady demand, particularly for lightweight and portable ladder solutions.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-aluminium-ladder
Frequently Asked Questions
Who are the key players in Global Aluminium Ladder industry?
The top 5 players in the Global Aluminium Ladder industry include Werner Co., Louisville Ladder Inc., Altrex B.V., ZARGES GmbH, and Gorilla Ladders. These companies are leaders in innovation, safety standards, and expansive distribution networks, playing a central role in driving global market competition and technological advancements.
What is the Global Aluminium Ladder growth?
The Global Aluminium Ladder market has witnessed steady growth in recent years, driven by increased infrastructure development and residential construction. For instance, Werner Co. reported strong sales growth in 2023 due to rising demand in both developed and emerging markets.
Which segment accounted for the largest Global Aluminium Ladder share?
The residential segment accounted for the largest share in the Global Aluminium Ladder market. High usage in maintenance, home improvement, and do-it-yourself (DIY) activities has propelled this segment's dominance, especially in North America and Europe, as more homeowners invest in multipurpose, lightweight ladders.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: SOI Market to Reach $3.85B by 2032, 13.5% CAGR Predicted Globally
By PW Consulting, 2026-09-07
Beyond the Bulk: Why the Silicon-on-Insulator Market Is Rewiring Strategic Planning for 2026 and Beyond
The semiconductor substrate landscape is undergoing a structural recalibration. For decades, bulk CMOS dominated the architecture of integrated circuits, but the relentless pursuit of power efficiency, radio frequency performance, and isolation integrity has pushed Silicon-on-Insulator technology from a specialized niche into a mainstream strategic imperative. As device geometries shrink and application demands compound, the SOI ecosystem is no longer a passive supplier of wafers. It is becoming a decisive determinant of product roadmaps, supply chain resilience, and regional manufacturing footprints. Our latest market research on the Silicon-on-Insulator Market is designed to give executives, product planners, and capital allocators the clarity required to navigate this inflection point with confidence.
Worldwide Asthma Nebulizer Market
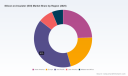
The trajectory is unmistakable. From 2020 through 2025, the global SOI market expanded from 0.85 billion USD to 1.6 billion USD, reflecting a compound annual growth rate that underscores sustained demand across mobility, connectivity, and high-performance computing verticals. Looking forward, the forecast period from 2026 to 2032 projects the market reaching 3.85 billion USD, driven by a CAGR of 13.5 percent. These figures are not abstract aggregates. They reflect a fundamental shift in how device manufacturers evaluate trade-offs between performance, power, and process complexity. For leadership teams planning capital deployment, capacity allocation, and partnership strategies in 2026, understanding the underlying architecture of this growth is no longer optional. It is a prerequisite for competitive positioning.
Worldwide Live Attenuated Influenza Vaccine (LAIV) Market
This report is structured to convert macroeconomic momentum into operational intelligence. Rather than stop at headline numbers, we map the forces shaping demand, the technologies redefining supply, and the competitive dynamics that will separate resilient players from vulnerable incumbents. The following sections preview the depth and practical orientation of the full study, while deliberately reserving the granular segmentation data for the complete report, where regional, type-level, and application-level breakdowns are presented with the precision required for investment committee and board-level decision-making.
18K Gold Jewelry Market
The Structural Case for SOI in a Performance-Constrained Era
The renewed emphasis on Silicon-on-Insulator reflects a convergence of electrical, thermal, and integration requirements that traditional bulk substrates struggle to satisfy simultaneously. SOI architectures introduce a buried oxide layer that decouples the active silicon film from the bulk substrate, delivering benefits that cascade across device physics. Reduced parasitic capacitance enables faster switching and lower dynamic power consumption. Enhanced isolation supports mixed-signal integration without cross-talk penalties. Radiation hardness and latch-up immunity broaden the technology's relevance to automotive, aerospace, and industrial applications where reliability is non-negotiable. For RF designs, the insulator layer provides a foundation for high linearity and low loss, which is critical as wireless standards evolve toward higher bandwidth and more complex modulation schemes.
These attributes are not incremental. They are reshaping design hierarchies. System architects are increasingly evaluating SOI not as a substitute for bulk silicon, but as a domain-specific enabler for functions where power, speed, and isolation define the performance envelope. That shift is visible across multiple end markets. Automotive electronics are demanding more robust, lower-power sensor and control architectures. Telecom infrastructure is pushing RF front-end complexity higher as 5G and next-generation Wi-Fi deployments mature. Consumer electronics continue to prioritize energy efficiency in always-on and edge-processing workloads. Each of these vectors contributes to sustained SOI adoption, but the composition of demand varies by region, application maturity, and technology generation. The full report dissects these variations in detail, allowing readers to see where the highest-value opportunities are forming and where growth is more transitional.
Market Dynamics: Capacity, Policy, and the New Geography of Risk
Capacity expansion is currently one of the most consequential forces in the SOI market. Producers are investing in larger-diameter wafers, improved bonding and separation processes, and dedicated lines for RF and power-oriented variants. Recent industry activity illustrates the pace of change. In March 2026, Soitec announced a EUR 500 million expansion of its 300 mm SOI facility in Bernin, France, lifting annual capacity by 40 percent to strengthen supply for automotive and RF applications. Earlier, in November 2025, Tower Semiconductor expanded its 300 mm wafer bonding technology across SiPho and RF-SOI platforms, targeting compact high-performance chips for wireless and automotive ICs. In December 2024, Soitec and GlobalFoundries formalized a supply arrangement for 300 mm RF-SOI substrates to support next-generation RF technologies in 5G and Wi-Fi markets. By mid-2024, GlobalWafers had increased 200 mm SOI wafer production and introduced 300 mm SOI manufacturing at its MEMC plant, signaling a broader transition toward advanced-diameter capability.
Policy and trade dynamics are equally influential. CHIPS Act funding has been enabling domestic SOI wafer capacity additions that reduce lead-time risk, with companies having announced more than 140 semiconductor projects across the United States totaling over USD 640 billion in investments since 2020. At the same time, global trade tensions and tariffs are impacting the cost of silicon substrates and related manufacturing equipment, driving regional SOI manufacturing and strategic investments. For executives, these forces create a dual imperative: secure supply continuity while managing exposure to geopolitical and input-cost volatility. The report quantifies these dynamics in a structured framework, helping organizations assess where localized capacity, long-term agreements, and multi-source strategies will deliver the greatest risk-adjusted value.
A critical element of the dynamic environment is the concentration of supply among established producers. The market displays meaningful consolidation, with the top three players accounting for 58 percent of revenue and the top five reaching 72 percent. Such concentration can support scale economics, process consistency, and customer confidence, but it also raises questions about supply flexibility, pricing power, and the pace at which new entrants or differentiated technology variants can gain traction. Understanding this concentration is essential for procurement strategy, partnership evaluation, and long-term capacity planning. The full report explores how this structure interacts with demand segmentation and technology transitions, without reducing the analysis to simplistic rankings.
Technology Segmentation and the Real Meaning of Type-Level Demand
SOI is not a single product category. It is a family of technologies, each optimized for different electrical and mechanical requirements. Thin Film SOI continues to serve a broad range of applications where a thin active layer supports low-power and high-speed operation. FD-SOI has gained attention for its ability to deliver high performance with reduced leakage and simplified biasing control, making it attractive for specific mobile, IoT, and edge-processing scenarios. RF-SOI remains central to wireless infrastructure, front-end modules, and connectivity ICs, where linearity, loss, and integration density define competitiveness. Together, these types represent a substantial share of current demand, but their relative importance is shifting as design priorities evolve and as 300 mm processing becomes more widely available.
What matters strategically is not only which type is growing, but why. Thin Film SOI demand is influenced by the balance between performance needs and cost sensitivity in high-volume electronics. FD-SOI adoption is shaped by design ecosystem maturity, tooling availability, and the degree to which designers can leverage bias-controlled performance for power-constrained devices. RF-SOI growth is tied to the expansion of wireless standards, the complexity of antenna and front-end architectures, and the push toward software-defined radio and advanced connectivity. The complete report provides a structured comparison of these types, mapping their technical value propositions to application fit, production economics, and near-term adoption catalysts. This allows decision-makers to see where each technology is positioned within the broader market and how the mix is expected to change over the forecast horizon.
Application Demand: Where the Growth Is Concentrated and Why
The SOI market's expansion is being propelled by a set of application categories that are each undergoing their own technology and volume transitions. Automotive systems continue to place heavier demands on sensor interfaces, power management, and robust electronics capable of operating in harsh environments. Telecom and 5G infrastructure are driving sustained RF-SOI requirements as base stations, small cells, and terminal devices evolve toward higher throughput and more complex signal processing. Consumer electronics remain a significant contributor, especially where low-power ICs, display drivers, and connectivity modules rely on the efficiency advantages of insulating substrates. A smaller but strategically important share of demand comes from other specialized applications that value isolation, radiation tolerance, or custom device configurations.
The strategic challenge for most organizations is not recognizing that these sectors matter, but determining how their SOI demand will behave as product cycles mature, as regional manufacturing shifts, and as alternative substrate or packaging approaches compete for share. In the full report, we break down application-level demand with enough granularity to support sourcing strategy, product positioning, and investment prioritization. We focus on the mechanisms that drive volume growth, the sensitivity of each segment to technology transitions, and the ways in which supply constraints or cost dynamics can alter adoption timing. This approach is designed to help leaders move beyond broad market narratives and into the kind of segment-level clarity that supports realistic forecasts and defensible plans.
Competitive Landscape: Leaders, Differentiators, and the Shape of the Battlefield
The SOI market is defined by a set of companies that combine wafer processing expertise, technology heritage, and increasingly, capacity scale. Soitec, headquartered in Bernin, France, is a leading designer and producer of SOI wafers through its Smart Cut technology, with strong relevance to mobile communications, automotive, and smart devices. Its recent capacity expansion underscores the strategic importance of 300 mm supply for high-volume RF and automotive demand. GlobalWafers, based in Taiwan, is a supplier of RF-SOI and Power-SOI wafers and has been expanding 300 mm manufacturing capacity, positioning itself at the intersection of connectivity and power-oriented substrate needs. Shin-Etsu Chemical, in Tokyo, Japan, is a mass producer of 300 mm SOI wafers for high-speed and low-power consumption applications, reflecting the scale and quality focus required in advanced wafer supply. SUMCO Corporation, also based in Tokyo, manufactures bonded SOI wafers for high integration, low power, high speed, and high reliability devices, emphasizing versatility across demanding device categories.
Other players add important dimensions to the competitive map. Shanghai Simgui Technology, in Shanghai, China, manufactures SOI wafers and EPI wafers using SIMOX, bonding, and Simbond technologies, illustrating the breadth of process approaches in the market. Okmetic, in Vantaa, Finland, is a pioneer in bonded SOI wafers for MEMS sensors, power devices, and RF applications, with E-SOI and C-SOI variants that target specialized performance and integration needs. Silicon Valley Microelectronics, in Santa Clara, California, operates as a distributor and provider of thin and thick film SOI wafers, cavity SOI, and custom manufacturing for low-power and high-speed devices, serving customers that require flexibility and tailored substrate configurations. Tower Semiconductor, in Migdal Haemek, Israel, provides foundry RF-SOI platforms for wireless and automotive ICs, linking substrate supply with integrated device solutions and platform-level differentiation.
These companies are not competing in a vacuum. Their strategies are increasingly shaped by capacity timing, process migration to 300 mm, customer co-development, and the ability to align substrate supply with downstream integration requirements. Recent developments show this clearly. Soitec's facility expansion directly targets automotive and RF supply scale. Tower Semiconductor's platform expansion connects bonding technology with compact high-performance chips. Soitec and GlobalFoundries' supply agreement ties substrate capability to next-generation RF technology roadmaps. GlobalWafers' production increases and 300 mm introduction reflect a broader industry push toward advanced-diameter economics. The report evaluates these moves within a competitive framework that considers technological differentiation, geographic positioning, customer relationships, and the implications for procurement and partnership strategy. Full company-level assessments, including capability mapping and strategic posture, are provided in the complete study.
How the Report Converts Intelligence into Decision Support
A market study is only valuable if it can be used. This report is built around practical decision support rather than descriptive storytelling. It combines quantitative context with qualitative analysis to address the questions that executives and technical leaders face when planning for 2026 and beyond. The structure is designed to support multiple use cases, from capacity and sourcing strategy to technology roadmapping, competitive positioning, and investment prioritization.
The report includes detailed coverage of the following areas:
- Macro market trajectory and forecast logic, anchored in historical performance and forward projections across the forecast period, with an emphasis on the drivers that explain the pace of growth rather than merely restating outcomes.
- Technology segmentation analysis that compares Thin Film SOI, FD-SOI, and RF-SOI in terms of performance fit, production economics, and adoption catalysts, helping readers anticipate where each variant will gain or lose relative importance.
- Application-level demand analysis that links automotive, telecom, consumer electronics, and other end-use categories to underlying technology requirements, volume dynamics, and regional variation, without reducing the picture to a single aggregate number.
- Competitive profiling of key producers and platform players, including their process strengths, capacity direction, and strategic moves, so that organizations can benchmark suppliers and assess partnership or procurement options.
- Market dynamics and risk framework covering capacity expansion, policy-enabled investments, trade-related cost pressures, and concentration effects, with guidance on how to interpret supply resilience and exposure.
- Strategic implications for capital allocation, sourcing architecture, technology selection, and regional planning, presented as actionable perspectives rather than abstract observations.
Throughout, the analysis is designed to be modular. Procurement teams can focus on supplier positioning and supply resilience. R&D and product leaders can concentrate on technology fit and application drivers. Strategy and finance groups can use the forecast logic, concentration data, and dynamic risk framework to inform scenario planning and capital decisions. The full report provides the underlying segmentation detail necessary to support these different lenses, while maintaining a consistent narrative about where the market is heading and why.
Why This Research Matters for 2026 Decision-Making
The key strategic question for 2026 is not whether SOI matters, but how to position within a market that is expanding quickly, consolidating selectively, and being reshaped by policy, trade, and technology migration. The headline growth rate of 13.5 percent and the projected ascent to 3.85 billion USD by 2032 indicate a market with durable momentum, but momentum alone does not tell an organization what to do. Decision-makers need to know where demand is most structurally supported, which supplier capabilities will become more valuable, how regional capacity shifts affect lead times and cost, and where competitive differentiation will be earned.
Our research addresses these questions by connecting market size to market mechanics. It examines how capacity additions change the supply environment, how policy and trade pressures influence regional manufacturing incentives, how concentration affects negotiation leverage and continuity risk, and how technology segmentation determines which applications and customers will drive the most valuable growth. This integrated view is especially important in a market where a single sourcing decision, technology choice, or capacity commitment can have multi-year consequences. The report is intended to reduce uncertainty in those decisions by replacing general assumptions with structured, evidence-based analysis.
At the same time, we recognize that the most useful intelligence is often the most specific. Regional demand composition, application-level revenue splits, and type-level market shares are essential for precise planning, but they are also the details that require careful interpretation. For that reason, the complete study presents these breakdowns in full, along with the methodology and context needed to use them responsibly. The preview above establishes the strategic frame; the full report delivers the operational detail.
Conclusion: A Market at the Intersection of Performance and Supply Chain Strategy
Silicon-on-Insulator has moved from a specialized substrate option to a central element of modern semiconductor strategy. Its value lies not only in device physics, but in the way it enables performance, power, and integration goals that are increasingly difficult to achieve with bulk alternatives alone. The market's growth trajectory reflects that value proposition, but it also reflects a broader set of forces: capacity investment, policy support, trade and cost pressures, technology migration, and a competitive field that is consolidating around scale, process maturity, and platform relevance.
For leaders planning in 2026, the most important task is to align strategy with the realities of this evolving landscape. That means understanding where growth is most durable, where supply risk is concentrated, where technology differentiation matters most, and how supplier capabilities map to future demand. Our Silicon-on-Insulator Market research is designed to provide that alignment. It offers a rigorous, decision-oriented view of the market, with enough depth to support strategic planning and enough discipline to avoid overgeneralization.
The complete report provides the full segmentation detail, competitive depth, and dynamic analysis needed to turn market insight into executable strategy. For organizations that depend on substrate supply, device performance, and supply chain resilience, that level of clarity is not a luxury. It is the foundation for smarter capital decisions, stronger partnerships, and more confident technology roadmaps in the years ahead.
For detailed analysis of this topic, please visit the official page: Silicon-on-Insulator (SOI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global felt tip pens market revenue is projected to grow steadily from $1,138 million in 2020 to approximately $2,130 million by 2035. The growth trajectory is driven by persistent demand in education, business, and creative sectors, with periodic boosts from product innovation and regional expansion. A notable uptick is observed after 2025 as eco-friendly and digital-hybrid stationery offerings gain traction in developed and emerging markets alike.
Read More - https://bussinessinsights.com/research-report/global-felt-tip-pens
The office and commercial segment dominates the applications share in 2025 due to heavy usage in businesses, meetings, and presentations. Educational use follows, fueled by increased adoption of felt tip pens in schools and colleges for creative projects and note-taking. The art & design application shows robust growth as hobbyists and professionals seek premium markers for illustration and calligraphy. The residential and other sectors represent emerging opportunities, especially as remote work and home education trends persist.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-felt-tip-pens
Frequently Asked Questions
Who are the key players in Global Felt Tip Pens industry?
The top five players in the global felt tip pens market include Sanford (Paper Mate), Faber-Castell, STABILO, Pilot Corporation, and Schneider Pen. These leading brands are known for innovative designs, strong reputations, and extensive distribution networks, serving educational, professional, and artistic markets worldwide with high-quality products.
What is the Global Felt Tip Pens growth?
The global felt tip pens market has shown a steady growth rate of 4-5% CAGR in recent years. Notably, Faber-Castell reported increased sales in 2023, driven by rising demand for creative and affordable writing tools in both school and professional settings.
Which segment accounted for the largest Global Felt Tip Pens share?
The education segment holds the largest share in the felt tip pens market. Schools and colleges worldwide commonly use these pens for writing, drawing, and art projects due to their affordability, vibrant colors, and ease of use, which drive continuous demand in the sector.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The Asia-Pacific EMC filtration market has exhibited strong revenue growth, with market size rising from $2,500 million in 2020 to an estimated $4,000 million in 2025. Forecasts indicate this momentum will continue, reaching approximately $9,800 million by 2035. Growth is fueled by digital transformation, the surge in electric mobility, and industrial automation. While consumer electronics and EV sectors are immediate drivers, regulatory pressures and technological advances will sustain high single-digit CAGR across the forecast period.
Read More - https://bussinessinsights.com/research-report/asia-pacific-emc-filtration-market
Consumer Electronics leads application segments in the Asia-Pacific EMC filtration market, reflecting rapid technology adoption and growing consumer demand for smarter devices. Automotive applications are gaining ground due to the electrification of vehicles and integration of sophisticated ADAS technologies. Industrial applications round out the top three, driven by smart factories and automation. This application distribution reaffirms the region's shift toward interconnected, high-performance environments that rely on comprehensive EMC management.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-emc-filtration-market
Frequently Asked Questions
Who are the key players in Asia-Pacific EMC Filtration Market industry?
The top 5 players in the Asia-Pacific EMC Filtration Market are Schaffner Group, TDK Corporation, Delta Electronics, ONFILTER Inc., and Murata Manufacturing Co., Ltd. These companies are renowned for their extensive product portfolios and innovative solutions in EMC filters, catering to diverse industrial and electronics markets across the region.
What is the Asia-Pacific EMC Filtration Market growth?
The Asia-Pacific EMC Filtration Market is experiencing robust growth, projected at a CAGR of around 6.5% from 2023 to 2028. Recent growth is driven by increased investments in electronics manufacturing, with companies like TDK Corporation expanding production capacities to meet rising demand.
Which segment accounted for the largest Asia-Pacific EMC Filtration Market share?
The industrial sector accounted for the largest share of the Asia-Pacific EMC Filtration Market. Industries such as automotive, telecommunications, and consumer electronics widely utilize EMC filters to prevent electromagnetic interference, ensuring product reliability and compliance with regulatory standards in heavily industrialized regions.
Thanks & Regards,
Priya
sales@bussinessinsights.com