

Blogs
The Asia-Pacific Sensor Patch market is set for exponential growth, with revenues anticipated to surge from USD 560 million in 2020 to USD 2,950 million by 2035. The meteoric rise is attributed to strong government eHealth initiatives, a burgeoning tech-savvy population, and escalating demand for chronic disease and fitness monitoring solutions. Recent improvements in sensor technology and wide-scale adoption by healthcare institutions support this upward trajectory. Significant investments by global and regional players in R&D and distribution expansion are expected to further strengthen market momentum through the next decade.
Read More - https://bussinessinsights.com/research-report/asia-pacific-sensor-patch-market
Healthcare remains the primary application for sensor patches in Asia-Pacific, capturing 38% of the total market in 2025, propelled by large-scale deployments in hospitals, clinics, and elderly care. Diagnostics hold the second-highest share at 22%, driven by the fast uptake of continuous, non-invasive assessment tools. Fitness & Sports (18%), Patient Monitoring (13%), Wearable Devices (6%), and others (3%) make up the remainder, underscoring the increasing versatility of sensor patches. Heightened focus on telemedicine, health tracking for athletes, and remote monitoring for chronic conditions are significant factors driving growth in these application segments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-sensor-patch-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Sensor Patch Market industry?
The key players in the Asia-Pacific Sensor Patch Market include Abbott Laboratories, Medtronic plc, Koninklijke Philips N.V., iRhythm Technologies, and Dexcom Inc. These companies lead through innovation in wearable health technology, strategic partnerships, and expanding their sensor patch portfolios to meet the growing demand for real-time health monitoring.
What is the Asia-Pacific Sensor Patch Market growth?
The Asia-Pacific Sensor Patch Market is experiencing robust growth, driven by rising healthcare digitalization and increasing prevalence of chronic diseases. For example, Medtronic’s advancements in continuous glucose monitoring technology have contributed to higher adoption rates across various countries in 2023, further accelerating market expansion.
Which segment accounted for the largest Asia-Pacific Sensor Patch Market share?
The healthcare monitoring segment accounted for the largest Asia-Pacific Sensor Patch Market share. Driven by rising demand for remote monitoring among patients with chronic conditions, applications such as cardiac monitoring, glucose monitoring, and temperature tracking are witnessing rapid growth and adoption across hospitals and personal healthcare settings.
Thanks & Regards,
priya
sales@bussinessinsights.com
Asia-Pacific High-speed Data Converter Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific high-speed data converter market was valued at approximately $1,200 million in 2020 and is forecasted to reach $3,850 million by 2035. This growth is largely attributed to a substantial upsurge in 5G communication infrastructure, surging adoption of industrial automation, and technological innovations in automotive electronics. A compound annual growth rate (CAGR) of around 10.2% is expected from 2025 to 2035. The revenue trajectory distinctly reflects the market’s evolving dynamics, as both established and emerging industries increasingly invest in high-performance converters to meet demanding data acquisition and processing needs across the region.
Read More - https://bussinessinsights.com/research-report/asia-pacific-high-speed-data-converter-market
The communications segment leads with an estimated 37% share of the high-speed data converter market in Asia-Pacific by 2025, driven by increased 5G adoption and expansions in broadband infrastructure. The industrial sector, including factory automation and process control systems, takes second place, as high precision and fast throughput are essential for real-time operations. The consumer electronics sector continues to grow, benefitting from innovation in multimedia and smart devices. Automotive and medical verticals are rapidly gaining momentum, spurred by technological advancements in electric vehicles and diagnostic imaging, respectively.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-high-speed-data-converter-market
Frequently Asked Questions
Who are the key players in Asia-Pacific High-speed Data Converter Market industry?
The top five players in the Asia-Pacific High-speed Data Converter Market include Analog Devices, Texas Instruments, Renesas Electronics, NXP Semiconductors, and ON Semiconductor. These companies are recognized for advanced product portfolios, strong R&D capabilities, and robust presence across sectors such as telecommunications, automotive, and industrial applications.
What is the Asia-Pacific High-speed Data Converter Market growth?
The Asia-Pacific High-speed Data Converter Market has experienced steady growth, with significant demand led by expanding 5G networks and IoT applications. For instance, in 2023, Texas Instruments saw increased revenue in Asia-Pacific, reflecting heightened investment in communication infrastructure and advanced electronics manufacturing.
Which segment accounted for the largest Asia-Pacific High-speed Data Converter Market share?
The telecommunications segment accounted for the largest market share in the Asia-Pacific High-speed Data Converter Market. This is attributed to the rapid 5G rollout, growing smartphone adoption, and increased demand for high-speed data processing, which drive the need for efficient data conversion solutions in network infrastructure.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific data center switch market is set for strong growth, with estimated revenues rising from $3,200 million in 2020 to $9,750 million by 2035, reflecting rapid cloud and digital infrastructure investments. The market sees a significant acceleration from 2025, driven by widespread 5G rollout, expanding hyperscale operations, and government smart nation initiatives. This growth is further catalyzed by a surge in data consumption and digital services adoption across both developed and emerging countries in the region. The revenue trend underscores the critical role of network infrastructure modernization in supporting Asia-Pacific’s digital economy.
Read More - https://bussinessinsights.com/research-report/asia-pacific-data-center-switch-market
Cloud service providers remained the largest application segment in 2025, securing a 45% market share due to extensive cloud infrastructure expansion across APAC. Enterprises held a 30% share, as digital transformation initiatives and hybrid cloud deployment drove steady demand for scalable data center networking. The telecommunication providers segment accounted for 13%, highlighting continued investment in 5G backbone and edge data solutions. Other sectors like BFSI, government, and IT & Telecom together comprised the residual share, pointing to diversified adoption trends.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-data-center-switch-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Data Center Switch Market industry?
The top 5 players in the Asia-Pacific Data Center Switch Market include Cisco Systems, Huawei Technologies, Arista Networks, Juniper Networks, and H3C Technologies. These companies specialize in advanced networking equipment, offering high-performance switches and scalable solutions essential for modern data centers across varied industries in the region.
What is the Asia-Pacific Data Center Switch Market growth?
The Asia-Pacific Data Center Switch Market is witnessing robust growth, driven by rising data center investments and cloud adoption. For instance, in 2023, Huawei reported expanding its data center network solutions portfolio to support increased demand, contributing significantly to regional market acceleration.
Which segment accounted for the largest Asia-Pacific Data Center Switch Market share?
The cloud service providers segment accounted for the largest market share in the Asia-Pacific Data Center Switch Market. Growing adoption of cloud computing and hyperscale data center developments have bolstered demand for switches, as evidenced by investments from companies like Alibaba Cloud and Tencent.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific Pyrometer Market is projected to grow robustly from $412 million in 2020 to $886 million by 2035. With a compound annual growth rate (CAGR) of approximately 5.2%, the market expansion is attributed to rapid industrialization, expansion of manufacturing sectors, and increasing adoption of automation and digital control technologies. Major countries like China, India, and South Korea are expected to be primary contributors to revenue growth. As regulatory compliance tightens and quality standards rise, companies are investing considerably in upgrading pyrometry systems, further uplifting market revenue trajectories over the forecasted years.
Read More - https://bussinessinsights.com/research-report/asia-pacific-pyrometer-market
The largest share of the Asia-Pacific Pyrometer Market is held by metal processing, driven by continuous investments in steel and non-ferrous manufacturing plants across China, India, and Southeast Asia. The glass and ceramics industries are also major adopters, where precise and consistent temperature control is critical for quality assurance and operational safety. Growing demand from the power generation and chemical sectors, on the back of stricter compliance and modernization, represents strong opportunities for pyrometer solutions. Other industrial uses, including electronics and precision manufacturing, are emerging as notable secondary application segments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-pyrometer-market
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific Image Intensifier Market revenue is set to surge from an estimated USD 2,650 Million in 2020 to USD 6,370 Million by 2035, exhibiting a consistent upward trajectory. Advancements in imaging technology, growing applications across healthcare and defense, and robust uptake in industrial sectors drive this expansion. Key contributors such as China, Japan, and South Korea are expected to maintain leadership, while Southeast Asian economies display robust growth rates owing to increased healthcare and infrastructure investments.
Read More - https://bussinessinsights.com/research-report/asia-pacific-image-intensifier-market
Medical Imaging dominates with the highest application share in 2025, attributed to ongoing advancements in diagnostic radiology and surgical imaging, as well as government support for healthcare upgrades. Defense & Surveillance follows, supported by robust military modernization, especially in China, India, and South Korea. Industrial uses, including non-destructive testing and quality inspection, are also expanding, driven by manufacturing automation.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-image-intensifier-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Image Intensifier Market industry?
The top 5 players in the Asia-Pacific Image Intensifier Market include Thales Group, Hamamatsu Photonics, Canon Inc., FLIR Systems, and L3Harris Technologies. These companies focus on innovative imaging solutions, advanced night vision technologies, and expanding their regional presence through strategic partnerships and product launches to address growing market demands.
What is the Asia-Pacific Image Intensifier Market growth?
The Asia-Pacific Image Intensifier Market is experiencing significant growth, driven by increased adoption in medical imaging and defense sectors. For example, Hamamatsu Photonics has reported strong demand due to technological advancements and growing healthcare infrastructure, leading to a robust CAGR of approximately 7% from 2023 onwards.
Which segment accounted for the largest Asia-Pacific Image Intensifier Market share?
The medical imaging segment holds the largest share in the Asia-Pacific Image Intensifier Market. Hospitals and clinics are increasingly deploying image intensifiers for fluoroscopy and radiology procedures, propelled by rising healthcare investment, improved diagnostic needs, and the demand for minimally invasive surgeries across emerging Asian economies.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The revenue for the Asia-Pacific Acoustic Camera Market is set to rise steadily from USD 150 million in 2020 to an estimated USD 560 million by 2035. This upward trend is fuelled by increased investments in manufacturing upgrades, robust automotive growth, and rising awareness of sound diagnostics in critical sectors such as healthcare and energy. The implementation of digital signal processing and AI across new product lines is catalyzing market expansion and opening additional revenue streams.
Read More - https://bussinessinsights.com/research-report/asia-pacific-acoustic-camera-market
Industrial applications dominate the Asia-Pacific Acoustic Camera Market in 2025, holding a 36% market share as manufacturers increasingly integrate acoustic diagnostics to enhance predictive maintenance. Automotive follows at 22%, leveraging acoustic imaging to optimize EV designs and reduce cabin noise. The healthcare sector accounts for 15%, primarily for diagnostics and noise control in sensitive environments. Aerospace & defense, energy & power, and electronics & telecom sectors compose the remaining share, signifying a balanced and expanding use across fields where sound monitoring is mission critical.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-acoustic-camera-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Acoustic Camera Market industry?
The top five players in the Asia-Pacific Acoustic Camera Market are Brüel & Kjær, Siemens, SM Instruments, CAE Software & Systems, and GFUVE Electronics. These companies are recognized for their advanced acoustic imaging technologies, strong R&D capabilities, and diverse product portfolios, serving industrial, automotive, and environmental sectors across the region.
What is the Asia-Pacific Acoustic Camera Market growth?
The Asia-Pacific Acoustic Camera Market has shown robust growth, with an estimated CAGR exceeding 8% from 2021 to 2024. Growth is driven by increasing adoption of noise control solutions in industrial sectors and smart manufacturing initiatives in countries like China and Japan. Siemens recently expanded acoustic solutions in the Japanese market.
Which segment accounted for the largest Asia-Pacific Acoustic Camera Market share?
The automotive application segment accounted for the largest market share in the Asia-Pacific Acoustic Camera Market. Acoustic cameras are widely used for detecting and analyzing vehicle noise and vibration, ensuring compliance with regulatory standards in manufacturing hubs such as China, India, and Japan, boosting growth in this segment.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Marketing Automation Software Market to Hit $7B in 2025, Projected 11.5% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Imperatives in the Marketing Automation Software Market: A 2026 Decision Framework
The landscape of customer engagement is undergoing a seismic shift. As organizations strive to balance personalization with privacy, scale with efficiency, and automation with human insight, the Marketing Automation Software Market has emerged as a critical infrastructure layer for enterprise growth. At PW Consulting, we recognize that navigating this complex ecosystem requires more than surface-level trend analysis. It demands a rigorous examination of historical trajectory, competitive dynamics, and emerging technological vectors. Our latest market research publication, the Marketing Automation Software Market Study 2026-2032, is designed specifically to equip senior executives, product leaders, and investment strategists with the actionable intelligence needed to make high-stakes decisions in 2026 and beyond.
Wireless Micrometer Heads Market
This introductory insight serves as a strategic primer. It outlines the macro environment, highlights the structural forces reshaping demand, and previews the depth of analysis contained within the full report. We will not obscure the magnitude of opportunity; however, to preserve the analytical integrity and commercial value of our comprehensive dataset, we deliberately withhold granular regional, application, and type-specific monetary breakdowns. The complete segmentation intelligence, coupled with proprietary company benchmarking and scenario modeling, is available exclusively through the full report. The following overview establishes the context and strategic framework that decision-makers must grasp before deploying capital or restructuring marketing technology stacks.
Far Infrared Panel Heaters Market
The Trajectory of Market Expansion and the 2026 Inflection Point
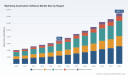
Establishing a reliable baseline is the first step in any strategic planning exercise. Over the historical review period from 2020 through 2025, the marketing automation software sector has demonstrated robust, compounding growth. Beginning at a foundational valuation of approximately 4.1 billion USD in 2020, the market advanced through successive years of acceleration, reaching an estimated valuation of 7.0 billion USD by the base year of 2025. This progression reflects not merely the adoption of digital tools but the structural embedding of automation into the core operational fabric of marketing organizations across industries.
Worldwide Bromine Tablet Market
Looking forward to the forecast period spanning 2026 to 2032, the appetite for scalable, intelligent automation continues to strengthen. Our projections indicate that the market will surpass the 7.6 billion USD threshold in 2026, setting the stage for a sustained expansion phase. Driven by an anticipated compound annual growth rate of 11.5 percent, the sector is on a trajectory to approach 15.0 billion USD by 2032. This growth corridor is not uniform; it is being shaped by divergent adoption curves, evolving procurement models, and a rapidly evolving technology landscape where artificial intelligence transitions from a value-add feature to an existential requirement.
For the 2026 strategic planner, these figures represent more than a growth narrative. They signal a market in transition from early-maturity consolidation to a phase where differentiation is determined by integration depth, AI capability, and compliance readiness. The 2026 horizon demands that leaders evaluate their automation investments against a backdrop of rising platform expectations, heightened data governance requirements, and intensifying vendor competition.
Key Structural Drivers Reshaping Market Dynamics
Several interconnected forces are propelling the market forward, yet each carries nuanced implications that require careful strategic interpretation. Understanding these dynamics is essential for framing the questions that our full research report answers in detail.
- Artificial Intelligence and Workflow Intelligence: The integration of AI-powered workflow orchestration, predictive segmentation, and intelligent prompt optimization is redefining what marketing automation platforms can achieve. Vendors are racing to embed generative and agentic capabilities that reduce manual configuration, accelerate campaign deployment, and improve personalization at scale. This shift is altering procurement criteria, with buyers increasingly prioritizing platforms that demonstrate tangible AI utility across the customer lifecycle rather than isolated machine learning features.
- Omnichannel Orchestration and Real-Time Engagement: Customer expectations have cemented the need for seamless, cross-channel engagement. Platforms that can synchronize messaging across email, social, web, mobile, and paid channels while maintaining contextual continuity are gaining traction. Real-time analytics, predictive behavioral scoring, and dynamic content adaptation are moving from premium capabilities to baseline expectations, particularly for organizations seeking to maximize lifetime value.
- Data Governance, Privacy Regulation, and On-Premise Resilience: The regulatory environment is imposing new constraints on data handling, consent management, and cross-border data flows. Recent adjustments to privacy frameworks have introduced stricter monetary thresholds and expanded deletion mechanisms, compelling organizations to reassess their data architecture. Concurrently, deployment preferences continue to reflect a strong preference for on-premise and hybrid models in segments where data control, sovereignty, and compliance assurance are paramount. This dynamic is creating a bifurcated market in which platform flexibility and governance tooling are decisive competitive differentiators.
- Talent Scarcity and Operational Efficiency: The demand for sophisticated marketing automation is outpacing the supply of specialized talent. Shortages in qualified marketing automation specialists are exerting measurable pressure on implementation timelines and optimization velocity, introducing a modest but persistent drag on growth trajectories. Organizations are responding by prioritizing platforms with intuitive configuration, low-code workflow design, and embedded guidance that reduce reliance on scarce technical resources while preserving operational rigor.
Competitive Landscape: Leadership, Differentiation, and Strategic Positioning
The vendor ecosystem in this market is characterized by a mix of broad-platform incumbents, specialized challengers, and enterprise-grade solution providers. Our analysis indicates a moderately concentrated market structure, with the top three players capturing a meaningful share of total revenue and the top five collectively accounting for a majority of market activity. This concentration does not imply stagnation; rather, it reflects a competitive arena where differentiation is increasingly articulated through product philosophy, ecosystem integration, and the ability to address distinct customer archetypes.
Several established leaders continue to set the pace. HubSpot, headquartered in Cambridge, Massachusetts, has reinforced its position through a comprehensive Marketing Automation Hub that tightly couples CRM integration, AI-powered workflows, and end-to-end funnel management. Its recent Spring 2026 Spotlight release introduced over 100 updates, including HubSpot AEO for AI-driven prompt suggestions and brand visibility analytics, signaling a strategic emphasis on search-augmented engagement and measurable brand impact. ActiveCampaign, based in Madison, Wisconsin, has pursued a focused strategy centered on sales and marketing alignment, deploying AI agents and omnichannel capabilities to unify customer communication. Its November 2025 product expansion, which integrated Active Intelligence Personalized Cards and Knowledge Base functionality, also established an official Claude Connector, reflecting a broader industry movement toward interoperable AI ecosystems.
Specialized strengths define other prominent players. Klaviyo, from Boston, has carved a distinct niche in customer lifecycle marketing automation, particularly for e-commerce, leveraging real-time segmentation and AI agents to drive commerce-oriented engagement. Braze, headquartered in New York, delivers real-time customer engagement automation across channels, using predictive analytics and its Sage AI framework to power moment-based interactions. On the enterprise side, Salesforce Marketing Cloud and Adobe Marketo Engage continue to anchor large-scale deployments. Salesforce’s San Francisco-based platform emphasizes multi-channel orchestration within a broader CRM ecosystem, while Adobe’s Marketo Engage, based in San Jose, remains a focal point for B2B demand generation and lead nurturing in complex enterprise environments.
Oracle Eloqua, from Austin, provides enterprise demand generation automation with deep integration into Oracle CX and sophisticated workflow capabilities, appealing to organizations already invested in the Oracle technology estate. Microsoft Dynamics 365 Marketing, rooted in Redmond, integrates marketing automation directly within the Dynamics 365 environment, aligning marketing execution closely with CRM and sales workflows. Meanwhile, Mailchimp, based in Atlanta, continues to serve a broad user base with accessible email and multi-channel automation, automation sequences, and CRM ties that lower the barrier to entry for smaller teams and scaling organizations.
This competitive mosaic illustrates a market where platform philosophy, target customer profile, and AI integration strategy are as consequential as raw feature counts. Our report provides a structured comparative analysis of these vendors, examining product roadmaps, deployment models, ecosystem alliances, pricing dynamics, and positioning relative to key customer segments. It also explores how recent product releases and partnership moves are reshaping buyer expectations and influencing vendor selection criteria in 2026.
Research Coverage and Operational Utility
A market study earns its place on a leadership team’s desk only if it translates data into decision-ready insight. Our Marketing Automation Software Market research is constructed to support a wide range of strategic applications, from technology investment planning and vendor evaluation to competitive benchmarking and market entry strategy. The report is organized to provide both macroeconomic clarity and granular, actionable detail, while maintaining the analytical discipline necessary to avoid oversimplified conclusions.
- Historical Baseline and Forecast Architecture: The research establishes a robust historical foundation spanning 2020 through 2025 and extends a forward-looking forecast through 2032. This dual-horizon approach enables executives to validate assumptions against observed performance and to model multiple growth scenarios based on different adoption and technology maturation pathways.
- Segmentation Frameworks: The study decomposes market activity across multiple dimensions, including functional type, application, and regional distribution. By mapping how value accrues across campaign management, email marketing, lead nurturing and scoring, social media marketing, analytics and reporting, content management, and other functional categories, the report helps organizations identify where investment intensity and platform maturity are most pronounced. Application-level analysis differentiates between large enterprise deployments and SME adoption patterns, providing context for procurement behavior, integration complexity, and scaling requirements.
- Competitive Company Profiles and Benchmarking: The report delivers in-depth profiles of leading vendors, including headquarters location, platform capabilities, product philosophy, and recent strategic moves. It evaluates how each player addresses core buyer needs, where they position themselves relative to competitors, and how their recent releases and integrations reshape the value proposition. This competitive mapping supports vendor shortlisting, partnership evaluation, and strategic positioning analysis.
- Regulatory, Compliance, and Deployment Considerations: Given the increasing importance of data governance and privacy compliance, the research examines how regulatory developments influence platform selection, deployment preferences, and operational processes. It addresses the continued relevance of on-premise and hybrid deployment models in segments where data control and regulatory assurance are decisive, and it contextualizes how compliance requirements are being operationalized within marketing technology stacks.
- Strategic Implications and Decision Frameworks: Beyond descriptive analysis, the report provides structured guidance for evaluating automation investments. It outlines criteria for assessing platform fit, integration depth, AI readiness, scalability, and total cost of ownership, helping leaders translate market intelligence into actionable plans for procurement, development, and organizational alignment.
What the Full Report Delivers
The excerpt presented here establishes the strategic terrain and highlights the critical forces that will shape decision-making in 2026. Yet the full complexity of the market, including the precise allocation of revenue across regions, functional types, and application segments, as well as the detailed vendor benchmarking and scenario modeling, resides within the complete research publication. Accessing the full report unlocks a comprehensive dataset and a structured analytical framework that enables executive teams to move beyond general market awareness to precise, evidence-based strategy formulation.
The complete study provides explicit segmentation values across all major geographic regions, granular breakdowns by functional type and application profile, and quantified concentration metrics that illuminate the competitive structure of the market. It also supplies a detailed catalog of recent product releases, partnership developments, and regulatory updates that are actively reshaping buyer expectations and implementation roadmaps. By consolidating these elements into a single, rigorously validated research asset, the report empowers leaders to benchmark their current position, evaluate alternative investment pathways, and anticipate the competitive moves that will define the next phase of market evolution.
Strategic Outlook for 2026 and the Path Forward
The Marketing Automation Software Market in 2026 is defined by a confluence of accelerating AI adoption, intensifying omnichannel expectations, tightening data governance, and a competitive vendor landscape that rewards differentiation through integration and usability. Organizations that treat automation as a strategic enabler rather than a tactical utility will be best positioned to capture the value embedded in this growth corridor. The window for decisive action is open, but it requires clarity about where to invest, which capabilities to prioritize, and which vendors align with an organization’s operational and compliance realities.
PW Consulting’s Marketing Automation Software Market research is built to provide that clarity. By combining a rigorous historical-to-forecast architecture with in-depth competitive analysis, segmentation insight, and actionable decision frameworks, the study offers a reliable foundation for executive strategy in a market that is both dynamic and consequential. The macro trajectory is promising, the competitive stakes are high, and the margin for strategic misjudgment is narrowing. Leaders who ground their 2026 decisions in comprehensive, current intelligence will be better equipped to navigate complexity, optimize investment outcomes, and build marketing automation capabilities that scale with their ambitions.
The complete intelligence, including detailed segmentation data, vendor benchmarking, regulatory impact assessment, and forecast scenarios, is available through the full report. Access the complete research to equip your leadership team with the depth of analysis required to make confident, forward-looking decisions in the Marketing Automation Software Market.
For detailed analysis of this topic, please visit the official page: Marketing Automation Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 10-Deacetylbaccatin III Market Hits $161.5M in 2025, Poised for 5.5% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the 10-Deacetylbaccatin III Market: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global landscape for oncology-supporting pharmaceutical intermediates is undergoing a structural transformation, driven by sustained demand for taxane-based therapeutics, expanding regional manufacturing capabilities, and an increasingly rigorous regulatory environment. As therapeutic pipelines continue to rely on semi-synthetic routes for paclitaxel and docetaxel production, the upstream supply of 10-Deacetylbaccatin III has evolved from a niche botanical input into a strategically critical node within the broader pharmaceutical value chain. Our latest market research delivers a comprehensive, forward-looking assessment of this segment, positioning corporate strategists, procurement leaders, and investment professionals with the analytical clarity required to make informed decisions across the forecast horizon.
Worldwide Aged Home Care Market
Designed to anchor executive planning for the 2026 strategic cycle and beyond, this study bridges historical performance tracking with multi-year projection modeling. Rather than offering static snapshots, the analysis maps the momentum of market expansion, dissects the structural forces shaping supply and demand, and evaluates how key enterprise players are positioning themselves amid shifting regulatory expectations, botanical sourcing constraints, and evolving purity specifications. The following exposition outlines the strategic rationale behind this research, previews the analytical architecture of the full report, and demonstrates how the intelligence contained within it can be operationalized to strengthen market entry strategies, optimize procurement frameworks, and refine competitive positioning.
Escape Hoods Market
Market Trajectory: Translating Historical Momentum into Forward-Looking Strategy
Market sizing and growth modeling form the quantitative backbone of any credible strategic assessment. Over the historical window spanning 2020 through 2025, the global 10-Deacetylbaccatin III market has demonstrated a consistent upward trajectory, moving from an initial revenue base into progressively higher valuation tiers as pharmaceutical manufacturers scaled production capacity and secured long-term supply agreements for taxane intermediates. The baseline year of 2025 establishes a clear inflection point, after which the forecast period extending to 2032 illustrates a steady compound annual growth rate that reflects both underlying demand expansion and incremental capacity rationalization across key producing regions.
Worldwide Food Foil Market
For corporate planners, this trajectory is not merely a numerical projection; it is a structural signal. A sustained mid-single-digit CAGR across the forecast window indicates a market that is maturing but far from saturated, with growth increasingly dependent on alignment between intermediate availability, downstream API scheduling, and regional regulatory clearance cycles. The projection framework incorporated in our study captures this dynamic by modeling demand propagation through manufacturing pipelines, accounting for capacity ramp-up timelines, and stress-testing scenarios against potential supply interruptions, botanical harvest variability, and shifts in procurement preference toward higher-purity grades.
Decision-makers leveraging this intelligence can translate the growth curve into actionable planning parameters. Procurement teams can map contract renewal cycles against projected supply tightness, manufacturing strategists can evaluate whether to expand in-house extraction or secure multi-source agreements with specialized botanical intermediate suppliers, and investors can distinguish between cyclical demand spikes and structural growth drivers when assessing exposure to taxane-related segments. By anchoring forecasts to scenario frameworks rather than single-point estimates, the research enables organizations to build flexible operating models that withstand market volatility while capturing upside from capacity expansions and regional demand acceleration.
The research deliberately withholds granular segment-level revenue breakdowns in this introductory preview, reserving those precise allocations for the full analytical suite. This approach ensures that prospective clients experience the methodological rigor of the study while recognizing the necessity of accessing the complete dataset to unlock region-specific sourcing strategies, application-driven demand mapping, and formulation-grade commercial prioritization.
Value Chain Architecture and Procurement Implications
The commercial ecosystem surrounding 10-Deacetylbaccatin III is defined by a complex intersection of botanical sourcing, semi-synthetic processing, regulatory documentation, and downstream pharmaceutical demand. Unlike commodity chemical intermediates, this compound requires specialized extraction and purification pathways originating from Taxus species, which introduces inherent volatility related to harvest cycles, geographic sourcing constraints, environmental regulations, and the operational maturity of extraction facilities. Simultaneously, downstream manufacturers depend on consistent intermediate quality and documented compliance frameworks to maintain uninterrupted production of anti-cancer APIs, making supply reliability as critical as cost competitiveness.
Our study maps this value chain in operational detail, providing procurement and supply chain leaders with a structured view of where value is created, where bottlenecks typically emerge, and how supplier capabilities differ across regions and processing standards. The analysis differentiates between standard formulation pathways and enhanced purity grade outputs, recognizing that while standard formulations address broad commercial manufacturing needs, enhanced purity specifications increasingly influence procurement decisions in markets where regulatory scrutiny, downstream process sensitivity, and quality documentation requirements have intensified.
Chemical synthesis and research and development applications further complicate the procurement landscape. While the majority of intermediate demand flows toward pharmaceutical manufacturing, a meaningful share of consumption originates from synthesis programs and R&D initiatives that prioritize availability, documentation, and formulation flexibility over bulk cost optimization. This dual-channel demand structure requires buyers to maintain differentiated sourcing strategies: long-term, volume-oriented agreements for manufacturing-scale requirements, and responsive, specification-sensitive procurement channels for development-stage consumption. The research outlines how leading suppliers structure their commercial offerings to serve both channels, and where structural gaps persist that forward-looking organizations can exploit through targeted supplier partnerships or vertical integration.
For strategic planners, the value chain analysis serves as a diagnostic tool for assessing exposure to supply concentration, evaluating the credibility of supplier certifications, and determining whether existing procurement architectures are aligned with anticipated demand quality and volume trajectories. Understanding how botanical extraction capacity, purification throughput, and documentation readiness interact enables organizations to anticipate lead-time variability, negotiate more effectively, and construct contingency plans that reduce vulnerability to regional disruptions or regulatory hold-ups.
Competitive Landscape: Strategic Positioning of Key Market Participants
The competitive environment for 10-Deacetylbaccatin III is characterized by a fragmented yet increasingly differentiated supplier base, with participants competing across dimensions such as botanical sourcing expertise, regulatory documentation breadth, processing infrastructure, geographic reach, and commercial specialization. Market concentration metrics indicate that while no single enterprise dominates the segment, a cluster of established players has secured meaningful positions through combinations of extraction capability, compliance readiness, and regional distribution networks. The strategic relevance of this landscape lies not in simple market share rankings, but in understanding how each participant’s operational profile shapes their ability to capture demand growth, withstand supply shocks, and expand into adjacent formulation or purity segments.
Indena S.p.A. exemplifies a Europe-based specialist with deep botanical intermediate expertise, leveraging established regulatory documentation and commercial readiness as a pure molecule precursor pathway for docetaxel-related applications. Its positioning reflects a broader strategic archetype: specialized extraction capability paired with compliance-oriented commercial deployment, enabling access to procurement programs that prioritize documented supply continuity and formulation traceability. Phyton Biotech LLC operates from a similar philosophy but with a stronger emphasis on plant-derived pharmaceutical intermediates for semi-synthetic taxane production, reinforcing its role as a globally oriented supplier that bridges extraction capability with downstream manufacturing requirements.
Within the Asia-Pacific region, several producers have built commercial footprints that combine regional manufacturing density with export-oriented distribution. Samyang Biopharmaceuticals Corporation maintains an active supply posture supported by Asia-Pacific manufacturing and distribution infrastructure, making it a relevant reference point for organizations evaluating regional sourcing diversification. ScinoPharm Taiwan, Ltd. brings advanced process control infrastructure to its intermediate production, an attribute that increasingly matters for buyers seeking consistent specification performance and scalable purification capacity. In China, a cluster of producers including Hainan Yew Pharmaceutical Co., Ltd., Fujian South Pharmaceutical Co., Ltd., Chengdu Biopurify Phytochemicals Ltd., Wuxi Taxus Pharmaceutical, and Ningbo Green-Health Pharmaceutical illustrate the breadth of domestic manufacturing capability, ranging from large-scale domestic and export-focused production to GMP-aligned facilities serving pharmaceutical-grade intermediate requirements. Each organization brings a distinct commercial emphasis, whether oriented toward volume leadership, cost optimization for export markets, or compliance and certification readiness.
India-based Alchem International Pvt. Ltd. adds another strategic dimension by combining botanical API manufacturing with a robust certification portfolio, reinforcing its relevance for buyers seeking internationally recognized documentation alongside export capability. Meanwhile, Germany-based PhytoLab GmbH occupies a specialized niche as a reference substance specialist, offering high-purity standards that support research and pharmaceutical benchmarking rather than bulk manufacturing supply. This diversity of strategic archetypes underscores the importance of matching supplier selection to procurement objectives: bulk manufacturing continuity, enhanced purity assurance, regulatory documentation strength, regional proximity, or research-grade standardization.
Our competitive analysis extends beyond individual company profiles to examine how these participants interact within the broader market structure. The study assesses where capacity expansion is likely to alter supply balance, where certification and compliance advantages translate into commercial preference, and where regional manufacturing networks may tighten or loosen depending on export policy, environmental constraints, and downstream demand distribution. For corporate strategists, this competitive mapping provides a framework for evaluating partnership candidates, assessing substitution risk, and identifying which supplier attributes will carry the most weight as regulatory expectations and purity requirements continue to evolve.
Structural Drivers, Regulatory Context, and Emerging Industry Dynamics
The medium-term trajectory of the 10-Deacetylbaccatin III market is shaped by a set of interlocking structural drivers that extend beyond simple demand growth. One of the most significant is the continuing reliance of taxane-based oncology therapies on semi-synthetic pathways that depend on dependable intermediate supply. As downstream pharmaceutical programs scale or sustain production to meet therapeutic demand, the upstream requirement for high-quality 10-Deacetylbaccatin III becomes increasingly embedded in operational planning, contract manufacturing schedules, and API continuity strategies. This structural dependency reinforces the market’s resilience even as pricing, sourcing conditions, and regional production dynamics fluctuate.
Regulatory and quality assurance expectations represent another central force. Buyers in pharmaceutical manufacturing environments are placing greater emphasis on documented GMP alignment, certification breadth, and consistent specification control, particularly when intermediates feed into regulated drug production pathways. In this context, suppliers that can demonstrate robust process control, traceability, and internationally recognized documentation gain a structural advantage, while those competing primarily on price without equivalent compliance readiness face increasing scrutiny. The research captures how these expectations are reshaping procurement criteria and influencing commercial negotiations across regions.
Botanical sourcing dynamics introduce additional complexity. Because the feedstock originates from biologically derived sources, supply planning must account for harvest timing, extraction yield variability, and the operational capacity of specialized processing facilities. Organizations that depend on single-source arrangements or geographically concentrated supply chains face elevated exposure to disruptions, making diversification, buffer inventory planning, and supplier qualification rigor more important than ever. At the same time, suppliers with mature extraction infrastructure, established regrowth or sustainable sourcing practices, and multi-regional distribution capability are better positioned to stabilize availability and support long-term contractual commitments.
In addition to these structural forces, the market is being shaped by evolving procurement preferences around formulation type and purity grade. As manufacturing processes become more sensitive to impurity profiles and downstream yields, demand for enhanced purity grades is gaining strategic relevance, particularly for applications where specification consistency directly influences processing efficiency or regulatory readiness. Simultaneously, standard formulations continue to serve a broad manufacturing base where cost-efficiency and reliable availability remain paramount. The interplay between these demand segments influences pricing behavior, supplier capacity allocation, and the strategic emphasis of intermediate producers as they decide whether to broaden standard-grade output or invest in higher-purity processing pathways.
This preview does not enumerate specific development announcements or transient market events; instead, it frames the analytical lens through which such dynamics are evaluated in the full report. The complete study assesses how operational developments, certification milestones, capacity adjustments, and regional supply shifts alter competitive positioning and procurement strategy, allowing decision-makers to distinguish signal from noise when planning for the 2026 horizon and beyond.
How the Full Research Converts Intelligence into Action
A market research report delivers value only when it converts analytical depth into operational decision support. Our 10-Deacetylbaccatin III study is structured to serve multiple strategic functions simultaneously: as a source of macro-level growth intelligence, as a diagnostic framework for supplier evaluation, as a reference for regional demand distribution, and as a planning tool for procurement, manufacturing, and investment teams. The report integrates historical performance tracking, forecast modeling, segmentation analysis, competitive profiling, and supply chain assessment into a unified analytical system that can be adapted to different organizational use cases.
For procurement and supply chain leaders, the study provides the context needed to design sourcing architectures that balance cost, quality, and continuity. By examining how intermediate supply flows through manufacturing pipelines, where specification sensitivity is highest, and which supplier profiles offer the strongest documentation or capacity advantages, procurement teams can construct more resilient contracts, evaluate multi-source strategies, and prioritize supplier qualification criteria that align with both near-term operational needs and longer-term regulatory expectations.
For business development and market entry strategists, the report offers a structured view of where demand is expanding, which formulation and purity segments present the strongest commercial opportunity, and how competitive intensity varies across sourcing regions. This intelligence supports decisions about partnership selection, distribution channel design, and capacity investment, helping organizations avoid overconcentration in saturated supply pathways while identifying underserved demand pockets that may warrant dedicated commercial engagement.
For investor and corporate strategy teams, the study provides a framework for assessing market maturity, growth sustainability, and competitive differentiation without relying on isolated data points. By linking growth projections to structural drivers, supply constraints, and supplier capability profiles, the analysis enables more disciplined evaluation of opportunities tied to taxane intermediate supply, botanical extraction capacity, and pharmaceutical intermediate manufacturing.
The full report contains the detailed segmentation architecture, regional demand distribution, formulation-grade commercial splits, and company-level capability assessments necessary to execute these strategies with precision. Those core segmentation figures and detailed allocations are intentionally reserved for the complete intelligence package, ensuring that the full depth of the analysis is accessible only to clients who obtain the complete research. This approach preserves the strategic value of the dataset while allowing the preview to demonstrate the rigor, structure, and decision orientation of the study.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle presents a pivotal moment for organizations engaged with pharmaceutical intermediates, botanical extraction supply chains, and taxane-related manufacturing pathways. Demand is not entering a speculative phase; it is continuing along a documented growth path that requires deliberate strategic alignment rather than reactive procurement adjustments. Supplier capabilities are diversifying, regulatory expectations are tightening, and the distinction between standard and enhanced-purity supply is becoming increasingly material to downstream operational outcomes. In this environment, decisions made with incomplete intelligence carry disproportionate risk, while organizations that ground their planning in structured, forward-looking analysis are better positioned to secure supply continuity, optimize cost-quality trade-offs, and build defensible competitive positioning.
This research is designed to support that discipline. It translates historical momentum into forecast orientation, maps competitive capability into procurement and partnership implications, and frames structural drivers in terms that can be directly applied to sourcing strategy, capacity planning, and market development decisions. By engaging with the full study, decision-makers gain access to the segmentation detail, regional demand architecture, company-level capability assessment, and scenario-based planning context needed to move from broad market awareness to executable strategy.
The 10-Deacetylbaccatin III market is not defined solely by its growth rate; it is defined by the strategic choices organizations make in response to supply complexity, regulatory evolution, and competitive differentiation. Our analysis provides the intelligence foundation for those choices. For executives seeking to align 2026 planning with a clear, evidence-based view of market direction and supplier landscape, the complete research offers the depth required to act with confidence and precision.
For detailed analysis of this topic, please visit the official page: 10-Deacetylbaccatin III Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Watermelon Seeds Market Hits $752.25M in 2025, Forecasts 6.8% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Horizons: Navigating the Watermelon Seeds Market in 2026 and Beyond
The global agriculture sector stands at a critical inflection point, where biological innovation meets complex supply chain dynamics. For stakeholders in the watermelon seeds market, the period from 2026 through 2032 represents more than just a forecast window; it is a decisive era for capital allocation, breeding strategy, and supply chain resilience. As we release the latest edition of our Watermelon Seeds Market research, our objective is to provide the strategic scaffolding necessary for enterprises to navigate this growth trajectory with precision.
Tea Cutting Machine Market
This report is designed not merely as a repository of statistics, but as a decision-support tool for executives, investors, and agricultural strategists. The following analysis outlines the macroeconomic landscape, competitive pressures, and regulatory vectors that will define market performance over the next seven years. By synthesizing historical performance with forward-looking indicators, we uncover the latent opportunities within a sector that is evolving faster than traditional agricultural models predict.
Business Valuation Software Market
Market Trajectory and Revenue Architecture
Understanding the current valuation and future potential of the watermelon seeds market requires a clear view of the revenue architecture established over the past half-decade. Our analysis covers a robust historical period from 2020 to 2025, establishing a baseline of stability before projecting growth into the 2026-2032 forecast period. The data indicates a consistent upward trend in market valuation, reflecting heightened demand across both commercial agriculture and specialized nutraceutical applications.
Worldwide Finger Expansion Joint Market
In 2020, the market established a foundational revenue base that has since compounded annually. By 2025, the overall market size had expanded significantly, signaling strong adoption rates and expanded cultivation areas globally. Looking toward the forecast horizon, the momentum continues unabated. The market is projected to reach substantial revenue milestones by 2032, driven by consistent compound annual growth. This growth is not linear but is influenced by technological adoption in seed breeding and shifting consumer preferences toward seedless and specialty varieties.
The Compound Annual Growth Rate (CAGR) observed during the forecast period underscores the resilience of this sector. Even amidst global supply chain perturbations, the demand for high-quality planting material remains inelastic relative to price fluctuations in many regions. For strategic planners, this implies that revenue models based on volume expansion must account for yield improvements rather than solely relying on acreage increases. The revenue unit measured in millions USD provides a standardized framework for comparing investment returns against the cost of research and development in seed genetics.
Competitive Dynamics and Strategic Positioning
The competitive landscape of the watermelon seeds market is characterized by a mix of global agrochemical giants, specialized seed breeders, and regional exporters. Our analysis identifies key companies that are shaping the market through variety launches, licensing agreements, and geographic expansion. Understanding the positioning of these entities is crucial for identifying partnership opportunities or assessing competitive threats.
Leading the charge in innovation are entities such as Syngenta Vegetable Seeds and Sakata Seed America. These organizations are not merely maintaining existing portfolios; they are actively expanding them to capture premium market segments. For instance, recent updates in early 2026 highlight the introduction of new triploid varieties designed for specific rind patterns and sugar content profiles. These launches are strategic moves to differentiate products in a crowded marketplace where visual appeal and taste consistency drive retailer and consumer choice.
In the Asia-Pacific region, companies like Safal Seeds and Seamons Seeds Pvt. Ltd. are focusing on high-yield hybrid varieties tailored for export and commercial production. Their strategies reflect the region's dual role as both a major producer and a growing consumer market. Similarly, Chinese enterprises such as Rizhao Spring Trading Co., Ltd. and Gansu Dunhuang Seed Co., Ltd. are leveraging manufacturing scale to serve international demand, emphasizing export capabilities for kernels and seeds alike.
The presence of firms like East-West Seed, utilizing AI-powered quality inspection systems, signals a broader industry trend toward technology integration in seed production. This shift aims to reduce variability and ensure genetic purity, which is a critical quality metric for commercial growers. Meanwhile, companies like High Mowing Organic Seeds and Johnny's Selected Seeds cater to the niche but growing demand for organic and open-pollinated varieties, addressing the needs of small-scale growers and specific consumer demographics that prioritize non-GMO attributes.
Strategic consolidation is also evident. Recent movements include licensing agreements that grant exclusive access to germplasm and breeding pipelines. These agreements accelerate the development cycle for new varieties, allowing larger entities to secure intellectual property advantages over competitors. For market entrants, this suggests that barriers to entry are rising, particularly in the segment of proprietary hybrid seeds.
Technological Innovation and Breeding Pipelines
The core of value creation in this market lies in breeding technology. The shift from traditional open-pollinated varieties to advanced hybrids, particularly triploid seedless varieties, is a primary driver of market differentiation. Industry data suggests that hybrid diploid seeds held a significant share in recent years, yet the forecast indicates that hybrid triploid seeds are expected to grow at a faster rate through the end of the decade.
This divergence creates distinct strategic pathways for seed companies. Those focused on diploid varieties must compete on cost efficiency and reliability for standard farming operations. Conversely, players in the triploid segment are commanding premiums based on consumer preference for convenience and eating quality. The development of varieties like the El Capitan triploid or the Midnight Jewels portfolio illustrates how breeders are targeting specific aesthetic and sensory traits to capture value-added market segments.
However, technological advancement brings complexity. Seedless varieties cannot be established by direct seeding in certain contexts, requiring specific transplanting protocols that increase operational complexity for growers. Furthermore, the biological requirements for producing triploid seeds involve specific pollinator ratios and handling procedures. Companies that can provide not just the seeds but also the technical support and agronomic guidance around these varieties gain a competitive moat.
Innovation is also responding to regulatory and environmental pressures. New launches are increasingly designed for export markets and fresh-cut applications, where shelf life and uniformity are paramount. The integration of digital tools in quality inspection, as seen with some leading breeders, ensures that the genetic potential of these new varieties is realized in the field without degradation during processing.
Regulatory Frameworks and Supply Chain Constraints
The operational environment for the watermelon seeds market is heavily influenced by regulatory frameworks and physical constraints. Phytosanitary regulations are becoming increasingly stringent, particularly regarding international trade. These regulations increase the demand for seed treatments to enhance germination rates and facilitate cross-border movement of planting material. Compliance is no longer optional; it is a prerequisite for market access in key regions.
Changes in seed handling and testing protocols have also impacted cost structures. Recent industry profiles indicate that changes in handling have led to significant increases in the price of watermelon seeds for growers. This cost pressure is compounded by the requirement for soil incorporation for certain seed treatments, such as those involving neonicotinoids, to ensure control and efficacy. These operational requirements add layers of complexity to the supply chain, affecting logistics and inventory management.
Labor conditions and input costs are shaping operational planning for seed production and field activities in 2026. Tight labor conditions in key agricultural regions are driving up the cost of harvesting and processing seeds, particularly for varieties that require manual sorting or delicate handling. Rising input costs for fertilizers and field maintenance further squeeze margins unless offset by higher yields or premium pricing strategies.
For strategic planners, these dynamics suggest that supply chain resilience must be prioritized. Dependence on single-source regions for raw materials or processing could expose companies to significant risk if regulatory or labor disruptions occur. Diversification of sourcing and investment in automated processing technologies may be necessary to mitigate these cost pressures.
Strategic Imperatives for 2026 Decision-Makers
Based on the comprehensive analysis contained in our report, several strategic imperatives emerge for stakeholders planning their moves in 2026. The market is no longer a commodity play; it is a technology and service play. Success will depend on the ability to navigate the intersection of biological innovation, regulatory compliance, and market demand.
- Invest in Breeding R&D: With triploid varieties forecast to grow faster than diploid segments, allocating resources to develop unique, proprietary hybrids is essential. Licensing agreements and germplasm access will become critical assets for maintaining competitive advantage.
- Optimize Supply Chain Compliance: Navigating phytosanitary regulations and seed treatment requirements is vital for international expansion. Companies must ensure their handling and testing protocols meet the highest standards to avoid trade barriers and ensure germination reliability.
- Diversify Application Focus: While the food industry remains the dominant application segment, the nutraceutical sector offers high-margin opportunities. Seeds and kernels rich in nutrients are increasingly valued for health applications, providing an avenue for premium pricing.
- Monitor Regional Shifts: Growth is not uniform across all geographies. Market concentration data suggests that a significant portion of revenue is generated by a few key regions. Understanding the specific demand drivers in North America, Europe, and Asia Pacific is necessary for targeted expansion.
- Address Cost Pressures: With rising labor and input costs, operational efficiency is key. Automation in seed processing and strategic sourcing of raw materials can help protect margins amidst inflationary pressures.
Conclusion: The Value of Comprehensive Intelligence
The watermelon seeds market offers substantial opportunities for growth, but realizing this potential requires more than surface-level analysis. The interplay between breeding technology, regulatory environments, and competitive strategies creates a complex web that demands deep insight. Our structured research provides the granularity needed to make informed decisions, from assessing specific variety performance to understanding the financial health of key market participants.
For organizations looking to secure their position in this evolving landscape, access to detailed segmentation data, regional breakdowns, and competitor profiling is indispensable. The macro trends outlined here provide the direction, but the tactical execution relies on precise data. We invite industry leaders to explore the full scope of our findings to refine their strategies for the 2026-2032 period.
By leveraging this intelligence, stakeholders can move beyond reactive planning and toward proactive market shaping. The future of the watermelon seeds market belongs to those who can balance biological innovation with operational excellence and strategic foresight.
For detailed analysis of this topic, please visit the official page: Watermelon Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dicing Blade Market to Reach USD 371M by 2032 with 4.87% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence in a Precision-Driven Era: Unlocking the Dicing Blade Market Opportunity for 2026 Decision-Makers
The precision manufacturing landscape is undergoing a structural recalibration, and few components illustrate this shift as clearly as the dicing blade. As semiconductor architectures shrink, ceramic substrates multiply, and glass-based solutions redefine optical and display supply chains, the tools that cut these materials with micron-level accuracy have moved from routine consumables to strategic procurement categories. For executives navigating 2026 capital allocation, supplier negotiations, and capacity planning, this transition demands a sharper analytical lens. Our latest market research publication on the Dicing Blade Market has been designed precisely for that moment of decision.
Papermaking Suction Rolls Market
This introductory overview outlines why the study matters now, what it contains, and how its findings translate into actionable strategy. It is not a data sheet. It is a framing device built to surface the questions that matter most to operations leaders, procurement directors, and R&D strategists, while preserving the granular intelligence that deserves dedicated exploration.
Worldwide Hydraulic Swing Beam Shear Market
Why 2026 Is a Pivot Year for Dicing Blade Strategy
The global market measured in our study has demonstrated a clear upward trajectory across the historical window from 2020 through 2025, and the momentum carries decisively into the forecast period extending through 2032. In baseline terms, the industry recorded a valuation of approximately 230.15 million USD in 2020 and has since progressed through successive growth phases, reaching an estimated 268.15 million USD by 2025. That progression reflects more than cyclical demand. It reflects a compounding effect of material innovation, tighter tolerance requirements, and a broader manufacturing ecosystem that is increasingly dependent on precision singulation and substrate preparation.
Product Data Management Software Market
Looking ahead, the forecast trajectory projects the market to exceed 283.04 million USD in 2026, with sustained expansion through the rest of the decade and a projected valuation approaching 371.0 million USD by 2032. The study attributes this expansion to a compound annual growth rate of 4.87 percent over the forecast horizon, a figure that may appear measured on the surface but carries strategic implications when viewed through the lens of segment competition, raw material transitions, and regional capacity shifts. In other words, the growth rate is not the whole story. The composition of that growth, the players driving it, and the operational constraints shaping it are where real decision advantage emerges.
For leadership teams planning 2026 investments, that means the question is no longer whether the dicing blade market is expanding. The question is whether an organization’s sourcing strategy, product roadmap, and geographic exposure are aligned with the segments and dynamics that will define the next cycle of value creation.
What the Study Delivers: Operational Intelligence, Not Just Market Size
A robust market research report should do more than describe what happened. It should equip teams to act on what comes next. Our Dicing Blade Market study is structured around that principle, with content developed for direct application in commercial planning, supplier evaluation, and technology assessment.
At its core, the report maps the market across multiple structural dimensions, giving readers a complete operational picture rather than a single aggregate number. The segmentation framework examines how demand disperses across blade type categories, application environments, and regional markets. It also provides historical context that helps distinguish temporary fluctuations from durable demand shifts. The forecast section translates that structure into forward-looking projections, allowing stakeholders to test scenarios against a consistent analytical baseline.
Beyond sizing and segmentation, the study integrates the forces that shape purchasing behavior and product development priorities. This includes the role of raw material characteristics in blade selection, with particular attention to how diamond grit continues to anchor market leadership due to its hardness profile and longevity in demanding dicing applications. It also addresses the regulatory and standards environment that increasingly governs production and deployment, including quality management expectations, safety considerations for dicing system implementations, and equipment automation guidelines that influence operational parameters. These are not peripheral details. They define what is commercially viable, what is auditable, and what can scale reliably across global supply chains.
The report also devotes substantial attention to the competitive landscape, evaluating how major manufacturers position themselves by bond type, application focus, and precision requirements. Rather than treating competition as a static ranking, the analysis emphasizes differentiation logic: where incumbents reinforce scale and process consistency, where specialized suppliers compete on low-chipping performance and ultra-thin geometries, and where regional manufacturers expand their footprint through materials-tailored solutions. This framing helps buyers and investors understand not only who operates in the market, but how value is created and defended within it.
How the Competitive Landscape Shapes 2026 Procurement and Partnership Decisions
The dicing blade market is characterized by a concentrated group of manufacturers whose capabilities span multiple blade families and end-use requirements. That concentration has implications for pricing discipline, supply reliability, and innovation cadence. The study examines several of the most influential participants, highlighting the specific roles they play in shaping demand pathways across semiconductor and adjacent precision material markets.
DISCO Corporation stands out as a manufacturer of precision diamond dicing blades offering resin, metal, and electroformed bond types for semiconductor wafer scribing and singulation. Their breadth across bond technologies gives them a strong position in applications where process flexibility and cut quality must be balanced against throughput requirements. Kulicke & Soffa Industries, Inc. operates as a supplier of hub dicing blades and specialized precision blades for wafer and package singulation in semiconductor assembly, reinforcing the importance of hub-based tooling in assembly-stage processing. Advanced Dicing Technologies Ltd. contributes a developer and global supplier profile that spans resin, nickel, and metal-bond families for high-precision semiconductor applications, emphasizing breadth and application adaptation.
UKAM Industrial Superhard Tools focuses on low-chipping, ultra-thin diamond dicing blades and precision tools for silicon wafers, sapphire, and ceramics, a positioning that matters in applications where edge quality and material integrity are non-negotiable. Ceiba Technologies provides specialized dicing blades, edge grind wheels, and precision consumables for semiconductor and hard drive applications, reflecting a broader consumable ecosystem approach rather than blade-only competition. Asahi Diamond Industrial Co., Ltd. is covered as a leading producer of diamond and CBN dicing blades and tools for semiconductor wafer processing and precision cutting, underscoring the continued importance of diamond and superhard material expertise. Tokyo Seimitsu Co., Ltd. enters the competitive picture as a supplier of precision ACCRETECH blades across resin, nickel, metal-bond, and hub types for wafer dicing, illustrating the role of established precision equipment ecosystems in blade demand. Shanghai Sinyang Semiconductor Materials Co., Ltd. represents a manufacturer of diamond dicing blades and solutions tailored for semiconductor wafer cutting and scribing, highlighting the growing influence of region-specific production capabilities and materials-oriented service models.
Read together, these profiles show that competition is not defined solely by blade pricing. It is defined by bond architecture, application fit, quality consistency, and the ability to support increasingly strict process standards. In 2026, procurement teams benefit from evaluating suppliers through that multidimensional lens rather than through headline specifications alone.
Forces Reshaping Demand, Cost, and Capability
Several industry dynamics are now influencing how dicing blade demand forms and how suppliers must respond. One of the most persistent is the continued dominance of diamond grit blades, which retain market leadership because of superior hardness and longevity in dicing applications. That advantage is not abstract. It translates into fewer blade changes, better edge control, and more predictable tool life in high-value processing steps. As a result, material performance remains a central variable in both product design and purchasing strategy.
At the same time, the regulatory and standards environment is tightening the operating perimeter for dicing-related production. Automotive-oriented quality expectations have introduced stricter requirements for semiconductor components used in dicing parameters, raising the bar for traceability, repeatability, and validation. Safety standards applicable to dicing system implementations impose operational constraints that affect layout, handling, and integration choices. Quality management frameworks require documented procedures for process control in dicing blade production, making consistency and procedural discipline part of the competitive baseline. Equipment automation guidelines also impose constraints on dicing saw operations, influencing how blade performance is evaluated in automated lines.
These forces matter because they interact with cost structures and supplier selection. A blade that delivers excellent cut quality but complicates compliance or integration may lose ground to a slightly less exotic alternative that performs reliably within a governed process. Conversely, in applications where chipping, surface integrity, or wafer yield dominate the value equation, premium tooling can justify its place in the process. The study provides the analytical scaffolding to assess those tradeoffs without reducing them to a single specification sheet.
Where Strategy Meets Market Reality
For organizations operating in or adjacent to semiconductor manufacturing, ceramics processing, glass cutting, and related precision material markets, the dicing blade segment offers a concrete example of how midstream tooling decisions shape upstream competitiveness. Blade selection influences yield, throughput, consumable costs, and downstream cleanliness. Supplier relationships influence lead-time stability, technical support depth, and the ability to adapt to changing substrate requirements. Regional exposure influences logistics, tariffs, and proximity to end-demand clusters.
The forecast period through 2032 suggests that these considerations will become more important, not less. Demand is projected to expand steadily, but the composition of that expansion will reward organizations that can align procurement with application needs, manage material and regulatory pressures intelligently, and select partners whose capabilities match the precision requirements of their specific production environment. In that context, the value of a detailed research study lies in its ability to convert aggregate growth into segment-level clarity.
Because the real strategic advantage often comes from the details, this overview intentionally focuses on the structure of the market and the logic behind the analysis rather than reproducing the full segmentation breakdown. The complete report reserves its deepest granularity for the audiences that need it: precise regional comparisons, application-level breakdowns, type-based demand splits, and the competitive profiles that connect those segments to real supplier behavior. That is where the numbers become operational.
How to Use This Research in 2026 Planning Cycles
The study is built to support several recurring planning needs. Procurement teams can use it to benchmark supplier positioning, evaluate whether current sourcing strategies align with the fastest-moving application and region combinations, and identify where bond-type and material preferences are shifting. Strategy and business development teams can use it to assess market entry feasibility, partnership logic, and the relative attractiveness of different precision material pathways. R&D and process engineering teams can use it to understand how tool performance expectations are evolving under tighter quality, safety, and automation requirements.
Executives can also use the report to test assumptions. If internal forecasts assume that one application vertical will carry most of the growth, the segmentation structure in the study provides a reference point for stress-testing that belief. If leadership expects regional demand to concentrate in familiar markets, the regional breakdown offers context for whether that exposure remains optimal. If the prevailing view is that tool purchasing is primarily a cost exercise, the competitive and regulatory analysis reframes it as a capability and compliance exercise as well.
Conclusion: Precision Is the New Strategic Currency
The dicing blade market may be specialized, but its implications are broad. It sits at the intersection of material science, process control, automation, and supply chain discipline. In 2026, organizations that treat dicing blades as mere consumables risk missing the larger signal: precision tooling is increasingly a determinant of yield, consistency, and downstream competitiveness.
Our Dicing Blade Market research was developed to help leaders read that signal clearly. It combines historical context, forward-looking projections, competitive profiles, and regulatory and material dynamics into a single analytical framework. The headline growth figures tell part of the story. The segment composition, supplier differentiation, and operating constraints tell the rest.
For decision-makers who need the full detail set, the complete report provides the regional, application, and type-level intelligence behind the narrative presented here. That is where the analysis moves from orientation to execution, and where strategy becomes measurable.
For detailed analysis of this topic, please visit the official page: Dicing Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com