

Blogs
PW Consulting: PC System Utilities Market Hits $17.125 Billion in 2025, Expands at 4.11% CAGR Through 2032
By PW Consulting, 2026-09-07
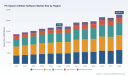
Navigating the PC System Utilities Software Market: Strategic Imperatives for 2026 and Beyond
The PC System Utilities Software Market has entered a phase of structured evolution. Over the historical period from 2020 to 2025, the sector demonstrated consistent upward momentum, with global revenue climbing from approximately 13,682 million USD to around 17,125 million USD. As organizations plan their technology roadmaps for 2026, the strategic value of this market lies not merely in incremental growth, but in the convergence of operational efficiency demands, heightened data-security expectations, and an increasingly fragmented competitive landscape. This research provides executive decision-makers with a rigorous, forward-looking framework to navigate market entry, portfolio expansion, and partnership strategies through the 2032 horizon.
Worldwide Drawer Air Fryer Market
Market Architecture and the Trajectory to 2032
Understanding the macroeconomic footprint of the market is the first step toward informed capital allocation. The baseline year of 2025 established a clear inflection, and the forecast window from 2026 to 2032 reveals a compound annual growth rate of 4.11 percent. While the headline figure signals stability, the underlying trajectory exposes a more nuanced reality: growth is not linear, and it is punctuated by structural shifts in how users and organizations interact with system maintenance tools. By 2032, the market is projected to reach approximately 22,739 million USD, representing a meaningful expansion from the 2025 baseline. This progression is shaped by several interlocking forces. First, the maturation of operating-system ecosystems has increased the baseline demand for third-party optimization and maintenance utilities, even as native OS capabilities have improved. Second, the proliferation of digital workflows across both individual and commercial environments has elevated the cost of downtime, driving users toward tools that promise faster system responsiveness and cleaner resource allocation. Third, infrastructure modernization has made it possible for software providers to scale update delivery, telemetry, and secure data-handling pipelines more efficiently, though not without introducing new cost dimensions that must be managed carefully.
CTC and CTB Batteries for EV Market
Strategic readers will note that the forecast period is not a straight extrapolation. The growth path reflects recalibrations tied to product innovation cycles, competitive repositioning, and macroeconomic conditions that influence consumer and enterprise spending on maintenance software. A measured CAGR in this environment does not imply stagnation; it indicates a market that rewards disciplined execution, differentiated feature sets, and clear value propositions. Organizations that approach the market with a clear sense of where growth concentrates, what constitutes defensible differentiation, and how regulatory expectations are reshaping product design will be better positioned to capture share without overextending resources.
Refrigerated Container Adhesive Market
The Strategic Value of This Research for 2026 Decision-Making
Market intelligence becomes actionable only when it connects data to decision. This report is designed to do exactly that: it translates a broad market trajectory into operational guidance for executives, product leaders, and investment teams evaluating the PC system utilities space in 2026. The analysis is structured around the questions that matter most in this stage of the market lifecycle. Where is demand most resilient? Which product categories are gaining or losing momentum relative to user expectations? How do competitors structure their market presence, and where do gaps remain for new entrants or incumbents seeking to pivot? What external pressures—regulatory, infrastructural, and labor-related—are reshaping cost structures and speed-to-market? The answers are not superficial. They are embedded in a research architecture that ties historical performance to forward-looking scenarios, allowing decision-makers to test assumptions rather than rely on static narratives.
For companies planning product roadmaps, the research provides a lens on where utility features intersect with user behavior. For investors and strategic partners, it clarifies the boundaries of market concentration and the practical implications of operating in a space where a small group of players commands a substantial portion of total revenue. For organizations evaluating expansion into adjacent maintenance, optimization, or data-protection segments, the report frames the operational realities that define margin potential and execution risk. The report is not intended as a retrospective summary. It is a decision-support instrument built to help leadership teams convert market signals into prioritized actions, whether those actions involve feature prioritization, channel strategy, pricing architecture, or geographic sequencing.
Inside the Report: Frameworks, Dimensions, and Actionable Intelligence
The research is organized to support both high-level strategy and granular execution. It opens with a comprehensive market sizing exercise that anchors the narrative in verified historical data and extends into forecast modeling for the 2026 to 2032 window. From there, the analysis decomposes the market along multiple dimensions so that leadership can evaluate where value is created and how it flows through the ecosystem. Rather than presenting a single aggregated number and stopping, the report examines how different product categories, user segments, and regional dynamics interact to produce the overall trajectory. This layered approach matters because aggregate growth can obscure divergent sub-trends, and executives need to see beneath the surface to allocate resources intelligently.
A core feature of the research is its focus on product-category dynamics. System optimization remains a central pillar of the market, reflecting sustained demand for tools that improve responsiveness, clear unnecessary files, and streamline routine maintenance. Disk cleanup and data recovery also represent significant components of the landscape, while file management and other utility functions occupy more specialized but still relevant positions. The report evaluates how these categories differ in terms of user adoption patterns, feature expectations, and competitive intensity. It also addresses application-level segmentation, distinguishing between individual users, small and medium enterprises, and large enterprises. Each of these user groups presents distinct purchasing drivers, sensitivity to pricing, and requirements for integration and support. Individual users often prioritize ease of use and immediate perceived performance gains, while smaller enterprises look for cost-effective bundles and manageable deployment. Large enterprises, by contrast, tend to emphasize reliability, compliance alignment, and centralized management considerations. The report maps these differences without reducing them to oversimplified generalizations, enabling readers to identify which segments align with their strategic objectives.
Geographic coverage is equally deliberate. The market is analyzed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with attention to how regional conditions influence adoption, pricing tolerance, and competitive presence. Each region carries its own mix of user behavior, infrastructure maturity, and regulatory environment, and the report uses these distinctions to inform market-access strategies. Rather than treating geography as a static backdrop, the research examines how regional demand patterns evolve in response to product updates, ecosystem changes, and broader technology adoption trends. Executives can use this framing to evaluate where to prioritize go-to-market efforts, where localization matters most, and where the balance between opportunity and operational complexity tilts one way or the other.
Beyond segmentation, the report incorporates operational and structural considerations that directly affect competitiveness. It addresses the cost environment that software providers face, including the labor intensity of specialized development and ongoing maintenance work, as well as the infrastructure burden associated with cloud hosting for update servers and secure data storage. These factors are not peripheral; they shape margin envelopes, product-update cadence, and the ability to scale without compromising reliability. The research also discusses the evolving impact of data privacy and compliance expectations on product design and operational practice. As utilities increasingly interact with system files, user data, and scanning routines, the standards for secure handling and regulatory alignment become central to both reputation and market access. ISO 27001 and related data-protection frameworks are treated as practical reference points that influence how providers structure their workflows and customer commitments. The report weaves these elements into the broader market narrative so that decision-makers can evaluate opportunity in the context of the operational realities that determine long-term viability.
Competitive Dynamics and the Shifting Battleground
No market assessment is complete without a rigorous competitive read. The PC system utilities space is characterized by a concentration of players that have built recognizable brands around system cleaning, optimization, and maintenance. The analysis profiles the firms that define much of the current competitive tension, including iolo Technologies with System Mechanic, Glarysoft Ltd with Glary Utilities, IObit with Advanced SystemCare, Ashampoo GmbH with WinOptimizer Pro, WiseCleaner Technology Co., Ltd. with Wise Disk Cleaner and Wise Care 365, Piriform Software Ltd with CCleaner, and Avanquest Software with its PC tune-up and optimization offerings. These companies do not occupy identical positions in the market. Their product philosophies, feature scopes, and positioning strategies differ in ways that matter for both incumbents and new entrants. Some emphasize comprehensive optimization suites, while others lean into cleaner-focused experiences or integrate security-minded functions alongside maintenance tasks. The report examines these distinctions as strategic signals, showing how each player’s approach shapes customer perception, feature competition, and the boundaries of market share.
The Microsoft trajectory adds an important layer to the competitive picture. Recent update activity underscores how a platform-level player can influence expectations across the broader utilities ecosystem. In late 2025, a new version of Microsoft PC Manager was released with enhancements to storage cleanup and PC performance monitoring. A subsequent update in mid-2026 continued the rollout with improvements aimed at broader global deployment. This cadence matters because it signals renewed attention to native or platform-adjacent maintenance tools, which can shift user baselines and raise the bar for third-party offerings. The presence of an established platform player in this space does not automatically compress the market for independent utilities, but it does change the competitive context. Third-party providers must articulate clear and credible reasons for users to adopt their solutions beyond what is already available through default system tools. The research addresses this dynamic directly, focusing on how differentiation, trust, and functional depth become more important when baseline expectations rise.
Market concentration further sharpens the competitive read. The sector is not evenly distributed across all participants. A meaningful share of total revenue is accounted for by a small group of leading firms, and the cumulative footprint of the top players remains substantial. This concentration has strategic implications. It suggests that established positions are not easily displaced, that brand trust and installed-base momentum carry weight, and that differentiation must be both credible and sustained. At the same time, concentration does not imply stagnation. It often signals where innovation pressure is highest, because leaders must continuously defend their positions while challengers search for underserved needs or alternative bundling strategies. The report helps executives interpret these concentration patterns not as barriers alone, but as indicators of where value capture is occurring and where competitive openings may still exist for focused execution.
Structural Forces Reshaping the Market
Beyond competition and segmentation, the market is being shaped by operational realities that influence how utilities are built, delivered, and trusted. Data privacy and compliance requirements have become embedded in product design considerations rather than treated as afterthoughts. Utilities that perform system scans, handle user files, or interact with sensitive system areas must navigate expectations around secure handling and transparent data practices. This dynamic raises the stakes for product architecture and customer communication. Providers that treat compliance as integral to their offering can turn it into a trust advantage, while those that underestimate it may face friction in adoption or reputational exposure.
The labor dimension is equally important. Specialized software development and maintenance represent a core operational expense, and the talent required to build and sustain reliable optimization tools is not commoditized. This cost pressure influences release cycles, feature ambition, and the pace at which providers can respond to user feedback. In a market where perceived performance improvements and stability are central purchase drivers, development discipline matters as much as marketing reach. Infrastructure cost has a parallel effect. Cloud hosting for update servers and secure storage for user data adds another layer to the expense profile, particularly as providers scale and seek to maintain consistent delivery across regions. The report integrates these cost drivers into the analysis so that growth estimates are evaluated alongside the operational commitments required to support them. This makes the forecast more than a projection of revenue movement; it becomes a practical assessment of what it takes to sustain position in a competitive environment.
How to Use This Research in 2026 Planning
The most valuable research is the kind that changes how a team thinks before it changes what the team does. In 2026, leadership teams can use this report to test several strategic hypotheses at once. It can support decisions about whether to enter the market, deepen an existing presence, or reposition an existing offering against evolving user expectations. It can help product leaders identify which categories and user segments offer the best alignment with current capabilities and where the opportunity cost of broadening too quickly may be highest. It can guide commercial teams in evaluating pricing, bundling, and channel strategies against a competitive backdrop in which trust, clarity, and reliability are increasingly important purchase drivers. It can also support investor and partnership conversations by providing a structured view of market size, trajectory, concentration, and the operational pressures that influence margin and execution speed.
Crucially, the report is built to be referenced, not just read. Its segmentation detail, competitive profiles, and structural analysis are designed to feed directly into planning cycles, scenario testing, and investment prioritization. Executives do not need every underlying data point presented as a static table to benefit from the analysis. What matters is that the research preserves enough depth to support real decisions while remaining clear about where additional intelligence is needed. That is why this overview is deliberately framed as an entry point rather than a full disclosure. The complete dataset, scenario pathways, and granular segment readings are available in the full report, where teams can examine the numbers that matter most to their specific strategies.
What the Full Report Unlocks
This introduction provides the strategic context, the competitive logic, and the structural forces that define the PC System Utilities Software Market in 2026 and beyond. It establishes that the market is growing with discipline, that concentration shapes the competitive battleground, and that operational realities around compliance, development labor, and infrastructure are central to sustainable positioning. It also makes clear that the deeper the decision stakes, the more valuable the underlying detail becomes. The full research release goes further by offering target-segment readings, detailed category-level assessments, regional deployment considerations, and the specific competitive intelligence needed to move from directional confidence to precise execution. For organizations that intend to act on this market with seriousness, the complete report is where the analysis converts into operational advantage.
The PC system utilities market is no longer a space where generic features or broad promises are sufficient. It rewards clarity of purpose, credible differentiation, and disciplined execution. For decision-makers in 2026, the strategic task is to understand not only how large the market is or how fast it is likely to grow, but where value concentrates, how competitors defend their positions, and what operational commitments are required to compete effectively. This research is designed to help leaders answer those questions with confidence, and to lay the groundwork for decisions that are grounded in evidence rather than assumption.
For detailed analysis of this topic, please visit the official page: PC System Utilities Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Agarwood Essential Oils Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The market has shown steady momentum with revenue rising from $187 Million in 2020 to an expected $465 Million by 2035. This trajectory is propelled by heightened consumer demand for niche luxury and wellness categories. Substantial revenue spikes are noted post-2025, in part due to major retailers expanding their natural product lines and pharmaceutical innovations leveraging agarwood’s bioactive compounds. Asia-Pacific remains the strongest revenue contributor, followed by Europe and North America, mirroring both mature consumer markets and dynamic new entrants.
Read More - https://bussinessinsights.com/research-report/global-agarwood-essential-oils
Aromatherapy remains the largest application segment in 2025, contributing 39% of total market share, attributed to rising wellness and holistic health trends. Personal Care & Cosmetics follows at 33% as top brands integrate agarwood oil into skincare and fragrances. Pharmaceuticals capture 11%, leveraging the oil’s therapeutic value in new product developments. Food & Beverages (6%), Home Care (6%), and Others (5%) represent emerging interest segments, notably for unique flavoring and air care solutions. Increasing consumer awareness, especially in Asia and Europe, steers preference toward multipurpose and natural-use products, sustaining growth across applications.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-agarwood-essential-oils
Frequently Asked Questions
Who are the key players in Global Agarwood Essential Oils industry?
The key players in the Global Agarwood Essential Oils industry include Givaudan, Firmenich, Tien Phuoc Agarwood, Nusaroma, and BioAromatic. These companies lead the market with extensive distribution networks, advanced extraction technologies, and strong R&D capabilities, enabling them to meet rising global demand for agarwood oils.
What is the Global Agarwood Essential Oils growth?
The Global Agarwood Essential Oils market has shown significant growth in recent years, particularly driven by rising demand in aromatherapy and luxury cosmetics. For instance, Givaudan reported increased sales of natural ingredients, including agarwood oil, contributing to a CAGR of more than 7% from 2021 to 2023.
Which segment accounted for the largest Global Agarwood Essential Oils share?
The fragrance and perfumes application segment holds the largest share in the Global Agarwood Essential Oils market. Agarwood oil’s unique scent profile and lasting aroma quality make it highly valued by premium perfume and cosmetic manufacturers, driving further expansion in this segment.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Biodegradable Tableware Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The biodegradable tableware market is expanding at a robust pace, projected to rise from USD 1,750 Million in 2020 to USD 12,350 Million by 2035. The CAGR of 13.2% is fueled by regulatory support, consumer shifts, and ongoing product innovation. Annual revenues show consistent acceleration, reflecting heightened commercial adoption as well as broader uptake among households and institutions globally. This growth trajectory indicates long-term sustainability and rising investor confidence across the industry.
Read More - https://bussinessinsights.com/research-report/global-biodegradable-tableware
Commercial applications—including restaurants, cafes, and catering services—account for the largest segment with 41% share in 2025, underlining the food service sector’s commitment to sustainable practices. Residential usage constitutes 28%, driven by eco-conscious households adopting biodegradable solutions for everyday use and gatherings. Events, parties, and institutional settings follow, as organizers and administrators prioritize green alternatives. The market reflects a broadening acceptance across end-user verticals, with major manufacturers targeting tailored solutions for each application category.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-biodegradable-tableware
Frequently Asked Questions
Who are the key players in Global Biodegradable Tableware industry?
The top 5 players in the global biodegradable tableware industry are Huhtamaki, Biopak, Dart Container Corporation, Vegware, and Pactiv LLC. These companies are renowned for their innovation in sustainable packaging solutions, international presence, and advancement of compostable disposable tableware for food service and retail sectors worldwide.
What is the Global Biodegradable Tableware growth?
The global biodegradable tableware market has been experiencing robust growth, with a CAGR of over 6% in recent years. In 2023, Huhtamaki reported increased demand for its fiber-based tableware products, propelled by greater environmental awareness and government restrictions on single-use plastics.
Which segment accounted for the largest Global Biodegradable Tableware share?
The food service segment accounted for the largest share of the global biodegradable tableware market. This is driven by high adoption among restaurants, cafes, and catering services seeking eco-friendly disposable solutions to comply with green regulations and consumer demand for sustainable practices.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Water Analysis Market Hits $372.81M in 2025, Projected to Reach $537.96M by 2032
By PW Consulting, 2026-09-07
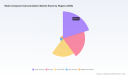
Strategic Intelligence for a Water-Stressed World: Why the 2026 Water Analysis Instrumentation Market Demands Executive Attention
The global imperative for precise, reliable, and increasingly automated water quality assessment has moved from a technical requirement to a boardroom priority. As municipalities grapple with aging infrastructure, industrial operators face tighter effluent compliance, and environmental agencies mandate real-time ecological monitoring, the instrumentation ecosystem that measures, analyzes, and validates water quality is undergoing a structural transformation. The period spanning 2026 through 2032 will not merely represent incremental growth; it will reward organizations that understand where capital is flowing, which analytical modalities are gaining regulatory tailwinds, and how competitive consolidation is reshaping procurement dynamics. Our latest market research on the Water Analysis Instrumentation Market provides the strategic scaffolding necessary to navigate this shift with confidence.
Zirconia Ceramic Femoral Head Market
The Macro Trajectory: Reading the Numbers as Strategic Signals
The baseline valuation for the global market stood at approximately 372.81 million USD in 2025, reflecting a compounding growth curve that has been consistently upward since 2020. When we trace the historical arc from 288.51 million USD in 2020 through successive annual expansions, a clear inflection pattern emerges: demand acceleration is no longer episodic but structurally embedded. The research projects that this momentum will carry the market to roughly 405.13 million USD in 2026, with sustained compounding that extends the revenue trajectory toward the 537.96 million USD range by 2032. These figures are underpinned by a forecast-period CAGR that anchors the entire analytical framework at 5.4 percent.
Universal CAR-T Cell Therapy Market
For executive decision-makers, this trajectory communicates several non-obvious signals. First, the growth is broad-based rather than dependent on a single geographic or application surge, which reduces portfolio concentration risk but simultaneously raises the bar for differentiation. Second, the steady compounding indicates that capital expenditure cycles in water analysis are transitioning from reactive replacement to proactive capability upgrading. Third, the extended forecast window provides a multi-year planning horizon that allows procurement, R&D, and merger-and-acquisition teams to align roadmaps with verifiable demand progression rather than quarterly speculation.
Aerospace and Defense Fans Market
Competitive Architecture: A Concentrated Landscape With Distinctive Strategic Niches
The market is not a undifferentiated commodity pool. Our concentration analysis reveals a top-three revenue share of approximately 43.0 percent and a top-five share of roughly 54.0 percent, indicating a moderately concentrated environment where scale, brand trust, and integrated solution portfolios matter. Yet concentration alone does not tell the competitive story. The real strategic insight lies in how leading players have carved adjacent capability centers that intersect with the core instrumentation market in highly specific ways.
Hach Company has established a comprehensive line of water quality testing instruments, analytical systems, and chemistries designed to cover laboratory, process, and field applications across municipal, industrial, and environmental water analysis. Their positioning illustrates a full-spectrum strategy where hardware, reagents, and method validation converge into a single procurement relationship. YSI Incorporated has focused its offering on water quality sampling and monitoring meters, sensors, and instruments tailored for environmental monitoring, wastewater, and drinking water treatment, with a recent January 2025 product launch introducing the HydroRIG IoT gateway device for enhanced environmental water quality monitoring. That move signals a deliberate pivot toward connected, field-deployed telemetry rather than standalone measurement alone.
Thermo Fisher Scientific brings ion chromatography systems, discrete analyzers, pH/conductivity meters, and other analytical instruments to drinking water, surface water, groundwater, and wastewater testing, leveraging laboratory-grade precision that resonates with regulated analytical workflows. Xylem Inc. complements this ecosystem by providing analytical instrumentation for water quality, level, and flow measurement across clean water, wastewater, and outdoor environments, including the YSI brand, which embeds a recognized monitoring heritage within a broader water technology suite. Agilent Technologies addresses regulated water testing and pollutant analysis through ICP-MS, LC-MS, and sample preparation systems, positioning at the intersection of trace contaminant detection and compliance-driven method specificity.
HORIBA Instruments Incorporated contributes benchtop and online water quality meters, UV-VIS spectrometers, and sensors for environmental and industrial water monitoring, bridging laboratory reference methods with process-line continuity. Myron L Company focuses on portable conductivity and pH meters for industrial, municipal, and pool/spa water quality testing, emphasizing field-deployable convenience and rapid decision support. CHEMetrics, LLC supplies self-filling ampoules and V-2000 spectrophotometer systems for accurate water testing of multiple parameters, offering a low-barrier, method-standardized approach that appeals to distributed testing networks. Martek Instruments, Inc. rounds out the landscape with ultrapure water quality analyzers and sensors designed for power generation, pharmaceutical, and semiconductor industries, highlighting the critical role of ultra-low-contaminant measurement in high-value manufacturing environments.
Strategically, this company set reveals a market where vertical integration, method ecosystem ownership, and connectivity roadmaps differentiate leaders from followers. Procurement teams evaluating vendors must look beyond sticker pricing to assess whether a supplier can anchor an entire analytical workflow, support digital telemetry, and maintain method alignment with evolving regulatory expectations.
Segmentation As a Strategic Lens, Not a Static Snapshot
A rigorous competitive and procurement strategy requires a nuanced understanding of how the market divides across operating contexts. Our research examines the instrumentation landscape through multiple segmentation dimensions, including geographic deployment patterns, instrument architecture categories, and end-use application environments. These dimensions interact in ways that single-axis views often obscure.
The regional architecture shows how demand is distributed across diverse regulatory, climatic, and infrastructural conditions. North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa each present distinct procurement cycles, compliance regimes, and field-deployment challenges. Understanding where capacity is being installed, maintained, and upgraded provides critical input for manufacturing footprint planning, distributor network design, and after-sales service readiness. Industrial and municipal application environments exhibit different instrumentation priorities: one set emphasizes process control, contaminant tracing, and continuous compliance verification, while the other centers on public health protection, distribution-system integrity, and regulatory reporting cadence. Recognizing these operational divergences prevents misalignment between instrument specifications and real-world decision thresholds.
On the instrument-side dimension, the market splits between laboratory-based analytical setups and online, in-situ measurement architectures. Laboratory-based systems anchor method validation, reference-grade accuracy, and complex multi-parameter workflows that support compliance documentation and forensic water quality assessment. Online instruments provide continuous monitoring, early-warning signaling, and process-loop integration that reduce sampling latency and support automated response protocols. The strategic tension between these two modalities is not zero-sum; rather, it reflects an organizational decision about how much analytical authority is retained in centralized laboratories versus embedded within distributed field and process environments. The balance a company strikes directly shapes capital allocation, data architecture, and workforce skill requirements.
Regulatory Pressure as a Demand Catalyst, Not a Compliance Burden
Regulatory evolution is actively reshaping measurement priorities across jurisdictions. In early 2025, the recast EU Drinking Water Directive began requiring monitoring of PFAS Total and Sum of PFAS parameters in drinking water using harmonized methods of analysis. Alongside this mandate, the revised directive updates parametric values and introduces new testing requirements for parameters including bisphenol A, chlorite, and haloacetic acids. These changes do more than add analytes to a checklist; they elevate the performance expectations for detection limits, method robustness, cross-laboratory comparability, and data traceability.
For instrumentation providers and end-users alike, this regulatory environment creates a dual strategic effect. First, it expands the addressable need for instruments capable of meeting stricter analytical specifications, particularly for emerging contaminants where method harmonization is still stabilizing. Second, it incentivizes the adoption of instruments and workflows that can produce defensible, auditable datasets with minimal manual intervention. Organizations that treat regulation purely as a compliance cost will underinvest in measurement capability; those that treat it as a design parameter for instrument selection, validation planning, and data management will convert regulatory pressure into a competitive moat.
Report Scope: What Decision-Makers Gain From the Full Analysis
This research was constructed to move beyond headline market sizing and into the operational intelligence that shapes capital allocation, vendor selection, product roadmapping, and market-entry strategy. The full study integrates historical performance context, forward-looking forecasts, and structural segmentation that maps how instrument types, application environments, and regional deployment patterns interact to define demand.
Readers will find actionable evaluation frameworks that connect instrument capabilities to real-world procurement criteria, including measurement range suitability, calibration burden, reagent or consumables dependency, field serviceability, and digital integration readiness. The analysis addresses how leading companies are positioning their portfolios across laboratory, process, and field contexts, and where capability gaps create opportunistic entry points for new solutions or strategic partnerships. It also examines the purchasing dynamics that govern laboratory-based versus online deployments, the role of regulatory mandates in shifting preferred analytical methods, and the service, calibration, and consumables ecosystems that influence total cost of ownership over multi-year asset lifecycles.
In addition, the report provides a structured view of recent market developments that signal near-term directional shifts. One notable example is the January 2025 introduction of the HydroRIG IoT gateway device by YSI, an initiative that points toward increasingly connected environmental monitoring deployments and the growing importance of telemetry-enabled data flow in water quality programs. Developments like these are not isolated product news; they are indicators of how instrument manufacturers are building toward continuous, networked monitoring architectures that change how data is generated, transmitted, and acted upon.
Strategic Implications for 2026 Decision-Making
As organizations plan their 2026 capital and capability cycles, several strategic priorities emerge from the market structure we have analyzed. Procurement leaders should evaluate instrumentation purchases against total program value rather than unit transaction cost. That means weighing method alignment, calibration frequency, consumables reliability, field-deployability, and data integration potential alongside initial pricing. R&D and product strategy teams should assess where instrument portfolios need to evolve to meet stricter parametric requirements and where connectivity, automation, or multi-parameter consolidation can unlock operational efficiency. M&A and business development teams should watch how concentration trends intersect with portfolio gaps, particularly where suppliers are extending from standalone measurement into integrated data platforms or expanded method ecosystems.
Regional and application diversification also deserves deliberate planning. Because demand is distributed across multiple geographies and operating environments, firms that rely on a narrow deployment footprint may experience uneven revenue resilience. Expanding service coverage, localizing calibration and support capacity, and tailoring instrumentation specifications to regional regulatory expectations can materially improve market responsiveness. Likewise, organizations operating across both municipal and industrial contexts should avoid forcing a single measurement strategy onto fundamentally different operational rhythms; instrument selection, sampling cadence, and reporting architecture should reflect the decision speed and compliance stakes of each environment.
Why This Research Matters Now
The Water Analysis Instrumentation Market is entering a phase where analytical rigor, regulatory alignment, and digital integration converge to determine competitive positioning. The trajectory from 2026 to 2032 will reward organizations that understand not just how large the market is becoming, but how its internal segmentation, concentration dynamics, and regulatory catalysts shape demand for specific instrument capabilities and service models. The figures and structural patterns outlined here establish the strategic context; the complete report builds the detailed operational blueprint.
We encourage executives, product leaders, procurement strategists, and market-development teams to access the full study for the comprehensive segmentation detail, company profile depth, regional demand architecture, and forward-looking scenario analysis that cannot be summarized in a single overview. The full intelligence package is designed to support investment prioritization, vendor evaluation, product roadmap planning, and risk-adjusted growth strategy across the 2026 to 2032 horizon. In a market where measurement precision increasingly underpins public health, industrial compliance, and environmental resilience, the ability to act on granular, well-structured market intelligence is itself a strategic asset.
For detailed analysis of this topic, please visit the official page: Water Analysis Instrumentation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Structural Bolts Market Hits $4.5B in 2025, Poised for 5.5% CAGR Through 2032
By PW Consulting, 2026-09-07
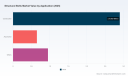
Strategic Fastening: Why the 2026 Structural Bolts Market Demands Deeper Intelligence
The structural bolts market stands at a critical inflection point. After a decade of steady expansion, the industry now faces a complex convergence of regulatory shifts, raw material volatility, and evolving infrastructure imperatives that will separate prepared incumbents from reactive followers. Our newly released Structural Bolts Market research study is designed to equip executives, procurement leaders, and investment analysts with the precise intelligence required to navigate this landscape through 2032. This article outlines the strategic architecture of the report, highlights the macro forces reshaping the sector, and demonstrates why rigorous, forward-looking analysis is no longer optional for firms operating in heavy construction, automotive manufacturing, or industrial fastening supply chains.
Portable Unmanned Surface Vessel Market
The Macro Trajectory: Growth Anchored by Infrastructure and Industrial Demand
Drawing on a comprehensive historical baseline spanning 2020 through 2025, our analysis projects the structural bolts market to reach a revenue benchmark of approximately 6.55 billion USD by 2032, up from an estimated 4.5 billion USD in the base year. The forecast period from 2026 to 2032 reflects a compound annual growth rate of 5.5 percent, a trajectory that underscores the market's resilience even as macroeconomic cycles introduce periodic demand fluctuations. This growth is not merely a function of population expansion or isolated project pipelines; it is structurally reinforced by sustained capital expenditure in transportation corridors, energy infrastructure, and commercial building frameworks, alongside steady replacement and maintenance cycles in established industrial installations.
Worldwide Virtual Clinics Market
The historical data reveals a clear upward arc: from 3.44 billion USD in 2020, the market climbed through successive years of incremental gains, reaching 4.34 billion USD by 2024 before stabilizing at 4.5 billion USD in 2025. The forward projection shows continued expansion, with revenue milestones advancing steadily toward the 2032 endpoint. For strategic planners, this pattern signals that volume growth will persist, but the composition of that growth, the geographies driving it, and the product categories capturing disproportionate share will require granular scrutiny. The report dissects these layers without oversimplifying them, ensuring that leadership teams can align capacity planning, sourcing strategies, and market entry decisions with verified demand signals rather than surface-level aggregates.
Air Purifiers for Mold Market
Structural Forces Reshaping the Competitive Landscape
The structural bolts sector is defined by a moderately fragmented yet increasingly strategic competitive environment. Concentration metrics indicate that the top three players account for approximately 28.5 percent of total market revenue, while the top five collectively represent roughly 35.2 percent. This distribution suggests that scale advantages exist, but they are not insurmountable, and that regional reliability, certification compliance, and service agility often outweigh pure price competition. The report profiles the companies that are setting the pace, examining how they differentiate through product specification depth, inventory positioning, and value-added engineering support.
Among the firms shaping the market's direction, several North American manufacturers and distributors stand out for their focus on high-strength fastening solutions and their alignment with structural steel fabrication workflows. Portland Bolt, headquartered in Portland, Maine, operates as both a manufacturer and distributor of high-strength structural bolts, including A325 and A490 grades, alongside nonstandard construction fasteners. Its customer base spans contractors, steel fabricators, original equipment manufacturers, and government or military projects, reflecting the breadth of demand that a well-positioned fastener supplier can capture. Haydon Bolts, Inc., based in Evergreen, Maine, is a family-owned domestic manufacturer specializing in high-strength structural bolts and anchor rods, with a particular emphasis on maintaining the largest inventory of U.S.-melted and manufactured bolts and offering rapid galvanizing turnaround. That domestic manufacturing pedigree and quick processing capability have become meaningful differentiators in an environment where lead times and traceability increasingly influence purchasing decisions.
Birmingham Fastener, located in Birmingham, Alabama, is recognized as the largest U.S. distributor and manufacturer of A325 and A490 structural bolts, T-head bolts, and custom fasteners, operating multiple distribution centers and providing value-added services that extend beyond simple fulfillment. American Bolt Corp supplies industrial fasteners, structural bolts, anchors, and stud welding products, emphasizing fast delivery and competitive pricing for steel fabricators. Würth Industry USA contributes to the landscape through structural fasteners, including A325 and A490 tension-control bolts, while also offering customized inventory solutions and direct support to construction teams. Simpson Strong-Tie, based in Pleasanton, California, manufactures structural connectors and fasteners, including galvanized steel structural bolts tailored for construction and infrastructure applications, reinforcing the connection between fastening systems and broader structural engineering outcomes.
These profiles are not static snapshots. The report integrates recent corporate developments that illustrate how leading firms are scaling, relocating, and engaging with industry events to secure pipeline visibility and customer relationships. In October 2025, Birmingham Fastener opened a new manufacturing facility in Querétaro City, Mexico, a move designed to support structural bolt production and distribution growth while positioning the company to serve cross-border demand with reduced logistics friction. Earlier, in September 2024, Portland Bolt exhibited at the International Fastener Expo in Las Vegas, using the platform to showcase structural steel fasteners and connect with fabricators, contractors, and specification professionals. Such developments matter because they reveal how incumbents are adapting to demand geography, supply chain considerations, and the need for face-to-face technical engagement in a category where specification trust is paramount.
Regulatory and Specification Frameworks as Strategic Variables
In structural fastening, compliance is not a peripheral concern; it is a core competitive parameter. The market operates within a framework of standards that define mechanical performance, material quality, and application appropriateness, and shifts in these frameworks can alter sourcing decisions, qualification cycles, and product mix. ASTM F3125 specifies minimum tensile strength requirements of 120 ksi (830 MPa) for A325 and 150 ksi (1040 MPa) for A490 high-strength structural bolts, establishing a baseline that fabricators and engineers rely on when specifying fasteners for load-bearing assemblies. ISO 898-1 complements this by defining mechanical properties classes for carbon and alloy steel bolts used in structural applications, broadening the reference architecture for international projects and multi-standard procurement environments.
These standards interact with broader regulatory and trade dynamics that influence cost structures and sourcing geography. In April 2026, U.S. Section 232 tariffs on steel and aluminum articles and their derivatives, including fasteners, increased to 50 percent ad valorem on full customs value. For a market where steel input costs and imported component flows directly affect margin and availability, this escalation introduces a material variable that procurement teams must model carefully. The report examines how such tariff dynamics interact with domestic manufacturing capacity, regional sourcing alternatives, and the degree to which specification requirements can be met by locally produced inventory versus imported supply.
On the raw material front, cost stability in certain periods can provide temporary planning confidence, but it does not eliminate exposure to cyclical steel pricing. For example, Nucor Corporation maintained its hot-rolled coil steel price at 950 USD per ton for the fourth consecutive week in January 2026, a data point that illustrates how input cost plateaus can emerge even as broader trade and demand conditions evolve. The study places such indicators within a wider cost architecture, helping readers understand how raw material pricing, tariff exposure, and specification requirements combine to shape the economics of structural bolt supply.
Compliance as a Market Access Condition
Beyond cost, standards function as gatekeepers to project eligibility. Fabricators and contractors operating on public infrastructure, commercial high-rises, or regulated industrial facilities must demonstrate that fastening products meet the required tensile, durability, and inspection criteria. The report maps how leading suppliers align their product lines with ASTM and ISO expectations, how certification and traceability are communicated to specification writers, and where gaps in compliance can create disqualification risk. This dimension is especially relevant for firms evaluating supplier qualification programs, because the cost of a non-conforming fastener batch or a documentation shortfall can far exceed the unit price differential between competing sources.
Report Architecture: What Decision-Makers Will Find Inside
The Structural Bolts Market study is built to translate macro trends into actionable decision inputs. It begins with a rigorous sizing and forecasting framework that anchors historical performance to forward projections, enabling readers to test assumptions against verified baselines rather than relying on indicative estimates. From there, the analysis moves into segmentation structures that clarify how demand distributes across product types, application domains, and regional markets, without reducing the picture to simplistic ratios. Instead, the report explains the drivers behind each segment's behavior, the constraints that bound its growth, and the indicators that signal near-term shifts.
The competitive analysis section profiles the companies that are most relevant to the market's evolution, detailing their operating models, product focus, service capabilities, and recent strategic moves. This company-level view is paired with a market concentration assessment that helps readers gauge the balance between scale incumbents and regional specialists, and to understand where differentiation is being created through inventory depth, manufacturing origin, galvanizing speed, or technical support. The report also integrates an industry dynamics review that connects standards, trade policy, and raw material conditions to commercial outcomes, giving procurement and strategy teams a shared reference for scenario planning.
For practitioners, the study includes practical frameworks for evaluating supplier risk, mapping specification requirements to product grades, and anticipating how changes in tariffs or steel pricing could affect total cost of ownership. It explores how distribution networks, value-added services, and regional manufacturing footprints influence reliability and responsiveness, which are often decisive factors in fastener procurement for time-sensitive construction schedules or just-in-time fabrication workflows. The structure is designed so that executives can extract high-level strategic direction while operational teams can drill into the specifics that inform sourcing protocols, inventory policies, and project qualification criteria.
Why This Research Matters for 2026 Strategy
The 2026 decision environment will be shaped by the intersection of sustained demand growth, evolving compliance expectations, and trade dynamics that directly affect input costs and supply geography. A 5.5 percent CAGR over the forecast horizon indicates that the market will continue to expand, but expansion alone does not guarantee profitable participation. Firms that succeed will be those that can align their product availability with specification requirements, manage tariff and raw material exposure intelligently, and position their distribution or manufacturing footprint where demand is most reliably served. The report provides the context needed to make those alignments with confidence.
For manufacturers and distributors, the analysis clarifies where differentiation is being earned: through domestic melting and production claims, rapid galvanizing turnaround, multi-center distribution capability, and customized inventory programs that reduce procurement friction for fabricators and contractors. For end-users and specification professionals, the study offers a structured view of how product grades, standards, and supplier capabilities intersect, supporting more resilient qualification decisions and reducing the likelihood of specification mismatches. For investors and market entrants, the concentration data and company profiles illuminate where scale advantages exist, where regional specialists can defend share through service and origin advantages, and where recent facility or event-driven moves may signal shifts in competitive posture.
Crucially, the report is designed to be forward-useful, not just descriptive. It connects the dots between historical trajectory and projected milestones, between standards and commercial qualification, and between trade policy and sourcing strategy. By presenting these elements in a unified analytical framework, it enables leadership teams to anticipate rather than react, to test scenarios against evidence, and to prioritize investments and partnerships that are aligned with the market's most probable direction.
From Signal to Strategy: Accessing the Full Intelligence
The structural bolts market is expanding, but its expansion is being shaped by forces that reward informed positioning and punish unexamined assumptions. Standards such as ASTM F3125 and ISO 898-1 define the performance floor; trade and raw material dynamics define the cost ceiling; and company-level choices around manufacturing origin, inventory depth, and service capability define the competitive field. Understanding how these layers interact is the difference between a sourcing strategy that is merely reactive and one that is strategically durable.
This article has outlined the strategic rationale for the study and previewed the analytical depth it contains. It has highlighted the macro growth arc, the concentration structure, the profile of leading firms, and the regulatory and material context that will influence commercial outcomes through 2032. What it has not done, and what the full report is designed to do, is provide the complete segmented breakdown, the detailed regional and application-level analysis, and the granular company evaluations that executives need to finalize sourcing frameworks, capacity decisions, and market entry strategies. Those deeper layers are available in the complete Structural Bolts Market research publication. For teams preparing for 2026 and the forecast horizon beyond it, accessing the full study is the logical next step to convert market signals into executable strategy.
For detailed analysis of this topic, please visit the official page: Structural Bolts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Synthetic Leathers Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global synthetic leathers market generated approximately $35,000 million in revenue in 2020 and is projected to reach $68,000 million by 2035, reflecting a robust compound annual growth rate. Consistent demand from automotive, footwear, fashion, and furnishing sectors is driving expansion, with significant uptake in Asia-Pacific due to manufacturing capacity and cost efficiency. The market saw a sharp rebound post-pandemic, with growth accelerating from 2023 onward as sustainability initiatives gained traction and new innovations entered the market. Revenue growth is anticipated to remain steady, underpinned by technological advancements, bio-based alternatives, and rising demand in emerging economies.
Read More - https://bussinessinsights.com/research-report/global-synthetic-leathers
Footwear continues to be the largest application segment for synthetic leather globally, accounting for 38% of total market share in 2025. The automotive sector has surged to 25%, spurred by auto OEMs and consumer preference for low-maintenance, stylish interiors. Furnishing (18%) remains important for both residential and commercial uses, benefiting from synthetic leather’s endurance and design appeal. Clothing, bags & wallets, and sports cumulatively represent approximately 19%, with demand rising in urban and athleisure markets. Electronics and other specialty applications are emerging but remain niche. The applications landscape is evolving as consumers and industries prioritize sustainability, performance, and design, reshaping where synthetic leathers find their biggest uses.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-synthetic-leathers
Frequently Asked Questions
Who are the key players in Global Synthetic Leathers industry?
Top players include Kuraray Co., Ltd., Teijin Limited, Toray Industries, Inc., Fujian Polyrech Technology Co., Ltd., and Mayur Uniquoters Ltd. These companies lead the market with innovations in eco-friendly synthetic leather, wide global distribution, and strategic partnerships, catering to automotive, footwear, and fashion segments.
What is the Global Synthetic Leathers growth?
The Global Synthetic Leather market is witnessing robust growth, driven by increasing demand for animal-free leather and sustainability trends. For example, in 2023, Toray Industries reported significant revenue growth in its man-made leather segment, propelled by rising applications in automotive and luxury goods.
Which segment accounted for the largest Global Synthetic Leathers share?
The footwear segment accounted for the largest share in the global synthetic leather market. High consumption in the production of shoes and sneakers, especially by leading brands like Adidas and Nike, due to affordability, durability, and vegan trends, has significantly boosted demand for synthetic leathers in this application.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Desktop IP Phone Market Hits $385M in 2025, Projected 4.25% CAGR to 2032
By PW Consulting, 2026-09-07
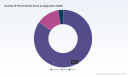
Desktop IP Phone Market 2026: A Strategic Roadmap for Enterprise Communications Buyers
The enterprise communications landscape is undergoing a quiet but profound recalibration. As organizations navigate hybrid work mandates, cloud migration backlogs, and tightening security postures, the humble desktop IP phone has reemerged not as a legacy relic but as a strategically placed endpoint that bridges unified communications, physical workspace design, and operational resilience. For executives, procurement leaders, and IT architects, the decisions made in 2026 around desktop IP telephony will echo across operational budgets, compliance postures, and employee experience metrics for years to come. Our newly published Desktop IP Phone Market research study is designed precisely for that moment of decision-making. Rather than offering a superficial snapshot, the report delivers a structured, forward-looking intelligence framework that helps leadership teams separate transient vendor narratives from structural market shifts.
Europium Acetate Market
The strategic value of this study lies in its ability to translate complex market trajectories into actionable procurement, deployment, and partnership choices. Base-year data anchored in 2025 reflects a market that has already absorbed years of infrastructure modernization, while the forecast window stretching from 2026 to 2032 captures the next wave of adoption curves, technology refinements, and competitive repositioning. Total market revenue, measured in millions of USD, moved from approximately 301.48 in 2020 to 385.02 in 2025, signaling a sustained climb that outpaces many adjacent endpoint categories. The projected trajectory through 2032 points toward continued expansion, with the 2026 forecast reading 409.53 and the 2032 horizon reaching 517.92. These figures are not merely arithmetic; they represent cumulative capital allocation, refresh-cycle timing, and competitive intensity across regions and verticals.
Worldwide Screw and Barrel Market
Crucially, the study captures a forecast period CAGR of 4.25 percent, a rate that reflects deliberate, enterprise-led growth rather than speculative hype. That percentage matters to decision-makers because it frames expectations for budget planning, inventory forecasting, and vendor negotiation leverage. A mid-single-digit growth environment rewards disciplined total cost of ownership modeling and penalizes reactive purchasing. The historical runway from 2020 through 2025 demonstrates how the market absorbed pandemic-era demand shocks, supply constraints, and accelerated digital transformation, while the forward window highlights where growth compounds through product innovation, integration depth, and regional maturation rather than through one-off order spikes.
Hoof Care Spray Market
Why 2026 Is a Pivotal Year for Desktop IP Phone Strategy
The 2026 decision environment is shaped by a convergence of forces that make endpoint selection more consequential than in prior refresh cycles. On the regulatory front, compliance and procurement scrutiny are intensifying. Recent developments have placed new constraints on the authorization and sale of certain equipment categories, and expanded covered-list rules effective in March 2026 have added complexity to sourcing decisions for IT teams that must now weigh supply continuity against geopolitical and regulatory exposure. Complementing these shifts, broader telecommunications equipment restrictions—including the placement of select vendors' devices on covered lists—have prompted enterprises to reassess vendor consolidation strategies and to prioritize interoperability, firmware lifecycle commitments, and transparent sourcing models.
Supply chain realities further sharpen the focus on endpoint strategy. Component shortages and disruptions affecting specialized electronic parts continue to extend lead times and elevate costs, which means that procurement timelines, inventory buffers, and vendor delivery reliability are now first-order planning variables rather than secondary considerations. For enterprises evaluating desktop IP phones in 2026, these dynamics elevate the importance of product roadmaps that emphasize longevity, modular firmware support, and ecosystem compatibility. The organizations that will navigate this period most effectively are those treating desktop IP phones as integrated components of a broader communications architecture—one where voice, video, presence, security, and network policy converge.
Against this backdrop, the desktop IP phone is no longer a commoditized accessory. It is an endpoint that must demonstrate compatibility with unified communications platforms, support enterprise-grade security expectations, and deliver a user experience that justifies physical deployment even in environments where soft clients and mobile devices are prevalent. The market research study examines these pressures through the lens of real procurement and deployment scenarios, ensuring that the analysis remains grounded in operational reality rather than abstract technology trends.
What the Research Delivers: An Operational Intelligence Framework
The Desktop IP Phone Market study is structured to support multi-stakeholder decision-making. It moves beyond top-line sizing to provide the analytical scaffolding necessary for segmentation, competitive benchmarking, and scenario planning. The report covers a detailed segmentation architecture that disentangles how market value is distributed across type, application, and geography without reducing the analysis to static snapshots. By examining the Video Desktop IP Phone category alongside Common Desktop IP Phone and other product variants, the study illuminates how form factor, display capability, and feature packaging influence buying behavior across different organizational contexts. Rather than treating all desktop endpoints as interchangeable, the segmentation analysis maps functional differentiation to procurement intent, helping teams align product selection with use-case requirements such as executive conferencing, frontline office deployment, or specialized departmental workflows.
The application-side segmentation further clarifies where demand is concentrated and why. Enterprise deployments continue to anchor the market's core, reflecting the centrality of desk-based voice and video endpoints in structured organizational environments. Office-centric demand and other application segments add nuance to rollout planning, particularly for organizations managing mixed environments that span corporate headquarters, satellite locations, and shared operational spaces. By situating these application patterns within the broader market trajectory, the report enables planners to prioritize deployment sequencing, lifecycle refresh timing, and support-model design with greater precision.
Geographic analysis is presented with the same analytical discipline. The report examines regional market structures across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing context on how regional maturity, regulatory environments, procurement norms, and deployment densities shape demand. Rather than isolating regions as disconnected markets, the study frames them as interconnected nodes within global enterprise strategies, where vendor presence, channel depth, and localization requirements influence both purchasing decisions and total cost of ownership. This regional framing is especially valuable for multinational organizations coordinating standardized endpoint policies while accommodating local compliance, language, and infrastructure realities.
Beyond segmentation, the research incorporates a rigorous competitive landscape assessment. It profiles the organizations that define product direction, set interoperability expectations, and shape procurement negotiations across the market. Cisco Systems maintains a prominent position through its 8800 Series and 6800/7800 series desk phones, which support full-featured VoIP with HD voice, video, and MPP firmware—an ecosystem-aligned approach that resonates with enterprises already invested in broader Cisco communications and networking architectures. Yealink, operating from Suzhou, Jiangsu, has built a strong desktop presence through its T-Series and W-Series desktop IP phones, which integrate Wi-Fi, Bluetooth, and support for up to 16 lines, positioning the brand as a flexible option for enterprise VoIP systems that demand mobility features and multi-line handling. Poly, now part of HP Inc., offers the VVX and Edge Series desk phones with color displays, support for up to 32 lines, and NoiseBlockAI technology, emphasizing audio clarity and high-density line management in professional environments.
The competitive field extends well beyond these headline names. Mitel Networks contributes the 6900 Series desktop IP phones, which combine Wi-Fi and Bluetooth support with PCLink for PC collaboration, appealing to organizations that value tighter integration between endpoints and desktop productivity workflows. Grandstream Networks, based in Belmont, Massachusetts, advances the GRP-Series of wired and Wi-Fi desktop IP phones designed around open SIP standards and enterprise integration, a posture that attracts deployments seeking interoperability and flexible system design. Fanvil focuses on professional IP desktop phones with rich functionality and high-quality builds for enterprise use, reinforcing the value proposition of durability and feature depth in demanding office environments. snom's UC Edition desktop IP phones, with Microsoft Lync and Teams qualification, address organizations that prioritize platform certification and unified communications compatibility as procurement prerequisites. Gigaset rounds out the competitive picture with a professional IP desktop phone portfolio developed for European markets, reflecting the importance of regional product strategy and localized go-to-market execution.
This competitive analysis is not a static company directory. It is constructed to reveal how product portfolios, firmware strategies, platform certifications, and regional focus intersect with procurement priorities. The study also incorporates recent market movements that illustrate how vendors are actively reshaping their positions. Gigaset expanded its professional category with a new IP desktop phone portfolio of three models and launched availability across all European markets in 2025, a sequence that signals deliberate regional emphasis and portfolio refinement. In parallel, snom's 370 UC Edition Desktop IP Phone achieved Microsoft Lync qualification in 2025, a milestone that underscores the persistent importance of platform certification in enterprise buying criteria. These developments are interpreted within the report as indicators of competitive momentum, product-directional shifts, and the evolving expectations placed on desktop IP endpoints.
Market Concentration and the Strategic Implications of an Oligopolistic Structure
One of the study's most decision-relevant contributions is its analysis of market concentration. The market exhibits a CR3 of 63.1 percent and a CR5 of 73.4 percent, indicating that a relatively small group of leading vendors commands a substantial share of revenue. For enterprise buyers, this concentration carries both benefits and risks. On one side, it suggests mature product portfolios, established interoperability ecosystems, and predictable support frameworks from the largest players. On the other side, it raises questions about pricing leverage, vendor lock-in, and the resilience of supply and firmware roadmaps if competitive intensity shifts.
The report contextualizes concentration not as a reason to default to incumbents, but as a parameter for disciplined evaluation. Enterprises are encouraged to weigh ecosystem alignment against openness, platform certification against long-term flexibility, and brand presence against total cost of ownership across multiple refresh cycles. In a concentrated market, negotiation strategy, lifecycle planning, and integration requirements become the true differentiators of procurement success. The research provides the comparative structure needed to evaluate those trade-offs systematically rather than reactively.
Translating Market Data Into Procurement and Deployment Decisions
The practical value of the study lies in its ability to connect macro trajectory with operational execution. When decision-makers understand how the market has grown from 2020 through 2025 and how the forecast extends toward 2032, they can better judge whether current procurement timing aligns with broader adoption momentum or risks buying into a slowing segment. When they examine how video-centric desktop IP offerings compare with common desktop variants, they can align hardware selection with actual usage patterns instead of defaulting to uniform endpoint standardization. When they assess application-side demand structures, they can sequence deployments to prioritize high-impact environments while managing budget phasing more effectively.
The study also supports vendor evaluation beyond feature lists. By mapping product characteristics to enterprise requirements such as HD voice quality, video readiness, multi-line capacity, wireless integration, noise suppression, platform certification, and open SIP compatibility, the report helps procurement teams build scoring frameworks that reflect operational priorities. This is particularly important in 2026, when regulatory and supply chain pressures make vendor selection a multi-dimensional exercise. A phone that satisfies a feature checklist may still underdeliver if firmware support timelines, regional availability, or certification status do not align with enterprise deployment schedules. The research's competitive and segmentation analyses are designed to expose those dependencies before purchase commitments are made.
How to Use This Study Within Your 2026 Planning Cycle
The Desktop IP Phone Market research is built to integrate with existing planning processes rather than interrupt them. It can inform budget forecasting by anchoring expectations in observed historical progression and forecast-period momentum. It can support vendor shortlisting by providing a structured basis for comparing portfolio breadth, platform alignment, and regional execution. It can guide rollout planning by showing how application and regional patterns interact with deployment density and support-model design. It can also strengthen negotiation positions by situating procurement decisions within a market where concentration, product differentiation, and regulatory dynamics all influence value creation.
For organizations managingmixed endpoint environments, the report's segmentation detail helps clarify where standardization adds value and where context-specific selection is warranted. For multinational teams, the regional framing supports coordination between global policy and local execution. For IT and procurement leaders managing risk, the regulatory and supply chain context embedded in the analysis reinforces the importance of sourcing discipline and lifecycle planning. In each case, the study is intended to reduce uncertainty without oversimplifying the decision space.
A Clear View of Where the Market Is Heading
The Desktop IP Phone Market will continue to be shaped by the interplay of enterprise adoption discipline, product differentiation, platform integration, and external pressures from regulation and supply chain conditions. The upward revenue trajectory reflected in the 2026 forecast and extending into 2032 indicates that demand is not collapsing into mobility-only paradigms; instead, it is being redefined around endpoints that deliver reliability, integration, and user experience in environments where voice and video remain mission-critical. At the same time, the mid-single-digit CAGR reminds planners that growth is methodical, which means timing, selection, and negotiation strategy matter as much as the technology itself.
This research study is designed to give decision-makers a credible, structured view of that reality. It offers the historical context to understand where the market has been, the segmentation depth to understand how value is distributed, the competitive analysis to understand who is shaping the landscape, and the forward-looking framework to anticipate where procurement conditions are heading. By combining these elements into a single intelligence asset, the report helps enterprises move from reactive endpoint purchasing to strategic communications infrastructure planning.
The full study contains the detailed data sets, segmentation splits, competitive profiles, and recent-market developments that support rigorous internal review and external negotiation. To access the complete analysis and the underlying intelligence that informs these strategic observations, visit the source page for the Desktop IP Phone Market research. There, you will find the full segmentation framework, company assessments, and market-trajectory detail needed to turn 2026 uncertainty into a defensible, data-informed action plan.
For detailed analysis of this topic, please visit the official page: Desktop IP Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Construction Chemicals Market to Hit $101.5B by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Construction Chemicals Market (2026-2032)
The global construction chemicals industry stands at a critical inflection point. As infrastructure aging, urbanization trends, and sustainability mandates converge, the sector is transitioning from a commoditized materials space into a technology-driven, performance-oriented ecosystem. For executives, investors, and strategic planners operating in 2026, understanding this transition is no longer optional. It is a prerequisite for capital allocation, portfolio positioning, and competitive resilience.
Worldwide Automatic Transport Robot Market
This market research report delivers a comprehensive, data-anchored blueprint of the construction chemicals landscape, covering historical performance from 2020 through 2025 and extending forward-looking projections across the 2026-2032 forecast horizon. The analysis is designed to cut through market noise, quantify structural drivers, and map the competitive architecture that will define industry winners in the coming years.
Worldwide Building ETFE (ethylene-tetrafluoroethylene copolymer) Membrane Market
Executive Market Trajectory and Structural Growth Context
The industry has demonstrated consistent expansion over the past half-decade, supported by steady construction activity, regulatory upgrades in building performance, and incremental adoption of advanced chemical formulations. Historical revenue progression from 2020 to 2025 reflects a sector that has navigated supply chain volatility, raw material price fluctuations, and shifting project pipelines while maintaining a clear upward trajectory. Building on this foundation, the forecast period is projected to sustain a compound annual growth rate of 6.5 percent, with market valuation advancing toward the 100 billion dollar threshold by the close of the forecast window.
Worldwide Rad-hard Semiconductor Market
This growth profile is not uniform across time or geography. The acceleration curve reflects the interplay of infrastructure stimulus programs, commercial and residential construction cycles, and the increasing specification of high-performance chemical solutions that extend asset life, reduce maintenance burdens, and improve structural reliability. For decision-makers, the strategic implication is clear: the market is large enough to absorb new entrants and product innovations, yet fragmented and regionally nuanced enough that generic strategies will underperform without localized execution and technical differentiation.
The report quantifies these macro trends while deliberately reserving granular regional and application-level breakdowns for the full dataset. This allows leadership teams to validate directional assumptions before diving into the specific splits that will inform country-level entry plans, channel strategies, and segment prioritization.
Industry Dynamics: Raw Material Pressures, Regulatory Shifts, and the Sustainability Imperative
The operating environment for construction chemical manufacturers and suppliers is being reshaped by simultaneous pressures on the cost side and the compliance side. Raw material dynamics have become a recurring strategic variable rather than an occasional disruption. In early 2026, pricing for MDI products in North America moved upward by 22 to 35 cents per pound, driven by supply constraints and broader raw material shortages. At the same time, dimethyldichlorosilane prices climbed 28 percent year-on-year in the first quarter of 2026, reflecting outages at Chinese chlor-alkali units and elevated tariffs on silicon metal. In Northeast Asia, upstream benzene and ethylene costs contributed to a 15.3 percent upward movement in styrene pricing during the same period.
These input cost movements matter because construction chemicals sit at the intersection of petrochemical feedstocks, specialty intermediates, and performance additives. Margin structures are sensitive to feedstock volatility, and procurement agility is increasingly a competitive differentiator. The report examines how leading players are responding through formulation optimization, supplier diversification, inventory strategies, and selective pass-through mechanisms, without exposing the proprietary margin models and cost-ecosystem assessments contained in the full analysis.
On the regulatory front, the landscape is tightening in ways that directly affect product development, testing, and market access. The new Construction Products Regulation in the European Union has entered into force, imposing stricter compliance requirements for construction chemical products. This shift raises the bar for documentation, performance verification, and lifecycle transparency. For multinational suppliers, the EU framework often becomes a de facto benchmark that influences product design and regulatory strategies in other regions as well.
Layering onto compliance is the accelerating emphasis on sustainability. Manufacturers are expanding eco-friendly waterproofing solutions and low-impact formulations to align with green building certifications, public procurement requirements, and customer expectations around embodied carbon and environmental footprint. The industry is moving beyond marketing claims toward measurable performance attributes, which means that R&D roadmaps, patent positioning, and product certification pipelines are becoming strategic assets in their own right.
The report integrates these dynamics into a cohesive market forces framework, helping readers distinguish between transient price shocks and structural cost shifts, and between regulatory compliance burdens and competitive opportunities created by early movers in sustainable product portfolios.
Competitive Architecture: Consolidation, Capability Build-Out, and Regional Re-positioning
The construction chemicals sector is characterized by a concentrated tier of global specialists operating alongside strong regional players and niche technology providers. The report profiles the core companies that are shaping competitive outcomes, including Sika AG, BASF SE through its Master Builders Solutions brand, MAPEI S.p.A., Dow Inc., Saint-Gobain, Arkema S.A., RPM International Inc., GCP Applied Technologies, Fosroc International, Pidilite Industries Limited, Wacker Chemie AG, Nouryon Holding B.V., and Chryso Group.
Rather than treating these firms as static corporate listings, the analysis maps their strategic positioning across concrete admixtures, waterproofing and roofing systems, flooring chemicals, sealants and adhesives, and repair and restoration solutions. The focus is on where each organization is building capability, where it is exposed to input cost risk, and how it is leveraging distribution networks, technical service teams, and application expertise to defend or expand share.
Recent corporate activity underscores a clear consolidation and capability-acquisition rhythm. In 2025, Saint-Gobain acquired the business assets of Interstar Materials, Inc., strengthening its Construction Chemicals activities in the United States and Canada. That move was followed by the completion of Saint-Gobain's acquisition of Fosroc, a leading player in construction chemicals across Asia and emerging markets, consolidating a broader international footprint and expanding access to high-growth regions. In parallel, Master Builders Solutions expanded its U.S. manufacturing footprint with two new admixture sites, signaling a commitment to capacity and proximity to key customer segments. Master Builders Solutions also inaugurated a new state-of-the-art manufacturing facility in Taloja, Navi Mumbai, India, reinforcing its presence in a market where infrastructure demand and urbanization continue to drive volume growth.
Trade presence and solution integration are equally indicative of strategic intent. Saint-Gobain showcased its unified construction chemicals solutions at World of Concrete 2026, highlighting the industry's broader move toward bundled performance offerings rather than isolated product sales. These developments matter because they reveal how incumbents are preparing for the next cycle: through capacity investment in priority markets, acquisition of specialized portfolios, and stronger integration across admixture, waterproofing, and repair ecosystems.
The report translates these moves into a competitive intensity assessment, including concentration patterns that illustrate how value is distributed across the top players. The top three firms collectively account for 52 percent of market revenue, while the top five reach 61 percent. This concentration profile signals that scale, technical portfolio breadth, and global service infrastructure remain powerful advantages, but it also leaves meaningful room for specialized challengers, regional leaders, and innovation-led entrants in adjacent segments. The full analysis provides a more detailed mapping of share dynamics and strategic group behavior, while preserving the granular splits for the complete report.
Product and Application Architecture: Where Value Is Created and Captured
Construction chemicals are no longer a supporting category. They are increasingly central to specification decisions because they influence durability, speed of construction, lifecycle cost, and overall building performance. The product landscape analyzed in the report spans concrete admixtures, waterproofing and roofing systems, flooring chemicals, sealants and adhesives, and a set of specialized repair and restoration solutions. Each category carries distinct demand drivers, formulation complexity, and margin characteristics, and each responds differently to regional construction practices and project types.
Concrete admixtures remain a cornerstone of the sector because they directly affect workability, strength development, durability, and construction efficiency. As projects demand faster cycle times, more resilient structures, and lower water-cement ratios in certain applications, admixture technology continues to evolve. Waterproofing and roofing solutions are gaining strategic importance as asset owners prioritize moisture management, energy efficiency, and long-term protection against environmental exposure. Flooring chemicals serve both aesthetic and functional requirements in commercial, industrial, and residential settings, while sealants and adhesives underpin envelope integrity, joint performance, and assembly reliability across multiple construction systems. Repair and restoration chemicals address the growing need to extend the service life of existing assets, a theme that becomes more prominent as infrastructure ages and renovation activity increases.
On the application side, demand is distributed across residential, non-residential, infrastructure, and repair segments. The balance among these segments varies by region, economic cycle, and public investment pipeline. Residential construction tends to be more cyclical and sensitive to housing market conditions, while non-residential projects reflect commercial development, institutional spending, and workplace transformation trends. Infrastructure demand is shaped by public capital programs, transit expansion, utilities modernization, and resilience-focused rebuilds. Repair and maintenance applications represent a smaller but strategically important pool, often linked to lifecycle management and the macroeconomic value of asset preservation.
The report structures these product and application dimensions around their strategic implications: where formulation leadership creates pricing power, where service and technical support influence specification, and where regional construction norms shape adoption curves. This framing allows readers to identify the segments most aligned with their capabilities before accessing the detailed breakdowns that support precise segment planning.
What the Report Delivers: Commercial Intelligence for 2026 Decision-Making
This market research is built for execution, not just observation. It is intended to support strategic planning, investment prioritization, competitive positioning, and market-entry evaluation in a sector where technical credibility and regional execution often determine outcomes more than broad market narratives.
The report includes the following operational content:
- Historical market sizing from 2020 to 2025, establishing a verified baseline for growth analysis and scenario calibration
- Forecast projections from 2026 to 2032, anchored to the 6.5 percent CAGR trajectory and extending to the projected 2032 valuation threshold
- Segment-level evaluation across product types and application categories, with guidance on where demand is structurally strengthening and where competitive intensity is rising
- Regional demand context that distinguishes between mature, stable markets and faster-growing regions without prematurely disclosing the full regional splits
- Competitive profiling of leading global and regional players, including capabilities, strategic moves, and positioning across core product families
- Recent corporate developments such as capacity expansions, acquisitions, facility inaugurations, and trade-show integrations that signal forward strategy
- Input cost and regulatory dynamics, including MDI pricing movements, silane and styrene cost pressures, and the impact of the new EU Construction Products Regulation
- Sustainability and compliance themes that affect product development, certification, and customer specification behavior
- Strategic implications for manufacturers, distributors, specifiers, and investors seeking to align portfolio choices with market reality
By combining macro growth context with company-level activity and sector-specific cost and regulatory signals, the report creates a decision-ready environment. Readers can test assumptions about demand durability, assess exposure to feedstock volatility, anticipate compliance-driven product changes, and evaluate where consolidation or capability investment is likely to reshape competitive access.
How to Use This Intelligence in 2026
For senior leadership teams, the immediate value of this research lies in its ability to convert a complex market into an actionable strategic map. The 2026 decision environment is shaped by three overlapping questions: where growth is most durable, where cost and compliance pressures will reshape economics, and where competitive positioning will be won through technology, service, or scale.
The report helps answer these questions by separating long-term structural demand from short-term project cyclicality, by clarifying which product families are most exposed to input cost volatility, and by highlighting the corporate moves that indicate where incumbents are placing their bets. It also provides a basis for scenario planning, whether the objective is to evaluate new geographic entry, prioritize R&D investment, refine channel strategy, or assess acquisition targets and partnership opportunities.
Because the construction chemicals market rewards specificity, the report intentionally preserves detailed regional and application-level data for the full edition. This ensures that decision-makers can first align on direction and strategic logic, then access the precise figures needed for country-level planning, segment targeting, and commercial modeling.
Strategic Conclusion: Positioning for the 2026-2032 Cycle
The construction chemicals market is entering a phase in which growth, regulation, sustainability, and consolidation will interact more intensely than in previous cycles. Historical momentum from 2020 to 2025 has set a solid foundation, and the forecast trajectory through 2032 points to continued expansion at a meaningful pace. Yet the operational reality for companies is more nuanced: input cost swings, evolving compliance requirements, regional demand differences, and concentrated competition all demand a disciplined strategic Response.
This report is designed to give executives that discipline. It combines validated market sizing, forward-looking growth analysis, competitive profiling, and recent industry developments into a single integrated view. It also respects the complexity of the sector by keeping the most granular splits and proprietary breakdowns within the full research package, where they can be used for detailed planning without diluting the strategic narrative.
For organizations seeking to act with confidence in 2026, the next step is to translate this market-level perspective into segment-specific strategy. The complete report provides the deeper data architecture required to do that, enabling more precise prioritization of regions, product families, application segments, and competitive responses as the market moves through the rest of the decade.
For detailed analysis of this topic, please visit the official page: Construction Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Fog Coatings Market to Surpass $272.92M by 2032 at 3.5% CAGR
By PW Consulting, 2026-09-07
Anti-Fog Coatings Market 2026–2032: Strategic Intelligence for Capital Allocation and Product Roadmapping
The global anti-fog coatings market has entered a phase of structural maturation, where incremental volume growth is increasingly decided by formulation chemistry, substrate compatibility, regulatory shifts, and downstream OEM integration rather than broad-based demand expansion. For executives planning capital deployment, R&D prioritization, and regional sourcing strategies through the remainder of the decade, the difference between reactive positioning and proactive market leadership will hinge on how precisely they can read the interplay between hydrophilic performance requirements, sustainability mandates, and appliance-specific optical clarity thresholds. This introduction frames why a rigorously constructed market study is no longer a passive reference document but a decision-grade asset for 2026 strategy cycles.
Worldwide Respiratory Collector Market
From Volume Recovery to Value Discipline
Over the 2020–2025 historical window, the market demonstrated a clear trajectory of recovery and consolidation. Revenue climbed from approximately 163.15 million USD in 2020 to 215.0 million USD by 2025, reflecting not only post-pandemic normalization across optical, safety, and automotive supply chains but also the embedding of anti-fog functionality as a baseline expectation rather than a premium add-on. Moving into 2026, the forecast period signals a more measured pace of expansion. The overarching compound annual growth rate is tracked at 3.5 percent, with revenue projected to reach 217.29 million USD in 2026 and gradually advance toward 272.92 million USD by 2032. This growth profile is deliberately moderate, underscoring that top-line expansion will be earned through product endurance, regulatory alignment, and premiumized performance tiers rather than through aggressive volume plays alone.
Powder Tablet Press Mold Market
For strategists, the implication is clear. Budgeting and forecasting models that assume linear ramp-up will overstate short-term upside and underappreciate the segment-level divergence that defines the market. Some applications and substrates will see faster payback cycles because of embedded OEM validation and repeat procurement, while others will experience margin compression as formulation costs, compliance overhead, and processing complexity rise. A disciplined research baseline separates these trajectories, enabling leadership to allocate engineering resources, inventory positioning, and partnership investments where the probability-adjusted return is strongest.
Ceramic Watertight Concrete Market
What the Study Delivers Beyond Top-Line Estimates
A commercially useful market study must go past aggregate revenue and CAGR figures. It needs to translate market structure into operational levers that product managers, procurement leads, and corporate development teams can act upon. The full report is built around that operational logic. It maps how hydrophilic and permanent anti-fog chemistries are distributed across substrate families, where water-washable and abrasion-resistant systems create application-fit advantages, and which product types hold structural cost or performance advantages under specific manufacturing conditions. Rather than presenting segmentation as a static snapshot, the study connects each segment to real-world adoption drivers, process constraints, and switching costs that influence procurement behavior.
Equally important is the treatment of end-use demand. The analysis dissects how building and construction, automotive, aviation and aerospace, electronics, military and security, medical and safety industries, and ancillary sectors each approach fog control with different performance thresholds, certification burdens, and durability expectations. Readers gain a clarified view of where optical clarity, heat stability, UV resistance, and long-term hydrophilic retention matter most, and where cost-efficiency and ease of application dominate purchasing decisions. By layering substrate suitability, product chemistry, regional procurement patterns, and end-use specifications into a single analytical framework, the report equips teams to evaluate not only where demand is forming, but how it is likely to be served and monetized.
The study also incorporates competitive intelligence that is practical rather than ceremonial. It examines the positioning of leading participants such as FSI Coating Technologies, Momentive Performance Materials, Hydromer Inc., NSG Group, and WeeTect Material Limited, alongside recent market activity from firms including Cosmo Films, Solabs Nanotechnology GmbH, PPG Industries, Hanwha Chemical, and 3M. The intent is not to catalog announcements, but to interpret what they reveal about formulation priorities, OEM alignment, sustainability direction, and technology differentiation. Recent activity—such as updated premium coating highlights, transparent BOPET lidding film introductions for food packaging, the emergence of passive thermal anti-fog solutions, water-based eco-friendly formulations for automotive windshields, capacity expansion for waterborne coatings with green chemistry incentives, and the integration of embedded anti-microbial properties in next-generation AR headset coatings—collectively signals where the industry is pushing its technical frontier.
Why 2026 Decisions Require Segmented Precision
The strategic urgency of 2026 lies in the widening gap between broad market growth and segment-level opportunity. Companies that treat the market as a single demand pool risk misallocating resources to applications where regulatory friction, raw material cost structures, or processing complexity erode profitability. At the same time, firms that understand where glycerol esters remain the practical workhorse chemistry due to low raw material cost and established food-contact acceptability, and where proprietary in-house anti-fog technologies are being adopted to reduce supply chain expenses, can structure sourcing and formulation strategies with greater leverage.
This is particularly relevant for organizations navigating sustainability and compliance transitions. Demand for eco-friendly, water-based, and otherwise compliant coatings is reshaping both automotive windshield applications and high-end optical and automotive markets, supported in some regions by government incentives for green chemistry. At the same time, expert lens treatments and coatings can elevate production costs, making supply chain improvements and proprietary processing capabilities a meaningful source of margin protection. The market study provides the evidentiary backdrop required to decide when to invest in formulation upgrades, when to secure OEM-approved product lines, and when to prioritize geographic or substrate exposure that offers faster route-to-market clearance.
Competitive Structure and the Reality of Market Share
A frequently underestimated strategic input is market concentration. With CR3 at 24.6 percent and CR5 at 26.2 percent, the industry is fragmented enough to preserve innovation entry points and customer-specific formulation opportunities, yet consolidated enough that established players command meaningful technical credibility, certification track records, and OEM relationships. This structure matters for both incumbents and entrants. For incumbents, it rewards continued differentiation through permanent performance-based systems, abrasion resistance, optical clarity, and application-specific approvals. For challengers, it suggests that broad commodity positioning is unlikely to outperform targeted, performance-validated solutions in high-specification segments.
The profiled companies illustrate how differentiation is being built. One global leader emphasizes permanent performance-based, water-washable anti-fog coating systems and abrasion-resistant coatings across polyester film, plastics, glass, mirrors, and metal substrates, with product lines approved for demanding OEM environments. Another major supplier focuses on silicone-based anti-fog coatings that deliver long-term hydrophilic performance, high transparency, and optical clarity for automotive lighting, sensors, ADAS, safety glasses, visors, ophthalmics, and electric vehicle front-end modules. A third manufacturer builds its identity around premium hydrophilic anti-fog and condensation control coatings with heat- and UV-stable options for medical and safety devices, eyewear, sensors, LEDs, automotive windshields, and industrial substrates. A fourth provider contributes high-performance sol-gel hybrid anti-fogging coatings designed for automotive cameras, ADAS, surveillance cameras, optical filters, lenses, and plastic substrates. A fifth developer targets hydrophilic anti-fog coatings applied through spraying or dipping for plastic sheets, films, and injection-molded visors, with emphasis on permanent anti-fog and anti-scratch performance for helmet visors, face shields, goggles, mirrors, and freezer displays.
Read together, these profiles show that competitive advantage is not simply a matter of price, but of performance durability, substrate fit, application approval, and increasingly, environmental and safety compliance. Strategic planning should therefore evaluate partnerships, acquisitions, and internal development not only through the lens of market size, but through the lens of specification capture and OEM trust.
How to Use This Research in 2026 Planning Cycles
The study is designed to support multiple decision pathways at once. Product leaders can use the segmentation mapping to identify which substrate and product-type combinations warrant deeper formulation investment. Procurement and supply chain teams can use the demand patterns to anticipate where repeat buying, certification cycles, and durability requirements will pressure lead times and inventory planning. Corporate development teams can use the competitive and regulatory context to assess where green chemistry momentum, capacity expansion, and next-generation thermal or embedded-property coatings are likely to reshape supplier options. And executives overseeing regional exposure can use the geographic distribution of demand to weigh where concentration offers efficiency against where diversification reduces dependency risk.
Because the report is structured to preserve segment-level distinctions without flattening them into headline numbers, it allows leadership to conduct scenario planning with greater confidence. Teams can compare a strategy centered on automotive-adjacent optical performance against one emphasizing medical and safety device compatibility, and they can evaluate whether premium permanent coatings or more cost-efficient hydrophilic systems align better with their target customer base. The value of the research lies in making those trade-offs explicit rather than speculative.
What Remains in the Full Study
To preserve analytical integrity while still driving action, this introduction deliberately omits the detailed regional and application breakdowns, segment-specific revenue figures, and granular product-type proportions that constitute the core intelligence of the full report. Those figures are not ornamental. They are the decision scaffolding that enables precise market entry timing, budget sizing, and competitive positioning. Access to the complete dataset is necessary for teams that need to compare specific regional demand intensity, segment revenue shares, and end-use prioritization without relying on approximations.
The full study also expands the competitive landscape beyond the most visible leaders, providing a wider view of supplier positioning, application-specific strengths, and recent product and partnership activity that shapes near-term buyer behavior. For organizations preparing 2026 budgets, roadmap approvals, and regional sourcing reviews, that expanded view is where the difference between good strategy and implementable strategy is usually found.
Final Strategic Takeaway
The anti-fog coatings market is not defined by dramatic volatility, but by the cumulative effect of formulation performance, regulatory direction, OEM specification capture, and substrate-level manufacturing realities. With moderate overall growth and a fragmented-but-concentrated competitive structure, the winners in 2026 will be those who act on segment-level clarity rather than aggregate momentum. The full market study provides that clarity, pairing macro trajectory with operational segmentation, competitive interpretation, and recent industry signals that matter for product, procurement, and corporate strategy. For decision-makers who need to convert market visibility into concrete investment and partnership choices, the complete report is the necessary next step.
For detailed analysis of this topic, please visit the official page: Anti-Fog Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global zipper market is projected to grow steadily, with revenues increasing from 13,450 Million USD in 2020 to approximately 24,800 Million USD by 2035. This upward trajectory is fueled by urbanization, value-added product demand, and market expansion in emerging economies. Recent innovations in advanced zipper functionality and the integration of sustainable materials are accelerating growth further, positioning market leaders to capture greater value across multiple industries.
Read More - https://bussinessinsights.com/research-report/global-zipper
The global zipper market in 2025 is led by the apparel segment, which accounts for the largest share due to the widespread and diverse use of zippers in garment manufacturing. Luggage and bag applications follow, responding to growth in travel, outdoor activities, and fashion accessories. The footwear and automotive sectors also contribute significantly, driven by global lifestyle and design trends. Manufacturers are innovating to address durability, sustainability, and aesthetic demands across these key application verticals, ensuring robust market momentum.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-zipper
Frequently Asked Questions
Who are the key players in Global Zipper industry?
The top 5 players in the global zipper industry are YKK Group, SBS Zipper, RIRI Group, IDEAL Fastener, and Fujian SBS Zipper Science & Technology. These companies are leaders in innovation, manufacturing, and global distribution, catering to major apparel, luggage, and footwear brands worldwide.
What is the Global Zipper growth?
The global zipper market has experienced steady growth, driven by the fashion and luggage sectors. For instance, YKK Group reported increased sales in 2023 due to heightened demand in the apparel industry, especially in Asia-Pacific, reflecting a positive trend in the overall zipper market.
Which segment accounted for the largest Global Zipper share?
The apparel segment accounts for the largest market share of global zippers, owing to their extensive use in jackets, trousers, jeans, and fashion accessories. Leading fashion brands’ increasing requirement for quality closures fuels this segment’s growth and dominance in the zipper industry.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com