

Blogs
PW Consulting: Battery Market Hits 200M USD in 2025, Projects 389.78M by 2032
By PW Consulting, 2026-09-07
Powering the Future: Strategic Intelligence for the 2026 Battery Market
Navigating an Era of Record Valuations and Technological Disruption
The global battery industry is currently undergoing one of the most significant transformations in its history. For executives, investors, and strategic planners, the difference between capturing market share and losing ground lies in the granularity of intelligence available at the decision-making table. As we move through 2026, the convergence of aggressive capacity expansion, fluctuating raw material costs, and evolving regulatory frameworks has created a landscape where generic market data is no longer sufficient. Organizations require specialized, forward-looking intelligence to architect resilient supply chains and identify high-growth verticals.
Worldwide Kraft Paper Label Market
This article serves as a strategic overview of the current market environment, drawing upon comprehensive data and industry analysis to highlight the critical dynamics shaping the sector. While public headlines often focus on headline figures, the real value for enterprise strategy lies in understanding the underlying segmentation, competitive positioning, and regulatory pressures that define the operational reality. The following insights are designed to frame the necessity for deep-dive analysis in order to secure a competitive advantage in the coming years.
Worldwide 3C Electronic Goods Shell Coating Market
The Macro Trajectory: Sustained Growth Amidst Volatility
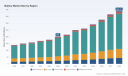
The fundamental demand drivers for batteries remain robust, underpinned by the dual engines of electrification in mobility and the rapid deployment of battery energy storage systems (BESS) globally. Historical data indicates a clear upward trajectory in market valuation, reflecting the tangible shift toward sustainable energy infrastructure. Starting from a base of approximately 140.0 million USD in 2020, the market has demonstrated consistent resilience, expanding to reach 200.0 million USD by the base year of 2025. This growth is not merely nominal; it represents a compounding expansion in both unit volume and value as applications diversify.
Worldwide Solar Clamp Meter Market
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum. The market is projected to climb from 215.7 million USD in 2026 to nearly 390.0 million USD by 2032. This expansion translates to a Compound Annual Growth Rate (CAGR) of approximately 10.06 percent over the forecast horizon. Such a rate signals a mature yet accelerating market phase. For strategic planners, this CAGR implies that passive participation is insufficient; companies must actively pursue capacity or partnership agreements to maintain relevance as the total addressable market widens significantly over the next half-decade.
However, macro growth figures often mask the friction points within the supply chain. The industry is not expanding in a vacuum. The cost of key inputs, particularly for lithium-based technologies, remains a critical variable. Recent industry intelligence notes that average lithium prices at the beginning of 2026 were more than twice as high as in the same period of the previous year. This was driven by faster demand growth in battery energy storage and temporary supply disruptions. This cost pressure directly impacts margin structures and necessitates sophisticated procurement strategies that go beyond simple hedging, requiring a deep understanding of regional production capacities and alternative chemistry pathways.
Segmentation Dynamics: Where Value Resides
Understanding the aggregate market size is only the first step. The real strategic opportunity lies in dissecting where the revenue is generated. The market is divided across multiple axes—technology type, application sector, and geography—each presenting distinct risk-reward profiles. While specific percentage breakdowns are proprietary to our full research suite, the broad strokes of the segmentation reveal clear hierarchies.
In terms of technology, the market is characterized by a dual dominance. Established lead-acid technologies continue to hold a significant portion of the market share, particularly in low-voltage and industrial applications where reliability and cost-efficiency are paramount. Simultaneously, lithium-ion technology continues to claim an increasing share of the revenue pie, driven by the high-energy density requirements of electric mobility and stationary storage. This technological bifurcation means that portfolio strategy cannot be monolithic. Firms must decide whether to double down on the stable cash flows of mature chemistries or take calculated risks on the higher growth potential of advanced lithium and emerging sodium-based technologies.
Application segmentation further complicates the picture. The automotive sector remains the largest revenue driver, absorbing a substantial portion of total battery demand as the global fleet transitions away from internal combustion engines. However, consumer electronics and other industrial applications contribute significantly to the overall volume. The "Others" category within the application segmentation, which includes industrial and specialized uses, often hides pockets of high-margin opportunity that are less susceptible to commodity price fluctuations. Identifying which specific sub-segments within these broader categories are outperforming requires access to granular data that aggregates often obscure.
Geographic and Competitive Concentration
Geographically, the market exhibits a distinct concentration of activity. The Asia Pacific region commands a dominant position in the global landscape, reflecting its role as both a manufacturing hub and a massive consumer market for electric vehicles and electronics. Europe and North America follow, with established industrial bases and strong regulatory push towards electrification. Latin America and the Middle East and Africa, while currently smaller in absolute terms, represent emerging zones of interest for resource extraction and future deployment.
This geographic distribution directly influences the competitive landscape. The market is not perfectly competitive; it is characterized by a moderate to high level of concentration among top players. The top three companies hold a significant portion of the market share, and the top five extend this dominance further. This concentration suggests that barriers to entry remain high, particularly in segments requiring complex manufacturing capabilities and extensive distribution networks. For new entrants or existing players looking to expand, M&A activity or strategic joint ventures may be more viable paths than organic build-outs in highly saturated regions.
Key incumbents have established strong footholds across these regions. Companies like Clarios have cemented their status as the world's largest manufacturer and supplier of low-voltage batteries and solutions, maintaining a leading global market share in low-voltage mobility batteries. Similarly, EnerSys stands as a leading provider of energy storage systems and industrial batteries for automotive, industrial, and renewable applications. These firms represent the benchmark for operational scale and technological integration.
In the lead-acid segment, traditional manufacturing powerhouses continue to leverage their specialized knowledge. East Penn Manufacturing Co serves as a BCI manufacturer member and key supplier of sealed lead-acid batteries, while Stryten Energy focuses on advanced battery solutions for industrial, agricultural, and commercial markets. Continental players, such as ContiTech Battery Systems, operate as global producers of low-voltage batteries and systems for automotive and industrial use, illustrating the transatlantic nature of the supply chain. Additionally, manufacturers like Crown Battery Mfg. Co. and U.S. Battery Mfg. Co. continue to produce advanced battery systems and heavy-duty industrial batteries, catering to niche but critical sectors.
The landscape also includes significant distribution and specialized production entities. Interstate Batteries operates as a major distributor and provider with manufacturing ties in the North American market, while CD Trojan produces deep-cycle and industrial batteries for renewable energy, marine, and backup power. On the international stage, producers like Leoch Battery Corporation and CSB Energy Technology provide global production capabilities for lithium-ion and lead-acid batteries, serving consumer and industrial use cases across different regions.
The 2026 Regulatory and Safety Horizon
Beyond economics and technology, 2026 is shaping up to be a pivotal year for regulation and safety standards. These factors are not peripheral concerns; they are central to compliance and market access. In February 2026, the U.S. Department of Labor OSHA issued a letter of interpretation clarifying the recording of workplace injuries involving personal rechargeable lithium-ion batteries on OSHA Forms 300. This clarification tightens the compliance requirements for facilities handling these batteries, directly impacting operational protocols and insurance liabilities.
Simultaneously, regional codes are evolving. New York State adopted updated energy storage safety codes, informed by collaboration with FDNY and national experts, with active application continuing through 2026 for battery installations. As one of the largest state markets in the U.S., New York's code updates often serve as a bellwether for broader national standards. Companies operating in stationary storage or large-scale deployment must ensure their products and installation practices align with these stringent safety protocols.
Consumer safety issues also remain prominent. In May 2026, significant recalls were reported involving lithium battery pouches due to risks associated with ingestion and child-resistant packaging statutes. These events highlight the ongoing scrutiny from regulatory bodies like the U.S. Consumer Product Safety Commission. For manufacturers of consumer-facing battery products, adherence to packaging and safety standards is a non-negotiable component of product lifecycle management. Failure to comply can result in costly recalls and reputational damage that outweighs short-term production savings.
Innovation and Industry Collaboration
Amidst the regulatory tightening, industry bodies are actively working to shape the future of battery technology. In May 2026, the Battery Council International (BCI) convened the first-ever meeting of its new Sodium Battery Industry Group (SBIG). This initiative aims to advance innovation in sodium-based battery technologies, signaling a strategic pivot towards chemistries that may offer cost and sustainability advantages over lithium-dependent solutions. This development is particularly relevant for entities looking at long-term technology roadmaps, as sodium-ion technology could disrupt the current cost structures of stationary storage.
Furthermore, BCI was awarded the Battery Star Award by the BEPA for contributions to safer batteries and industry standards, reinforcing the industry's commitment to safety culture. Conferences such as the RISE Battery Safety Conference in Gothenburg, Sweden, continue to focus on battery safety standards and recycling, emphasizing the circular economy aspect of the battery lifecycle. These industry gatherings provide crucial networking and intelligence-gathering opportunities, allowing stakeholders to stay ahead of standardization curves that might otherwise catch them off guard.
Strategic Imperatives for Decision Makers
Given the complexity of the market dynamics, what should the strategic focus be for 2026? First, supply chain resilience must be prioritized. With lithium prices fluctuating significantly and supply disruptions occurring, relying on single-source procurement is a strategic vulnerability. Diversification of supplier bases and exploration of alternative chemistries, inspired by developments like the SBIG initiatives, should be part of the risk management framework.
Second, regulatory compliance must be treated as a strategic capability rather than a back-office function. The OSHA clarifications and new state-level energy storage codes mean that product design and operational safety protocols need to be reviewed continuously. Companies that proactively adapt to these standards can use them as a competitive differentiator, marketing their adherence to safety as a value proposition to risk-averse institutional buyers.
Third, competitive positioning requires a clear understanding of the market concentration. In segments dominated by top players like Clarios or EnerSys, competition will likely revolve around service quality, total cost of ownership, and specialized application expertise rather than price alone. For smaller or mid-tier manufacturers, finding a niche in the industrial or specialized application sectors—where the "Others" categories reside—may offer better margins than competing head-to-head in high-volume automotive segments.
Leveraging Deep Market Intelligence
While the macro trends, key players, and regulatory shifts outlined above provide a valuable context, they represent only the surface level of the available intelligence. The true value for your organization lies in the specific data points that drive investment decisions. This includes precise segmentation splits by region, type, and application, detailed profiles of over twenty key companies with URLs and specific market positions, and granular data on market concentration and growth rates by sub-sector.
Our comprehensive Battery Market Market Research report encapsulates these details. It provides the analytical depth required to model future scenarios, benchmark against competitors, and validate entry strategies. The report captures the nuances of the revenue units, the specific historical trajectories from 2020 to 2025, and the detailed forecast period through 2032. It also integrates the latest recent developments and industry context noise into a cohesive analytical framework.
To make informed decisions in this high-stakes environment, relying on high-level summaries is insufficient. You need the full spectrum of data to validate your hypotheses and secure your strategic roadmap. We invite you to access the complete report to unlock the specific insights necessary to navigate the battery market's growth trajectory through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Steering System Market to Reach $493M by 2032 at 4.94% CAGR
By PW Consulting, 2026-09-07
Navigating the Currents: Strategic Insights into the Marine Steering System Market Through 2032
The global marine steering system market is entering a pivotal phase of transformation, driven by evolving vessel architectures, tightening regulatory frameworks, and the accelerating adoption of electronic and hybrid control technologies. For executives, procurement leaders, and strategic planners operating in commercial shipping, recreational marine manufacturing, naval procurement, or offshore operations, understanding the trajectory of this market is no longer optional—it is a critical input to capital allocation, product roadmap development, and competitive positioning. Our latest comprehensive study on the Marine Steering System Market delivers the analytical rigor and forward-looking intelligence required to navigate this space with confidence through 2032.
Matte Tin Additives Market
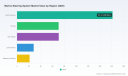
The market has demonstrated consistent upward momentum over the past half-decade, reflecting broader trends in marine fleet modernization, rising demand for precision maneuvering capabilities, and the gradual shift from purely mechanical linkages toward integrated hydraulic and electro-mechanical solutions. Base-year valuations for 2025 sit at $352.0 million, with historical tracking showing a steady climb from $277.1 million in 2020. Looking ahead, the forecast horizon extends to 2032, projecting revenues to reach $493.0 million. This expansion translates to a compound annual growth rate of 4.94 percent, underscoring a market that is growing at a measured but structurally significant pace. The consistency of this trajectory suggests durable demand fundamentals rather than cyclical spikes, making it an attractive space for long-term investment and strategic partnership development.
Escape Door Control Unit Market
However, aggregate figures only tell part of the story. The real strategic value of our research lies in its granular dissection of how value flows across vessel types, steering technology categories, and regional operating environments. Our analysis maps the competitive architecture of the industry, highlighting a moderately fragmented landscape where concentration ratios remain relatively contained. The top three players account for approximately 25.0 percent of total market revenue, while the top five collectively capture 28.5 percent. This structure signals both opportunity and challenge: entrants and established players alike must differentiate through engineering excellence, certification portfolios, service networks, and technological integration rather than relying solely on scale. For organizations evaluating mergers, acquisitions, supplier diversification, or market entry strategies, understanding this concentration dynamic is essential to anticipating competitive retaliation, pricing power limits, and partnership leverage.
Worldwide Tram Pantograph Market
Decomposing the Market by Technology and Vessel Architecture
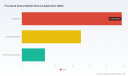
The marine steering system landscape is fundamentally shaped by the interplay between steering technology categories and the diverse vessel segments they serve. Our report provides a meticulous breakdown of how revenue distributes across rotary vane, ram-type, and electro-mechanical configurations, alongside a parallel analysis of small recreational boats, yachts and luxury boats, commercial vessels, passenger vessels, and military and defense vessels. Rather than presenting static percentage splits, our methodology evaluates the underlying demand drivers, lifecycle cost considerations, regulatory compliance pathways, and performance expectations that dictate share dynamics within each segment.
Ram-type steering systems continue to hold substantial relevance for applications demanding high load-bearing capacity, precise hydraulic response, and robust durability under demanding sea states. Rotary vane architectures remain entrenched in specific commercial and recreational use cases where compactness, ease of integration, and maintenance accessibility drive procurement decisions. Meanwhile, electro-mechanical steering is gaining incremental ground as vessel builders and operators pursue reduced hydraulic fluid dependency, simplified routing, and compatibility with integrated bridge and automation systems. The pace and magnitude of this technology transition are not uniform; they vary significantly based on vessel size, operational profile, regional classification society requirements, and total cost of ownership calculations. Our report quantifies these nuances, helping decision-makers identify which technology pathways are likely to capture incremental share in specific sub-segments and which face headwinds from cost, certification complexity, or operator resistance.
On the vessel side, small recreational boats and yachts and luxury boats represent high-volume, design-sensitive segments where steering systems must balance performance, aesthetics, weight constraints, and price elasticity. Commercial vessels and passenger vessels prioritize reliability, redundancy, class approval, and adherence to stringent maintenance schedules. Military and defense vessels introduce additional layers of requirement around stealth, electronic hardening, rapid deployability, and integration with combat management or navigation suites. By mapping revenue dynamics across these vessel categories, our study illuminates where margin profiles are strongest, where volume growth is most predictable, and where customization requirements create barriers to entry or opportunities for differentiated value propositions.
Regional Dynamics and the Geography of Demand
Geographic distribution of marine steering system revenue reflects the interplay of shipbuilding activity, fleet renewal cycles, regulatory environments, and end-user purchasing behavior. Our analysis examines North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa not merely as destination markets but as ecosystems with distinct procurement rhythms, certification expectations, and competitive intensities. In regions with active commercial shipbuilding and offshore infrastructure development, demand is often tied to newbuild programs and yard throughput. In mature recreational marine markets, purchasing patterns are more closely linked to consumer confidence, marina expansion, and 애프터마켓 replacement cycles. In defense and governmental procurement contexts, budgeting cadence, platform integration timelines, and Sovereign procurement rules shape demand trajectories in ways that differ sharply from commercial markets.
Our report avoids oversimplified regional generalizations. Instead, it evaluates how regional concentration of classification societies, local content expectations, logistics and service network requirements, and the presence of domestic manufacturers influence both pricing strategies and market access. For companies assessing export potential, localizing supply chains, or selecting pilot markets for new product introductions, this regional granularity is indispensable. It enables leadership teams to align go-to-market sequencing with regions where regulatory friction is manageable, where service infrastructure is sufficiently developed, and where competitor density permits realistic positioning.
Competitive Landscape: Ten Companies Shaping the Market
The marine steering system sector is defined by a mix of established global manufacturers, specialized hydraulic and mechanical engineers, and emerging players introducing smart steering technologies and patent-pending innovations. Our research profiles ten key enterprises whose product portfolios, certification footprints, and strategic moves collectively influence pricing norms, technology adoption curves, and procurement standards across the industry.
Kobelt Manufacturing, based in Canada, manufactures complete hydraulic and electronic marine steering systems for vessels of all sizes, encompassing manual hydraulic, power-assisted, and hybrid configurations. Its portfolio is distinguished by certifications from leading classification societies, positioning it as a trusted supplier for operators requiring verified compliance and long-term service support. Jefa Steering, headquartered in Norway, provides professional shipbuilders with a full range of best-in-class mechanical steering systems, pedestals, and autopilot drive units tailored for yachts and commercial vessels. Its reputation rests on precision engineering and seamless integration with high-end vessel architectures. Dometic Group, headquartered in Sweden, offers electric and hydraulic marine steering systems, including the Optimus series for inboard vessels and SeaStar and Seastar hydraulic kits for outboards and sterndrives. The company has recently accelerated its electrification roadmap, reflecting broader industry shifts toward reduced mechanical complexity and improved operator ergonomics.
Uflex USA, operating from the United States, manufactures marine steering wheels, helms, and complete control systems for pleasure boats and commercial applications, offering both hydraulic and electronic options. Its catalog alignment with ISO 10592 standards for hydraulic steering systems underscores a commitment to interoperability and regulatory conformity. Hypro Marine, based in the United Kingdom, produces marine hydraulic steering cylinders and complete systems for high-performance vessels, supported by on-site cylinder build and test services that reinforce quality assurance and customization capability. Its use of stainless steel piston rods and heavy-duty components exemplifies the material standards that high-stress marine applications demand.
Kawasaki Heavy Industries, headquartered in Japan, supplies its unified-edition E-series steering gear for commercial and naval vessels. The product line is optimized for labor savings and IoT integration, reflecting a strategic emphasis on reducing manual intervention during installation and maintenance while enabling data-driven monitoring of steering performance. Damen Marine Components, based in the Netherlands, integrates steering systems into broader marine equipment solutions for commercial vessels, supporting full hydraulic and electronic steering architectures within a systems-integration mindset. Wills Ridley Ltd, also based in the United Kingdom, manufactures marine steering gear for commercial and industrial applications, including hydraulic and electro-hydraulic systems that cater to demanding operational profiles.
Jastram Engineering Ltd, headquartered in Canada, produces ship steering systems and components for marine vessels, contributing to the North American supply base with specialized engineering capabilities. Deyuan Marine, based in China, supplies a wide range of marine steering gears including hydraulic, electric-hydraulic, and manual types for boats and offshore vessels, expanding affordability and availability for price-sensitive segments. Glydus India, operating from India, offers a complete range of marine steering systems including its Smart Steering line featuring patent-pending technology, and has actively showcased its portfolio at international trade platforms, signaling ambition to expand its global footprint.
Together, these companies illustrate the diversity of strategic approaches within a single market: some compete on class certifications and integration depth, others on material durability and service intensity, and others on technological differentiation and cost positioning. Our report evaluates how these differing value propositions translate into share dynamics, pricing power, and customer retention, providing a competitive intelligence foundation for supplier selection, benchmarking, and partnership strategy.
Industry Dynamics: Regulation, Standards, Materials, and Labor Economics
Market evolution in marine steering systems does not occur in a vacuum. Regulatory mandates, technical standards, material specifications, and labor economics collectively shape the cost structure, compliance burden, and innovation incentives that define competitive success. Our report integrates these dynamics into a cohesive analytical framework, enabling readers to anticipate how shifts in one dimension will reverberate across product design, supplier selection, and procurement timing.
Regulatory expectations continue to raise the bar for hydraulic steering gear arrangements. U.S. Coast Guard requirements under 46 CFR Part 58, Subpart 58.25, mandate that hydraulic steering gear on ships include arrangements for steadying the rudder and maintaining cleanliness in piping. These requirements influence system architecture, filtration design, and maintenance protocols, creating both compliance costs and opportunities for manufacturers that engineer solutions aligned with regulatory intent from the outset. In Canada, the Marine Machinery Regulations require pressure-retaining components in hydraulic power-operated steering gears to maintain tensile strength not exceeding 650 MPa with elongation of at least 12 percent. Such specifications directly affect material selection, manufacturing processes, and quality control regimes, reinforcing the importance of certified material supply chains and traceable testing documentation.
Technical standards further codify expectations for performance and interoperability. ISO 10592 governs hydraulic steering systems for marine applications, and compliance with this standard is a significant commercial advantage for suppliers seeking to demonstrate reliability and ease of integration. Manufacturers that align product development with recognized standards reduce buyer risk, simplify classification society review, and improve cross-vendor compatibility—factors that increasingly matter as vessel systems become more integrated and lifecycle support more complex.
Material specifications remain a critical differentiator in high-stress applications. Stainless steel piston rods and heavy-duty components are standard in marine hydraulic steering cylinders produced by companies such as Hypro Marine and Deyuan Marine, reflecting the corrosive, high-load, and variable-temperature environments in which steering systems must operate reliably. These material choices carry cost implications but also deliver durability, reduced maintenance frequency, and longer service intervals—attributes that can shift the total cost of ownership calculus in favor of premium solutions for demanding use cases.
Labor economics are also reshaping procurement logic. The Kawasaki Unified-Edition E-series steering gear, for example, is engineered to optimize equipment configuration and reduce manual labor requirements in marine operations. As skilled labor availability fluctuates and installation and maintenance costs rise, steering systems that simplify assembly, reduce alignment precision requirements, and support remote diagnostics gain strategic appeal. This trend aligns with broader maritime digitization efforts, where operational efficiency, predictive maintenance, and reduced onboard labor dependency are becoming central value drivers.
Recent Developments Signaling the Direction of Travel
Recent activity among leading manufacturers confirms that innovation, certification, and market visibility are converging as strategic priorities. Dometic Group expanded its electrification portfolio by launching the Optimus 3000 Series Electric Steering System for inboard powered boats up to 40 feet, directly addressing demand for simplified, high-performance steering solutions in the recreational and light commercial segments. The same company garnered industry recognition at IBEX 2025, winning two EPIC Awards for marine steering innovations and an NMMA Innovation Award for related marine controls exhibit presence, reinforcing its positioning at the intersection of product design and functional advancement.
At Metstrade 2025, multiple manufacturers used the global platform to demonstrate product breadth and technological ambition. Glydus India showcased its complete range of marine steering systems, including Smart Steering patent-pending models, signaling an intent to compete on intelligent control features and differentiated engineering. Hypro Marine exhibited its marine steering cylinders and systems, reinforcing its focus on high-performance applications and on-site build-and-test capabilities. These trade-show movements are not merely promotional; they reflect supplier strategies to secure early visibility with shipbuilders, refit yards, and procurement teams, shaping demand before formal specification cycles begin.
The cumulative effect of these developments is a market in which product differentiation is increasingly tied to electrification readiness, compliance architecture, material robustness, and service integration. Suppliers that can articulate clear total-cost advantages, demonstrate class and standard conformity, and support operators with lifecycle service models are best positioned to capture share as fleet renewal and refit activity accelerate.
Why This Study Matters for 2026 Strategic Decisions
Enterprise decisions made in 2026 will determine competitive positioning for the remainder of the decade. Whether an organization is evaluating a new product introduction, selecting a multi-year supplier partner, planning a regional expansion, assessing merger or acquisition targets, or preparing for regulatory and standard shifts, the quality of market intelligence directly influences outcome quality. Our Marine Steering System Market study is designed to provide that intelligence with practical precision.
The report delivers detailed segmentation analysis that quantifies how revenue moves across technology categories and vessel types, while maintaining the analytical discipline necessary to avoid misleading averages. It examines regional demand patterns with attention to shipbuilding cycles, classification expectations, and procurement behaviors. It profiles the competitive positions of the principal manufacturers, highlighting product coverage, certification strength, service models, and recent strategic moves. It integrates regulatory and standard developments into a forward-looking assessment of compliance costs and innovation incentives. And it synthesizes material and labor considerations into actionable guidance on total cost of ownership, lifecycle support, and installation efficiency.
Importantly, the study is structured to support decision-making at multiple levels. Executive leadership can use the macroeconomic trajectory, CAGR context, and concentration analysis to frame investment and diversification strategies. Product and engineering teams can leverage technology-by-vessel and region-by-segment insights to prioritize design trade-offs and certification pathways. Commercial and procurement teams can use competitive profiles and recent development tracking to benchmark suppliers, negotiate terms, and time sourcing decisions. Regulatory and compliance professionals can use the standards and regulation integration to anticipate documentation requirements, testing protocols, and class review timelines.
What the Full Report Delivers
Readers who access the complete study will gain a comprehensive working knowledge of the marine steering system market through 2032, supported by structured analysis across every major dimension of strategic relevance. The report covers historical revenue tracking from 2020 through 2025, the 2026 baseline, and a full forecast sequence extending to 2032, enabling trend validation and scenario comparison. It breaks down market composition by region, by steering type, and by vessel category, providing the segment-level visibility needed to model revenue opportunities and assess competitive exposure. It includes detailed profiles of the ten core companies that shape the competitive landscape, with attention to headquarters location, product scope, certification positioning, and strategic trajectory.
The study also integrates recent developments from late 2025, including product launches, innovation awards, and trade-show participation, to illustrate how suppliers are actively shaping market expectations and securing early design-in opportunities. Regulatory and standard references are woven into the dynamics section, ensuring that compliance considerations are presented as commercial factors rather than abstract obligations. Material specifications and labor-optimization themes are incorporated into the analysis of cost structure, durability expectations, and operational efficiency, helping readers evaluate total value rather than sticker price alone.
All financial figures are presented in USD millions, with a base year of 2025 and a forecast horizon spanning 2026 through 2032. The compound annual growth rate of 4.94 percent frames the overall growth environment, while segment and regional breakdowns provide the granularity required for practical planning. Concentration metrics for the top three and top five firms are included to support competitive intensity assessment and partnership strategy development.
Moving Forward with Confidence
The marine steering system market is not characterized by sudden disruption but by steady architectural shifts, regulatory refinement, and incremental technology adoption that cumulatively reshape competitive advantage. Organizations that approach 2026 with a clear understanding of these forces will be better equipped to allocate resources, select suppliers, design products, and time market entry with discipline. Our study is built to deliver that clarity, combining macroeconomic context with operational-level insight across technologies, vessel segments, regions, and competitors.
For decision-makers seeking to convert market intelligence into executable strategy, the full report provides the depth, structure, and forward-looking analysis necessary to act decisively. We invite you to access the complete study and equip your team with the comprehensive marine steering system intelligence needed to navigate the coming years with precision and confidence.
For detailed analysis of this topic, please visit the official page: Marine Steering System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Parameter Patient Monitoring Market to Hit $17 Billion by 2032 at 7.9% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence in Multi-Parameter Patient Monitoring: Navigating the 2026 Landscape
Executive Overview
The global healthcare technology sector stands at a critical inflection point, driven by aging demographics, the expansion of remote care models, and an uncompromising focus on clinical accuracy. Within this broader ecosystem, multi-parameter patient monitoring equipment has emerged as a foundational infrastructure component, bridging acute hospital settings with decentralized care environments. As we transition into 2026, market trajectories indicate a sustained upward curve, reflecting both the maturation of established clinical workflows and the aggressive integration of data analytics into bedside and wearable devices.
Private Equity Services Market
For executives, procurement leaders, and investment strategists, the margin for error in capital allocation has narrowed. Understanding where value is created, how competitive boundaries are shifting, and which regulatory or reimbursement developments will reshape purchasing behavior requires more than headline figures. It demands a structured, empirically grounded examination of the forces defining the next seven years. This article outlines the strategic rationale behind our latest comprehensive research release and demonstrates how decision-makers can leverage granular intelligence to de-risk product positioning, partnership evaluation, and market entry planning.
Athermal Lens Market
Macro Trajectory and Structural Momentum
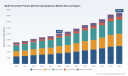
Drawing on a historical baseline spanning 2020 through our base year of 2025, the multi-parameter patient monitoring sector has demonstrated consistent expansion, reinforced by recurring clinical demand and incremental technology substitution. Our modeled projections extend through 2032, capturing a compound annual growth rate of 7.9 percent across the forecast horizon. The revenue trajectory reflects an industry that has moved beyond early adoption cycles into a phase of standardized deployment, where monitoring capability is increasingly treated as a prerequisite rather than a discretionary upgrade.
Worldwide Pet Pup Food Market
The historical sequence illustrates how procurement rhythms, clinical volume recovery, and technology refresh cycles have compounded into a measurable upward arc. As we step into the first forecast year, the baseline revenue level establishes a clear reference point from which subsequent growth vectors radiate. Over the full forecast window, the market is projected to reach a substantially higher valuation, underscoring the durability of demand drivers. Importantly, this progression is not uniform across every channel or customer segment. The cumulative growth masks divergent pacing between high-acuity environments, intermediate care units, and lower-intensity monitoring contexts, as well as varying adoption velocities across geographies.
Strategic planners should treat the headline CAGR and the absolute revenue path as useful orientation tools, but not as operational playbooks. The real competitive advantage lies in understanding which sub-channels are absorbing capacity faster, where pricing elasticity is shifting, and how procurement consolidation is altering the supplier landscape. These dynamics determine whether a firm captures premium positioning, competes on volume, or must recalibrate its value proposition to remain relevant in specific care pathways.
What This Research Delivers
Our latest Multi-Parameter Patient Monitoring Equipment Market study is built for practitioners who require actionable intelligence rather than descriptive summaries. The report is structured to support decisions across product strategy, commercial execution, partnership evaluation, and regulatory preparedness. Each section is anchored in verifiable market data and supplemented with qualitative context drawn from recent corporate activity, policy shifts, and clinical deployment patterns.
Core Analytical Components
- Segmentation architecture covering product acuity tiers, clinical application pathways, and regional deployment patterns, with explicit attention to volume distribution and relative share positioning.
- Revenue baselines and forward projections that distinguish between mature segments and faster-growing pockets of adoption, enabling scenario planning for capacity investment and inventory strategy.
- Competitive profiling of incumbent and emerging participants, with focus on product line breadth, technological differentiation, integration capabilities, and geographic reach.
- Regulatory and reimbursement mapping that tracks clearance pathways, quality management requirements, and payment code adjustments affecting purchasing behavior and service design.
- Strategic development tracking, including recent product launches, partnership expansions, and co-development initiatives that signal how incumbents are reinforcing their market positions.
Operational Utility for Decision-Makers
The research is designed to translate market structure into executable strategy. A product leadership team can use the segmentation and revenue distribution to evaluate whether to prioritize high-acuity innovation, expand into mid-tier ward deployments, or build complementary remote monitoring configurations. A commercial director can map concentration patterns and competitor footprints to identify underserved geographies or care settings where distribution partnerships may yield faster penetration. A regulatory affairs function can align internal quality systems with evolving standards while anticipating how reimbursement adjustments influence the business case for remote physiologic monitoring.
Throughout the report, we deliberately isolate the analytical layers that matter for execution while withholding the precise numerical splits and micro-level breakdowns that form the backbone of full market intelligence. Those granular figures, including exact regional shares, product-level revenue distributions, and application-specific valuations, are embedded in the complete dataset and accessible through our source portal. The purpose of this framing is simple: provide enough structural clarity to establish analytical credibility, while preserving the exact data that clients pay to access and apply in proprietary planning cycles.
Competitive Architecture: The Incumbent Core
The market structure is characterized by a high degree of concentration, with a limited group of global manufacturers commanding the majority of revenue. This concentration is not accidental; it reflects the capital intensity of clinical-grade monitoring, the importance of integration with hospital information environments, and the trust requirements associated with continuous vital signs measurement. At the same time, targeted innovation and partnership expansion are creating differentiation vectors that allow select players to extend their reach into adjacent care settings and digital service models.
Profiles of Strategic Positioning
Royal Philips, headquartered in Amsterdam, continues to anchor its offering through IntelliVue bedside monitors and central monitoring architectures that consolidate multi-parameter vital signs into unified data streams. Its emphasis on analytics-enabled observation aligns with the broader industry shift from raw measurement toward interpreted clinical signals. GE HealthCare, based in Chicago, maintains a strong presence through its Infinity and Carestation families and the Portrait VSM solution, leveraging the FlexAcuity platform to adapt monitoring configurations across critical care and ambulatory environments. Medtronic, operating from Dublin, brings a broad monitoring portfolio that spans capnography, pulse oximetry, and vital signs integration, positioning itself within both in-hospital and remote care architectures.
Nihon Kohden, headquartered in Tokyo, reinforces its standing with Life Scope series monitors designed for ICU and general ward environments, emphasizing cardiac, respiratory, and hemodynamic parameter coverage. Shenzhen Mindray, based in Shenzhen, competes with the BeneVision series, offering high-acuity multi-parameter capability and configurations oriented toward wireless and cable-lite deployment models. Schiller AG, located in Baar, focuses on clinical accuracy and data integration across full multi-parameter vital signs monitoring. SternMed, headquartered in Hamburg, supplies critical care monitors that cover ECG, respiration, temperature, SpO2, and NIBP within specialized care workflows.
Hill-Rom, also based in Chicago, extends its presence through the Connex Vital Signs Monitor and integrated care systems that combine ECG, SpO2, NIBP, temperature, and respiration tracking with wider patient care workflows. Masimo, headquartered in Irvine, differentiates through wearable and bedside multi-parameter solutions, including the Radius VSM platform that supports pulse oximetry, NIBP, temperature, ECG, and respiration in more mobile configurations. Drägerwerk, operating from Lübeck, contributes Infinity patient monitoring systems tailored to anesthesia and critical care integration, reinforcing the linkage between monitoring and therapeutic delivery environments.
These players illustrate a market where technical breadth, integration depth, and geographic reach remain essential, but where differentiation is increasingly defined by how well monitoring data flows into clinical decision support, remote service delivery, and workflow efficiency. The competitive story is no longer purely about parameter count; it is about data usability, reliability under varying acuity conditions, and the ability to pair hardware with software and service ecosystems.
Recent Developments Reshaping the Field
The intensity of recent corporate activity signals that incumbents are not resting on installed-base advantages. In early 2026, Nihon Kohden introduced the Life Scope E7 multi-parameter patient monitoring system for ICU applications, integrating cardiac, respiratory, and hemodynamic measurement into a unified platform. This launch reflects a continued push toward consolidating parameter sets in high-acuity environments while tightening the link between bedside monitoring and clinical workflow integration.
A more expansive signal came from the strategic partnership expansion between Philips and Masimo. The collaboration broadens the integration of SET pulse oximetry and Radius PPG wearables into Philips multi-parameter bedside monitors, with co-development of AI-based technologies intended to enhance monitoring intelligence at the point of care. This type of partnership matters because it bridges established bedside architectures with advanced sensor and wearable capabilities, reinforcing the industry direction toward hybrid monitoring models that span fixed and mobile use cases.
These developments are not isolated events. They sit within a broader rhythm of product refreshes, integration alliances, and software-led enhancement that is reshaping how suppliers compete. For buyers and competitors alike, the practical implication is that vendor evaluation can no longer rely solely on parameter specifications. The evaluation must also include integration roadmaps, interoperability commitments, and the pace at which AI or analytics features are being embedded into mainstream monitoring platforms.
Regulatory and Reimbursement Dynamics
Market momentum is partly endogenous to technology and partly shaped by the policy environment. In the regulatory sphere, the February 2026 application of the FDA QMSR standard to medical device quality management systems, including multi-parameter patient monitors, introduces a compliance layer that affects manufacturers across the value chain. Firms that can align quality systems efficiently may reduce friction in clearance and market maintenance, while those with slower adaptation cycles could face operational drag.
At the same time, reimbursement architecture continues to evolve in ways that influence the economics of remote and extended monitoring. The CMS finalization of 2026 remote physiologic monitoring CPT codes, including code 99445 for monitoring with two to fifteen days of data transmission per thirty-day period at an approximate reimbursement rate of $47, provides a clearer payment pathway for certain decentralized monitoring services. This adjustment does not single-handedly transform the market, but it strengthens the economic logic for configurations that extend monitoring beyond the bedside and supports service models that depend on periodic data transmission.
On the clearance side, FDA 510(k) authorization of multi-parameter monitors from Shenzhen Comen Medical Instruments Co., Ltd., covering the N10, N12, and N15 series in December 2025, illustrates how additional entrants are progressing through regulatory gates and expanding the pool of commercially available equipment. Each clearance event incrementally broadens competitive options in specific segments and geographies, particularly where price sensitivity and service responsiveness matter.
Industry projections from external sector analysis also place the broader multi-parameter patient monitoring market in the vicinity of USD 12.30 billion in 2025, moving toward approximately USD 13.2 billion in 2026. While such external estimates vary in scope and methodology, they reinforce the general impression of a market with strong near-term continuity and limited signs of demand contraction. The alignment between internal modeling and external commentary increases confidence that the observed growth path is durable, even as the mix of contributors shifts over time.
Interpreting Movement, Avoiding False Precision
A recurring mistake in strategic planning is treating aggregate growth as a substitute for segment-level understanding. In this market, the headline progression from the base year into the late 2020s and early 2030s is meaningful primarily as an indicator of overall market health. It does not tell a product team whether to emphasize high-acuity bedside monitoring, mid-tier ward solutions, or lower-acuity configurations. It does not specify whether the greatest incremental opportunity lies in cardiology workflows, respiratory care pathways, neurological observation, fetal and neonatal applications, or other clinical domains. It also does not reveal how revenue is apportioned across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
The concentration profile of the market further complicates simple growth interpretations. With a small group of manufacturers commanding the majority of revenue, the market is not a blank canvas for undifferentiated entry. Instead, it is a structured battlefield where share gains often depend on integration strength, service coverage, clinical credibility, and the ability to align with procurement and clinical preferences in specific care environments. The presence of high concentration also means that partnership strategy, channel design, and technology collaboration can be as important as product specifications in shaping commercial outcomes.
For decision-makers, this means the real value of detailed market research lies in its ability to convert macro direction into segment-specific logic. Which acuity tiers are absorbing capacity fastest? Where are application-specific workflows creating buying urgency? Which regions are showing stronger deployment momentum based on clinical infrastructure and procurement patterns? How are reimbursement adjustments altering the relative attractiveness of remote versus in-hospital monitoring configurations? These are the questions that determine whether strategy is grounded or speculative. The full study isolates these answers and presents them with the precision required for internal planning, while the public-facing narrative intentionally keeps the exact percentage splits and micro-level values reserved for clients.
Strategic Implications for 2026 Decision-Makers
The 2026 landscape rewards organizations that combine technical credibility with commercial responsiveness. Three strategic priorities emerge from the current market configuration.
First, monitoring investment is increasingly linked to workflow integration and data utility. Devices that deliver reliable multi-parameter measurement remain essential, but the relative value of a solution now depends on how effectively its outputs connect to central stations, electronic health records, analytics layers, and remote care workflows. Product and service strategies should be evaluated not only on parameter coverage, but also on interoperability, configuration flexibility, and the speed with which new capabilities such as AI-supported interpretation can be deployed in clinical settings.
Second, the partnership and co-development trend is reshaping competitive boundaries. The recent expansion between Philips and Masimo illustrates how incumbents are incorporating advanced sensing and wearable technologies into established bedside platforms. This pattern suggests that future differentiation may depend as much on ecosystem design and partnership architecture as on standalone hardware performance. Firms that can access complementary sensor technology, remote monitoring capabilities, or analytics assets through collaboration may accelerate their relevance across both hospital-based and decentralized care environments.
Third, regulatory and reimbursement change is becoming a strategic variable rather than a background assumption. Quality management standards, clearance pathways, and payment code adjustments all influence the cost, speed, and commercial viability of monitoring solutions. Organizations that monitor these changes proactively can align quality systems ahead of enforcement, structure service models to match reimbursement logic, and position their offerings to take advantage of expanded clearance activity that widens competitive options in certain segments.
Closing Perspective
The multi-parameter patient monitoring equipment market is moving with measured but persistent momentum, shaped by clinical demand, technological integration, and an evolving policy environment. The aggregate growth path through the end of the forecast window indicates a sector with durable fundamentals, while the concentration profile and recent corporate activity highlight the importance of strategic precision. For executives navigating product roadmaps, commercial plans, and partnership evaluations, the challenge is no longer whether the market is expanding, but where value is being created and how to position for it with confidence.
This article provides the structural context and analytical framing needed to understand why detailed intelligence matters. To access the full segmentation breakdowns, regional and application-level revenue distributions, competitive share mapping, and the complete dataset underpinning the 7.9 percent CAGR projection and the 2026 to 2032 revenue path, we invite you to explore the complete Multi-Parameter Patient Monitoring Equipment Market research on our source page. The full report is designed to convert market visibility into decision-ready intelligence.
For detailed analysis of this topic, please visit the official page: Multi-Parameter Patient Monitoring Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Processed Cheese Market to Grow at 4.86% CAGR Through 2032: PW Consulting Report
By PW Consulting, 2026-09-07
Navigating the Processed Cheese Market: Strategic Intelligence for 2026 and Beyond
The processed cheese sector stands at a critical inflection point. After a period of contraction that saw the global market value decline from 2020 through 2025, early indicators suggest a measured recovery is taking shape. For executives, procurement leaders, and strategy teams operating in dairy, food manufacturing, and foodservice supply chains, the distinction between noise and signal has never been more important. This introduction outlines the strategic architecture of our latest Processed Cheese Market research report, explains why 2026 represents a pivotal planning year, and highlights the analytical frameworks that will help organizations convert macro trends into executable decisions.
Wireless Industrial Joystick Market
Readers should understand from the outset that this document functions as a strategic preview. It demonstrates the depth of methodology, the scope of coverage, and the competitive intelligence embedded in the full study. Core segmentation figures, regional revenue splits, and application-level breakdowns are intentionally held back so that operational teams can evaluate the complete dataset before committing capital or adjusting supply contracts. The objective is straightforward: provide enough analytical transparency to establish credibility, while preserving the granular intelligence that drives board-level resource allocation.
Worldwide New Energy Commercial Vehicle Market
The Macro Trajectory: Why 2026 Matters
The processed cheese market has experienced a sustained contraction over the past half-decade. Historical valuations show a peak near the start of the tracking window, followed by a progressive drawdown through 2025. That trajectory reflects a combination of input cost inflation, shifting consumer preferences, supply chain recalibration, and regulatory friction across key trade corridors. However, the forward curve tells a different story.
Outdoor Griddles Market
Our forecasting model projects a reversal beginning in 2026, with the market moving from a subdued baseline into a steady expansion phase that extends through the end of the decade. The compound annual growth rate calculated for the forecast period stands at 4.86 percent, a figure that may appear moderate on the surface but carries meaningful implications when layered against the post-contraction starting point. For planning purposes, the growth rate is not the only metric that matters. The absolute revenue recovery path, the timing of inflection points across regions, and the interaction between price dynamics and volume recovery are where strategic value is actually created.
Executive teams should treat 2026 as a re-baselining year. Organizations that continue to operate against pre-2020 assumptions risk misreading demand elasticity, overcommitting to legacy SKU structures, or mispricing input exposure. Conversely, teams that rebuild their plans around the emerging growth curve can position procurement, production capacity, and distribution agreements ahead of competitors who wait for consensus to solidify.
What the Report Delivers: Analytical Scope and Operational Utility
The full study is designed as a decision-support system rather than a static market summary. It integrates historical reconstruction, forward-looking modeling, competitive positioning analysis, and regulatory mapping into a single planning framework. Below is a structured overview of the report's core components and how each translates into operational value.
- Historical Baseline Reconstruction: The report traces market behavior across the 2020 to 2025 window, identifying the structural and cyclical forces that shaped the contraction phase. This historical grounding allows readers to separate temporary shocks from durable shifts in consumption and sourcing patterns.
- Forecast Architecture: Projections span the 2026 to 2032 period and are built around a growth rate of 4.86 percent across the full forecast horizon. The model accounts for volume-price interaction, regional divergence, and product-form momentum, giving strategy teams a multi-variable view rather than a single-line estimate.
- Segmentation Frameworks: The analysis disaggregates the market across product types, application channels, and geographic regions. These lenses are essential for identifying where growth concentrates, which formats face headwinds, and how end-use demand differs between foodservice operators, retail channels, and industrial processors. The full segmentation matrix is reserved for the complete report so that commercial teams can validate numbers before acting on them.
- Competitive Positioning and Concentration Analysis: The study maps the market's structural concentration, including the share held by the top three and top five players, and examines how that concentration shapes pricing power, capacity utilization, and partnership dynamics. Company-level profiles provide context on manufacturing footprint, brand portfolios, and geographic reach.
- Regulatory and Trade Dynamics: A dedicated analysis tracks tariff actions, classification requirements, certification obligations, and recall events that influence cross-border movement, compliance cost, and risk exposure. This section is intended for teams managing import/export exposure, supplier diversification, and quality assurance protocols.
- Input Cost and Supply-Side Monitoring: The report incorporates recent pricing signals for key dairy inputs, including dry whey, and frames them within broader supply-demand volatility. This provides procurement and finance teams with context for margin modeling, contract structuring, and hedging decisions.
Each section is built to be referenced independently or synthesized into a broader strategic narrative. Whether the reader is evaluating a new product launch, renegotiating a supplier agreement, or reassessing regional distribution strategy, the report is organized to support rapid extraction of relevant insights without requiring the user to reconstruct the analysis from scratch.
Competitive Landscape: Who Shapes the Market and How
The processed cheese market is characterized by a concentrated core of established manufacturers alongside a broader field of regional and specialty players. Concentration matters because it influences how quickly pricing signals propagate, how capacity shifts translate into supply availability, and how aggressively incumbents can defend share during periods of volatility. The report examines this structure in detail, including the interplay between global scale players and regionally anchored producers.
At the center of the competitive field are large diversified food and dairy companies with substantial branded portfolios, extensive distribution networks, and the ability to move across slices, blocks, spreads, and related formats. Kraft Heinz Company, headquartered in Chicago, Illinois, remains a primary producer across slices, blocks, and spreads under well-known brand assets. Dairy Farmers of America, based in Roseville, Minnesota, operates as a major U.S. manufacturer and marketer of processed American cheese and cheese spreads, with influence that extends through cooperative sourcing and broad channel coverage.
European and international players add further depth to the landscape. The Bel Group, headquartered in Liège, Belgium, is a leading producer of processed cheese spreads and slices with strong European and international distribution. Arla Foods, based in Viby J, Denmark, produces processed cheese under its own and Puck brands, with a focus on cream and processed segments. Fonterra Co-operative Group, headquartered in Auckland, New Zealand, supplies both ingredients and finished processed cheese products globally, giving it a dual role in the value chain. Lactalis Group, from Rennes, France, produces processed cheese products and ingredients that support processed cheese manufacturing across multiple markets. Savencia Fromage and Dairy, based in Paris, specializes in processed cheese and dairy-based spreads for industrial and retail use, while Sargento Foods Inc., in Plymouth, Wisconsin, manufactures processed cheese slices, shreds, and snacks with a strong presence in convenience-oriented formats.
The report uses these company profiles not as static bios but as strategic reference points. Each profile is evaluated in the context of manufacturing scale, product-form coverage, regional strength, and likely response patterns to regulatory or input-cost shocks. The concentration data included in the study shows that the top three players hold a combined share of approximately 40 percent, while the top five reach roughly 55 percent. That level of concentration suggests a market where incumbents have meaningful influence over supply conditions and where new entrants or smaller specialists must navigate carefully around distribution bottlenecks and brand loyalty.
Recent industry events also inform competitive risk assessment. In late 2025 and early 2026, The Ambriola Company experienced a recall of select grated pecorino romano and related cheese products distributed nationwide due to the presence of Listeria monocytogenes, followed by an FDA upgrade of the recall to the highest risk category after routine testing confirmed the pathogen. While this event centers on a specific product category rather than processed cheese directly, it illustrates how quality and safety incidents can rapidly reshape buyer confidence, retailer compliance requirements, and supplier qualification standards across the broader dairy and cheese sector. The report integrates such developments into its risk and compliance analysis so that procurement and quality teams can anticipate downstream effects on vendor audits, testing protocols, and contract safeguards.
Market Dynamics: Regulation, Trade Friction, and Input Volatility
No strategy for processed cheese is complete without a clear view of the regulatory and trade environment. The current landscape includes a series of policy actions and classification requirements that affect cost structures, route-to-market decisions, and cross-border sourcing flexibility. These dynamics are not abstract; they influence landed cost, inventory positioning, and the relative attractiveness of domestic versus imported supply.
Tariff actions have introduced new friction into key trade lanes. Cheese and curd, including processed cheese not grated or powdered, became subject to a 25 percent tariff on U.S. imports into Canada effective 4 March 2025, according to the Department of Finance Canada. In parallel, processed cheese not grated or powdered faces a 24 percent import tariff into the UK as of 29 August 2025, as documented by the Agriculture and Horticulture Development Board. For companies with North American or European distribution interests, these duties alter the economics of cross-border supply and may accelerate shifts toward local manufacturing, supplier substitution, or formulation adjustments designed to maintain margin under higher landed-cost conditions.
Classification and compliance requirements add another layer of operational complexity. Processed cheese is assigned HS code 040630 and is subject to mandatory 12-digit HS classification for certain imports effective 2025, according to FreightAmigo Trade Classification. Precise classification matters because it influences duty assessment, customs clearance speed, and documentation risk. Errors or ambiguity in coding can create delays, penalties, or unexpected cost exposure, particularly for companies managing multiple SKUs across different markets.
In the United States, FDA certification remains required for all dairy processing facilities producing processed cheese, as noted in the USDA Foreign Agricultural Service Dairy Industry Profile for 2025. This baseline requirement reinforces the importance of facility-level compliance, traceability, and ongoing audit readiness. For buyers and suppliers alike, certification status is not merely a regulatory checkbox; it is a commercial prerequisite that affects sourcing eligibility, retailer acceptance, and risk allocation in supply agreements.
Input cost volatility further shapes the operating environment. Recent reporting from the USDA Agricultural Marketing Service for May 2026 indicates that dry whey prices for the central U.S. averaged 0.6775 USD per pound, with volatility driven by supply and demand factors. Because dairy inputs influence formulation economics and co-product value, fluctuations in whey pricing can ripple through margin calculations, blend decisions, and supplier negotiations. The report incorporates these signals into its cost-structure analysis so that finance and procurement teams can test scenarios rather than rely on static assumptions.
Where Growth Is Likely to Concentrate
While specific segmentation figures are reserved for the full report, the strategic direction is clear enough to inform early planning. The processed cheese market is not homogeneous, and the recovery path will differ meaningfully across product forms, end-use channels, and regions. Organizations that assume a uniform rebound are likely to misallocate resources.
Product-form dynamics matter because slices, blocks, spreads, and cubes serve different usage occasions, shelf requirements, and price sensitivities. Some formats benefit from convenience-driven consumption and foodservice integration, while others are more exposed to retail promotion cycles or industrial ingredient demand. Understanding which forms carry stronger momentum, and why, helps R&D, packaging, and production planning teams prioritize capacity and innovation investment where return potential is highest.
Application channels also diverge in their growth behavior. Foodservice operators, household and retail consumers, and food processing industry buyers each respond differently to price changes, menu trends, promotional activity, and supply reliability. Foodservice demand, for example, is often tied to menu engineering, labor constraints, and operator margin pressure, while retail demand may be more influenced by branding, shelf visibility, and household purchasing patterns. Industrial processors, meanwhile, tend to focus on consistency, specification stability, and total delivered cost. These differences make channel-level analysis essential for sales planning, inventory positioning, and customer targeting.
Regional variation adds a third dimension. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct combinations of demand maturity, distribution infrastructure, regulatory context, and competitive intensity. The full report provides the regional breakdown needed to assess where growth is most attainable, where competition is most entrenched, and where trade or compliance factors may constrain expansion. Until those figures are reviewed in detail, teams should avoid overgeneralizing regional opportunity based on macro totals alone.
Strategic Implications for 2026 Decision-Making
The practical value of this research lies in its ability to convert market structure into action. For executive and operational teams, the report supports several categories of decision-making that are especially relevant in 2026.
- Capital and Capacity Planning: The forecast path provides a basis for evaluating whether to expand, consolidate, or reconfigure production and distribution assets. Teams can test whether demand growth justifies incremental investment or whether efficiency and mix optimization offer better risk-adjusted returns.
- Procurement and Supplier Strategy: With concentration, input volatility, and regulatory friction all in play, sourcing decisions should be stress-tested against multiple scenarios. The report's supplier and competitive context helps organizations assess dependency risk, negotiate from a more informed position, and identify diversification opportunities.
- Pricing and Margin Management: Because tariffs, classification requirements, and input pricing can shift cost structures quickly, pricing strategies need to be flexible and regionally aware. The study gives finance teams the context needed to separate sustainable price moves from reactive adjustments.
- Portfolio and SKU Rationalization: Not all formats and channels will recover at the same pace. Segmentation analysis supports more disciplined portfolio decisions, helping companies retire underperformers, strengthen high-momentum lines, and avoid stretching resources across low-return SKUs.
- Risk and Compliance Readiness: Regulatory developments and recall events underscore the importance of audit readiness, documentation discipline, and supplier qualification. The compliance section helps teams anticipate where scrutiny is likely to intensify and where process gaps could become commercial liabilities.
In each case, the benefit comes from having a coherent evidence base rather than fragmented data points. Strategy teams can use the report to align commercial, supply chain, finance, and quality functions around a shared view of the market, reducing the risk of contradictory assumptions and siloed planning.
How to Use This Research in Practice
The report is built to support both high-level strategic planning and tactical execution. To extract maximum value, organizations should approach it as a working document rather than a one-time read. The most effective use patterns include scenario testing, cross-functional alignment sessions, and periodic refresh cycles tied to major market or regulatory changes.
For scenario testing, teams can combine the forecast trajectory with input cost signals, tariff exposure, and competitive behavior to model best-case, base-case, and stress-case outcomes. This is particularly useful for budgeting, contract negotiation, and inventory strategy. For cross-functional alignment, the segmentation and competitive sections provide a common reference point that sales, supply chain, marketing, and finance can use to reconcile priorities and reduce internal disagreement about where to focus. For ongoing monitoring, the regulatory and input-cost components help organizations stay alert to changes that could alter the planning baseline before the next formal review cycle.
Leaders should also resist the temptation to treat any single metric in isolation. The market's behavior is best understood as the interaction of recovery timing, segmentation momentum, concentration dynamics, and external shocks. The report's structure is intended to make those interactions visible, so that decisions reflect the full system rather than one component of it.
Conclusion: From Market Awareness to Strategic Advantage
The processed cheese market is entering a phase where disciplined analysis will separate resilient operators from reactive ones. The contraction of the past few years has cleared away assumptions that no longer hold, while the emerging growth path through 2032 creates new opportunities for companies that can position themselves ahead of consensus. A compound annual growth rate of 4.86 percent across the forecast period, layered onto the post-contraction baseline, offers more than a headline number; it defines the terrain on which competitive battles will be fought.
This preview has outlined the report's strategic intent, its analytical scope, and the market forces that make 2026 a decisive planning year. It has also deliberately withheld the detailed segmentation figures, regional splits, and application-level breakdowns that belong in the full study. Those specifics are where the real planning precision lives, and they should be evaluated by the teams who will act on them before any commitments are made.
For organizations ready to move from broad awareness to decision-grade intelligence, the complete Processed Cheese Market report provides the segmented data, competitive profiles, regulatory mapping, and scenario-ready forecasts needed to support confident action. The information is structured to be used, not merely reviewed, and it is designed to integrate directly into procurement, commercial, and strategic planning workflows.
The market is no longer contracting, but the recovery is not uniform, and the external environment remains fluid. Companies that equip themselves with detailed, well-structured intelligence will be better positioned to price intelligently, source resiliently, allocate capital wisely, and respond to regulatory or supply shocks with less disruption. The full report is the next step for teams that want to convert this landscape into a deliberate strategy rather than a reactive posture.
For detailed analysis of this topic, please visit the official page: Processed Cheese Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts High Purity Quartz Sand Market to Hit $2.86 Billion by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the High Purity Quartz Sand Market: Navigating Growth and Geopolitical Complexity in 2026
As the global technology landscape accelerates toward greater sophistication, the foundational materials underpinning these advancements become critical strategic assets. High Purity Quartz Sand (HPQ) stands at the forefront of this material revolution, serving as an indispensable input for industries ranging from semiconductor fabrication to renewable energy. PW Consulting is pleased to introduce our latest comprehensive market research study, designed to equip stakeholders with the actionable intelligence required to navigate the complexities of the HPQ market through 2032. This report is not merely a collection of statistics; it is a strategic roadmap for optimizing supply chains, identifying investment opportunities, and mitigating risks in a sector characterized by high concentration and technological specificity.
Food Grade Cellulose Filter Aid Market
The Macro Economic Trajectory: Resilience Amidst Disruption
The global demand for high purity quartz sand has demonstrated remarkable resilience and steady expansion over the past half-decade. Our analysis indicates that the total market revenue, denominated in USD Millions, has grown consistently from 2020 through 2025. This upward trajectory reflects the broader industrialization of high-tech sectors and the relentless push for higher purity standards in manufacturing processes. As we move into the forecast period covering 2026 to 2032, the market is projected to sustain a compound annual growth rate of approximately 6.98 percent.
Ion Exchange Membrane for Iron-Chromium Battery Market
This growth rate underscores a shifting paradigm where demand is not just maintaining pace with economic output but is increasingly driven by technological substitution and capacity expansions in critical industries. The baseline year of 2025 establishes a solid foundation for this forecast, reflecting a market that has already absorbed significant shocks and supply chain reconfigurations. Understanding the magnitude of these figures is essential for corporate planning, yet the true value lies in dissecting the drivers behind these numbers. Our report delves into the quantitative forecasts, providing a granular view of how revenue streams are expected to evolve, without exposing the specific valuation models publicly, thereby reserving the full strategic breakdown for our subscribers.
Worldwide Ward Trolley Market
Segmentation Dynamics: Where Value is Concentrated
The HPQ market is not a monolith; it is a complex ecosystem defined by specific applications that command varying levels of premium pricing and supply security. Our research highlights that the semiconductor wafer manufacturing sector remains the primary consumption engine, accounting for the largest share of revenue generation within the application landscape. This dominance is logical given the stringent purity requirements for silicon ingots and the growing complexity of integrated circuits. Following closely, the Solar PV sector represents a significant and growing demand pillar, driven by global renewable energy targets and the need for efficient photovoltaic modules.
Beyond these primary verticals, specialized applications such as fiber optics and specialty lighting contribute to the market's depth, though they operate at different scales of material throughput. The distinction between these application segments is crucial for investors and supply chain managers. A shortage in semiconductor-grade material does not necessarily equate to a surplus in solar-grade material, creating arbitrage opportunities and specific logistical challenges. Our report provides a detailed breakdown of these application segments, analyzing the consumption patterns and growth drivers for each. However, the specific proportional splits and revenue allocations for each application category are detailed within the full proprietary dataset, accessible only through our complete market intelligence package.
Geographically, the market is distributed across key industrial hubs, with significant activity observed in North America, Europe, and the Asia Pacific region. Each region presents a unique risk-reward profile. North America and Europe host critical mining sources and processing facilities, often linked to legacy supply chains that have recently faced stress tests. Meanwhile, the Asia Pacific region continues to be a dominant center for downstream manufacturing consumption. Latin America and the Middle East and Africa represent emerging avenues with potential for resource development. Our geographic analysis goes beyond simple market sizing; it evaluates the regulatory environments, logistical infrastructure, and political stability influencing supply security in each territory. The precise revenue distribution across these regional boundaries is a key component of our confidential analysis, offered in full to ensure clients can make location-specific investment decisions.
Competitive Landscape: Oligopoly and Strategic Barriers
The high purity quartz sand industry is characterized by a high degree of market concentration. Our data suggests that the top three players control a significant portion of the market share, while the top five entities command an even larger majority of the supply. This concentration creates a landscape where strategic partnerships, long-term offtake agreements, and vertical integration are not just beneficial but often necessary for survival and growth. The barriers to entry are substantial, involving not only the discovery of high-quality quartz deposits but also the proprietary processing technologies required to achieve the necessary purity levels.
Key industry participants include global leaders with established footholds in critical geological regions. Sibelco, headquartered in Brussels, Belgium, stands as a prominent global leader in HPQ production. Their primary offering, IOTA HPQ sand, is mined and processed from Spruce Pine, North Carolina, USA. This location is historically significant due to the unique quality of the quartz found there. Sibelco supplies premium grades for semiconductors, solar PV, and optical fiber applications, making them a linchpin in the global supply chain. Similarly, The Quartz Corp, based in Toronto, Canada, actively produces and supplies high-purity quartz sand from its Spruce Pine, North Carolina operations, alongside sources in Norway. Their focus on crucible-grade and ultra-pure material positions them as a critical supplier for high-tech manufacturing processes that demand exceptional consistency.
In the Asia Pacific region, Jiangsu Pacific Quartz Co., Ltd., located in Lianyungang, China, operates as an active manufacturer offering high-purity quartz sand and related products. Their integrated processing from natural quartz sources allows them to serve solar, electronics, and industrial applications, providing a competitive alternative in the eastern hemisphere. Meanwhile, Russian Quartz LLC, based in Kyshtym, Russia, is an active producer of High Purity Quartz concentrates under the Russian Quartz brand, supplying material for various industrial and high-tech uses from its South Ural facilities, adding another layer of geographic diversification to the supply base.
Emerging players are also reshaping the competitive dynamics. Homerun Resources Inc., headquartered in Vancouver, Canada, is delivering high-purity industrial silica sand and quartz sand products sourced from projects in Brazil and Canada. Recent developments include first-order shipments under distribution agreements, signaling their entry into the active supply phase. These companies represent the core of our competitive analysis. Our report provides detailed company profiles, capacity assessments, and strategic positioning for each key player. Understanding the specific operational capacities and expansion plans of these entities is vital for benchmarking, yet the comprehensive competitive matrix and detailed market share estimations are reserved for the full report subscription.
Market Dynamics: Supply Chain Vulnerability and Expansion
The resilience of the HPQ market was tested recently by significant operational disruptions. In October 2024, operations at Spruce Pine facilities were temporarily halted following Hurricane Helene, with recovery underway and planning for capacity expansions. This event highlighted the geographical concentration risk associated with some of the world's highest quality quartz deposits. The impact on global supply was palpable, reinforcing the need for diversified sourcing strategies. Our report analyzes the duration of these disruptions, the recovery timelines, and the subsequent shifts in pricing power among suppliers.
In response to growing demand and the need to secure supply, major players are undertaking aggressive expansion strategies. Sibelco's expansion plans at Spruce Pine to double HPQ capacity are on track for completion in 2025, with a follow-on expansion planned for 2024-2027. This level of capital expenditure indicates confidence in long-term demand but also reflects the intensity of competition for feedstock. Such expansions are critical for stabilizing supply chains, yet the detailed modeling of how these capacity additions affect market equilibrium is a core feature of our analytical framework.
Furthermore, exploration and validation of new deposits are ongoing. In April 2026, Nordic Mining ASA announced that pilot testing confirms the Kvinnherad deposit in Norway can be processed into high-purity quartz with very low impurity levels suitable for high-end applications including semiconductors. This development is significant as it introduces a European source capable of meeting stringent semiconductor-grade impurity thresholds, potentially reducing reliance on transatlantic shipping for certain grades. Similarly, Homerun Resources delivered the first order of high-purity industrial silica sand under a distribution agreement with Cristal Sand Group in December 2025, marking a tangible step in commercializing new supply routes. These events are tracked in detail within our dynamic market monitoring section, but the strategic implications of each development on supply security and pricing are fully elaborated in the comprehensive study.
Regulatory and Raw Material Context
The operational environment for HPQ producers is increasingly influenced by regulatory frameworks and raw material availability. Regulations regarding mining rights, environmental standards, and export controls can significantly alter the viability of specific projects. For instance, the progress of major capacity expansions is often tied to regulatory approvals and community engagement. Our report examines the regulatory landscape across key jurisdictions, identifying potential bottlenecks that could delay capacity additions or restrict trade flows.
Raw material constraints remain a persistent theme. The quality of quartz is not uniform, and the ability to process lower-grade material into high-purity standards depends on technological capability and energy costs. The recent pilot testing results from Norway validate new sources, but scaling these operations requires significant investment. Our analysis integrates these factors into a supply risk assessment, helping clients understand where the vulnerabilities lie in the upstream segment. The interplay between regulatory hurdles and raw material constraints is complex, and our full report offers a nuanced view of how these factors will shape market dynamics over the forecast period.
Why This Report Matters for 2026 Decision Making
In 2026, decision-makers in the HPQ sector face a triad of challenges: securing supply in a concentrated market, managing volatility caused by geopolitical and environmental events, and aligning procurement with technological shifts in downstream industries. Generic market data is insufficient for addressing these challenges. You need intelligence that distinguishes between different grades of purity, understands the implications of specific operational disruptions, and forecasts the impact of capacity expansions with accuracy.
PW Consulting's High Purity Quartz Sand Market report is designed to meet this need. It provides a deep dive into the market size, growth rates, and segmentation that define the industry. It offers a thorough evaluation of the competitive landscape, profiling key companies and analyzing their strategic moves. It tracks recent developments, from hurricane recovery to new pilot testing results, to give you a real-time view of market momentum. Most importantly, it synthesizes this information into strategic recommendations that can guide resource allocation, partnership strategies, and risk management protocols.
While the insights provided in this overview highlight the breadth of our research, the depth of our analysis remains exclusive. The specific regional revenue splits, application-level consumption models, and detailed competitor capacity matrices are withheld from this public summary to preserve the value of our proprietary intelligence. Secure access to the complete dataset allows you to validate assumptions, stress-test scenarios, and commit to strategies with confidence.
Conclusion
The High Purity Quartz Sand market is poised for continued growth, driven by the essential needs of the semiconductor and solar industries. However, this growth is underpinned by a fragile and concentrated supply chain that requires careful navigation. The insights contained in PW Consulting's latest research offer a vital tool for investors, manufacturers, and supply chain strategists looking to secure their position in this critical market. We invite you to explore the full report to gain the comprehensive intelligence necessary to lead in the 2026 landscape and beyond.
For detailed access to the complete market models, segmentation data, and proprietary competitor analysis, please visit the source webpage to download the full report.
For detailed analysis of this topic, please visit the official page: High Purity Quartz Sand Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sparkling Juice Market Hits $1.02B in 2025, Poised for 11.67% CAGR to 2032
By PW Consulting, 2026-09-07
The Effervescent Opportunity: Strategic Intelligence for the Sparkling Juices Market in 2026 and Beyond
The global beverage landscape is undergoing a structural transformation, and sparkling juices are at the forefront of this shift. For executive teams, investors, and strategy leaders operating in 2026, the ability to separate fleeting consumer fads from durable demand curves is no longer a luxury it is a prerequisite for capital allocation, portfolio positioning, and competitive resilience. PW Consulting's latest Sparkling Juices Market research delivers precisely that clarity. Built on five years of historical tracking and extended through a six-year forward forecast, this report translates macro momentum into operational intelligence that can be deployed across pricing, supply chain, product development, and channel strategy.
Automatic Dipping Machine Market
What makes this edition particularly timely is the convergence of three macro forces: a sustained double-digit growth trajectory, an intensifying clean-label consumer mandate, and a tightening regulatory environment around sugar and labeling claims. Companies that treat these as isolated challenges will find themselves reacting to market signals rather than shaping them. The research is designed to move decision-makers from observation to action, mapping where value is being created, where margins are under pressure, and how the competitive field is being reorganised in real time.
Worldwide Anti-static Freezing Spray Market
Macro Trajectory and the Shape of Demand
The numbers tell a story of durable expansion. The global sparkling juices market has progressed from approximately 586.6 million USD in 2020 to a projected 1,143.58 million USD in 2026, before climbing toward 2,216.3 million USD by 2032. Across the 2026 to 2032 forecast window, the sector is expected to compound at a rate of 11.67 percent, a pace that places it well above many mature beverage categories and signals sustained pull-through rather than one-off volume spikes.
Worldwide Premium Liqueur Market
This growth is not merely a function of population or nominal inflation. It reflects a genuine category evolution: sparkling juice is shedding its legacy positioning as a seasonal or impulse product and is increasingly being evaluated through the lens of everyday hydration, flavor exploration, and health-aligned consumption. The compound trajectory is broad-based enough to reward well-positioned players across multiple formats, yet uneven enough in its underlying drivers that strategic segmentation, rather than blanket scaling, determines who captures disproportionate share.
Historical data from 2020 through 2025 confirms an acceleration pattern, with each successive year adding meaningful incremental volume. The forecast period extends that momentum, but the report's deeper architecture shows where that growth concentrates, which formats are leading the charge, and how channel infrastructure is evolving to meet it. Those granular insights which are essential for scenario planning and investment prioritisation are detailed in the full report, where decision-makers can align regional deployment, SKU architecture, and go-to-market investments against the most defensible pockets of expansion.
Competitive Architecture: How the Field Is Being Rewritten
The sparkling juices landscape is defined by a concentrated but dynamic set of players, with a CR3 of 35.0 percent and a CR5 of 50.0 percent. That level of concentration suggests enough fragmentation for agile entrants and differentiated line extensions to gain traction, while simultaneously indicating that the larger players hold meaningful sway over shelf space, retailer relationships, and consumer recognition. In 2026, the battleground is less about sheer scale and more about how quickly companies can translate clean-label credibility, fruit-forward formulation, and channel agility into repeat purchase behaviour.
S. Martinelli & Co., headquartered in Watsonville, California, anchors its sparkling portfolio around 100 percent juice sparkling ciders and blends made from U.S.-grown apples with no added sweeteners or preservatives. That formulation strategy positions Martinelli squarely in the premium, no-compromise segment, appealing to consumers who want the sensory profile of sparkling fruit without the trade-offs they associate with added sugar or artificial inputs.
Spindrift Beverage Co., based in Charlestown, Massachusetts, has built a distinct identity around real squeezed fruit sparkling beverages with no artificial ingredients or unnecessary additives. Spindrift's playbook demonstrates how authenticity in sourcing and ingredient transparency can serve as a defensible brand moat, particularly among shoppers who are actively comparing labels and trading down from more heavily processed alternatives.
Cawston Press, operating out of London in the United Kingdom, offers sparkling juices and drinks made with real pressed fruit juices and sparkling spring water, with no added sugar or sweeteners. The British-based producer illustrates how regional provenance, clean formulation, and a clear water-plus-fruit architecture can resonate in markets where consumers are highly attuned to sugar content and natural claims.
Talking Rain Beverage Company, headquartered in Preston, Washington, leverages its Sparkling Ice line of zero-sugar sparkling waters with real fruit flavors and natural colors. While often positioned within the broader functional beverage conversation, the Sparkling Ice platform shows how zero-sugar fruit-forward options can capture cross-category demand, especially when consumers want effervescence and fruit taste without the caloric load they increasingly seek to avoid.
Welch Foods Inc., based in Waltham, Massachusetts, maintains a broad fruit portfolio, including sparkling grape and fruit juice cocktails across flavors such as Sparkling Blueberry, Strawberry, and White Grape. Welch's scale and brand heritage give it a powerful distribution and recognition foundation, and its 2026 activity demonstrates how established players can continue to refresh relevance through limited editions and retailer-aligned launches.
R.W. Knudsen, also known as Knudsen & Sons and headquartered in Orrville, Ohio, focuses on organic sparkling juices such as Crisp Apple, Organic Pear, and Cranberry blends. Its organic positioning reinforces a “better-for-you” halo that aligns with the category's clean-label trajectory and offers a credible alternative for shoppers who want fruit character without conventional processing trade-offs.
Belvoir Farm, based in Bottesford, England, rounds out the competitive landscape with sparkling elderflower, pink apple, and botanical-infused drinks made from real fruit juices and spring water. Belvoir's recent school-compliant innovation highlights how targeted formulation and packaging choices can open adjacent use cases, particularly where family convenience and regulated environments create new demand pathways.
These profiles are not static snapshots. The report maps each company's formulation philosophy, channel emphasis, brand architecture, and strategic positioning, then layers in recent moves that reveal where momentum is building and where competitive pressure is intensifying. The goal is not simply to catalogue rivals, but to help clients anticipate where line extensions, acquisition targets, or defensive positioning will matter most in the next planning cycle.
Recent Moves That Signal Where the Category Is Heading
In mid-2026, Welch's introduced a limited-edition Sparkling Blueberry flavor with patriotic Americana packaging for America's 250th anniversary, available at major retailers including Costco and Walmart. This launch reflects a deliberate use of occasion-based marketing and retailer-anchored visibility to drive trial and basket attach in a mature market. It also shows how established brands can use limited editions not just for short-term revenue, but to test flavor extensions and packaging cues that may inform broader portfolio decisions.
Earlier in the year, Belvoir Farm launched a school-compliant sparkling fruit juice range with 45 percent real fruit juice, zero added sugar, and no sweeteners, packaged in 330ml cans for lunchboxes and family use. This move is strategically notable because it bridges the gap between health-conscious formulation and practical convenience. By designing for school compliance and on-the-go family consumption, Belvoir is tapping into a use case where repeat purchase frequency and household buying behaviour can reinforce brand loyalty over time.
Also in January 2026, Cawston Press launched a zero-sugar sparkling apple and rhubarb drink with natural sweeteners and real pressed fruit juices. This product demonstrates how producers are pushing the boundary between authentic fruit character and sugar reduction, using natural sweeteners to preserve taste while preserving the clean-label narrative that many consumers now expect. It is precisely this kind of reformulation and line-extension activity that decision-makers need to track, because it often signals where the category's next wave of mainstream acceptance will emerge.
The full report contextualises these launches within a broader framework of tactical innovation, retailer alignment, and consumer testing, so that clients can distinguish between one-off visibility plays and genuinely durable portfolio shifts.
Market Dynamics: The Forces Shaping Margins and Execution
Behind the growth narrative lies a set of operational realities that are reshaping how sparkling juice companies compete. The report's dynamics section examines the structural pressures that are influencing cost structures, compliance exposure, and formulation strategy across key markets. These forces are not peripheral concerns; they are central to whether growth in this category translates into profitable growth or simply higher volume at thinner margins.
One of the most persistent headwinds is the volatility of raw-material costs, particularly for fresh fruit concentrates. Fluctuating input prices have compressed margins and forced producers to renegotiate contracts more frequently, which in turn affects pricing flexibility, promotional cadence, and the ability to maintain consistent flavor and quality. In a category where taste authenticity and ingredient quality are part of the value proposition, supply-side instability can have an outsized impact on consumer perception if it leads to formulation variability or availability gaps.
At the same time, stringent labeling requirements for added sugars and natural claims have increased compliance expenses across North America, Europe, and Asia Pacific. These requirements are not merely administrative; they are actively influencing product architecture, ingredient selection, and marketing language. Nutritional labeling mandates for added sugars and natural claims are driving reformulation strategies among manufacturers, and that reformulation is not always straightforward, because reducing sugar while preserving taste, shelf stability, and consumer satisfaction requires careful balancing across recipe, processing, and packaging.
Supply chain volatility in fresh fruit sourcing is further complicating production timelines and costs for sparkling juice manufacturers. When sourcing disruptions intersect with regulatory scrutiny and retail price sensitivity, the margin for error shrinks. Companies that succeed in this environment tend to be those that combine rigorous supplier management, formulation flexibility, and clear internal decision rights around trade-offs between cost, taste, and compliance.
On the demand side, a significant consumer shift is underway toward clean-label and low-sugar sparkling juice options that double as functional beverages. This is not simply a preference for fewer additives; it reflects a broader expectation that everyday beverages should contribute positively to wellness routines without sacrificing enjoyment. That expectation is reshaping how consumers evaluate sparkling juice, moving the category closer to the mindset that has long governed water, tea, and functional drink segments.
These dynamics interact in complex ways. A company that excels at reformulation may still face margin pressure if input costs remain volatile. A brand that wins on clean-label credentials may need to invest more in compliance and packaging to meet evolving labeling rules. The report examines these intersections in detail, providing a structured view of where risk concentrates and where strategic flexibility can be converted into advantage.
What the Report Delivers: An Architecture Built for Decision-Making
PW Consulting's Sparkling Juices Market research is designed to serve multiple planning functions simultaneously. It moves beyond top-line market sizing to give strategy, marketing, operations, and M&A teams a common evidence base. The report's structure is built around practical deployment, so that readers can translate findings into pricing actions, portfolio decisions, channel investments, and competitive responses.
The analysis begins with a rigorous historical and forecast framework that maps the market's evolution from 2020 through 2032, anchoring strategic discussions in observed momentum rather than optimistic projections. From that foundation, the report examines the category's segmentation logic, including how product types, flavor preferences, distribution channels, and regional demand patterns are shaping where growth is most credible. These dimensions are explored in sufficient depth to guide scenario planning, but without the kind of narrow numeric disclosure that would reduce the analysis to a static spreadsheet reference. Instead, the report helps clients understand the relative pull of each segment, the stability of its growth drivers, and the strategic implications for portfolio balance and market entry.
Equally important is the competitive intelligence layer. Beyond the company profiles already highlighted, the report evaluates how major players are positioning across formulation, branding, channel access, and innovation cadence. It identifies where concentration creates defensive advantages, where fragmentation creates openings, and where recent launches and product architecture shifts suggest a change in the competitive baseline. That perspective is critical for companies deciding whether to defend a current position, pursue a flank, or reposition entirely in response to shifting consumer expectations.
The report also includes a dedicated dynamics section that turns industry noise into structured analysis. Rather than treating raw-material volatility, packaging regulation, nutritional labeling mandates, and supply chain disruption as isolated headlines, it examines how they interact to shape cost structures, compliance exposure, time-to-market, and consumer acceptance. This integrated view is particularly useful for operations and supply chain leaders who need to anticipate where renegotiation, reformulation, or channel reallocation may become necessary, and for marketers who need to understand which claims and formulations will remain durable under evolving regulatory conditions.
Finally, the analysis is framed around the practical question every leadership team faces in 2026: not just where the category is growing, but where the growth is defensible, how margins will behave under current dynamics, and which strategic moves are most likely to compound over the forecast window. The full report provides the level of segment-level disclosure and tactical interpretation required to answer those questions with confidence.
Strategic Implications for 2026 Decision-Makers
For companies operating in or adjacent to this market, the central strategic question is how to align growth ambition with execution reality. The forecast period through 2032 suggests ample room for expansion, but that expansion is being mediated by formulation expectations, cost volatility, regulatory stringency, and channel evolution. The most resilient strategies will be those that treat these factors as design constraints rather than external surprises.
In practice, that means prioritising clean-label credibility without ignoring the cost and reformulation complexity behind it. It means building channel strategies that can flex across supermarkets, hypermarkets, convenience, and online routes as consumer purchasing behaviour continues to diversify. It means monitoring competitive launches not just for their immediate sales impact, but for the signals they send about flavor direction, sugar-reduction ambition, and the use of limited editions to test broader portfolio shifts. And it means constructing supply and sourcing strategies that can withstand input volatility while preserving the consistency that fruit-forward sparkling juice consumers expect.
This research is intended to support that level of strategic judgement. It gives leadership teams a shared reference point for where the category is headed, how the competitive field is shifting, and which operational pressures are likely to persist through the forecast period. For organisations that need to move quickly but avoid costly missteps, the difference between reacting to headlines and acting on structured evidence is often the difference between capturing share and merely defending it.
The full report contains the deeper segmentation detail, regional nuances, channel dynamics, and competitive intelligence required to operationalise these insights. For strategy, marketing, and operations leaders preparing for the rest of 2026 and the years beyond, PW Consulting's Sparkling Juices Market research offers the kind of evidence base that turns category momentum into a deliberate, defensible plan.
For detailed analysis of this topic, please visit the official page: Sparkling Juices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glycomics Market to Hit $732.05 Million by 2032, 14.3% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Decade: Strategic Intelligence in the Global Glycomics and Glycobiology Market (2026-2032)
The landscape of life sciences is undergoing a fundamental shift, moving beyond genomics and proteomics to embrace the complex layer of biology defined by glycans. As we enter 2026, the glycomics and glycobiology sector represents not merely a niche scientific endeavor but a critical frontier for pharmaceutical innovation, diagnostic precision, and therapeutic development. For executive leadership and strategic planners, understanding the trajectory of this market is no longer optional; it is a prerequisite for capitalizing on the next wave of biomedical breakthroughs. Our latest comprehensive market research report offers a detailed examination of this evolving landscape, providing the data-driven foundation necessary to navigate the complexities of the industry through 2032.
Automatic Underwear Washing Machine Market
Market Evolution and Historical Trajectory
The growth narrative of the glycomics market over the past five years underscores a sector gaining significant momentum. Between 2020 and 2025, the global market expanded from approximately 145.66 million USD to 290.44 million USD. This historical progression reflects a compound annual growth rate that signals robust adoption across multiple verticals. The acceleration observed during this period was driven by increasing recognition of glycosylation's role in drug efficacy, immune response modulation, and disease biomarker identification. As organizations invested in capacity and technology during these foundational years, the infrastructure required for scalable glycobiology solutions began to mature.
Ecommerce Shipping Software Market
Looking forward, the forecast period from 2026 to 2032 projects continued robust expansion. The market size is anticipated to reach 732.05 million USD by the end of the forecast window. This trajectory implies a CAGR of 14.3 percent throughout the forecast period. Such growth rates indicate that the market is transitioning from an emerging phase into a more mature, high-velocity growth stage. For stakeholders, this suggests that the window for establishing early market presence or securing supply chain advantages is narrowing, making timely strategic decisions critical. The revenue projections highlight an industry where value accumulation will likely be concentrated among entities that can successfully bridge the gap between complex glycan chemistry and commercial application.
Worldwide Metal Stamping Technology Market
Segmentation Dynamics and Value Distribution
Understanding where value is generated within the glycomics ecosystem is essential for resource allocation. The market is broadly categorized by type, application, and region, each presenting distinct opportunities and challenges. In terms of product types, the market encompasses instruments, reagents and kits, and enzymes. Instruments constitute a significant portion of the market value, reflecting the high technical barrier and capital intensity associated with glycan analysis technologies. Reagents and kits follow closely, indicating a strong demand for standardized, accessible tools that enable laboratories to integrate glycobiology workflows without developing proprietary chemistry from scratch. Enzymes, while representing a smaller share of the total revenue mix, remain critical for specific derivatization and processing tasks where specificity is paramount.
Application-wise, the demand is distributed across drug discovery and development, diagnostics, and academic research. Drug discovery and development currently commands the largest share of application-related revenue, driven by the pharmaceutical industry's pursuit of glycosylated biologics and glycan-targeted therapies. Diagnostics represents another substantial pillar, as glycan biomarkers offer unique insights into disease states that protein or DNA markers may miss. Academic research continues to be a steady contributor, fostering innovation that often trickles down to commercial applications. However, it is important to note that the specific revenue splits and percentage contributions for each segment are detailed within the full report, as these figures fluctuate based on regional adoption rates and technological breakthroughs that require nuanced analysis.
Geographic distribution of market value reveals a concentration in developed economies. North America holds the largest share of the market revenue, followed by Europe and Asia Pacific. The dominance of North America is attributable to its strong biotechnology funding environment, presence of major pharmaceutical hubs, and early adoption of advanced analytical technologies. Europe maintains a significant position, bolstered by strong academic institutions and specialized glycomics centers. Asia Pacific, while currently holding a smaller share, is identified as a region with high growth potential due to increasing investment in life sciences infrastructure. Latin America and the Middle East and Africa represent smaller but emerging markets, where entry strategies must be tailored to local regulatory environments and investment capacities. The full report provides a granular breakdown of these regional dynamics, including specific growth drivers that are not visible in macro-level data alone.
Competitive Landscape and Strategic Players
The competitive environment in glycomics is characterized by a mix of specialized service providers, technology developers, and pharmaceutical entities leveraging glycobiology for pipeline advancement. Market concentration indicates a moderately consolidated environment, with the top three companies holding a significant portion of the market share and the top five firms controlling the majority of the sector's revenue. This concentration suggests that while there is room for innovation-driven entrants, scale and proprietary technology remain powerful moats.
Several key companies define the current operating landscape. Asparia Glycomics, based in San Sebastián, Spain, exemplifies the service-oriented model, offering custom glycan synthesis and multi-level analysis services. Their portfolio, including patented standards like CarboQuant, supports therapeutics and diagnostics development, particularly in oncology and infectious diseases. This type of player is crucial for reducing the technical burden on pharmaceutical clients who need precise glycan profiling without building internal capacity.
Lectenz Bio, located in Athens, Georgia, USA, focuses on accessibility and validation. By providing lectin-like binding proteins, recombinant enzymes, and detection kits, they aim to simplify glycomics integration for biomarker detection and bioprocessing. Their approach addresses a common market friction: the complexity of glycan analysis methods that demand extensive technical proficiency. By lowering this barrier, companies like Lectenz Bio expand the total addressable market for glycobiology tools.
In Europe, GlycoMar Limited in Scotland operates as a center for marine biotechnology and glycobiology. They develop saccharide-based functional products for healthcare and nutraceutical applications, showcasing the diversification of glycobiology beyond traditional pharma into cosmeceuticals and nutrition. Similarly, IntelliHep Ltd in Liverpool focuses on heparin-based glycans and proprietary platform technology. Their pipeline targets neurodegeneration, cancer, and inflammation, illustrating how glycan therapeutics are moving into high-value therapeutic areas like Alzheimer's disease and regenerative medicine.
On the pharmaceutical side, the recent restructuring of Crescent Biopharma, Inc. in Waltham, Massachusetts, marks a significant industry event. Following its 2025 merger with GlycoMimetics, the company advanced its oncology pipeline, including PD-1 x VEGF bispecific antibodies. This merger highlights the consolidation trend among entities with specific glycan-related intellectual property, as they seek to combine resources to navigate clinical trials and regulatory pathways. These profiles represent only a subset of the competitive intelligence available; the full report includes deeper analysis of operational strategies, partnership networks, and technology pipelines for these and other market participants.
Industry Dynamics, Challenges, and Regulatory Headwinds
Despite the positive growth trajectory, the glycomics market faces distinct structural challenges that strategic planners must account for. One primary obstacle is the cost and complexity associated with glycan chemistry. The cost of glycans and the overall time required for derivatization and subsequent purification can be significant. This is due to complex chemistry capabilities and limited enzymes and acceptors available for specific modifications. These technical hurdles increase the cost of goods sold for glycan-based products and can extend development timelines for diagnostics and therapeutics.
Regulatory frameworks also play a pivotal role in shaping market dynamics. The interaction between glycobiology products and regulatory bodies like the FDA can introduce uncertainty. For instance, recent communications regarding specific therapeutic candidates, such as uproleselan in acute myeloid leukemia, have indicated that bringing certain glycan-related products to market may require additional clinical trials. Such regulatory demands can impact commercialization timelines and capital expenditure requirements. Companies operating in this space must maintain robust regulatory affairs capabilities to navigate these requirements effectively.
Reimbursement and market access present another layer of complexity. The high expense associated with glycobiology studies, combined with the complicated nature of analysis methods, creates a barrier to widespread adoption in routine clinical settings. While the value of glycan biomarkers is scientifically established, translating this into reimbursable diagnostics requires demonstrating clear clinical utility and cost-effectiveness to payers. This dynamic slows the transition of glycomics from research tools to standard-of-care diagnostics in some regions.
Supply chain considerations are also relevant. The reliance on specialized enzymes and chemical acceptors means that supply disruptions can impact production schedules for reagents and kits. As the market grows, ensuring a stable supply of high-quality raw materials becomes a strategic priority for manufacturers. These dynamics are explored in depth in our report, where we analyze how leading companies are mitigating these risks through vertical integration, partnerships, or diversified sourcing strategies.
Recent Developments and Collaborative Innovation
The period leading into 2026 has seen a surge in collaborative initiatives aimed at accelerating glycomics applications. Mergers and partnerships are becoming key vehicles for sharing risk and combining expertise. A notable example is the completion of the merger between Crescent Biopharma and GlycoMimetics in mid-2025. This consolidation brought together complementary assets to advance an oncology pipeline that includes bispecific antibody studies. Such moves signal to the market that intellectual property in glycobiology is viewed as a strategic asset worthy of significant capital deployment.
Research partnerships are also gaining traction, particularly between academic institutions and commercial entities. In May 2026, Griffith University's Institute for Biomedicine and Glycomics entered into a partnership with Taiwanese company Intelligene. The goal of this collaboration is to deliver new therapies for infectious diseases through joint commercial research. This type of cross-border collaboration leverages academic discovery capabilities alongside commercial development expertise, potentially speeding up the translation of glycan-based solutions into therapeutic products.
Furthermore, major chemical and life science companies are expanding their footprint in this sector. In late 2025, Nagase Viita Co., Ltd. partnered with Okayama University to establish a Laboratory of Glycobiology and Phytochemistry. This initiative reflects a broader industry trend where large suppliers are investing in foundational research to identify new applications for their materials and services. These developments indicate that the ecosystem is becoming more interconnected, with knowledge flow between academia, large corporations, and specialized biotechs driving innovation. The full report tracks these events and analyzes their implications for market share and technology diffusion.
Strategic Imperatives for 2026 Decision Making
For organizations operating in or entering the glycomics market in 2026, several strategic imperatives emerge from the data. First, timing is critical. With a projected CAGR of 14.3 percent over the next seven years, the market will expand significantly, but early movers who secure technology partnerships or supply chain positions now may capture disproportionate value. Delaying entry until the market is more mature may result in higher acquisition costs for technology or talent.
Second, vertical specialization offers a pathway to differentiation. Given the concentration of market share among top players, new entrants or expanding existing players should consider focusing on high-value niches. This could involve targeting specific therapeutic areas like neurodegeneration or oncology, where glycan therapeutics show promise, or focusing on diagnostic applications where unmet clinical needs exist. The report provides detailed segmentation data to help identify these pockets of opportunity without relying on generalized market averages.
Third, managing complexity is a competitive advantage. The barriers related to glycan chemistry complexity and regulatory hurdles are significant. Companies that can offer streamlined solutions, whether through simplified kits, validated standards, or outsourced analysis services, are well-positioned to capture market share from organizations struggling with internal technical limitations. The profiles of companies like Lectenz Bio and Asparia Glycomics illustrate how service and product models can address these pain points.
Finally, monitoring regulatory and reimbursement landscapes is essential. As glycan-based diagnostics and therapeutics move closer to clinical use, the policies governing their approval and reimbursement will dictate commercial viability. Strategic planning should include scenario analysis for different regulatory outcomes, ensuring that investment decisions are robust against potential delays or additional trial requirements.
Conclusion: The Value of Comprehensive Intelligence
The glycomics and glycobiology market stands at an inflection point. The historical growth from 2020 to 2025 has laid the groundwork, and the forecast to 2032 suggests a period of accelerated value creation. However, the complexity of the science, the nuances of the competitive landscape, and the evolving regulatory environment require more than surface-level understanding.
This market research report is designed to provide the depth required for high-stakes decision making. It moves beyond aggregate numbers to explore the structural drivers of growth, the specific strategies of key competitors, and the operational challenges that define the sector. Whether you are evaluating investment opportunities, planning product development, or assessing competitive threats, the granular insights contained in this analysis are indispensable.
The data presented here offers a high-level view of the trajectory, but the true strategic advantage lies in the detailed breakdowns of regional dynamics, segment-specific growth rates, and comprehensive company profiles. To access the full suite of intelligence, including specific revenue projections by segment, detailed competitive benchmarking, and actionable strategic recommendations, we invite you to explore the complete report. In a market moving at 14.3 percent CAGR, having the right data at the right time is the difference between leading the market and chasing it.
For detailed analysis of this topic, please visit the official page: Glycomics/Glycobiology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mattress Toppers Market Hits $1.825B in 2025, Projected to Reach $2.816B by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-07
Navigating the Mattress Toppers Market: Strategic Imperatives for 2026 and Beyond
The global sleep economy continues to evolve at a rapid pace, driven by heightened consumer awareness of health, wellness, and the direct correlation between sleep quality and daily performance. Within this expanding ecosystem, the mattress toppers market stands out as a critical segment, offering a cost-effective solution for consumers seeking to enhance existing sleep surfaces without the capital expenditure of a full mattress replacement. For industry stakeholders, investors, and strategic planners, understanding the nuanced trajectories of this market is no longer optional—it is essential for capitalizing on emerging opportunities and mitigating risks in a competitive landscape.
Enterprise External Information Sharing Content Management Market
PW Consulting's latest comprehensive market research report on the Mattress Toppers Market provides an exhaustive analysis of the sector's past performance, current dynamics, and future projections. This document serves as a strategic briefing, distilling complex data into actionable intelligence designed to inform decision-making throughout the forecast period extending to 2032. By examining historical trends from 2020 through 2025 and projecting growth trajectories, this research equips organizations with the foresight needed to navigate supply chain complexities, shifting consumer preferences, and regulatory environments that define the modern sleep industry.
Paclitaxel Coated Balloon Catheter Market
The significance of this study lies in its ability to bridge the gap between macro-economic indicators and micro-level operational strategies. As companies strive to optimize their product portfolios and expand their market footprint, access to precise, validated data becomes a key differentiator. The following analysis highlights the core components of this research, illustrating how it serves as a vital tool for stakeholders aiming to secure a competitive edge in the years ahead.
Worldwide Fluoro-Pyridines Market
Market Trajectory and Growth Horizons
Analyzing the historical performance of the mattress toppers market reveals a consistent upward trend, reflecting the growing prioritization of sleep ergonomics and comfort. Between 2020 and 2025, the market demonstrated resilience and expansion, navigating through various global economic shifts while maintaining positive momentum. The data indicates that the market revenue, measured in USD Million, grew from a baseline of 1250.0 in 2020 to approximately 1825.0 in 2025. This progression underscores a robust adoption rate across various consumer demographics and geographic regions.
Looking forward, the forecast period from 2026 to 2032 suggests continued expansion, though the pace may be influenced by broader economic conditions and saturation levels in mature markets. The research projects that the market size will reach approximately 1945.4 in 2026, climbing steadily to an estimated 2815.95 by the end of the forecast window in 2032. This growth trajectory is supported by a compound annual growth rate (CAGR) of 6.5 percent during the forecast period. Such figures provide a foundational benchmark for companies evaluating potential return on investment for new product launches, distribution channel expansions, or manufacturing capacity upgrades.
Understanding these macro-level figures is crucial, but the true value lies in dissecting the drivers behind them. The research delves into the specific factors propelling this growth, including the rising prevalence of sleep disorders, the increasing aging population seeking comfort solutions, and the surge in e-commerce channels facilitating easier access to sleep accessories. By contextualizing these numbers within broader consumer behavior trends, the report offers a narrative that goes beyond simple extrapolation, providing a nuanced view of where the market is heading and why.
Segmentation Dynamics and Product Innovation
A key strength of this market research is its detailed breakdown of the industry by type, application, and region, allowing stakeholders to identify high-potential niches. The market is diversified across several material types, each catering to different consumer needs regarding comfort, durability, and thermal regulation. The analysis highlights that Memory Foam continues to hold a significant share of the market, driven by its pressure-relieving properties and widespread consumer acceptance. However, the report also sheds light on the growing interest in Latex, Feather and Down, Wool, and Polyurethane Foam variants, each offering distinct value propositions ranging from breathability to eco-friendliness.
In terms of application, the market is primarily divided between Residential and Commercial segments. The Residential sector remains the dominant force, fueled by home improvement trends and consumer spending on personal comfort. Nevertheless, the Commercial segment, encompassing hospitality and healthcare facilities, presents a distinct growth avenue as establishments upgrade their bedding infrastructure to enhance guest and patient satisfaction. The research provides insights into the revenue contribution of each segment without disclosing sensitive competitive data, enabling companies to benchmark their own performance against industry averages.
Furthermore, the report examines regional performance, acknowledging that market maturity and consumer preferences vary significantly across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While overall global figures provide a broad view, understanding regional nuances is critical for firms planning international expansion or localized marketing campaigns. The study avoids publishing specific percentage splits for these regions in public summaries to maintain the competitive advantage of the full report, but it emphasizes the importance of regional customization strategies for market penetration.
Competitive Landscape and Key Player Strategies
The mattress toppers market is characterized by a mix of established brands and niche innovators, resulting in a fragmented yet dynamic competitive environment. Market concentration metrics indicate that the top three players hold a collective share of approximately 24.0 percent, while the top five control around 26.0 percent of the market. This structure suggests that while there are dominant forces, there is ample room for agile competitors to carve out specialized positions through product differentiation and targeted marketing.
Several key companies are shaping the industry through continuous innovation and strategic product line extensions. For instance, Saatva has focused on offering Graphite Memory Foam and Natural Latex Toppers, catering to consumers seeking cooling properties and organic options. Similarly, Helix Sleep has introduced Premium Mattress Toppers featuring GlacioTex and ErgoAlign technologies, emphasizing advanced cooling and zoned support for specific physical needs. Nolah distinguishes itself with the AirFoam Luxe Mattress Topper, utilizing high-density foam with CertiPUR-US certification to promise pressure relief and cooling efficiency.
Traditional powerhouses are also adapting to modern demands. Tempur-Pedic continues to leverage its signature TEMPUR material in toppers like the TEMPUR-Adapt, delivering personalized adaptive pressure relief. Meanwhile, companies like Brooklyn Bedding are exploring hybrid technologies with their 3-inch Talalay Latex and Microcoil Mattress Toppers, emphasizing ultra-responsive latex and supportive coil technology. Avocado Green Mattress targets the eco-conscious demographic with its Eco Organic Latex Mattress Topper, made from GOLS-certified organic talalay latex.
Recent developments highlight the intensity of this competition. In March 2025, Helix Sleep launched two new mattress toppers featuring a GlacioTex cover aimed at advanced cooling and back pain relief. Later, in August 2025, Tempur-Pedic unveiled a new line of eco-friendly mattress toppers using sustainable materials, signaling a shift towards environmental responsibility in product design. These moves illustrate the industry's pivot towards specialized features such as temperature regulation, spinal alignment, and sustainability. The report provides detailed profiles of these companies, including their headquarters, product offerings, and strategic directions, offering a clear view of the competitive battlefield.
Regulatory Environment and Industry Dynamics
Navigating the regulatory landscape is a critical component of strategic planning in the mattress and bedding industry. The research incorporates recent industry context noise to highlight potential risks and compliance requirements. For example, regulatory bodies continue to monitor safety standards rigorously. In May 2026, BHS issued a recall for Lyocell and Plush Mattress Enhancers due to fire safety non-compliance with the Furniture and Furnishings (Fire) (Safety) Regulations 1988. Such events underscore the importance of adherence to local safety standards to avoid reputational damage and financial loss.
Certifications play a pivotal role in consumer trust and market access. Multiple mattress topper brands now require certifications such as GOLS, GOTS, CertiPUR-US, and OEKO-TEX to meet organic and low-emission standards. These certifications are increasingly becoming a baseline expectation rather than a differentiator, especially among educated consumers who prioritize health and environmental impact. The report details the implications of these certification requirements for manufacturing and sourcing strategies.
Furthermore, regulatory monitoring is ongoing in various jurisdictions. The CPSC continues to monitor flammability standards for mattresses and pads, with public meetings held on updates to 16 CFR 1632 and 1633. Staying abreast of these regulatory updates is essential for companies operating in or exporting to the United States. The industry context provided in the research helps stakeholders anticipate changes in compliance costs and product design requirements, ensuring that their operations remain resilient against regulatory shifts.
Consumer Trends and Future Outlook
Consumer habits are shifting rapidly, influencing product design and marketing strategies across the sector. There is an increasing demand for organic and cooling toppers, driven by a preference for sustainable and temperature-regulated sleep products. This trend aligns with broader wellness movements where consumers are willing to invest more in products that promise better health outcomes and environmental stewardship. The research explores these consumer habit shifts in depth, linking them to specific product features and material choices.
Trade exhibitions also play a role in signaling industry direction. For example, the ISPA EXPO attended in October 2025 showcased the latest mattress components and toppers, indicating where innovation is heading within the supply chain. Such events provide valuable networking opportunities and insights into emerging technologies that may disrupt the market in the coming years.
The strategic value of this report extends beyond static data points. It offers frameworks for analyzing how these consumer trends will evolve through 2032. By understanding the interplay between economic factors, regulatory changes, and consumer preferences, companies can develop robust strategies that are adaptable to change. Whether it is deciding on inventory levels, planning R&D investments, or identifying potential acquisition targets, the insights provided serve as a foundation for sound decision-making.
Conclusion: The Strategic Value of Intelligence
In an industry as competitive and dynamic as the mattress toppers market, relying on assumptions or outdated information can lead to missed opportunities and strategic missteps. PW Consulting's market research report offers a comprehensive, data-driven perspective that empowers organizations to act with confidence. From historical revenue analysis covering 2020 to 2025 to forward-looking projections through 2032, the report covers all critical aspects of the market landscape.
The inclusion of detailed company profiles, recent development tracking, and regulatory analysis ensures that readers gain a holistic understanding of the forces at play. While the executive summary provides a strong overview of market size, growth rates, and key trends, the full report contains granular segmentation data, deep-dive regional analyses, and specific strategic recommendations that are essential for detailed planning. Accessing the complete intelligence allows stakeholders to move beyond general awareness into precise execution.
For businesses aiming to lead in the mattress toppers sector, understanding the trajectory of the market is the first step. The next step is leveraging that knowledge to build strategies that are resilient, innovative, and customer-centric. This research serves as that crucial bridge, transforming raw data into strategic advantage. Stakeholders are encouraged to explore the full report to uncover the specific insights needed to navigate the complexities of the market and capitalize on the growth opportunities available in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Mattress Toppers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Craft Soda Market to Hit $1.03B by 2032, Growing at 6.5% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for the Craft Soda Sector: Navigating the 2026–2032 Growth Horizon
The craft soda market is undergoing a structural transformation that demands more than surface-level trend watching. Over the past half-decade, consumer preferences have shifted decisively toward transparent ingredient lists, reduced sugar profiles, and experiential flavor narratives. Simultaneously, supply chain friction, packaging cost volatility, and an expanding web of regulatory sugar mandates have reshaped the economics of production and distribution. For executives operating in or adjacent to the non-alcoholic beverage space, the question is no longer whether this category will continue to grow, but how to position portfolios, pricing architectures, and channel strategies to capture durable margin expansion rather than transient volume spikes.
Worldwide FEP Dispersion Market
This article serves as a strategic preview of our newly released Craft Soda Market research. It outlines the macro trajectory that defines the 2026 decision window, frames the operational and competitive forces that will separate winners from laggards, and previews the analytical architecture behind our full report. The goal is straightforward: give leadership teams enough forensic depth to validate the study’s relevance, while reserving the most consequential segmentation contours for the complete intelligence package.
Car WIFI Diagnostic Tool Market
The 2026 Decision Window: Why Now
Our analysis anchors its baseline in 2025 market revenue of approximately 635 million USD, building on a multi-year expansion that has taken the category from roughly 450 million USD in 2020. The growth curve has not been linear; it has reflected shifting consumer spending, channel reallocation, and periodic supply disruptions. Looking forward, the forecast period extends through 2032, with the market projected to approach 1.03 billion USD by the end of the horizon. At the center of this trajectory sits a compound annual growth rate of 6.5 percent, a figure that blends organic volume expansion, premiumization, and the gradual migration of mainstream consumers into craft-adjacent purchasing behaviors.
Worldwide Micromanipulation Pipettes Market
For 2026 planning, the most consequential takeaway is that this growth rate is not a uniform tide. It is being shaped by uneven channel performance, divergent regional demand intensity, and a reformulation cycle that is compressing sugar levels while elevating the strategic importance of flavor differentiation. Executives who treat the category as a single-block opportunity will misread where profitability is forming. The 2026 vintage of our research maps these divergences directly, aligning market sizing with the specific demand levers that matter for sourcing, production scheduling, and channel mix decisions.
The 6.5 percent CAGR is best understood as a composite of several underlying dynamics. Volume in core craft formats continues to rise, but the faster-moving contribution comes from premium pricing tolerance, seasonal flavor rotations, and the integration of craft soda into broader on-premise and off-premise beverage ecosystems. Our full report decomposes these drivers into actionable variables, but the headline message for leadership is clear: the market is large enough to support multiple winning strategies, yet granular enough that undifferentiated plays will face margin compression. The 2026 update is designed to help teams identify which levers are within their control and which require external intelligence to navigate.
What the Report Delivers: Operational Intelligence, Not Just Headlines
A market study earns its place on a strategy desk only when it converts numbers into decisions. The Craft Soda Market research was built for that standard. Rather than functioning as a static sizing exercise, the report is structured around the operational questions that arise when procurement, brand, sales, and finance teams try to align their 2026 plans. The following components form the core of the analysis:
- Strategic market sizing and forward trajectory, anchored in historical performance from 2020 through 2025 and extended across the 2026–2032 forecast window, with explicit attention to the inflection points that could accelerate or dampen growth.
- A structured decomposition of market segments by region, product type, and application, enabling teams to evaluate where demand intensity, pricing power, and competitive pressure are most pronounced.
- Company-level profiles that connect strategic positioning, production philosophy, and portfolio orientation to the broader market architecture, providing a practical lens for benchmarking and competitive response.
- A close examination of recent corporate activity, including retail expansion moves, new flavor line launches, and product-line extensions that signal how incumbents and challengers are contesting share.
- A regulation and input-cost review that captures packaging supply constraints, nutritional labeling mandates, sugar-content compression trends, sugar-tax proliferation, and cross-border tariff exposure, all of which affect cost-to-serve and formulation roadmaps.
- Market concentration indicators that contextualize competitive fragmentation and help leadership assess the realistic scope for share gains versus consolidation risk.
The throughline across these sections is practical deployment. The report is designed to inform capacity planning conversations, inform pricing architecture reviews, guide channel investment choices, and support portfolio pruning or extension decisions. It also serves as a reference point for investor relations and fundraising narratives where credible category trajectory and competitive differentiation need to be articulated without overclaiming. In other words, the report is not merely a description of where the market has been; it is a decision-support instrument for where the market is going and what it will take to win within it.
Competitive Architecture: Who Is Shaping the Category
The craft soda space is populated by a diverse set of companies whose strategies reflect different answers to the same market pressure: how to deliver distinct flavor, credible ingredient integrity, and scalable production without surrendering premium positioning. Our research profiles several core players whose approaches illuminate the competitive fault lines in the category.
Spindrift Beverage Co., headquartered in Newton, Massachusetts, has built its identity around real-fruit-squeezed sparkling sodas made with natural fruit juice and a deliberately minimal ingredient set. That formulation philosophy positions the brand as a transparent alternative in a category where consumers increasingly scrutinize label simplicity. Reed’s, Inc., based in Norwalk, Connecticut, competes through ginger ale and soda products made with fresh ginger and no artificial ingredients, leaning into a flavor provenance narrative that resonates with consumers seeking sensory authenticity rather than generic sweetness. Boylan Bottling Company, operating from New York, New York, offers cane sugar sodas, seltzers, and mixers produced in small batches since 1891, combining heritage manufacturing with a modern craft appeal.
Sprecher Brewing Company, headquartered in Glendale, Wisconsin, distinguishes itself through craft sodas and root beer brewed using a fire-brewing process since 1985, an operational signature that supports both product differentiation and a story consumers can visualize. Fever-Tree Drinks plc, based in London, England, has extended the craft soda conversation into premium tonic waters and mixers built with quinine bark and natural botanicals, reflecting the category’s increasing overlap with mixer ecosystems and adult-oriented consumption occasions. Jones Soda Co., operating from Seattle, Washington, continues to expand its craft soda portfolio, including recent cola variants made with cane sugar and natural ingredients, while also pursuing broader retail reach.
Dry Soda Co., also based in Seattle, Washington, brings botanical and botanical-bubbly zero-proof sodas into the landscape, an approach that aligns with the category’s growing intersection with wellness-oriented and low-alcohol or no-alcohol consumption patterns. Wild Bill’s Craft Beverage Co., headquartered in Millington, New Jersey, contributes veteran-owned cane sugar sodas and root beer, reinforcing the role of identity-driven branding in a market where authenticity and community positioning can translate into durable advocacy. Fentimans Ltd., from Hexham, England, competes with botanically brewed ginger beer and sodas, emphasizing fermentation-style craftsmanship as a point of differentiation. Q Mixers, located in Brooklyn, New York, extends the category into premium non-alcoholic mixers and craft sodas, bridging standalone soda consumption with cocktail-adjacent demand. Lady Bird Soda Co., based in Austin, Texas, rounds out the competitive set with all-natural, low-sugar, gluten-free sodas expressed through Texas-inspired flavors, an example of how regional identity and dietary positioning can be combined in a single product strategy.
These profiles are not included as a catalog of names. They are used to illustrate how different strategic bets are being made across ingredient philosophy, production method, flavor provenance, channel orientation, and brand identity. In the full report, these company narratives are connected to broader segmentation patterns so that leadership teams can see not only who is active, but how each player’s positioning relates to the demand pockets they are targeting.
Recent Corporate Activity and What It Signals for 2026
Market structure is not static; it is revealed in the moves companies make when they believe the timing is right. Several recent developments underscore the strategic intensity of the category and provide early signals for the 2026 planning cycle.
In January 2026, Jones Soda Co. introduced its craft soda 4-pack in 650 high-volume Walmart stores throughout the U.S. This retail expansion move is significant because it reflects a deliberate push into a higher-throughput channel where visibility and basket presence can accelerate trial and repeat purchase. It also suggests confidence in a packaging and pricing architecture capable of performing in a mass-retail environment without eroding the brand’s craft framing. For competitors, the implication is clear: distribution breadth is becoming an increasingly important variable, and channel entry decisions need to be evaluated against both volume potential and brand equity preservation.
In March 2025, Hank’s Beverage Company launched four new flavors as part of its “Hank’s ZERO craft soda” product line. The launch illustrates a reformulation and extension strategy oriented toward zero-calorie or low-intake consumption preferences, an area where product architecture must balance flavor credibility with the demand for cleaner nutritional profiles. Then, in June 2025, Pelican Brewing Company launched two craft soda products, Craft Sodas and Hard Hops, indicating that some producers are exploring adjacent format boundaries and occasion expansion, potentially blurring the line between standalone soda and broader beverage experiences.
These events are representative of a broader pattern: companies are not merely riding category growth, they are actively reshaping their portfolios to capture specific demand shifts. Our report places these developments in context, connecting launch timing, channel selection, and product architecture to the segmentation framework that explains where such moves are likely to succeed or encounter headwinds.
Market Dynamics: Regulation, Inputs, and Pricing Architecture
Craft soda strategy cannot be separated from the environment in which production and distribution occur. Several industry dynamics are reshaping cost structures and formulation choices in ways that directly affect 2026 decision-making.
One persistent pressure involves packaging inputs. The U.S. beverage industry has experienced increased prices for glass bottles over the last several years, and the availability of glass supply has diminished for companies not under contract. This constraint matters because packaging is not simply a logistics line item; it is a brand signal, a shelf-performance variable, and a cost driver that can alter margin planning. Compounding this issue, fixed-price purchase commitments are expiring at the end of 2028, a timeline that creates near-term planning uncertainty for companies that must decide whether to lock in supply, renegotiate terms, or accelerate packaging diversification.
On the regulatory front, beverage manufacturers must comply with nutritional labeling mandates and regulatory sugar limits, and the practical effect has been substantial. Average sugar content has been reduced by 18 percent on product lines since 2022. This reformulation trend is not cosmetic; it reflects a structural shift in how products are engineered, how sweetness is managed, and how flavor balance is maintained when sugar levels decline. In parallel, more than 35 countries have implemented sugar taxes that influence pricing strategies and formulation processes, adding another layer of complexity for companies operating across multiple markets or planning to expand internationally.
Trade policy adds still another dimension. Tariffs affecting raw materials or finished goods transported between the United States and Canada impact ingredient and packaging material costs, meaning that even firms with primarily domestic footprints may face indirect cost pressure through their supply chains. These dynamics are not isolated footnotes. They are central to understanding why some companies can sustain premium pricing while others are forced into competitive price concessions, and why formulation flexibility has become a strategic asset rather than a back-office function.
The full report integrates these dynamics into the broader market narrative, showing how they interact with segmentation patterns and competitive behavior. For 2026, the strategic implication is that cost planning and regulatory readiness need to be treated as market-strategy inputs, not compliance afterthoughts.
Concentration and Strategic Implications for Market Entry and Expansion
One of the most useful questions a market study can answer is how fragmented or consolidated the competitive field truly is. In the craft soda market, concentration levels suggest a moderately dispersed landscape rather than a tightly controlled oligopoly. The top three firms account for approximately 26.5 percent of market revenue, while the top five firms account for roughly 31.2 percent. These figures indicate that a meaningful share of the market remains available to mid-sized and regional players, specialty brands, and new entrants that can differentiate on flavor, ingredient story, channel fit, or brand identity.
At the same time, the concentration profile should not be read as an open field. The leading companies have established distribution relationships, recognizable brand equities, and production capabilities that create real barriers for undifferentiated entrants. The practical reality for 2026 is that successful expansion will likely depend on targeted positioning rather than broad-based imitation. Companies that try to compete everywhere often end up competing on price; companies that compete with a clear formulation, channel, or occasion thesis are better positioned to command shelf space and retailer interest. Our report examines how these concentration patterns interact with regional and application-level demand so that teams can assess where entry or expansion is realistically viable.
Segmentation Lens: Where Demand Intensity Is Concentrated
The craft soda market is not uniform across geographies, product types, or consumption channels. Our research segments the market along three axes that matter most for strategic planning: region, type, and application. Each axis reveals a different layer of opportunity and constraint, and together they help leadership teams avoid the mistake of assuming that a single growth narrative applies to every market touch point.
At the regional level, the market reflects differing levels of maturity, retail infrastructure, consumer taste preferences, and price sensitivity. Some markets are more advanced in their adoption of craft-oriented beverage choices, while others are still in the process of building awareness and distribution density. Rather than flattening these differences into a single aggregate number, the report uses regional segmentation to help teams evaluate where to prioritize sales investment, where to adapt packaging and pricing, and where to expect longer adoption cycles.
At the type level, the category is shaped by distinct ingredient and formulation philosophies. One segment centers on natural ingredients, another on organic ingredients, and a third on sugar-based formulations. These distinctions are not merely academic. They correspond to different consumer expectations, different labeling conversations, different cost structures, and different degrees of exposure to sugar-related regulation. The report examines how these type-based segments interact with pricing and channel strategy, enabling teams to see where formulation choices can open or close market access.
At the application level, demand splits between on-trade and off-trade environments. That division matters because the two channels differ in velocity, margin architecture, consumer experience, and brand-building mechanics. On-trade demand often hinges on service context, pairing potential, and occasion-based differentiation, while off-trade demand depends more directly on shelf visibility, package convenience, and household repeat purchase. The report’s segmentation framework helps leaders determine how to allocate effort across channels and how to adjust product and packaging decisions to fit the realities of each environment.
Because the precise regional, type, and application splits contain the kind of granular intelligence that shapes specific investment and pricing decisions, we have reserved the full breakouts for the complete study. The preview here is intentionally focused on the strategic logic of segmentation itself: the market should be managed as a set of distinct opportunity pockets, not as one blended volume line.
How to Use This Research for 2026 Strategy Formation
Executive teams can use this report in several concrete ways. For corporate strategy and business development, it provides a basis for evaluating adjacency moves, channel entry decisions, and geographic prioritization. For brand and marketing leadership, it supports flavor and portfolio decisions by connecting consumer-facing differentiation to underlying segmentation and competitive dynamics. For supply chain and procurement, it frames the input-cost and packaging issues that will affect margin planning through the end of the decade. For finance and investor-facing teams, it offers a structured growth narrative that ties market sizing to formulation, channel, and regulatory realities rather than relying on generic category optimism.
The most valuable use, however, is as a coordination tool. Craft soda strategy tends to fragment when brand, sales, procurement, and finance each interpret the market through a different lens. This report is designed to give those functions a shared map: a common view of where growth is occurring, what is driving it, and what constraints are shaping the cost and execution environment. That shared map is essential for building 2026 plans that are coherent rather than internally contradictory.
Preview Versus Full Intelligence: What Stays Behind the Curtain
This article is a strategic trailer, not the full film. It establishes the macro trajectory, the competitive architecture, the operational dynamics, and the segmentation logic that make the category strategically meaningful in 2026. It also demonstrates that the analysis is grounded in real company activity, real supply and regulatory pressure, and a market structure that rewards differentiated positioning.
What this preview does not do is release the full segmentation contours, the complete regional and application breakouts, or the detailed company-level benchmarking that forms the analytical core of the study. Those elements are deliberately held back because they are the difference between general category awareness and decision-ready intelligence. The full report transforms the framework outlined here into a detailed, actionable pack that teams can use to compare markets, test channel assumptions, assess competitive exposure, and build 2026 plans with precision.
For leadership teams planning capital allocation, portfolio adjustments, pricing reviews, or channel expansion, the complete study offers the level of specificity required to move from directional confidence to executable strategy. The preview above is intended to make one point unmistakably clear: the craft soda market is large enough, dynamic enough, and structurally differentiated enough that the right intelligence can change the quality of the decisions being made this year.
Closing Perspective
The craft soda market in 2026 is being shaped by three overlapping forces: sustained category growth, accelerating formulation and packaging pressure, and a competitive field that rewards distinctiveness over imitation. Companies that treat these forces as separate issues will likely underprice risk and overindex on a single dimension of strategy. Companies that integrate them into a single planning lens will be better positioned to choose the right markets, the right channels, and the right product architecture for durable growth.
Our Craft Soda Market research was built to support that integrated view. It combines forward-looking market sizing, segmentation logic, competitive profiling, and dynamic factor analysis into a single decision-support framework. The 6.5 percent CAGR, the progression toward a 1.03 billion USD market by 2032, and the underlying year-by-year trajectory all point to a category with real momentum. But momentum alone does not create winners. The winners will be the teams that can read the segmentation, anticipate the cost and regulatory environment, and position their offerings where demand intensity and differentiation align.
The complete report provides the detailed market intelligence required to make those choices with confidence. For executives who need to move from category awareness to actionable market strategy in 2026, that level of detail is not optional. It is the difference between participating in growth and directing it.
For detailed analysis of this topic, please visit the official page: Craft Soda Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Fuel Tanks Market to Reach $1.25B by 2032 at 3.7% CAGR
By PW Consulting, 2026-09-07
Navigating the Horizon: Strategic Imperatives in the Global Aircraft Fuel Tanks Market Through 2032
As global aviation enters a decisive phase of fleet renewal and regulatory transformation, the aircraft fuel tanks market stands at the intersection of engineering precision, supply chain resilience, and environmental compliance. For executives, procurement leaders, and strategic planners, understanding where this niche yet critical segment is heading is no longer a technical exercise. It is a boardroom imperative. Our latest comprehensive study on the Aircraft Fuel Tanks Market maps the trajectory from 2020 through 2032, offering a data-rich, operationally grounded view of how demand, innovation, and competitive forces will reshape procurement strategies and partnership architectures in the years ahead.
HFW Steel Pipe Market
The market has demonstrated consistent expansion over the past five years, driven by steady commercial fleet utilization, defense modernization programs, and the enduring requirements of business and general aviation operators. From a baseline exceeding 750 billion USD in market valuation in 2020, the sector has progressed through a series of incremental but structurally significant annual increases, reaching approximately 970 billion USD in 2025. Looking forward, the forecast period from 2026 to 2032 points to a compound annual growth rate of 3.7, positioning the market to surpass the 1.2 trillion USD threshold by the close of the decade. These figures do more than chart historical momentum. They signal a maturing ecosystem where volume growth is increasingly intertwined with performance specifications, material innovation, and regulatory readiness.
Worldwide Stirring Rod Market
The Architecture of Our Analysis
Our research framework is designed to move beyond headline economics and into the operational realities that shape sourcing decisions, capacity planning, and risk mitigation. The study delivers a multi-layered examination of the aircraft fuel tanks landscape, structured to support scenario modeling, vendor evaluation, and long-term portfolio alignment. Each chapter has been built around actionable intelligence rather than abstract commentary, ensuring that readers can translate findings into procurement roadmaps, capacity allocation strategies, and competitive positioning exercises.
Worldwide Multifunctional Wheelchair Market
What the Report Delivers
The publication combines quantitative rigor with qualitative depth, offering a suite of analytical tools that executives can deploy immediately. Key deliverables include:
- A decade-spanning historical reconstruction from 2020 through 2025, paired with a forward-looking 2026 to 2032 forecast model that captures growth inflection points, demand elasticity, and macro sensitivity variables.
- A structural breakdown of market composition across product architectures and end-use applications, highlighting how internal and external tank configurations, as well as commercial, military, and business aviation requirements, diverge in specification, certification pathways, and procurement cycles.
- A geographic assessment that maps regional demand centers, localized supply chain dynamics, and regulatory environments, helping organizations identify where capacity constraints, logistics complexity, or partnership opportunities are likely to emerge.
- An executive competition matrix that profiles the strategic positioning, technological focus, and geographic footprint of leading manufacturers, supplemented by recent market activity and service innovation case studies.
- A dedicated dynamics chapter that examines material substitution trends, sustainability mandates, certification burdens, and aftermarket service evolution, translating these forces into procurement risk indicators and time-to-market considerations.
Throughout the report, we prioritize clarity over complexity, ensuring that decision-makers can isolate the variables that matter most to their specific operating context. Rather than presenting a monolithic view, the analysis preserves the granularity required to distinguish between high-volume commercial sourcing requirements, specialized defense specifications, and lightweight optimization priorities in business aviation platforms.
Market Scale and the Growth Trajectory
The headline trajectory tells a story of steady, compounding expansion. Between 2020 and 2025, the market advanced from roughly 753 billion USD to approximately 971 billion USD, reflecting a period of consistent aviation activity, maintenance-driven replacement cycles, and incremental fleet upgrades. The 2026 forecast value of approximately 993 billion USD marks the beginning of a forward phase in which growth becomes more structurally embedded, shaped by platform modernization, material innovation adoption, and regulatory-aligned procurement adjustments.
By 2032, the market is projected to reach approximately 1.25 trillion USD. This path is not a straight line. The progression reflects interplay between aviation utilization patterns, fleet retirement schedules, defense procurement pacing, and the gradual integration of next-generation tank architectures. A 3.7 CAGR over the forecast period indicates a segment that is expanding at a measured but deliberate pace, characteristic of a market where certification cycles, engineering validation, and supply chain qualification impose discipline on the rate of change. For strategists, this profile matters: it suggests that market share gains will increasingly depend on technical differentiation, service integration, and the ability to align with emerging compliance expectations rather than on volume alone.
Segment Structure and Demand Differentiation
The market’s composition reveals distinct demand profiles that require tailored sourcing and engineering strategies. Tank architectures span external configurations, which dominate overall market volume due to their central role in commercial and large-platform applications, and internal systems, which serve specialized integration requirements across a range of aircraft types. On the application side, commercial aviation remains a substantial contributor, reflecting the scale and flight-hour intensity of airline operations. Military aviation represents a smaller but highly specification-driven segment, where crash-resistant designs, self-sealing systems, and mission-specific containment requirements create long qualification cycles and elevated technical barriers. Business and general aviation occupies a distinct middle ground, where weight optimization, customization, and service accessibility shape purchasing behavior.
In our report, these structural dimensions are explored with an emphasis on what they mean for procurement timing, supplier qualification, and risk allocation. Rather than offering isolated share figures or percentage splits, we focus on the operational implications of each segment’s demand rhythm, certification profile, and material preference. This approach enables readers to see where substitution pressures are likely to intensify, where aftermarket replacement cycles will concentrate, and where specialized engineering expertise will command premium positioning.
Geographic Footprint and Supply Chain Logic
Regional dynamics in the aircraft fuel tanks market reflect the broader geography of aerospace manufacturing, MRO infrastructure, and regulatory jurisdictions. North America, Europe, and Asia Pacific each represent significant demand centers, but they differ in the composition of platform mix, the maturity of local supplier ecosystems, and the pace at which compliance frameworks are being operationalized. Additional regional markets in Latin America and the Middle East and Africa contribute more specialized demand streams, often tied to specific fleet bases, defense programs, or growing general aviation activity.
For sourcing and partnership strategies, the geographic dimension is less about ranking share and more about understanding where qualification pathways are shortest, where logistics resilience is most vulnerable, and where localized technical support can reduce lifecycle cost. Our analysis maps these structural realities across regions, giving executives a framework to evaluate dual-sourcing feasibility, regional content targets, and the strategic value of proximity to certification authorities or major OEM assembly ecosystems.
Competitive Landscape: Strategy, Specialization, and Strategic Alliances
The competitive environment in aircraft fuel tanks is defined by a blend of established aerospace component suppliers, specialized tank manufacturers, and materials-focused innovators. Market concentration remains notable, with the top tier of players accounting for a substantial share of activity, yet the ecosystem also includes a wide range of niche participants that serve specific platform types, applications, or material technologies. This structure creates a landscape where scale advantages coexist with deep specialization, and where long-term competitiveness depends on the ability to combine engineering credibility with supply chain reliability.
Several organizations illustrate the strategic diversity within the sector. ContiTech AG has built a recognized profile in rigid and flexible fuel tank solutions for commercial and business aviation platforms, emphasizing integration and platform-specific engineering. Meggitt PLC has focused on fuel bladders, crash-resistant tanks, and self-sealing fuel systems for both military and commercial aircraft, aligning its portfolio with safety-critical and defense-oriented requirements. Safran S.A. contributes through fuel tanks, inerting systems, and full fuel management components, positioning itself across the broader fuel system value chain for commercial and military platforms. Parker Hannifin Corporation offers fuel tanks, inerting systems, and flow control technologies, integrating containment with functional system performance. Collins Aerospace develops tanks, bladders, and integrated fuel systems for OEM platforms, reinforcing its strength in aerospace-grade system integration.
GKN Aerospace supplies composite and metallic fuel tanks for commercial and military applications, drawing on advanced material processing capabilities. Aero Tec Laboratories, Inc. specializes in lightweight flexible bladder tanks and crash-resistant fuel cells for aerospace and defense, addressing weight and safety priorities simultaneously. Integral Aerospace, LLC manufactures metallic and filament-wound fuel tanks for fixed-wing aircraft across military and commercial use cases. Kautex Textron GmbH & Co. KG supplies rigid and flexible fuel tanks with an emphasis on lightweight composite designs. TI Automotive Inc. provides fuel tank systems and related containment technologies, while Magam Safety Ltd. delivers self-sealing fuel bladders and crash-resistant tanks for military aircraft. Musthane and Plastimo contribute specialized containment and tank solutions spanning marine and small aircraft applications, and Turtle-Pac focuses on custom fuel tanks and containment devices for general aviation and business jets.
Additional participants extend the ecosystem’s breadth. GEI Works supplies fuel tanks and components for aviation and industrial use, Vetus provides tanks for small aircraft and marine contexts, and IMTRA manufactures fuel tanks and related systems for commercial and general aviation. FW Aerospace GmbH concentrates on fuel tank manufacturing and integration for aircraft, Dakota Cub Aircraft, Inc. produces custom tanks for experimental and kit-built aircraft, and Vinyl Technology, Inc. manufactures fuel tanks and containers for aviation and defense. Prentex Alloy Fabricators, Inc. specializes in alloy-based fuel tanks, and The Plastic Omnium Group supplies lightweight fuel tanks using composite and polymer technologies. Collectively, these organizations reflect a market in which application specificity, material expertise, and integration capability determine competitive advantage more than volume positioning alone.
Recent Activity and the Shape of Innovation
Competitive differentiation is increasingly shaped by service innovation and operational method upgrades, not just hardware design. A notable example is Lufthansa Technik AG, which in May 2024 launched a novel chemical-free fuel tank sanitization procedure using steam cleaning and vacuum suction combined with post-treatment microbe examinations, certified for business jet maintenance. This kind of development matters because it signals a broader shift toward maintenance-friendly, environmentally conscious, and certification-aligned service practices that can influence aftermarket demand, operator preferences, and the value proposition of integrated solution providers. In our report, we examine these kinds of developments as indicators of where competitive advantage will be created through process innovation, compliance readiness, and lifecycle service differentiation.
Market Dynamics: Materials, Regulation, and the Procurement Ripple Effect
Two forces are reshaping the aircraft fuel tanks market with particular intensity: material substitution and regulatory alignment. On the material front, carbon-fiber reinforced polymer composites are increasingly used in aircraft fuel tank construction to deliver exceptional strength-to-weight ratios and corrosion resistance. By 2025, carbon-fiber composites accounted for approximately 41% of material revenues in the aircraft fuel tank segment, driven by OEM weight-reduction priorities. This shift has direct implications for sourcing, qualification, repair practices, and lifecycle cost calculations. As composite content rises, procurement teams must evaluate supply continuity for advanced materials, the readiness of manufacturing partners for composite processing, and the long-term implications for maintenance and inspection protocols.
On the regulatory side, the ReFuelEU aviation initiative mandates higher sustainable aviation fuel blending rates starting in 2026 to reduce lifecycle CO2 emissions across the aviation sector. The European Commission published the 2026 reporting list of competent authorities and economic operators in scope of ReFuelEU aviation on 23 April 2026. Although fuel tank hardware is not the direct subject of blending mandates, the regulatory environment influences operational expectations, fleet planning, and the broader sustainability narrative that shapes procurement criteria. Operators and OEMs are increasingly attuned to lifecycle emissions, process chemistry, and maintenance practices that align with broader environmental performance goals. The chemical-free sanitization approach launched by Lufthansa Technik, for example, is directly relevant in this context because it demonstrates how operational methods can support compliance-minded, sustainability-aligned service ecosystems.
Together, these dynamics create a market environment where strategic sourcing cannot be separated from technical foresight. Buyers need to understand not only current specifications, but also the direction of material adoption, the cadence of regulatory updates, and the service practices that will become standard as operators respond to environmental and operational pressures. Our report translates these dynamics into procurement-relevant indicators, helping organizations anticipate where specification changes are most likely to occur, which suppliers are best positioned to support transition requirements, and how aftermarket demand patterns may evolve as fleets adapt to new compliance realities.
Why This Study Matters for 2026 Decision-Making
The 2026 to 2032 window is not a routine forecasting period. It is a phase in which aviation markets will be shaped by simultaneous pressures: fleet renewal pacing, material and weight optimization, regulatory compliance, and the pursuit of maintenance efficiency. In that environment, aircraft fuel tanks cannot be treated as a static commodity category. They are a system-critical component whose supply, specification, and service ecosystem directly affect aircraft availability, safety assurance, and total cost of ownership.
For executives planning sourcing strategies, the study provides a structured way to evaluate supplier portfolios, assess regional supply resilience, and identify where specialized capabilities will be most valuable. For market entrants and investors, it offers a disciplined view of where concentration is meaningful, where niche positioning remains viable, and where innovation in materials, integration, or service processes can create durable differentiation. For program planners and engineering leaders, it supplies the context needed to align specification decisions with expected material trends and regulatory trajectories.
Most importantly, the report is built to support decisions that must hold up under scrutiny. It combines macro-level growth context with segment-level operational logic, profiles the strategic posture of key competitors, and integrates the recent developments and sector dynamics that will influence demand behavior over the next several years. By preserving detail where it matters and avoiding oversimplified headline splits, the analysis gives leadership teams a credible foundation for scenario planning, vendor selection, and long-range portfolio design.
Inside the Full Intelligence Package
Readers who engage with the complete study will find a comprehensive set of analytical components designed for direct application. Beyond the growth and segmentation frameworks, the report includes detailed company profiles that map operational focus, technological emphasis, and strategic posture for the core participants shaping the market. These profiles are paired with recent activity tracking, allowing decision-makers to see how suppliers are expanding capabilities, adjusting service offerings, and responding to evolving platform and compliance requirements.
The study also isolates the practical implications of material trends, particularly the growing role of carbon-fiber composites and the associated qualification, manufacturing, and maintenance considerations. It examines how regulatory developments such as ReFuelEU aviation influence the broader operating context for operators, OEMs, and service providers, even where hardware specifications are not directly mandated. And it places these factors within the competitive structure of the market, helping readers understand where concentration creates stability, where specialization creates opportunity, and where integration and service capability may become the decisive battlegrounds for share and margin.
Looking Ahead
The aircraft fuel tanks market is evolving within a demanding technical and regulatory environment, and its future will be defined by the organizations that can combine material expertise, platform integration, certification discipline, and service innovation. The growth path projected through 2032 is steady rather than explosive, which makes competitive positioning and procurement precision all the more important. In a market where scale alone does not guarantee advantage, the ability to align sourcing strategy with engineering trends and compliance expectations will separate resilient operators from the rest.
Our full study provides the depth required to navigate that environment with confidence. For executives and analysts who need more than a top-line number, the report offers a structured, evidence-based view of where the market has been, how it is composed today, and what forces will shape its next phase of development. The complete intelligence package, including detailed segmentation logic, regional context, competitor profiles, and forward-looking dynamics, is available through the source page, where readers can access the full dataset and the operational frameworks needed to translate these insights into concrete 2026 and beyond strategies.
For detailed analysis of this topic, please visit the official page: Aircraft Fuel Tanks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com