

Blogs
PW Consulting: Blood Irradiation Market Hits 63.61M USD in 2025, Projects 5.49% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Blood Irradiation Market: Navigating Growth, Regulation, and Competitive Dynamics Through 2032
The global blood irradiation market stands at a critical inflection point. As healthcare systems worldwide confront the persistent challenge of Transfusion-Associated Graft-versus-Host Disease (TA-GVHD) and the rising demand for pathogen inactivation protocols, the infrastructure supporting safe blood transfusion is undergoing decisive transformation. For executives, procurement leaders, and strategic planners operating in medical devices, healthcare services, or life sciences supply chains, understanding the trajectory of blood irradiation technology is no longer optional. It is a prerequisite for capital allocation, risk mitigation, and competitive positioning.
Worldwide Grain Silos and Ancillary Equipment Market
This article serves as a strategic preface to PW Consulting's comprehensive market research study on the blood irradiation industry. It outlines the macro-level forces shaping the sector, highlights the operational and regulatory currents driving demand, and demonstrates how our full report equips decision-makers with the granular intelligence required to act decisively in 2026 and beyond. Consistent with a trailer approach, we reserve the deepest segmentation analysis, regional revenue distributions, and detailed company benchmarking for the complete study. Here, we establish the strategic context, validate the methodology, and illustrate why this intelligence matters for your next boardroom discussion.
Three-Finger Dexterous Hand Market
Macro Trajectory and the Strategic Imperative for 2026–2032
The blood irradiation market has exhibited steady, compounding growth over the past half-decade, and our forecasts indicate that this momentum will continue through the end of the decade. Building on a base year of 2025, the market has transitioned from a phase of incremental expansion to one characterized by structural demand drivers: aging populations, increased surgical volumes, expanding blood banking networks in emerging economies, and heightened regulatory emphasis on preventing TA-GVHD and mitigating pathogen transmission risks.
Portable Ultrasound Solutions for Chronic Liver Disease Market
Historical data from 2020 through 2025 reveals a consistent upward arc. The market measured approximately 48.78 million USD in 2020 and climbed to 50.8 million USD in 2021, 53.83 million USD in 2022, and 56.56 million USD in 2023. By 2024, revenue reached 58.61 million USD, and the base year of 2025 closed at 63.61 million USD. This progression reflects more than cyclical recovery; it represents the cumulative effect of sustained procurement cycles, technology refresh programs in hospitals and blood banks, and the gradual institutionalization of irradiation as a standard safeguard in transfusion medicine.
Our forecast period, spanning 2026 through 2032, projects continued expansion with a compound annual growth rate of 5.49 percent. The market is expected to reach 66.82 million USD in 2026, followed by 70.49 million USD in 2027, 72.64 million USD in 2028, 78.05 million USD in 2029, 81.94 million USD in 2030, 88.78 million USD in 2031, and 93.35 million USD in 2032. While these figures establish the overall revenue envelope, the real strategic value lies in understanding the forces that will distribute growth unevenly across technology types, end-use settings, and geographies. Our full report deconstructs these layers so that stakeholders can identify where to invest, where to consolidate, and where to anticipate regulatory friction.
Regulatory and Standards Landscape: The 2026 Inflection
Few factors will shape procurement cycles and product roadmaps more decisively than the evolving regulatory environment. In March 2026, the U.S. Food and Drug Administration issued a proposed rule to classify blood irradiators used for TA-GVHD prevention as Class II devices subject to special controls and 510(k) requirements. This classification carries significant implications for both new entrants and incumbents. For existing devices, the proposed framework generally requires compliance within twelve months after the final rule's effective date, creating a defined but urgent window for manufacturers and healthcare providers to align their inventories, documentation, and quality systems with the new controls.
Concurrently, the FDA released a proposed order requiring premarket approval applications for blood irradiators intended to prevent metastasis in intraoperatively salvaged blood. This order mandates that such applications be filed by the last day of the 30th calendar month following the effective date of the classification. The dual-track regulatory posture — special controls for TA-GVHD prevention devices and premarket approval for metastasis-prevention applications — signals a more nuanced regulatory architecture. It differentiates use cases, imposes distinct evidentiary burdens, and will likely influence procurement preferences as hospital systems and blood centers evaluate compliance risk alongside clinical utility.
On the standards side, the 34th edition of the AABB Standards for Blood Banks and Transfusion Services, published in the 2026 AABB Publications Catalog, incorporates explicit requirements for blood irradiation and TA-GVHD prevention. As one of the most widely referenced frameworks in transfusion medicine, the updated standards will cascade into accreditation expectations, institutional policies, and vendor qualification criteria. Together, the FDA actions and the revised AABB standards create a regulatory cadence that rewards manufacturers with mature quality systems and clear technical documentation, while raising the bar for those still relying on legacy compliance postures.
Our study provides a detailed mapping of these regulatory milestones, their anticipated implementation timelines, and their downstream effects on procurement lead times, device validation costs, and market entry strategies. Readers of the full report will find scenario-based guidance that translates regulatory language into operational checkpoints.
Technology and Application Dynamics
Blood irradiation is not a monolithic category. The market encompasses distinct technological approaches, each with its own clinical rationale, operational footprint, and commercial profile. Gamma-ray systems have long been a cornerstone for TA-GVHD prevention, particularly in large hospital and blood bank settings where throughput and reliability are paramount. X-ray-based platforms have gained traction as facilities seek alternatives that reduce reliance on radioactive sources, simplifying logistics and aligning with evolving institutional safety preferences. Ultraviolet blood irradiation, while representing a smaller share of the overall devices landscape, continues to be explored for pathogen inactivation and adjunctive therapeutic applications, though its adoption pathways differ materially from those of ionizing radiation methods.
On the application side, hospitals and blood banks remain the primary deployment environments, reflecting the core clinical workflow of transfusion safety. Research institutions constitute an additional demand node, leveraging irradiation capabilities for translational studies, cellular therapy preparation, and quality assurance programs. End-user dynamics further differentiate procurement behavior: healthcare providers prioritize workflow integration and compliance readiness, research laboratories emphasize reproducibility and instrument flexibility, and other segments bring their own operational constraints and procurement cycles.
The strategic takeaway is that growth will not be uniform. Some technology segments will benefit from regulatory tailwinds and supply chain modernization, while others will face headwinds related to source material logistics, capital intensity, or competing inactivation methods. Similarly, application-level demand will diverge based on regional blood banking maturity, surgical volume trends, and research funding patterns. Our report isolates these dynamics and provides decision-makers with a clear view of which sub-segments are likely to outperform, which require defensive positioning, and where cross-segment substitution risks are material.
Competitive Landscape and Strategic Positioning
The competitive structure of the blood irradiation market is moderately concentrated, with a handful of established manufacturers holding meaningful share while a broader set of regional and specialized players compete on specification, service, and localization. Our concentration analysis indicates a CR3 of 22.4 percent and a CR5 of 27.8 percent, reflecting an environment where scale advantages exist but do not fully dictate outcomes. This structure creates both opportunities and threats: large incumbents can leverage installed-base service relationships and regulatory expertise, while smaller or regionally focused firms can compete through customization, faster deployment, and targeted clinical partnerships.
Several companies define the current competitive perimeter. Best Theratronics Ltd., based in Canada, has built a reputation around gamma-ray blood irradiation systems and services, with a clear focus on TA-GVHD prevention for hospitals and blood banks. Rad Source Technologies, Inc., in the United States, provides X-ray blood irradiation equipment and systems aimed at pathogen inactivation and TA-GVHD prevention, often serving blood centers with throughput-sensitive requirements. Gilardoni S.p.A., headquartered in Italy, supplies X-ray blood irradiation systems alongside related medical equipment, positioning itself within a broader diagnostic and therapeutic portfolio. Gamma-Service Medical GmbH, based in Germany, offers both gamma-ray and X-ray blood irradiation devices and services, providing customers with technology choice and service continuity.
JL Shepherd & Associates, also U.S.-based, manufactures blood irradiation equipment including systems and indicators tailored for blood banks, emphasizing quality assurance and operational visibility. In Asia, Shinva Medical Instrument Co. Ltd. in China supplies blood irradiation equipment and related medical devices, catering to domestic and export demand with a focus on cost-effective, scaled production. NPIC, also based in China, provides blood irradiation systems and equipment, while CIF Medical, likewise headquartered in China, manufactures blood irradiation devices and related products. Cegelec NDT-PES, based in France, supplies medical and industrial irradiation equipment, including blood irradiation systems, and leverages cross-sector engineering expertise. Hitachi, based in Japan, contributes to the category through medical irradiation equipment, including blood irradiation systems, and brings engineering scale and integration capabilities to the market.
Beyond company profiles, our study analyzes commercial tactics: pricing architectures, service contract structures, installation and training models, regulatory submission strategies, and regional partnership approaches. We examine how firms are responding to the 2026 FDA classification trajectory, how they are differentiating in a market where CR3 and CR5 values suggest room for share-shifting, and where consolidation or partnership activity is most likely to emerge. The full report includes comparative matrices and strategic grouping frameworks that allow readers to benchmark their own position and identify white space for product development, M&A, or commercial expansion.
Regional and Demand-Side Forces
Geographic distribution of demand will remain a critical variable for manufacturers, distributors, and service providers. Different regions exhibit distinct blood banking infrastructure maturity, regulatory adoption speeds, and clinical procurement cycles. In some markets, established hospital networks and centralized blood services drive steady replacement and upgrade cycles. In others, the growth story is tied to the expansion of transfusion services, the formalization of blood bank standards, and the introduction of irradiation as a default safeguard in transfusion protocols.
Demand-side dynamics also vary by setting. Hospitals prioritize reliability, integration with existing transfusion workflows, and regulatory compliance. Blood banks focus on throughput, source management, inventory control, and the ability to meet accreditation requirements efficiently. Research institutions value instrument flexibility, data integrity, and the ability to support experimental and quality control applications. These divergent priorities mean that a single product narrative rarely suffices. Successful commercial strategies increasingly rely on setting-specific value propositions, tailored service packages, and clear documentation that maps device capabilities to the compliance expectations of each stakeholder group.
Our analysis disentangles these regional and demand-side factors without relying on reductive top-line splits. Instead, we provide context-rich descriptions of procurement behavior, infrastructure constraints, and adoption catalysts that explain why certain markets advance faster than others and how companies can align their go-to-market models accordingly. The complete study offers the detailed regional and segment-level quantification that operations and strategy teams need for capacity planning, inventory positioning, and sales force deployment.
What the Full Study Delivers
PW Consulting's Blood Irradiation Market research is built for practitioners who need to move from narrative to numbers. The report is structured to support both strategic planning and operational execution. It combines macro trend analysis with segment-level quantification, regulatory mapping with commercial implications, and company profiling with competitive scenario planning. Key contents include:
- A comprehensive market size and forecast framework covering the historical period from 2020 through 2025 and the forecast window from 2026 through 2032, with revenue trajectories expressed in USD million and a consolidated CAGR that anchors the overall growth narrative.
- Segmentation analysis across technology types, application settings, end-user categories, and regional markets, enabling readers to identify where growth is concentrated, where substitution risks exist, and how demand patterns diverge by deployment context.
- A competitive landscape assessment that maps leading manufacturers, their headquarters, core offerings, and strategic positioning, supplemented by concentration metrics and an analysis of how firms are likely to compete on service, compliance, and differentiation.
- A detailed regulatory and standards review covering the 2026 FDA proposed rule and proposed order, the implementation timelines for existing and new devices, the premarket approval pathway for metastasis-prevention applications, and the updated AABB standards requirements for blood irradiation and TA-GVHD prevention.
- Scenario-based guidance that translates regulatory and standards developments into procurement implications, validation burdens, market entry considerations, and competitive responses.
- Commercial and operational intelligence relevant to product planning, capacity allocation, service strategy, pricing, and partnership or M&A evaluation.
The study is designed to be referenced, not merely read. It provides the inputs that strategy teams need for market entry assessments, the data that finance teams need for revenue planning, and the compliance context that quality and regulatory teams need for submission and audit preparedness. By integrating demand-side, supply-side, and regulatory perspectives into a single framework, the report helps stakeholders avoid the common mistake of treating market growth as a uniform trend and instead plan for a market that is diversifying in technology, applications, and geography.
How to Use This Intelligence in 2026
For executives and planners, the immediate value of this research lies in its ability to convert uncertainty into a structured set of decisions. In the near term, 2026 is a year in which regulatory clarity will improve but implementation pressure will intensify. Companies that map their device portfolios against the proposed FDA classification and the AABB standards can anticipate documentation gaps, schedule validation activities, and communicate realistic lead times to customers. Healthcare providers and blood banks that understand the classification distinctions can align procurement cycles with compliance timelines, reducing the risk of last-minute substitutions or service interruptions.
Over the medium term, the 2026–2032 forecast horizon offers a framework for capacity and investment decisions. A CAGR of 5.49 percent, applied to a market that grows from 66.82 million USD in 2026 to 93.35 million USD in 2032, provides a directional anchor, but the strategic advantage comes from knowing which technology and application segments will contribute most to that growth and which will lag. Manufacturers can use this insight to prioritize R&D, shape service offerings, and target geographic expansion where infrastructure and standards adoption are most favorable. Distributors and service providers can align inventory and staffing with regional demand patterns and regulatory-driven replacement cycles. Investors and corporate development teams can use the concentration metrics and company profiles to identify acquisition targets, partnership opportunities, and segments where share consolidation is plausible.
The report also supports defensive planning. In a market where regulatory change, standards updates, and source management considerations can shift procurement preferences quickly, the ability to model compliance costs, anticipate substitution dynamics, and benchmark against peer strategies is a tangible advantage. Our study provides the structure needed to run these scenarios with discipline rather than intuition.
Closing Perspective
The blood irradiation market is entering a phase in which growth, regulation, and competition will interact more tightly than in previous years. The 2026 regulatory actions in the United States, the updated AABB standards, and the broader global emphasis on transfusion safety will raise the operational bar for all participants. At the same time, the underlying demand drivers — aging populations, expanding transfusion services, pathogen inactivation requirements, and institutional adoption of irradiation as a standard safeguard — will continue to pull the market upward. The companies and organizations that thrive will be those that can navigate this intersection with clear data, realistic timelines, and differentiated commercial strategies.
This article has outlined the strategic context and the macro trajectory, but the detailed segmentation numbers, regional revenue distributions, application-level demand splits, and company-level comparative benchmarks are reserved for the full study. That is by design. The complete report is where the intelligence becomes actionable: where high-level trends are converted into segment-specific growth estimates, where regulatory language is mapped to validation and procurement steps, and where competitive positioning is quantified against real market structure. For decision-makers who need to move from awareness to execution in 2026 and beyond, the full Blood Irradiation Market research from PW Consulting provides the depth, structure, and operational relevance required to act with confidence.
For detailed analysis of this topic, please visit the official page: Blood Irradiation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Automated Passenger Counting and Information System Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
From 2020 to 2025, the Asia-Pacific automated passenger counting and information system market exhibits robust momentum—reaching USD 700 Million in 2025. Fueled by infrastructure modernization and sustainability imperatives, annual revenue is anticipated to climb steadily, surpassing USD 2,100 Million by 2035. Surging government investments and the proliferation of IoT and cloud-based solutions indicate sustained multi-year expansion, positioning Asia-Pacific as a cornerstone market globally.
Buses remain the primary application segment for automated passenger counting and information systems, accounting for the largest market share in 2025. This dominance is driven by extensive investments in city bus fleets and efforts to improve operational efficiency and safety. Airports and metro transit systems are rapidly escalating their adoption, reflecting ongoing smart city initiatives and a focus on enhancing the commuter experience. Trains, ferries, and other modes follow as multi-modal integrations become more prevalent across regions.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-automated-passenger-counting-and-information-system-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Automated Passenger Counting and Information System Market industry?
The top five players in the Asia-Pacific Automated Passenger Counting and Information System Market are Eurotech, DILAX, iris-GmbH, Cisco Systems, and Hitachi. These companies offer advanced technologies for accurate passenger counting, real-time analytics, and integrated passenger information systems, driving innovation and competitiveness across public transportation networks in the region.
What is the Asia-Pacific Automated Passenger Counting and Information System Market growth?
The Asia-Pacific market is witnessing substantial growth, projected to sustain a CAGR above 15% through 2027. Recent adoption of real-time data solutions by operators like SMRT Corporation has enhanced efficient resource allocation, reflecting strong regional investments in smart transportation amid rising urban mobility needs.
Which segment accounted for the largest Asia-Pacific Automated Passenger Counting and Information System Market share?
Public transport buses accounted for the largest share in the Asia-Pacific market. Widespread deployment of automated passenger counting and real-time information systems in city buses is driven by the growing urban population and smart city initiatives, which prioritize efficient public transport operations and better passenger experience.
Thanks & Regards,
priya
sales@bussinessinsights.com
The Asia-Pacific Micro Server IC Market demonstrates robust year-on-year growth, expanding from USD 2,100 Million in 2020 to projections of over USD 11,950 Million by 2035. This evolution is underpinned by widespread digitization, cloud adoption, and edge computing proliferation. Growth rates accelerate post-2025, reflecting broader deployment of AI-driven analytics and IoT services, especially in developed markets such as China, Japan, and Australia. Strategic investments from global and regional vendors into APAC-specific infrastructure and tailored server IC solutions are key contributors to the upward trajectory.
Read More - https://bussinessinsights.com/research-report/asia-pacific-micro-server-ic-market
Data centers constitute the largest application segment for micro server ICs in the Asia-Pacific region, reflecting ongoing expansion of hyperscale and enterprise facilities. Cloud computing applications closely follow, benefiting from scalable and efficient micro server deployments. Edge computing is emerging rapidly as smart city, industrial IoT, and autonomous infrastructure demand low-latency, localized compute. This distribution underscores the versatility of micro server ICs in powering next-generation, decentralized computing environments and their strategic role in supporting digital transformation across industries.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-micro-server-ic-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Micro Server IC Market industry?
Key players in the Asia-Pacific micro server IC market include Intel Corporation, Advanced Micro Devices (AMD), Nvidia Corporation, Marvell Technology Group, and Qualcomm Inc. These companies are known for their innovation, advanced IC product lines, and strategic partnerships, driving adoption of efficient, scalable micro server architectures across data centers and cloud solutions.
What is the Asia-Pacific Micro Server IC Market growth?
The Asia-Pacific Micro Server IC market has experienced robust growth, largely due to rising cloud adoption and data center expansion. For instance, in 2023, AMD reported significant revenue increases in Asia-Pacific, attributed to its EPYC server processors, which have seen strong demand from hyperscale data center providers across the region.
Which segment accounted for the largest Asia-Pacific Micro Server IC Market share?
The data center application segment accounted for the largest share of the Asia-Pacific Micro Server IC Market. This is driven by the booming cloud computing landscape, with expanding needs for efficient, scalable, and high-density server solutions to support large-scale enterprise, AI, and analytics workloads in APAC countries.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific smart greenhouse market is poised for remarkable revenue growth, with values projected to rise from USD 1,050 million in 2020 to approximately USD 5,450 million by 2035. The sharp upward trend is driven by technological adoption, policy support, and large-scale agri-investments, notably in China, India, and Southeast Asia. As governments promote sustainable agriculture and food security, market revenue is expected to grow at a CAGR of 14.8% between 2025 and 2035. This surge reflects rising adoption across hydroponic farms, sensor-based controls, and vertical farming setups, positioning the region at the forefront of next-generation agriculture.
Read More - https://bussinessinsights.com/research-report/asia-pacific-smart-greenhouse-market
The dominant application segment in 2025 is vegetables, accounting for 44% of the market share, reflecting high demand for year-round, pesticide-free produce in urbanized regions. Flowers and ornamentals hold 27%, leveraged by flourishing export markets and premium domestic sales, followed by fruit plants at 13%. Nursery crops and others collectively comprise 16%, encapsulating research, educational, and specialty applications. Innovative technologies in climate and light control enable tailored environments for diverse crops, contributing to improved quality and profitability. The segmental breakdown demonstrates the market's core focus on food production, while highlighting expanding opportunities in specialty and high-value horticulture.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-smart-greenhouse-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Smart Greenhouse Market industry?
Key players in the Asia-Pacific Smart Greenhouse Market include Netafim, Certhon, Richel Group, Heliospectra AB, and Rough Brothers Inc. These companies are recognized for their advanced automation solutions and greenhouse management technologies, enabling higher crop yields and efficiency through innovative climate control, irrigation systems, and remote monitoring platforms.
What is the Asia-Pacific Smart Greenhouse Market growth?
The Asia-Pacific Smart Greenhouse Market has witnessed rapid growth, driven by rising demand for sustainable agriculture. For instance, Netafim pioneered new irrigation automation solutions in 2023, supporting increased adoption and fueling market expansion with a CAGR estimated at over 12% during the forecast period.
Which segment accounted for the largest Asia-Pacific Smart Greenhouse Market share?
The hydroponics segment accounted for the largest market share in the Asia-Pacific Smart Greenhouse Market. Hydroponic systems allow efficient use of resources, reduced water consumption, and higher productivity, making them highly popular for smart greenhouse applications, especially in countries like China, Japan, and Australia.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Geotechnical Instrumentation and Monitoring Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific GIM market is projected to grow from USD 640 Million in 2020 to USD 2,120 Million by 2035, demonstrating a strong compound annual growth rate fueled by increased infrastructure spending, regulatory compliance demands, and expanding urbanization. The steepest year-on-year growth is anticipated from 2025 onwards, correlating with massive government investment programs and upgraded technological adoption, especially in China, India, and Southeast Asia.
Tunnels & Bridges constitute the dominant application segment in 2025, with complex urban projects and expanding transport corridors necessitating robust geotechnical monitoring. Buildings & Utilities are increasingly adopting monitoring solutions to ensure structural safety, especially in seismically active regions. Dams also represent a key segment, as governments invest in upgrading monitoring protocols for water management infrastructure.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-geotechnical-instrumentation-and-monitoring-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Geotechnical Instrumentation and Monitoring Market industry?
The top 5 players in the Asia-Pacific Geotechnical Instrumentation and Monitoring Market are Fugro, Keller Group, Geokon, Sisgeo, and Sixense. These companies possess advanced technologies, offer comprehensive geotechnical solutions, and maintain significant projects across infrastructure, mining, and construction sectors throughout the Asia-Pacific region.
What is the Asia-Pacific Geotechnical Instrumentation and Monitoring Market growth?
The Asia-Pacific Geotechnical Instrumentation and Monitoring Market is witnessing strong growth, with recent reports indicating a CAGR of over 8%. Growth is driven by increasing infrastructural developments, such as the Metro Rail projects in India and Southeast Asia, with companies like Fugro expanding their service capabilities.
Which segment accounted for the largest Asia-Pacific Geotechnical Instrumentation and Monitoring Market share?
Infrastructure applications, particularly tunnel and bridge monitoring, accounted for the largest market share. With rapid urbanization and government investments in large-scale infrastructure projects across countries like China, India, and Australia, demand for advanced geotechnical monitoring solutions has surged in this segment.
Thanks & Regards,
Priya
sales@bussinessinsights.com
PW Consulting: Human Rabies Immunoglobulin Market Estimated at $758M by 2032, CAGR 5.5%
By PW Consulting, 2026-09-07
# Strategic Intelligence in a Critical Niche: The Human Rabies Immunoglobulin (IM) Market Outlook 2026-2032
Executive Overview
In the landscape of global public health infrastructure, few therapeutic categories hold as much immediate consequence as Human Rabies Immunoglobulin (IM). While often overshadowed by the broader vaccine market, the immunoglobulin segment represents a critical bottleneck in post-exposure survival rates. As we move into 2026, the market stands at a inflection point where supply chain resilience, regulatory shifts, and clinical efficacy standards are converging to redefine competitive advantage.
Pharmaceutical Grade Povidones Market
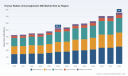
PW Consulting is pleased to introduce our comprehensive market research report on the Human Rabies Immunoglobulin (IM) Market. This document is not merely a collection of statistics; it is a strategic asset designed for executive decision-makers, investment analysts, and supply chain leaders. Our analysis spans historical performance from 2020 through 2025 and projects forward through 2032. The data reveals a market that has demonstrated resilience despite global disruptions, culminating in a total revenue value of approximately 527.5 Million USD by the base year 2025, with a projected trajectory toward 758.0 Million USD by 2032.
Garden Sweepers Market
For stakeholders operating in this space, understanding the velocity of this growth is essential. The report details a compound annual growth rate (CAGR) of 5.5 percent over the forecast period. This moderate yet steady expansion underscores a stable demand environment driven by consistent exposure risks and standardized prophylactic protocols. However, aggregate numbers only tell half the story. The strategic value lies in dissecting the underlying dynamics that fuel this growth, identifying where supply meets demand, and anticipating the regulatory headwinds that could alter market access.
Preformed Crowns for Deciduous Teeth Market
The Macroeconomic Trajectory of Immunoglobulin Demand
Historical Performance and Stabilization
The historical data from 2020 to 2025 indicates a market that has recovered from early pandemic-era irregularities. After reaching 450.63 Million USD in 2022, the market experienced slight fluctuations before stabilizing and accelerating toward the 2025 mark. This stabilization suggests that supply chains for plasma-derived products have matured, reducing the volatility seen in other therapeutic sectors. The jump from 479.6 Million USD in 2024 to 527.5 Million USD in 2025 highlights renewed confidence in procurement processes globally.
Looking forward, the forecast period from 2026 to 2032 outlines a clear path of accumulation. Starting at 538.0 Million USD in 2026, the market is expected to cross the 700 Million USD threshold by 2030. This growth is not linear but punctuated by periods of acceleration that correlate with regulatory approvals and shifts in healthcare funding. For strategic planners, this trajectory implies that capacity investments made today will align with significant revenue opportunities within the next five years.
Growth Drivers and Clinical Necessity
The fundamental driver of this market remains unchanged: the lethality of rabies necessitates immediate and effective post-exposure prophylaxis. Unlike elective treatments, rabies immunoglobulin is a emergency intervention. This inelastic demand profile provides a floor for revenue that protects the market from severe downturns. However, growth is increasingly tied to efficiency improvements and geographic expansion rather than solely on volume increases. The industry is shifting toward high-potency formulations that allow for smaller injection volumes, improving patient compliance and reducing administration time.
Furthermore, the integration of immunoglobulin into broader rabies management protocols continues to evolve. Recent guidance updates from health security agencies in various regions have emphasized efficient use during heightened demand periods. These operational insights are critical for manufacturers and distributors who must balance inventory levels against unpredictable exposure incidents. Our report dives deep into how these clinical guidelines influence procurement cycles and inventory management strategies for hospitals and public health bodies.
Regional Landscape and Supply Chain Dynamics
While specific regional revenue figures are reserved for the full dataset within our paid report, the broader geographic narrative is one of distinct maturity levels and growth potentials. The market is divided across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents a unique set of challenges regarding plasma sourcing, regulatory approval timelines, and reimbursement models.
In developed markets, the focus is often on supply chain security and the assurance of continuous availability. Regulatory bodies have clarified the status of supply adequacy. For instance, recent communications from the Centers for Disease Control and Prevention as of July 2025 indicated that no human rabies immunoglobulin shortage exists in the United States. This assurance allows clinicians to focus on protocol adherence rather than scarcity management. However, for manufacturers, maintaining this level of supply security requires robust logistics and inventory buffering, which impacts operational costs.
Conversely, emerging regions face different dynamics. Access to high-quality immunoglobulin remains a priority, and the growth potential in these areas is significant as healthcare infrastructure improves. The Asia Pacific and Latin American markets, for example, are characterized by increasing awareness and better integration of rabies prophylaxis into national health strategies. Our analysis explores how tiered pricing, distribution partnerships, and local regulatory hurdles shape market entry strategies in these zones.
Supply chain integrity also depends on the raw material foundation. The production of these immunoglobulins relies heavily on plasma from donors hyper-immunized with rabies vaccines. This dependency creates a specialized upstream link that requires careful management. Recent industry communications from January 2025 highlighted this manufacturing basis for key products, emphasizing the need for consistent donor programs. Any disruption in plasma sourcing can ripple through the entire value chain, making supplier diversification a key strategic consideration for large-scale producers.
Competitive Landscape and Key Player Positioning
The Human Rabies Immunoglobulin market is moderately concentrated, with a significant portion of revenue attributed to established multinational pharmaceutical entities. Our report analyzes the strategic positioning of key companies that define the competitive boundaries. Understanding the product portfolios and operational footprints of these players is essential for benchmarking and competitive strategy.
Sanofi Pasteur
Based in Cambridge, Massachusetts, USA, Sanofi Pasteur remains a cornerstone player in the rabies prophylaxis space. The company manufactures Imogam Rabies-HT, a standard human rabies immunoglobulin formulation with a concentration of 150 IU/mL. Their long-standing presence in the market provides a benchmark for clinical reliability and distribution reach. For competitors, matching Sanofi's supply consistency and clinical acceptance is a primary challenge. Strategic analysis suggests that Sanofi's integrated approach to vaccine and immunoglobulin delivery strengthens their position in hospitals requiring comprehensive prophylaxis kits.
Grifols Therapeutics
Grifols Therapeutics, headquartered in Barcelona, Spain, competes with a focus on high-potency solutions. Their product, HyperRab, offers a concentration of 300 IU/mL for passive post-exposure prophylaxis. A key strategic advantage noted in recent industry materials from 2026 is the ability of this high-potency formulation to enable smaller injection volumes for the standard 20 IU/kg rabies immunoglobulin dose. This feature addresses clinical pain points related to administration volume and patient comfort, potentially driving preference in specific clinical settings. Grifols' strategy highlights the market trend toward product differentiation based on formulation efficiency.
Kedrion Biopharma and Kamada Ltd.
Kedrion Biopharma, based in Rome, Italy, operates in partnership with Kamada Ltd. to manufacture KEDRAB, another 150 IU/mL human rabies immunoglobulin for passive post-exposure prophylaxis. This partnership model illustrates the collaborative nature of plasma-derived therapeutics, where manufacturing capabilities are often shared or licensed to optimize reach. The commercial performance of this franchise has been notable. Recent financial disclosures from June 2026 indicated that KEDRAB sales reached over 70 Million USD in 2025, establishing it as a leading franchise for Kamada.
This revenue milestone underscores the commercial viability of specialized immunoglobulin products when supported by strong plasma sourcing and regulatory compliance. For investors and partners, the KEDRAB case study provides a template for how niche biologics can achieve significant scale through focused marketing and reliable supply.
Regulatory and Operational Shifts Shaping 2026 and Beyond
Regulatory Approvals and Testing Capabilities
Regulatory frameworks are tightening and evolving to ensure safety and efficacy. A significant recent development occurred in June 2026, when Kamada Ltd. received FDA approval for a new in-house Rapid Fluorescent Focus Inhibition Test (RFFIT) laboratory. This facility is dedicated to rabies virus neutralization testing. The implication for the market is twofold: it enhances quality control capabilities for the manufacturer, and it potentially reduces turnaround time for testing required for regulatory compliance. For the broader industry, this signals a trend toward greater in-house testing control, reducing reliance on external laboratories and potentially speeding up batch release processes.
Guidance and Utilization Protocols
Operational guidance plays a crucial role in how products are consumed. In June 2025, the UK Health Security Agency issued interim recommendations for the efficient use of HRIG following increased demand after a human rabies exposure incident. Such guidance updates can instantly alter procurement patterns and hospital stocking behaviors. Our report analyzes the ripple effects of these guidance changes, helping strategists anticipate similar shifts in other regions. Understanding the cadence of regulatory communication allows companies to prepare supply responses that align with public health priorities without overstocking or creating waste.
Reimbursement and Market Access
Reimbursement landscapes vary significantly by region and influence the adoption speed of specific products. In markets where reimbursement is streamlined, premium products with higher potency or better administration profiles may gain traction faster. In contexts with tighter budget controls, cost-effectiveness becomes the primary decision criterion. The report examines the reimbursement dynamics affecting immunoglobulin access, highlighting how pricing strategies must align with payer expectations to sustain market share. The success of products reaching over 70 Million USD in annual sales suggests that there is room for premium positioning when clinical value is clearly demonstrated and supported by payer coverage.
Strategic Implications for Decision Makers in 2026
As we navigate the forecast period from 2026 to 2032, several strategic imperatives emerge for stakeholders in the Human Rabies Immunoglobulin market. First, supply chain resilience must be prioritized. The absence of current shortages does not guarantee future stability. Manufacturers and distributors must maintain buffer stocks and diversified sourcing to mitigate risks associated supply dependencies or sudden demand spikes following exposure incidents.
Second, product differentiation will become increasingly important. As the market grows toward 758.0 Million USD by 2032, competition for shelf space and clinical preference will intensify. Innovations that reduce injection volume, improve stability, or streamline administration offer avenues for differentiation. Companies that can demonstrate clear clinical or operational advantages, such as the high-potency options enabling smaller volumes, will be better positioned to capture value.
Third, regulatory engagement is critical. With testing capabilities expanding and guidance documents evolving, staying ahead of compliance requirements is a competitive moat. Investments in testing infrastructure, such as the RFFIT laboratory developments, indicate a commitment to quality that resonates with regulators and healthcare providers alike. Strategic foresight involves anticipating these regulatory needs and preparing capabilities before they become mandatory.
Finally, market intelligence must be granular. Aggregate growth rates mask the nuances of regional performance and segmentation dynamics. To make informed decisions, leaders need access to detailed breakdowns that reveal where growth is concentrated and which application areas are driving volume. The strategic value of this report lies in its ability to provide that granularity without overwhelming the reader with noise.
Conclusion and Access to Full Intelligence
The Human Rabies Immunoglobulin (IM) Market represents a vital component of global health security, characterized by steady growth, specialized production requirements, and a competitive landscape dominated by experienced pharmaceutical players. The transition from a 527.5 Million USD market in 2025 to a projected 758.0 Million USD by 2032 offers substantial opportunities for those who can navigate the operational and regulatory complexities of the space.
However, the macro trends discussed here only scratch the surface of what is required for successful strategic execution. To truly capitalize on the 5.5 percent CAGR and optimize portfolio decisions, stakeholders need access to the underlying data that drives these conclusions. PW Consulting's full market research report provides the comprehensive depth required for high-stakes planning.
The complete report includes detailed segmentation analysis across regions and types, precise market size estimates for all forecast years, and in-depth competitive profiling. It also contains specific scenarios regarding supply chain vulnerabilities and reimbursement shifts that are not outlined in this overview. For executives and analysts who require actionable intelligence to guide investment, production, and distribution strategies in 2026 and beyond, accessing the full dataset is essential.
We invite you to review the complete findings and leverage our proprietary data to inform your strategic roadmap. The full intelligence is available via the PW Consulting market research portal, where you can download the comprehensive report and integrate these insights into your decision-making process.
For detailed analysis of this topic, please visit the official page: Human Rabies Immunoglobulin (IM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Electronic Shelf Labels Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
Asia-Pacific ESL market revenue is projected to accelerate from USD 780 Million in 2021 to an estimated USD 2,650 Million by 2035, reflecting strong penetration across retail and logistics sectors. The CAGR over this period is driven by continuous innovation in e-paper technology and increasing digital transformation efforts among APAC retailers. China, Japan, and South Korea contribute the lion’s share due to early adoption and large-scale rollouts, while India and Southeast Asia emerge as high-growth markets.
Read More - https://bussinessinsights.com/research-report/asia-pacific-electronic-shelf-labels-market
Retail remains the core application segment for ESLs in the Asia-Pacific, accounting for the largest market share in 2025, driven by the need for automated pricing and in-store digitization. Supermarkets & Hypermarkets continue to expand their ESL footprint, while industrial and warehousing applications see significant uptake for inventory and process management. The growth in commercial and warehouse uses reflects broader adoption beyond traditional retail, as businesses seek efficiency and real-time visibility across supply chains.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-electronic-shelf-labels-market
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific high power LED market revenue is forecast to surge from $6,120 million in 2020 to $18,430 million by 2035, reflecting a strong CAGR over the projection period. Key drivers include expanding adoption across end-use sectors like automotive, general, and industrial lighting, alongside technological advancements and declining product costs. Strategic government policies around energy efficiency and sustainability continue to underpin market expansion. China, India, and Japan contribute the majority of revenues, followed by growing markets in Vietnam, South Korea, and Australia.
Read More - https://bussinessinsights.com/research-report/asia-pacific-high-power-led-market
Automotive lighting is the leading application segment in the Asia-Pacific high power LED market, representing 35% of the total share in 2025. General lighting follows, driven by ongoing government-led initiatives for smart and energy-efficient cities. Backlighting for displays and digital signage also contributes significantly, as electronics manufacturing expands in countries like China and South Korea. The surge in automotive manufacturing, coupled with higher adoption of advanced digital screens, underpins rapid growth in these segments. LEDs' performance advantages—such as longevity, energy savings, and compact footprint—are reinforcing their preference over traditional counterparts.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-high-power-led-market
Frequently Asked Questions
Who are the key players in Asia-Pacific High Power LED Market industry?
The Asia-Pacific High Power LED Market is led by companies such as Nichia Corporation, Osram Opto Semiconductors, Seoul Semiconductor, Samsung Electronics, and Cree Inc. These firms are renowned for their innovation, extensive LED product ranges, and strategic partnerships, significantly shaping market growth and technological advancements in the region.
What is the Asia-Pacific High Power LED Market growth?
The Asia-Pacific High Power LED Market is experiencing robust growth, driven by increased adoption in automotive, industrial, and street lighting applications. For instance, Samsung Electronics recently saw a significant sales uptick due to government smart city initiatives and the expansion of energy-efficient infrastructure across key Asia-Pacific markets.
Which segment accounted for the largest Asia-Pacific High Power LED Market share?
The general lighting segment held the largest market share in the Asia-Pacific High Power LED Market. The surge in demand for energy-efficient solutions in residential, commercial, and industrial lighting applications has propelled this segment, thanks to stringent government policies, urbanization, and the rapid adoption of smart lighting systems.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Tunnel Monitoring System Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific Tunnel Monitoring System market revenue is projected to show strong growth between 2020 and 2035. In 2025, revenues are estimated at USD 1,220 Million, with a steady CAGR anticipated through 2035 due to increased infrastructure investments and technology adoption. The rise is primarily supported by new tunnel construction, upgrades of existing tunnels, and the integration of resilient monitoring solutions. Market expansion is particularly significant in China, India, and Southeast Asia, where government support for smart infrastructure is robust. By 2035, market revenues are forecasted to surpass USD 3,980 Million, reflecting widespread digitization and urbanization trends across the region.
Read More - https://bussinessinsights.com/research-report/asia-pacific-tunnel-monitoring-system-market
Railway tunnels lead the Asia-Pacific Tunnel Monitoring System market by application in 2025, driven by massive investments in high-speed and metro rail networks across the region. Highway tunnels also account for a substantial share due to growing vehicular traffic and the need for efficient cross-city connectivity. Mining tunnels, though a smaller portion, require specialized monitoring solutions for safety, ensuring constant market demand in resource-rich countries such as Australia and China. The trend reflects the region’s ongoing efforts to modernize critical infrastructure and improve urban mobility.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-tunnel-monitoring-system-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Tunnel Monitoring System Market industry?
Key players in the Asia-Pacific Tunnel Monitoring System Market include Siemens AG, Geokon, SICK AG, Nova Metrix, and HBM. These companies lead the sector by offering advanced monitoring solutions, innovative sensor technologies, and comprehensive data analytics for tunnel safety, infrastructure health, and real-time system diagnostics.
What is the Asia-Pacific Tunnel Monitoring System Market growth?
The Asia-Pacific Tunnel Monitoring System Market is witnessing robust growth, driven by large-scale infrastructure projects in China and India. For example, Siemens AG recently reported increased demand for its digital tunnel solutions as governments prioritize tunnel safety, leading to higher adoption rates and market expansion across the region.
Which segment accounted for the largest Asia-Pacific Tunnel Monitoring System Market share?
The 'Roadway Tunnel' application segment holds the largest market share in the Asia-Pacific Tunnel Monitoring System Market. This dominance is due to massive investments in highway and metro tunnel construction, where monitoring systems are crucial for ensuring safety, structural integrity, and efficient traffic management across urban regions.
Thanks & Regards,
Priya
sales@bussinessinsights.com
PW Consulting: Cellulose Powder Market Hits $190M in 2025, Projected 5.48% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Horizons for the Cellulose Powder Market: Navigating Growth Through 2032
The global demand for cellulose powder has evolved from a niche functional ingredient to a cornerstone of modern formulation strategy. As industries increasingly prioritize clean labels, texture optimization, and stable supply chains, understanding the trajectory of this market has become a critical component of executive planning. This latest market research publication offers a comprehensive, data-driven roadmap for stakeholders seeking to align their portfolios with the structural shifts shaping the cellulose powder landscape from 2026 through 2032.
Worldwide Propionitrile Market
A Decade of Resilient Expansion and the 2026 Inflection Point
Historical performance provides the most reliable foundation for forward-looking strategy. Tracking demand from 2020 through 2025, the market demonstrated consistent upward momentum, beginning at approximately 148.0 million USD and advancing steadily to an estimated 190.0 million USD by the base year of 2025. This growth curve reflects a compounding acceleration rather than isolated price spikes or temporary demand surges, signaling a mature yet expanding ecosystem where cellulose powder has secured indispensable roles across multiple value chains.
Worldwide LED Rechargeable Power Tool Flashlight Market
The projection for 2026 opens at roughly 197.57 million USD, marking a practical inflection point where short-term operational planning must give way to multi-year capacity and product-mix decisions. Over the seven-year forecast horizon extending to 2032, the market is expected to reach 276.0 million USD, underpinned by a compound annual growth rate of 5.48 percent. This growth trajectory is neither speculative nor overly aggressive; it is anchored in recurring application demand, formulation innovation, and regulatory frameworks that continue to validate cellulose-derived ingredients as safe, functional, and increasingly preferred in consumer-facing products.
Worldwide Acrylic Impact Modifier (ACR) Market
For corporate strategists, the significance of this trajectory lies less in any single annual figure and more in the cadence of expansion. The interval between 2026 and 2029 represents a period of intensifying competition, regional capacity realignment, and formulation repositioning. The latter half of the forecast period, from 2030 to 2032, suggests a phase where scale advantages, differentiated grades, and supply reliability become decisive. Decisions made in 2026—whether regarding procurement contracts, capacity investment, distribution partnerships, or product development pipelines—will echo through the subsequent seven years of market evolution.
Structural Demand Drivers: Beyond Volume Growth
The projected expansion of the cellulose powder market is not merely a function of population growth or generic industrial consumption. It is being reshaped by a convergence of technical, regulatory, and consumer-driven dynamics that reward early movers with defensible market positions. Several structural forces deserve strategic attention as decision-makers interpret the full research publication.
Formulation complexity continues to rise across food and beverage portfolios. Manufacturers are seeking functional ingredients that can modulate texture, improve mouthfeel, act as anti-caking agents, and support fiber fortification without compromising flavor or stability. Cellulose powder, in its various grades, answers these requirements with a versatility that few alternative excipients can match. As clean-label mandates tighten and consumers scrutinize additive lists, the ability to position cellulose-based solutions as natural, functional, and compliant becomes a competitive differentiator rather than a baseline expectation.
Regulatory clarity is simultaneously reinforcing market confidence. International standards have long permitted powdered cellulose under good manufacturing practice conditions, providing a stable baseline for global trade. Yet the regulatory environment remains dynamic, with ongoing consultations and labeling adjustments that influence sourcing, documentation, and formulation transparency. Companies that internalize the implications of these evolving frameworks can reduce compliance risk, accelerate product launches, and build stronger relationships with regulators and downstream buyers alike.
Supply chain resilience has also emerged as a strategic priority. The post-pandemic emphasis on reliable sourcing, inventory buffering, and multi-origin procurement has transformed cellulose powder from a simple commodity into a strategically managed input. Buyers are increasingly evaluating not only price per unit but also batch consistency, technical support, documentation rigor, and the ability of suppliers to scale in response to seasonal or regional demand variations. In this environment, suppliers with transparent quality systems and established technical service capabilities gain measurable advantages in retention and contract renewal.
Segmentation Dynamics: Mapping Opportunities Without Over-Committing to Single Narratives
The full research publication maps the market across multiple segmentation lenses, enabling readers to identify where growth is concentrated and where competitive intensity is shifting. Rather than relying on superficial volume assumptions, the analysis isolates the structural logic behind each segment, helping organizations prioritize commercial focus, R&D investment, and partnership strategies.
By material type, the market includes distinct categories of cellulose-derived ingredients that serve overlapping yet differentiated functions. Microcrystalline cellulose occupies a prominent position due to its functional versatility in food, beverage, and pharmaceutical contexts. Its role as a texturizer, stabilizer, and bulking agent continues to drive broad adoption, and variations in particle size, moisture content, and processing refinement create sub-markets with differing value propositions. Alongside this dominant segment, other specialized cellulose grades and related compounds address specific performance needs, including flow improvement, anti-caking functionality, and targeted application compatibility. The research highlights how type-level segmentation informs procurement strategy, especially when manufacturers are balancing performance requirements against cost structures and supply availability.
Application segmentation reveals where dollar value is being generated and which use cases are expanding most rapidly. Food and beverage formulations represent a substantial share of demand, consistent with the ingredient’s established role in processed foods, beverage stability, and fiber-enriched products. Pharmaceutical applications constitute another significant demand pool, where cellulose-based excipients support tablet binding, compression, and controlled functional performance. Personal care applications, while smaller in absolute terms relative to food and pharma, are gaining attention as formulators explore natural texture modifiers and functional additives for creams, powders, and specialty products. The report examines these application pathways without oversimplifying them, recognizing that each vertical carries distinct purchasing criteria, regulatory expectations, and formulation constraints.
Geographically, the market reflects uneven but complementary demand hubs. Mature markets in North America and Europe continue to anchor volume and value, supported by established food manufacturing bases, stringent quality norms, and long-standing supplier relationships. Asia Pacific represents a growth-intensive region, where expanding production capacity, evolving food processing infrastructure, and rising consumer demand are reshaping regional consumption patterns. Latin America and the Middle East and Africa contribute additional complexity, with growth trajectories that depend on local manufacturing development, import dynamics, and food system modernization. The full research publication avoids flattening these regional differences into a single average, instead offering readers the analytical tools to evaluate where regional advantages, risks, and partnership opportunities are most relevant to their own footprints.
Competitive Landscape: Strategic Positioning Among Leading Players
Market growth of this scale does not occur in an undifferentiated vacuum. The cellulose powder landscape is shaped by manufacturers that combine production capability, grade specialization, technical service, and regional presence to secure competitive positioning. The research publication profiles the core companies driving supply and illustrates how their strategies intersect with broader market dynamics.
Sigachi Industries Limited, headquartered in Hyderabad, India, has established itself as a major global producer with a strong orientation toward food-grade microcrystalline cellulose and cellulose powder grades. Its emphasis on food and beverage applications positions it within a high-volume demand environment where functional consistency and application support matter greatly to buyers. The company’s scale advantages and grade breadth make it a relevant benchmark for understanding how manufacturers compete on both cost efficiency and application-specific performance.
J. Rettenmaier & Söhne GmbH + Co. KG, based in Rosenberg, Germany, brings a well-recognized portfolio through its VITACEL® line. Its powdered cellulose and microcrystalline cellulose offerings are optimized for food-grade use, particularly as anti-caking agents and texture modifiers in processed foods and beverages. This positioning reflects a strategy grounded in formulation-specific functionality and brand trust, which is especially valuable in markets where ingredient traceability and functional reliability are closely scrutinized.
Asahi Kasei Corporation, operating from Tokyo, Japan, supplies food-grade microcrystalline cellulose and cellulose powder for beverage and food formulations, with emphasis on bulking and stabilizing applications. Its role in the competitive field illustrates how large, diversified material manufacturers extend their reach into specialty functional ingredients, leveraging process expertise and global delivery capability to serve multinational formulation requirements.
DFE Pharma, with operations in Göttingen, Germany, focuses on food-grade cellulose powder and microcrystalline cellulose for food and beverage use, emphasizing purity and performance in processed applications. Its profile highlights the competitive importance of quality assurance and application precision, particularly for buyers whose end products depend on tight specifications and consistent batch behavior.
Roquette Frères, based in Lestrem, France, provides microcrystalline cellulose and cellulose powder grades certified for food and beverage use, supporting texture and functional needs in packaged foods. The company’s participation underscores how European producers maintain strong relevance through certification, application orientation, and integration with broader plant-based ingredient ecosystems.
Ankit Pulps and Boards Pvt. Ltd., situated in Ahmedabad, India, produces MICCEL-P powdered cellulose derived from pure alpha cellulose for food industry applications, including anti-caking and dietary fiber fortification. This specialized positioning demonstrates how regional manufacturers can build competitive niches through feedstock selection, product naming, and targeted application messaging that align with specific buyer needs.
International Fiber Corporation, located in Tonawanda, New York, USA, supplies food-grade powdered cellulose and cellulose-based ingredients for cheese and other processed foods as anti-caking agents. Its application-focused offering reflects a more narrowly defined but commercially valuable segment, showing that competitive relevance is not limited to broad-scale producers but also extends to suppliers with highly tailored use-case expertise.
Taken together, these companies illustrate a competitive environment that is moderately concentrated yet functionally diverse. Market concentration data within the research indicates that the top three players account for approximately 24.6 percent of market share, while the top five reach about 26.2 percent. This structure suggests that no single entity dominates the entire market, leaving meaningful room for differentiated positioning, regional strength, and application specialization. For buyers and investors alike, this means competitive strategy cannot rely on assuming a single price setter or supplier monopoly; instead, it requires careful evaluation of grade fit, service capability, and supply reliability across multiple credible sources.
Regulatory and Compliance Forces Reshaping Market Behavior
Regulatory developments are not peripheral considerations; they actively shape sourcing, documentation, formulation decisions, and market timing. The research publication integrates the most consequential regulatory signals affecting cellulose powder and related food-contact or food-additive applications, helping decision-makers anticipate operational adjustments rather than merely react to them.
One important backdrop is the established permitting of powdered cellulose as a food additive under the General Standard for Food Additives, with use governed by good manufacturing practice conditions. This standard provides a stable foundation for international trade and formulation planning, but it also implies that manufacturers and suppliers must maintain rigorous process control and documentation consistency. Compliance is not a one-time certification event; it is an ongoing operational requirement that reinforces the value of suppliers with transparent quality systems.
In parallel, China’s National Health Commission has published a draft national standard for food contact regenerated cellulose materials, open for consultation through June 2026. This development matters because it can influence material specifications, testing expectations, and sourcing logic for products that intersect with cellulose-based food contact applications. Stakeholders with exposure to Asian supply chains or regional distribution networks should monitor how this consultation evolves, since final standards can affect qualification timelines and material substitution decisions.
On the labeling and disclosure side, the FDA’s uniform compliance date for certain final food labeling regulations published between January 1, 2025 and December 31, 2026 is set for January 1, 2028. This timing has practical consequences for packaging, labeling claims, and documentation workflows. For companies using cellulose powder in consumer-facing formulations, label alignment is not merely an administrative task; it affects claim substantiation, ingredient listing clarity, and the speed at which reformulated or repositioned products can reach market. The research publication situates these regulatory milestones within the broader commercial environment so that readers can integrate compliance planning into product strategy and procurement timing.
What the Full Report Enables: From Strategic Question to Operational Decision
This market research is designed to move beyond high-level commentary and provide actionable intelligence for multi-functional teams. While the overview presented here establishes the strategic backdrop, the full publication delivers detailed, structured content that supports concrete decision-making across commercial, supply chain, R&D, and investment functions.
Readers can expect a systematic mapping of market size and growth patterns across historical and forecast periods, giving planning teams the baseline needed to test scenarios rather than rely on intuition. The segmentation analysis offers a framework for assessing which material types, applications, and regional pathways are most relevant to specific business objectives. Rather than presenting raw figures in isolation, the report connects them to operational implications, helping users determine where to concentrate sales efforts, where to evaluate supplier diversification, and where to prioritize product development resources.
The competitive profiles and market concentration context allow procurement and strategy teams to benchmark supplier landscapes, assess dependency risk, and identify where technical service or grade differentiation may justify partnership selection beyond price alone. For organizations evaluating market entry, expansion, or acquisition, the research provides the analytical scaffolding needed to ask sharper questions about demand durability, competitive overlap, and the realistic pace of adoption in different end-use segments.
Equally important, the regulatory sections bring compliance considerations into the same view as commercial analysis, enabling leaders to coordinate product planning, documentation, and sourcing decisions without treating regulatory change as a separate workstream. In practice, this integration helps reduce the likelihood of misaligned launches, delayed qualification processes, or sourcing choices that later require costly rework.
Strategic Implications for 2026 Decision-Makers
The cellulose powder market entering 2026 presents a rare combination of stability and opportunity. The growth trajectory is robust enough to justify investment and long-term planning, yet the market remains segmented and competitively diverse enough to reward organizations that make informed, targeted choices. For executives and analysts, the central challenge is not whether the market is expanding, but how to position within that expansion in a way that aligns with portfolio goals, risk tolerance, and operational capabilities.
Procurement leaders should use the full research to evaluate supplier options not just on unit economics, but on grade breadth, application support, documentation reliability, and regional service reach. Product developers can build formulation strategies around the functional versatility of cellulose powder, especially where texture, anti-caking performance, and fiber positioning matter to downstream customers. Commercial teams can identify which application segments offer the best balance of demand scale and competitive differentiation, while avoiding overexposure to areas where commoditization or supplier concentration could compress margins. Investors and corporate development teams can use the concentration data and company profiles to assess where consolidation, regional expansion, or capability acquisition may create value relative to the broader market structure.
Finally, regulatory planning should be embedded early in the decision cycle. The consultation processes and compliance timelines relevant to cellulose-based ingredients and food-contact contexts can influence sourcing choices, qualification schedules, and label readiness. Companies that incorporate these factors into their 2026 planning will be better positioned to protect timelines, reduce rework, and preserve credibility with both regulators and end customers.
Why the Full Study Matters Now
Market intelligence is only as valuable as its relevance to the decisions pending on the desk. The cellulose powder market is at a stage where broad directional knowledge is useful, but decisive advantage comes from understanding how size, segmentation, competition, and regulation interact in practice. This research publication is built for that purpose: to give strategists, analysts, and commercial leaders a coherent foundation for planning through 2032 without relying on speculation or incomplete snapshots.
The overview provided here captures the strategic logic and the scale of the opportunity, but the full study goes further. It delivers the structured detail, comparative context, and operational framing needed to convert market awareness into procurement confidence, product strategy, and investment discipline. For organizations preparing for 2026 planning cycles, accessing the complete research will make the difference between short-term reaction and longer-term advantage.
For detailed analysis of this topic, please visit the official page: Cellulose Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com