

Blogs
The Role of Digital PTW in Safer, More Efficient Work Management
Many organizations still approach the permit to work (PTW) process as a procedural requirement that needs to be completed before a job can begin. In many situations, permits are treated mainly as evidence that company procedures, regulatory expectations, or audit requirements have been satisfied. While compliance remains important, treating PTW simply as documentation overlooks the wider value the process can provide. When supported by an effective digital platform, permit to work can become a practical operational system for planning, coordinating, and controlling high risk activities.
A modern PTW solution establishes a structured workflow for planning, reviewing, approving, carrying out, and recording critical work. Rather than depending on separate procedures and disconnected records, organizations can create consistent processes, define responsibilities, minimize variation, and reduce avoidable delays. This structure becomes especially useful for organizations managing several facilities, where safety standards and operational practices need to remain aligned across different locations. It can support activities ranging from hot and cold work to confined space entry, electrical isolation, and simultaneous operations.
The Role of a Permit to Work System
A permit to work system provides formal authorization for specific activities and confirms that essential conditions have been considered before work starts. Before an activity begins, relevant hazards should be identified, associated risks assessed, and necessary controls verified. Following this sequence creates a structured approach for protecting employees, equipment, other assets, and the surrounding environment.
PTW also helps establish a shared understanding among everyone involved in the activity. Supervisors, permit requesters, approvers, and field personnel can access key information about the job, including the work involved, its location, responsible individuals, and the period during which authorization remains valid. Keeping these details organized and accessible improves coordination and lowers the likelihood of confusion while work is underway.
When managed digitally, PTW can move beyond being a group of individual documents. It can function as an integrated workflow where permits connect with isolation information, gas testing results, inspections, and supporting checklists. Bringing related records into one process helps reduce misplaced paperwork, incomplete information, and delays created when separate systems do not communicate effectively.
How Digital PTW Systems Improve Efficiency
Paper based permit processes can consume significant administrative time and often introduce unnecessary bottlenecks. Employees may have to search for physical documents, obtain multiple signatures, repeatedly enter the same information, or wait for one approval before moving to the next stage. In addition to slowing operations, these manual activities can increase the likelihood of omissions, inconsistencies, and errors.
Digital PTW platforms can address these issues by bringing together automation, standardized workflows, and immediate visibility into the current status of permits.
Key advantages include:
- Centralized work management: Permits, risk assessments, isolation information, and gas testing records can remain together, allowing authorized users to locate and review required information more easily.
- Faster approval workflows: Requests can be automatically directed to the appropriate personnel, while alerts and notifications can reduce unnecessary waiting between stages.
- Real time operational visibility: Supervisors can see permits awaiting approval, activities in progress, completed work, and tasks experiencing delays. Field personnel can also see which activities have received authorization.
- Fewer errors and less rework: Automated checks can identify missing information, expired qualifications, or incomplete lockout/tagout requirements before a permit moves forward for approval.
Key Features of an Effective Digital PTW Platform
An effective digital permit to work platform should do more than place a paper form onto a computer screen. It should manage the complete permit lifecycle while incorporating appropriate safety controls directly into the workflow.
- Standardized Permit Templates
Organizations can create predefined templates for recurring activities such as hot work, confined space entry, excavation, electrical tasks, and work at height. Consistent templates help ensure that required precautions, questions, and verification activities are applied consistently across comparable jobs.
- Embedded Risk Management Controls
Integrated risk assessment features, required safeguards, and questions based on working conditions can guide users through identifying and evaluating hazards before work begins. A structured assessment process can promote a more consistent and thorough approach to risk management.
- Isolation and Lockout/Tagout Integration
Permit workflows can incorporate isolation information, equipment conditions, lockout activities, tagging requirements, and verification steps within the same process. Connecting these elements makes isolation activities easier to coordinate, track, and manage consistently.
- Simultaneous Operations Management
When multiple activities are taking place in the same area, visibility into overlapping work can help teams identify potential conflicts before activities begin. This improves coordination between concurrent jobs and supports better management of interactions between different work activities.
- Competency and Qualification Verification
Automated checks can help determine whether assigned workers have the required training, certifications, and qualifications for particular activities. This supports the assignment of specialized or higher risk work to personnel with the appropriate qualifications.
- Mobile Access for Field Teams
Field personnel should have access to relevant digital PTW functions through mobile devices while performing work. Depending on the platform, users may approve permits, capture and attach photographs, record gas testing information, or document toolbox talks directly from the work area. Offline functionality can also be valuable at remote locations or where network connectivity is unreliable.
- Audit and Reporting Capabilities
Detailed audit trails, reliable timestamps, and comprehensive reports can provide greater visibility into permit performance. These capabilities can also make compliance reviews and audit preparation easier by allowing records of decisions, approvals, and activities to be accessed and examined efficiently.
A Four Step Approach to PTW Implementation
Implementing a digital PTW platform requires more than installing software. Organizations also need practical processes, clear expectations, and employee involvement to make the system part of everyday operations and deliver sustainable results.
Step 1: Establish Standardized Processes
Create consistent permit templates, approval routes, and governance practices that can operate across facilities. At the same time, these standards should provide enough flexibility to accommodate legitimate site specific requirements when differences are necessary.
Step 2: Prioritize High Risk Work Activities
Start with activities where stronger controls can deliver immediate value, such as hot work and confined space entry. Focusing initially on higher risk categories can help organizations establish effective safety and operational controls during the early implementation period.
Step 3: Connect PTW with Existing Operations
Link permit management with related processes such as maintenance planning, asset information, and shift handovers. Connecting these activities can reduce repeated data entry, improve information sharing, and create a smoother flow of information between teams and departments.
Step 4: Use Practical, Scenario Based Training
Training should reflect the situations employees encounter during normal operations rather than focusing exclusively on software functions. Scenario based exercises give users an opportunity to practice applying the platform to realistic work situations. Tracking adoption and relevant performance measures can then highlight areas where additional support or process improvement may be required.
Evaluating the Effectiveness of Digital PTW
A significant advantage of digital permit management is the ability to assess process performance through operational data. Organizations can monitor indicators such as:
- Average time between permit submission and approval
- Percentage of permits receiving the correct approval during the initial review
- Number of simultaneous operations conflicts identified before work begins
- Corrective actions raised while permits are active and the time taken to close them
- Reduction in audit time and effort resulting from complete, searchable records
These measurements provide practical evidence of how the permit process is operating. They can also highlight areas that may require additional attention, changes, or further process improvement.
Turning PTW Data into Continuous Improvement
When permit approvals, actions, changes, and verification activities are captured automatically, PTW can provide value far beyond basic safety and compliance requirements. The information generated through the process can become a useful source of operational insight.
Analyzing this information can help organizations identify repeated approval delays, safeguards that are frequently overlooked, and areas where employees may need additional training. The information can also reveal opportunities to improve procedures or introduce stronger engineering controls. Over time, these insights can contribute to continuous improvements in workplace safety and operational efficiency.
A digital permit to work system should therefore be understood as more than paperwork that needs to be completed before a task starts. When implemented properly, it can become a proactive framework for managing work. It can provide stronger control over high risk activities, support safer execution, improve productivity, reinforce accountability, and transform permit information into operational insight that supports continuous improvement across the organization. It can also give decision makers clearer visibility into the status of work at every stage, allowing teams to respond to issues earlier and maintain a more predictable flow of authorized activities without depending on repeated manual follow up across busy operations, changing conditions, different facilities, and each working shift.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=How-a-permit-to-work-system-improves-efficiency-(and-safety)
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Refinery-tank-farms-management:-the-digital-imperative-for-safety-and-profit
https://toolkitx.com/blogsdetails.aspx?title=What-is-a-Confined-Space-Entry-Permit-A-Simple-Guide
Digital Hot Work Permits: Improving Safety, Control, and Compliance
Hot work is routinely required during construction, maintenance, repairs, fabrication, and many other industrial and commercial operations. Activities such as welding, grinding, brazing, torch cutting, and soldering can generate intense heat, open flames, sparks, or molten material. When proper precautions are missing, these ignition sources can introduce significant hazards. A task that appears straightforward can quickly turn into a serious event when sparks contact combustible materials or enter an atmosphere that is not safe for hot work.
For this reason, hot work permits continue to serve as an important safety control. They create a formal checkpoint before work starts, giving teams an opportunity to identify hazards, verify precautions, and assign responsibilities. As organizations modernize their safety processes in 2026, many are moving away from paper-based permits and adopting digital hot work permit systems. These solutions can provide greater visibility, consistency, and efficiency while preserving the controls required for potentially high-risk activities.
What Is a Hot Work Permit?
A hot work permit is a formal authorization required before carrying out activities that generate heat, sparks, or flames in locations that have not been permanently approved for hot work. The permit process is intended to verify that relevant hazards have been assessed, appropriate safeguards have been put in place, and everyone involved understands their responsibilities before the work begins.
The permitting process may involve several individuals, including the person responsible for issuing the permit, the worker carrying out the hot work, and the designated fire watch. Each participant has defined duties that contribute to maintaining safe conditions throughout the activity.
A permit should not be viewed simply as paperwork that must be completed. It functions as a temporary risk control designed around a particular task, location, and period of work. When safety decisions reflect actual conditions at the worksite rather than assumptions, the process can help limit exposure to fires, explosions, and other dangerous situations.
Why Hot Work Permits Matter
Industrial and commercial environments may contain combustible substances, flammable products, enclosed locations, hidden hazards, and other conditions that can make an ignition source particularly dangerous. A properly controlled hot work permit process gives organizations a structured method for recognizing these conditions and deciding which safeguards are necessary.
Preventing Fires and Explosions
Sparks, molten metal, radiant heat, and other hot work byproducts can travel beyond the immediate work area. Combustible materials can also begin to smolder without being noticed and may eventually develop into a fire after the task has ended. A well-managed permit process helps verify that combustible materials have been identified, atmospheric checks have been completed when necessary, and appropriate barriers or shielding are available to limit ignition hazards.
Defining Responsibility
A completed permit should make it clear who requested the work, who approved it, who is carrying out the activity, and who has responsibility for watching for potential fire hazards. Establishing these roles in advance can reduce uncertainty, prevent important duties from being missed, and improve coordination among everyone involved in the job.
Supporting Compliance and Traceability
Completed permits create a record showing that hazards were reviewed and necessary controls were established before work commenced. Such documentation can support inspections, audits, investigations, and incident reviews. It also demonstrates that the organization used a defined process where safety decisions, approvals, and responsibilities were recorded.
Creating Consistent Safety Standards
Organizations with multiple facilities frequently depend on both employees and contractors. Applying a consistent permitting method helps establish similar expectations across different workplaces. Standardized processes can minimize variations between sites, departments, and workforce groups while giving everyone a common approach for managing hot work hazards.
Key Elements of an Effective Hot Work Permit
Permit formats can vary from one organization to another, but an effective hot work permitting process normally addresses several essential areas.
- Task and Location Information
The permit should explain the work being carried out, identify the precise location, list relevant equipment, and state the period for which the authorization is valid. Clear information helps ensure that the permit remains limited to the approved task and designated work area.
- Hazard Assessment
Potential hazards should be reviewed before work starts. This assessment can cover combustible materials, flammable gases or vapors, accumulated dust, nearby equipment, and concealed or enclosed locations where sparks or heat might travel. Identifying these conditions beforehand helps determine which controls are appropriate for the specific job.
- Preparing the Work Area
Where reasonably possible, combustible materials should be removed from the work zone. When removal cannot be achieved, safeguards such as fire-resistant barriers and protective shielding should be used. Depending on the activity and surrounding conditions, further measures may involve equipment isolation, drain protection, or lockout/tagout procedures.
- Atmospheric Testing
Where a hazardous atmosphere may be present, relevant gas testing details should be captured on the permit. Information can include oxygen readings, lower explosive limit (LEL) results, and measurements for toxic substances. Recording the results alongside testing times and reviewer details provides clearer documentation that atmospheric conditions were evaluated.
- Required Safety Measures
The permit should identify the safeguards needed for the particular hot work activity. Based on site conditions, these may involve ventilation, methods for containing sparks, fire extinguishers, fire-resistant blankets, and continuous monitoring by a fire watch.
- Authorization and Approval
Individuals responsible for issuing and receiving the permit should be identified through the required approvals, signatures, and contact details. This creates a clear authorization path and makes it easier to determine who holds responsibility during the work.
- Fire Watch Duties
The designated fire watch should monitor the work area while hot work is underway and continue observing the area after the activity has stopped. Depending on the organization's procedures, post-work monitoring may continue for 30 to 60 minutes to help identify delayed ignition, concealed heat, or materials that may still be smoldering.
- Closing the Permit
The permit should be formally closed only after the work area has been inspected. The final inspection should confirm that equipment has cooled, combustible hazards have been dealt with, and the area is appropriate for normal operations to resume.
The Move Toward Digital Hot Work Permits
More organizations are moving from traditional paper permits toward digital permitting solutions. This transition is not simply about eliminating paperwork. Digital workflows can also address several challenges created by manual forms, physical signatures, and documentation that is separated across different systems or locations.
Structured Workflows and Required Information
Digital permit platforms can require important information to be entered before a request is allowed to move forward. Mandatory fields and controlled workflows can reduce incomplete applications and make it more difficult for essential safety checks or verification steps to be accidentally skipped.
Faster Approvals
Supervisors, safety teams, and contractors can review permit requests using mobile devices rather than waiting for paper forms and physical signatures to move between individuals. This can shorten approval delays while enabling authorized personnel to review and approve requests closer to the location where work will actually take place.
Better Gas Testing Oversight
Gas test information can be connected directly to the relevant permit and stored automatically with timestamps. Digital systems can also provide reminders when another test is needed or when a permit is nearing its expiration, helping teams maintain greater awareness of testing and authorization requirements.
More Reliable Location Verification
Digital mapping and geo-tagging functions can help teams confirm the location where authorized hot work is being performed. They can also provide greater visibility into surrounding hazards and other activities taking place nearby, helping workers understand the conditions around the designated work area.
Automated Compliance Controls
Digital permitting platforms can build predefined safety requirements directly into the approval process. If a required condition has not been satisfied, the workflow can stop the permit from progressing or send the exception to an authorized individual for review and appropriate action.
Easier Access to Historical Records
Digital permit information is typically easier to locate, search, and review than large collections of paper documents. Organizations can use historical records to recognize repeated deviations, recurring patterns, higher-risk areas, and potential opportunities to strengthen safety practices.
Consistent Contractor Management
A centralized digital permitting process can apply the same basic expectations to contractors and internal employees across different locations. This can reduce reliance on printed forms, scanned paperwork, and disconnected email-based approval procedures while creating a more unified approach to hot work authorization.
Best Practices for Implementing a Digital Hot Work Permit
Introducing digital permitting gradually can make the transition easier to manage than attempting to change every process simultaneously.
- Start with a standardized permit structure and add site-specific requirements only where they are genuinely necessary.
- Define clear approval routes and establish backup arrangements for weekends, night shifts, and other periods outside normal operating hours.
- Focus first on digitizing essential records, such as permit forms, gas testing information, fire watch documentation, and supporting photographs.
- Provide practical, role-specific training so employees and contractors understand how the system should be used during everyday operations.
- Test the process through a pilot lasting several weeks, collect feedback from users, and make improvements before expanding the system to additional locations.
- Introduce connections with other safety and operational platforms gradually instead of trying to integrate every system during the first stage of implementation.
Hot work will continue to present inherent hazards involving ignition, heat, sparks, and fire across many industries and working environments. These hazards can be managed more effectively when organizations combine a structured permitting process with appropriate protective measures. A well-designed digital hot work permit system can strengthen visibility, accountability, and consistency when high-risk activities are being controlled. By bringing established safety practices together with efficient digital workflows, organizations can reinforce compliance, reduce operational exposure, and carry out hot work with greater control, confidence, and efficiency.
Read more about this article @ https://toolkitx.com/blogsdetails.aspx?title=Hot-work-permit:-definition,-requirements,-and-practical-guide-to-going-digital
Browse More
https://toolkitx.com/campaign/certificate-management/
https://toolkitx.com/campaign/log-books/
https://toolkitx.com/campaign/hse/
How EHS Audits Improve Safety, Compliance, and Accountability
Organizations often realize they need a more structured safety approach when everyday operations become consumed by urgent corrections, rushed documentation, and reactions to incidents that have already taken place. An Environmental, Health & Safety (EHS) audit can restore discipline by providing a structured method to evaluate performance, establish accountability, and promote consistency. A properly planned audit is more than a recurring compliance check. It examines whether defined expectations are actually being followed, relies on objective evidence to identify weaknesses, and helps determine corrective steps that can reduce operational risk. Today, organizations increasingly need to demonstrate performance rather than simply communicate intentions. Leaders require reliable documentation, clear visibility into corrective actions, and proof that earlier findings have truly been addressed. EHS software can support this process by providing an organized system for managing, documenting, and monitoring the complete audit lifecycle.
Audits and Inspections: Different Roles Within EHS
Although audits and inspections both support workplace safety and compliance, they serve different purposes within an EHS program.
An EHS audit evaluates how well an organization's management system is operating. It considers policies, procedures, controls, and documented processes to determine whether they satisfy internal expectations and applicable external requirements. An inspection focuses more directly on daily workplace conditions. It examines factors such as equipment condition, employee behavior, housekeeping, and how work is actually performed.
A strong EHS program requires both approaches. Inspections provide a snapshot of conditions and behaviors at a particular point in time, while audits evaluate whether the systems intended to control those conditions are working properly. Together, they create a continuous improvement cycle in which observations become findings, findings result in corrective actions, and completed actions are subsequently checked to confirm that the solution remains effective and sustainable.
Defining an Audit Scope That Matters
The value of an audit depends heavily on how its scope is defined. When an audit is excessively broad, poorly structured, or missing clear priorities, it can become a paperwork focused exercise that produces extensive documentation while failing to address the organization's most important risks. Effective planning ensures that available time and resources are directed toward areas where an audit can deliver meaningful improvement.
Common audit categories include:
- Compliance audits that evaluate adherence to requirements associated with permits, emissions, waste management, and water related responsibilities.
- Management system audits that examine frameworks such as ISO 14001 and ISO 45001, including operational controls, employee competency, risk management, incident response, corrective action processes, and management review activities.
- Program audits that concentrate on higher risk activities, including contractor management, lockout/tagout (LOTO), confined space entry, and hot work controls.
- Environmental audits that assess hazardous material management, waste handling, spill prevention, reporting preparedness, and applicable environmental responsibilities.
The objective is to direct audit attention toward areas presenting the greatest potential exposure and consequence, rather than selecting subjects simply because the supporting documentation is easy to collect.
Strengthening Audit Credibility With Requirement Mapping
Audit findings become more meaningful when they are directly connected to defined requirements. Connecting observations with specific regulations, standards, or internal expectations reduces uncertainty and establishes a more consistent foundation for evaluating performance.
ISO 14001 focuses on environmental risk, impact evaluation, operational control, and emergency preparedness. ISO 45001 addresses auditing effectiveness, auditor competency, hazard identification, risk assessment, and operational controls that can include contractor management, permit systems, management of change, and lockout/tagout programs.
Organizations conducting OSHA oriented reviews commonly examine areas such as hazard communication, machine guarding, personal protective equipment, lockout/tagout, confined spaces, electrical safety, hot work, fall protection, and other fundamental workplace safeguards.
Traceability is essential to a dependable audit process. Every finding should establish a clear relationship between the evidence gathered, the requirement being assessed, and the corrective action necessary to resolve the deficiency. With that relationship established, leadership can understand the reason behind an action and identify what must be done to move the organization toward compliance.
Seven Steps for a Consistent EHS Audit
EHS auditing delivers greater value when it follows a repeatable process supported by clear methods and consistent discipline.
- Define the Audit Purpose and Boundaries
Start by establishing why the audit is being conducted, which facilities, activities, or operations will be reviewed, and which qualified individuals will perform the audit. Areas involving greater risk and operations that have recently changed should receive appropriate additional attention.
- Complete the Preparation Work
Before entering the field, collect and review information relevant to the audit. This can include procedures, permits, training records, maintenance documentation, incident investigations, risk assessments, monitoring data, and records of previous corrective actions. Providing the audit schedule in advance can also give personnel adequate time to prepare.
- Conduct Field Observations and Interviews
Evaluate actual operations rather than relying solely on written documentation. Observe significant activities, gather objective evidence, and speak with employees responsible for performing or supervising the work. Interviews may involve operators, supervisors, contractors, maintenance staff, and EHS personnel.
- Review Evidence and Classify Findings
Use a consistent and clearly defined approach when evaluating observations. When determining the significance of a finding, consider both the potential severity of the outcome and the likelihood that it could occur. Nonconformities can then be classified according to the relevant requirements.
- Develop Reports That Drive Action
A useful audit report should allow decision makers to quickly understand what needs attention and why it matters. It typically outlines the audit scope and methodology, recognizes areas of strength, identifies significant risks, presents supporting evidence, assigns responsibility, and establishes expected completion dates. Effective reporting prioritizes clarity and practical decision making instead of unnecessary detail.
- Implement Corrective and Preventive Measures
Every significant deficiency should result in a clearly defined response. Depending on the issue, corrective measures may involve revising procedures, expanding training, strengthening permit controls, improving lockout/tagout execution, or introducing additional engineering controls.
- Verify Closure and Sustainability
The audit is not complete simply because the final report has been delivered. Organizations must verify that corrective actions were completed and produced the intended outcome. Management oversight can help track progress, while trend analysis can identify whether similar problems continue to appear over time.
Measuring Audit Performance With KPIs
The success of an audit program should be measured by the improvements it generates, not simply by the number of audits completed. Appropriate performance indicators can help determine whether corrective actions are effectively resolving identified issues.
Useful metrics can include the average time required to close findings, the percentage of high priority findings completed within their deadlines, the frequency of recurring deficiencies, and the number of corrective actions that remain overdue.
Leading indicators can provide another layer of visibility. Examples include the percentage of risk assessments completed before work begins and confirmation that required training has been completed before permits are approved.
Regularly reviewing these measures helps organizations shift their perspective from treating audits as routine compliance activities to using them as practical tools for improving overall performance.
Critical Areas Within an EHS Audit Program
A comprehensive EHS audit should examine the controls, practices, and management systems that have the greatest impact on safety performance.
Important areas can include leadership participation, governance, risk management, employee training and competency, permit to work procedures, lockout/tagout controls, incident investigations, emergency preparedness, contractor management, machine guarding, chemical management, industrial hygiene, personal protective equipment, environmental compliance, and corrective action effectiveness.
Auditors can also examine housekeeping practices, ergonomic hazards, document management, evidence retention, document version control, and the security of organizational records.
Turning Audit Findings Into Sustainable Improvements With EHS Software
The true value of an audit becomes apparent in how an organization responds once a problem has been identified. Teams require a dependable method for correcting deficiencies, confirming that solutions work, and reducing the possibility of the same issues returning. Modern EHS software can connect audit findings with practical follow through by creating a structured system for managing improvement activities.
Corrective actions can be monitored and automatically escalated when deadlines are missed. Permit requirements can be reviewed before work begins, lockout/tagout activities can be checked in the field, maintenance tasks can be created for critical equipment, procedures can be revised through controlled workflows, and refresher training can be assigned when requirements change or gaps are identified.
Maintaining these activities within secure and traceable records provides organizations with dependable evidence for future audits while maintaining accountability throughout the corrective action process. The result is more than a record of problems discovered during an audit. Organizations can demonstrate that deficiencies were addressed, corrective measures were verified, and appropriate steps were taken to reduce the possibility of recurring issues.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=EHS-audit-(2025-guide):-definition,-checklist,-process,-and-ISO/OSHA-mapping
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Why-manual-excel-sheets-are-silently-draining-your-tank-farm%27s-profitability
The South Korea Industrial Robotics Market comprehensive study reveals that South Korea—already globally renowned for maintaining the highest industrial robot density per capita—is experiencing a monumental structural shift. Accelerated by acute labor shortages, rapid demographic aging, and national manufacturing modernization policies, the market is on track to scale aggressively through the forecast period.
Key Findings from the Report
-
Market Valuation & Growth Trajectory: The South Korea Industrial Robotics Market was valued at USD 422.10 million in 2025 and is projected to reach USD 968.69 million by 2032, expanding at a CAGR of 12.60%.
-
Base Year & Forecast Period: The report establishes 2025 as the base estimation year, with comprehensive tracking and forecasts mapped through the 2026–2032 period.
-
Dominant Segment by Type: Articulated and traditional stand-alone robots continue to dominate revenue shares, powered by heavy-duty requirements in automobile spot-welding, heavy metal fabrication, and continuous structural handling.
-
Fastest-Growing Segment: Collaborative robots (cobots) emerge as the fastest-growing category, thriving on safety features that enable side-by-side deployment with human operators in cramped assembly layouts.
-
Leading End-Use Vertical: The Electrical & Electronics sector secures the largest market revenue share, spearheaded by continuous micro-component placement, semiconductor wafer handling, and PCB automated manufacturing.
-
Regional Hub Concentration: The Seoul Capital Area and the Southeastern Yeongnam industrial belt lead regional adoption, anchoring critical automotive and semiconductor manufacturing clusters.
-
Investment & Capital Dynamics: Venture capital and corporate funding are increasingly pivoting toward software-defined robotics, smart factory analytics, and indigenous component localization to minimize supply chain vulnerabilities.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/south-korea-industrial-robotics-market/2946
Market Drivers and Restraints
Drivers
-
World-Leading Robot Density & Factory Automation Mandates: South Korea consistently leads global metrics in robot density per 10,000 industrial employees. Government-backed initiatives, such as the Korean New Deal and smart factory deployment subsidies, heavily incentivize automated infrastructure upgrading.
-
Accelerated Demographic Aging & Shrinking Labor Pool: A rapidly aging workforce and declining birth rates have created persistent structural labor deficits across manufacturing sectors, forcing employers to automate core operations to maintain continuous output.
-
Technological Convergence (AI and IoT Integration): The embedding of AI-driven vision systems, adaptive path-planning, and real-time IoT diagnostic monitoring allows robots to handle complex, unstructured tasks with minimal human intervention.
Restraints
-
High Initial Capital Expenditure (CapEx): Advanced multi-axis industrial robots, integrated safety enclosures, and custom software integration impose heavy upfront financial burdens, deterring cash-constrained SMEs.
-
Complex System Integration & Maintenance Hurdles: Deploying heterogeneous automation architectures requires specialized system integrators and rare technical expertise, leading to potential deployment bottlenecks and operational downtime risks.
Technology, Regulation, and Sustainability Trends
The latest market evaluation highlights a definitive shift toward cognitive manufacturing and ESG-aligned operations . Modern South Korean facilities are increasingly implementing energy-efficient servo drives and lightweight composite materials to lower the carbon footprint of robotic assembly lines.
On the regulatory front, stringent workplace safety laws—such as South Korea’s Serious Accidents Punishment Act—are accelerating the replacement of hazardous, manual material-handling tasks with fail-safe automated systems. Concurrently, technological evolution is moving past rigid programming; edge-AI enabled robots can now autonomously recalibrate upon detecting micro-defects, drastically reducing material waste and supporting corporate circular-economy targets.
Regional Insights
-
Seoul Capital Area (Leading Region): Retains its status as the prime commercial and technological engine, heavily driven by high concentrations of electronics headquarters, R&D labs, and advanced precision engineering units.
-
Yeongnam Region (Southeastern Industrial Core): Dominates heavy industrial applications. Home to major automotive and shipbuilding clusters in cities like Ulsan, Busan, and Changwon, this region commands massive deployment of heavy-payload articulated and SCARA robots.
-
Hoseo & Honam Regions (Emerging Pockets): Witnessing accelerated adoption due to regional provincial grants designed to decentralize smart manufacturing and uplift local automotive-part suppliers and chemical processing plants.
Recent Industry Developments
-
Doosan Robotics (2025): Launched an advanced AI-powered collaborative robot series equipped with enhanced tactile feedback, successfully securing major deployment contracts across electronics assembly plants in North Asia and driving a 24% boost in operational line-speed efficiency.
-
Hyundai Motor Group (2025): Integrated an advanced fleet of autonomous mobile robots (AMRs) and automated guided vehicles (AGVs) at its Metaplant smart manufacturing ecosystem, cutting internal component transfer times by 31%.
-
Samsung Electronics (2024): Partnered with domestic automation developers to launch completely lights-out, unmanned sub-assembly lines for next-generation mobile displays, minimizing defect rates by nearly 18%.
-
Hanwha Robotics (2024): Expanded its production capacity via a strategic manufacturing facility upgrade in South Korea, scaling up annual output of safety-certified collaborative robots to cater to surging global and domestic SME demand.
-
Ministry of Trade, Industry and Energy, South Korea (2024): Rolled out an expanded funding framework targeting indigenous robotics component development, aiming to lift local supply chain self-sufficiency for core robotic reducers and software controllers above 50%.
Competitive Landscape
The South Korea Industrial Robotics Market exhibits a dynamic mix of entrenched global conglomerates and agile domestic robotics innovators. Key market participants focus heavily on strategic localization, joint ventures, and tailored software upgrades to outpace rivals.
Leading players profiled in the report include Doosan Robotics, Hyundai Robotics, Hanwha Robotics, Samsung Electronics (Automation Divisions), Fanuc Corporation, Yaskawa Electric, ABB, and KUKA . These frontrunners are emphasizing modular product expansions, open-architecture software platforms, and comprehensive after-sales maintenance packages to secure long-term enterprise contracts.
Analyst Commentary
"South Korea is no longer just experimenting with automation; it is rewriting the global playbook for cognitive, lights-out manufacturing," said a Senior Research Analyst at Stellar Market Research. "As demographic pressures mount, the race is won by enterprises that seamlessly merge AI software with versatile hardware. The projected climb to USD 968.69 million by 2032 underscores that industrial robotics has transitioned from a localized manufacturing tool into the bedrock of South Korea's macroeconomic resilience and technical sovereignty."
Future Outlook
Through the forecast period, the South Korean industrial robotics market will experience accelerated maturation. Growth will be propelled by the transition from rigid mass production to hyper-personalized, batch-of-one manufacturing.
While heavy automotive and electronics sectors will sustain baseline volume demand, emerging verticals such as pharmaceuticals, food and beverages, and secondary battery recycling will unlock new frontiers for specialized robotic applications. As 5G-driven smart factories and cloud-managed fleets become standard, the competitive battleground will shift decisively toward advanced cognitive software, predictive maintenance capabilities, and human-centric safety compliance.
For further information, click the following link: https://www.stellarmr.com/report/req_sample/south-korea-industrial-robotics-market/2946
About Stellar Market Research
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656
Oral Chemotherapy Market Forecast: Global Industry Trends, Segmentation and Regional Analysis
By preeti mmr, 2026-09-23
Market Overview
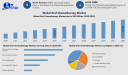
The global Oral Chemotherapy Market was valued at approximately US$ 1.78 billion in 2025 and is projected to reach nearly US$ 3.15 billion by 2032 , expanding at a CAGR of 8.52% during the forecast period 2026–2032 . The market is experiencing sustained growth as healthcare providers, pharmaceutical companies, and patients increasingly recognize the benefits of orally administered cancer therapies, including convenience, reduced dependence on infusion-based treatment, and greater flexibility for patients undergoing long-term treatment.
Download PDF Brochure: https://www.maximizemarketresearch.com/request-sample/98685/
Cancer treatment has traditionally relied heavily on intravenous administration. However, advances in pharmaceutical research and drug development have resulted in an expanding pipeline of oral oncology therapies. Oral chemotherapy can allow eligible patients to administer medication outside conventional hospital infusion settings, potentially supporting home-based treatment and reducing the frequency of hospital visits.
The increasing global burden of cancer is another important factor supporting market expansion. Governments and healthcare organizations continue to invest in cancer detection, treatment, research, and monitoring programs. At the same time, pharmaceutical companies are developing targeted therapies designed to address specific molecular pathways associated with different cancers.
The market is segmented according to drug class, form, distribution channel, and region . Tablets, capsules, and liquid formulations serve different patient and therapeutic requirements, while hospital pharmacies, retail pharmacies, and drug stores represent important distribution channels.
Market Drivers and Trends
Increasing Demand for Convenient Cancer Treatment
Convenience is one of the major factors contributing to the adoption of oral chemotherapy. Compared with treatments that require repeated intravenous administration, suitable oral therapies can provide patients with greater flexibility in managing their treatment schedules. This is particularly relevant for patients receiving prolonged courses of therapy and for healthcare systems seeking to expand outpatient and home-based care.
Download PDF Brochure: https://www.maximizemarketresearch.com/request-sample/98685/
The growing emphasis on patient-centered treatment is encouraging pharmaceutical companies to develop therapies that can be administered outside traditional clinical environments. The increasing availability of oral oncology medicines is therefore expected to support market growth throughout the forecast period.
Growth in Targeted and Personalized Therapies
Advances in molecular biology and oncology have enabled the development of therapies designed to target specific molecular alterations associated with cancer. Targeted oral medicines have become an important area of pharmaceutical research because they can be developed for specific patient populations and cancer types.
The development of therapies targeting molecular pathways is creating opportunities for pharmaceutical companies to expand their oral oncology portfolios. Continued investment in research and development is expected to introduce additional treatment options and broaden the potential applications of oral chemotherapy.
Expansion of Home-Based and Self-Administered Treatment
The pharmaceutical drug-delivery sector is increasingly focusing on self-administration and residential care. An aging population is contributing to demand for healthcare solutions that reduce the need for frequent hospital visits. Oral chemotherapy fits within this broader movement toward outpatient and home-based treatment for appropriate patients.
Digital health technologies, medication-management tools, remote monitoring, and patient-support programs can further support adherence and treatment management. These developments are expected to influence how oral oncology therapies are prescribed, distributed, and monitored.
Increasing Focus on Cost Containment
Healthcare systems in both developed and emerging economies are facing pressure to control pharmaceutical expenditure. Governments, insurers, healthcare providers, and patients are increasingly examining the cost-effectiveness of medicines and encouraging the use of generic alternatives where appropriate.
The availability of lower-cost treatment options can improve access to cancer medicines in price-sensitive markets. At the same time, pharmaceutical companies face continued pressure to balance investment in innovative therapies with affordability and reimbursement considerations.
Primary Market Constraints
Despite strong growth prospects, the Oral Chemotherapy Market faces several challenges. High treatment costs , particularly for innovative targeted therapies, remain a major concern for patients and healthcare systems. New oncology medicines often require substantial research and development investment, which can contribute to higher prices.
Another important challenge is medication adherence. Oral chemotherapy transfers a significant portion of treatment administration from healthcare professionals to patients or caregivers. Missed doses, incorrect administration, drug interactions, and inadequate understanding of treatment instructions can affect therapeutic outcomes.
Healthcare professionals therefore need to provide appropriate patient education, monitoring, and medication-management support. Pharmaceutical companies and healthcare providers are increasingly developing adherence programs and patient-support services to address these challenges.
Pricing pressure and reimbursement uncertainty may also affect market expansion. Governments and insurance providers continue to evaluate pharmaceutical expenditures, while manufacturers must navigate different regulatory and reimbursement frameworks across countries.
Key Market Segments
By Drug Class
The market is segmented into Non-steroidal Aromatase Inhibitors, Protein Kinase Inhibitors, Anti-Androgens, Antineoplastic Agents, and Alkylating Agents .
Protein kinase inhibitors represent an important area within modern oral oncology because of their role in targeted treatment approaches. Their development reflects the broader transition toward therapies designed around specific molecular mechanisms.
Antineoplastic agents and other established drug classes continue to contribute to the overall market, while targeted therapies are creating new opportunities for innovation.
By Form
Based on form, the market is categorized into Tablets, Capsules, and Liquids .
The tablet segment dominated the Oral Chemotherapy Market in 2025 and is expected to maintain significant demand during the forecast period. Tablets are widely used because of their convenient administration, portability, and compatibility with a broad range of oral pharmaceutical formulations.
Capsules also represent an important segment, particularly where specific drug formulations or controlled-release characteristics are required. Liquid formulations can serve patients who experience difficulty swallowing solid dosage forms and may provide additional flexibility for specific patient populations.
By Distribution Channel
The market is divided into Hospital Pharmacies, Retail Pharmacies, and Drug Stores .
Hospital pharmacies remain important because oncology patients frequently receive prescriptions and treatment guidance through hospital-based cancer centers. Retail pharmacies and drug stores are increasingly relevant as oral cancer therapies facilitate treatment outside infusion centers.
The expansion of specialty pharmacy services and patient-support programs may further influence distribution patterns during the forecast period.
Download PDF Brochure: https://www.maximizemarketresearch.com/request-sample/98685/
Regional Insights
North America accounted for a leading share of the global Oral Chemotherapy Market in 2025. The region benefits from comparatively high healthcare expenditure, advanced oncology infrastructure, pharmaceutical research capabilities, and the presence of major pharmaceutical companies. The growing availability of oral cancer medicines and continued investment in oncology research are expected to support the regional market.
The Asia Pacific region is expected to experience strong growth during the forecast period, with the market projected to expand at approximately 9.34% CAGR according to the provided market assessment. Rising healthcare expenditure, increasing cancer incidence, expansion of healthcare infrastructure, and growing pharmaceutical activity are important factors contributing to regional opportunities.
Countries across Asia Pacific are also experiencing changes in healthcare access and treatment patterns. Increasing awareness of cancer diagnosis and treatment, combined with expanding pharmaceutical distribution networks, is expected to support adoption of oral oncology medicines.
Europe represents another significant market, supported by established healthcare systems, pharmaceutical research, and increasing demand for advanced cancer treatment options. Meanwhile, Latin America and the Middle East & Africa offer opportunities associated with improving healthcare infrastructure and increasing access to oncology treatment.
Major Industry Players
The competitive landscape includes established pharmaceutical companies and specialized biotechnology firms involved in oncology drug development, commercialization, and distribution. Major companies identified in the market include:
- Amgen Inc.
- Pfizer Inc.
- Sanofi S.A.
- Novartis AG
- Johnson & Johnson
- Merck & Co. Inc.
- F. Hoffmann-La Roche Ltd. (Roche)
- Bristol-Myers Squibb
- Eli Lilly and Company
- Exelixis Inc.
- Clovis Oncology Inc.
- Jazz Pharmaceuticals Inc.
- Puma Biotechnology Inc.
- AstraZeneca
- GlaxoSmithKline (GSK)
- Teva Pharmaceutical Industries Ltd.
- Zydus Lifesciences Ltd.
- Astellas Pharma Inc.
- Takeda Pharmaceutical Company Ltd.
- Bayer AG
- Daiichi Sankyo Co. Ltd.
- Regeneron Pharmaceuticals Inc.
- Gilead Sciences Inc.
- Ipsen S.A.
- Merck KGaA
Competition within the market is influenced by product development, clinical research, regulatory approvals, therapeutic portfolios, geographical presence, and strategic collaborations. Pharmaceutical companies are increasingly focusing on targeted therapies and next-generation oncology platforms to strengthen their positions in the rapidly evolving cancer-treatment landscape.
Frequently Asked Questions
1. What is the projected size of the Oral Chemotherapy Market by 2032?
The Oral Chemotherapy Market was valued at approximately US$ 1.78 billion in 2025 and is projected to reach nearly US$ 3.15 billion by 2032 , registering a CAGR of approximately 8.52% during 2026–2032 .
2. Which region led the Oral Chemotherapy Market in 2025?
North America led the global market in 2025, supported by healthcare expenditure, cancer treatment infrastructure, pharmaceutical research, and increasing adoption of oral oncology therapies.
3. Which form dominated the Oral Chemotherapy Market?
The tablet segment dominated the market in 2025. Its growth is supported by convenient administration, widespread pharmaceutical availability, and increasing use of prescription medicines.
4. What are the major factors driving the Oral Chemotherapy Market?
Key growth factors include the increasing availability of oral cancer medicines, demand for convenient treatment options, expansion of targeted therapies, growth of home-based care, increasing cancer prevalence, and continued pharmaceutical research and development.
5. What are the major challenges facing the market?
Major challenges include high costs associated with innovative cancer medicines, medication adherence, reimbursement pressure, pricing constraints, and the need for patient education and monitoring during self-administered treatment.
Conclusion
The global Oral Chemotherapy Market is entering a period of continued expansion as pharmaceutical innovation, patient preference for convenient treatment, and advances in targeted oncology contribute to demand for orally administered cancer medicines. The market is expected to grow from US$ 1.78 billion in 2025 to approximately US$ 3.15 billion by 2032 , reflecting an estimated 8.52% CAGR .
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.
Revenue Outlook and Market Expansion
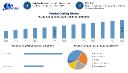
The global Powder Coating Market was valued at USD 14.5 billion in 2025 and is projected to reach nearly USD 22 billion by 2032 , expanding at a CAGR of 6% from 2025 to 2032 . Demand is supported by the growing use of powder coatings across automotive, appliances, furniture, architectural, and general industrial applications.
Powder coatings are increasingly preferred for their durable finish, flexibility, efficiency, and environmental advantages. Their growing use in developing and developed economies is also connected with rising demand for consumer goods, automobiles, and furniture.
Industry Dynamics and Emerging Market Trends
Powder coating is a dry finishing process used across a broad range of industrial and consumer applications. One of the major factors supporting market growth is the reduced use of volatile organic compounds (VOCs). Powder coatings do not require petroleum-based solvents and can help manufacturers address environmental requirements associated with VOC emissions.
Access the Complete Report Sample : https://www.maximizemarketresearch.com/request-sample/13419/
The technology is widely used in automotive, appliances, furniture, architectural, and general industrial applications . Growing demand for consumer products and increasing investments in automotive and manufacturing industries are supporting additional applications.
The automotive sector represents an important opportunity because powder coatings are used on components such as engines, frames, wheels, filters, mirrors, wipers, horns, and other vehicle parts. Continued investment in automotive production, particularly in countries such as China, India, Mexico, Brazil, and other emerging markets, is expected to support demand.
However, producing very thin and uniform powder-coating films can be challenging. Particle size, powder chemistry, flow, leveling, and film characteristics can influence the final surface finish. Environmental requirements related to wastewater generated during cleaning and pretreatment processes also present challenges for manufacturers.
Research Scope, Timeline and Methodology
The MMR report uses 2025 as the base year , with historical data covering 2020–2025 and a forecast period from 2026 to 2032 . The study evaluates the market by product type, resin, coating method, end-use industry, and geographic region.
The report covers the following market segments:
- By Type: Thermoset, Thermoplastic
- By Resin: Epoxy, Polyester, Epoxy-Polyester (Hybrid), Acrylic, Polyurethane, Others
- By Coating Method: Electrostatic Spray, Fluidized Bed, Others
- By End Use: Appliances, Automotive, General Industrial, Architectural, Furniture, Others
- By Region: North America, Europe, Asia Pacific, Middle East & Africa, South America
The research framework also includes Porter's Five Forces, PESTLE analysis, technology roadmaps, regulatory analysis, government initiatives, trade analysis, competitive benchmarking, and regional market assessments .
Get a Free Preview of Market Insights : https://www.maximizemarketresearch.com/request-sample/13419/
Regional Market Performance and Growth Opportunities
Asia Pacific dominated the Powder Coating Market in 2025 with approximately 42% of the global market share and is expected to grow at a 6% CAGR during the forecast period . The region benefits from investment across construction, appliances, automotive, electronics, and other industrial sectors.
India, China, and Indonesia are highlighted as important markets because of investments across multiple end-use industries and rising income levels. Infrastructure development in China and India is also creating opportunities for powder coatings in architectural applications, including aluminum extrusions, window frames, doorframes, and building facades.
North America is expected to experience rapid growth, supported particularly by automotive manufacturing in the United States and Mexico. Concerns about VOC emissions in automotive coating processes are encouraging greater interest in powder coatings.
Europe also represents an important market, with automotive manufacturing in countries including Germany, Austria, Romania, Hungary, and Turkey contributing to demand. Regulatory requirements concerning VOC emissions, including REACH-related requirements, are another factor supporting powder-coating adoption.
The report additionally covers Middle East & Africa and South America , including country-level assessments across major markets.
Segment-Level Market Analysis and Leading Categories
Thermoset and Thermoplastic Technologies
The Thermoset segment dominated the market in 2025 and is expected to maintain its leading position through the forecast period. Thermoset powder coatings include resin systems such as epoxy, polyester, acrylic, and polyurethane and offer properties including corrosion, impact, and temperature resistance.
The Thermoplastic segment is projected to grow at a 6% CAGR during the forecast period. Its relatively simple manufacturing and application process, along with properties such as solvent resistance, weather resistance, wear resistance, and aesthetic performance, supports its use across multiple industries.
End-Use Industry Development
The Appliances segment held the largest market share in both value and volume in 2025 . Powder coatings are used in refrigeration systems, dryers, air-conditioner cabinets, washing machines, boilers, dishwasher racks, freezers, and microwave ovens.
The Automotive segment is expected to grow at the fastest rate during the forecast period . Increasing automobile production and demand across the United States, Mexico, China, India, Brazil, South Africa, Indonesia, Malaysia, and other markets are supporting the segment's development.
The Architectural segment is also expected to develop steadily, supported by the durability of powder coatings and advances in polyester-resin technologies that enable different finishes for architectural applications.
Competitive Environment and Leading Companies
The Powder Coating Market includes global coating manufacturers, resin producers, paint companies, and specialized powder-coating suppliers. Competition is shaped by product development, sustainability initiatives, geographic expansion, coating technologies, and solutions designed for specific end-use industries.
Key companies profiled in the MMR report include:
- The Sherwin-Williams Company
- PPG Industries, Inc.
- Axalta Coating Systems
- RPM International Inc.
- Valspar
- Hentzen Coatings, Inc.
- IFS Coatings
- BASF SE
- Bayer AG
- Emil Frei GmbH & Co. KG
- Arkema S.A.
- SOMAR
- Kansai Paint Co., Ltd.
- Nippon Paint Holdings Co., Ltd.
- Berger Paints India Limited
- Asian Paints Limited
- Jotun
- TIGER Coatings GmbH & Co. KG
- KAPCI Coatings
- DuluxGroup Limited
- Primatek Coatings OÜ
- KCC Corporation
- IGP Powder Technik AG
- DSM
- Haztek Coating Technology
Recent developments also highlight the industry's focus on sustainability and coating efficiency. PPG introduced ENVIROLUXE Plus powder coatings containing up to 18% recycled plastic (rPET) in May 2025. Arkema achieved ISCC PLUS certification for its North Kansas City polyester powder-coating resin facility in September 2025, while Haztek introduced new powder-coating equipment and intelligent electrostatic spray solutions during 2025.
Get Your Complimentary Market Report : https://www.maximizemarketresearch.com/request-sample/13419/
Key Questions and Market Insights
- What was the Powder Coating Market size in 2025?
The market was valued at USD 14.5 billion . - What is the expected market size by 2032?
The market is projected to reach nearly USD 22 billion by 2032 . - What CAGR is expected during the forecast period?
The market is projected to grow at a 6% CAGR . - Which region dominated the market in 2025?
Asia Pacific led the market with approximately 42% share .
Report Coverage and Strategic Intelligence
The MMR Powder Coating Market report provides a detailed assessment of the global industry, including:
- Market size and revenue forecast through 2032
- Historical analysis from 2020–2025
- Type-based segmentation
- Resin-level analysis
- Coating-method assessment
- End-use industry analysis
- Regional and country-level market evaluation
- Market drivers and restraints
- Opportunities and challenges
- Industry trends and technology developments
- Competitive landscape
View More Related Reports :
Heavy-Duty Bags & Sacks Market https://www.maximizemarketresearch.com/market-report/global-heavy-duty-bags-sacks-market/96364/
Global Mica Market https://www.maximizemarketresearch.com/market-report/global-mica-market/42926/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us :
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
Building a Stronger EHS Strategy Through Data Driven Insights
The success of an Environmental, Health, and Safety (EHS) program cannot be measured simply by the number of policies, procedures, forms, or records an organization has in place. Its true effectiveness is reflected in the decisions people make while performing their responsibilities every day. Even a well structured EHS framework may deliver limited results when decisions depend on assumptions, disconnected information, or incomplete records. Data driven decision making (DDDM) gives organizations a more reliable basis for setting priorities and determining where action is necessary. Information collected from audits, inspections, training, incident investigations, and workplace observations can help teams manage risk, support compliance, and improve EHS performance across multiple sites.
Understanding Data Driven Decision Making in EHS
Within an EHS environment, data driven decision making means applying reliable information to establish priorities, determine suitable responses, and direct resources toward areas where they are most needed. It can help organizations understand where hazards are occurring, which weaknesses deserve immediate attention, where investments may deliver meaningful improvements, and whether current EHS initiatives are actually producing measurable results.
Yet collecting information alone does not create meaningful value. An effective EHS data strategy depends on how information is handled throughout its entire lifecycle, beginning when it is captured and continuing until it contributes to an actual decision. Information needs to be collected consistently, structured properly, checked for accuracy, analyzed for useful patterns, and ultimately transformed into corrective and preventive actions (CAPA). The objective is not simply to create additional reports or fill dashboards with figures because those figures are available. The real objective is to improve the quality of decisions and use those decisions to strengthen safety results and environmental performance.
Why a Data Driven EHS Strategy Matters
Reliable EHS information gives organizations a clearer view of their operational strengths, weaknesses, and developing concerns. One major benefit is the ability to recognize potential problems early enough to address them before they develop into serious incidents. Carefully selected leading indicators can expose warning signs and give teams an opportunity to intervene while risks are still manageable.
Data can also strengthen accountability across different levels of an organization. When executives, managers, employees, and contractors rely on common measurements, there is less ambiguity about expectations and results. A shared understanding of performance can make responsibilities clearer and encourage departments and locations to apply more consistent practices.
Complete and accurate records can also improve regulatory preparedness. Consistent reporting and properly maintained documentation can make inspections and audits easier to coordinate while reducing uncertainty around compliance related activities. The benefits of stronger EHS information can extend beyond regulatory needs as well. Better informed decisions may help minimize operational interruptions, reduce near miss events, accelerate approvals, and make workplace processes easier to manage. Over time, these improvements can support productivity, build employee confidence, and strengthen organizational credibility.
Key EHS Metrics Organizations Should Track
A useful EHS measurement strategy should combine both leading and lagging indicators. Leading indicators concentrate on potential risks, weaknesses, and preventive activities before an incident takes place. Lagging indicators, on the other hand, examine events and outcomes that have already occurred. Looking at both categories together provides a more complete picture of prevention efforts as well as overall EHS performance.
Leading Indicators: Identifying Risk Before Incidents
Leading indicators can function as an early warning mechanism for EHS teams. They help bring attention to developing hazards, weaknesses in controls, and situations where timely intervention could prevent an unwanted event.
Near miss reporting is one important source of information. Near misses can expose unsafe conditions, behaviors, or procedural gaps before they develop into injuries or more serious incidents. When employees are encouraged to report these situations, organizations can uncover potential problems that might otherwise remain hidden.
Behavior Based Safety (BBS) observations can provide another valuable perspective. Their effectiveness should not be measured only by the number of observations completed. The quality of those observations, the issues they identify, and the follow up actions taken afterward can provide much greater insight into workplace safety.
Training data should also go beyond simply recording attendance or course completion. Organizations can obtain a clearer picture of workforce readiness by examining competency, assessing knowledge retention, monitoring refresher training participation, and determining whether employees are capable of applying their training effectively in actual workplace situations.
Permit to work data can help organizations assess whether operational controls are working as intended. Measures such as approval rates, processing duration, and deviations identified during work can reveal weaknesses, highlight improvement opportunities, and support greater operational discipline.
Inspection results and CAPA performance should also receive consistent attention. Examining the severity of findings alongside the amount of time required to close corrective actions can help organizations determine whether identified risks are genuinely being resolved or whether the same issues continue to reappear.
Lagging Indicators: Understanding Results
Lagging indicators concentrate on actual outcomes and can reveal situations where processes, controls, or management systems did not achieve their intended objectives.
Measurements such as Total Recordable Incident Rate (TRIR) and Lost Time Injury Frequency Rate (LTIFR) remain useful standardized metrics. Organizations can use them to review performance and compare results across facilities, departments, and contractor groups.
Environmental performance should be evaluated using a similarly detailed approach. Simply counting environmental exceedances may not explain the full situation. Organizations can also examine how long each exceedance remains unresolved and whether the same underlying causes continue to occur.
Equipment related events can provide another important source of information. Repeated equipment failures, maintenance delays, and recurring breakdowns can create implications for workplace safety while simultaneously affecting operational reliability.
Financial metrics can help connect EHS performance with wider business consequences. Expenses associated with medical treatment, lost productivity, insurance claims, and other incident related costs can give leadership a clearer picture of the financial and operational implications connected to safety and environmental performance.
How to Begin a Data Driven EHS Program
Organizations do not need to achieve a perfect data environment before starting a data driven EHS initiative. A practical program can begin with a small number of important priorities and expand as the organization gains experience and confidence.
The starting point should be identifying a limited set of high value objectives. These might involve preventing incidents from escalating, making permit processing more efficient, or reducing the number of overdue audit findings. A focused starting scope allows teams to concentrate on defined outcomes and makes it easier to demonstrate measurable progress.
The following step is establishing consistent standards. Using common terminology, classifications, forms, and severity definitions across locations can improve the consistency of collected information while making comparisons between sites more useful.
Data quality should be addressed as early as possible, particularly at the point where information enters the system. Required fields, validation rules, and predefined selections can reduce the likelihood of incomplete, inconsistent, or inaccurate information entering the database and causing difficulties during later analysis.
Once dependable information is available, organizations can consolidate data from inspections, incidents, training programs, permits, and asset management activities into a centralized environment. Bringing these sources together can create a broader operational picture and make relationships and patterns easier to identify. Those connections may remain difficult to recognize when information is kept in separate systems or locations.
Dashboards should be designed around the requirements of the people who use them. Managers and supervisors need practical visibility into trends, thresholds, and emerging risks so they can respond while concerns are still developing. Providing decision makers with relevant information at the right time can support quicker and more proactive responses.
The final step is turning identified issues into a structured CAPA process. Clear ownership, defined deadlines, and verification activities can help ensure that corrective actions are completed and that improvements continue to work as intended. As the program begins delivering results, organizations can gradually increase the number of measurements, extend the approach to additional locations, and explore predictive capabilities that could help identify risks at an even earlier stage.
Governance and Culture: Foundations for Long Term Success
Technology, analytics, and reporting platforms can play an important role in supporting a data driven EHS strategy, but technology alone does not guarantee successful outcomes. Sustainable results also require effective governance and a workplace culture that supports transparency, accountability, and continuous improvement.
Ownership of important datasets should be clearly established. Individuals or teams need to understand who is responsible for collecting, validating, reviewing, and approving information. Defined review schedules, documented processes, and appropriate change management can help preserve consistency and protect data integrity as the EHS program develops.
Reporting culture is just as important. Employees should feel comfortable identifying hazards, raising concerns, and reporting near misses without fearing blame or negative consequences. When workers choose not to report problems, organizations lose valuable information, making it harder to understand what is actually happening within the workplace.
Simple reporting procedures, recognition of employee participation, and clear communication about what happens after a report is submitted can encourage greater involvement. As employees become more comfortable contributing information, organizations can build a more dependable picture of workplace conditions, risks, and behaviors.
Ultimately, dependable EHS information gives organizations a stronger foundation for addressing challenges, making operational decisions, and demonstrating measurable progress. By establishing meaningful objectives, tracking indicators that provide genuine insight, and consistently turning findings into action, organizations can move EHS beyond a largely reactive compliance role. This creates an approach centered more strongly on controlling risk, improving performance, and supporting continuous improvement across the organization.
Book a free demo @ https://toolkitx.com/blogsdetails.aspx?title=Data-driven-decision-making-in-EHS:-what-to-track,-and-where-to-start
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Safety-culture:-what-it-is,-why-it-matters,-and-how-to-build-it
https://toolkitx.com/blogsdetails.aspx?title=Hot-work-permit:-definition,-requirements,-and-practical-guide-to-going-digital
Lonavala is a beautiful hill station in Maharashtra, known for its green hills, scenic valleys, waterfalls, and peaceful surroundings. It is a popular weekend destination for travellers from Mumbai and Pune. If you are planning a relaxing trip, finding the best homestay in Lonavala can make your stay more comfortable and enjoyable.
Why Choose a Homestay in Lonavala?
A homestay can offer a comfortable and homely environment for travellers. It is a good option for families, couples, and groups of friends who want more space and common areas to spend time together.
Depending on the property, you may find facilities such as spacious rooms, gardens, outdoor seating, kitchens, parking, and swimming pools.
Enjoy the Natural Beauty of Lonavala
Lonavala is surrounded by beautiful hills and greenery, making it an excellent place to take a break from busy city life. During the monsoon season, the area becomes especially scenic with waterfalls and lush landscapes.
A comfortable homestay gives you a peaceful place to relax after a day of sightseeing. You can enjoy a cup of tea outdoors, admire the views, or simply spend time with your loved ones.
Perfect for Families and Groups
The best homestay in Lonavala can be suitable for family holidays, friends' trips, birthday celebrations, anniversaries, and weekend getaways.
A spacious property with common living areas can make group travel more convenient. Families travelling with children can also check the property's safety facilities and house rules before booking.
Places to Visit in Lonavala
There are many attractions to explore during your stay. Popular places include Bhushi Dam, Tiger Point, Rajmachi Point, Kune Waterfalls, and Karla Caves.
You can plan sightseeing during the day and return to your homestay in the evening to relax and enjoy some peaceful time.
Things to Check Before Booking
Before selecting a homestay, check its location, room facilities, cleanliness, parking availability, food options, amenities, and house rules.
If you are specifically looking for a swimming pool or private pool, confirm its availability and timings before booking. Recent guest reviews and updated property photographs can also help you make an informed choice.
Plan Your Lonavala Getaway
Finding the best homestay in Lonavala depends on your budget, group size, preferred location, and required amenities. Whether you are planning a family vacation, a friends' trip, or a peaceful weekend escape, a homestay can provide a comfortable base for exploring the region.
Choose a property that suits your requirements and enjoy a refreshing break surrounded by the natural beauty of Lonavala.
Hair loss and thinning hair are common concerns for many people. Receding hairlines, bald patches, and reduced hair density can happen due to different reasons. For people exploring hair restoration options, a Hair Transplant in Gurgaon can be considered after consulting a qualified specialist.
Gurgaon has several clinics offering hair restoration consultations and procedures. Understanding the treatment and choosing a suitable clinic are important steps before starting the process.
What Is a Hair Transplant?
A hair transplant is a procedure in which healthy hair follicles are taken from a donor area of the scalp and transplanted into areas affected by hair loss. The transplanted follicles can gradually grow new hair.
The treatment plan can vary from person to person depending on the pattern of hair loss, donor hair availability, scalp condition, and desired coverage.
Why Consider Hair Transplant in Gurgaon?
Gurgaon is a major healthcare destination in the Delhi-NCR region. People considering hair restoration can find clinics offering consultations and different treatment techniques.
When looking for a Hair Transplant in Gurgaon , it is important to consider the doctor's qualifications and experience, clinic facilities, hygiene standards, treatment methods, and post-treatment support.
Common Hair Transplant Techniques
FUE Hair Transplant
Follicular Unit Extraction (FUE) involves extracting individual hair follicles from the donor area and transplanting them into areas with reduced hair growth. It is one of the commonly used hair restoration techniques.
FUT Hair Transplant
Follicular Unit Transplantation (FUT) involves removing a strip of scalp containing hair follicles. The follicles are then separated and transplanted into areas requiring coverage.
A qualified doctor can explain both techniques and determine which approach may be suitable based on the individual's condition.
How to Choose a Hair Transplant Clinic
Before choosing a clinic, research the doctor's qualifications, experience, treatment approach, clinic hygiene, consultation process, and aftercare services.
During the consultation, ask about the estimated number of grafts, procedure details, recovery time, possible risks, aftercare instructions, and realistic expectations about the results.
Recovery and Aftercare
Following the doctor's instructions is important after a hair transplant. Temporary redness, swelling, or scalp sensitivity may occur during the initial recovery period.
The doctor may provide instructions regarding scalp washing, medication, exercise, and follow-up appointments. Transplanted hair may also shed temporarily before new hair growth develops.
Final Thoughts
A Hair Transplant in Gurgaon may be an option for people experiencing certain types of hair loss. However, treatment suitability and results can vary from person to person.
A consultation with a qualified hair-restoration doctor can help you understand the cause of your hair loss, available treatment options, expected results, and whether a hair transplant is suitable for your individual needs.
Paving Equipment Market Forecast: Technology Advancements, Industry Trends and Future Growth to 2034
By preeti mmr, 2026-09-23
Market Overview
The Paving Equipment Market was valued at approximately US$ 1,049.4 million in 2025 and is expected to reach nearly US$ 1,881.14 million by 2034 , expanding at a CAGR of 6.7% during 2026–2034 . Paving equipment plays an important role in modern construction activities, including road development, highways, bridges, pavements, walkways, flyovers, and underpasses. These machines are designed to handle and accurately place materials such as asphalt, concrete, blocks, and bricks while maintaining the required thickness, elevation, and surface quality.
Download PDF Brochure: https://www.maximizemarketresearch.com/request-sample/68947/
Increasing expenditure on transportation infrastructure, urban expansion, highway modernization, and road connectivity is supporting demand for paving equipment worldwide. Governments and infrastructure developers are increasingly investing in efficient construction machinery to reduce project completion time, improve material utilization, and maintain consistent paving quality.
Paving equipment generally incorporates components such as material hoppers, augers, screeds, conveyors, vibrators, guides, and other control systems. Technological improvements in these systems are enabling contractors to achieve greater accuracy and productivity while reducing material wastage and operating costs.
Market Drivers and Trends
A major factor supporting the growth of the paving equipment market is the continued development of road and transportation infrastructure . Emerging and developed economies are allocating significant resources toward highways, urban roads, bridges, airports, and other transportation projects. Expansion of road networks improves connectivity between cities and commercial centers while supporting logistics and economic activity.
Download PDF Brochure: https://www.maximizemarketresearch.com/request-sample/68947/
Urbanization and population growth are also increasing the requirement for new roads and the rehabilitation of existing infrastructure. Growing cities require wider roads, improved pedestrian infrastructure, parking areas, and transportation corridors, creating opportunities for manufacturers of paving machinery.
Another important trend is the increasing adoption of automated and intelligent paving technologies . Modern paving equipment can incorporate machine-control systems, automated steering, digital grade control, sensors, and productivity monitoring. These technologies can reduce dependence on manual measurements and help contractors achieve greater consistency during paving operations.
The industry is also moving toward lower-emission and fuel-efficient equipment . Environmental regulations and sustainability objectives are encouraging manufacturers to develop machines with improved fuel efficiency, reduced emissions, and more efficient hydraulic and power systems. Hybrid and electrically assisted technologies may gain greater attention as construction companies seek to reduce operating costs and environmental impact.
Three-dimensional paving and digital machine-control technologies represent another emerging trend. Digital models and automated control systems can help contractors maintain precise paving profiles and reduce the need for conventional stringline-based processes.
Manufacturers are additionally focusing on operator comfort, remote monitoring, telematics, predictive maintenance, and connected construction equipment . These capabilities can improve equipment utilization and provide contractors with operational information for maintenance planning and fleet management.
Primary Market Constraints
Despite positive growth prospects, the paving equipment market faces several challenges. High initial equipment costs can limit adoption among small and medium-sized contractors. Advanced paving machines equipped with automation, digital controls, and telematics typically require higher upfront investments than conventional machinery.
Maintenance and operating costs are another consideration. Paving equipment operates in demanding environments involving dust, heat, vibration, heavy loads, and continuous operation. Regular maintenance of engines, hydraulic systems, screeds, conveyors, and other components is essential for maintaining productivity.
The market is also influenced by fluctuations in construction activity and infrastructure spending . Delays in public infrastructure projects, changes in government budgets, economic uncertainty, and fluctuations in raw-material prices can affect equipment purchasing decisions.
A shortage of skilled equipment operators and technicians can create additional challenges. As paving machinery becomes increasingly automated and digitally connected, contractors require personnel capable of operating advanced systems and interpreting machine data.
Environmental regulations may also increase development and compliance costs for manufacturers, particularly as governments introduce stricter standards for emissions and fuel consumption.
Key Market Segments
The Paving Equipment Market is segmented by material, type, fuel, and region .
By Material
Asphalt Paving Equipment represents an important segment because asphalt remains widely used in highways, urban roads, airport surfaces, and other transportation infrastructure. The demand for asphalt paving equipment is closely associated with road construction and rehabilitation activities.
Concrete Paving Equipment is used for concrete roads, industrial floors, pavements, airport infrastructure, and other applications requiring durable surfaces. Growing investment in long-life infrastructure can support demand for specialized concrete paving machinery.
Block and Brick Paving Equipment is primarily used for applications involving paving blocks, bricks, and related construction materials. These machines are particularly relevant for sidewalks, driveways, pedestrian areas, landscaping, and urban infrastructure.
The Others category includes specialized equipment designed for specific paving and construction applications.
By Type
The market is divided into Wheel Paving Equipment and Tracked Paving Equipment .
Wheel paving equipment offers mobility and relatively easy transportation between work locations. Its maneuverability makes it suitable for various construction applications where frequent movement is required.
Tracked paving equipment provides stability and traction, making it suitable for larger paving projects and challenging working environments. These machines can support paving operations across wide road surfaces, although their transportation requirements can be comparatively more complex.
By Fuel
Based on fuel, the market includes Diesel, Gasoline, and Others . Diesel-powered equipment remains significant in heavy construction applications because of its power and suitability for extended operations. At the same time, manufacturers are developing more efficient powertrains and exploring alternative technologies in response to emissions regulations and sustainability requirements.
Download PDF Brochure: https://www.maximizemarketresearch.com/request-sample/68947/
Regional Market Analysis
Asia Pacific is expected to remain a significant region in the paving equipment market, supported by substantial infrastructure investment, urban development, and expansion of road and rail networks. Countries including China, India, Japan, and Australia have extensive transportation infrastructure and continue to invest in road modernization and connectivity.
India is witnessing increasing infrastructure development, including highways, expressways, urban roads, and transportation corridors. Such projects can generate demand for road construction machinery and advanced paving solutions.
China's large-scale transportation infrastructure programs and investments in roads, tunnels, and urban development also create opportunities for paving equipment manufacturers. Japan's established infrastructure network and ongoing modernization activities contribute to demand for technologically advanced construction machinery.
North America represents another important market because of highway rehabilitation, road maintenance, infrastructure modernization, and demand for advanced construction equipment. The United States, in particular, has significant requirements for road resurfacing and infrastructure renewal.
Europe is characterized by established road networks and increasing attention toward infrastructure modernization, energy efficiency, emissions reduction, and sustainable construction. Demand for technologically advanced and environmentally efficient paving machinery can support market development across the region.
Meanwhile, Latin America and the Middle East & Africa provide growth opportunities through transportation infrastructure expansion, urban development, and investment in road connectivity. Increasing infrastructure projects in emerging economies can create additional demand for paving equipment.
Major Industry Players
The competitive landscape includes established construction-equipment manufacturers and specialized paving-equipment companies. Key industry participants include Ingersoll Rand, LeeBoy, Vögele, Dynapac, Roadtec, Terex Road Building, Caterpillar, BOMAG, Atlas Copco, Volvo Construction Equipment, Liebherr Construction Machines, GOMACO Corporation, Besser, HEM Paving, Rexcon LLC, Power Curbers Inc., and Allen Engineering Corporation .
Companies in the market are focusing on product innovation, equipment efficiency, automation, digital machine control, emissions reduction, operator productivity, and expanded product portfolios. Strategic partnerships can also help manufacturers integrate advanced positioning, machine-control, and digital technologies into paving equipment.
Recent developments demonstrate this shift toward technology-enabled paving. Vögele launched its Dash 5 Generation paving equipment line in North America at CONEXPO 2026 , introducing the SUPER 2000-5 X tracked paver and SUPER 2003-5 X wheeled paver along with associated screed systems. The company highlighted productivity improvements and technologies such as EcoPlus and AutoTrac.
Dynapac partnered with Leica Geosystems to integrate automated 3D machine-control capabilities into selected paver models through the Leica iCON pave system. Such developments illustrate the industry's movement toward digitally controlled and more precise paving operations.
Frequently Asked Questions
1. What was the size of the Global Paving Equipment Market in 2025?
The Global Paving Equipment Market was valued at approximately US$ 1,049.4 million in 2025 .
2. What will be the size of the Paving Equipment Market by 2034?
The market is expected to reach approximately US$ 1,881.14 million by 2034 .
3. What is the expected CAGR of the Paving Equipment Market?
The market is projected to grow at a CAGR of 6.7% from 2026 to 2034 .
4. What are the major segments of the Paving Equipment Market?
The market is segmented by Material, Type, Fuel, and Region . Material includes asphalt, concrete, block and brick, and others. Type includes wheel and tracked paving equipment, while fuel includes diesel, gasoline, and others.
5. Which region is expected to hold a significant share of the market?
Asia Pacific is expected to remain a significant regional market, supported by infrastructure investment, urbanization, and road and rail network development.
Conclusion
The global Paving Equipment Market is entering a period of continued expansion as governments and construction companies increase investments in road infrastructure, urban development, and transportation connectivity. The market's projected growth from US$ 1,049.4 million in 2025 to US$ 1,881.14 million by 2034 reflects the growing requirement for productive, accurate, and technologically advanced paving solutions.
Connect With Us:
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT park Phase 3,
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India.
+91 9607365656
sales@maximizemarketresearch.com
About Maximize Market Research:
Maximize Market Research is one of the fastest-growing market research and business consulting firms serving clients globally. Our revenue impact and focused growth-driven research initiatives make us a proud partner of majority of the Fortune 500 companies. We have a diversified portfolio and serve a variety of industries such as IT & telecom, chemical, food & beverage, aerospace & defense, healthcare and others.