

Blogs
Management Consulting Services Market: Why 5.63% CAGR Redefines Competitive Dynamics
By PW Consulting, 2026-09-21
Management Consulting Services Market: Strategic Shifts and Commercial Opportunities in an AI-Reshaped Landscape
The global management consulting services market has entered a period of structural acceleration, with total revenue expanding from approximately $302.15 billion in 2020 to an estimated $391.68 billion in 2025. Projections indicate continued growth through 2032, with the market expected to reach $572.38 billion, sustaining a compound annual growth rate of 5.63 percent across the 2026 to 2032 forecast period. The trajectory reflects more than cyclical demand recovery; it signals a fundamental recalibration of how organizations procure, deploy, and measure advisory services. Growth is being concentrated in regions and segments where digital transformation, operational resilience, and regulatory complexity intersect, while traditional retainer-based engagements face mounting scrutiny over measurable outcomes. For executives and investors, the market is no longer simply expanding; it is reorganizing around new capability requirements, pricing models, and delivery architectures.
The expansion has been uneven across functional and industry dimensions, with operations-focused advisory and technology-adjacent consulting capturing disproportionate shares of incremental spend. At the same time, the market remains moderately concentrated, with the top three firms commanding roughly 52 percent of total revenue and the top five accounting for approximately 68 percent. This concentration masks a deeper fragmentation at the practice and sub-sector level, where specialized boutiques, technology-enabled delivery units, and cross-industry alliances are steadily redefining competitive boundaries. The persistence of concentration alongside rising specialization suggests that scale alone is no longer the primary competitive moat; instead, firms that can combine domain depth, implementation capacity, and technology integration are capturing the most durable growth.
1. Market Current State and Core Challenges
Redefining Value in a High-Expectation Environment
The consulting market is operating under a dual pressure: clients demand faster, more measurable impact while simultaneously questioning whether traditional advisory fare delivers sufficient differentiation. Several macroeconomic and structural forces have hardened this expectation. Organizations are navigating persistent cost discipline, supply chain reconfiguration, and a heightened focus on operational execution rather than purely strategic diagnosis. As a result, advisory engagements are increasingly judged against implementation readiness, technology integration, and the ability to embed change within legacy operating models. The consequence is a shift from episodic strategy projects to multi-year transformation partnerships, where value is measured in throughput gains, cost-to-serve improvements, and time-to-market for new products and channels.
This shift is colliding with a volatile cost environment for specialized talent. Specialized human labor costs within the sector have risen by an estimated 15 to 20 percent annually in 2025 and 2026, driven by demand for professionals who can combine domain expertise with AI-augmented advisory capabilities. Projected labor costs are anticipated to rise another 10 percent in 2026, reflecting shortages of skilled AI and digital transformation professionals. For consulting firms, this creates a margin equation that cannot be solved by headcount alone; productivity gains, automation of analytical workflows, and new delivery models are becoming essential to protect profitability while meeting rising client expectations.
Regulatory and Data-Privacy Complexity as a Delivery Constraint
Regulatory exposure is intensifying across multiple jurisdictions, with compliance requirements expanding around data privacy, algorithmic transparency, and the governance of technology-enabled advisory services. Recent assessments from US agencies and international bodies emphasize that management consulting services are increasingly subject to scrutiny when they intersect with sensitive client data, quantitative decision models, and AI-assisted recommendations. This adds a layer of operational complexity to engagement design, requiring stronger data handling protocols, auditability of analytical methods, and clearer boundaries between advisory input and client-controlled implementation. In practice, compliance costs are rising not only as a legal expense but as a design constraint that influences how engagements are scoped, delivered, and priced.
Concentration, Specialization, and the Hybridization of Delivery Models
While the market remains concentrated at the top, the competitive frontier is diversifying. Firms are blending strategy, operations, and technology advisory in ways that blur traditional category boundaries, while specialized players are gaining traction by focusing on high-complexity niches such as risk analytics, actuarial integration, and AI-enabled process redesign. The result is a market in which scale provides distribution and client access, but differentiation is increasingly driven by proprietary tools, implementation partnerships, and the ability to stand up large-scale transformation programs. New entrants and alliances are exploiting gaps where incumbents are either too broad to move quickly or too narrow to support end-to-end change. This hybridization is reshaping buyer behavior: organizations increasingly assemble portfolios of providers rather than relying on a single lead advisor, which rewards firms that can demonstrate interoperability, repeatability, and clear handoff to execution.
2. Key Drivers of Market Change
Technology Innovation and the Shift Toward Agentic AI
Technology is no longer a standalone consulting vertical; it is becoming the delivery backbone for strategy and operations alike. The integration of generative and agentic AI into advisory workflows is changing the economics of analysis, synthesis, and recommendation development. Rather than relying solely on manual research and bespoke modeling, firms are deploying AI agents to accelerate scenario analysis, benchmark extraction, process mapping, and unstructured data interpretation. This does not eliminate the need for senior judgment; it elevates it. The premium is moving toward professionals who can define the right problem frames, validate AI-generated outputs, and design human-in-the-loop processes that preserve accountability. The most consequential shift is operational: engagements are increasingly designed to leave behind reusable models, decision tools, and capability building rather than static decks.
Recent developments indicate that this transition is already at scale within leading firms. McKinsey & Company, for example, announced in January 2026 that it is deploying approximately 25,000 AI agents alongside roughly 40,000 human consultants to enhance productivity and client delivery. This combination signals a structural bet on blended delivery, where AI supports volume-intensive analytical tasks while human consultants concentrate on client interaction, synthesis, and implementation design. Similarly, Capgemini launched its Resonance AI Framework in July 2025 to help clients implement agentic AI at scale with human-AI collaboration for measurable business impact. These moves collectively suggest that AI is transitioning from an experimentation topic to a production-focused capability, with implications for pricing, staffing, and engagement timelines across the market.
Regulatory and Policy Environment as a Catalyst and Constraint
Policy dynamics are reshaping demand patterns in two directions. On one hand, emerging compliance obligations around data privacy, algorithmic accountability, and technology governance are prompting organizations to seek advisory support for risk assessment, control design, and transformation roadmaps. On the other hand, these same obligations constrain how consulting firms can collect, process, and reuse data across engagements. The July 2025 USITC report highlights that management consulting services face rising compliance requirements tied to data privacy and technological advancements, underscoring the regulatory weight now attached to advisory activities that involve sensitive information or automated decision support.
This environment favors firms with robust data governance, clear methodologies, and the ability to translate regulatory complexity into operational design. Sectors such as financial services, healthcare, and public-sector adjacent services are particularly exposed, which in turn shapes where demand is most resilient. For buyers, regulatory pressure is also changing procurement behavior: engagements increasingly require demonstrable compliance with data handling standards, clearer separation of advisory from implementation liability, and documented methodological rigor. The net effect is a market in which regulation is simultaneously expanding demand for advisory services and raising the bar for what qualifies as a credible engagement.
Demand-Side Shifts in Enterprise and Consumer Behavior
Client organizations are reevaluating what they expect from advisory relationships. There is growing skepticism toward generic strategy narratives, especially in environments where execution capacity is constrained by talent shortages or cost pressure. Buyers are increasingly prioritizing engagements that are tied to specific operating improvements, customer value creation, and technology-enabled change. This is reflected in a broader shift toward outcome-oriented commercial models, where pricing and success metrics are linked to measurable business impact rather than time and materials alone. In parallel, consumer-facing industries are pushing firms to integrate experience design, channel optimization, and data-driven personalization into their transformation agendas, while industrial and service sectors are focusing on productivity, asset utilization, and supply chain resilience.
This demand-side evolution is also driving fragmentation in spend patterns. Organizations are allocating more budget to capabilities that directly support execution, including process redesign, workforce change management, and digital operating model design. At the same time, the appetite for pure diagnostic work is becoming more selective, reserved for moments of strategic redirection, market entry, or major capital allocation decisions. For consulting providers, the implication is that durable demand will come from firms that can connect upstream insight to downstream execution, rather than from those offering isolated point solutions.
Cost Structure and Supply Dynamics in a Talent-Constrained Market
The supply side of the market is being reshaped by talent scarcity and cost escalation. The rising premium for professionals with AI, digital transformation, and domain-specific expertise is altering the cost structure of advisory delivery. With specialized labor costs rising sharply, firms are under pressure to improve throughput without diluting quality. This has accelerated interest in labor-mixing strategies, where routine analytical tasks are delegated to automation or lower-cost pools while senior professionals focus on high-leverage decisions and client relationships. It has also intensified the search for repeatable methodologies, modular deliverables, and knowledge assets that can be reused across clients to reduce marginal cost.
On the supply frontier, geography and capability availability are increasingly intertwined. Regional demand is growing in areas where industrial transformation, digital adoption, and regulatory change converge, but the ability to deliver depends on access to skilled talent and implementation partners. This is creating a two-sided constraint: demand is strong where transformation is urgent, but execution capacity is uneven. Firms that can mobilize blended teams, leverage alliances, and scale delivery through standardized toolkits are gaining an advantage, while those dependent on bespoke, high-cost teams risk margin compression and slower responsiveness.
3. Competitive Landscape and Leading Strategies
Strategic Positioning Across Different Firm Archetypes
The competitive map is defined less by uniform scale than by differentiated positioning along strategy, operations, technology, and industry depth. At one end are global strategy-oriented firms that compete on thought leadership, senior client access, and cross-functional problem framing. These firms typically build their reputations on high-stakes decisions, corporate strategy, and transformation direction-setting. At another end are firms with strong implementation credentials, where consulting is integrated with technology services, systems integration, or outsourcing capabilities. These players compete on end-to-end delivery, scale, and the ability to transition recommendations into operational reality. A third archetype includes specialized boutiques that win through depth in narrow domains, such as private equity value creation, risk and actuarial advisory, or growth strategy in particular industries.
The largest players illustrate these strategic choices clearly. McKinsey & Company positions around strategy, digital transformation, and operations advisory, and is actively reinforcing that model with large-scale AI deployment to improve productivity and client delivery. Boston Consulting Group emphasizes strategy, corporate finance, and digital innovation, with a focus on business and government clients, suggesting a balanced orientation toward high-level problem formulation and digital execution. Bain & Company leans into strategy, private equity, and operations, aligning its brand with value creation and performance-focused engagements. Accenture differentiates through the integration of consulting with technology and digital transformation solutions, making implementation capacity a core part of its advisory proposition. Deloitte, PwC, EY, and KPMG each offer management consulting within broader professional services portfolios, allowing them to connect advisory work with audit, tax, technology, and risk capabilities. Oliver Wyman, Booz Allen Hamilton, Capgemini, L.E.K. Consulting, and Kearney further diversify the landscape through specialized strengths in risk management, government and technology solutions, AI-enabled operations, growth advisory, and strategy-operations integration.
Business Management Consulting Service Market
Differentiation Through Capability, Alliance, and Delivery Models
The most sustainable advantages in this market are emerging from three sources. The first is proprietary capability that can be scaled, including AI-enabled analysis, decision-support tools, and reusable transformation frameworks. The second is ecosystem positioning, where alliances and partnerships extend a firm’s reach into adjacent domains such as actuarial risk, systems integration, or industry-specific implementation. The third is delivery architecture, where firms design engagements to leave behind capabilities, governance, and measurement systems rather than one-off recommendations. These advantages matter because clients increasingly evaluate providers on repeatability, speed, and the ability to transfer knowledge into the organization.
Recent moves highlight how these differentiators are being operationalized. Oliver Wyman’s April 2026 strategic partnership with Actuarial teams under Marsh McLennan is an example of extending strategy and risk advisory capabilities through specialized integration, strengthening the firm’s position where financial, operational, and risk considerations intersect. Such alliances reflect a broader trend in which consulting firms expand credibility and coverage by partnering with domain specialists rather than building every competency internally. This pattern is likely to accelerate where complexity is high and where the cost of building proprietary depth in every niche would be prohibitive.
Toward Consolidation, Fragmentation, and Selective New Entry
Market structure is evolving along multiple axes at once. Concentration at the top remains significant, which implies that scale, brand, and global client access continue to confer advantages in large enterprise accounts and multi-year transformation programs. At the same time, the front edge of competition is fragmenting as practice-level specialization, regional capability centers, and technology-led delivery models create new competitive dynamics. New entrants and mid-tier challengers are gaining relevance where they can offer speed, niche depth, or more flexible commercial terms, particularly in engagements that require rapid mobilization or deep operational involvement.
The likely trajectory is not simple consolidation or fragmentation, but selective combination. Larger firms will continue to acquire reach and cross-functional breadth, but they will also face pressure to modularize services and improve delivery economics. Specialized players will seek to scale through partnerships, productized offerings, or targeted expansion into adjacent capabilities. Meanwhile, technology providers and implementation-centric firms will continue to blur the line between consulting and execution, creating hybrid competition that traditional strategy firms must either match or complement through alliances. For buyers, this means that provider selection is becoming more multidimensional, with evaluation criteria that include capability depth, delivery model, technology enablement, and the ability to integrate with internal teams.
4. Future Trends and Commercial Implications
Trend One: AI-Augmented Advisory Becomes the Delivery Default
Over the next three to five years, AI-augmented advisory is expected to shift from a differentiator to a baseline expectation. The combination of agentic AI, advanced analytics, and human judgment will become embedded in problem definition, scenario design, benchmarking, and implementation planning. The commercial implication is significant: engagements that rely solely on manual analysis will face growing cost and speed disadvantages, while firms that can operationalize AI safely and effectively will be able to scale insight generation and improve throughput. The opportunity lies not in replacing consultants, but in reconfiguring the value chain so that human expertise concentrates on judgment, client alignment, and implementation design while AI supports volume-intensive analytical tasks. The risk is execution discipline: firms that deploy AI without strong governance, validation, and client-ready explainability may expose themselves to quality and trust issues, especially in regulated or high-stakes contexts.
Trend Two: Outcome-Oriented Commercial Models Gain Ground
Commercial models are likely to continue shifting toward measurable outcomes, with pricing and incentives tied more closely to business impact, adoption metrics, and sustained operating improvements. This trend will be reinforced by rising labor costs and client demand for greater accountability. Advisory engagements will increasingly need to define success in operational terms, such as improved throughput, reduced cost-to-serve, faster decision cycles, or stronger customer outcomes. For providers, this creates both opportunity and risk. The opportunity is to build repeatable frameworks that connect strategy to execution and to develop measurement systems that demonstrate value over time. The risk is that outcome-based models require deeper client integration, stronger change management, and the ability to navigate implementation complexity, which may not suit all engagement types or all buyers.
Trend Three: Regulatory and Compliance Complexity Drives Demand for Governance-Led Transformation
Regulatory and compliance complexity is expected to remain a structural driver of demand, particularly in sectors where data usage, technology deployment, and decision automation are accelerating. Organizations will increasingly seek advisory support not only for growth and efficiency, but for governance design, risk integration, and compliance-ready operating models. This opens commercial opportunities for firms that can connect strategy, operations, and technology with clear accountability and auditability. At the same time, it introduces uncertainty: regulatory trajectories differ across regions, and expectations around data privacy and technology governance may evolve quickly. Firms that can maintain methodological rigor while adapting to local requirements will be better positioned than those relying on one-size-fits-all frameworks. A further uncertainty is the potential for regulatory fragmentation to slow cross-border delivery models or increase the cost of data reuse across engagements.
Uncertainty and Risk Factors to Monitor
Several factors could alter the trajectory of growth and competitive dynamics. Continued escalation in specialized labor costs may compress margins for firms that cannot offset them through productivity improvements or delivery redesign. Talent shortages in AI and digital transformation could constrain the speed at which firms scale new capabilities, particularly in regions where skilled professionals are scarce. Regulatory developments may raise compliance costs or limit the reuse of data and models across engagements, affecting both economics and speed. In addition, client budget discipline could shift spend toward a smaller number of higher-conviction initiatives, intensifying competition for large mandates while reducing appetite for exploratory work. These risks do not negate growth, but they suggest that the market will reward firms that manage cost, compliance, and capability deployment with discipline.
5. Strategic Actions for Decision Makers
For Transformation Leaders and Operating Executives
Treat advisory selection as an execution decision, not just a strategy purchase. When evaluating providers, prioritize those that can demonstrate how insight will translate into operating change, including clear handoff to implementation, reusable tools, and measurable success criteria. Favor engagements that are designed to build internal capability and leave behind decision-support assets rather than static deliverables. Given rising labor costs and talent constraints, also assess whether a provider’s delivery model uses automation, knowledge reuse, and blended teams in ways that protect speed and quality without inflating cost.
For Investors and Portfolio Managers
Evaluate consulting exposure with attention to delivery economics and positioning, not only revenue scale. Firms that combine domain depth with AI-enabled productivity, implementation alliances, and outcome-oriented commercial models are better placed to sustain margins in a cost-escalating environment. Monitor concentration carefully, but also watch the specialized and hybrid players that are gaining traction in high-complexity niches. The most useful signals will come from evidence of repeatable delivery, credible governance around data and AI, and the ability to win engagements where execution—not just diagnosis—is the primary value driver.
PW Consulting
For Procurement and Commercial Teams
Use the shifting supply landscape to improve commercial terms and risk allocation. Expect greater variation in pricing models, delivery approaches, and liability structures, which creates room to negotiate outcome-linked components, clearer data-handling obligations, and stronger handoff arrangements. Where possible, assemble multi-provider portfolios that separate strategy, implementation, and specialist risk or technology work, allowing each partner to play to its strengths. Ensure that procurement criteria include governance standards, methodological transparency, and evidence of capability transfer, since these will increasingly determine whether an engagement creates durable value or remains a short-term intervention.
Computer Consulting Services Market
The trajectory of the management consulting services market is being shaped by the convergence of technology-enabled delivery, regulatory complexity, rising talent costs, and a client base that is more demanding in return for its spend. These forces are not simply expanding the market; they are redefining where value is created and how competitive advantage is earned. For decision makers seeking to act with precision—whether in provider selection, investment allocation, or transformation planning—the value of detailed segment-level data, competitive mapping, and customized scenario analysis is substantial. A comprehensive research report can provide deeper visibility into regional and functional splits, company-level positioning, and forward scenarios that support more targeted execution.
For detailed analysis of this topic, please visit the official page: Management Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Organic Elemental Analyzer Market: What the 6.98% 2032 Growth Path Really Means
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Organic Elemental Analyzer Market
The global market for Organic Elemental Analyzers (OEA) has entered a phase of sustained, structurally driven expansion. Valued at approximately USD 215.0 million in 2025, the sector has demonstrated consistent upward momentum over the past half-decade, building from a baseline of USD 163.15 million in 2020. The trajectory is projected to accelerate through the forecast horizon, reaching an estimated USD 344.8 million by 2032. This translates to a compound annual growth rate of 6.98 percent, a figure that places the market above the broader analytical instrumentation sector average. Growth is not merely cyclical; it reflects a fundamental recalibration in how laboratories, manufacturers, and regulatory bodies approach material characterization, quality assurance, and environmental compliance.
The expansion narrative, however, cannot be reduced to aggregate numbers. The market is navigating a complex landscape where technological capabilities, supply chain realities, and end-user expectations are intersecting. Below the headline growth rate lies a competitive environment shaped by consolidation pressures, regional demand divergence, and rapid innovation in combustion and detection methodologies. Stakeholders who understand the underlying mechanics of this expansion will be better positioned to allocate capital, design product roadmaps, and negotiate procurement strategies with confidence.
Market Architecture and the Friction Points Defining the Next Cycle
The current market architecture is characterized by a moderate degree of concentration. The three largest players collectively account for roughly 24.6 percent of total revenue, while the top five firms control approximately 26.2 percent. This distribution suggests a market that remains sufficiently fragmented to allow specialized entrants and regional champions to compete on niche capabilities, yet consolidated enough that incumbents hold meaningful pricing power, distribution leverage, and service network advantages. The gap between the top three and top five is notably narrow, indicating that mid-tier competitors are increasingly closing the performance and commercial coverage gap through targeted product development rather than broad-spectrum expansion.
Several structural challenges are simultaneously acting as inflection points. First, the cost and complexity of analytical workflows continue to pressure end-user budgets, particularly in mid-sized laboratories and contract research organizations operating under tight capital expenditure constraints. High-caliber OEA systems require robust sample preparation protocols, calibrated reference materials, and specialized maintenance routines. When total cost of ownership rises faster than budget allocations, procurement cycles elongate and buyers increasingly scrutinize return on investment at the application level rather than the instrument level.
Total Organic Carbon (TOC) Analyzer Market
Second, the industry is grappling with a skills and operational expertise gap. Modern elemental analyzers integrate sophisticated combustion chambers, automated gas handling, and advanced detection optics. While automation has reduced manual intervention, operators still require training in method validation, baseline drift management, and cross-application method transfer. Institutions that cannot staff adequately or upskill existing personnel face throughput bottlenecks, which in turn dampen the perceived utility of higher-throughput systems and slow replacement cycles for legacy assets.
Third, supply chain volatility for high-purity reagents, specialized catalysts, and precision-machined components has introduced uncertainty into both manufacturing lead times and service-level commitments. Even as logistics networks normalize following earlier disruptions, the underlying dependency on tightly specified consumables and calibration standards means that any regional constraint or pricing shift can ripple through deployment schedules and affect near-term revenue recognition for manufacturers.
These challenges are not merely obstacles; they are forcing functions that are reshaping competitive priorities. Manufacturers that can decouple performance from consumables consumption, streamline software-driven calibration, and offer application-specific validation packages are gaining traction. Buyers that internalize total cost of ownership calculations and align instrument selection with validated workflow requirements are reducing unexpected downtime and improving analytical consistency across campaigns.
Key Drivers Accelerating Market Trajectory
Technical Innovation as the Primary Growth Engine
The most consequential driver of market expansion is the steady progression of combustion and detection technologies. Contemporary OEA platforms increasingly deliver simultaneous determination of carbon, hydrogen, nitrogen, sulfur, and oxygen within unified analytical runs, reducing the need for sequential testing and minimizing sample consumption. This capability is particularly valuable in environments where throughput, repeatability, and sample scarcity intersect. High-throughput modules, automated sample introduction, and software-assisted method selection have lowered the operational burden for routine analyses while expanding the range of matrices that can be processed reliably.
A notable example of this direction is found in the FlashSmart Elemental Analyzer and the FLASH 2000 Series, which are engineered to provide simultaneous CHNS/O determination tailored for pharmaceutical workflows and analytical laboratories. These systems illustrate how modern architectures prioritize streamlined sample handling, integrated data processing, and robust baseline stability to meet the documentation and reproducibility standards expected in regulated environments. By compressing the time between sample loading and validated output, such platforms directly address the throughput and consistency pressures that laboratories face when scaling analytical operations.
Policy and Regulatory Mandates Expanding the Addressable Base
Regulatory frameworks and compliance requirements continue to broaden the applications for which elemental analysis is indispensable. In pharmaceutical and fine chemical manufacturing, stringent impurity profiling, identity confirmation, and batch consistency checks depend on reliable carbon, nitrogen, and sulfur determinations. Environmental testing and waste characterization protocols similarly require accurate organic composition data to support reporting, risk assessment, and remediation planning. As jurisdictions tighten reporting standards and enforcement diligence, laboratories and industrial quality teams are compelled to formalize their analytical capabilities rather than rely on ad hoc testing or outsourced services.
This regulatory tailwind does not simply increase volume; it changes the purchasing calculus. Buyers seek instruments with traceable method documentation, validated performance characteristics, and service support that can withstand audit scrutiny. The compliance dimension elevates the importance of vendor reputation, application support, and long-term availability of consumables and software updates. In many procurement scenarios, the decision to standardize on a particular platform is as much about risk management and audit readiness as it is about analytical performance.
Demand-Side Shifts in Quality Assurance and Advanced Materials
Demand patterns are evolving as end-users place greater emphasis on predictive quality and material consistency. Semiconductor-related manufacturing and advanced packaging workflows, for example, require rigorous control over organic residues, process contaminants, and material purity indicators. While the OEA category spans diverse end uses, the semiconductor wafer manufacturing segment has emerged as a substantial demand driver, reflecting the industry's need for precise characterization of materials that influence device yield and reliability. IC packaging activities also contribute meaningfully, as miniaturization and heterogeneous integration increase the sensitivity of final device performance to surface chemistry and organic contamination profiles.
Beyond electronics, food, feed, and organic matrix testing remain significant application areas where carbon, hydrogen, nitrogen, and protein determinations underpin nutritional labeling, authenticity verification, and quality control. The 828 Series macro combustion analyzer, focused on carbon, hydrogen, nitrogen, and protein in food, feeds, and organic matrices, reflects how instrument design is being adapted to application-specific throughput and sample-scale requirements. When analytical platforms align closely with the sample type, throughput expectations, and reporting formats of a given industry, adoption friction decreases and replacement cycles accelerate.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the interplay between instrument capability, consumables intensity, and regional service economics. Manufacturers are increasingly differentiating on the basis of how efficiently their systems consume reagents and reference materials, how predictable maintenance intervals are, and how quickly field service can restore operational status. In parallel, regional service density and local technical support availability have become decisive factors for buyers in markets where downtime carries high cost. Companies that build or partner into responsive service networks, localize consumable supply where feasible, and provide remote diagnostics and software-based troubleshooting are strengthening their commercial resilience.
The vario EL cube platform, which offers simultaneous CHNS with oxygen, chlorine, and total inorganic carbon determination across micro to macro sample ranges, demonstrates how expanded parameter coverage and flexible sample handling can command premium positioning. By consolidating multiple analytical objectives into a single workflow, such systems reduce fragmentation in laboratory inventories and simplify method management. This value proposition is especially relevant for organizations that seek to standardize instrumentation across multiple sites or consolidate legacy platforms onto a modern, software-integrated architecture.
Competitive Landscape and the Logic of Differentiation
Incumbent Positioning and Capability Mapping
The competitive field is anchored by a group of established manufacturers with distinct strategic orientations. Thermo Fisher Scientific, based in Waltham, Massachusetts, competes through integrated analytical portfolios that emphasize simultaneous CHNS/O determination and laboratory workflow compatibility, particularly in pharmaceutical and analytical lab settings. The company's positioning leverages broad commercial coverage, established service infrastructure, and the ability to embed elemental analysis into wider laboratory information and quality management ecosystems.
LECO Corporation, headquartered in St. Joseph, Michigan, has built recognition around macro combustion analysis for carbon, hydrogen, nitrogen, and protein applications in food, feeds, and organic matrices. Its strategic emphasis reflects deep application focus, robust engineering tradition in combustion analysis, and a commercial approach that prioritizes method reliability and throughput for high-volume routine testing. This application specialization enables the firm to serve buyers whose primary concern is consistency across large sample populations rather than maximally broad elemental coverage.
Elementar Analysensysteme, located in Langenselbold, Germany, addresses the market with platforms that combine simultaneous CHNS capability with oxygen, chlorine, and total inorganic carbon determination for micro to macro sample analysis. The strategic logic here centers on analytical flexibility, parameter expansion within a single instrument, and the ability to serve laboratories that need to consolidate multiple characterization tasks. European manufacturing heritage, precise engineering, and configurable sample handling contribute to a value proposition that appeals to organizations seeking method consolidation and enhanced data continuity.
OEA Laboratories, based in Exeter, United Kingdom, occupies a complementary position by focusing on supplies and products designed for use with OEA and EA-IRMS instruments. Rather than competing directly on complete instrument platforms, the company supports the consumables, accessories, and application ecosystem that surround elemental analysis workflows. This positioning can be strategically valuable for buyers that prioritize supply reliability, application-specific consumables optimization, and ecosystem compatibility across different instrument brands.
PerkinElmer, also headquartered in Waltham, Massachusetts, competes through established analytical instrumentation offerings such as the 2400 CHNS/O Organic Elemental Analyzer for total carbon, nitrogen, hydrogen, and sulfur determination. Its market presence benefits from a broad instrument portfolio, longstanding relationships in analytical laboratories, and integration pathways that connect elemental analysis with other characterization and quality control functions within laboratory environments.
Strategic Patterns in a Consolidating yet Accessible Market
The market is not trending toward extreme concentration; instead, it is evolving toward functional specialization and ecosystem-based competition. The relatively narrow gap between the top three and top five firms suggests that competitive advantage is increasingly derived from application-specific validation, software-enabled workflow simplification, service responsiveness, and consumables efficiency rather than from sheer scale alone. Incumbents with broad portfolios can leverage cross-selling and service density, while focused competitors can gain share by solving a narrowly defined problem exceptionally well and building reference installations that propagate through industry networks.
New entrants and regional specialists continue to find viable niches, particularly where local service expectations, language and compliance requirements, or application-specific sample types create friction for global platforms that are not sufficiently localized. At the same time, acquisition activity and partnership strategies are quietly reshaping the landscape. Larger players seek to strengthen application coverage, consumables supply chains, and geographic service reach, while mid-tier firms explore agreements that expand their parameter coverage or software capabilities without undertaking full-platform development programs.
For procurement leaders and investors, the strategic implication is that vendor evaluation should extend beyond headline specifications. The durability of a purchasing decision depends on the alignment between instrument architecture and validated workflows, the predictability of consumables and service costs, the availability of method support for the specific matrices in use, and the likelihood that the platform can evolve as application requirements change. Competitors that invest in these dimensions are building switching costs that are based on operational reliability and data continuity rather than on lock-in alone.
PW Consulting
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Workflow Consolidation and Software-Defined Analysis
Over the next several years, the market is likely to reward platforms that reduce the complexity of method selection, calibration management, and data interpretation. Software-defined workflows that guide users from sample preparation through validated result reporting will become more important as laboratories seek to standardize operations across sites and reduce dependence on highly specialized operators. The commercial opportunity lies not only in instrument sales but in the recurring value of software subscriptions, method libraries, remote configuration support, and training ecosystems that lower the operational burden for buyers. Organizations that can demonstrate measurable reductions in setup time, method transfer errors, and result variability will capture disproportionate share in regulated and high-throughput environments.
A risk to monitor is the potential for software complexity to outpace user readiness. If interface design and validation tools are not intuitive, the promised efficiency gains may be undermined by longer adoption cycles and increased reliance on external support. Vendors that invest in user experience, documentation clarity, and role-based access will differentiate themselves in a segment where operational simplicity is becoming a competitive requirement.
Trend Two: Regional Demand Divergence and Service-Led Growth
Demand is expected to continue diverging by region, with Asia Pacific representing a substantial share of market expansion, North America sustaining strong adoption driven by pharmaceutical, analytical, and advanced manufacturing demand, and Europe maintaining robust activity shaped by regulatory and industrial testing requirements. Latin America and the Middle East and Africa will likely grow from smaller bases, with adoption shaped by the pace of laboratory modernization, regulatory formalization, and the availability of localized service support. The commercial opportunity for manufacturers is to align regional go-to-market strategies with local application priorities, establish service density where downtime is costly, and offer financing or managed-service models that reduce upfront capital barriers for mid-sized buyers.
A key uncertainty is the degree to which macroeconomic fluctuations and currency volatility affect procurement timing in emerging markets. Even when underlying demand is strong, budget cycles and foreign exchange dynamics can delay deployment. Companies that build flexible commercial terms and maintain reliable local consumables availability will be better positioned to convert demand into installed base over time.
Trend Three: Application Convergence and Cross-Industry Method Transfer
As analytical requirements become more tightly integrated into quality systems, there will be increasing interest in platforms capable of supporting method transfer across applications and sites with minimal revalidation burden. Laboratories that serve multiple industries or that operate shared analytical facilities will favor instruments that can accommodate diverse matrices while maintaining consistent performance characteristics. This trend creates opportunities for vendors that provide robust application libraries, cross-method validation guidance, and consumables configurations optimized for multi-application environments. The strategic benefit will accrue to organizations that can reduce the friction of moving methods between development, quality control, and contracted testing workflows.
The primary risk is that application diversity can also fragment demand if instruments are perceived as too specialized or too generalized. Vendors must strike a balance between parameter coverage, sample-scale flexibility, and the clarity of application-specific support. Overreach into configurations that dilute ease of use or inflate consumables overhead can weaken adoption, while overly narrow designs may miss cross-selling opportunities in laboratories with expanding analytical portfolios.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Product strategy should prioritize the intersection of analytical performance and operational simplicity. Investments in simultaneous multi-parameter determination, predictable consumables consumption, and software-assisted method management are likely to yield the strongest competitive returns. Equally important is the development of application-specific validation packages and service models that reduce total cost of ownership for buyers in regulated and high-throughput environments. Manufacturers that can articulate measurable improvements in throughput, repeatability, and method transfer efficiency will strengthen their positioning against both broad-portfolio incumbents and focused niche competitors.
Commercial strategy should emphasize regional service density and local application support where downtime and compliance scrutiny are significant concerns. Aligning consumables supply, calibration standards, and remote diagnostics with the realities of local procurement cycles can improve both win rates and long-term retention. For organizations considering portfolio expansion, targeted acquisitions or partnerships that add parameter coverage or software capabilities may deliver faster market impact than full-platform development programs.
For Investors and Strategic Allocators
Investment theses should account for the market's moderate concentration and the enduring role of application specialization. Recurring revenue streams tied to consumables, service agreements, and software support are valuable complements to instrument sales, particularly where buyers prioritize predictable operating costs and rapid issue resolution. When evaluating opportunities, diligence should examine not only technological specifications but also the depth of application validation, the reliability of consumables supply, and the credibility of regional service networks. Companies that can demonstrate durable customer relationships in regulated or high-volume applications are better positioned to sustain growth through procurement cycles and regional volatility.
Portfolio diversification across application areas and regions can reduce exposure to localized demand shocks, but only if the underlying commercial model supports effective service delivery and consumables management. Investors should also monitor the pace of consolidation and partnership activity, as these dynamics can reshape competitive advantages in parameter coverage, service reach, and software ecosystems faster than organic product roadmaps alone.
For Procurement Leaders and Laboratory Managers
Procurement decisions should be anchored in validated workflow fit rather than nominal specification comparisons. Evaluate platforms against the specific matrices, throughput requirements, documentation standards, and reporting formats that your operations demand. Assess total cost of ownership with explicit consideration of consumables consumption, calibration frequency, maintenance intervals, and the availability of local service and remote diagnostics. Where possible, structure evaluations around method transfer scenarios and multi-application use cases to ensure that the selected platform can support evolving analytical needs without excessive revalidation burden.
Worldwide Automatic Elemental Analyzer Market
Negotiation strategies should account for software support, training, and consumables predictability as value levers alongside hardware pricing. Establishing clear expectations for service response times, software update continuity, and application support can reduce operational risk and improve long-term return on investment. In multi-site organizations, standardizing on platforms that simplify method management and deliver consistent performance across locations can yield operational savings that exceed the apparent price differential between alternatives.
Why Detailed Market Intelligence Remains Essential
The Organic Elemental Analyzer market is expanding along a credible growth trajectory, but the most consequential decisions will be made at the level of application fit, service economics, and workflow integration rather than at the level of aggregate demand. The segmentation of demand across regions, instrument types, and application contexts matters because it determines where competitive advantage is created and where procurement risk is concentrated. Detailed breakdowns of regional dynamics, product-type adoption patterns, and application-level volume distribution provide the granularity needed to calibrate product strategy, service investments, and purchasing decisions with precision.
Executive teams, strategic planners, and investors who require that level of granularity can benefit from the full research report, which provides comprehensive segmentation data, company profiles, and forward-looking scenario analysis. Access to detailed submarket data and tailored strategic recommendations enables more disciplined capital allocation, more confident procurement negotiations, and more targeted product development priorities. For organizations seeking to act on the trends outlined here with specificity and speed, the complete research resource offers the depth required to translate market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Organic Elemental Analyzer (OEA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Driving Recorder Market Set for 8.5% CAGR Growth Through 2032: Strategic Shifts Redefining Profitability
By PW Consulting, 2026-09-21
The Driving Recorder Market: Strategic Shifts and Commercial Opportunities from 2025 to 2032
The global market for driving recorders, commonly known as car dashcams, has grown from approximately US$163 million in 2020 to an estimated US$215 million in 2025. This trajectory reflects a compound annual growth rate of roughly 8.5 percent through 2032, when revenue is projected to exceed US$344 million. Behind these figures lies a sector undergoing structural transformation: what began as a consumer safety accessory is evolving into a data-rich, connectivity-enabled platform that intersects fleet management, insurance telematics, and advanced driver-assistance systems.
The market is no longer defined solely by onboard video capture. Multi-lens configurations, artificial intelligence–based event detection, and cloud-synchronized storage are reshaping product expectations across passenger cars, commercial fleets, and specialized applications. At the same time, supply chain friction, memory cost volatility, and shifting regulatory frameworks are introducing both constraints and differentiation opportunities. The following analysis maps the forces reshaping the driving recorder landscape and outlines where strategic value is likely to accrue over the next three to five years.
Market Snapshot and Core Challenges Facing the Industry
Revenue across the global driving recorder market reached US$215 million in 2025 and is projected to expand to US$344 million by 2032, supported by an 8.5 percent CAGR over the 2026–2032 period. The segment has demonstrated resilience through recent macroeconomic volatility, with year-over-year growth resuming after a brief contraction in 2022.
PW Consulting
Two structural challenges are defining the near-term operating environment. First, cost pressure from memory and semiconductor inputs is compressing margins for hardware-first players. Memory chip prices used in dashcams have risen 80 to 90 percent since late 2025, driven by surging AI data storage demand and allocation-only procurement practices among leading suppliers. Semiconductor lead times have been climbing for a full year and spiked dramatically in early 2026, with top-component lead times reaching 40 weeks. These dynamics create inventory planning complexity, lengthen time-to-market for new model iterations, and favor companies with stronger supplier relationships or differentiated bill-of-materials strategies.
Second, the market is navigating a maturity inflection in the consumer segment while simultaneously opening a higher-value pathway in commercial and connected-vehicle applications. Single-lens dashcams continue to anchor a substantial share of revenue, but multi-lens and AI-enabled configurations are expanding as fleet operators, insurers, and OEMs seek richer data sets. The strategic question is no longer whether to add connectivity or analytics, but how to do so without triggering a margin squeeze from raw-material inflation or exposing the product to cyber and data-privacy vulnerabilities that accompany cloud-based architectures.
A third, more geopolitical challenge is emerging around export controls and hardware provenance. Policy activity, including the April 2026 House Foreign Affairs Committee markup of national security-focused bills such as the Stop Stealing Our Chips Act, signals a more active regulatory posture around semiconductor and electronics supply chains. For manufacturers that rely on cross-border component sourcing or assemble in specialized hubs, this trend introduces planning uncertainty and may accelerate regional sourcing shifts or dual-supplier strategies.
Key Drivers Shaping the Driving Recorder Market
Technological Innovation and the Shift Toward AI-Enabled Recording
The most consequential technological shift is the migration from passive recording to intelligent event detection and post-incident analytics. Recent product introductions illustrate this direction. In April 2026, Thinkware introduced its flagship U3000 dash cam with 4K/2K resolution, built-in front and rear RADAR sensors, Sony STARVIS 2 image sensors, ADAS alerts, and mobile-app connectivity. In March 2026, BlackVue released the DR770X Box triple-camera cloud-compatible system with a separate secure recording unit designed for enhanced parking surveillance in fleet applications. These launches reflect a broader industry move toward higher resolution, sensor fusion, and dedicated storage architectures that preserve evidence even when primary systems are offline.
The practical implication for manufacturers and fleet operators is that video is increasingly treated as one input within a larger safety and compliance data stack. AI-based event classification, driver behavior scoring, and voice alerts are reducing reliance on manual footage review. Geotab’s September 2025 launch of the GO Focus Plus AI dashcam, which incorporates voice alerts and a video intelligence platform reported to reduce risky driving behaviors by up to 95 percent in fleet pilots, is an early indicator of how analytics can translate directly into measurable safety outcomes. For companies evaluating product roadmaps, the opportunity lies in pairing reliable image capture with differentiated analytics, low-latency alerts, and integration-friendly data outputs.
Policy and Regulatory Dynamics Supporting Adoption
Regulatory and compliance trajectories are creating tailwinds for higher-quality recording solutions, particularly in commercial and fleet environments. Although the specific content and timing of regulations vary by jurisdiction, the broader direction favors evidence-grade documentation, driver safety accountability, and telematics integration. At the same time, policy activity around semiconductors and electronics adds a layer of operational complexity. The April 2026 markup of export-control-related bills and ongoing scrutiny of chip supply chains suggest that companies should treat supply chain resilience and component traceability as strategic priorities rather than back-office concerns.
The commercial opportunity here is twofold. First, fleet operators and insurance-linked programs increasingly prefer dashcam solutions that can demonstrate consistent functionality, clean data handling, and integration with existing compliance workflows. Second, OEMs and tier-one suppliers are exploring ways to embed recording capabilities more tightly into vehicle architectures. In February 2025, Magna International advanced next-generation front camera systems for OEMs that integrate higher-resolution imaging with onboard video recording capabilities within a single ADAS module. This type of integration suggests a future in which aftermarket and OEM recording functions converge, expanding the addressable opportunity while also raising the competitive bar for standalone hardware.
Demand-Side Evolution Across Passenger Cars and Commercial Fleets
Consumer demand continues to be driven by safety concerns, insurance incentives, and a growing expectation that vehicles should document incidents clearly and reliably. Passenger cars remain the largest application category, reflecting broad adoption of dashcams as both a protection tool and a driver-assistance aid. However, the most dynamic growth is occurring where recording intersects with operational value: fleet safety programs, driver coaching, claim verification, and parking-mode protection.
Commercial vehicles represent a smaller but strategically important segment. Fleet operators are drawn to multi-channel systems and cloud-compatible architectures that support centralized monitoring, evidence preservation, and integration with broader telematics platforms. The appeal of separate secure recording units for parking surveillance, as seen in recent BlackVue fleet-oriented offerings, underscores a practical need: commercial users want continuity of protection when vehicles are unattended, plus administrative simplicity when incidents occur. As parking-mode features and ADAS alerts become standard expectations in premium segments, products that fail to offer robust post-event capture or seamless mobile connectivity risk losing share in higher-margin applications.
Supply Chain and Cost Structure Pressures
The cost environment is a defining constraint for the sector. The sharp rise in memory chip prices and extended semiconductor lead times mean that hardware planners must balance performance upgrades against input-cost volatility. Suppliers and integrators that can secure allocation, diversify sources, or design around memory-intensive architectures will have an advantage in maintaining price competitiveness. At the same time, the trend reinforces the case for software and service margins, subscription-linked features, and analytics offerings that can generate recurring revenue independent of component cost cycles.
This dynamic also favors consolidation and partnership. Companies with established supplier relationships, regional manufacturing flexibility, or strong logistics capabilities are better positioned to manage lead-time volatility. Conversely, smaller hardware-only entrants may find it increasingly difficult to compete on both speed-to-market and cost discipline without a clear software, integration, or brand differentiation.
Competitive Landscape and Leading Strategies
The driving recorder market remains moderately fragmented, with five companies accounting for roughly 48 percent of revenue and three firms representing about 32 percent. This concentration suggests that leading players have meaningful brand and distribution advantages, yet the sector still leaves room for specialized entrants that address fleet, premium consumer, or OEM-adjacent use cases.
Dashboard Camera Market
Viofo, based in Shenzhen, has built a reputation around professional-grade dash cameras featuring Sony STARVIS 2 IMX sensors, 4K ultra-high-definition recording, and advanced multi-channel recording. Its positioning reflects a clear focus on image quality and multi-channel capture, which appeals to users who prioritize evidence-grade footage. BlackVue, headquartered in Seongnam-si, South Korea, competes in the premium segment with 4K UHD dash cams, cloud features, parking mode protection, and triple-camera cloud-compatible systems. BlackVue’s strategy leans toward connectivity and continuous protection, particularly in scenarios where vehicles are parked and unattended.
70mai, based in Shanghai, has positioned itself as an innovator in smart car electronics with intelligent dash cams that combine AI features, 4K recording, and safety enhancements. Its approach emphasizes intelligent functionality and broader vehicle-electronics integration, aligning with consumer expectations for connected devices. In North America, Garmin contributes an automotive portfolio that includes wireless backup cameras, voice-controlled models, and GPS integration, giving it an advantage in ecosystems where navigation and vehicle electronics are purchased together. Thinkware, based in Coquitlam, British Columbia, is recognized as a global leader in premium dash cams with 4K UHD, AI parking surveillance, ADAS alerts, and mobile-app connectivity. Thinkware’s advantage lies in bundling high-resolution recording with radar-based sensing and app-level interaction, which supports both consumer and fleet-oriented positioning.
Vantrue operates in the United States with a premium high-end lineup focused on 4K ultra-HD recording and multi-channel options for automobile security, reinforcing a niche for users who want comprehensive coverage in a single device. Nextbase, based in the United Kingdom, has built an award-winning portfolio around high-resolution recording, fleet-optimized solutions, and proven safety features, giving it a strong narrative in markets where fleet safety and image quality are deciding factors. Pittasoft, also headquartered in Seongnam-si, South Korea, is associated with BlackVue premium dash cams and emphasized capabilities in cloud security, parking surveillance, and advanced video analytics, underscoring how software and data-management value can complement hardware.
Recent developments suggest the competitive edge is shifting toward integration and analytics. Geotab’s September 2025 launch of the GO Focus Plus AI dashcam with voice alerts and a video intelligence platform, which reportedly cut risky driving behaviors by up to 95 percent in fleet pilots, highlights how behavior-reduction messaging and video analytics can become differentiating value propositions in fleet environments. Thinkware’s April 2026 U3000 launch and BlackVue’s March 2026 DR770X Box release reinforce a premiumization trend in which multi-camera setups, secure storage units, and sensor-enhanced ADAS alerts are becoming standard features in higher-tier products. Magna’s February 2025 work on OEM-integrated front camera systems with onboard video recording indicates that the boundary between aftermarket and factory-installed recording is beginning to blur, a development that could reshape channel dynamics over time.
The strategic takeaway is that winning products are increasingly defined by more than resolution or channel count. Differentiation is coming from cloud compatibility, parking-mode resilience, ADAS-linked alerts, behavior analytics, and integration with fleet or telematics platforms. Companies that can combine reliable capture with actionable data outputs and robust supply-chain execution are best positioned to defend margins and capture share in the next phase of growth.
Forward-Looking Trends and Commercial Implications
Trend 1: AI and Video Intelligence Become Baseline Expectations
Over the next three to five years, AI-based detection and video intelligence are likely to move from premium differentiators to baseline expectations, especially in commercial and fleet applications. Voice alerts, event classification, and behavior scoring will increasingly be expected alongside high-resolution capture. This shift creates opportunities for products that can translate video into measurable safety improvements and for service models that help operators act on footage without large manual review teams. It also raises the importance of algorithm reliability, false-positive management, and data governance, since poorly tuned analytics can erode trust quickly.
Trend 2: Convergence of Aftermarket and OEM-Embedded Recording
The integration of recording capabilities into ADAS-related modules, as signaled by Magna’s next-generation front camera systems, points toward a future where onboard recording is more tightly embedded in vehicle architecture. This convergence could expand adoption through factory channels while increasing competition for standalone aftermarket devices. Manufacturers that can offer complementary aftermarket products, retrofit solutions, or strong integration interfaces may be able to serve customers who choose either path. The risk is that purely hardware-focused aftermarket products lose relevance if OEMs make recording a standard part of the vehicle package.
Worldwide Car Video Monitors Market
Trend 3: Supply-Chain Resilience and Component Cost Management as Strategic Capabilities
With memory chip prices up significantly since late 2025 and semiconductor lead times extending toward 40 weeks for key components, supply-chain management is becoming a strategic capability rather than a procurement exercise. Companies that diversify memory sourcing, optimize storage architectures, and build allocation resilience will be better able to sustain product launches and pricing. There is also an opportunity to shift some value toward software, cloud analytics, and subscription-linked features that are less exposed to component cost swings. The primary risk is that cost pressure forces broad price increases before consumers or fleet buyers are ready to absorb them, potentially slowing volume growth in price-sensitive segments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize sensor quality, multi-channel reliability, and ADAS-linked alert features as core product pillars, since these are becoming table stakes in premium consumer and fleet segments.
- Invest in analytics, cloud compatibility, and parking-mode resilience that deliver measurable operational value, rather than competing only on resolution or channel count.
- Strengthen memory and semiconductor sourcing strategies now, including supplier diversification and storage-architecture optimization, to reduce exposure to lead-time spikes and component-price inflation.
- Prepare for OEM adjacency by designing products that can complement factory-installed recording or serve retrofit and aftermarket niches with clear differentiation.
For Investors and Capital Allocators
- Look for companies that have credible analytics roadmaps, cloud integration capabilities, and evidence of fleet or insurance-linked demand, since these areas are where margin expansion and recurring revenue are most plausible.
- Evaluate supply-chain resilience as part of the investment thesis, especially for hardware-heavy models that may face margin volatility from memory and semiconductor costs.
- Monitor convergence signals between aftermarket and OEM-embedded recording, as these can reshape channel economics, competitive moats, and long-term growth trajectories.
For Fleet Operators, Procurement Teams, and Insurance-Aligned Buyers
- Prioritize solutions that combine high-quality capture with cloud-synchronized storage, parking-mode protection, and ADAS alerts, since these features reduce risk exposure and simplify incident response.
- Evaluate integration with existing telematics or safety platforms before procurement, because the operational value of a dashcam often depends on how easily footage and analytics can be used in daily workflows.
- Consider total cost of ownership in the context of memory and hardware cost trends, and weigh products that offer differentiated analytics or behavior-reduction features against straightforward recording-only options.
The driving recorder market is moving beyond simple onboard video capture into a space where image quality, AI analytics, cloud connectivity, and supply-chain discipline jointly determine competitive outcomes. For companies and investors seeking to navigate this shift with confidence, detailed segmentation data, company-level revenue estimates, and region-specific demand dynamics can sharpen planning considerably. PW Consulting maintains a dedicated research practice covering this sector, and the full Driving Recorder market report provides deeper breakdowns and customized scenarios for manufacturers, investors, and procurement teams evaluating entry, expansion, or sourcing decisions.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Digital Employee Scheduling Improves Workforce EfficiencyHow Digital Employee Scheduling Improves Workforce Efficiency
By toolkitx, 2026-09-21
How Digital Employee Scheduling Improves Workforce Efficiency
Managing a workforce manually can quickly become far more complicated than it first appears. What begins as a basic employee roster can soon involve spreadsheets, phone calls, staffing gaps, shift changes, and constant questions about working hours. Even a small modification may result in several different schedule versions, leaving employees unsure about which information is accurate. Employee scheduling software addresses these difficulties by bringing workforce planning, staffing decisions, and schedule updates together within one centralized platform. Solutions such as ToolKitX go a step further by automating roster preparation and delivering schedule changes directly to employees through mobile access, helping organizations remain coordinated when plans shift unexpectedly.
What Is Employee Scheduling Software?
Employee scheduling software is a cloud based workforce management solution designed to help organizations assign the right employees to the right shifts more efficiently. Rather than depending entirely on manual calculations and separate scheduling decisions, the software can consider factors including employee availability, qualifications, certifications, skills, staffing needs, and workforce compliance requirements.
After schedules are reviewed and approved, they can be distributed digitally through web and mobile platforms so employees can access the most recent information. Over time, the platform can become a central hub for workforce activities such as shift planning, leave applications, approvals, and employee communication. Bringing these activities together eliminates scattered messages and outdated schedule files, creating a process that is easier to oversee, more consistent, and more dependable.
Why Scheduling Problems Can Become Expensive
Workforce scheduling challenges can affect considerably more than administrative efficiency. When too many employees are scheduled, labor expenses can rise without producing a corresponding increase in business value. When too few people are available, organizations may experience slower service, greater employee pressure, operational interruptions, and possible safety related concerns.
Unclear schedule communication can also contribute to missed shifts, late attendance, and frequent last minute adjustments. Modern scheduling platforms help address these challenges by bringing staffing requirements, workforce policies, employee qualifications, and operational restrictions together in a single environment. Automation reduces repetitive scheduling work, while improved visibility helps managers recognize potential overtime and coverage problems before they become larger operational issues. This creates a more organized scheduling process, reduces conflicts, and strengthens coordination across the workforce.
Key Features That Create Operational Value
Modern employee scheduling software is designed to do much more than replace a traditional calendar. Its broader purpose is to make workforce planning easier, increase visibility across teams, and reduce the manual work required to manage employees and shifts.
Automated Schedule Creation and Reusable Patterns
Building every roster manually from scratch can consume significant time during every scheduling cycle. Automated scheduling solutions can create more suitable rosters by considering staffing requirements, workforce policies, and operating conditions. Repeated shift arrangements can also be saved as reusable templates, allowing managers to apply established patterns instead of rebuilding them each time. ToolKitX expands this functionality with an AI powered scheduling engine that allows organizations to create schedules within minutes.
Centralized Planning Across Multiple Locations
Businesses managing several facilities, projects, teams, or shifts need a complete picture of workforce coverage. A centralized scheduling platform gives managers the ability to coordinate employees across different locations and teams while keeping availability, assignments, and operational requirements visible through one system.
Immediate Schedule Communication
After a roster has been approved, it can be distributed immediately. Employees can receive updated assignments and schedule changes through their mobile devices, reducing the need for phone calls, emails, and repeated circulation of revised schedule documents.
Simplified Leave Requests and Shift Changes
Employees can submit leave requests and arrange shift exchanges directly through the scheduling system. Managers can then review requests, authorize changes, and maintain visibility over the entire process. Approved activities are automatically recorded, creating a useful history that supports accountability and future reference.
Overtime and Compliance Visibility
Scheduling platforms can monitor factors such as overtime thresholds, certification requirements, staffing coverage, and working hour restrictions. This provides organizations with greater insight into workforce costs while helping them maintain alignment with applicable workforce requirements.
Connected Operational Workflows
Scheduling can become considerably more valuable when it connects with other operational processes. Linking workforce schedules with work orders, task management, project activities, and room scheduling can give decision makers a more complete view of how people and operations interact. It also reduces dependence on multiple disconnected systems and minimizes the need to maintain the same information in different places.
Industries That Can Benefit Most
Employee scheduling software can support organizations across many sectors, but industries with complex staffing requirements or changing workforce demands can particularly benefit from structured digital scheduling.
Field Services and Construction
Construction and field projects often require employees who possess specific qualifications, certifications, or site permissions. Scheduling software can make it easier to coordinate these workers while giving teams greater flexibility when projects experience delays, requirements change, or unexpected circumstances arise.
Manufacturing and Offshore Operations
Organizations running continuous operations need appropriate personnel available at specific times. Scheduling software can support workforce coverage and operational planning while accounting for practical considerations such as accommodation arrangements, resource availability, and logistical limitations.
Hospitality, Retail, and Customer Service Environments
Customer demand can change significantly according to the time of day, day of the week, or season. Scheduling software allows organizations to adjust staffing according to changing demand, helping them manage labor expenses while maintaining appropriate service levels.
How Modern Workforce Scheduling Works
Organizations moving toward digital scheduling can establish a more organized and efficient process for managing their workforce.
- Managers access the scheduling platform, choose an appropriate shift pattern, and begin automated roster generation using employee availability, qualifications, and role requirements.
- Before the schedule is released, the system evaluates the proposed roster and identifies potential issues, including overtime exposure, certification conflicts, or insufficient workforce coverage.
- Employees access their schedules through web or mobile platforms, review their assignments, submit leave requests, or request exchanges with other employees.
- Once requested changes have been reviewed and approved, employees receive timely notifications, ensuring that everyone is working from the latest version rather than an outdated schedule.
Measurable Business Advantages
The value of employee scheduling software goes beyond eliminating repetitive administrative work.
- Greater productivity: Scheduling activities that previously required hours of manual effort can often be completed in a much shorter period.
- More efficient workforce utilization: A clearer view of employee availability and staffing requirements allows organizations to align workforce levels more closely with operational demand.
- Fewer attendance issues: Real time schedule notifications reduce confusion and make it easier for employees to remain informed about changes to their shifts and assignments.
- Better employee experience: Easier schedule access, quicker approvals, and greater consideration of employee availability can contribute to a more positive workforce experience.
Implementing Employee Scheduling Software Successfully
Organizations transitioning away from spreadsheet based scheduling can often improve adoption by introducing the software gradually. A practical approach is to begin with one department or team that follows a recurring schedule, such as a 2 2 3 rotation or another repeatable shift pattern. Before implementation begins, organizations should establish clear workforce policies, qualification criteria, and operational restrictions.
Employee availability details can then be added to the platform, allowing managers to use automated scheduling for an initial planning cycle. During this stage, organizations should monitor practical measurements such as the amount of time required to create schedules, overtime levels, the frequency of shift adjustments, and the time taken to publish completed rosters. Once the process is stable and teams are comfortable using the system, scheduling can gradually be extended to additional departments, teams, and locations. Connecting scheduling with tasks, work orders, and room planning can create further coordination opportunities while supporting more efficient workforce management over the long term.
Book a free demo @ https://toolkitx.com/campaign/employee scheduling/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Cold work permit (2025 guide)%3A definition%2C OSHA%2FHSE mapping and checklist
https://toolkitx.com/blogsdetails.aspx?title=Refinery tank farms management: the digital imperative for safety and profit
https://toolkitx.com/blogsdetails.aspx?title=What is a Confined Space Entry Permit A Simple Guide
Histidine Market Outlook 2026–2032: The Real Drivers Behind a 6.8% CAGR
By PW Consulting, 2026-09-21
The Histidine Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global market for L-Histidine has entered a phase of steady, compounding expansion. From 2020 through 2032, the sector is projected to advance at a compound annual growth rate of 6.8 percent, with market value climbing from roughly $163 million to over $338 million over the forecast horizon. The trajectory is not a straight line: a contraction in 2022 underscored the fragility of supply chains, while post-pandemic recovery and downstream demand acceleration pushed the market past $215 million in 2025. This growth is anchored in biology as much as economics. Histidine’s role as an essential amino acid, a buffering agent, and a precursor in specialty formulations makes it indispensable across pharmaceuticals, animal nutrition, food processing, and life sciences research. Yet the market’s maturity is uneven, and the companies that will capture disproportionate value are those that understand where production is shifting, where regulation is tightening, and where end-use demand is evolving faster than capacity.
L-Alanine Market
Market Structure and Core Challenges
The histidine market is characterized by moderate fragmentation and a production base that leans heavily on two manufacturing paradigms. Fermentation-derived routes dominate the volume conversation, supported by steady gains in yield optimization and strain engineering. Hydrolysis-based production remains relevant where specific purity profiles or legacy supply arrangements dictate. The regional distribution of revenue reflects a geography in transition. Developed markets in North America and Europe continue to anchor high-value, regulated end markets, while Asia Pacific has emerged as both the largest consumption region and a critical production hub. Latin America and the Middle East and Africa contribute smaller but structurally important flows, often tied to feed-grade applications and emerging pharmaceutical manufacturing.
Against this backdrop, three structural challenges define the current operating environment.
PW Consulting Health Care Research Center
- Purity and regulatory divergence across applications. Pharmaceutical and biopharmaceutical demand requires GMP-grade, low-endotoxin, and low-metal specifications that are expensive to validate and qualify. Feed and food-grade applications operate on thinner margins and more price-sensitive procurement cycles. The gap between these tiers creates a bifurcated market where the same molecule carries radically different cost structures, qualification timelines, and competitive moats.
- Supply chain concentration and verification risk. A handful of large producers accounts for a modest share of total revenue, which means the market is not dominated by a single oligopoly, but it is also not broadly commoditized. Semi-concentrated supply, combined with geographic clustering of fermentation capacity, leaves downstream buyers exposed to qualification bottlenecks, logistics disruption, and batch-to-batch consistency concerns.
- Input volatility and the cost of biological production. Fermentation economics are influenced by substrate pricing, water and energy intensity, strain performance, and downstream purification costs. Hydrolysis routes face their own raw material dependencies. When energy prices or feedstock costs move sharply, margin discipline becomes a differentiator rather than a baseline expectation.
Key Drivers Reshaping the Market
The 6.8 percent growth rate is not merely an extrapolation of historical demand. It reflects a convergence of technical, regulatory, and commercial forces that are changing how histidine is produced, qualified, and deployed.
Technology and Process Innovation
Process innovation is the most direct lever for expanding margins and unlocking new use cases. In fermentation, the competitive frontier has shifted from basic titer improvements to integrated strain design, reduced impurity profiles, and more efficient downstream recovery. The practical impact is significant: higher-purity outputs lower the burden of endotoxin and metal removal, which in turn shortens qualification cycles for biopharmaceutical customers. For hydrolysis-based producers, the opportunity lies less in volume leadership and more in precise specification control where specialty grades command premium pricing.
This dynamic is visible in recent strategic moves to combine complementary capabilities. A notable example is the 2025 partnership between a major fermentation-based producer and a Chinese chemical supplier to co-develop and secure global supply of L-Histidine HCl monohydrate, explicitly aimed at expanding fermentation-derived production capacity. The significance of this move is not just incremental capacity. It signals a deliberate effort to align biological production expertise with regional supply reach, reducing lead-time risk and reinforcing supply continuity for regulated end markets. In an environment where qualification and consistency are as valuable as price, partnerships that bridge process technology and distribution are becoming a strategic necessity rather than an optional synergy.
Policy and Regulatory Environment
Regulation is quietly reshaping histidine’s cost of entry and the geography of trade. For pharmaceutical and biopharma buyers, GMP compliance, traceability, and impurity control are non-negotiable. For industrial and feed users, the regulatory burden differs, but documentation, residue limits, and regional approval pathways still shape sourcing decisions. The effect on competition is twofold: regulatory readiness functions as a barrier that rewards established, well-documented suppliers, while new entrants must invest not only in capacity but in quality systems and audit readiness.
On the trade side, export control dynamics add another layer of complexity. In early 2026, the U.S. Federal Register noted that China suspended export controls on six critical dual-use items until November 2026, with potential implications for trade in chemical intermediates used in amino acid production. Even where the direct link to histidine is indirect, the broader signal is important: the availability and pricing of intermediates, precursor chemicals, and specialty inputs can shift with regulatory calendars, not just market fundamentals. Producers and buyers that map their supply chains against such policy windows are better positioned to avoid surprise cost spikes or sourcing gaps.
Demand-Side Shifts
End-use demand is expanding along two converging paths. The first is the continued growth of biopharmaceutical manufacturing and cell-based processes, where histidine and its salts serve as excipients, buffering components, and media constituents. As biologics, cell therapies, and advanced manufacturing formats scale, the volume of high-purity amino acids required per facility increases, raising the stakes for suppliers that can deliver consistent, low-endotoxin material at commercial scale.
The second path is more traditional but structurally durable: animal feed and food-grade applications. In feed, histidine availability supports formulation flexibility and animal performance objectives, while in food and supplements it serves functional and nutritional roles. These segments are less glamorous than biopharma, but they contribute steady volume and can act as absorbers during periods when pharmaceutical demand is qualification-constrained. Importantly, the demand mix is not uniform across regions. Where animal production intensifies and where food processing modernizes, histidine consumption grows in ways that reward suppliers with reliable feed-grade and food-grade streams as well as the capability to serve regulated markets when opportunities arise.
Supply Chain and Cost Structure Evolution
The market’s cost structure is increasingly shaped by the distance between production and qualification. Fermentation scale brings advantages in unit cost, but it does not automatically solve purity, endotoxin control, or documentation. As a result, the most resilient supply chains are those that integrate fermentation output with disciplined downstream processing and strong quality systems. This integration reduces rework, shortens batch release timelines, and improves predictability for buyers who are themselves managing tight production schedules.
Logistics and geographic concentration also matter more than they appear to on a spreadsheet. A supply base that is efficient but geographically narrow can create hidden exposure: port delays, regional fuel cost fluctuations, and regulatory checks can each erode service levels. The practical response is diversification of qualified sources combined with audited quality agreements. Buyers are increasingly treating qualification as a portfolio decision, balancing cost against continuity, and favoring suppliers that can demonstrate both scale and verifiable control over critical quality attributes.
Competitive Landscape and Leading Strategies
The competitive set in histidine is geographically diverse and strategically differentiated. Japanese producers have built strong reputations in fermentation-based, high-purity supplies for pharmaceutical and biopharmaceutical use, with product profiles explicitly oriented toward cell culture media, parenteral and enteral nutrition, and biopharmaceutical applications. A leading German specialty supplier has emphasized highly purified histidine for biopharma, amino acid derivatives, and GMP-grade applications, reinforcing a positioning around purity and compliance. Another major European life sciences player has extended its brand into histidine for laboratory and biopharma use, leveraging established quality systems and broad distribution networks.
Lysine Market
In the United States, a supplier focused on high-purity, low-endotoxin, low-metal material has carved a defensible niche in biopharmaceutical formulations, where impurity control and specification consistency directly affect customer outcomes. In Asia, a Korean fermentation producer supplies histidine base for medicines, food supplements, and animal feed, reflecting a model that spans both regulated and lower-margin volume applications. China-based chemical suppliers remain active in pharmaceutical and industrial streams, often competing on responsiveness and cost while navigating the same quality expectations as global buyers.
Several patterns stand out in how leading players are positioning themselves.
- Segment specialization as a moat. The most defensible positions are not simply about volume. They are about owning a specification tier that matters to a specific customer class. High-purity, low-endotoxin material creates switching costs because re-qualification is expensive and time-consuming. Feed-grade and food-grade leadership, by contrast, requires scale, cost discipline, and reliable delivery. Few companies optimize both tiers equally, which is why specialization remains a rational strategy.
- Capacity expansion tied to partnership, not just CAPEX. The recent co-development partnership to expand fermentation-derived supply illustrates a broader trend: companies are extending reach through alliances that combine process know-how, regional access, and supply security. This reduces the capital intensity of standalone expansion while improving resilience.
- Quality systems as commercial infrastructure. In regulated segments, quality documentation, audit readiness, and impurity control are no longer back-office functions. They are commercial differentiators that determine whether a supplier is invited into a qualified vendor list in the first place.
The market structure suggests continued evolution rather than abrupt consolidation. Because concentration is moderate, the field remains open to capable new entrants with strong process or quality advantages, but the qualification barrier protects incumbents who have already invested in relationships and documentation. Over the next few years, the most likely shifts are selective integration around capability gaps—partnerships, co-development, and regional supply reinforcement—rather than broad-based mergers. At the same time, buyers are likely to keep qualifying multiple sources where possible, balancing cost and continuity, which will reinforce the value of differentiated quality and reliable service.
Future Trends and Commercial Implications
Looking ahead three to five years, three trends are likely to shape where value migrates within the histidine market.
First, the premium on high-purity, biopharma-ready material will keep rising. As biologics manufacturing and advanced cell-based processes scale, demand for low-endotoxin, low-metal, well-documented histidine will grow faster than the general market. The commercial opportunity lies in building or acquiring the process control and quality systems that make that purity reproducible at scale. Suppliers that can compress qualification timelines and reduce variability will be able to command pricing power even in an otherwise competitive category.
Second, production geography will keep rebalancing around cost, continuity, and policy. Asia remains a central production axis, but buyers are likely to seek qualified alternatives and redundancy where possible. Trade and export-control dynamics may also influence intermediate availability, which will make forward inventory planning and supplier mapping more important. Companies that treat geography as a risk variable—not just a cost variable—will be better prepared to maintain service during disruption.
Third, segmentation will sharpen rather than blur. The gap between regulated pharmaceutical grades and feed/food grades is structural, and the strategies that succeed in one segment do not automatically transfer to the other. That creates both risk and opportunity. Manufacturers that can selectively bridge high-margin, high-specification demand with stable volume streams will capture more resilient economics than those forced to compete purely on price in undifferentiated segments.
Each trend carries uncertainty. Regulatory expectations may tighten further in certain jurisdictions, raising the cost of entry for new suppliers. Energy and feedstock volatility can compress margins for fermentation producers that lack pricing power or hedging discipline. And while partnerships can extend reach, they also introduce coordination risk, especially when co-developing capacity across regions with different regulatory environments and operating norms. The most resilient strategies will account for these variables explicitly rather than assuming smooth demand growth will absorb operational shocks.
Actionable Guidance for Decision Makers
For manufacturers, the strategic question is where to invest next. If the portfolio already leans toward feed or food grades, the highest-return move may be disciplined expansion of purification capability that opens a credible path into pharmaceutical or biopharma-adjacent specifications. If the portfolio already serves regulated markets, the priority is likely to reinforce supply continuity through partnerships or regional capacity that reduces lead-time exposure, while maintaining rigorous impurity and endotoxin control. In both cases, qualification readiness should be treated as part of the product, not a separate compliance exercise.
For investors, the opportunity is less about total market size than about the distribution of value within it. Segments that require high purity, low variability, and documented compliance tend to support more durable margins and stronger customer stickiness. Capital should be assessed against the ability to scale process control, reduce batch failure and rework, and qualify sources in multiple geographies where appropriate. Projects that rely on undifferentiated volume growth without a quality or continuity advantage are more exposed to margin compression and competitive entry.
For procurement and supply chain leaders, the practical priority is to convert qualification from a one-time gate into an ongoing risk-management process. That means evaluating suppliers not only on price and lead time, but on impurity profiles, endotoxin and metal control, documentation depth, and the resilience of their production geography. Multi-sourcing qualified alternatives, even where one supplier dominates volume, can reduce exposure to disruption. Aligning inventory planning with potential policy windows and trade dynamics—such as the recent suspension of certain export controls affecting chemical intermediates—can also prevent avoidable cost shocks.
For organizations evaluating where to focus next, the histidine market rewards precision. The growth rate is healthy, but the real differentiation comes from understanding which specification tiers are expanding fastest, where supply is becoming more or less concentrated, and how regulatory and trade dynamics will alter the cost of intermediates and finished material. A detailed segmentation view—by production method, application tier, end-market requirements, and regional qualification pathways—can sharpen capacity planning, sourcing strategy, and investment prioritization in ways that aggregate market figures cannot. For teams that need segment-level sizing, region-specific supply analysis, and tailored scenarios for qualifying new sources or expanding into higher-purity grades, the full research report provides the structured data and actionable detail to support those decisions.
For detailed analysis of this topic, please visit the official page: Histidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vinylphosphonic Acid Market: Why 8.7% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
Vinylphosphonic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for vinylphosphonic acid (VPA) has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 10.8 million USD in 2020 to an estimated 16.4 million USD in 2025. The trajectory points toward continued growth, with the market projected to reach nearly 29.3 million USD by 2032, reflecting a compound annual growth rate of 8.7 percent. This scale places VPA in the niche specialty chemicals segment, where volume is modest but value addition through application-specific performance is substantial.
At first glance, the numbers suggest uninterrupted expansion. Closer examination reveals a market that is fragmenting around performance thresholds rather than pure capacity. The revenue distribution across grades, applications, and geographies shows that demand is not uniform. High-purity grades dominate share, while coatings and water treatment applications account for the bulk of consumption. Asia Pacific leads regional contribution, reflecting concentrated industrial activity and manufacturing capacity in the region, while mature markets in North America and Europe sustain steady, high-value demand.
PW Consulting
Despite the positive outlook, the sector faces structural challenges that complicate straightforward growth strategies.
Challenge One: Purity Thresholds and Application-Specific Performance
The market is no longer defined by generic chemical supply. Buyers in coatings, corrosion inhibition, and polymer modification increasingly require tight impurity profiles and consistent batch-to-batch performance. The shift from 80 percent grades toward 90 percent and higher purity thresholds is reshaping procurement logic. Suppliers that cannot demonstrate controlled impurity levels risk being relegated to lower-margin segments, while those that can command premium positioning and longer-term contracts.
Challenge Two: Feedstock Volatility and Cost Structure Pressure
Production economics are tightly coupled to phosphorus-based feedstock availability and pricing. Raw material price volatility affects a significant portion of global producers, placing pressure on margin forecasting and inventory planning. Facilities operating with narrow buffers or inflexible procurement arrangements face heightened exposure to cost swings, which in turn influences pricing stability for downstream buyers. This dynamic is particularly acute in regions where feedstock logistics and storage constraints amplify supply variability.
Challenge Three: Regulatory and Logistics Compliance Burden
Hazardous chemical handling introduces a compliance layer that touches production, storage, transportation, and labor practices. A meaningful share of manufacturers report increased compliance costs tied to storage regulations, while logistics providers face restrictions related to chemical transportation safety standards. Elevated labor and safety costs in production facilities further contribute to operating expense pressure. These factors are not marginal; they influence site selection, capacity expansion timing, and the cost of serving distant markets.
Key Drivers Behind Market Evolution
Growth in the VPA market is not accidental. It is being shaped by a set of reinforcing drivers that alter where value is created and how companies compete. Four forces stand out.
Technical Innovation and Purity Engineering
The most visible driver is the push toward higher purity and application-tuned specifications. Industry developments in 2024 and 2025 illustrate this direction. A high-purity 92 percent grade with 14 percent lower impurities was introduced, reflecting a strategic emphasis on impurity control as a differentiator. This matters because even modest reductions in trace contaminants can translate into improved performance in coatings, corrosion inhibition, and polymer modification. Innovation is increasingly less about new molecule discovery and more about precision manufacturing, analytical control, and specification reliability.
Phosphoric Acid Market
Policy and Regulatory Environment
Regulatory expectations around hazardous chemical storage and transportation continue to tighten. Rather than acting as a uniform brake, these requirements are reshaping competitive dynamics. Companies with mature compliance infrastructure, documented safety processes, and regional distribution capacity are better positioned to absorb regulatory friction. Conversely, organizations with fragmented logistics or limited safety investment face higher relative cost and longer time to market. In practice, compliance is becoming a selection criterion for buyers who need predictable supply and reduced operational risk in their own value chains.
Demand-Side Shifts Across Industrial and Specialty Applications
Demand is broadening but not evenly. Coatings remain a core consumption center, driven by performance needs in corrosion resistance, adhesion, and flame retardancy. Water treatment and oil well applications sustain steady demand linked to industrial infrastructure and resource extraction activity. Fuel cells represent a smaller but strategically important segment, where VPA’s functional properties support research and development pathways even if commercial scale remains nascent. Medical care and printing applications contribute niche volumes with distinct purity and handling requirements.
The common thread is not volume growth in isolation but specification sensitivity. Buyers are less interested in generic availability and more focused on whether a grade reliably meets performance thresholds in their process. This shifts purchasing decisions toward suppliers who can evidence consistency, provide technical support, and align product grades with application outcomes.
Supply Chain and Cost Structure Realignment
Supply chain design is becoming a strategic variable. Regional distribution optimization has reduced delivery lead times by 21 percent across three regional distribution centers for one manufacturer, a change that directly affects service levels and inventory planning for downstream customers. At the same time, upstream feedstock fluctuations continue to drive raw material volatility, influencing production economics. Together, these factors are pushing companies to balance proximity, redundancy, and cost efficiency more deliberately. Supply chains that can flex across regions while maintaining specification integrity are gaining a practical advantage.
Competitive Landscape and Leading Strategies
The competitive structure of the VPA market is moderately concentrated, with the top three players accounting for approximately 28.5 percent of revenue and the top five reaching roughly 35.2 percent. This level of concentration indicates that while no single company controls the market, a small group of established players sets much of the pace in specification development, regional coverage, and compliance posture. The rest of the market is dispersed among regional suppliers, specialty producers, and laboratory-focused vendors, creating a multi-layered landscape rather than a simple oligopoly.
Strategic Positioning Among Leading Companies
Several firms illustrate the different ways competition is being structured.
- One German-based producer emphasizes high-purity VPA in both 80 percent and 90 percent grades, with ISO 9001 certification and a portfolio covering monomer and polymer grades for coatings, corrosion inhibition, flame retardancy, and adhesion. Its positioning centers on specification breadth and certified quality control, which supports use across multiple industrial functions.
- A major European chemical company offers specialty VPA grades aimed at polymer modification, coatings, and water treatment. Its advantage lies in the ability to slot VPA into broader specialty chemical portfolios and leverage existing customer relationships in performance materials and water-related applications.
- A Brussels-based supplier provides VPA grades including a formulation for aluminum pretreatment and corrosion inhibition. Its differentiation is application-solving rather than generic supply, targeting a specific industrial pretreatment need with a branded grade.
- A Tokyo-headquartered chemical supplier markets VPA as a high-purity liquid for laboratory and specialty chemical synthesis. Its role is narrower, serving R&D, pilot-scale, and specialty synthesis demand where purity and traceability matter more than bulk cost.
- An Italian manufacturer focuses on VPA for industrial and pharmaceutical applications, indicating a dual-use orientation that spans conventional industrial demand and higher-specification pharmaceutical relevance.
These profiles show that leadership is not defined by a single formula. Some players win through certified quality and grade variety, others through application-specific formulation, and others through purity and technical service for specialized users.
Differentiation Levers and Recent Moves
In a market where volume is constrained and performance requirements are rising, differentiation tends to appear in three levers: purity and impurity control, application reliability, and service responsiveness. Recent industry developments reinforce this pattern. The introduction of a 92 percent high-purity grade with lower impurities reflects a purity-driven differentiation strategy. The reduction in delivery lead times through regional distribution optimization shows a service-level differentiation strategy that improves reliability for buyers. Meanwhile, upgraded polymer modification testing facilities in Asia-Pacific have increased quality assurance throughput by 25 percent, pointing to investment in process verification and application readiness.
These moves matter because they align with how buyers purchase in specialty chemicals. In coatings and water treatment, batch consistency and impurity control affect end-product performance. In polymer modification, testing throughput and quality assurance affect the speed at which new formulations can be validated. In laboratory and specialty synthesis, purity and documentation support downstream reproducibility. Companies that invest in these levers are not simply selling a chemical; they are selling predictable outcomes.
Market Structure Evolution
The market is likely to evolve along two concurrent paths: selective consolidation and continued niche segmentation. Consolidation will probably remain measured rather than aggressive. Because VPA serves multiple applications with different specification needs, scale alone does not guarantee advantage. However, companies that can combine purity control, compliance readiness, and regional distribution capacity are well placed to acquire share from smaller competitors that lack one or more of these capabilities.
At the same time, segmentation will persist. Laboratory-grade supply, industrial bulk grades, and specialized pretreatment or polymer modification grades each carry different buyer expectations, pricing logic, and service requirements. New entrants are most likely to appear in niche positions where a specific grade, regional service advantage, or technical support capability can create a defensible position without requiring dominant scale. The practical outcome is a market that becomes more tiered, with premium specification players, application-focused specialists, and cost-oriented regional suppliers coexisting.
Strategic Outlook for the Next Three to Five Years
Looking ahead to 2032, three trends are likely to shape commercial opportunity and risk.
Trend One: Purity and Specification As control Become the Default Expectation
As higher-purity grades become more widely available and application performance expectations rise, what is considered acceptable purity will shift upward across more use cases. This will compress the middle ground where generic, lower-specification supply once found a home. Suppliers will need to demonstrate tighter impurity control, stronger analytical documentation, and consistent lot performance. The commercial opportunity lies in grades and services that reduce downstream processing variability, especially in coatings and polymer modification, where small quality differences can have outsized effects on end-use performance.
Trend Two: Regional Service Networks Will Matter More Than Raw Proximity
Lead-time reduction, regional distribution optimization, and improved delivery reliability are becoming competitive differentiators. Buyers increasingly value predictable timing and service consistency as much as unit price, particularly when chemical handling and logistics constraints raise the cost of disruption. Companies that build or strengthen regional service networks will be better positioned to capture share in markets where responsiveness and safety compliance are closely linked. This trend also creates opportunities for partnerships that improve storage, transportation, and inventory buffering without requiring every producer to own the full logistics chain.
Trend Three: Regulatory Friction Will Elevate Compliant Operators
Compliance costs tied to hazardous chemical storage, transportation safety standards, and elevated labor and safety requirements are unlikely to recede. Instead, they will continue to separate operators that have built institutional capability from those that have not. Over the next few years, this will influence which producers can expand efficiently, which can serve certain regions reliably, and which can maintain stable pricing. The strategic opportunity is to treat compliance as part of the value proposition rather than a cost to minimize in isolation. Buyers in sensitive applications may prefer suppliers whose safety and transport readiness lower their own operational exposure.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Feedstock volatility remains a persistent risk; if phosphorus-based feedstock supply fluctuations intensify, production economics could tighten and pricing volatility could increase. Regulatory changes could further raise storage and transportation requirements, reshaping cost structures and market access. Demand may also shift faster than expected in certain applications, particularly where alternative materials, formulation changes, or new process technologies reduce reliance on VPA in specific functions. Finally, capacity additions in Asia-Pacific and other regions could alter supply balance, intensifying competition in some segments while creating export opportunities in others.
Actions for Decision-Makers
The VPA market rewards companies that align their strategy with specification sensitivity, service reliability, and compliance readiness. The following actions are most relevant across different roles.
Phosphonate Market
For Manufacturers and Producers
- Prioritize purity engineering and analytical consistency over undifferentiated capacity expansion. In a market where higher-purity grades and lower impurity levels are gaining traction, the ability to document and replicate performance will shape pricing power and customer retention.
- Invest in regional distribution and lead-time reliability. Reducing delivery friction is not just a logistics improvement; it is a commercial differentiator that supports premium positioning and reduces the likelihood of substitution under pressure.
- Design compliance into operations as a competitive asset. Storage, transportation, and labor safety costs are real, but companies that manage them systematically can use reliability and risk reduction as part of their customer value proposition.
For Investors and Strategic Partners
- Focus on business models that combine specification control with service differentiation rather than volume alone. The strongest growth potential lies in companies that can secure long-term relationships through purity, consistency, and responsiveness, especially in coatings, water treatment, and polymer modification.
- Watch for selective consolidation opportunities where regional or specialty players lack the compliance infrastructure, analytical capability, or distribution reach to compete upward. Value creation may come more from capability alignment than from scale expansion.
- Monitor feedstock exposure and regional capacity dynamics. Margins and pricing stability will depend on how well companies manage raw material volatility and adapt to shifting supply balance across regions.
For Procurement and Supply Chain Leaders
- Evaluate suppliers on specification reliability and service consistency as well as price. In applications where impurity levels and batch consistency affect performance, the lowest headline price may not translate into the lowest total cost if variability creates processing risk.
- Build buffer and logistics strategies that account for hazardous chemical transportation constraints. Where safety standards and transport restrictions raise the cost of disruption, regional distribution capability and documented handling practices can reduce supply risk.
- Align grade selection with application outcomes. The choice between 80 percent, 90 percent, and higher-purity grades should be tied to actual performance requirements and downstream process sensitivity, not just inventory convenience.
The commercial dynamics of vinylphosphonic acid are increasingly defined by precision, service, and compliance rather than by bulk commodity logic. For companies operating in coatings, water treatment, polymer modification, fuel cells, medical care, printing, and related specialty segments, the window to strengthen positioning is now, before specification expectations and regulatory expectations become even more firmly entrenched. Detailed segmentation data, regional breakdowns, grade-level dynamics, and customized scenario analysis are available in the full PW Consulting report on the Vinylphosphonic Acid Market, which provides the deeper quantitative and strategic detail needed for planning beyond high-level trends.
For detailed analysis of this topic, please visit the official page: Vinylphosphonic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Bike Market 2026: 10.54% CAGR Trajectory and the Asia Pacific Shift
By PW Consulting, 2026-09-21
Electric Bike Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The electric bike market has transitioned from a niche alternative to a mainstream mobility solution, demonstrating sustained expansion over the past five years. Between 2020 and 2025, industry revenue climbed from approximately 41.9 billion USD to 73.2 billion USD, reflecting a compound annual growth rate that underscores the sector's resilience and accelerating adoption. Forward projections indicate continued momentum, with revenue expected to reach 147.2 billion USD by 2032, translating to a CAGR of 10.54 percent across the 2026-2032 forecast horizon. This trajectory positions electric bikes as one of the fastest-growing segments within the broader micro-mobility and personal transportation landscape, driven by urbanization pressures, sustainability mandates, and evolving consumer preferences for flexible, low-emission transit options.
Despite the robust growth trajectory, the industry stands at a critical inflection point where several structural challenges threaten to reshape competitive dynamics. First, regulatory fragmentation is intensifying across key markets. Jurisdictions are diverging on speed limits, motor power thresholds, battery safety mandates, and classification frameworks, creating compliance complexity for manufacturers operating across multiple regions. Second, raw material volatility is introducing cost uncertainty, particularly in battery component pricing, which directly impacts margin structures and pricing strategies. Third, market concentration remains relatively high, with the top three players holding a substantial share of global revenue and the top five firms commanding an even larger portion, which raises barriers to entry and compresses differentiation opportunities for smaller competitors. These forces collectively demand strategic agility from market participants seeking to capture growth without exposing themselves to excessive regulatory, cost, or competitive risk.
Key Drivers Shaping Market Evolution
Technological Innovation and Performance Differentiation
Technology remains the primary engine of market expansion, with advancements in motor efficiency, battery energy density, and smart connectivity reshaping product expectations. Manufacturers are increasingly embedding proprietary control units, GPS tracking, over-the-air updates, and integrated app ecosystems into their platforms. These features extend beyond novelty; they address safety concerns, enable fleet management capabilities, and create recurring engagement loops that strengthen brand loyalty. Recent model launches illustrate this trajectory: one U.S.-based brand introduced a fat-tire model with enhanced range and a proprietary control unit supporting GPS and OTG functionality, signaling how connectivity and utility features are becoming baseline expectations rather than premium add-ons. Simultaneously, performance-oriented manufacturers are pushing torque outputs and frame materials to cater to aggressive riding styles and demanding terrain, while other players focus on step-through designs and extended range to serve senior and recreational segments. The technological arms race is widening product segmentation and forcing companies to clarify whether they compete on accessibility, performance, or integrated digital experience.
Policy and Regulatory Environment as a Market Accelerant and Constraint
Policy frameworks are actively reshaping demand patterns and compliance requirements. In the United States, reciprocal tariffs on Chinese electric bicycle imports were reduced from 55 percent to 45 percent effective November 2025, easing some cost pressures on imported finished goods while still maintaining a significant trade barrier. This adjustment alters sourcing economics and encourages regional assembly or supply chain diversification strategies. Concurrently, California implemented updated State Fire Marshal safety standards for electric bike batteries effective January 2026, requiring manufacturers to demonstrate enhanced thermal management and certification compliance. In Europe, the European Commission fully enforced the revised EN 15194 standard after August 2025, harmonizing technical requirements but also tightening conformity assessment processes. Meanwhile, the United Kingdom revoked anti-dumping duties on non-folding electric bikes of Chinese origin in February 2025, opening a pathway for cost-competitive imports in that segment. Collectively, these regulatory shifts are creating a patchwork environment where successful players must navigate divergent safety, classification, and trade rules while leveraging favorable policy windows to optimize cost structures.
Demand-Side Shifts in Urban Mobility and Commercial Utility
Consumer and enterprise behavior is evolving beyond recreational use toward practical, daily mobility solutions. City and urban applications continue to dominate usage patterns, reflecting the role of electric bikes in first-mile and last-mile connectivity, commute substitution, and congestion avoidance. At the same time, cargo and utility applications are gaining meaningful traction as businesses and households recognize the cost and efficiency advantages of electric cargo bikes for local deliveries, family transport, and municipal operations. This shift is reinforced by rising fuel costs, parking constraints, and corporate sustainability targets that incentivize fleet electrification at the micro-mobility level. Demand is also becoming more segmented by rider profile: high-performance models appeal to enthusiasts and trail riders, while accessible step-through designs and folding formats attract seniors, multi-modal commuters, and space-constrained urban users. These diverging demand clusters require manufacturers to align product architecture, marketing positioning, and distribution channels with specific use cases rather than relying on generic electric bike positioning.
Supply Chain and Cost Structure Dynamics
The supply chain environment is undergoing a period of recalibration as material costs, logistics constraints, and sourcing strategies interact. Lithium carbonate prices rose sharply in December 2025 and January 2026, with industrial grades increasing by double-digit percentages, placing upward pressure on battery pack costs and, by extension, finished product pricing. This volatility highlights the sensitivity of margin profiles to commodity cycles and underscores the value of long-term supplier agreements, battery chemistry diversification, and design efficiencies that reduce dependency on constrained inputs. At the same time, tariff adjustments and trade remedy decisions are prompting companies to reconsider manufacturing footprints, assembly locations, and inventory strategies. Some manufacturers are responding by emphasizing regional distribution, localized assembly partnerships, or product architectures that optimize shipping efficiency and tariff exposure. The net effect is a market where cost discipline and supply chain resilience are becoming as strategically important as product features in determining competitive outcomes.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of regional specialists, performance-focused incumbents, and accessible-value brands, each pursuing distinct strategic positioning. Premium German manufacturers have built strong reputations around integrated drive systems, advanced battery integration, and high-end frame engineering, targeting customers who prioritize durability, ride quality, and ecosystem alignment with established component suppliers. These firms compete on engineering credibility and residual value, often anchoring their portfolios in eMTB, cargo, and city categories with sophisticated powertrain integration. U.S.-based brands occupy a broad value spectrum, ranging from budget-friendly folding and cruiser models with emphasis on quiet operation and certified electrical safety, to mid-range and premium platforms that differentiate through proprietary app controls, GPS tracking, and over-the-air update capabilities. This stratification allows American manufacturers to address price-sensitive urban riders as well as tech-conscious consumers seeking connected features. Global players such as hybrid bike leaders and Taiwanese high-end manufacturers leverage scale, alloy frame expertise, and battery option flexibility to serve commuter and performance segments with broad geographic reach. A Dutch specialist has carved out a niche in compact folding designs with efficient pedal-assist systems, targeting urban mobility users who prioritize portability and maneuverability.
Recent product activity reinforces the intensity of differentiation. A U.S. brand expanded its fat-tire lineup with enhanced range and GPS/OTG functionality, reinforcing its focus on connected adventure and urban versatility. A Taiwanese manufacturer introduced new eMTB series powered by Bosch CX motors in alloy frames, emphasizing improved affordability while maintaining performance credibility. A major global brand launched a flagship model with a carbon frame and high torque output, signaling continued investment in premium performance segments. These moves illustrate how leaders are contesting multiple battlegrounds simultaneously: range and battery endurance, motor torque and frame material, connectivity and software integration, and price-to-performance ratios across accessibility and premium tiers.
The market structure is evolving along two parallel paths. Consolidation is likely to accelerate among mid-tier players seeking scale, distribution leverage, and cost efficiencies, particularly as compliance and battery cost pressures raise the fixed-cost threshold for sustained competitiveness. At the same time, fragmentation persists in specialized niches such as cargo utility, folding urban formats, senior-focused accessibility designs, and high-performance trail categories, where targeted product architecture and community-driven branding can sustain differentiation. New entrants are most likely to succeed by focusing on underserved use cases, regional compliance advantages, or digital service ecosystems rather than attempting to compete broadly on hardware alone. Companies that combine clear segmentation, disciplined cost structures, and defensible feature sets are best positioned to navigate this environment.
Electric Bicycles Market
Strategic Trends and Outlook for 2026-2032
Several trends are likely to define the market over the next three to five years. First, connectivity and software-defined features will become increasingly central to product value propositions. As GPS tracking, app-based controls, and over-the-air updates move from differentiators to expectations, manufacturers that treat the electric bike as a platform with ongoing digital engagement will have an advantage in retention, service revenue, and fleet integration. This trend creates opportunities for brands that can build reliable software stacks, secure update pathways, and data-informed rider experiences without compromising electrical safety or user privacy.
Second, regulatory alignment and battery safety certification will increasingly shape market access and sourcing decisions. As jurisdictions tighten battery standards and harmonize technical requirements, companies with robust quality assurance processes and transparent compliance documentation will face fewer market entry frictions. The trend also opens opportunities for suppliers and assemblers that can deliver certified battery systems with traceable sourcing and consistent performance. However, the risk lies in uneven enforcement and periodic standard revisions that can disrupt product roadmaps and require rapid design adjustments.
Third, cargo and utility applications are expected to expand beyond early adopters into broader commercial and household use. Local delivery operators, municipal programs, and multi-purpose household users are likely to increase adoption as total cost of ownership advantages become more apparent and as frame, battery, and load-capacity designs improve. This trend presents opportunities for purpose-built cargo architectures, swappable battery configurations, and service networks tailored to commercial uptime requirements. The associated risk is that utility-focused models must withstand higher usage intensity, which places greater demands on component durability, warranty management, and after-sales support.
Underlying these trends are unresolved uncertainties. Commodity price swings can quickly alter margin assumptions, and tariff or trade-remedy shifts may change the cost competitiveness of imported versus regionally assembled products. Demand could also diverge by region if economic conditions affect discretionary spending or if public transport investments alter commute substitution dynamics. Manufacturers and investors should therefore treat growth as achievable but contingent on strategic choices around sourcing, compliance, segmentation, and service infrastructure.
Electric Motorcycle Market
Actionable Recommendations for Decision Makers
For manufacturers, the priority is to reinforce product architecture decisions with clear segmentation and compliance readiness. Rather than broadening portfolios indiscriminately, companies should define whether they compete on accessible value, performance credibility, or connected digital experience, and then align motor, battery, frame, and software choices accordingly. Investing in battery safety certification, traceable sourcing, and design efficiencies that reduce exposure to commodity volatility will help protect margins and ensure continuity across regulatory cycles. Manufacturers should also evaluate assembly and distribution footprints against tariff exposure and shipping efficiency, especially as trade conditions remain fluid. Building proactive after-sales and service capabilities is equally important, particularly for cargo and utility models where uptime and durability directly influence commercial adoption.
For investors, the opportunity lies in identifying players with defensible segmentation, resilient cost structures, and scalable digital or service propositions. Due diligence should extend beyond top-line growth to assess battery supply agreements, certification readiness, tariff sensitivity, and the credibility of software and connectivity roadmaps. Companies that combine clear use-case positioning with disciplined manufacturing and compliance practices are more likely to sustain margins and navigate consolidation pressures. Investors should also monitor regions where regulatory changes create temporary cost advantages or new import pathways, as these conditions can reshape competitive positioning over short to medium horizons.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet decision makers, the focus should be on total cost of ownership, safety compliance, and operational fit rather than upfront price alone. Evaluating battery certification status, warranty structures, service network coverage, and load-capacity suitability for specific urban or cargo tasks will reduce operational risk and support longer asset life. Organizations deploying electric bikes at scale should consider standardized battery and component specifications where possible, while preserving enough flexibility to match different rider profiles and route requirements. Procurement teams should also track regulatory updates in their operating jurisdictions, as changing safety and classification standards can affect model availability, replacement part compatibility, and compliance timelines.
For decision makers seeking deeper granularity on regional demand patterns, segment-level sizing, pricing dynamics, and company-specific competitive benchmarks, the full research report provides detailed quantitative breakdowns and customized strategic guidance. Accessing that level of detail can help narrow strategic options, stress-test sourcing and compliance plans, and prioritize investments in the segments most aligned with specific business objectives.
For detailed analysis of this topic, please visit the official page: Electric Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silver-based Antimicrobial Agent Market: What 6.98% CAGR Means for 2032 Growth
By PW Consulting, 2026-09-21
The Silver-Based Antimicrobial Agent Market: Navigating Growth, Regulation, and Strategic Opportunities Through 2032
The silver-based antimicrobial agent market has evolved from a niche specialty segment into a structurally significant component of the broader biocides and functional materials landscape. Between 2020 and 2025, global revenue expanded from approximately USD 153.44 million to USD 215.0 million, reflecting a compound trajectory shaped by sustained infection-control priorities, material-performance demands, and incremental substitution against conventional chemical biocides. Looking ahead to 2032, the market is projected to reach USD 344.79 million, underpinned by a forecast-period CAGR of 6.98%. This growth rate signals steady, technology-led expansion rather than speculative boom dynamics, making it a market where disciplined positioning, regulatory fluency, and application-specific differentiation will separate long-term winners from cyclical participants.
PW Consulting Health Care Research Center
Despite the positive directional signal, the sector operates at a critical inflection point. Three structural challenges are reshaping how manufacturers, formulators, and end-users approach silver-based antimicrobial solutions. First, feedstock volatility has moved from a background concern to a core planning variable. Silver prices climbed sharply through 2024 and 2025, reaching roughly $50 per ounce amid converging industrial demand pressures, which directly elevated the cost base for silver nitrate and related precursors. Second, regulatory gatekeeping is tightening across major end markets. In the United States, EPA registration requirements for silver or silver-ion applications in textiles now demand rigorous safety, efficacy, and environmental-impact documentation, adding time and compliance cost to product development cycles. Third, downstream sustainability mandates are rewriting formulation rules. China’s Recycled Plastics Standards (GB/T 45091-2024), effective from June 2025, introduced restricted-substance guidelines for antimicrobial additives in recycled polymer streams, forcing suppliers to demonstrate compatibility with circularity goals rather than simply delivering antimicrobial performance. Together, these forces are compressing the window for undifferentiated commodity offerings and elevating the value of technically validated, regulation-ready, and application-optimized products.
Technical Innovation and Carrier Architecture
The most consequential driver of market evolution is not silver itself but the carrier systems that control ion release, durability, and compatibility. Silicate-based carriers continue to anchor a large share of the market because they offer a balanced combination of sustained antimicrobial activity, thermal stability, and processing flexibility across polymers and coatings. Phosphate-based carriers occupy a complementary role where controlled reactivity and specific substrate interactions are prioritized, while titanium dioxide carrier systems are gaining relevance in applications that pair antimicrobial function with photocatalytic or surface-modification benefits. The strategic implication is clear: competitive advantage is shifting from raw silver content to engineered release kinetics, particle morphology, and formulation compatibility. Companies that can demonstrate predictable performance across extrusion, coating, or textile-finishing processes are capturing premium positioning, while those relying on generic silver inputs face margin pressure and heightened customer qualification hurdles.
Regulatory Architecture as a Market Filter
Regulation is no longer a peripheral compliance cost; it functions as a market filter that shapes entry dynamics, product architecture, and go-to-market pacing. EPA registration for silver-based applications in U.S. textiles has raised the evidentiary bar for safety, efficacy, and environmental impact, making regulatory readiness a de facto competitive requirement. At the same time, China’s updated recycled-plastics standards have intensified scrutiny on restricted substances, pushing formulators to align antimicrobial additives with broader material-circularity expectations. For market participants, this means that product pipelines must be built with regulatory trajectory in mind, not simply current technical performance. Early alignment with testing protocols, documentation standards, and regional substance restrictions reduces time-to-market risk and strengthens customer trust, particularly in applications where compliance failures can disrupt entire supply chains.
Demand-Side Shifts and Application Expansion
Demand is being reshaped by a blend of consumer behavior, institutional procurement standards, and functional-material expectations. Textiles remain a dominant application environment, where antimicrobial and odor-control performance supports hygiene-sensitive use cases, performance apparel, and institutional fabric programs. Beyond textiles, coatings and plastics are expanding the addressable surface area for silver-based antimicrobials, particularly where long-lasting protection, surface durability, and low-maintenance operation are valued. Consumer and enterprise buyers increasingly evaluate antimicrobial features not as isolated add-ons but as part of broader product reliability, sustainability, and lifecycle narratives. This shift rewards solutions that can be integrated without compromising material properties, appearance, or recyclability, and it penalizes formulations that create processing friction or end-of-life complications.
Supply-Side Dynamics and Cost Structure
On the supply side, the market is navigating the intersection of precious-metal economics and industrial chemistry. Silver nitrate export prices displayed notable volatility in mid-2025, influenced by Asian production declines and feedstock-level dynamics, reinforcing the need for procurement agility and formulation efficiency. Manufacturers are responding by optimizing carrier loadings, improving dispersion and ion-release efficiency, and diversifying source strategies where feasible. The broader implication is that cost leadership in this market is increasingly derived from process efficiency and application engineering rather than from raw-material arbitrage alone. Companies that can maintain performance while reducing effective silver intensity, or that can offer stable pricing through long-term supply arrangements and technical service support, are better positioned to retain customers through cycles of input-cost volatility.
Strategic Positioning Among Leading Players
The competitive landscape remains moderately consolidated, with the top three participants holding roughly 24.6% of market revenue and the top five reaching approximately 26.2%. This concentration suggests a market where scale, application breadth, and technical service networks matter, but where meaningful space still exists for specialized players with strong formulation expertise or regional execution capabilities. Leading participants are differentiating along several axes. Some emphasize inorganic silver carrier technologies purpose-built for water treatment, polymers, and resins, positioning around durability and controlled release. Others focus on silver-based additives for textiles, plastics, and coatings, integrating antimicrobial functionality into broader material portfolios. A further group targets disinfectant and hygiene applications through silver-based chemistries such as silver dihydrogen citrate, highlighting food-hygiene and surface-sanitation use cases. There is also notable activity around glass-carrier and inorganic silver systems, where the emphasis is on stability and compatibility in demanding material environments. Rather than competing solely on price, the more defensible strategies combine application-specific validation, regulatory documentation, and technical support that lowers integration risk for customers.
Antimicrobial Peptides Market
M&A, Portfolio Shaping, and New-Entry Dynamics
Recent corporate activity signals an ongoing reshaping of portfolios around silver-based antimicrobial capabilities. BASF’s completion of the Aseptrol biocide business transaction with Oxidium Technologies LLC, including silver-based antimicrobial solutions, illustrates how large chemical and biocides players are consolidating functional-material assets to strengthen application coverage and technology breadth. At the same time, PURE Bioscience’s brand repositioning around its silver dihydrogen citrate technology for food hygiene reflects a strategic attempt to sharpen market identity and align product messaging with specific end-use priorities. These moves point to a broader pattern: incumbents are tightening their focus around differentiated technology platforms, while the entry of new players is likely to occur through targeted application niches, regional distribution partnerships, or specialized carrier chemistry rather than through broad commodity competition. The practical consequence is an environment where customer qualification, regulatory readiness, and proven integration performance increasingly determine market access.
Forecast Trends and Commercial Implications
Over the next three to five years, three interlocking trends are likely to define how value is created in this market. First, application engineering will become the primary battleground. As carrier technologies mature, differentiation will depend on how well antimicrobial performance is maintained across specific processing conditions, substrates, and end-use environments. Companies that invest in application-level validation and offer formulation guidance will capture more resilient demand than those selling generic functional ingredients. Second, regulatory and sustainability integration will move from a compliance exercise to a product-design input. Documentation readiness, restricted-substance alignment, and compatibility with recycled or circularity-driven material flows will influence purchasing decisions, especially among multinational buyers and regulated-industry customers. Third, input-cost volatility will continue to reward efficiency and service depth. Pricing pressure from silver feedstock fluctuations will likely persist, but customers will increasingly prefer partners who can stabilize total cost of ownership through technical optimization, predictable supply, and quality assurance rather than chasing the lowest nominal price point.
These trends translate into tangible commercial opportunities. There is room for growth in high-value application segments where antimicrobial durability and regulatory confidence carry premium value, especially in hygiene-sensitive textiles, performance coatings, and specialized polymer applications. There is also opportunity for suppliers that can provide regionally compliant documentation packages and application-specific testing support, reducing the burden on formulators and procurement teams. At the same time, uncertainty remains. Silver price trajectories, regulatory tightening in key markets, and evolving standards for recycled-content materials could alter relative competitiveness across carrier types and end-use segments. Participants should therefore avoid overcommitting to a single application or carrier architecture without scenario planning for regulatory shifts and feedstock volatility.
Strategic Actions for Manufacturers
For manufacturers and formulators, the priority is to treat silver-based antimicrobial ingredients as engineered system components rather than commoditized additives. That means validating performance under actual processing conditions, building regulatory documentation early, and aligning product design with downstream sustainability requirements. Where possible, optimize carrier loading and ion-release efficiency to protect performance while managing silver intensity. Strengthening technical-service capabilities can also create a durable moat, because customers increasingly value partners who reduce integration risk and accelerate qualification cycles.
Worldwide Smart Antimicrobial Surface Market
Strategic Actions for Investors
For investors, the market offers attractive structural growth, but returns will likely accrue to platforms with defensible application breadth, regulatory readiness, and disciplined feedstock management. Due diligence should focus on the quality of carrier technology, the strength of application validation, and the ability to navigate regional compliance requirements. Visibility into customer concentration, product qualification pipelines, and exposure to silver-input volatility is essential when evaluating long-term resilience. Companies that can demonstrate recurring demand from regulated or hygiene-critical applications are better positioned than those reliant on discretionary or price-sensitive volume.
Strategic Actions for Procurement and Sourcing Leaders
For procurement and sourcing leaders, the strategic task is to balance cost, compliance, and performance stability. Multi-source planning, clear specification of required antimicrobial performance and regulatory documentation, and evaluation of supplier technical support can reduce exposure to both price volatility and compliance disruption. Where applications are regulated or publicly visible, prioritizing suppliers with established registration footprints and robust testing packages can lower downstream risk. In parallel, procurement teams should monitor changing restricted-substance and recycled-material standards to avoid specification mismatches that could affect product acceptability.
The silver-based antimicrobial agent market is entering a phase where informed, application-aware decision-making matters more than ever. Growth is supported by durable demand in hygiene-sensitive and performance-driven applications, but the payoff will go to participants who can integrate technical, regulatory, and supply-side realities into coherent commercial strategies. For executives and planners seeking detailed segmentation data, regional and application-level revenue splits, competitive benchmarking, and scenario-based forecasts, a full research report can provide the granularity needed to translate these market dynamics into specific sourcing, investment, and product-development decisions.
For detailed analysis of this topic, please visit the official page: Silver-based Antimicrobial Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silicon Monoxide Market: Why 15.1% CAGR Reshapes Automotive & Electronics Demand
By PW Consulting, 2026-09-21
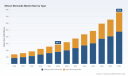
Silicon Monoxide Market: Strategic Trends and Commercial Opportunities (2025–2032)
The silicon monoxide market has entered a phase of accelerated expansion, driven by converging demands across advanced electronics, energy storage, and industrial coatings. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenues climbing from approximately $141 million to $285 million. This trajectory is projected to continue through the forecast period ending in 2032, with an estimated compound annual growth rate of 15.1 percent. By the close of the decade, the market is expected to surpass $760 million, reflecting a structural shift rather than a cyclical upswing. The growth is not uniform across all verticals or geographies; it is concentrated in application areas where material purity, thermal stability, and barrier properties are becoming critical differentiators.
For executives and investors tracking specialty materials, this market presents a compelling case study in how a relatively niche inorganic compound is transitioning into a strategic enabler for multiple high-growth industries. The challenge lies in navigating a fragmented supply base, evolving regulatory frameworks, and rapidly changing end-user specifications. Understanding where value is being created—and where vulnerabilities are emerging—requires moving beyond headline figures to examine the underlying technological, policy, and supply chain dynamics.
Market Status and Core Challenges
The current market structure reflects a balance between established industrial uses and emerging high-performance applications. Gaseous and solid forms of silicon monoxide serve distinct processing requirements, with each format catering to specific deposition, coating, or synthesis workflows. The revenue split between these formats underscores a mature but still evolving production ecosystem, where manufacturers are increasingly pressured to deliver consistent purity levels while scaling output. Similarly, demand is distributed across automotive and transportation, consumer electronics, energy and power systems, and a range of secondary applications. This distribution signals that no single industry dominates the growth narrative; instead, multiple sectors are pulling the market forward, each with its own technical thresholds and procurement cycles.
Geographically, the market exhibits a multi-polar character. North America, Europe, and Asia Pacific each command significant shares, while Latin America and the Middle East and Africa represent smaller but gradually expanding footholds. This geographic spread is not merely a reflection of historical manufacturing capacity; it is increasingly shaped by localized supply chain strategies, trade flows, and regional industrial policies. The presence of verified exporters across multiple continents, alongside targeted trade activity in emerging markets, indicates that silicon monoxide is moving through a globalization phase where sourcing flexibility and regulatory compliance are becoming as important as price competitiveness.
Several structural challenges complicate this growth trajectory.
- Purity and consistency requirements are intensifying. As silicon monoxide finds its way into battery anodes, thin-film deposition, and high-barrier packaging, end users are demanding tighter control over impurities and particle morphology. Inconsistent feedstock quality or variable reaction conditions can disrupt downstream performance, making quality assurance a competitive moat rather than a baseline expectation.
- Regulatory and trade compliance is fragmenting. Classification under inorganic compound duty frameworks, coupled with shifting export documentation requirements and country-specific trade data reporting, adds layers of complexity for cross-border procurement. Companies that treat compliance as an afterthought face delays, cost overruns, and potential supply interruptions.
- Supply chain concentration risks are emerging. While the market remains relatively fragmented at the top, with the top three and top five players holding modest combined shares, the underlying production ecosystem depends on high-temperature reaction processes and reliable silicon feedstock. Any disruption in upstream material availability or energy-intensive manufacturing capacity can create bottlenecks that ripple through multiple application sectors.
For decision makers, these challenges are not merely operational headaches; they are strategic inflection points. Companies that proactively address purity standardization, trade compliance, and feedstock resilience will be better positioned to capture premium segments, while those that compete primarily on price risk margin compression as customer expectations rise.
Key Demand Drivers Analysis
Technological Innovation and Material Breakthroughs
The most powerful accelerator for silicon monoxide demand is the ongoing push toward higher-performance materials in energy storage and electronic fabrication. In lithium-ion battery development, silicon-based anodes are attracting sustained attention for their potential to increase energy density compared with conventional graphite formulations. Silicon monoxide plays a role in this ecosystem both as a precursor and as a functional component in coating and synthesis workflows. Manufacturers that can deliver high-purity forms tailored to anode development are aligning themselves with a long-term technological shift rather than a short-term procurement trend.
At the same time, vacuum deposition and sputtering applications continue to rely on silicon monoxide evaporation sources and related deposition materials. As thin-film processing becomes more precise in semiconductor-adjacent and industrial coating environments, the need for stable evaporation behavior, predictable particle size, and reproducible deposition rates is increasing. This is driving suppliers to refine product forms—pieces, powders, and customized evaporation sources—so that downstream users can reduce process variability and improve yield.
Policy and Regulatory Environment
Regulatory conditions are shaping market access and cost structures in subtle but meaningful ways. In key markets such as the United States, silicon monoxide is classified under inorganic compound duty frameworks that generally allow duty-free treatment, lowering the tariff barrier for cross-border trade. While this may appear to be a minor detail, it has practical implications for sourcing strategies, especially for manufacturers that operate across multiple jurisdictions or assemble final products from globally sourced components.
Beyond tariffs, export documentation and trade transparency are becoming more prominent. Verified export activity across multiple shippers and destinations over recent periods indicates that the trade network is active but still relatively dispersed. For companies engaged in import/export operations, the ability to navigate shipment verification, country-of-origin documentation, and destination-specific requirements is increasingly a differentiator. Regulatory clarity can reduce lead times and working capital friction, while ambiguity can create hidden costs that erode competitiveness.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user behavior is changing on two fronts. In consumer electronics, the drive toward smaller, more durable, and better-protected devices is reinforcing interest in barrier materials and thin-film coatings where silicon monoxide can contribute. In industrial and energy sectors, procurement teams are increasingly evaluating materials not just on specification sheets but on total cost of ownership, including process stability, waste reduction, and integration ease. This shift is pushing suppliers to offer more than raw material; it is encouraging value-added formats, technical support, and application-specific packaging.
The automotive and transportation segment reflects a broader transition toward electrification and lightweighting, where material performance and supply reliability matter more than ever. As vehicle manufacturers and their tier suppliers reassess component sourcing in response to electrification roadmaps and regional content requirements, silicon monoxide’s role in battery-related workflows and specialized coatings positions it as a material worth monitoring in procurement strategies.
Supply Chain and Cost Structure Evolution
The production of silicon monoxide typically involves high-temperature reactions between silicon and silicon dioxide, or carbon-based reduction of silicon dioxide, with high-purity silicon feedstock underpinning consistent quality. This process architecture means that energy costs, feedstock availability, and reaction control are central to margin dynamics. As energy markets fluctuate and industrial energy efficiency becomes a broader corporate priority, producers that can optimize thermal processes, reduce waste, and maintain tight purity control will gain an advantage.
At the same time, the supply base is expanding in certain regions, with manufacturers offering silicon monoxide pieces, powders, and chemical-grade products for coating and inorganic chemical portfolios. This diversification increases buyer options but also raises the importance of qualification and vendor evaluation. Buyers that build rigorous technical assessment processes can secure better terms and more reliable supply, while those that rely on spot purchasing without technical due diligence may encounter inconsistent performance.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized producers, broad-line material suppliers, and regional manufacturers targeting distinct application niches. Rather than competing as a single undifferentiated market, participants are carving out positions based on purity ranges, product forms, application alignment, and geographic reach.
Several companies illustrate the strategic diversity currently shaping the market.
- Osaka Titanium Technologies Co., Ltd. has positioned itself around high-purity silicon monoxide for food packaging barrier applications and lithium-ion battery anode development. This dual focus reflects a strategy of linking material quality to high-value downstream uses, where purity and consistency directly influence customer outcomes.
- RD Mathis Company concentrates on evaporation sources, pieces, and deposition materials for vacuum technology. Its approach emphasizes process enablement, supplying the forms and configurations that deposition users need to reduce setup complexity and improve reproducibility.
- American Elements offers silicon monoxide in multiple purities and forms for research, sputtering targets, and industrial applications. This breadth-based model appeals to customers who require flexibility across R&D and production environments, and who value a supplier capable of supporting varied procurement scenarios.
- Stanford Advanced Materials (SAM) leverages manufacturing experience to supply high-quality silicon monoxide for electronic and industrial uses. Its long-standing production background supports a reliability narrative that resonates with buyers seeking stable supply and predictable specifications.
- Unilong Industry Co., Ltd. focuses on pieces and powder for coating and material applications, targeting customers that need practical forms for surface engineering and coating workflows.
- Hebei Yanxi Chemical Co., Ltd. and Hefei TNJ Chemical Industry Co., Ltd. operate within the inorganic chemical space, supplying silicon monoxide as part of broader chemical portfolios. Their presence highlights how the material is integrated into wider chemical supply chains, where procurement efficiency and portfolio breadth can be as important as isolated product specs.
The strategic positioning of these players reveals several differentiation levers. Some compete on purity and application alignment, others on product form and process support, and still others on portfolio breadth and regional availability. What is notable is that none of these approaches is inherently superior; rather, their effectiveness depends on the customer’s technical requirements, procurement model, and risk tolerance.
Market evolution is likely to follow a path of partial consolidation alongside continued specialization. On one hand, buyers increasingly prefer suppliers that can demonstrate consistent quality, regulatory familiarity, and application expertise, which may favor larger or more integrated players over time. On the other hand, the diversity of end uses—from packaging barriers to battery development to vacuum deposition—creates room for specialized manufacturers that can serve narrow but high-value segments. New entrants may find opportunities by focusing on underserved application niches, offering custom particle or form factors, or building stronger technical service capabilities around deposition and coating processes.
For competitive strategy, the key question is not simply who has the largest footprint, but who can reduce uncertainty for the buyer. Suppliers that combine reliable purity, clear trade documentation support, and application-relevant product forms are better positioned to command preference in procurement decisions, especially as customers move from spot buying toward longer-term supply relationships.
Future Trends Forecast
Looking ahead three to five years, several trends are likely to shape the market’s direction and create actionable opportunities.
Carbon Monoxide Market
1. Higher-purity, application-tailored forms will become the norm in premium segments. As silicon monoxide is integrated into more performance-sensitive workflows, buyers will increasingly differentiate between commodity-grade supply and specification-driven material. This will reward suppliers that invest in controlled reaction conditions, consistent particle morphology, and transparent quality documentation. The commercial opportunity lies in shifting from price-based competition to value-based positioning, where reliability and specification alignment justify premium margins.
2. Battery-related and energy storage workflows will continue to be a strategic growth vector. The broader interest in silicon-based anode development and energy density improvements is not a short-lived trend; it reflects a structural interest in next-generation storage materials. Silicon monoxide’s role in these workflows may evolve as formulations and processing methods mature, but the directional signal is clear: materials that support battery performance and manufacturing consistency will remain in focus. Companies that build application expertise and supply readiness for this vector can capture a growing share of demand, provided they can navigate technical qualification cycles and scale requirements.
3. Trade transparency and regional sourcing strategies will intensify. With active export flows across multiple shippers and destination markets, procurement teams are likely to place greater emphasis on supply visibility, documentation reliability, and regional resilience. This trend creates opportunities for suppliers that can offer predictable lead times, clear compliance support, and flexible sourcing arrangements. At the same time, it introduces risk for companies that rely on opaque supply chains or assume that duty-free classification automatically translates into frictionless trade. Regulatory interpretation, documentation quality, and destination-specific requirements will continue to matter.
PW Consulting
These trends carry inherent uncertainties. Technological adoption in battery anodes may proceed at different speeds across vehicle platforms and cell manufacturers. Energy costs and feedstock availability could affect production economics, particularly for energy-intensive synthesis routes. Trade documentation and compliance expectations may become more stringent in certain jurisdictions, adding cost and administration even where tariffs remain favorable. Decision makers should therefore treat growth opportunities as conditional on operational readiness, not as automatic outcomes of market expansion.
Actionable Guidance for Decision Makers
The market’s direction offers different implications depending on a company’s role in the value chain. The following recommendations are designed to translate market dynamics into practical next steps.
For Manufacturers and Material Suppliers
Focus on specifying and communicating purity, form consistency, and application fit rather than competing solely on unit price. Customers in deposition, coating, and battery-related workflows are increasingly weighing total process performance, so suppliers that provide clear technical documentation, reproducible product forms, and responsive support can differentiate more effectively. At the same time, review production economics with energy efficiency and feedstock reliability in mind, since these factors will influence margin stability as demand scales.
For Investors and Strategic Planners
Evaluate exposure to silicon monoxide not as a single market bet but as a cross-cutting enabler across electronics, energy storage, and industrial coatings. The most resilient opportunities are likely to be tied to suppliers or downstream users that can demonstrate application-specific value, reliable compliance handling, and the ability to serve multiple verticals without diluting quality. When assessing potential investments or partnerships, pay attention to qualification readiness, supply chain transparency, and the company’s ability to navigate trade documentation and regional sourcing requirements.
Silicon 28 Market
For Procurement and Sourcing Leaders
Strengthen technical qualification processes before committing to volume supply. Given the variability in product forms and purity ranges across the supply base, spot purchasing without specification alignment can create downstream variability and hidden costs. Build a shortlist based on documented purity consistency, form suitability for the intended process, and trade compliance reliability. Where possible, favor suppliers that can support predictable documentation and lead times, as these attributes reduce operational friction in multi-source or multi-region procurement strategies.
For organizations that need deeper segmentation, region-specific trade dynamics, and customized scenario planning, a more detailed research view can help translate these strategic signals into precise procurement, investment, and production decisions. A comprehensive report is available for teams that require granular data, application-level breakdowns, and tailored recommendations aligned with specific operational objectives.
For detailed analysis of this topic, please visit the official page: Silicon Monoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Building Safer Workplaces Through Smarter Employee Training
In demanding work environments, employee training needs to be treated as much more than an annual obligation or a compliance exercise. Workers routinely handle sophisticated equipment, complex systems, and procedures that can change with little warning. Under these conditions, even a small mistake can produce serious consequences. Training should therefore remain an active part of the overall safety strategy one that responds to workplace hazards, strengthens judgment, and helps stop incidents before they occur.
Organizations can achieve stronger results when learning is treated as an operational protection rather than simply a regulatory duty. A useful training framework is continuous, measurable, and accountable. Digital learning platforms can support this model by providing instruction based on job responsibilities, checking competency during normal operations, and keeping reliable records of training, certifications, and authorization for specific tasks. Bringing courses, assessments, and certification tracking together also promotes consistency when procedures are revised, requirements change, or employees and contractors enter or leave a workplace.
Training That Improves Everyday Work
When learning is woven into daily operations, it can influence safety and performance instead of merely transferring information. Rather than asking employees to sit through long sessions well before they need the knowledge, modern approaches can provide useful guidance closer to the moment it matters.
Microlearning is especially useful in this approach. Brief, focused modules allow workers to reach essential information connected to their responsibilities from any device. Training becomes easier to access and more closely connected with operational needs, while interruptions to productive work can be minimized.
Learning also becomes more effective when it reflects the responsibilities of roles. Operators, supervisors, maintenance teams, and contractors encounter different hazards, pressures, and expectations, so identical generic material may not address their needs. Activities involving confined spaces, lockout procedures, or hot work require instruction that reflects the conditions workers may encounter. Company policies, compliance obligations, and client expectations can be built into learning as well, reducing reliance on scattered paperwork or inconsistent explanations from people.
Digital learning can also provide clearer evidence of competency instead of treating course completion as proof of capability. Records of training, assessment results, and certifications can be organized in one place, creating useful evidence of workforce readiness. Such information can support inspections and audits while helping organizations verify that expected requirements are being applied consistently.
Keeping Learning Current as Conditions Change
Industrial workplaces are constantly evolving. Equipment may be replaced, procedures can be updated, and workforce needs may shift. Large projects can face additional complexity when contractors regularly rotate, making it harder to keep skills and qualifications current. Traditional classroom programs may be less flexible in these circumstances because updating materials requires coordination, while revised information may not reach every worker or site in the same way.
A digitally managed learning environment can address many of these challenges. When new hazards or competency gaps are identified, revised instruction can be shared more rapidly. Learning can therefore stay current, accurate, and connected to operating conditions. Organizations can establish common expectations across several facilities while still adapting content for regional requirements, language preferences, and project specific circumstances. Training records can also give managers a clearer picture of certification status, completed courses, expiration dates, and workforce learning history.
Built Around Real Operational Needs
Training is most useful when it fits naturally into daily work rather than creating an unnecessary interruption. Effective learning systems consider shift patterns, established routines, and the responsibilities attached to positions. Defined learning paths make expectations easier to understand, while reminders and refresher activities help employees maintain knowledge and competency.
Certification tracking becomes more manageable when it is connected with learning. Upcoming qualification expirations can be monitored automatically, while advance notifications can reduce the risk of unexpected gaps. Contractors can also complete required onboarding before reaching a site, helping them begin work with an understanding of safety expectations, workplace rules, and required procedures.
Centralized oversight allows organizations to maintain consistent practices across locations while preserving local variations. Audit preparation can become more efficient when dashboards provide a view of participation, assessment outcomes, and completion records. In some workplaces, training can even function as an operational control, with access to certain activities limited until required learning has been successfully completed.
Turning Learning Into Operational Value
Training can provide practical benefits when it becomes part of operational management. Employees are better prepared for permit driven activities when required instruction and competency checks have already been completed. Safety awareness initiatives can also be introduced quickly when new concerns appear, allowing organizations to address risks before they develop into incidents.
Project mobilization and site startup can be more orderly when employees and contractors arrive with a common understanding of requirements and expectations. Contractor oversight is strengthened through consistent learning standards and competency checks. Certification renewals can be planned ahead of time rather than becoming urgent tasks at the last minute. When workers receive timely instruction that reflects the conditions they encounter, organizations can also create conditions that support fewer incidents over time.
Putting the Learning Framework Into Action
Implementation should begin by linking job responsibilities with workplace hazards and permit requirements. That connection provides the basis for a structured learning strategy. Organizations can then develop focused learning paths that bring together essential knowledge, role specific instruction, and scheduled refresher activities.
Learning should become part of operational routines as well, including safety inspections and checks completed before work starts. Regular review of performance indicators and incident patterns can reveal where training needs reinforcement and where emerging risks require new or revised content.
When workforce competency is visible, current, and consistently verified, training can deliver benefits well beyond regulatory compliance. Organizations can create safer workplaces, strengthen day to day performance, and support productivity while offering greater protection to the people carrying out the work.
Book a free demo @ https://toolkitx.com/campaign/elearning/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Why-manual-excel-sheets-are-silently-draining-your-tank-farm%27s-profitability