

Blogs
Paracetamol Market: Why the 4.5% CAGR Trajectory Changes Everything by 2032
By PW Consulting, 2026-09-21
Paracetamol Market: Strategic Trends and Commercial Opportunities Through 2032
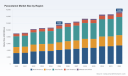
The global paracetamol market has reached a significant inflection point, with total revenues climbing to approximately USD 11,500 million in 2025 and a projected trajectory toward USD 15,300 million by 2032. This expansion reflects a compound annual growth rate of 4.5 percent across the 2026 to 2032 forecast window, building on a period of steady recovery and structural reshaping from 2020 through 2025. The market's resilience stems from paracetamol's entrenched position as a first-line analgesic and antipyretic, yet the operating environment is no longer defined by stable demand and predictable margins. Instead, manufacturers, distributors, and investors are navigating a landscape shaped by raw material volatility, evolving regulatory expectations, and shifting consumer preferences that favor differentiated delivery formats. Understanding where value is being created—and where it is being eroded—requires looking beyond headline figures to the underlying dynamics that will dictate competitive outcomes over the next several years.
Market Snapshot and Emerging Challenges
The paracetamol sector has grown from a baseline of roughly USD 9,000 million in 2020 to its current scale, with the pace of expansion accelerating modestly as healthcare systems stabilized and over-the-counter self-medication regained momentum following pandemic-era disruptions. Growth has been broad-based, but regional performance tells a more nuanced story. Asia Pacific and North America together account for the largest revenue shares, reflecting both high population density in the former and strong branded distribution networks in the latter. Europe remains a mature but stable contributor, while Latin America and the Middle East and Africa represent smaller but strategically important markets where access-to-medicine initiatives and pricing reforms continue to shape volume trajectories.
Industry concentration offers another lens on market structure. The top three players command roughly 35 percent of global revenue, while the top five extend that share to approximately 45 percent. Such concentration indicates that scale, supply chain leverage, and regulatory expertise remain meaningful barriers to entry, yet it also signals room for specialization. Smaller and mid-tier manufacturers can compete effectively by focusing on niche formulations, regional regulatory approvals, or value-added delivery systems rather than attempting to match incumbents across every segment.
Several challenges are reshaping how companies approach the market. First, the supply chain for para-aminophenol, the primary precursor for paracetamol synthesis, experienced notable disruption in 2025 when export controls imposed by China constrained global availability. This episode exposed the sector's reliance on a concentrated precursor base and highlighted the vulnerability of cost structures that lack diversification or contractual flexibility. Second, pricing pressures intensified in key markets. In India, the National Pharmaceutical Pricing Authority documented sharp increases in paracetamol prices during 2025, driven by raw material cost escalation and the complex interplay of government production-linked incentive schemes that altered competitive dynamics among domestic manufacturers. Third, the regulatory environment is becoming more demanding. Amendments to US FDA monographs expected in 2026 are projected to raise labeling compliance costs, adding a new layer of expense for both branded and generic producers operating in or exporting to the United States.
For executives, these challenges translate into three immediate priorities: securing more resilient raw material sourcing, preparing for incremental compliance costs that may compress margins on low-differentiation products, and evaluating whether existing portfolio mixes align with markets where pricing power can be defended.
Key Drivers Shaping Market Trajectory
Technological and Formulation Innovation
Innovation in paracetamol has shifted from the molecule itself to the way it is delivered, absorbed, and experienced by patients. Recent developments underscore this focus. In early 2025, Haleon completed a bioequivalence study of an orodispersible paracetamol tablet at a 500 mg dose in healthy adults under fasting conditions. By mid-2025, ClinicalTrials.gov recorded the completion of a Phase 1 bioequivalence study for similar orodispersible tablets. These activities point to a broader industry effort to improve convenience, adherence, and perceived efficacy, particularly in segments where swallowing conventional tablets is a barrier for certain patient populations.
Orodispersible formats are not merely a technical exercise; they represent a pathway to premium positioning in over-the-counter channels where consumer perception and ease of use influence purchase decisions. Companies that can demonstrate consistent bioavailability, stable manufacturing processes, and acceptable taste profiles are better placed to capture share in categories where differentiation has historically been thin. The commercial implication is clear: formulation capability is becoming a competitive lever, and manufacturers that invest in delivery-system expertise can reduce reliance on commodity pricing dynamics.
Policy and Regulatory Environment
Regulatory developments are reshaping both market access and cost structures. In India, the National Pharmaceutical Pricing Authority's 2025 findings on paracetamol price increases illustrate how domestic policy can amplify or mitigate the effects of raw material inflation. Production-linked incentive schemes, while intended to strengthen domestic manufacturing capacity, have interacted with cost escalation in ways that produced noticeable price movements and altered competitive positioning among local suppliers.
In the United States, anticipated FDA monograph amendments for 2026 are expected to increase labeling costs for paracetamol products. While these changes do not alter the drug's clinical role, they do affect the economics of product line management. Companies with complex SKU portfolios, multiple packaging configurations, or extensive distribution footprints will need to model the cumulative impact of compliance costs and decide where simplification or consolidation can preserve profitability. Parallel attention to pharmacovigilance expectations remains relevant, as regulatory bodies continue to evaluate the broader safety narrative around widely used analgesics, even when clinical evidence remains reassuring.
Demand-Side Shifts and Consumer Behavior
Consumer behavior continues to evolve in ways that influence both volume and product mix. A growing preference for self-care and accessible over-the-counter options has reinforced demand for paracetamol across multiple indications, including headache, fever, cold and cough, and muscle cramps. The application landscape is broad, and the relative weight of each use case varies by region and demographic profile. What matters strategically is that demand is not monolithic; it is segmented by age, presentation, and purchase context, which creates opportunities for targeted product design and channel strategy.
Recent safety research has also contributed to a more stable demand environment by addressing long-standing public questions. A February 2026 meta-analysis published by UpToDate found no association between prenatal paracetamol use and autism or ADHD risk in low-bias studies with long follow-up. In January 2026, MedicalXpress released findings supporting the safety of paracetamol and ibuprofen in infants under one year of age, with no link to eczema or other measured risks. In April 2026, JAMA Network published a trial comparing acetaminophen versus opioid addition to ibuprofen for pediatric pain relief, contributing to ongoing discussions about optimal analgesia strategies. Collectively, these developments help sustain confidence in paracetamol's role in both adult and pediatric settings, reducing the likelihood that safety concerns will materially disrupt demand in mainstream markets.
Supply Chain and Cost Structure Dynamics
The cost side of the equation has become a strategic focal point. China's dominant position in paracetamol precursor supply has been a defining feature of the market. A May 2026 US State Department report highlighted China's roughly 70 percent share of para-aminophenol supply, with direct US imports at only 17 percent. That concentration became more consequential in 2026, when an Iran-related conflict triggered vessel shortages that restricted API movement from China and drove paracetamol raw material prices up by more than 26 percent in India.
These events are not isolated; they reveal structural dependencies that companies must manage proactively. Firms that depend on single-source precursor procurement or that lack visibility into tiered supplier networks are exposed to both price shocks and availability risk. Conversely, organizations that have built multi-source strategies, maintained strategic inventory buffers for critical inputs, or invested in forward contracting are better positioned to stabilize costs and protect supply continuity. The broader lesson is that supply chain design is now a competitive differentiator in a market where margins on undifferentiated products are already under pressure.
Competitive Landscape and Leading Strategies
The paracetamol market features a mix of large multinationals, established Indian API and formulation producers, and regional specialists. This blend creates a competitive environment in which scale, geographic reach, and formulation capability interact in different ways across segments.
Among the companies shaping the market, several Indian manufacturers stand out for their high-volume production of paracetamol API and finished dosage forms. Granules India Limited, based in Hyderabad, is a major producer of paracetamol API and tablets with extensive global supply relationships. IOL Chemicals and Pharmaceuticals Limited, headquartered in Ludhiana, is an active manufacturer and exporter of paracetamol API and formulations. Farmson Pharmaceutical Gujarat Private Limited, operating from Gujarat, produces paracetamol API and tablets under WHO-GMP and other recognized standards. These firms illustrate the strategic importance of cost-efficient, compliant manufacturing in a market where precursor dynamics and pricing regulation can move quickly.
Larger integrated players bring a different set of advantages. Sun Pharmaceutical Industries Ltd, based in Mumbai, operates as a global pharmaceutical company with paracetamol tablet and API production capabilities. Cipla Ltd, also headquartered in Mumbai, manufactures paracetamol tablets and formulations across multiple markets. Their scale, regulatory infrastructure, and distribution reach allow them to compete across both generic and branded contexts, though they must still navigate the same raw material and compliance pressures affecting the broader industry.
On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. These organizations typically compete on brand equity, patient-facing positioning, and broader portfolio integration rather than price alone.
Acetaminophen Market
The strategic positioning of these players diverges in ways that matter for competitive planning. Indian API and formulation manufacturers often emphasize volume, cost discipline, and export capacity, leveraging regulatory certifications and production efficiency to serve both domestic and international markets. Multinationals and branded players more frequently invest in patient convenience, formulation variety, and trust-based consumer relationships, which can support pricing resilience in categories where differentiation is credible. Companies that combine strong manufacturing fundamentals with formulation-driven differentiation are increasingly well placed to navigate both commodity pressure and premium opportunity.
PW Consulting
Market structure is evolving through selective consolidation and parallel fragmentation. On one hand, larger players continue to seek efficiencies in supply, regulatory management, and distribution, which can lead to tighter integration across API, formulation, and packaging. On the other hand, specialized niche participants are carving out positions around delivery formats, regional approvals, and patient-centric packaging that do not require matching the full scale of the largest competitors. New entrants face meaningful hurdles given existing concentration and regulatory complexity, but targeted entry remains possible where formulation novelty, local market knowledge, or channel access provides a defensible starting point.
Recent industry events reinforce the strategic significance of these divergent paths. Safety and clinical developments have reinforced demand confidence in established use cases, while formulation work on orodispersible tablets indicates where incremental differentiation is being pursued. At the same time, raw material disruptions and pricing actions in key markets show that even well-positioned companies must manage upstream dependencies and regulatory cost exposure with discipline.
Antipyretic and Analgesic Market
Forward Outlook: Trends and Commercial Implications
Trend One: Greater Emphasis on Delivery Format Differentiation
Over the next three to five years, formulation differentiation is likely to become a more visible feature of competition, especially in over-the-counter channels where consumer choice is shaped by convenience, taste, and perceived ease of use. Orodispersible and other patient-friendly formats are attracting clinical and commercial attention, and companies that can bring these formats to market with consistent quality and credible bioequivalence data may gain incremental pricing latitude. The commercial opportunity lies in aligning format innovation with target populations and channel strategies, rather than treating new delivery systems as a generic upgrade. A related risk is that differentiation only pays off when it is supported by manufacturing reliability, taste acceptability, and clear consumer communication; otherwise, premium positioning is difficult to sustain.
Trend Two: Supply Chain Reconfiguration and Sourcing Diversification
The concentration of para-aminophenol supply and the price shocks associated with geopolitical and logistical disruptions point toward a longer-term shift in sourcing strategies. Companies are likely to pursue a combination of multi-source procurement, closer supplier relationships, and regional capacity planning to reduce exposure to single-point failures. For manufacturers with significant exposure to precursor imports, this may mean renegotiating supply terms, qualifying alternative sources, or adjusting production planning to absorb short-term volatility more efficiently. The opportunity here is to convert supply chain resilience into a more stable cost base and more dependable fulfillment, both of which support customer trust and margin protection. The risk is that diversification takes time and capital, and that transitional periods can create their own inefficiencies if supplier qualification and quality assurance are not managed carefully.
Trend Three: Regulatory Cost Management as a Core Competency
As labeling and monograph requirements evolve, particularly in major markets such as the United States, regulatory cost management will become a more central element of portfolio strategy. Companies that proactively rationalize SKU complexity, streamline packaging variations, and align compliance processes with manufacturing workflows are more likely to preserve margins than those that treat regulatory changes as an external cost to be absorbed passively. This trend also intersects with market access and pricing policy in regions such as India, where domestic regulation can interact with raw material economics in ways that drive price outcomes. Businesses that monitor these dynamics closely and incorporate them into planning will be better positioned to anticipate margin shifts and adjust product strategies before pressure becomes acute.
Implications for Decision Makers
For manufacturers, the immediate priority is to strengthen upstream resilience while identifying where formulation or delivery improvements can support differentiation. This means reviewing precursor sourcing strategies, testing alternative supply paths, and assessing whether current portfolio complexity is justified by the margin it generates. Where product lines are commoditized, simplification can reduce compliance burden and improve operating efficiency. Where there is credible potential for a differentiated format, targeted development and evidence generation can create a more defensible position in specific consumer segments.
For investors, the market rewards companies that combine cost discipline with credible differentiation and that demonstrate visibility into supply risk. The most attractive profiles are likely those with diversified sourcing, manageable regulatory exposure, and a clear strategy for where premium positioning is possible. It is equally important to distinguish between growth that comes from volume recovery and growth that is supported by product or process advantages, because the durability of each differs. Raw material volatility and regulatory cost changes should be treated as structural considerations rather than temporary noise, and valuation assumptions should reflect the sensitivity of margins to those factors.
For procurement and supply chain leaders, the priority is to reduce single-point dependencies and increase transparency across tiered suppliers. This includes mapping exposure to precursor concentration, evaluating contractual protections, and planning for periods of elevated cost or constrained availability. Building scenarios that account for geopolitical disruption, vessel availability, and regional pricing actions can improve responsiveness and reduce the likelihood of reactive purchasing at unfavorable terms. Procurement strategy in this market is not only about price; it is about continuity, quality assurance, and the ability to support manufacturing stability when upstream conditions shift.
Bringing the Analysis Together
The paracetamol market is moving through a phase in which growth is real but not uniform, and where competitive advantage will increasingly depend on how well companies manage supply exposure, regulatory cost pressure, and the opportunity to differentiate through formulation and patient-facing value. Demand fundamentals remain strong across core indications, and recent clinical and safety developments have helped sustain confidence in the molecule's role. At the same time, precursor concentration, pricing dynamics in key markets, and evolving compliance expectations mean that the path to profitable growth is narrower than it may appear from headline size alone.
Companies and investors that gain the deepest visibility into these interacting forces will be best positioned to act early—whether that means restructuring sourcing, refining portfolio complexity, investing in format differentiation, or reassessing where pricing power can be defended. The strategic window is open now, before further regulatory changes, supply disruptions, or competitive moves reshape the terms of participation.
For decision makers seeking detailed segmentation data, company-level benchmarks, and scenario-based guidance tailored to specific geographies and product lines, the full PW Consulting research report provides a more granular view of the market and its strategic levers. The broader analysis presented here is intended to frame the most important choices; the complete study is designed to support the next step in planning with deeper segmentation, competitive mapping, and forward-looking scenarios.
For detailed analysis of this topic, please visit the official page: Paracetamol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laminate Flooring Market: How the 6.98% CAGR and Residential Demand Redefine Growth
By PW Consulting, 2026-09-21
Navigating the Laminate Flooring Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context: Scale, Growth Trajectory, and Structural Headwinds
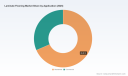
The laminate flooring sector has demonstrated resilient expansion over the past half-decade, recovering from a brief contraction in 2024 to reach an estimated USD 1.7 billion in annual revenue by 2025. Over the 2020–2025 historical window, the market expanded at a compound annual rate that reflected both post-pandemic housing activity and a steady shift toward cost-effective, aesthetically versatile flooring alternatives. Looking ahead to the 2026–2032 forecast horizon, the sector is positioned to sustain a robust growth path, with revenues projected to cross the USD 2.6 billion threshold by the end of the period. The annualized growth rate implied by these projections underscores a market that is not merely rebounding but structurally expanding, driven by durable demand signals and incremental product innovation rather than short-lived cyclical spikes.
Despite the favorable top-line trajectory, the industry sits at a inflection point where growth alone no longer guarantees profitability or market share retention. Three structural challenges are reshaping how participants compete and allocate capital. First, raw material volatility—particularly in amino resin inputs—has compressed margins and forced manufacturers to revisit pricing strategies, inventory planning, and formulation alternatives. Second, the regulatory environment has tightened on both sides of the Atlantic, with formaldehyde emission thresholds and performance standards creating a compliance barrier that favors established producers with robust quality systems and penalizes smaller players lacking technical infrastructure. Third, consumer and specifier preferences are shifting faster than traditional product development cycles, placing a premium on waterproof capabilities, realistic wood visuals, and sustainable positioning—attributes that require sustained R&D investment and supply chain coordination.
Cork Flooring Market
Core Drivers Reshaping the Laminate Flooring Landscape
Material Innovation and Performance Upgrades
The most visible driver of market evolution is the transition from traditional laminate as a purely decorative, moisture-sensitive surface to engineered formats that deliver water resistance, enhanced durability, and tighter click mechanisms. Recent product updates emphasizing multi-hour water resistance and spill-defense technologies illustrate how manufacturers are responding to real-life usage scenarios in both homes and light commercial settings. These advances are not cosmetic; they alter the value proposition of laminate relative to rigid core and luxury vinyl alternatives, allowing laminate to retain relevance in moisture-prone spaces such as kitchens, entryways, and some hospitality environments. The integration of advanced locking systems and refined surface treatments also raises installed performance, which matters increasingly to contractors and end-users who weigh total cost of ownership rather than upfront material price alone.
Regulatory Tightening as Both Constraint and Differentiator
Regulatory frameworks governing formaldehyde emissions and product performance have matured from compliance checkboxes into strategic variables. In the United States, emission standards under TSCA Title VI and CARB Phase 2 continue to shape sourcing decisions, while European market access hinges on performance classifications and emission limits that must be demonstrated through consistent testing and documentation. For manufacturers, these requirements raise the cost of entry and reward scale, process control, and transparent supply chains. At the same time, they create a differentiation path for brands that can communicate low-emission credentials and certified performance with credibility. The net effect is a market where regulatory conformance is becoming a competitive asset rather than a simple cost of doing business.
Demand-Side Shifts in Residential and Commercial End Use
Demand patterns reflect evolving lifestyles and asset management priorities. In residential settings, owners are prioritizing flooring that balances visual warmth with practical resilience—especially in households with children and pets, where spill resistance and easy maintenance carry real purchase weight. In commercial applications, facility managers and designers are seeking products that support durability targets, ease of replacement, and sustainability goals without sacrificing design quality. This dual demand profile encourages product line extensions that serve both segments while preserving distinct branding and performance messaging. Trade show activity and industry trend publications reinforce the direction of travel, with recurring emphasis on natural textures, sustainable design narratives, and installation-friendly systems that reduce labor friction.
Supply Chain and Cost Structure Realignment
The laminate value chain remains sensitive to input costs, particularly resin systems and wood fiberboard substrates sourced from sustainably managed forests. Price fluctuations in amino resin inputs during recent periods have rippled through production economics, prompting producers to diversify suppliers, renegotiate contracts, and in some cases reformulate top-layer compositions where feasible. Alongside input volatility, logistics costs and trade dynamics influence landed pricing and geographic availability. Some producers have repositioned local or regional manufacturing as a hedge against tariff-heavy import exposure, using design-forward, PVC-free programs to capture buyers seeking quality and supply security. This reorientation hints at a broader supply chain realignment in which proximity, compliance assurance, and material transparency are gaining strategic weight alongside unit cost.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive set spans large diversified flooring organizations and specialized laminate producers, each pursuing distinct positioning strategies. Several North American-based manufacturers have concentrated on waterproof laminate collections with realistic wood visuals and advanced locking systems, targeting both residential and commercial use cases where moisture performance is a deal driver. Others have built premium lines around integrated technology for durability and low-emission residential options, using certification and performance messaging to justify price premiums and strengthen dealer confidence. In Europe, established panel and flooring groups continue to emphasize high-quality laminate built on wood fibreboard substrates and impregnation papers, aligning product development with on-trend residential and commercial aesthetics. A parallel strand of competition comes from brands advancing sustainable sourcing narratives, including high proportions of sustainably sourced wood and eco-conscious resins, paired with click systems designed to improve installation speed and joint integrity.
Recent activity shows how these strategies are being operationalized. One major European panel and flooring group re-established design-forward, sustainable, PVC-free laminate programs as a high-quality alternative to tariff-heavy imports, signaling a deliberate pivot toward supply resilience and material positioning. Around the same period, another producer showcased new PVC and mineral core flooring technologies alongside laminate offerings at a major trade event, reflecting a broader portfolio approach that treats laminate as part of a wider hard-surface ecosystem rather than a standalone silo. Industry associations and expos continue to function as coordination points for new product catalogs and installation techniques, while trend reports from European producer groups highlight natural textures and sustainable design as recurring themes for upcoming collections. Product-level updates extending water resistance in core collection lines further illustrate the pace of incremental improvement across the market.
PW Consulting Health Care Research Center
Market structure data indicates a moderately fragmented landscape with a consolidated top tier. The combined share of the leading three participants sits below a quarter of total revenue, and the top five collectively account for just over a quarter. This concentration pattern suggests room for both specialized challengers and scaled incumbents, but also implies that share gains are likely to accrue to players that can combine compliance assurance, performance differentiation, and efficient scale rather than to those competing primarily on price. The market is simultaneously consolidating where manufacturing and compliance require capital intensity, while fragmenting in design-led niches where visual differentiation and installation characteristics allow smaller brands to carve out positioning. New entrants tend to succeed when they bring a clear material or performance claim—such as enhanced water resistance, low-emission credentials, or sustainable sourcing—backed by credible documentation and a distribution pathway that reaches specifiers and retailers efficiently.
LVT Flooring Market
Forward Outlook: Three Trends Defining the Next 3–5 Years
Performance-Led Product Convergence
Over the next several years, laminate offerings are likely to converge further toward performance characteristics that were once the domain of rigid core and luxury vinyl products. Water resistance, spill defense, and improved locking systems will become baseline expectations in many residential and light commercial applications, reshaping comparison sets at point of sale. The commercial opportunity lies in packaging these capabilities with credible installation benefits and maintenance narratives that reduce total cost of ownership arguments against competing formats. The risk is a race to the middle if differentiation rests on similar claims without supporting documentation, installation consistency, or durable quality control. Winners will be those who pair performance upgrades with transparent testing, clear warranties, and installer education that converts technical claims into confident purchase decisions.
Sustainability as Specification Currency
Sustainability is transitioning from a marketing accent to a specification factor in both residential and commercial procurement. Sourcing transparency, emission performance, and material choices are increasingly weighed alongside aesthetics and price, particularly in projects with environmental certification targets or corporate sustainability commitments. The commercial opportunity is to build coherent product stories that link sourcing, resin choices, and emission compliance into a verifiable narrative supported by recognized standards and documentation. The uncertainty lies in the pace and harmonization of regulatory expectations across markets, which can shift the relative attractiveness of specific formulations or sourcing models. Participants that maintain flexible input strategies and robust compliance systems will be better positioned to adapt without sacrificing market access.
Regional Rebalancing and Supply Chain Localization
Geographic demand and supply strategies are likely to rebalance as trade dynamics, input cost volatility, and lead-time expectations evolve. Producers with localized manufacturing or diversified sourcing footprints can mitigate exposure to import-related cost shocks and respond more quickly to regional design preferences. The commercial opportunity is to align product portfolios with regional demand signatures—warm natural visuals in some markets, performance-led waterproof lines in others—while maintaining economies of scale in core processes. The risk is over-investment in capacity ahead of demand or under-investment in compliance and quality infrastructure that erodes brand trust. Strategic capacity decisions should be tied to verified regional demand signals and a realistic assessment of input cost trajectories, rather than to short-term promotional cycles.
Decision-Maker Playbook: Actions by Stakeholder Type
For Manufacturers and Brand Owners
- Prioritize performance claims that can be documented and defended, especially water resistance, emission compliance, and installation reliability, because these attributes increasingly determine specification outcomes and reduce returns.
- Diversify resin and substrate sourcing while maintaining formulation integrity, and build scenario plans around input cost volatility so that pricing and margin decisions do not depend on a single supply assumption.
- Align product development with regional demand signatures and installation realities, using design-led and performance-led line extensions where they address real specifier concerns rather than pursuing broad portfolios that dilute focus.
For Investors and Corporate Development Teams
- Evaluate exposure to regulatory and input-cost risk as part of valuation, focusing on producers with credible compliance systems, diversified supply chains, and documented performance advantages that support pricing power.
- Look for consolidation opportunities where scale improves margin stability and market access, but distinguish true operational value from purely financial engineering by examining quality systems, distribution strength, and brand credibility.
- Consider the pace of format convergence carefully, since laminate’s relative attractiveness will depend on its ability to hold performance and aesthetic ground against competing rigid core and vinyl solutions in key demand segments.
For Procurement, Distribution, and Channel Partners
- Assess supplier health and compliance documentation alongside unit pricing, since emission standards and performance consistency affect downstream risk, customer satisfaction, and rework costs over the lifecycle of a project.
- Match portfolio breadth to channel demand, emphasizing product lines with clear installation and maintenance benefits in segments where labor time, durability, and maintenance are decisive for repeat business.
- Track regional trend signals and trade activity to anticipate demand shifts, using design and performance cues to inform range planning and inventory commitments without overcommitting to short-lived style cycles.
Closing Perspective
The laminate flooring market is moving from a phase defined by price competition and basic decorative utility toward one where performance, compliance, and sustainability credentials determine competitive advantage. The mid-term growth path remains attractive, but value capture will favor organizations that convert technical improvements into credible customer benefits, manage input and regulatory risk with discipline, and align portfolios with real regional demand. For leaders seeking to shape strategy rather than react to it, detailed segmentation data, company-level benchmarking, and scenario analysis can sharpen resource allocation and timing decisions. A comprehensive research report offering granular segment splits, competitive profiles, and forward scenarios is available for teams that need to translate these market-level insights into actionable plans with greater precision.
For detailed analysis of this topic, please visit the official page: Laminate Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Leave In Meat Thermometers Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Leave In Meat Thermometers Market
Overview
The Leave In Meat Thermometers Market encompasses advanced temperature monitoring devices designed for continuous use during cooking processes. These thermometers are essential tools in professional kitchens and food production facilities, ensuring precise internal meat temperatures for safety and quality. Their core functionalities include real-time temperature tracking, durable sensor integration, and user-friendly interfaces, supporting industries that prioritize food safety and consistency.
The importance of the Leave In Meat Thermometers Market lies in its ability to enhance culinary precision and compliance with health standards. By enabling chefs and food manufacturers to monitor meat temperatures without frequent interruptions, these devices streamline operations. The market’s growth is driven by increasing demand for automation and accuracy in food preparation, making it a vital component of modern food service and processing industries.
Market Size and Growth
The current market value of the Leave In Meat Thermometers Market is estimated at around USD 250 million. Projected growth over the next 7 to 10 years suggests a compound annual growth rate (CAGR) of approximately 8%. This expansion is fueled by rising consumer awareness of food safety, technological advancements, and expanding adoption in commercial kitchens and industrial settings.
Key drivers include the increasing emphasis on health standards, the proliferation of smart kitchen appliances, and the growing trend toward automated cooking solutions. Additionally, rising demand for high-quality, consistent meat products across global markets supports sustained growth.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2070
Key Drivers
• Rising food safety regulations and standards
• Adoption of smart kitchen technologies
• Growing demand for automation in foodservice
• Increasing consumer focus on quality and safety
• Expansion of commercial and industrial food sectors
Restraints
• High costs of advanced sensor technology
• Technical challenges in sensor durability and calibration
• Regulatory hurdles in certain regions
• Operational complexity for small businesses
• Limited awareness in emerging markets
Segmentation
• By Type: Digital, Analog
• By Deployment: Commercial, Residential
• By Enterprise Size: Small, Medium, Large
• By End User: Restaurants, Food Processing, Catering, Household
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits robust demand driven by high food safety standards and technological integration in culinary practices. Europe’s focus on quality standards and regulatory compliance fuels adoption among premium food producers. Asia-Pacific presents significant growth potential due to expanding foodservice markets and rising disposable incomes. Latin America’s increasing industrialization supports market expansion, while the Middle East & Africa show emerging opportunities linked to modernization efforts in food safety practices.
Opportunities
• Expanding adoption in emerging markets
• Integration with IoT and smart kitchen systems
• Development of wireless and portable models
• Industry-specific customizations for food safety compliance
• Adoption in industrial food processing and catering
Key Companies
Johnson Controls, ThermoWorks, Taylor Precision Products, CDN, Maverick, Lavatools, Polder, Inkbird, Kizen, Edlund, iChef, Weber
Conclusion
The overall outlook for the Leave In Meat Thermometers Market remains positive, with long-term growth potential driven by technological innovations and increasing safety standards. As industries continue to prioritize quality and efficiency, the strategic importance of these devices will expand across commercial and industrial sectors. The market’s future growth depends on advancements in sensor technology and broader industry adoption, making it a critical component of modern food safety infrastructure.
Related Reports
Microwave Light Wave Ultrasonic Extractor Market , Size Share and Analysis | Report 2033
Dark Stem Soft Seal Gate Valve Market , Size Share and Analysis | Report 2033
Servo Hydraulic Cylinder Market , Size Share and Analysis | Report 2033
Marine Exhaust Manifolds Market , Size Share and Analysis | Report 2033
Desulphurization And Dust Removal Fan Market , Size Share and Analysis | Report 2033
Dc Tig Welding Machine Market , Size Share and Analysis | Report 2033
Three Phase Tig Welding Machine Market , Size Share and Analysis | Report 2033
Ecm Constant Torque Motor Market , Size Share and Analysis | Report 2033
Single Phase Tig Welding Machine Market , Size Share and Analysis | Report 2033
Cbl Cracking Furnace Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
How Connected Asset Management Can Transform Operational Efficiency
Business assets often do their most important work without attracting much attention. They can continue operating quietly while inefficient practices build beneath the surface. Because problems may not produce immediate alarms, visible damage, or obvious disruption, weaknesses can remain unnoticed for months or longer. Poor asset utilization and limited oversight can steadily raise expenses through reduced productivity, ineffective workforce allocation, increasing maintenance costs, and greater compliance exposure. When these problems finally become visible, the resulting operational and financial impact may already be significant.
For modern organizations, asset management is therefore not simply about preventing equipment breakdowns. It is also about reducing the long-term impact of disconnected systems, limited performance visibility, and decisions made without reliable operational information. This broader view also helps organizations connect day-to-day asset decisions with longer-term operational priorities, making it easier to recognize where resources are being consumed, where attention is required, and where better coordination can prevent avoidable costs from accumulating over time across different teams, sites, and operational processes consistently.
This is why asset management now goes well beyond keeping orderly asset records. A database filled with information does not, by itself, make operations more effective. Organizations need an asset management platform that creates a connected operational foundation, linking asset information with maintenance activities, governance needs, and performance intelligence. When these functions work together, teams can spot early warning signs, make better-informed decisions, and resolve developing problems before they become expensive failures. ToolKitX follows this connected model through a real time environment that unites maintenance, finance, and compliance stakeholders. A dependable shared information base can strengthen consistency, accountability, and operational visibility across the organization.
In ToolKitX, an asset is not simply a fixed record stored inside software. It becomes a digital history that evolves throughout its working life. That journey begins with installation and continues through daily use, inspections, servicing, repairs, upgrades, incidents, and eventual retirement. Each significant activity contributes to the asset's lifecycle record. Teams can therefore see the broader history of an asset instead of reconstructing its story from separate, disconnected sources.
Registration details, inspection findings, maintenance records, service histories, disposal documents, and other essential information can be held within one centralized environment. Teams can quickly determine an asset's location, review its current condition, and understand its operational significance without switching between multiple applications. Visibility can also move beyond the initial purchase cost by incorporating maintenance expenses, downtime risk, repeated failures, and performance patterns. Serial level tracking adds another layer of traceability and accuracy, helping organizations maintain reliable records for audits and accountability.
ToolKitX brings structured maintenance workflows, controlled documentation, and intelligent recommendations together to encourage a more proactive approach. Rather than waiting until equipment stops working, maintenance teams can monitor asset health and respond earlier. As operational information grows, recurring behaviors and performance patterns become easier to recognize. This helps organizations progress from traditional preventive maintenance toward a more predictive, data informed approach to asset management.
Connected asset management becomes especially important when interruptions can have serious operational consequences. Manufacturing, transportation, utilities, and energy organizations all depend on strong reliability, safety, and performance standards. A single equipment problem can affect production schedules, employee safety, and regulatory responsibilities simultaneously. ToolKitX connects asset information, maintenance planning, permit management, and change control within one operational framework. Instead of depending on isolated spreadsheets and separate applications, teams can work from a coordinated environment designed for information sharing and collaboration. Consistent information can support everyday decisions while also simplifying audits, investigations, and management reviews.
From an organization wide view, users can drill down into the details of individual assets. Records may include operating manuals, certifications, calibration documents, approvals, and other supporting files. Keeping these materials together helps management and operational personnel reach important performance information and audit ready documentation faster, without repeatedly collecting records from different places.
Preventive maintenance can be organized around calendar intervals, equipment usage, or condition based events. Tasks can be assigned to technicians, who can capture readings, add photographs, record observations, and complete work orders from the field. These activities can continue when an active internet connection is unavailable. As field data builds over time, organizations gain stronger evidence for assessing reliability, maintenance effectiveness, and changes in asset condition.
Fault information becomes more useful when repeated problems can be analyzed for patterns. ToolKitX turns recurring failures and equipment issues into reliability intelligence that maintenance teams can act upon. Teams can identify assets that repeatedly cause trouble, spot developing concerns sooner, and apply corrective actions before failures lead to costly downtime or serious equipment damage.
Maintenance also relies on having replacement parts available when they are needed. ToolKitX connects inventory information with maintenance requirements by centralizing stock quantities, storage locations, and replenishment needs. Barcode and QR code capabilities can improve inventory accuracy and reduce handling mistakes. Easier access to required components can reduce technician delays, unnecessary searching, and avoidable trips.
Organizational changes can follow defined approval workflows while preserving a complete time stamped history of decisions and activities. This produces a transparent, auditable record for each change, supporting governance and accountability. It can also reduce the manual follow up and continuous monitoring burden placed on teams.
ToolKitX uses an API first microservices architecture that can connect with ERP, MES, SCADA, and other enterprise technologies. Organizations can extend their existing technology environment rather than replacing established systems. By building on current investments, businesses can gain stronger operational visibility, intelligence, and control while continuing to use the technologies already in place.
The platform also supports needs beyond routine maintenance. Real time dashboards bring asset location, condition, and maintenance status together in one interface, helping teams understand current operational conditions more clearly. Asset availability can be supported through threshold monitoring, IoT generated information, and predictive indicators that help reveal potential issues before they become operational disruptions.
Compliance activities can benefit from secure lifecycle records, traceable change histories, and performance information that can be exported when required. Finance teams can gain clearer insight by connecting asset lifecycle costs and performance with ERP processes. This information can support depreciation planning, spare parts forecasting, and future capital investment decisions. Cloud deployment choices and guided implementation services can also help organizations begin realizing value sooner instead of enduring the extended implementation periods often associated with traditional enterprise software.
A mature asset management process can function as a repeatable operating cycle. Assets are registered and identified, maintenance needs are defined, failures are documented with supporting evidence, and dashboards deliver real time visibility into measures such as MTTR and MTBF. As more operational data accumulates, predictive insights can inform future planning and support continuous improvements in asset performance.
When maintenance, inventory, permits, change management, and performance analytics work within one connected environment, organizations can build a clearer picture of how their operations are performing. Frontline teams and leadership can work from the same dependable information, creating a stronger foundation for decisions, greater efficiency, clearer accountability, and more consistent business results.
Book a free demo @ https://toolkitx.com/campaign/asset-management/
Browse More
https://toolkitx.com/electrical-work-permit-template.html
https://toolkitx.com/excavation-work-permit-template.html
https://www.toolkitx.com/blogs.aspx
Solar Encapsulation Materials Market: Why 7.83% CAGR and EVA's Lead Change Strategy
By PW Consulting, 2026-09-21
Global Solar Encapsulation Materials Market: Strategic Trends & Commercial Opportunities
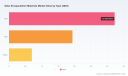
The solar encapsulation materials marketplace has matured from a commodity-driven segment into a strategically critical layer of photovoltaic module performance and longevity. During the 2020-2025 historical period, the sector demonstrated steady expansion, driven by accelerating photovoltaic deployment, material innovation, and shifting module architectures. Current valuations place the overall market at approximately 5.87 billion USD for 2025, with a projected trajectory toward 9.95 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.83 percent across the 2026-2032 forecast window, signaling sustained structural demand rather than cyclical fluctuations.
Behind these headline figures lies a more nuanced transformation. Encapsulation has evolved from a passive protective function to an active enabler of module efficiency, reliability, and warranty economics. This shift is reshaping competitive dynamics, supply network configurations, and investment priorities. Decision-makers evaluating exposure to solar value chains must look beyond volume growth and understand the material, technological, and geographic realignments that are redefining commercial viability in this segment.
Market Snapshot and Structural Realities
The encapsulation sector operates at the intersection of polymer engineering, module architecture, and long-term performance guarantees. Crystalline silicon photovoltaic systems continue to anchor the majority of demand, reflecting their dominant position across utility-scale, commercial, and residential installations. Within the material mix, ethylene vinyl acetate (EVA) retains a leading position, accounting for roughly 55 percent of the market in 2025, while polyolefin elastomer (POE) represents the fastest-growing category, driven by compatibility with advanced cell architectures and improved moisture and potential-induced degradation resistance.
Regional demand is distributed across major solar manufacturing and deployment hubs, with North America holding a notable share, Asia Pacific maintaining strong volume leadership, and Europe sustaining steady consumption supported by local manufacturing incentives and project pipeline development. The market remains moderately concentrated, with the top three suppliers capturing approximately 62.5 percent of revenue and the top five reaching around 75.0 percent. This structure indicates that scale, formulation expertise, and module-maker relationships confer meaningful advantages, even as demand fragmentation across geographies and module types creates room for specialized entrants.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market faces structural frictions that will determine which participants capture value in the next cycle. Three challenges stand out as particularly decisive.
LED Encapsulation Market
Material specification pressure and warranty economics. Twenty-five-year module warranties have become standard expectations rather than premium differentiators. Encapsulants must now demonstrate high gel content, robust moisture barriers, and sustained potential-induced degradation resistance under diverse operating conditions. Failure to meet formulation thresholds increases financial exposure for module makers and complicates downstream bankability. The requirement for gel content above 50-70 percent for POE and EPE formulations, and above 75-80 percent for EVA, illustrates how material performance has become a gatekeeper for commercial acceptance.
Architecture transitions reshaping demand composition. The rise of TOPCon, heterojunction, bifacial, and tandem-oriented concepts is changing encapsulant requirements. Traditional EVA formulations optimized for earlier-generation cell designs require reformulation or replacement when paired with high-efficiency back-contact structures, bifacial light management, or emerging perovskite combinations. Suppliers that can deliver co-extruded solutions tailored to these architectures are gaining strategic relevance, while general-purpose material providers face margin and volume pressure.
Supply network localization and geopolitical realignment. End-users and manufacturers increasingly prioritize supply resilience over lowest-cost sourcing. The expansion of U.S. production capacity for high-performance encapsulants reflects a broader effort to reduce import dependencies and align material availability with domestic module assembly and deployment timelines. At the same time, emerging manufacturing centers in South and Southeast Asia are driving regional demand for cost-competitive yet specification-grade encapsulants. These parallel forces are bifurcating procurement strategies between premium localized supply and volume-driven regional sourcing.
Strategic Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
Encapsulation technology is moving rapidly from commodity film production to engineered material systems that support incremental module efficiency gains and durability requirements. Co-extruded structures are gaining prominence because they enable layered functionality, such as improved UV stabilization, enhanced moisture resistance, or tailored optical properties, without requiring separate processing steps. For bifacial modules, premium anti-reflective and optimized encapsulant films can deliver absolute efficiency improvements in the range of 0.5-1.0 percent, which translates into meaningful energy yield differences over a project lifecycle. This performance link justifies price premiums in the order of 15-25 percent for specification-grade films and reinforces the commercial logic of advanced material investment.
Recent product activity confirms the pace of innovation. Next-generation co-extruded POE and EPE formulations optimized for TOPCon and bifacial modules have advanced toward commercialization, with some offerings demonstrating enhanced potential-induced degradation resistance beyond 300 hours. In parallel, new encapsulant film generations incorporating UV down-conversion technology and ultrafast-cure EVA variants have entered the market alongside capacity expansions designed to support higher-volume deployment. These developments indicate that material innovation is no longer confined to laboratory feasibility; it is being scaled into commercial supply pipelines linked to module-maker qualification cycles.
Policy, Regulation, and Warranty-Driven Standards
Regulatory and financing environments are tightening the performance bar for encapsulants indirectly but powerfully. Long-duration warranties, bankability requirements, and durability expectations are translating into practical formulation thresholds. Advanced encapsulants for bifacial and next-generation modules must meet stringent moisture barrier and potential-induced degradation resistance requirements to support extended warranty commitments. This has elevated the importance of certificate-backed validation, standardized testing, and consistent batch quality.
At the same time, industrial policy and trade dynamics are reshaping where production is located and how supply chains are structured. Domestic capacity expansion in the United States is reducing exposure to cross-border disruptions for high-performance encapsulants used in advanced module types. This localization trend is not merely about cost; it is about securing predictable supply for products where qualification cycles are long and switching costs are high. In parallel, export-oriented manufacturers in Asia are aligning production with regional demand centers and international qualification requirements, creating a more geographically diversified but increasingly specification-sensitive competitive landscape.
Demand-Side Evolution and Module Architecture Shift
Demand growth is being shaped by both volume and value. Solar installation continues to expand across utility, distributed, and commercial segments, but the more strategically important shift is the changing composition of module technology adoption. Crystalline silicon remains the backbone of the market, yet the rising share of high-efficiency variants is altering encapsulant selection criteria. Bifacial modules, TOPCon cells, and back-contact configurations increasingly require materials that preserve optical performance while protecting cell interfaces over decades of operation.
For module manufacturers, this means encapsulant choice is becoming a design decision with direct implications for energy yield, degradation profile, and total cost of ownership. For buyers of finished modules, encapsulant quality is increasingly visible through warranty terms, degradation guarantees, and long-term performance expectations. As a result, encapsulant material is transitioning from a hidden component to a value-differentiating element in product positioning, especially in competitive segments where efficiency and reliability claims are scrutinized during procurement and financing.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being driven by raw material economics, processing complexity, and the premium attached to specification-grade products. Polyolefin-based materials are growing faster than established EVA streams, supported by their compatibility with advanced module designs and improved durability profiles. However, higher-performance films often involve more complex extrusion and formulation requirements, which affect conversion economics and supplier capability thresholds.
The cost dynamic is not simply about raw material price movement; it is about the widening spread between standard and premium encapsulants. Suppliers capable of delivering consistent high gel content, UV stabilization, and co-extrusion performance can capture meaningful margins through specification differentiation, while undifferentiated commodity production faces intensifying competition and pressure from regional capacity additions. This bifurcation is encouraging strategic positioning around either volume reliability or advanced material differentiation, with limited middle ground for players unable to meet either cost or specification targets consistently.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines large multinational polymer and materials companies with specialized regional manufacturers that have built strong relationships with module makers and emerging production hubs. Several patterns define current strategic positioning.
Hangzhou First PV Material Co., Ltd. has established a strong position as a large-scale producer of EVA and POE encapsulation films for crystalline silicon modules, with a product focus that extends to TOPCon, heterojunction, bifacial, and high-efficiency applications. Its scale and breadth allow it to address mainstream and advanced architectures simultaneously, making it a relevant reference point for suppliers seeking to balance volume and specification growth.
Jiangsu Sveck New Material Co., Ltd. has built a profile around EVA, POE, and high-performance co-extruded encapsulant films, with particular emphasis on serving module manufacturers in emerging markets such as Vietnam and India. This geographic orientation reflects an understanding that demand growth is not limited to established hubs and that regional supply proximity can reduce logistics risk and improve responsiveness.
Shanghai HIUV New Materials Co., Ltd. has focused on high-performance polymer materials and UV-resistant encapsulation technologies, emphasizing long-term stabilization and durability. This durability-centered positioning aligns with warranty-driven procurement and suggests a strategy oriented toward performance assurance rather than lowest-cost volume.
Changzhou Betterial Film Technologies Co., Ltd. has moved toward advanced polymer film solutions for photovoltaic encapsulation, including tandem perovskite and back-contact module technologies. This forward-looking product direction illustrates how some suppliers are positioning for next-generation cell concepts before they reach mass deployment, aiming to secure early qualification advantages.
Zhejiang Sinopont Technology Co., Ltd. is expanding its development of high-barrier co-extruded encapsulation films and TOPCon-compatible POE materials, reinforcing the broader industry emphasis on formulation precision for advanced cell architectures. Similarly, Hanwha Solutions, Mitsui Chemicals, Kuraray, SKC, Bridgestone, and Coveme represent established material capabilities and regional strengths, while U.S. and European names such as 3M, STR Holdings, Dow, DuPont, and Eastman contribute advanced polymer chemistry and specialty encapsulant expertise.
RenewSys India and Alishan Green Energy illustrate the growing role of Indian manufacturers in EVA, POE, EPE, and TPO supply. Alishan's recent moves are particularly notable: the company launched a new generation of encapsulant films including low-acid EVA, EPE-NT, and EPE-DC with UV down-conversion technology, expanded capacity to approximately 6.6 GW, and continued toward a 10 GW target by the end of 2026. This scale-up, combined with product differentiation, signals that emerging-market suppliers are not only competing on cost but are also building specification-grade portfolios for advanced applications.
Evolution of Market Structure
The market is simultaneously consolidating at the top and fragmenting in the middle. Concentration among leading suppliers reflects the advantages of scale, formulation depth, qualification track records, and long-standing relationships with module manufacturers. At the same time, technological differentiation is creating niches for specialized players focusing on co-extrusion, UV management, ultrafast curing, or next-generation cell compatibility.
Chip Encapsulation Resin Market
This dual dynamic suggests that the competitive frontier will not be defined purely by price. Instead, it will be shaped by the ability to meet specific module requirements, support qualification timelines, maintain batch consistency, and provide supply continuity in a geopolitically sensitive environment. New entrants with differentiated technology can gain traction in targeted segments, but broad-based competition is intensifying where specifications are relatively standardized and regional capacity is expanding. As manufacturing footprints shift and advanced module adoption accelerates, the landscape is likely to reward suppliers that can combine technical precision with dependable commercial execution.
Forward Outlook: Trends for the Next 3-5 Years
Trend 1: Advanced, Co-Extruded, and Architecture-Specific Encapsulants Will Become the New Baseline for Premium Modules
Over the next several years, co-extruded and architecture-tailored encapsulants will move from differentiated offerings to expected components in high-efficiency and bifacial modules. TOPCon and bifacial adoption will continue to expand, and suppliers that can deliver formulations optimized for moisture resistance, UV behavior, and potential-induced degradation control will be better positioned to secure qualification and repeat procurement. The commercial implication is clear: module manufacturers will increasingly weigh encapsulant performance as part of product design rather than treating it as a generic input.
For suppliers, this trend favors investment in formulation engineering, testing infrastructure, and application-specific product lines. For buyers, it means selection criteria will shift toward proven compatibility with target cell architectures and verifiable long-term stability. The opportunity lies in aligning encapsulant development with module roadmaps early, reducing rework and qualification delays.
Trend 2: Regional Supply Localization Will Deepen Where Premium Modules Are Made and Deployed
Localization of high-performance encapsulant production will continue in regions where advanced module manufacturing and project deployment are concentrated. In the United States, facility expansions for advanced encapsulants are strengthening domestic supply for bifacial, TOPCon, and next-generation high-efficiency modules, mitigating import dependencies from Asia. This pattern is likely to encourage parallel investments in other regions seeking to secure material availability for domestic manufacturing and export-quality production.
PW Consulting
The strategic implication is that supply chain design will become more regionalized and more sensitive to qualification continuity. Suppliers that can build localized capacity or reliable regional partnerships will increase their relevance to customers who prioritize resilience and predictable delivery. At the same time, cost-competitive regional producers in Asia will continue to serve volume demand, creating a market structure where premium localization and efficient regional supply coexist.
Trend 3: Durability-Weighted Procurement Will Redefine Value Comparison Across Materials
Procurement decisions will increasingly incorporate lifetime performance considerations rather than initial material cost alone. Warranty expectations, degradation profiles, and bankability requirements are pushing buyers to evaluate encapsulants through the lens of long-term reliability. Gel content thresholds, moisture barrier performance, and potential-induced degradation resistance are becoming practical decision metrics because they directly affect warranty exposure and asset longevity.
This shift creates opportunity for suppliers that can document durability with consistent quality and credible validation. It also introduces risk for manufacturers that compete primarily on price without robust formulation control. Over time, the market will likely see more explicit differentiation between standard and premium encapsulant tiers, with premiums justified by efficiency, durability, and qualification readiness rather than brand alone.
Risks and Uncertainties
While the outlook is favorable, several uncertainties could alter the pace or direction of value capture. Raw material cost volatility and polymer feedstock dynamics can affect margins, especially for suppliers with limited pricing power. Overcapacity in commodity-grade production could compress returns if demand growth does not absorb new capacity in certain regions. Qualification cycles are lengthy and can delay the commercial payoff of advanced formulations, creating execution risk for companies investing ahead of module adoption curves. Finally, technology transitions in next-generation cells, including tandem and back-contact concepts, remain uneven in timing and scale, which could shift encapsulant demand patterns faster than suppliers anticipate.
Actionable Guidance for Decision-Makers
For Module Manufacturers
Treat encapsulant selection as a product architecture decision rather than a procurement commodity exercise. Align material qualification with your cell technology roadmap, prioritizing suppliers that can demonstrate compatibility with bifacial, TOPCon, and other advanced designs while maintaining batch consistency. Build early-stage testing and qualification into development plans to reduce launch risk and avoid late-stage redesigns. Where warranty and bankability requirements are stringent, prioritize documented durability metrics such as gel content, moisture barrier performance, and potential-induced degradation resistance alongside cost.
For Investors and Strategic Buyers
Evaluate exposure to encapsulant suppliers based on technology differentiation, regional supply positioning, and qualification relationships rather than volume alone. Companies with credible co-extrusion capabilities, UV and durability-focused formulations, and the ability to scale advanced materials for high-efficiency modules are better positioned to capture premium segment growth. At the same time, assess whether capacity expansions are aligned with actual regional demand and whether pricing power is sustainable given regional supply additions. Portfolio value will increasingly depend on a supplier's ability to serve specification-grade demand without being dragged into undifferentiated commodity competition.
For Procurement and Supply Chain Leaders
Diversify sourcing strategies to balance premium localized supply with regional volume options, especially where module assembly, deployment, and warranty exposure create supply continuity requirements. Use qualification lead times to build relationships with suppliers that can support long-term consistency rather than short-term spot pricing. Incorporate performance-based criteria into purchasing decisions, including durability validation and compatibility with target module architectures. This approach reduces switching risk and strengthens resilience against supply disruptions, qualification delays, and regional production shifts.
The strategic significance of encapsulation materials will continue to rise as module architectures become more advanced and warranty expectations more demanding. Market participants that understand the interplay between formulation innovation, regional supply strategy, and procurement-driven durability requirements will be best positioned to manage risk and capture value. For professionals seeking deeper segmentation detail, competitive benchmarking, and tailored scenario analysis across regions and applications, the full PW Consulting research report provides expanded data sets and customized strategic guidance to support immediate planning decisions.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Quality Sensor Market Insights: How a 7.9% CAGR Reshapes Competition Through 2032
By PW Consulting, 2026-09-21
Navigating the Air Quality Sensor Market: Strategic Trends and Commercial Opportunities
Market Evolution and Structural Challenges
The air quality sensor market has transitioned from a niche environmental monitoring segment to a foundational infrastructure component across industrial, commercial, and consumer domains. By 2025, global market revenue reached approximately USD 5.95 billion, reflecting a steady expansion trajectory from the USD 3.85 billion recorded in 2020. The forward-looking horizon paints a clear growth arc: the market is projected to expand to USD 6.56 billion in 2026, USD 7.53 billion in 2028, and cross the USD 10 billion threshold by 2032. This progression translates to a compound annual growth rate of 7.9 percent across the 2026 to 2032 period, indicating that demand momentum is not cyclical but structurally embedded in how buildings, cities, and industrial facilities are managed.
Beneath the headline figures, the industry operates in a moderately concentrated environment. The top three players capture roughly 25.5 percent of total revenue, while the top five account for 31.2 percent. This concentration level suggests that while established sensor manufacturers hold meaningful scale advantages in calibration, supply chain resilience, and regulatory certification, the market remains accessible enough for specialized innovators and regional integrators to compete on application-specific performance, integration simplicity, or cost efficiency.
The industry currently sits at a structural inflection point, shaped by two persistent challenges. The first is the durability and lifecycle economics of low-cost sensing platforms. Short operating lifespans, often ranging from two months to two years for entry-tier devices, create recurring replacement cycles, calibration overhead, and total cost of ownership variability that complicate long-term deployment models. For commercial building operators and municipal monitoring networks, this introduces maintenance uncertainty and data continuity risks that traditional procurement models were not designed to absorb.
The second challenge is the tightening of regulatory and trade conditions around critical hardware inputs. Export controls on rare earth materials and permanent magnets, such as those introduced under China’s Ministry of Commerce Announcement No. 61 of 2025, have added new layers of supply chain compliance and foreign approval requirements starting in late 2025. For sensor manufacturers and system integrators, this translates into sourcing uncertainty, potential lead-time volatility, and the need to re-evaluate supplier diversification strategies before procurement bottlenecks affect production schedules.
A third pressure point lies in the widening gap between laboratory-grade accuracy and field-deployed real-world performance. Independent evaluation programs such as AQ-SPEC have continued to release field evaluation reports covering particulate and gas monitoring devices, underscoring the market’s growing expectation that sensor performance claims must be validated under operational conditions rather than controlled environments alone. As monitoring networks scale and data feeds increasingly inform compliance decisions, facility management, and public information systems, the tolerance for unexplained drift, cross-sensitivity, or inconsistent environmental compensation is shrinking.
Core Drivers Shaping Market Trajectory
Technology innovation remains the most direct growth catalyst, but the center of competitive advantage has shifted. Rather than isolated sensor components, the value is increasingly created through integrated environmental modules that combine particulate, gas, and contextual readings in a single form factor. Recent product activity illustrates this direction: Sensirion’s environmental sensor modules have been incorporated into indoor air quality monitors designed to deliver simultaneous PM, gas, and environmental measurements, reinforcing the industry’s movement toward multi-parameter visibility rather than single-pollutant point sensing. Similar integration logic is visible across building-grade platforms, where sensor capability is being packaged together with interfaces and software connectivity that reduce deployment friction.
A parallel innovation thread is the push toward safer and more sustainable sensor chemistry. The introduction of the first galvanic lead-free oxygen sensor reflects a broader industry re-evaluation of consumable sensor materials, particularly where maintenance frequency, environmental handling, and long-term deployment safety intersect. In industrial and environmental monitoring contexts, such developments matter because they influence not only device performance but also operational procedures, spare-part logistics, and regulatory acceptability over the equipment lifecycle.
PW Consulting
Policy and regulatory evolution is compounding these technical shifts. Building performance standards, occupational health expectations, and municipal air quality transparency initiatives are expanding the footprint of monitoring requirements. In parallel, independent evaluation frameworks are becoming more influential in procurement decisions, pushing manufacturers and system integrators to treat validated field performance as a commercial prerequisite rather than a technical footnote. The market is therefore moving toward an environment where accuracy claims, calibration support, and documented real-world behavior directly affect vendor credibility and purchasing decisions.
Demand-side behavior is also changing the shape of the market. Facility operators are increasingly treating air quality data as an operational input rather than a compliance checkbox. In commercial buildings, data centers, and managed indoor environments, air quality visibility is being linked to equipment protection, comfort management, and operational efficiency. In outdoor contexts, measurement networks are gaining relevance for urban planning, environmental monitoring programs, and situational awareness applications. The effect is a broader application base in which sensors are selected not only for detection capability but also for ease of integration, maintenance burden, and compatibility with existing building or asset management ecosystems.
Supply chain and cost structure dynamics complete the picture. Sensor producers and integrators are having to balance miniaturization, material availability, and manufacturing scale against the expectation of competitive pricing. Where low-cost sensors expand accessibility, they also intensify lifecycle management concerns and can shift the real economic question from unit price to total cost over deployment. This is especially relevant for organizations planning network-scale rollouts, where replacement frequency, calibration support, and field service requirements can outweigh initial hardware economics.
Competitive Positioning and Market Structure
The competitive landscape is defined by a mix of diversified industrial suppliers, specialized sensing experts, and platform-oriented manufacturers. Each group is pursuing a distinct route to value, and the differences in their product emphasis reveal how the market is segmenting.
Automotive Cabin Air Quality Sensor Market
Honeywell International Inc. anchors its position in industrial-grade air quality sensing, with offerings such as MIDAS and Sensepoint aimed at gas and particulate monitoring in commercial and industrial settings. This focus gives the company a strong fit with environments where robustness, process integration, and compliance-oriented performance are primary concerns. The strategic advantage here is not just detection capability but the ability to serve demanding installation contexts where downtime, environmental stress, and integration complexity raise the bar for sensor reliability.
Sensirion AG has built visibility around compact environmental sensor modules that combine multiple measurement functions in a single package. The uptake of these modules in indoor air quality monitoring devices reflects a strategy centered on enabling downstream manufacturers and system builders with ready-to-integrate sensing building blocks. In this model, value is created by reducing integration effort, broadening measurement coverage, and supporting a wide range of device form factors rather than competing primarily as a finished monitoring equipment brand.
Bosch Sensortec GmbH emphasizes MEMS-based multi-sensor solutions and compact particulate sensing for indoor air quality measurement. The strategic logic is similar in part to Sensirion’s, but with a distinct emphasis on highly miniaturized, embedded sensing suitable for products that must balance performance with size, power, and cost constraints. This positions the company well in consumer-adjacent and commercial building applications where space and integration simplicity matter.
Alphasense Ltd and Figaro Engineering Inc. represent the more specialized sensor chemistry and detection side of the market. Alphasense’s focus on electrochemical and optical gas sensors for industrial and environmental monitoring, including recent developments in lead-free oxygen sensing, points to a strategy built on measurement specificity and application reliability. Figaro’s TGS series electrochemical gas sensors reinforce a similar niche, where toxic gas and air quality monitoring demand stable, recognizable detection characteristics and predictable maintenance behavior. These players compete on measurement trust and application fit, often in settings where misinterpretation of sensor output carries operational or safety consequences.
Platform and systems-oriented players such as Siemens AG, Teledyne Technologies, TSI Incorporated, 3M Company, Aeroqual Ltd, and AKCP illustrate the market’s diversification across building management, environmental monitoring, aerosol and particle measurement, and specialized deployment scenarios. Siemens’ recent redesign of air quality sensors with touch interfaces and mobile app integration signals a move toward more operator-friendly building and facility monitoring experiences, where usability and connectivity are part of the commercial proposition. Teledyne’s gas and particulate sensor solutions and TSI’s aerosol and particle counter expertise reflect long-standing strengths in measurement integrity for environmental and industrial assessment workflows. 3M’s integration of particulate and gas detection into monitoring systems and Aeroqual’s portable and fixed sensor network offerings show how sensing capability is increasingly being sold as part of broader monitoring architectures. AKCP’s all-in-one sensor for data center dust and gas monitoring highlights a growing application-specific demand: protecting sensitive equipment environments through targeted air quality visibility.
The market structure appears to be evolving along two tracks at once. On one side, consolidation pressure exists among players that can combine sensor performance, calibration support, certification, and integration ecosystems at scale. On the other, differentiation is intensifying around application-specific needs, form-factor constraints, connectivity expectations, and lifecycle economics. New entrants and specialist suppliers are not necessarily trying to outperform incumbents across the board; many are competing by solving a particular deployment pain point more cleanly, whether that is miniaturization, multi-parameter integration, field validation, or maintenance-friendly consumable design.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, one of the clearest trends is the normalization of integrated multi-parameter sensing as a baseline expectation rather than a premium option. As indoor and outdoor monitoring deployments mature, buyers will increasingly compare solutions based on how well they combine particulate, gas, and environmental readings in a maintainable package, and how easily those outputs feed into building, facility, or municipal data workflows. The commercial opportunity here sits not only in sensor hardware but in the surrounding integration logic: calibration support, data compatibility, and ease of operational adoption.
Worldwide Air Quality Sensor ICs Market
A second trend is the growing operational importance of validated field performance. Independent field evaluation activity is reinforcing a market expectation that measurement claims must hold up in deployed conditions. For suppliers, this opens a differentiation path centered on transparent performance documentation, robust environmental compensation, and sustained calibration reliability. For buyers, it increases the value of evidence-based selection and post-deployment performance monitoring. Organizations that treat validation as part of the procurement process are likely to reduce downstream data quality risk and maintenance surprises.
A third trend is the continued specialization of monitoring solutions by environment and use case. Data centers, commercial buildings, industrial sites, and outdoor networks each place different demands on accuracy, response time, maintenance cadence, and integration style. As a result, market growth will not be evenly distributed across generic sensor categories. Instead, it will concentrate where sensor packaging, software experience, and service models align closely with the operating realities of a specific environment. The commercial opportunity for manufacturers and integrators is to move from broadly advertised detection capability to clearly articulated deployment value in a defined setting.
These trends carry associated risks. Supply chain constraints around critical materials and magnets could affect cost predictability and product availability if not managed through sourcing diversification and design flexibility. Low-cost sensor durability remains a structural limitation in some segments, meaning that scaling deployment without accounting for replacement and maintenance cycles can undermine long-term economics. In addition, the widening use of sensor data in operational and public-facing contexts raises the stakes for data quality, making performance inconsistency more costly than in earlier phases of market development.
Strategic Actions for Decision-Makers
For sensor manufacturers and device builders, the priority is to align product roadmaps with the market’s shift toward integration, validation, and lifecycle manageability. This means treating multi-parameter capability, field reliability, and usability not as separate features but as interconnected commercial requirements. Differentiation is increasingly likely to come from how well a solution reduces deployment friction, supports sustained accuracy, and fits into the operational environment where it will be maintained, not just installed. Supply chain resilience should also be designed into product strategy early, particularly where material constraints or export-related approvals may influence availability and lead times.
For investors, the opportunity is less about broad market growth alone and more about identifying which business models are best positioned to capture value in a maturing landscape. Companies that can combine credible field performance, application-specific fit, and scalable integration support are better placed to defend margins than those competing primarily on unit price in commoditizing segments. The lifecycle economics of low-cost sensors, the influence of independent evaluation programs, and the impact of material trade controls all point to a market where durability, documentation, and supply chain planning can be as important as sensing performance itself.
For procurement teams and end-user organizations, the strategic task is to move beyond surface-level specification comparisons and evaluate total deployment risk. This includes weighing calibration support, replacement intervals, integration complexity, and the availability of independent field evidence alongside initial hardware cost. In network-scale or mission-critical deployments, the most cost-effective solution on paper may not be the most economical over time if it introduces higher maintenance burden or data reliability risk. Procurement criteria that account for field performance history and long-term serviceability are more likely to produce stable operational outcomes.
For organizations seeking to shape strategy with greater precision, detailed segmentation data, application-level demand patterns, regional deployment dynamics, and company-specific positioning can materially improve planning quality. A deeper research perspective can help translate these market-level trends into segment-specific priorities, whether the focus is on indoor versus outdoor monitoring, industrial-grade versus compact sensing, or the integration requirements of a particular deployment environment. The commercial decisions that matter most are often the ones that require finer granularity than headline market size and growth rate can provide.
For detailed analysis of this topic, please visit the official page: Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laser Liquid Particle Counter Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Laser Liquid Particle Counter Market Overview
The Laser Liquid Particle Counter Market is a specialized segment within the broader particle measurement and contamination control industry. It involves the use of laser-based technology to detect, count, and analyze particles suspended in liquids, primarily for quality assurance and process validation. These instruments are essential in sectors such as pharmaceuticals, biotechnology, food & beverage, and electronics, where liquid purity directly impacts product safety and performance. By providing precise particle size and concentration data, the market supports industries that demand stringent cleanliness standards and contamination monitoring.
The core functionalities of laser liquid particle counters include real-time particle detection, size distribution analysis, and data logging, facilitating compliance with regulatory standards. The Laser Liquid Particle Counter Market plays a vital role in modern manufacturing and laboratory environments by ensuring liquid purity, optimizing filtration systems, and reducing contamination risks. Their ability to deliver accurate, rapid results makes them indispensable for quality control and process optimization across various high-precision industries.
Market Size and Growth
The current market value of the Laser Liquid Particle Counter Market is estimated at around USD 250 million. Over the next decade, the market is projected to reach approximately USD 450 million, reflecting a compound annual growth rate (CAGR) of about 7%. Growth is driven by increasing regulatory requirements for contamination control, technological advancements, and rising adoption in emerging markets. The expanding need for high-precision liquid analysis in pharmaceutical and biotech sectors significantly propels market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1965
Key Drivers
• Stringent industry regulations and standards
• Growing demand for contamination monitoring in pharmaceuticals
• Technological innovations enhancing detection accuracy
• Rising adoption in food safety and beverage industries
• Increased focus on quality assurance in electronics manufacturing
Restraints
• High initial investment costs for advanced systems
• Operational complexity requiring specialized training
• Regulatory hurdles across different regions
• Limited awareness in some emerging markets
• Maintenance and calibration expenses
Segmentation
• By Type
- Portable
- Benchtop
- Inline
• By Deployment
- Laboratory
- In-line/Process
• By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
• By End User
- Pharmaceuticals & Biotechnology
- Food & Beverage
- Electronics & Semiconductors
- Water Treatment
- Others
• By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Insights
North America leads the Laser Liquid Particle Counter Market due to stringent regulatory frameworks and high technological adoption in pharmaceutical and biotech industries. The region's focus on quality control and contamination prevention sustains robust demand.
Europe exhibits steady growth, driven by strict compliance standards and advanced manufacturing sectors, notably in Germany and France. Investment in innovation and regulatory alignment further support regional expansion.
Asia-Pacific presents significant growth opportunities, fueled by rapid industrialization, increasing pharmaceutical manufacturing, and rising awareness of contamination control. Emerging markets like China and India are adopting laser liquid particle counting technology at an accelerating pace.
Latin America shows moderate growth, largely driven by expanding pharmaceutical and food processing industries. Regulatory reforms and increasing infrastructure investment are key factors.
Middle East & Africa are in early stages of market development, with growth potential tied to industrial expansion and rising healthcare investments. Adoption remains limited but is expected to increase with regional economic development.
Opportunities
• Expansion in emerging markets, especially in Asia-Pacific and Latin America
• Integration of IoT and automation in particle counting systems
• Development of portable and user-friendly devices for field use
• Adoption of laser liquid particle counters in water treatment facilities
• Innovation in real-time data analytics and reporting tools
Key Companies
TSI Incorporated
Particle Measuring Systems
Beckman Coulter
Hach Company
Palintest Ltd.
Hindustan Group of Institutions
Grimm Aerosol Technik
Particle Technology Systems
Measuring Instruments Inc.
Krones AG
Shimadzu Corporation
Merck KGaA
Conclusion
The Laser Liquid Particle Counter Market exhibits strong long-term growth potential driven by increasing regulatory demands and technological advancements. Its strategic importance in ensuring liquid purity and process control makes it a vital component across multiple high-precision industries. As industries continue to prioritize quality and contamination prevention, the market is poised for sustained expansion and innovation.
Related Reports
Pet Imaging X Ray Flat Panel Detector Market , Size Share and Analysis | Report 2033
Flameproof Electrical Equipment Market , Size Share and Analysis | Report 2033
5g Law Enforcement Recorders Market , Size Share and Analysis | Report 2033
Radiofrequency Electromagnetic Radiation Detectors Market , Size Share and Analysis | Report 2033
Industrial Frequency Electromagnetic Radiation Detectors Market , Size Share and Analysis | Report 2033
Australian Style Roller Doors Market , Size Share and Analysis | Report 2033
Electric Roll Up Doors Market , Size Share and Analysis | Report 2033
Catering Cashier All In One Machines Market , Size Share and Analysis | Report 2033
Single Screen Cash Registers Market , Size Share and Analysis | Report 2033
Large Format Scanners Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Thioctic Acid (ALA) Market at $985M: 5.92% CAGR Trajectory & 3 Strategic Shifts Reshaping the Industry
By PW Consulting, 2026-09-21
Navigating the Thioctic Acid (Alpha Lipoic Acid) Market: Strategic Trends and Commercial Opportunities
The Thioctic Acid (Alpha Lipoic Acid) market has matured beyond its origins as a niche chemical intermediate into a strategic ingredient spanning pharmaceuticals, nutraceuticals, and personal care. Global revenue climbed from $650.0 million in 2020 to an estimated $985.0 million in 2025, with a projected compound annual growth rate of 5.92 percent through 2032. This trajectory reflects broader shifts in preventive health, oxidative-stress management, and the convergence of clinical-grade efficacy with consumer-facing formulations. Yet the expansion path is uneven. Structural cost pressures, regulatory scrutiny, and geographic supply concentration are reshaping how manufacturers, investors, and procurement teams approach the category. Understanding where value accrues—and where it erodes—requires a clear read on technological differentiation, policy signals, and the evolving purchasing behavior of end markets.
Market Landscape and Structural Challenges
The baseline trajectory of the ALA market is anchored by steady volume growth and expanding application breadth. Revenue expanded consistently from 2020 through 2025, with the most pronounced inflection occurring between 2023 and 2024 as formulation adoption accelerated across multiple end-use channels. Forward projections indicate sustained growth through the early 2030s, positioning the category as a durable component of the broader bioactives ecosystem. This expansion is not uniform across applications or regions. Dietary supplements and cosmetics together represent the dominant commercial weight, while pharmaceutical-grade formulations maintain a meaningful but slower-moving share tied to clinical validation cycles and reimbursement pathways. Asia Pacific and North America anchor demand volume, with Europe contributing steady consumption supported by established supplement infrastructure. By molecular form, the market is increasingly bifurcated between racemic blends and enantiomer-pure variants, a distinction that increasingly influences pricing, formulation flexibility, and downstream marketing claims.
Concentration and Fragmentation Dynamics
Market structure remains moderately consolidated, with the largest players commanding a combined share in the mid-thirties and the top five entities approaching nearly half of total commercial activity. This concentration coexists with a long tail of regional suppliers, contract formulators, and research-grade distributors. The resulting landscape presents both stability and vulnerability. Consolidation has improved quality consistency and supply visibility for large-scale buyers, yet it also concentrates execution risk around a limited number of manufacturing nodes. Meanwhile, smaller regional players compete on agility, local regulatory navigation, and specialized enantiomer or derivative offerings, creating a segmented environment where competitive advantage depends on more than scale alone.
PW Consulting
Key Challenges at the Current Inflection Point
Several structural frictions are redefining how stakeholders position themselves in the ALA market. First, raw material volatility has become a persistent margin test. Octanoic acid prices swung between 15 and 25 percent during 2024 and 2025 as El Niño-related disruptions affected palm kernel and coconut oil availability. Because octanoic acid is integral to ALA conversion pathways, this input movement directly inflated production costs and compressed the economics of supplement formulators and private-label buyers who operate on thin spreads. Second, regulatory uncertainty is reshaping demand visibility, particularly in Europe, where ongoing scrutiny under Article 8 proceedings may reduce the addressable supplement market meaningfully. The prospect of tighter claim structures or usage limitations has prompted formulation teams to reevaluate ingredient positioning, shelf-life planning, and geographic allocation of inventory. Third, geographic concentration in sourcing remains a latent operational risk. With a concentrated share of global capacity centered in China, supply chain shocks such as shipping route disruptions highlighted the fragility of relying on a narrow set of origin points. Buyers with lean inventories and just-in-time procurement models faced disproportionate exposure, reinforcing the need for diversified origin strategies and buffer planning.
Core Demand Drivers Shaping the Category
The growth of ALA is not driven by a single tailwind but by intersecting forces across technology, regulation, consumer behavior, and cost architecture. Each driver alters where investment should flow and how product portfolios should be constructed.
Technological Differentiation and Form Advances
Innovation in molecular form and stabilization has emerged as a decisive commercial lever. The shift from racemic blends toward stabilized enantiomer forms reflects a broader consumer and formulation preference for bioavailability and consistent performance. Suppliers offering stabilized R-lipoic acid or solvent-free grades have carved defensible positions by aligning molecular purity with formulation stability, lower excipient load, and clearer claim narratives. These advances do not merely improve technical specs; they influence downstream pricing power and the ability to serve premium supplement and cosmeceutical applications where performance consistency is a purchase driver. In practical terms, form innovation has become a gatekeeper to higher-margin segments and a differentiator against commoditized bulk supply.
Worldwide Thiochemicals Market
Policy, Regulatory, and Reimbursement Signals
Regulatory dynamics are acting as both a filter and a directional signal. In the United States, compounded ALA remains accessible for patient use through established bulk drug substance pathways, preserving a channel for clinical and customized applications. In parallel, marketing environments for combination products face tighter constraint. Recent restrictions on DHA/EPA nutrient claims have limited how omega-3-enriched ALA supplements can be promoted, compelling brands to reposition messaging around antioxidant support, nerve health, and metabolic wellness rather than synergistic fatty-acid narratives. European scrutiny adds an additional layer of uncertainty. Potential adjustments to supplement usage could reshape regional demand, pushing manufacturers to diversify geographic exposure and to validate formulations against evolving compliance expectations before committing to large-scale inventory. These policy developments reward companies that invest early in compliance readiness, claim substantiation, and flexible formulation architectures.
Consumer Behavior and Application Expansion
Demand-side behavior continues to tilt toward preventive wellness and multi-benefit formulations. ALA benefits from its dual visibility as an antioxidant agent and a metabolic support ingredient, allowing it to enter product architectures spanning nerve comfort, energy metabolism, and skin-care antioxidant coverage. In supplements, the ingredient is increasingly paired with complementary actives in comprehensive wellness regimens. In cosmetics, the emphasis on oxidative stress mitigation and skin resilience has opened room for ALA in premium topical formats. Importantly, consumer purchasing is increasingly influenced by transparency around origin, purity, and molecular form. Buyers are less responsive to generic ingredient listings and more attentive to differentiators such as stabilized enantiomers, solvent-free processing, and documented quality systems. This behavioral shift raises the bar for supplier positioning and rewards brands that can translate technical superiority into clear consumer and practitioner messaging.
Supply Chain Architecture and Cost Structure Evolution
Cost structure evolution is reshaping sourcing strategies. The octanoic acid price volatility of 2024-2025 underscored how input concentration can cascade into margin pressure across conversion and formulation. Beyond raw material swings, logistics risk has become a strategic consideration. The Red Sea shipping disruptions demonstrated how quickly geographic concentration in manufacturing capacity can translate into delivery uncertainty, particularly for buyers dependent on a limited set of origin countries. In response, supply chain design is moving toward multi-origin sourcing, regional safety stock, and longer-term supplier agreements that stabilize pricing while preserving flexibility. For manufacturers, this means that cost leadership is no longer purely a function of scale; it increasingly depends on input hedging, logistics redundancy, and the ability to maintain consistent quality across multiple production sites.
Competitive Positioning and Strategic Moves
The competitive field is defined by companies that have chosen distinct lanes of differentiation: enantiomer purity, solvent-free processing, medical-grade quality systems, and application-specific formulation expertise. These choices shape pricing, customer segments, and resilience to regulatory and cost shocks.
Differentiated Leaders and Value Propositions
Several established players illustrate how strategic focus translates into market positioning. One group of suppliers emphasizes high-purity ALA for cosmeceutical and nutraceutical applications, building brand trust around consistent assay and documented quality for formulators who require reliable input characteristics. Another tier focuses on solvent-free grades for dietary supplements and pharmaceutical use, positioning around cleaner processing profiles and suitability for sensitive formulations. A third orientation centers on bio-enhanced stabilized enantiomer forms, targeting applications where bioavailability and stability are central to the value narrative. Alongside ingredient suppliers, branded supplement manufacturers and formulators convert these inputs into finished products with specific nerve-support and antioxidant messaging. Across these categories, the common thread is that technology and quality claims are no longer optional enhancements; they are the primary mechanisms for distancing from bulk commodity pricing.
Competitive Evolution: Integration, Specialization, and New Entrants
The market is evolving along multiple axes simultaneously. Larger, integrated suppliers are expanding application coverage, attempting to serve pharmaceutical, supplement, and cosmetic channels with consistent quality systems and broader grade portfolios. This integration can strengthen negotiation leverage with downstream buyers and reduce dependency on any single channel. At the same time, specialization continues to thrive. Niche players that concentrate on stabilized enantiomers, research-grade material, or region-specific GMP supply maintain relevance by serving customers who value technical specificity and local compliance familiarity. New entrants typically emerge by targeting underserved formulation needs or by offering differentiated processing attributes that incumbent bulk suppliers do not prioritize. The resulting landscape is neither purely consolidated nor fully fragmented. It is a layered market in which scale, technical specificity, and compliance readiness each create distinct lanes of advantage.
Competitive Implications for Commercial Strategy
For buyers and investors, the practical implication is that supplier selection must account for more than unit cost. Evaluation criteria increasingly include molecular form availability, processing attributes, country-of-origin exposure, and the supplier’s ability to navigate evolving regulatory expectations. For manufacturers, competitive positioning depends on whether they can convert technical differentiation into formulation performance, claim support, and supply reliability. Companies that treat ALA as a commodity input risk margin erosion and exposure to volatility; those that integrate quality narratives, form differentiation, and diversified sourcing into their planning are better positioned to protect pricing and expand premium product lines.
Forward Outlook: Trends Defining the Next Three to Five Years
Looking toward the late 2020s and early 2030s, three trends are likely to shape where value is created and where risk concentrates.
Stabilization and Enantiomer Premiumization
The market is likely to continue shifting toward stabilized and enantiomer-pure forms in higher-value applications. As formulators and brands seek consistent bioavailability and stronger claim narratives, demand for premium grades should outpace growth in bulk racemic supply. The commercial opportunity lies in building product architectures that make molecular differentiation visible to practitioners and consumers, while ensuring that stability claims are substantiated through robust quality documentation. The uncertainty here is regulatory interpretation: if claim environments tighten, the premiumization path depends on the ability to justify performance benefits without overextending marketing language.
L-Alanine Market
Geographic Rebalancing and Supply Resilience
Supply concentration risk will continue to drive rebalancing. Buyers and manufacturers will likely diversify origin points, increase regional inventory buffers, and strengthen contractual safeguards against logistics shocks. This creates opportunities for suppliers in alternative regions to capture share by offering reliable quality, transparent documentation, and flexible commercial terms. The risk is that diversification introduces complexity in quality harmonization and cost management, requiring disciplined vendor qualification and ongoing audit processes. Companies that treat resilience as an investment rather than a reactive measure will be better placed to maintain continuity when disruption recurs.
Regulatory Navigation as a Competitive Advantage
Regulatory developments in key regions will function as both constraint and selection mechanism. In Europe, potential adjustments to supplement usage could compress demand in the near term while rewarding manufacturers with prepared compliance strategies and reformulated product options. In the United States, continued access for compounded use preserves clinical and customized pathways, but marketing constraints on combination products will require sharper positioning. The companies most likely to capture opportunity are those that build regulatory intelligence into product planning, maintain claim substantiation readiness, and keep formulation portfolios flexible enough to adapt to shifting compliance boundaries without sacrificing core consumer benefits.
Strategic Actions for Decision Makers
Different roles within the market face distinct priorities, but a few strategic moves apply broadly and can improve positioning regardless of whether the focus is manufacturing, investment, or procurement.
For Manufacturers and Formulators
- Prioritize form and processing differentiation that translates into measurable formulation advantages, such as stability, lower excipient burden, and cleaner processing profiles, rather than competing primarily on bulk pricing.
- Build multi-origin sourcing and agreed buffer inventory to reduce exposure to raw material swings and logistics disruptions, and structure supplier relationships to provide pricing visibility over longer horizons.
- Align product claims and documentation with evolving regulatory expectations early, especially in regions where scrutiny may reshape addressable demand, so reformulation and repositioning can be managed proactively.
For Investors and Capital Allocators
- Assess exposure to enantiomer purity, solvent-free processing, and application diversification when evaluating companies, because these attributes increasingly determine margin resilience and pricing power.
- Monitor regulatory trajectories in Europe and the United States as signals that can alter demand visibility, and weigh portfolio exposure against potential claim constraints or usage adjustments.
- Seek suppliers and brands with demonstrated quality systems and supply resilience, since geographic concentration and input volatility remain structural risks that can affect continuity and profitability.
For Procurement and Supply Chain Leaders
- Diversify source geography and establish qualification protocols that account for both quality consistency and continuity risk, rather than optimizing solely on spot pricing.
- Negotiate commercial terms that provide clarity on input cost linkage, especially for conversion-dependent materials, to reduce surprise margin compression when commodity prices move.
- Treat ALA sourcing as a multi-dimensional decision that includes molecular form availability, processing attributes, and documentation readiness, so downstream product performance and compliance posture are protected.
The Thioctic Acid (Alpha Lipoic Acid) market is moving from broad expansion toward a more differentiated and compliance-sensitive phase. Growth remains attractive, but the reward is increasingly concentrated in players who can combine technological specificity, supply resilience, and regulatory readiness. A deeper look at segment-level demand shifts, regional dynamics, grade-level pricing behavior, and competitive benchmarking can sharpen planning and reduce exposure to volatility. For stakeholders seeking a more granular view with tailored scenario analysis and actionable recommendations, the complete PW Consulting research report provides the detailed breakdowns and customized guidance needed to convert market intelligence into execution.
For detailed analysis of this topic, please visit the official page: Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydropneumatic Fender Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-21
Hydropneumatic Fender Market
Overview
The Hydropneumatic Fender Market encompasses specialized marine safety devices designed to absorb and dissipate energy during vessel docking and berthing operations. These fenders are critical components in port infrastructure, providing protection for ships and quay walls from impact forces. Their core functionalities include energy absorption, load distribution, and durability, supporting the safe and efficient handling of maritime traffic. The market plays a vital role in modern port operations, offshore platforms, and shipbuilding industries by enhancing safety protocols and reducing structural damage.
The Hydropneumatic Fender Market supports a wide array of maritime and offshore applications, integrating advanced materials and engineering designs. Its importance is underscored by the increasing volume of global shipping and offshore activities, which demand reliable impact mitigation solutions. As ports expand and technological innovations advance, the market's significance continues to grow, with Hydropneumatic fenders being essential for maintaining operational integrity and safety standards.
Market Size and Growth
The current market value for the Hydropneumatic Fender Market is estimated at around USD 1.2 billion in 2024. It is projected to reach approximately USD 2.0 billion by 2034, with a compound annual growth rate (CAGR) of about 6.5% over the next decade. Growth is driven by expanding maritime trade, increasing offshore infrastructure projects, and the adoption of advanced safety standards across the shipping industry. Rising investments in port modernization also bolster market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI1985
Key Drivers
• Growing global maritime trade and port development
• Increasing offshore oil and gas exploration activities
• Technological advancements in fender design and materials
• Regulatory emphasis on safety and environmental standards
• Rising demand for durable and high-performance impact protection solutions
Restraints
• High installation and maintenance costs
• Technical complexities in retrofitting existing port infrastructure
• Regulatory delays and compliance challenges
• Limited awareness in emerging markets
• Operational disruptions during upgrades or replacements
Segmentation
• By Type: Hydropneumatic, Pneumatic, Hybrid
• By Deployment: Fixed, Portable
• By Enterprise Size: Large, Medium, Small
• By End User: Ports, Offshore Platforms, Shipyards, Naval Bases
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits steady demand driven by port modernization and offshore energy projects, with increasing safety regulations fueling adoption. Europe’s focus on sustainable port operations and offshore wind infrastructure supports growth, especially in northern and western regions. In Asia-Pacific, rapid port development and expanding maritime trade make it the largest market, with China and India leading demand. Latin America is gradually adopting Hydropneumatic fenders, primarily in Brazil’s expanding port sector. The Middle East & Africa show emerging opportunities, particularly in offshore oil and gas and port infrastructure investments.
Opportunities
• Expansion into emerging maritime markets in Africa and Southeast Asia
• Integration of IoT and smart monitoring systems for real-time impact management
• Development of eco-friendly, sustainable fender materials
• Adoption in offshore renewable energy projects, including wind and wave farms
• Innovation in modular and scalable fender designs for versatile applications
Key Companies
JIER Marine Equipment Co., Ltd., Marine Impact, Trelleborg Marine Systems, MacGregor, Yokohama Fenders, BlueForce, Guangzhou Fenders, TTS Group, Peninsular Marine, Shin Yang Group, YOKOHAMA Rubber Co., Ltd.
Conclusion
The overall outlook for the Hydropneumatic Fender Market remains robust, driven by increasing maritime trade, offshore infrastructure development, and safety regulations. Long-term growth potential is significant as industries seek more durable and technologically advanced impact mitigation solutions. The strategic importance of hydropneumatic fenders in safeguarding port and offshore assets underscores their critical role in modern maritime operations and industry resilience.
Related Reports
Marine Fastenings Market , Size Share and Analysis | Report 2033
Potato Chips Dehydrator Machines Market , Size Share and Analysis | Report 2033
Potato Washing And Peeling Machines Market , Size Share and Analysis | Report 2033
Potato Chips Machines Market , Size Share and Analysis | Report 2033
2d Galvo Scanner Market , Size Share and Analysis | Report 2033
High Precision Galvo Scanner Market , Size Share and Analysis | Report 2033
Laser Servo Control System Market , Size Share and Analysis | Report 2033
Laser Scanner Control System Market , Size Share and Analysis | Report 2033
Laser Processing Control System Market , Size Share and Analysis | Report 2033
Food Granule Packaging Machines Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Pulmonary Function Testing Systems Market: Why 6.8% CAGR and COPD Drivers Change Everything
By PW Consulting, 2026-09-21
The Pulmonary Function Testing Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The global pulmonary function testing systems market has entered a phase of sustained expansion, with total revenue projected to reach approximately $5.95 billion by 2032. This trajectory reflects a compound annual growth rate of 6.8% across the 2026–2032 forecast period, building on a market base that surpassed $3.7 billion in 2025. The growth is not merely a function of incremental demand; it signals a structural shift in how respiratory diagnostics are deployed across clinical, occupational, and decentralized care settings. Equipment that once lived exclusively in hospital pulmonary labs is now being adapted for primary care, home monitoring, and clinical trial environments, driven by tighter diagnostic protocols, evolving reimbursement models, and a wave of technology miniaturization.
For executives, investors, and procurement leaders, the market presents a dual reality: steady top-line growth alongside intensifying competition for specific use cases. The challenge is no longer whether pulmonary function testing will grow, but where value will concentrate, which product configurations will win procurement contracts, and how regulatory and reimbursement pressures will reshape margins. Understanding these dynamics requires moving beyond headline figures and examining the underlying drivers, competitive moves, and emerging risk vectors that will define the next five years.
Market Landscape and Structural Challenges
The market's expansion has been broad-based, but the composition of demand reveals clear Concentration patterns and pressure points. Pulmonary function testing systems span a diverse equipment set, including spirometers, peak flow meters, gas analyzers, oximeters, and associated diagnostic platforms. This breadth creates both opportunity and fragmentation: buyers increasingly expect integrated solutions rather than standalone instruments, while manufacturers must balance specialization with system-level interoperability. In practice, the market is transitioning from a device-centric model to a workflow-centric one, where accuracy, data connectivity, and compliance documentation carry as much commercial weight as raw measurement performance.
Fragmented Demand and Integration Pressure
One of the defining characteristics of the current market is the uneven distribution of demand across clinical applications. Chronic respiratory conditions, asthma management, cystic fibrosis monitoring, and a wider set of respiratory diseases each pull equipment requirements in different directions. For example, an asthma-focused program may prioritize portable peak flow and spirometry tools with patient-friendly interfaces, while a cystic fibrosis center may require more comprehensive lung volume and gas exchange capabilities. This segmentation makes it difficult for any single product architecture to dominate every setting, and it forces manufacturers to develop modular portfolios or risk missing high-value niches.
PW Consulting Health Care Research Center
At the same time, hospitals and diagnostic networks are consolidating procurement around platforms that can reduce training burden, standardize quality control, and integrate with electronic health records. The result is a market where incumbents with established clinical reputations retain advantages, but new entrants with stronger software ecosystems and simpler device form factors can gain traction in specific customer segments.
Regulatory Compliance as a Strategic Filter
Regulatory and certification requirements are becoming a significant filter in procurement decisions, particularly in regulated healthcare markets. Pulmonary function equipment must increasingly align with international standards for spirometry and lung volume measurement, and reimbursement pathways often depend on demonstrated compliance with accepted clinical protocols. In parallel, infection control expectations for reusable equipment have tightened, with accreditation bodies emphasizing documented cleaning, disinfection, and sterilization procedures consistent with the Spaulding classification. This creates a compliance burden that small or under-resourced manufacturers may struggle to absorb, while also rewarding companies that can provide clearer validation packages and service support.
Reimbursement Stability and Margin Constraints
While clinical demand continues to expand, reimbursement structures remain a critical determinant of commercial viability for many deployment models. Medicare Physician Fee Schedule pricing for common pulmonary function testing codes has provided a baseline of predictability, but the rates do not automatically translate into strong equipment margins, especially for high-volume, lower-acuity testing. Providers must weigh capital cost, maintenance, and workflow efficiency against reimbursement levels that differ across codes and care settings. This tension encourages buyers to favor equipment that enables faster throughput, fewer repeated tests, and more reliable data capture, reinforcing the strategic importance of system reliability and software usability.
Key Drivers Shaping Market Direction
Technology Innovation and Device Miniaturization
The most visible driver of market change is the ongoing miniaturization and digitization of pulmonary function equipment. Compact spirometers, connected oximeters, and smartphone-compatible testing devices are expanding the practical boundaries of where testing can occur. This shift matters because it broadens the addressable use case set: primary care clinics can perform more standardized spirometry on site, occupational health programs can conduct field testing with portable units, and home-based monitoring can complement clinic visits for chronic disease management. Innovation is not limited to hardware size; it extends to workflow integration, wireless data transfer, and software-assisted quality control that helps reduce operator-dependent variability.
Recent product activity illustrates the direction of travel. In mid-2025, Vitalograph expanded its respiratory diagnostics portfolio through a strategic partnership with Thorasys, introducing the tremoflo C2 oscillometer at the Respiratory Diagnostics Summit. The move highlights a broader industry pattern: established diagnostic companies are extending beyond conventional spirometry into complementary measurement modalities that capture lung mechanics and airway resistance, thereby deepening their clinical value proposition. At the same time, Norav Medical launched a compact USB-powered spirometer designed for fast and accurate pulmonary analysis, with certifications aligned to international standards and regulatory requirements. The emphasis on compact form factors, certification readiness, and demonstration at a major trade event signals that portability and compliance are being pursued together rather than as separate priorities.
Policy, Certification, and Quality Standards
Policy and standards environments are shaping both market access and competitive differentiation. Equipment classification under medical device regulations, conformity assessment pathways, and international standards for spirometry and lung volume measurement have become central to procurement eligibility in many healthcare systems. Buyers are increasingly looking for documented alignment with recognized standards because it simplifies internal validation, supports accreditation, and reduces the risk of audit findings. In practice, this means that certification is not merely a regulatory checkbox; it is a commercial asset that can shorten sales cycles and strengthen positioning in tenders and group purchasing environments.
The same logic applies to infection control expectations. As accreditation standards reinforce the need for disciplined reprocessing of reusable equipment, manufacturers that provide clearer instructions, validated cleaning workflows, and Accessories that support safe handling can differentiate themselves in hospital and clinic markets. This is a subtle but meaningful shift: product performance alone no longer defines leadership; operational support and compliance documentation increasingly do.
Demand-Side Shifts in Care Delivery
On the demand side, pulmonary function testing is benefiting from broader changes in respiratory care delivery. Rising awareness of chronic obstructive pulmonary disease, asthma control, and other respiratory conditions is encouraging earlier and more frequent testing in both specialty and general practice settings. At the same time, the growth of decentralized and home-based care models is creating new expectations for equipment that can be used outside traditional lab environments without sacrificing data quality. Clinical research is also a growing application area, where pulmonary function endpoints must be collected consistently across sites and often integrated with other physiologic measurements.
This demand evolution is pushing manufacturers toward solutions that are easier to deploy, simpler to interpret, and more compatible with distributed care workflows. For buyers, the implication is that equipment selection is increasingly influenced by total cost of ownership and workflow fit, not just measurement accuracy in a controlled setting. For manufacturers, it means that winning products are those that reduce friction across the testing pathway, from patient intake to result documentation.
Supply Chain and Cost Structure Realignment
Cost structures across the industry are being reshaped by component availability, manufacturing scale, and software development intensity. As devices become more connected and standards compliance more demanding, the cost of quality systems, certification preparation, and post-market support grows. At the same time, buyers are increasingly price-conscious in lower-acuity settings, putting pressure on manufacturers to balance feature richness with affordability. This environment favors companies that can achieve reliable scale, standardize core platforms, and invest selectively in differentiated capabilities rather than attempting to compete across every price tier simultaneously.
The practical effect is a market in which some suppliers are consolidating around stronger platform architectures while others focus on specialized, high-touch applications. This reallocation of resources is visible in product launches and partnership activity, where the emphasis is often on expanding clinical reach through targeted capability additions rather than broad, undifferentiated expansion.
Competitive Landscape and Evolving Strategies
The competitive field includes established diagnostic manufacturers with strong clinical reputations and a growing set of smaller or regionally focused players that compete through portability, affordability, and software usability. Companies such as Vitalograph, Jaeger Medical, MGC Diagnostics Corporation, Norav Medical, and MIR Medical International Research each illustrate a distinct strategic posture within the same overall market.
Incumbent Positioning and Differentiated Strengths
Larger, clinically entrenched manufacturers tend to compete on completeness of offering, diagnostic reliability, and integration with laboratory or hospital workflows. Their advantage lies in established relationships with pulmonary function labs, familiarity among clinicians, and the ability to deliver system-level solutions that span multiple measurement types. In this context, strategic moves are often about deepening the portfolio rather than simply broadening it. For example, the introduction of oscillometry capabilities alongside existing spirometry and diagnostic platforms reflects an effort to serve a wider set of respiratory assessments without forcing customers to assemble multipurpose solutions from multiple vendors.
Agile and Access-Oriented Positioning
Other participants differentiate through compact devices, simplified operation, and compatibility with decentralized use. A USB-powered spirometer designed for rapid professional testing, or smartphone-compatible devices intended for both clinical and home settings, points to a strategy centered on accessibility and ease of deployment. These offerings are particularly relevant where procurement budgets are tighter, space is constrained, or testing must occur outside a dedicated pulmonary function laboratory. The commercial logic is not to win every high-complexity lab contract, but to capture volume in primary care, occupational health, and home monitoring pathways where convenience and cost matter disproportionately.
Regulatory and Certification-Led Differentiation
A third strategic thread is compliance-driven positioning. Manufacturers that align product development and documentation with recognized certification requirements and regulatory clearance pathways can use this alignment as a differentiator in regulated procurement environments. Recent FDA clearance activity for a wireless-integrated pulmonary function testing device intended for clinical trials underscores how regulatory milestones can open specific commercial doors, especially in research and specialized clinical use. In such cases, the clearance itself becomes part of the value proposition because it reduces buyer uncertainty and supports adoption in settings where regulatory confidence is essential.
Market Evolution: Consolidation, Fragmentation, and New Entry
Looking across these strategies, the market appears to be evolving through a combination of consolidation at the platform level and fragmentation at the application level. Larger players are strengthening system coherence and expanding modality coverage, while smaller firms continue to find room in portable, home-use, and price-sensitive segments. At the same time, new entrants with strong software, connectivity, or trial-focused capabilities can gain relevance by solving narrow but high-value problems rather than competing head-to-head across the entire equipment spectrum. The net effect is a market where broad incumbents and specialized challengers can coexist, provided each clearly defines the workflow problems it solves best.
Forward-Looking Trends and Commercial Implications
Trend One: Workflow-Integrated Diagnostics Will Outpace Standalone Devices
Over the next three to five years, pulmonary function testing is likely to be evaluated less as a collection of instruments and more as an integrated diagnostic workflow. Buyers will increasingly favor platforms that reduce manual steps, improve repeatability, and connect cleanly with record-keeping and quality assurance processes. This trend favors manufacturers that invest in software usability, data standardization, and service support, while pressuring those that rely primarily on hardware specifications to win deals. The commercial opportunity lies in packaging measurement capability with workflow reliability, so that testing becomes easier to scale across sites and staff configurations.
Trend Two: Decentralized Testing and Home-Based Monitoring Will Expand the Addressable Base
Decentralized care models and chronic disease management programs are expected to continue expanding the contexts in which pulmonary function testing is used. Compact, connected devices that can be deployed in primary care, occupational settings, and home environments will broaden the market's reach, but they will also introduce new requirements around patient training, data transmission, and result interpretation. Companies that can provide not only the device but also the supporting instructions, software, and service model will be better positioned to convert this expansion into durable revenue. The opportunity is significant, yet it depends on demonstrating that decentralized testing can deliver reliable data without adding operational burden.
Trend Three: Compliance and Standards Will Act as Both Gatekeeper and Advantage
As regulatory classification, certification expectations, and infection control standards remain central to procurement, compliance will function as both a barrier and a competitive lever. Manufacturers with mature quality systems and clear documentation will find it easier to enter or expand in regulated markets, while those with weaker compliance infrastructure may face longer adoption cycles or limited access to certain buyer groups. The risk here is twofold: compliance costs can compress margins if not managed efficiently, and any lapse in documentation or post-market support can quickly undermine trust in a market where clinical credibility is paramount. The upside is equally real, because strong compliance positioning can differentiate a product in tenders, group purchasing, and multi-site deployments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
Focus product strategy on workflow fit as much as measurement performance. In practice, this means prioritizing software usability, data connectivity, and compliance documentation alongside hardware accuracy. Where portability or home use is a target, ensure that the complete offering—device, software, instructions, and support—is designed for non-specialist environments. Consider whether the portfolio should be extended through complementary modalities or consolidated around a stronger core platform, and treat certification and regulatory readiness as commercial enablers rather than back-office tasks.
FeNO Breathing Monitor Market
For Investors and Strategic Allocators
Evaluate opportunities with attention to deployment context and total cost of ownership rather than unit price alone. Segments that require broader system integration, stronger service networks, or specialized clinical validation may offer more durable positioning than commoditized low-complexity segments. Monitor moves that combine modality expansion, software connectivity, and regulatory milestones, since these often signal an intent to capture higher-value workflows. Also watch for consolidation patterns, because platforms that can serve multiple respiratory testing needs with reduced training and support burden may gain procurement preference over time.
Worldwide Lung Diffusion Gas (Pulmonary Diffusion Gas) Market
For Procurement and Clinical Operations Leaders
When evaluating equipment, weigh not only measurement performance but also the operational burden of deployment, training, cleaning and disinfection requirements, and integration with existing documentation systems. In regulated environments, prioritize vendors that can provide clear evidence of standards alignment and post-market support, since these factors affect both accreditation risk and long-term operating cost. For decentralized or home-based testing, require a realistic plan for data handling, result interpretation, and patient support, because the device alone does not determine outcomes in those settings.
Conclusion
The pulmonary function testing systems market is moving from steady expansion to a more structurally complex phase in which value is shaped by workflow integration, compliance readiness, and deployment flexibility. The growth trajectory remains attractive, but the commercial winners will be those who convert that growth into differentiated solutions for specific care settings rather than competing solely on device specifications. As regulatory expectations firm up, decentralized testing broadens, and software becomes a central part of the value proposition, the market will increasingly reward clarity of strategy and operational execution.
Detailed segmentation data, regional and application-level breakdowns, and customized scenario analysis can further sharpen these decisions. For leaders who need a more granular view of where demand is concentrating and how procurement dynamics are evolving, the full research report provides deeper datasets and focused recommendations tailored to specific strategic questions.
For detailed analysis of this topic, please visit the official page: Pulmonary Function Testing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com