

Blogs
Asia-Pacific Electronic Design Automation Market Asia-Pacific Electronic Design Automation Market Outlook & Forecast
By priyaRaut, 2026-09-07
The Asia-Pacific Electronic Design Automation market revenue surged from $3,120 million in 2020 to $4,950 million in 2025, and is forecasted to reach approximately $13,400 million by 2035. This dynamic growth trajectory is attributed to technological innovation, proliferation of smart devices, and expanded semiconductor fabrication capacity across the region. Leading players are capitalizing on these trends by strengthening R&D investments and forming strategic alliances, ensuring that the APAC market remains at the forefront of EDA adoption over the forecast period.
Read More - https://bussinessinsights.com/research-report/asia-pacific-electronic-design-automation-market
Consumer electronics remains the largest application, reflecting sustained demand for smartphones, wearable devices, and smart home solutions across APAC countries. Automotive electronics is quickly gaining share on the back of electric vehicle investments and advanced driver-assistance systems (ADAS) adoption. Industrial automation, healthcare, and telecom applications account for a significant portion, driven by the proliferation of IoT and 5G technologies. Major EDA vendors are customizing offerings to address unique requirements in each vertical, positioning themselves for further growth.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-electronic-design-automation-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Electronic Design Automation Market industry?
The top five players in the Asia-Pacific EDA market include Synopsys, Cadence Design Systems, Siemens EDA, Keysight Technologies, and ANSYS. These companies dominate the region by offering advanced tools and solutions for designing semiconductors, integrated circuits, and systems, facilitating innovation and efficient electronics manufacturing.
What is the Asia-Pacific Electronic Design Automation Market growth?
The Asia-Pacific Electronic Design Automation market is experiencing rapid growth, driven mainly by increased demand for consumer electronics and automotive solutions. In 2023, Synopsys reported strong revenue growth in this region, attributed to a surge in semiconductor innovation and wider adoption of automation in design processes.
Which segment accounted for the largest Asia-Pacific Electronic Design Automation Market share?
The IC (Integrated Circuit) Design segment holds the largest market share in the Asia-Pacific EDA market. This dominance is due to the growing need for advanced chips in smartphones, automotive electronics, and IoT devices, pushing companies to invest significantly in design and verification automation tools.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Holographic Display Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
Steady market expansion is evident from 2020 to 2035, with revenues projected to escalate from USD 1,820 Million in 2020 to USD 12,630 Million by 2035. The growth is primarily attributed to robust demand from electronics and therapeutics, alongside advancements in visualization technology and manufacturing processes. Strategic government initiatives promoting digital transformation, increasing startup investments, and rapid urbanization across Asia-Pacific further enhance market prospects.
Read More - https://bussinessinsights.com/research-report/asia-pacific-holographic-display-market
The consumer electronics segment remains the primary revenue contributor in 2025, fueled by rising integration of holographic features in smartphones, tablets, and smart wearables. Healthcare applications, led by real-time 3D imaging and surgical visualization, are accelerating rapidly, followed by retail where interactive displays transform in-store experiences. Ongoing investments by defense and educational institutions are expanding use cases, with key players collaborating on advanced simulation, training, and security systems.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-holographic-display-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Holographic Display Market industry?
Key players include Holoxica Limited, Realfiction, Looking Glass Factory Inc., Leia Inc., and EON Reality Inc. These companies are pioneers in developing innovative holographic display solutions for sectors like retail, healthcare, and entertainment, and are actively expanding their presence across the Asia-Pacific region through partnerships and advanced product launches.
What is the Asia-Pacific Holographic Display Market growth?
The Asia-Pacific Holographic Display Market is witnessing substantial growth, driven by the rising adoption in entertainment and healthcare. For instance, in 2023, Realfiction reported increased demand for its Dreamoc displays in education and retail, fueling an estimated CAGR of over 25% from 2023 to 2028.
Which segment accounted for the largest Asia-Pacific Holographic Display Market share?
The commercial sector, particularly retail and advertising applications, held the largest market share. Retailers use holographic displays for interactive product demonstrations and advertising, maximizing customer engagement. Companies like Leia Inc. and Realfiction are leading the integration of holographic technology in storefronts and shopping centers across the region.
Thanks & Regards,
priya
sales@bussinessinsights.com
The Asia-Pacific Sensor Patch market is set for exponential growth, with revenues anticipated to surge from USD 560 million in 2020 to USD 2,950 million by 2035. The meteoric rise is attributed to strong government eHealth initiatives, a burgeoning tech-savvy population, and escalating demand for chronic disease and fitness monitoring solutions. Recent improvements in sensor technology and wide-scale adoption by healthcare institutions support this upward trajectory. Significant investments by global and regional players in R&D and distribution expansion are expected to further strengthen market momentum through the next decade.
Read More - https://bussinessinsights.com/research-report/asia-pacific-sensor-patch-market
Healthcare remains the primary application for sensor patches in Asia-Pacific, capturing 38% of the total market in 2025, propelled by large-scale deployments in hospitals, clinics, and elderly care. Diagnostics hold the second-highest share at 22%, driven by the fast uptake of continuous, non-invasive assessment tools. Fitness & Sports (18%), Patient Monitoring (13%), Wearable Devices (6%), and others (3%) make up the remainder, underscoring the increasing versatility of sensor patches. Heightened focus on telemedicine, health tracking for athletes, and remote monitoring for chronic conditions are significant factors driving growth in these application segments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-sensor-patch-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Sensor Patch Market industry?
The key players in the Asia-Pacific Sensor Patch Market include Abbott Laboratories, Medtronic plc, Koninklijke Philips N.V., iRhythm Technologies, and Dexcom Inc. These companies lead through innovation in wearable health technology, strategic partnerships, and expanding their sensor patch portfolios to meet the growing demand for real-time health monitoring.
What is the Asia-Pacific Sensor Patch Market growth?
The Asia-Pacific Sensor Patch Market is experiencing robust growth, driven by rising healthcare digitalization and increasing prevalence of chronic diseases. For example, Medtronic’s advancements in continuous glucose monitoring technology have contributed to higher adoption rates across various countries in 2023, further accelerating market expansion.
Which segment accounted for the largest Asia-Pacific Sensor Patch Market share?
The healthcare monitoring segment accounted for the largest Asia-Pacific Sensor Patch Market share. Driven by rising demand for remote monitoring among patients with chronic conditions, applications such as cardiac monitoring, glucose monitoring, and temperature tracking are witnessing rapid growth and adoption across hospitals and personal healthcare settings.
Thanks & Regards,
priya
sales@bussinessinsights.com
Asia-Pacific High-speed Data Converter Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific high-speed data converter market was valued at approximately $1,200 million in 2020 and is forecasted to reach $3,850 million by 2035. This growth is largely attributed to a substantial upsurge in 5G communication infrastructure, surging adoption of industrial automation, and technological innovations in automotive electronics. A compound annual growth rate (CAGR) of around 10.2% is expected from 2025 to 2035. The revenue trajectory distinctly reflects the market’s evolving dynamics, as both established and emerging industries increasingly invest in high-performance converters to meet demanding data acquisition and processing needs across the region.
Read More - https://bussinessinsights.com/research-report/asia-pacific-high-speed-data-converter-market
The communications segment leads with an estimated 37% share of the high-speed data converter market in Asia-Pacific by 2025, driven by increased 5G adoption and expansions in broadband infrastructure. The industrial sector, including factory automation and process control systems, takes second place, as high precision and fast throughput are essential for real-time operations. The consumer electronics sector continues to grow, benefitting from innovation in multimedia and smart devices. Automotive and medical verticals are rapidly gaining momentum, spurred by technological advancements in electric vehicles and diagnostic imaging, respectively.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-high-speed-data-converter-market
Frequently Asked Questions
Who are the key players in Asia-Pacific High-speed Data Converter Market industry?
The top five players in the Asia-Pacific High-speed Data Converter Market include Analog Devices, Texas Instruments, Renesas Electronics, NXP Semiconductors, and ON Semiconductor. These companies are recognized for advanced product portfolios, strong R&D capabilities, and robust presence across sectors such as telecommunications, automotive, and industrial applications.
What is the Asia-Pacific High-speed Data Converter Market growth?
The Asia-Pacific High-speed Data Converter Market has experienced steady growth, with significant demand led by expanding 5G networks and IoT applications. For instance, in 2023, Texas Instruments saw increased revenue in Asia-Pacific, reflecting heightened investment in communication infrastructure and advanced electronics manufacturing.
Which segment accounted for the largest Asia-Pacific High-speed Data Converter Market share?
The telecommunications segment accounted for the largest market share in the Asia-Pacific High-speed Data Converter Market. This is attributed to the rapid 5G rollout, growing smartphone adoption, and increased demand for high-speed data processing, which drive the need for efficient data conversion solutions in network infrastructure.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific data center switch market is set for strong growth, with estimated revenues rising from $3,200 million in 2020 to $9,750 million by 2035, reflecting rapid cloud and digital infrastructure investments. The market sees a significant acceleration from 2025, driven by widespread 5G rollout, expanding hyperscale operations, and government smart nation initiatives. This growth is further catalyzed by a surge in data consumption and digital services adoption across both developed and emerging countries in the region. The revenue trend underscores the critical role of network infrastructure modernization in supporting Asia-Pacific’s digital economy.
Read More - https://bussinessinsights.com/research-report/asia-pacific-data-center-switch-market
Cloud service providers remained the largest application segment in 2025, securing a 45% market share due to extensive cloud infrastructure expansion across APAC. Enterprises held a 30% share, as digital transformation initiatives and hybrid cloud deployment drove steady demand for scalable data center networking. The telecommunication providers segment accounted for 13%, highlighting continued investment in 5G backbone and edge data solutions. Other sectors like BFSI, government, and IT & Telecom together comprised the residual share, pointing to diversified adoption trends.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-data-center-switch-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Data Center Switch Market industry?
The top 5 players in the Asia-Pacific Data Center Switch Market include Cisco Systems, Huawei Technologies, Arista Networks, Juniper Networks, and H3C Technologies. These companies specialize in advanced networking equipment, offering high-performance switches and scalable solutions essential for modern data centers across varied industries in the region.
What is the Asia-Pacific Data Center Switch Market growth?
The Asia-Pacific Data Center Switch Market is witnessing robust growth, driven by rising data center investments and cloud adoption. For instance, in 2023, Huawei reported expanding its data center network solutions portfolio to support increased demand, contributing significantly to regional market acceleration.
Which segment accounted for the largest Asia-Pacific Data Center Switch Market share?
The cloud service providers segment accounted for the largest market share in the Asia-Pacific Data Center Switch Market. Growing adoption of cloud computing and hyperscale data center developments have bolstered demand for switches, as evidenced by investments from companies like Alibaba Cloud and Tencent.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific Pyrometer Market is projected to grow robustly from $412 million in 2020 to $886 million by 2035. With a compound annual growth rate (CAGR) of approximately 5.2%, the market expansion is attributed to rapid industrialization, expansion of manufacturing sectors, and increasing adoption of automation and digital control technologies. Major countries like China, India, and South Korea are expected to be primary contributors to revenue growth. As regulatory compliance tightens and quality standards rise, companies are investing considerably in upgrading pyrometry systems, further uplifting market revenue trajectories over the forecasted years.
Read More - https://bussinessinsights.com/research-report/asia-pacific-pyrometer-market
The largest share of the Asia-Pacific Pyrometer Market is held by metal processing, driven by continuous investments in steel and non-ferrous manufacturing plants across China, India, and Southeast Asia. The glass and ceramics industries are also major adopters, where precise and consistent temperature control is critical for quality assurance and operational safety. Growing demand from the power generation and chemical sectors, on the back of stricter compliance and modernization, represents strong opportunities for pyrometer solutions. Other industrial uses, including electronics and precision manufacturing, are emerging as notable secondary application segments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-pyrometer-market
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific Image Intensifier Market revenue is set to surge from an estimated USD 2,650 Million in 2020 to USD 6,370 Million by 2035, exhibiting a consistent upward trajectory. Advancements in imaging technology, growing applications across healthcare and defense, and robust uptake in industrial sectors drive this expansion. Key contributors such as China, Japan, and South Korea are expected to maintain leadership, while Southeast Asian economies display robust growth rates owing to increased healthcare and infrastructure investments.
Read More - https://bussinessinsights.com/research-report/asia-pacific-image-intensifier-market
Medical Imaging dominates with the highest application share in 2025, attributed to ongoing advancements in diagnostic radiology and surgical imaging, as well as government support for healthcare upgrades. Defense & Surveillance follows, supported by robust military modernization, especially in China, India, and South Korea. Industrial uses, including non-destructive testing and quality inspection, are also expanding, driven by manufacturing automation.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-image-intensifier-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Image Intensifier Market industry?
The top 5 players in the Asia-Pacific Image Intensifier Market include Thales Group, Hamamatsu Photonics, Canon Inc., FLIR Systems, and L3Harris Technologies. These companies focus on innovative imaging solutions, advanced night vision technologies, and expanding their regional presence through strategic partnerships and product launches to address growing market demands.
What is the Asia-Pacific Image Intensifier Market growth?
The Asia-Pacific Image Intensifier Market is experiencing significant growth, driven by increased adoption in medical imaging and defense sectors. For example, Hamamatsu Photonics has reported strong demand due to technological advancements and growing healthcare infrastructure, leading to a robust CAGR of approximately 7% from 2023 onwards.
Which segment accounted for the largest Asia-Pacific Image Intensifier Market share?
The medical imaging segment holds the largest share in the Asia-Pacific Image Intensifier Market. Hospitals and clinics are increasingly deploying image intensifiers for fluoroscopy and radiology procedures, propelled by rising healthcare investment, improved diagnostic needs, and the demand for minimally invasive surgeries across emerging Asian economies.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The revenue for the Asia-Pacific Acoustic Camera Market is set to rise steadily from USD 150 million in 2020 to an estimated USD 560 million by 2035. This upward trend is fuelled by increased investments in manufacturing upgrades, robust automotive growth, and rising awareness of sound diagnostics in critical sectors such as healthcare and energy. The implementation of digital signal processing and AI across new product lines is catalyzing market expansion and opening additional revenue streams.
Read More - https://bussinessinsights.com/research-report/asia-pacific-acoustic-camera-market
Industrial applications dominate the Asia-Pacific Acoustic Camera Market in 2025, holding a 36% market share as manufacturers increasingly integrate acoustic diagnostics to enhance predictive maintenance. Automotive follows at 22%, leveraging acoustic imaging to optimize EV designs and reduce cabin noise. The healthcare sector accounts for 15%, primarily for diagnostics and noise control in sensitive environments. Aerospace & defense, energy & power, and electronics & telecom sectors compose the remaining share, signifying a balanced and expanding use across fields where sound monitoring is mission critical.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-acoustic-camera-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Acoustic Camera Market industry?
The top five players in the Asia-Pacific Acoustic Camera Market are Brüel & Kjær, Siemens, SM Instruments, CAE Software & Systems, and GFUVE Electronics. These companies are recognized for their advanced acoustic imaging technologies, strong R&D capabilities, and diverse product portfolios, serving industrial, automotive, and environmental sectors across the region.
What is the Asia-Pacific Acoustic Camera Market growth?
The Asia-Pacific Acoustic Camera Market has shown robust growth, with an estimated CAGR exceeding 8% from 2021 to 2024. Growth is driven by increasing adoption of noise control solutions in industrial sectors and smart manufacturing initiatives in countries like China and Japan. Siemens recently expanded acoustic solutions in the Japanese market.
Which segment accounted for the largest Asia-Pacific Acoustic Camera Market share?
The automotive application segment accounted for the largest market share in the Asia-Pacific Acoustic Camera Market. Acoustic cameras are widely used for detecting and analyzing vehicle noise and vibration, ensuring compliance with regulatory standards in manufacturing hubs such as China, India, and Japan, boosting growth in this segment.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Marketing Automation Software Market to Hit $7B in 2025, Projected 11.5% CAGR Through 2032
By PW Consulting, 2026-09-07
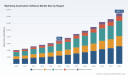
Strategic Imperatives in the Marketing Automation Software Market: A 2026 Decision Framework
The landscape of customer engagement is undergoing a seismic shift. As organizations strive to balance personalization with privacy, scale with efficiency, and automation with human insight, the Marketing Automation Software Market has emerged as a critical infrastructure layer for enterprise growth. At PW Consulting, we recognize that navigating this complex ecosystem requires more than surface-level trend analysis. It demands a rigorous examination of historical trajectory, competitive dynamics, and emerging technological vectors. Our latest market research publication, the Marketing Automation Software Market Study 2026-2032, is designed specifically to equip senior executives, product leaders, and investment strategists with the actionable intelligence needed to make high-stakes decisions in 2026 and beyond.
Wireless Micrometer Heads Market
This introductory insight serves as a strategic primer. It outlines the macro environment, highlights the structural forces reshaping demand, and previews the depth of analysis contained within the full report. We will not obscure the magnitude of opportunity; however, to preserve the analytical integrity and commercial value of our comprehensive dataset, we deliberately withhold granular regional, application, and type-specific monetary breakdowns. The complete segmentation intelligence, coupled with proprietary company benchmarking and scenario modeling, is available exclusively through the full report. The following overview establishes the context and strategic framework that decision-makers must grasp before deploying capital or restructuring marketing technology stacks.
Far Infrared Panel Heaters Market
The Trajectory of Market Expansion and the 2026 Inflection Point
Establishing a reliable baseline is the first step in any strategic planning exercise. Over the historical review period from 2020 through 2025, the marketing automation software sector has demonstrated robust, compounding growth. Beginning at a foundational valuation of approximately 4.1 billion USD in 2020, the market advanced through successive years of acceleration, reaching an estimated valuation of 7.0 billion USD by the base year of 2025. This progression reflects not merely the adoption of digital tools but the structural embedding of automation into the core operational fabric of marketing organizations across industries.
Worldwide Bromine Tablet Market
Looking forward to the forecast period spanning 2026 to 2032, the appetite for scalable, intelligent automation continues to strengthen. Our projections indicate that the market will surpass the 7.6 billion USD threshold in 2026, setting the stage for a sustained expansion phase. Driven by an anticipated compound annual growth rate of 11.5 percent, the sector is on a trajectory to approach 15.0 billion USD by 2032. This growth corridor is not uniform; it is being shaped by divergent adoption curves, evolving procurement models, and a rapidly evolving technology landscape where artificial intelligence transitions from a value-add feature to an existential requirement.
For the 2026 strategic planner, these figures represent more than a growth narrative. They signal a market in transition from early-maturity consolidation to a phase where differentiation is determined by integration depth, AI capability, and compliance readiness. The 2026 horizon demands that leaders evaluate their automation investments against a backdrop of rising platform expectations, heightened data governance requirements, and intensifying vendor competition.
Key Structural Drivers Reshaping Market Dynamics
Several interconnected forces are propelling the market forward, yet each carries nuanced implications that require careful strategic interpretation. Understanding these dynamics is essential for framing the questions that our full research report answers in detail.
- Artificial Intelligence and Workflow Intelligence: The integration of AI-powered workflow orchestration, predictive segmentation, and intelligent prompt optimization is redefining what marketing automation platforms can achieve. Vendors are racing to embed generative and agentic capabilities that reduce manual configuration, accelerate campaign deployment, and improve personalization at scale. This shift is altering procurement criteria, with buyers increasingly prioritizing platforms that demonstrate tangible AI utility across the customer lifecycle rather than isolated machine learning features.
- Omnichannel Orchestration and Real-Time Engagement: Customer expectations have cemented the need for seamless, cross-channel engagement. Platforms that can synchronize messaging across email, social, web, mobile, and paid channels while maintaining contextual continuity are gaining traction. Real-time analytics, predictive behavioral scoring, and dynamic content adaptation are moving from premium capabilities to baseline expectations, particularly for organizations seeking to maximize lifetime value.
- Data Governance, Privacy Regulation, and On-Premise Resilience: The regulatory environment is imposing new constraints on data handling, consent management, and cross-border data flows. Recent adjustments to privacy frameworks have introduced stricter monetary thresholds and expanded deletion mechanisms, compelling organizations to reassess their data architecture. Concurrently, deployment preferences continue to reflect a strong preference for on-premise and hybrid models in segments where data control, sovereignty, and compliance assurance are paramount. This dynamic is creating a bifurcated market in which platform flexibility and governance tooling are decisive competitive differentiators.
- Talent Scarcity and Operational Efficiency: The demand for sophisticated marketing automation is outpacing the supply of specialized talent. Shortages in qualified marketing automation specialists are exerting measurable pressure on implementation timelines and optimization velocity, introducing a modest but persistent drag on growth trajectories. Organizations are responding by prioritizing platforms with intuitive configuration, low-code workflow design, and embedded guidance that reduce reliance on scarce technical resources while preserving operational rigor.
Competitive Landscape: Leadership, Differentiation, and Strategic Positioning
The vendor ecosystem in this market is characterized by a mix of broad-platform incumbents, specialized challengers, and enterprise-grade solution providers. Our analysis indicates a moderately concentrated market structure, with the top three players capturing a meaningful share of total revenue and the top five collectively accounting for a majority of market activity. This concentration does not imply stagnation; rather, it reflects a competitive arena where differentiation is increasingly articulated through product philosophy, ecosystem integration, and the ability to address distinct customer archetypes.
Several established leaders continue to set the pace. HubSpot, headquartered in Cambridge, Massachusetts, has reinforced its position through a comprehensive Marketing Automation Hub that tightly couples CRM integration, AI-powered workflows, and end-to-end funnel management. Its recent Spring 2026 Spotlight release introduced over 100 updates, including HubSpot AEO for AI-driven prompt suggestions and brand visibility analytics, signaling a strategic emphasis on search-augmented engagement and measurable brand impact. ActiveCampaign, based in Madison, Wisconsin, has pursued a focused strategy centered on sales and marketing alignment, deploying AI agents and omnichannel capabilities to unify customer communication. Its November 2025 product expansion, which integrated Active Intelligence Personalized Cards and Knowledge Base functionality, also established an official Claude Connector, reflecting a broader industry movement toward interoperable AI ecosystems.
Specialized strengths define other prominent players. Klaviyo, from Boston, has carved a distinct niche in customer lifecycle marketing automation, particularly for e-commerce, leveraging real-time segmentation and AI agents to drive commerce-oriented engagement. Braze, headquartered in New York, delivers real-time customer engagement automation across channels, using predictive analytics and its Sage AI framework to power moment-based interactions. On the enterprise side, Salesforce Marketing Cloud and Adobe Marketo Engage continue to anchor large-scale deployments. Salesforce’s San Francisco-based platform emphasizes multi-channel orchestration within a broader CRM ecosystem, while Adobe’s Marketo Engage, based in San Jose, remains a focal point for B2B demand generation and lead nurturing in complex enterprise environments.
Oracle Eloqua, from Austin, provides enterprise demand generation automation with deep integration into Oracle CX and sophisticated workflow capabilities, appealing to organizations already invested in the Oracle technology estate. Microsoft Dynamics 365 Marketing, rooted in Redmond, integrates marketing automation directly within the Dynamics 365 environment, aligning marketing execution closely with CRM and sales workflows. Meanwhile, Mailchimp, based in Atlanta, continues to serve a broad user base with accessible email and multi-channel automation, automation sequences, and CRM ties that lower the barrier to entry for smaller teams and scaling organizations.
This competitive mosaic illustrates a market where platform philosophy, target customer profile, and AI integration strategy are as consequential as raw feature counts. Our report provides a structured comparative analysis of these vendors, examining product roadmaps, deployment models, ecosystem alliances, pricing dynamics, and positioning relative to key customer segments. It also explores how recent product releases and partnership moves are reshaping buyer expectations and influencing vendor selection criteria in 2026.
Research Coverage and Operational Utility
A market study earns its place on a leadership team’s desk only if it translates data into decision-ready insight. Our Marketing Automation Software Market research is constructed to support a wide range of strategic applications, from technology investment planning and vendor evaluation to competitive benchmarking and market entry strategy. The report is organized to provide both macroeconomic clarity and granular, actionable detail, while maintaining the analytical discipline necessary to avoid oversimplified conclusions.
- Historical Baseline and Forecast Architecture: The research establishes a robust historical foundation spanning 2020 through 2025 and extends a forward-looking forecast through 2032. This dual-horizon approach enables executives to validate assumptions against observed performance and to model multiple growth scenarios based on different adoption and technology maturation pathways.
- Segmentation Frameworks: The study decomposes market activity across multiple dimensions, including functional type, application, and regional distribution. By mapping how value accrues across campaign management, email marketing, lead nurturing and scoring, social media marketing, analytics and reporting, content management, and other functional categories, the report helps organizations identify where investment intensity and platform maturity are most pronounced. Application-level analysis differentiates between large enterprise deployments and SME adoption patterns, providing context for procurement behavior, integration complexity, and scaling requirements.
- Competitive Company Profiles and Benchmarking: The report delivers in-depth profiles of leading vendors, including headquarters location, platform capabilities, product philosophy, and recent strategic moves. It evaluates how each player addresses core buyer needs, where they position themselves relative to competitors, and how their recent releases and integrations reshape the value proposition. This competitive mapping supports vendor shortlisting, partnership evaluation, and strategic positioning analysis.
- Regulatory, Compliance, and Deployment Considerations: Given the increasing importance of data governance and privacy compliance, the research examines how regulatory developments influence platform selection, deployment preferences, and operational processes. It addresses the continued relevance of on-premise and hybrid deployment models in segments where data control and regulatory assurance are decisive, and it contextualizes how compliance requirements are being operationalized within marketing technology stacks.
- Strategic Implications and Decision Frameworks: Beyond descriptive analysis, the report provides structured guidance for evaluating automation investments. It outlines criteria for assessing platform fit, integration depth, AI readiness, scalability, and total cost of ownership, helping leaders translate market intelligence into actionable plans for procurement, development, and organizational alignment.
What the Full Report Delivers
The excerpt presented here establishes the strategic terrain and highlights the critical forces that will shape decision-making in 2026. Yet the full complexity of the market, including the precise allocation of revenue across regions, functional types, and application segments, as well as the detailed vendor benchmarking and scenario modeling, resides within the complete research publication. Accessing the full report unlocks a comprehensive dataset and a structured analytical framework that enables executive teams to move beyond general market awareness to precise, evidence-based strategy formulation.
The complete study provides explicit segmentation values across all major geographic regions, granular breakdowns by functional type and application profile, and quantified concentration metrics that illuminate the competitive structure of the market. It also supplies a detailed catalog of recent product releases, partnership developments, and regulatory updates that are actively reshaping buyer expectations and implementation roadmaps. By consolidating these elements into a single, rigorously validated research asset, the report empowers leaders to benchmark their current position, evaluate alternative investment pathways, and anticipate the competitive moves that will define the next phase of market evolution.
Strategic Outlook for 2026 and the Path Forward
The Marketing Automation Software Market in 2026 is defined by a confluence of accelerating AI adoption, intensifying omnichannel expectations, tightening data governance, and a competitive vendor landscape that rewards differentiation through integration and usability. Organizations that treat automation as a strategic enabler rather than a tactical utility will be best positioned to capture the value embedded in this growth corridor. The window for decisive action is open, but it requires clarity about where to invest, which capabilities to prioritize, and which vendors align with an organization’s operational and compliance realities.
PW Consulting’s Marketing Automation Software Market research is built to provide that clarity. By combining a rigorous historical-to-forecast architecture with in-depth competitive analysis, segmentation insight, and actionable decision frameworks, the study offers a reliable foundation for executive strategy in a market that is both dynamic and consequential. The macro trajectory is promising, the competitive stakes are high, and the margin for strategic misjudgment is narrowing. Leaders who ground their 2026 decisions in comprehensive, current intelligence will be better equipped to navigate complexity, optimize investment outcomes, and build marketing automation capabilities that scale with their ambitions.
The complete intelligence, including detailed segmentation data, vendor benchmarking, regulatory impact assessment, and forecast scenarios, is available through the full report. Access the complete research to equip your leadership team with the depth of analysis required to make confident, forward-looking decisions in the Marketing Automation Software Market.
For detailed analysis of this topic, please visit the official page: Marketing Automation Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 10-Deacetylbaccatin III Market Hits $161.5M in 2025, Poised for 5.5% CAGR Through 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the 10-Deacetylbaccatin III Market: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global landscape for oncology-supporting pharmaceutical intermediates is undergoing a structural transformation, driven by sustained demand for taxane-based therapeutics, expanding regional manufacturing capabilities, and an increasingly rigorous regulatory environment. As therapeutic pipelines continue to rely on semi-synthetic routes for paclitaxel and docetaxel production, the upstream supply of 10-Deacetylbaccatin III has evolved from a niche botanical input into a strategically critical node within the broader pharmaceutical value chain. Our latest market research delivers a comprehensive, forward-looking assessment of this segment, positioning corporate strategists, procurement leaders, and investment professionals with the analytical clarity required to make informed decisions across the forecast horizon.
Worldwide Aged Home Care Market
Designed to anchor executive planning for the 2026 strategic cycle and beyond, this study bridges historical performance tracking with multi-year projection modeling. Rather than offering static snapshots, the analysis maps the momentum of market expansion, dissects the structural forces shaping supply and demand, and evaluates how key enterprise players are positioning themselves amid shifting regulatory expectations, botanical sourcing constraints, and evolving purity specifications. The following exposition outlines the strategic rationale behind this research, previews the analytical architecture of the full report, and demonstrates how the intelligence contained within it can be operationalized to strengthen market entry strategies, optimize procurement frameworks, and refine competitive positioning.
Escape Hoods Market
Market Trajectory: Translating Historical Momentum into Forward-Looking Strategy
Market sizing and growth modeling form the quantitative backbone of any credible strategic assessment. Over the historical window spanning 2020 through 2025, the global 10-Deacetylbaccatin III market has demonstrated a consistent upward trajectory, moving from an initial revenue base into progressively higher valuation tiers as pharmaceutical manufacturers scaled production capacity and secured long-term supply agreements for taxane intermediates. The baseline year of 2025 establishes a clear inflection point, after which the forecast period extending to 2032 illustrates a steady compound annual growth rate that reflects both underlying demand expansion and incremental capacity rationalization across key producing regions.
Worldwide Food Foil Market
For corporate planners, this trajectory is not merely a numerical projection; it is a structural signal. A sustained mid-single-digit CAGR across the forecast window indicates a market that is maturing but far from saturated, with growth increasingly dependent on alignment between intermediate availability, downstream API scheduling, and regional regulatory clearance cycles. The projection framework incorporated in our study captures this dynamic by modeling demand propagation through manufacturing pipelines, accounting for capacity ramp-up timelines, and stress-testing scenarios against potential supply interruptions, botanical harvest variability, and shifts in procurement preference toward higher-purity grades.
Decision-makers leveraging this intelligence can translate the growth curve into actionable planning parameters. Procurement teams can map contract renewal cycles against projected supply tightness, manufacturing strategists can evaluate whether to expand in-house extraction or secure multi-source agreements with specialized botanical intermediate suppliers, and investors can distinguish between cyclical demand spikes and structural growth drivers when assessing exposure to taxane-related segments. By anchoring forecasts to scenario frameworks rather than single-point estimates, the research enables organizations to build flexible operating models that withstand market volatility while capturing upside from capacity expansions and regional demand acceleration.
The research deliberately withholds granular segment-level revenue breakdowns in this introductory preview, reserving those precise allocations for the full analytical suite. This approach ensures that prospective clients experience the methodological rigor of the study while recognizing the necessity of accessing the complete dataset to unlock region-specific sourcing strategies, application-driven demand mapping, and formulation-grade commercial prioritization.
Value Chain Architecture and Procurement Implications
The commercial ecosystem surrounding 10-Deacetylbaccatin III is defined by a complex intersection of botanical sourcing, semi-synthetic processing, regulatory documentation, and downstream pharmaceutical demand. Unlike commodity chemical intermediates, this compound requires specialized extraction and purification pathways originating from Taxus species, which introduces inherent volatility related to harvest cycles, geographic sourcing constraints, environmental regulations, and the operational maturity of extraction facilities. Simultaneously, downstream manufacturers depend on consistent intermediate quality and documented compliance frameworks to maintain uninterrupted production of anti-cancer APIs, making supply reliability as critical as cost competitiveness.
Our study maps this value chain in operational detail, providing procurement and supply chain leaders with a structured view of where value is created, where bottlenecks typically emerge, and how supplier capabilities differ across regions and processing standards. The analysis differentiates between standard formulation pathways and enhanced purity grade outputs, recognizing that while standard formulations address broad commercial manufacturing needs, enhanced purity specifications increasingly influence procurement decisions in markets where regulatory scrutiny, downstream process sensitivity, and quality documentation requirements have intensified.
Chemical synthesis and research and development applications further complicate the procurement landscape. While the majority of intermediate demand flows toward pharmaceutical manufacturing, a meaningful share of consumption originates from synthesis programs and R&D initiatives that prioritize availability, documentation, and formulation flexibility over bulk cost optimization. This dual-channel demand structure requires buyers to maintain differentiated sourcing strategies: long-term, volume-oriented agreements for manufacturing-scale requirements, and responsive, specification-sensitive procurement channels for development-stage consumption. The research outlines how leading suppliers structure their commercial offerings to serve both channels, and where structural gaps persist that forward-looking organizations can exploit through targeted supplier partnerships or vertical integration.
For strategic planners, the value chain analysis serves as a diagnostic tool for assessing exposure to supply concentration, evaluating the credibility of supplier certifications, and determining whether existing procurement architectures are aligned with anticipated demand quality and volume trajectories. Understanding how botanical extraction capacity, purification throughput, and documentation readiness interact enables organizations to anticipate lead-time variability, negotiate more effectively, and construct contingency plans that reduce vulnerability to regional disruptions or regulatory hold-ups.
Competitive Landscape: Strategic Positioning of Key Market Participants
The competitive environment for 10-Deacetylbaccatin III is characterized by a fragmented yet increasingly differentiated supplier base, with participants competing across dimensions such as botanical sourcing expertise, regulatory documentation breadth, processing infrastructure, geographic reach, and commercial specialization. Market concentration metrics indicate that while no single enterprise dominates the segment, a cluster of established players has secured meaningful positions through combinations of extraction capability, compliance readiness, and regional distribution networks. The strategic relevance of this landscape lies not in simple market share rankings, but in understanding how each participant’s operational profile shapes their ability to capture demand growth, withstand supply shocks, and expand into adjacent formulation or purity segments.
Indena S.p.A. exemplifies a Europe-based specialist with deep botanical intermediate expertise, leveraging established regulatory documentation and commercial readiness as a pure molecule precursor pathway for docetaxel-related applications. Its positioning reflects a broader strategic archetype: specialized extraction capability paired with compliance-oriented commercial deployment, enabling access to procurement programs that prioritize documented supply continuity and formulation traceability. Phyton Biotech LLC operates from a similar philosophy but with a stronger emphasis on plant-derived pharmaceutical intermediates for semi-synthetic taxane production, reinforcing its role as a globally oriented supplier that bridges extraction capability with downstream manufacturing requirements.
Within the Asia-Pacific region, several producers have built commercial footprints that combine regional manufacturing density with export-oriented distribution. Samyang Biopharmaceuticals Corporation maintains an active supply posture supported by Asia-Pacific manufacturing and distribution infrastructure, making it a relevant reference point for organizations evaluating regional sourcing diversification. ScinoPharm Taiwan, Ltd. brings advanced process control infrastructure to its intermediate production, an attribute that increasingly matters for buyers seeking consistent specification performance and scalable purification capacity. In China, a cluster of producers including Hainan Yew Pharmaceutical Co., Ltd., Fujian South Pharmaceutical Co., Ltd., Chengdu Biopurify Phytochemicals Ltd., Wuxi Taxus Pharmaceutical, and Ningbo Green-Health Pharmaceutical illustrate the breadth of domestic manufacturing capability, ranging from large-scale domestic and export-focused production to GMP-aligned facilities serving pharmaceutical-grade intermediate requirements. Each organization brings a distinct commercial emphasis, whether oriented toward volume leadership, cost optimization for export markets, or compliance and certification readiness.
India-based Alchem International Pvt. Ltd. adds another strategic dimension by combining botanical API manufacturing with a robust certification portfolio, reinforcing its relevance for buyers seeking internationally recognized documentation alongside export capability. Meanwhile, Germany-based PhytoLab GmbH occupies a specialized niche as a reference substance specialist, offering high-purity standards that support research and pharmaceutical benchmarking rather than bulk manufacturing supply. This diversity of strategic archetypes underscores the importance of matching supplier selection to procurement objectives: bulk manufacturing continuity, enhanced purity assurance, regulatory documentation strength, regional proximity, or research-grade standardization.
Our competitive analysis extends beyond individual company profiles to examine how these participants interact within the broader market structure. The study assesses where capacity expansion is likely to alter supply balance, where certification and compliance advantages translate into commercial preference, and where regional manufacturing networks may tighten or loosen depending on export policy, environmental constraints, and downstream demand distribution. For corporate strategists, this competitive mapping provides a framework for evaluating partnership candidates, assessing substitution risk, and identifying which supplier attributes will carry the most weight as regulatory expectations and purity requirements continue to evolve.
Structural Drivers, Regulatory Context, and Emerging Industry Dynamics
The medium-term trajectory of the 10-Deacetylbaccatin III market is shaped by a set of interlocking structural drivers that extend beyond simple demand growth. One of the most significant is the continuing reliance of taxane-based oncology therapies on semi-synthetic pathways that depend on dependable intermediate supply. As downstream pharmaceutical programs scale or sustain production to meet therapeutic demand, the upstream requirement for high-quality 10-Deacetylbaccatin III becomes increasingly embedded in operational planning, contract manufacturing schedules, and API continuity strategies. This structural dependency reinforces the market’s resilience even as pricing, sourcing conditions, and regional production dynamics fluctuate.
Regulatory and quality assurance expectations represent another central force. Buyers in pharmaceutical manufacturing environments are placing greater emphasis on documented GMP alignment, certification breadth, and consistent specification control, particularly when intermediates feed into regulated drug production pathways. In this context, suppliers that can demonstrate robust process control, traceability, and internationally recognized documentation gain a structural advantage, while those competing primarily on price without equivalent compliance readiness face increasing scrutiny. The research captures how these expectations are reshaping procurement criteria and influencing commercial negotiations across regions.
Botanical sourcing dynamics introduce additional complexity. Because the feedstock originates from biologically derived sources, supply planning must account for harvest timing, extraction yield variability, and the operational capacity of specialized processing facilities. Organizations that depend on single-source arrangements or geographically concentrated supply chains face elevated exposure to disruptions, making diversification, buffer inventory planning, and supplier qualification rigor more important than ever. At the same time, suppliers with mature extraction infrastructure, established regrowth or sustainable sourcing practices, and multi-regional distribution capability are better positioned to stabilize availability and support long-term contractual commitments.
In addition to these structural forces, the market is being shaped by evolving procurement preferences around formulation type and purity grade. As manufacturing processes become more sensitive to impurity profiles and downstream yields, demand for enhanced purity grades is gaining strategic relevance, particularly for applications where specification consistency directly influences processing efficiency or regulatory readiness. Simultaneously, standard formulations continue to serve a broad manufacturing base where cost-efficiency and reliable availability remain paramount. The interplay between these demand segments influences pricing behavior, supplier capacity allocation, and the strategic emphasis of intermediate producers as they decide whether to broaden standard-grade output or invest in higher-purity processing pathways.
This preview does not enumerate specific development announcements or transient market events; instead, it frames the analytical lens through which such dynamics are evaluated in the full report. The complete study assesses how operational developments, certification milestones, capacity adjustments, and regional supply shifts alter competitive positioning and procurement strategy, allowing decision-makers to distinguish signal from noise when planning for the 2026 horizon and beyond.
How the Full Research Converts Intelligence into Action
A market research report delivers value only when it converts analytical depth into operational decision support. Our 10-Deacetylbaccatin III study is structured to serve multiple strategic functions simultaneously: as a source of macro-level growth intelligence, as a diagnostic framework for supplier evaluation, as a reference for regional demand distribution, and as a planning tool for procurement, manufacturing, and investment teams. The report integrates historical performance tracking, forecast modeling, segmentation analysis, competitive profiling, and supply chain assessment into a unified analytical system that can be adapted to different organizational use cases.
For procurement and supply chain leaders, the study provides the context needed to design sourcing architectures that balance cost, quality, and continuity. By examining how intermediate supply flows through manufacturing pipelines, where specification sensitivity is highest, and which supplier profiles offer the strongest documentation or capacity advantages, procurement teams can construct more resilient contracts, evaluate multi-source strategies, and prioritize supplier qualification criteria that align with both near-term operational needs and longer-term regulatory expectations.
For business development and market entry strategists, the report offers a structured view of where demand is expanding, which formulation and purity segments present the strongest commercial opportunity, and how competitive intensity varies across sourcing regions. This intelligence supports decisions about partnership selection, distribution channel design, and capacity investment, helping organizations avoid overconcentration in saturated supply pathways while identifying underserved demand pockets that may warrant dedicated commercial engagement.
For investor and corporate strategy teams, the study provides a framework for assessing market maturity, growth sustainability, and competitive differentiation without relying on isolated data points. By linking growth projections to structural drivers, supply constraints, and supplier capability profiles, the analysis enables more disciplined evaluation of opportunities tied to taxane intermediate supply, botanical extraction capacity, and pharmaceutical intermediate manufacturing.
The full report contains the detailed segmentation architecture, regional demand distribution, formulation-grade commercial splits, and company-level capability assessments necessary to execute these strategies with precision. Those core segmentation figures and detailed allocations are intentionally reserved for the complete intelligence package, ensuring that the full depth of the analysis is accessible only to clients who obtain the complete research. This approach preserves the strategic value of the dataset while allowing the preview to demonstrate the rigor, structure, and decision orientation of the study.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle presents a pivotal moment for organizations engaged with pharmaceutical intermediates, botanical extraction supply chains, and taxane-related manufacturing pathways. Demand is not entering a speculative phase; it is continuing along a documented growth path that requires deliberate strategic alignment rather than reactive procurement adjustments. Supplier capabilities are diversifying, regulatory expectations are tightening, and the distinction between standard and enhanced-purity supply is becoming increasingly material to downstream operational outcomes. In this environment, decisions made with incomplete intelligence carry disproportionate risk, while organizations that ground their planning in structured, forward-looking analysis are better positioned to secure supply continuity, optimize cost-quality trade-offs, and build defensible competitive positioning.
This research is designed to support that discipline. It translates historical momentum into forecast orientation, maps competitive capability into procurement and partnership implications, and frames structural drivers in terms that can be directly applied to sourcing strategy, capacity planning, and market development decisions. By engaging with the full study, decision-makers gain access to the segmentation detail, regional demand architecture, company-level capability assessment, and scenario-based planning context needed to move from broad market awareness to executable strategy.
The 10-Deacetylbaccatin III market is not defined solely by its growth rate; it is defined by the strategic choices organizations make in response to supply complexity, regulatory evolution, and competitive differentiation. Our analysis provides the intelligence foundation for those choices. For executives seeking to align 2026 planning with a clear, evidence-based view of market direction and supplier landscape, the complete research offers the depth required to act with confidence and precision.
For detailed analysis of this topic, please visit the official page: 10-Deacetylbaccatin III Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com