

Blogs
Global Food Contract Manufacturing Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global food contract manufacturing market is projected to grow steadily from 2020 to 2035, with revenue rising from USD 48,000 Million in 2020 to an estimated USD 128,500 Million by 2035. The market recorded robust momentum during 2021-2025, driven by shifting consumer preferences, technology advancement, and regional expansion. Strong CAGR performance is seen during 2025-2030 due to scalable outsourcing opportunities and retailer emphasis on private label offerings. The forecast period up to 2035 further reflects sustained industry investment and adoption of hybrid retail and distribution channels, making contract manufacturing an increasingly integral part of the global food ecosystem.
Read More - https://bussinessinsights.com/research-report/global-food-contract-manufacturing
The retail segment commands the largest share of the global food contract manufacturing market by application in 2025, at 37%. Food service applications, encompassing quick-service restaurants and catering, comprise 24% due to heightened demand for outsourced meal preparation. Industrial uses, featuring bulk ingredients and intermediates for other manufacturers, account for 18%. Institutional applications, including healthcare and education, contribute 11%, as organizations optimize foodservice costs. Online platforms are gaining popularity, representing 7% of the market, driven by the surge in e-commerce grocery services. Other applications, such as specialty and niche food production, collectively make up 3%, underlining a diversified application landscape catering to varying end-user needs.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-food-contract-manufacturing
Frequently Asked Questions
Who are the key players in Global Food Contract Manufacturing industry?
The top five players in the global food contract manufacturing industry are Buhler Group, Tetra Pak International S.A., Nestlé, Cargill, and Nissin Foods Holdings. These companies lead due to their extensive manufacturing capabilities, global supply chains, innovation in food processing technologies, and strong partnerships with established food brands.
What is the Global Food Contract Manufacturing growth?
The global food contract manufacturing market has seen significant growth, with recent reports indicating a CAGR of over 9% between 2021 and 2024. Companies like Tetra Pak have reported increased demand for outsourced food processing due to shifting consumer preferences and cost-effective production models.
Which segment accounted for the largest Global Food Contract Manufacturing share?
The beverages segment accounted for the largest share in global food contract manufacturing. This is driven by the rising consumption of ready-to-drink products and the demand for specialized bottling and packaging solutions, with numerous manufacturers focusing on outsourcing beverage production to optimize efficiency and quality.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global General Purpose Lighting Equipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global general purpose lighting equipment market is projected to climb from $82,400 Million in 2025 to $140,800 Million by 2035, reflecting a robust CAGR driven by widespread adoption of energy-efficient and smart lighting solutions. Revenue growth is underpinned by investments in urban development, infrastructure upgrades, and heightened demand for integrated lighting systems. North America and Asia-Pacific remain primary revenue contributors, spurred by rapid urbanization and government initiatives on sustainability. Significant growth potential is also emerging from Latin America, the Middle East, and Africa as they accelerate city modernization programs.
Read More - https://bussinessinsights.com/research-report/global-general-purpose-lighting-equipment
The global market share by applications in 2025 shows residential lighting leading the segment, driven by renovation activities, urban population growth, and smart home adoption. Commercial and industrial applications collectively account for over half the market demand, propelled by large-scale facility upgrades, sustainability initiatives, and regulatory compliance. Outdoor and automotive applications also witness continual growth as governments invest in smart city and public infrastructure projects, including street lighting and smart parking solutions. The increasing integration of adaptive and connected lighting in commercial spaces is bolstering growth in hospitality, retail, and office environments.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-general-purpose-lighting-equipment
Frequently Asked Questions
Who are the key players in Global General Purpose Lighting Equipment industry?
Key players include Signify (Philips Lighting), Osram Licht AG, GE Lighting (a Savant company), Acuity Brands, and Eaton Corporation. These companies are recognized for their innovation, extensive product portfolios, global reach, and continuous investment in energy-efficient lighting technologies, catering to diverse residential, commercial, and industrial sectors.
What is the Global General Purpose Lighting Equipment growth?
The Global General Purpose Lighting Equipment market has witnessed steady growth, driven by increasing demand for energy-efficient solutions. For example, Signify reported strong year-on-year revenue growth in its LED segment in 2023, citing accelerated adoption of intelligent lighting systems in both developed and emerging markets.
Which segment accounted for the largest Global General Purpose Lighting Equipment share?
The residential application segment commands the largest market share in the Global General Purpose Lighting Equipment market. The rise in urbanization, increasing home renovation projects, and consumer demand for smart, energy-saving lighting solutions are significant contributors to this dominance within the application landscape.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Commercial Payment Cards Market to Hit $364.76B by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Insights from the Commercial Payment Cards Market Research 2026
The landscape of corporate spending is undergoing a seismic shift. As businesses grapple with inflationary pressures, evolving regulatory frameworks, and the demand for seamless digital integration, the commercial payment card sector has emerged as a critical lever for operational efficiency. For decision-makers navigating the fiscal calendar of 2026, understanding the trajectory of this market is not merely an academic exercise—it is a strategic imperative. PW Consulting is proud to unveil our latest comprehensive market research, designed to equip leaders with the intelligence needed to capitalize on growth opportunities and mitigate emerging risks in the commercial payment ecosystem.
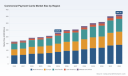
This research is anchored in rigorous data analysis covering historical performance from 2020 through 2025 and extending robust forecasts through 2032. The macro-environment presents a compelling story of resilience and expansion. In 2025, the global revenue for commercial payment cards reached approximately 229.05 billion USD. Looking ahead, the market is projected to climb to 249.66 billion USD in 2026, marking a significant inflection point in corporate adoption rates. Our forecast models indicate a steady compound annual growth rate of 6.98 percent throughout the forecast period, with revenues expected to surpass 364.76 billion USD by 2032. These figures underscore a sustained appetite for flexible payment instruments that bridge the gap between traditional corporate treasury functions and modern procurement needs.
Decoding Market Concentration and Competitive Forces
One of the most critical aspects of our analysis focuses on the competitive dynamics that define the industry. The market is characterized by a moderate level of concentration, where strategic positioning among top-tier players dictates the pace of innovation. Our report details a landscape where the top three companies command a combined market share of roughly 49.5 percent, while the top five entities control approximately 62.8 percent of the revenue pool. This structure suggests that while dominant networks hold significant sway, there remains substantial room for specialized issuers and niche providers to carve out profitable segments.
Plastic Cards Market
The competitive arena is populated by a diverse mix of global network operators and specialized issuers. Giants like American Express, Visa, and Mastercard continue to dominate the infrastructure layer, offering robust networks that support virtual purchase cards and corporate spend management solutions. American Express, headquartered in New York, remains a key player in issuing commercial payment cards including virtual purchase cards for business-to-business procurement. Similarly, Visa, based in San Francisco, operates a global network supporting commercial payment cards including virtual cards for corporate spend management, while Mastercard, located in Purchase, NY, provides network infrastructure with a focus on virtual and single-use variants for B2B transactions.
However, the ecosystem extends far beyond these primary networks. Discover Financial Services, based in Riverwoods, IL, issues commercial payment cards for business expense tracking and virtual solutions, catering to specific expense management needs. International reach is exemplified by JCB in Tokyo and UnionPay in Beijing, the latter facilitating commercial payment cards with contactless and virtual options to support cross-border commerce. On the specialized issuer front, companies like WEX in Minneapolis provide commercial fleet and virtual payment cards for business expenses, whereas Corpay in Nashville issues and manages commercial payment cards for corporate travel and expense programs.
Innovation is also being driven by agile entrants and standards bodies. Engine, based in Denver, recently made waves with the launch of the Engine X Visa-branded corporate charge card specifically for small and mid-sized businesses. This product features spending controls and travel rewards, directly addressing the needs of the SMB segment which often feels overlooked by larger issuers. Furthermore, standards development plays a crucial role in interoperability and security. X9, the standards body in Annapolis, MD, developed and published X9.149 for single-use virtual business-to-business payment cards, aiming to streamline transaction efficiency.
Recent Developments Shaping the 2026 Landscape
Real-time intelligence is vital in a sector moving this fast. Our research integrates the latest developments that are actively reshaping the value proposition for corporate clients. In March 2026, Engine announced the launch of their corporate charge card, featuring spending limits, merchant restrictions, and up to 10 percent rewards on business travel. This move highlights a trend toward incentivizing specific spending categories while maintaining strict control parameters, a balance that many finance teams are seeking.
Simultaneously, the regulatory and standards environment is tightening to support higher efficiency and security. In April 2026, the Accredited Standards Committee X9 published the X9.149 standard for single-use virtual purchase card payment automation. This development is designed to improve B2B transaction efficiency and reconciliation following ISO 20022 messaging standards. Such standardization efforts are critical for reducing friction in accounts payable processes and enhancing the auditability of corporate spending.
Beyond specific product launches, broader industry dynamics are influencing market behavior. The Federal Reserve Board reported on average debit card interchange fees by payment card network in December 2025, providing essential data for cost-benefit analyses of different card programs. Security remains paramount, with the PCI DSS Card Production and Provisioning Physical and Logical Security Requirements defining standards for card manufacturing, transport, and personalization. Additionally, the Payment Card Industry Data Security Standard version 4.0 guides organizations on card data handling and compliance, a critical consideration for any firm integrating payment cards into their IT infrastructure.
Infrastructure costs also play a background role in the economics of payment processing. The American Society of Civil Engineers 2025 Infrastructure Report Card noted that deployment costs for broadband infrastructure increased over 10 percent with materials and labor as primary drivers. While this relates to physical infrastructure, it impacts the broader digital ecosystem supporting payment technologies. Furthermore, macro-level shifts are occurring, as highlighted by the McKinsey Global Payments Report in September 2025, which pointed to growing payment sovereignty initiatives in regions such as Europe and Brazil to reduce reliance on global intermediaries. This trend could influence network selection and localization strategies for multinational corporations.
Segmentation Dynamics and Application Scenarios
Understanding where the revenue is generated is key to allocating resources effectively. Our research delves deep into the segmentation of the market by type and application, revealing distinct growth drivers within each category. The market is segmented by type into Credit Cards, Debit Cards, and Prepaid Cards. Credit cards continue to hold a substantial portion of the market value, reflecting their utility in managing cash flow and earning rewards, while Debit Cards offer a controlled spending mechanism linked directly to funds. Prepaid Cards also represent a significant segment, often utilized for specific budgeting purposes or employee allowances.
From an application perspective, the divide between Large Business Cards and Small Business Cards illustrates the diverse needs across the corporate spectrum. Large Business Cards constitute a major share of the application market, driven by high-volume procurement and complex travel requirements. Small Business Cards, while representing a smaller total revenue share compared to the enterprise segment, are witnessing heightened innovation and competitive pressure from issuers like Engine looking to capture the SME market. Our report provides granular analysis of how these segments interact with regional dynamics and type preferences without exposing the specific numerical splits that constitute our core proprietary intelligence.
Geographic distribution also plays a pivotal role in strategy formulation. The market serves key regions including North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique regulatory environments, adoption rates, and competitive intensities. For instance, payment sovereignty trends may impact strategies in Europe and Latin America differently than in North America. Our analysis contextualizes these regional variations to help clients prioritize market entry or expansion efforts based on their specific risk tolerance and growth objectives.
The Strategic Value of Comprehensive Intelligence
Why does this level of detail matter for your 2026 planning? In a market projected to grow by over 130 billion USD between 2026 and 2032, the margin for error shrinks as competition intensifies. Access to detailed segmentation data, competitive profiling, and regulatory roadmaps allows organizations to move from reactive spending management to proactive financial strategy. Whether you are a issuer looking to refine your product portfolio, a corporate treasurer optimizing expense policies, or an investor assessing the viability of fintech ventures in the payments space, this report provides the foundational knowledge required to make informed decisions.
The report goes beyond high-level numbers to explore the operational realities faced by market participants. It examines how reimbursement dynamics, influenced by factors such as interchange fee structures, affect the total cost of ownership for corporate card programs. It also assesses how compliance with evolving security standards impacts procurement timelines and vendor selection. By synthesizing data on market concentration, company profiles, and recent developments, we offer a 360-degree view of the ecosystem.
Our analysis of key companies includes detailed profiles covering their headquarters, operational focus, and strategic moves. For example, understanding the focus of WEX on fleet and virtual payment cards versus Corpay's emphasis on corporate travel and expense programs helps tailor partnership or benchmarking strategies. Similarly, tracking the standardization efforts of bodies like X9 ensures that technology investments align with future-proof protocols.
Commercial Payment Cards Market
Unlock the Full Intelligence
The insights summarized here represent only the surface of the comprehensive intelligence available in the full PW Consulting Commercial Payment Cards Market Research. To truly leverage the 6.98 percent CAGR opportunity and navigate the complexities of a market reaching 364.76 billion USD by 2032, decision-makers need access to the complete dataset, detailed forecasts, and proprietary analytical models.
We invite you to access the source webpage to download the full report. There you will find the specific regional growth rates, detailed application segment valuations, and deep-dive competitive benchmarking that cannot be fully disclosed in this overview. Equip your team with the precise data needed to outperform in the evolving commercial payment landscape. Visit our report page today to secure your copy and start transforming market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Commercial Payment Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Market revenue for indoor air quality monitors in China demonstrates robust growth, rising from USD 520 Million in 2020 to an anticipated USD 2,120 Million in 2035. Key growth inflections are observed post-2025, attributed to technological advancements, policy boosts, and increased user awareness. This upward trajectory reflects both expanded consumer base penetration and upgrades within commercial and government facilities, indicating sustained value creation for stakeholders in the coming decade.
Read More - https://bussinessinsights.com/research-report/china-indoor-air-quality-monitor-market
The residential sector leads the indoor air quality monitor market in China for 2025, reflecting the increased consumer priority on health and safety within homes. The commercial segment, encompassing offices, malls, and retail, follows closely as businesses aim to create healthier workspaces and meet regulatory requirements. Industrial and institutional usage is rising in line with stricter occupational health standards and corporate sustainability initiatives. This segmentation underlines the diversified deployment of IAQ monitors beyond just residential use, signaling market maturity and wider acceptance amid different end-users.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-indoor-air-quality-monitor-market
Frequently Asked Questions
Who are the key players in China Indoor Air Quality Monitor Market industry?
The top five players in the China indoor air quality monitor market include Thermo Fisher Scientific, Siemens AG, Honeywell International, Aeroqual, and Qingdao Tianer. These companies are recognized for their advanced technologies, strong distribution networks, innovative product ranges, and commitment to research and development in environmental monitoring solutions.
What is the China Indoor Air Quality Monitor Market growth?
The China indoor air quality monitor market has experienced robust growth in recent years, driven by increasing public health awareness and strict government regulations. For instance, in 2023, Honeywell reported increased demand for its smart air quality monitoring devices amid rising urbanization and concerns over particulate pollution.
Which segment accounted for the largest China Indoor Air Quality Monitor Market share?
The commercial segment held the largest market share in the China indoor air quality monitor market. Offices, shopping malls, schools, and hospitals are increasingly adopting air quality monitoring systems to ensure healthy indoor environments and compliance with government standards, thus driving significant demand in this application area.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The global mobile antivirus market is poised for robust revenue growth, projected from $5,800 Million in 2020 up to $21,550 Million by 2035. The compounded growth rate is fueled by increased cyber risks, enterprise digitization, and expansion into underserved markets. Post-pandemic digital adoption and regulatory compliance particularly contributed to steep rises between 2023-2025, with the forecast period showing steady gains as advanced technologies become mainstream and user awareness deepens.
Read More - https://bussinessinsights.com/research-report/global-mobile-antivirus
In 2025, Android maintains dominance in the mobile antivirus application market, largely due to its vast global user base and the higher frequency of malware attacks targeting the platform. iOS appeals to users seeking robust but lightweight protection, given iOS’s built-in security but rising phishing threats. Other platforms, including Windows, Blackberry, and Symbian, have a much smaller share as their presence in the global handset market declines. Security vendors continue to focus R&D on Android while enhancing cross-platform compatibility.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-mobile-antivirus
Frequently Asked Questions
Who are the key players in Global Mobile Antivirus industry?
The top 5 players in the Global Mobile Antivirus industry are Avast, McAfee, Kaspersky Lab, NortonLifeLock (Norton), and Bitdefender. These companies provide comprehensive mobile security solutions, including malware detection, real-time protection, and privacy features, both for Android and iOS devices. Their global reach ensures robust competitive influence.
What is the Global Mobile Antivirus growth?
The Global Mobile Antivirus market has witnessed significant growth, with a CAGR exceeding 10% in recent years. Companies like Avast reported increased adoption due to rising mobile threats and increased smartphone usage. Market expansion is fueled by enterprise mobility trends and heightened consumer awareness about mobile cybersecurity.
Which segment accounted for the largest Global Mobile Antivirus share?
The consumer application segment accounted for the largest share in the Global Mobile Antivirus market. Due to a surge in mobile device usage and the rising threat of personal data theft, end-users are increasingly installing antivirus apps for personal protection, driving higher adoption rates in this application area.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The market has experienced exponential revenue growth from 2020 to 2025, with total revenue rising from $850 million in 2020 to $2,430 million in 2025. Future revenue is projected to reach $13,400 million by 2035, marking a compound annual growth rate exceeding 19% over the period. This trajectory is fueled by significant advancements in SiC device manufacturing, widespread EV adoption, and the accelerating deployment of renewable energy worldwide.
Read More - https://bussinessinsights.com/research-report/global-sic-inverter
Electric vehicles represent the leading application for SiC inverters in 2025, making up 38% of market share as automakers scale production of EVs globally. Renewable energy systems, including solar and wind, account for 27%, fueled by aggressive renewable installation targets. Industrial motor drives comprise 15%, reflecting ongoing automation and electrification trends, followed by rail traction at 9%, power supplies 7%, and other applications at 4%. The increasing emphasis on energy efficiency and emission reductions in mobility and energy sectors continues to drive robust demand.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-sic-inverter
Frequently Asked Questions
Who are the key players in Global SiC Inverter industry?
The top 5 players in the Global SiC Inverter industry are Infineon Technologies, Mitsubishi Electric, ON Semiconductor, Fuji Electric, and ROHM Semiconductor. These companies are recognized for their advanced SiC technology, wide portfolio of inverter products, and strong market presence across automotive, industrial, and renewable energy applications.
What is the Global SiC Inverter growth?
The Global SiC Inverter market is experiencing rapid growth, driven by rising electric vehicle adoption and renewable energy initiatives. For example, Infineon Technologies reported significant growth in SiC inverter sales in 2023, attributing it to increased EV production and the shift towards more efficient power electronics.
Which segment accounted for the largest Global SiC Inverter share?
The automotive segment accounted for the largest share of the Global SiC Inverter market. The demand for high-efficiency inverters in electric vehicles, especially for traction inverters, has surged as automakers like Tesla and BYD integrate SiC-based solutions to enhance performance and range.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Compact Construction Equipment Market to Reach $311M by 2032, Growing at 5.1% CAGR
By PW Consulting, 2026-09-16
Compact Construction Equipment Market: Strategic Intelligence for 2026 Decision-Makers
The compact construction equipment sector is entering a phase of transformative acceleration, driven by shifting labor dynamics, stringent regulatory frameworks, and rapid technological integration. For enterprise leaders, procurement strategists, and market development teams, the operational environment in 2026 demands more than surface-level awareness. It requires granular, forward-looking intelligence capable of informing capital allocation, product positioning, and competitive response. Our latest comprehensive research report on the Compact Construction Equipment Market delivers precisely this intelligence, translating historical trajectories and forward forecasts into actionable strategic playbooks for the 2026 fiscal landscape and beyond.
The Macro Trajectory: From Recovery to Sustained Expansion
Over the past half-decade, the compact equipment segment has demonstrated remarkable resilience, evolving from post-pandemic supply chain recalibration into a structurally expanding market. The addressable revenue base has grown consistently, reflecting sustained demand across construction, infrastructure, and specialized industrial applications. This growth trajectory is not merely cyclical; it is underpinned by fundamental shifts in how site work is executed, how fleets are optimized, and how operators are trained. With a projected compound annual growth rate of 5.1 percent across the forecast horizon extending to the early 2030s, the market is poised to surpass the 300 million dollar threshold, representing a meaningful expansion from its mid-2020s baseline.
This macro progression masks critical inflection points that will define competitive positioning throughout 2026 and the subsequent years. Understanding where volume is accumulating, how pricing power is shifting among equipment classes, and which operational bottlenecks are reshaping procurement cycles requires a disciplined analytical framework. Our report constructs that framework, offering enterprise teams a structured vantage point from which to evaluate market entry, product portfolio expansion, and commercial strategy.
Market Structure and Competitive Realities in 2026
The competitive architecture of the compact equipment landscape is defined by a concentrated yet highly dynamic environment. Leading manufacturers have entrenched strong market share, with the top three and top five players collectively commanding substantial portions of total industry revenue. This concentration reflects decades of brand equity, distribution network maturity, and service infrastructure investment. Yet, within this consolidated top tier, a wave of strategic repositioning is underway, particularly as electrification, smart automation, and regional market penetration converge to reshape competitive boundaries.
Established industrial leaders continue to leverage their scale, engineering heritage, and financing ecosystems to reinforce their standing. Their compact offerings span tracked loaders, skid steers, and mini excavators, each engineered for versatility across general construction, landscaping, utility work, and material handling. Financing incentives, including promotional terms structured through mid-2026, are actively deployed to stimulate fleet acquisition and lower procurement barriers for contractors and rental operators. At the same time, legacy manufacturers are recalibrating product roadmaps to address evolving operator expectations and compliance mandates.
Compact Construction Equipment Market
Construction Equipment Market
Simultaneously, emerging entrants and regional manufacturers are intensifying their competitive presence. Korean equipment groups, for instance, have been aggressively expanding their compact construction and demolition equipment portfolios, emphasizing hands-on demonstrations, customizable job-site configurations, and brand-led North American market entry strategies. These organizations are signaling long-term commitment through trade show participations, product unveilings, and operational demonstrations designed to capture the attention of procurement teams seeking differentiated value propositions.
Product Innovation and the Strategic Imperative of Electrification
Equipment innovation in the compact segment is no longer a peripheral development track; it is a central driver of commercial differentiation. Recent industry showcases have highlighted a clear pivot toward next-generation smart and automated compact equipment, with manufacturers unveiling concept platforms, enhanced operator-assist technologies, and streamlined mechanical architectures. Electrically powered models are increasingly prominent, reflecting both regulatory tailwinds and end-user demand for quieter, zero-emission site operations. Mini excavator lineups, in particular, have seen notable advancements in chassis engineering, control precision, and modular customization capabilities.
For corporate strategy teams, these product developments carry direct implications. Fleet electrification planning, service network readiness, battery lifecycle considerations, and operator training reconfiguration all intersect with procurement timing and total cost of ownership models. Our analysis dissects these innovation trajectories, mapping them against adoption curves, segment-specific demand patterns, and regional compliance timelines to help decision-makers anticipate where competitive advantage will be captured in the near term.
Regulatory Shifts, Labor Dynamics, and Supply Chain Headwinds
The operational environment for compact equipment operators is being reshaped by intersecting external forces. In Europe, the revised Construction Products Regulation has taken full effect, introducing stricter sustainability and digital compliance requirements that reverberate through equipment specifications, documentation, and certification workflows. Across North America, regional energy codes and space conditioning mandates are altering equipment specification standards, placing renewed emphasis on efficiency-aligned machinery and compliant operational configurations.
Concurrently, labor market realities continue to exert pressure on construction operations. Skilled labor shortages persist, accelerating the adoption of compact equipment that reduces training time, simplifies site workflows, and integrates automation features capable of compensating for workforce constraints. This labor-driven demand signal reinforces the strategic value of compact machinery as a productivity multiplier rather than a mere capacity substitute.
On the supply side, material cost volatility remains a persistent concern. Fluctuations in steel and aluminum pricing, influenced by tariff structures and trade tensions, continue to impact manufacturing margins, inventory planning, and lead-time reliability. At the same time, engineering adaptations such as the incorporation of high-strength steel and advanced alloys in booms and chassis are improving durability and extending service intervals, partially offsetting input cost pressures through performance gains. These interconnected dynamics require scenario-aware planning, and our report structures this complexity into clear strategic considerations for procurement, production, and distribution leadership.
What follows is a curated overview of the analytical depth contained within our full market research publication. The sections below illustrate how each dimension of the study is designed to support concentrated decision-making in 2026.
In-Depth Market Sizing, Segmentation, and Forecast Architecture
Our research constructs a multi-layered sizing and forecasting model that traces historical performance and projects forward market evolution across the defined forecast period. Rather than presenting a single top-line figure, the report decomposes market structure across equipment classifications, application domains, and geographic footprints, enabling stakeholders to identify where volume concentration is strongest and where growth acceleration is most pronounced. Each segmentation layer is examined through the lens of operational relevance, allowing readers to evaluate how product mix decisions, regional expansion initiatives, and application-specific demand signals will interact throughout the planning horizon.
The forecast architecture accounts for base-year baselines, historical trend calibration, and forward projections that incorporate demand elasticity, regulatory pacing, and technology adoption curves. By aligning forecast outputs with strategic planning cycles, enterprise teams can stress-test portfolio assumptions, evaluate market entry timing, and model revenue scenarios with greater precision. The complete segmentation datasets, regional volume distributions, application-level revenue splits, and equipment-class breakdowns are detailed within the full report, providing the quantitative foundation required for board-level presentations, capital planning, and commercial forecasting.
Competitive Intelligence and Strategic Move Analysis
Understanding competitive positioning requires more than a roster of key players. It demands a structured assessment of where manufacturers are deploying capital, how they are differentiating product lines, and which commercial tactics are reshaping buyer behavior. Our competitive analysis maps the strategic activity of leading organizations across the compact equipment ecosystem, examining product specialization, geographic focus, financing programs, and demonstration-driven market engagement.
Analysis covers organizations with broad compact equipment portfolios as well as those executing targeted regional expansions and product launches. The report evaluates how manufacturers are aligning their offerings with application-specific requirements, how they are leveraging trade events and hands-on demonstrations to accelerate adoption, and how new model introductions are influencing competitive pressure points. Recent product unveilings, trade show activations, and electrification-focused launches are contextualized within broader market dynamics, allowing readers to distinguish between tactical visibility and structurally significant strategic moves.
This competitive mapping is designed to support benchmarking, identify white-space opportunities, and inform partnership or distribution strategy decisions. Full competitive profiles, recent development timelines, product positioning summaries, and strategic implication analyses are documented comprehensively within the complete publication.
Operational Dynamics, Risk Factors, and Strategic Response Frameworks
Effective market strategy requires an integrated view of external pressures and internal capability adjustments. Our report synthesizes the most consequential operational dynamics shaping the compact equipment sector, translating regulatory, labor, and supply-chain developments into actionable response frameworks. Rather than treating these factors as isolated constraints, the analysis positions them as interconnected variables that collectively influence pricing strategy, inventory management, product specification decisions, and regional market prioritization.
Labor-driven productivity requirements, compliance deadlines, raw material cost exposure, and material innovation trends are examined as strategic inputs rather than background noise. The report outlines how organizations can structure procurement timing, service readiness, and product mix adjustments to navigate these pressures while preserving margin integrity and market responsiveness. Scenario-based considerations are embedded throughout, helping leadership teams prepare for divergent operating environments and make calibrated decisions under uncertainty.
Why This Research Matters for 2026 Strategic Planning
As market participants navigate a landscape defined by concentrated competition, accelerating product innovation, evolving compliance mandates, and persistent operational constraints, the cost of incomplete information is rising. Strategic decisions made in 2026 will have compounding effects on fleet positioning, regional growth trajectories, and competitive resilience through the remainder of the decade. Access to structured, forward-looking intelligence is therefore not a supplementary advantage but a foundational requirement.
Our Compact Construction Equipment Market research is engineered to serve as that foundation. It consolidates historical context, forecast modeling, competitive mapping, regulatory analysis, and operational dynamics into a unified decision-support resource. The complete report enables leadership teams to move beyond high-level market awareness and into precise, evidence-based strategy formulation. For organizations seeking to refine procurement roadmaps, evaluate product portfolio expansion, benchmark against rival moves, or identify high-opportunity segments and regions, the full publication provides the depth and clarity necessary to act with confidence.
The complete dataset, extended segmentation breakdowns, detailed competitive profiles, and forward scenario analyses are available in the full report. Explore the complete intelligence package to align your 2026 strategy with the structural realities shaping the compact construction equipment market.
For detailed analysis of this topic, please visit the official page: Compact Construction Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global multi-joint robot market demonstrates robust revenue growth from 2020 through 2035. Valued at approximately $7,800 million in 2025, the market is projected to reach $22,450 million by 2035, reflecting the accelerating pace of industrial automation and adoption across new sectors. Year-over-year gains are powered by technological advancements, lower implementation costs, and expanding applicability in both developed and developing markets. The forecasted trajectory indicates sustained momentum as manufacturers continue to prioritize automation for efficiency, resilience, and competitiveness.
Read More - https://bussinessinsights.com/research-report/global-multi-joint-robots
Automotive remains the leading application segment for multi-joint robots worldwide in 2025, comprising 28% of the total market due to established automation practices in vehicle manufacturing. Electrical & electronics follows closely, accounting for 25%, driven by surging demand for precise assembly in high-volume production lines. Metals & machinery, plastics & chemicals, and food & beverages round out the top segments, highlighting the broadening utilization of robotics technology beyond traditional manufacturing. The diversification of robot use cases into new verticals speaks to the ongoing optimization and versatility offered by multi-joint platforms, with future growth expected in food, healthcare, and logistics.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-multi-joint-robots
Frequently Asked Questions
Who are the key players in Global Multi-joint Robots industry?
The top five players in the Global Multi-joint Robots industry include FANUC, ABB, YASKAWA, KUKA, and Kawasaki. These companies are pioneering in robotics technology and offer advanced multi-joint robots for a variety of industrial applications, maintaining robust global presence, innovation leadership, and comprehensive service networks.
What is the Global Multi-joint Robots growth?
The Global Multi-joint Robots market has witnessed steady growth, driven by rising automation adoption, especially in automotive and electronics sectors. In 2023, FANUC reported double-digit sales growth due to increased demand for flexible automation solutions, highlighting robust market expansion.
Which segment accounted for the largest Global Multi-joint Robots share?
The automotive segment accounted for the largest share in the Global Multi-joint Robots market, fueled by high demand for precision assembly, welding, and painting. Automakers worldwide rely on multi-joint robots for efficient production lines, with top manufacturers continually expanding their automotive robotics portfolios.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Automatic Pool Cleaning Equipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The market has shown a robust upward trajectory, with global revenue rising from $1,500 million in 2020 to an estimated $2,350 million in 2025. The sustained growth is attributed to evolving consumer preferences, increasing pool construction, and greater penetration of smart and energy-efficient equipment. With continuous innovation and geographical expansion, the market is expected to surpass $4,550 million by 2035, demonstrating a strong CAGR and underscoring its resilience and capacity for innovation.
Read More - https://bussinessinsights.com/research-report/global-automatic-pool-cleaning-equipment
Residential segment dominates the market in 2025, capturing the largest share, driven by increasing adoption among homeowners seeking automated cleaning solutions for their pools. Commercial applications, including hotels and sports complexes, are also significant contributors, spurred by the need for efficient, hygienic, and cost-effective pool maintenance. Public and specialty facilities constitute a smaller yet notable portion, reflecting institutional modernization and health regulations enforcement.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-automatic-pool-cleaning-equipment
Frequently Asked Questions
Who are the key players in Global Automatic Pool Cleaning Equipment industry?
The top five players in the global automatic pool cleaning equipment industry are Maytronics, Zodiac Pool Systems, Pentair, Hayward Industries, and Waterco. These companies lead the market with advanced robotic technologies, extensive product portfolios, reliable after-sales support, and strong international presence to meet the growing demand for automated pool maintenance.
What is the Global Automatic Pool Cleaning Equipment growth?
The global automatic pool cleaning equipment market has seen robust growth, with a CAGR of around 7% from 2021 to 2024. Factors like increasing adoption of smart and energy-efficient pool cleaners, spearheaded by companies such as Maytronics and Hayward, have driven recent industry expansion.
Which segment accounted for the largest Global Automatic Pool Cleaning Equipment share?
The residential application segment accounted for the largest share in the global automatic pool cleaning equipment market. Growing urbanization and increased spending on home leisure amenities have fueled demand. Manufacturers like Zodiac Pool Systems target residential users with innovative robotic pool cleaners, boosting this segment's dominance.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Visual Effects Services Market to Reach $344.8M by 2032, Growing at 7.12% CAGR from 2026-2032
By PW Consulting, 2026-09-16
The Visual Effects Services Market in 2026: Strategic Intelligence for Enterprise Decision-Making
Navigating a Transformative Era in Visual Storytelling
The global Visual Effects Services Market has entered a defining phase where artistic ambition, technological acceleration, and financial engineering converge. As production pipelines evolve and audience expectations shift toward immersive, photorealistic storytelling, enterprises across film, television, gaming, and advertising must look beyond creative intuition and ground their strategies in rigorous market intelligence. This new research publication from PW Consulting provides a comprehensive, data-driven examination of the Visual Effects Services Market, offering executives a strategic blueprint for navigating the opportunities and pressures that will shape the industry through the end of the decade.
The market has demonstrated consistent momentum across the historical review period, reflecting sustained demand for high-end visual content and expanding investment in digital production capabilities. Our analysis traces this trajectory from 2020 through the base year of 2025, capturing the structural shifts that have redefined competitive positioning, service delivery models, and revenue generation across the sector. The data underscores a market that has not merely grown but fundamentally restructured itself around new workflows, platform diversification, and the integration of advanced computation into creative processes.
For enterprise leaders, the critical question is no longer whether visual effects will play a central role in content strategy, but how to allocate capital, select partners, and position operations in a landscape characterized by rapid technological change, evolving incentive frameworks, and intensifying competition for specialized talent. This research is designed to answer that question with precision, offering actionable intelligence that supports investment planning, vendor selection, geographic expansion, and long-term portfolio management.
Forecasting Framework: Aligning 2026 Decisions with the 2026–2032 Outlook
The forecast period covered in this report spans from 2026 through 2032, a window that coincides with pivotal developments in production technology, distribution economics, and regulatory incentives. By anchoring strategic planning in a disciplined forward-looking framework, organizations can anticipate demand shifts, assess the ROI of capability investments, and identify the inflection points where competitive advantage will be won or lost.
The report integrates historical demand patterns with forward projections to deliver a coherent view of market evolution. This approach enables decision-makers to stress-test assumptions against multiple scenarios, evaluate the timing of capacity expansions, and understand how macro-level growth translates into sector-specific opportunities. Rather than presenting growth as a monolithic trend, the analysis disentangles the underlying drivers—content volume, platform fragmentation, technological adoption, and regional production migration—to reveal where value is being created and how it is likely to redistribute over time.
Strategic alignment with this forecast horizon is essential for organizations that must commit resources today to capabilities that will mature over the next several years. Whether the objective is to internalize certain production functions, form strategic alliances with specialized vendors, or reallocate budget toward higher-value service tiers, the report provides the contextual foundation needed to make those choices with confidence. The emphasis throughout is on decision relevance: every dataset, every segmentation lens, and every competitive observation is framed to support operational and financial planning in the current fiscal cycle and beyond.
Report Architecture: Operational Depth Across Segments, Competition, and Dynamics
To support rigorous strategic analysis, this research is structured around a set of operational modules that together provide a complete picture of the market environment. The segmentation framework examines the market through multiple dimensions, allowing readers to isolate the demand characteristics, service configurations, and growth profiles that are most relevant to their specific business context. By analyzing the market across type-based and application-based lenses, the report illuminates how different service categories and end-use channels contribute to overall demand patterns and where structural advantages are emerging.
The regional dimension of the analysis adds further granularity, mapping how production activity, vendor ecosystems, and incentive environments vary across major geographic corridors. This regional perspective is particularly valuable for organizations evaluating location strategy, outsourcing partners, or international expansion, as it surfaces the interplay between local production capacity, talent availability, and policy support. Importantly, the report maintains a disciplined focus on strategic interpretation rather than exhaustive enumeration, ensuring that the data serves decision-making rather than overwhelming it.
Complementing the segmentation analysis is a detailed competitive landscape assessment that profiles the leading operators shaping the market. The research examines the positioning, capability strengths, and strategic moves of prominent firms, including Industrial Light & Magic, Weta Digital, Framestore, DNEG, Pixomondo, Animal Logic, Rodeo FX, Cinesite, Method Studios, Deluxe, Digital Domain, The Mill, and Scanline VFX. These profiles are not static company summaries; they are structured to reveal how each organization competes on technology, service breadth, artistic reputation, and operational scale, and how recent consolidation, investment, and partnership activity is reshaping the hierarchy.
The report also incorporates a dedicated dynamics module that captures the forces currently redefining market behavior. This includes an examination of labor cost structures and talent availability, with attention to median compensation levels and employment growth trajectories for visual effects artists and animators in the context of sustained demand across gaming, film, and television. The regulatory landscape receives equal attention, with analysis of incentive programs and policy initiatives that are actively influencing production location decisions and cost structures. Recent developments illustrate how these forces are unfolding in real time, including significant investment activity, acquisitions that consolidate animation and VFX operations, award-recognized creative campaigns, and organizational rebranding efforts that reflect evolving workflow integration.
By integrating these content streams, the report functions as both a reference document and a planning tool. Readers will find a clear path from high-level market context to granular operational insight, enabling them to draw connections between market structure, competitor behavior, and their own strategic priorities.
Competitive Intensity and Strategic Positioning in a Consolidating Landscape
The competitive environment in the Visual Effects Services Market is characterized by a combination of creative differentiation, technological capability, and ongoing consolidation. With a moderately concentrated market structure, the leading firms compete not only on artistic quality but also on their ability to deliver end-to-end solutions that span visual effects, animation, virtual production, and post-production support. This breadth of capability has become increasingly important as producers seek to streamline workflows, reduce integration risk, and maintain consistency across complex, multi-platform projects.
Several of the most prominent operators have pursued strategic moves that signal how they intend to strengthen their competitive position. Investment activity has provided selected companies with the capital to expand technology pipelines, deepen AI-driven workflows, and scale content production capacity. Acquisitions have been used to consolidate complementary capabilities, particularly where animation and visual effects operations can be integrated to offer more complete service offerings. At the same time, high-profile creative recognition continues to serve as a powerful differentiator, reinforcing brand equity and attracting premium client relationships.
For enterprise buyers and investors, this dynamic landscape raises important questions about vendor stability, service continuity, and the long-term implications of consolidation. The report addresses these concerns by evaluating how recent transactions and investments are likely to affect pricing, capacity, and service specialization. It also examines how firms are positioning themselves around emerging capability areas, including simulation, creature work, motion capture, immersive media, and AI-assisted production. Understanding these strategic vectors is essential for organizations that must select partners capable of supporting both current production needs and future content ambitions.
Regulatory and Cost Dynamics: Incentives, Labor, and Operational Strategy
Market behavior in the Visual Effects Services Market is increasingly shaped by the interaction between labor economics and policy incentives. On the labor side, specialized creative and technical roles command significant compensation, and employment growth in animation and visual effects is projected to remain positive over the coming decade, driven by ongoing demand across entertainment and interactive media. This sustained demand places pressure on talent availability and reinforces the strategic importance of workforce planning, retention, and productivity-enhancing technology adoption.
Worldwide CG Visual Service Market
At the same time, a range of incentive programs is actively reshaping where and how visual effects work is performed. Recent policy developments have expanded or clarified credit structures in key production markets, giving producers new options for optimizing cost structures while maintaining access to high-quality service providers. In some jurisdictions, tax credit frameworks have been updated to increase eligible spend or streamline application and audit processes, reducing administrative friction and making incentive capture more predictable. In others, advocacy efforts are pushing for standalone post-production incentives that would better align support with the specific economics of visual effects work.
Visual Effects Services Market
These dynamics create both opportunities and risks for enterprises. Advantages can be gained by aligning production footprints with favorable incentive environments, but such strategies must be balanced against considerations of talent quality, vendor capability, delivery timelines, and long-term relationship strength. The report provides a structured examination of these trade-offs, helping decision-makers evaluate how regulatory and cost factors should inform location strategy, vendor selection, and budget allocation. Rather than treating incentives as isolated financial benefits, the analysis situates them within the broader operational context in which content is produced and delivered.
Strategic Imperatives for 2026 and Beyond
As enterprises move through 2026, the most successful organizations will be those that treat visual effects not as a discretionary enhancement but as a core component of content strategy and operational planning. That shift requires a clear understanding of where the market is heading, which capabilities will command premium value, and how competitive and regulatory forces will influence cost and access over time. This research is designed to provide that understanding in a form that can be directly applied to investment decisions, partnership strategies, and organizational planning.
Among the strategic imperatives highlighted in the report are the need to evaluate vendor partners against long-term capability roadmaps rather than short-term project requirements, the importance of monitoring consolidation and investment activity for signals about market concentration and service availability, and the value of integrating incentive and labor considerations into location and sourcing decisions from the outset. The report also emphasizes the growing relevance of technology adoption, particularly where advanced workflows can improve efficiency, quality, and scalability without compromising artistic integrity.
For executives seeking to translate market intelligence into action, the full study offers a more detailed evidentiary base, including deeper segmentation analysis, competitive profiling, and scenario-based interpretation of demand drivers. The complete research package is available through the source publication, where readers can access the full range of data, analysis, and strategic recommendations that support enterprise decision-making across the 2026–2032 horizon.
In a market defined by rapid change and high creative stakes, disciplined intelligence is the foundation of confident strategy. This report provides the context, structure, and insight needed to make that strategy durable, responsive, and aligned with the realities of the Visual Effects Services Market as it enters its next phase of growth.
For detailed analysis of this topic, please visit the official page: Visual Effects Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com