

Blogs
PW Consulting: Espresso Market Hits $16.17 Billion in 2025, 5.7% CAGR to 2032
By PW Consulting, 2026-09-16
Executive Preview: Navigating the Espresso Coffee Market in 2026 and Beyond
The global espresso coffee market stands at a pivotal inflection point. As consumer preferences shift towards premiumization, convenience, and sustainability, stakeholders across the value chain require a precise navigation tool to separate transient trends from structural growth drivers. PW Consulting's latest comprehensive market research on the Espresso Coffee Market offers exactly that: a data-backed strategic compass designed for enterprise decision-makers operating in a complex, high-growth environment.
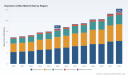
This market study, anchored in a rigorous historical analysis spanning 2020 to 2025 and projecting forward through the 2026 to 2032 forecast period, provides an unvarnished look at the revenue dynamics shaping one of the world's most beloved beverage categories. With total market revenue valuation expanding from approximately 12.26 billion USD in the base year of 2020 to a projected 23.84 billion USD by 2032, the trajectory is unmistakable. The intervening years tell a story of resilient demand, with revenue climbing to 14.5 billion USD in 2023 and further to 14.93 billion USD in 2024, before reaching an estimated 16.17 billion USD in 2025. Our forecast models project this momentum to sustain, with the market advancing to 16.95 billion USD in 2026 and scaling toward 18.36 billion USD in 2027. The compound annual growth rate over the forecast horizon is calculated at 5.7 percent, signaling steady, compounding expansion rather than volatile spikes.
Espresso Coffee Market
For corporate strategists, regional directors, and investment committees, this report serves as a critical intelligence asset. It moves beyond superficial headline figures to interrogate the underlying mechanics of growth, competitive positioning, and structural headwinds. What follows is a curated overview of the analytical depth, practical utility, and market context contained within this publication.
A Multi-Dimensional Analytical Framework
The research is structured to deliver actionable clarity across the primary axes that govern strategic planning. Rather than presenting a flat revenue projection, the study disaggregates the market along dimensions that directly inform operational priorities, product portfolio decisions, and market entry strategies. The segmentation architecture examines value distribution across geographic territories, product typologies, and consumption application channels. Each segment is contextualized with demand drivers, saturation indicators, and growth velocity differentials, enabling readers to identify where capital deployment will yield the highest marginal returns.
Our analysis of the product landscape distinguishes between the hardware and consumables dynamics that define the category. The equipment dimension encompasses espresso machines, where precision engineering, durability, and feature sets drive procurement cycles across both residential and commercial environments. The beverage dimension captures the recurring revenue streams associated with espresso-based products, where brand loyalty, formulation quality, and packaging innovation dictate share shifts. By mapping the interplay between these two pillars, the report highlights cross-segment opportunities, such as bundled equipment-and-consumable offerings, subscription models, and white-label partnerships.
Equally critical is the application-channel perspective. The market bifurcates into at-home consumption and commercial outlets, each governed by distinct purchasing behaviors, price elasticity thresholds, and distribution architectures. Home consumption continues to benefit from lifestyle shifts that prioritize café-quality experiences in domestic settings, while commercial venues navigate a post-pandemic operational landscape characterized by labor optimization, throughput demands, and experiential differentiation. The study dissects these channels with granularity, identifying sub-segments where margin structures diverge and where infrastructure investments must be calibrated to local competitive intensity.
Geographically, the report maps revenue footprints across all major regions, providing a comparative view of market maturity, growth acceleration, and structural entry barriers. Decision-makers gain insight into which territories are exhibiting relative under-penetration versus those approaching saturation, allowing for differentiated go-to-market playbooks. Whether evaluating sourcing strategies, distribution network expansion, or localized product adaptation, the geographic intelligence herein supports evidence-based resource allocation.
Espresso Machines Market
Competitive Dynamics and Strategic Positioning
Concentration is a defining feature of this category. The top three participants command a combined market share of 57.3 percent, while the top five hold 68.4 percent of total industry revenue. This level of concentration indicates that scale advantages, brand equity, and distribution infrastructure confer significant defensive moats, yet it also signals that targeted disruptors can capture meaningful share by exploiting niche demand or delivery innovation. Our report profiles the leading incumbents in detail, examining their headquarters bases, core competencies, and strategic postures.
Nespresso, headquartered in Switzerland, operates as a specialized provider of espresso coffee pods and machines, with a pronounced focus on premium espresso extraction and a subscription-integrated revenue model. Starbucks Corporation, based in the United States, remains a major provider of ready-to-drink and at-home espresso-based beverages and equipment, leveraging its global retail footprint to anchor brand presence across multiple consumption occasions. Luigi Lavazza S.p.A., an Italian producer, emphasizes high-quality Arabica in its espresso bean, capsule, and machine portfolio, catering to consumers who prize origin character and consistency. Illycaffè, also based in Italy, specializes in single-origin espresso beans and professional-grade equipment optimized for espresso brewing, positioning itself at the intersection of authenticity and performance.
Peet's Coffee, headquartered in the United States, supplies espresso roast beans and ready-to-drink espresso drinks, maintaining a strong foothold in segments that value intensity and roast-forward flavor profiles. Rocket Espresso, an Italian manufacturer, produces commercial and professional espresso machines and grinders certified for precise espresso extraction, serving operators who demand repeatability and technical fidelity. OutIn, an Italian producer, has gained traction with portable electric espresso machines designed for on-the-go espresso brewing, reflecting the growing consumer appetite for mobility and convenience. Flair Espresso, based in the United States, manufactures manual lever espresso machines and accessories for home and professional espresso preparation, appealing to enthusiasts and baristas who prioritize tactile control. Eversys, headquartered in Italy, develops compact professional espresso machines with automated menus for versatile espresso-based beverages, addressing the operational efficiency needs of high-volume environments.
Beyond firm-level profiles, the research systematically tracks recent competitive moves that recalibrate the market. In May 2026, OutIn executed a global debut of the Cup of OutIn and participated in the World of Coffee San Diego 2026 with dual booths, reinforcing its commitment to portability and consumer-facing visibility. Also in May 2026, Rocket Milano s.r.l. launched the Gravo Grinder, featuring grind-by-weight technology and a single-shot mode, an advancement that signals intensifying engineering competition at the professional equipment tier. In April 2026, Flair Espresso introduced the Flair 49 Pro manual espresso machine with a 49mm portafilter and stainless brew path, illustrating continued innovation in the manual segment. Earlier in March 2026, Nguyen Coffee Supply launched its first product, Ground Espresso, sourced and roasted in Vietnam, demonstrating how origin diversification is opening new flavor and sourcing narratives in the espresso market.
These developments are not isolated product announcements; they are indicators of where competitive intensity is concentrating and which attribute sets are gaining currency among buyers. The report's competitive analysis integrates these events into a wider assessment of share dynamics, partnership opportunities, and threat vectors, enabling leadership teams to anticipate rather than react.
Macroeconomic and Operational Backdrop
No strategic assessment is complete without anchoring market projections in the material conditions that influence cost structures, supply reliability, and regulatory compliance. Our research synthesizes the latest external intelligence to frame the operating environment with precision and foresight.
On the raw material front, coffee commodity pricing and crop expectations directly affect input costs for roasters, capsule manufacturers, and beverage producers. The International Coffee Organization reported that the ICO Composite Indicator Price averaged 266.24 US cents per pound in April 2026, a 2.7 percent decrease from March 2026. This moderation in pricing provides temporary relief on input costs, but also requires producers to manage futures hedging and procurement timing carefully. Concurrently, the USDA Foreign Agricultural Service projected Brazil's 2026/27 coffee crop at a record 71.9 million bags, up 14 percent from 2025/26. A larger Brazilian harvest has implications for global supply adequacy, price volatility, and origin diversification strategies, particularly as buyers balance cost efficiency against quality and traceability expectations.
Regulatory developments are equally consequential. The European Union Deforestation Regulation mandates full supply-chain traceability for coffee imports by late 2025, compelling market participants to invest in provenance documentation, supplier audits, and digital traceability platforms. Organizations that proactively build compliance capabilities will mitigate disruption risk, while those that defer face potential shipment delays, reputational exposure, and market access constraints. In parallel, the U.S. Food and Drug Administration does not require a Nutrition Facts label for plain roasted coffee beans, a regulatory distinction that affects labeling strategy, consumer communication, and product differentiation in jurisdictions where transparency expectations are rising.
Operational standards further shape the competitive landscape. The Specialty Coffee Association Certified Espresso Machines program for 2025-2027 lists Rancilio, Faema, and LaCimbali as certified manufacturers, a designation that carries weight in commercial procurement decisions. Certification influences vendor selection in hospitality, office, and retail environments where reliability, service support, and performance consistency are non-negotiable. Our analysis incorporates these standards as qualitative filters that affect commercial-channel demand and equipment segment growth.
Practical Utility for Executive Decision-Making
This report is designed to be a working document, not a static snapshot. across its chapters, readers will find a suite of practical analytical tools that translate market intelligence into executable strategy. The segmentation breakdowns enable scenario planning by allowing teams to model revenue sensitivity under varying assumptions about channel mix, price points, and geographic penetration. The competitive profiling supports benchmarking exercises, revealing adjacencies for partnership, acquisition targets for capability enhancement, and whitespace opportunities for new product development.
The industry dynamics section provides a consolidated view of cost-side and compliance-side factors, helping procurement, supply chain, and legal teams align sourcing calendars, supplier contracts, and traceability investments with regulatory timelines and commodity cycles. This integration is critical for organizations that must balance margin protection with brand integrity and market access requirements.
Furthermore, the report's forward-looking forecast horizon, extending through 2032, supports investment committee deliberations by quantifying the durability of demand trends. Whether the objective is to size a new market entry, justify capital expenditure on equipment manufacturing capacity, or evaluate the long-term attractiveness of a regional distribution network, the modeling framework provides the evidentiary basis for confident decision-making. By distinguishing between cyclical fluctuations and secular shifts, the analysis reduces the risk of misallocating resources to short-lived opportunities.
Readers will also find strategic implications surfaced explicitly throughout the report. Where quality premiums are expanding, where convenience is trumping origin storytelling, where portable formats are cannibalizing traditional consumption occasions, and where professional-grade equipment certification is becoming a procurement prerequisite, the research offers interpretation and recommended posture. The goal is not merely to inform, but to equip leadership teams with a clear line of sight from market signal to strategic response.
Why This Research Matters in 2026
The current moment demands a disciplined, evidence-led approach to strategy. Consumer expectations are rising across taste, sustainability, and convenience simultaneously. Equipment buyers are demanding greater precision and automation. Regulators are tightening traceability requirements. Commodity markets are experiencing shifting harvest dynamics and price moderation that complicate procurement planning. In this environment, assumptions are expensive, and generic market narratives are insufficient.
PW Consulting's Espresso Coffee Market research delivers the granularity, contextualization, and forward lens required to navigate these complexities. Total revenue projections, growth rates, segmentation differentials, and competitive intelligence are woven together to create a coherent narrative that speaks directly to strategic priorities. The study is built for executives who need to justify investment decisions, align cross-functional teams, and respond to competitors with agility and foresight.
To access the complete dataset, detailed segmentation analysis, full competitor profiles, and the comprehensive forecast tables that underpin this preview, we invite you to visit the source webpage where the full report is available. The complete intelligence package extends far beyond the highlights presented here, offering the depth and precision your organization requires to act with confidence.
In an industry defined by both tradition and rapid innovation, informed strategy is the decisive advantage. This research provides the foundation for that strategy, and we look forward to equipping your team with the insights necessary to shape outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Espresso Coffee Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From 2020 to 2025, the digital scent technology market in China has witnessed a remarkable uptrend, growing from $160 million in 2020 to $420 million by 2025. Projected figures highlight sustained expansion, aiming to surpass $1,300 million by 2035, thanks to accelerated adoption in healthcare, food safety, and consumer electronics. Increased R&D investments and government support have also contributed to year-on-year revenue growth, positioning China as a pivotal global hub for scent technology development.
Read More - https://bussinessinsights.com/research-report/china-digital-scent-technology-market
Medical remains the most prominent application for digital scent technology in China, given the sector’s emphasis on innovation and diagnosis accuracy. Food & beverage ranks next, where scent-driven analytics help maintain competitive quality control. Marketing and entertainment applications see growing adoption as brands and content creators tap into multi-sensory engagement for consumers.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-digital-scent-technology-market
Frequently Asked Questions
Who are the key players in China Digital Scent Technology Market industry?
Top players in the China Digital Scent Technology Market include Airsense Analytics, Alpha MOS, Odotech Inc., Aromajoin Corporation, and Olorama Technology. These companies lead the market by providing advanced digital scent detection, e-nose systems, and scent delivery technology for a variety of applications including healthcare, environmental monitoring, and marketing.
What is the China Digital Scent Technology Market growth?
The China Digital Scent Technology Market has witnessed accelerated growth, driven recently by growing demand in smart devices and health diagnostics. For example, Alpha MOS reported an expansion in healthcare odor analysis solutions in late 2023, contributing to a market growth rate exceeding 10% annually.
Which segment accounted for the largest China Digital Scent Technology Market share?
The medical diagnostics application segment holds the largest share in the China Digital Scent Technology Market. With increased focus on non-invasive disease detection and air quality monitoring, hospitals and diagnostic centers are rapidly incorporating e-nose technology for fast and reliable results, further propelling segment growth.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Harmonic Filter Market: by Type (Passive Harmonic Filters, Active Harmonic Filters, Hybrid Harmonic Filters), Application (Industrial, Commercial, Residential, IT & Data Centers, Oil & Gas, Others), Distribution Channels (Direct Sales, Distributors & Resellers, Online, System Integrators, Specialty Stores, Others), Technology (Tuned Passive Filters, Detuned Passive Filters, Multi-Tuned Filters, Active Power Filters, Hybrid Filters, Others), Organization Size (Small, Medium, Large) and By China Historical & Forecast Period (2020-2035) Comprehensive Study 2025
Read More - https://bussinessinsights.com/research-report/china-harmonic-filter-market
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-harmonic-filter-market
Frequently Asked Questions
Who are the key players in China Harmonic Filter Market industry?
Top players in the China Harmonic Filter Market include Schneider Electric, Siemens AG, ABB Ltd., Eaton Corporation, and TDK Corporation. These companies offer advanced harmonic filtering solutions, strong R&D capabilities, and extensive distribution networks. Their innovations help industries mitigate power quality issues and comply with grid regulations.
What is the China Harmonic Filter Market growth?
The China Harmonic Filter Market is witnessing robust growth, driven by rapid industrialization and increasing adoption of electrical and electronic devices. For example, ABB Ltd. recently expanded their product portfolio for passive and active harmonic filters to meet growing demand and address national electric grid standards.
Which segment accounted for the largest China Harmonic Filter Market share?
The industrial application segment accounted for the largest market share in China’s Harmonic Filter Market. Due to high usage of power electronics and non-linear loads, industries such as manufacturing, oil & gas, and chemical processing are the primary adopters, demanding reliable power quality and reduced equipment downtime.
Thanks & Regards,
priya
sales@bussinessinsights.com
China Microcontrollers, DSP, & IP Core Chip Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-16
The China Microcontrollers, DSP, & IP Core Chip Market is projected to grow from USD 17,200 Million in 2025 to nearly USD 49,300 Million by 2035. This robust growth is primarily attributed to the accelerating adoption of smart devices, automation, and rising investment in domestic chip manufacturing. The market experienced steady growth between 2020 and 2024, but is expected to see a sharper increase post-2025 as policy support encourages R&D and production capacity expansion, particularly in embedded and programmable chip segments.
Read More - https://bussinessinsights.com/research-report/china-microcontrollers,-dsp,-and-ip-core-chip-market
In 2025, consumer electronics remain the dominant application for microcontrollers, DSP, and IP core chips with a 39% share, reflecting robust growth in smart devices and IoT ecosystem expansion. The automotive sector follows closely with 28%, buoyed by the rapid electrification of vehicles and integration of advanced driver assistance systems. Industrial automation captures 19%, underpinned by strong investments in smart manufacturing and industrial robotics. The remaining share is distributed among healthcare, telecommunications, and others, indicating the pervasive role of advanced chips in digital transformation across China's major economic sectors.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-microcontrollers,-dsp,-and-ip-core-chip-market
Frequently Asked Questions
Who are the key players in China Microcontrollers, DSP, & IP Core Chip Market industry?
Top players include HiSilicon (Huawei), Zhaoxin, Fudan Microelectronics, Ingenic Semiconductor, and Rockchip. HiSilicon leads with advanced SoCs, Zhaoxin focuses on x86 architecture CPUs, Fudan Microelectronics specializes in secure chips, Ingenic is known for low-power MCUs, and Rockchip excels in AI-powered application processors.
What is the China Microcontrollers, DSP, & IP Core Chip Market growth?
The China market saw rapid growth in 2023, driven by increased adoption in automotive and IoT sectors. Companies like Ingenic Semiconductor expanded their MCU product lines significantly, contributing to a CAGR above 8% due to government policies supporting domestic chip production and technological advancements.
Which segment accounted for the largest China Microcontrollers, DSP, & IP Core Chip Market share?
The automotive segment held the largest application share, as the demand for microcontrollers and DSPs surged in electric vehicles and advanced driver-assistance systems (ADAS). The focus on smart cars and intelligent transportation by domestic firms like BYD and NIO accelerated this segment's rapid expansion.
Thanks & Regards,
priya
sales@bussinessinsights.com
China’s organic electronics market is set for an impressive growth trajectory, with revenue poised to rise from $2,100 Million in 2020 to $9,800 Million by 2035, reflecting a strong compound annual growth rate over the forecast period. The acceleration is attributed to surging investments in display technologies, expanding renewable energy projects, and proactive government support for advanced manufacturing. The sector’s resilience is evident as it consistently outpaces legacy electronics sectors, affirming its status as a primary innovation driver in China’s high-tech economy.
Read More - https://bussinessinsights.com/research-report/china-organic-electronics-market
Display applications dominate the China organic electronics market, capturing the highest market share thanks to robust demand in smartphones, televisions, and automotive clusters. Lighting applications, powered by efficient organic LEDs, hold the second-largest share, while organic photovoltaic solutions are gaining traction in renewable energy projects. Additional applications, including smart cards, automotive, and others, contribute to overall market dynamism, reflecting a broadening scope for organic electronic integration across industry verticals.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-organic-electronics-market
Frequently Asked Questions
Who are the key players in China Organic Electronics Market industry?
The top five players in the China Organic Electronics Market are BOE Technology Group, TCL Technology, Visionox, Royole Corporation, and Konica Minolta. These companies are leading innovators in organic electronics, offering advanced OLED displays, organic semiconductors, and flexible electronic devices, driving the market's growth and technological development.
What is the China Organic Electronics Market growth?
The China Organic Electronics Market has experienced rapid growth in recent years, driven by increasing investment in flexible displays and organic solar cells. In 2023, BOE Technology reported a significant rise in OLED panel production, supporting market growth through advancements in quality and scale.
Which segment accounted for the largest China Organic Electronics Market share?
The display application segment holds the largest share of the China Organic Electronics Market. This dominance is attributed to the high demand for OLED panels in televisions, smartphones, and wearable devices, with companies like Visionox and TCL expanding their display product lines to meet consumer demand.
Thanks & Regards,
priya
sales@bussinessinsights.com
China’s induction motor market is on a growth trajectory with total revenue projected to reach $14,250 Million by 2025, up from $10,200 Million in 2020. This growth is underpinned by sustained industrial automation, rising adoption in smart factories, and the country’s expanding EV sector. Revenue is anticipated to maintain a healthy CAGR of 5.2% through 2035, driven by replacement demand, industry upgrades, and technological innovation. Regulatory support for energy efficiency and clean technologies further fortifies long-term market prospects.
Read More - https://bussinessinsights.com/research-report/china-induction-motor-market
Industrial applications account for the lion’s share of the China induction motor market in 2025, driven by burgeoning manufacturing and process automation. The automotive sector, propelled by the EV boom, and residential/commercial segments together form about one-third of the application market. Ongoing urbanization, upgrades to smart appliances, and agricultural modernization continue to spur diversified demand. Technological improvements, government incentives, and the rising middle class ensure that the application landscape remains dynamic and competitive.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-induction-motor-market
Frequently Asked Questions
Who are the key players in China Induction Motor Market industry?
The top 5 players in the China Induction Motor Market include Siemens AG, ABB Ltd., Nidec Corporation, WEG S.A., and Wolong Electric. These companies lead in innovation, manufacturing scale, and distribution network, providing advanced solutions for diverse industrial, commercial, and household applications across China.
What is the China Induction Motor Market growth?
The China Induction Motor Market has experienced significant growth, with a CAGR of around 6% in recent years. This growth is driven by rising automation and industrial investments, notably from companies like Wolong Electric, which has expanded production to meet the surge in demand for energy-efficient motors.
Which segment accounted for the largest China Induction Motor Market share?
The industrial segment holds the largest share of the China Induction Motor Market. Induction motors are widely used in manufacturing, mining, and water treatment sectors due to their reliability and efficiency, with automation projects from companies like Siemens AG boosting demand for industrial-grade motors.
Thanks & Regards,
priya
sales@bussinessinsights.com
Market revenue in China’s automotive smart display segment is projected to rise from USD 1,200 Million in 2020 to USD 8,000 Million by 2035, reflecting burgeoning adoption of advanced displays. Accelerated OEM partnerships and growth in electrification drive robust revenue gains. Between 2025 and 2030, average annual revenue growth is forecast to exceed 15%, underpinned by widespread implementation of high-resolution OLED panels, digital clusters, and HUD. OEM and aftermarket channel expansions further propel market value, with significant upward trends expected through 2035.
Read More - https://bussinessinsights.com/research-report/china-automotive-smart-display-market
Center stack displays remain predominant in 2025, accounting for 38% share, as most vehicles prioritize main infotainment and navigation interfaces. Digital instrument clusters account for 25% and are rapidly gaining traction on the back of digitalization trends among Chinese automakers. Head-up displays (HUD) command 18%, reflecting increased focus on driver safety and real-time road information. Rear seat entertainment systems and navigation-specific displays make up the remaining 19%, driven by rising demand for passenger comfort and luxury experiences. The composition signals strong OEM focus on core and safety-focused display uses.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-automotive-smart-display-market
Frequently Asked Questions
Who are the key players in China Automotive Smart Display Market industry?
The top 5 players in the China Automotive Smart Display Market are BOE Technology Group, Tianma Microelectronics, Shenzhen China Star Optoelectronics, Continental AG, and Panasonic Corporation. These companies are recognized for their advanced display technologies, strong R&D capabilities, large-scale production, and significant strategic partnerships within the automotive sector.
What is the China Automotive Smart Display Market growth?
The China Automotive Smart Display Market is experiencing robust growth, with increasing adoption of smart cockpits and digital dashboards. For example, BOE Technology Group reported a surge in demand for their automotive display panels in 2023, attributing growth to rising integration of connectivity and infotainment systems in vehicles.
Which segment accounted for the largest China Automotive Smart Display Market share?
The center stack display segment holds the largest share of the China Automotive Smart Display Market. These displays are vital for navigation, media, and vehicle information control, becoming standard in both premium and mass-market models due to consumer demand for enhanced connectivity and user experience.
Thanks & Regards,
priya
sales@bussinessinsights.com
Market revenue for North America signaling devices is projected to steadily increase from approximately USD 2,500 Million in 2020 to around USD 5,900 Million by 2035. Key growth spurts are anticipated in the next five years due to regulatory upgrades and rapid digital transformation across industries. The market maintains a healthy compound annual growth rate, supported by recurring investments in industrial safety, modernization of infrastructure, and a surge in demand for smart and wireless devices. Year-over-year increments remain consistent as market adoption broadens into diverse sectors.
Read More - https://bussinessinsights.com/research-report/north-america-signaling-devices-market
Industrial sectors heavily influence the application mix of signaling devices in North America for 2025. Oil & gas represents the largest application share, reflecting the criticality of advanced alarms and communications for hazardous operations. The chemical & pharmaceutical and energy & power sectors also demonstrate robust demand due to strict safety compliance mandates and the need for continuous process monitoring. Food & beverage, mining, and other industries collectively contribute to the market’s overall volume, with increasing investment in modern signaling infrastructure.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/north-america-signaling-devices-market
Frequently Asked Questions
Who are the key players in North America Signaling Devices Market industry?
Key players include Honeywell International Inc., Siemens AG, Rockwell Automation, Eaton Corporation, and Emerson Electric Co. These companies are at the forefront, offering advanced signaling solutions for industrial, commercial, and safety applications. Their innovative products and wide presence drive significant growth and competitiveness across the North American market.
What is the North America Signaling Devices Market growth?
The North America Signaling Devices Market is experiencing steady growth, with a CAGR of over 5% from 2021 to 2026. This growth is fueled by increasing industrial automation initiatives. For instance, Honeywell International's focus on smarter safety solutions has expanded its market presence, supporting sectoral advancements.
Which segment accounted for the largest North America Signaling Devices Market share?
The industrial application segment holds the largest market share in North America. Industries such as oil & gas, manufacturing, and mining rely heavily on signaling devices for operational safety and process efficiency. Increased automation and strict safety regulations have accelerated demand for signaling devices in these sectors.
Thanks & Regards,
priya
sales@bussinessinsights.com
The North America sports technology market is on a strong growth trajectory, with revenues surging from $2,950 Million in 2020 to an anticipated $8,930 Million in 2025. By 2035, the market is projected to reach $26,580 Million, propelled by the adoption of digital technologies, increased fan engagement, and the proliferation of AI-driven sports analytics. Year-over-year growth is supported by significant investments by sports franchises, technology vendors, and e-sports organizations, alongside shifting consumer preferences toward immersive and interactive experiences.
Read More - https://bussinessinsights.com/research-report/north-america-sports-technology-market
Player tracking & analysis is the leading application in 2025, making up the highest share, driven by the growing use of wearable sensors and advanced video analytics for athlete monitoring. Fan engagement applications are gaining traction as franchises focus on interactive digital platforms and AR/VR experiences to enhance spectator involvement. Fitness & training follows, with consumers adopting digital coaching and training solutions. Team & club management, broadcast & streaming, and sports event management together cater to the holistic needs of teams, fans, and organizers, ensuring efficient operations and maximizing event value through technology.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/north-america-sports-technology-market
Frequently Asked Questions
Who are the key players in North America Sports Technology Market industry?
The top 5 players in the North America Sports Technology Market are Catapult Sports, Zebra Technologies, IBM, Garmin Ltd., and Stats Perform. These companies lead in athlete tracking, performance data analytics, wearable devices, and AI-powered insights, significantly enhancing sports performance, fan engagement, and operational efficiency throughout the region.
What is the North America Sports Technology Market growth?
The North America Sports Technology Market has experienced robust growth, driven by increasing adoption of analytics and wearables. In 2023, Catapult Sports reported a surge in demand for athlete monitoring technology, while partnerships between leagues and tech firms have accelerated innovation, propelling overall market expansion across the region.
Which segment accounted for the largest North America Sports Technology Market share?
The performance tracking and analytics segment holds the largest share in the North America Sports Technology Market. Adopted widely by professional teams, this application leverages data to enhance player performance, reduce injuries, and optimize strategies, supported by widespread use of advanced analytics solutions offered by companies like Stats Perform and IBM.
Thanks & Regards,
priya
sales@bussinessinsights.com
The China Situational Awareness Market revenue is on an impressive growth trajectory, catapulting from around USD 1,980 Million in 2020 to a projected USD 7,420 Million by 2035. This sustained double-digit CAGR reflects the country's rapid digitization, surging cybersecurity priorities, and large-scale smart infrastructure rollouts. Continuous innovation across AI, IoT, and data analytics ensures robust expansion. Sector investments from both public and private actors are driving significant market growth, cementing China’s position as a leader in situational awareness technology.
Read More - https://bussinessinsights.com/research-report/china-situational-awareness-market
Military & Defense applications represent the largest segment within the situational awareness market in China for 2025. The rising geopolitical landscape and demand for advanced surveillance and early threat detection drive investment in these areas. Healthcare and aerospace sectors closely follow, propelled by real-time patient monitoring and airspace security needs, respectively. Demand in automotive and cybersecurity also rises, reflecting extensive digital transformation and the emergence of autonomous vehicles. Adoption is widespread, but priorities vary by sector focus.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-situational-awareness-market
Frequently Asked Questions
Who are the key players in China Situational Awareness Market industry?
The top five players in the China Situational Awareness Market are Huawei Technologies, ZTE Corporation, Hikvision, Dahua Technology, and CETC. These companies offer advanced situational awareness solutions for security, defense, and smart city applications, focusing on artificial intelligence, data analytics, and real-time monitoring for the Chinese market.
What is the China Situational Awareness Market growth?
The China Situational Awareness Market has experienced robust growth, with a CAGR above 12% in recent years, driven by increased demand for security and surveillance systems. For example, Hikvision reported strong revenue growth in 2023 due to investments in AI-based situational awareness solutions for public safety.
Which segment accounted for the largest China Situational Awareness Market share?
The security and military applications segment accounted for the largest market share in China’s Situational Awareness Market. This is due to significant government investments and the adoption of advanced surveillance and command-control systems to enhance national security, public safety, and critical infrastructure protection in urban areas.
Thanks & Regards,
priya
sales@bussinessinsights.com