Unlocking Growth: Investment Potential and Strategic Horizons in the Global Uhp Tubings Market
As global industries pivot toward advanced manufacturing, stringent purity standards, and hyper-controlled processing environments, the Global Uhp Tubings Market emerges as a critical cornerstone for high-stakes capital allocation. Ultra-High Purity (UHP) tubings are indispensable components ensuring zero-contamination fluid and gas delivery across mission-critical sectors such as semiconductor fabrication, biopharmaceuticals, and advanced chemical processing. For institutional investors, venture capitalists, and industry stakeholders, this market presents a compelling narrative of sustained high-margin growth, driven by technological miniaturization, rising electronic consumption, and rigorous regulatory mandates. Strategic entry and expansion within this domain offer robust avenues for long-term value creation, portfolio diversification, and technological leadership.
Access Your Free Sample & Investment Insights:

Market Opportunity and Investment Thesis
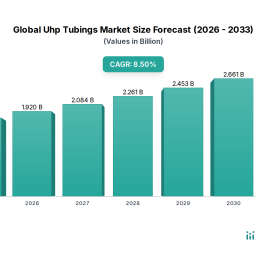
The financial outlook for the global sector is exceptionally bullish, underpinned by foundational macroeconomic tailwinds. The market is currently valued at approximately $1.77 billion and is projected to expand at a robust compound annual growth rate (CAGR) of 8.5% over the forecast period. This accelerated growth trajectory is primarily catalyzed by the massive global expansion of semiconductor fabrication plants (fabs) and increasing investments in biopharmaceutical manufacturing infrastructure. Furthermore, stringent purity requirements, the necessity to eliminate microscopic particulate contamination, and the transition toward advanced fluoropolymers and electropolished stainless steel present lucrative entry points for investors seeking high-yield opportunities in specialized industrial manufacturing.
Segmentation Analysis
Understanding the granular dynamics of the market requires a comprehensive look at its core verticals. The table below outlines the primary segmentation parameters, sub-segment examples, and projected growth characteristics.
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Material Type 1 |
Stainless Steel |
7.8% |
|
Material Type 2 |
PFA |
9.2% |
|
Material Type 3 |
PTFE |
8.4% |
|
Material Type 4 |
PVDF |
8.1% |
|
Material Type 5 |
Others |
7.5% |
|
Application 1 |
Semiconductor |
9.5% |
|
Application 2 |
Pharmaceutical |
8.8% |
|
Application 3 |
Biotechnology |
9.0% |
|
Application 4 |
Chemical Processing |
7.2% |
|
Application 5 |
Others |
7.0% |
|
End-User 1 |
Electronics |
9.3% |
|
End-User 2 |
Healthcare |
8.6% |
|
End-User 3 |
Chemical |
7.4% |
|
End-User 4 |
Others |
6.9% |
Strategic Company Analysis
The competitive landscape of the market is characterized by a mix of established industrial giants and specialized material innovators focusing on technological differentiation, stringent quality control, and global distribution capabilities. Key market players profiled in this comprehensive research report include Swagelok Company, Parker Hannifin Corporation, Saint-Gobain Performance Plastics, High Purity Products Inc., Valex Corporation, NewAge Industries Inc., Entegris Inc., Fujikin Incorporated, Ham-Let Group, Hy-Lok Corporation, Dockweiler AG, Tylok International Inc., Rubicon Gasket Company, Sani-Tech West Inc., Watson-Marlow Fluid Technology Group, Zeus Industrial Products Inc., Habia Teknofluor AB, CoorsTek Inc., CPC (Colder Products Company), and Eldon James Corporation. These industry leaders maintain their market dominance through strategic mergers, continuous R&D investment in advanced fluoropolymers, and capacity expansions tailored to high-growth regional semiconductor hubs.
Profitable Regions & Expansion Hotspots
Geographically, the market exhibits distinct pockets of high profitability and aggressive expansion. Asia Pacific stands out as the primary growth engine, heavily fueled by rapid semiconductor manufacturing investments in China, South Korea, Japan, Taiwan, and ASEAN nations, alongside a booming healthcare sector in India. Meanwhile, North America (United States, Canada, Mexico) continues to represent a mature, high-value market driven by rigorous domestic manufacturing standards, cutting-edge biotech research, and reshoring initiatives in electronics. Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics) maintains steady growth backed by stringent pharmaceutical regulations and advanced chemical processing industries. Additionally, emerging opportunities are surfacing across the Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa) and South America (Brazil, Argentina), driven by infrastructure modernization and industrial diversification.
Table of Contents (TOC)
- 1. Executive Summary
- 1.1. Market Overview
- 1.2. Key Financial Highlights & CAGR Projections
- 1.3. Strategic Investment Recommendations
- 2. Research Methodology & Scope
- 2.1. Market Definitions & Assumptions
- 2.2. Data Sourcing & Triangulation
- 2.3. Forecasting Methodology
- 3. Market Dynamics & Outlook
- 3.1. Growth Drivers
- 3.2. Market Restraints & Challenges
- 3.3. Emerging Opportunities & Industry Trends
- 3.4. Porter's Five Forces Analysis
- 4. Global Uhp Tubings Market, By Material Type
- 4.1. Stainless Steel
- 4.2. PFA
- 4.3. PTFE
- 4.4. PVDF
- 4.5. Others
- 5. Global Uhp Tubings Market, By Application
- 5.1. Semiconductor
- 5.2. Pharmaceutical
- 5.3. Biotechnology
- 5.4. Chemical Processing
- 5.5. Others
- 6. Global Uhp Tubings Market, By End-User
- 6.1. Electronics
- 6.2. Healthcare
- 6.3. Chemical
- 6.4. Others
- 7. Global Uhp Tubings Market, By Region
- 7.1. North America (U.S., Canada, Mexico)
- 7.2. Europe (U.K., Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe)
- 7.3. Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific)
- 7.4. South America (Brazil, Argentina, Rest of South America)
- 7.5. Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of MEA)
- 8. Competitive Intelligence & Strategic Company Profiles
- 8.1. Market Share Analysis
- 8.2. Company Profiles (Swagelok Company, Parker Hannifin Corporation, Saint-Gobain Performance Plastics, Entegris Inc., Fujikin Incorporated, and others)
- 8.3. Strategic Developments (M&A, Expansions, Partnerships)
- 9. Strategic Conclusions & Investment Roadmap
Explore the full report for deeper insights:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
Phone: +1 231-515-5523
Email: sales@datainsightsreports.com
Comprehensive Analysis of the Global Pressure Sensitive Adhesives For Waterproofing Membrane Market
The modern construction and industrial sectors demand advanced bonding solutions that offer superior durability, moisture resistance, and ease of application. The Global Pressure Sensitive Adhesives For Waterproofing Membrane Market plays a critical role in meeting these rigorous standards by providing reliable adhesive technologies that enhance the performance and longevity of waterproofing systems across various structural applications.
📊 Get a Free Sample Report + All Related Graphs & Charts:
Market Overview and Dynamics
The market is experiencing robust growth driven by rapid urbanization, infrastructure expansion, and a rising emphasis on sustainable, high-performance building materials. The market size is currently valued at approximately $1.69 billion and is projected to expand significantly over the forecast period, registering a steady CAGR of 6.1%. Primary market drivers include strict regulatory standards regarding building safety, the growing adoption of pre-applied waterproofing membranes, and technological advancements in adhesive formulations that improve bond strength under extreme environmental conditions. However, the market faces certain challenges, such as fluctuating raw material costs and stringent environmental regulations concerning volatile organic compounds (VOCs). Despite these hurdles, continuous product innovations and eco-friendly adhesive developments are expected to unlock lucrative opportunities for industry participants.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Product Type 1 |
Acrylic |
6.3% |
|
Product Type 2 |
Rubber |
5.9% |
|
Product Type 3 |
Silicone |
6.5% |
|
Product Type 4 |
Others |
5.4% |
|
Application 1 |
Residential |
6.0% |
|
Application 2 |
Commercial |
6.2% |
|
Application 3 |
Industrial |
5.8% |
|
Application 4 |
Infrastructure |
6.4% |
|
Distribution Channel 1 |
Direct Sales |
5.7% |
|
Distribution Channel 2 |
Distributors |
6.1% |
|
Distribution Channel 3 |
Online Sales |
7.0% |
|
Distribution Channel 4 |
Others |
5.2% |
|
End-User 1 |
Construction |
6.3% |
|
End-User 2 |
Automotive |
5.6% |
|
End-User 3 |
Packaging |
5.5% |
|
End-User 4 |
Others |
5.1% |
Competitive Landscape and Key Players
The competitive landscape of the market is characterized by intense rivalry among established multinational corporations and agile emerging players striving for market share. Key industry participants are heavily investing in research and development, strategic mergers and acquisitions, and geographic expansions to strengthen their product portfolios and customer base. The prominent companies profiled in the comprehensive report include 3M Company, Henkel AG & Co. KGaA, Sika AG, Bostik SA, Dow Inc., H.B. Fuller Company, Avery Dennison Corporation, Arkema Group, Wacker Chemie AG, Ashland Global Holdings Inc., Mapei S.p.A., Carlisle Companies Incorporated, BASF SE, Saint-Gobain Weber, Tremco Incorporated, GCP Applied Technologies Inc., Johns Manville Corporation, Soprema Group, Polyglass S.p.A., and Henry Company LLC.
Regional Outlook
The geographical evaluation of the report provides a detailed breakdown of major global regions, encompassing North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific). Asia Pacific dominates the global market consumption owing to massive construction booms, rapid industrialization, and infrastructural investments in emerging economies like China and India. Meanwhile, North America and Europe maintain substantial market shares driven by stringent building codes, renovation projects, and high adoption rates of advanced construction technologies.
📊 Explore the full report for deeper insights:
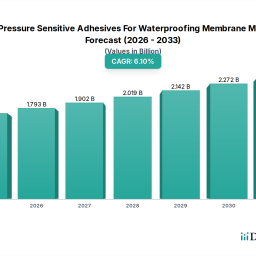
Table of Contents (TOC)
- 1. Introduction and Research Methodology
- 2. Executive Summary
- 3. Market Dynamics and Industry Outlook
- 4. Global Pressure Sensitive Adhesives For Waterproofing Membrane Market Analysis by Product Type
- 5. Global Pressure Sensitive Adhesives For Waterproofing Membrane Market Analysis by Application
- 6. Global Pressure Sensitive Adhesives For Waterproofing Membrane Market Analysis by Distribution Channel
- 7. Global Pressure Sensitive Adhesives For Waterproofing Membrane Market Analysis by End-User
- 8. Regional Market Analysis and Country-Level Insights
- 9. Competitive Landscape and Company Profiles
- 10. Appendix and Data Sources
📊 For complete insights, forecasts, and data tables, visit the full report:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@datainsightsreports.com
Comprehensive Market Insights into the Global Environmental Conscious Pvc Stabilizer Market
The rapid shift toward sustainable manufacturing practices has positioned the Global Environmental Conscious Pvc Stabilizer Market as a critical sector for modern industrial applications. As regulatory bodies enforce stringent environmental standards and consumers increasingly demand eco-friendly alternatives to traditional heavy-metal-based stabilizers, the adoption of green PVC stabilizing agents has surged exponentially.
📊 Get a Free Sample Report + All Related Graphs & Charts:
Market Overview and Dynamics
The global environmental conscious PVC stabilizer market size is estimated at approximately $1.50 billion and is projected to expand significantly, registering a steady compound annual growth rate (CAGR) of 7.5% over the forecast period. This remarkable growth trajectory is primarily driven by mounting environmental concerns, the progressive phase-out of lead- and cadmium-based stabilizers, and the expansion of eco-friendly building codes across developed and emerging economies. Furthermore, technological advancements in organic and calcium-zinc-based formulations have enhanced thermal stability and mechanical performance, making them viable replacements for conventional additives. However, higher initial production costs and technical hurdles related to formulating bio-based alternatives for extreme application conditions remain key challenges constraining rapid market acceleration.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Type 1 |
Organic Stabilizers |
7.8% |
|
Type 2 |
Inorganic Stabilizers |
7.1% |
|
Application 1 |
Pipes & Fittings |
7.6% |
|
Application 2 |
Profiles & Tubing |
7.4% |
|
Application 3 |
Rigid & Semi-Rigid Films |
7.2% |
|
Application 4 |
Wires & Cables |
7.9% |
|
Application 5 |
Others |
6.8% |
|
End-User Industry 1 |
Building & Construction |
7.7% |
|
End-User Industry 2 |
Automotive |
7.5% |
|
End-User Industry 3 |
Electrical & Electronics |
7.3% |
|
End-User Industry 4 |
Packaging |
7.0% |
|
End-User Industry 5 |
Others |
6.9% |
Competitive Landscape and Key Players
The competitive environment of the global environmental conscious PVC stabilizer market features a robust mix of established industry leaders and innovative emerging players striving for market dominance through continuous research and development, strategic mergers and acquisitions, and portfolio expansions. Key market participants place strong emphasis on developing high-performance, non-toxic formulations to meet evolving international environmental regulations. Prominent companies covered in this comprehensive report include Baerlocher GmbH, Akcros Chemicals Ltd., Pau Tai Industrial Corporation, Valtris Specialty Chemicals, Songwon Industrial Co., Ltd., Adeka Corporation, Reagens S.p.A., Sun Ace Kakoh (Pte.) Ltd., PMC Group Inc., Nitto Kasei Co., Ltd., Ferro Corporation, Chemson Group, Galata Chemicals, MOMCPL, Shital Industries Pvt. Ltd., Patcham FZC, Novista Group Co., Ltd., Arihant Stabilizers, PlastiStab, and BASF SE.
Regional Outlook
The geographical scope of the report provides a detailed regional analysis covering North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific). Asia Pacific currently leads the global market, propelled by rapid industrialization, robust infrastructural development, and stringent regulatory policies implemented across major economies like China and India. Meanwhile, Europe and North America demonstrate high adoption rates driven by strict environmental mandates and mature construction and automotive sectors prioritizing sustainability.
📊 Explore the full report for deeper insights:
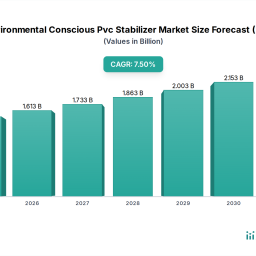
Table of Contents (TOC)
- Chapter 1: Introduction and Research Methodology
- Chapter 2: Executive Summary of the Global Environmental Conscious Pvc Stabilizer Market
- Chapter 3: Market Dynamics, Drivers, Restraints, and Opportunities
- Chapter 4: Global Market Segmentation Analysis by Type, Application, and End-User Industry
- Chapter 5: Regional Market Analysis and Growth Projections (North America, Europe, Asia-Pacific, South America, Middle East & Africa)
- Chapter 6: Competitive Landscape, Market Share Analysis, and Company Profiles
- Chapter 7: Strategic Recommendations and Future Outlook
📊 For complete insights, forecasts, and data tables, visit the full report:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@datainsightsreports.com
Navigating the Competitive Arena of the Global Wind Turbine Structural Adhesive Market
The Global Wind Turbine Structural Adhesive Market operates within a highly competitive and rapidly evolving landscape. Driven by the global push for renewable energy expansion and increasingly stringent performance standards for wind power infrastructure, industry participants are constantly vying for market dominance. Manufacturers are under intense pressure to deliver high-strength, durable, and weather-resistant bonding solutions capable of withstanding extreme environmental stresses encountered in both onshore and offshore installations.
📊 Get Your Free Competitive Analysis Sample:
In-Depth Competitive Analysis
The global market exhibits a moderately consolidated yet fiercely contested structure, characterized by the dominance of several well-established chemical and material science giants alongside agile regional specialists. Market share concentration is heavily skewed toward top-tier companies that possess extensive research and development capabilities, global distribution networks, and strong partnerships with wind turbine OEMs. Strategic initiatives among these market leaders primarily focus on mergers and acquisitions, technological collaborations, and capacity expansions to capture emerging regional opportunities. Key players profiled in this comprehensive report include 3M, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Dow Inc., Huntsman Corporation, Lord Corporation, Wacker Chemie AG, Ashland Global Holdings Inc., Bostik (Arkema Group), Permabond LLC, Scott Bader Company Ltd., Avery Dennison Corporation, Master Bond Inc., ITW Performance Polymers, Parson Adhesives Inc., DELO Industrial Adhesives, Panacol-Elosol GmbH, and Weicon GmbH & Co. KG. These companies actively invest in formulating eco-friendly, fast-curing, and high-performance adhesives to secure a competitive edge.
Factors Influencing Competitive Rivalry
Competitive rivalry within the industry is significantly intensified by rapid technological advancements and the continuous need for cost optimization. With the market valued at approximately $1.53 billion and expanding at a robust compound annual growth rate (CAGR) of 8.6%, participants are motivated to innovate continuously. The transition toward larger wind turbine rotor blades to maximize energy capture creates immense demand for specialized structural adhesives capable of structural load-bearing without adding excessive weight. Furthermore, fluctuations in raw material prices and stringent environmental regulations regarding volatile organic compounds (VOCs) compel companies to develop sustainable, bio-based adhesive formulations, further sharpening the competitive edge of market pioneers.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Resin Type 1 |
Epoxy |
8.8% |
|
Resin Type 2 |
Polyurethane |
8.5% |
|
Resin Type 3 |
Acrylic |
8.7% |
|
Resin Type 4 |
Others |
8.1% |
|
Application 1 |
Blade Bonding |
8.9% |
|
Application 2 |
Tower Bonding |
8.3% |
|
Application 3 |
Nacelle Bonding |
8.2% |
|
Application 4 |
Others |
8.0% |
|
End-User 1 |
Onshore Wind Turbines |
8.4% |
|
End-User 2 |
Offshore Wind Turbines |
9.1% |
Regional Market Leaders
Geographically, the competitive landscape varies significantly across key regions, including North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific). Asia Pacific currently stands as the dominant regional market, propelled by massive investments in wind energy capacity, particularly in China and India, where local and international adhesive manufacturers compete aggressively. Meanwhile, Europe remains a mature market heavily focused on offshore wind installations and stringent technological standards, while North America exhibits steady growth supported by renewable energy incentives and grid modernization initiatives.
📊 Explore the full report for deeper insights:
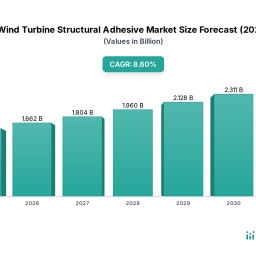
Table of Contents (TOC)
- 1. Executive Summary and Market Overview
- 2. Industry Dynamics, Drivers, Restraints, and Opportunities
- 3. Global Wind Turbine Structural Adhesive Market Analysis and Forecast (Valuation and CAGR)
- 4. Competitive Landscape and Market Share Analysis
- 5. Strategic Profiles of Key Players (3M, Henkel, Sika, Dow, Huntsman, and Others)
- 6. Global Market Segmentation by Resin Type (Epoxy, Polyurethane, Acrylic, Others)
- 7. Global Market Segmentation by Application (Blade Bonding, Tower Bonding, Nacelle Bonding, Others)
- 8. Global Market Segmentation by End-User (Onshore, Offshore)
- 9. Regional Market Analysis (North America, Europe, Asia Pacific, South America, Middle East & Africa)
- 10. Future Outlook and Strategic Recommendations
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@datainsightsreports.com
Unlocking Growth: Investment Opportunities of Global Hexagonal Bn Cooling Filler Market
The rapid technological evolution across electronics, automotive, and aerospace sectors has placed unprecedented demands on advanced thermal management solutions. At the epicenter of this industrial shift lies the Global Hexagonal Bn Cooling Filler Market , a high-growth sector driven by the necessity for superior heat dissipation in increasingly compact and high-performance devices. Hexagonal boron nitride (h-BN), often referred to as "white graphite," exhibits exceptional thermal conductivity, electrical insulation, and high-temperature stability, making it an indispensable material for forward-thinking manufacturers and institutional investors alike. As industries worldwide transition toward electrification, 5G infrastructure, and next-generation power electronics, the demand for advanced cooling fillers is projected to scale exponentially, offering lucrative entry and expansion points for venture capitalists and industry stakeholders.
📊 Access Your Free Sample & Investment Insights:
Market Opportunity and Investment Thesis
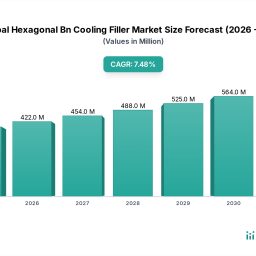
From a financial perspective, the market presents a compelling growth narrative underpinned by robust macroeconomic tailwinds. According to recent industry estimations, the market size is valued at approximately $392.91 million, with expectations to expand at a steady CAGR of 7.5% over the forecast period. This upward trajectory is primarily catalyzed by the booming consumer electronics market, the exponential rise of electric vehicles (EVs), and stringent thermal efficiency standards in aerospace and industrial manufacturing. Investors seeking exposure to high-margin specialty materials will find that hexagonal boron nitride fillers offer a resilient growth profile. The convergence of miniaturization trends in electronics and the electrification of global transport networks ensures sustained, long-term demand, minimizing cyclical downside risks while maximizing upside return potential.
Segmentation Analysis
A granular understanding of market segments is critical for precise capital allocation. The market exhibits diverse growth dynamics across its product types, functional applications, and end-user landscapes.
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Product Type 1 |
Powder |
7.8% |
|
Product Type 2 |
Granules |
7.2% |
|
Product Type 3 |
Sheets |
6.9% |
|
Application 1 |
Electronics |
8.1% |
|
Application 2 |
Automotive |
7.6% |
|
Application 3 |
Aerospace |
7.0% |
|
Application 4 |
Industrial |
6.8% |
|
Application 5 |
Others |
6.5% |
|
End-User 1 |
Consumer Electronics |
8.0% |
|
End-User 2 |
Automotive |
7.7% |
|
End-User 3 |
Aerospace |
7.1% |
|
End-User 4 |
Industrial Manufacturing |
6.7% |
|
End-User 5 |
Others |
6.4% |
Strategic Company Analysis
The competitive landscape of the market is characterized by a mix of established global chemical conglomerates and specialized advanced ceramic producers focusing on continuous technological innovation, strategic partnerships, and capacity expansions. Market leaders are heavily investing in research and development to optimize particle size distribution, purity, and surface functionalization of h-BN to meet stringent tier-1 customer requirements. The comprehensive market research report profiles key industry participants, offering critical insights into their competitive positioning, product portfolios, recent developments, and strategic maneuvers. Major players featured in the report include Saint-Gobain, 3M Company, Denka Company Limited, Showa Denko K.K., ZYP Coatings Inc., Kennametal Inc., Henze BNP AG, Momentive Performance Materials Inc., H.C. Starck GmbH, Zibo Jonye Ceramic Technologies Co., Ltd., Zhonglan Industry Co., Ltd., EPRUI Nanoparticles & Microspheres Co. Ltd., UK Abrasives, Inc., Shandong Pengcheng Special Ceramics Co., Ltd., Dandong Rijin Science and Technology Co., Ltd., Qingzhou Fangyuan Boron Nitride Co., Ltd., Qingzhou Orient Special Ceramics Co., Ltd., Yingkou Tanyun Chemical Research Institute Corporation, Qingdao Sinyo Chemical Co., Ltd., and Suzhou Ginet New Material Technology Co., Ltd.
Profitable Regions & Expansion Hotspots
Geographically, the market presents distinct regional opportunities driven by localized manufacturing hubs, technological adoption rates, and governmental support for green technologies. Asia Pacific emerges as the most dominant and profitable regional hotspot, led by China, Japan, and South Korea, where massive concentrations of electronics and automotive manufacturing infrastructure aggressively drive consumption. Meanwhile, North America (comprising the United States, Canada, and Mexico) and Europe (anchored by Germany, the United Kingdom, France, Italy, Spain, Russia, Benelux, and the Nordics) remain primary centers for high-value aerospace applications, defense electronics, and advanced R&D initiatives. Additionally, emerging markets across the Middle East & Africa (including Turkey, Israel, the GCC, North Africa, and South Africa) and South America (Brazil, Argentina, and the Rest of South America) offer untapped greenfield expansion opportunities for stakeholders looking to diversify their geographical footprints.
Table of Contents (TOC)
- 1. Executive Summary & Market Overview
- 2. Industry Dynamics, Drivers, Restraints, and Opportunities
- 3. Global Hexagonal Bn Cooling Filler Market Analysis & Forecast by Product Type
- 4. Global Hexagonal Bn Cooling Filler Market Analysis & Forecast by Application
- 5. Global Hexagonal Bn Cooling Filler Market Analysis & Forecast by End-User
- 6. Regional Market Analysis (North America, Europe, Asia Pacific, South America, Middle East & Africa)
- 7. Competitive Landscape & Strategic Company Profiles
- 8. Investment Thesis & Future Outlook
📊 Explore the full report for deeper insights:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@datainsightsreports.com
Comprehensive Analysis and Future Outlook of the Global Specialty Gases For Semiconductor Market
The rapid expansion of the electronics and technology sectors has significantly elevated the demand for high-purity materials, making the Global Specialty Gases For Semiconductor Market a critical component of modern manufacturing. Specialty gases play an indispensable role in microelectronics fabrication, enabling precise material deposition, etching, and doping processes necessary for producing advanced integrated circuits and semiconductors.
📊 Get a Free Sample Report + All Related Graphs & Charts:
Market Overview and Dynamics
The Global Specialty Gases For Semiconductor Market is currently valued at approximately $6.67 billion and is projected to expand significantly, registering a steady compound annual growth rate (CAGR) of 8.2% over the forecast period. The market is primarily driven by the surging global demand for consumer electronics, the proliferation of Internet of Things (IoT) devices, and the continuous miniaturization of semiconductor nodes. Key industry trends include the development of eco-friendly alternative gases to reduce environmental footprints and strategic investments in semiconductor fabrication plants worldwide. However, the market faces challenges such as stringent environmental regulations regarding toxic gas emissions, complex supply chain logistics, and high initial setup costs for high-purity gas infrastructure.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Product Type 1 |
Electronic Specialty Gases |
8.5% |
|
Product Type 2 |
Bulk Gases |
7.9% |
|
Product Type 3 |
Rare Gases |
8.1% |
|
Product Type 4 |
Others |
7.5% |
|
Application 1 |
Deposition |
8.3% |
|
Application 2 |
Etching |
8.6% |
|
Application 3 |
Doping |
7.8% |
|
Application 4 |
Lithography |
8.0% |
|
Application 5 |
Others |
7.4% |
|
End-User 1 |
Integrated Device Manufacturers |
8.2% |
|
End-User 2 |
Foundries |
8.7% |
|
End-User 3 |
Others |
7.6% |
Competitive Landscape and Key Players
The competitive landscape of the Global Specialty Gases For Semiconductor Market features a dynamic mix of established global chemical conglomerates and specialized regional providers focusing on high-purity technological advancements. These key industry participants continuously invest in research and development, strategic mergers, acquisitions, and facility expansions to strengthen their market positioning and meet stringent semiconductor manufacturing standards. Prominent companies covered in this comprehensive report include Air Liquide, Linde plc, Praxair Technology, Inc., Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, Showa Denko K.K., Sumitomo Seika Chemicals Company, Ltd., Iwatani Corporation, Advanced Specialty Gases Inc., Matheson Tri-Gas, Inc., Electronic Fluorocarbons, LLC, Central Glass Co., Ltd., REC Silicon ASA, Versum Materials, Inc., Solvay S.A., The Linde Group, Honeywell International Inc., Mitsui Chemicals, Inc., and Kanto Denka Kogyo Co., Ltd.
Regional Outlook
The report provides a thorough geographical assessment across major global regions, including North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific). Asia Pacific holds a dominant share of the global market due to the heavy concentration of semiconductor foundries and electronics manufacturing hubs in countries like South Korea, Taiwan, China, and Japan. Meanwhile, North America and Europe remain vital markets driven by strong technological innovation and investments in domestic semiconductor manufacturing capabilities.
📊 Explore the full report for deeper insights:
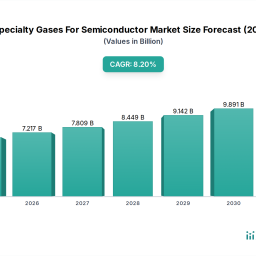
Table of Contents (TOC)
- 1. Introduction and Research Methodology
- 2. Executive Summary
- 3. Market Dynamics (Drivers, Restraints, Opportunities, and Challenges)
- 4. Global Specialty Gases For Semiconductor Market Segmentation Analysis
- 5. Regional Market Analysis and Projections
- 6. Competitive Landscape and Company Profiles
- 7. Strategic Recommendations and Future Outlook
📊 For complete insights, forecasts, and data tables, visit the full report:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@datainsightsreports.com
The Future of CoCr Alloy Powder for Dental 3D Printing: Trends, Innovations, and Opportunities to 2033
The dental industry is currently on the verge of a profound transformation, driven by unprecedented advancements in digital dentistry, custom manufacturing, and advanced material science. At the heart of this digital evolution is CoCr Alloy Powder for Dental 3D Printing , a foundational material enabling the production of highly durable, biocompatible, and patient-specific dental restorations. As dental laboratories increasingly transition from traditional casting methods to additive manufacturing, the demand for precision-engineered metallic powders continues to surge, opening remarkable avenues for forward-thinking innovators and strategic investors.
📊 Preview the Future with a Free Sample Report:
Emerging Trends and Technological Disruptions
The market landscape is rapidly shifting due to major technological disruptions in powder morphology, atomization techniques, and digital workflow integration. The integration of artificial intelligence and automated nesting software in 3D printing pipelines is streamlining production, minimizing material waste, and elevating structural integrity. Furthermore, sustainability is becoming a key focal point, with powder manufacturers optimizing gas and plasma atomization processes to reduce carbon footprints while enhancing particle sphericity and flowability. Backed by a robust projected CAGR of 5% from a base year valuation of $742.2 million in 2025, the market is demonstrating steady resilience and continuous commercial expansion as dental clinics adopt chairside and lab-side additive manufacturing solutions.
High-Growth Segments of Tomorrow
Dissecting the granular segments of the industry reveals distinct pockets of high-growth potential. Within product types, CoCrMo and ASTM F75 CoCr formulations are expected to dominate due to their superior mechanical strength and biocompatibility for long-term implants. Manufacturing technologies are leaning heavily toward Gas Atomized and Plasma Atomized powders, prized for their ultra-clean microstructures and precise particle size distributions, specifically the 15–45 μm range tailored for high-resolution printing. Printing technologies such as Selective Laser Melting (SLM), Laser Powder Bed Fusion (LPBF), and Direct Metal Laser Sintering (DMLS) remain the gold standards for fabricating complex geometries. Among applications, Removable Partial Denture (RPD) frameworks and implant-supported prosthetics are poised to capture the largest share of future demand, driven by an aging global population requiring advanced restorative solutions.
Pioneers and Innovators
The competitive arena is defined by aggressive research and development, strategic partnerships, and a relentless pursuit of superior powder quality. Industry pioneers such as EOS GmbH, Carpenter Additive, Oerlikon Metco, Höganäs AB, Sandvik AB, and Tekna Holding ASA are spearheading next-generation product development. These market leaders are continuously refining powder recycling methodologies, custom alloy compositions (including specialized CoCrW variants), and spherical consistency to meet the rigorous regulatory standards of the medical and dental sectors. Collaborations between material scientists and dental equipment manufacturers are further accelerating the commercialization of tailored printing powders.
Future Regional Dynamics
Geographically, the market outlook varies significantly across regions. North America (comprising the United States, Canada, and Mexico) continues to lead in adoption rates, fueled by advanced healthcare infrastructure, high disposable incomes, and early adoption of digital dentistry workflows. Meanwhile, Europe—anchored by key markets like Germany, the United Kingdom, France, and Italy—remains a stronghold for precision dental engineering and stringent quality compliance. However, the Asia-Pacific region (led by China, Japan, India, and South Korea) is anticipated to register the fastest-growing momentum, propelled by expanding healthcare access, rising medical tourism, and the rapid modernization of regional dental laboratories. South America and the Middle East & Africa are also presenting lucrative incremental opportunities as dental digitalization gradually penetrates emerging economies.
📊 Explore the full report for deeper insights:
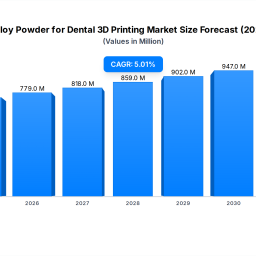
Table of Contents (TOC)
- 1. Executive Summary and Market Overview
- 2. Industry Trends and Technological Disruptions in Dental Additive Manufacturing
- 3. Global CoCr Alloy Powder Market Size and Forecast (2025–2033)
- 4. Market Segmentation Analysis by Product Type (CoCrMo, CoCrW, ASTM F75 CoCr)
- 5. Market Segmentation Analysis by Manufacturing Technology (Gas Atomized, Plasma Atomized, PREP, Water Atomized)
- 6. Market Segmentation Analysis by Particle Size (Below 15 μm, 15–45 μm, 45–75 μm, Above 75 μm)
- 7. Market Segmentation Analysis by Printing Technology (SLM, LPBF, DMLS, EBM)
- 8. Market Segmentation Analysis by Application (Crowns, Bridges, RPD Frameworks, Implant-Supported Prosthetics, Orthodontic Appliances)
- 9. Regional Market Dynamics and Country-Level Analysis (North America, Europe, Asia Pacific, South America, Middle East & Africa)
- 10. Competitive Landscape and Strategic Profiling of Key Innovators (EOS GmbH, Sandvik AB, Höganäs AB, Oerlikon Metco, Tekna, and Others)
- 11. Future Opportunities, Strategic Recommendations, and Risk Analysis
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@sectordatainsights.com
Navigating the Competitive Arena of the Coffee Dripper Market
The global Coffee Dripper market is characterized by a fiercely contested battleground where heritage craftsmanship meets modern specialty coffee culture. As discerning consumers increasingly seek artisanal brewing experiences at home, manufacturers are locked in a continuous race for design innovation, material quality, and brand loyalty. The competitive intensity is palpable, forcing both legacy brands and agile newcomers to refine their value propositions continually.
Get Your Free Competitive Analysis Sample:
In-Depth Competitive Analysis
The market exhibits a moderately fragmented yet highly competitive structure, featuring a mix of century-old ceramic icons and sleek, modern equipment manufacturers. While market share is somewhat dispersed, a few dominant leaders hold significant sway over global distribution and consumer preference through aggressive product differentiation and strategic retail partnerships. The report profiles key industry pacesetters, including HARIO, KALITA, BODUM, Tiamo, FRANKFURT, KONO, Bonmac, Alfi, KOONAN, BREWISTA, Creano, TORCH, CAFEDE KONA, A-IDIO, Zero Japan, TIMEMORE, and several other emerging regional participants. Major players are aggressively deploying strategies such as limited-edition colorways, precision-engineered flow-rate structures, and eco-friendly material adoption to capture higher margins and outmaneuver rivals.
Factors Influencing Competitive Rivalry
Competitive rivalry within this space is significantly amplified by shifting consumer behaviors toward specialty home brewing and the rising demand for sustainable, durable kitchenware. With the market valued at approximately $500 million and expanding at a steady compound annual growth rate (CAGR) of 7% starting from the base year 2025, companies are heavily incentivized to capture expanding demographic segments. Technological advancements in thermal retention, precision drainage geometry, and lightweight, unbreakable materials further intensify the battle for market supremacy, as brands race to eliminate brewing inconsistencies and deliver the ultimate cup of coffee.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Beer Type 1 |
Coffee Stout |
6.8% |
|
Beer Type 2 |
Coffee Porter |
6.5% |
|
Material |
Ceramics |
7.2% |
|
Alcohol Content (ABV) |
Standard Alcohol (4%–6%) |
6.9% |
|
End User |
Individual Consumers |
7.5% |
|
Distribution Channel |
Specialty Beer Stores |
6.7% |
Regional Market Leaders
Geographically, the competitive landscape varies extensively across North America, South America, Europe, the Middle East & Africa, and Asia Pacific. Asia Pacific remains a powerhouse of both manufacturing and consumption, driven by dense café cultures in Japan, China, and South Korea, where foundational brands like HARIO, KALITA, and KONO maintain strong regional strongholds. Meanwhile, North America and Europe exhibit intense rivalry fueled by specialty coffee enthusiasts and a booming direct-to-consumer e-commerce ecosystem, where international players and modern brands aggressively contest shelf space.
Explore the full report for deeper insights:
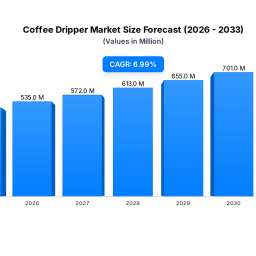
Table of Contents (TOC)
- 1. Executive Summary
- 2. Market Overview and Macroeconomic Trends
- 3. Competitive Landscape & Strategic Developments (Key Players, Market Share Analysis, Expansion Strategies)
- 4. Global Coffee Dripper Market Segmentation by Material, End User, and Distribution Channel
- 5. Regional Market Analysis (North America, Europe, Asia Pacific, South America, Middle East & Africa)
- 6. Company Profiles (HARIO, KALITA, BODUM, TIMEMORE, and more)
- 7. Future Outlook and Investment Opportunities
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
Phone: +1 231-515-5523
Email: sales@sectordatainsights.com
Navigating the Competitive Arena of the Collaborative Documentation Market
The global Collaborative Documentation market is characterized by fierce rivalry, rapid technological convergence, and constant product innovation as enterprises vie for superior digital workspace solutions. Industry participants are continuously upgrading their offerings with artificial intelligence, real-time editing capabilities, and robust security protocols to capture higher market share in an increasingly crowded ecosystem.
📊 Get Your Free Competitive Analysis Sample:
In-Depth Competitive Analysis
The collaborative documentation market features a moderately consolidated structure, where established tech giants and agile SaaS disruptors fiercely contest leadership. Market share concentration is notably high among legacy productivity suite providers, yet specialized workspace innovators are carving out substantial niches through superior user experience and flexible integration capabilities. Strategic initiatives among top-tier players heavily emphasize mergers and acquisitions, ecosystem expansion, and continuous AI-driven feature rollouts to maximize customer retention and lifetime value. The comprehensive report meticulously profiles key industry participants, including Notion, Dozuki, PDFTron, Atlassian, Microsoft, Google, Tencent Holdings, ByteDance, Alibaba Group, and Wuhan Chuxin Technology, highlighting their individual market positioning, financial performance, and strategic maneuvers.
Factors Influencing Competitive Rivalry
Competitive rivalry within the industry is heavily escalated by rapid technological advancements, shifting enterprise demands for remote-first collaboration tools, and the continuous need for seamless cross-platform integrations. With the market valued at approximately $2.6 billion in the base year of 2025 and expanding at a robust compound annual growth rate (CAGR) of 13.1%, companies are under immense pressure to out-innovate competitors to capture lucrative enterprise accounts. Furthermore, challenges such as data privacy compliance, cybersecurity threats, and the steep learning curve of advanced platforms compel vendors to invest heavily in research and development, further intensifying the competitive landscape.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Application 1 |
Enterprise |
13.5% |
|
Application 2 |
Personal |
12.2% |
|
Types 1 |
SaaS Model |
13.8% |
|
Types 2 |
PaaS Model |
12.0% |
Regional Market Leaders
Regionally, the competitive dynamics vary significantly across North America, South America, Europe, the Middle East & Africa, and Asia Pacific. North America remains a highly contested stronghold dominated by established tech titans headquartered in the United States and Canada, alongside active regional players operating across Mexico. Meanwhile, Europe features stringent regulatory compliance drivers that shape local vendor strategies across the United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, and the Nordics. Concurrently, the Asia Pacific region—led by major tech conglomerates in China, India, Japan, South Korea, ASEAN, and Oceania—exhibits hyper-growth and intense domestic competition, with heavyweights like Tencent Holdings, ByteDance, and Alibaba Group aggressively expanding their regional footprints.
📊 Explore the full report for deeper insights:
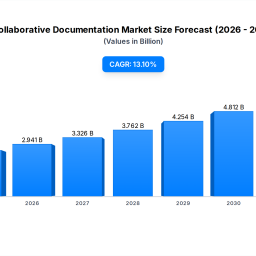
Table of Contents (TOC)
- 1. Executive Summary
- 2. Research Methodology and Scope
- 3. Market Overview and Industry Dynamics
- 4. Competitive Landscape and Market Share Analysis
- 5. Collaborative Documentation Market, By Application (Enterprise, Personal)
- 6. Collaborative Documentation Market, By Types (SaaS Model, PaaS Model)
- 7. Regional Market Analysis (North America, South America, Europe, Middle East & Africa, Asia Pacific)
- 8. Company Profiles (Notion, Dozuki, PDFTron, Atlassian, Microsoft, Google, Tencent Holdings, ByteDance, Alibaba Group, Wuhan Chuxin Technology)
- 9. Strategic Recommendations and Future Outlook
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@sectordatainsights.com
Unlocking Growth: Investment Opportunities of Cold Cereal Food
The global breakfast landscape is undergoing a strategic evolution, presenting astute investors with high-yield prospects in the packaged foods sector. As consumer preferences shift toward convenient, nutrient-dense, and functional morning meals, the Cold Cereal Food market emerges as a resilient asset class. This comprehensive research report is engineered to provide executives, institutional investors, and stakeholders with the precise data-driven insights required to capitalize on emerging trends, optimize portfolio positioning, and mitigate market entry risks. By examining shifting demographics, rapid urbanization, and continuous product innovations—such as organic, plant-based, and protein-fortified varieties—this intelligence report decodes the key drivers accelerating profitability across the value chain.
📊 Access Your Free Sample & Investment Insights:
Market Opportunity and Investment Thesis
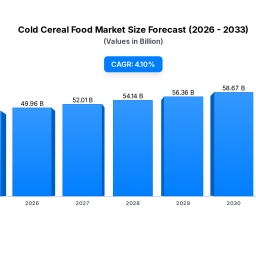
The global Cold Cereal Food market is on a robust financial trajectory, estimated at approximately $47.99 billion in the base year 2025. Driven by an anticipated Compound Annual Growth Rate (CAGR) of approximately 4.1% over the forecast period, the market demonstrates steady, predictable cash flows paired with scalable expansion avenues. Investment interest is heavily anchored by the rising demand for ready-to-eat (RTE) meal solutions among time-constrained urban populations. Furthermore, aggressive marketing campaigns emphasizing whole grains, digestive health, and clean-label ingredients are successfully revitalizing legacy categories. For investors seeking exposure to defensive consumer staple stocks that still harbor strong organic growth vectors, the cold cereal sector offers a compelling risk-reward profile.
Segmentation Analysis
To fully grasp the macroeconomic and microeconomic forces at play, the report breaks down the market into granular segments. Investors can leverage these vectors to pinpoint high-margin niches and direct capital toward outperforming sub-sectors.
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Product Type 1 |
Flaked Cereals |
3.8% |
|
Product Type 2 |
Granola Cereals |
5.2% |
|
Product Type 3 |
Muesli Cereals |
4.7% |
|
Product Type 4 |
Puffed Cereals |
3.5% |
|
Product Type 5 |
Shredded Cereals |
3.9% |
|
Product Type 6 |
Bran Cereals |
4.0% |
|
Product Type 7 |
Others |
3.6% |
|
Ingredient Type 1 |
Wheat-Based Cereals |
3.7% |
|
Ingredient Type 2 |
Corn-Based Cereals |
3.9% |
|
Ingredient Type 3 |
Oat-Based Cereals |
5.0% |
|
Ingredient Type 4 |
Rice-Based Cereals |
4.1% |
|
Ingredient Type 5 |
Barley-Based Cereals |
3.4% |
|
Ingredient Type 6 |
Multigrain Cereals |
4.6% |
|
Ingredient Type 7 |
Others |
3.5% |
|
Nature 1 |
Conventional |
3.2% |
|
Nature 2 |
Organic |
6.1% |
|
Flavor 1 |
Plain/Original |
3.1% |
|
Flavor 2 |
Chocolate |
4.8% |
|
Flavor 3 |
Honey |
4.3% |
|
Flavor 4 |
Fruit-Based |
4.9% |
|
Flavor 5 |
Vanilla |
3.9% |
|
Flavor 6 |
Cinnamon |
4.2% |
|
Flavor 7 |
Others |
3.6% |
|
Distribution Channel 1 |
Supermarkets & Hypermarkets |
3.5% |
|
Distribution Channel 2 |
Convenience Stores |
4.0% |
|
Distribution Channel 3 |
Specialty Stores |
4.5% |
|
Distribution Channel 4 |
Online Retail/E-Commerce |
7.2% |
|
Distribution Channel 5 |
Wholesale Clubs |
3.8% |
|
Distribution Channel 6 |
Others |
3.4% |
Strategic Company Analysis
The competitive landscape of the Cold Cereal Food market is characterized by a mix of established multinational giants and agile challengers driving category disruption through health-focused formulations. The report offers an exhaustive evaluation of key players, examining their market positioning, competitive advantages, M&A activities, supply chain resilience, and R&D pipelines. Evaluated market leaders include Kellanova, General Mills, Inc., Post Holdings, Inc., Nestlé S.A., PepsiCo, Inc., WK Kellogg Co., Cereal Partners Worldwide, Weetabix Limited, Calbee Inc., Jordans Dorset Ryvita, and Others. Understanding these industry heavyweights' strategic maneuvers is critical for identifying potential partnership targets, competitive threats, or acquisition opportunities within the global ecosystem.
Profitable Regions & Expansion Hotspots
Geographically, the report maps out high-growth territories and mature markets to direct regional expansion strategies effectively. North America (United States, Canada, Mexico) remains a massive, highly consolidated revenue generator driven by high per capita consumption of ready-to-eat breakfast foods. Meanwhile, Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe) presents lucrative opportunities centered on premiumization, organic certifications, and sustainable packaging initiatives. The Asia Pacific region (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) stands out as the ultimate expansion hotspot, propelled by rising disposable incomes, westernization of dietary habits, and expanding modern retail infrastructure. South America (Brazil, Argentina, Rest of South America) and the Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa) also offer untapped frontier markets for forward-thinking stakeholders.
Table of Contents (TOC)
- 1. Executive Summary
- 2. Market Overview and Strategic Context
- 3. Global Cold Cereal Food Market Dynamics (Drivers, Restraints, Opportunities)
- 4. Global Cold Cereal Food Market Analysis & Forecast by Product Type
- 5. Global Cold Cereal Food Market Analysis & Forecast by Ingredient Type
- 6. Global Cold Cereal Food Market Analysis & Forecast by Nature
- 7. Global Cold Cereal Food Market Analysis & Forecast by Flavor
- 8. Global Cold Cereal Food Market Analysis & Forecast by Distribution Channel
- 9. Global Cold Cereal Food Market Analysis & Forecast by Region
- 10. Competitive Landscape & Strategic Company Profiles
- 11. Strategic Recommendations and Investment Conclusions
📊 Explore the full report for deeper insights:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@sectordatainsights.com
Navigating the Future of Financial Security with Advanced Collateral Management Services
In today's complex financial ecosystem, effective risk mitigation and liquidity optimization are paramount for institutional success. The implementation of modern Collateral Management Services enables financial institutions to streamline asset utilization, comply with stringent global regulatory mandates, and minimize credit risk across diverse portfolios. As markets evolve toward greater automation, adopting robust collateral frameworks has transitioned from a back-office necessity to a critical strategic advantage.
📊 Get a Free Sample Report + All Related Graphs & Charts:
Market Overview and Dynamics
The global financial landscape is experiencing a transformative shift, heavily driven by the increasing demand for operational efficiency and real-time risk management solutions. According to recent market evaluations, the collateral management services market is estimated to reach approximately $15 billion by the base year 2025. Furthermore, the market is projected to expand at a robust compound annual growth rate (CAGR) of around 12% over the forecast period. Primary growth drivers include escalating regulatory pressures such as uncleared margin rules (UMR), the continuous need for optimized liquidity, and technological advancements like blockchain and cloud computing integration. However, the market faces certain challenges, including high implementation costs associated with legacy system integration and complex cross-border regulatory compliance frameworks. Despite these hurdles, ongoing innovations in automated asset allocation and intelligent margin optimization are creating lucrative opportunities for market participants.
Segmentation Analysis
|
Segment Type |
Sub-Segment Example |
Forecast CAGR (2024–2032) |
|
Application 1 |
Banking and Finance |
12.5% |
|
Application 2 |
Enterprise |
11.2% |
|
Application 3 |
Others |
10.8% |
|
Type 1 |
Cash Collateral Management Services |
11.9% |
|
Type 2 |
Derivatives Collateral Management Services |
12.4% |
|
Type 3 |
Securities Financing Collateral Management Services |
11.6% |
Competitive Landscape and Key Players
The competitive environment of the collateral management services market features a dynamic mix of established financial market utilities, global custodian banks, and specialized technology vendors striving for market dominance through strategic partnerships, technological enhancements, and service portfolio expansions. Prominent companies covered in this comprehensive report include Hong Kong Exchanges and Clearing Limited, Deutsche Börse, Euroclear, State Street Corporation, Broadridge Financial Solutions, Inc, European Central Bank, Bank of England, SmartStream Technologies ltd, FirstRand Bank Limited, OpenGamma, BNP Paribas, ASEE Group, LCH Group, and CME Group Inc.
Regional Outlook
The report provides a thorough geographical analysis covering key regions, including North America (United States, Canada, Mexico), South America (Brazil, Argentina, Rest of South America), Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), and Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific). North America and Europe currently dominate the market share due to stringent regulatory frameworks and advanced financial infrastructures, whereas the Asia Pacific region is anticipated to showcase the fastest growth rate, propelled by rapid digitization and expanding financial sectors in emerging economies.
📊 Explore the full report for deeper insights:
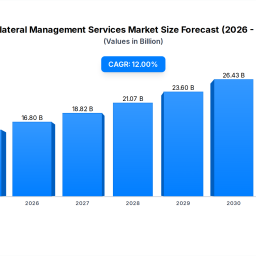
Table of Contents (TOC)
- 1. Introduction and Research Methodology
- 2. Executive Summary
- 3. Market Dynamics (Drivers, Restraints, Opportunities, and Challenges)
- 4. Global Collateral Management Services Market Analysis and Forecast by Application
- 5. Global Collateral Management Services Market Analysis and Forecast by Type
- 6. Regional Market Analysis and Forecast
- 7. Competitive Landscape and Company Profiles
- 8. Strategic Recommendations and Future Outlook
📊 For complete insights, forecasts, and data tables, visit the full report:
Contact US:
Craig Francis (PR & Marketing Manager)
Data Insights Market
Ansec House, 3rd Floor, Tank Road
Yerwada, Pune
📞 Phone: +1 231-515-5523
📧 Email: sales@sectordatainsights.com