



PW Consulting: Cold Box Resin Casting Market Set to Expand at a 5.1% CAGR in the 2026–2032 Forecast

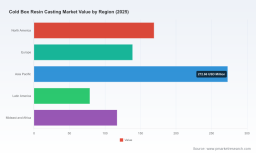
Cold Box Resin Casting Market: Strategic Preview for 2026 — PW Consulting Report Highlights
PW Consulting’s new Cold Box Resin Casting Market study (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a focused, decision-ready intelligence package for executive teams preparing strategy in 2026. The industry has moved from a mid-single‑hundred‑million USD base five years ago to an enlarged addressable market in 2025, and our forecast shows continued expansion through 2032 at a compound annual growth rate (CAGR) of 5.1%. This executive preview outlines why the dataset and strategic playbooks in the full report will be essential to procurement, product, and M&A leaders — while keeping the granular segment tables and vendor scorecards reserved for subscribers.
Cold Box Resin Casting Market
Why this report matters for 2026 decision-makers
-
Actionable foresight: Our analysis converts macro trends (raw material volatility, tightening VOC regulations, and shifting foundry economics) into clear decision triggers for 2026 capital and sourcing choices.
Cold Box Resin Casting Market -
Risk-to-return clarity: We combine market sizing, scenario forecasts and sensitivity models so leaders can weigh investments in low‑emission binders, process upgrades, or bolt‑on M&A with quantified upside and downside.
Cold Box Resin Casting Market -
Vendor and technology playbooks: The report benchmarks incumbent resin suppliers, emerging chemistries and plant‑scale retrofit approaches to accelerate time-to-value for product and operations teams.
Market trajectory in one glance (high level)
Between 2020 and 2025 the Cold Box Resin Casting market experienced sustained expansion, reflecting recovering foundry activity and incremental technology adoption. By our accounting the market grew significantly between 2020 and 2025 and is projected to continue expanding through 2032, with a modeled CAGR of 5.1% over the forecast period. The full report provides the year-by-year historical series, 2026–2032 forecast scenarios and a downloadable forecasting model that lets clients stress-test assumptions against raw‑material price pathways and demand shocks.
Key market dynamics shaping 2026 strategies
-
Raw‑material volatility — phenol & isocyanate: Price moves matter. Phenol and isocyanate — core inputs for many cold box binders — experienced a sharp increase (notably a strong spike between 2022 and 2023). That volatility forced pricing adjustments across the value chain, squeezed margins and changed procurement behaviours (Industry Market Data, March 2026).
-
Margin compression and price pass‑through: In early 2025 volatile raw material markets led to an observable reduction in manufacturers’ profit margins. A majority of resin producers implemented pricing revisions; many applied unit price uplifts in response to input costs (Industry Market Data, March 2026).
-
Regulatory tightening and emission control: Intensifying regulations on VOCs and labelling requirements (including relevant CLP impacts) are increasing compliance costs for foundries and shifting demand toward low‑emission, low‑formaldehyde and solventless systems (F.lli Mazzon S.p.A., 2026; Industry Market Data, March 2026).
Supply chain & pricing sensitivity — strategic implications
Procurement teams can no longer treat binders as a simple commodity buy. The combination of raw‑material supply risk and regulatory pressure creates a three‑pronged set of options for buyers and producers:
-
Hedge and diversify inputs: Multi‑sourcing and forward contracting for phenol and isocyanate derivatives reduce exposure to single‑vendor disruptions and price spikes.
-
Invest in alternative chemistries: Solventless, plant‑based and reduced‑VOC formulations are not only compliance enablers but are becoming differentiators in tender processes.
-
Operational mitigation: Foundries can realize quick margin recovery by optimizing binder usage rates through process controls and by investing in fume‑extraction or capture equipment that reduces VOC levies.
Competitive landscape — who to watch and why
The market remains moderately concentrated (top‑three players account for roughly half of industry volumes, while a top‑five bracket controls materially more). Leading global and regional suppliers are pursuing differentiated strategies across product chemistry, low‑emission formulations and foundry service models.
-
ASK Chemicals (Dublin, Ohio) — Emphasis on low‑emission, solventless phenolic‑urethane systems (ISOCURE, ECOCURE series) aimed at aluminum, steel and iron cores; positions itself on formulation performance and emission reduction.
-
Hüttenes‑Albertus Group / HA International (Düsseldorf / Westmont) — Broad portfolio with reduced‑VOC and plant‑based options (Sigmacure, Biocure, etc.); leveraging global labs to accelerate regulatory‑compliant product rollouts.
-
Vesuvius Group / Foseco (London) — Focus on gas‑setting and polyurethane systems optimized for foundry process integration; strength is in application engineering and multi‑alloy capability.
-
REFCOTEC (Orrville, Ohio) and United Erie (Pennsylvania) — Phenolic urethane and other tailored binders for core production, competing on service and formulation breadth.
-
Jinan Shengquan Group (Jinan) and IVP Limited (India) — Concentrated on high‑volume, cost‑efficient amine‑catalyzed phenolic systems for automotive and industrial foundries in high‑growth regional markets.
-
Furtenbach (Germany), Mancuso Chemicals (Canada), Asahi Yukizai (Japan) and F.lli Mazzon (Italy) — Prioritizing niche differentiation such as aromatic‑solvent‑free resins, rapid‑curing systems and low‑formaldehyde binders for premium and regulated segments.
What the PW Consulting report delivers (practical contents)
-
Market sizing & forecast model (historical 2020–2025; base year 2025; forecast scenarios 2026–2032) — interactive spreadsheet for in‑house sensitivity testing.
-
Macro to micro scenarios — baseline, commodity‑shock, and accelerated‑regulation cases with quantified P&L impacts for producers and foundries.
-
Supplier capability matrix — high‑level benchmarking of global players across chemistry, low‑emission credentials, application breadth, and foundry support services.
-
Raw‑material risk heatmap — phenol/isocyanate exposure analysis, substitute pathways and procurement levers.
-
Regulatory compliance navigator — mapping VOC and labeling regimes affecting binder selection plus mitigation options for foundries.
-
M&A & partnership playbook — acquisition targets, value creation roadmaps and integration KPIs for quick synergy capture.
-
Go‑to‑market and innovation priorities — product development templates for low‑VOC binders, pilot design for scale‑up and customer adoption frameworks.
How to use this intelligence in 2026 — recommended decision triggers
-
Procurement: If your binder spend exceeded threshold X (use the interactive model), initiate multi‑year supply contracts with indexed passthrough clauses and option windows for alternative chemistries.
-
Operations: Prioritise piloting solventless and low‑VOC binders on high‑volume lines where emissions penalties or permitting costs are projected to rise.
-
Product: Redirect R&D to lower‑formaldehyde urethane and phenolic blends that preserve mechanical performance while improving regulatory positioning.
-
M&A: Screen regional formulators with strong low‑VOC portfolios or proprietary catalysts that reduce cure time — these are high‑leverage targets under both margin and regulation scenarios.
Methodology note
The study integrates primary interviews with foundry managers, binder chemists and procurement leads, proprietary pricing and shipment datasets, and triangulation against public filings and regulatory databases. Our forecast scenarios use bottom‑up demand drivers (casting tonnages, alloy mix and binder intensity) combined with top‑down macro controls for commodity pricing and regulatory tightening.
Next steps & where to get the full intelligence
This release is a strategic preview intended to demonstrate the practical value of the full Cold Box Resin Casting Market report for 2026 planning. The complete report includes the detailed segmentation tables, per‑company scorecards, downloadable forecast model and regulatory checklists that procurement, product and corporate development teams will need to execute confidently in 2026. For access to the full dataset, bespoke briefings and licensing of the forecasting model, contact PW Consulting or visit our report page to download the subscriber package.
Note: Selected industry facts cited in this preview include: phenol/isocyanate price movements and their market impact (Industry Market Data, March 2026) and evolving CLP and low‑formaldehyde regulatory consequences (F.lli Mazzon S.p.A., 2026).
For detailed analysis of this topic, please visit the official page: Cold Box Resin Casting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


