



PW Consulting Forecast: Aerogel Market Poised to Grow at a 13.8% CAGR During 2026–2032

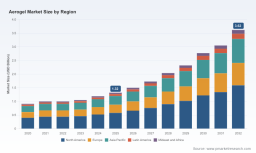
Aerogel Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive summary
PW Consulting’s latest Aerogel Market report (base year 2025; historical 2020–2025; forecast 2026–2032) maps a rapidly maturing sector that is transitioning from niche high‑tech use cases to broader industrial adoption. Our model indicates the global aerogel market will grow from an estimated USD 1.32 Billion in 2025 to roughly USD 3.62 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 13.8% across the forecast window. For executive teams planning capital allocation, product roadmaps, or M&A playbooks in 2026, this trajectory creates both time‑sensitive opportunities and strategic risks that require targeted, data‑driven responses.
Aerogel Market
Why 2026 is the inflection point
- Commercial scale-up is reaching a tipping point. Multiple producers have moved from pilot to full‑scale lines and blanket panel manufacture is beginning to reach the volumes required by energy, transportation and industrial insulation markets.
- Value migration beyond thermal insulation is accelerating. Aerogel formulations are being designed for EV battery safety, acoustic insulation, fire protection and lightweight structural uses, broadening total addressable markets for incumbent and new‑entrant manufacturers.
- Policy and procurement drivers are coalescing. Carbon accounting, stricter thermal performance regulations, and industrial decarbonisation targets are raising the procurement priority for high‑performance insulation, making 2026 a year of contract formation and supplier re‑ranking.
Data‑driven clarity — without giving away the farm
We present headline macro sizing and trajectory here to orient decision‑makers. The full report contains the granular segmentations, price decks, supplier scorecards and contract templates you need to execute. In this briefing we deliberately withhold discrete region‑ and application‑level percentage splits and individual product revenue lines to preserve the commercial value of the primary research; the detailed splits and downloadable financial models are available in the full PW Consulting report.
Aerogel Market
Key growth drivers and headwinds
- Demand pull from electrification: OEMs and tier‑ones seeking improved EV battery thermal management and fire prevention are committing to materials that balance thermal resistance with low mass and form factor flexibility.
- Industrial insulation replacement cycles: Asset owners in energy and process industries are pursuing retrofit programs where aerogel blankets and panels deliver lifecycle cost advantages despite higher upfront price points.
- Manufacturing scale and unit‑cost momentum: Recent capacity additions and continuous production innovations are compressing cost curves, improving availability, and enabling new configurations (monolithics, blankets, granules).
- Regulatory and trade complexity: Tariffs on silica precursors and specialized equipment, carbon border mechanisms, and rising scrutiny on embodied carbon are reshaping sourcing strategies and supplier risk profiles.
- Raw material and input volatility: While metallurgical silicon prices showed pockets of stability into late 2025, volatility remains — including measured upticks in silicone‑related indices in North America in 2026 — which can quickly affect margin for manufacturers with thin hedging strategies.
Competitive landscape — who matters and why
The aerogel industry today is a mixed structure of established specialty chemical and advanced materials firms plus agile pure‑play aerogel producers. Competitive advantage is being forged along three vectors: scale and cost of production, product form‑factor and performance, and go‑to‑market partnerships in adjacent value chains (e.g., EV battery systems, construction supply, energy OEMs).
Aerogel Market
- Aspen Aerogels, Inc. — A de facto commercial leader, Aspen has invested in flexible silica aerogel blankets and focused go‑to‑market channels in energy and EV battery applications. Their scale and field experience give them preferred supplier status in many industrial contracts.
- Cabot Corporation — Cabot’s continuous ambient‑condition particulate silica processes and experience in thermal management for batteries provide a differentiated materials approach suited for high‑volume, high‑consistency applications.
- Aerogel Technologies, LLC — With a portfolio spanning monolithics, panels and custom solutions, Aerogel Technologies competes on product breadth and engineered systems for scientific and industrial users.
- Armacell International — Armacell’s ArmaGel series targets industrial thermal and fire protection with global manufacturing footprints that accelerate project delivery for asset owners and EPCs.
- LG Chem Ltd. — Leveraging large‑scale plant operations, LG Chem targets the EV battery thermal barrier market with an emphasis on fire prevention and integration into battery module manufacturing.
- Alkegen — Alkegen’s recent commercialisation of its proprietary AlkeGel material and step‑ups in production capacity position it as an aggressive challenger in the EV safety segment.
- Svenska Aerogel, Green Earth Aerogel, Nano Technology Co., Active Aerogels, Resonac — These regional and technology‑specialist players are important for niche applications and local supply chains; their engineered formulations and partnerships can be decisive in specific tenders.
Recent market moves illustrate strategic posturing: Alkegen announced full‑scale commercial production for EV battery applications in mid‑2025; Armacell expanded manufacturing capacity in 2024 and launched a higher‑temperature product line in late 2024; partnerships such as the strategic distribution arrangement between Foli Aerogel and Aerogel Technologies in 2025 show the growing importance of channel plays. These events are not isolated — they are part of a pattern of capacity additions, product iterations, and route‑to‑market alignments that will define supplier hierarchies through 2026.
What PW Consulting’s report delivers — practical, executable content
Beyond headline sizing and forecasts, the full report is built as a toolkit for 2026 decision cycles. Highlights include:
- Decomposed market models (historical to 2025, base year 2025, detailed forecasts 2026–2032) with scenario variants and sensitivity to raw‑material, tariff and adoption‑speed assumptions.
- Supply‑side maps and a capacity tracker that connect production technology to unit costs, scale economics and likely commercialization timelines.
- Supplier due‑diligence templates, negotiation playbooks and RFP scorecards tailored for large procurement events (EPC, OEM, fleet electrification programs).
- Unit economics and component price decks (confidential appendices) for capex planning, break‑even analyses and contract pricing strategies.
- Regulatory impact matrices and embodied carbon scenario analyses, including potential consequences of carbon border adjustments and tightened European environmental standards.
- M&A and partnership heat maps identifying targets across technology, capacity and geography, plus near‑term integration risk checklists.
- Technology roadmaps that benchmark silica, polymer and carbon‑based aerogels against alternative thermal and fire safety solutions, with R&D priority recommendations.
- Interactive dashboards and downloadable financial models to stress‑test investment cases and prioritize use cases by ROI, time‑to‑market and strategic fit.
Strategic recommendations for 2026
- Prioritise supplier partnerships that combine scale with product validation in your end market. For OEMs and major energy companies, anchoring a preferred supplier relationship in 2026 will secure supply and price advantage as demand ramps.
- Adopt a dual track: secure short‑term off‑take and pilot projects while participating in equity or strategic investments to capture long‑term upside from capacity expansions. Where financial exposure is constrained, consider structured offtake with price collars.
- Factor regulatory and carbon considerations into sourcing decisions today. Hedging material and embodied‑carbon risk through diversified suppliers and pre‑qualified low‑carbon feedstock pathways will reduce procurement disruption risk from tariffs and CBAM‑style measures.
- Embed aerogel unit economics into product design early. For product teams (EV battery packs, industrial equipment, building components), small design shifts that reduce required material volume can materially alter total system cost and adoption probability.
- Use scenario and sensitivity analysis to plan capex: only greenlight large‑scale investments after stress‑testing against slower adoption and higher input‑cost outcomes; maintain agility with modular plant designs where possible.
Risks to monitor closely
- Input price volatility: short windows of silicone and silicon feedstock price movement can compress margins for vertically exposed suppliers without hedging strategies.
- Trade and regulatory shifts: tariff changes or stricter standards on embodied carbon could re‑order supply competitiveness and import flows.
- Concentration and customer power: growth will attract entrants, but procurement consolidation among large OEMs could concentrate negotiating power and pressure supplier pricing.
How to access the full intelligence
This release is intended as an executive‑level primer. The PW Consulting Aerogel Market report contains the confidential segment economics, supplier scorecards, downloadable models and tender templates necessary to operationalise a 2026 strategy. For access to the full dataset, primary interviews, and the interactive dashboards referenced above, visit PW Consulting’s Aerogel Market report page or contact our industry team for a briefing and tailored workshop.
In short, 2026 will be a defining year for organisations that wish to convert aerogel’s technical promise into commercial advantage. The choices made this year about partners, plant footprints, and product design will determine who captures the upside as the market scales toward our 2032 outlook.
For detailed analysis of this topic, please visit the official page: Aerogel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


