



PW Consulting: Industrial Cameras Market to Reach USD 455.0 Million by 2032, Growing at a 7.6% CAGR (Base Year 2025; 2026–2032 Forecast)

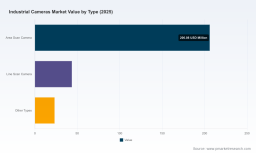
Industrial Cameras Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Intelligence
PW Consulting today publishes a forward-looking industry briefing that synthesizes our 2025 base-year market model and a robust forecast to 2032 for the global industrial cameras market. Built from a validated historical series (2020–2025) and scenario-tested assumptions for 2026–2032, the report equips executives with the commercial and operational levers they will need to act confidently in 2026. This release intentionally showcases the analytical depth of our work while withholding primary segment tables and granular regional shares to motivate direct engagement with the full report and underlying datasets.
Industrial Cameras Market
Market snapshot: scale, trajectory, and concentration
Using 2025 as the base year, our core forecast shows the market continuing to expand at a mid-single-digit compound annual growth rate (CAGR) of 7.6% through the 2026–2032 horizon. In absolute terms, the industry—measured in USD Million revenue—has moved from a clearly recoverable post‑pandemic baseline in the early 2020s to materially larger market sizes by the end of the forecast. The 2026 inflection reflects renewed capex cycles across factory automation, logistics automation, and data-capture applications; by 2032 the market is projected to be substantively larger than in 2025.
Industrial Cameras Market
Market concentration is notable: the top three suppliers account for a majority of sales, while the top five increase share materially, translating into a CR3 of 55.2% and CR5 of 67.8%. That structure creates both competitive pressures and strategic opportunities: incumbents gain margin and scale advantages, but focused challengers can win on specialization, software ecosystems, and channel strategies.
Industrial Cameras Market
What PW Consulting’s report delivers (practical, decision-ready resources)
- Closed-form market model (USD Million revenue, base year 2025) with high/central/low scenarios for 2026–2032—designed for board-level briefing decks and integration into financial planning systems.
- Actionable go-to-market playbooks for hardware OEMs, system integrators, and component suppliers that balance direct sales, distribution, and strategic partnerships.
- Technology roadmaps mapping sensor innovation (including low-light sCMOS and thermal modules), interface standards, and edge-compute integration—paired with R&D investment guidance tied to expected time-to-market shifts.
- Regulatory and supply-chain risk matrix covering export controls, critical minerals, and compliance pathways—complete with contingency triggers for sourcing and localization strategies.
- Competitive landscaping with vendor scorecards, capability matrices, and a curated list of potential M&A and JV targets ranked by fit and integration risk.
- Commercial diagnostics and pricing playbooks that translate market size and concentration dynamics into margin optimization tactics for 2026 procurement cycles.
Competitive landscape: what the established vendors are doing now
The market remains populated by a mix of global platform providers, specialist imaging companies, and systems vendors who embed cameras into larger automation stacks. Key incumbents continue to differentiate along three vectors: sensor & optics performance, platform software/integration, and global go-to-market reach.
- KEYENCE CORPORATION (Osaka, Japan) — continues to leverage tightly integrated hardware-software offerings and a direct-sales field force to command premium pricing in high-throughput semiconductor and electronics inspection. Their playbook favors system-level differentiation over component commoditization.
- Basler AG (Ahrensburg, Germany) — maintains a broad product portfolio across area and line-scan cameras and is investing in interface and ecosystem compatibility to protect industrial channel relationships in Europe and beyond.
- Teledyne Technologies (including FLIR IIS / Vision Solutions) — combines visible and thermal imaging capabilities, which creates unique solutions-selling options for robotics and quality assurance. Note: companies in this grouping are operating under heightened regulatory scrutiny in several jurisdictions, which is an active risk vector for buyers and partners.
- The Imaging Source (Bremen, Germany) — a high-volume, product-focused supplier emphasizing USB/GigE camera lines for repeatable production-line applications and rapid time-to-delivery advantages for OEMs.
- IDS Imaging Development Systems GmbH (Obersulm, Germany) — positions itself on developer friendliness and AI-enablement at the edge, offering modular camera systems with software toolkits that shorten integrator cycles for semiconductor and electronics inspection.
- TKH Group (TKH Vision, Eindhoven, Netherlands) — brings 2D/3D system integration experience and is a strong choice for customers seeking turnkey machine vision subsystems rather than component purchases.
- Cognex Corporation (Natick, Massachusetts, USA) — continues to integrate cameras tightly with its vision software stack, emphasizing application-specific performance and enterprise-grade support that appeals to high-reliability manufacturing.
For buyers, this means vendor selection is more than price competition: it is a holistic evaluation of support, software lifecycle, sensor roadmap, and supply-chain resilience. Our vendor scorecards quantify those trade-offs (available in the full report).
Dynamics & systemic risks shaping 2026 decisions
A confluence of regulatory and supply-chain events has reshaped the risk profile for the industry. Several developments warrant particular attention:
- Export-control dynamics and enforcement actions have increased commercial compliance costs and created near-term supplier uncertainty. Buyers and investors should assume higher due diligence requirements and potential re-routing costs in vendor contracts.
- Concentration risks in critical minerals and semiconductor inputs raise the probability of episodic supply shocks. Recent multilateral ministerial activity signals geopolitical will to rework these supply chains—but reconfiguration timelines extend beyond typical procurement cycles.
- Standards evolution is accelerating—example: the latest iteration of a leading high-speed machine-vision interface standard was released in mid-2026. Vendors that rapidly certify and integrate the new standard stand to lower integration friction with modern edge systems and robotics platforms.
- Product innovation continues apace: suppliers are commercializing ultra‑low-light sCMOS modules and hybrid visible/thermal sensors, providing new value in logistics and automated-inspection niches. Early movers gain both reference wins and IP advantages.
Strategic recommendations for 2026 corporate decision-makers
We designed the following recommendations to be executable within the 2026 planning cycle. Each recommendation aligns to the market model and risk scenarios contained in the full report.
- Re-balance supplier portfolios for resilience and optionality. Build layered sourcing strategies to mitigate critical input concentration. Prioritize dual-sourcing for high-risk components and negotiate cost pass-through clauses linked to geopolitical trigger events.
- Invest selectively in standards compliance and certification. Allocate budget to certify new interface standards and to validate interoperability with major robotics/PLC vendors—this reduces time-to-integration and is a high-return commercial investment.
- Prioritize product lineups by value elasticity, not volume alone. Use our market model to stress-test pricing strategies across component scarcity and demand shock scenarios; protect margins by differentiating through software, calibration services, and extended warranties.
- Stand up an M&A playbook focused on software and niche sensors. With market concentration favoring platform vendors, targeted acquisitions of AI-software players, edge-inference vendors, or specialized sensor makers can accelerate entry into adjacent automation segments with lower integration risk than greenfield builds.
- Embed compliance and localization into contract templates. Move from reactive to proactive compliance by elevating export-control checks into supplier scorecards and including localized supply commitments where strategic risk warrants.
- Monetize after-sales and data services. Create annuity streams via calibration-as-a-service, health monitoring, and model-updates for AI-based inspection. These services improve customer stickiness and smooth revenue cyclicality.
- Use scenario planning to inform capex and inventory strategy. Our three-tier scenarios highlight different inventory and production implications—use the central and downside scenarios to set conservative working capital limits while maintaining optionality for upside demand.
How to use this briefing—and where to find the full intelligence
This briefing is a directional summary intended for senior leadership and strategy teams preparing 2026 plans. The full PW Consulting Industrial Cameras Market Report contains the proprietary market model (USD Million unit), detailed vendor scorecards, product roadmaps, downloadable Excel models, and the full set of segment-level forecasts and regional allocations. To preserve the strategic value of those granular tables we have purposely omitted segment-level shares and dollar-by-dollar regional splits from this public summary.
If you are preparing sourcing contracts, technology roadmaps, investor materials, or an M&A screening shortlist for 2026 decisions, the full report provides the evidence base and ready-to-use tools that reduce execution risk and shorten decision cycles. Contact PW Consulting to request the comprehensive dataset, scenario workshop, and tailored advisory support.
For detailed analysis of this topic, please visit the official page: Industrial Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


