



PW Consulting: Hydrogen Cooling Synchronous Condenser Market to Reach USD 573.78 Million by 2032, Expanding at a 5.86% CAGR

Hydrogen-Cooled Synchronous Condenser Market — A 2026 Strategic Preview for Decision-Makers
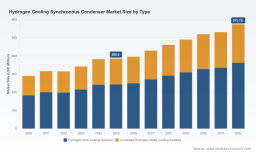
As utilities and grid operators accelerate the transition away from conventional synchronous thermal generation, hydrogen-cooled synchronous condensers are emerging as a tactical solution for large-scale inertia, short-circuit strength, and dynamic reactive-power support. PW Consulting’s latest market study — anchored on a 2025 base year and a 2026–2032 forecast horizon — projects the global market will expand at a compound annual growth rate of 5.86% through 2032, reflecting a steady rise in demand from utility, transmission, and industrial buyers. Our modelling shows the market moving from approximately USD 385.4 Million in 2025 toward a materially larger opportunity by the end of the forecast window, underscoring why 2026 is the year organizations should convert strategy into procurement and partnership action.
Hydrogen Cooling Synchronous Condenser Market
Why 2026 is an inflection point
-
System-strength needs are shifting from short-term pilot projects to portfolio-level planning. As large synchronous plants retire, grid operators are increasingly issuing tenders and building Renewable Energy Zone (REZ)-style programs that require engineered solutions for inertia and voltage control at gigawatt scale.
Hydrogen Cooling Synchronous Condenser Market -
Hydrogen cooling has resurfaced as the preferred thermal management approach for high-capacity rotating machinery in utility contexts because of its superior thermal conductivity and low density — characteristics that enable higher continuous ratings and improved electrical efficiency versus air-cooled alternatives. That technical edge is material when sizing assets that must deliver sustained reactive power and inertia to renewables-heavy grids.
Hydrogen Cooling Synchronous Condenser Market -
Procurement and project pipelines have begun to converge into real contracts and EPC awards. Recent vendor wins and consortia activity demonstrate an active market where execution capability, local presence, and hydrogen-handling expertise are decisive procurement filters.
What PW Consulting’s report delivers — practical outputs for 2026 decisions
Our report is structured to be immediately operational for corporate strategy, procurement, and project teams evaluating synchronous condenser options in 2026. Key actionable components include:
-
Market sizing and scenarios: a transparent methodology covering historical trends (2020–2025) and a detailed forecast (2026–2032) with scenario stress-testing to evaluate demand under different renewable rollout, retirement, and policy pathways.
-
Vendor benchmarking and capability maps: qualitative and quantitative scores for OEMs, EPCs, and integrators across technology maturity, hydrogen-cooling experience, modularity, digital diagnostics, and local content.
-
Procurement playbook and contract templates: recommended commercial terms, performance guarantees, acceptance tests, and hydrogen-specific clauses (purity, leak-rate warranties, safety training, and maintenance obligations).
-
Total cost-of-ownership models: capex/opex comparison tools that capture cooling-system trade-offs (hydrogen-only, combined hydrogen-water, air/TEWAC variants), lifecycle maintenance, spare-parts logistics, and reliability assumptions — model variants remain interactive to support buyer-specific inputs.
-
Site-integration and O&M guidance: engineering checklists for hydrogen handling, sealing systems, gas-management, port and transport constraints, and maintenance regimes tailored to different climate and regulatory environments.
-
Deal flow and contract database: curated summaries of recent awards, EPC arrangements, consortiums, and project timelines to help procurement teams benchmark lead times and negotiation points.
To preserve commercial value for report subscribers — and to comply with the “trailer” principle of this press release — we present the analytical depth and practical use cases above while withholding granular segment and regional figures here. The full dataset and interactive models are available in the complete report.
Competitive landscape — who matters in 2026
The market exhibits meaningful concentration at the top. The three largest suppliers control a notable majority of deployed capacity, with the top five firms collectively holding an even larger share — a structural reality that shapes pricing power, lead times, and technology diffusion. For buyers and investors this concentration translates into a small set of preferred partners capable of meeting the largest utility-scale, hydrogen-cooled requirements.
Key vendor archetypes and strategic positioning:
-
Legacy rotating-machinery incumbents with deep hydrogen experience and global service networks (e.g., historic hydrogen-cooled generator developers). These firms excel in high-rating machines, long-term O&M contracts, and white-space leverage into synchronous condenser configurations.
-
Electrification and grid-systems specialists that package advanced control systems, high-inertia options, and turnkey offerings for REZs and transmission-scale retrofits. Their strengths lie in systems integration and proven project delivery across challenging regulatory regimes.
-
Regional players and new entrants that compete on local manufacturing, competitive pricing, and flexibility in tender responses — critical where localization rules or rapid deployment windows dominate procurement criteria.
Recent contract activity signals how these archetypes are translating capability into backlog. Highlights include major awards covering multi-unit supplies to transmission networks and REZ projects, consortium-driven EPC contracts in large interconnection zones, and targeted single-unit deployments to shore up system strength in regions undergoing rapid coal-to-renewables transitions. These developments confirm two immediate lessons: (1) buyers value end-to-end execution capability that spans hydrogen handling, commissioning, and long-term service, and (2) first-mover procurement decisions in 2026 will shape local supply chains and aftermarket economics for years.
Technical and operational preconditions for hydrogen-cooled success
-
Hydrogen handling and purity controls: hydrogen’s flammability and diffusion characteristics require specialized sealing systems, purity regimes, and leak-detection infrastructures. These are not add-ons — they materially affect lifecycle risk profiles and maintenance scheduling.
-
Safety, regulation, and site planning: project teams must coordinate early with local authorities on safety cases, training, and emergency response capability. Tender specifications that ignore these upstream costs materially underprice true lifecycle obligations.
-
Digitalization and remote diagnostics: real-time monitoring of shaft vibration, hydrogen pressure, and cooling-system thermal profiles reduces forced outages and optimizes maintenance windows — a differentiator in vendor selection.
-
Maintenance and spare-parts strategies: long-lead components for hydrogen systems and high-capacity rotors necessitate a strategic spares plan or guaranteed availability clauses in supplier contracts.
Policy, procurement and supply risks to watch in 2026
-
Regulatory direction on grid codes and resource adequacy will continue to drive demand, but tender specifications remain mixed: some transmission operators favor hydrogen-cooled solutions for large ratings, while others explicitly specify non-hydrogen options to reduce operational complexity. Procurement teams must therefore align technical specs with the regulatory appetite in target grids.
-
Hydrogen supply-chain and component market dynamics: while hydrogen consumption within synchronous condensers is modest by energy-system standards, the requirement for certified gas-handling equipment, seals, and testing capacity creates supply concentration risks that can extend lead times.
-
Commodity and logistics volatility: large rotating machinery is sensitive to lead-time inflation and port/logistics constraints. Early contracting and clear acceptance criteria materially reduce schedule risk.
How to act in 2026 — tactical recommendations for executives
-
Integrate synchronous condenser strategy into capital-planning cycles now. Use multi-scenario procurement timelines that account for manufacturer lead times, site readiness, and grid-code updates.
-
Prioritize vendors with documented hydrogen-cooled experience and validated service offers. Where local content requirements matter, evaluate tiered contracting approaches that combine global OEM capability with regional manufacturing partners.
-
Insist on transparent lifecycle modelling from bidders. Ask for sensitivity analyses on hydrogen-management costs, seal-replacement schedules, and digital monitoring guarantees.
-
Embed safety and regulatory deliverables within commercial milestones. Early regulatory engagement is often the single largest determinant of on-time commissioning.
-
Consider strategic partnerships or minority investments to secure preferential design and supply queue positions if your 2026–2028 project pipeline depends on highly rated hydrogen-cooled machines.
Conclusion — a pragmatic outpost in an evolving market
Hydrogen-cooled synchronous condensers are not a generic plug-in; they are a specialist choice that unlocks higher continuous ratings, efficiency, and grid-strength capabilities for large renewable integration projects. With market momentum, a clear set of incumbent suppliers, and a forecasted multi-year expansion at a mid-single-digit CAGR, 2026 is the year to convert strategy into binding procurement choices or strategic partnerships. PW Consulting’s full market study provides the confidential segment-level data, vendor scorecards, financial models, and contract templates you need to execute with confidence.
About PW Consulting
PW Consulting advises utilities, OEMs, investors, and government agencies on decarbonization technologies and grid modernization. Our Hydrogen-Cooled Synchronous Condenser Market report combines project-level intelligence, vendor due diligence, engineering constraints, and commercial playbooks to support capital decisions in 2026 and beyond. For the full dataset, interactive models, and procurement templates, access the complete report via PW Consulting’s official channels.
For detailed analysis of this topic, please visit the official page: Hydrogen Cooling Synchronous Condenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


