



PW Consulting Forecast: Global Medical Device Calibration Services Market to Expand at a Robust 9.25% CAGR Through 2032

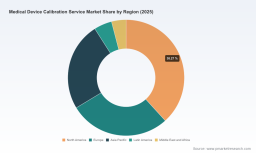
Medical Device Calibration Service Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s new market research brief on the Medical Device Calibration Service market delivers a focused strategic lens for decision-makers preparing plans in 2026. Built on a rigorous base year of 2025, the study synthesizes five years of historical data (2020–2025) and an actionable forecast (2026–2032), projecting a compound annual growth rate (CAGR) of 9.25% through the forecast window. The market value in 2025 stood at USD 2,156.16 Million (Revenue unit: Million, USD); our model anticipates sustained expansion to just over USD 4,005 Million by 2032. This trajectory reflects accelerating compliance demands, equipment complexity, and a shift to managed service models in clinical and manufacturing environments.
Medical Device Calibration Service Market
Why this brief matters for 2026 corporate decisions
-
Timing matters. The market is transitioning from routine piece-rate calibrations toward integrated service offerings that combine on-site response, accredited lab traceability, digital evidence chains, and outcome-based SLAs. 2026 is the year many buyers will convert pilot programs into procurement standards; suppliers who set the commercial terms now will capture durable margins.
Medical Device Calibration Service Market -
Regulatory tailwinds are driving demand for accredited, traceable calibration. ISO/IEC 17025 accreditation, ISO 13485-aligned systems, and evolving FDA expectations (including ASCA pathways and requirements around 21 CFR Part 820.72) are shifting procurement criteria from price-only to competence, traceability, and defensible data management.
Medical Device Calibration Service Market -
Fragmented competitive dynamics create opportunity windows. Despite the presence of global incumbents, market concentration remains low (CR3 ~18.45%; CR5 ~26.8%), signaling substantial room for regional consolidators, niche specialists, and technology-enabled entrants to scale rapidly.
Headline market signals — what the numbers reveal (and what we intentionally reserve)
-
Historical momentum: the market expanded materially between 2020 and 2025, reflecting increased device volumes, replacement cycles, and stricter compliance checks in healthcare delivery and device manufacturing.
-
Near-term outlook: our forecast shows a steady acceleration beginning in 2026 as national quality infrastructures and mobile calibration capabilities mature in key growth markets.
-
Note on disclosure: to preserve the integrity of commercial insights and to drive direct engagement, this release highlights macro scale and dynamics while withholding granular regional, service-type, and device-type revenue splits. The full report contains the segment-level intelligence buyers and investors need to act decisively.
What the report contains — practical, transaction-focused deliverables
-
Market model and scenario frameworks: transparent bottom-up and top-down models reconciling historical datapoints with 2026–2032 scenarios (base, upside, downside) and sensitivity to regulatory and macroeconomic inflections.
-
Buyer personas and procurement playbooks: decision-tree templates for hospitals, OEMs, contract testing labs, and device manufacturers that transform compliance requirements into vendor selection criteria and SLA negotiation levers.
-
Service line economics: relative margin profiles across third-party lab services, OEM calibration offers, and in-house calibration operations; guidance on pricing architecture, attach-rate levers, and service bundling strategies.
-
M&A and partnership blueprint: valuation heuristics, integration checklists, and a prioritized target list by capability gap—designed to accelerate bolt-on and capability-driven acquisitions without exposing our premium segment-level tables in this summary.
-
Operational risk matrix and compliance checklist: end-to-end operational KPIs, traceability controls aligned to ISO/IEC 17025:2017 and ISO 13485, and recommended audit bench-marks for defending regulatory submissions (including ASCA considerations).
Competitive landscape — strategic implications from company profiles
The market displays a mix of multinational specialists, regionally focused service providers, and equipment manufacturers offering calibration as a complementary service. Our competitive layer analysis identifies four archetypes: global accredited networks, OEM-led service arms, regional niche specialists, and emerging technology-integrated disruptors.
-
Trescal (France) — A prototypical global accredited network offering ISO 17025-traceable services, capable of on-site and laboratory calibrations. Trescal’s model is instructive for companies seeking scale with compliance as a selling point: deep accreditation, cross-border logistics, and multi-standard support (ISO 13485, GMP/GLP, QSR, FDA) enable premium positioning in regulated accounts.
-
Transcat, Inc. (United States) — Demonstrates the inorganic growth path. Recent acquisitions of regional calibration laboratories have strengthened local presence and expanded capacity in healthcare and life sciences. For buyers, Transcat’s playbook highlights the efficiency of acquiring accreditation and customer relationships versus building greenfield capabilities.
-
Tektronix and Fluke Biomedical (United States) — Represent OEM/service hybrids. Their advantage is multi-brand expertise, instrument-level know-how, and the ability to cross-sell test equipment with service contracts—an attractive model for healthcare systems that prefer bundled capital and service solutions to minimize equipment downtime.
-
Regional specialists (e.g., JM Test Systems, Biomedical Technologies Inc./ISS Solutions, NS Medical Systems, Calyx Met, and a cohort of smaller players) — These firms illustrate the competitive depth of local, accredited providers. They often win on responsiveness, domain specialization (e.g., imaging or ultrasonic), and relationships with hospital biomedical engineering teams.
Strategic reading: established global players provide scale and standardization; OEMs offer lifecycle alignment; and regional specialists dominate speed-of-service. For 2026, we expect more M&A and partnership activity as global players seek density while regional firms monetize platform value.
Regulatory and infrastructure dynamics reshaping demand
-
Accreditation as a commercial differentiator — ISO/IEC 17025:2017 is increasingly treated as a baseline for market access. Additionally, the FDA’s ASCA program and statutory obligations (e.g., 21 CFR Part 820.72) are prompting buyers to accept only providers who can produce defensible, traceable calibration records.
-
National quality infrastructure investments — Public and academic initiatives are expanding capacity. Recent examples include mobile calibration facilities and apex-level national labs that will reduce turnaround times in underserved regions and increase local demand for accredited services.
-
Technology uplift — Digital calibration records, remote verification tooling, and connected test instruments are enabling new service propositions: predictive calibration scheduling, asset-health scoring, and performance-as-a-service contracts. These capabilities change margin mechanics and customer stickiness.
Recent industry moves that change the competitive map
-
Strategic acquisitions: notable roll-ups and add-on acquisitions have concentrated capabilities in specific geographies and have served as catalyst events for consolidation of laboratory footprints and client lists.
-
Public-sector capacity building: launches of mobile calibration facilities and national-level labs are creating new demand corridors and shortening calibration lead times in regions that previously relied on imports or long-distance shipments.
-
OEM service expansion and partnerships: equipment manufacturers are continuing to bundle calibration and maintenance into asset lifecycle agreements, putting pressure on independent providers to demonstrate higher-value analytics and faster service response.
Actionable recommendations for executive teams in 2026
-
For suppliers: prioritize accreditation investments and digital evidence chains. Winning proposals will couple ISO/IEC 17025 traceability with encrypted, tamper-evident calibration records and standardized reporting templates compatible with regulatory submissions.
-
For acquirers: focus on targets that deliver immediate accreditation uplift, regional density, or specialty device expertise. Avoid paying for geographic overlap without clear operational synergies—our report’s integration checklist helps quantify those synergies.
-
For buyers (hospitals and OEMs): restructure procurement toward outcome-based SLAs that measure asset uptime, compliance readiness, and total cost of service, not just per-calibration pricing. The procurement playbook in the full report contains contract language templates and KPIs.
-
For technology investors: seek opportunities in SaaS and instrumentation that enable predictive calibration, remote verification, and secure digital traceability—these are the enablers that will reconfigure supplier-buyer economics over the next three years.
How to use this brief and where to go next
This industry brief is a strategic primer intended to inform 2026 planning cycles. It articulates the macro scale, competitive archetypes, regulatory inflections, and practical steps executives should consider now. For teams preparing business plans, RFPs, M&A decks, or compliance investments, the full PW Consulting report provides the segment-level revenue tables, regional and device-type breakdowns, vendor scorecards, and playbooks necessary to move from strategy to execution.
Accessing the complete dataset and our customized advisory services will provide the specific segmentation and toolkits referenced here. PW Consulting stands ready to translate the research into a bespoke road map—whether that is a go-to-market plan for a calibration provider, an integration playbook for an acquirer, or a procurement transformation for a large healthcare system.
For licensing, bespoke briefings, or to request the full report with its granular tables and model files, please contact PW Consulting’s Industry Practice. Our team will tailor the insight package to your role—supplier, buyer, investor, or regulator—and provide the actionable deliverables to accelerate decision quality in 2026.
For detailed analysis of this topic, please visit the official page: Medical Device Calibration Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


