



PW Consulting Forecast: IT Spending on Clinical Analytics Market to Expand at 13.45% CAGR, Reaching USD 54,426.95 Million by 2032

It Spending On Clinical Analytics Market — Strategic Briefing for 2026 Decision-Makers
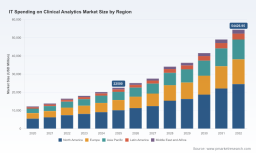
PW Consulting’s latest market study, It Spending On Clinical Analytics Market (base year 2025), arrives at a pivotal moment for health systems, payers, life‑sciences organizations and technology vendors. Our research finds that the global clinical analytics IT market has entered a sustained growth phase, with the 2025 market estimated at USD 22,500 Million and a compound annual growth rate (CAGR) of 13.45% across the 2026–2032 forecast window. By 2032 the market is projected to more than double from the 2025 baseline, underscoring that investments made this year will materially shape organizational competitiveness through the next decade.
It Spending On Clinical Analytics Market
Why 2026 is a Strategic Inflection Point
Several converging forces elevate 2026 from planning year to action year. First, rapid adoption of AI and predictive analytics is moving from pilot-to-scale in provider and payer settings, shifting budget lines from experimental R&D to core IT and clinical operations. Second, macro infrastructure trends — notably a surge in AI infrastructure investment and emerging data‑center cost and regulatory pressures — are reshaping total cost of ownership (TCO) assumptions for cloud-first architectures. Third, regulatory and national security measures around cross‑border data flows are forcing re-evaluation of global data strategies.
It Spending On Clinical Analytics Market
- Market momentum: The market’s mid‑double digit CAGR signals a durable demand curve for analytics capabilities across the care continuum, from clinical decision support to quality improvement and population health use cases.
- Concentration and competition: Our concentration analysis shows the market remains moderately fragmented (CR3 ~28.4%; CR5 ~36.2%), leaving strategic room for both incumbents and specialized entrants to capture share through differentiated offerings and vertical integration.
- Cost & regulatory headwinds: New legislation and cost allocation requirements for data centers, coupled with national restrictions on bulk health data transfers, create operational and compliance risks that can negate expected efficiency gains if not managed proactively.
What PW Consulting’s Report Delivers — Practical, Transactional Intelligence
This study is built for executives who need to translate market direction into concrete programs, investments and deals in 2026. We avoid high‑level platitudes and instead provide a layered, use‑case driven toolkit that guides procurement, architecture, clinical operations and M&A teams through implementation realities.
It Spending On Clinical Analytics Market
- End‑to‑end market sizing and forecast model (2020–2032) with sensitivity scenarios reflecting variations in AI adoption rates, cloud migration speeds, and regulatory shocks.
- Buyer personas and procurement playbooks for health systems, payers, life sciences firms and ambulatory networks — mapping decision drivers, procurement cycles and typical contract terms.
- Vendor landscaping and matchup frameworks that score vendors across data assets, analytics IP, deployment flexibility, regulatory compliance posture, and partnership ecosystems.
- Implementation roadmaps and TCO models that explicitly account for infrastructure externalities (energy & grid costs), anticipated data center legislation, and the hidden life‑cycle costs of large model deployments.
- Regulatory risk matrix and data residency playbook aligned to recent policy changes affecting health data transfers and cross‑border collaborations.
- M&A and partnership playbooks tailored to buyers and sellers aiming to scale analytics capabilities quickly while managing integration risk.
Competitive Landscape: Who Matters and Why
The competitive terrain blends enterprise IT giants, healthcare‑native analytics firms and specialized data players. Leading incumbents maintain advantages in installed base, clinical data access, and integration capabilities, while challengers focus on high‑value niches, cloud‑native architectures and advanced modeling.
- Optum (UnitedHealth Group) — Leverages one of the largest combined clinical and claims datasets; its scale supports population health optimization and risk stratification at enterprise scope. Strategic implication: buyers seeking rapid population‑level insights may trade off openness for the advantages of pre‑integrated data and managed services.
- Oracle Health (formerly Cerner) — Recent platform expansions reinforce Oracle Health’s push to unify EHR and analytics. Strategic implication: expect continued emphasis on enterprise‑grade EHR‑adjacent analytics and integrated workflows that reduce clinician friction.
- Epic Systems — Embedded analytics within a dominant EHR footprint continue to position Epic as a primary option for care coordination and real‑world evidence generation. Strategic implication: interoperability and extensibility are critical when deploying third‑party analytic modules.
- IQVIA — Strong in life‑sciences and real‑world evidence; their strengths align to outcomes research and commercial evidence generation. Strategic implication: life sciences buyers should evaluate vendors’ clinical and claims data pedigrees in tandem with analytics tooling.
- SAS Institute & Health Catalyst — Both provide advanced analytics platforms with complementary strengths: SAS in statistical modeling and enterprise analytics, Health Catalyst in clinical, financial and operational data integration. Strategic implication: platform selection should be driven by analytical depth needs versus ease of operational integration.
- GE HealthCare & Siemens Healthineers — Integration of diagnostic imaging and monitoring data with analytics yields differentiated diagnostic and workflow value. Strategic implication: organizations prioritizing imaging‑heavy pathways or hybrid device‑to‑analytics solutions find strategic value in these vendors’ portfolios.
- Merative, Philips, Veradigm, McKesson — Each brings focused capabilities across population health, connected care, ambulatory analytics and supply‑chain analytics. Strategic implication: niche strengths and partnerships often unlock quicker ROI in constrained budgets.
Recent market moves — for example, GE HealthCare’s acquisition activity to expand cloud imaging analytics and industry publications citing C‑suite prioritization of AI — signal an acceleration of consolidation around cloud and AI capabilities. These dynamics favor vendors that can demonstrate both domain accuracy and enterprise operational resilience.
Risk & Dynamics: Infrastructure, Regulation, and the Hidden Costs
Our analysis layers recent regulatory and macro trends onto traditional vendor and buyer decision criteria. Three dynamics stand out:
- Infrastructure externalities: Recent analysis highlights multi‑billion dollar annual hidden costs tied to data center operations and AI workloads, including health and environmental damages. For buyers, this means internal TCO models that ignore energy, grid upgrade, and carbon liabilities materially understate long‑term costs.
- State and federal policy shifts: Several U.S. states have advanced or enacted legislation reallocating energy and grid upgrade costs to large data center operators. These policy changes, combined with DOJ restrictions on bulk transfers of sensitive health data, force reappraisal of cloud strategies, particularly for multinational data flows and centralized model training.
- AI infrastructure boom: With industry estimates pointing to hundreds of billions in AI infrastructure investment in 2026, competition for compute and data center capacity will intensify. Procurement teams must balance latency‑ and residency‑driven choices against escalating cloud services pricing and capacity constraints.
For strategy teams, the implication is clear: technology selection decisions cannot be disentangled from energy, regulatory, and geopolitical risk assessments. Our report embeds scenario analyses that quantify the sensitivity of TCO and deployment timelines to these factors.
How Buyers Should Act in 2026 — A Playbook
Based on the study’s integrated analysis, PW Consulting recommends the following priority actions for organizations allocating 2026 budgets:
- Adopt a two‑tier investment strategy: stabilize clinical core analytics (quality, safety, CDS) while selectively funding high‑value AI pilots with clear governance and ROI thresholds.
- Rebuild TCO models to include infrastructure externalities and policy‑driven cost shifts; require vendors to disclose projected energy consumption and data‑transfer footprints for proposed solutions.
- Prioritize vendors with flexible deployment models and clear data residency controls; demand contractual SLAs that address not just uptime but compliance and data portability obligations.
- Use vendor scorecards that weigh domain data assets and model explainability as heavily as feature parity; for mission‑critical clinical use cases, prioritize clinical validation and clinician workflow fit over headline AI capabilities.
- For acquirers: target bolt‑on acquisitions that extend data assets or specialized analytics capabilities rather than repeatable engineering spend; for sellers: emphasize recurring revenue and validated clinical outcomes to maximize valuation.
What the Full Report Contains (and Why You Need It)
This press briefing is intentionally strategic and directional. The full PW Consulting It Spending On Clinical Analytics Market report contains the granular segmentation, vendor scorecards, financial models and executable playbooks that in‑house strategy, procurement and digital transformation teams require to make high‑confidence 2026 decisions. Key deliverables include:
- Detailed segmentation across components, deployment modes, applications and geographies, with downloadable financial models and sensitivity toggles (note: detailed segment tables are available only in the full report).
- Comparative vendor profiling and a decision matrix to map vendor capabilities to buyer personas and desired outcomes.
- Procurement RFP templates, contract clauses and due‑diligence checklists tailored to energy, compliance and data residency risks.
- Implementation timelines and clinical validation checklists that reduce adoption risk and accelerate time to value.
Final Word
Clinical analytics is no longer an exploratory IT line item — it is a core lever for care quality, operational resilience and commercial growth. The market’s strong growth trajectory and persistent fragmentation create an environment rich in opportunity for buyers that act decisively and for vendors that can couple clinical credibility with disciplined operational economics. PW Consulting’s full report provides the forensic detail and executable tools necessary to convert 2026 spending into sustained competitive advantage.
To access the full analytics, vendor scorecards, and downloadable financial models, visit our report page and request the comprehensive dataset and executive briefing.
For detailed analysis of this topic, please visit the official page: It Spending On Clinical Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


