



PW Consulting: Aircraft Collision Avoidance System Market to Grow at 6.5% CAGR, Reaching USD 25.09 Billion by 2032 as TCAS II/ACAS‑X Takes Lead

Aircraft Collision Avoidance System Market — Strategic Outlook for 2026: A PW Consulting Preview
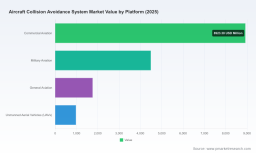
PW Consulting today publishes a strategic preview of our forthcoming Aircraft Collision Avoidance System Market report. Built on a base year of 2025 and a seven-year forecast horizon to 2032, our analysis quantifies a market that reached approximately USD 16,149 Million in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 6.5% through 2032, when our central-case projection approaches USD 25,095 Million. This preview outlines why the 2026 planning cycle is a critical inflection point for operators, OEMs, Tier‑1 suppliers, MROs, and investors navigating a complex regulatory and technological transition.
Aircraft Collision Avoidance System Market
Why this report matters for 2026 decision-making
-
Regulatory inflection: 2025–2026 marks a visible shift in certification pathways and airworthiness expectations. The FAA’s recent TSO release enabling ACAS Xu certification for unmanned aircraft systems (March 2026) and ongoing ACAS Xa/Xo transition processes require procurement teams and program managers to re-evaluate retrofit timetables, certification budgets, and fleet integration plans.
Aircraft Collision Avoidance System Market -
Technology transition: ACAS X family developments (Xa for larger transport, Xu and sXu for unmanned systems) are moving from research to operational demonstration. This reduces nuisance alerts and supports mixed manned–unmanned operations, but it also introduces software‑centric certification and multi-sensor fusion challenges that stretch traditional avionics roadmaps.
Aircraft Collision Avoidance System Market -
Commercial imperative: With a mid-term market expansion driven by retrofit activity, new-platform integration, and the maturation of detect-and-avoid architectures, 2026 is the year to decide whether to lead, follow, or niche-invest in collision-avoidance capabilities. Those choices will materially affect product roadmaps, aftermarket revenues, and MRO capacity allocation across the forecast period.
What the report delivers — operational, actionable intelligence
-
Proven market model: A transparent, reproducible financial model calibrated to historical performance (2020–2025) and scenario-tested across conservative, central, and aggressive adoption curves for ACAS X variants.
-
Regulatory timelines and impact mapping: A staged analysis of FAA, EASA, and ICAO drivers, including certification windows, retrofit trigger points, and enforcement risk—translated into procurement decision calendars for OEMs and operators.
-
Technology and integration playbooks: Practical guidance for system selection (TCAS II vs ACAS X pathways), sensor-fusion architectures, software update strategies, and avionics‑bus integration that minimize downtime and certification exposure.
-
Vendor benchmarking and negotiation levers: A competitive framework that compares product portfolios, upgradeability, software lifecycle approaches, support footprints, and aftermarket pricing levers—designed for sourcing, legal and program teams to use in RFPs and contract negotiations.
-
Supply‑chain and MRO capacity stress-tests: Identification of bottlenecks—components, test resources, and skilled labor—that could elongate retrofit cycles, with mitigation options and contingency sourcing recommendations.
-
Scenario-based risk analysis: Quantified downside cases tied to certification delays, adverse safety recommendations, and accelerated regulatory mandates; and upside cases driven by faster-than-expected unmanned integration or aggressive retrofits following safety advisories.
Market dynamics: Drivers, friction points, and concentration
The collision avoidance market is expanding on multiple fronts: legacy retrofit demand, fleet modernization programs, and the emergent need for robust detect‑and‑avoid solutions for unmanned aircraft. These drivers are producing steady revenue growth and creating new product adjacencies—particularly for suppliers capable of delivering software-defined, upgradeable platforms.
At the same time, market concentration is non-trivial: our analysis indicates that the top three suppliers capture a meaningful share of the market, and the top five account for a clear majority of market revenues. This concentration shapes competitive dynamics, pricing power, certification pathway control, and aftermarket economics—factors that every buyer and investor should weigh when making 2026 commitments.
Competitive landscape — positioning and strategic moves
-
Honeywell International Inc. — A dominant incumbent in TCAS II systems with a strong installed base across commercial and business aviation. Honeywell’s focus on certified traffic computers and continuity in support positions it as a preferred partner for large transport retrofit programs.
-
Collins Aerospace (RTX) — Offers a broad TCAS product line with upgradeable software pathways. Collins’ depth in avionics integration and OEM relationships makes it a natural supplier for platform-level retrofit strategies and new-production installations.
-
ACSS / Thales consortium — Through joint ventures, ACSS and Thales combine heritage TCAS installations with an increasing focus on integrated solutions (TCAS + TAWS + Mode S). Their global install base creates network effects for support and upgrade monetization.
-
Garmin Ltd. — A key competitor in the general and business aviation segments, integrating TCAS-class solutions into modern flight decks. Garmin’s strength is rapid integration cycles and favorable cost-of-entry for GA operators.
-
L3Harris Technologies — Offers surveillance and collision avoidance capabilities, leveraging defense and avionics expertise. Their portfolio supports both legacy systems and newer surveillance architectures suited to mixed airspace operations.
-
Sagetech Avionics — A leader in lightweight ACAS X implementations for crewed and uncrewed platforms. Sagetech’s ACAS Xu/sXu work and active flight research in multi‑sensor fusion make it a strategic partner for BVLOS drone operators and integrators.
-
Avidyne Corporation — Focused on next-generation cockpit integration for GA and business aviation, Avidyne is notable for its glass‑cockpit integrations and approachable upgrade pathways for smaller fleets.
These vendors occupy overlapping but distinct strategic spaces: incumbents with large transport footprints, avionics integrators targeting fleet-scale retrofits, and agile newcomers specializing in low‑SWaP ACAS X solutions for unmanned systems. The result is an ecosystem where partnerships, software roadmaps, and aftermarket services determine future share more than hardware alone.
Recent industry developments shaping near-term choices
-
FAA TSO release for ACAS Xu (March 2026): Opens a formal certification route for detect‑and‑avoid equipment on UAS, accelerating procurement decisions for operators pursuing BVLOS operations.
-
NTSB safety recommendation after a 2025 mid‑air collision (public follow-up March 2026): Creates reputational and regulatory pressure that could precipitate targeted retrofit programs or expanded ACAS X adoption in certain fleet segments.
-
Industry R&D collaborations: Examples include Sagetech’s flight research into layered ACAS X + multi‑sensor fusion for drones—indicative of practical pathways to address mixed-traffic airspace challenges.
-
FAA transition dynamics: While ACAS Xa/Xo advancement continues, full replacement of all TCAS II mandates remains a work in progress in certain jurisdictions. This hybrid regulatory state requires parallel planning: compliance with existing TCAS II obligations and readiness for ACAS X opportunities.
Strategic playbook — prioritized recommendations for 2026
-
Operators (airlines, cargo, large fleets): Initiate a two-track procurement strategy—maintain compliance with current TCAS II mandates while allocating a capital reserve and technical workstream for ACAS Xa retrofit pilots. Accelerate fleet‑level readiness assessments in Q1–Q2 2026 to lock favorable MRO windows.
-
OEMs and Tier‑1 suppliers: Prioritize software modularity and certificatable update pipelines. Establish cross‑licensing and integration agreements now to shorten delivery cycles for customers seeking ACAS X migration paths.
-
MRO and aftermarket providers: Invest in test benches and skilled certification teams for ACAS X variants and multi‑sensor fusion diagnostics. Capacity investments in 2026 will pay back as retrofit demand converges.
-
UAS operators and system integrators: Leverage the FAA’s ACAS Xu TSO to accelerate BVLOS deployments, focusing first on validated flight corridors and partner ecosystems where detect‑and‑avoid demonstrators already exist.
-
Investors and strategic acquirers: Target companies with software upgrade pathways, strong service revenue streams, and niche ACAS X capabilities—especially those that can bridge crewed and uncrewed markets.
-
Regulators and safety bodies: Use phased mandates and incentivized retrofit programs to reduce sudden aftermarket shocks; publish harmonized certification guidance for ACAS X family elements to reduce commercial uncertainty.
Next steps and how to use the full report
This preview synthesizes the strategic contours of a market in transition. The full PW Consulting Aircraft Collision Avoidance System Market report contains the detailed datasets, region‑ and platform-level scenarios, vendor scorecards, and our full financial model that underpin the insights summarized here. To preserve the integrity of client-grade modelling and to support actionable contracting and investment decisions, we publish granular tables and proprietary segmentation only in the paid report.
For senior leaders preparing 2026 budgets and multi-year-tech roadmaps, the decision window is short. Our report equips teams to quantify retrofit versus new‑build tradeoffs, evaluate supplier negotiation strategies, and stress-test certification/timing risk against revenue and safety objectives. PW Consulting’s structured scenario outputs and implementation playbooks are designed explicitly to convert macro market trends into executable 12–36 month plans.
Contact PW Consulting for a briefing and to access the complete report, datasets, and our interactive decision-support model tailored to your fleet or investment thesis. The next 12 months will define winners and followers in a market where software‑defined avionics and cross-domain integration are reshaping competitive advantage.
For detailed analysis of this topic, please visit the official page: Aircraft Collision Avoidance System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


