



PW Consulting: Satellite Manufacturing and Launch Systems Market to Grow from USD 35,450 Million in 2025 to USD 61,780 Million by 2032 at an 8.26% CAGR

Satellite Manufacturing and Launch System Market: Strategic Guidance for 2026 Decisions
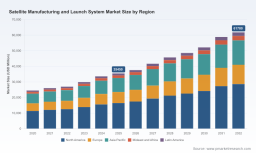
PW Consulting today publishes a forward-looking industry briefing drawn from our comprehensive Satellite Manufacturing And Launch System Market report (base year 2025, forecast 2026–2032). The report synthesizes five years of historical tracking and seven-year forecasts to equip boards, investors, and executive teams with the decision-grade intelligence required for 2026 strategy cycles. At a macro level, the worldwide market expands from approximately USD 35,450 Million in 2025 to an anticipated USD 61,780 Million by 2032, reflecting a compound annual growth rate (CAGR) of 8.26% across the forecast window.
Satellite Manufacturing And Launch System Market
Why this report matters for 2026 planning
-
Timing capital allocation: The market’s mid-to-high single-digit CAGR and the accelerating commercial launch cadence create windows for both growth investments and strategic consolidation. Our report shows where near-term capital delivers the highest optionality and which bets carry doubling-time risk in a 24–36 month horizon.
Satellite Manufacturing And Launch System Market -
Portfolio prioritization: Satellite manufacturing and launch services are intertwined but follow different commercial rhythms. We provide prescriptive frameworks to prioritize product lines, manufacturing capacity, and launch procurement over the next 12–18 months.
Satellite Manufacturing And Launch System Market -
Regulatory and supply-chain readiness: Recent regulatory updates and raw-material constraints materially change program risk profiles. Proactive compliance and diversified sourcing become competitive differentiators in 2026.
-
M&A and partnership playbook: With market concentration leaning toward a mid-sized group of dominant players (CR3 ~48.2%; CR5 ~61.5%), the report outlines tactical M&A windows, JV structures, and non-equity partnerships to secure capability quickly without overpaying for scale.
Core market dynamics shaping 2026 strategy
-
Commercial scale meets incumbent specialization: Demand is being driven by both mega-constellation programs and traditional GEO/MEO payloads. Manufacturing volume and launch cadence are rising in parallel, but the operational requirements for mass-produced smallsats differ sharply from traditional, bespoke GEO satellites.
-
Regulatory tightening: Spectrum allocation changes (notably FCC updates in 2025) and ITU enforcement of debris mitigation (including deorbit timelines) are increasing program compliance costs and altering lifecycle planning for constellations. Operators will need interference-mitigation and end-of-life strategies baked into procurement contracts.
-
Critical materials constraints: Export restrictions and supply concentration for high-purity gallium and germanium are affecting solar cell and IR detector availability—components found in a large share of contemporary satellites. Sourcing risk will influence supplier selection, inventory policy, and potential vertical integration discussions in 2026.
-
Manufacturing infrastructure scarcity: High-grade assembly environments (e.g., ISO 5 cleanrooms with vibration isolation) remain limited globally. Capacity constraints create lead-time premiums and favor firms with owned or long-term access to controlled facilities.
Competitive landscape: who matters and why
The market exhibits a mix of vertically integrated incumbents and high-growth niche challengers. The competitive map is nuanced: some firms compete primarily on manufacturing scale and satellite platforms, others on launch reliability and cadence, and an emerging group on smallsat end-to-end solutions.
-
SpaceX — A high-volume manufacturer-launcher hybrid. Its large-scale satellite production and proven Falcon family create commercial advantages in pricing and cadence. Recent constellation deployments underline the company’s ability to compress timelines for vertically integrated operators.
-
Boeing and Lockheed Martin — Incumbent systems integrators with deep heritage in GEO, military, and national programs. Their value remains strong where mission assurance and legacy-system integration are non-negotiable.
-
Airbus Defence and Space, Thales Alenia Space — European platform specialists focused on telecom and high-throughput payloads, leveraging partnerships with commercial launch providers.
-
Rocket Lab and smaller launch specialists — Competitive in the smallsat segment with rapid, responsive launch services and turnkey spacecraft solutions. Their operational model is attractive for distributed architectures and on-orbit experimentation.
-
Blue Origin, ULA, Arianespace — Heavy and medium-lift launcher providers essential to large GEO missions and growing constellation deployments as they ramp newer vehicles to commercial availability.
-
Specialists (Maxar, Ball Aerospace, OHB, SSTL, ISRO, CASC) — Focused on imaging, EO, and government programs; their strengths include high-resolution payloads, regional access, and cost-competitive options for specific mission classes.
Recent industry developments through 2025—commercial launches by SpaceX, Rocket Lab’s in-orbit manufacturing payload deployment, Ariane 6’s ongoing flights, ULA’s Vulcan missions, and Blue Origin’s production funding—underscore the tempo shift from development to sustained operations for launch and manufacturing capacity. For 2026, expect competition to center on launch cadence, contract flexibility, and supplier risk mitigation rather than raw technological novelty alone.
Practical, actionable content inside the report
Our report is constructed to be directly usable by executives during 2026 planning cycles. Highlights include:
-
An investment-timing model that maps revenue and unit-cost inflection points against capital deployment windows.
-
A launch procurement playbook with contract templates and decision criteria for fixed-price versus incentive-based launches.
-
A manufacturing-footprint decision tree that evaluates build-vs-buy, cleanroom access strategies, and co-location benefits for launch-integration.
-
A supply-chain risk matrix addressing critical minerals, key component single-sourcing, and alternative technology pathways to reduce exposure to export restrictions.
-
A regulatory compliance checklist covering FCC/ITU changes and export-control scenarios (including ITAR considerations) to accelerate licensing and offset program delays.
-
Company benchmarking dashboards and a prioritized M&A/partnership target list based on capability adjacency, integration risk, and market reach.
Risks you must account for in 2026 — and how to mitigate them
-
Material access risk: Hedge supply by qualifying multiple vendors, invest in substitutes or recycling programs, and structure payment terms to secure long-lead components.
-
Regulatory risk: Build compliance roadmaps into product lifecycles, fund independent spectrum and debris-risk assessments, and prioritize interoperability testing to reduce post-launch rework.
-
Capacity and scheduling risk: Secure cleanroom and test-facility slots through long-term leases or partnerships, and stagger program phases to avoid bottlenecks.
-
Concentration risk: Given the market’s moderate concentration (CR3 and CR5 figures noted above), avoid single-provider dependencies for critical services. Diversify launch providers where contractual flexibility allows.
-
Insurance and liability risk: Reassess launch and on-orbit insurance structures in light of increased debris liability and constellation scale; consider pooled underwriting for program-level coverage.
How C-suite teams should use this intelligence in 2026
-
CEOs and Boards: Use the report’s scenario maps to validate capital deployment timelines and to set measurable go/no-go gates for large program commitments.
-
CFOs: Leverage our cost curves and investment timing model to align financing instruments with milestone-driven capital needs and to evaluate lease vs. purchase of manufacturing infrastructure.
-
CTOs and Program Leads: Adopt the supplier-qualification and regulatory checklists to de-risk early design choices and to accelerate integration testing windows.
-
Corporate Development: Utilize our M&A screen and partnership scoring to prioritize targets that fill capability gaps or provide strategic access to launch capacity and manufacturing floor space.
Next steps and where to find the full intelligence
This release outlines the strategic contours we expect to shape decision-making in 2026. The full Satellite Manufacturing And Launch System Market report contains the granular, actionable data that underpins these conclusions, including regional and segment breakdowns, company-level revenue models, downloadable financial workbooks, and deal-by-deal benchmarking. To access the complete dataset, segmentation analysis, and proprietary modelling tools, visit PW Consulting’s report page or contact our industry practice for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Satellite Manufacturing And Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


