



PW Consulting: Nickel Boride Alloy Market Set to Expand at a 5.48% CAGR Through 2026–2032

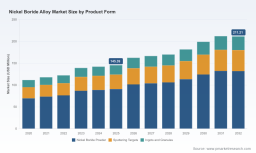
Nickel Boride Alloy Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive overview
Our latest Nickel Boride Alloy Market research positions industry leaders and strategic investors to make high-confidence decisions in 2026. The global market has moved from a modest base in the early 2020s to deutlich expansion: total market revenue increased from approximately USD 111 million in 2020 to about USD 145 million in the 2025 base year, and our forecast projects continued expansion through 2032, with the market approaching the low‑to‑mid‑hundreds of millions by the end of the period. This trajectory reflects a compound annual growth rate (CAGR) of roughly 5.48% across the forecast window of 2026–2032.
Nickel Boride Alloy Market
That topline growth belies a more nuanced landscape: cyclical raw-material pressures, evolving downstream specifications (from catalysts to wear‑resistant coatings and semiconductor‑grade materials), and a competitive mix of global specialty players and regional producers. For corporate leaders, these dynamics create both risk and strategic optionality — the very reason this report is designed as an operational playbook rather than a descriptive summary.
Nickel Boride Alloy Market
Why this report matters for 2026 decision-makers
- Procurement and cost control: Rising nickel markets and volatility have moved procurement from a tactical to a strategic lever; companies without robust hedging, indexation, or vertical sourcing plans face margin compression.
- CapEx and plant positioning: Choosing whether to add conversion capacity, or to invest in higher‑value product forms (e.g., engineered powders, sputtering targets), is dependent on forward demand assumptions and capital intensity — this report links demand scenarios to CAPEX decision thresholds.
- M&A and partnership targeting: Fragmentation in specialty segments presents roll‑up and capability acquisition opportunities; we map realistic targets and valuation sensitivities under multiple pricing regimes.
- Go‑to‑market strategy: For suppliers and new entrants, understanding which downstream specifications drive premium pricing (and which are commoditized) is the difference between sustained margins and margin erosion.
- Regulatory and supply‑risk planning: Export controls and ore export restrictions are reshaping regional supply chains; companies must weigh relocation, alternative sourcing, or product reformulation options.
Report contents — practical, actionable modules
We designed the study to be immediately useful to strategy, procurement, and business‑development teams. Key components include:
Nickel Boride Alloy Market
- Top‑down and bottom‑up market sizing, with sensitivity testing across three demand scenarios and explicit modelling of price pass‑through to end markets.
- Detailed supply‑chain maps that trace material flows from raw nickel feedstocks through master alloys and powders to application grade products, highlighting choke‑points and long‑lead suppliers.
- Cost‑build models for representative product forms that allow in‑house teams to run what‑if analyses under variable nickel price cases.
- Commercial playbooks: customer segmentation, pricing strategies, channel choices, and contract templates tailored to catalyst, thermal‑spray, brazing, and semiconductor customers.
- M&A and partnership scorecards identifying high‑value targets by capability, geography, and integration fit, plus worked examples of accretion/dilution under different financing options.
- Regulatory scenario planning that translates export controls and ore‑export policies into quantifiable supply‑risk indices and mitigation pathways.
Competitive landscape — read‑between‑the‑lines analysis
The market structure combines a handful of established specialty alloy houses with a broader cohort of OEM‑facing and regional manufacturers. Our concentration metrics indicate that the top three suppliers account for a material share of market supply, with the top five firms representing a clear majority — a dynamic that shapes pricing power, technology investment, and access to high‑value channels.
Key players profiled in the report (selected examples):
- American Elements (United States) — a diversified supplier of high‑purity nickel boride variants and specialty forms for research and advanced applications ( https://www.americanelements.com).
- Stanford Advanced Materials (SAM) (United States) — supplier of nickel boride powders and evaporation materials serving high‑performance applications ( https://www.samaterials.com).
- KBM Affilips (Netherlands) — European master‑alloy producer with capabilities in nickel‑boron master alloys used for deoxidation and performance enhancement of Ni‑based superalloys ( https://www.kbmaffilips.com).
- Westbrook Resources (United Kingdom) — specialist supplier focused on master alloys for hard‑facing and superalloy production ( https://www.wbrl.co.uk).
- Luoyang Golden Egret Geotools , Huarui Metal , and Xinglu Chemical (China) — regional manufacturers supplying powder portfolios that feed thermal spray and industrial markets (respective sites: https://www.xtc-thermalspray.com, https://www.hruimetal.com, https://www.xingluchemical.com).
- ESPI Metals and PTG Advanced Catalysts (United States and China) — niche suppliers focused on specialized grades for catalysts and lab‑scale applications ( https://www.espimetals.com, https://www.ptgchemical.com).
Our analysis emphasizes capability differences rather than headline market share alone: purity and particle size control, consistency in master alloy chemistry, and trace‑element management determine which suppliers win high‑margin contracts. Regional logistics and certifications (e.g., semiconductor cleanroom standards) further segment supplier attractiveness.
Supply‑chain dynamics and raw‑material pressures
Two structural themes are driving near‑term risk: raw‑material price pressure and strategic resource policy. Nickel prices have experienced a meaningful upswing into 2026, reflecting competing industrial demand and constrained upstream capacity — a trend that materially affects cost structures for nickel‑containing alloys. Price volatility remains a core planning challenge; our report provides hedging matrices and supplier contract constructs that can protect margin through rolling hedges, indexation clauses, and physical offtake arrangements.
On the policy front, export rules and upstream restrictions are reshaping availability. Long‑standing ore export restrictions in certain producing countries, combined with targeted export controls on specific alloy families from major producing economies, mean companies must reassess sourcing footprints. The practical implications are threefold: higher working capital needs to pre‑position feedstock, a premium for onshore downstream processing, and accelerated interest in substitute chemistries where feasible.
Market concentration and strategic implications
The market’s moderate concentration offers distinct pathways depending on an organization’s position. Incumbent leaders benefit from scale economies and established quality credentials, enabling them to invest in R&D and capture premium applications. Mid‑tier suppliers and new entrants succeed by focusing on differentiated capabilities — ultra‑tight particle distributions, proprietary formulations for catalytic selectivity, or rapid custom‑blend response times.
For buyers, the concentration profile suggests a balance between leveraging supplier relationships for innovation and maintaining optionality through dual‑sourcing. For private equity and strategic acquirers, the fragmentation in certain product forms creates roll‑up opportunities, while the presence of certified, high‑barrier niches (for example, semiconductor‑grade products) demands a different valuation lens.
Strategic playbook for 2026
- Producers: Prioritize product premiumization (application‑specific formulations), invest in quality certifications for semiconductor and catalyst customers, and develop flexible pricing mechanisms tied to nickel indices.
- Buyers/Downstream users: Implement dual‑track sourcing (global + regional), build safety stocks strategically tied to lead times, and negotiate dynamic price‑adjustment mechanisms to limit input cost volatility.
- New entrants: Target narrow, high‑margin niches where quality barriers deter mass competition; partner with certified toll‑processors rather than deploying full greenfield capacity initially.
- Investors: Look for assets with demonstrable technical IP, customer contracts in high‑barrier applications, and supply‑chain control that mitigates nickel price exposure.
How PW Consulting’s analysis de‑risks your 2026 decisions
This report converts market intelligence into executable plans: from granular cost models and supplier scorecards to M&A playbooks and regional risk matrices. Crucially, it provides a framework for scenario‑based planning — enabling executives to stress‑test capital investments, negotiate durable commercial terms, and define tactical sourcing responses as macro conditions evolve.
Next steps — access full intelligence
The summary above highlights the strategic contours you need to know now. Our published report contains the full dataset, scenario models, supplier scorecards, and downloadable financial templates that enable immediate implementation. In accordance with our “trailer” approach, we have intentionally omitted detailed segment breakouts and proprietary subsegment figures from this release to preserve the report’s commercial value and to encourage direct access to the source materials.
For procurement leaders, R&D heads, corporate strategy teams, and investors preparing 2026 plans, the report provides the empirical backbone and pragmatic guidance required to convert uncertainty into competitive advantage. To obtain the full report and the accompanying scenario models and templates, please visit the PW Consulting website and request access to the Nickel Boride Alloy Market report.
For detailed analysis of this topic, please visit the official page: Nickel Boride Alloy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


