



PW Consulting Report: Coal Tar Pitch for Graphite Electrodes Market to Grow at a 5.61% CAGR from 2026 to 2032

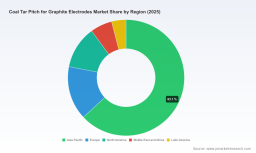
Coal Tar Pitch for Graphite Electrodes Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As global steelmaking and specialty carbon markets navigate a period of structural change, the coal tar pitch for graphite electrodes sector is transitioning from incremental demand growth to strategic centrality. PW Consulting’s latest market study — covering 2020–2025 as the historical window, using 2025 as the base year, and presenting forecasts to 2032 — equips executives with the forward-looking intelligence required to make high-consequence decisions in 2026. The study projects the market to expand at a compound annual growth rate (CAGR) of 5.61% through the forecast horizon, reflecting both cyclical recovery and durable secular drivers. Measured on an absolute basis (USD Million), the market progressed materially between 2020 and 2025 and is modeled to continue rising through 2032 under multiple scenarios.
Coal Tar Pitch For Graphite Electrodes Market
Why 2026 is a Strategic Inflection Point
-
Demand-side reconfiguration: The rising penetration of electric arc furnaces (EAFs) in steelmaking, together with growth in aluminum and specialty carbon applications, is changing the quality and mix requirements for coal tar pitch used in graphite electrodes. These changes are not merely additive; they alter procurement specifications, inventory strategies, and technical partnerships.
Coal Tar Pitch For Graphite Electrodes Market -
Supply-side stressors: Feedstock volatility, emissions compliance costs, and selective capacity additions are reshaping supplier economics. Coal tar commodity price data from late 2025 illustrates firmer feedstock pricing, which amplifies margin sensitivity across the value chain and increases the importance of hedging and backward integration analyses.
Coal Tar Pitch For Graphite Electrodes Market -
Regulatory and geopolitical friction: Tightening PAH-focused emissions regulations, EU directives on industrial emissions, US Clean Air Act implementation, and country-level export licensing decisions are creating uneven cost structures and export dynamics. Companies must evaluate not only where to source material, but where to localize processing or build compliance into unit economics.
What PW Consulting’s Report Delivers — Practical, Transaction-Ready Insight
Our market report is structured to move leaders from awareness to action. Key deliverables include:
-
Concise market sizing and growth pathways: A transparent base-year accounting (2025) and scenario-modeled forecasts to 2032 that quantify upside and downside cases under alternative demand and regulatory assumptions.
-
Supply-demand modelling with price elasticity: A bottom-up supply model cross-referenced with electrode production trajectories to surface tightening timelines, unit-cost inflection points, and likely pricing corridors.
-
Regulatory impact quantification: Scenario analyses that translate PAH and emissions compliance into per-tonne cost uplift and capital expenditure profiles for facilities in different jurisdictions.
-
Supplier and procurement playbooks: A supplier selection matrix, cost-to-serve frameworks, and hedging strategies tailored to procurement teams seeking to balance quality, security of supply, and total landed cost.
-
Investment and M&A intelligence: Deal-sourcing filters, valuation sensitivity tables, and a short-list of structural acquisition targets or JV archetypes suited to different strategic aims (vertical integration, geographic diversification, specialty-grade access).
-
Operational levers: Manufacturing yield improvement levers, impregnation and binder optimization checklists, and quality assurance protocols that translate R&D and process improvements into reduced raw-material intensity and higher electrode throughput.
-
Risk heatmap and contingency playbooks: Prioritized risks (regulatory, feedstock, logistics, geopolitics) with pre-configured mitigation actions, including contract clauses, alternative sourcing templates, and capital allocation triggers.
Market Structure and Competitive Dynamics
The coal tar pitch market for graphite electrodes exhibits a moderate concentration profile: the top three players account for a meaningful but not dominant portion of industry capacity, and the top five move the market to a clear but not prohibitive oligopolistic structure. This dynamic creates differentiated opportunities — scale advantages for incumbents, and niche openings for technically specialized or lower-cost regional producers.
Leading industry participants profiled in our report include multinational chemicals groups, specialized tar processors, and regional champions. Each player brings different strengths and strategic considerations for potential partners, buyers, and investors:
-
Rain Carbon Inc. (United States): A producer focused on binder-grade pitch tailored to graphite electrode manufacture. Recent capacity expansion efforts — including the first phase of a new facility commissioned in India in mid-2025 by a related corporate entity — underline an intent to capture growth and proximity advantage to regional electrode manufacturers.
-
Himadri Speciality Chemical Ltd. (India): A dominant domestic manufacturer with deep integration into local electrode supply chains. Recent milestones include executing significant liquid pitch exports to the Middle East, signaling an evolution from domestic consolidation to international supply ambitions.
-
Koppers Inc. (United States): A broad carbon and coating specialist supplying a range of pitches, with strengths in engineered solutions and established customer relationships across multiple end-markets.
-
JFE Chemical Corporation (Japan): High-quality binder pitch supplier with strong ties to synthetic graphite electrode producers and global customers seeking premium, consistent grades.
-
Mitsubishi Chemical Corporation (Japan) and Lone Star Specialties LLC (United States): Players that emphasize integrated carbon-chemical portfolios and custom-blend capabilities, useful for electrode manufacturers tuning performance.
-
DEZA, a.s. , Shanghai Baosteel Chemical , Jining Carbon Group and others: Regional producers and processors that can be competitive on cost and proximity, but in many cases face higher compliance or technology-related upgrade needs to serve premium electrode grades.
-
Dubai Tar Pitch Company and certain Indian specialty names: Important logistical and market-access roles for Middle East, Africa, and adjacent markets, often functioning as both producers and distributors.
For buyers, the strategic takeaway is clear: supplier selection must balance cost, grade capability, security of supply, and compliance risk. For suppliers, the imperative is to align capital allocation to the grades and geographies where premium and scale economics converge.
Near-Term Signals to Watch in 2026
-
Capacity rollout timelines vs. electrode demand: Monitor announced expansions for slippage or acceleration. Delays in compliance-driven upgrades could tighten markets quicker than raw demand growth would suggest.
-
Feedstock price trajectories and backward integration moves: Higher coal tar levels in late 2025 have already put upward pressure on cost structures. Expect some players to pursue upstream contracts or captive processing to stabilize margins.
-
Regulatory enforcement episodes: As national regulators tighten PAH and emissions enforcement, expect short-notice operational constraints and potential temporary capacity removal, particularly among smaller or older facilities.
-
Trade policy and export controls: Given export licensing measures on certain graphite-related products, alternative supply chains or localized blending might become strategic necessities.
Recommended 2026 Actions for Executive Teams
-
Establish a two-track procurement strategy: immediate 12–18 month tactical hedges to manage feedstock and price risk, paired with a strategic 36–48 month supplier consolidation or diversification plan focused on quality and compliance.
-
Stress-test capital projects against regulatory cost additions: integrate emissions CAPEX and operating compliance into project IRR models rather than treating them as contingencies.
-
Pursue targeted JV or offtake agreements with suppliers that offer both grade flexibility and geographic coverage; prioritize partners with recent investments in quality control and environmental upgrades.
-
Use M&A selectively: prioritize assets that offer either de-risking of feedstock access, a proprietary specialty pitch formulation, or cost-advantaged footholds in under-served regions.
-
Invest in technical differentiation: impregnation technologies and binder optimization can materially affect electrode yield and lifecycle costs — invest in co-development where possible.
How This Preview Fits into PW Consulting’s Full Report
This briefing highlights the strategic contours and decision imperatives for 2026. The full PW Consulting report contains the granular models, supplier scorecards, and scenario matrices that underpin these conclusions — including downloadable datasets, a regulatory compliance calculator, and an M&A screening toolkit tailored to coal tar pitch investments. We intentionally withhold core subsegment tables and region-by-application breakdowns in this preview to preserve the integrity of the proprietary analyses and to channel stakeholders to the full report for transaction-grade intelligence.
For companies making 2026 decisions — whether capital deployment, sourcing transformation, or M&A — the window for shaping competitive position is narrow. Those who combine disciplined supplier engagement, regulatory-forward CAPEX planning, and selective technical partnerships will capture disproportionate value as the market evolves through the forecast period.
Next Steps
-
Contact PW Consulting to access the full report, the underlying models, and executive workshops that translate the findings into a 90-day action plan.
-
Request a tailored briefing to assess how the report’s scenarios change under your company’s specific production footprint and procurement contracts.
For detailed analysis of this topic, please visit the official page: Coal Tar Pitch For Graphite Electrodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


