



PW Consulting Report: Distilled Gum Turpentine Market Poised for a 4.81% CAGR Through 2032

Distilled Gum Turpentine Market: Strategic Imperatives for 2026 Decision-Makers
Executive preview
As companies reposition supply chains and product portfolios for a post-pandemic, decarbonizing economy, distilled gum turpentine has re-emerged as a strategically important, bio-based intermediate and solvent. PW Consulting’s new Distilled Gum Turpentine Market report—anchored on a 2025 base year and projecting through 2032—delivers the analytical backbone that procurement, R&D, and corporate development teams need to make high-confidence decisions in 2026.
Distilled Gum Turpentine Market
High-level, market growth is steady: the global distilled gum turpentine market expanded meaningfully through the first half of the decade and is forecast to continue expanding at a compound annual growth rate (CAGR) of 4.81% over the forecast horizon. That trajectory underpins the twin realities facing corporates this year: sustained demand for pine-derived turpentine as a renewable feedstock, and ongoing supply-side tightness that elevates strategic risk if unintended exposures remain unmanaged.
Distilled Gum Turpentine Market
Why 2026 is a strategic inflection point
-
Recovery and composition: Demand recovery across coatings, adhesives, flavors & fragrances, and selected specialty chemical chains has shifted the product mix toward higher-value fractions and rectified grades. This is changing margin dynamics across the value chain and creating differentiated commercial opportunities for producers and buyers.
Distilled Gum Turpentine Market -
Supply consolidation and concentration: The market displays moderate concentration at the top end, with the largest three and five players controlling a material share of global supply. This concentration creates windows for strategic partnerships, offtake agreements, and targeted investments that can move a mid-sized buyer from price-taker to price-anchored counterparty.
-
Regulatory scrutiny and downstream labeling: Regional regulatory regimes continue to evolve—particularly in Europe and North America—affecting product registration, labeling, and permitted uses. These changes are reshaping commercial terms and product specifications for turpentine-containing formulations.
Market snapshot (what the headline numbers mean)
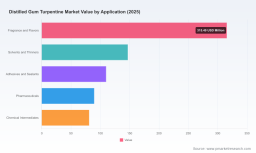
Our market model documents the evolution of total industry revenues from the historical period into the forecast window, showing steady expansion through 2025 and a continued upward path through 2032. The projected CAGR of 4.81% reflects a mix of volume growth and gradual value capture as higher-purity and specialty grades increase their share in applications such as fragrance intermediates, pharmaceutical intermediates, and high-performance solvents.
For decision-makers, the key takeaways are straightforward: the market is large enough to sustain multiple strategic plays (procurement optimization, upstream investment, or downstream product differentiation), yet concentrated enough that supplier selection and contractual design will materially affect cost of goods sold and margin performance in 2026.
Practical, decision-ready content in the report
The report is built to be operationally useful in Q1–Q3 2026. Rather than a high-level narrative, PW Consulting provides an actionable toolkit built around a granular but commercially guarded base of analysis. Highlights include:
-
Proprietary demand model segmented by application cluster and grade tier (alpha-pinene rich, beta-pinene heavy, rectified pharmaceutical grades), with scenario capability to stress-test demand under alternative macro and substitution assumptions.
-
Supplier scorecard and strategic sourcing playbook: capacity maps, reliability indices, ESG and traceability checklists, typical commercial levers, and a templated RFP that buyers can adapt to extract better pricing and security of supply.
-
Pricing and margin sensitivity analysis: drivers include resin/tapping yields, rosin co-product dynamics, freight and logistics volatility, and regulatory cost pass-throughs. The model enables corporate procurement to quantify the P&L impact of feedstock shocks and hedging strategies.
-
Regulatory risk matrix: country- and region-level implications of registration regimes, labeling obligations, and potential restrictions—paired with mitigation pathways for formulators and importers.
-
M&A and partnership playbook: identification of capability gaps (e.g., fractionation, rectification to pharmacopeial standards, domestic supply hubs), likely acquisition targets by capability, and valuation sensitivities under constrained supply scenarios.
-
Go-to-market options for downstream firms: grade-selection decision trees, innovation pathways for bio-based aromatics, and sample commercial structures (tolling, captive supply, joint ventures) to secure feedstock while limiting capital outlay.
Competitive landscape: who matters and why
Our qualitative and proprietary assessments profile leading producers and material regional players—ranging from integrated European terpene specialists to family-run producers in the Americas and Asia. Each player brings different strategic relevance depending on buyer priorities (cost, traceability, grade purity, or geographic proximity).
-
Established terpene integrators remain central: producers with deep fractionation capabilities and downstream chemistry know-how are uniquely positioned to capture margin in higher-value product lines (e.g., terpineol, high-purity alpha-pinene). Recent capacity additions and fractionation investments among leading European players signal continued value migration to ultra-pure derivatives.
-
Regional, forest-based suppliers command resilience on traceability: family-owned and regionally anchored producers that use traditional tapping methods offer differentiated sustainability credentials and supply-chain transparency. For buyers with ESG mandates or pharmaceuticals-grade requirements, these suppliers often become strategic partners.
-
New product introductions are shifting supplier differentiation: product launches of high-purity alpha-pinene lines and other BioRenewables platform offerings demonstrate how incumbents are leveraging turpentine streams to move into higher-margin chemical intermediates—broadening the set of competitive outcomes.
Recent commercial moves to watch (implications for 2026)
-
Capacity upgrades and automation are changing commercial bargaining power. Select suppliers have completed facility modernizations and are commissioning improved distillation and fractionation assets—this increases available high-purity supply but also raises the bar for entrants attempting to undercut on quality.
-
Product launches focused on higher-purity streams broaden substitution options for formulators and intermediates manufacturers. Buyers evaluating reformulations should begin qualification tracks in 2026 to realize cost or performance gains in subsequent product cycles.
-
Price and raw-material tightness persist. Recent market activity has shown that oleoresin and rosin market dynamics—driven by weather, tapping yields, and co-product processing rates—can create periods of acute margin pressure. Procurement teams must embed volatility scenarios into contract structures and inventory strategies.
Risk management and strategic playbook for 2026
We recommend a three-tiered approach for corporate decision-makers planning resource allocation and commercial strategy this year:
-
Near-term (0–12 months): Establish flexible offtake mechanisms combined with strategic safety stock for critical grades; begin supplier audits focused on traceability and REACH/labeling compliance; launch product requalification programs where substitution to higher-purity, bio-based intermediates offers margin or sustainability benefits.
-
Medium-term (12–36 months): Pursue joint-investment options with trusted suppliers to secure access to fractionation or rectification capacity; consider bolt-on M&A in regions where domestic supply reduces logistical and regulatory complexity; integrate price-sensitivity outputs into product pricing and procurement scorecards.
-
Longer-term (3–7 years): Build capabilities in derivative chemistry and circular sourcing to capture more value from terpene streams; where strategic, vertically integrate select upstream tapping or rosin processing assets to reduce exposure to co-product volatility and improve margin resilience.
What this means for specific corporate functions
-
Procurement: Move beyond commodity bids to supplier partnerships that include capacity reservation, quality campaigns, and shared-risk commercial terms.
-
R&D and Product Development: Prioritize early qualification of alternative grades and begin formulation roadmaps that allow switching between turpentine fractions and synthetic substitutes, balancing performance, cost, and regulatory safety.
-
M&A and Corporate Development: Use concentration metrics and supplier capability maps in the report to screen targets that close capability gaps or provide regional supply hubs—especially in markets with evolving regulatory burdens.
-
Risk and Compliance: Operationalize the report’s regulatory matrix to ensure labeling, registration, and workplace hazard communication processes are aligned with the latest standards in major markets.
Why PW Consulting’s report is uniquely actionable
We combine a robust, transparent market model with practitioner-focused deliverables—supplier scorecards, a procurement RFP template, a regulatory mitigation playbook, and M&A screening criteria. The report was designed to be used at the deal table or in cross-functional strategy sessions, not simply to inform executives from a distance.
Importantly, our approach follows the “pre-release” philosophy: we show the analytical scaffolding and strategic implications necessary for 2026 planning, while protecting the detailed, proprietary segment-level tables and valuation outputs that buyers and partners rely on to act decisively. Those granular datasets and interactive models are available with the full report purchase.
Next steps for leaders who need to act in 2026
-
Request the supplier scorecard and scenario model to stress-test your current supply agreements under adverse feedstock and regulatory scenarios.
-
Run a short-form commercial diligence using our templated RFP and qualification checklist to re-baseline supplier risk and renegotiate terms where appropriate.
-
Engage our corporate development team to use the report’s M&A playbook when evaluating acquisition targets or JV partners that close strategic gaps.
Conclusion
Distilled gum turpentine sits at the intersection of renewable chemistry, traditional forestry supply chains, and evolving regulatory expectation. The market’s steady expansion—supported by a multi-year CAGR and an evolving competitive topology—creates opportunities for those who align procurement, R&D, and corporate development around a coordinated strategy in 2026.
For a full set of proprietary tables, interactive scenario models, supplier-level metrics, and the practical templates referenced above, access PW Consulting’s complete Distilled Gum Turpentine Market report and supporting toolset on our website. The granular intelligence contained in the full report is the difference between informed planning and operationally executable strategy in 2026.
For detailed analysis of this topic, please visit the official page: Distilled Gum Turpentine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


