



PW Consulting: EV Solid-State Battery Market Poised for Breakout Growth — 67.35% CAGR Projected Through 2032

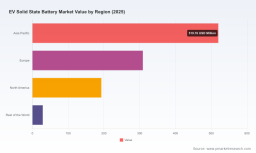
EV Solid-State Battery Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's new market study on EV solid‑state batteries frames 2026 as a pivotal year for industrial strategy. Our analysis tracks an accelerating curve: the market moved from a modest base in 2020 to just over USD 1,050 million in 2025 (base year), and under our central forecast expands into the tens of billions by the early 2030s — implying an extraordinarily steep compound annual growth rate (CAGR) throughout the forecast window. For executives and investors planning resource allocation, partnerships, manufacturing footprints, or M&A activity next year, the report distills the evidence you need to move from speculative positioning to executable strategy.
Ev Solid State Battery Market
Why 2026 Is an Inflection Point
-
Commercial readiness is converging with regulatory and incentive tailwinds. Multiple OEM and battery developers have announced prototype validations and pilot production milestones through 2024–2025, and several are publicly targeting late‑decade commercialization. Those timelines mean 2026 is the window for committing capital to scale pilots into automotive‑grade production rather than remaining at the demonstration phase.
Ev Solid State Battery Market -
Policy and incentives are reshaping cost equations. North American production credits and European regulatory thresholds tied to energy density and recyclability are already influencing site selection, supplier contracts, and product specifications. These measures materially impact project IRR calculations and time‑to‑market decisions.
Ev Solid State Battery Market -
Supply chain and material dynamics are normalizing but remain a source of competitive differentiation. Key inputs such as lithium metal foil and sulfide electrolytes have real‑world price bands that buyers and procurement teams must incorporate into cost models. Component cost curves and the emergence of domestic production incentives will determine where gigafactories are viable without chronic subsidy dependence.
What Our Report Delivers — Practical, Decision‑Ready Tools
We designed the report for executives who need actionable intelligence, not academic prose. Highlights include:
-
Comprehensive market sizing and forecast model (historical 2020–2025; forecast 2026–2032) with scenario variants to stress‑test upside, baseline and downside commercialization pathways.
-
Technology readiness and commercialization timelines for major solid‑electrolyte chemistries, mapped against manufacturing scale factors and projected cost curves.
-
Unit cost buildups and sensitivity analyses that translate raw material and component price swings into vehicle electrification economics and OEM payback timelines.
-
Supply chain and raw‑material risk matrices covering sourcing alternatives, inventory strategies, and strategic stockpiling options for critical inputs.
-
Regulatory and standards playbook — practical checklists to meet regional compliance milestones (including recyclability and minimum performance standards) and adoption timelines for industry testing norms.
-
Commercial partner and M&A playbooks that outline the expected negotiation levers, valuation approaches for IP‑rich startups versus scale‑focused incumbents, and a staged contracting template for offtake and co‑investment structures.
-
Operational readiness templates for pilot to series production transitions, including CAPEX estimates, staffing profiles, and quality assurance gating criteria tailored to automotive qualification cycles.
Competitive Landscape — Who Matters and Why
The market shows meaningful concentration around a mix of incumbent battery makers, incumbent OEMs, and specialized new entrants. Our report quantifies this concentration and interprets what it means for partnership strategy and competitive response.
-
Toyota Motor Corporation (Japan) — Pursuing multi‑generation solid‑state prototypes with aggressive range and charging targets. Toyota’s vertical integration and automotive systems expertise make it a bellwether for mainstream EV adoption tempos.
-
Samsung SDI (South Korea) — Demonstrating high energy‑density prototype cells and extending collaborations with automakers; a capable partner for scaled EV integration when production ramps are required.
-
LG Energy Solution (South Korea) — Focused on sulfide chemistry and piloting automotive lines; its legacy cell manufacturing capability gives it a time‑to‑scale advantage for automotive qualifications.
-
CATL (China) — Working to condense solid‑state technology towards mass production with a manufacturing footprint designed for rapid volume scaling; a strategic competitor in global supply dynamics.
-
QuantumScape (USA) — Anode‑free lithium‑metal approach and validated prototypes with large OEM partners; its IP posture and partner relationships make it a high‑impact acquisition or strategic alliance target.
-
Solid Power, ProLogium, Blue Solutions, Murata, Toshiba — A cohort of specialized suppliers and innovators offering differentiated approaches (sulfide, ceramic, polymer and miniaturized cells). Each presents either a sourcing opportunity or a potential consolidation target depending on a firm’s vertical strategy.
Our concentration metrics show a market where the top few players hold material influence, but substantial room remains for new entrants and niche specialists — provided they can clear automotive qualification gates and secure supply chain resilience.
Industry Signals and Recent Developments
-
Prototype and pilot progress: Several firms shipped validated samples and ramped EV‑cell production during 2024–2025, moving the industry out of purely lab‑scale claims and into supply‑chain engineering conversations.
-
Raw material and component trends: Lithium metal foil and bulk sulfide electrolyte prices have stabilized into observable ranges, enabling more reliable cost forecasting for 2026 investment cases.
-
Regulatory and standardization dynamics: Regional regulations mandate energy density and recyclability thresholds in the coming years while established testing standards define automotive qualification paths — these are non‑negotiable for market access.
Strategic Recommendations — What to Do in 2026
Our recommendations are calibrated to organizational roles and time horizons. Below are priority actions for the coming 12 months.
-
OEMs: Move from LOI to limited series commitments with technology partners only after completion of vehicle‑level validation tests. Protect optionality by structuring staged offtake contracts with technology milestones rather than single‑stage large take‑or‑pay agreements.
-
Battery manufacturers: Invest in flexible pilot lines that can accommodate more than one solid‑electrolyte chemistry. This hedges technology risk while enabling faster qualification for multiple OEM programs.
-
Suppliers of critical materials: Expand turnkey supply agreements and consider nearshoring options to capture regional incentives. Hedging strategies for lithium metal and specialized electrolytes will be decisive for margin protection.
-
Investors and PE: Prioritize capital for assets that de‑risk scale (equipment suppliers, pilot‑line integrators, IP‑light contract manufacturers). For equity in IP‑rich startups, use milestone‑based tranche structures tied to automotive qualification stages.
-
Policymakers and economic development agencies: Structure incentives to reward not only headline manufacturing but the full value chain — cell assembly, electrode fabrication, and recycling infrastructure — to avoid bottlenecks downstream.
Roadmap — First 90 Days to First Year
-
0–90 days: Conduct a rapid readiness assessment using our operational templates; secure conditional offtake/partnership terms; begin supply‑chain audits for critical inputs.
-
90–270 days: Execute pilot‑line capex decisions, finalize key supplier agreements, and lock in regulatory compliance roadmaps for your target markets.
-
270–365 days: Complete OEM validation loops, finalize series‑production contracts or staged investment agreements, and scale workforce and quality systems for automotive qualification.
Why PW Consulting’s Analysis Matters for 2026
Decision cycles in EV battery supply chains are long and capital‑intensive. Our report converts macro momentum — the rapid market expansion implied by multi‑year growth trajectories — into specific operational choices that preserve optionality while positioning for scale. The difference between signing the right partnership in 2026 and waiting can mean the difference between leading or following during the next wave of electrification.
Next Steps — Accessing the Full Intelligence
This briefing highlights the strategic contours you need now; the full report contains the proprietary models, detailed scenario outputs, supplier scorecards, and executable templates that senior teams will use to finalize 2026 budgets and projects. To obtain the full dataset, interactive models, and practitioner playbooks, please visit PW Consulting’s market portal or contact our client services team for an executive briefing.
PW Consulting — turning accelerating market signals into disciplined industrial strategy for the solid‑state era.
For detailed analysis of this topic, please visit the official page: Ev Solid State Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


