



PW Consulting: ROS1‑Targeted NSCLC Drug Market Reaches USD 655.0 Million in 2025, Forecast to Surge at 14.85% CAGR to USD 1,726.43 Million by 2032

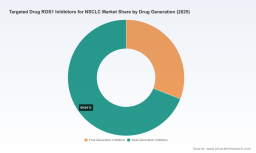
Targeted Drug ROS1 Inhibitors for NSCLC Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s new market study on Targeted Drug ROS1 Inhibitors for Non–Small Cell Lung Cancer (NSCLC) synthesizes regulatory inflection points, competitive maneuvering, and payer dynamics into a single, decision-ready narrative for corporate leaders planning 2026 strategies. The market has evolved from a niche oncology segment into a commercially material opportunity: according to our base-year analysis (2025), the global market reached approximately USD 655.0 million and is forecast to expand to about USD 1.73 billion by 2032, reflecting a compound annual growth rate (CAGR) of 14.85% across the 2026–2032 forecast window. That trajectory is driven by a combination of next-generation product approvals, label expansions, and intensifying diagnostic adoption—but the coming 12–18 months will determine which players capture the lion’s share of value.
Targeted Drug Ros1 Inhibitors For Nsclc Market
Executive snapshot
- Market growth: accelerated expansion from 2020 through 2025, with a steep growth profile projected into the late 2020s.
- Competitive concentration: a highly consolidated supplier base has dominated the category to date, amplifying the strategic importance of pipeline differentiation and lifecycle management.
- Clinical and regulatory catalysts: multiple label extensions and new approvals since 2023, alongside ongoing phase-3 readouts, create meaningful first-mover windows.
- Access environment: companion diagnostics and guideline-level reimbursement have materially improved treatability, but payer segmentation and country-specific HTA processes will determine uptake velocity.
Why 2026 is a strategic inflection point
Several converging forces make 2026 pivotal for sponsors, investors, and commercial teams. First, patent and exclusivity timelines for legacy ROS1 agents create an impending competitive inflection that will open price and access pressure when generics and biosimilars become viable alternatives. Second, next-generation inhibitors that demonstrate activity against resistance mutations and CNS metastases are shifting the standard-of-care calculus. Third, regulator-driven diagnostic integration—exemplified by long-standing companion assays for ROS1—means patient selection is now a core commercial competency, not merely a clinical nicety.
Targeted Drug Ros1 Inhibitors For Nsclc Market
Importantly, recent regulatory milestones underscore these dynamics: repotrectinib obtained accelerated and expanded approvals in 2024 for select ROS1-positive NSCLC indications, and entrectinib’s pediatric label expansion in 2023 evidences continued lifecycle momentum among incumbent innovators. Meanwhile, large randomized studies—including ongoing phase-3 comparators—will materially influence first-line treatment share over the next 24 months. PW Consulting’s scenario models quantify the commercial impact of each of these clinical outcomes under conservative and aggressive adoption assumptions.
Targeted Drug Ros1 Inhibitors For Nsclc Market
Competitive landscape: incumbents, challengers, and tactical playbooks
The market is currently shaped by a mix of established pharmaceutical players and smaller, acquisition-prone biotech innovators. Legacy agents retain sizeable clinical adoption due to early approvals and guideline inclusion; newer entrants are differentiating on breadth of activity, CNS penetration, safety profile, and line-of-therapy positioning. Recent M&A activity reflects an industry race to consolidate next-generation assets under well-resourced commercial platforms.
- Incumbents are defending by pursuing label expansions, pediatric approvals, and diagnostic co-development to extend lifetime value.
- Challengers and acquirers are accelerating late-stage programs and investing in real-world evidence (RWE) generation to shorten payer negotiation cycles.
- Commercial tactics we observe winning in other precision-oncology subsegments—diagnostic bundling, indication-based pricing, and value-based contracting pilots—are being actively tested in ROS1-targeted therapies.
PW Consulting’s competitive profiles synthesize public filings, approvals, clinical-trial registries, and primary market interviews into tactical playbooks that show how each named company can plausibly move the market. For commercial confidentiality and to preserve client advantage, detailed market-share and channel-split tables are reserved for the full report.
Report deliverables: what’s inside and how it helps 2026 planning
This report is designed as an operational toolkit for strategy, BD&L, market access, and commercial teams. Highlights include:
- Top-down market sizing and bottom-up patient-flow models (base year 2025) that reconcile epidemiology, testing rates, and treatment patterns to produce revenue scenarios through 2032.
- Multiple forecast scenarios (base, conservative, upside) driven by alternative assumptions on assay uptake, guideline changes, and first-line conversion rates.
- Competitive response matrices and timing-sensitive market-share simulations that map likely outcomes from key regulatory readouts and generic entry.
- Payer and HTA playbooks with negotiation points, required evidence packages, and exemplar reimbursement timelines for major markets.
- Launch sequencing optimization, including prioritization of diagnostic partnerships, field force sizing models, and early-access program templates.
- M&A and licensing heatmaps identifying high-value targets and likely acquirers by asset class and clinical profile.
- Commercial risk dashboards and mitigation plans—supply continuity, pricing compression scenarios, and signalling strategies to preserve gross-to-net economics.
All workstreams are delivered with client-ready slide decks, an interactive financial model, and an executive one-page strategy that translates analysis into immediate 90–180 day actions.
Actionable strategic recommendations for 2026 leadership
- Prioritize clinical differentiation that aligns with payer value levers—CNS efficacy, resistance-mutation coverage, and safety profile will drive favorable reimbursement.
- Lock in diagnostic partnerships now: diagnostic-lab network agreements and bundled testing programs materially shorten the commercialization ramp.
- Prepare a multi-scenario pricing and contracting strategy in anticipation of patent-expiry dynamics—define triggers for value-based agreements and capped rebates.
- Invest in RWE and pragmatic trials to support label expansions and to accelerate HTA submissions in high-priority countries.
- Consider targeted M&A or licensing for assets that fill clinical gaps or provide near-term revenue synergies; the market’s concentration means well-timed deals can move share rapidly.
- Operationalize supply-chain resiliency and inclusive manufacturing capacity planning to avoid launch disruptions when demand spikes after approvals.
Methodology and confidence envelope
Our analysis combines primary interviews (oncologists, payers, diagnostic lab directors), secondary research (regulatory filings, clinicaltrials.gov, patent databases), and proprietary modeling calibrated to observed uptake patterns in comparable targeted oncology segments. The base-year dataset anchors to 2025; forecasts run through 2032 and include sensitivity testing around the most consequential uncertainties: clinical trial outcomes, patent expiry timing, and payer policy shifts. While this executive summary highlights directional takeaways, the full report contains the modeled assumptions, scenario toggles, and segmented outputs necessary to operationalize decisions.
Next steps and how to access the full dataset
For executive teams preparing budgets and product strategies in 2026, this is a limited window to act on differentiation, access, and partnership strategies before price erosion and intensified competition reshape economics. PW Consulting’s full report provides the granular segmentation, per-market access timelines, and client-ready playbooks withheld here to preserve advisory value and confidentiality. Visit our report page to access the complete dataset, interactive models, and to schedule a bespoke briefing where we translate these insights into a tailored go-to-market plan for your asset or portfolio.
PW Consulting—combining market rigor with commercial pragmatism—to turn the ROS1 inhibitors opportunity into a 2026 competitive advantage.
For detailed analysis of this topic, please visit the official page: Targeted Drug Ros1 Inhibitors For Nsclc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


