



PW Consulting: Veterinary Examination Light Market Reaches USD 403.0 Million in 2025; LED Segment Leads with USD 319.4 Million

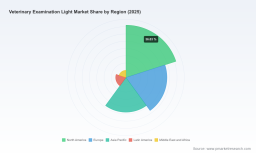
Veterinary Examination Light Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market research brief on the Veterinary Examination Light market distills actionable intelligence for executives, procurement leads, product teams, and M&A advisors preparing for 2026. Built on a robust historical base (2020–2025) and a detailed forecast (2026–2032), the study quantifies a stable, mid-single-digit growth trajectory (5.28% CAGR across the forecast window) and maps the commercial, regulatory, and technological inflection points that will shape supplier and buyer strategies in the coming 18–36 months.
Veterinary Examination Light Market
Quick strategic takeaways
- Market scale and momentum: The global market expands from a mid-three-hundred million USD base in 2025 to a significantly larger opportunity by 2032 (detailed figures included in the full report), driven by technology refresh cycles, increasing adoption of LED-based platforms, and widening clinical expectations in companion-animal and specialty care.
- Consolidation signal: The top-tier concentration is meaningful but not prohibitive — the three- and five-firm concentration ratios indicate room for both incumbents to extend leadership and for focused challengers to gain share through product differentiation or channel excellence.
- Business priorities for 2026: Resilient sourcing, product modularity, higher CRI and thermal management specifications, camera/video integration for telemedicine/referral workflows, and compliance with medical device standards will be decisive in procurement and specification choices.
Market evolution and what the numbers say
PW Consulting’s topline sizing shows the Veterinary Examination Light market progressing from the early-2020s base through a recovery and growth phase into 2026 and beyond. After a period of modest fluctuation across 2020–2024, the market reached an estimated USD 403.0 Million in our base year (2025). Under our central forecast, the market continues to expand at a compound annual growth rate of roughly 5.28% through 2032, reaching a substantially larger addressable pool by the end of the projection period. This pace reflects a mix of replacement demand, upgrades to LED and integrated systems, and incremental purchases driven by the growth of veterinary outpatient services and specialty referral centers.
Veterinary Examination Light Market
Those preparing strategic plans for 2026 should treat these numbers as directional evidence of a stable, investible sector: not ultra-high growth, but attractive for companies that can execute on product innovation, channel strategies, and supply-chain resilience.
Veterinary Examination Light Market
Key demand and supply drivers
- Technology migration: LED platforms continue to displace legacy halogen designs due to longevity, reduced heat, and energy efficiency. Buyers are demanding higher color rendering indices, better thermal management, and increasingly, camera/video integration for documentation and teleconsultation.
- Clinical expectations: Veterinary clinics and hospitals are upgrading lighting to meet the needs of soft-tissue procedures and expanded outpatient services; this is complemented by adopters in academic and research contexts who require reproducible lighting characteristics for training and study.
- Regulatory and standards pressure: Compliance with medical electrical equipment standards is a differentiator—manufacturers that demonstrate adherence to recognized standards and maintain quality management certifications reduce procurement friction in institutional sales.
- Supply-chain and trade dynamics: Manufacturers with localized production footprints are better positioned to manage tariffs, lead times, and custom integration requests. Recent industry behavior shows a clear bias toward suppliers that can guarantee shorter lead times and predictable warranty support.
What PW Consulting’s report delivers — the operational intelligence
Our report is explicitly designed as a decision-support tool for 2026. It combines market sizing and forecast rigor with practical, executable outputs:
- Buyer decision frameworks: procurement scorecards, total cost of ownership templates, and specification matrices that link clinical requirements to product features and service commitments.
- Supplier benchmarking and scorecards: quality, warranty, production footprint, channel strength, and aftermarket service assessments for the leading global and regional vendors.
- Commercial playbooks: targeted GTM strategies for OEMs, distributors, and private-label manufacturers across clinic, hospital, and academic segments, with go-to-market tactics calibrated by buyer persona.
- Pricing and contract guidance: dynamic pricing models, tender negotiation levers, and sample SLA language for 2026 procurement cycles.
- M&A and partnership lenses: candidate screening criteria for roll-up strategies, bolt-ons to enhance service capabilities, and integration checklists for lighting + camera/video or lighting + IT connectivity bundles.
- Supply-chain risk matrix: supplier redundancy planning, localization trade-offs, and tariff mitigation playbooks to minimize delivery disruption.
- Regulatory and compliance annexes: summary of relevant medical-device standards and certification expectations that buyers and OEMs must factor into purchasing and R&D roadmaps.
Competitive landscape — who matters and why
The competitive set spans specialized lighting houses, diversified medical-device groups, and regional manufacturers. PW Consulting profiles each player not merely by product portfolio but by what truly drives competitive advantage in 2026: manufacturing footprint, service capabilities, product durability, integration readiness, and channel reach.
- Burton Medical LLC (Addison, IL, USA): A long-established U.S. manufacturer with a deliberate domestic production strategy to insulate customers from global supply-chain shocks. Their positioning around reliability and Made-in-USA lead times makes them a default option for procurement organizations prioritizing lead-time certainty and localized support.
- Waldmann Lighting Company (U.S. operations; German HQ): Known for veterinary-focused surgical and exam lights with strong color rendering and heat-management features. Their product ergonomics and clinical design focus appeal to referral centers and clinics performing routine procedures.
- Huot Instruments / StarTrol: Rugged, long-warranty LED platforms with articulated arms and a reputation for longevity—attributes that reduce total cost of ownership for high-use clinic environments.
- ACEM Spa and RIMSA (Italy): European engineering-led players with product families that scale from exam-level to surgical-grade lighting; compliance with recognized safety standards and quality certifications is a core selling point in institutional procurement.
- Brandon Medical (UK): Differentiates with integrated HD video and camera systems—an increasingly important capability for referral hospitals and institutions deploying telemedicine and teaching applications.
- Regional manufacturers (Mindray, GPC Medical, Narang Medical, Medical Illumination, Surgiris and others): Provide competitive pricing and locally adapted configurations, and in some markets they form the backbone of equipment refresh cycles where value and channel proximity dominate.
Across this set, PW Consulting highlights that the market concentration is notable but allows for disruption: the three-firm concentration (CR3) and five-firm concentration (CR5) ratios reflect meaningful share by top players while leaving competitive space for fast-followers and niche specialists to expand through targeted investments.
Recent signals you must factor into 2026 plans
- Product refreshes and catalog updates continue to push higher illuminance and CRI levels while adding focusable optics and dimming features; catalog releases in early 2026 confirm this trend.
- Manufacturers emphasizing domestic production or diversified footprints are reducing lead-time risk and mitigating tariff exposure — a clear procurement preference emerging in 2025–2026.
- Regulatory compliance (medical electrical standards) and quality certifications are becoming table stakes for institutional sales; suppliers lacking certified processes face longer approval cycles and lost tenders.
- Integration of cameras and video systems into exam and surgical lighting is evolving from a niche upgrade to a mainstream requirement for referral centers and teaching hospitals.
Practical implications for corporate decision-making in 2026
- Procurement leaders should adopt a TCO + resiliency framework: quantify not only price but warranty, repairability, spare-parts lead times, and supplier geographic risk.
- Product teams must prioritize modularity and integration: design LED platforms that can accept camera modules, different mounting configurations, and IoT-enabled monitoring to stay relevant across clinic tiers.
- M&A strategists should look for targets that add either high-margin service capabilities (preventive maintenance, calibration) or integration expertise (video/IT), rather than purely volume plays.
- Channel and distribution leaders must invest in training and service networks—post-sale uptime and rapid parts replacement are major competitive differentiators.
- Compliance and regulatory functions should map certification timelines into product-roadmap gating decisions to avoid lost opportunities in institutional tender cycles.
Accessing the full intelligence
This article summarizes the strategic contours of PW Consulting’s Veterinary Examination Light market report and highlights the decision-grade outputs that will matter in 2026. In keeping with our “trailer” principle, we have showcased the analytical depth and decision frameworks while intentionally withholding detailed subsegment tables, region-by-region breakdowns, and proprietary pricing matrices. These core datasets and the full set of annexes are available through PW Consulting’s report access portal and are essential for teams that must build investment cases, procurement RFPs, or M&A screeners.
For executives preparing budgets, sourcing strategies, or product roadmaps for 2026, the full report provides the granular inputs and executable templates needed to act with confidence. PW Consulting remains available for bespoke briefings, scenario modeling, and M&A advisory to translate the market forecast and supplier intelligence into concrete business outcomes.
For detailed analysis of this topic, please visit the official page: Veterinary Examination Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


