



PW Consulting: Wafer FOUP Market to Reach USD 1,045 Million in 2025; Forecast Points to 8.7% CAGR Through 2032

Wafer FOUP Market 2026: Strategic Imperatives for Semiconductor Leaders
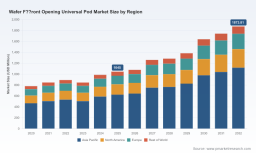
PW Consulting’s latest market study on Wafer Front Opening Universal Pods (FOUPs) positions the segment as a critical, yet often underappreciated, lever in semiconductor supply-chain resilience and process yield optimization for 2026 and beyond. The FOUP market reached approximately USD 1,045 million in 2025 and — driven by capacity expansions, automation upgrades, and contamination-control investments across fabs — is modeled to grow at a compound annual growth rate (CAGR) of 8.7% through our 2026–2032 forecast horizon, reaching roughly USD 1,874 million by 2032. These headline figures understate the tactical and strategic choices that fab operators, equipment suppliers, and materials vendors must make this year.
Wafer Front Opening Universal Pod (FOUP) Market
Why FOUPs Matter Now — Beyond a Container
FOUPs are no longer passive transport vessels. As process nodes shrink, EUV overlay tolerances tighten, and advanced packaging flows increase wafer handling frequency, FOUPs influence contamination budgets, tool uptime, and automation throughput. Two converging forces are elevating their importance:
Wafer Front Opening Universal Pod (FOUP) Market
- Process sensitivity: Particle budgets and microenvironment stability inside carriers increasingly translate into measurable yield impact, especially for EUV-intensive processes and advanced logic nodes.
- Operational scale and automation: New fabs and AMHS deployments raise FOUP throughput expectations while tightening requirements for standardization, materials performance, and integration with factory automation.
Market Trajectory: Interpreting the Macros
PW Consulting’s time-series model, calibrated on historical data from 2020–2025 and validated against supplier shipment signals and fab buildouts, captures both cyclical effects and structural growth. After pandemic-era volatility and mid-cycle corrections, the market regained momentum in 2024–2025 as capex resumed and regional supply diversification projects matured. Our central forecast foresees steady expansion at the 8.7% CAGR cited above, driven by replacement cycles, increased unit counts per fab, and growing adoption of higher-specification carriers (e.g., purge-capable and advanced sealing FOUPs) in process-critical environments.
Wafer Front Opening Universal Pod (FOUP) Market
These aggregate metrics yield practical inference: capital planners should expect non-trivial FOUP demand when sizing AMHS investments and in contract negotiations for wafer handling automation. Procurement and operations teams that treat FOUPs as a line-item expense rather than a systems component risk underestimating their total cost of ownership (TCO) impact over multi-year production ramps.
Industry Structure and Competitive Dynamics
The FOUP market exhibits significant concentration among a small number of global suppliers. Our competitive analysis shows a high market share concentration among leading manufacturers, underscoring both supplier bargaining power and the importance of strategic vendor selection for buyers. Key dynamics shaping competitive behavior include:
- Standards-driven lock-in: SEMI compliance (M31, E1.9, E47.1, E15.1, E57, E62, and related interfaces) remains the baseline for interoperability with AMHS and automated tools; suppliers that accelerate standards alignment enjoy faster qualification cycles.
- Materials differentiation: High-purity, low-outgassing polymers and conductive components (E7–E10 grade materials) are technical differentiators that materially reduce contamination risk and extend FOUP lifecycles.
- Service and aftermarket: Cleaning, recertification, and component repair services are emerging as margin drivers and retention levers for suppliers; buyers benefit from bundled service-level agreements to reduce lifecycle costs.
Representative suppliers we examined — from global incumbents to regional specialists — include Entegris (U.S.), ePAK International (Malaysia/global), Miraial (Japan), Shin-Etsu Polymer (Japan), Gudeng Precision (Taiwan), and multiple other Asia-based and U.S. suppliers. Their product positioning ranges from high-capacity 300mm standard FOUPs to nitrogen-purgeable and diffusion-control variants, and from commodity manufacturing to value-added service models. Recent supplier moves (production expansion in North America, refreshed product catalogs, and targeted supply agreements) signal tactical responses to both demand growth and geopolitical sourcing diversification.
Recent Industry Signals to Monitor
- Supply agreements and service expansion: Notable orders and cleaning-equipment contracts with major memory and logic fabs indicate a tightening market for ancillary services that support FOUP life extension.
- Reshoring and capacity investments: Production facility expansions in North America and incremental localization efforts in Japan reflect supplier strategies to mitigate geopolitical and logistics risks for key customers.
- Product refreshes: Catalog updates and new product introductions highlight continued feature competition around purge options, slot capacity, and automation compatibility.
Regulatory and Materials Constraints
Beyond commercial dynamics, regulatory and technical constraints shape procurement windows and qualification timetables. SEMI standards remain the technical backbone for dimensional tolerances and automation interfaces. Concurrently, a limited set of polymer formulations compatible with low particle generation and long-term dimensional stability constrains supplier flexibility and extension strategies. Buyers must therefore plan qualification cycles that accommodate both standards testing and accelerated aging or outgassing assessments.
Practical, Actionable Content in the Full Report
The PW Consulting FOUP Market report is designed as a decision-ready playbook for 2026. It integrates market modeling with practical tools and intelligence, including (but not limited to):
- A validated market sizing framework and scenario-based forecasts through 2032, including sensitivity analyses tailored to capex timing and yield-improvement programs.
- Supplier dossiers and a vendor-selection matrix that score capabilities across technical fit, geographic footprint, capacity flexibility, service offerings, and risk exposure.
- Procurement playbooks for fab operators that map qualification steps, typical lead times, and cost levers (purchase vs. lease, cleaning contracts, spare pools), with sample timelines calibrated to standard fab ramp plans.
- Contamination-risk quantification templates linking FOUP microenvironment attributes (sealing performance, material outgassing, purge efficacy) to process-level yield impact estimates.
- Supply-chain stress tests and sourcing strategies that model the implications of regional disruptions, lead-time shocks, and rapid capacity shifts.
To preserve competitive value for subscribers and corporate decision-makers, the report intentionally withholds granular regional and application split tables in this public release. Those detailed segmentations, supplier shipment-level estimates, and contract-level benchmarks are available in the full report package on our website.
Strategic Recommendations for 2026 Decision-Makers
- Adopt a systems view: Treat FOUPs as components in yield and automation systems. Incorporate FOUP TCO into tool uptime and yield improvement business cases rather than isolating them as packaging spend.
- Accelerate vendor qualification in 1H–2H 2026: Given forecast demand growth and supplier lead times, start parallel qualification tracks with primary and secondary suppliers now to avoid constraint-driven premium sourcing later in the year.
- Layer inventory and service contracts: Combine strategic buffer inventories for critical fabs with long-term cleaning and recertification contracts to minimize unexpected downtime and reduce life-cycle costs.
- Prioritize materials and purge capabilities for EUV/advanced nodes: For nodes with tight contamination budgets, prioritize carriers with validated purge and sealing performance; invest in lab-level joint testing with suppliers to close uncertainty fast.
- Use regional diversification defensively: Balance cost efficiencies with geopolitical risk. Work with suppliers that offer multi-region manufacturing or contract manufacturing partnerships to mitigate single-source exposure.
- Incentivize modularity and retrofit compatibility: Select FOUP configurations that facilitate interchangeability and retrofit into existing AMHS to future-proof investments against incremental process changes.
For Suppliers: Commercial and Product Playbooks
FOUP manufacturers and tiered suppliers should consider three concurrent strategies to capture the growth opportunity:
- Differentiate on end-to-end value: Expand cleaning, repair, and lifecycle services to lock customers into longer revenue streams and to demonstrate measurable TCO reductions.
- Invest in materials and standards leadership: Accelerate certification to SEMI updates and invest in low-outgassing polymer formulations to be the preferred partner for advanced-node fabs.
- Pursue geographic flexibility: Target targeted capacity investments or partnership models near major fab clusters to shorten lead times and offer localized service contracts.
Closing Perspective
The FOUP market is shifting from a commoditized ancillary market to a strategic focal point that affects yield, uptime, and capital efficiency. With a 2025 market base of roughly USD 1,045 million and a clear growth trajectory through 2032 at an 8.7% CAGR, companies that incorporate FOUP strategy into their 2026 procurement, process, and supply-chain plans will gain incremental yield and resiliency advantages. Our report equips decision-makers with the models, supplier intelligence, and procurement playbooks necessary to act decisively — while the full dataset and granular segmentation remain reserved for report subscribers and corporate clients.
To obtain the comprehensive dataset (including detailed regional and application splits, supplier shipment tables, and downloadable procurement templates), visit the PW Consulting FOUP Market report page and download the full report package. Strategic windows in 2026 are short; leaders should act now to align supply, certification, and lifecycle strategies with the evolving market dynamics.
For detailed analysis of this topic, please visit the official page: Wafer Front Opening Universal Pod (FOUP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


