



PW Consulting: Metal Halide Light Tower Market Tops USD 1,470 Million in 2025, Poised for a 2.81% CAGR Through 2032

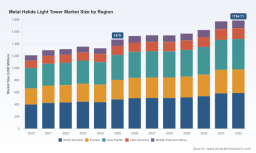
Metal Halide Light Tower Market — PW Consulting Executive Preview (2026): Strategic Guidance for CapEx, Procurement and Competitive Positioning
PW Consulting today releases an executive preview of our Metal Halide Light Tower Market report, a practical intelligence product designed to support capital and operational decisions in 2026. Drawing on a five‑year historical analysis and a seven‑year forecast horizon, the study places the global metal halide light tower market in clear strategic context: from a measured recovery over 2020–2025 to a stable, slower‑growth trajectory through 2032. The market registered a level of approximately USD 1,470.0 million in 2025 and, at a 2026–2032 CAGR of 2.81%, is projected to finish the forecast period materially higher while remaining a niche, mission‑critical segment for certain heavy‑industry and rental customers.
Metal Halide Light Tower Market
Why this report matters for 2026 decision‑makers
-
Actionable intelligence for procurement: precise supplier diagnostics, risk scores and a procurement playbook tailored to high‑intensity illumination applications where uptime and luminous performance, not pure energy efficiency, drive buying decisions.
Metal Halide Light Tower Market -
CapEx vs. rental modelling: side‑by‑side TCO frameworks and scenario outputs that quantify trade‑offs across purchase, lease and rental strategies for corporate fleets and rental houses facing variable utilization.
Metal Halide Light Tower Market -
Regulatory and emissions roadmaps: compliance trajectories for diesel‑powered units (including Tier‑4 Final implications in key jurisdictions), plus retrofit and replacement thresholds that tie regulatory timing to equipment replacement cycles.
-
Supply‑chain resilience playbook: mapping of critical lamp and component dependencies, supplier single‑point‑of‑failure diagnostics, and practical mitigation options—from dual sourcing to strategic stocking and near‑shoring considerations.
What the PW Consulting report contains — practical deliverables
-
Market sizing and trend analysis (2020–2025 historical, 2026–2032 forecast) with scenario sensitivity to macro growth, commodity pressure and emissions policy changes.
-
Demand archetypes and buyer personas for construction, heavy industrial, rental and emergency‑response users—translated into procurement decision trees and maintenance schedules.
-
Supplier benchmarking and scorecards covering product robustness, mast and fixture architectures, service networks, spare‑parts support, and rental readiness.
-
CapEx/Opex modelling templates that allow CFOs and fleet managers to stress test fleet renewal cycles versus LED migration and emissions compliance costs.
-
Risk matrix and playbooks for raw‑material volatility (notably lamp and arc‑tube supply), logistics disruption, and regulatory shocks affecting field operations.
-
M&A and partnership watchlist—actionable flags for acquirers and strategic partners based on capability gaps and aftermarket potential.
Market dynamics shaping 2026 choices
Two structural drivers define the market’s strategic profile. First, metal halide light towers continue to serve applications where high lumen output and large‑area coverage are non‑negotiable—mining, oil & gas turnarounds, and specific heavy construction use cases. In these contexts, operators prioritize luminous intensity, penetration, and temporary large‑area coverage over absolute energy efficiency, preserving demand for metal halide technology even as LED alternatives proliferate.
Second, the regulatory and emissions environment is increasingly influential. For diesel‑powered mobile units, compliance with stringent emissions standards in key markets has raised the bar for engine selection and aftertreatment strategies, influencing total ownership costs and replacement timing. On the supply side, metal halide lamps rely on specialized materials—metal halide salts and quartz arc‑tube components—and operate within a lamp market ecosystem that itself demonstrates meaningful scale (industry estimates put the lamp market in the low single‑billion USD range in 2025). These two facts together create a landscape in which manufacturers, rental companies and large end users must balance procurement, inventory and lifecycle decisions against component availability and emissions compliance timing.
Competitive landscape — who to watch and why
The market remains characterized by a set of well‑established industrial OEMs and niche specialists. Competing strategies fall into a few distinct patterns: industrial robustness and rental‑friendliness; vertical mast and compact designs for urban construction; ultra‑large mast and fixture counts for heavy industrial coverage; and custom offerings for project specialists. Highlights from the competitive set include:
-
Atlas Copco (Stockholm, Sweden — https://www.atlascopco.com): positions products around ruggedness and rental suitability, with canopy and structural features designed for harsh quarry and rental environments. Their product messaging emphasizes durability, which is a core procurement criterion for rental houses and contractors aiming to minimize downtime and service costs.
-
Generac Mobile (Magnum) (Waukesha, Wisconsin, USA — https://www.generac.com): emphasizes compact, serviceable vertical‑mast designs that suit congested construction sites. Generac’s product portfolio is built to balance portability with the high lumen output demanded by contractors, making it a common choice for mixed fleet strategies.
-
Wacker Neuson (Munich, Germany — https://www.wackerneuson.com): competes with jobsite‑focused towers that integrate into broader equipment fleets and service infrastructures; differentiation is based on system interoperability and global service reach.
-
Grandwatt Electric Corp (USA/China operations — https://www.grandwatt.com): operates across custom and standard segments, serving clients requiring tailored solutions for unique project needs—an important niche for large‑scale, irregular projects.
-
Boss LTG (BossLTR) (Baton Rouge, Louisiana, USA — https://bossltr.com): focuses on trailer‑mounted high‑output models aimed at construction and mining applications; their positioning reflects a strategy built on high lumen per unit and heavy‑duty trailering.
-
DMI Light Towers (Greenwell Springs, Louisiana, USA — https://dmilighttowers.com): known for very large portable configurations with extended mast heights and high fixture counts, targeting expansive industrial sites where coverage area matters more than portability.
-
Trime USA (part of Trime Group — https://trimeusa.com): offers mobile light towers tuned to contractor and rental needs, blending ease of transport with field reliability.
-
Larson Electronics (Kemp, Texas, USA — https://www.larsonelectronics.com): supplies high‑lumen solutions for hazardous and industrial environments, often competing on niche configurations and rapid delivery for service outages and emergency deployments.
Across this set, competitive differentiation increasingly hinges on aftersales, digital enablement (remote monitoring, telematics for utilization and maintenance), and flexible rental or service models. For buyers, supplier selection is as much about network and spare‑parts agility as it is about lamp and mast specifications.
Strategic recommendations for executives in 2026
-
Revisit fleet renewal timelines with regulatory milestones in mind. Align engine and emissions investments to regulatory windows so replacement and retrofit cycles minimize stranded assets.
-
Adopt a hybrid acquisition strategy: retain ownership where utilization is predictable and serviceable centrally; favor rental for episodic, large‑area projects and peak‑season surges.
-
Insist on supplier scorecards that weigh service network depth and spare‑parts lead times as heavily as initial unit price—downtime cost can exceed purchase savings in heavy‑duty applications.
-
Build a strategic inventory of critical lamp components or establish contractual safeguards with lamp suppliers; material specialization and concentrated supplier capacity can create single‑source risk.
-
Pursue aftermarket monetization: extended warranties, predictive maintenance services enabled by telematics, and rapid‑response field teams unlock recurring revenue and reduce total fleet cost.
How to use the full PW Consulting report
The full report contains the granular tables, regional and application segmentation, and vendor‑level scorecards that underpin the executive recommendations summarized here. Subscribers receive dynamic modelling files, procurement templates and a regulatory compliance roadmap specific to major jurisdictions. For teams building 2026 capital budgets, the forecast scenarios and TCO calculators included in the full study will materially reduce uncertainty when comparing purchase, lease and rental strategies.
To protect strategic value for paying clients while demonstrating the depth of our work, this executive preview highlights direction and implications without publishing the detailed regional, application and type splits. Those granular tables, time‑series datasets and supplier quantitative comparisons are available on the report landing page.
Conclusion
For companies making 2026 capital and operational choices, metal halide light towers remain a distinct category where product performance, regulatory timing and supply‑chain fragility intersect. PW Consulting’s Metal Halide Light Tower Market report equips executives with the scenario‑tested analytics, supplier playbooks, and procurement templates required to optimize fleet decisions, mitigate supply risk, and capture aftermarket value. For access to the full dataset, downloadable modelling tools, and supplier scorecards, please visit our report page to review the comprehensive findings and purchase options.
— PW Consulting, Strategic Advisory and Industry Analysis
For detailed analysis of this topic, please visit the official page: Metal Halide Light Tower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


