



PW Consulting: PAG Compressor Oil Market to Reach USD 1.46 Billion by 2032 with a 6.51% CAGR — Automotive A/C and End‑Capped PAG Fuel Growth

Pag Compressor Oil Market: A 2026 Strategic Playbook for Industry Leaders
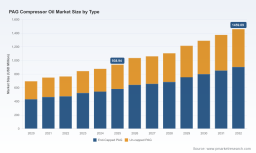
As companies set budgets and strategic priorities for 2026, the Pag (polyalkylene glycol) compressor oil market is at an inflection point. PW Consulting’s latest Pag Compressor Oil Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—delivers the market context and decision-grade analytics that executives and commercial teams need to navigate accelerating regulatory shifts, raw-material volatility, and technology-driven demand changes. The market’s multi-year compound annual growth rate (CAGR) of 6.51% underpins a trajectory that moves the sector into a different competitive posture by late-decade; this analysis translates that macro momentum into concrete strategic options without disclosing the granular splits reserved for the full report.
Pag Compressor Oil Market
Why this report matters for 2026 decisions
-
Timing: 2026 is a planning inflection—capital allocation cycles, OEM specification updates, and refrigerant transitions aligned with regulatory timetables converge this year. Companies that use 2026 as the year to set new supplier, product, and R&D strategies will capture disproportionate upside.
Pag Compressor Oil Market -
Regulatory pressure: Global low‑GWP refrigerant adoption and regional regulatory actions accelerate demand for PAG chemistries compatible with next‑generation refrigerants. The resulting specification changes create both technical barriers to entry and premium pricing opportunities for compliant formulations.
Pag Compressor Oil Market -
Cost and margin volatility: Upstream feedstocks for PAG synthesis experienced measurable cost pressure in late 2025 and into 2026, creating near-term margin compression unless firms adopt hedging, backward-integration, or dynamic pricing strategies.
-
Product evolution: Longer-life formulations, low-ash and dielectric-optimized oils for electrified compressors, and cross‑OEM approvals are reshaping procurement criteria—buyers are prioritizing total cost of ownership and performance under higher discharge temperatures.
What the report delivers: operational depth, built for use
The report is engineered as an operational playbook, not just a market narrative. Key practical deliverables include:
- Market sizing and scenario forecasts built from 2020–2025 historicals and modeled forward across multiple demand and regulatory scenarios for 2026–2032.
- Demand-driver diagnostics linking refrigerant transitions, OEM electrification timetables, and industrial equipment replacement cycles to near- and mid‑term PAG demand.
- Supply-chain and cost modelling that quantifies the impact of feedstock price swings and CPI/PPI trends on cost structures and gross margins.
- Commercial playbooks for pricing, channel segmentation (OEM vs aftermarket vs industrial), and contract design to protect margin under price volatility.
- Supplier and technology scorecards assessing base‑stock producers, additive specialists, and formulators on supply security, technical approvals, and scale-readiness.
- M&A and partnership analytics setting out target profiles, valuation sensitivities, and integration checklists for buyers seeking scale or capability gaps.
- Regulatory heatmaps and compliance roadmaps aligned to the EU F‑Gas timeline, Kigali Amendment implications, and other jurisdictional drivers affecting refrigerant-compatible lubricants.
Competitive landscape: what leading players reveal about industry direction
Market leadership today is defined by three capabilities: approved formulation breadth (multiple refrigerant and compressor types), secure supply of PAG base stocks, and channel penetration across OEM, industrial, and aftermarket sales. The report examines how strategic positions are evolving among the sector’s core participants.
- ExxonMobil —leverages OEM approvals and high-performance synthetic formulations to compete on specification and reliability for industrial and refrigeration applications.
- Shell —positions PAG offerings around fire-resistance and efficiency, with branded lines that emphasize performance in demanding compressor environments.
- Chevron —focuses on reciprocating compressor segments and has pursued scale via strategic transactions to broaden its industrial lubricants footprint.
- Phillips 66 —markets premium synthetic PAGs across a wide set of compressor types, emphasizing versatility and approval breadth.
- BASF —a critical upstream player supplying PAG base stocks; its backward integration and raw materials capability are a supply-security differentiator for formulators.
- TotalEnergies and Idemitsu —both offer formulations tailored for automotive AC and refrigeration use-cases, with attention to compatibility across refrigerant families.
- Specialists and niche players —FUCHS, Klüber, AMSOIL, Castrol (BP), Shrieve, Cargill, Next Lubricants, and Matrix—continue to innovate on additive packages, dielectric properties, and application-specific solutions, competing through technical differentiation rather than scale.
Recent moves underscore two concurrent dynamics: consolidation at scale and rapid product innovation at the edges. Recent product launches for electric and hybrid vehicle HVAC, extended-life air compressor oils, and strategic acquisitions highlight a bifurcation—larger players are securing supply and distribution scale while nimble innovators push technical boundaries that will influence OEM specs.
Supply-chain and raw-material dynamics shaping 2026 strategies
Polyalkylene glycol feedstocks remain the most immediate source of cost and supply risk. Late-2025 inflation and producer price upticks have translated into higher PAG production costs and more volatile procurement windows. Ethylene oxide and propylene oxide price movements are the primary drivers; their volatility forces manufacturers to adopt more flexible sourcing, active hedging, or closer integration with base‑stock suppliers.
For 2026 planning, firms should stress-test procurement strategies against three scenarios: stable feedstock prices, a sustained up‑cycle driven by upstream capacity tightness, and sporadic spikes from feedstock disruptions. Each scenario has distinct implications on pricing strategy, inventory policy, and customer contract terms.
Strategic recommendations for 2026 (executive priorities)
- Prioritize refrigerant compatibility as a product design principle: Update R&D roadmaps to ensure formulations meet low‑GWP refrigerant compatibility and dielectric requirements for electrified compressors—this will unlock OEM approvals and premium pricing.
- Lock in supply through diversified sourcing and strategic partnerships: Negotiate multi-tier agreements with base‑stock suppliers and consider minority investments or offtake arrangements to stabilize input costs.
- Adopt dynamic pricing frameworks: Move away from fixed multi-year pricing where possible; deploy index-linked clauses tied to feedstock cost drivers to preserve margins.
- Segment commercial models by TCO, not price alone: Market extended-life and high-temperature-tolerant oils on lifecycle cost savings to OEMs and industrial customers to capture value beyond commodity pricing.
- Identify M&A and JV targets now: Use 2026 to close capability gaps—whether in additive R&D, specialty formulations for EV HVAC, or geographic distribution—before regulatory and technology transitions accelerate consolidation.
- Invest in compliance and certification pipelines: Fast-track testing and approvals for new refrigerant compatibility and advertise validated approvals as a differentiation tool in procurement cycles.
- Deploy scenario-based capital allocation: Maintain a capital buffer for rapid capacity or capability investment should feedstock or regulatory scenarios require accelerated response.
Decision-support assets you can deploy immediately
Beyond narrative, the report contains actionable templates for 2026 execution: supplier scorecards that map technical and delivery risk; a cost-to-serve matrix for channel optimization; a procurement playbook with negotiation levers tied to feedstock scenarios; and an M&A diligence checklist tailored to lubricant and base-stock assets. These assets are designed to be operationalized within 60–120 days to influence 2026 procurement cycles and partnership negotiations.
How to use this intelligence
Executives should treat the report as a decision-support system: run a three-scenario workshop with commercial, procurement, and R&D leads; prioritize shortlists for supplier and M&A targets; and lock in 2026 procurement terms aligned with the scenario most likely for your cost and margin tolerance. Marketing and product teams should use the regulatory heatmap to accelerate product approvals that will unlock premium segments.
PW Consulting’s Pag Compressor Oil Market report balances strategic narrative and executable detail. It demonstrates why the market’s underlying growth (as captured in our 2026–2032 forecast and the underlying CAGR) creates both opportunity and risk, and it supplies the practical instruments companies require to convert that macro trajectory into winning 2026 actions.
Next steps
-
For full regional and application splits, granular company scorecards, downloadable models, and the regulatory-compliance appendices that inform 2026 decisions, please consult the full report and supporting datasets available from PW Consulting.
-
If you would like a tailored briefing—scenario modeling for your portfolio, supplier stress-testing, or a rapid M&A screen—contact PW Consulting to set up a strategy workshop focused on executable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Pag Compressor Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


