



PW Consulting Report: Road Crash Attenuator Market to Grow at 6.09% CAGR, Reaching USD 977.02 Million by 2032

Road Crash Attenuator Market 2026: Strategic Imperatives for Resilient Growth — PW Consulting Insight
Executive summary
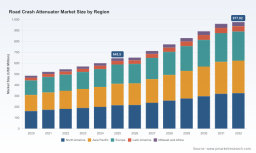
PW Consulting’s latest Road Crash Attenuator Market report synthesizes five years of historical performance and a seven-year forward view to equip executive teams with the evidence base needed for decisive 2026 strategy. The market has demonstrated steady expansion, rising from approximately USD 485.2 Million in 2020 to USD 645.5 Million in 2025. Our model projects continued growth through 2032, with a compound annual growth rate of 6.09% across the 2026–2032 forecast window and an expected market approaching USD 1.0 Billion by 2032.
Road Crash Attenuator Market
This release presents the strategic highlights from that research: a concise interpretation of demand drivers, supply-side pressures, competitive positioning, regulatory implications, and the practical playbook PW Consulting recommends for product, procurement, and M&A agendas in 2026. Detailed segment tables and granular regional/application breakdowns are intentionally held back to preserve the “trailer” principle of this announcement—full segmentation and company-level benchmarking are available in the full report on our website.
Road Crash Attenuator Market
Why this matters for 2026 decision-making
2026 will be a hinge year for road safety infrastructure suppliers and buyers. Governments and contractors face increased pressure to improve work-zone safety, reduce highway fatalities, and meet stricter procurement rules. At the same time, rising raw material costs and concentrated vendor dynamics are reshaping commercial and operational levers. The figures above mask a complex mix of structural demand and episodic procurement cycles; leaders that align product portfolios, capital allocation, and supply chain hedges to these dynamics will capture disproportionate share of the next growth wave.
Road Crash Attenuator Market
Key market dynamics
-
Demand momentum: Public infrastructure programs and renewed focus on work-zone safety undergird the medium-term uplift. Adoption of higher-performance attenuators and increased use of truck-mounted attenuators in temporary works are primary market drivers.
-
Supply-side pressure: Steel — specifically hot-rolled coil (HRC) — remains a cost vector to monitor. Early-2026 HRC price indications in the U.S. were around USD 1,002–1,118 per short ton; such ranges materially affect manufacturing margins, inventory strategy, and contract pricing for larger fabricators.
-
Regulatory gating: Compliance requirements continue to be a market fulcrum. In the U.S., federal-aid eligibility pivots on AASHTO MASH or legacy NCHRP 350 TL-3 approvals as validated by FHWA processes. In Europe, EN 1317 testing and CE marking, supplemented by ASI classifications, define product eligibility and procurement preference.
-
Market concentration: The sector shows moderate concentration at the top; our CR3 and CR5 metrics register at approximately 42.5% and 58.8% respectively — a structural environment that supports both competitive scale plays and targeted consolidation.
Competitive landscape — who’s shaping product and go-to-market
Our competitive profiling identifies a set of established incumbents and technology leaders who together shape product expectations, performance benchmarks, and procurement specifications:
-
Lindsay Corporation (Omaha, Nebraska) — Continues to expand its TAU technology line and truck-mounted offerings. Recent launches include a next-generation Road Runner TMA (early 2026) emphasizing rapid deploy/stow and vertical storage, and the TAU-M Wide 72-inch cushion (late 2025) that underscores a dual focus on enhanced protection and maintainability.
-
TrafFix Devices (San Clemente, California) — Maintains strong positioning with MASH-tested redirective systems and the Scorpion II family of TMAs; their engineering focus on full-width protection and short deployment length sets deployment efficiency benchmarks for contractors.
-
Hill & Smith (Columbus, Ohio / Hill & Smith Holdings) — Offers speed-dependent, self-restoring attenuators that optimize deceleration behavior across vehicle weight and speed profiles, reflecting a trend toward technology differentiation through adaptive resistance characteristics.
-
Valtir LLC (formerly Trinity Highway) — Broad portfolio across crash cushions and TMAs, including systems designed for both permanent and temporary applications; their multi-technology approach supports diverse procurement specifications.
-
Saferoad (Europe) — Emphasizes European compliance and high-performance ASI A certification for high-speed contexts; modular designs supporting rapid installation and repair are gaining traction in continental procurement frameworks.
-
Energy Absorption Systems — Known for compact, deployable TMA innovations; their product features underscore the value of logistical efficiency for contractor fleets.
Strategic implications by capability
-
Product development: Capitalize on value migration toward modularity, maintainability, and rapid deployment. Differentiation via speed-dependent energy management and reduced repair-cycle designs will command premium positioning in tenders that internalize life-cycle cost, not just capex.
-
Manufacturing and cost strategy: Lock in raw-material exposure through hedging, long-term supplier agreements, or material substitution where standards permit. Facility footprint decisions should weigh proximity to key public-works clusters to reduce logistic costs and accelerate response times for repairable systems.
-
Commercial and aftermarket: Build recurring revenue models around maintenance, rapid-repair modules, and rental fleets for TMAs. Competitive advantage accrues to firms that couple product sales with guaranteed service-level response times for work-zone redeployments.
-
M&A and partnerships: Given the sector’s moderate top-end concentration, selective M&A can accelerate entry into complementary segments (e.g., rental fleet providers, repair-service specialists, or regional installers). Joint development agreements with materials innovators (composites, energy-absorbing polymers) can shorten the product roadmap for lighter-weight attenuators.
-
Regulatory and tendering strategy: Invest in regulatory-compliance capability early. Products that are pre-qualified to MASH and EN 1317/ASI regimes unlock the broadest procurement pools. Anticipate evolving test protocols and embed testing timelines in the product development lifecycle to avoid go-to-market delays.
Actionable 90‑day playbook for executives
-
Conduct a rapid supply-cost audit: quantify direct exposure to HRC costs and identify immediate vendor hedging or inventory strategies to smooth margin volatility.
-
Prioritize product backlog by procurement impact: map each SKU against MASH/EN eligibility and expected tender windows over the next 12–18 months.
-
Initiate rental and service pilots in two high-density corridor markets to validate aftermarket revenue potential and improve asset utilization.
-
Target one bolt-on acquisition or strategic JV that adds either geographic reach or service capability within a six- to nine-month window, using a valuation framework that accounts for recurring service cashflows.
Methodology and confidence envelope
Our findings are derived from a multi-source methodology combining supplier financials, product registers, procurement tender analysis, primary interviews with public-works buyers and contractor fleets, and a bottoms-up installations model covering the historical window (2020–2025) and projecting through 2032. Sensitivity scenarios incorporate low/high infrastructure spend assumptions and a commodities shock case reflecting ±20% variance in HRC price paths. While the headline CAGR of 6.09% represents our central forecast for 2026–2032, our scenario analysis equips decision makers to stress-test investment plans against downside and upside macroeconomic outcomes.
What’s in the full report (practical deliverables)
The complete PW Consulting Road Crash Attenuator Market report includes:
-
Comprehensive market sizing and forecast tables (by region, application, and product type) with build-up methodology and source references.
-
Detailed supplier dossiers and benchmarking matrices covering product specs, regulatory certifications, installed base estimates, and go-to-market models.
-
Contract pricing compendia and a total-cost-of-ownership model to support procurement negotiations and lifecycle budgeting.
-
Supply-chain risk map with mitigations for commodity exposure, logistics choke points, and single-source dependencies.
-
Investment screening tool for M&A and JV evaluation, plus a 12–36 month execution roadmap for integration and value capture.
Final recommendation
For senior leaders preparing 2026 plans: treat the road crash attenuator market as a consolidating but innovation-driven sector where scale, regulatory certification, and service capability will determine winners. Prioritize actions that lock in material cost exposure, accelerate certification pipelines, and build recurring-service models. Companies that align product engineering with procurement realities — while remaining opportunistic on strategic partnerships — will be best placed to convert the sector’s steady top-line growth into durable margins and higher enterprise value.
To access the full segmentation dataset, company-level benchmarking, and our downloadable financial models, consult the PW Consulting report landing page. The detailed analyses and appendices provide the operative intelligence required to operationalize the strategic pathways summarized above.
For detailed analysis of this topic, please visit the official page: Road Crash Attenuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


