



PW Consulting: Radiation Dermatitis Cream Market valued at USD 520.4 Million in 2025, forecast to reach USD 744.56 Million by 2032 at a 5.25% CAGR

Radiation Dermatitis Creams: Strategic Imperatives from PW Consulting’s 2026 Market Outlook
Executive snapshot
The global Radiation Dermatitis Cream market is at an inflection point. Our latest market research, with a 2025 base year and a forecast spanning 2026–2032, shows the market growing at a compound annual growth rate (CAGR) of 5.25%. Having expanded materially since 2020, the market reached an estimated USD 520.4 Million in 2025 and is projected to approach approximately USD 744.6 Million by 2032 under our central scenario. For business leaders preparing 2026 budgets, product roadmaps, and M&A playbooks, the implications are clear: steady, clinically-driven demand presents predictable expansion opportunities—but only for organizations that execute against the right clinical, regulatory and commercial levers.
Radiation Dermatitis Cream Market Research
Why this report matters for 2026 decision-making
- Actionable forecast horizon. Our 2026-oriented analysis translates multi-year forecasts into short- to medium-term decision triggers—procurement cadence changes, reimbursement dossier timelines, and channel investment points that can be operationalized during fiscal-year planning.
- Clinically anchored commercial strategy. With practice guidelines increasingly favoring non-steroidal moisturizers and barrier approaches for early-grade radiation dermatitis, manufacturers must align product labels, clinical evidence generation and payer engagement to accelerate uptake.
- Risk-adjusted opportunities. We convert macro growth into prioritized, risk-weighted initiatives—R&D, regulatory, distribution, and M&A—that can be actioned within 12–18 months.
Market trajectory and practical implications
Historical dynamics show consistent expansion from 2020 through 2023, a modest correction in 2024, and a renewed upward trend into 2025. This pattern underlines two facts: end-market demand is resilient (anchored to oncology service volume) and short-term volatility can be driven by clinical guideline shifts, payer policies, and raw-material availability.
Radiation Dermatitis Cream Market Research
For commercial teams, the 5.25% CAGR through 2032 is not a passive signal; it defines capacity planning, inventory strategy, and go-to-market prioritization. Firms that treat this projection as an operational planning input—aligning manufacturing scale-up, SKU rationalization, and evidence generation timelines—will capture outsized share. Conversely, late adopters risk higher go-to-market costs and missed placement in institutional formularies.
Radiation Dermatitis Cream Market Research
Key dynamics shaping 2026 opportunities
- Clinical guidance drives product mix. National oncology guidelines increasingly recommend moisturizers and barrier creams without routine steroid use for low-grade radiation dermatitis. Products aligned with these recommendations gain preferential consideration in clinical procurement and formulary decisions.
- Formulation science is the differentiator. Silicone-based formulations offer occlusive protection that reduces trans-epidermal moisture loss, while hydrogel systems deliver targeted hydration and anti-inflammatory support. These mechanistic differences translate into distinct value propositions for clinicians and payers.
- Reimbursement contours matter. Select prescription creams for oncology patients are reimbursable under major payers in certain markets—an enabler of adoption in hospital settings. Manufacturers must craft reimbursement dossiers and coding strategies early.
- Supply-chain resilience is strategic. Raw material concentrations (e.g., specialty silicones) and specialized manufacturing for sterile hydrogels mean procurement disruptions can have an outsized commercial impact; vertical integration or dual-sourcing strategies are high-return moves in 2026.
Competitive landscape: what incumbents are doing (and where gaps remain)
The competitive field is populated by specialist dermatology players and established medtech/pharma distributors, each pursuing distinct routes to market. Representative profiles in our analysis include:
- PrimaMed Clinical Systems (Miaderm): Steroid-free formulations incorporating antioxidants and emollients—positioned for patients and clinicians seeking a conservative, tolerability-first option.
- Stratpharma AG (StrataXRT): Silicone gel dressings that emphasize occlusive protection and moisture retention—appealing to centers prioritizing prevention and wound-care integration.
- Integra LifeSciences (Xeladrone): Hydrogel-based approaches focused on hydration and modulation of the inflammatory cascade—targeted at acute symptom control settings.
- Viatris Inc. (Biafine Emulsion Cream): A broadly distributed topical emulsion used for barrier protection and skin repair—leveraging established distribution networks and brand recognition.
Our competitive scoring highlights that incumbent advantage derives not only from product efficacy, but from hospital formulary access, reimbursement navigation, and clinical-education programs. Moreover, the market shows moderate concentration: a group of specialty brands and large distributors together account for roughly half of current market activity. This opens room for focused challengers to disrupt through niche clinical differentiation or superior access models.
What the full report contains (practical deliverables)
- Detailed, audited market-sizing (historical and forecast) with scenario and sensitivity models that can be downloaded into corporate planning tools.
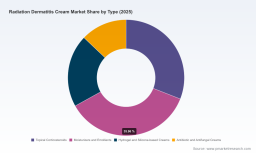
- Segmentation frameworks by product type, distribution channel, and therapeutic application—accompanied by a reproducible methodology and underlying data tables.
- Competitive profiles with go-to-market playbooks, win-loss insights from primary interviews, and capability heatmaps for top players.
- Clinical and regulatory mapping that ties guideline changes and payer policies to adoption inflection points.
- Reimbursement guidance and coding strategies, including country- and payer-specific pathways where applicable.
- IP landscape and patent watch, plus a pipeline tracker of investigational formulations and delivery platforms.
- Acquisition and partnership screening: quantifiable criteria to identify high-impact targets and a shortlist of potential bolt-on acquisitions based on capability, clinical fit and commercial reach.
- A proprietary decision-support model for prioritizing R&D, commercial and M&A investments over 12–36 months.
Strategic recommendations for 2026 (prioritized)
- Prioritize clinical alignment over feature differentiation. Products that can demonstrate alignment with oncology guideline recommendations (e.g., non-steroidal moisturizers and barrier creams for early grades) will secure faster formulary entry than those relying solely on novel ingredient claims.
- Invest in payer- and hospital-facing evidence. A concise reimbursement dossier and short-term real-world evidence (RWE) studies—focused on reduced treatment interruptions, decreased need for topical steroids, or improved patient-reported outcomes—are high-ROI investments.
- Optimize channel strategy with hospital pharmacy-first plays. Institutional placement drives volume and legitimizes retail and online expansion. Allocate commercial effort and samples budget to oncology pharmacy liaisons and formulary committees in 2026.
- Secure raw-material continuity. Early supplier contracts or co-manufacturing agreements for specialty silicones or hydrogel components mitigate production risk and preserve launch timelines.
- Use M&A and partnerships to accelerate clinical capability. For firms without established hospital access, acquiring a specialty brand with clinical relationships or partnering with wound-care specialists can compress time-to-reimbursement.
Scenarios and sensitivities executives must model now
Our report supplies three actionable scenarios—conservative, central and accelerated—each incorporating clinical-guideline shifts, reimbursement changes, and raw-material supply shocks. Sensitivity analysis shows that modest acceleration in guideline adoption or broader payer reimbursement materially increases the addressable opportunity; conversely, sustained supply constraints compress near-term upside. Leaders should stress-test capital allocation under each scenario before finalizing 2026 budgets.
Final note: the tactical edge for 2026
The Radiation Dermatitis Cream market is not a winner-takes-all arena, but it rewards disciplined, evidence-based commercial execution. The next 12 months will decide which companies convert modest market growth into leadership positions in oncology formularies and outpatient channels. PW Consulting’s report translates market trajectories into executable steps—prioritized research plans, channel plays, reimbursement blueprints and M&A screens—designed for immediate integration into 2026 corporate planning processes.
For the complete dataset, regional and channel tables, full competitive profiles with capability scores, and the downloadable decision-support model, consult the full Radiation Dermatitis Cream Market Research report on our site.
For detailed analysis of this topic, please visit the official page: Radiation Dermatitis Cream Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


