



PW Consulting: Countertop Water Flosser Market Poised to Reach USD 970.36 Million by 2032, New Report Finds

Countertop Water Flosser Market 2026 Strategic Preview — PW Consulting Intelligence Brief
As healthcare consumerization, home-based preventive dentistry, and omnichannel retailing continue to reshape personal oral care, countertop water flossers have moved from niche clinical adjuncts to mainstream household health appliances. PW Consulting’s latest Market Research on Countertop Water Flossers provides executive teams with the forward-looking analysis necessary to make high-stakes decisions in 2026 — from product roadmaps and channel investment to M&A targeting and regulatory risk mitigation.
Countertop Water Flosser Market Research
Executive snapshot
Our base-year assessment (2025) shows the global countertop water flosser market at roughly USD 591 million. Driven by steady consumer adoption, product innovation and distribution expansion, the market is forecast to grow at a compound annual growth rate (CAGR) of 7.34% through our forecast horizon, reaching an aggregate near USD 970 million by 2032. Market concentration metrics indicate a competitive landscape where the top three players control a material majority of market value, and the top five firms deepen that dominance — a dynamic that shapes pricing power, channel leverage, and M&A incentives.
Countertop Water Flosser Market Research
Why 2026 is a pivotal year for executive strategy
-
Post-pandemic behavior locks in new hygiene routines: Consumers who adopted enhanced oral-care routines during the pandemic are less likely to revert — creating a structural uplift for devices that demonstrably improve interdental cleaning.
Countertop Water Flosser Market Research -
Retail rebalancing accelerates strategic inflection points: With e-commerce continuing to grow alongside revitalized brick-and-mortar formats, 2026 is the window when incumbents and challengers must finalize channel plays that will determine customer lifetime value for the next decade.
-
Regulatory clarity reduces one axis of uncertainty: Classification as Class I medical devices (FDA) and widely recognized certification standards provide a known compliance baseline — yet material, labeling and safety requirements still influence sourcing, cost and speed-to-market.
What the data tells strategic leaders (without spoiling the proprietary detail)
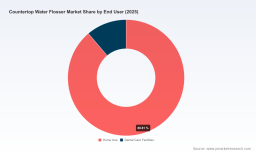
At a high level, the numbers point to a healthy, mid-single-digit-plus growth market with clear monetization paths for product differentiation, bundled services and subscription consumables. The growth is neither hypercyclical nor commodity-driven; instead, it favors companies that can combine clinical credibility, ease-of-use, and retail availability. While PW Consulting’s full dataset includes granular regional, channel and end-user breakdowns, the strategic signal is clear: firms must align product innovation, pricing models and channel partners to capture the durable margin pool that sits above commodity price competition.
Competitive landscape — players, positioning and battlegrounds
-
Church & Dwight Co., Inc. (Waterpik brand) — As an established leader, Waterpik benefits from decades of brand equity and clinical validation, including third-party endorsements that materially reduce consumer purchase friction. Strategically, incumbency enables scale advantages in retail placement and marketing; however, it also requires continuous product modernization to defend against agile challengers.
-
Procter & Gamble (Oral-B) — Leverages integrated oral-care platforms and cross-category bundling. The strategic opportunity for P&G lies in marrying irrigator functionality with established oral-care consumables and leveraging distribution relationships to promote bundled offers to both mass and premium segments.
-
Panasonic Corporation — Brings differentiated engineering and quality-perception advantages, including proprietary water-delivery technologies. Panasonic’s strategic edge is in feature-led productization and international distribution networks; its challenge is translating technology leadership into scalable, price-competitive offerings for diverse retail channels.
-
Dentaprobes, Inc. (HydroFloss) — A specialist focused on electromagnetic-drive innovation. Niche technological differentiation creates clear positioning for clinicians and discerning consumers, but scaling requires partnerships for broader retail penetration or selective licensing to larger OEMs.
Across incumbents and challengers, the competitive battleground is shifting from pure product specs to ecosystem ownership: consumption-driven accessories, subscription filament/attachment replenishment, warranty and service extensions, and co-marketing relationships with dental professionals. Our report maps these battlegrounds and highlights priority plays for market entrants and incumbents alike.
Regulatory, certification and material implications for product strategy
-
Regulatory status: Powered oral irrigators are categorized as Class I medical devices under current FDA policy, easing premarket constraints but maintaining obligations around labeling, manufacturing quality and post-market surveillance.
-
Certification benefits: ADA-level endorsements materially increase consumer confidence and are directly correlated with propensity-to-purchase in our consumer-panel analysis. Securing such seals or credible clinical trials should be treated as a strategic investment rather than a compliance checkbox.
-
Materials and supply chain: Reservoirs and fluid-contact components must conform to BPA-free and food-contact polymer standards. This drives engineering choices, supplier selection, and unit-cost dynamics; companies that lock in compliant, cost-effective polymer sources gain meaningful margin resilience.
Actionable strategic playbook for 2026
The following strategic levers are prioritized in PW Consulting’s advisory work for the coming planning cycle. Each lever ties directly to measurable KPIs and executable initiatives detailed in the full report.
-
Product segmentation and feature prioritization — Differentiate by clinical validation (e.g., plaque/gingivitis performance), convenience features (cordless options, noise reduction, reservoir capacity), and adjacent functionality (combined brush-irrigation systems). A rapid prototyping track coupled with clinician-led trials shortens time-to-efficacy claims.
-
Channel-tailored go-to-market — Optimize SKU and pricing architecture per channel: online marketplaces, specialty dental outlets, and mass channels require distinct value propositions. Invest in channel-specific content, review strategies and logistics partnerships in 1H 2026 to capture peak selling seasons.
-
Subscription and consumables strategies — Design replenishment models for tips, membranes and accessories. Bundling consumables with the device at point-of-sale and incentivized auto-replenishment are high-margin levers that deepen customer lifetime value.
-
M&A and partnership playbook — Look for bolt-on acquisitions that add specialty patents, regional distribution, or clinical trial capability. Alternatively, consider licensing electromagnetic or nanoe technologies to accelerate product differentiation without full-scale R&D investment.
-
Cost-to-serve and supply risk mitigation — Reconfigure supplier contracts for polymer components to balance compliance, cost and lead time. Dual-sourcing and nearshoring of critical components reduce vulnerability to shipping disruptions while preserving margin.
Scenarios, sensitivities and near-term risks
Our scenario framework evaluates demand under optimistic, baseline and downside assumptions — including shifts in consumer spending, changes in certification standards, and increased price competition from private-label entrants. Key sensitivities include: consumer adoption velocity in emerging channels, cost inflation on compliant polymers, and the timing of competitor product launches. PW Consulting models these variables to produce decision-ready threshold analyses (NPV breakevens, payback timelines, and channel ROI curves) that are included in the full report.
What the full PW Consulting report includes (select highlights)
-
Comprehensive market model with historicals and a 2026–2032 forecast (interactive dashboard included in the full report).
-
Competitive heatmaps, feature-benchmarking matrices and patent landscaping for incumbent and challenger technologies.
-
Go-to-market templates for channel-specific SKU, pricing and promotional strategies optimized for Q3–Q4 2026 execution windows.
-
Supply-chain maps, supplier scorecards and a materials cost-sensitivity model calibrated to current polymer and logistics pricing.
-
M&A target shortlists and partnership canvases with deal-valuation ranges and integration checkpoints.
-
Regulatory and certification roadmap, including checklists to secure professional endorsements and consumer trust signals.
How to use this intelligence to finalize your 2026 plan
-
Product leaders should use the feature-benchmark and consumer-preference modules to prioritize development sprints tied to clinical claims and user convenience.
-
Commercial teams can adopt our channel ROI templates to reallocate marketing spend toward the highest return mix of digital, specialty and mass retail initiatives in Q1 2026.
-
M&A and corporate development should apply the provided valuation frameworks to screen targets that immediately augment distribution, IP or clinical credibility.
-
Supply-chain and operations executives will find the materials sourcing playbook useful for contracting and dual-sourcing decisions to keep unit economics stable under stress scenarios.
Final perspective — where to place your 2026 bets
Countertop water flossers occupy an intersection of clinical efficacy, consumer convenience and retail accessibility. For companies with the capacity to invest in clinical validation, channel acceleration and service-led monetization, the 2026 planning year is an inflection point: decisive investments now will compound into defensible consumer relationships and margin accretion through the remainder of the decade.
PW Consulting’s Market Research offers the factual backbone and pragmatic templates executive teams need to convert market opportunity into shareholder value. For a complete, interactive view of our models, bespoke scenario runs, and the granular segment and regional disclosures that support board-level decisions, visit the official report page. The public brief in this release purposefully omits some proprietary granularities — those datasets and dashboards are available to licensed subscribers and advisory clients.
For detailed analysis of this topic, please visit the official page: Countertop Water Flosser Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


